💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Search results for: “”

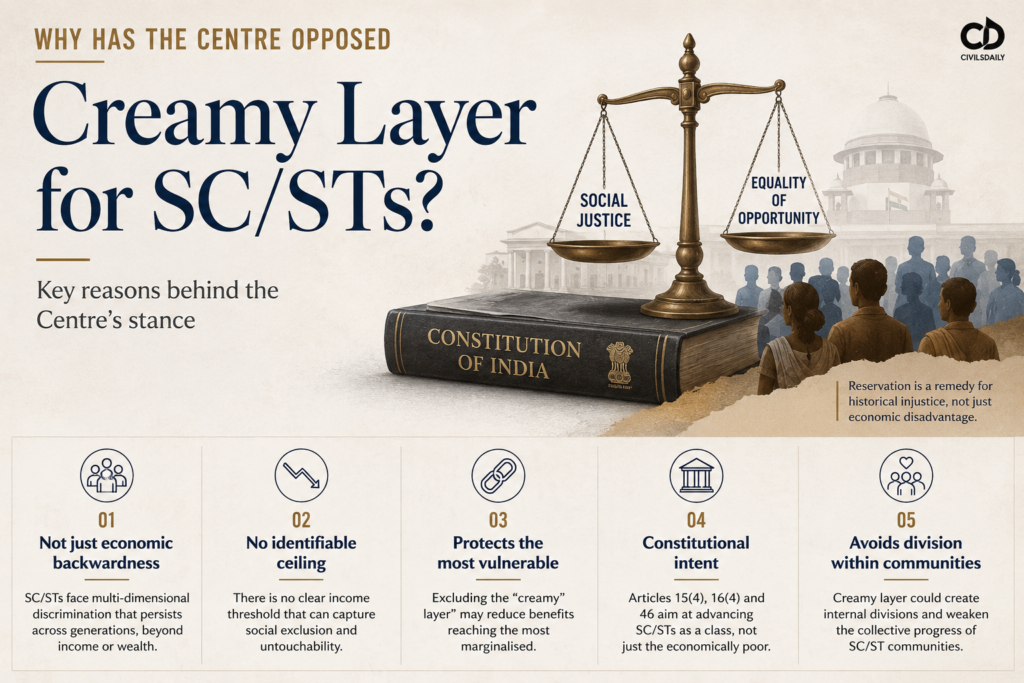
  • Why has the Centre opposed creamy layer for SC/STs?

    Why in the News

    The Union government reiterated before the Supreme Court that the creamy layer exclusion does not apply to Scheduled Caste and Scheduled Tribe classification. The position runs against a separate opinion in the 2024 sub categorisation ruling that urged the Court to consider extending the exclusion. The tension is between the constitutional premise that Scheduled Caste and Scheduled Tribe disadvantage is social rather than economic, and evidence that reservation benefits concentrate within a few advanced sub groups.

    What is the creamy layer?

    1. About: The creamy layer is the economically and socially advanced section within a reserved category, excluded from reservation benefits so that the quota reaches the genuinely disadvantaged.
    2. Origin: The exclusion was mandated for Other Backward Classes in Indra Sawhney vs Union of India (1992).
    3. Mechanism: Exclusion operates through an income and status ceiling, currently Rs 8 lakh of annual family income for Other Backward Classes, alongside constitutional post and service rank criteria.
    4. Point of dispute: The doctrine has never been extended to Scheduled Castes and Scheduled Tribes, whose identification rests on untouchability and social exclusion rather than income.

    Current Status of Reservation in India

    1. Category shares: Scheduled Castes hold 15 per cent, Scheduled Tribes 7.5 per cent, and Other Backward Classes 27 per cent subject to the creamy layer exclusion.
    2. Economically Weaker Sections: A further 10 per cent applies to those outside the reserved categories, introduced by the 103rd Constitutional Amendment.
    3. Ceiling position: The 50 per cent ceiling set in Indra Sawhney stands, and the Economically Weaker Sections quota was upheld in 2022 as sitting outside it.
    4. Sub categorisation: States may sub categorise within the Scheduled Caste and Scheduled Tribe lists after the 2024 ruling, but exclusion of individuals remains barred.
    5. Central practice: The only central use of sub categorisation within the Scheduled Tribe quota is in Eklavya Model Residential Schools, which reserve minimum representation for Particularly Vulnerable Tribal Groups.

    Constitutional Provisions Related to Reservation

    1. Article 15(4) and 15(5): Permit special provisions for the advancement of socially and educationally backward classes, Scheduled Castes and Scheduled Tribes, including in educational institutions.
    2. Article 16(4): Permits reservation in appointments for any backward class not adequately represented in state services.
    3. Article 16(4A): Permits reservation in promotion with consequential seniority for Scheduled Castes and Scheduled Tribes.
    4. Article 335: Requires that claims of Scheduled Castes and Scheduled Tribes be considered consistently with the maintenance of administrative efficiency.
    5. Article 341 and Article 342: Empower the President to specify the Scheduled Castes and Scheduled Tribes for each state, with Parliament alone able to include or exclude from the list.
    6. 103rd Constitutional Amendment, 2019: Inserted Articles 15(6) and 16(6) creating the Economically Weaker Sections quota.

    What did the Davinder Singh ruling actually decide?

    1. Sub categorisation permitted: A seven judge Bench in August 2024 held that states may sub categorise within the Scheduled Caste and Scheduled Tribe lists to give preference to the most backward within them.
    2. Homogeneity rejected: The Bench held that Scheduled Castes are not a homogeneous class, which is the premise sub categorisation rests on.
    3. The separate opinion: One judge wrote separately that the creamy layer principle applied to Other Backward Classes in Indra Sawhney should be considered for Scheduled Castes and Scheduled Tribes.
    4. Status of that view: The separate opinion did not create a binding direction, which is the gap the current litigation is testing.

    What is the government’s stated objection?

    1. Parliamentary competence: The power to include or exclude any community or individual from the Scheduled Caste and Scheduled Tribe lists rests solely with Parliament under Articles 341 and 342.
    2. Precedent claim: No binding judicial precedent has ever mandated a creamy layer for Scheduled Castes and Scheduled Tribes.
    3. Process objection: Any change should follow a holistic review and an empirical study, and should not arrive through judicial direction.
    4. Basis of identification: Scheduled Caste status derives from the disability of untouchability, which income does not extinguish.

    Major debates surrounding creamy layer extension

    1. Social versus economic disadvantage: Whether caste based exclusion persists after income rises is the empirical question the entire dispute turns on.
    2. Benefit capture: Sub categorisation was permitted precisely because a few advanced sub groups were found to be capturing a disproportionate share of the quota.
    3. Consistency argument: The Economically Weaker Sections quota already applies an income exclusion, which is the same logic being resisted for Scheduled Castes.
    4. Institutional route: Whether the change should come from Parliament under Article 341, from the executive, or from judicial interpretation.
    5. Empirical gap: The Justice G Rohini Commission, set up in 2017 to examine Other Backward Classes sub categorisation, submitted its report three years ago and it remains unpublished.
    6. Political mobilisation: The Reservation Hatao Andolan, an online movement with over five million followers, demands replacing caste based reservation with income based reservation.

    Challenges to reservation policy design

    1. Absence of current data: Caste wise socio economic data has not been published in usable form since 1931 for most categories. e.g. the Socio Economic and Caste Census of 2011 whose caste data was never released.
    2. Ceiling pressure: State legislations repeatedly breach the 50 per cent ceiling and are struck down. e.g. the Maratha reservation law set aside by the Supreme Court in 2021.
    3. Backlog vacancies: Reserved posts remain unfilled while the quota is nominally in force. e.g. the recurring backlog vacancies reported in central government establishments.
    4. Promotion quota litigation: The requirement to demonstrate inadequacy of representation before reserving in promotion generates continuous litigation. e.g. the Jarnail Singh line of cases refining the M Nagaraj test.
    5. Sub categorisation without data: States may now sub categorise but lack the empirical base to defend a specific split. e.g. the unpublished Rohini Commission report on Other Backward Classes sub categorisation.
    6. Private sector exclusion: Reservation does not extend to private employment, which now accounts for most new job creation. e.g. the repeated but unlegislated demand for reservation in the private sector.

    Conclusion

    The dispute is not about whether advanced sub groups capture a disproportionate share of the Scheduled Caste quota, which the 2024 ruling accepted, but about who may act on that finding and on what evidence. The government’s position keeps the exclusion power with Parliament under Article 341 and makes the missing empirical study the precondition for any change. The next milestone is the Supreme Court’s decision on whether the creamy layer question survives as a live issue after the government’s stand.

    Back2Basics: Justice G Rohini Commission

    1. Constituted in October 2017 under Article 340 to examine sub categorisation of Other Backward Classes.
    2. Mandated to examine the uneven distribution of reservation benefits among castes within the central Other Backward Classes list.
    3. Also tasked with working out a scientific approach for sub categorisation and correcting errors in the central list.
    4. Received repeated extensions and submitted its report to the President in July 2023.
    5. The report has not been made public or acted upon, which is central to the current debate on evidence.

    Way Forward

    1. Publish the empirical base: Release caste wise socio economic data and the Rohini Commission report so any exclusion rests on evidence rather than assertion.
    2. Legislate rather than litigate: Settle the exclusion question through Parliament under Article 341, which the government itself identifies as the competent authority.
    3. Complete sub categorisation frameworks: Give states a model methodology for defensible sub categorisation after the 2024 ruling.
    4. Fill backlog vacancies: Address unfilled reserved posts, since unused quota undercuts arguments on both sides of the debate.
    5. Track outcomes, not intake: Report reservation performance through completion, retention and promotion data, not through admission and appointment counts alone.

    “[2026] Consider the following statements about provisions pertaining to SC/STs in India:

    1. Provisions for Tribal Areas in Assam, Meghalaya, Tripura and Mizoram are in the Fifth Schedule.

    2. Some tribes of India are entitled to exemption from paying Income Tax on certain incomes.

    3. The Constitution provides for reservation of seats in Panchayats for women belonging to SCs and STs.

    (a) There are two correct statements, that include statement 2

    (b) There are two correct statements, that are statements 1 and 3

    (c) There is only one correct statement

    (d) All three statements are correct
  • How US is building a case for ‘transhipment crackdown’ and why India may be at risk

    Why in the News

    A United States government report titled The Great Transhipment Scam: Global Evasion and Economic Costs names over 40 countries in a claimed shadow transhipment network and places India, Mexico, Canada and the European Union in Tier 1. The classification arrives while an India United States trade deal is under negotiation. The tension is between a tariff enforcement category built to catch origin fraud and a manufacturing model that legitimately imports Chinese components for domestic value addition.

    What is transhipment in trade enforcement?

    1. About: Transhipment in this context means routing goods of one origin through a third country so they enter the destination market under the third country’s tariff treatment.
    2. Why it matters: Origin determines the tariff rate, so mislabelling origin converts a high tariff good into a low tariff one.
    3. The legitimate case: Goods that undergo substantial transformation in the third country acquire that country’s origin lawfully under rules of origin.
    4. The disputed boundary: The report’s methodology does not separate origin fraud from genuine domestic value addition, which is where India’s exposure arises.

    What does the report actually claim?

    1. Tier 1 classification: India, Mexico, Canada and the European Union are placed in the highest risk tier.
    2. Volume estimate: About $67 billion of United States bound goods are estimated to be transhipped from China through top hubs, named as Mexico, India and Vietnam.
    3. Revenue estimate: The estimated tariff revenue loss is about $28 billion.
    4. Cluster naming: The report labels the Pune, Gujarat and Chennai industrial corridor as a cluster of concern.
    5. Institutional source: The estimates come from the Office of Trade and Economic Analysis within the United States Commerce Department.

    Why is India exposed despite genuine manufacturing?

    1. Component dependence: Indian electronics assembly imports a large share of components from China, so import content is high even where assembly is real.
    2. Measurement problem: A high Chinese import share can be read either as origin fraud or as an early stage manufacturing base, and the report does not distinguish the two.
    3. Scheme linkage: Production Linked Incentive driven assembly expanded exports faster than the domestic component base grew, which widens the gap the report treats as suspicious.
    4. Corridor concentration: Export clusters concentrate assembly activity geographically, which makes them visible in trade data as hubs.

    What enforcement instruments follow from such a report?

    1. Section 301 action: The United States Trade Representative can open an investigation and impose tariffs on a trading partner’s practices under Section 301 of the Trade Act, 1974.
    2. Trade deal clause: A transhipment clause can be written into the pending India United States trade agreement, binding India to origin verification obligations.
    3. Legal context: Reciprocal tariffs imposed earlier were struck down by the United States Supreme Court, which pushes enforcement toward statutory routes that survive judicial review.
    4. Secondary tariff route: Separate legislation permitting tariffs of up to 100 per cent on major buyers of Russian oil provides an additional pressure point.

    What is the counter argument to the report’s framing?

    1. Value addition versus routing: A country that imports components, assembles and exports is performing manufacturing, not evasion, when the transformation meets the origin threshold.
    2. Rules of origin already exist: Preferential and non preferential rules of origin provide a legal test for substantial transformation, so a new category adds pressure rather than clarity.
    3. Negotiating leverage: Naming a partner in a public report ahead of a trade negotiation functions as leverage over the terms of that negotiation.
    4. Bilateral drift: The instrument bypasses the multilateral dispute settlement route, which has been non functional since the Appellate Body lost quorum.

    Challenges to India’s export position

    1. Origin verification capacity: Certifying substantial transformation at scale requires customs documentation India’s exporters are not uniformly equipped for. e.g. disputes over certificates of origin under the India ASEAN agreement.
    2. Component import dependence: Domestic value addition in electronics remains low even as export volumes rise. e.g. mobile handset exports growing faster than domestic component sourcing.
    3. Dispute settlement vacuum: The World Trade Organization Appellate Body has been non functional since 2019, removing the appeal route against unilateral measures. e.g. appeals filed into the void by multiple members since then.
    4. Tariff exposure concentration: The United States is India’s largest single export market, so a unilateral measure has outsized effect. e.g. the disruption to Indian shrimp and steel exports during earlier tariff rounds.
    5. Rules of origin complexity: Each trade agreement carries a different origin threshold, raising compliance cost for the same exporter. e.g. differing value addition thresholds under India’s agreements with Japan and ASEAN.
    6. Retaliation limits: India’s counter tariff capacity is small relative to the market it would be retaliating against. e.g. the limited effect of India’s 2019 retaliatory tariffs on United States agricultural goods.

    Conclusion

    The report converts a measurement ambiguity, high Chinese import content in Indian assembly, into an enforcement category, and that conversion is what puts India at risk rather than any finding of fraud. The remedy runs through demonstrable domestic value addition, not through contesting the label. The next milestone is whether a transhipment clause appears in the text of the India United States trade agreement.

    Back2Basics: Rules of Origin

    1. Rules of origin are the criteria used to determine the country of origin of a product for the purpose of applying tariffs and trade measures.
    2. Non preferential rules of origin apply for most favoured nation tariffs, anti dumping duties and trade statistics.
    3. Preferential rules of origin apply under free trade agreements and decide whether a good qualifies for concessional duty.
    4. Substantial transformation is the core test, applied through a change in tariff classification, a regional value content threshold, or a specified processing operation.
    5. India tightened enforcement through the Customs (Administration of Rules of Origin under Trade Agreements) Rules, 2020, which placed the burden of proof on the importer.

    Way Forward

    1. Raise domestic value addition thresholds: Tie incentive disbursement to verified local content rather than to export value alone.
    2. Build an origin audit trail: Create a digital component provenance record for export clusters so transformation can be evidenced rather than asserted.
    3. Negotiate the clause narrowly: Confine any transhipment clause in the trade agreement to documented origin fraud, not to import content share.
    4. Deepen component manufacturing: Extend incentives to sub assemblies and passive components, since the exposure originates in the missing component layer.
    5. Diversify export destinations: Reduce single market concentration through the concluded agreements with the United Kingdom and the European Free Trade Association bloc.

    Matching Previous Year Question

    “[2025, GS3, 10 marks] What are the challenges before the Indian economy when the world is moving away from free trade and multilateralism to protectionism and bilateralism? How can these challenges be met?”

  • As Govt. mulls MDR on UPI, data shows cash usage quickening

    Why in the News

    The Taxation and Other Laws (Amendment) Act, 2026, passed in the concluded Monsoon Session, enables a Merchant Discount Rate on Unified Payments Interface and RuPay debit card transactions that are currently free. Data over the same period shows digital transaction growth decelerating while cash with the public rose to Rs 41.8 lakh crore. The tension is between making the payments system financially self sustaining and preserving the zero cost design that drove its adoption.

    What is the Merchant Discount Rate?

    1. About: The Merchant Discount Rate (MDR) is the charge a bank levies on a merchant for accepting a customer payment through a card or a digital payment instrument.
    2. How it is split: The charge is shared between the card issuing bank, the acquiring bank and the network operator.
    3. Current position in India: MDR on UPI and RuPay debit card transactions was set at zero in 2020, making the rails free at the point of acceptance.
    4. What the Act changes: The amendment enables the government to permit an MDR on these instruments, reversing the zero charge position.

    What do the payment and cash numbers actually show?

    1. UPI value growth, decelerating: Growth fell from 133 per cent in 2019-20 to 95 per cent in 2020-21, 105 per cent in 2021-22, 20.3 per cent in 2025-26 and 18.7 per cent so far in 2026-27.
    2. Cash growth, accelerating: Growth in cash with the public fell to about 4 per cent in 2023-24, then rose to 6.5 per cent in 2024-25, 12 per cent in 2025-26 and about 13 per cent in 2026-27.
    3. Absolute cash level: Cash with the public stood at Rs 41.8 lakh crore as on 31 July 2026.
    4. The anomaly: Digital payments and cash holdings are growing together, which contradicts the substitution assumption behind the zero MDR policy.

    Why are digital payments and cash rising together?

    1. Under counted inflation: If nominal transactions require more cash than measured inflation implies, the price index is understating actual price growth. Retail inflation was 4.45 per cent in July 2026 while wholesale inflation stood at 9.8 per cent.
    2. Real growth explanation: A rate of real growth above 7 per cent expands nominal transaction demand for both cash and digital instruments at once.
    3. Distress explanation: Rising cash holding is read as precautionary balances accumulating under high youth unemployment.
    4. Measurement gap: The wholesale and retail inflation series have diverged by more than five percentage points, which is itself the evidence the competing explanations turn on.

    What is contested about charging for UPI?

    1. Government position: The charge will not fall on the general public and will apply only to certain high value transactions.
    2. Opposition position: Merchants will pass the charge on to customers, so the incidence reaches the consumer regardless of who is billed.
    3. Underlying fiscal problem: Zero MDR shifted the cost of running the rails onto banks and the exchequer through incentive payments, which is not indefinitely sustainable.
    4. Adoption risk: Small merchants accepted UPI precisely because acceptance was costless, so a charge changes the acceptance calculation at the margin.

    Challenges to the digital payments system

    1. Cost recovery without an acceptance charge: Banks carry infrastructure costs with no transaction revenue on UPI. e.g. the annual incentive outlay the government has budgeted to compensate banks for zero MDR.
    2. Concentration risk: Two applications account for the overwhelming majority of UPI volume. e.g. the National Payments Corporation of India repeatedly deferring its 30 per cent market share cap.
    3. Fraud and mule accounts: Instant irreversible settlement makes recovery difficult once a payment is made. e.g. the rise in digital arrest and investment fraud cases routed through UPI collect requests.
    4. Outage exposure: A single operator running the rails concentrates systemic failure risk. e.g. the intermittent UPI outages that halted merchant acceptance across the country in 2025.
    5. Rural acceptance gap: Feature phone and low connectivity users remain outside the mainstream flow. e.g. limited uptake of UPI123Pay against smartphone based volumes.
    6. Cash persistence in the informal economy: Cash remains preferred where transactions are deliberately unrecorded. e.g. cash with the public rising to Rs 41.8 lakh crore alongside record digital volumes.

    Conclusion

    The amendment converts a policy question about who pays for the payments system into an operative legal power, and the answer will determine whether acceptance keeps widening. The simultaneous rise in cash is the more important signal, since it suggests digital adoption has been additive rather than substitutive. The next milestone is the notification specifying which transaction categories will attract the charge and at what rate.

    Back2Basics: National Payments Corporation of India

    1. Set up in 2008 as an umbrella organisation for retail payments and settlement systems in India.
    2. Incorporated as a not for profit company under Section 8 of the Companies Act, 2013, promoted by public and private sector banks.
    3. Operates under the regulatory authority of the Reserve Bank of India, which draws its powers from the Payment and Settlement Systems Act, 2007.
    4. Runs UPI, RuPay, Immediate Payment Service, National Automated Clearing House, National Electronic Toll Collection and Bharat Bill Payment System.
    5. Established NPCI International Payments Limited in 2020 to take UPI and RuPay to overseas markets.

    Way Forward

    1. Define the threshold in the notification: State the transaction value above which the charge applies, so small merchant acceptance is not affected by ambiguity.
    2. Cap the pass through: Prohibit merchant surcharging on transactions below the threshold, since incidence rather than billing decides the consumer effect.
    3. Reconcile the inflation series: Investigate the divergence between retail and wholesale inflation before treating cash growth as evidence of either strength or distress.
    4. Enforce the market share cap: Implement the volume cap on individual UPI applications to reduce concentration risk.
    5. Fund the rails transparently: Publish the annual cost of running the zero charge system, so the trade off between an explicit charge and a budgetary subsidy is visible.

    Matching Previous Year Question

    “[2018] Which one of the following best describes the term Merchant Discount Rate sometimes seen in news? (a) The incentive given by a bank to a merchant for accepting payments through debit cards pertaining to that bank. (b) The amount paid back by banks to their customers when they use debit cards for financial transactions for purchasing goods or services. (c) The charge to a merchant by a bank for accepting payments from his customers through the bank’s debit cards. (d) The incentive given by the Government to merchants for promoting digital payments by their customers through Point of Sale (PoS) machines and debit cards. Answer: (c)”

  • Govt. brings scheme to disclose foreign assets

    Why in the News

    The Central Board of Direct Taxes notified the Foreign Assets of Small Taxpayers Disclosure Scheme (FAST-DS), open from 16 August to 31 December 2026. The scheme offers immunity from penalty and prosecution under the black money law in exchange for an effective 60 per cent levy. The tension is between clearing a large stock of inadvertent non disclosure by salaried professionals and the moral hazard of repeated amnesty windows.

    What is FAST-DS?

    1. About: FAST-DS is a time bound voluntary disclosure window for undisclosed foreign income and assets held by small taxpayers.
    2. Category one: Previously untaxed foreign assets or income with an aggregate value up to Rs 1 crore, charged at 30 per cent tax plus 30 per cent in lieu of penalty, an effective 60 per cent.
    3. Category two: Foreign assets up to Rs 5 crore that were already offered to tax, or acquired while the holder was non resident, but were not reported in the return schedule, settled through a flat fee of Rs 1 lakh.
    4. Valuation date: Fair market value is determined as of 31 March 2026.
    5. Relief granted: Immunity from penalty and prosecution under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015.
    6. Exclusion: Immunity does not extend to proceedings under the Prevention of Money Laundering Act, 2002.

    Who is the scheme actually aimed at?

    1. Target group: Students, young technology professionals and returning non resident Indians who hold foreign equity awards.
    2. Typical asset: Restricted stock units and employee stock options vested while working for a foreign parent company.
    3. Nature of default: The default is usually a failure to fill the foreign asset schedule of the return, not concealment of income.
    4. Penalty exposure avoided: The 2015 Act prescribes a flat penalty of Rs 10 lakh for non disclosure of a foreign asset regardless of the asset’s size.

    Why is the government able to detect these assets now?

    1. Common Reporting Standard: Participating jurisdictions automatically exchange financial account information on each other’s residents.
    2. Foreign Account Tax Compliance Act: The bilateral arrangement with the United States requires reporting of accounts held by Indian residents.
    3. Effect on enforcement: Automatic exchange converts detection from an investigative exercise into a data matching exercise.
    4. Consequence for taxpayers: Non disclosure that once went unnoticed now surfaces as a mismatch in the department’s records.

    What does the design tell us about the government’s calculation?

    1. Rate choice: An effective 60 per cent rate is punitive against the 30 per cent maximum marginal rate, so the scheme is not priced as a concession.
    2. Threshold choice: The Rs 1 crore and Rs 5 crore ceilings exclude large scale offshore holdings, keeping the window away from serious evaders.
    3. Money laundering carve out: Retaining Prevention of Money Laundering Act exposure signals that the scheme buys relief from reporting failure, not from criminal conduct.
    4. Duration: A four and a half month window forces disclosure decisions inside one assessment cycle.

    Challenges to voluntary disclosure schemes

    1. Moral hazard: Repeated windows teach compliant taxpayers that waiting is rewarded. e.g. the Income Declaration Scheme of 2016 following earlier voluntary disclosure rounds.
    2. Modest collections: Disclosure schemes typically raise far less than projected. e.g. the 2015 black money compliance window collecting about Rs 2,428 crore in tax and penalty.
    3. Valuation disputes: Fair market value of unlisted foreign equity is contestable and invites later litigation. e.g. disputes over the valuation of unlisted shares under earlier disclosure rounds.
    4. Equity objection: Constitutional challenges have been mounted arguing amnesty discriminates against honest taxpayers. e.g. the Supreme Court’s observations in the challenge to the 1997 Voluntary Disclosure of Income Scheme.
    5. Residual exposure: Immunity under one statute does not close exposure under others, which suppresses participation. e.g. the explicit exclusion of Prevention of Money Laundering Act proceedings in this scheme.
    6. Data mismatch errors: Automatic exchange data carries identity and currency conversion errors that generate wrongful notices. e.g. duplicate reporting of joint accounts under the Common Reporting Standard.

    Conclusion

    FAST-DS is priced and capped so that it functions as a clean up of reporting failure by salaried professionals rather than as an amnesty for offshore concealment. Retaining money laundering exposure is what keeps the scheme distinguishable from a general pardon. The next milestone is the disclosure volume reported when the window closes on 31 December 2026.

    Back2Basics: Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015

    1. Enacted in 2015 to deal specifically with undisclosed foreign income and assets, separately from the Income-tax Act.
    2. Levies a flat tax of 30 per cent on undisclosed foreign income and assets, with no deductions or exemptions permitted.
    3. Prescribes a penalty of three times the tax on undisclosed foreign assets, and a flat penalty of Rs 10 lakh for failure to disclose a foreign asset in the return.
    4. Provides for rigorous imprisonment of three to ten years for wilful attempt to evade tax on foreign income or assets.
    5. Applies to persons resident in India, and covers assets held as a beneficial owner or beneficiary.

    Way Forward

    1. Make the disclosure schedule simpler: Redesign the foreign asset schedule so vested equity awards can be reported without professional assistance.
    2. Pre fill from exchanged data: Populate the return with information already received under automatic exchange, converting disclosure into confirmation.
    3. Separate reporting failure from evasion: Set a lower statutory penalty for a first time reporting lapse below a defined threshold, so an amnesty window is not needed to fix it.
    4. Publish outcome data: Report collections and participant counts after closure, so the case for or against future windows rests on evidence.
    5. Close the window credibly: State that no further disclosure window will follow, since the deterrent value of the 2015 Act depends on that expectation.

    Matching Previous Year Question

    “[2021] Which one of the following effects of the creation of black money in India has been the main cause of worry to the Government of India? (a) Diversion of resources to the purchase of real estate and investment in luxury housing (b) Investment in unproductive activities and purchase of precious stones, jewelry, gold, etc. (c) Large donations to political parties and the growth of regionalism (d) Loss of revenue to the State Exchequer due to tax evasion Answer: (d)”

  • Why India needs more power for AI, chips and datacentres

    Why in the News

    The Department of Atomic Energy released draft rules covering private participation, captive generation, licensing, safety oversight and nuclear liability under the SHANTI Act. The rules follow a stated target of 100 GWe of nuclear capacity by 2047 against an operating base of 8.7 GWe. The tension is between opening a sector historically closed to private capital and retaining state control over fissile material, safety and liability.

    What is the SHANTI Act?

    1. About: The SHANTI Act is the legislation passed last year that opens nuclear power generation to private participation, ending the state monopoly on reactor operation.
    2. What it changes: It creates a licensing route for private operators and permits captive nuclear generation for industrial users.
    3. What it retains: Fuel cycle control, safety regulation and the liability framework stay with the state.
    4. Status: Draft rules under the Act have been released, so the operating framework is now in the consultation stage rather than in force.

    What is a Small Modular Reactor?

    1. About: A Small Modular Reactor (SMR) is a reactor of up to about 300 MWe built from factory fabricated modules rather than constructed entirely on site.
    2. Why it matters: Factory fabrication shortens construction time and lowers the upfront capital block that makes large reactors hard to finance.

    Where does India’s nuclear capacity actually stand?

    1. Operating fleet: 25 reactors in operation with a combined capacity of 8.7 GWe.
    2. Under construction: 10 reactors adding about 8 GWe.
    3. Pre project stage: 10 further reactors accounting for about 66 GWe, which is where most of the 100 GWe target sits.
    4. Commissioning plan: Five new reactors are to be commissioned this decade.
    5. Backbone technology: Pressurised Heavy Water Reactors remain the mainstay of the operating fleet.

    What is the indigenous small reactor programme?

    1. Bharat Small Modular Reactor: A 200 MWe design (BSMR-200) intended for grid and captive industrial supply.
    2. Compact variant: A 55 MWe small modular reactor for smaller loads and remote siting.
    3. High temperature design: A 5 MWt high temperature gas cooled reactor aimed at hydrogen production through a thermochemical process.
    4. Deployment target: At least five indigenous small modular reactors operational by 2033.
    5. Mission funding: The Nuclear Energy Mission carries an outlay of Rs 20,000 crore.
    6. Site reuse: Retiring thermal plant sites are being studied for repurposing, since they already carry grid connection and cooling water access.

    Why is demand growth driving the target now?

    1. Datacentre load: Artificial intelligence and datacentre expansion require firm, round the clock power that intermittent renewables cannot supply alone.
    2. Capacity addition: Operational datacentre stock stands at 1.8 GW of information technology load, with about 500 MW projected to be added in 2026.
    3. Industrial decarbonisation: Semiconductor fabrication and green hydrogen electrolysis both need continuous low carbon power.
    4. Grid character: Nuclear supplies baseload, which is the specific gap left by a renewables heavy addition profile.

    Where does foreign collaboration fit?

    1. Russia: The existing large light water reactor partnership at Kudankulam is the deepest supplier relationship.
    2. United States: Collaboration is expected to centre on small modular designs rather than large units.
    3. France: Large reactor negotiations have run for over a decade without financial closure.
    4. Design economics: Foreign collaboration is shifting toward small modular reactors because large light water reactors carry costs India has not been able to close on.

    Challenges to the 100 GWe nuclear target

    1. Liability deterrence: Supplier liability provisions have kept foreign vendors from signing commercial contracts. e.g. the Jaitapur project’s unresolved negotiation with the French supplier since 2010.
    2. Construction schedule slippage: Indian reactors have historically overrun their commissioning schedules by years. e.g. the Kudankulam units commissioned well past their original dates.
    3. Land acquisition and local resistance: Reactor siting has triggered sustained local opposition. e.g. the prolonged protests at Kudankulam in Tamil Nadu.
    4. Fuel supply: Domestic uranium output is insufficient, leaving the fleet dependent on imported fuel under safeguards. e.g. supply agreements with Kazakhstan, Canada and Russia.
    5. Regulatory independence: The Atomic Energy Regulatory Board is not a statutory body independent of the Department of Atomic Energy. e.g. the Comptroller and Auditor General’s 2012 audit flagging this exact conflict.
    6. Cooling water availability: Reactor cooling depends on assured water, which climate stress is making less reliable. e.g. Hungary running the Paks plant at a quarter of capacity in 2026 because Danube levels fell.

    Conclusion

    The draft rules are the point at which the SHANTI Act stops being an enabling statute and becomes an operating framework, which is what private capital has been waiting for. The 100 GWe target is arithmetically dominated by reactors still at the pre project stage, so the binding question is licensing throughput rather than intent. The next milestone is the finalisation of the draft rules and the first private licence issued under them.

    Nuclear Energy in India

    1. Three stage programme: India’s programme runs from pressurised heavy water reactors using natural uranium, to fast breeder reactors using plutonium, to thorium based reactors exploiting India’s large thorium reserves.
    2. Thorium position: India holds among the world’s largest monazite bearing thorium reserves, concentrated in the beach sands of Kerala, Tamil Nadu and Odisha.
    3. Share of generation: Nuclear supplies about 3 per cent of India’s electricity generation.
    4. Institutional structure: The Department of Atomic Energy reports directly to the Prime Minister, and the Nuclear Power Corporation of India Limited operates the commercial fleet.
    5. Safeguards status: India operates a separated civil and military nuclear programme, with civil facilities placed under International Atomic Energy Agency safeguards after the 2008 waiver.

    Laws and Rules Governing Nuclear Energy

    1. Atomic Energy Act, 1962: Vests control of atomic minerals, fissile material and reactor operation in the central government. Reserved commercial nuclear generation to public sector entities until the SHANTI Act.
    2. Civil Liability for Nuclear Damage Act, 2010: Channels liability to the operator and creates a right of recourse against the supplier. Section 17(b) is the specific provision that foreign suppliers have objected to.
    3. Atomic Energy (Radiation Protection) Rules, 2004: Govern radiation safety, licensing of radiation installations and occupational exposure limits.
    4. SHANTI Act: Opens generation to private participation and provides for captive nuclear generation. Draft rules covering licensing, captive generation, safety oversight and liability were released on 14 August 2026.

    Government Initiatives

    1. Nuclear Energy Mission: Carries an outlay of Rs 20,000 crore for research and deployment of small modular reactors.
    2. Bharat Small Modular Reactor programme: Develops a 200 MWe indigenous design for grid and captive industrial supply.
    3. Nuclear Power Corporation of India fleet mode procurement: Approves multiple pressurised heavy water reactors together to compress procurement and construction timelines.
    4. India based Neutrino Observatory and allied research: Supports the domestic research base underpinning the three stage programme.

    Way Forward

    1. Finalise the liability rules: Settle supplier recourse in the notified rules so vendor contracts can reach financial closure.
    2. Make the regulator statutory: Give the Atomic Energy Regulatory Board statutory independence from the Department of Atomic Energy.
    3. Standardise the small reactor design: Freeze one design for repeat build so factory fabrication delivers its cost advantage.
    4. Use retiring thermal sites: Convert closed thermal plant land, which already has grid and water access, into small reactor sites.
    5. Publish a licensing timeline: Give applicants a defined statutory clock for licence decisions, since 66 GWe of the target sits in reactors not yet approved.

    Matching Previous Year Question

    “[2018, GS3, 15 marks] With growing energy needs should India keep on expanding its nuclear energy programme? Discuss the facts and fears associated with nuclear energy.”

  • Modi pitches reforms, reaches out to Gen Z

    Why in the News

    The 80th Independence Day address from the Red Fort organised the government’s economic agenda into a seven stream framework named Saptadhara, alongside a 100 GW nuclear capacity target and eight semiconductor units by 2047. The framework restates ambition at a moment when three semiconductor plants are already exporting and 88 per cent of India’s crude oil is still imported. The tension is between a widening list of strategic sectors and the fiscal and execution capacity to carry all seven at once.

    What is the Saptadhara framework?

    1. About: Saptadhara is the seven stream articulation of the government’s next phase reform agenda, announced as the organising structure for the Viksit Bharat 2047 goal.
    2. The seven streams: Manufacturing quality, agriculture and food processing, technology and innovation, logistics and connectivity, defence and security, the green and blue economy, and soft power.
    3. Design logic: Each stream pairs a production target with an import substitution objective, rather than a single sectoral subsidy.
    4. Status: The framework is a policy statement of direction, not a notified scheme with its own outlay.

    What is Mission Sudarshan Chakra?

    1. About: Mission Sudarshan Chakra is a multi layered national defence shield combining air defence, ballistic missile defence and aerial offensive capability.
    2. Design features: It integrates artificial intelligence and cyber security components into a single detection and response architecture.
    3. Coverage goal: The stated aim is a nationwide security shield extending to public places by 2035.

    What did the address actually commit to?

    1. Semiconductors: Three plants are already in production and exporting, with five to eight more expected over the next seven to eight years.
    2. Nuclear capacity: A target of 100 GW of nuclear power, against the present operational base of 8.7 GWe from 25 reactors.
    3. Hydrocarbons: 99 per cent of India’s coastline, previously classified as a no go area for exploration, has been opened to upstream oil and gas activity.
    4. Skilling: Artificial intelligence skilling for over one crore youth within a year, delivered in mission mode.
    5. Public examination access: Free online coaching for competitive examination aspirants routed through India’s digital public infrastructure.
    6. Sport: A national talent hunt for ages five to sixteen, tied to the bid to host the 2036 Olympics.

    Why does energy security dominate the economic streams?

    1. Import dependence: India imports over 88 per cent of its crude oil and about half its natural gas.
    2. Chokepoint concentration: Roughly 40 per cent of oil imports, over 50 per cent of gas and 90 per cent of liquefied petroleum gas transit the Strait of Hormuz.
    3. Current disruption: Transit through the Strait has collapsed to a handful of vessels a day, converting a theoretical vulnerability into a live supply shock.
    4. Policy response: The nuclear target and the coastline opening are both framed as reducing exposure to a single maritime corridor.
    5. Critical minerals: Bilateral critical minerals pacts are named as the input security leg of the same strategy.

    What does the reform list leave unresolved?

    1. Sequencing: Seven streams compete for the same administrative bandwidth and the same capital budget, with no stated priority order.
    2. Women’s reservation: The Nari Shakti Vandan Adhiniyam, 2023 was pressed on all parties for implementation, while its rollout stays tied to the completion of the Census and the delimitation exercise that follows.
    3. Employment gap: Skilling targets are stated in numbers trained, not in jobs created or wages earned.
    4. Semiconductor arithmetic: Eight units by 2047 depends on fabrication grade water, uninterrupted power and a materials supply chain that no announcement can compress.
    5. Statistical base: The address urged public participation in the Census, the exercise that itself gates delimitation and the women’s quota.

    Challenges to the Saptadhara agenda

    1. Capital intensity of chips: A single fabrication unit costs several billion dollars and takes three to five years to reach yield. e.g. the Dholera fabrication unit’s phased ramp against its original commissioning date.
    2. Nuclear liability overhang: Supplier liability under the civil nuclear liability framework has deterred foreign vendors for over a decade. e.g. the Jaitapur project’s prolonged commercial negotiation with the French vendor.
    3. Land and water for the green economy: Solar and green hydrogen capacity needs contiguous land and demineralised water in the same arid states. e.g. Kutch and Barmer hosting both renewable parks and acute groundwater stress.
    4. Skilling absorption: Training throughput has historically outrun placement, leaving certified candidates without matching vacancies. e.g. the gap between Skill India certification volumes and reported placement rates.
    5. Blue economy governance: Coastal exploration opening collides with coastal regulation zone protections and fisher livelihoods. e.g. the sustained opposition to hydrocarbon exploration off the Tamil Nadu delta districts.
    6. Import content in exports: Assembly led manufacturing can raise export value without raising domestic value addition. e.g. mobile handset exports rising faster than the domestic component base supplying them.

    Conclusion

    The address converts a scattered set of sectoral pushes into one named framework, which makes the ambition legible but does not resolve which stream gets first claim on capital and administrative attention. Energy security is the binding constraint underneath most of the seven streams, and it is the one the government has least unilateral control over. The next milestone is the movement of the semiconductor units from announcement to commissioning, and of the nuclear target from a headline number into notified private participation rules.

    Manufacturing in India

    1. Sectoral share: Manufacturing contributes roughly 17 per cent of gross value added, against the long standing policy target of 25 per cent.
    2. Policy vehicles: The Production Linked Incentive (PLI) scheme covers 14 sectors, tying disbursement to incremental sales rather than to capital investment alone.
    3. Semiconductor position: India entered fabrication only after the India Semiconductor Mission was approved in 2021, with an initial outlay of Rs 76,000 crore.
    4. Structural weakness: The sector remains capital intensive rather than labour intensive, so output growth has not translated into proportional employment.
    5. Global standing: India is the second largest mobile handset manufacturer by volume, largely through final assembly.

    Government Initiatives

    1. Production Linked Incentive scheme: Pays incentives on incremental sales across 14 sectors, targeting large scale domestic manufacturers and their supply chains.
    2. India Semiconductor Mission: Provides fiscal support for fabrication, display fabrication, assembly and testing units, targeting global and domestic chip makers.
    3. PM GatiShakti National Master Plan: A geographic information system based platform integrating infrastructure ministries’ project planning to cut logistics cost.
    4. National Green Hydrogen Mission: Targets 5 million metric tonnes of annual green hydrogen production capacity by 2030.
    5. National Critical Mineral Mission: Covers exploration, overseas acquisition and recycling of minerals essential to batteries, magnets and semiconductors.

    Way Forward

    1. Publish a sequencing order: State which of the seven streams carries first claim on budgetary support in each year of the framework.
    2. Tie skilling to placement: Report skilling outcomes as verified placements and wage levels, not as enrolment counts.
    3. Deepen component manufacturing: Shift incentive design from assembly output to domestic value addition thresholds.
    4. Resolve nuclear liability: Notify the private participation and liability rules so the 100 GW target has a legal pathway.
    5. Diversify crude sourcing: Expand term contracts outside the Persian Gulf and enlarge strategic petroleum reserve coverage beyond the current few days of imports.

    Matching Previous Year Question

    “[2025, GS3, 15 marks] India aims to become a semiconductor manufacturing hub. What are the challenges faced by the semiconductor industry in India? Mention the salient features of the India Semiconductor Mission.”

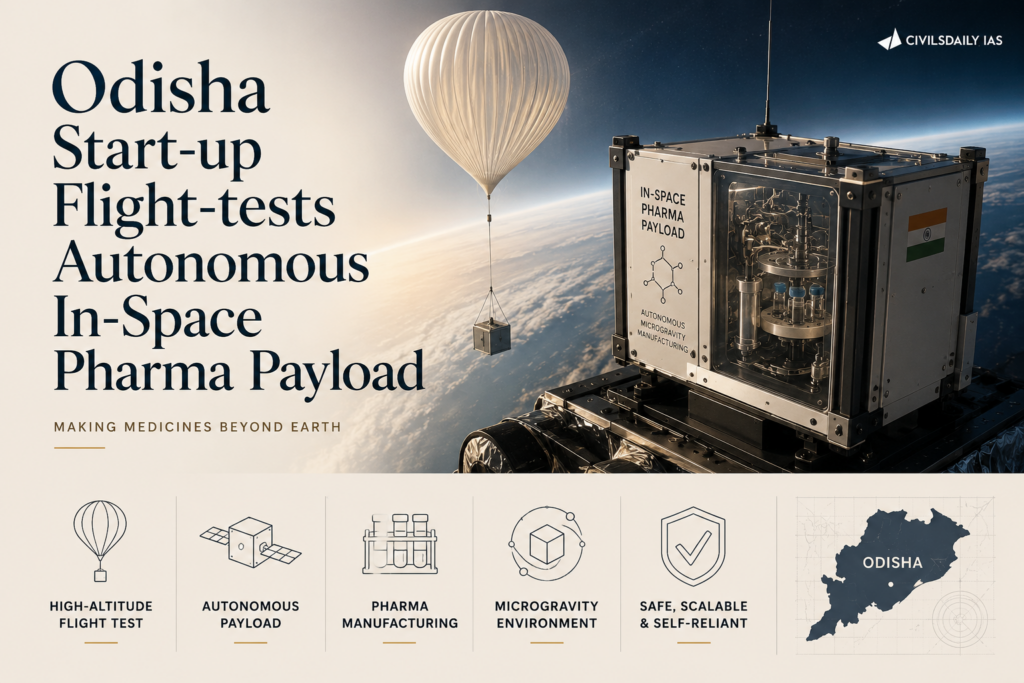
  • Odisha start-up flight-tests an autonomous in-space pharmaceutical manufacturing payload

    Why in the News

    A Bhubaneswar-based start-up, Serendipity Space, has flight-tested a prototype satellite carrying Alchemy, an autonomous pharmaceutical manufacturing payload, using a high-altitude balloon at the TIFR facility in Hyderabad. The technology aims to manufacture pharmaceutical products in microgravity without human supervision.

    How does it work?

    1. Microgravity: Near-weightlessness reduces sedimentation, buoyancy and convection.
    2. Crystal growth: Crystals can form differently and potentially with greater uniformity than on Earth.
    3. Autonomous processing: The satellite carries reagents and hardware and executes the manufacturing sequence independently.
    4. Recovery: Processed material is returned to Earth using a re-entry system and heatshield.

    What is LEO?

    • Low Earth Orbit (LEO) extends roughly up to 2,000 km above Earth.
    • The proposed system is intended for an altitude of about 400 to 500 km.

    What did the balloon test demonstrate?

    • Tested the satellite prototype under near-space conditions.
    • Validated avionics, heatshield and Alchemy payload.
    • Demonstrated autonomous operation.
    • Tested controlled return to Earth.
    • Serves as a relatively low-cost step before orbital deployment.

    How is it different from earlier space-based drug research?

    • Earlier experiments on platforms such as the ISS generally required crew involvement. The distinguishing feature here is a dedicated free-flying satellite designed for autonomous pharmaceutical manufacturing.
    • International examples include Varda Space Industries, Redwire and experiments aboard China’s Tiangong station.

    Why is it important for India?

    • Promotes private-sector space innovation.
    • Expands India’s space ecosystem beyond Bengaluru to cities such as Bhubaneswar, Pune and Ahmedabad.
    • Creates opportunities in pharma, biotechnology, space engineering and advanced manufacturing.
    • Demonstrates potential convergence of space technology + biotechnology + pharmaceuticals.

    Laws, Treaties and Rules Governing Space Activities

    1. Outer Space Treaty, 1967: Bars national appropriation of outer space and makes States internationally responsible for national activities, including those of private entities.
    2. Liability Convention, 1972: Makes the launching State absolutely liable for damage caused on the surface of the Earth or to aircraft in flight.
    3. Registration Convention, 1975: Requires launching States to maintain a registry of objects launched into outer space and to furnish details to the United Nations.
    4. Rescue Agreement, 1968: Obliges States to assist astronauts in distress and to return space objects to the launching State.
    5. Indian Space Policy, 2023: Defines the roles of ISRO, IN-SPACe and NSIL and permits private entities across the full value chain from launch to satellite operations.
    6. Space Activities Bill, 2017: Proposed a licensing and liability framework for private Indian space activity but lapsed without enactment.
    7. Norms, Guidelines and Procedures issued by IN-SPACe: Prescribe the authorisation route, safety requirements and liability sharing for non governmental entities operating from India.
    8. Telecommunications Act, 2023 and allied spectrum rules: Govern satellite spectrum assignment and the licensing of satellite based communication services.

    Indian National Space Promotion and Authorisation Centre

    1. What it is: IN-SPACe is the single window autonomous agency that authorises, promotes and supervises space activities by non governmental entities in India.
    2. Year established: Announced in 2020 as part of the space sector reforms and made operational in 2022.
    3. Parent department: It functions as an autonomous body under the Department of Space.
    4. Headquarters: Ahmedabad, Gujarat.
    5. Jurisdiction: It authorises private launches, satellite establishment and operation, ground station creation and the dissemination of space based data.
    6. Enabling role: It permits private entities to use ISRO facilities and to access ISRO technologies through transfer agreements.
    7. Distinction from NSIL: IN-SPACe regulates and promotes, while NewSpace India Limited is the commercial arm that contracts launches and technology transfers.

    “[2026] Consider the following statements about involvement of private entities in India’s space programme:
    1. IN-SPACe is an autonomous agency formed to facilitate participation of private entities.
    2. Agnikul Cosmos launched the world’s first flight using 3D-printed rocket engine.
    3. Skyroot Aerospace has developed liquid fuel for GSLV.
    (a) 1 only
    (b) 2 and 3 only
    (c) 1 and 2 only
    (d) 1, 2 and 3

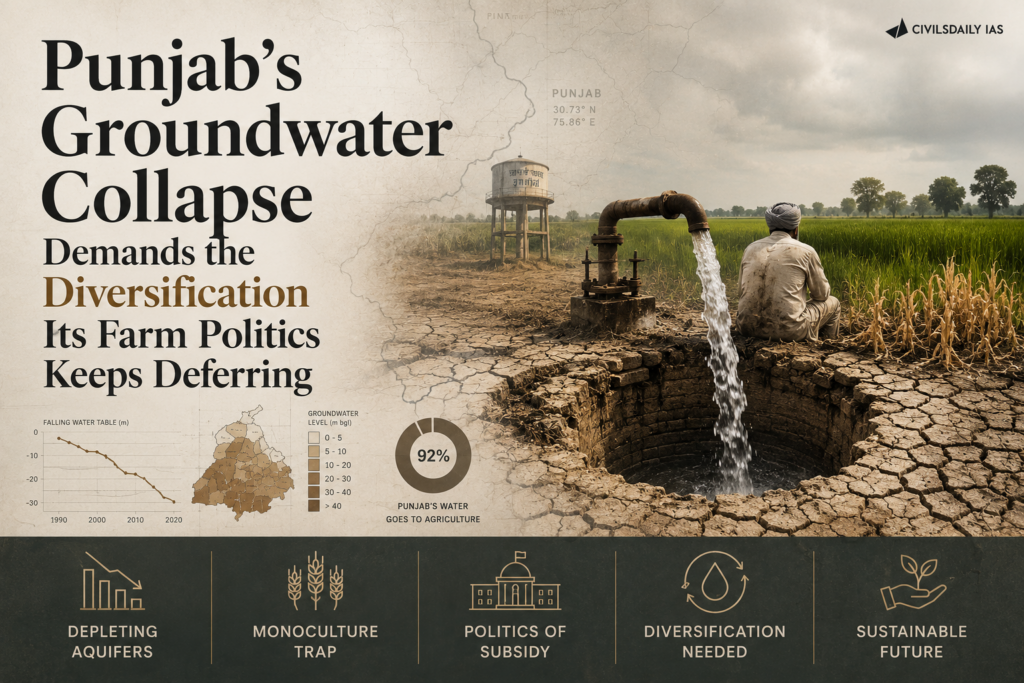
  • Punjab’s groundwater collapse demands the diversification its farm politics keeps deferring

    Why in the News

    The acreage under water intensive paddy in Punjab touched a record high this year, even as the water table continues to fall and experts warn of impending desertification. The State that built its agrarian success on assured irrigation is now consuming the resource that made it possible, while governments across party lines keep supplying free water and power rather than executing the diversification plans already drafted.

    What is crop diversification?

    1. About: Crop diversification is the shift of cropped area away from one or two dominant crops toward a wider mix of crops within the same season or rotation.
    2. How it works: A cultivator replaces part of the area under a water intensive or soil depleting crop with pulses, oilseeds, maize, cotton or horticulture.
    3. Rationale: It reduces the drawdown on a single natural resource and spreads market and weather risk across several crops.
    4. The precondition: It requires an assured market or procurement for the replacement crop, since the displaced crop already has one.

    Who was Ajit Singh?

    1. About: Ajit Singh was a peasant leader of colonial Punjab and the uncle of Bhagat Singh, and one of the main architects of the Pagdi Sambhal Jatta agitation against British agricultural laws.
    2. Exile and return: Hounded by the British, he spent nearly four decades abroad, engaging with revolutionaries including Lala Har Dayal and Subhas Chandra Bose, and was imprisoned in Germany after the Second World War before Jawaharlal Nehru secured his release in early 1947.
    3. Death: He died at Dalhousie at about 3.30 am on 15 August 1947, aged 66, his last words recorded as “Jai Hind”.

    What were the canal colonies of western Punjab?

    1. About: The canal colonies, known locally as the Baar, were settlements created in western Punjab after the British built an extensive canal network in the late nineteenth and early twentieth centuries.
    2. Why they were created: Large parts of western Punjab had remained uncultivated for centuries for want of irrigation, and the canals made cultivation possible for the first time.

    What is a murabba?

    1. About: A murabba is a square land allotment of 25 acres, the standard unit granted to settlers in the canal colonies.
    2. Who received them: Cultivators from what is now Indian Punjab, including retired soldiers, were moved into the colonies and allotted murabbas.

    What is abiana?

    1. About: Abiana is the water charge levied on cultivators for the use of canal irrigation.
    2. Why it mattered: A hike in abiana was one of the three grievances that triggered the 1907 Pagdi Sambhal Jatta agitation.

    What was the Pagdi Sambhal Jatta movement?

    1. About: Pagdi Sambhal Jatta was a peasant agitation of 1907 in colonial Punjab against three British laws that threatened farmers’ rights over their land and raised the water charge.
    2. How it got its name: Lala Banke Dayal’s poem of that title was recited at a rally in Lyallpur in March 1907, giving the movement its name and its anthem.

    What is desertification?

    1. About: Desertification is the degradation of land in dry, semi dry and dry sub humid areas, driven by climatic variation and human activity, until it loses its biological productivity.
    2. How it applies to Punjab: Sustained groundwater extraction beyond the recharge rate turns irrigated land progressively unproductive, which is the process experts have warned of in Punjab.

    What is Vibhajan Vibhishika Smriti Diwas?

    1. About: Vibhajan Vibhishika Smriti Diwas, or Partition Horrors Remembrance Day, is observed on 14 August each year since 2021.
    2. Purpose: It commemorates the displacement and loss suffered during the Partition of 1947.

    How did canal irrigation create Punjab’s agrarian identity?

    1. Arid land before irrigation: Large parts of western Punjab stayed uncultivated for centuries for want of irrigation.
    2. The canal network was the first input: The British built an extensive canal system across the region in the late nineteenth and early twentieth centuries.
    3. Settlers were the second input: Water alone was not enough, so cultivators from what is now Indian Punjab, including retired soldiers, were moved into the new tracts.
    4. Land allotted as murabbas: Each settler household received a murabba of 25 acres in the colonies.
    5. Settlements numbered, not named: New colonies were given administrative numbers such as Chak 8, Chak 20 and Chak 503, often carrying the name of the migrants’ original village, as in Chak 503 Narangwal.
    6. Reclamation took years: The land was arid and took years of sustained work before it turned fertile, which is why its loss at Partition was felt as the loss of built capital.

    What does Punjab’s tradition of agrarian resistance consist of?

    1. The 1907 movement: Ajit Singh led the Pagdi Sambhal Jatta agitation alongside Lala Lajpat Rai against three British laws that threatened farmers’ rights and hiked the water charge or abiana.
    2. Scale of mobilisation: Ajit Singh addressed 19 of the 33 meetings recorded by British intelligence.
    3. The anthem: Lala Banke Dayal’s poem was recited at a rally in Lyallpur in March 1907 and gave the movement its name.
    4. The outcome: The British withdrew the farm laws, and both leaders were imprisoned in Mandalay, Burma.
    5. Recognition: Bal Gangadhar Tilak hailed Ajit Singh as the “king of Punjab peasantry” on his return.
    6. The tradition carried forward: The same slogan was raised during the 2020-21 farmers’ agitation against the since repealed central farm laws.

    Why has the adversary shifted from colonial law to resource depletion?

    1. The threat is now internal: The challenge today is not colonial rule but the depletion of the resource that made Punjab’s agrarian success possible.
    2. Warnings are long standing: Experts have warned of impending desertification in Punjab for years.
    3. The trend is worsening, not stabilising: Acreage under water intensive paddy cultivation touched a record high this year.
    4. The water table keeps falling: The aquifer continues to drop even as extraction expands with every additional paddy season.
    5. The cost is deferred, not avoided: Groundwater does not recharge at the rate at which it is being pumped, so each season transfers the shortfall to a later one.

    Why has a known diagnosis not produced action?

    1. The solutions are already documented: Economist S S Johl outlined diversification measures during the tenure of the previous Congress government in the State.
    2. Later plans exist as well: The current State government has also prepared plans on the water issue.
    3. Implementation is the gap: Execution of both sets of plans remains negligible.
    4. The problem is not knowledge: Punjab knows precisely what has to be done and consistently fails to do it, which makes this an execution failure rather than a policy vacuum.

    Why do free water and assured paddy procurement keep expanding the crop that is emptying the aquifer?

    1. The case for the free provision: Free water and free power for tubewells lower the cash cost of cultivation for a farm sector carrying heavy debt.
    2. The political arithmetic: State governments cutting across party lines have continued the free provision for political reasons, since withdrawing it carries an immediate electoral cost.
    3. Assured procurement completes the lock in: Paddy and wheat carry guaranteed purchase at a minimum support price, and no alternative crop offers comparable certainty.
    4. The other side of the ledger: Free power removes the price signal on extraction, so pumping continues well past the rate at which the aquifer can recharge.
    5. Two legitimate claims in conflict: Farm income security and aquifer survival both carry a genuine claim, and current policy settles the question entirely in favour of the first.
    6. The cost appears nowhere: The support shows up as a power subsidy line in the State budget, while the depletion appears in no account until wells begin to fail.

    Why have farmer unions’ priorities not tracked the water crisis?

    1. Attention directed at trade: Farmer unions have mobilised strongly against free trade agreements.
    2. The nearer threat is unaddressed: The same unions have overlooked aquifer depletion as a looming calamity of comparable scale.
    3. Individual adaptation is happening: Some individual farmers have adopted alternatives to paddy on their own initiative.
    4. Collective adaptation is not: Most cultivators remain caught within an unsustainable farming model that no organised body is challenging.

    What does the stated way forward require?

    1. Reduce paddy dependence: Cut the area under water intensive paddy cultivation.
    2. Guarantee markets for the substitutes: Ensure assured markets for diversified crops so that the switch is not a loss of income.
    3. Invest in micro irrigation: Move field irrigation from flood delivery to drip and sprinkler systems.
    4. Build food processing capacity: Create processing demand that gives non paddy crops a committed buyer.
    5. Align policy with ecology: Set agricultural policy against ecological limits rather than electoral compulsions.

    Challenges to crop diversification in Punjab

    1. Absence of assured procurement for alternative crops: Only paddy and wheat carry guaranteed purchase, so any switch transfers price risk to the farmer. e.g. maize in Punjab routinely selling below its minimum support price for want of a procurement agency.
    2. Free power removes the cost of extraction: Zero marginal cost pumping eliminates any incentive to economise on water. e.g. blocks in Sangrur, Barnala and Moga classified as over exploited by the Central Ground Water Board while tubewell use continues unchecked.
    3. Sunk investment in the paddy and wheat rotation: Farm assets are built around a single cycle and cannot be repurposed. e.g. combine harvesters, paddy transplanters and laser levelled fields configured for that rotation alone.
    4. Labour and machinery calendar locked to paddy: The seasonal labour supply arrives for a specific operation window. e.g. migrant labour arriving in June for transplanting, a cycle no substitute crop matches.
    5. Groundwater regulation limited to sowing dates: Existing law delays transplanting without reducing total irrigated area. e.g. the Punjab Preservation of Subsoil Water Act, 2009, which shifted the transplanting date later but left acreage untouched.
    6. Weak processing and cold chain for horticulture: Perishable substitutes fail without storage and processing capacity nearby. e.g. kinnow growers in Abohar and Fazilka facing distress sales in glut years.
    7. Residue burning tied to the compressed paddy to wheat window: The delayed transplanting date leaves too little time between harvest and the next sowing. e.g. the October and November stubble fires across Sangrur, Bathinda and Patiala every year.

    Conclusion

    Punjab’s crisis is not the absence of a diversification plan but the presence of a policy structure that pays cultivators to keep growing paddy. Free water and power remove the cost of extraction while assured procurement removes the risk of continuing, so a record paddy acreage now coexists with a falling water table and warnings of desertification. Diversification will begin only when an alternative crop carries the same market certainty that paddy already has. Until then the tradition of agrarian resistance will keep facing outward while the aquifer empties.

    Groundwater Irrigation in India

    1. About: Groundwater irrigation is the extraction of water from aquifers through wells and tubewells for crop cultivation, as distinct from surface canal irrigation.
    2. India’s standing: India is the largest user of groundwater in the world, extracting more than the United States and China combined.
    3. Share of irrigation: Groundwater accounts for roughly 60 per cent of irrigated area and about 85 per cent of rural drinking water supply.
    4. The assessment system: The Central Ground Water Board and State agencies jointly assess blocks annually and classify them as safe, semi critical, critical or over exploited.
    5. Regional concentration of stress: Punjab, Haryana, Rajasthan, western Uttar Pradesh and parts of Tamil Nadu carry the highest proportion of over exploited units.
    6. The energy link: Subsidised or free electricity for agricultural pumping is the single largest driver of extraction, since it removes the marginal cost of drawing water.

    Constitutional Framework Governing Water in India

    1. Entry 17, State List, Seventh Schedule: Places water supply, irrigation, canals, drainage, embankments and water storage under State legislative competence.
    2. Entry 56, Union List, Seventh Schedule: Empowers Parliament to regulate inter State rivers and river valleys where it declares such regulation expedient in the public interest.
    3. Article 262: Allows Parliament to provide for adjudication of inter State river water disputes and to bar the jurisdiction of courts in such disputes.
    4. Article 21: Interpreted by the Supreme Court to include the right to clean and adequate water as part of the right to life.
    5. Article 48A: Directs the State to protect and improve the environment, which courts have read as covering groundwater conservation.
    6. Article 243G and the Eleventh Schedule: Assign minor irrigation, water management and watershed development to panchayats.

    Laws and Rules Governing Groundwater Use

    1. Indian Easements Act, 1882: Treats groundwater as attached to land ownership, which is the legal root of unrestricted extraction by landowners.
    2. Environment (Protection) Act, 1986: Provides the authority under which the Central Ground Water Authority was constituted to regulate and control groundwater development.
    3. Water (Prevention and Control of Pollution) Act, 1974: Governs the quality dimension of water resources through the pollution control boards.
    4. Punjab Preservation of Subsoil Water Act, 2009: Bars paddy nursery sowing and transplanting before notified dates, in order to shift the crop’s peak water demand closer to the monsoon.
    5. Model Bill for Conservation, Protection and Regulation of Groundwater, 2016: Circulated to States to establish groundwater as a public trust and to create local level groundwater security plans.
    6. Electricity Act, 2003: Governs agricultural power tariffs and the State subsidy mechanism that determines the cost of pumping.
    7. Guidelines for groundwater extraction, 2020: Prescribe the no objection certificate regime for industrial, infrastructure and mining users of groundwater.

    Back2Basics: Central Ground Water Board

    1. What it is: The Central Ground Water Board (CGWB) is the national apex agency for groundwater assessment, exploration, monitoring and management.
    2. Year established: Constituted in 1970, on the reorganisation of the Exploratory Tubewells Organisation.
    3. Parent ministry: It functions under the Department of Water Resources, River Development and Ganga Rejuvenation, Ministry of Jal Shakti.
    4. Headquarters: Faridabad, Haryana, with regional offices across the country.
    5. Mandate: It develops and disseminates technologies and monitors and implements national policies for the scientific and sustainable development of groundwater.
    6. Key outputs: It publishes the annual Dynamic Ground Water Resource Assessment and the groundwater year book, and it categorises assessment units by stage of extraction.
    7. Regulatory arm: The Central Ground Water Authority, constituted under Section 3(3) of the Environment (Protection) Act, 1986, exercises the regulatory powers over extraction.

    Government Initiatives for Groundwater and Crop Diversification

    1. Atal Bhujal Yojana: A community led groundwater management scheme in water stressed blocks across seven States, with incentives linked to measured improvement in the water table.
    2. Pradhan Mantri Krishi Sinchayee Yojana, Per Drop More Crop: Funds drip and sprinkler micro irrigation to raise water use efficiency at the farm level.
    3. Crop Diversification Programme: Operates in the original Green Revolution States of Punjab, Haryana and western Uttar Pradesh to shift area from paddy to alternative crops.
    4. Pani Bachao Paisa Kamao: A Punjab scheme paying farmers for electricity saved against a benchmark, converting free power into a metered incentive to pump less.
    5. Direct Seeded Rice incentive: A per acre payment in Punjab for sowing paddy directly rather than transplanting into puddled fields, cutting water use substantially.
    6. Jal Shakti Abhiyan, Catch the Rain: A national campaign for rainwater harvesting and recharge structure creation in water stressed districts.
    7. National Food Security Mission and the National Mission on Edible Oils: Support pulses and oilseeds as area substitutes for paddy through seed, input and market interventions.

    Key Facts about Groundwater and Punjab Agriculture

    1. Extraction stage: Punjab has the highest stage of groundwater extraction among Indian States, exceeding the annual recharge by a wide margin.
    2. Over exploited units: A large majority of Punjab’s assessment blocks are classified as over exploited by the Central Ground Water Board.
    3. Tubewell density: Punjab operates well over a million agricultural tubewells, nearly all running on subsidised or free power.
    4. Paddy water requirement: Transplanted paddy consumes several thousand litres of water per kilogram of grain, the highest among Punjab’s field crops.
    5. Procurement share: Punjab and Haryana together account for a dominant share of central wheat procurement and a large share of rice procurement.
    6. Green Revolution origin: Punjab was the first State where high yielding wheat varieties were introduced in the mid 1960s, establishing the wheat and paddy rotation.
    7. The 2009 legal shift: The Punjab Preservation of Subsoil Water Act, 2009 pushed paddy transplanting to mid June to align it with the monsoon onset.

    Challenges in Groundwater Management in India

    1. Legal treatment of groundwater as private property: Ownership attached to land under the Indian Easements Act, 1882 makes extraction limits hard to enforce. e.g. the absence of any cap on the number of tubewells a landowner may sink in most States.
    2. Free or heavily subsidised farm power: Zero marginal cost pumping removes the economic brake on extraction. e.g. Punjab, Haryana and Tamil Nadu supplying agricultural power free or at a nominal flat rate.
    3. Minimum support price incentives skewed to water intensive crops: Assured procurement concentrates in paddy and wheat and pulls area toward them. e.g. paddy area in Punjab reaching a record high in 2026 despite falling water tables.
    4. Weak metering and monitoring of extraction: Without volumetric measurement, regulation cannot be calibrated. e.g. the very small share of agricultural connections in the northern States that carry functioning energy meters.
    5. Aquifer contamination alongside depletion: Falling water tables concentrate geogenic contaminants and draw in poor quality water. e.g. arsenic in the Gangetic plains and fluoride in parts of Rajasthan and Telangana.
    6. Fragmented institutional responsibility: Water is a State subject while the regulatory authority is central, producing overlapping mandates. e.g. Central Ground Water Authority notifications applying to industry while agricultural extraction stays outside their reach.
    7. Poor uptake of micro irrigation: Capital cost and small holding size limit the spread of drip and sprinkler systems. e.g. micro irrigation covering only a small fraction of Punjab’s net sown area despite years of subsidy.

    Way Forward

    1. Extend assured procurement to substitute crops: Guarantee purchase of maize, pulses and oilseeds in Punjab at announced prices so the switch out of paddy carries no income penalty.
    2. Convert free power into a measured entitlement: Scale the Pani Bachao Paisa Kamao model, paying farmers for unused power rather than withdrawing the subsidy outright.
    3. Meter agricultural extraction: Install energy or volumetric meters on tubewells to make regulation and incentive design possible.
    4. Fund micro irrigation at scale: Raise the subsidy and credit support for drip and sprinkler systems to cover small holdings.
    5. Build processing and cold chain capacity: Locate processing units for maize, kinnow, potato and dairy in Punjab to create local demand for diversified output.
    6. Enact a groundwater law based on public trust: Adopt the Model Bill for Conservation, Protection and Regulation of Groundwater so extraction rights derive from a shared resource rather than land title.
    7. Link central assistance to measured water table outcomes: Extend the Atal Bhujal Yojana incentive design, so State transfers respond to verified improvement in the aquifer.

    “[2021, GS3, 15 marks] What are the present challenges before crop diversification? How do emerging technologies provide an opportunity for crop diversification?”

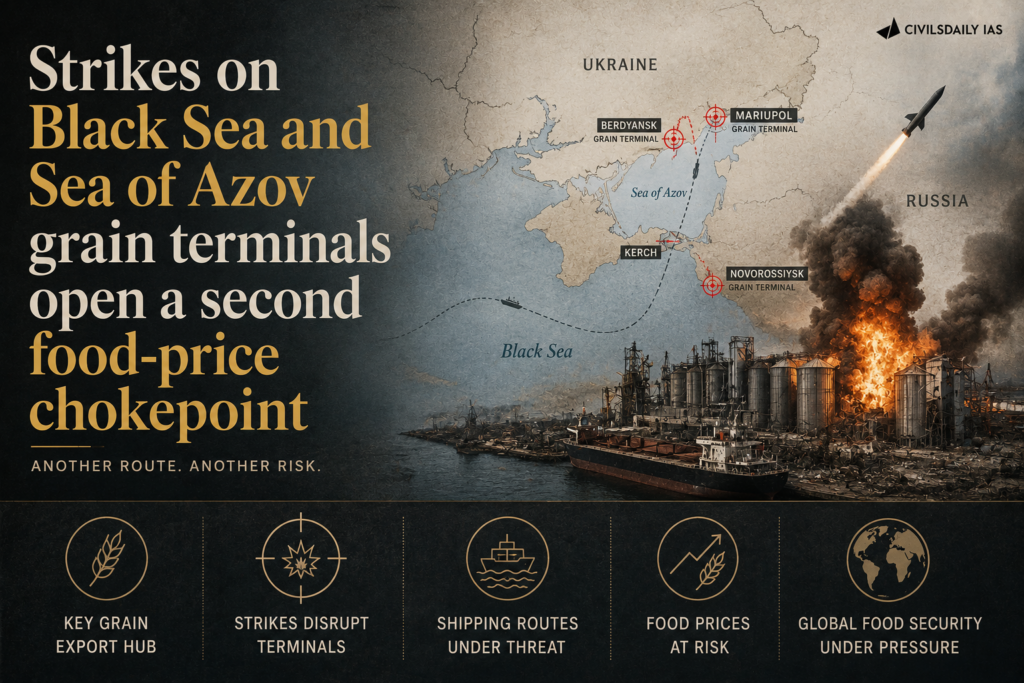
  • Strikes on Black Sea and Sea of Azov grain terminals open a second food-price chokepoint

    Why in the News?

    A Ukrainian drone strike on 11 August destroyed two major grain export terminals at Russia’s Novorossiysk port, removing 15.6 million tonnes (mt) of annual export capacity. This opens a second global trade chokepoint alongside the Strait of Hormuz, shifting the food security crisis from a production problem to a shipping/transit blockade.

    Key Geography & Infrastructure

    • Black Sea & Sea of Azov Grain Corridor: Primary maritime route for Russian and Ukrainian agricultural exports via the Kerch Strait and Turkish Straits.
    • Novorossiysk: Major Russian Black Sea port handling bulk grain shipments.
    • Kerch Strait: The sole, narrow maritime outlet connecting the Sea of Azov to the Black Sea (a classic single point of failure).
    • Greater Odesa Port Complex: Ukraine’s main shipping hub (Odesa, Chornomorsk, Pivdennyi), handling ~90% of its agricultural exports.
    • Izmail: Ukraine’s primary Danube River port, serving as an alternative inland waterway route.

    Regional Dependence & Export Weight

    • Russian Routing: Over 80% of Russian grain exports move through Sea of Azov and Black Sea ports.
    • Ukrainian Routing: The Greater Odesa complex handles about 90% of Ukraine’s agricultural exports.
    • Global Wheat Share: Russia and Ukraine combined account for 27.4% of global wheat exports.
    • Global Sunflower Oil Share: Russia and Ukraine combined supply 61.5% of global sunflower oil shipments, the highest concentration of any commodity.
    • Other Staples: Together they control 15.8% of global barley and 12.5% of global corn shipments.

    Causes of the Global Price Shock

    1. Shipping Bottleneck, Not Output Deficit: Granaries are full in Russia and Ukraine, but cross-border strikes have created severe risk, stopping safe physical transport.
    2. Soaring Insurance Premiums: War risk cover on hulls and cargo acts as a hidden tariff, driving up freight costs and pricing out smaller buyers.
    3. Compounding EU Crop Yield Reductions (USDA Data):
      • Wheat: Projected to drop 7.5% (down to 134.2 mt).
      • Corn: Expected to drop to 50.2 mt (a nearly two-decade low).
      • Cause: Record summer heatwaves and prolonged drought cut yields across Europe.
    4. Global Repricing: CBOT wheat and corn futures rose 4–5% following the strikes. Major alternative exporters (US, Canada, Australia) saw prices surge simultaneously.

    Impact on India & Domestic Policy Measures

    Key Exposures

    • Edible Oil Risk: India is the world’s largest vegetable oil importer and heavily relies on Black Sea sunflower oil.
    • Dual Chokepoint Strain: Simultaneous disruptions in the Strait of Hormuz (energy/fertilizers) and Black Sea/Kerch Strait (food/edible oils).

    Statutory & Policy Framework

    • Essential Commodities Act, 1955: Regulates production, stock limits, and distribution of foodstuffs and edible oils.
    • National Food Security Act (NFSA), 2013: Guarantees subsidized foodgrains to ~two-thirds of India’s population.
    • Foreign Trade (D&R) Act, 1992: Legal framework for export bans, quotas, and Minimum Export Prices (MEP).
    • Customs Tariff Act, 1975: Regulates import duty structures on crude and refined edible oils.
    • Key Interventions: Open Market Sale Scheme (OMSS), Price Stabilisation Fund (PSF), Pradhan Mantri Garib Kalyan Anna Yojana (PMGKAY), and the National Mission on Edible Oils – Oil Palm (NMEO-OP).

    Key Institutional Concepts

    • FAO Food Price Index: A monthly index tracking international market prices of five commodity groups (Cereals, Vegetable Oils, Dairy, Meat, Sugar), weighted by export shares. Hosted by the Food and Agriculture Organization (HQ: Rome, established 1945).
    • Chicago Board of Trade (CBOT): Premier futures exchange establishing global benchmark prices for wheat, corn, and soybeans.
    • USDA WASDE Report: World Agricultural Supply and Demand Estimates; the primary global benchmark for crop yields and trade shares.
    • Maritime Chokepoint: A narrow, strategic passage (e.g., Turkish Straits, Kerch Strait, Strait of Hormuz, Bab el-Mandeb) where high volumes of global trade pass, creating high geographical vulnerability.

    “[2024, GS3, 15 marks] Elucidate the importance of buffer stocks for stabilizing agricultural prices in India. What are the challenges associated with the storage of buffer stock? Discuss.”

    [2014] Turkey is located between

    [A] Black Sea and Caspian Sea

    [B] Black Sea and Mediterranean Sea

    [C] Gulf of Suez and Mediterranean Sea

    [D] Gulf of Aqaba and Dead Sea

  • India contracts 17 lakh tonnes of urea at $390 a tonne, a fraction of the April tender price

    Why in the News?

    India has contracted 17 lakh tonnes (1.7 mt) of imported urea at landed prices of $390.25 to $393.65 per tonne, marking a ~58% drop from the peak rates of $935 to $959 per tonne seen in the April 2026 tender. This sharp collapse highlights how heavily India’s fertiliser subsidy bill depends on external factors, ranging from West Asian energy disruptions to Chinese inventory accumulation.

    Global Urea Import Tender Mechanism

    • Nominated State Agencies: Import tenders are invited by designated state-owned canalising agencies like Rashtriya Chemicals and Fertilizers (RCF) and Indian Potash Limited (IPL).
    • Landed Price (CFR): Offers are quoted on a landed basis—covering both material cost and ocean freight to destination ports. This shifts shipping risk to the supplier.
    • Geographical Distribution: Tenders split required tonnages between the East Coast and West Coast to optimize port discharge and domestic logistics.
    • Market Signals: Bids from multiple global traders (e.g., Ameropa Group) establish the benchmark. High oversubscription indicates a loose global supply market.

    Price Trajectory & Global Supply Dynamics

    1. April Peak ($935–$959/tonne): Driven by peak war risk premiums, high global fuel prices, and Strait of Hormuz shipping anxieties.
    2. May Moderation ($444.9–$449.3/tonne): Easing immediate supply shocks.
    3. July/August Drop ($390.25–$393.65/tonne): Triggered by:
      • China’s Surplus Inventory: Domestic in-plant inventories in China surged 76% year-on-year, turning it into a major swing supplier.
      • Re-routed Supplies: Iranian material reaching markets through China.
      • Alternative Sourcing: Diversification of LNG feedstock by agencies like GAIL and IOC away from Hormuz transit routes toward the US, Oman, Norway, Angola, Congo, Indonesia, and Trinidad.

    Current Supply & Demand Position

    • Adequate Reserves: Imports reached 25.08 lakh tonnes in Q1 (April–June 2026) compared to 8.38 lakh tonnes in the previous year.
    • Domestic Production: Expanded to 71.53 lakh tonnes in Q1 2026.
    • Cropping Seasons Covered: Sufficient availability reported across both the ongoing Kharif (monsoon) season and upcoming Rabi (winter/spring) sowing.

    Challenges in India’s Fertiliser Policy

    • Subsidy Exposure: Urea sells at a statutorily controlled Maximum Retail Price (MRP), meaning any surge in landed cost directly increases the exchequer’s subsidy burden.
    • Nutrient Imbalance: Controlled urea pricing versus decontrolled phosphatic and potassic nutrients encourages over-application of nitrogen (N), skewing the ideal 4:2:1 (N:P:K) ratio.
    • Phosphate Vulnerability: While urea and LNG supply sources have been widened, Di-ammonium Phosphate (DAP) and raw intermediates (phosphoric acid, ammonia, sulphur) remain vulnerable to concentrated import sources and price spikes.
    • Feedstock Dependence: Domestic plants remain tied to imported LNG, linking production costs directly to international gas trends.

    Statutory & Regulatory Framework

    • Essential Commodities Act, 1955: Empowers the Union Government to regulate production, stock limits, supply, and pricing of fertilisers.
    • Fertiliser (Control) Order, 1985 & Movement Control Order, 1973: Governs quality standards, dealer registrations, and inter-state distribution.
    • New Urea Policy, 2015: Promotes energy efficiency in production units and mandates 100% Neem Coating of domestic urea to prevent industrial diversion.
    • Nutrient Based Subsidy (NBS) Scheme, 2010: Provides a fixed annual per-kg subsidy on N, P, K, and S for decontrolled fertilisers (DAP, MOP, Complex).
    • Direct Benefit Transfer (DBT): Releases subsidies to manufacturers only after Aadhaar-authenticated point-of-sale (PoS) transactions at retail outlets.

    Key Government Initiatives

    • PM PRANAM: Encourages States to reduce chemical fertiliser usage by sharing the resulting subsidy savings.
    • One Nation One Fertiliser: Standardises all subsidised crop nutrients under the single Bharat brand.
    • Nano Urea: Liquid alternative developed by IFFCO to lower overall bulk tonnage requirements.
    • Plant Revivals: Reactivation of closed units (Ramagundam, Gorakhpur, Sindri, Barauni, Talcher) to boost domestic capacity.
    • Coal Gasification: Talcher plant designed to produce urea using coal gasification rather than natural gas, cutting gas import reliance.

    Key Concepts

    • Urea: Solid nitrogenous fertiliser (carbamide) carrying 46% Nitrogen—the highest among solid fertilisers.
    • Di-ammonium Phosphate (DAP): Phosphatic fertiliser containing 18% Nitrogen and 46% Phosphorus.
    • Fertiliser Association of India (FAI): Industry body (est. 1955) providing production, import, and consumption stats for supply planning.
    • Muriate of Potash (MOP): Fully import-dependent nutrient; India has no commercial potash reserves.

    [2020] With reference to chemical fertilizers in India, consider the following statements:
    1. At present, the retail price of chemical fertilizers is market-driven and not administered by the Government.
    2. Ammonia, which is an input of urea, is produced from natural gas.
    3. Sulphur, which is a raw material for Phosphoric acid fertilizer, is a by-product of oil refineries.
    Which of the statements given above is/are correct?
    (a) 1 only
    (b) 2 and 3 only
    (c) 2 only
    (d) 1, 2 and 3
    Answer: (b)”