💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Search results for: “”

  • Forex swap rakes in over $136 bn

    Forex swap rakes in over $136 bn

    Why in the News

    Foreign exchange inflows under the Reserve Bank of India’s (RBI) special swap facility have crossed $136 billion, surpassing all projections. The facility was introduced on 8 June this year to deal with forex outflows caused by high oil prices and by the exit of Foreign Portfolio Investors from the stock market. The task has now shifted from raising dollars to managing what they release. Every dollar brought in creates rupee liquidity in the banking system, and the RBI has already begun absorbing it to stop call rates falling below the policy rate.

    What is the RBI’s special USD-INR swap facility?

    1. What it does: The facility lets a bank exchange dollars raised abroad for rupees with the RBI at a concessional rate, with a commitment to reverse the exchange at a future date.
    2. What it covers: It applies to three instruments, Foreign Currency Non-Resident (Bank) or FCNR(B) deposits, Overseas Foreign Currency Borrowings (OFCBs), and External Commercial Borrowings (ECBs).
    3. Why it was opened: It was designed to attract fresh foreign currency at a time when the rupee and India’s reserves were under pressure from oil prices and portfolio outflows.

    Where did the $136 billion come from?

    1. The total mobilised: A total of $1,36,377 million has been mobilised, according to data released by the RBI.
    2. FCNR(B) deposits dominate: Deposits by overseas Indians accounted for $1,27,226 million, the overwhelming share of the mobilisation.
    3. Corporate borrowing contributed little: OFCBs brought in $5,260 million and ECBs a further $3,891 million.

    Why does the RBI’s short forward dollar position matter now?

    1. What a short forward position is: Short forward dollars are currency derivative contracts in which the RBI commits to sell dollars at a future date at a predetermined rate.
    2. Why the RBI built one: The instrument defends the rupee without drawing down spot reserves immediately, so the headline reserve figure holds while the commitment sits in the forward book.
    3. The size of the book: The RBI carries an outstanding short forward position of $137 billion, close to the entire mobilisation under the swap facility.
    4. How the two connect: If the RBI decides not to roll over those positions, it may use the excess reserves generated from the FCNR(B) scheme to deliver the dollars it has contracted to sell.

    What does the inflow do to domestic liquidity?

    1. Rupees enter as dollars arrive: Delivering on the forward book absorbs rupee liquidity from the banking system, which is why the RBI has begun draining it before call rates slip under the policy rate.
    2. The surplus is large: Banking system liquidity stood at Rs 6.5 lakh crore, and the RBI may absorb part of it so short term money supply does not feed into inflation and borrowing costs stay aligned with the policy rate.
    3. Banks gain a cheap funding base: In the immediate term banks are inclined to use the inflow to strengthen their asset side books and cut their dependence on wholesale deposits.
    4. The longer use is credit: Over a longer horizon the same liquidity can be deployed to fund credit growth.

    Conclusion

    The facility has done more than it was designed to do, and the constraint has moved from the external account to the domestic money market. The decision that now matters is whether the central bank rolls its forward commitments over or lets them run off against the deposits it has raised. Rolling over keeps the liquidity in the system; delivering drains it. That choice, and the pace at which it is made, is what will determine short term rates over the coming quarter.

    Back2Basics: External Commercial Borrowings

    1. What they are: ECBs are loans raised by eligible Indian entities from recognised non resident lenders, denominated in foreign currency or in rupees.
    2. Forms they take: They cover bank loans, buyers’ and suppliers’ credit, and instruments such as foreign currency convertible bonds.
    3. How they are regulated: The RBI governs them under the Foreign Exchange Management Act, 1999, through the automatic route up to prescribed limits and the approval route beyond them.
    4. What the framework controls: The rules set the minimum average maturity, the all in cost ceiling and the end uses for which the borrowed money may be applied.

    [2022] With reference to the Indian economy, consider the following statements :

    1. An increase in Nominal Effective Exchange Rate (NEER) indicates the appreciation of rupee.

    2. An increase in the Real Effective Exchange Rate (REER) indicates an improvement in trade competitiveness.

    3. An increasing trend in domestic inflation relative to inflation in other countries is likely to cause an increasing divergence between NEER and REER.

    Which of the above statements are correct ?

    (a) 1 and 2 only

    (b) 2 and 3 only

    (c) 1 and 3 only

    (d) 1, 2 and 3
  • Chinese overcapacity is a problem for the world

    Chinese overcapacity is a problem for the world

    Why in the News

    Chinese manufacturing overcapacity is being framed as a global structural challenge rather than a bilateral trade irritant. China is the world’s largest trade surplus economy, with a surplus valued at $1.2 trillion, and accounts for roughly 30 per cent of global manufacturing output. Cheap Chinese supply lowers input and consumer prices everywhere it lands. The same supply also removes the space in which importing economies would build their own manufacturing capability. What is contested is whether import dependence on the world’s most competitive producer thwarts capability building and upgradation in manufacturing value chains.

    What is Chinese overcapacity?

    1. Capacity built beyond profitable demand: Chinese industry carries production capacity well past what commercial returns justify, sustained by state support rather than by market profitability.
    2. The subsidy and credit mechanism: State backed industrial subsidies and a state directed financial system supplying cheap credit allow firms to expand without being concerned about profits and returns against their international competitors.
    3. How it shows up in prices: Firms operating on razor thin or negative margins run zero sum price wars at home and abroad to expand market share, producing a self defeating race to the bottom.

    How did China build an “absolute advantage” in manufacturing?

    1. The advantage is not price alone: China’s success reflects scale, supplier networks, infrastructure, technological capabilities and state supported industrial ecosystems, not only low cost production.
    2. Breadth of the product range: The same base manufactures textiles, machinery, electronics, solar photovoltaic (solar PV) modules, batteries and electric vehicles (EVs) at competitive prices.

    What does China’s low cost supply give the rest of the world?

    1. Gains accrue to rich and poor economies alike: China’s rise has produced significant economic gains for both developed and developing countries.
    2. Cheaper inputs, not only cheaper consumption: Low cost Chinese goods reduce the prices of consumer goods, machinery, clean technology products and intermediate inputs.
    3. A development effect: Those cheaper inputs support industrial transformation and infrastructure development in developing economies.

    Why does the same cheap supply weaken manufacturing in developing countries?

    1. Asymmetric competitive pressure: Producers in developing countries face difficulty competing with Chinese producers, creating what is termed a “late industrialisation dilemma”.
    2. Upstream capability erodes: The pressure gradually weakens both the incentives and the capabilities to foster domestic upstream industries.
    3. The question is dependence, not efficiency: The issue is not whether Chinese imports are efficient and competitive, but whether import dependence blocks capability building and upgradation in manufacturing value chains.

    How is China’s dominance reshaping global value chains?

    1. Control of critical nodes: In the EV sector China controls 65 per cent of lithium refining, 70 per cent of cobalt refining and over 80 per cent of battery manufacturing.
    2. A position across multiple stages: China occupies a dominant and critical position across multiple stages of manufacturing value chain networks, which is transforming the geography of those networks.
    3. The paradox of dominance: The most competitive supplier in the system is also the source of strategic vulnerability for every country that relies excessively on a single supplier.

    What does Chinese overcapacity mean for India’s self reliance?

    1. Import concentration: China accounts for roughly 17 per cent of India’s imports, with dependence concentrated in solar PV modules, telecom components, electronics and active pharmaceutical ingredients (APIs).
    2. The MSME layer takes the hit: Chinese imports have affected micro, small and medium enterprise (MSME) led domestic manufacturing, undermining India’s manufacturing imperatives.
    3. A component bottleneck: India’s electronics industry faces a shortage of printed circuit boards because of geopolitical headwinds and supply chain impediments, which affects downstream manufacturing.
    4. The pincer dilemma: Chinese export curbs could restrict India’s access to key inputs such as solar wafers, cells and batteries. India’s Production Linked Incentive (PLI) scheme for solar and EVs is at the same time challenged at the World Trade Organization (WTO) for violating local content rules.

    Challenges to rebalancing Chinese overcapacity

    1. No effective multilateral discipline on industrial subsidies: Trade rules reach export and local content subsidies, and reach unreported state support and cheap state bank credit only weakly. Eg. China’s subsidy notifications to the WTO have been repeatedly counter notified as incomplete by the United States, the European Union and Japan.
      The Fix: Negotiate a subsidy transparency code with automatic counter notification, so unreported support carries a rebuttable presumption of injury.
    2. Rebalancing depends on Chinese household demand, which stays weak: Household consumption remains under 40 per cent of Chinese output, so domestic absorption cannot take the place of exports. Eg. The property sector downturn after 2021 cut household wealth and pushed precautionary saving higher.
      The Fix: Tie any coordinated adjustment to verifiable social security and household income targets rather than to currency movement alone.
    3. Tariffs shift trade rather than retire capacity: Duties raise the price of arriving goods and leave the surplus plants that produced them in operation. Eg. Duties on Chinese solar cells were followed by assembly routed through Southeast Asia, later covered by circumvention findings.
      The Fix: Pair every trade remedy with rules of origin and value addition thresholds, so relief is not defeated by transshipment.
    4. Alternative suppliers do not exist at the required scale: Refining and processing capacity outside China takes years to build even where the ore is available. Eg. Indonesia’s nickel processing expansion was itself built largely with Chinese capital and technology.
      The Fix: Fund refining and processing capacity through pooled offtake guarantees among importing countries rather than through single country subsidies.
    5. No forum acts on the surplus itself: Existing instruments discipline individual programmes and individual shipments, not aggregate industrial capacity. Eg. WTO subsidy disputes are brought against named schemes one at a time.
      The Fix: Open a global dialogue on gradually rebalancing the Chinese economy in partnership with the United States and other major economies, on the pattern of the 1985 Plaza Accord.

    Conclusion

    The argument over Chinese overcapacity is not an argument about efficiency. Cheap supply and domestic capability building pull against each other, and no importing economy has yet found a way to hold both. The unresolved question is whether a surplus economy will accept an adjustment that no external rule obliges it to accept.

    What is Global Trade Governance?

    1. About: Global trade governance is the body of rules framing trade between nations, administered mainly through the World Trade Organization, founded in 1995 as successor to the General Agreement on Tariffs and Trade (GATT).
    2. Membership: The WTO has 166 members covering over 98 per cent of world trade.
    3. Rationale: The system exists to make market access predictable and to lower barriers. Average industrial tariffs fell from around 40 per cent in 1947 to about 4 per cent today.
    4. Core principles: Most Favoured Nation treatment requires favourable terms offered to one member to extend to all, and National Treatment bars discrimination against imported goods once they enter a market.

    Laws and Rules Governing Global Trade Governance

    1. Agreement on Subsidies and Countervailing Measures, 1995: Classifies subsidies and permits an affected member to impose countervailing duties where a subsidised import causes injury.
    2. Agreement on Trade Related Investment Measures, 1995: Prohibits investment conditions that discriminate against imports, including local content requirements.
    3. Customs Tariff Act, 1975: Sections 9 and 9A give India its statutory power to levy countervailing and anti dumping duties.
    4. Foreign Trade (Development and Regulation) Act, 1992: Provides the legal basis for India’s import and export policy and for the Director General of Foreign Trade.

    Challenges in Global Trade Governance

    1. The dispute settlement tier is paralysed: Appeals cannot be heard, so a losing member can appeal into a void and avoid compliance. Eg. The Appellate Body has been non functional since December 2019 after appointments were blocked.
      The Fix: Restore an automatic and binding two tier dispute settlement system with appointments delinked from any single member’s consent.
    2. Unilateral measures bypass the rulebook: Members increasingly act outside the agreed remedy process, which removes the predictability the system was built to supply. Eg. Sweeping reciprocal tariffs imposed in 2025 were applied without recourse to WTO procedures.
      The Fix: Strengthen the organisation’s standing to act against politically motivated tariff action rather than leaving each dispute to bilateral settlement.
    3. The negotiating function has stalled: Multilateral talks have produced little since 2008, so the rulebook does not cover the trade that has grown since. Eg. The 2026 ministerial conference closed without an overall declaration and the electronic commerce duty moratorium lapsed.
      The Fix: Modernise the rules to cover electronic commerce, digital trade and cross border data flows, and consider majority voting for defined categories of agreement.

    Back2Basics: Plaza Accord

    1. What it was: An agreement reached in 1985 among the United States, Japan, West Germany, France and the United Kingdom to act jointly on exchange rates.
    2. What it did: The five agreed to intervene in currency markets to depreciate the US dollar against the Japanese yen and the Deutsche Mark.
    3. Why it is cited: It remains the standard example of major economies coordinating to correct a large trade imbalance rather than each acting through tariffs.

    “[2025, GS3, 10 marks] What are the challenges before the Indian economy when the world is moving away from free trade and multilateralism to protectionism and bilateralism? How can these challenges be met?”

  • Progress review of Prime Minister Dhan Dhaanya Krishi Yojana

    Progress review of Prime Minister Dhan Dhaanya Krishi Yojana

    Why in News

    The Union Minister of Agriculture and Farmers Welfare reviewed the implementation progress of the Prime Minister Dhan Dhaanya Krishi Yojana (PMDDKY).

    Core facts

    1. What it is: PMDDKY is a district focused agriculture development scheme. It converges existing schemes to raise farm productivity in India’s weakest performing agricultural districts.
    2. Implementing ministry: Ministry of Agriculture and Farmers Welfare is the nodal ministry. Multiple line departments contribute converged schemes.
    3. Coverage: The scheme targets 100 districts. Districts are selected on three parameters. The parameters are low agricultural productivity, low cropping intensity, and low credit disbursement.
    4. Convergence design: The scheme pools 36 existing schemes across 11 departments. It layers these on a single district plan rather than creating a new fund line.
    5. Release specific review figures: The specific progress numbers, district status, and targets reported in PRID 2305501 could not be verified from PIB this run. They are not reproduced here.

    Static Context

    1. Origin: The scheme was announced in the Union Budget 2025 to 2026. The Union Cabinet approved it in July 2025.
    2. Duration: The scheme runs for 6 years from 2025 to 2026.
    3. Model: The scheme is modelled on the Aspirational Districts Programme. That programme uses ranking, convergence, and competitive monitoring to lift the weakest districts.
    4. Focus areas: The scheme covers productivity, crop diversification, sustainable agriculture, irrigation and water conservation, post harvest storage at panchayat and block level, and farm credit.
    5. Monitoring: District, State, and National level committees oversee the scheme. NITI Aayog and assigned Central Nodal Officers support monitoring.

    Prelims angle

    1. Number of districts covered: 100 districts.
    2. Selection parameters: low productivity, low cropping intensity, low credit disbursement.
    3. Number of converged schemes: 36 schemes across 11 departments.
    4. Parent design model: Aspirational Districts Programme.
    5. Nodal ministry: Ministry of Agriculture and Farmers Welfare.

    Mains angle

    GS3, agriculture theme (major crops, cropping patterns, agricultural productivity, and scheme convergence). A question can ask how a convergence and district targeting model raises productivity in low performing agricultural districts. It can also ask how crop diversification and integrated farming raise small farmer incomes.

    “[2022, GS3, 15] What is Integrated Farming System ? How is it helpful to small and marginal farmers in India ?”

    “[2025, GS3, 10] Explain the factors influencing the decision of the farmers on the selection of high value crops in India.”

  • China, US are in race to connect science with industry. India must catch up [Express]

    China, US are in race to connect science with industry. India must catch up [Express]

    Mentor Comment

    Beijing’s second World Humanoid Games has showcased a Chinese project to become the world’s leading science power, rooted in the Chinese President’s call to mobilise “new quality productive forces” released by the current revolutions in science and technology. The US administration has released Science: A New Golden Age, billed as the first major reset in US science policy since World War II, aimed at reintegrating discovery with production. Both powers are building an ecosystem that connects science with industry, from opposite starting points. India has launched missions on artificial intelligence (AI), semiconductor production and quantum technologies, but its private capital has retreated from science and its state-led scientific institutions remain unreformed.

    How are China and the United States racing toward the same goal from opposite directions?

    1. China’s break with the old growth model: The Chinese President holds that the next phase of growth cannot rely on cheap labour, large-scale manufacturing, infrastructure and capital accumulation, and must come from innovation.
    2. AI diffused across the physical economy: Beijing’s objective is to diffuse AI across robotics, machine tools, automobiles, biotechnology, materials, energy, agriculture and scientific research.
      • It bets that fusing digital intelligence with the world’s largest industrial ecosystem will make China the leading technological power.
    3. From adaptation to original discovery: For decades China absorbed foreign technology, improved it through manufacturing and dominated production. It now wants to move upstream to original discovery.
    4. China’s spending signal: China spent 2.8 per cent of GDP on research and development (R&D) in 2025, and its basic-research expenditure rose by 11 per cent.
    5. China’s four-step logic: AI accelerates discovery; discovery produces technology; technology transforms industry; industrial strength generates national power and a geopolitical edge.
    6. The US reset names its own weakness: Science: A New Golden Age, released in July, recognises American strengths in universities, laboratories, technology companies and capital markets. It acknowledges the erosion of the capacity to turn discoveries into production.
    7. How globalisation split US innovation from manufacturing: Companies designed at home, produced abroad and depended on long supply chains. That model generated wealth and also the vulnerabilities exposed by the pandemic, China’s rise and geopolitical rivalry.
    8. Mirror-image fears: China begins with the largest manufacturing base and moves upstream into science. The US begins with the strongest scientific system and moves downstream into manufacturing. China fears dependence on American technology; the US fears dependence on Chinese production.

    What does “connecting science with industry” actually mean in this contest?

    1. AI as an accelerator of knowledge, not a product: Washington and Beijing see AI not merely as a general-purpose technology but as an accelerator central to the production of new knowledge that in turn transforms industry.
    2. Discovery made continuous with manufacturing: By making discovery continuous with design and manufacturing, AI-driven science transforms production itself and converts scientific speed into economic power and geopolitical capability.
    3. The ecosystem, not the model, is the prize: The contest is not about who unveils the cleverest AI model or the most sophisticated humanoid. It is about building the most effective ecosystem connecting universities, laboratories, entrepreneurs, finance, energy, factories, supply chains and markets.

    Where does India stand as the race intensifies?

    1. Missions exist on paper: Delhi recognises the trend and has launched missions on AI, semiconductor production and quantum technologies, and has a draft robotics policy.
    2. The spending gap: The Economic Survey 2025-26 puts India’s R&D expenditure at 0.64 per cent of GDP, against about 2.8 per cent for China and 3.5 per cent for the US.
    3. The absolute gap is wider: The World Intellectual Property Organisation estimates India’s total R&D spend at $75 billion in purchasing-power-adjusted dollars, against $786 billion for China and $782 billion for the United States. In nominal dollar terms India looks even smaller.

    Why does the first weakness, the retreat of private capital from science, matter most?

    1. Ambition lives in government declarations: Ambition and imagination are concentrated in government declarations at a time when the private sector contributes more than ever to producing knowledge in the US and China.
    2. Indian capital has no science project: Indian capital rarely articulates a project for mastering the new forces of production or a new project for science and basic research.
    3. It was not always so: Jamsetji Tata helped create the Indian Institute of Science in 1909. The Kirloskars and other western Indian business families sent their children to the Massachusetts Institute of Technology from the 1920s, recognising that independent India’s future lay in mastering modern science.
    4. Private philanthropy built the strategic programmes: The Sir Dorabji Tata Trust supported Homi Bhabha in establishing the Tata Institute of Fundamental Research, which formed the nucleus of India’s atomic energy and space programmes. Indian capital has retreated from that tradition.

    Why does the second weakness, unreformed scientific institutions, compound the first?

    1. No overhaul in India’s reform era: China’s reform era, launched in the late 1970s under Deng Xiaoping, put the revitalisation of science and technology at the heart of the Four Modernisations. India’s reform era, beginning in the 1990s, produced no comparable overhaul.
    2. Same American training, different follow-through: India and China both benefited from access to American universities that trained their vast talent pools. China combined that opportunity with massive domestic investment in science and higher education and incentives for researchers to return.
    3. India does not draw talent back: India’s science sector fails to attract its trained talent home, and the shortfall is severe rather than marginal.

    Can “technological sovereignty” be built without global science?

    1. Bureaucratisation, then cultural nationalism: The Congress era saw the steady bureaucratisation of Indian science, and the BJP era is adding cultural nationalism to it.
    2. Mythology is not evidence: Civilisational pride cannot make mythology a substitute for evidence, experiment and scientific temper. India’s most confident claim should be that the greatest Indian contributions lie in the future, not that all modern science was discovered in its past.
    3. The cost of talking tall, once before: Delhi’s radical posturing on technological “self-reliance” in the 1970s and 1980s isolated India from global technological advances. Today there is grandiose talk of “technological sovereignty”.
    4. Two tracks at once: India must deepen cooperation with global science, capital, technology and talent, and at the same time build domestic research, industrial and institutional capacity. Neither track substitutes for the other.

    Challenges to India’s science-industry linkage

    1. Research sits outside the universities that supply the workforce: Most public research is done in mission agencies and Council of Scientific and Industrial Research (CSIR) laboratories, so graduates and firms rarely meet discovery where it happens. Eg. The Defence Research and Development Organisation, the Indian Space Research Organisation, the Department of Atomic Energy and CSIR absorb the bulk of central research spending, and State universities receive a marginal share.
      The Fix: Route Anusandhan National Research Foundation grants preferentially to State universities with mandatory industry co-investment.
    2. Industry does not fund its own research: The private sector contributes 36 per cent of India’s gross R&D expenditure, against 77 per cent in China and 79 per cent in the US and Japan. Eg. The weighted tax deduction on in-house R&D under Section 35(2AB) of the Income Tax Act, 1961 was cut from 200 per cent to 100 per cent from 2020-21, removing the one fiscal incentive firms used.
      The Fix: Restore a weighted deduction tied to patents filed and products commercialised rather than to spending alone.
    3. Deep technology has no patient capital: Venture funds back consumer applications that return within five years, not fabs or materials that need fifteen. Eg. Micron’s assembly and test plant at Sanand, approved in 2023, needed roughly 70 per cent of its project cost as central and Gujarat subsidy before private capital moved.
      The Fix: Deploy the Research Development and Innovation scheme corpus as long tenure, low interest loans and fund-of-funds equity for private deep technology projects.
    4. Public procurement does not buy the first unit: Government buyers demand a track record, so an Indian prototype finds no first customer and licenses abroad. Eg. The United States’ Small Business Innovation Research programme reserves a fixed share of federal agency R&D budgets for small firms’ first contracts, and India has no equivalent set-aside.
      The Fix: Add a first-buyer set-aside in the General Financial Rules for Indian deep technology products validated by a designated national laboratory.

    Conclusion

    The contest India has to enter is an ecosystem contest, and an ecosystem cannot be declared into existence by a mission document. Two things remain unreconciled: a state-led science system that has never been restructured, and a private sector that has stopped funding discovery. Whether Indian capital returns to the tradition that built the Indian Institute of Science and the Tata Institute of Fundamental Research is the marker to watch, and the disbursal of the new research finance corpus to private laboratories is where it will first show.

    About India’s Research and Innovation Ecosystem

    1. What the ecosystem measures: Gross expenditure on R&D (GERD) counts spending by government, industry and higher education on basic research, applied research and experimental development.
    2. Who does the research: Central agencies dominate, with a small set of premier institutes such as the Indian Institutes of Technology, the Indian Institute of Science and the National Institute of Immunology providing the academic base.
    3. Global standing: India ranked 39th of 133 economies in the World Intellectual Property Organisation’s Global Innovation Index 2024, first among lower middle income economies.

    Laws and Rules Governing India’s Research and Innovation Ecosystem

    1. Anusandhan National Research Foundation Act, 2023: Creates an apex body to seed, grow and promote research in universities and laboratories, with a planned Rs 50,000 crore over 2023-28 of which Rs 36,000 crore is to come from non-government sources.
    2. The Act repealed the Science and Engineering Research Board Act, 2008 and subsumed that board into the new foundation.
    3. Patents Act, 1970: Governs the grant and enforcement of patents; the 2005 amendment introduced product patents in pharmaceuticals, chemicals and food to comply with the World Trade Organisation’s TRIPS agreement.

    Government Initiatives for India’s Research and Innovation Ecosystem

    1. Research Development and Innovation scheme: Approved by the Union Cabinet in July 2025 with a Rs 1 lakh crore corpus to finance private sector research in sunrise sectors through long tenure, low or nil interest loans and equity.
    2. IndiaAI Mission: Launched in 2024 by the Ministry of Electronics and Information Technology, anchored in shared compute of 38,000-plus GPUs, the AI Kosh open dataset platform, and 570 FutureSkills and AI Labs in Tier 2 and Tier 3 cities.
    3. National Quantum Mission: Launched in April 2023 with an outlay of Rs 6,003 crore for 2023-31, building four Thematic Quantum Technology Hubs in computing, communication, sensing and metrology, and materials and devices.
    4. India Semiconductor Mission: Approved in December 2021 with a Rs 76,000 crore outlay to subsidise fabrication, display and assembly plants and to fund chip design startups.
    5. VAIBHAV Fellowship: Launched in 2023 by the Department of Science and Technology to bring diaspora scientists to Indian institutions for collaborative research stints.

    Key Facts about India’s Research and Innovation Ecosystem

    1. National Science Day, 28 February: Marks the announcement of the Raman effect in 1928.
    2. National Technology Day, 11 May: Marks the Pokhran-II nuclear tests of 1998 and the first flight of the indigenous Hansa aircraft the same day.

    Back2Basics

    1. What they were: China’s programme to modernise agriculture, industry, national defence, and science and technology.
    2. When adopted: First articulated by Premier Zhou Enlai in 1963 and again in 1975, and made the centrepiece of the reform era at the Third Plenum of December 1978.
    3. Why science was listed: Science and technology was named as the modernisation that enabled the other three, which is why the reform era began by rehabilitating scientists and reopening universities to competitive entrance examinations.

    [2019, GS3, 10 marks] How was India benefited from the contributions of Sir M.Visvesvaraya and Dr. M. S. Swaminathan in the fields of water engineering and agricultural science respectively?”

  • Why risk-monitoring in the Himalayas is like looking for ‘needles in haystacks’

    Why risk-monitoring in the Himalayas is like looking for ‘needles in haystacks’

    Why in the News

    A Senior Fellow of the Energy, Water and Sustainability Program at the Stimson Center, a US based non-profit think tank, has set out the sequence of the recent Nepal flood and the lessons it holds for hazard monitoring across the Himalayas.

    What triggered the Nepal flood, and why is the trigger still uncertain?

    1. A glacial detachment carrying bedrock: The present consensus is that the initial trigger was a glacial detachment that included bedrock on the northern slopes of Langtang Lirung, a 7,000-plus-metre peak in the Langtang range.
    2. The triggering process is not understood: The failure could be related to climate-related risks or to gradual shifts at the site itself.
    3. A slow creep, then a tipping point: Preliminary analysis indicates minor movement of the glacial mass in the weeks or months before the event, followed by a tipping point.

    How did a single glacial failure cascade more than 100 kilometres downstream?

    1. The descent: The failed mass swept down a gully toward the Lhende River, which reaches the Chinese border. The source area was around 5,200 metres, so the flow descended a couple of thousand metres.
    2. A temporary natural dam: The flow deposited a mixture of ice, rock and sediment that blocked the river.
    3. Three contested water sources: Debate continues on how much water came from the glacier itself, from melting of entrained ice, and from water that accumulated behind the landslide dam.
    4. Nine minutes to the border: The dam failed and sent a major pulse of water downstream, which reached the China border in roughly nine minutes. Footage from the Gyirong border facility shows a massive dark wave carrying a large volume of material, not just water.
    5. Back into Nepal within seconds: The border facility sat at a confluence with the Gyirong River tributary, and within seconds of hitting it the flow was already moving back into Nepal. There was no realistic opportunity to warn communities downstream, and many of those who could have generated an alert were themselves swept away.
    6. Dams, hydropower and villages: The flow destroyed dams and hydropower projects downstream, recruited additional sediment, and swept through villages along the river corridor.
    7. Beyond every mapped floodplain: The event continued into Nuwakot district and affected larger market towns in the floodplain, in areas well beyond the 100-year or 500-year floodplain (the extent a flood of that average recurrence interval is expected to reach). This was a thousand-year-plus flood event.
    8. Registered at the India-Nepal border: Significant impacts extended more than 100 kilometres downstream, and the flood pulse also registered at the India-Nepal border.

    Why are cascading hazard chains the larger Himalayan problem?

    1. A pattern across three countries: The same chain has appeared in Chamoli, in Sikkim with the South Lhonak GLOF (glacial lake outburst flood), and in Nepal with the Melamchi disaster.
    2. Climate risk as an amplifier: Climate risks are interacting with and amplifying other disaster risks, and these events are becoming more frequent and more intense.

    Why does hazard monitoring keep missing the sites that fail?

    1. Known high-risk sites exist, and this was not one: Several places around Nepal have been identified as high-risk areas for glacial detachment and surges, and glaciers immediately on the other side of Langtang Lirung are high-priority research sites. This particular location had no red flags.
    2. Hindsight still needs a target: Analysts are examining whether changes could have been detected in the days before the event, but that would still require knowing where to look.
    3. No signal to separate from noise: Monitoring every glacier and every mountainside that could collapse is not feasible without some signal that narrows the search.
    4. Satellites answer only the question they were pointed at: Remote sensing and satellite-based analysis are important, but different satellite tools answer different questions, and each needs a target. Engaging local communities is how the target is found.
    5. Almost every event came from an unknown place: Of over a dozen extreme events in the Himalayas over 10 years, almost all came from unknown places, the South Lhonak GLOF being the one known risk.
    6. No borrowed training data: Patterns are beginning to emerge, but no training dataset from the Alps or Norway can simply be transferred to the Himalayas, which have their own context and significant data scarcity and data sparsity.

    What monitoring triangle does the interview propose for India, Nepal and the Himalayas?

    1. Mapping is the baseline: The mapping exercise undertaken by India’s Home Ministry and space agencies to monitor glacial lakes and hazards is an absolute necessity. Nepal does not have the same level of resources. Some mapping has been done there, and it is not as comprehensive.
    2. Maps enable zoning; monitoring is the key: Once maps exist, hazard zoning and modelling can begin, but detection depends on continuous monitoring.
    3. Corner one, remote sensing: Remote sensing and satellite imagery form one part of the triangle.
    4. Corner two, fixed station networks: Hydromet (hydrological and meteorological) and seismic stations form the second.
    5. Corner three, localised monitoring through local government: Local governments, disaster managers and Community Disaster Management Committees can collect local data, report landslides and monitor impacts after storms.
    6. Localised monitoring through people immersed in the terrain: Yak herders and fishermen notice changes in rivers, glaciers and glacial lakes. Oral histories with elders reveal smaller avalanches, glacial-lake floods and other events that science has not recorded, helping identify potential hotspots.
    7. The combination is the detector: Combining the station network, remote sensing and localised monitoring gives a better chance of detecting changes and distinguishing the signal from the noise that tells you where to look.

    Challenges to Himalayan hazard monitoring

    1. Hydropower sited in hazard corridors without upstream sensing: Projects sit in narrow gorges below unstable ice and rock with no instrument between the source and the intake. Eg. The February 2021 Chamoli rock and ice avalanche from Ronti peak destroyed the Rishiganga and Tapovan-Vishnugad projects with no upstream warning.
      The Fix: Make a hazard chain assessment and ridge line sensors with satellite telemetry a condition of clearance for every Himalayan hydropower project.
    2. Instruments die with the event they are meant to detect: A sensor placed at the lake or in the channel is destroyed by the first surge and reports nothing. Eg. Monitoring equipment installed at South Lhonak lake in September 2023 was washed away in the October 2023 outburst that also breached the Teesta III dam at Chungthang.
      The Fix: Place redundant stations on high ground and at staggered distances downstream so at least one survives to trigger sirens.
    3. Cross-border flows carry no shared alert: The upstream country holds the first minutes of warning and no protocol obliges it to pass them on. Eg. India’s hydrological data sharing arrangement with China on the Brahmaputra lapsed in 2023.
      The Fix: Adopt a Hindu Kush Himalaya alert protocol through the International Centre for Integrated Mountain Development (ICIMOD) that pushes automatic upstream alerts to downstream disaster authorities within minutes.
    4. Warnings that never reach the last mile: A satellite detection is useless to a village asleep in a gorge with no siren and no signal. Eg. The Sikkim outburst struck after 10 pm on 3 October 2023 and reached the Teesta valley settlements in the dark.
      The Fix: Pair the National Disaster Management Authority’s Common Alerting Protocol based cell broadcast with battery-backed community sirens in every mapped downstream settlement.

    Conclusion

    India has the baseline map; Nepal has part of one. Neither has the monitoring triangle that turns a map into a warning. The unresolved gap is that detection still depends on knowing where to look, and the herders, fishermen and village committees who hold that knowledge are not yet wired into any station network. The test of the next monsoon is whether a single high mountain site with no red flag gets watched because a community reported it first.

    Back2Basics

    1. What it is: A sudden release of water from a lake formed by melting glaciers, held back by a natural dam of loose moraine debris or ice rather than bedrock.
    2. How it starts: An avalanche, rockfall or ice calving into the lake sends a displacement wave over the dam, or seepage erodes the moraine from within until it collapses.
    3. Why it is deadlier than a rain flood: The surge carries rock and sediment, arrives with minutes of warning, and can breach infrastructure far below the lake.
    4. India’s framework: The National Disaster Management Authority issued dedicated guidelines on GLOF and Landslide Lake Outburst Flood management in 2020.

    [2021, GS1, 15 marks] How does the melting of the Arctic ice and glaciers of the Antarctic differently affect the weather patterns and human activities on the Earth? Explain. (250 words)

  • Solution for stubble burning lies close to the farm

    Solution for stubble burning lies close to the farm

    Why in the News


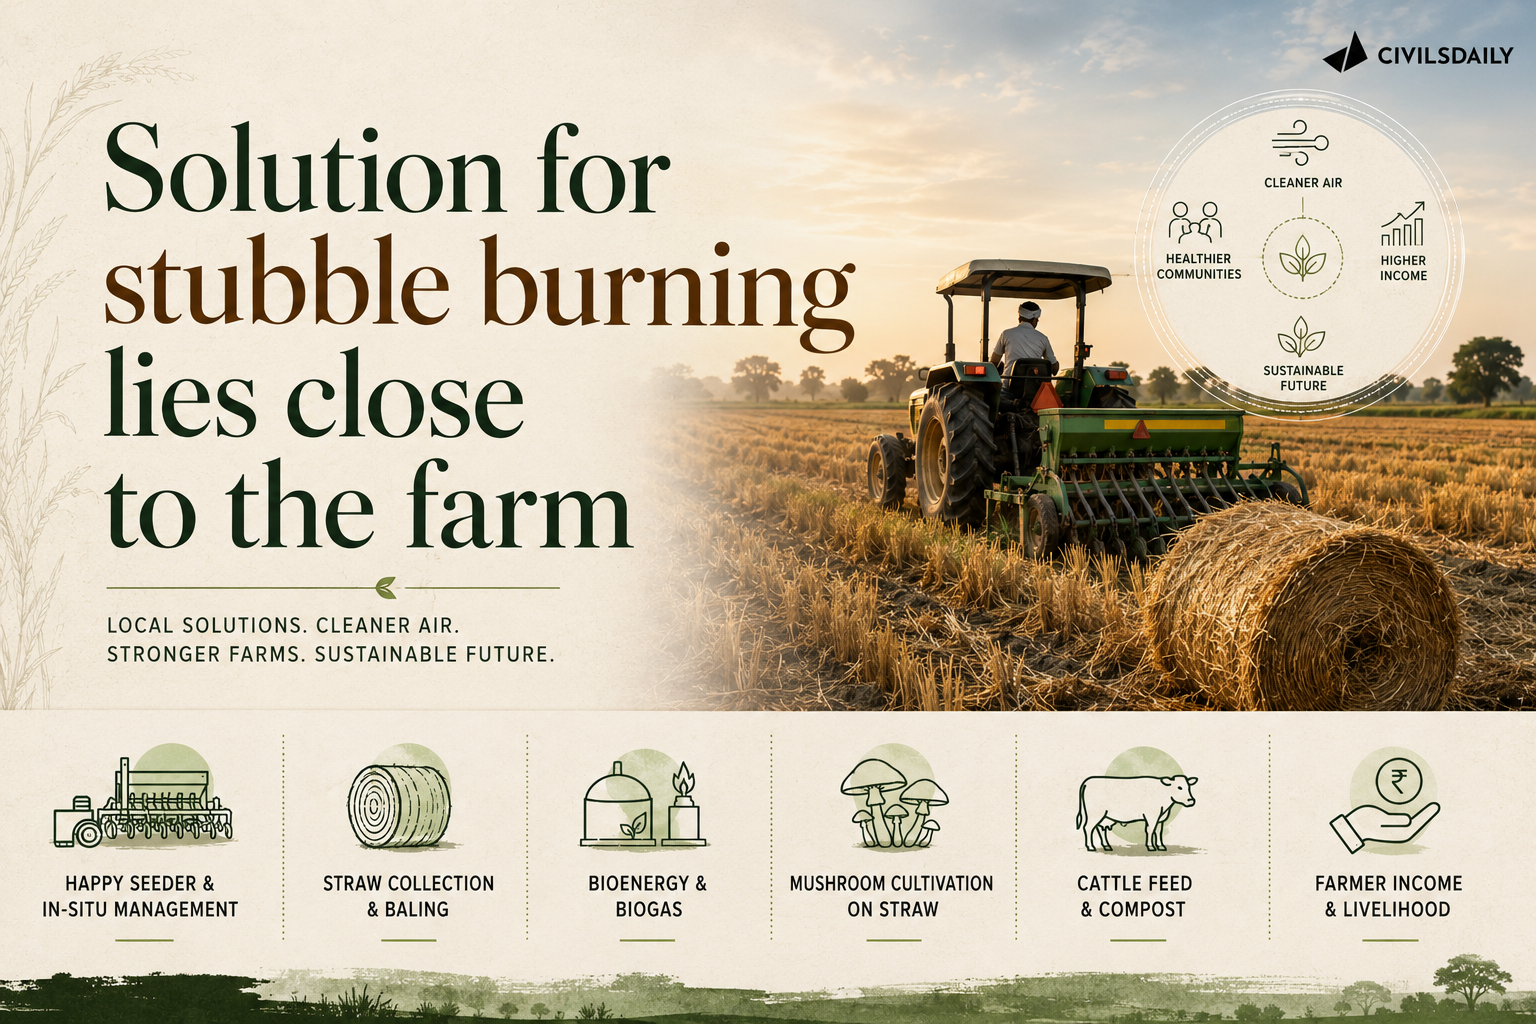
    Punjab’s paddy harvesting season is approaching, reviving Delhi’s air-pollution concerns. The focus is shifting from banning stubble burning to creating profitable markets for parali and increasing farmers’ income.

    What is biochar?

    1. Definition: Biochar is a carbon-rich material produced by heating biomass under limited oxygen, so the carbon is retained as char rather than burnt away.
    2. Feedstock: It can be made from crop residues such as paddy, maize, cotton and mustard stalks.
    3. Yield: Roughly 100 kg of dry parali yields around 30 kg of char.
    4. Use in soil: Applied to soil, it improves water retention and nutrient-use efficiency and locks carbon away for a century.

    Why do farmers still burn after years of measures?

    1. Unchanged economics: Residue is bulky, the window before wheat sowing is narrow, and almost every alternative to burning carries a cost.
    2. Burning is quick and cheap: Alternatives involve cost, labour and uncertainty, so burning remains the rational choice at the field.
    3. Limits of enforcement and subsidy: Enforcement and machinery subsidies help, and behaviour changes only when the residue itself becomes valuable.

    What has changed in the economics of parali?

    1. From a cost to a price: Farmers in several locations were paying to have straw removed. Today in parts of Punjab the same straw fetches around Rs 1.5 to 2 per kg.
    2. Who is buying: Demand from power plants, compressed biogas (CBG) units and pellet manufacturers is slowly creating a market for what was treated as waste.
    3. The new question: If parali now has value, the issue is where that value should be created and how much can remain with the farmer.

    Why is biochar different from burning straw for energy?

    1. Carbon fate: Burning biomass as fuel recovers energy and returns much of its carbon to the atmosphere. Biochar applied to soil retains a significant share of the carbon and serves an agronomic purpose.
    2. Punjab’s need: The rice-wheat system is under stress from declining soil quality, intensive fertiliser use and groundwater depletion, and residue generated by the same system could improve its soils.

    Where is the value created, and who captures it?

    1. The processing location problem: Parali has to be collected, baled, stored and transported within the narrow window before wheat sowing. Long-distance transport of a bulky, relatively low-value material quickly eats into its economics.
    2. Farmer as raw material supplier: The farmer supplies the raw material, and most value addition happens after the biomass leaves the village.
    3. The biochar irony: A farmer supplies the straw, sees it processed elsewhere and later buys back a product made from biomass originating on farms like his.
    4. The chakki precedent: Wheat does not travel 100 km merely because flour requires machinery. The village chakki places processing close to where the commodity is produced and consumed.

    How would a village-scale biochar system work?

    1. Build-operate-transfer: A technology provider installs and operates the unit, trains local operators and ensures quality and emission standards. Over time the asset and the capability transfer to a farmer producer organisation (FPO), a self-help group (SHG) or a cooperative.
    2. Government’s role: The government provides standards, training, concessional finance and initial support rather than running thousands of units, and panchayats help with land and coordination.
    3. Farmer’s routine: Farmers bring straw to a nearby processing point much as they bring wheat to a flour mill. Some biochar returns to their fields and the rest is sold where markets exist.
    4. What changes: Raw straw travels less, value addition happens closer to the farmer, and villages are not left with subsidised machinery nobody knows how to operate.

    Challenges to village-scale biochar processing

    1. Emissions from small kilns: A poorly run pyrolysis unit releases methane, carbon monoxide and particulate matter, and so replaces one smoke source with another. Eg. The Kon-Tiki flame curtain kiln, the low-cost design most village pilots use, has no flue gas treatment.
      The Fix: Notify emission standards for small pyrolysis units under the Central Pollution Control Board and make the build-operate-transfer operator liable for them until handover.
    2. Carbon credit verification: Biochar earns carbon removal credits only where permanence is measured, and a village unit cannot measure it alone. Eg. The Puro.earth biochar methodology requires a hydrogen to organic carbon ratio below 0.7 as the test of permanence.
      The Fix: Aggregate village units under an FPO level registry with laboratory testing so that credits are pooled and sold at scale.
    3. Paddy straw is a poor feedstock on its own: Paddy straw carries a high silica content, so its char is ash heavy and lower in fixed carbon than wood char. Eg. Rice straw ash is largely silica, and the char inherits it.
      The Fix: Blend paddy straw with maize, cotton and mustard stalks across seasons so that a unit runs year round on a better mix.
    4. Competition from existing straw buyers: A village unit competes for the same straw as large plants that already pay for it. Eg. The Verbio compressed biogas plant at Lehragaga in Sangrur, Punjab, consumes about one lakh tonnes of paddy straw a year.
      The Fix: Site biochar units in blocks beyond the collection radius of existing CBG and pellet plants, using the State’s straw balance map.
    5. Window mismatch: Straw arrives in three weeks and a unit needs feedstock for months. Eg. Punjab’s paddy harvest runs through late October and wheat sowing closes by mid-November.
      The Fix: Subsidise baling and covered storage at the processing point under the crop residue scheme so that processing continues after the window closes.

    Conclusion

    The policy question on parali has moved from stopping a practice to locating a market, and the location decides who captures the value. Village-scale processing answers that question only if quality, emissions and offtake are secured before the technology provider exits. The next window is the October to November harvest. Whether any State pairs its residue management subsidies with village-level processing points is the thing to watch.

    Stubble Burning in India

    1. What it is: Stubble burning is the practice of setting fire to the straw residue left in fields after harvest, especially paddy, to clear the land quickly for the next sowing.
    2. Where and when: It is concentrated in Punjab, Haryana, Uttar Pradesh and the National Capital Region during the post-monsoon October to November window.
    3. Why it happens: The narrow gap between paddy harvest and wheat sowing pushes farmers toward the cheapest and fastest clearing method.
    4. Scale: Punjab alone generates about 20 million tonnes of paddy straw a year.

    Challenges in Stubble Burning

    1. Episodic air pollution: Burning sharply aggravates the Air Quality Index across the Indo-Gangetic Plain within days. Eg. In December 2025 Delhi’s AQI crossed 500 and over 150 flights were delayed.
      The Fix: Front-load machine deployment in the fortnight before harvest with block-level fire targets monitored by satellite.
    2. Soil degradation: Burning destroys beneficial soil microbes, nitrogen and organic carbon. Eg. Each tonne of burnt paddy straw loses about 5.5 kg of nitrogen, 2.3 kg of phosphorus and 25 kg of potassium.
      The Fix: Pay a per-acre incentive for in-situ incorporation with Happy Seeder or Super Seeder, verified by satellite.
    3. Meteorological trap: Winter temperature inversions and calm winds prevent dispersal and compound the damage. Eg. Delhi invoked Stage IV of the Graded Response Action Plan in November 2024 when the AQI crossed 450.
      The Fix: Time enforcement and straw collection to the weeks before inversions set in rather than to the pollution peak.
    4. Paddy-centric cropping in a water-stressed region: Free farm power and assured procurement lock Punjab into paddy. Eg. About three fourths of Punjab’s groundwater assessment units are over-exploited as per the Central Ground Water Board.
      The Fix: Offer a per-hectare diversification incentive for maize and pulses with assured procurement so that the residue problem shrinks at source.
    5. Penalty without a price: Enforcement fines farmers who have no cheaper alternative. Eg. Environmental compensation for burning was doubled in November 2024 to Rs 5,000 for under two acres, Rs 10,000 for two to five acres and Rs 30,000 above five acres.
      The Fix: Pair the penalty with a guaranteed straw purchase price at the block level so that not burning is the cheaper option.

    “[2025, GS3, 10 marks] What is Carbon Capture, Utilization and Storage (CCUS)? What is the potential role of CCUS in tackling climate change?”

  • All animals need equal consideration

    All animals need equal consideration

    Why in the News

    A division Bench of the Supreme Court has ordered the Keralam government to take custody of Raman, Keralam’s tallest elephant, in Jayakrishna Menon vs. Krishnankutty & Ors. The Bench observed that the court cannot remain a mute spectator in matters concerning animals and that their wellbeing is of “paramount importance”. It held that it would fail in its duty towards “voiceless animals” if it ignored the elephant’s continued use for temple activities after its own prohibition. The order stands in contrast with Re: City Hounded by Strays, Kids Pay Price (2026). There a three judge Bench adopted a much narrower interpretation of the law. That reading led to the removal of large numbers of dogs from public institutions. The divergence raises the question whether Indian animal law grades animals by their value to humans rather than by their capacity to suffer.

    What is equal consideration?

    1. The principle: Framed by moral philosopher Peter Singer, equal consideration holds that the basic principle of equality does not require equal or identical treatment; it requires that the interests of each being be weighed equally.
    2. Who qualifies: Every being that has interests, some subjective awareness, or the capacity to feel pleasure or pain.
    3. Different treatment can follow: Equal consideration for different beings can lead to different treatment and different rights, because their needs differ.

    What questions does the differential treatment of two animals raise?

    1. The court’s own premise: The elephant order implicitly acknowledges an animal’s propensity to suffer and the need to ensure its wellbeing.
    2. One elephant against lakhs of dogs: Why one elephant’s wellbeing is of paramount importance and the welfare of lakhs of street dogs is disregarded.
    3. One institution, two approaches: How the same institution adopts two contrasting, if not contradictory, approaches to issues involving similar moral considerations.
    4. Whether courts should decide at all: Whether the judiciary is the best positioned institution to decide cases that seal the fate of animals, for better or for worse.

    Do the differences between the two animals justify different consideration?

    1. The elephant’s legal standing: The Indian elephant is a charismatic animal, listed as Endangered on the International Union for Conservation of Nature (IUCN) Red List, and explicitly protected under the Wild Life (Protection) Act, 1972.
    2. The street dog’s legal standing: The street dog is legally perceived as a problem that needs to be tackled.
    3. Different relationships with humans: One is expected to live in the wild away from human habitation. The other shares public spaces, requiring humans to learn to coexist in shared spaces.
    4. The test: Whether these differences are significant enough to attract completely different moral and legal considerations.
    5. What is actually missing: In the two judgments the absence of equal consideration itself drives the differential treatment. Equal consideration would require an assessment of the needs of each animal and then the determination of a course of action.

    Why does the remedy lie with Parliament rather than the courts?

    1. Anthropocentric bias in both statutes: The Wild Life (Protection) Act, 1972 for elephants and the Prevention of Cruelty to Animals Act, 1960 for street dogs evaluate the worth of animals by their value to humans. That valuation determines the nature and level of protection each animal receives.
    2. A gap in legislative guidance: Two cases involving different animals produced contrasting approaches from the same court. That exposes the absence of a legislative standard for animal well-being across legal categories.
    3. The Swiss model, cited in passing: The Swiss Constitution ensures the well-being of animals and also protects animal dignity, granting animals an inherent worth.
    4. Parliament’s responsibility: Parliament should extend protection to every being worthy of moral consideration, through a legislative foundation that provides moral consideration to all animals and pathways for ethical coexistence.

    Challenges to an equal consideration standard in Indian animal law

    1. Fragmented statutes: The same act of harm is governed by different laws depending on the animal’s legal category, so no single test of suffering applies. Eg. Street dogs fall under the Animal Birth Control Rules, 2023 made under the cruelty law, and elephants fall under Schedule I of the wildlife law.
      The Fix: Enact a single animal welfare code with a sentience-based standard that applies across categories, with the wildlife schedules layered on top for conservation purposes.
    2. Nominal penalties: Section 11 of the Prevention of Cruelty to Animals Act, 1960 punishes a first cruelty offence with a fine of Rs 10 to Rs 50, unchanged since enactment. Eg. The draft Prevention of Cruelty to Animals (Amendment) Bill, 2022 proposed fines up to Rs 75,000 and imprisonment for gruesome cruelty and has not been introduced in Parliament.
      The Fix: Introduce the amendment Bill with graded penalties and a statutory definition of sentience.
    3. Unsettled legal status of animals: High Courts and the Supreme Court have taken different positions on whether animals are legal persons, so lower courts have no stable rule. Eg. The Uttarakhand High Court in Narayan Dutt Bhatt v. Union of India (2018) and the Punjab and Haryana High Court in Karnail Singh v. State of Haryana (2019) declared animals legal persons, a status no Supreme Court ruling has endorsed.
      The Fix: Settle the legal status of animals in statute rather than leaving it to divergent judicial declarations.
    4. No enforcement arm: The Animal Welfare Board of India is advisory, and district level societies exist on paper. Eg. The Prevention of Cruelty to Animals (Establishment and Regulation of Societies for Prevention of Cruelty to Animals) Rules, 2001 require a society in every district, and many districts have none.
      The Fix: Fund district societies from State budgets with mandated veterinary and inspector staffing and a reporting line to the State Animal Welfare Board.

    Conclusion

    The two rulings leave a tension unresolved. Indian animal law protects by category, endangered species on one side and nuisance animals on the other, and the capacity to suffer sits on neither side of that line. A court can decide the case before it; it cannot write a standard that applies to every animal. The thing to watch is whether Parliament takes up the pending amendment to the cruelty law and whether it writes sentience, rather than human utility, into the test.

    Animal Welfare Law in India

    1. What it covers: Statutory protection of animals from cruelty and of wild species from harm, spread across a cruelty statute, a wildlife statute and subordinate rules for specific uses such as transport, slaughter, performance and experiments.
    2. Two regimes: The cruelty law applies to any animal, domestic, captive or stray. The wildlife law protects species by schedule, and the Wild Life (Protection) Amendment Act, 2022 reduced the schedules from six to four.
    3. Institutions: The Animal Welfare Board of India (statutory since 1962), the Committee for Control and Supervision of Experiments on Animals for laboratory use, and the National Board for Wildlife for protected species.
    4. Scale: India holds about 60 percent of the world’s Asian elephants, with 29,964 counted in the 2017 synchronised census, and the 20th Livestock Census (2019) counted 1.53 crore stray dogs.

    Challenges in Animal Welfare

    1. Rabies from an unmanaged stray population: Sterilisation and vaccination have not reached the coverage that stops transmission. Eg. India accounts for about 36 percent of global rabies deaths as per the World Health Organization.
      The Fix: Fund local bodies to reach 70 percent vaccination coverage of the dog population in each ward, since transmission breaks at that threshold.
    2. Captive elephants at festivals: Parading in heat, crowds and noise causes injury and deaths of animals and people. Eg. The Kerala High Court’s 2024 guidelines on distance and rest norms for parading elephants were contested before the Supreme Court by festival organisers.
      The Fix: Enforce microchip registration and the 2024 transfer rules so that every captive elephant has a traceable owner accountable for its welfare.
    3. Culture against welfare: Traditional events with animals are permitted by State amendments to the cruelty law. Eg. A five judge Bench in Animal Welfare Board of India v. Union of India (2023) upheld Tamil Nadu’s Jallikattu amendment.
      The Fix: Codify measurable welfare conditions for each permitted event under the Performing Animals rules, with veterinary supervision as a licence condition.
    4. Regulation of livestock trade: Welfare rules for animal markets have collapsed under political contest. Eg. The Prevention of Cruelty to Animals (Regulation of Livestock Markets) Rules, 2017 were stayed by the Supreme Court and withdrawn in 2018.
      The Fix: Re-notify market rules confined to welfare conditions such as water, shade and transport limits, without conditions on the purpose of sale.

    “[2022] Which one of the following has been constituted under the Environment (Protection) Act, 1986 ?

    (a) Central Water Commission

    (b) Central Ground Water Board

    (c) Central Ground Water Authority

    (d) National Water Development Agency

  • [2nd September 2026] The Hindu OpED: The two balance sheets behind every e-waste decision

    [2nd September 2026] The Hindu OpED: The two balance sheets behind every e-waste decision

    Question (2018): “What are the impediments in disposing the huge quantities of discarded solid wastes which are continuously being generated? How do we remove safely the toxic wastes that have been accumulating in our habitable environment?
    Linkage: Discarded computers, servers, and networking systems are a rapidly growing source of toxic and solid electronic waste. This question directly addresses the core administrative and logistical bottlenecks that prevent advanced recycling from becoming the default choice in India.

    Mentor Comment

    Governments and companies replace thousands of computers, servers, networking devices and storage systems every few years, and this discarded equipment holds copper, aluminium, gold, silver, palladium and critical minerals. Advanced recycling of such equipment has still not become the default choice in India. The reason is that procurement in both the public and private sectors rewards the lowest visible cost at the point of disposal. Every disposal decision creates two balance sheets, one financial and closed with the transaction, the other strategic and open long after it. The lowest-price principle that secures transparency and fiscal discipline in public procurement now sits in tension with the lifetime cost of decisions in electronics, batteries and renewable energy.

    What is urban mining?

    1. Definition: Urban mining is the recovery of valuable materials from products that have already served their purpose, in place of extracting fresh ore from the earth.
    2. The ore body: Discarded IT equipment is among the largest untapped sources of strategic raw materials as economies digitise, and it is hazardous waste when poorly handled.
    3. What safe recovery needs: Sophisticated technology, secure data destruction, environmentally compliant processing and traceable supply chains, with collection and segregation adding to the cost.

    Why has advanced recycling not become the default choice in India?

    1. Procurement rewards the lowest visible cost: Public and private buyers maximise resale value and minimise processing cost when they dispose of equipment.
    2. Strategic value stays off the invoice: Recovery of critical minerals, secure data destruction, environmental benefit and domestic industrial capability rarely appear in the price that decides the contract.
    3. The gains accrue to others: Less virgin mining, stronger domestic supplies of critical materials, lower import dependence and responsible handling of hazardous components are benefits the disposing organisation does not book.

    What are the two balance sheets every disposal decision creates?

    1. The first, financial and immediate: Purchase price, resale value and savings achieved, all measurable, auditable and reflected in annual budgets.
    2. The second, strategic and open ended: It stays open long after the transaction and records resource security, environmental sustainability, industrial capability, supply-chain resilience, public health and national competitiveness.
    3. Good governance manages both: Some investments look expensive at first and later transform economies. Eg. Fifteen years ago solar power struggled to compete with conventional electricity on cost and governments that invested early were criticised for paying too much. Scale and learning have since made solar one of the world’s cheapest sources of electricity, and countries that built manufacturing capacity early hold advantages a cost comparison could not have predicted.

    How do the costs left off the invoice return later?

    1. Recovery priced against disposal: Investment in urban mining infrastructure looks expensive when judged only against the cost of disposing of a computer. The calculation changes when recovered materials, avoided imports, environmental safeguards, data security and future industrial capability are counted together.
    2. Pollution becomes health-care expenditure: The public health cost of unsafe processing lands on the exchequer years after the disposal saving was booked.
    3. Resource depletion becomes import dependence: Metals not recovered at home are bought abroad, raising manufacturing costs.
    4. Weak domestic capability becomes strategic vulnerability: An economy without recovery capacity depends on others for the materials its industry runs on.
    5. Environmental costs turn economic: Governments spend more on remediation, businesses face higher compliance costs and citizens pay through taxes and lost productivity. The costs are delayed or redistributed and rarely avoided.

    What should an organisation ask before selecting a recycler?

    1. Secure data destruction: Whether sensitive data on the equipment is securely destroyed before any material moves.
    2. Refurbishment before recycling: Whether working equipment is refurbished for reuse before it is broken down for materials.
    3. Efficient and transparent mineral recovery: Whether critical minerals are recovered efficiently and the recovery is traceable.
    4. The cost of skipping the questions: A marginal gain today becomes tomorrow’s cybersecurity risk, import dependence, reputational damage and permanent loss of strategic resources.

    Can the lowest-price principle survive in sectors where acquisition cost is not lifetime cost?

    1. What the principle protects: Governments have relied on the lowest-price rule to ensure transparency and fiscal discipline in public spending.
    2. Where it fails: Renewable energy systems, batteries, electronics and advanced manufacturing are sectors where the lowest acquisition cost is rarely the lowest lifetime cost.
    3. The alternative many countries have adopted: Life-cycle costing (pricing an option across purchase, operation, disposal and recovery rather than at purchase alone) and value-based procurement ask which option delivers the greatest long-term public value. Procurement then becomes a tool of industrial policy that shapes which technologies scale and which capabilities are built.
    4. The same logic in compliance markets: Judging Extended Producer Responsibility (EPR, the obligation on a producer to finance the collection and recycling of the products it sells) compliance on the cheapest available certificate rewards the lowest-cost provider over the highest-quality outcome. Rewarding traceability, recovery efficiency and technological capability would instead draw investment into advanced recycling and strengthen India’s domestic supply of critical minerals.

    Challenges to urban mining of e-waste in India

    1. Fake certificates break traceability: An EPR certificate market cannot reward quality when the certificates themselves are unverified. Eg. The Central Pollution Control Board (CPCB) found over 600,000 fake recycling certificates in 2023 across Gujarat, Maharashtra, Karnataka.
      The Fix: Digitise certificate tracking against audited mass balance at each registered recycler, with cancellation of registration for a fake certificate.
    2. A floor price too low to sustain formal recycling: EPR pricing set below the cost of compliant recovery pushes material to informal and fraudulent channels. Eg. In April 2025 Daikin, Hitachi and Samsung sued the government opposing the mandated minimum recycler price.
      The Fix: Index the floor price to the audited cost of compliant recovery and revise it annually through a published formula.
    3. Inefficient recovery loses the minerals the policy exists to secure: Crude recycling wastes lithium, cobalt, nickel, copper, gold and silver. Eg. Improper battery handling alone could cost India over USD 1 billion in foreign exchange by 2030.
      The Fix: Fund research in advanced shredding, bioleaching and non-thermal recovery and tie EPR credit to recovery efficiency rather than to tonnage collected.
    4. No domestic refining of precious metals: Indian recyclers dismantle equipment and export the printed circuit boards, so the highest-value step happens abroad. Eg. Circuit boards from Indian dismantlers are shipped to integrated smelters in Belgium, Japan and South Korea for gold and palladium refining.
      The Fix: Mandate a minimum domestic refining share within EPR targets and treat integrated refining as eligible infrastructure under the critical mineral recycling incentive.

    Conclusion

    India’s discarded IT equipment will become either a strategic reserve or an environmental liability, and the deciding instrument is the procurement rule rather than the recycling technology. The reform that follows is to score public disposal tenders on lifetime value. That means amending the General Financial Rules, 2017, the rules for central procurement, so that a tender can weigh quality of recovery against the immediate price. The unresolved question is who pays: the buyer who funds advanced recycling is not the one who gains from resource security, and no mechanism yet closes that gap.

    E-Waste Management in India

    1. Scale: As per the CPCB, India generated 14,14,645 metric tonnes (about 1.41 million tonnes) of e-waste in 2025-26 till March 2026, of which 9,79,080 metric tonnes (about 0.98 million tonnes) was recycled.
    2. Global standing and growth: India is the third largest generator behind China and the United States. Volumes surged over 150 percent in six years from 0.71 million tonnes in 2017-18 and are projected to nearly double by 2030.
    3. Formal capacity: 386 registered recyclers across 19 States and Union Territories offer a capacity of about 34.66 lakh metric tonnes per annum.
    4. Concentration: Just 65 cities generate over 60 percent of total e-waste, and 10 States account for around 70 percent.

    Laws and Rules Governing E-Waste Management

    1. Environment (Protection) Act, 1986: The parent statute under which every set of e-waste rules is notified.
    2. E-Waste (Management) Rules, 2016: Introduced the Producer Responsibility Organisation (PRO) concept.
    3. E-Waste (Management) Rules, 2022: Make EPR the core engine, mandate registration of all producers, refurbishers and recyclers on the CPCB portal, and expand coverage from 21 to 106 electrical and electronic equipment items.
    4. E-Waste (Management) Second Amendment Rules, 2023: Added provisions for safe, sustainable refrigerant management in refrigeration and air-conditioning manufacturing.
    5. E-Waste (Management) Amendment Rules, 2024: Enabled CPCB supervised platforms for trading EPR certificates, priced between 30 percent and 100 percent of the environmental compensation for non-compliance.
    6. Hazardous and Other Wastes (Management and Transboundary Movement) Amendment Rules, 2025: Introduced an EPR framework for non-ferrous metal scrap, with targets rising from 10 percent in 2026-27 to 75 percent in 2032-33.
    7. Basel Convention, 1989: India is a signatory to this treaty limiting the transboundary movement of hazardous waste, including e-waste.

    Challenges in E-Waste Management

    1. Informal-sector dominance: Over 50 percent of e-waste is handled informally through open-air burning and acid leaching, exposing workers and residents to respiratory illness, neurological damage and DNA damage. Eg. Acid leaching of circuit boards in Moradabad releases toxic slurry into the Ramganga and local groundwater.
      The Fix: Train waste-pickers as certified green collar technicians with protective gear, certification and links to healthcare, insurance and pensions.
    2. Illegal imports: Developed nations export e-waste to India under cover of used goods. Eg. 29 illegal-import instances were identified during 2019-22 across Tamil Nadu, Maharashtra, Gujarat, West Bengal and Uttar Pradesh.
      The Fix: Pre-shipment inspection of used electronics consignments at ports under the Basel Convention notification procedure.
    3. Low awareness in the trade itself: The people who handle discarded electronics first do not know the rules. Eg. A 2021 Delhi study found 70 percent of repair workers and 79 percent of scrap dealers unaware of e-waste rules.
      The Fix: Run registration and awareness campaigns through resident welfare associations and self-help groups linked to registered collection points.
    4. Uneven infrastructure: Recycling capacity and expertise are concentrated in a few States. Eg. Telangana has built formal capacity, and Chandigarh lacks formal facilities.
      The Fix: Set up decentralised recycling hubs in every State with a collection target tied to the State’s generation share.
  • At SCO, Modi seeks dismantling of terror infra as Pak’s Shehbaz listens

    At SCO, Modi seeks dismantling of terror infra as Pak’s Shehbaz listens

    Why in the News

    The Prime Minister told the leaders of the Shanghai Cooperation Organisation (SCO) (the ten member Eurasian security grouping that includes India, Pakistan, China, Russia and Iran) that the crisis in West Asia demonstrates that a conflict in one region does not remain confined there. He said it impacts global energy security, maritime trade and supply chains, and that the Global South bears the brunt of the consequences.

    Why did India put the West Asia war at the centre of its SCO message?

    1. Security has widened: In an interconnected world the scope of security has expanded significantly, so a regional war becomes an energy, shipping and supply chain problem for every member.
    2. The meeting with Iran: Iran’s President was among the leaders at the summit. The Prime Minister met him on Monday, their first meeting since the start of the war.

    What did India demand on terrorism, and what gives the demand its weight?

    1. Beyond action and reaction: With Pakistan’s Prime Minister listening, the Prime Minister said terrorism remains a grave challenge for all of humanity and that the fight cannot be limited to a mere “action-reaction” mindset.
    2. Dismantle the whole ecosystem: He called for dismantling the entire ecosystem of terror financing, recruitment, radicalisation and safe havens, and for members to speak in one voice that there is no room for double standards.
    3. Terrorism as state policy: Countries that use terrorism as an instrument of state policy and shelter terrorists must be sent a strong message that terrorism cannot be a strategic asset for anyone.
    4. The Operation Sindoor antecedent: In May 2025, days after the Pahalgam terror attack, India launched Operation Sindoor, striking terror targets in Pakistan-occupied Kashmir and Pakistan. Four days of hostilities followed and ended with Pakistan seeking a ceasefire.
    5. The Tianjin precedent: At the SCO summit in Tianjin on August 31 and September 1 last year, the Prime Minister called the Pahalgam attack the “most heinous face of terrorism” and an open challenge to every nation, and said double standards on terrorism are unacceptable.

    What are the three pillars India set out for the SCO’s next 25 years?

    1. The framework: India’s vision for the SCO rests on three pillars, S for Security, C for Connectivity and O for Opportunity. Over 25 years the grouping built a tradition of dialogue across Eurasia, and the goal for the next 25 is to translate that cooperation into tangible results.
    2. Security: This pillar is the terrorism agenda set out above, carried as a demand on the grouping rather than as a bilateral grievance.
    3. Connectivity: Its scope must expand beyond roads, railways and air corridors to simplifying customs procedures, promoting digital documentation and enhancing the efficiency of logistics networks.
    4. Opportunity: The benefits of cooperation must directly reach people, with people-to-people ties at the heart of the next 25 years. The yardstick of success is new opportunities for youth, new markets for entrepreneurs, farmers benefiting from technology and improvement in citizens’ lives.
    5. Shared geography: As the world navigates uncertainty and instability, the task is to transform shared geography into shared opportunities.

    Why is connectivity the pillar that divides the members?

    1. Sovereignty as the condition: India supports all initiatives that connect markets, facilitate trade and open growth avenues, on the condition that respect for the sovereignty and territorial integrity of all nations is paramount, which it described as the core spirit of the SCO Charter.
    2. The Iran route: India wants to access Central Asia through Iran, since Pakistan has denied India overland transit to the region.
    3. The corridor objection: The China-Pakistan Economic Corridor is an irritant for India because it runs through territory India claims and so violates its territorial integrity and sovereignty.

    What follows the summit?

    1. The Delhi BRICS summit: The Chinese President and the Russian President attended, and the Prime Minister met them informally during the leaders’ group photograph. Both are expected at the BRICS summit in New Delhi on September 12 and 13.
    2. A Pakistan-hosted summit: Pakistan hosts the next SCO summit in 2027, and India’s participation will be watched closely by members of the grouping.

    Conclusion

    India has made no double standards on terrorism the price of its engagement with the SCO. The grouping’s next chair is the country that demand is aimed at. Two dates now test the position: the BRICS summit in New Delhi on September 12 and 13, where the same Chinese and Russian leaders reconvene, and the next SCO summit under the Pakistani chair, where India must decide whether and at what level to attend.

    [2026] Which of the following countries are members of the European Union?

    1. Belarus

    2. Poland

    3. Germany

    4. Switzerland

    (a) 1, 2 and 4 (b) 1 and 4 only (c) 2 and 3 (d) 2 and 4 only

  • Russian oil imports fell 26% in Aug amid supply pressure, China factor

    Russian oil imports fell 26% in Aug amid supply pressure, China factor

    Why in the News

    India’s oil imports from Russia fell 26 per cent in August from the historic highs of July, driven by tighter Russian export availability and stronger competition from Chinese refiners, according to provisional tanker data. Those July highs were themselves a product of the shift in India’s import strategy since March 2026, when Strait of Hormuz disruptions tightened West Asian oil flows. The fall in Russian volumes was the primary reason for the over 8 per cent decline in India’s overall oil imports in the month, even as imports from Venezuela reached their highest monthly level since 2020. The open question is whether August is a temporary retreat or the start of a period in which Russian barrels become scarcer, costlier and harder for Indian refiners to secure.

    How sharp was the fall, and does the data show a structural retreat?

    1. The Russian volume: India imported 2.08 million barrels per day (bpd) of Russian oil in August, down 26.3 per cent from July’s record 2.82 million bpd, on vessel tracking data from the commodity market analytics firm Kpler.
    2. The total intake: India’s total oil imports stood at 4.62 million bpd in August, down 8.4 per cent from July’s 5.04 million bpd.
    3. Russia’s share: Moscow’s share of India’s crude imports declined to 45 per cent in August from 55.9 per cent in July.
    4. Domestic contribution: Maintenance shutdowns at a few Indian refineries also contributed to the lower crude intake.
    5. Kpler’s reading: The shift points to market normalisation rather than a structural retreat from Russian crude. Flows are expected to stabilise at 2.0 to 2.5 million bpd, so Russian oil remains the mainstay of India’s imports.

    Why are Russian barrels getting harder to move to India?

    1. Attacks on export infrastructure: Ukrainian attacks on Russia’s oil and gas infrastructure are a key reason for the pressure on Russian exports. Attacks on export infrastructure in the Black Sea have become a tangible threat to the navigation of energy tankers in the region.
    2. The Black Sea freight penalty: Moving a Suezmax tanker (a crude carrier sized to transit the Suez Canal fully loaded) from the Black Sea port of Novorossiysk to India’s west coast now costs about $20 million, or roughly $20 per barrel, compared with about $13 per barrel from the Baltic Sea ports.
    3. The Baltic seizure risk: Dispatches from the Baltic ports carry their own risk, since Russian tankers sailing around Europe face detention or seizure by European countries.
    4. The Arctic route favours China: Russian exporters are sending more vessels through the Northern Sea Route, for which August and September are the peak traffic months even in a normal year because ice is thinnest. Black Sea drone threats add to that pressure, and the Arctic routing makes China the most cost-competitive destination.

    Why is China competing harder for the same cargoes?

    1. Russia is exporting less: Moscow is trying to maximise domestic refinery production to meet domestic fuel demand amid the Ukrainian attacks on its energy infrastructure, which lowers the crude available for export to India and to everyone else.
    2. Iranian barrels have thinned: Iranian oil volumes available to Chinese refiners have fallen amid the Strait of Hormuz crisis, pushing Chinese buyers towards Russian cargoes.
    3. The question for the coming months: With Russia exporting less to India and overall, and China competing more aggressively for available cargoes, the issue is whether Russian barrels become scarcer, costlier and harder for Indian refiners to secure.

    How has the Hormuz crisis reshaped India’s import slate?

    1. The break in March 2026: India’s crude import strategy shifted sharply since March 2026 as Strait of Hormuz disruptions tightened West Asian oil flows and increased freight risks.
    2. The scale of the Gulf loss: About 40 per cent of India’s crude imports usually came through the Strait of Hormuz, and a large part of that supply has effectively been offline.
    3. Diversification beyond Russia: Russian crude remains the backbone of the import slate, and refiners have diversified aggressively towards African, North American and South American barrels to offset the drop from the Gulf.
    4. Venezuela’s return: Imports from Venezuela jumped 60.2 per cent over July to 350,000 bpd in August. India restarted Venezuelan imports a few months ago after nearly a year of zero imports, once the US allowed Caracas’s oil to flow into the global market.
    5. How Venezuelan oil was unlocked: After the US captured Venezuela’s then President in early January, the US President said Washington would take control of Caracas’s oil sector. A few commodity traders were then authorised by Washington to sell Venezuelan oil, previously under US sanctions, globally.

    Conclusion

    Russian crude still anchors India’s imports, and the August fall reads as normalisation rather than exit. The pressure is now on the supply side, in Russia’s own export capacity and in China’s bidding for the same barrels. The figure to watch is whether India’s Russian intake holds its recent range in September, when Arctic routing to China is at its seasonal peak.

    Back2Basics: Northern Sea Route

    1. What it is: An Arctic shipping lane along Russia’s Siberian coast, running from the Kara Sea in the west to the Bering Strait in the east, linking Europe with East Asia.
    2. Why it is seasonal: Sea ice makes it navigable mainly in late summer and early autumn, and outside that window ships need icebreaker escort.
    3. Why it matters: It cuts the Europe to East Asia distance substantially compared with the Suez Canal route, and Russia regulates transit through its own Northern Sea Route administration.

    [2025, GS2, 15 marks] “Energy security constitutes the dominant kingpin of India’s foreign policy, and is linked with India’s overarching influence in Middle Eastern countries.” How would you integrate energy security with India’s foreign policy trajectories in the coming years?”