Why in the News
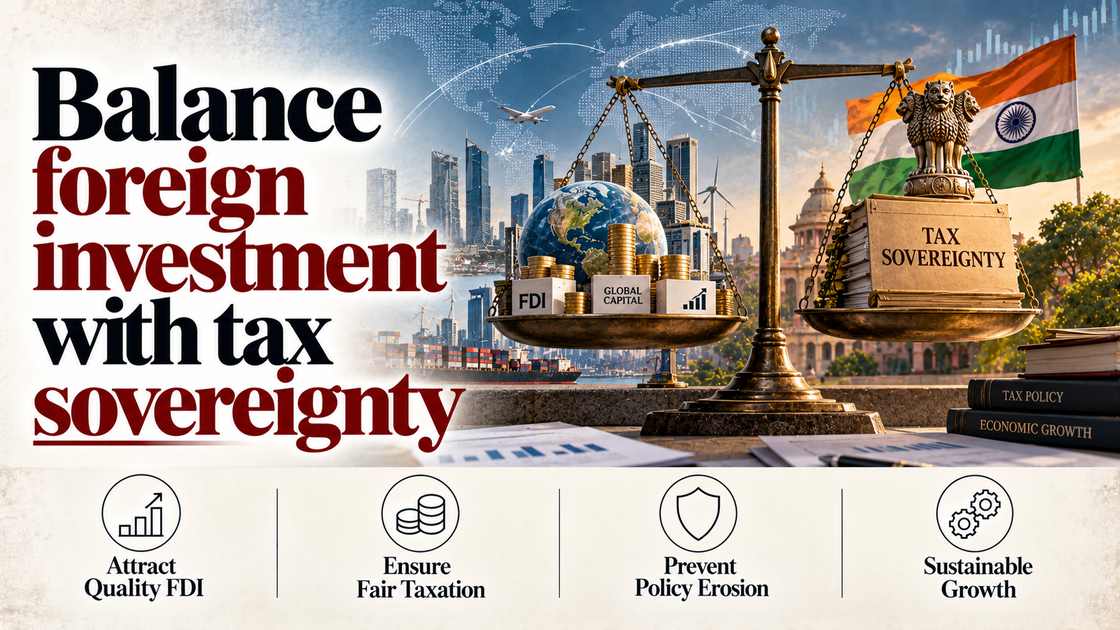
India is signing new bilateral investment treaties (BITs), and their investor protections now compete with its power to tax. Foreign investors increasingly use them, not tax treaties, to challenge tax measures, a route India rejects.
What is a bilateral investment treaty, and how can it limit a state?
- What it is: A BIT is a pact protecting investors from each partner country, like insurance against sudden policy change. Under investor-state dispute settlement (ISDS), investors can sue the host state before international arbitrators.
- Why countries sign them: Countries see foreign investment as a sign of economic success. BITs promise investors a steady regulatory framework, rules that will not change suddenly.
- What went wrong: Investors treat these promises as strict legal standards and use them against a state’s sovereign regulatory powers, its right to make rules and tax.
- Cairn and Vodafone: Arbitrators ruled against India’s retrospective tax demands, taxes on past deals, on these firms’ overseas share sales in 2020, regardless of the investment’s intent.
- The takeaway: A treaty meant to reassure investors can limit how a state taxes and regulates.
Are treaty protection standards fair to host states?
- Asymmetric fair treatment: The fair and equitable treatment standard protects investors from arbitrary action, but gives the host state’s tax base, the income it can tax, no matching protection.
- Expropriation fears: Treaties guard against expropriation, a state seizing foreign assets. Eg. Mexico’s oil nationalisation (1938) and Cuba’s seizures (1959).
- Extractive industries: Energy and extractive industries make up a third of investor-state disputes. Compensation can replace a lost asset, not lost policy sovereignty.
- Uneven enforcers: The United States accounts for 17.4% of ISDS cases, yet developing countries must extend treaty protection to tax.
- Limited payoff: Little evidence shows BITs attract investors. They mainly reassure those who come for higher returns anyway.
Why does India keep tax out of treaty arbitration?
- Unequal rights: Treaties give foreign investors rights, such as arbitration in tax matters, that domestic investors lack. India holds at international forums that tax cannot be arbitrated.
- Forum shopping: Investors pick the forum likeliest to favour them. In 134 tax related ISDS cases over the last decade, tax treaties offered a remedy in 53%, yet claimants, mostly Western European and North American, chose BITs.
What do other models show about settling tax and investment disputes?
- United Nations model: The United Nations (UN) model treaty is being revised to keep tax out of investment and trade agreement disputes.
- Brazil: Brazil’s Cooperation and Investment Facilitation Agreements exclude ISDS, relying on state-to-state dispute resolution and joint implementation committees.
- India’s carve-out: India’s explicit tax exclusion in its BITs is therefore not unusual.
How can India offer investors quick justice without a separate track?
- Mutual Agreement Procedure: Under the Mutual Agreement Procedure (MAP), two countries’ tax authorities settle a dispute between themselves, faster than courts. India can strengthen it.
- Local remedies window: Investors must try domestic courts before arbitration. India’s BIT with the United Arab Emirates (UAE) allows three years, against five in the 2015 Model BIT.
- Equal treatment: A faster timeline must not slow justice for domestic investors, create a nationality based fast track, or burden domestic institutional investors.
Challenges
- Award exposure: Treaty claims still bring large awards. Eg. Deutsche Telekom‘s award over the cancelled Antrix-Devas deal.
- Gaps in treaty cover: Much foreign investment lacks treaty protection since older BITs ended. Eg. About €120 billion of European Union (EU) investment.
- Treaty shopping: Investors route money through shell firms, companies with no real business, in partner countries to claim protection.
Way Forward
- Explicit tax exclusion: The Department of Economic Affairs should write a clear tax carve-out into every new BIT.
- Denial of benefits: New treaties should deny protection to shell firms in the partner country.
- Commercial court capacity: Add commercial benches so investor disputes finish within the treaty window.
Conclusion
India is trading tax powers it cannot easily win back for investor confidence that BITs do not reliably deliver. What to watch is whether new treaties keep tax out of arbitration and speed remedies for all investors.
Government Initiatives on Investment Treaties
- Termination of older BITs: India ended most older BITs from 2017 and offered renegotiation on its new model.
- Taxation Laws (Amendment) Act, 2021: Withdrew retrospective tax demands on indirect transfers, refunding sums once firms dropped claims.
- New treaties: BITs on the new model with Uzbekistan (2024) and Israel (2025).
- India-EU investment protection agreement: Negotiated apart from the trade deal; taxation jurisdiction is a sticking point.
Matching Previous Year Question
“No direct PYQ traced in the provided files. Thematic PYQ: [2014, GS3, 12 marks] Foreign Direct Investment (FDI) in the defence sector is now set to be liberalized: What in fluence this is expected to have on Indian defence and economy in the short and long run?”