Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS3-01.Indian Economy and issues relating to planning, mobilization of resources, growth, development and employment.

  • Household debt, financing today against tomorrow

    Why in the News

    India’s household debt has reached 45.5% of gross domestic product (GDP) as of September 2025, according to the Reserve Bank of India (RBI). The level is modest beside several emerging market economies, but the mix and pace of borrowing deserve attention.

    What is household debt, and how has it changed?

    1. What it is: Household debt is what families owe through credit cards, personal and consumer durable loans, digital lending and buy-now-pay-later plans. It is like spending next year’s salary today.
    2. Rising trend: The debt ratio has climbed steadily from 39.2% of GDP in March 2021.
    3. Savings recovery: Household net financial savings (financial assets added minus new borrowing) fell from pandemic highs without collapsing, then recovered to about 6% of GDP in 2024-25.
    4. Housing versus consumption: Housing loans, traditionally the main component, create an asset; consumption borrowing creates none.
    5. The takeaway: A modest ratio does not prove safety, because the real risk lies in what borrowing pays for and who must repay it.

    Why does the reason for borrowing matter?

    1. Unsecured lending boom: Fast-growing personal loans and credit-card borrowing, backed by no asset, keep family spending steady when income falls short. They also lock up future income in repayment.
    2. Unequal repayment risk: A salaried household with predictable pay repays comfortably. A self-employed, informal-sector or casual worker with irregular pay faces far higher risk.
    3. Shift in loan purpose: The RBI finds consumption borrowing still large but slowing, and productive borrowing rising.
    4. Two kinds of borrowing: Debt for houses, education or productive assets from rising incomes is benign. Debt for food, health care, rent or durables because income is inadequate only postpones the problem.
    5. Easier digital credit: Instant app-based loans make borrowing quick and cheap, so households confuse what they can afford with what they can borrow.

    How can household debt weaken the economy?

    1. Short-run boost: Credit-financed consumption supports aggregate demand (total spending in the economy), but creates future repayment obligations for households.
    2. Debt-service squeeze: As loan repayments rise, households cut non-essential spending, so consumption moves with interest rates and job security.
    3. Self-reinforcing cycle: Weak incomes set off a loop:
      • income stagnation;
      • borrowing to sustain consumption;
      • rising debt service;
      • declining disposable income;
      • weaker consumption;
      • greater dependence on credit.
    4. Two growth models: Spending funded by credit lifts demand only temporarily. Spending funded by rising incomes is the sustainable foundation for growth.

    Is a modest debt ratio a sign of health or of hidden distress?

    1. Official reassurance: The government stresses that household leverage is below many emerging-market peers and savings have improved.
    2. Debt replacing social protection: Families borrow for health care, education, housing or old age because public support for these needs is weak. Debt therefore reflects gaps in social protection, not only personal choice.
    3. Questions behind the number: The issue is not how much households owe, but why they owe, to whom, at what cost and against what income.
    4. Credit mistaken for welfare: As incomes grow more unequal and uncertain, households borrow to keep up living standards, so easy credit is wrongly read as rising welfare.

    Challenges

    1. No data on loan purpose: Lenders record loan type, not why a family borrowed, so distress credit is hard to spot.
    2. Illegal loan apps: Unregulated digital lenders operate outside RBI oversight and often charge very high interest.
    3. Elevated small-loan defaults: Missed repayments on personal loans and small digital loans stayed high through 2025-26.

    Way Forward

    1. Credit by purpose: The RBI should separate productive credit from distress credit, borrowed to meet basic needs, rather than simply restricting lending.
    2. Wider social protection: The Union and States should expand health insurance and pensions so families need not borrow for basic needs.
    3. Purpose-level reporting: The RBI should make credit bureaus record loan purpose and borrower income type.

    Conclusion

    The household debt question has shifted from how much families owe to whether they borrow to build assets or to get by. Unless incomes steady and social protection widens, credit will keep financing today’s living out of tomorrow’s income.

    Key numbers

    1. Household debt, June 2023: About 42% of GDP.
    2. Net financial savings, 2023-24: 5.2% of GDP.

    Government Initiatives on Household Credit

    1. RBI Digital Lending Directions (2025): Bind regulated lenders on recovery practices, data privacy, transparency and grievance redressal.
    2. RBI Digital Lending Directory (2025): Lets borrowers check whether a lending platform is legitimate.
    3. Blocking illegal apps: The Ministry of Electronics and Information Technology (MeitY) can block illegal loan apps under Section 69A of the Information Technology Act, 2000.

    Matching Previous Year Question

    “[2026] Which one of the following correctly represents the three key sub-indices of the Financial Inclusion Index (FI-Index) of the RBI? (a) Credit access, Insurance depth, and Pension coverage (b) Banking access, GDP contribution, and Financial literacy (c) Access, Usage, and Quality (d) Access, Affordability, and Transparency Answer: C”
  • Release of Sub-Sectoral Trial Index of Services Production (ISP) for July 2026

    Release of Sub-Sectoral Trial Index of Services Production (ISP) for July 2026

    Why in the News?

    MoSPI released the Index of Services Production (ISP) for July 2026, covering 19 sub-sectors, with 2024-25 as the base year.

    Key Highlights

    • Released by: Ministry of Statistics & Programme Implementation (MoSPI).
    • Index: Index of Services Production (ISP).
    • Reference month: July 2026.
    • Base year: 2024-25.
    • Covers 19 service sub-sectors.
    • Highest growth in July 2026:
      • Administrative and support services: 20.9%
      • Retail Trade: 18.5%
      • Real Estate: 14.4%
      • Accommodation and food: 12.6%
      • Banking: 12.3%
    • Lowest growth:
      • Air Transport: -8.4%
      • Repair Services: -5.0%
      • Arts, Entertainment and Recreation Services: 1.7%.

    Index of Services Production (ISP)

    • ISP measures production trends across 19 sub-sectors of services.
    • July 2026 indices include:
      • Wholesale Trade: 126.8
      • Retail Trade: 140.0
      • Accommodation and food: 144.0
      • Road Transport: 132.1
      • Telecommunications: 121.4
      • Banking: 121.9
      • Real Estate: 121.2.

    Trial Series and Data Status

    • Monthly ISPs are being published on an experimental basis.
    • The trial series aims to:
      • Examine data quality.
      • Test resilience of the data.
      • Obtain feedback from stakeholders and users.
    • Indices for Railways, Banking and Insurance are based on provisional monthly data.
    • These three indices will undergo annual revision.

    Prelims Quick Revision

    • ISP July 2026: Released by MoSPI.
    • Base year: 2024-25.
    • Covers 19 service sub-sectors.
    • Highest July 2026 growth: Administrative and support services – 20.9%.
    • Retail Trade growth: 18.5%.
    • Air Transport growth: -8.4%.
    • ISP is currently published on an experimental/trial basis.
    • Railways, Banking and Insurance data are provisional and subject to annual revision.

    UPSC Prelims Trap

    • ISP is not an index of only transport services; it covers 19 broad service sub-sectors.
    • 2024-25 is the base year, not 2011-12.
    • Air Transport recorded negative growth of 8.4%, while Road Transport grew by 9.9%.
    • Railways, Banking and Insurance are specifically based on provisional monthly data and are subject to annual revision.
  • Funds awaited, Govt showpiece deep-tech initiative hits pause

    Why in the News

    The government’s showpiece deep-tech fund has moved from selecting beneficiaries to inviting no new applications, because the money to make fresh offers has not arrived. The Technology Development Board (TDB), a statutory body under the Department of Science and Technology (DST) and the only agency now selecting beneficiaries for the Research, Development and Innovation (RDI) Fund, has stopped inviting applications after this month, citing “administrative reasons”.

    What is the RDI Fund, and why was it created?

    1. What it is: The RDI Fund lends to private firms and start-ups researching sunrise sectors such as quantum, space, robotics and artificial intelligence (AI). It is like a patient loan banks avoid.
    2. Why it was created: The Government set it up in November 2025 to finance technologies seen as crucial for the economy’s growth and strategic independence.
    3. Size and form: It promised Rs 1 lakh crore over six years, largely as low-cost, long-term loans. It sits under the Anusandhan National Research Foundation (ANRF), a statutory body under DST.
    4. Co-funding rule: A soft loan covers up to half of a project’s cost, so the company must raise the rest from non-government sources.
    5. The takeaway: The fund was meant to carry deep-tech firms from research to product, so a pause hits them when private money is scarcest.

    How far has the fund got, and where has it stalled?

    1. Custodian’s role: Only DST, the fund’s administrative custodian, can allot money to the agencies that pick borrowers.
    2. First round: TDB’s Rs 2,000 crore ran out in April, when 22 companies were offered soft loans.
    3. Beneficiaries: Approved firms include space ventures Agnikul Cosmos and GalaxEye, quantum start-up QuNu Labs, and robotics firms ideaForge and EndureAir.
    4. Second round stuck: TDB finalised 13 more firms in August but has not issued their letters of intent, the formal offer that comes before a loan.
    5. Money released: Nearly a year after launch, only the Rs 2,192 crore offered to first round firms has been made available.

    Why is the fund falling behind?

    1. Fund managers: Companies are chosen by agencies called Second Level Fund Managers (SLFMs). TDB and the Biotechnology Industry Research Assistance Council (BIRAC) under the Department of Biotechnology were nominated first.
    2. Delayed private managers: Applications from private SLFMs closed in January and a committee finalised its recommendations in May, yet appointments are still pending.
    3. BIRAC’s tax question: BIRAC, a non-profit company, has not begun selecting firms. Loans can convert into equity (a shareholding) earning taxable dividends, so BIRAC awaits a Finance Ministry tax ruling.
    4. Conflict of interest: An August investigation found 15 first-round recipients had investment ties to seven selection committee members. The members said they had recused themselves from appraising those firms.
    5. Target at risk: Industry expects the six-year target to be missed at this pace.

    Challenges

    1. Single-agency bottleneck: With the Biotechnology Industry Research Assistance Council (BIRAC) idle and no private Second Level Fund Managers (SLFMs), TDB alone picks borrowers, so a funding gap halts the scheme.
    2. Opaque pause: The notice cites only “administrative reasons”, so applicants cannot plan.
    3. Investor-linked selection: Committee members from the investment community can hold stakes in applicants, weakening trust.
    4. Matching capital burden: Early-stage deep-tech start-ups struggle to raise the private half of project cost.

    Way Forward

    1. Scheduled releases: DST should release allocated money to selecting agencies on a fixed schedule tied to approved rounds.
    2. Appoint private SLFMs: DST and ANRF should finalise the recommended private fund managers to spread the selection load.
    3. Tax ruling: The Finance Ministry should settle how loan-to-equity conversion is taxed.
    4. Disclosure norms: ANRF should publish committee members’ interests and recusals for every funding round.

    Conclusion

    The fund’s design is in place, but money and selecting agencies have not kept pace with applicants. Whether DST releases fresh money and private fund managers are appointed once invitations close will show if the flagship lending restarts.

    Key numbers

    1. DST allocation for the fund: Rs 23,000 crore (Rs 3,000 crore in last year’s Budget, Rs 20,000 crore this year).
    2. Applications: over 300 companies applied; about 100 appraised; 35 selected so far.
    3. Private SLFMs expected: 30 to 40 entities.

    Back2Basics: Anusandhan National Research Foundation (ANRF)

    1. Legal basis: Set up under the Anusandhan National Research Foundation Act, 2023.
    2. Mandate: Funds and coordinates research across universities, laboratories and industry.
    3. Governance: Its governing board is chaired by the Prime Minister.
    4. Predecessor: It subsumed the Science and Engineering Research Board (SERB).

    Matching Previous Year Question

    “[2026] In what way(s) does the Vizhinjam International Seaport represent a structural shift in India’s maritime trade and logistics policy? 1. By functioning exclusively as a domestic cargo hub to reduce reliance on coastal shipping and eliminate the need for foreign collaborations. 2. By focusing primarily on passenger cruise tourism and heritage shipping to increase Kerala’s profile as a maritime heritage destination. 3. By leveraging its natural deep draft and strategic location to reduce dependence on foreign trans-shipment ports, enhance revenue retention, and reposition India in regional maritime trade. Select the answer using the code given below: (a) 1 only (b) 1 and 2 (c) 2 and 3 (d) 3 only Answer: D”

  • Market plunges, more bad weather may lie ahead

    Why in the News

    Indian equities saw a sharp, broad-based selloff on Monday, with the BSE Sensex falling 1,124 points. Global shocks and steady selling by foreign portfolio investors (FPIs) are driving the fall even as corporate earnings stay healthy, so investor concerns run deeper than company results.

    What is the Sensex, and how deep is the fall?

    1. What it is: The Sensex is the Bombay Stock Exchange’s index of 30 large companies. It works like a thermometer for investor mood.
    2. A broad fall: Monday’s 1.52 per cent drop hit public sector bank, fast-moving consumer goods (FMCG), utilities, auto and financial services stocks alike.
    3. A long slide: The Sensex has fallen almost 15 per cent since the start of 2026.
    4. The takeaway: A fall this broad and long reflects a reassessment of India’s risks, not a one-day shock.

    Why has market sentiment soured?

    1. West Asia conflict: The conflict in West Asia and the high energy prices it has caused weigh heavily on India, which imports most of its crude oil.
    2. Hormuz shock: Oil prices spiked after the US President rejected Iran’s proposal to reopen the Strait of Hormuz, the narrow sea passage through which much of the Gulf’s oil is shipped.
    3. Rising bond yields: The 10-year US bond yield stands at 5.2 per cent. When safe US bonds pay more, global investors move money out of riskier emerging markets such as India.
    4. Tighter global money: Tightening global financial conditions, meaning costlier and scarcer credit worldwide, leave less money for equities.

    Why are foreign investors selling despite healthy earnings?

    1. What FPIs are: Foreign portfolio investors buy shares and bonds for returns without seeking control, so they can exit quickly. They are net sellers again, selling more than they buy.
    2. Scale of the exit: FPIs have taken $26.2 billion out of Indian equities so far in 2026, after heavy outflows the previous year.
    3. Deeper doubts: Brokerage Bernstein argues the “case for a structural India allocation has become harder to make”, meaning a lasting place for India in global portfolios.
    4. Earnings still healthy: Ratings agency ICRA expects Indian companies’ second quarter revenue to grow 13 to 15 per cent. Operating margins, the share of sales left after running costs, are under pressure.

    What will drive markets in the near term?

    1. US interest rates: After the US Federal Reserve‘s recent rate hike, markets will read upcoming data for clues on the path of interest rates.
    2. Energy markets: How long and how hard the West Asia conflict runs will shape oil prices, and so the markets.
    3. El Niño: El Niño, a warming of the Pacific Ocean that often weakens India’s monsoon, can cut crop output and raise food prices.
    4. RBI policy: The Reserve Bank of India (RBI)‘s Monetary Policy Committee (MPC) meets next week amid expectations of a rate hike, which would tighten domestic policy further.

    Challenges

    1. Imported inflation: Costly oil raises fuel and transport costs, pushing up prices across the economy.
    2. Rupee pressure: FPI outflows raise demand for dollars, weakening the rupee and making imports dearer.
    3. Growth versus inflation: A rate hike raises borrowing costs for firms already facing margin pressure.
    4. Food supply risk: A weak El Niño monsoon can cut farm output and add to food inflation.

    Way Forward

    1. Calibrated monetary policy: The MPC should weigh imported inflation against growth in sizing any hike.
    2. Deeper domestic investor base: Channel household savings into equities through mutual and pension funds to cushion foreign exits.
    3. Energy buffers: Expand strategic petroleum reserves and diversify crude supply away from Hormuz.
    4. Food supply planning: Use buffer stocks and open market sales to contain El Niño-linked food inflation.

    Conclusion

    India’s market fall is driven more by global shocks and foreign investor doubt than by weak corporate earnings. The MPC’s decision and the course of the West Asia conflict will show whether the pressure eases or deepens.

    Key numbers

    1. FPI equity outflow, September 2026: $2.1 billion.
    2. FPI equity outflow, 2025: $18.9 billion.

    Back2Basics: Monetary Policy Committee

    1. What it is: A statutory body under the Reserve Bank of India Act, 1934, created by a 2016 amendment. It sets the repo rate, the RBI’s lending rate to banks.
    2. Composition: Six members: three from the RBI, including the Governor as chair, and three external members appointed by the Centre.
    3. Mandate: Keep retail inflation at 4 per cent, within a tolerance band of two percentage points either side.
    4. Decisions: Taken by majority vote, with the Governor holding a casting vote in a tie.

    Matching Previous Year Question

    “[2022] Which one of the following situations best reflects “Indirect Transfers” often talked about in media recently with reference to India ? (a) An Indian company investing in a foreign enterprise and paying taxes to the foreign country on the profits arising out of its investment (b) A foreign company investing in India and paying taxes to the country of its base on the profits arising out of its investment (c) An Indian company purchases tangible assets in a foreign country and sells such assets after their value increases and transfers the proceeds to India (d) A foreign company transfers shares and such shares derive their substantial value from assets located in India Answer: D”

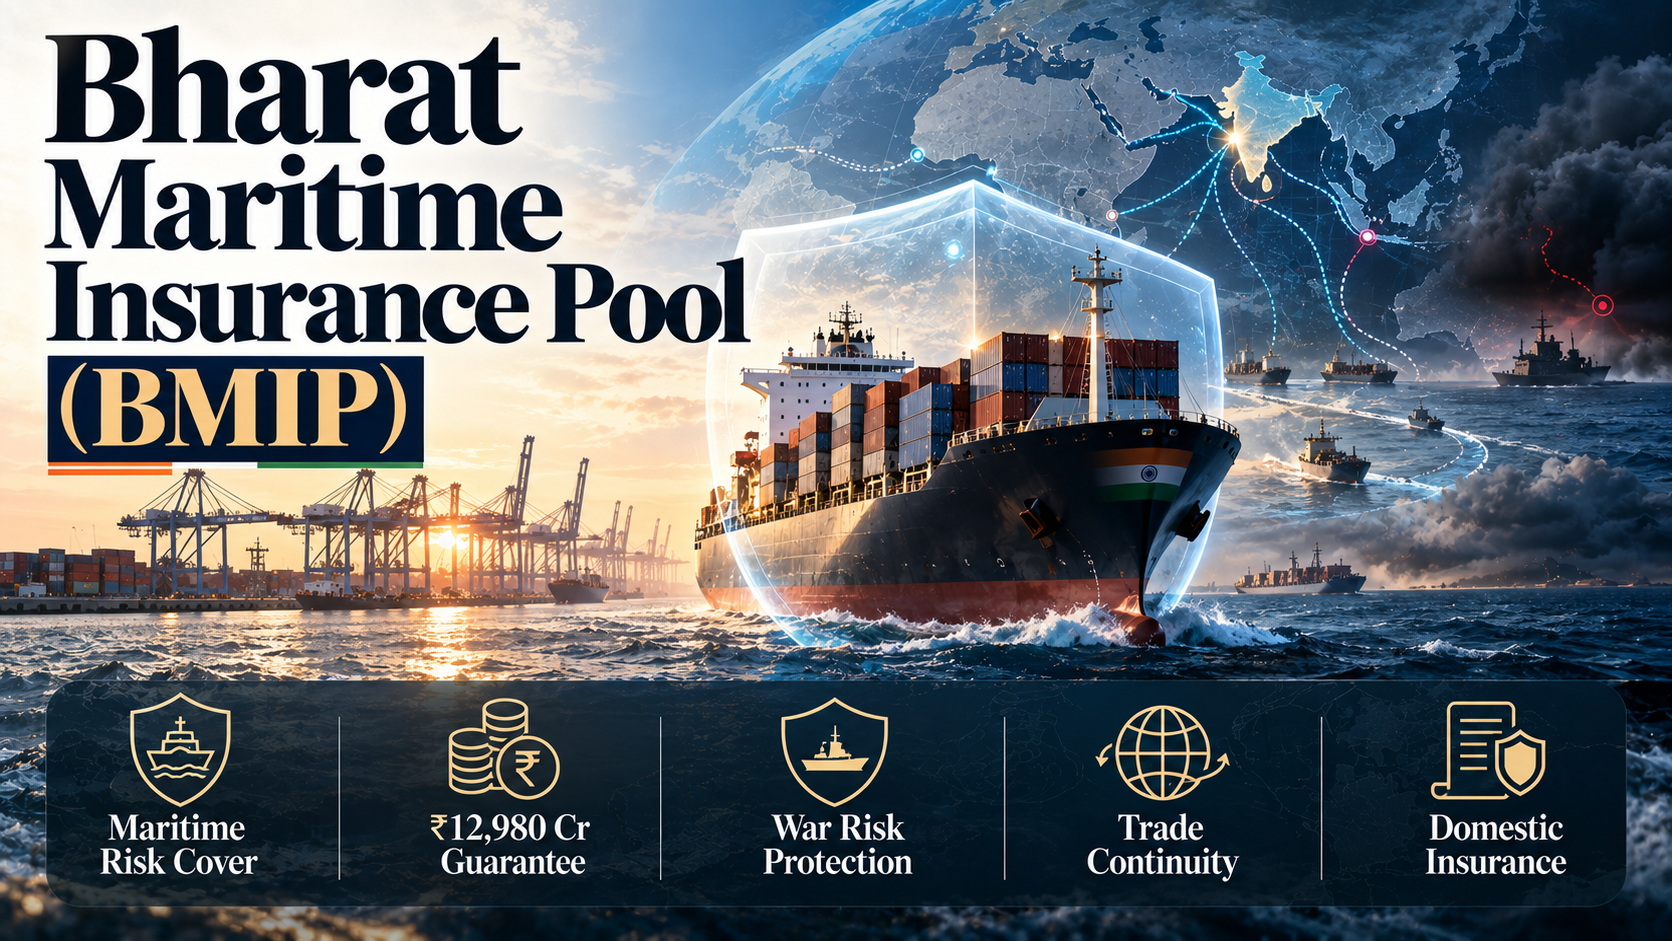
  • Bharat Maritime Insurance Pool (BMIP)

    Bharat Maritime Insurance Pool (BMIP)

    Why in the News?

    • The Bharat Maritime Insurance Pool (BMIP) was launched in May 2026 as India’s first domestic maritime insurance pool.
    • It provides domestic insurance coverage for Indian-linked vessels and cargo, reducing dependence on foreign marine insurers.

    Key Highlights

    • Approved: 18 April 2026.
    • Launched: 12 May 2026.
    • Insurance capacity: ₹13,906.50 crore (US$1.5 billion).
    • Sovereign guarantee: ₹12,980 crore (US$1.4 billion).
    • Pool duration: 10 years, extendable up to 15 years.
    • Covers:
      • Hull & Machinery
      • Cargo
      • Protection & Indemnity (P&I)
      • War Risks
    • Eligible vessels:
      • Indian-flagged vessels
      • Vessels owned, managed or controlled by Indian entities
      • Cargo vessels destined to or originating from India.

    Why India Needs BMIP

    • 95% of India’s trade value and 70% of trade volume flows through maritime routes.
    • India previously depended heavily on foreign insurers, particularly international P&I Clubs.
    • Foreign insurance dependence resulted in an annual outflow of US$45-60 million in P&I premiums.
    • Geopolitical disruptions such as conflicts in the Red Sea and tensions around the Strait of Hormuz increased insurance premiums and created risks of coverage withdrawal.

    Insurance Coverage

    • Hull & Machinery: Protects the ship’s hull, propulsion machinery and installed equipment.
    • Cargo: Covers goods transported through international sea routes against specified war-related losses.
    • Protection & Indemnity (P&I): Covers third-party liabilities such as:
      • Pollution
      • Oil pollution clean-up
      • Wreck removal
      • Crew injury
      • Cargo damage
    • War Risk: Covers risks arising from:
      • Armed conflict
      • Piracy
      • Terrorism
      • Hostile vessel seizure.

    BMIP Structure

    • Policies: Issued by domestic insurers that are members of the Pool.
    • Reinsurance: Risks are collectively reinsured by Pool members according to their committed capacity.
    • Claims up to US$100 million: Met from accumulated reserves and reinsurance recoveries.
    • Claims above US$100 million: Sovereign guarantee becomes available after exhaustion of Pool reserves.
    • Pool Administrator: General Insurance Corporation of India (GIC Re).
    • Governing Body: Oversees and regulates Pool operations.
    • Underwriting Committee: Ensures risk evaluation and underwriting discipline.

    Important Outcomes

    • War-risk insurance premiums reportedly fell by around 35-40% from their peak during the West Asia conflict.
    • As of 7 September 2026:
      • 3,000 Cargo War policies
      • 92 Hull War-risk policies
      • 3 P&I policies
    • India’s first BMIP P&I policy was issued on 30 July 2026 to Shipping Corporation of India Ltd.
    • The first Hull and Machinery War-risk policy was issued on 12 May 2026.

    India’s Maritime Sector

    • Major ports: 12.
    • Non-major ports: 217.
    • Cargo handled during 2025-26: 1,668 million metric tonnes.
    • Coastline: Around 11,098 km.
    • Exclusive Economic Zone (EEZ): 2.4 million sq km.
    • Inland waterways: More than 14,500 km.
    • Maritime sector supports over 30 million livelihoods.
    • Indian-flag fleet as of mid-2026: 1,609 ships and 14.33 million GT.

    Prelims Quick Revision

    • BMIP: India’s first domestic maritime insurance pool.
    • Launch: 12 May 2026.
    • Capacity: ₹13,906.50 crore / US$1.5 billion.
    • Sovereign guarantee: ₹12,980 crore / US$1.4 billion.
    • Administrator: General Insurance Corporation of India (GIC Re).
    • Main insurance categories: Hull & Machinery, Cargo, P&I and War Risk.
    • Claims up to US$100 million: Reserves and reinsurance recoveries.
    • Duration: 10 years, extendable up to 15 years.

    UPSC Prelims Trap

    • BMIP is an insurance pool, not a standalone insurance company.
    • P&I vs Hull & Machinery: P&I primarily covers liabilities such as pollution and crew injury, while Hull & Machinery covers physical damage to the vessel and its machinery.
    • Sovereign guarantee ≠ initial insurance capacity: Pool capacity is ₹13,906.50 crore, while sovereign backing is ₹12,980 crore.
    • Foreign P&I Clubs vs BMIP: International P&I Clubs provide global maritime liability insurance, while BMIP provides a domestic pool-based mechanism for eligible Indian-linked maritime risks.
  • WorldSkills Shanghai 2026

    WorldSkills Shanghai 2026

    Why in the News?

    • India secured 10th position at the 48th WorldSkills Competition, Shanghai 2026, improving from 13th position at WorldSkills Lyon 2024.
    • India won 6 Silver Medals and 20 Medals for Excellence with its largest-ever contingent of 70 competitors across 63 skills.

    Key Highlights

    • Edition: 48th WorldSkills Competition.
    • Venue: Shanghai, China.
    • Dates: 22-27 September 2026.
    • India’s rank: 10th.
    • Indian contingent: 70 competitors across 63 skills.
    • Global participation: Over 1,400 competitors from around 70 countries and regions.
    • Silver Medals: 6.
    • Medals for Excellence: 20.
    • Best of Nation: Smriti Nambiar, Bakery.
    • WorldSkills Lyon 2024: India ranked 13th, with 4 Bronze Medals and 12 Medals for Excellence.

    Silver Medal Winners

    • Bakery: Smriti Nambiar
    • Dental Prosthetics: Mohammed Salam
    • Digital Interactive Media Design: Kovid Ajay Gangrade
    • Industrial Design Technology: Parth Vohra
    • Logistics and Freight Forwarding: Mehrunissa Begum
    • Retail Sales: Saniya Joshi

    New and Emerging Skills

    India made its debut in 11 new and emerging skill categories, including:

    • Dental Prosthetics
    • Digital Interactive Media Design
    • Intelligent Security Technology
    • Landscape Gardening
    • Optoelectronic Technology
    • Retail Sales
    • Unmanned Aerial Systems
    • Industrial Mechanics
    • Software Testing
    • Heavy Vehicle Technology
    • Aircraft Maintenance

    Medal for Excellence

    • A Medal for Excellence is awarded to competitors demonstrating a high level of professional proficiency against internationally established WorldSkills standards.
    • India won 20 Medals for Excellence across technical, industrial, digital, creative and service skills.

    India’s Participation

    • Participation coordinated by National Skill Development Corporation (NSDC) under the Ministry of Skill Development and Entrepreneurship (MSDE).
    • Supported by:
      • Sector Skill Councils
      • Industry partners
      • Training institutions
      • Technical experts
      • Other stakeholders
    • India’s participation focused on global occupational standards, emerging technologies and international best practices.

    WorldSkills Competition

    • WorldSkills is an international skills competition showcasing excellence in vocational and technical skills.
    • Held every two years.
    • Promotes:
      • International skills standards
      • Knowledge exchange
      • Technical excellence
      • Skilled career development

    Prelims Quick Revision

    • WorldSkills Shanghai 2026: 48th edition.
    • Host: Shanghai, China.
    • India’s rank: 10th.
    • Indian medals: 6 Silver + 20 Medal for Excellence.
    • Indian contingent: 70 competitors across 63 skills.
    • Previous Indian rank: 13th at Lyon 2024.
    • Best of Nation: Smriti Nambiar, Bakery.
    • WorldSkills frequency: Every two years.

    UPSC Prelims Trap

    • WorldSkills is not a conventional sports competition: It focuses on vocational and technical skills.
    • India’s 2026 result: 10th position, not 13th. The 13th position refers to India’s performance at Lyon 2024.
    • Medal for Excellence ≠ Silver Medal: Medal for Excellence recognises achievement against established professional standards.
    • NSDC vs MSDE: NSDC coordinated India’s participation, while MSDE is the concerned Union ministry.
  • World Tourism Day 2026: Digital Transformation of Tourism

    World Tourism Day 2026: Digital Transformation of Tourism

    Why in the News?

    • World Tourism Day 2026 will be observed on 27 September under the theme “Digital Agenda and Artificial Intelligence to Redesign Tourism”.
    • India is expanding its tourism ecosystem through AI, digital platforms, destination development, connectivity and skill development.

    Key Highlights

    • India’s tourism contribution: 5.22% of GDP.
    • Tourism employment: 8.46 crore jobs in 2023-24.
    • Domestic Tourist Visits: 428.55 crore in 2025.
    • Foreign Tourist Visits: 2.53 crore in 2025.
    • Foreign Exchange Earnings: ₹2,76,831 crore in 2025.
    • Global tourism contributed US$10.9 trillion, or 10% of global GDP, in 2024.
    • Global tourism supported 357 million jobs in 2024.
    • World Tourism Day 2026: Observed in El Salvador.
    • First celebrated: 1980.
    • Linked to adoption of UNWTO statutes in 1970.

    Digital Transformation of Tourism

    • e-Visa
      • Introduced in 2014 with Electronic Travel Authorisation for 43 countries.
      • Now available to nationals of 172 countries.
      • Entry through 88 international ports:
        • 37 airports
        • 38 seaports
        • 13 land ports
      • Around 78% of visas are issued electronically.
      • Around 95% of e-Visa applications are processed within 72 hours.
    • Incredible India Digital Platform
      • Provides virtual experiences covering cultural, heritage, adventure, gastronomical, wellness, art and craft, and rural tourism.
      • Uses AI-powered tools for personalised experiences.
      • Provides weather updates, city exploration and travel services.
      • Connects travellers with Online Travel Agents and tourism stakeholders.
    • NIDHI+
      • National Integrated Database of Hospitality Industry.
      • Digital platform for registration, recognition and classification of tourism service providers.
      • As of 23 September 2026:
        • 63,740 accommodation units
        • 54 convention centres
        • 215 food business operators
        • 1,450 online travel aggregators
        • 15,531 tourism service providers

    Major Tourism Schemes

    • Swadesh Darshan
      • Launched in 2014-15.
      • 76 projects sanctioned with over ₹5,295.24 crore.
      • Covers 15 thematic tourist circuits.
      • 75 projects physically completed.
    • Swadesh Darshan 2.0
      • Destination-centric and focused on sustainable and experience-based tourism.
      • 53 projects worth ₹2,207.08 crore sanctioned.
    • Challenge-Based Destination Development (CBDD)
      • Sub-scheme of Swadesh Darshan 2.0.
      • Focuses on holistic destination development and sustainable tourism.
      • 37 projects worth ₹687.99 crore sanctioned.
    • PRASHAD
      • Pilgrimage Rejuvenation and Spiritual, Heritage Augmentation Drive.
      • Launched in 2014-15.
      • 54 projects worth ₹1,726.18 crore sanctioned.
      • Focuses on infrastructure and visitor facilities at pilgrimage and heritage destinations.

    Tourism Infrastructure and New Segments

    • Cruise tourism
      • Sea cruise passenger traffic increased from 1.08 lakh in 2014-15 to 4.62 lakh in 2025-26.
      • International cruise terminals upgraded at Visakhapatnam, Mumbai and Chennai.
      • Puducherry added to the East Coast Cruise Circuit.
    • Lighthouse tourism
      • Promoted under Section 23 of the Marine Aids to Navigation Act, 2021.
      • Tourism facilities developed at 75 lighthouses.
    • MICE tourism
      • MICE = Meetings, Incentives, Conferences and Exhibitions.
      • Major infrastructure includes Bharat Mandapam, Yashobhoomi and Jio World Centre.
      • Government aims to develop at least 10 Indian cities as global MICE destinations.

    International Tourism Cooperation

    • BRICS Tourism Ministers’ Meeting: Held in Jaipur, August 2026.
    • Adopted the Jaipur Declaration.
    • Four priorities:
      • AI and tourism
      • Sustainable and responsible tourism
      • Tourism skilling and capacity building
      • Tourism exchanges and seamless travel facilitation

    Tourism Skill Development

    • Capacity Building for Service Providers (CBSP) provides skilling, upskilling and reskilling.
    • Hunar Se Rozgar Tak implemented under CBSP.
    • CBSP trained over 1.68 lakh people and placed more than 36,000 between FY 2020-21 and FY 2024-25.
    • Paryatan Mitra/Paryatan Didi, launched in 2024, has trained around 4,382 candidates.

    Prelims Quick Revision

    • World Tourism Day: 27 September.
    • 2026 theme: “Digital Agenda and Artificial Intelligence to Redesign Tourism”.
    • First World Tourism Day: 1980.
    • UNWTO statutes: adopted in 1970.
    • India’s tourism contribution: 5.22% of GDP.
    • Domestic Tourist Visits in 2025: 428.55 crore.
    • NIDHI+: Digital database/platform for hospitality and tourism service providers.
    • Swadesh Darshan 2.0: Destination-centric approach focused on sustainable and experience-based tourism.

    UPSC Prelims Trap

    • World Tourism Day is not first celebrated in 1970: 1970 marks adoption of the UNWTO statutes; World Tourism Day was first celebrated in 1980.
    • NIDHI+ is not a visa platform: It concerns registration, recognition and classification of tourism service providers.
    • Swadesh Darshan vs Swadesh Darshan 2.0: The original scheme focuses on thematic tourism circuits, while Swadesh Darshan 2.0 adopts a destination-centric approach.
    • PRASHAD is not a general tourism infrastructure scheme: It specifically focuses on pilgrimage and heritage destinations.
  • Life of buildings to gold: Lesser known changes in GDP series

    Why in the News

    The new Gross Domestic Product (GDP) series splits a mixed firm’s output by activity rather than by major activity, and assumes dwellings last 60 to 75 years, not 70 to 80. Both are among five lesser known changes in the Ministry of Statistics and Programme Implementation (MoSPI)‘s ‘Sources and Methods’.

    What is the new GDP series, and what has dominated the debate?

    1. What it is: A GDP series measures output against a base year, whose prices and structure act as a fixed yardstick. The new series moves the base from 2011-12 to 2022-23.
    2. Why the base is updated: An old base misses how the economy has changed, leaving newer sectors and data sources out or wrongly weighted.
    3. The five headline changes: Most debate has covered:
      • the updated base year;
      • double deflation, which adjusts both output and inputs for price changes to get real gross value added (GVA);
      • two price indices for that deflation, the output Producer Price Index and the Banking Services Price Index, tracking prices producers and banks charge;
      • better informal sector estimates from surveys;
      • no gap between GDP measured by production and GDP measured by spending.
    4. The takeaway: The quieter changes decide what counts as output and savings, so they shape the numbers as much as the headline ones.

    How is a multi-activity enterprise now classified?

    1. Old rule, major activity: A firm doing both manufacturing and services was placed wholly in the sector of its major activity.
    2. New rule, activity share: GVA is now split by activity. Eg. Of a firm’s Rs 50 GVA, Rs 20 earned from services now goes to services.
    3. Data that makes it possible: Companies file annual returns, forms MGT-7 (public and private companies) and MGT-7A (one person and small companies), with the Ministry of Corporate Affairs. These report results, shareholding and loans.

    What else is now counted or measured differently?

    1. Government housing: Housing given to government staff was not valued before, unlike House Rent Allowance paid in cash. It is now valued at building cost, less repair, maintenance and annual wear.
    2. Useful life of buildings: Dwellings are now assumed to last 60 to 75 years, down from 70 to 80, so they wear out faster each year.
    3. Household financial savings: Data on shares, debentures and mutual funds now come from the Securities and Exchange Board of India (SEBI), not the Reserve Bank of India.
    4. Physical savings: Household savings also include physical assets and valuables such as gold.
    5. Rooftop solar: Power households generate from their own rooftop panels is now counted in the utilities sub-sector. Its real GVA was Rs 1.92 lakh crore in April to June 2026.

    Why do these changes matter?

    1. Truer sector picture: Splitting a firm’s GVA shows the real size of services inside manufacturing companies, which matters for industrial and trade policy.
    2. Higher capital consumption: A shorter asset life raises the yearly wear charged on buildings, so net measures of output and savings fall.
    3. Wider savings coverage: Pooled funds such as Real Estate Investment Trusts and Alternative Investment Funds now enter household savings.
    4. Hidden output recognised: Counting government housing and self generated solar power records services that earlier went unmeasured.

    Challenges

    1. Comparability with the old series: Methods differ from the 2011-12 series, so long run comparisons need a back series, meaning old years recalculated by the new method.
    2. Dependence on company filings: Splitting GVA relies on MGT-7 data, which covers companies and not the unincorporated sector.
    3. Estimation assumptions: Asset lives and imputed values such as government housing rest on assumptions that users cannot easily test.

    Way Forward

    1. Publish a back series: MoSPI should release a linked series so growth before and after 2022-23 can be compared.
    2. Extend activity data: Use enterprise surveys to split activity shares for unincorporated firms as well.
    3. Explain assumptions openly: Publish the basis for asset lives and imputed values so analysts can test them.

    Conclusion

    The new series changes not only the base year but also what the economy is judged to produce, own and save. What to watch is whether MoSPI publishes a back series linking the new figures to a decade of old ones.

    Back2Basics: Back series

    1. What it is: A back series re-estimates GDP for years before the new base year, using the new series’ methods and data.
    2. Why it is needed: Without it, old and new years use different yardsticks, so a change in method can look like a change in growth.
    3. How it is built: Where new data do not reach back, the two series are spliced, scaling old figures by their ratio in a common year.

    Matching Previous Year Question

    “[2019] Consider the following statements: 1.Purchasing Power Parity (PPP) exchange rates are calculated by comparing the prices of the same basket of goods and services in different countries. 2.In terms of PPP dollars, India is the sixth largest economy in the world. Which of the statements given above is/are correct? (a) 1 only (b) 2 only (c) Both 1 and 2 (d) Neither 1 nor 2 (a) 1 only (b) 2 only (c) Both 1 and 2 (d) Neither 1 nor 2 Answer: (a)”

  • Why bank unions are going on strike

    Why in the News

    The United Forum of Bank Unions, claiming seven unions and around 90 percent of banking employees, has called a three day nationwide strike from 28 to 30 September, with an indefinite strike threatened from 26 October. The demand driving it, a five day banking week, has already been accepted by the banks’ own representative body and sent to the government. The strike is aimed at a decision the employers cannot take.

    What are the four demands?

    1. Five day banking week: All Saturdays should become bank holidays, so branches work Monday to Friday.
    2. Performance linked incentive scheme: The government’s revised incentive scheme should be changed, because it rewards only the senior grades.
    3. Bilateral discussion on that scheme: The scheme should be settled by negotiation with the unions, not by a government order.
    4. Pending issues: Items left outstanding from earlier wage settlements should be closed.

    Why has the five day week not closed?

    1. What it would change: Branches now close on the second and fourth Saturdays, and the unions want every Saturday closed, with weekday hours lengthened so customer hours do not fall.
    2. The employers already agreed: The Indian Banks’ Association, the representative body of banks in India, accepted the demand and sent it to the government more than two years ago.
    3. Why bargaining cannot finish it: Pay and hours are set by bipartite settlements between the unions and the banks. A bank holiday is notified by government under the Negotiable Instruments Act, 1881.
    4. The government’s position: The finance ministry says the proposal remains under consideration with several stakeholders to be weighed, and has asked the unions to defer the strike.
    5. The takeaway: A demand both sides at the table have settled cannot be implemented, because the authority that decides it does not sit at the table.

    Why is the incentive scheme contested?

    1. What the scheme is: The performance linked incentive was introduced in the 2020 wage settlement and paid staff according to their own bank’s performance.
    2. What the revision did: A revised government scheme covers Grade 4A officers and above, so the lower scales get nothing, which is why officers’ associations opposed it.

    What will the strike disrupt?

    1. Timing is the pressure point: The strike ends on 30 September, the half yearly closing date, when banks must close their books for the half year.
    2. Branches carry the impact: Cash deposits and withdrawals, cheque clearing and account related work at public sector branches face disruption.
    3. Where service continues: Unified Payments Interface, internet banking and automated teller machines are expected to keep running, and private bank branches to function largely as usual.
    4. Sunday opening to shorten the gap: Public sector and regional rural banks opened on Sunday, because a weekend followed by three strike days would close branches for five days running.
    5. Contingency steps: The finance ministry has asked banks to keep automated teller machines stocked, and banks have advised customers to finish time sensitive work early.

    Challenges

    1. A settled bargain with no closing authority: Bipartite settlements can agree hours, but only government can convert them into a banking holiday, so agreement alone changes nothing.
    2. Incentive design splits the workforce: A scheme confined to senior grades sets officers against clerical staff inside the same union platform.
    3. Digital channels reduce the strike’s reach: With most retail transactions on the Unified Payments Interface and automated teller machines, a branch strike reaches fewer customers each year.
    4. Rural branches absorb the gap: Cash dependent customers have no digital substitute, so a branch closure falls unevenly. Eg. regional rural bank branches.

    Way Forward

    1. Give the proposal a dated decision: The finance ministry should fix a deadline for deciding the five day banking proposal.
    2. Bring the notifying authority into the talks: Since bank holidays are notified by government, involve the Department of Financial Services and State governments before a settlement on working days is signed.
    3. Extend the incentive across scales: Link the incentive to bank level performance for every grade, so the scheme does not divide the workforce it motivates.
    4. Agree an essential services protocol: Settle with the unions which functions continue during a strike, covering cash logistics and cheque clearing.

    Conclusion

    A demand the employers accepted cannot be delivered by the employers, because the working days of banks are fixed by government notification rather than by a wage settlement. What to watch is whether a decision arrives before the indefinite strike the unions have threatened.

    Matching Previous Year Question

    “[2024, GS3, 15 marks] Discuss the merits and demerits of the four ‘Labour Codes’ in the context of labour market reforms in India. What has been the progress so far in this regard?”

  • Growth holds up for now. Inflation clouds outlook

    Why in the News

    Global agencies have raised their full year growth estimates for India to about 7 per cent. The upgrades follow the first quarter Gross Domestic Product (GDP) estimates. Those estimates recorded stronger economic momentum than expected. The same agencies expect that momentum to fade in the second half of the fiscal year. They also project average inflation of 5.1 per cent and a higher policy rate. The growth upgrade therefore arrives with the case for tighter money attached to it.

    Why have the growth forecasts been raised?

    1. Asian Development Bank: The bank now pegs growth at 7 per cent for the year. Its earlier forecast was 6.6 per cent.
    2. S&P Global: The agency forecasts the economy to grow at 7 per cent.
    3. Organisation for Economic Cooperation and Development (OECD): The OECD has raised its projection from 6.3 per cent to 7.1 per cent.
    4. Moody’s: The agency had earlier raised its growth forecast for the year to 7 per cent, up from 6 per cent.

    What is carrying growth in the first half?

    1. Conflict in West Asia: Concerns persist over economic activity being affected by the conflict in West Asia. Growth has held up through those concerns.
    2. Industrial production: The Index of Industrial Production (IIP), a volume measure of output in mining, manufacturing and electricity, grew at 6.3 per cent during April to July. Manufacturing grew at 7 per cent.
    3. Central capital spending: Capital expenditure by the Centre has surged by almost 30 per cent during April to July this year.
    4. Merchandise exports: Goods exports grew at 17.8 per cent during April to August. A weak currency aided that growth.

    Why is the second half expected to be weaker?

    1. Fading tax tailwinds: S&P Global expects growth to ease in the second half of the fiscal year as the tailwinds from sales tax rationalisation and income tax cuts diminish.
    2. Momentum into 2027: The OECD expects momentum to weaken before a gradual recovery takes place in 2027.
    3. Farm sector risk: The farm sector has emerged as a key area of risk. The Asian Development Bank states that an El Nino worse than expected could reduce agricultural output and raise food inflation across the wider region.

    What do the same forecasts imply for monetary policy?

    1. Price pressures: Price pressures are building up in the economy. Expectations of higher interest rates have gained traction.
    2. Inflation path and the policy rate: S&P Global expects inflation to average 5.1 per cent. It expects the Reserve Bank of India (RBI) to raise its policy rate by 25 basis points in the current fiscal year.
    3. A temporary rise in rates: The OECD projects India to raise policy rates temporarily to offset stronger inflationary pressures.
    4. The next decision point: The central bank’s monetary policy committee meets in a few weeks. The growth and inflation dynamics tilt the scales towards tighter policy.

    Conclusion

    Growth readings and price readings are now pointing in opposite directions. The upgrades rest on a first half that the forecasters themselves do not expect to repeat. What remains unsettled is whether output can hold its pace once borrowing costs rise and a poor farm season arrives together. The next monetary policy review is the first place that question gets tested.

    Back2Basics: India’s Inflation Targeting Framework

    1. The target: The government has retained a Consumer Price Index (CPI) inflation target of 4 per cent for the period April 2026 to March 2031.
    2. Legal basis: Section 45ZA of the Reserve Bank of India Act, 1934 requires the target to be reset every five years.
    3. Who sets the rate: A six member monetary policy committee sets the repo rate. The combined Consumer Price Index published by the National Statistical Office is the target measure.
    4. Accountability: A breach of the 2 to 6 per cent tolerance band for three consecutive quarters obliges the RBI to report to the government.

    Matching Previous Year Question

    “[2019, GS3, 10 marks] Do you agree with the view that steady GDP growth and low inflation have left the Indian economy in good shape? Give reasons in support of your arguments.”