Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS3-01.Indian Economy and issues relating to planning, mobilization of resources, growth, development and employment.

  • Banks can’t use force to seize vehicles over loan default: SC

    Why in the News

    The Supreme Court has reiterated that banks and Non-Banking Financial Companies (NBFCs), which are Reserve Bank of India registered lenders that extend credit without holding a banking licence, cannot use force to seize financed vehicles in loan default cases. A two judge Bench recorded that the guidelines the Reserve Bank of India (RBI) issued to prevent exactly this have “existed only on paper, and no steps have been taken to implement it”. The ruling answers the Court’s own decision in Manager, ICICI Bank Ltd vs Prakash Kaur and Others (2007), which held that recovery of loans and seizure of vehicles can be made only through legal means. The tension the Court set out is between a financier’s contractual right to take possession without going to court, and a borrower’s entitlement to notice and due process before losing the asset he earns his living from.

    What is the Fair Practices Code for Lenders?

    1. What it is: It is a set of RBI guidelines, issued on 5 May 2003, governing how lenders may conduct loan recovery.
    2. What it bars: It states that in matters of recovery, lenders should not resort to undue harassment, including persistently bothering borrowers at odd hours and the use of muscle power for recovery.
    3. Status of the instrument: It operates as a supervisory direction on regulated entities rather than as a penal statute, so compliance turns on the regulator enforcing it.

    On what basis can a financier repossess a vehicle at all?

    1. Repossession as a contractual right: The right to take possession of a financed vehicle in the first instance is a matter of contract between the lender and the borrower.
    2. Commercial purpose of the right: Such clauses make it commercially feasible for institutions to extend credit against the security of the financed asset to borrowers of modest means.
    3. Why it demands strict reading: The right operates outside the supervision of a court at the first instance, so it must be construed with great circumspection.
    4. What happens if it is left unchecked: Read loosely, it becomes a licence to seize property by stealth, by force or in the dead of night, converting a facility meant to promote financial inclusion into an instrument of oppression against the class it was designed to serve.

    Why was this particular repossession held unlawful?

    1. How the vehicle was taken: Four unidentified persons broke the truck’s steering lock at about 1 am on 9 April 2023 while it stood parked after a delivery at a godown in Ayodhya, and drove it away.
    2. Absence of notice: No seven-day notice was issued to the borrower before repossession, and the sale proceeds were adjusted before he was asked to pay the outstanding amount.
    3. The Court’s characterisation: Taking possession by breaking open the steering lock bears every mark of the “goondaism” that the Court in Prakash Kaur and the RBI in its successive guidelines have condemned.
    4. The loan clause itself: The agreement placed the borrower entirely at the mercy of the financier’s unilateral discretion, both on whether notice would be given at all and on the manner and timing of the sale. The Bench held this to be in consonance with neither the RBI guidelines nor the provisions of the Indian Contract Act, 1872.

    What did the Court order, and what does it demand of the regulator?

    1. Compensation to the borrower: The Bench ordered payment of compensation for violation of the borrower’s constitutional rights, treating a private recovery action as engaging rights rather than as a purely contractual dispute.
    2. Direction to the regulator: The RBI was directed to take effective steps to secure genuine compliance with its guidelines and circulars.
    3. The balance the Court named: The failure identified was of the balance between the financier’s legitimate need for an efficient recovery mechanism and the borrower’s equally legitimate entitlement to fair treatment before being deprived of the asset by which he earns his bread.
    4. Route the case took: The Chief Judicial Magistrate’s court at Ayodhya and the Allahabad High Court had earlier dismissed the borrower’s plea, so relief came only at the third tier.

    Challenges to enforcing the Fair Practices Code

    1. A direction without a penalty: The Code binds regulated entities but attaches no automatic consequence to a breach in an individual recovery. Eg. The Court found the 2003 guidelines had existed only on paper for over two decades.
      The Fix: Attach a defined monetary penalty and a compensation floor to each proved instance of forcible repossession, payable by the lender to the borrower without separate litigation.
    2. Outsourced recovery breaks the accountability chain: Lenders engage third party recovery agents, and the agent’s conduct is difficult to attribute to the regulated entity. Eg. The Prakash Kaur ruling of 2007 turned on banks employing “goondas” to take possession of vehicles.
      The Fix: Make the lender vicariously liable in the circular itself for every act of a contracted recovery agent, with the agent’s identity recorded against the loan account.
    3. Borrowers cannot realistically litigate: A commercial vehicle borrower who loses the asset also loses the income needed to fund a case through three tiers. Eg. This borrower’s plea was dismissed by a magistrate’s court and a High Court before the Supreme Court heard it.
      The Fix: Route repossession complaints to the RBI Ombudsman with a fixed timeline, so the first remedy is administrative rather than judicial.
    4. One-sided loan contracts: Standard-form agreements let the lender decide unilaterally whether notice is given and when the asset is sold. Eg. The clause in this case left both notice and the timing of sale to the financier’s discretion.
      The Fix: Prescribe a mandatory model repossession clause, carrying a minimum notice period and a floor price mechanism for sale, that no lender may contract out of.
    5. Supervisory attention follows systemic risk, not conduct: Prudential supervision of NBFCs concentrates on capital and asset quality rather than on recovery conduct at the branch level. Eg. Digital lending recovery practices drew RBI action only after the 2021 working group report on digital lending.
      The Fix: Add a conduct-compliance return on recovery complaints to the periodic supervisory reporting NBFCs already file.

    Conclusion

    The prohibition on forcible seizure was settled in 2007 and has been restated now because restating it has not been enough. What is new is the direction to the RBI, which moves the problem from the borrower’s ability to litigate to the regulator’s willingness to supervise its own conduct rules. The measure to watch is whether the RBI converts the Fair Practices Code into a reporting and penalty framework rather than a circular, and whether repossession complaints begin to be resolved before they reach a court.

    Back2Basics: Non-Banking Financial Companies

    1. What they are: Companies registered under the Companies Act, 2013 that lend, invest or acquire financial assets, without holding a banking licence.
    2. Registration and supervision: They must register with the RBI under the Reserve Bank of India Act, 1934, and are supervised by it.
    3. How they differ from banks: They cannot accept demand deposits, are not part of the payment and settlement system, and cannot issue cheques drawn on themselves.
    4. Deposit insurance: Deposit insurance cover from the Deposit Insurance and Credit Guarantee Corporation is not available to NBFC depositors.

    Matching Previous Year Question

    “No direct PYQ traced in the provided files”
  • Social security net widens: Govt nod for raising EPFO wage ceiling to Rs 25,000

    Why in the News

    The Union Cabinet has approved raising the mandatory wage ceiling for subscribers of the Employees’ Provident Fund Organisation (EPFO), the statutory body that runs India’s largest contributory retirement savings system, from Rs 15,000 to Rs 25,000 a month. The last revision came in September 2014, when the ceiling moved from Rs 6,500 to Rs 15,000. The stated reason for acting now is sustained wage growth, rising incomes and the continued expansion of formal employment over the intervening years. The revision widens mandatory coverage by about 51 lakh workers, and it also raises what employers must set aside for every worker earning between Rs 15,000 and Rs 25,000. The contested point is who absorbs that higher cost, since employers may adjust it inside the existing cost-to-company structure and reduce take-home pay.

    What is the EPFO wage ceiling?

    1. Statutory wage ceiling: It is the monthly wage level up to which provident fund contributions are compulsory for both the employee and the employer. Contributions above that level are voluntary rather than mandated.
    2. Wage base it is applied to: The ceiling applies to basic salary, dearness allowance and retaining allowance where one is paid, not to gross salary.
    3. Coverage trigger: A worker earning at or below the ceiling must be enrolled, so raising the ceiling pulls a fresh band of salaried workers into statutory coverage rather than leaving their savings to voluntary choice.
    4. What it governs beyond savings: The same ceiling fixes the wage on which pension and insurance entitlements are calculated, so it sets the size of the benefit and not only the size of the deduction.

    What changes in contributions and pension after the revision?

    1. Contribution rate: Employees and employers each contribute 12% of the wage base. The employee’s entire share goes to the Employees’ Provident Fund (EPF).
    2. Split of the employer’s share: Of the employer’s 12%, 3.67% goes to EPF and 8.33% goes to the Employees’ Pension Scheme (EPS), the defined-benefit pension arm.
    3. Pension contribution cap: The monthly EPS contribution is capped at Rs 2,080, up from Rs 1,250. Employees make no contribution of their own to the pension scheme.
    4. The Centre’s own share: The government contributes 1.16% towards an employee’s pension up to the wage ceiling, so the higher ceiling raises the Centre’s per-worker liability automatically.
    5. Effect on a single worker: Total EPF contribution for a worker is expected to rise by about Rs 600 a month on average, as per official estimates.

    Who does the wider net cover, and at what fiscal cost?

    1. Additional coverage: About 51 lakh more employees come under the EPFO’s ambit. Over 8 crore workers will be mandated to contribute up to the Rs 25,000 wage limit.
    2. Three benefits widened at once: The higher ceiling expands access to provident fund savings, pension protection under EPS and insurance protection under the Employees’ Deposit Linked Insurance Scheme (EDLI), which pays a lump sum to the nominee of a member who dies in service.
    3. Additional budgetary cost: The Centre bears an added Rs 1,089 crore. Annual government outgo on pension contributions rises to about Rs 11,339 crore against existing budgetary support of about Rs 10,250 crore.
    4. Date of effect: The revised ceiling takes effect from 18 September 2026, which the Labour and Employment Ministry marked as Vishwakarma Puja.

    Why had the ceiling stayed unchanged for 12 years?

    1. Gap since the last revision: The previous revision came in September 2014, when the ceiling moved from Rs 6,500 to Rs 15,000, and that level then stood unchanged for 12 years.
    2. Statutory ceiling below statutory minimum wages: At least seven major States and Union Territories already fix minimum wages for unskilled workers above the old Rs 15,000 ceiling. Eg. Delhi at Rs 17,800, Maharashtra Rs 17,000, Karnataka Rs 16,800, Haryana Rs 16,500, Gujarat Rs 16,000, Rajasthan Rs 15,500 and Uttarakhand Rs 15,220.
    3. Signalling effect on the labour market: A ceiling set above every State minimum wage signals a higher reference wage scale for workers to States and to employers.
    4. Framework realignment: The revision lets the statutory contribution and pensionable-wage framework track prevailing wage levels rather than wage levels of a decade ago.

    Challenges to the higher EPFO wage ceiling

    1. Absorption inside cost-to-company: Employers may absorb the higher contribution within the existing cost-to-company structure, so the worker funds a larger part of a benefit that is formally split. Eg. An employee drawing Rs 22,000 a month gains statutory coverage and loses monthly take-home pay at the same time.
      The Fix: Issue the revised wage ceiling guidelines with an explicit restatement that the employer’s provident fund share cannot be deducted from the employee’s pay, backed by inspection of pay structures in the affected band.
    2. Cost pressure on small employers: Higher provident fund, pension and insurance liabilities land hardest on labour-intensive units with thin margins. Eg. Manufacturing units and micro, small and medium enterprises face higher operating costs in the short run.
      The Fix: Extend an employer-share support window for newly covered workers in small units, on the design already used for employment-linked incentive support.
    3. Informality is untouched: The statutory framework applies to establishments with 20 or more employees, so the vast majority of India’s workers remain outside it whatever the ceiling. Eg. Casual and own-account workers in construction and retail gain nothing from a ceiling revision.
      The Fix: Link the revised ceiling to universal registration of workers on the e-Shram database, so coverage expands by widening the base and not only by raising the wage line.
    4. Pension adequacy: A pension calculated on a capped pensionable wage still delivers a small monthly pension after decades of service. Eg. The minimum monthly pension under the Employees’ Pension Scheme has stood at Rs 1,000 since 2014.
      The Fix: Fix a periodic statutory review cycle for both the wage ceiling and the minimum pension, so neither depends on a discretionary decision once in 12 years.
    5. Contested exit and withdrawal rules: Frequent changes to withdrawal and settlement rules reduce the predictability that a long-horizon savings product depends on. Eg. The 2016 proposal to restrict full provident fund withdrawal before retirement was rolled back after protests.
      The Fix: Settle withdrawal rules through the tripartite Central Board of Trustees with a stated notice period before any change takes effect.

    Conclusion

    Coverage and adequacy have moved together for the first time in over a decade in this scheme. The revision settles the width of the statutory net; it leaves open who ultimately pays for the widening. The test is whether the guidelines still to be issued hold employers to the rule that their share cannot be recovered from wages, and whether the newly covered band sees its take-home pay protected in the first pay cycles after 18 September 2026.

    Back2Basics: Employees’ Provident Fund Organisation

    1. Governing statute: It functions under the Employees’ Provident Funds and Miscellaneous Provisions Act, 1952, and is administered by the Ministry of Labour and Employment.
    2. Applicability: The Act applies to notified establishments employing 20 or more persons.
    3. Three schemes it runs: The Employees’ Provident Fund Scheme, 1952, the Employees’ Pension Scheme, 1995 and the Employees’ Deposit Linked Insurance Scheme, 1976.
    4. Governance: It is steered by the tripartite Central Board of Trustees, which carries representatives of the Centre, State governments, employers and employees.

    Matching Previous Year Question

    “With reference to casual workers employed in India, consider the following statements: 1.All casual workers are entitled to Employees Provident Fund coverage. 2.All casual workers are entitled to regular working hours and overtime payment. 3.The government can, by notification, specify that an establishment or industry shall pay wages only through its bank account. Which of the above statements are correct?”

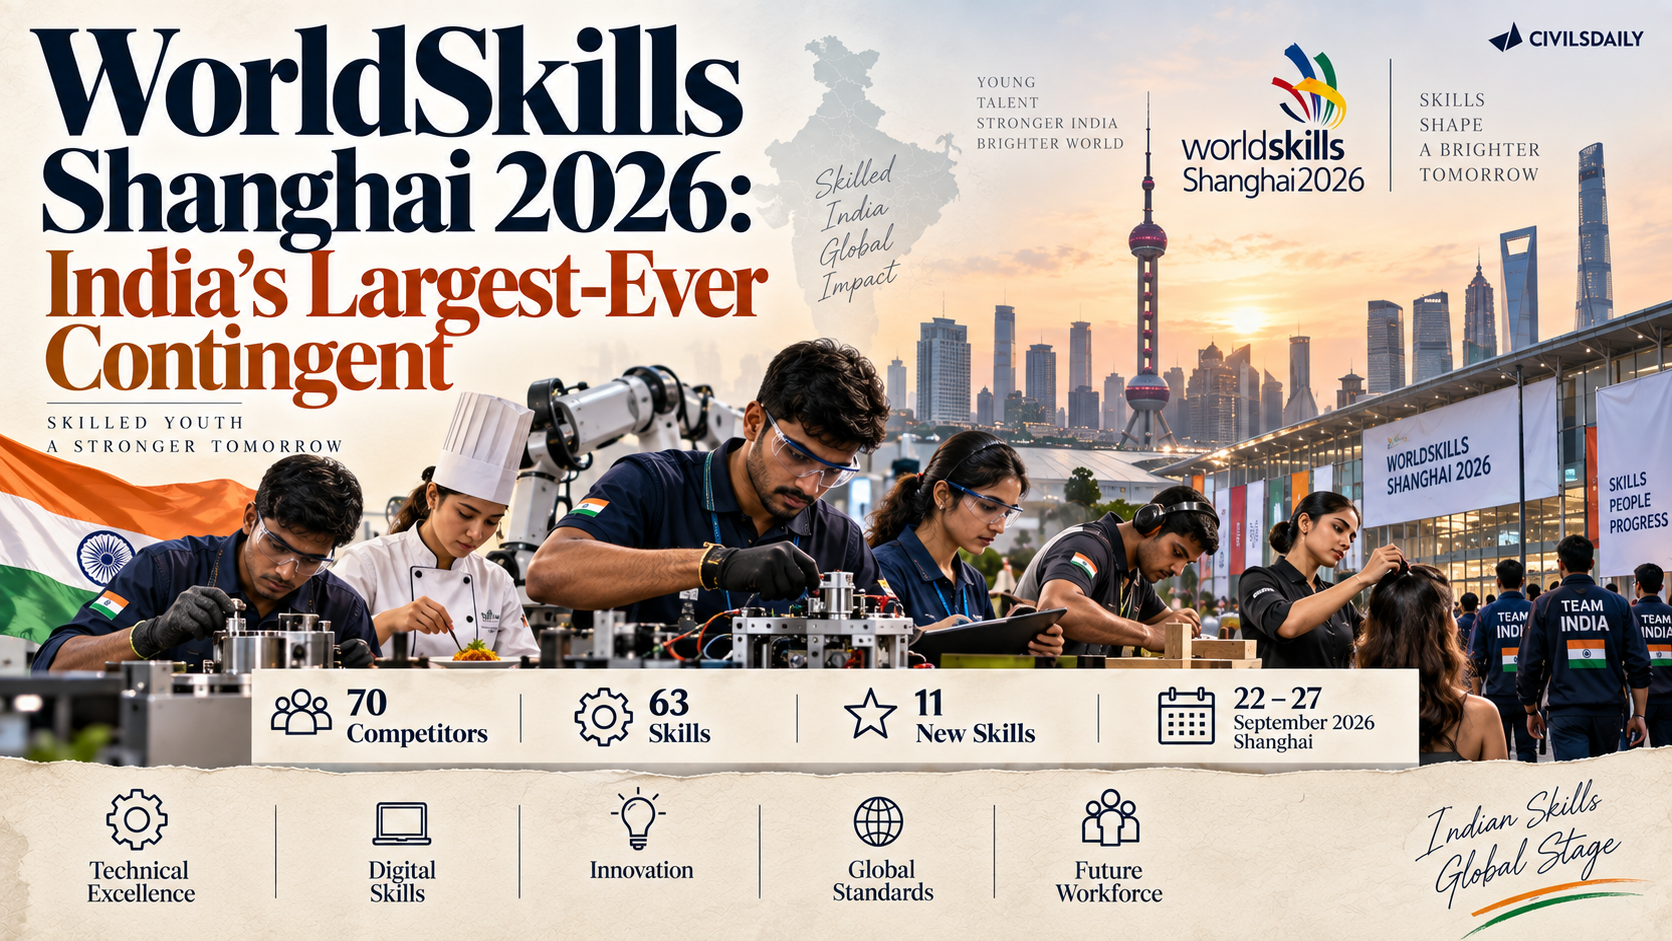
  • WorldSkills Shanghai 2026: India’s Largest-Ever Contingent

    WorldSkills Shanghai 2026: India’s Largest-Ever Contingent

    Why in the News?

    India has flagged off its largest-ever 70-member contingent for the 48th WorldSkills Competition, to be held in Shanghai from 22-27 September 2026.

    Key Highlights

    • 70 competitors representing India.
    • Competing across 63 skill categories.
    • India will debut in 11 new-age skill categories.
    • WorldSkills Shanghai: 1,400+ competitors from 60+ countries/regions.
    • Focus: technical excellence, innovation, creativity and craftsmanship.

    11 New Skill Categories

    • Dental Prosthetics
    • Digital Interactive Media Design
    • Intelligent Security Technology
    • Landscape Gardening
    • Optoelectronic Technology
    • Retail Sales
    • Unmanned Aerial Systems
    • Industrial Mechanics
    • Software Testing
    • Heavy Vehicle Technology
    • Aircraft Maintenance

    India’s Performance

    • WorldSkills ranking improved from 29th (2015) to 13th (WorldSkills Lyon 2024).
    • Lyon 2024: 4 Bronze Medals + 12 Medallions for Excellence.
    • 8th position in Asia at WorldSkills Asia 2025.

    What is WorldSkills?

    • WorldSkills International is a global organisation that promotes vocational education, technical skills and excellence in skilled professions.
    • The competition works like an international championship for skills. Competitors demonstrate practical expertise under standardized conditions and are assessed against international benchmarks.

    India and WorldSkills

    • India has been a member of WorldSkills International since 2007.
    • The country’s participation is closely linked with the Skill India ecosystem and efforts to improve the quality, employability and international competitiveness of India’s workforce.

    WorldSkills India Champions Club

    • First cohort of 16 former competitors and medallists inducted.
    • Aim: mentor aspiring competitors and promote India’s skills ecosystem.

    Important Full Forms

    • MSDE: Ministry of Skill Development and Entrepreneurship
    • NSDC: National Skill Development Corporation
    • ICAR: Indian Council of Agricultural Research

    Prelims Quick Revision

    • WorldSkills Competition: Major international competition promoting excellence in vocational skills.
    • 2026 edition: Shanghai, China.
    • India: 70-member contingent, 63 skill categories.
    • WorldSkills Lyon 2024: India ranked 13th.
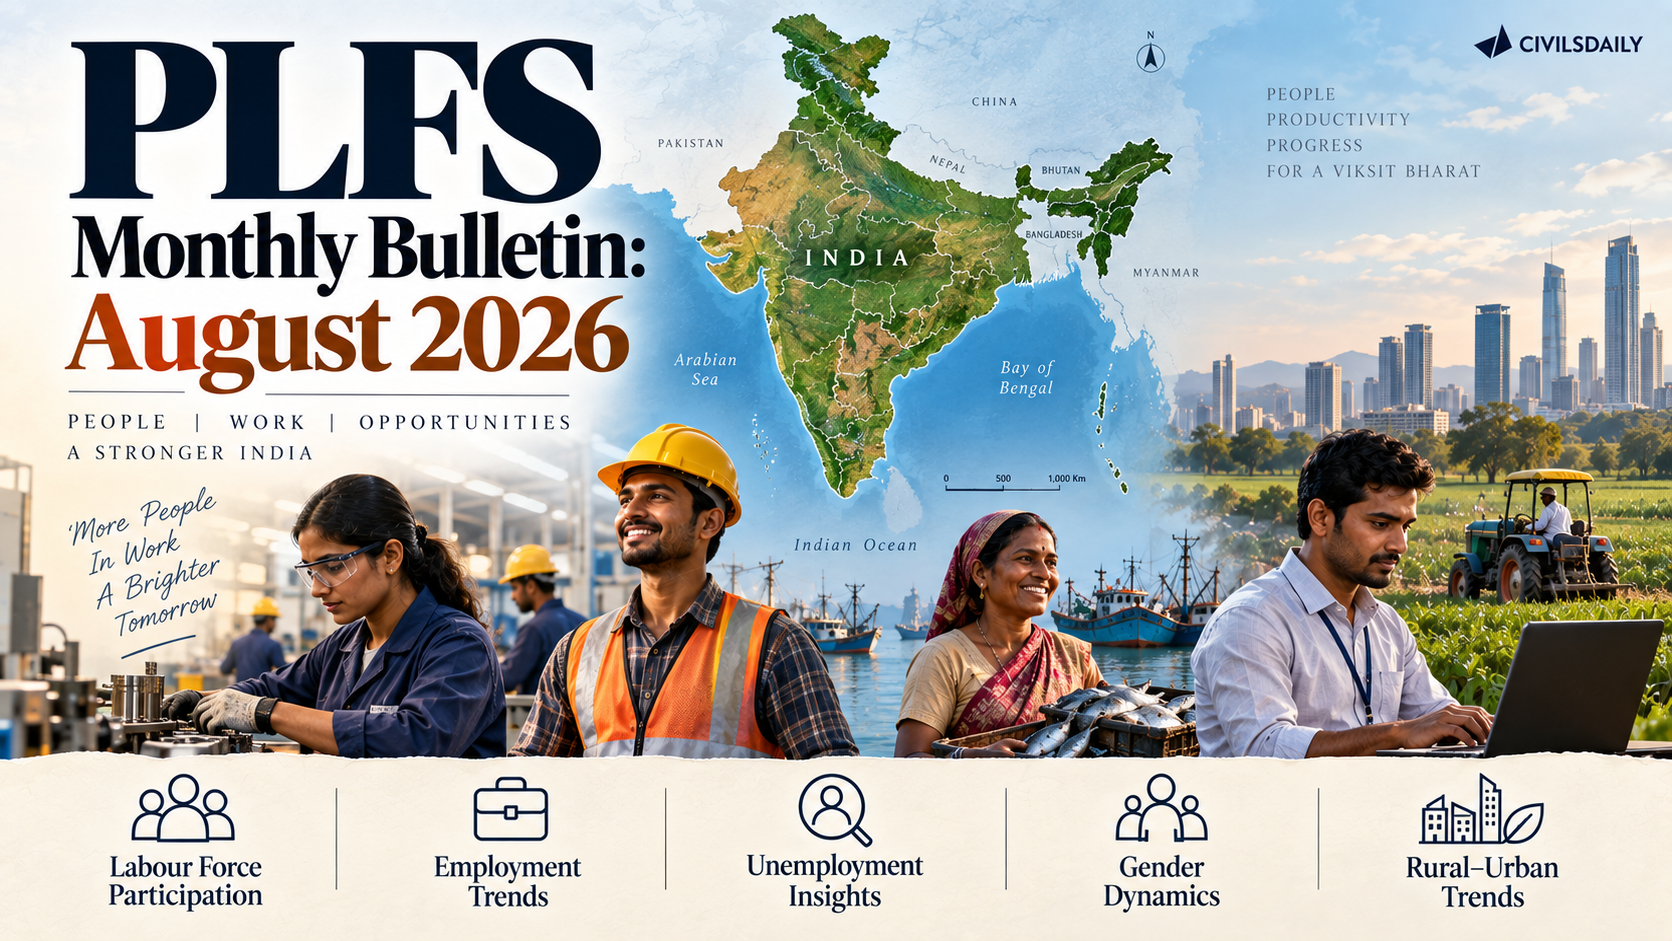
  • PLFS Monthly Bulletin: August 2026

    PLFS Monthly Bulletin: August 2026

    Why in the News?

    The Periodic Labour Force Survey (PLFS) August 2026 bulletin shows stronger labour force participation, mainly driven by rural areas.

    Key Findings

    • Overall LFPR: 55.6%, up from 55.4% in July.
    • Rural LFPR: 58.2%, up 1.2 percentage points YoY.
    • Female LFPR: 34.8%, up from 33.7% in August 2025.
    • Overall WPR: 52.8%, highest since March 2026.
    • Rural WPR: 55.8%, up 1.3 percentage points YoY.
    • Overall UR: 5.0%, broadly stable.
    • Rural UR: 4.1%, lowest since January 2026.
    • Urban UR: 6.8%.

    Gender Trends

    • Female LFPR increased to 34.8%.
    • Rural female LFPR: 39.4%.
    • Urban female LFPR: 25.4%.
    • Overall female WPR increased to 33.0% from 32.0% a year earlier.

    Survey Details

    • 3,70,160 persons surveyed.
    • Rural: 2,11,353
    • Urban: 1,58,807
    • Monthly estimates use the Current Weekly Status (CWS) approach.

    Important Full Forms

    • PLFS: Periodic Labour Force Survey
    • NSO: National Statistical Office
    • MoSPI: Ministry of Statistics and Programme Implementation
    • LFPR: Labour Force Participation Rate
    • WPR: Worker Population Ratio
    • UR: Unemployment Rate
    • CWS: Current Weekly Status

    Prelims Quick Revision

    • LFPR = proportion of population participating in the labour force.
    • WPR = proportion of population that is employed.
    • UR = proportion of labour force that is unemployed.
    • PLFS is conducted by NSO under MoSPI.
    • Since January 2025, PLFS methodology provides monthly and quarterly labour market estimates.
  • Sugar rush, chip price surge: RBI rate hike looms as price pressures spread

    Why in the News

    Retail inflation rose to an eight month high of 4.82 percent in August, with wholesale inflation at 9.92 percent and producers’ output price inflation at 9.81 percent. The increase was concentrated in two small parts of the consumption basket, sugar and goods built around memory chips, both of which had until now been read as contained supply side pressures. Economists expect the Monetary Policy Committee (MPC) to raise the policy repo rate by 25 basis points to 5.5 percent on 7 October, which would be the first rate increase in three and a half years. The contested point is whether this is a supply shock that will pass, as the committee held in August, or the start of a generalised rise in prices.

    What is the Monetary Policy Committee’s inflation target?

    1. Monetary Policy Committee: It is the statutory committee that fixes the policy repo rate, the rate at which the Reserve Bank of India (RBI) lends overnight to banks against government securities.
    2. The target is retail, not wholesale: RBI’s inflation target is defined in terms of retail inflation measured by the Consumer Price Index (CPI), so wholesale and producer price numbers inform the decision without setting it.
    3. What a rate rise is meant to do: Raising the repo rate raises the cost of funds for banks, which is intended to slow credit growth and demand, and through them the pace of price increases.

    Why did sugar prices drive the headline number?

    1. Sugar price index: It soared 19 percent in August over July, with a year on year inflation rate of 24 percent.
    2. Spread within the category: Jaggery rose 8 percent from July, candy and misri 3 percent, sweets prepared with and without milk around 1.5 percent, cake, pastry and bread 0.6 percent, and jams 0.5 percent.
    3. Category level movement: The sugar, confectionery and desserts index rose 7.6 percent from July to August and stood 10.8 percent above a year earlier.
    4. Weight against contribution: The category is only 1.4 percent of the CPI basket, yet contributed around 15 basis points to the headline rate and was one of the largest drivers of food price momentum, per Emkay Global Financial Services.
    5. The supply response: The Centre allowed duty free imports of up to 10 lakh tonnes of raw sugar until 31 October, after domestic prices spiked on lower than expected production and multi year low inventories.
    6. Prices kept climbing: Department of Consumer Affairs data put the all India average retail price of sugar 10 percent higher in the first half of September, at Rs 60.85 per kg.

    What is chipflation adding to retail inflation?

    1. Chipflation: The term describes consumer price increases traced back to the rising cost of memory chips embedded in everyday goods.
    2. Scale of the chip price rise: Dynamic Random Access Memory (DRAM) chip prices are expected to be up over 400 percent from the start of 2024 to the end of 2026.
    3. The historical break: For the preceding seventy or so years DRAM prices fell by 90 percent every five years, so the direction itself has reversed.
    4. Where it surfaces in the CPI: Inflation for information and communication equipment rose to 2.95 percent in August, after its price index rose sequentially for the ninth month running.
    5. The wider category: Inflation for the broader information and communication category more than tripled to 2.01 percent in August from 0.63 percent in July, with its price index up 1.4 percent over the month.
    6. Beyond phones and computers: Refrigerators, washing machines and air conditioners also carry memory chips, so the price effect of the global artificial intelligence boom reaches household durables.

    How far have price pressures spread across the basket?

    1. Items inflating above 4 percent: The count rose from 65 in January to 110 in August, out of the 358 items the CPI basket contains.
    2. Items dearer over the month: Prices of 314 of the 358 items were higher in August than in July, against 236 on the same measure in February.
    3. Weight of the two named drivers: Sugar, confectionery and desserts together with information and communication make up only about 5 percent of the CPI, so the spread is happening outside them.
    4. How generalisation works: A price rise in one input spreads when businesses reprice their own output to protect margins. Eg. Commercial cooking gas turned expensive during the West Asia war, and restaurants and cafes then raised menu prices sharply.

    Why do economists reject the supply shock reading?

    1. The committee’s August position: The MPC held that it would wait to see price pressures become more general, and described the increase then visible as a supply shock.
    2. The counter argument: ICICI Securities Primary Dealership stated that this position does not hold up to scrutiny, since input price pressures are already visible in Producer Price Index measures, which track prices received by domestic producers.
    3. The global synchrony: Those producer price pressures are appearing simultaneously across economies, including China, which is known for producer price deflation rather than inflation.
    4. The demand condition: Pass through from producer to consumer prices is treated as a question of timing rather than of possibility wherever underlying demand is running strong, as in India.

    Challenges to inflation targeting through the repo rate

    1. Supply driven food inflation resists rate action: A rate increase compresses demand and cannot add a single tonne to sugar or cereal supply within the season it is announced. Eg. The duty free raw sugar import window, not the policy rate, is the instrument the Centre reached for against the sugar spike.
      The Fix: Pair each rate decision with a published buffer stock and import calendar for the few food items driving momentum, so the supply instrument is timed rather than reactive.
    2. Imported input prices sit outside domestic policy: Memory chip and crude oil prices are set in world markets, so a domestic rate rise raises the cost of credit without touching the source of the pressure. Eg. DRAM prices are being driven by worldwide artificial intelligence data centre demand.
      The Fix: Identify the externally determined component explicitly in the policy statement, so the rate response is calibrated to the domestically generated part of the increase.
    3. Transmission to lending rates is incomplete: A change in the policy rate reaches deposit rates and older loan portfolios slowly, so the intended slowdown arrives well after the decision. Eg. Loans priced off the marginal cost of funds based lending rate reprice on their own reset cycles rather than with the repo rate.
      The Fix: Extend external benchmark linking beyond retail and small business loans to a larger share of the banking system’s credit book.
    4. The index can lag the basket it measures: Consumption patterns shift faster than the weights fixed in a price index, so the measured rate can understate what households actually face. Eg. School fees, rent and health care carry weights set when the basket was last constructed.
      The Fix: Shorten the interval between CPI base revisions and publish the weighting diagram with each revision.
    5. Tightening carries an output cost: Raising rates against a price rise concentrated in a small share of the basket slows credit across the whole economy, including sectors with no price pressure at all. Eg. Labour intensive export sectors were already recording year on year declines before any monetary tightening.
      The Fix: Attach an explicit exit trigger to the tightening, such as the count of basket items inflating above 4 percent, so it ends when the spread reverses rather than on a calendar date.

    Conclusion

    The argument has moved on from whether a few commodities are dearer to whether the increase has become general, and the count of items rising across the basket is now the variable that settles it. Monetary tightening can compress demand, but it cannot produce sugar or memory chips, so the domestic half of the pressure falls to trade and buffer stock policy. The marker to watch at the next Monetary Policy Committee meeting is whether the committee names the spread, rather than the level, as the reason for whatever it decides.

    Matching Previous Year Question

    “What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.”

  • Decoding India’s GDP base revision

    Why in the News

    India’s nominal Gross Domestic Product (GDP) has been revised down by roughly 3 percent across the three years in which the old and new series overlap, under the New GDP Series with base year 2022-23. The Ministry of Statistics and Programme Implementation (MoSPI) set out the methodological improvements and updated data sources behind the revision when it released the series, along with a comparative table giving activity wise revisions and their reasons. The principal driver is a better measurement of India’s unincorporated services sector, which the earlier series estimated by carrying benchmark figures forward on proxy indicators. The contested point is whether a lower headline number means a smaller economy or only a better measured one.

    What is a GDP base year revision?

    1. Base year: It is the reference year whose price structure and economic composition the national accounts are built on, so every later estimate is expressed against that year’s conditions.
    2. What a rebasing changes: It updates the data sources, the coverage and the methods together, so it changes the estimated rupee size of the economy and not merely the growth rate.
    3. Direction is not fixed: International statistical practice recognises that the estimated size of an economy can move up or down after a rebasing, depending on what the new data and methods reveal.
    4. India’s current shift: The base has moved from 2011-12 to 2022-23, with three overlap years across which the two series can be compared directly.

    How large was the revision, and over which years?

    1. Year wise cuts: Nominal GDP was revised down by about 2.7 percent in 2022-23, 3.5 percent in 2023-24 and 3.8 percent in 2024-25.
    2. An independent estimate: The World Bank’s India Development Update of April 2026 put the cut at 3 to 4 percent in each of the four years from FY23, attributing it mainly to a reassessment of the informal economy.
    3. Volatility fell in the new series: The same update found quarterly growth between FY 2023-24 and FY 2025-26 to be less volatile and more broad based than previously estimated.
    4. Size is not activity: A lower estimate does not mean the economy became smaller or slowed in those years, since part of the change is simply a different and better measured starting number.

    Which sectors were revised up, and which down?

    1. Agriculture and allied activities: Revised up by about 3.8 to 5.9 percent.
    2. Financial services, real estate, professional services and ownership of dwellings: Revised up by roughly 7.8 to 9.0 percent over comparable years.
    3. Trade, transport and storage: Revised down by around 23 to 26 percent, the sharpest movement in the exercise.
    4. Trade and road transport in detail: Trade Gross Value Added (GVA), the value an activity adds before product taxes and subsidies, was cut by 36 percent and road transport by 16.9 percent.
    5. Hotels and restaurants: Revised up by 5.7 percent, mainly on the revised estimates for the unincorporated sector.

    Why did the unincorporated sector drive the change?

    1. The old method: In the 2011-12 series the unincorporated sector was estimated by moving benchmark estimates forward with proxy indicators, so the sector’s actual size was never measured afresh between benchmarks.
    2. The new inputs: The new series uses the Annual Survey of Unincorporated Sector Enterprises (ASUSE), which enumerates unregistered non farm enterprises, and the Periodic Labour Force Survey (PLFS), which measures employment and how it is distributed across enterprise types.
    3. Direct measurement: Together these give a direct basis for measuring the sector instead of an extrapolation anchored to an ageing benchmark.
    4. The correction is not uniform: Revisions within the unincorporated sector vary from activity to activity rather than moving in one direction.

    Why did a single year’s revision carry into later years?

    1. How the estimates are built: India’s quarterly and provisional GDP estimates are constructed from the previous year’s quarterly figures.
    2. The updating indicators: Those figures are then updated using information such as Goods and Services Tax collections and industrial production.
    3. The carry forward: Once the 2022-23 estimate was revised under the new methodology, every subsequent annual and quarterly estimate moved down with it as a matter of arithmetic.

    How common is a rebasing revision across other economies?

    1. Nigeria and Indonesia, 2014: Both rebased their national accounts and both saw their previously estimated nominal GDP levels revised.
    2. Brazil, 2015, and South Africa, 2018: Each rebasing likewise produced a revision to the previously estimated level of nominal GDP.
    3. Mexico, 2019, China, 2021, and Spain, 2024: All three changed their previously estimated nominal GDP on rebasing.
    4. India’s own precedent: The earlier shift from base year 2004-05 to 2011-12 also changed the estimated size of the Indian economy.
    5. What the set can bear: These are cited as country and year only, without the methodological detail that would allow a like for like comparison, so they establish that revision on rebasing is routine and nothing further.

    Challenges to the new GDP series

    1. Transparency of sources and methods: Independent verification of the estimates depends on a detailed Sources and Methods publication, which lags the release of the series itself. Eg. The comparative table issued with the new series gives activity wise reasons but not the underlying computation.
      The Fix: Publish the full Sources and Methods volume alongside the series release rather than months after it.
    2. Deflator weakness: Real GDP is deflated largely with the Wholesale Price Index, which does not cover services, so measured real growth in services can be distorted. Eg. India has no full Producer Price Index of the kind most large economies use for deflating output.
      The Fix: Complete the Wholesale Price Index base revision and introduce a Producer Price Index for deflating services output.
    3. Residual extrapolation in the informal economy: ASUSE and PLFS improve coverage, but a portion of informal activity is still estimated rather than enumerated. Eg. Enterprises that operate seasonally or from a dwelling are the hardest to capture in an establishment survey.
      The Fix: Run ASUSE on a fixed annual calendar and publish its enterprise coverage rate, so the extrapolated share is visible to users.
    4. Irregular rebasing intervals: Uneven gaps between base years let the series drift away from the actual structure of the economy between revisions. Eg. The 2011-12 base remained in use for well over a decade, through a period of rapid digitisation and sectoral change.
      The Fix: Institutionalise a base year revision every five years, which is the international practice.
    5. Institutional independence: Confidence in the numbers rests on the statistical system being visibly insulated from the government of the day. Eg. Past resignations from the National Statistical Commission and the withholding of completed survey results drew attention to exactly this.
      The Fix: Give the National Statistical Commission a statutory basis, so decisions on methodology and release are not administrative ones.

    Conclusion

    A statistical system is judged by whether it changes its numbers when better evidence arrives, not by whether the numbers hold still. The unresolved half of this exercise sits on the price side: coverage of output has improved while the indices used to convert output into real terms have not been rebuilt to match. The next marker is whether the promised documentation of sources and methods arrives in a form that lets independent researchers reproduce the estimates rather than only read the reasons for them.

    Back2Basics: National Statistical Commission

    1. Nature: It is the apex advisory body on India’s official statistical system.
    2. Origin: It was set up in 2005 by a government resolution, following the recommendation of the Rangarajan Commission on statistics, and has no statutory backing.
    3. Composition: It has a part time Chairperson, four part time members, the NITI Aayog Chief Executive Officer as an ex officio member, and the Chief Statistician of India as Secretary.
    4. Mandate: It advises on statistical priorities, standards and survey design, and its recommendations are given effect through the Ministry of Statistics and Programme Implementation.

    Matching Previous Year Question

    “Explain the difference between computing methodology of India’s Gross Domestic Product(GDP) before the year 2015 and after the year 2015.”

  • Merchants to pay 0.4% fee on UPI payments over Rs 2,000

    Why in the News

    The National Payments Corporation of India (NPCI) has restored a Merchant Discount Rate (MDR) of 0.4 percent on Unified Payments Interface (UPI) payments above Rs 2,000, payable by the merchant and capped at Rs 300 a transaction, with effect from 15 October. MDR on UPI and RuPay debit cards was removed in January 2020 to accelerate adoption of digital payments, and payment providers have since sought its return to meet infrastructure and settlement costs. The framework follows the Centre’s notification a day earlier barring any charge on UPI payments below Rs 2,000 and on RuPay debit card payments. The Union Ministry of Finance has advised banks to ensure merchants do not pass the cost on to customers, and that advice carries no prohibition behind it.

    What is the Merchant Discount Rate?

    1. Merchant Discount Rate: It is the fee a business pays on a digital payment it receives, deducted from the amount finally credited to the business rather than added to the customer’s bill.
    2. Person to merchant payments: The fee applies only to person to merchant (P2M) payments, where a customer pays a business. Person to person transfers between individuals carry no fee.
    3. Who counts as a merchant: An e-commerce website, grocery shop or shopkeeper receiving more than Rs 1 lakh a month from customers through UPI is classified as a merchant.
    4. Who receives the fee: The charge is shared between banks, payment apps and payment service providers.

    What does the new framework charge, and on which payments?

    1. Slab structure: Payments up to Rs 2,000 attract no MDR, and payments from Rs 2,001 to Rs 74,999 attract 0.40 percent. Eg. A merchant receiving Rs 10,000 pays Rs 40.
    2. Absolute cap: Payments of Rs 75,000 and above attract a fixed Rs 300, so the charge does not rise beyond that point.
    3. Flat fee for essential categories: A flat Rs 5 applies to payments for rail tickets, fuel, agricultural inputs, credit card dues, telecom and utility bills, insurance premiums and taxes. The stated purpose is to stop costs rising in critical public services and in sectors with thin profit margins.
    4. Capital market payments: UPI payments to mutual funds, securities and stock brokers carry a lower 0.02 percent fee, intended to encourage retail participation in formal financial markets.
    5. Autopay exemption: Systematic Investment Plan (SIP) payments and recurring standing instructions carry no fee at all. Eg. Monthly utility bills and OTT streaming subscriptions set on autopay.
    6. Review cycle: The charges are to be reviewed every six months to one year.

    Who stays outside the fee?

    1. Person to person transfers: These remain free, with no monthly quota, volume limit or tiered cap on free transactions for individuals.
    2. Small merchants under P2PM: A merchant receiving up to Rs 1 lakh a month through UPI QR codes faces zero MDR under the Person to Person Merchant (P2PM) framework.
    3. Purpose of the category: It bridges informal street vendor setups and formal merchant acquiring accounts, keeping digital acceptance costless for micro businesses in the unorganised sector.
    4. Migration trigger: A merchant crossing Rs 1 lakh a month for three consecutive months is moved into the P2M category and becomes liable for MDR.
    5. Daily limits are not charges: Daily transaction limits of Rs 1 lakh to Rs 5 lakh enforced by banks and NPCI are risk management measures and carry no cost.

    Why was the zero MDR regime abandoned?

    1. Zero MDR since January 2020: The charge was removed on UPI and RuPay debit cards to accelerate adoption, leaving the network running without a transaction revenue stream.
    2. The subsidy substitute: The Centre has since covered part of the cost through the Incentive scheme for promotion of RuPay Debit Cards and low-value BHIM-UPI transactions (P2M), capped at 0.15 percent of transaction value and not extending to large merchants.
    3. Industry cost claim: Payment providers have put their infrastructure and transaction settlement costs at around Rs 20,000 crore a year.
    4. The regulator’s position: The Reserve Bank of India (RBI) backed MDR on large value UPI payments as necessary for the long term sustainability of India’s digital payments ecosystem.
    5. Comparison with cards: Debit and credit card payments already carry an MDR of 1 to 3 percent, well above the rate now set for UPI.

    What is the revenue meant to fund?

    1. Technology and acceptance networks: RBI’s stated position is that a fair distribution of MDR among ecosystem participants supports continued investment in technology, infrastructure and payment acceptance networks.
    2. Competition in fintech: NPCI expects the fee to let new fintech startups and technology companies enter digital payments and compete with well capitalised conglomerates.
    3. Security spending: MDR revenue is also to fund cyber security infrastructure, artificial intelligence driven fraud detection and encryption upgrades.
    4. Small merchant fund: Five percent of all MDR collected goes into a dedicated fund to help small merchants accept UPI payments.

    How much of UPI does the fee actually touch?

    1. Share of volume: Payments above Rs 2,000 are only 4 percent of all UPI payments to merchants, and the remaining 96 percent sit below that ticket size.
    2. Share of value: Those same payments carry two thirds of all person to merchant value, so a small slice of volume is a large slice of money.
    3. Industry categories: The flat Rs 5 categories account for 17 percent of P2M transactions by volume and 46 percent by value.
    4. Scale of the network: UPI carried more than 24,000 crore transactions worth Rs 314 lakh crore in 2025-26.

    Challenges to the Merchant Discount Rate on UPI

    1. Pass through to customers is unenforced: The Union Ministry of Finance has only advised banks to ensure merchants do not recover the fee from buyers. Eg. Card MDR is routinely recovered through visible surcharges at fuel stations and on utility payments.
      The Fix: Convert the advisory into a binding condition of the acquiring bank’s merchant agreement, with the acquirer answerable for a surcharge its merchant levies.
    2. The Rs 1 lakh threshold creates a splitting incentive: A merchant near the P2PM ceiling gains by routing collections across several QR codes or accounts to stay below it. Eg. Value splitting across accounts is a documented pattern around registration thresholds for small traders under the Goods and Services Tax.
      The Fix: Anchor the P2PM classification to the merchant’s permanent account number rather than to an individual bank account or QR code.
    3. A flat cap favours the largest tickets: Because the charge stops at Rs 300, the effective rate falls as the payment size rises, so the biggest sellers pay proportionately least. Eg. A Rs 5 lakh payment carries an effective rate of 0.06 percent against 0.40 percent on a Rs 10,000 payment.
      The Fix: Tier the cap by merchant turnover band so the concession reaches smaller sellers rather than the largest acquirers.
    4. Concentration in the payments market: MDR revenue accrues to banks and payment service providers in a market where two applications already carry most UPI volume. Eg. NPCI’s own 30 percent market share cap on third party UPI applications has been deferred repeatedly rather than enforced.
      The Fix: Tie disbursal from the small merchant fund to acquirers that add new merchants outside the largest cities.
    5. Adoption risk in the unorganised sector: A visible charge on larger payments gives merchants a reason to steer high value sales back to cash. Eg. Currency in circulation continued to grow through the years of zero MDR and rapid UPI expansion.
      The Fix: Publish the share of high value merchant collections leaving UPI as part of each scheduled review, so the review has a trigger rather than only a date.

    Conclusion

    Costless merchant acceptance on the country’s dominant retail payment network has ended for large payments, and the terms are set to be revisited at fixed intervals rather than settled once. The unresolved question is who finally bears the charge, since the protection against merchants recovering it from customers is an advisory and not a prohibition. The thing to watch at the first review is whether large ticket merchant collections stay on the network or shift back to cash.

    Back2Basics: National Payments Corporation of India

    1. Nature: It is the umbrella organisation for retail payments and settlement systems in India, incorporated as a not for profit company.
    2. Founding: It was set up in 2008 by the Reserve Bank of India and the Indian Banks’ Association, under Section 25 of the Companies Act, 1956, now Section 8 of the Companies Act, 2013.
    3. Statutory basis: It operates under the Payment and Settlement Systems Act, 2007, which gives RBI authority over payment systems.
    4. Products: It runs UPI, RuPay, IMPS, NACH, AePS, FASTag and BHIM.

    Matching Previous Year Question

    “Which of the following is a most likely consequence of implementing the ‘Unified Payments Interface (UPI)’?”

  • Subhash Chandra case: IBBI to tighten guarantor resolution

    Why in the News

    The Insolvency and Bankruptcy Board of India (IBBI) has proposed four amendments to the insolvency resolution process for personal guarantors to corporate debtors, extending to banks and creditors safeguards already available under the corporate insolvency resolution process (CIRP) of a company. The proposals follow a special bench of the National Company Law Tribunal (NCLT) staying a single bench order that had approved a repayment plan offering creditors Rs 6.25 crore against admitted claims of Rs 22,006.57 crore. That case led experts to question the efficacy of the Insolvency and Bankruptcy Code, 2016, which was introduced to revive companies under heavy debt and secure repayment to banks. The contested point is that the guarantor track of the Code was built with weaker creditor protections than the corporate track, and a related party of the guarantor can currently vote on the plan that decides what creditors recover.

    What is the personal guarantor resolution process?

    1. Who a personal guarantor is: An individual, usually a promoter, who personally guarantees a company’s borrowing, so the lender can proceed against that individual’s own estate when the company defaults.
    2. How the process runs: A resolution professional is appointed, a repayment plan is prepared for the guarantor, and the plan is put to a vote of the creditors before it goes to the adjudicating authority for approval.
    3. How it differs from the corporate track: Under CIRP the plan is decided by a committee of creditors from which a related party of the debtor company is excluded from voting. In a personal guarantor resolution only an associate is barred, and the definition of associate is far narrower.

    What triggered the review?

    1. The order under stay: On August 25 the NCLT single bench approved a repayment plan involving personal guarantor and Essel Group founder Subhash Chandra, and a special bench has since stayed that order.
    2. The recovery on offer: Creditors were offered Rs 6.25 crore against admitted claims of Rs 22,006.57 crore.
    3. What the banks alleged: The banks alleged that the non bank entities voting on the plan were associates or related parties of the guarantor and had acted under his influence to push through a plan carrying a very large haircut.
    4. The gap the case exposed: The narrower associate test let entities that would fail a related party test vote on the plan. The IBBI’s own illustration is a company that habitually acts on the guarantor’s advice or instructions, without the guarantor holding any shares in it or controlling its board.

    What are the four proposed amendments?

    1. Voting rights of related parties: Any creditor who is a related party of the guarantor would get no voting right in approving the resolution plan, replacing the narrower associate test.
    2. Scrutiny of avoidance transactions: Resolution professionals would have to examine whether the guarantor was party to any avoidance transactions, meaning undervalued transactions, transactions giving preference and extortionate credit transactions, present those findings to creditors before the vote, and initiate legal proceedings with creditor approval.
    3. Independent asset valuation: A registered valuer would have to determine the fair value and the realisable value of the guarantor’s assets, and the valuation report would go to creditors along with the repayment plan.
    4. Reasoned minutes of creditor meetings: Resolution professionals would have to record creditors’ deliberations and the reasons for their decision in the minutes of creditors’ meetings.

    How do these proposals close the gap with the corporate process?

    1. Parity on the voting bar: The related party exclusion is the CIRP standard, and applying it to guarantor resolutions removes the mismatch the Chandra case turned on.
    2. A duty that does not currently exist: When a guarantor’s repayment plan is put to a vote, the resolution professional is today under no obligation to examine whether an avoidance transaction took place or whether the guarantor made full disclosure of affairs.
    3. Informed commercial judgement: The IBBI’s stated purpose for the valuation report is to let creditors assess the adequacy of the proposed security, the viability of the repayment plan and the potential recovery available from the guarantor’s assets.
    4. An auditable record: Recording only raw voting tallies leaves no record of commercial reasoning, and reasoned minutes give an appellate forum something to review beyond the arithmetic of the vote.

    Challenges to the personal guarantor resolution framework

    1. Asset shielding before the filing: A guarantor can move assets into family or trust structures well before insolvency begins, leaving little to value. Eg. Promoter assets held through family trusts have repeatedly fallen outside the estate available to lenders in large default cases.
      The Fix: Extend the look back period for avoidance transactions involving a guarantor’s relatives and require a sworn asset disclosure covering it.
    2. Proving a related party connection: The related party test is broader than the associate test and is also harder to establish, since control through habitual instruction leaves no shareholding trail. Eg. The IBBI’s own example is a company acting on the guarantor’s instructions without any shareholding or board control.
      The Fix: Place the burden on the creditor claiming unrelated status to establish it, rather than on the objecting bank to disprove it.
    3. Delay in adjudication: The guarantor track sits in the same tribunals already carrying a heavy corporate caseload, so an order and its stay can consume months while asset value erodes. Eg. The stay in this case leaves the approved plan in suspension with no fixed date for a decision.
      The Fix: Fix a statutory outer limit for disposal of a personal guarantor repayment plan and report breaches bench wise.
    4. Valuation of illiquid personal assets: Fair value and realisable value diverge sharply for unlisted shareholdings, disputed land and pledged promoter stock. Eg. Pledged promoter shareholdings lose value the moment a lender begins to sell them into the market.
      The Fix: Require two independent registered valuers where the guarantor’s estate is dominated by unlisted or pledged securities.

    Conclusion

    The guarantor track of the Code was written as a lighter version of the corporate one, and the difference has turned out to matter most in exactly the cases where recovery is largest. The four proposals move that track towards the corporate standard on voting, scrutiny, valuation and record keeping, and each of them constrains the resolution professional rather than the tribunal. The proposals sit in a discussion paper open for public comment, and the special bench’s stay holds until it decides the matter.

    Back2Basics: Insolvency and Bankruptcy Board of India

    1. What it is: The IBBI is the regulator for insolvency and bankruptcy proceedings in India, established in 2016 under the Insolvency and Bankruptcy Code, 2016.
    2. Who it regulates: Insolvency professionals, insolvency professional agencies, registered valuers and information utilities.
    3. What makes it unusual: It holds regulatory, executive and quasi judicial functions over the same set of entities, which is rare among Indian regulators.
    4. Its rule making role: It frames the regulations that govern both the corporate insolvency resolution process and the resolution of personal guarantors, which is what the present discussion paper proposes to amend.

    Matching Previous Year Question

    “[2019] What was the purpose of Inter-Creditor Agreement signed by Indian banks and financial institutions recently? (a) To lessen the Government of India’s perennial burden of fiscal deficit nd current account deficit (b) To support the infrastructure projects of Central and State Governments (c) To act as independent regulator in case of applications for loans of Rs. 50 crore or more (d) To aim at faster resolution of stressed assets of Rs. 50 crore or more which are under consortium lending Answer: (d)”

  • Govt: No bank charge on UPI payment up to Rs 2,000

    Why in the News

    The Ministry of Finance has notified that no bank or system provider may impose any charge, directly or indirectly, on a payment made through RuPay debit cards or through the Unified Payments Interface (UPI), the National Payments Corporation of India’s real time system for transferring money between bank accounts using a virtual address, up to Rs 2,000. The notification does not specify any charge for transactions above that amount, which opens the way for a fee on higher value person to merchant payments. It follows the Taxation and Other Laws (Amendment) Bill, 2026, passed by Parliament last month, which removed the statutory bar on charging for these payment modes. The contested point is that a threshold covering 96 per cent of person to merchant transactions by number leaves roughly two thirds of their value open to a charge.

    What is the Merchant Discount Rate?

    1. What it is: The Merchant Discount Rate (MDR) is the fee a bank that processes a card or digital payment levies on the merchant receiving it.
    2. What it pays for: It covers transaction processing, settlement and payment infrastructure costs across the chain of banks and providers that carry the payment.
    3. The usual range: An MDR normally runs between 1 and 3 per cent of transaction value on debit and credit card payments.
    4. The exemption since 2020: No MDR has been levied on RuPay debit cards and UPI transactions since January 2020, a decision taken to promote adoption of digital payments.

    What has the notification done, and who decides a fee above the threshold?

    1. The prohibition: The notification bars any charge, direct or indirect, on RuPay debit card payments and on UPI transactions of up to Rs 2,000, whether imposed on the person making or the person receiving the payment.
    2. The silence above the threshold: The ministry did not specify charges for transactions above Rs 2,000, which is what creates the opening for an MDR on higher value person to merchant payments.
    3. The deciding body: Whether an MDR is imposed above the threshold will be decided by the UPI and Services Steering Committee, headed by the National Payments Corporation of India (NPCI), with 22 members including banks, third party application providers such as PhonePe and Google Pay, the Payments Council of India and the Indian Banks’ Association.
    4. The rate under discussion: Payments industry officials have suggested an MDR of around 0.4 to 0.5 per cent for UPI payments to large merchants, which would help meet the industry’s annual cost of about Rs 20,700 crore.

    What legal change made this possible?

    1. The provision amended: The Bill amended Section 10A of the Payment and Settlement Systems Act, 2007, which had barred any bank or system provider from imposing a charge on payments made through the electronic modes prescribed under Section 269SU.
    2. The modes covered: Those prescribed modes were RuPay debit cards, BHIM UPI and the UPI QR code.
    3. Who the underlying obligation binds: Section 269SU of the Income Tax Act, 1961 applies to businesses with a turnover of over Rs 50 crore, requiring them to offer the prescribed electronic payment modes.
    4. What the amendment enables: Removing the exemption paves the way for an MDR on UPI and RuPay debit card payments to large merchants such as e commerce platforms.
    5. The stated rationale: The amendment is presented as an enabling provision for UPI’s long term sustainability, technological advancement and resilience against emerging risks.

    Why does the Rs 2,000 threshold matter for UPI’s economics?

    1. Small share by number: Only 4 per cent of person to merchant UPI payments in 2025 to 26 were for more than Rs 2,000.
    2. Large share by value: Those same transactions accounted for about two thirds of total person to merchant UPI payment value.
    3. The base: More than 24,000 crore UPI transactions worth Rs 314 lakh crore were made during the year.
    4. What the design achieves: The threshold protects the small ticket everyday payment from any charge while leaving the value where a percentage fee actually earns revenue open to one.

    How has the state paid for zero MDR so far?

    1. The incentive scheme: The government subsidises payments of up to Rs 2,000 made to small merchants through its incentive scheme for promotion of RuPay debit cards and low value BHIM UPI person to merchant transactions.
    2. The cap and the exclusion: The incentive is capped at 0.15 per cent of transaction value, and large merchants are not covered by the scheme at all.
    3. What it costs: The Budget for 2026 to 27 estimated the payout at Rs 2,000 crore. Rs 2,196.21 crore was paid in 2025 to 26, up from Rs 1,922.77 crore in 2024 to 25.
    4. The sustainability finding: A March report of the Standing Committee on Finance recorded that the absence of MDR makes the UPI ecosystem financially unsustainable.

    Challenges to reintroducing a Merchant Discount Rate on UPI

    1. Merchant pass through to the customer: A merchant charged a percentage fee recovers it by quoting a higher price or by preferring cash for large tickets. Eg. Many small retailers added a surcharge on card payments before the Reserve Bank of India barred the practice on debit cards.
      The Fix: Bar surcharging by contract with the acquiring bank and make the ban a condition of merchant onboarding.
    2. Threshold gaming by splitting payments: A fixed value threshold invites a single large payment being broken into several below the cut off. Eg. A Rs 5,000 purchase settled as three separate UPI transfers falls entirely inside the exempt band.
      The Fix: Apply the threshold to the aggregate value settled to one merchant from one payer in a day rather than to a single transaction.
    3. Definition risk on the large merchant: The charge is designed to fall on large merchants, and the line between a large and a small merchant sits on self declared turnover. Eg. Section 269SU already uses a Rs 50 crore turnover test that a merchant can restructure across entities.
      The Fix: Anchor the classification to verified Goods and Services Tax turnover rather than to a declaration made at onboarding.
    4. Fiscal and commercial funding running in parallel: An incentive subsidy and an MDR answer the same infrastructure cost, and running both leaves the split unstated. Eg. The subsidy payout has risen each year while the industry’s stated annual cost has stayed far above it.
      The Fix: Publish a stated glide path withdrawing the incentive as MDR revenue begins, so the two do not fund the same cost twice.

    Conclusion

    The zero fee regime on UPI was paid for by the exchequer, and the bill grew every year while the payments industry’s own cost stayed several times larger. The notification shifts the funding of the large value end of the system from the Budget to the merchant, and leaves the small everyday payment where it was. What to watch is whether the UPI and Services Steering Committee sets a rate above the threshold at all, and whether merchants at that end of the market stay on UPI once it does.

    Back2Basics: National Payments Corporation of India

    1. What it is: NPCI is the umbrella organisation for retail payments and settlement systems in India.
    2. How it was set up: It was incorporated in 2008 as a not for profit company, promoted jointly by the Reserve Bank of India and the Indian Banks’ Association.
    3. Its statutory anchor: It operates under the Payment and Settlement Systems Act, 2007, which is the law governing payment systems in India.
    4. What it runs: Its systems include UPI, RuPay, the Immediate Payment Service, the National Automated Clearing House and FASTag.

    Matching Previous Year Question

    “[2023, GS3, 10 marks] What is the status of digitalization in the Indian economy? Examine the problems faced in this regard and suggest improvements.”

  • Key inflation numbers rise in August, all eyes on RBI’s interest rate decision next month

    Why in the News

    Retail inflation measured by the Consumer Price Index (CPI) rose to 4.82 per cent in August from 4.45 per cent in July, the highest reading in at least eight months. This is the third month in a row that headline retail inflation has stayed above the 4 per cent target the Reserve Bank of India (RBI) is legally mandated to hold it at. The Monetary Policy Committee (MPC), the six member body that sets the policy repo rate, left that rate unchanged at 5.25 per cent last month and has not raised it since February 2023. The contested point is whether a price rise now visible across food, fuel and manufactured goods obliges the MPC to begin tightening even as output is growing faster than expected.

    What is India’s inflation targeting framework?

    1. The statutory target: The RBI is legally mandated to keep CPI inflation at 4 per cent, within a tolerance band of 2 to 6 per cent.
    2. The instrument: The MPC sets the policy repo rate, the rate at which the RBI lends overnight to commercial banks against government securities, and changes in it are expected to pass through to deposit and lending rates.
    3. Why the band matters: Inflation inside the band does not by itself require action. A reading persistently above the central target, rather than a breach of the 6 per cent ceiling, is what builds the case for a rate increase.

    What do the August retail price numbers actually show?

    1. Food inflation: Food inflation measured by the CPI rose from 5.52 per cent in July to 5.95 per cent in August.
    2. Sugar: The CPI for sugar surged 19 per cent over July and 24 per cent over August 2025, on lower than expected production and inventory falling to multi year lows.
    3. Policy response on sugar: The government last month allowed duty free imports of up to 10 lakh tonnes of raw sugar until October 31, with sugar a key input through the festival season.
    4. Onion: Onion prices were up 22 per cent in August over July, with late rains delaying planting.

    Why is the price rise being read as broad based rather than a food shock?

    1. Breadth of the increase: 314 of the 358 items in the CPI recorded higher prices in August than in July. The figure was 310 in July and 236 in February, before the war in West Asia began.
    2. Items above target: The number of items with inflation above the target rate rose from 101 in July to 110 in August.
    3. Spillover risk: Price pressure spreading from food and fuel into other categories is what distinguishes a broad based rise from a seasonal vegetable spike, and it is the pattern the data now shows.

    What do the wholesale and producer numbers add?

    1. Wholesale Price Index: Wholesale inflation rose to 9.92 per cent in August from 9.78 per cent in July, driven by food and fuel.
    2. Wholesale food: Wholesale food inflation hit a 20 month high of 7.05 per cent in August, which ICRA attributes largely to higher prices of fruits, vegetables, milk, spices and sugar.
    3. Producer prices: Inflation based on the output Producer Price Index (PPI) edged up to 9.81 per cent from 9.57 per cent in July.
    4. Structural signal in manufacturing: India Ratings and Research reads the rise as becoming structural, since seven manufacturing sub categories, tobacco products, textile products, chemical products, rubber and plastic products, base metals, electrical equipment and other manufacturing, all carry wholesale inflation above 10 per cent. Those seven make up more than a quarter of the manufacturing group, which is itself almost two thirds of the entire Wholesale Price Index.

    Where does this leave the Monetary Policy Committee?

    1. Direction from the last meeting: Minutes of last month’s meeting showed the RBI Governor and a Deputy Governor both hinting towards an increase in interest rates.
    2. The RBI’s own projections: The central bank expects CPI inflation to average 4.7 per cent in July to September, 5.9 per cent in October to December, 5.5 per cent in January to March 2027 and 5.3 per cent in April to June 2027.
    3. Growth is not a constraint: GDP growth was 7.8 per cent in the first quarter of 2026 to 27, which removes the usual argument against tightening.
    4. The meeting date: The MPC meets on October 5 to 7, three weeks after this price data, and could deliver the first interest rate increase in three and a half years.

    What is the external monetary backdrop?

    1. US Federal Reserve: The Fed announces its own interest rate decision this week, with markets expecting a 25 basis point increase in the federal funds rate target range to 3.75 to 4 per cent.
    2. The US price trigger: American consumer prices rose 0.4 per cent month on month in August against a 0.1 per cent increase in July, with the year on year headline rate steady at 3.4 per cent.
    3. The tightening cycle: ANZ economists expect a compressed 75 basis point tightening cycle, with the increase this week followed by further increases in October and December to take the key rate to 4.25 to 4.50 per cent.
    4. Why it matters for India: Major central banks have already begun raising rates, which narrows the room for the MPC to hold while inflation runs above target.

    Challenges to inflation targeting in India

    1. Food weight in the index: Food carries a large share of the CPI basket, so a supply shock in one commodity moves the headline number that policy is judged against. Eg. A sugar output shortfall and delayed onion planting moved the August print on their own.
      The Fix: Publish the policy response against core inflation alongside the headline, so a supply driven spike is not read as a demand signal.
    2. Interest rates do not reach a supply shock: The repo rate works on credit demand and cannot add a tonne of sugar or an onion crop to the market. Eg. The government answered the sugar price surge with an import window rather than with monetary policy.
      The Fix: Pair the rate decision with a stated buffer stock and import calendar for the commodities driving the print.
    3. Transmission lag to borrowers: A change in the repo rate reaches lending and deposit rates only over several quarters, so a decision taken after inflation is established arrives late. Eg. The policy rate has been unchanged for four consecutive meetings while the headline number has risen for three months.
      The Fix: Widen the share of loans benchmarked to an external rate, so a policy change reaches borrowers in the same quarter.
    4. Imported price pressure: A large share of fuel and edible oil demand is met by imports, so the exchange rate and global prices set domestic costs irrespective of the domestic rate stance. Eg. Landed prices of imported crude palm, soyabean and sunflower oil in Mumbai are all above their September 2025 levels.
      The Fix: Use a calibrated import duty schedule on edible oils that moves against global prices rather than staying fixed through a cycle.

    Conclusion

    Inflation has moved from a food story to a broader one, and the numbers that usually lag the headline, wholesale and producer prices, are now leading it. The central bank holds a rate that has not changed in three and a half years against a growth rate that gives it no reason to wait. The thing to watch is the next Monetary Policy Committee decision and whether it treats the current run as a supply spike that will pass or as the start of a demand driven episode requiring a rate increase.

    Back2Basics: Producer Price Index

    1. What it measures: The Producer Price Index tracks the average change in prices received by domestic producers for their output, measured from the seller’s side of a transaction.
    2. How it differs from the Wholesale Price Index: The Wholesale Price Index measures the price a buyer pays at the wholesale stage, so it includes trade margins and indirect taxes. The PPI strips those out and measures the producer’s own realisation.
    3. Why it is tracked: It signals cost pressure building upstream before that pressure reaches retail prices, so it works as a leading indicator for consumer inflation.

    Matching Previous Year Question

    “[2024, GS3, 10 marks] What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.”