Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS2-02.Functions & responsibilities of the Union and the States; issues and challenges of federal structure;

  • Why are States divided over the mining amendment?

    Why in the News

    Taxing mineral rights and mineral-bearing land, which a nine-judge Constitution Bench held in Mineral Area Development Authority v. Steel Authority of India (2024) to be largely a State power, now needs conditions set by the Union under the Mines and Minerals (Development and Regulation) Amendment Act, 2026. Mineral-rich States have split on challenging it, along lines of revenue dependence and political alignment.

    How does the Constitution divide power over minerals?

    1. Regulation: States regulate mines under State List Entry 23. Under Union List Entry 54, Parliament can take control in the public interest, like a master switch.
    2. Taxation: Separately, Entries 50 and 49 of the State List let States tax mineral rights (the right to extract minerals) and land.
    3. The takeaway: Regulation and taxation sit in different entries, so the dispute is whether a regulatory power can be used to cut a taxing power.

    What does the amendment change?

    1. Wider central control: The Act, passed by Parliament, extends the Centre’s regulatory power from mines and mineral development to mineral-bearing land.
    2. Tax bar: States may not impose fresh taxes on mineral rights or mineral-bearing land, except under conditions the Union government prescribes.
    3. Past dues cancelled: Mineral taxes that States imposed but had not fully collected before the Act took effect are cancelled.
    4. Clash with the ruling: The Court let Parliament limit State taxes on mineral rights, but held that Entry 54 cannot curtail their power to tax mineral-bearing land.
    5. From mining to fiscal autonomy: Using a regulatory power to limit State taxes makes this a question of the fiscal autonomy, or revenue freedom, of mineral-rich States.

    What is at stake for the Centre and the States?

    1. The Centre’s case: Uneven, multiple State levies raise domestic mineral costs, so industries turn to imports and the exchequer bears more.
    2. Lost revenue: Cancelling unrecovered dues removes a revenue source and narrows future mineral income for the major mineral-bearing States.
    3. Most dependent: Minerals supply 85% of non-tax revenue in Jharkhand and 80% in Odisha, so the curbs hit them hardest.
    4. Least dependent: The immediate impact is smaller in Telangana and Chhattisgarh.

    Why have States responded differently?

    1. Legal challenge: Karnataka, Telangana, Himachal Pradesh and Kerala plan to move the Supreme Court, saying the curbs undermine States’ fiscal powers and federalism.
    2. Kerala’s added objection: The new treatment of mineral-bearing land gives the Centre wider power over the State’s coastal and forest regions.
    3. Jharkhand’s warning: The Chief Minister warns that losing mineral taxes and past dues could hit social-security schemes benefiting millions.
    4. Odisha’s stand: The Bharatiya Janata Party (BJP) government rejected the Opposition’s call for a special Assembly session, saying mineral revenue will not suffer.
    5. Alignment over dependence: Low-dependence Telangana, ruled outside the National Democratic Alliance (NDA), joined the challenge. Madhya Pradesh, Rajasthan and Chhattisgarh have not objected, so alignment decides who sues.

    How does the dispute fit India’s fiscal federalism?

    1. Asymmetric design: India’s fiscal federalism gives the Centre greater taxing powers and places greater spending duties on the States.
    2. Leverage over States: The Centre’s control of borrowing approvals and transfers limits States that depend on them.
    3. Recurring disputes: The amendment joins earlier Centre-State disputes over Goods and Services Tax compensation, Finance Commission mandates, the National Education Policy, the Citizenship Amendment Act and All-India Services rules.

    Challenges

    1. Ordinary law against a ruling: Parliament is doing by ordinary law what the Court’s reading of the State List ruled out.
    2. Retrospective loss: Cancelling dues already levied unsettles State budgets planned around them.
    3. No bargaining forum: No standing body reconciles uniform mineral costs with States’ room to tax. Eg. The Inter-State Council last met in 2016.

    Way Forward

    1. Consult on conditions: The Union should frame the prescribed conditions for State mineral taxes with States through the Inter-State Council.
    2. Transitional compensation: The Centre should compensate States for cancelled dues over a fixed transition period.
    3. Rate ceiling, not a bar: A ceiling on State mineral levies in place of Union approval would keep costs predictable.

    Conclusion

    The amendment answers industry’s cost complaint by moving taxing room from mineral-rich States to the Union, against the Court’s reading of where that power lies. Whether the Supreme Court lets a regulatory entry override a taxing entry will decide the States’ planned challenges.

    Key numbers

    1. Mineral share of non-tax revenue, Karnataka and Madhya Pradesh: 48% and 41%.
    2. Mineral share of non-tax revenue, Rajasthan: 39%.
    3. Least dependent States: Telangana 11%, Chhattisgarh 6%.

    Matching Previous Year Question

    “[2021] Which one of the following in Indian polity is an essential feature that indicates that it is federal in character? (a) The independence of the judiciary is safeguarded. (b) The Union Legislature has elected representatives from constituent units. (c) The Union Cabinet can have elected representatives from regional parties. (d) The Fundamental Rights are enforceable by Courts of Law. ANSWER: (a)”

  • As J&K House passes resolution on statehood, CM Omar asks, ‘what does uchit samay mean?’

    Why in the News

    The Jammu and Kashmir Legislative Assembly has turned the Centre’s open ended promise of statehood at an “uchit samay” (opportune moment) into a formal legislative demand that the Union Territory (UT) be made a State again. The resolution passed by voice vote as Bharatiya Janata Party (BJP) members walked out, and the Chief Minister asked what that timeline means when the Supreme Court had sought restoration “at the earliest”.

    What is J&K’s present status, and what did the Supreme Court say?

    1. What it is: The Jammu and Kashmir Reorganisation Act, 2019 split the State into two UTs: Jammu and Kashmir, with a legislature, and Ladakh, without one.
    2. How a UT works: Like Delhi or Puducherry, an elected government works alongside a Lieutenant Governor (LG) representing the Centre.
    3. Court’s position: In In Re: Article 370 of the Constitution (2023), a five judge Constitution Bench upheld ending J&K’s special status. It recorded the Centre’s assurance of restored statehood.
    4. The takeaway: Until statehood returns, the elected government lacks powers a State holds, so the timing is contested.

    What did the Chief Minister argue?

    1. Long wait: Chief Minister Omar Abdullah said J&K has waited two years for the Centre to keep its word, with no clarity on when statehood will return.
    2. Link to militancy: He asked whether the Centre’s promise is linked to militancy, meaning statehood would wait until “guns fall silent”.
    3. Decision left to Pakistan: The Centre says militancy is instigated from Pakistan. Linking statehood to it, he argued, leaves the decision to Islamabad rather than New Delhi.

    How does the UT set-up limit the elected government?

    1. Sub judice opinion: The Law Department told the Speaker the debate was sub judice (pending in court). The Chief Minister, also Law Minister, said he never saw that opinion.
    2. Chief Secretary’s letter: He said the Chief Secretary had also written to the Speaker, and asked on whose directions this was done.
    3. Limited domain of the LG: The Act reserves only security and law and order for the LG, he said, yet the revenue department sits outside the elected government.
    4. Universities and reservation: Control of the Islamic University of Science and Technology and Baba Ghulam Shah Badshah University, and rationalisation of reservation, are other areas where UT status “affects us daily”.

    Where do the parties differ on the resolution?

    1. BJP’s stand: The Leader of the Opposition said the BJP favours restoring statehood but called the resolution’s language unacceptable.
    2. “Pre-1953 position”: He called the resolution’s reference to J&K’s pre-1953 position unconstitutional.
    3. Demands from allies and rivals: At least eight Members of the Legislative Assembly (MLAs), including from the ruling National Conference, the Congress and the Peoples Democratic Party (PDP), sought amendments naming Articles 370 and 35A.
    4. Condemnation sought: The same members wanted the resolution to condemn “the events of August 5, 2019”, the day J&K’s special status was ended.

    Challenges

    1. No timeline: The Centre’s promise names no date, leaving restoration to its discretion without any enforceable deadline.
    2. Dual power centres: Split control between the LG and the elected government blurs accountability for administration.
    3. Security linkage: Tying statehood to the end of militancy makes a constitutional decision depend on events outside India’s control.
    4. Parliamentary route: Restoration needs Parliament to amend the Reorganisation Act under Articles 3 and 4, and the Assembly’s resolution carries no binding force.

    Way Forward

    1. Dated roadmap: The Union Ministry of Home Affairs should publish a time-bound roadmap for statehood.
    2. Interim transfer: The Centre should move departments such as revenue to the elected government under the Act’s business rules before full statehood.
    3. Legislative step: The Centre should introduce a Bill in Parliament amending the Reorganisation Act.
    4. Separate tracks: J&K’s parties should keep statehood distinct from the Article 370 dispute to build consensus.

    Conclusion

    The resolution shows that an elected government in a UT answers to voters without holding the powers they expect it to use. What to watch is whether the Centre turns its promise into a dated plan or a Bill in Parliament.

    Back2Basics: Articles 370 and 35A

    1. Article 370: A “temporary provision” that gave J&K special status. Most Union laws applied there only with the State government’s concurrence.
    2. Article 35A: Added by a 1954 Presidential Order, it let J&K’s legislature define permanent residents and reserve rights such as land ownership and State jobs for them.
    3. Pre-1953 arrangement: Until 1953, J&K had its own Prime Minister and a Sadr-i-Riyasat (head of state), and the Union’s role centred on defence, external affairs and communications.

    Matching Previous Year Question

    “[2021] Which one of the following in Indian polity is an essential feature that indicates that it is federal in character? (a) The independence of the judiciary is safeguarded. (b) The Union Legislature has elected representatives from constituent units. (c) The Union Cabinet can have elected representatives from regional parties. (d) The Fundamental Rights are enforceable by Courts of Law. Answer: A”

  • Union Minister says Jharkhand’s opposition to the MMDR Act facilitates coal theft

    Why in the News

    The Union Minister of Women and Child Development has said Jharkhand opposes the Mines and Minerals (Development and Regulation) Amendment (MMDR) Act, 2026 to facilitate coal theft. Jharkhand’s Chief Minister calls it a black Bill.

    What does the MMDR Act, 2026 change?

    1. Uniform national levies: The amendment fixes mining taxes and levies nationally instead of State by State, like one national price list for every mine.
    2. Why it was brought: The stated aim is to streamline taxation under the Mines and Minerals (Development and Regulation) Act, 1957 and stop arbitrary State levies.
    3. What went wrong before: A mineral bearing State added fresh cesses, meaning charges on top of the main levy, after auctions closed, so bidders faced new demands.
    4. The takeaway: A bidder can now calculate the levy before bidding, and a mineral bearing State loses the one revenue lever it controlled alone.

    Why does the Centre say Jharkhand is resisting?

    1. Auctions not held on time: The State does not put mineral blocks to auction on schedule.
    2. Five intents alleged: The Centre’s charge names five intents behind the State’s opposition:
      • revenue kept from reaching the State exchequer;
      • mining administration kept dysfunctional;
      • facilities denied to licensed operators;
      • illegal activity allowed to rise;
      • a racket in illegal mining left to flourish.
    3. Coal theft as the motive: The opposition is put down to an interest in personal revenue rather than legitimate State revenue.
    4. Political messaging: The ruling Jharkhand Mukti Morcha (JMM), Congress and Rashtriya Janata Dal (RJD) are accused of misleading people about the Act.

    What does the Centre say the State gains?

    1. Investment and jobs: Predictable levies are expected to draw mining investment and keep young people working within the State.
    2. States already applying it: Odisha, West Bengal, Chhattisgarh, Karnataka and Kerala have implemented the Act.
    3. Opposition ruled States included: Several of those are Congress ruled and welcome the Act, which weakens the claim that it targets Jharkhand.
    4. End of red tapism: The claim is that implementing the Act will end red tapism, meaning delays caused by layers of official permission.

    Why is this a question of federal power?

    1. Minerals belong to the State: Jharkhand’s ground is that minerals and land belong to the State, so the Centre should not decide its entitlements over them.
    2. Constitutional split of power: Entry 54 of the Union List lets Parliament regulate mines once it declares central regulation expedient. Entry 50 of the State List lets a State tax mineral rights.
    3. Court upheld the State levy: A nine judge Bench held in Mineral Area Development Authority v. Steel Authority of India (2024) that royalty is not a tax, so the State’s mineral levy stayed beyond challenge.
    4. What Jharkhand stands to lose: The State holds India’s largest coal resources, so a uniform central rate hits its own revenue hardest.

    Challenges

    1. State revenue capped from outside: A mineral bearing State can no longer raise its own levy when mining income falls short.
    2. Auctions still depend on the State: The Act fixes rates, not the pace at which a State puts blocks to auction.
    3. Enforcement stays with the State: Illegal mining is detected and prosecuted by State agencies, so a tax rule cannot stop coal theft.
    4. Past dues remain unsettled: Operators still carry demands raised under the old State cesses.

    Way Forward

    1. Compensate the lost headroom: Route a share of the central mining levy back to the producing State, on a Finance Commission formula.
    2. Publish an auction calendar: The Ministry of Mines should notify State wise auction dates, with missed blocks reverting to central auction.
    3. Close the old cess demands: Notify one settlement window for dues raised after past auctions.
    4. Use Article 263: Place mineral taxation before the Inter State Council, so a producing State’s objection is answered rather than litigated.

    Conclusion

    The quarrel is not about whether a mineral is taxed but about who fixes the charge on a mineral the State owns. Watch whether Jharkhand takes its objection to court, because refusal alone cannot stop a central levy.

    Back2Basics: Mines and Minerals (Development and Regulation) Act, 1957

    1. Scope of the Act: The Act regulates mineral concessions and the development of major minerals, other than petroleum and atomic minerals.
    2. Who grants a lease: State governments grant prospecting licences and mining leases, under rules the Centre lays down.
    3. Auction and the district fund: The 2015 amendment made auction the only route to a concession and created a District Mineral Foundation in every mining district.

    Matching Previous Year Question

    “[2025, GS2, 15 marks] Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India?”

  • Bengal ‘Anti-Goonda’ Bill fails to get President’s nod due to overlap with Central legislation

    Why in the News

    The President has returned the West Bengal Public Safety and Control of Anti-Social Activities Bill, 2026 to the State for reconsideration. The Bill was introduced in the Assembly in June to curb anti social activities. The Centre’s note recorded that one clause of the Bill may create a parallel preventive detention mechanism for drug related activities. The stated objection is that this raises an issue of repugnancy under Article 254 of the Constitution. The contested point is that a State preventive detention law was stopped on duplication of a Central statute rather than on the reach of the powers it confers.

    What does the West Bengal Public Safety and Control of Anti-Social Activities Bill, 2026 do?

    1. The externment power: A District Magistrate, a Commissioner of Police or an authorised police officer not below the rank of Deputy Inspector General may order a person identified as a goonda out of a specified area, district or part of a district. The prohibition on entering or returning may run for up to one year.
    2. The reporting power: The same order may require that person to report his movements, or to report himself, at specified times to a specified authority.
    3. The trigger: The power turns on the authority’s apprehension that the person is engaging in or will engage in anti social activities. No finding on a past offence is required.
    4. The stated safeguard: The Chief Minister assured the Assembly that the legislation would not be used for political vendetta and that the preventive arrest provisions would not be misused.

    What exactly did the Centre object to?

    1. The clause in question: The Bill’s definition of goonda covers a person who commits, attempts to commit, abets, promotes, finances or facilitates any offence punishable under the Narcotic Drugs and Psychotropic Substances Act, 1985 (NDPS Act). The objection is confined to that single reference.
    2. The Central statute it collides with: The Prevention of Illicit Traffic in Narcotic Drugs and Psychotropic Substances Act, 1988 (PITNDPS Act) already provides a preventive detention framework for persons engaged in illicit traffic in narcotic drugs and psychotropic substances. The Centre’s note describes it as a specific Central legislation on that subject.
    3. The change asked for: The note asked that the reference to NDPS Act offences in the definition clause be deleted. Deletion is the only remedy proposed, and it leaves the rest of the Bill untouched.

    Why does a State law duplicating a Central law fail at the assent stage?

    1. The rule in Article 254: Article 254(1) makes a State law void to the extent that it is repugnant to a Central law on the same Concurrent List subject. Repugnancy does not require the State law to be objectionable in itself.
    2. The saving clause: Article 254(2) saves such a State law where it has been reserved for and has received the assent of the President. Presidential assent is therefore the only route by which an inconsistent State law can stand.
    3. The assent route: Under Article 200 a Governor may assent to a State Bill, withhold assent and return it once for reconsideration, or reserve it for the President. A Bill carrying a possible conflict with Central law travels by the third route.
    4. The ground of the return: The objection is to duplication rather than to the preventive powers. A parallel State mechanism on a subject a Central Act already occupies is precisely what Article 254 is designed to prevent.

    What happens to the Bill now?

    1. Return to the Assembly: The recorded position of the State administration is that the Bill may be tabled again once the conflicting portion is changed. It would then be sent again for the assent of the President.
    2. The six month clock: Where a reserved Bill is returned, the legislature must consider it within six months. The President is under no obligation to act if the Bill reaches him a second time.
    3. No judicially enforced deadline: State of Tamil Nadu v. Governor of Tamil Nadu (2025) required a decision within three months on a Bill reserved for the President. The Supreme Court’s later advisory opinion on the Presidential Reference under Article 143 held that courts cannot impose timelines under Articles 200 and 201.

    Challenges to the West Bengal Public Safety and Control of Anti-Social Activities Bill, 2026

    1. Procedure is the only real check: Preventive detention is tested on the fairness of its procedure rather than on guilt. Eg. Article 22 was read as a self contained code in 1950, and since 1978 the procedure for any deprivation of liberty must also be just, fair and reasonable under Article 21.
      The Fix: Write the grounds, the representation route and the review reference into the statute itself rather than leaving them to executive instructions.
    2. Central statutes already occupy the field: Each class of preventive detention already has a Central Act, so a State Act reaching the same conduct invites the objection this Bill received. Eg. Smuggling and foreign exchange violations are covered by the Conservation of Foreign Exchange and Prevention of Smuggling Activities Act, 1974 (COFEPOSA).
      The Fix: Screen a State preventive detention Bill against every Central Act on the same subject before introduction rather than at the assent stage.
    3. The assent stage has no agreed discipline: A State Bill reserved for the President can wait without a stated end date, and the reform proposals on this have not been acted on. Eg. The Punchhi Commission recommended time limits for granting assent in 2010.
      The Fix: Require the Centre’s observations on a reserved Bill to be published within a fixed period, so a State learns the objection during the same session.

    Conclusion

    The objection returned to West Bengal is narrow and curable by deleting one reference. That is also what makes it revealing. A State preventive detention law was stopped on the tidiness of the statute book rather than on the reach of the powers it grants, and nothing in the return questions the externment or reporting powers themselves. The thing to watch is whether the amended Bill goes back with only the drug reference removed, or whether the Assembly uses the reconsideration to write procedural safeguards into the text.

    Back2Basics: Preventive detention

    1. Nature of the power: Detention imposed to prevent a future act rather than to punish a past one. No trial follows, and the detention rests on executive satisfaction.
    2. Safeguards that do not apply: Articles 22(1) and 22(2) do not apply, so there is no right to be produced before a Magistrate within 24 hours and no constitutional right to counsel at the initial stage.
    3. The outer limit: Article 22(4) caps detention at three months without a reference to an Advisory Board. Parliament may extend that period under Article 22(7).
    4. The Central statutes: The National Security Act, 1980 covers national security and public order, COFEPOSA covers smuggling and foreign exchange, and the PITNDPS Act covers drug trafficking.

    Matching Previous Year Question

    “[2026, GS2, 15 marks] Discuss the position of the Governor in the federal polity of India. What is the nature of his power while giving assent to a bill passed by the State Legislature? Is he bound by the aid and advice of his Council of Ministers in all his functions?”

  • Why does Article 371 exist in so many different forms?

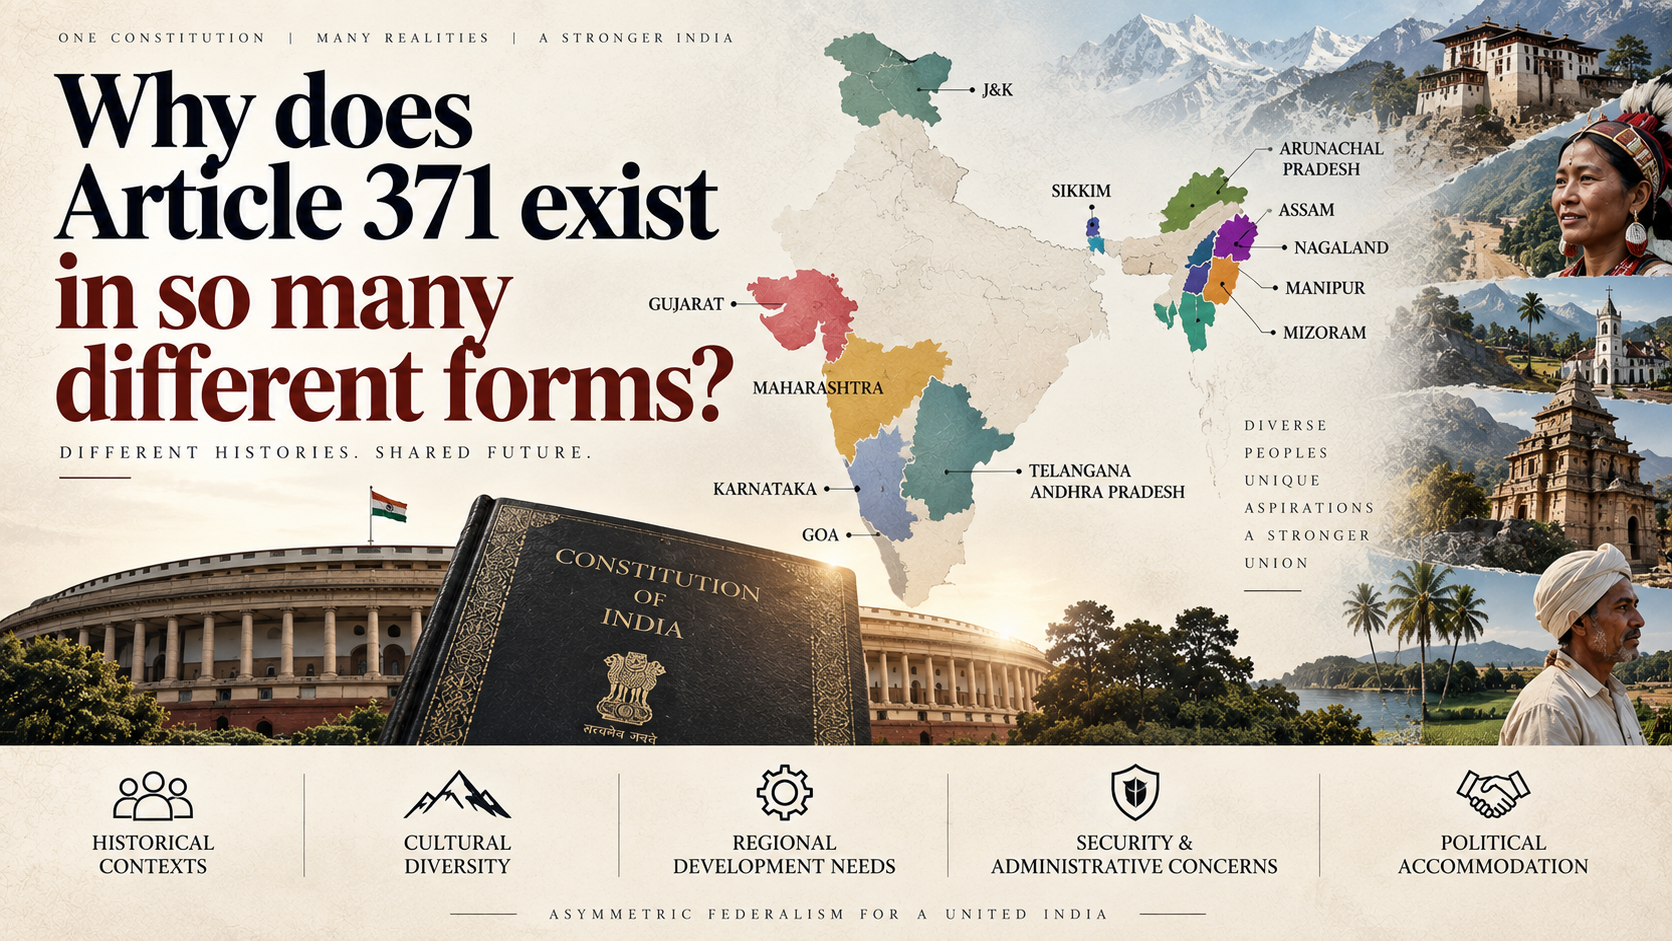
    Why does Article 371 exist in so many different forms?

    Why in the News

    The Centre has proposed inserting a new provision, Article 371K, in the Constitution to give special constitutional safeguards to Ladakh. The proposal follows an “in-principle understanding” reached between the Ministry of Home Affairs and representatives of the Apex Body, Leh (ABL) and the Kargil Democratic Alliance (KDA). That understanding is to create a directly elected Union Territory level body carrying legislative, executive, financial and planning powers. The tension is that every existing Article 371 provision was written for a State, while Ladakh is a Union Territory with no legislature at all, so the proposed clause has to create the institution before it can protect it.

    What is Article 371?

    1. The original purpose: Article 371 was not written to protect the Northeast or tribal regions. It was a transitional provision for Central supervision over the Part B States, the former princely territories that acceded to India under different historical and administrative circumstances.
    2. The Part B classification: The Constitution classified Hyderabad, Mysore, Jammu and Kashmir, Rajasthan and others separately as Part B States, because the framers were concerned about newly integrated territories functioning immediately within the same framework as the former British provinces.
    3. What it actually did: Adopted in 1950, it placed the governments of the Part B States under the general control of the President for 10 years, or for such longer or shorter period as Parliament might prescribe.
    4. How it disappeared: The States Reorganisation Act and the Seventh Constitutional Amendment of 1956 abolished the Part A, Part B and Part C classification. The original Article 371 vanished with it, and Parliament replaced it with a provision for equitable development of Vidarbha, Marathwada, Saurashtra and Kutch in Maharashtra and Gujarat.

    Why did a transitional clause become the constitutional home for special protection?

    1. Flexibility as a design choice: India’s constitutional system was built to accommodate regions whose historical circumstances, social structures or political demands differed from the rest of the country.
    2. Bespoke rather than uniform: Parliament repeatedly created individually negotiated arrangements under the same Article number, so the 371 series is a set of separate bargains and not a single doctrine of autonomy.
    3. The trigger is always political settlement: Each insertion followed an accord, a formula or a reorganisation, which is why no two clauses protect the same thing or work the same way.
    4. The number is a container, not a principle: A clause under Article 371 can mean customary law protection in one State and a minimum Assembly size in another, so the label carries no fixed content.

    What does each State specific provision actually protect?

    1. Nagaland, Article 371A: Inserted by the 13th Amendment Act, 1962 following the 16-Point Agreement of 1960. It protects Naga religious and social practices, customary law and procedure, and ownership and transfer of land and its resources.
    2. Assam, Article 371B: Inserted by the 22nd Amendment Act, 1969. It allows the President to create a committee within the Assam Legislative Assembly of members elected from the tribal areas covered by the Sixth Schedule, giving protected tribal areas a distinct voice.
    3. Manipur, Article 371C: Inserted by the 27th Amendment Act, 1971, ahead of Manipur becoming a full State in 1972. It provides a special Assembly committee of members elected from the hill areas, with the Governor responsible for reporting to the President on their administration.
    4. Andhra Pradesh and Telangana, Article 371D: Inserted by the 32nd Amendment Act, 1973 after the Six-Point Formula of 1973, and substituted by the Andhra Pradesh Reorganisation Act, 2014. It provides equitable opportunities in education and public employment across regions of the State.
    5. Sikkim, Article 371F: Inserted by the 36th Amendment Act, 1975. It was essentially a transition instrument for the integration of the erstwhile independent State, which became India’s 22nd State after a referendum.
    6. Mizoram, Article 371G: Inserted by the 53rd Amendment Act, 1986 following the 1986 Mizo Peace Accord. Parliamentary laws on Mizo religious and social practices, customary law and procedure, customary administration of justice, and land ownership do not apply unless the Mizoram Assembly agrees.
    7. Arunachal Pradesh, Article 371H: Inserted by the 55th Amendment Act, 1986 ahead of statehood in 1987. It gives the Governor a special responsibility for law and order, which is the opposite of the autonomy model used elsewhere.
    8. Goa, Article 371I: Inserted by the 56th Amendment Act, 1987. It is comparatively modest and simply requires the Goa Legislative Assembly to have at least 30 members.
    9. Karnataka, Article 371J: Inserted by the 98th Amendment Act, 2012 for the Hyderabad-Karnataka region, now Kalyana Karnataka. It addresses regional backwardness through a development board, equitable allocation of funds, and opportunities in public employment and education.

    Why does Ladakh’s demand not fit any existing 371 provision?

    1. A Union Territory without a legislature: Every existing clause operates on a State that already has an Assembly. The proposed Article 371K would apply to a Union Territory that has none, so it has to create the elected body rather than qualify one.
    2. The subject list sought: The Ministry of Home Affairs has said the body would have legislative powers over land, culture and language, forests, environment and natural resources, along with other subjects reserved for the Union Territory under Article 240.
    3. Law and order runs the other way: Article 371H gives the Governor special responsibility for law and order in Arunachal Pradesh. Ladakh’s leaders are seeking the opposite, which is control over law and order by the elected body.
    4. Land protection borrows a different model: The land protection sought resembles the design of Articles 371A and 371G, under which certain Parliamentary laws on land and customary practices do not apply automatically.

    What will decide whether Article 371K is strong or symbolic?

    1. The weak version: A provision that merely creates an elected body and lists the subjects it may legislate on would offer relatively limited protection.
    2. The demonstrated failure case: Hill tribes in Manipur have argued that Article 371C has failed to deliver on its promise of meaningful autonomy and protection, so a committee based design is not evidence that protection follows.
    3. The strong version: A clause protecting the elected body’s control over land, natural resources, recruitment and administration would be considerably stronger.
    4. The strongest version: Placing law and order and the bureaucracy under the elected executive would make the Ladakh head of government more powerful than the Jammu and Kashmir Chief Minister.

    Challenges to the proposed Article 371K

    1. Special provisions are read down by courts over time: A protective clause survives on paper while its practical scope narrows through litigation on which Parliamentary laws it actually excludes. Eg. Article 371A’s protection over land and resources has been repeatedly tested against Central directives in the petroleum and mining sectors in Nagaland.
      The Fix: Enumerate in the clause itself the Union List and Concurrent List entries that will not apply automatically, rather than leaving the exclusion to interpretation.
    2. Legislative power without fiscal capacity is nominal: An elected body can legislate on land and forests and still depend entirely on Central transfers for every scheme it runs. Eg. The Hyderabad-Karnataka development board under Article 371J operates on annual State allocations rather than an assured statutory share.
      The Fix: Attach a statutory minimum devolution to the Ladakh body, computed on a formula, so its legislative competence is matched by a predictable resource base.
    3. A committee model can be captured by the majority region: Where a special committee sits inside a larger Assembly, the protected region can be outvoted on everything the committee does not exclusively own. Eg. The hill areas committee under Article 371C in Manipur has been the standing grievance of the hill districts against the Imphal Valley.
      The Fix: Give the Ladakh body exclusive rather than advisory competence over the named subjects, so its decisions do not require ratification by a wider chamber.
    4. Two subregions with divergent demands: Leh and Kargil have historically sought different constitutional outcomes, and a single body can reproduce that contest instead of settling it. Eg. The Ladakh Autonomous Hill Development Councils were created separately for Leh in 1995 and Kargil in 2003.
      The Fix: Fix a seat and revenue sharing formula between the two districts inside the constitutional provision, rather than leaving it to the body’s own rules of business.
    5. Law and order transfer is the hardest concession to obtain: The Centre has consistently retained police and public order in Union Territories, and Ladakh sits on a live boundary with China. Eg. Delhi’s elected government has no control over the police despite having a legislature since 1993.
      The Fix: Create a staged transfer, with a Ladakh police service raised under the elected executive for civil policing while border and internal security remain with the Centre.

    Conclusion

    Article 371 has never been a single guarantee, and its nine surviving clauses were each written to close a specific political settlement. The Ladakh proposal is the first attempt to use that Article to build a legislature where none exists, which makes it a constitutional innovation rather than an extension. What to watch is whether the final text of Article 371K lists exclusive subjects and places law and order under the elected executive, or stops at creating a body and naming what it may discuss.

    Back2Basics

    1. Article 240: It empowers the President to make regulations for the peace, progress and good government of certain Union Territories, including Ladakh.
    2. Force of law: A regulation made under Article 240 has the same force and effect as an Act of Parliament, and may repeal or amend a law made by Parliament as it applies to that Union Territory.
    3. Why it matters here: The subjects reserved to Ladakh under Article 240 are the pool from which the proposed elected body’s legislative competence would be drawn.
    4. Its limit: The power belongs to the President, so a Union Territory governed under it has no democratic legislature of its own unless one is separately created.

    Matching Previous Year Question

    “[2013, GS2, 10 marks] Recent directives from Ministry of Petroleum and Natural Gas are perceived by the `Nagas’ as a threat to override the exceptional status enjoyed by the State. Discuss in light of Article 371A of the Indian Constitution.”
  • Won’t provide land in T.N. for Navodaya schools: Minister

    Why in the News

    Tamil Nadu’s Minister for School Education has said the State will not provide land for establishing Navodaya schools that follow the Central Board of Secondary Education (CBSE) syllabus, and that the State remains firm on its two language policy in schools. The statement answers the Supreme Court, which has given Tamil Nadu three months to comply with its direction of 15 December 2025 to identify land in each district for Navodaya schools. At the same hearing on the adoption of the Navodaya Vidyalaya Scheme in the State, the Court said Tamil Nadu had to change its “mindset” that Hindi could not be taught there, and cautioned that “individual States cannot act like individual countries”. The tension is between a judicial direction to perform an administrative act and a State’s control over both land and school language policy. The State has offered no legal challenge to the direction and no compliance with it either.

    What is the Navodaya Vidyalaya Scheme?

    1. What it provides: It runs Jawahar Navodaya Vidyalayas, co educational residential schools offering free education from Class VI to Class XII, with one school intended for every district.
    2. Who runs it: It is administered by the Navodaya Vidyalaya Samiti, an autonomous body under the Ministry of Education, and the schools are affiliated to the CBSE.
    3. Who it targets: Admission is through a selection test at Class VI, and at least 75% of seats in a school are reserved for candidates from rural areas of that district.
    4. What the State must supply: The Centre funds and runs the school, while the State government is expected to provide the land on which it is built.

    What is Tamil Nadu’s stated ground for refusing?

    1. The language policy: The State follows a two language policy in schools and has said there will be no change in that stand.
    2. The statutory anchor: The previous Dravida Munnetra Kazhagam (DMK) government, in an affidavit filed in March this year, said the Navodaya scheme deviated from the mandate of the Tamil Nadu Tamil Learning Act, 2006.
    3. The stated motive alleged: That affidavit alleged the scheme was only a “backdoor” route to making Hindi compulsory in the State.
    4. The claimed alternative: The State’s position is that it already runs model schools successfully, and that students from those schools have gone on to higher education.
    5. The position on the Court’s remarks: The State has treated the judge’s oral observations as an opinion rather than a verdict, on the stated ground that the judicial proceedings are still under way.

    Why is land the pressure point in this dispute?

    1. Two different lists: Education sits at Entry 25 of the Concurrent List after the Constitution (Forty second Amendment) Act, 1976, while land sits at Entry 18 of the State List, so the Centre may frame the scheme but cannot supply the site.
    2. A veto without a challenge: A State that declines to allot land stalls a central scheme without having to contest its validity, so the dispute never reaches the question of legislative competence.
    3. What the Court can and cannot order: A direction to identify land can be issued, and it has been, but the identification itself is an executive act of the State administration, which is why the remedy has so far been an extension of time rather than an execution order.

    Challenges to the Navodaya Vidyalaya Scheme in Tamil Nadu

    1. A central scheme dependent on a State asset: A centrally funded school cannot be built without a State allotment order, so a State can stop the scheme without legislating against it. Eg. The direction to identify land in every district has run since December 2025 without a single site being notified.
      The Fix: Route the scheme through central government land holdings or centrally acquired land in States that decline allotment, so the school is not contingent on a State order.
    2. Weak enforcement of a direction against a State government: A court can direct compliance but has no machinery of its own to perform an administrative act, so compliance turns on political will. Eg. The Court has had to extend time rather than treat its earlier direction as executed.
      The Fix: Require a dated compliance affidavit for each district with the State Chief Secretary personally answerable for every district returned as nil.
    3. Language requirement as a condition of access: Tying a school system to a language requirement converts an education entitlement into a political question, and the entitlement is what is lost. Eg. Admission runs through a common selection test at Class VI, so a student in a State without these schools has no route into free residential central schooling.
      The Fix: Permit the State’s own two language combination inside the school, so the language dispute stops deciding who gets a seat.
    4. Rural students bear the cost of the standoff: Most seats are reserved for rural candidates, so the students shut out are those least able to pay for residential schooling. Eg. The dispute has run for the length of a full academic cycle without a school being sited.
      The Fix: Pending resolution, extend seats in Navodaya schools in neighbouring States to Tamil Nadu candidates on the same rural reservation terms.

    Conclusion

    The standoff is not about whether a school can be built. It is about what a court can require a State to do when the State’s objection is to a scheme’s content rather than to its legality. Tamil Nadu has neither challenged the direction nor complied with it, and the Court has answered with more time rather than with coercive process. The marker to watch is what the State files at the end of the three months, since a district by district compliance statement would close the matter and its absence would move it from direction to enforcement.

    Back2Basics: the three language formula

    1. What it prescribes: It requires the study of three languages in school, and in the form recommended for Hindi speaking States it covers Hindi, English and a modern Indian language, while in non Hindi speaking States it covers the regional language, English and Hindi.
    2. Where it comes from: It was adopted in the National Policy on Education, 1968, carried forward in the National Policy on Education, 1986, and retained in the National Education Policy, 2020.
    3. What the 2020 policy changed: The policy states that no language will be imposed on any State and leaves the choice of the three languages to States, regions and students, provided at least two of the three are native to India.
    4. Tamil Nadu’s position: The State has stayed outside the formula since 1968 and has followed a two language policy of Tamil and English in schools since then.

    Matching Previous Year Question

    “[2024, GS2, 15] What changes has the Union Government recently introduced in the domain of Centre-State relations? Suggest measures to be adopted to build the trust between the Centre and the States and for strengthening federalism.”

  • Supreme Court asks Tamil Nadu to comply with order to identify land for Navodaya schools

    Why in the News

    The Supreme Court has asked the Tamil Nadu government to comply with its order to identify land for establishing Navodaya schools in every district of the State, and has given it three months to do so. A two judge Bench framed the direction around the need to strengthen cooperative federalism, and asked the Centre and the State to settle their differences on language policy and funding through dialogue. The direction continues a chain that began with a Madras High Court order of 11 September 2017, which asked the State to identify an appropriate place and building for the school and thereafter to allocate suitable land in every district. The Supreme Court had itself asked the State to identify the land in December 2025, and the State came back seeking a recall of that order rather than compliance. The contest is over what a national residential school brings with it: the State’s stated objection is not to Hindi being taught but to Hindi being taught as the predominant language in higher classes, while the Court’s position is that an additional school network cannot lower the State’s own standards.

    What is the Navodaya Vidyalaya Scheme?

    1. About: Jawahar Navodaya Vidyalayas are fully residential, co educational schools funded by the Union government to give talented rural children access to quality schooling without paying for it.
    2. Administration: The schools are run by the Navodaya Vidyalaya Samiti, an autonomous body under the Ministry of Education, and are affiliated to the Central Board of Secondary Education (CBSE).
    3. Coverage design: The scheme provides for one school in each district of the country, with the State supplying the land and the Centre funding construction and running costs.
    4. Entry: Admission is at Class 6 through the Jawahar Navodaya Vidyalaya Selection Test, with a majority of seats in each district reserved for rural candidates.

    What did the Court direct, and what was it responding to?

    1. Compliance, not recall: The State asked the Court to recall its earlier direction to identify land, and the Court refused, giving the State three months to identify the land instead.
    2. Scope of the direction: The obligation is to identify land in all districts, which is the same two step sequence the Madras High Court laid down: fix a place and a building first, then allot suitable land.
    3. Dialogue as the route: The Bench asked the State’s Secretary to speak with Central officials, and directed that differences on language policy and funding be resolved through discussion rather than through further litigation.

    Why has Tamil Nadu resisted the schools?

    1. Language policy, not Hindi teaching: Counsel for the State told the Court that the objection is not to Hindi being taught, but to Hindi being taught as the predominant language in higher classes.
    2. The Court’s factual answer: The Bench pointed out that Hindi is already taught in many schools in the State, and said the State should change its mindset on the question.
    3. A middle position was offered: The Bench indicated that a demand for Tamil as a second language inside the school is a matter that can be considered.
    4. Beyond language: The Court grouped funding alongside language as a live Centre State difference to be settled by discussion, so the dispute is not confined to the medium of instruction.

    How did the Court frame this as a federal question?

    1. Cooperative federalism as the stated ground: The Court underlined the need to strengthen cooperative federalism as the reason for asking the State to comply, rather than treating the matter as a bare question of executing a High Court order.
    2. Addition, not substitution: The Bench held that more schools of another type in the State would only enhance its education network and expand opportunity for students, and would not lower the standard of education there.
    3. Neither side is being displaced: The Bench recorded that the order alienates neither the State nor the Centre, adding that people in Chennai should not alienate Delhi and the reverse should not happen either, and that everybody must ultimately work together.

    Challenges to the Navodaya Vidyalaya Scheme

    1. Dependence on State land allotment: The Centre funds and runs the school but cannot open one until the State allots land, so a State that withholds land blocks the scheme completely. Eg. Tamil Nadu has no Jawahar Navodaya Vidyalaya despite the scheme having run since 1986.
      The Fix: Write a land allotment timeline into the scheme guidelines against a named nodal secretary in each State, so the step produces a dated decision rather than an open file.
    2. A single entry point: General admission happens only at Class 6 through one selection test, so a child who misses that year has no ordinary route in later. Eg. Entry at Class 9 is confined to seats left vacant in a school.
      The Fix: Reserve a fixed share of Class 9 seats in every school for lateral entry, advertised on the same calendar as the Class 6 test.
    3. Scale against district demand: One school per district cannot absorb the demand for free residential schooling in a populous district. Eg. A standard Jawahar Navodaya Vidyalaya admits about 80 students a year at Class 6.
      The Fix: Sanction a second school in districts where applications exceed a set multiple of the sanctioned intake.

    Conclusion

    The dispute is no longer about whether the schools are good for students. It is about whether a State can decline a centrally funded institution because of the language package attached to it. The Court has converted that into a procedural question with a deadline: identify the land in three months, and take the language and funding disagreement to the officials rather than back to the Bench. What to watch is whether the State’s Secretary and the Central officials produce a settled position on the second language inside these schools before the three months run out.

    Matching Previous Year Question

    “[2024, GS2, 15] What changes has the Union Government recently introduced in the domain of Centre-State relations? Suggest measures to be adopted to build the trust between the Centre and the States and for strengthening federalism.”

  • Mining amendment is unfair to States

    Mining amendment is unfair to States

    Why in the News

    Section 9D of the Mines and Minerals (Development and Regulation) Amendment Act, 2026 restricts State governments from imposing taxes, cesses or other levies on mineral rights or mineral-bearing land, except in accordance with conditions prescribed by the Centre. The provision follows Mineral Area Development Authority vs. Steel Authority of India (2024), in which a nine-judge Bench of the Supreme Court held that royalty payable on minerals is not a tax. The same Bench recognised the States’ legislative power to tax mineral rights and held that mineral-bearing land falls within the States’ taxation power over land. The tension is that Entry 50 of the State List lets Parliament limit State taxation of mineral rights, while the new section extends its restriction to levies on mineral-bearing land, a separate power under Entry 49 of the State List. What is contested is not the revenue States receive today but the levies they may be barred from raising tomorrow.

    What does Section 9D do?

    1. Scope of the restriction: It bars States from imposing taxes, cesses or other levies on mineral rights or on mineral-bearing land except as the Centre prescribes.
    2. Where the discretion sits: The conditions under which a State may levy are set by the Central government, so future State levies depend on a framework the Centre controls.
    3. What it does not touch: Royalty, the auction premium and the other mineral revenues States currently receive are not altered by the section.

    What is the Centre’s case for a uniform levy framework?

    1. Predictability for investors: The stated objective is to create a predictable tax environment, prevent excessive levies and encourage long-term investment in mining.
    2. Project horizons: Mining projects involve enormous investment and operate over decades, so investors need assurance that financial rules will not change unpredictably from one year to the next.
    3. Revenue assurance offered: The Centre’s position is that 90% of mining sector revenue accrues to the States and that this will continue.

    Why do mineral-rich States object?

    1. Uneven distribution of the resource: India’s mineral wealth is concentrated rather than spread evenly. Odisha, Jharkhand, Chhattisgarh and Karnataka hold enormous reserves of coal, iron ore and other minerals that feed industries across the country.
    2. Costs land on the host State: The host State handles resettlement of displaced groups, environmental damage, pressure on public infrastructure and the long-term consequences of extracting minerals that can never be replaced.
    3. Budgets tied to mining receipts: NITI Aayog’s Fiscal Health Index has recognised the role mining receipts play in the strong revenue mobilisation performance of Odisha and Chhattisgarh. Mining accounts for a large proportion of Odisha’s non-tax revenue.
    4. Higher spending needs in mineral districts: Mineral producing districts require greater public expenditure precisely because they bear the costs of mining.
    5. Loss of a natural advantage: A mineral-rich State ordinarily expects some ability to convert that advantage into resources for its own development, and the section substantially reduces that freedom.

    What is the constitutional objection to Section 9D?

    1. Entry 50 and its built-in limit: The Constitution gives States the power to tax mineral rights under Entry 50 of the State List, subject to limitations Parliament may impose through laws relating to mineral development.
    2. Entry 49 is a separate power: The power to tax lands and buildings under Entry 49 of the State List is a distinct constitutional head and carries no equivalent parliamentary limitation clause.
    3. Where the section goes further: By extending the restriction to taxes or levies on mineral-bearing land, the section reaches a power Entry 50 does not authorise Parliament to limit.
    4. Risk to the 2024 ruling: The amendment risks rendering the impact of the nine-judge ruling nugatory, since a power the Court affirmed can be neutralised by prescription rather than by overruling.
    5. The question it raises: How far can a Central law dealing with mineral development restrict a State’s exclusive power to tax land is now a live constitutional question rather than a mining policy dispute.

    Challenges to Section 9D

    1. Responsibility without fiscal capacity: A federal system cannot function where States carry obligations they have no independent means to fund. Eg. Mineral districts must fund resettlement and infrastructure repair from receipts the Centre may now condition.
      The Fix: Confine the prescribed conditions to levies on mineral rights under Entry 50 and leave the Entry 49 land taxation power untouched.
    2. Predictability purchased by narrowing State choice: Uniformity makes taxation more predictable for investors and reduces the fiscal options available to States. Eg. A State cannot design a mineral-linked levy to fund a district-specific rehabilitation programme without Central prescription.
      The Fix: Set a ceiling on State mineral levies in the statute itself rather than routing each levy through Central approval, so investors get the certainty without the States losing the power.
    3. Litigation risk over a settled question: A provision that neutralises a nine-judge ruling by executive prescription invites a fresh round of constitutional challenge. Eg. Mineral Area Development Authority vs. Steel Authority of India itself ran for decades before it was settled in 2024.
      The Fix: Refer the scope of Section 9D to the Inter-State Council under Article 263 before conditions are prescribed, so the levy framework is negotiated rather than litigated.
    4. Concentration of the burden on a few States: The section’s cost is borne almost entirely by a handful of mineral-bearing States rather than spread across the Union. Eg. Odisha, Jharkhand, Chhattisgarh and Karnataka carry the bulk of the country’s coal and iron ore output.
      The Fix: Weight mineral-bearing districts explicitly in the next Finance Commission’s horizontal devolution formula, so extraction costs are recognised in transfers.

    Conclusion

    The minerals beneath a State’s soil serve the entire country, and the costs of extracting them are felt most directly by the people who live above them. A State that bears the infrastructural and social consequences of extraction must retain a meaningful stake in the economic value its natural resources generate. The unresolved point is whether a Central law on mineral development may condition a State’s power to tax land, a power the Constitution places under a separate entry and does not subject to parliamentary limitation. That question now sits between a statute in force and a nine-judge ruling that has not been overruled.

    What is Fiscal Federalism?

    1. About: It is the division of taxation powers, expenditure responsibilities and transfer arrangements between the levels of government in a federation.
    2. Rationale: It exists because the level of government best placed to raise a tax is often not the level that must spend on the service, so the design has to close that gap without destroying accountability.
    3. Vertical imbalance: The Union raises a larger share of revenue than it spends directly, while States carry the larger share of expenditure obligations, and transfers bridge the difference.
    4. Horizontal imbalance: Revenue capacity differs sharply across States of similar need, which is why devolution formulas weight income distance, area and population rather than collections alone.

    Back2Basics: NITI Aayog’s Fiscal Health Index

    1. What it is: A composite index published by NITI Aayog that ranks States on the quality of their public finances.
    2. What it measures: It scores States on sub-indices covering quality of expenditure, revenue mobilisation, fiscal prudence, debt index and debt sustainability.
    3. First edition: The maiden report was released in January 2025 and covered 18 major States.
    4. Why it matters here: It is the benchmark that records mining receipts as a driver of revenue mobilisation performance in mineral-bearing States.

    Matching Previous Year Question

    [2025] Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India?

  • Mining, money & federalism: Why a new law is at the centre of a political tussle in Odisha

    Why in the News

    Parliament has passed the Mines and Minerals (Development and Regulation) Amendment Act, 2026. It sets a uniform national tax framework for major minerals and limits the power of States to levy taxes on mining lands. The step overrides the financial effect of Mineral Area Development Authority v. Steel Authority of India (2024). A nine judge Constitution Bench had held there, by a majority of 8 to 1, that States hold the power to tax mineral rights and mineral bearing lands. The contest is over who collects the revenue that mining generates, and Odisha is where it is sharpest. Three States have taken the amendment to the Supreme Court, so a question the largest Bench to hear it had settled is open again.

    What does the 2026 amendment change about who can tax mining?

    1. A bar on State levies: The new Section 9D provides that no tax, cess or other levy shall be imposed by a State on mineral rights or on mineral bearing lands, whether computed on mineral quantity, mineral value, royalty payable or otherwise.
    2. A conditional exception only: A State may levy only in accordance with such conditions or restrictions as the Central Government prescribes.
    3. Wider central reach: Amendments to Section 2 and Section 13 extend the Centre’s control to mineral bearing lands.
    4. Rule making is centralised: The Centre is given sole authority to frame the rules that restrict the taxing power of States over minerals.

    What did the Supreme Court hold in 2024?

    1. Royalty on extraction: States were held competent to levy royalty on the extraction of minerals from land within the State.
    2. Tax on mineral bearing land: The same ruling held that States may tax the lands which comprise mines and quarries.
    3. The central law was read as no bar: The Bench held that the parent mining statute did not take away the taxing competence of the States in this field.
    4. Past dues were opened up: Recovery of dues for earlier years was permitted in staggered instalments, which is the origin of the arrears claims now in dispute.

    Why is Odisha the sharpest site of the dispute?

    1. The stakes as the Opposition states them: The Biju Janata Dal (BJD) puts the cost to Odisha at Rs 12,000 crore a year in foregone revenue and Rs 1 lakh crore in arrears.
    2. The procedural objection: A letter from the former Chief Minister of Odisha to the State’s ruling party Members of Parliament records that the Bill was passed with less than 10 minutes of discussion in the Lok Sabha.
    3. The framing of the contest: The Opposition presents the law as an attack on federalism and on the financial rights of the State rather than as a technical tax measure.
    4. Street level escalation: The Congress and the Left have announced a gherao of the Odisha Assembly on 29 September.
    5. The legal challenge is already under way: Karnataka, Kerala and Telangana have moved the Supreme Court against the amendment, and the Odisha unit of the Congress has said it will do the same.
    6. Why the State is so exposed: The economy and the politics of Odisha are closely tied to mining, so a change in mineral taxation reaches its budget directly.

    What is the case made for a uniform national framework?

    1. Multiple levies deter industry: On the State government’s own argument, arbitrary and multi level levies on mineral bearing land would cause extensive damage to the industrial ecosystem of the State.
    2. Mining revenue has already risen sharply: The State’s Steel and Mines Minister puts earnings from the mining sector at about Rs 50,000 crore, against about Rs 5,000 crore before 2014.
    3. A second channel already reaches States: States continue to receive money for mining affected areas through the District Mineral Foundation (DMF), a non profit trust set up by the State government.
    4. The earlier reform is offered as the cause: That rise in receipts is attributed to the last amendment of the parent Act in 2015, which moved major mineral concessions to competitive auction.

    Challenges to the MMDR Amendment Act, 2026

    1. A statute answering a constitutional finding invites a second round: Where a Bench locates a taxing power in the State List, an ordinary central law restricting its exercise raises the question of legislative competence rather than settling it. Eg. Royalty and cess on minerals has been litigated repeatedly since the India Cement judgment of 1990.
      The Fix: Route the change through a constitutional amendment or a Finance Commission mediated compensation formula rather than through a bar inserted by ordinary law.
    2. Producing districts carry the costs of mining and lose the levy: Land degradation, displacement and water stress sit in the mining district, with the taxing power moving upward. Eg. The iron ore districts of Keonjhar and Sundargarh in Odisha carry heavy overburden dumping and haulage traffic.
      The Fix: Make a fixed share of central mineral receipts a statutory entitlement of the producing district rather than a discretionary allocation.
    3. Revenue predictability for States falls: A levy that can be permitted or withdrawn through prescribed central conditions cannot be budgeted for with confidence. Eg. Mineral rich States had already built projected receipts into their medium term fiscal statements.
      The Fix: Fix the permitted State levy in the Act itself with a floor, so it is not alterable by executive prescription.
    4. Uniformity ignores unequal mineral endowment: A single national framework treats a State with large reserves and a State with none as comparable for taxation purposes. Eg. Odisha, Jharkhand and Chhattisgarh together account for the bulk of India’s iron ore and coal output.
      The Fix: Build an endowment weighted transfer into the framework so producing States are not equalised downward.
    5. Litigation freezes investment decisions: A pending challenge to the taxing framework leaves both States and lessees uncertain about liability for the interim period. Eg. The 2024 ruling itself came at the end of litigation running over three decades on the same question.
      The Fix: Seek an early and time bound hearing along with an interim arrangement on collection, so liability does not accumulate unresolved.

    Conclusion

    The dispute is no longer about the rate at which minerals are taxed. It is about whether a fiscal power the Court located with the States can be narrowed by ordinary central legislation. Until the challenge is decided, mineral rich States must budget for revenue they may not be permitted to collect. The marker to watch is whether the Court treats the new bar as a permissible exercise of the Union’s mining power or as an encroachment on a State legislative field.

    Back2Basics: Mines and Minerals (Development and Regulation) Act, 1957

    1. What it governs: It is India’s principal law for the development and regulation of mines and minerals.
    2. The Union’s declared control: The Act declares that the Union should take control of mining and mineral development to the extent provided by the Act.
    3. Major and minor minerals: Major minerals are regulated centrally under this Act, and minor minerals such as sand, building stone and ordinary clay are governed by State rules.
    4. The 2015 overhaul: That amendment moved allocation of major mineral concessions to auction, created the District Mineral Foundation and the National Mineral Exploration Trust (NMET), and strengthened penalties for illegal mining.

    Matching Previous Year Question

    “[2025] Consider the following statements: I. India has joined the Minerals Security Partnership as a member. II. India is a resource-rich country in all the 30 critical minerals that it has identified. III. The Parliament in 2023 has amended the Mines and Minerals (Development and Regulation) Act, 1957 empowering the Central Government to exclusively auction mining lease and composite license for certain critical minerals. Which of the statements given above are correct? (a) I and II only (b) II and III only (c) I and III only (d) I, II and III ANSWER: (c)”

  • BJD stages protest over Mines and Minerals Amendment Act

    Why in the News

    The Biju Janata Dal has demanded constitutional intervention to reverse the Mines and Minerals (Development and Regulation) Amendment Act, 2026, marching to the Lok Bhavan in Bhubaneswar and submitting a memorandum addressed to the President through the Governor. The demand answers the Supreme Court’s judgment in Mineral Area Development Authority v. Steel Authority of India (2024). That judgment recognised the power of State governments to impose taxes and levies on mines and mineral bearing lands. It also dealt with recovery of such dues for the period beginning 1 April 2005, which the party values at more than Rs 1 lakh crore in arrears for Odisha alone. The contest is between Parliament’s power to limit State taxation in the name of mineral development and a State’s claim on the revenue from minerals it owns.

    What has the party actually asked for?

    1. Reversal, not amendment: The memorandum seeks constitutional intervention for the reversal of the 2026 amendment rather than a modification of its terms.
    2. The route chosen: The petition was addressed to the President and routed through the Governor, placing the objection outside the legislative process the amendment has already cleared.
    3. The stated test: Any legislative measure that substantially curtails the rights and financial interests of a State in relation to mines and mineral bearing lands deserves careful constitutional and legal examination.

    What is at stake for Odisha’s revenue?

    1. The arrears claim: The State was estimated to become entitled to more than Rs 1 lakh crore towards arrears of mining related taxes and levies following the 2024 judgment.
    2. The recurring claim: A further approximately Rs 12,000 crore of additional annual revenue was estimated to follow from the recognised taxing power.
    3. Why the base is large: Odisha’s reserves of iron ore, coal, bauxite, chromite and other minerals have historically been a major source of revenue for the State government, so a change in the taxing head moves a large absolute sum.

    How does the amendment reverse the judgment’s effect?

    1. The provision used: A new Section 9D bars a State from imposing any tax, cess or other levy on mineral rights or mineral bearing lands, whether measured by quantity, value or royalty, except in accordance with conditions the Central Government prescribes.
    2. The constitutional hook: Entry 50 of the State List gives States the power to tax mineral rights subject to any limitations imposed by Parliament by law relating to mineral development, and this is the first exercise of that limitation.
    3. The stated justification: Some States had stacked around fourteen separate charges, with land taxes reaching 20 per cent, on the ground that blocks were being made commercially unviable.
    4. The disputed edge: The judgment recognised a separate State power to tax lands under Entry 49 of the State List, which Entry 50’s limitation clause does not reach, and that gap is what a challenge would target.

    Challenges to the Mines and Minerals (Development and Regulation) Amendment Act, 2026

    1. A statutory limit on a constitutional head: Curbing a State land tax through a central mining statute rather than a constitutional amendment leaves the reversal open to challenge on the ground that Parliament used a power it does not hold over Entry 49. Eg. Odisha and Jharkhand have both said they will test the amendment in the Supreme Court.
      The Fix: Settle the boundary between Entry 49 and Entry 50 by a reference under Article 143 before assessments under the new section are raised, rather than after a decade of recovery litigation.
    2. A recognised entitlement is extinguished after it accrued: The 2024 judgment allowed recovery from 1 April 2005, so States had already booked receivables that the amendment removes prospectively and retrospectively at once. Eg. Odisha’s estimated arrears rest entirely on that recovery window.
      The Fix: Protect dues that accrued before the amendment’s commencement by an express saving clause, so the limitation operates only on future levies.
    3. Mineral revenue is concentrated in a few States: A uniform national bar falls almost entirely on the small group of mineral bearing States, which cannot substitute the lost head from any other source. Eg. Odisha, Jharkhand and Chhattisgarh carry the bulk of India’s iron ore, coal and bauxite output and therefore the bulk of the foregone levy.
      The Fix: Compensate the affected States from a share of central mining receipts for a fixed transition period, on the model used for the Goods and Services Tax transition.
    4. Input cost stability is bought with fiscal centralisation: Capping State levies stabilises costs for steel, aluminium, cement and power at the price of removing a State’s only mineral specific tax head. Eg. The uneven and rising input cost that followed the 2024 judgment is the stated reason for the amendment.
      The Fix: Prescribe a ceiling rate for State levies under Section 9D rather than a bar, so cost predictability is achieved without extinguishing the head.

    Conclusion

    The dispute has moved from the courtroom to the constitutional offices and is heading back to the courtroom. A State whose taxing power was recognised by a judgment has been overridden by an ordinary central statute, and the party in opposition in that State has taken the objection to the President rather than to Parliament, where the amendment has already passed. What to watch is whether the mineral bearing States file the challenge they have threatened, and whether it is framed on Entry 49 rather than Entry 50.

    Back2Basics: The Mines and Minerals (Development and Regulation) Act, 1957

    1. Scope: It is the parent law for every mineral except petroleum and natural gas, and it sets who may explore, who may mine and what they pay.
    2. Ownership and leasing: The State government owns the mineral in its territory and signs every lease, even for a block the Centre has auctioned.
    3. Auction as the only route: The MMDR Amendment Act, 2015 made competitive auction the sole route to a mineral concession, replacing discretionary first come first served allocation.
    4. The 2023 shift: For 24 critical and strategic minerals the Centre took over the auction itself, moving the auctioning authority upward while leaving State ownership untouched.

    Matching Previous Year Question

    “[2025] Consider the following statements: I. India has joined the Minerals Security Partnership as a member. II. India is a resource-rich country in all the 30 critical minerals that it has identified. III. The Parliament in 2023 has amended the Mines and Minerals (Development and Regulation) Act, 1957 empowering the Central Government to exclusively auction mining lease and composite license for certain critical minerals. Which of the statements given above are correct? (a) I and II only (b) II and III only (c) I and III only (d) I, II and III ANSWER: (c)”