Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS3-01.Indian Economy and issues relating to planning, mobilization of resources, growth, development and employment.

  • Insurers seek first third party premium hike in four years

    Why in News?

    Non life insurers are pressing for their first motor third party premium hike in four years, citing a Supreme Court judgment recognising the economic value of homemakers’ unpaid domestic work.

    Key Highlights

    • In its 11 June 2026 judgment, the Supreme Court held that unpaid domestic work performed by homemakers has measurable economic value and must be fairly considered while awarding compensation under the Motor Vehicles Act, 1988.
    • Insurers argue that the ruling is likely to increase compensation payouts, adding to existing underwriting losses.
    • They have requested an upward revision in motor third party insurance premiums, the first such increase in four years.
    • The Central Government, in consultation with the Insurance Regulatory and Development Authority of India (IRDAI), notifies third party premium rates.

    Motor Third Party (TP) Insurance

    • Mandatory under the Motor Vehicles Act, 1988 for all motor vehicles operating in India.
    • Covers death, bodily injury, or property damage caused to a third party due to the insured vehicle.
    • Does not cover damage to the insured vehicle; that requires comprehensive motor insurance.
    • Premium rates are regulated by the Central Government, based on recommendations from IRDAI.

    Value Addition

    • IRDAI: Statutory regulator established under the Insurance Regulatory and Development Authority Act, 1999.
    • Motor Accident Claims Tribunal (MACT): Adjudicates compensation claims arising from road accidents under the Motor Vehicles Act, 1988.
    • Significance of the Supreme Court ruling: Strengthens recognition of the economic contribution of unpaid care work, advancing substantive gender equality and ensuring more equitable compensation in accident claims.

    [2026] With reference to different Committees in India, consider the following details :

    Sl. No.CommitteeObjectiveOrganization under which it was formed
    1R.N. Malhotra CommitteeComprehensive reforms of Insurance sector in IndiaInsurance Regulatory and Development Authority of India
    2L.C. Gupta CommitteePreparing a roadmap for the introduction of derivatives trading in IndiaSecurities and Exchange Board of India
    3Urjit R. Patel CommitteePreparing a roadmap for reforming bank lending to the Housing sectorReserve Bank of India
    4Y.H. Malegam CommitteePreparing a roadmap for reforms in Microfinance sector in IndiaReserve Bank of India


    In which of the above rows are all the details correctly matched ?

    [A] 2 only

    [B] 2 and 3

    [C] 1, 3 and 4

    [D] 2 and 4

  • Investment Friendliness Index (IFI)

    Why in News?

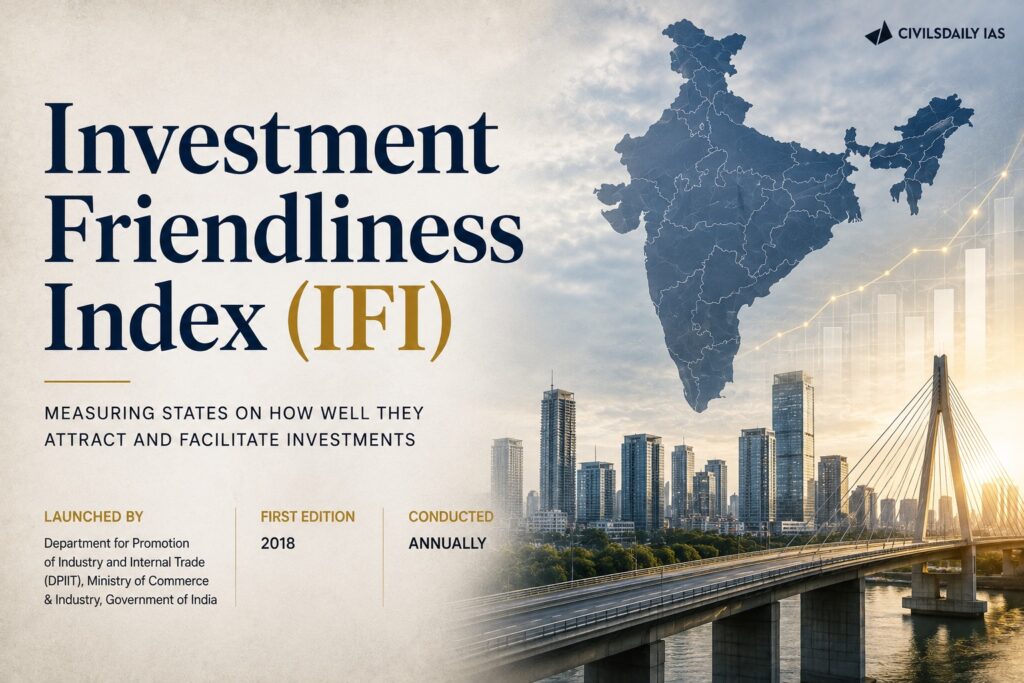
    NITI Aayog launched the Investment Friendliness Index (IFI) to assess and improve the investment ecosystem across States and UTs through competitive and cooperative federalism.

    What is IFI?

    • A data driven index that benchmarks how effectively States and UTs attract and sustain investments by evaluating their policy, regulatory, institutional, and infrastructure ecosystem.

    Background

    • Proposed after the 9th NITI Aayog Governing Council Meeting (2024).
    • Announced in the Union Budget 2025-26.

    Key Features

    • Covers 28 States and 8 UTs.
    • Based on 84 indicators using: Secondary data and Investor perception survey.

    Eight Pillars

    • Infrastructure. Business Climate, Resources, Government Policy, Regulatory Ease, Institutional Environment, Financial Health, and Environmental Resilience

    Performance Categories

    • Top Performers: Above 50
    • Frontrunners: 45 to 50
    • Emerging Performers: 40 to <45
    • Aspiring States: Below 40

    Top Performers

    • Overall: Gujarat, Maharashtra, Tamil Nadu, Goa, Odisha.
    • Hilly & NE States: Uttarakhand.
    • UTs & City States: Goa.

    Significance

    • Promotes competitive and cooperative federalism.
    • Encourages State level reforms and ease of investment.
    • Supports Viksit Bharat @2047 and Viksit Rajya @2047.

    [2019] Which one of the following is not a sub-index of the World Bank’s ‘Ease of Doing Business Index’?

    [A] Maintenance of law and order

    [B] Paying taxes

    [C] Registering property

    [D] Dealing with construction permits

  • Is FCNR(B) a litmus test for diaspora deposits?

    Why in the News?

    The Reserve Bank of India (RBI) has revived the Foreign Currency Non-Resident (Bank) [FCNR(B)] concessional swap window, last used when Raghuram Rajan was Governor, to defend a rupee that has depreciated 12% year-on-year against the U.S. dollar. The move comes as Foreign Portfolio Investors (FPIs) withdrew ₹2.87 lakh crore from Indian equities between January and the first week of June 2026, already surpassing the ₹1.66 lakh crore pulled out in all of 2025.

    What is Foreign Currency Non-Resident (Bank) [FCNR(B)] account and its concessional swap window?

    1. Definition: It is a fixed-term deposit account for Non-Resident Indians (NRIs), Persons of Indian Origin (PIOs), and Overseas Citizens of India (OCIs) that keeps funds in foreign currencies like USD, GBP, EUR, JPY, AUD, or CAD with tax-free interest and full repatriation.
    2. No Exchange Risk: Funds stay in the original foreign currency from deposit to maturity, protecting from rupee value changes.
    3. The FCNR(B) concessional swap window: It is a special Reserve Bank of India (RBI) facility that allows Indian banks to swap long-term foreign currency NRI deposits at a heavily discounted hedging cost, helping boost India’s foreign exchange inflows.

    What has the RBI designed to attract diaspora capital, and how has the market responded?

    1. Concessional swap facility: The RBI is offering banks a swap facility for FCNR(B) deposits with maturities of three to five years, cutting the cost of hedging foreign currency exposure by around 3% against prevailing FX swap rates of 2.8%-3.3% for that tenor.
    2. Deposit window: The scheme covers fresh FCNR(B) deposits mobilised until September 30, 2026, and targets $50-70 billion in inflows.
    3. Higher returns for depositors: Most large banks are offering around 6%, and some smaller or private banks up to 7.1%, under the swap window, compared with 4%-4.4% on U.S. Treasuries.
    4. Response so far: Total foreign currency mobilisation under the scheme has reached $20.72 billion, of which $17.4 billion (84%) has come through FCNR(B) deposits alone.
    5. Currencies covered: Deposits are maintained in the U.S. Dollar, Pound Sterling, Euro, Japanese Yen, Australian Dollar, and Canadian Dollar, with both principal and interest denominated in foreign currency.

    Why has this window become necessary now?

    1. Rupee under pressure: The rupee has depreciated 12% year-on-year against the U.S. dollar as of July 22, reflecting elevated geopolitical risk, a stronger dollar, higher import dependence and recently negative Foreign Direct Investment (FDI).
    2. FCNR(B) inflows had collapsed: Net FCNR(B) inflows fell to $946 million in FY26 from $7.1 billion in FY25, a decline of nearly 86%, before the swap window revived them.
    3. FPI outflows outpacing prior years: Foreign Portfolio Investors (FPIs) withdrew ₹2.87 lakh crore from Indian equities between January and the first week of June 2026, already exceeding the entire ₹1.66 lakh crore withdrawn in 2025.
    4. Unwinding forward positions: Reuters reported on July 22 that the RBI has likely used part of the initial inflows to unwind a portion of its forex forward book. (A forex forward book is the total record of all outstanding forward foreign exchange contracts held by an institution, such as the Reserve Bank of India on Reuters or a commercial bank, representing future agreements to buy or sell currencies at preset rates. It shows whether the entity holds more commitments to buy (long) or sell (short) a specific foreign currency like the U.S. dollar)

    Does this mark a return to crisis-driven fundraising, or a shift to strength-based buffer-building?

    1. Earlier crisis episodes: Resurgent India Bonds (1998) followed the Pokhran-II sanctions, India Millennium Deposits (2000) followed the post-Pokhran sanctions and the dotcom bust, and the first FCNR(B) drive (2013) raised about $34 billion from the diaspora during the “taper tantrum.”
    2. Current fundamentals differ: India’s forex reserves exceed $650 billion, there is no Balance of Payments (BoP) crisis, and the country retains investment-grade macroeconomic fundamentals.
    3. Stated aim now is buffer-building: The RBI’s objective is to build additional buffers against geopolitical uncertainty and volatile capital flows, not resolve an emergency.
    4. Liability trade-off remains: FCNR(B) deposits still add to India’s external liabilities even though they carry no exchange-rate risk for depositors.

    What precondition could undermine the scheme’s sustainability?

    1. Dependence on West Asia: West Asia accounts for nearly 50% of India’s inward remittances, which totalled about $129 billion in 2024, the world’s largest, according to the World Bank.
    2. Remittance growth moderating: Growth from Gulf countries has moderated as governments pursue labour nationalisation policies, oil-price volatility affects fiscal spending, and hiring of expatriate workers slows in some sectors.
    3. Competing Gulf deposit rates: Banks in Gulf countries are offering competitive dollar deposit rates amid war risk and digital-rival competition, making it harder for Indian lenders to compete.
    4. Crowding-out concerns: The RBI and the UAE Central Bank have reportedly held talks on concerns that Indian banks’ dollar deposit drive is crowding out UAE banks.
    5. Access gap for smaller banks: Small and mid-sized private banks without overseas branches or a GIFT City presence are exploring tie-ups with larger Indian banks that have a GIFT City presence.

    Conclusion

    The FCNR(B) revival shows India can mobilise diaspora capital from a position of macroeconomic strength, with forex reserves above $650 billion and no Balance of Payments (BoP) crisis, unlike the crisis-driven 1998 and 2013 fundraising drives. Its success is conditional on a precondition now under strain: continued remittance growth from a West Asia destabilised by war, oil-price volatility and labour nationalisation, even as the deposits themselves add to India’s external liabilities.

    PYQ Relevance

    [UPSC 2016] Justify the need for FDI for the development of the Indian economy. Why is there a gap between MOUs signed and actual FDIs? Suggest remedial steps to increase actual FDI in India.

    Linkage: The PYQ examines India’s external capital mobilisation strategy and the role of foreign capital in sustaining macroeconomic stability and economic growth. The FCNR(B) article extends this theme from equity capital (FDI/FPI) to diaspora debt capital. It analyses how the RBI uses FCNR(B) deposits to cushion FPI outflows, stabilise the rupee, augment forex reserves and strengthen external-sector resilience, while highlighting the trade-off of rising external liabilities.
  • Core upgrade: On the Index of Core Industries

    Why in the News?

    The Index of Core Industries (ICI) has been rebased and restructured, joining the Consumer Price Index (CPI), Wholesale Price Index (WPI), Index of Industrial Production (IIP) and national accounts in India’s overdue statistical modernisation cycle. The revised series adds a ninth sector, sharply changes sector weights, and reports a five-month-high growth rate for June 2026. The update, however, exposes a real production shortfall that better statistics cannot fix, and leaves an institutional anomaly in the compilation of core economic indices unresolved.

    What is the Index of Core Industries (ICI)?

    1. Definition: The Index of Core Industries (ICI) is a monthly production volume index released by the Office of Economic Adviser on the DPIIT Portal that measures the output of key foundational infrastructure sectors in India
    2. Predictor of industrial performance: It acts as an early predictor of overall industrial performance well ahead of the broader Index of Industrial Production (IIP) release.
    3. Revised base year: The base year has shifted from 2011-12 to 2022-23 to reflect current economic realities.

    What does the revised Index of Core Industries change, and why now?

    1. New base year and coverage: The ICI has been rebased (2022-23) and now covers nine sectors instead of eight, with iron ore added as the ninth sector.
    2. Correction of double-counting: The measurement of the steel and coal sectors has been revised to remove double-counting present in the earlier series. Only Raw Coal has been retained in the new series of ICI, by excluding Coal Middling and Washed Coal in order to remove double counting, since Coal Middling and Washed Coal are made from Raw Coal.
    3. Reweighting toward electricity: The electricity sector’s weight has risen to more than 30% of the index from less than 20% in the previous series.
    4. Reweighting away from fossil fuels: The coal and natural gas sectors have had their weights nearly halved, to about 5.6% and 3.8% respectively.
    5. Delayed catch-up/Alignment with other Index: The revision aligns the ICI with recent updates to the CPI, WPI, IIP, and National Accounts. Following the earlier practice, the weights of the ICI (2022-23) series have been derived from the weights of the corresponding items of IIP (2022-23) series, which have been pro-rata distributed to 100.

    Does the headline growth number reflect genuine industrial strength or a statistical mirage?

    1. Five-month-high growth: The new series recorded ICI growth of 5% in June 2026.
    2. Base-effect distortion: Iron ore output grew 43.9% and electricity output grew 9.8% in June 2026, but both figures reflect a statistical base effect, since both sectors had contracted in June 2025.
    3. Uncertain durability: It remains unclear whether current growth rates will hold once the base effect wears off in coming months.
    4. Persistent contraction underneath: The crude oil sector has contracted continuously for 18 months and the natural gas sector for 24 months, a real supply-side weakness the new series does not resolve.
    5. The deeper shortcoming: This is a serious shortcoming if India possesses these resources but cannot extract them economically, rather than a case of resource absence.

    Should ICI and WPI be compiled by MoSPI?

    1. The Ministry of Statistics and Programme Implementation (MoSPI) already compiles the Consumer Price Index (CPI) and the Index of Industrial Production (IIP).
    2. However, the Index of Core Industries (ICI) and the Wholesale Price Index (WPI) continue to be compiled by the Ministry of Commerce and Industry.
    3. Methodological Harmonization: ICI weights are derived directly from the IIP basket managed by MoSPI. Unifying them under one roof prevents administrative friction during base-year overhauls and weight redistributions.
    4. Streamlined Deflators: WPI and output-based producer price metrics are heavily relied upon to deflate nominal macroeconomic numbers like Gross Domestic Product (GDP) and IIP. Moving price and production tracking to the nodal statistical ministry improves synchronization.
    5. Institutional Credibility: Centralizing macro data collection reduces inter-ministerial silos, creating a single unified command for official national statistics.
    6. Domain Expertise: The Ministry of Commerce and Industry works closely with industrial stakeholders, trade bodies, and sector-specific experts (like DPIIT), which helps in real-time ground tracking of wholesale prices and core output.

    Conclusion

    The revised Index of Core Industries brings India’s oldest industrial data series current, with a new base year, a ninth sector and reweighted components. But June 2026’s five-month-high growth figure is partly a statistical base effect masking continuous contraction in crude oil and natural gas output. What remains unresolved is not measurement but extraction capability, along with an institutional anomaly by which the WPI and the ICI still sit outside MoSPI, unlike the CPI and the IIP.

  • FDI Allowed in Inventory-Based E-commerce Model for Exports

    Why in News?

    The Department for Promotion of Industry and Internal Trade (DPIIT) has allowed Foreign Direct Investment (FDI) in the inventory-based model of e-commerce for the export of goods manufactured in India, marking the first major relaxation in India’s e-commerce FDI policy.

    What is the New Policy?

    • 100% FDI is now permitted in the inventory-based e-commerce model, only for exports of goods manufactured in India.
    • The relaxation is under the Foreign Trade Policy (FTP), 2023 and related regulations.
    • It does not apply to domestic e-commerce sales.

    Marketplace vs Inventory Model

    • Marketplace Model: The e-commerce platform acts as an intermediary connecting buyers and sellers without owning inventory. 100% FDI under the automatic route is already permitted.
    • Inventory Model: The e-commerce entity owns the inventory and sells directly to consumers. FDI was previously prohibited but is now allowed only for export operations.

    Why is this Significant?

    • Aims to boost India’s e-commerce exports, currently around US$5 billion, compared to China’s US$300 billion.
    • Encourages exports by Micro, Small and Medium Enterprises (MSMEs), artisans, and startups.
    • Supports exports of handicrafts, garments, books, gems and jewellery, and other Made in India products.

    Concerns

    • Monitoring separate inventories for domestic and export sales may be difficult.
    • Experts believe this could become a stepping stone towards permitting FDI in inventory-based domestic e-commerce.

    About DPIIT

    • Full Form: Department for Promotion of Industry and Internal Trade.
    • Ministry: Ministry of Commerce and Industry.
    • Functions:
      • Formulates and administers India’s FDI Policy.
      • Promotes industrial development and ease of doing business.
      • Oversees startup and industrial promotion initiatives.

    [2022] With reference to foreign-owned e-commerce firms operating in India, which of the following statements is/are correct?
    1. They can sell their own goods in addition to offering their platforms as market-places.
    2. The degree to which they can own big sellers on their platforms is limited.
    Select the correct answer using the code given below:

    [A] 1 only

    [B] 2 only

    [C] Both 1 and 2

    [D] Neither 1 nor 2

  • RBI Plans Trial of Polymer (Plastic) Currency Notes

    Why in News?

    The Reserve Bank of India (RBI) is set to begin field trials of polymer (plastic) currency notes, nearly 15 years after an earlier pilot was proposed but not implemented. An RBI subsidiary has invited bids to procure polymer sheets for printing trial notes.

    Why Polymer Notes?

    • More durable: Last 2 to 6 times longer than cotton-based paper notes.
    • Lower long-term costs: Fewer notes need to be printed, transported, and destroyed.
    • Environment-friendly: Worn-out polymer notes can be recycled into plastic products.
    • Better security: More resistant to counterfeiting due to advanced security features.

    India’s Earlier Attempt

    • In 2009, RBI proposed a pilot of ₹10 polymer notes.
    • Field trials were planned in Kochi, Mysuru, Shimla, Jaipur, and Bhubaneswar.
    • The project was shelved after technical issues were identified during evaluation.

    Global Adoption

    • First introduced by Australia (1988).
    • Used in 50+ countries, including the UK, Canada, New Zealand, Singapore, Malaysia, Thailand, and Vietnam.

    Challenges

    • India may initially need to import polymer sheets, creating import dependence.
    • Transition requires fresh investment despite existing domestic facilities for banknote paper and security ink.
    • RBI is therefore expected to adopt a gradual transition.

    Prelims Value Added

    • Indian currency notes are currently made from 100% cotton-based paper.
    • Bharatiya Reserve Bank Note Mudran Pvt. Ltd. (BRBNMPL) is a wholly owned subsidiary of the Reserve Bank of India that prints banknotes.
    • Bank Note Paper Mill India Pvt. Ltd. (BNPMIPL) manufactures banknote paper domestically.
    • Security Printing and Minting Corporation of India Ltd. (SPMCIL) prints banknotes, mints coins, and produces security documents.

    [2025] Which of the following are the sources of income for the Reserve Bank of India?
    I. Buying and selling Government bonds
    II. Buying and selling foreign currency
    III. Pension fund management
    IV. Lending to private companies
    V. Printing and distributing currency notes
    Select the correct answer using the code given below.

    [A] I and II only

    [B] II, III and IV

    [C] I, III, IV and V

    [D] I, II and V

  • With a Page Out of China’s Book, TN Maintains Lead in Share of Women Workers

    Why in the News:

    New data from the Ministry of Statistics and Programme Implementation (MoSPI) on India’s 46 most populous cities places Coimbatore and Madurai at the top of the female labour force participation rate (FLFPR) rankings, with Tamil Nadu holding nearly half the country’s women employed in electronics manufacturing. States with comparable industrial investment, such as Karnataka and Maharashtra, show far lower and declining shares, sharpening the question of what specifically converts factory investment into women’s employment.

    What does the MoSPI data show about Tamil Nadu’s lead in female employment?

    1. City rankings: Coimbatore records an FLFPR of 41.3% and Madurai 37%, both above the urban India average of 27.7%; Surat ranks between them at 40.6%.
      • Term: Labour Force Participation Rate (LFPR): The percentage of people either employed or actively looking for work.
    2. Electronics manufacturing share: Tamil Nadu’s share of women employed in computer, electronics and optical products manufacturing rose from 20% to 43% between 2013 to 2014 and 2023 to 2024, as per the Annual Survey of Industries.
    3. Divergent state trends: Gujarat’s women’s share in electronics manufacturing remained at 10% over the same decade; Maharashtra’s fell from 24% to 6%, and Karnataka’s from 11% to 8%.
    4. Overall factory employment: Tamil Nadu accounted for 14,814 of the 34,531 women directly employed nationally in electronics manufacturing in 2023 to 2024, and holds the largest state share of all women employed in factories at 40% in 2023 to 2024, down slightly from 43% in 2021 to 2022.

    Why has housing infrastructure become the deciding factor, not industrial investment alone?

    1. Housing as the binding constraint: Housing is cited as the single issue causing 80% of women to decline job offers, according to the Udaiti Foundation.
    2. Two hostel models: The Tamil Nadu Working Women’s Hostels Corporation runs large SIPCOT linked industrial dormitories alongside smaller Thozhi hostels of 100 to 150 beds. The 19 existing Thozhi hostels operate at 87% occupancy and are expected to expand to 46 within two years.
    3. Housing as economic infrastructure: The state treats women’s hostels as economic infrastructure rather than welfare spending, reducing employers’ need for separate mobility infrastructure and improving retention of migrant labour.
    4. Concentration in two states: Almost half of India’s working women’s hostels are located in Tamil Nadu and Kerala, according to a December 2024 ICRIER paper.

    Is the model being replicated elsewhere, and does hostel capacity alone explain the outcome?

    1. Kerala’s shortfall: Despite similar hostel infrastructure, Kerala’s share of women in electronics manufacturing declined from 8% to 6% between 2013 to 2014 and 2023 to 2024, showing that housing alone does not create an electronics manufacturing base.
    2. Karnataka’s reactive catch up: Foxconn’s Devanahalli plant hired around 30,000 workers, nearly 80% women, and began expanding dormitory facilities only after recruitment.
    3. China comparison unsubstantiated: The comparison with China’s women led electronics manufacturing model is presented as a framing device and is not supported by comparative evidence in the report.

    Does a rising employment share also mean better quality jobs?

    1. Wage gap: The average monthly wage for salaried women in Chennai was Rs 22,919 in 2025, below the average for million plus cities of Rs 23,707. Wages were lower in Coimbatore (Rs 19,149) and Madurai (Rs 18,247).
    2. Sectoral wage gap: The average annual wage per worker in Tamil Nadu’s electronics manufacturing was Rs 2.45 lakh in 2023 to 2024, slightly below the all India average of Rs 2.5 lakh and well below Telangana’s Rs 4.46 lakh.
    3. Fast growth from a low base: Tamil Nadu’s wages increased by 83% between 2013 to 2014 and 2023 to 2024, more than double the all India average growth of 36%, though behind Delhi, Puducherry, Madhya Pradesh, Goa, and Uttarakhand.
    4. Restrictive hostel norms: Hostels are reported to have restrictive rules, and factories have historically been reluctant to hire married women.
    5. Data undercount: The MoSPI dataset covers only cities with populations above 10 lakh as per Census 2011, excluding newer industrial hubs such as Hosur, Erode, and Oragadam.

    Conclusion:

    Tamil Nadu’s leadership is driven by a deliberate policy of treating women’s housing as economic infrastructure rather than welfare, enabling higher female participation in manufacturing. However, employment gains remain concentrated in relatively low wage, hostel based jobs with continuing social restrictions, while official statistics understate the model’s reach by excluding newer industrial centres. Whether this approach can expand beyond electronics manufacturing and improve job quality and wages remains an open question.

  • Why Inflation Is Rising in India

    Why in the News?

    India’s Wholesale Price Index (WPI) inflation climbed to 9.87% by June 2026, after staying negative or near zero for over a year. This reverses more than a decade of relatively low inflation. It appears, on the surface, to confirm the common belief that rising prices signal demand outpacing supply.

    Why has India’s WPI inflation surged sharply, and why does simple demand overheating not explain it?

    1. Wholesale Price Index (WPI): an index tracking price changes of goods at the wholesale stage, split into three sub-categories, primary articles, fuel and power, and manufactured products.
    2. Sharp reversal: WPI inflation stayed negative or close to zero until December 2025, then climbed sharply from March 2026 onward, reaching 9.87% by June 2026.
    3. Popular assumption: Conventional economic intuition treats rising prices as a sign of demand outpacing supply (overheating), and falling prices as the reverse.
    4. Composition of the jump: Fuel and power, and manufactured products, not primary articles, accounted for the dominant share of the WPI rise in the months leading up to June 2026.

    Why do primary commodity prices and manufactured goods prices respond differently to demand and supply?

    1. Kaleckian distinction: Economist Michal Kalecki argued that primary commodity prices are demand-determined, while industrial and manufactured prices are cost-determined.
    2. Primary commodities: Supply is largely fixed in the short run, shown as a vertical supply curve. A supply shock, such as a bad monsoon, shifts this curve and directly raises prices. This is demand-pull inflation.
    3. Manufactured goods: Firms typically operate below full capacity, so the supply curve is flat. A rise in demand is met by higher production, not higher prices.
    4. Markup pricing: Manufactured goods prices are set as a cost markup over production cost. Prices rise only when input costs rise, making this cost-push inflation rather than demand-pull inflation.

    What specifically pushed up food and manufactured goods prices in India’s current surge?

    1. Fuel and power drove manufactured inflation: Fuel and power prices moved almost one-to-one with manufactured goods inflation, confirming a cost-push channel.
    2. Wages ruled out as a driver: Indian workers largely lack bargaining power over wages, so wage costs are not treated as the factor pushing up manufactured prices.
    3. Monsoon failure drove food inflation: An inadequate monsoon, linked to the El Niño effect, hurt agricultural production and pushed up food prices through 2026.
    4. Historical pattern confirmed: Data spanning 1953-54 to 2025-26 show drought years consistently coinciding with sharp spikes in food article inflation, supporting the Kaleckian structuralist explanation.
    5. Not an absolute rule: Food inflation has also occurred in some non-drought years, suggesting demand-side pressure can independently raise food prices. A drought is a sufficient but not a necessary condition for food prices to soar.

    Is India’s current inflation surge purely an external shock, or has government policy made it worse?

    1. A tool that worked: The government previously held domestic pump prices steady despite rising global crude oil prices by cutting customs and excise duties on fuel.
    2. Tool withdrawn: This countercyclical duty-cut measure has since been withdrawn.
    3. Self-inflicted component: The withdrawal is identified as one of the primary reasons for the sharp rise in WPI inflation, turning part of what looks like an external oil-price shock into a domestic policy choice.
    4. Framework critique: The existing inflation-targeting framework is described as ill-suited to managing fuel-driven, cost-push inflation, since it is built to respond to demand-side pressure rather than cost-side pressure.

    What structural policy changes are proposed to control inflation going forward?

    1. Decouple food supply from the monsoon: Heavy investment in irrigation infrastructure is proposed to reduce agriculture’s dependence on rainfall, since continued dependence on the monsoon is called unscientific and anachronistic in the present technological era.
    2. Countercyclical indirect tax policy for fuel: Customs and excise duties on fuel should be systematically lowered when global crude prices rise and restored when prices fall, rather than applied inconsistently.
    3. Move beyond inflation targeting for cost-push inflation: A rule-based countercyclical duty policy is presented as a more effective response to oil-driven, cost-push inflation than the existing inflation-targeting framework, which is tuned to demand-side price pressure.

    Conclusion

    India’s WPI inflation surge is a cost-push and supply-shock phenomenon, not demand overheating. Food prices rose due to an inadequate monsoon, and manufactured goods inflation tracked global fuel costs almost one-to-one. The government’s withdrawal of a countercyclical duty-cut measure on fuel is identified as one of the primary reasons for the sharp WPI rise. This makes part of the current inflation surge a self-inflicted policy outcome rather than a purely external shock. Going forward, food security needs to be decoupled from monsoon dependence through irrigation investment. Also, fuel-price shocks need to be cushioned through a rule-based countercyclical indirect tax policy rather than the existing inflation-targeting approach.

    PYQ Relevance

    [UPSC 2024] What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.

    Linkage: The PYQ asks for the causes of persistent food inflation in India and evaluates whether RBI monetary policy is effective in controlling it. The article gives a structural, non-monetary explanation for food inflation (monsoon-driven supply shocks) and manufactured inflation (fuel cost pass-through). It argues that both are cost-push phenomena rather than demand/monetary phenomena. 

  • [20th July 2026] The Hindu OpED: The Stark Reality of the Missing Jobs for India’s Gen Z

    PYQ Relevance[UPSC 2014] While we flaunt India’s demographic dividend, we ignore the dropping rates of employability. What are we missing while doing so? Where will the jobs that India desperately needs come from? Explain.
    Linkage: The PYQ asks whether India is ignoring falling employability while flaunting its demographic dividend, and where future jobs will come from. It matches the article’s central tension between the demographic dividend narrative and the graduate unemployment reality.

    Mentor’s Comment

    Periodic Labour Force Survey (PLFS) 2023-24 data shows that unemployment among India’s Gen Z rises, not falls, with higher education. Also, most employed Gen Z workers hold no job contract or social security cover. This has exposed a widening gap between India’s celebrated demographic dividend and the actual quality of work available to its youngest working-age cohort.

    How Wide Is India’s Youth Employment Gap?

    1. Low participation: Labour Force Participation Rate (LFPR) for Gen Z stands at 41.7%, against 75% for Millennials, reflecting continued engagement in education as well as exit from the workforce.
    2. Rural-urban reversal: Rural Gen Z participation (44.1%) exceeds urban participation (37.2%), indicating urban youth delay labour market entry for education and training while rural youth enter earlier out of necessity.
    3. Unemployment gap across cohorts: Overall Gen Z unemployment is 11.9%, compared to just 2% among Millennials, showing the crisis is concentrated in the youngest cohort.
    4. Urban unemployment is sharper: Urban Gen Z unemployment rises to 17.1%, well above the national Gen Z average.
    5. Gender compounds urban unemployment: Urban young women face 22.6% unemployment, the highest among all sub-groups measured.

    How Does Gender Deepen the Employment Crisis for Gen Z?

    1. Domestic duties as exclusion: 27.1% of Gen Z women are engaged only in domestic duties, against just 0.32% of Gen Z men, pulling them out of the labour force altogether.
    2. Low regular wage employment for women: Only 4.7% of Gen Z women hold regular wage jobs, compared to 14.8% of Gen Z men.
    3. Male LFPR advantage: Male labour force participation stands at 59.3% in rural India and 51.3% in urban India, against just 28% and 21.1% respectively for young women.
    4. Structural, not just economic, barriers: Childcare burdens, safety concerns, mobility constraints, and social norms keep women out of paid work, independent of job availability.
    5. Demographic dividend undermined: A large share of young women outside the paid economy weakens the case that India is fully harnessing its demographic dividend.

    Why Does More Education Correlate with Higher Unemployment? 

    1. Graduate unemployment exceeds average: Among Gen Z men with graduate-level education or above, unemployment stands at 29%, and among Gen Z women at 36.9%, both far above the respective cohort averages.
    2. Inverted assumption: Education is expected to lower unemployment; instead, unemployment rises at the highest education levels, contradicting the standard human capital logic.
    3. Persists across cohorts: Millennial graduate unemployment is 5.2% for men and 13.8% for women, confirming the pattern is not unique to Gen Z alone but is sharper for Gen Z.
    4. Root cause is mismatch: The gap reflects a mismatch between what the education system produces and what the labour market demands, not merely a shortage of degree-holders.
    5. Technology reshapes demand: Automation and growing adoption of artificial intelligence are altering the nature of available jobs, widening the skill mismatch further.
    6. Risk of delay compounding: When higher education does not convert quickly into employment, frustration rises, family investment in education comes under strain, and confidence in the growth story weakens.

    Why Is Social Security Coverage a “Mirage” Even for Employed Gen Z?

    1. Low social security coverage: Only 20.1% of Gen Z individuals are covered by social security, leaving the vast majority without protection even when employed.
    2. Job contracts are rare: Just 14.1% of Gen Z workers have a formal job contract; among the 79.9% lacking social security, only 3.2% have a job contract.
    3. Contractual employment is the exception: Only 17.3% of Gen Z workers hold any form of contractual employment, meaning most enter the workforce without either a contract or social protection.
    4. Informalisation within formal employment: Recent years show growing evidence of informalisation of formal employment among Gen Z, meaning even formal-sector jobs are losing security features.
    5. Millennials are only marginally better: Only 26% of Millennials have a job contract and 28.6% are covered by social security, showing the informality problem extends across cohorts, not just Gen Z.
    6. Social cost visible: Large-scale labour protests by industrial and factory workers in Noida, Uttar Pradesh, demanding higher wages and better working conditions, reflect the frustration insecure and poorly protected employment can produce.

    Why Must India Treat Unemployment, Skilling, Women’s Work, and Informality as One Problem?

    1. Debate wrongly siloed: India’s jobs debate is usually discussed separately as unemployment, skilling, women’s work, and labour force participation, obscuring their common origin.
    2. Single connected failure: All four are facets of one connected failure of labour market transition, where education is prolonged but the bridge from education to work remains weak.
    3. Skilling alone is insufficient: Skill programmes have value but cannot substitute for actual job creation, since the binding constraint is demand for labour, not only its quality.
    4. Structural, not motivational, barrier for women: Women face structural barriers that keep them out of work or push them into unpaid roles, and even when employed, work is too often outside formal protection.
    5. Precondition for resolution: Expanding labour-intensive sectors, strengthening school-to-work pathways, aligning training with employer needs, and enabling women’s paid work through apprenticeships, hiring incentives, safe transport, and childcare support are named as the necessary conditions for change.

    Conclusion

    India’s demographic dividend is faltering not from a shortage of young workers but from a labour market unable to convert education into secure, well-paid work; unemployment rises rather than falls with higher education, and even the employed largely lack contracts or social security. Until labour-intensive job creation, skilling-employer linkages, and women’s structural access to work are addressed together rather than in silos, the demographic dividend will remain, in the article’s own words, a promise deferred.

  • Future-Ready Workforce for India’s Creative Economy

    Why in News?

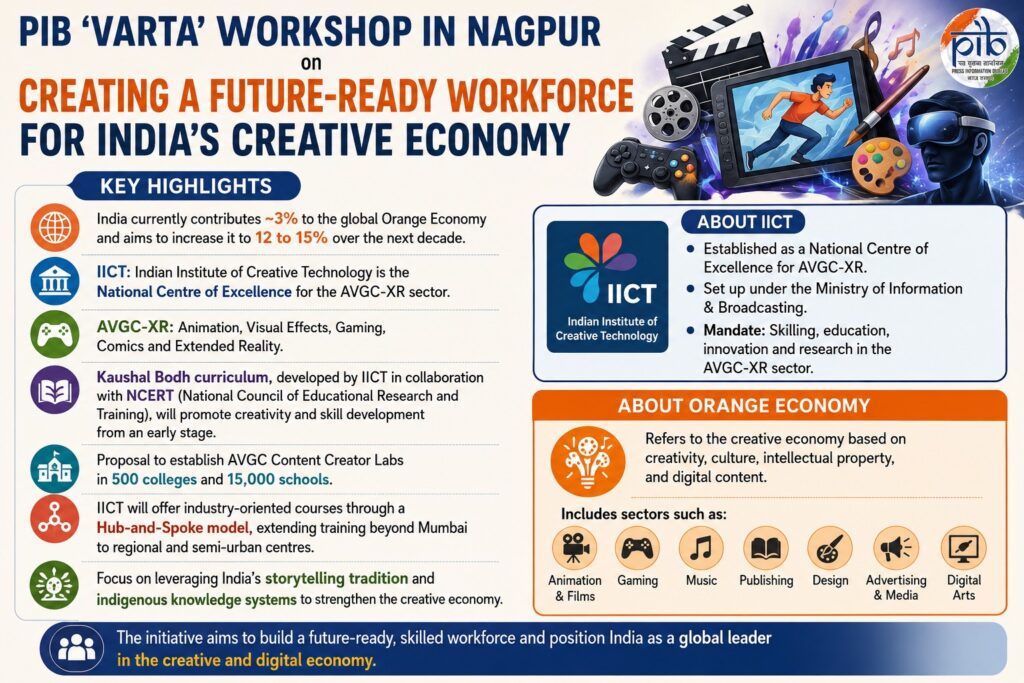
    The Press Information Bureau (PIB) organised a ‘Varta’ workshop on “Creating a Future-Ready Workforce for India’s Creative Economy” in Nagpur.

    Key Highlights

    • India currently contributes ~3% to the global Orange Economy and aims to increase it to 12 to 15% over the next decade.
    • IICT: Indian Institute of Creative Technology is the National Centre of Excellence for the AVGC-XR sector.
    • AVGC-XR: Animation, Visual Effects, Gaming, Comics and Extended Reality.
    • Kaushal Bodh curriculum, developed by IICT in collaboration with NCERT (National Council of Educational Research and Training), will promote creativity and skill development from an early stage.
    • Proposal to establish AVGC Content Creator Labs in 500 colleges and 15,000 schools.
    • IICT will offer industry-oriented courses through a Hub-and-Spoke model, extending training beyond Mumbai to regional and semi-urban centres.
    • Focus on leveraging India’s storytelling tradition and indigenous knowledge systems to strengthen the creative economy.

    About Orange Economy

    • Refers to the creative economy based on creativity, culture, intellectual property, and digital content.
    • Includes sectors such as animation, films, gaming, music, publishing, design, advertising, media, and digital arts.

    [2019] In the context of digital technologies for entertainment, consider the following statements:
    1. In Augmented Reality (AR), a simulated environment is created and the physical world is completely shut out.
    2. In Virtual Reality (VR), images generated from a computer are projected onto real-life objects or surroundings.
    3. AR allows individuals to be present in the world and improves the experience using the camera of smart-phones or PC.
    4. VR closes the world, and transposes an individual, providing complete immersion experience.
    Which of the statements given above is/are correct?

    [A] 1 and 2 only

    [B] 3 and 4

    [C] 1, 2 and 3

    [D] 4 only