Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS3-01.Indian Economy and issues relating to planning, mobilization of resources, growth, development and employment.

  • Economy is resilient, the road ahead will be less forgiving

    Why in the News

    India’s Gross Domestic Product (GDP) grew 7.8 per cent in the first quarter of 2026-27, beating expectations for yet another quarter. The print exceeded the 6.8 per cent median forecast of professional forecasters and the Reserve Bank of India’s (RBI) revised projection of 7 per cent. The outperformance came from domestic drivers holding up in a global environment marked by conflict in West Asia and weather uncertainty. The tension is that the conditions that produced this print are turning. Crisil expects the growth-inflation mix to worsen through 2026-27, with growth moderating to 7 per cent and inflation rising to 5.1 per cent, and the balance of risks has shifted from rate cuts towards possible rate hikes.

    What is the growth-inflation mix?

    1. About: The growth-inflation mix is the combination of real output growth and the inflation rate an economy records in the same period. A favourable mix pairs high growth with inflation inside the RBI’s target band of 4 per cent, with a tolerance of 2 percentage points either side.
    2. Why it matters for policy: The RBI sets the policy rate against this mix. Rising inflation alongside slowing growth forces a choice between tightening to contain prices and holding rates to protect activity.

    What drove the first quarter outperformance?

    1. Broad based domestic momentum: Robust industrial activity, healthy consumption and strong goods exports combined with accelerating government investment to drive growth. High-frequency indicators had signalled this momentum in advance.
    2. Residual policy support and transfers: Policy measures introduced last fiscal continued to feed through, and direct benefit transfers expanded steadily. 17 States now provide cash transfers, primarily to women.
    3. Goods and Services Tax (GST) rate cuts, visible in automobiles: Dealer discounts and higher disposable incomes from income-tax relief added to the effect of GST rate cuts. Eg. The Society of Indian Automobile Manufacturers (SIAM) reported first quarter sales growth of 26 per cent for passenger vehicles, 20.3 per cent for commercial vehicles and 18.3 per cent for two-wheelers.
    4. Retail credit funding consumption: Other personal loans, a proxy for short-term consumption, grew 14.2 per cent.
    5. Households shielded from crude: The government and oil companies absorbed most of the sharp rise in crude prices, particularly in the initial phase of the West Asia conflict, so household budgets did not take the hit.

    Why will the growth-inflation mix turn less favourable in 2026-27?

    1. Four sources of moderation: Growth will slow on disruptions from the West Asia conflict, unresolved tariff issues with the United States, weather-related risks and a strong base effect in the second half of the year.
    2. Last year’s two tailwinds are gone: Low crude oil prices and a normal monsoon were the two exogenous factors that worked in India’s favour last year. Neither is expected to provide similar support this year.
    3. The conflict’s cost channel: The West Asia conflict has disrupted supply chains and raised insurance, freight and input costs. This weighs on global and domestic growth at the same time.

    Does a deficient monsoon still translate into food inflation?

    1. The El Nino signal: El Nino conditions (a periodic warming of the equatorial Pacific that weakens the Indian monsoon) are intensifying. Over the past 25 years, five of the six El Nino years produced below-normal rainfall.
    2. The deficit so far: Cumulative rainfall stood 14 per cent below the long-period average (LPA) at the end of August. July was 1 per cent above the LPA, and August recorded a deficit of 16 per cent. The India Meteorological Department (IMD) has signalled below-normal rainfall in September.
    3. Irrigation has widened the cushion: India’s net irrigated area has risen by 10 percentage points to 59 per cent over the past decade, improving resilience to rainfall shocks.
    4. Stocks exceed buffer norms: The country holds ample rice and wheat stocks. Foodgrain stocks currently stand at more than twice the buffer norms. That cushion contains price spikes.
    5. Non-crop agriculture now carries the sector: Crop gross value added contracted by an average 0.5 per cent annually in the five years to 2023-24. Non-crop agriculture, now nearly 40 per cent of agricultural gross value added, expanded 6.5 per cent annually over the same period.
    6. The historical record is not linear: Deficient monsoons have not always led to higher food inflation.
    7. The vulnerability that remains: Crops without buffer stocks and perishable vegetables stay exposed to adverse weather. A weak monsoon also hurts rabi production by reducing soil moisture and lowering reservoir levels, so agricultural output and food inflation remain the key variables to watch.

    Why does benign core inflation understate the price risk?

    1. Headline eased, risks did not: Headline inflation eased in July and core inflation remained benign. Upside risks persist on three fronts, crude, input costs and demand.
    2. The crude assumption: Crisil’s base case assumes Brent crude averaging $82 to 87 per barrel this fiscal, with the unresolved West Asia conflict keeping prices volatile. Higher crude translates into slower growth, higher inflation and a wider current account deficit.
    3. Wholesale pressure is being passed on: Core inflation, a gauge of underlying demand pressure, appears deceptively low. Strong demand, rising fuel costs and other input pressures show up in near-double-digit wholesale price inflation, and are gradually being passed through to consumers.
    4. Automobiles show the pass-through: Vehicle prices are set to rise as manufacturers protect margins and dealer discounts are withdrawn. Combined with a high base effect, this moderates automobile growth in the second half.
    5. The rate cycle may reverse: Unlike last year, the balance of risks points towards possible interest rate hikes. Persistent inflationary pressure, the unresolved conflict and weather risk together bring monetary tightening back into consideration.

    What still supports activity through the moderation?

    1. External buffers: Foreign exchange reserves cover more than nine months of imports.
    2. Balance sheet strength: Corporate and banking-sector balance sheets are in robust health.
    3. Fiscal and wage support: Tax relief and public investment continue to support activity. The Pay Commission’s recommendations will add a further boost to consumption when implemented.
    4. The structural condition: Beyond cyclical tailwinds, sustained progress on structural reforms that enhance competitiveness is the condition for maintaining growth momentum.

    Challenges to sustaining the growth momentum

    1. Export exposure to United States tariff policy: Unresolved tariff issues leave goods exporters unable to price contracts beyond a quarter. Eg. In August 2025 the United States raised tariffs on Indian goods to 50 per cent, half of it as a penalty tied to Russian oil purchases.
      The Fix: Conclude the bilateral trade agreement under negotiation and operationalise the Comprehensive Economic and Trade Agreement with the United Kingdom signed in 2025, so exposure to one market falls.
    2. Crude dependence transmits every West Asian shock: India imports over 85 per cent of its crude, so a supply disruption raises the import bill, the fiscal cost of absorbing it and consumer prices together. Eg. About 40 per cent of India’s crude imports normally transit the Strait of Hormuz, and a large part of that supply has been offline since the disruptions of March 2026.
      The Fix: Widen the import slate to African, North American and South American barrels under term contracts and expand strategic petroleum reserve capacity beyond the present three sites.
    3. Consumption leaning on one-off boosts: Income-tax relief, GST rate cuts and a Pay Commission award lift spending once, and the base effect then turns against growth. Eg. The HSBC India Manufacturing Purchasing Managers’ Index fell to a five-year low of 52.8 in August 2026, with the survey recording job losses for the first time in over two years.
      The Fix: Tie the next round of support to employment, through the Employment Linked Incentive scheme, so that income growth rather than tax relief carries consumption.
    4. State cash transfers stretch State finances: A cash transfer to women is a recurring commitment that a State cannot withdraw without political cost. Eg. States’ aggregate fiscal deficit rose to 3.2 per cent of GDP in 2024-25, and only 11 States recorded a revenue surplus.
      The Fix: Ring-fence State capital expenditure under the Finance Commission’s fiscal roadmap so transfers do not crowd out investment.
    5. A rate hike would hit credit-led consumption first: Retail borrowing has been funding short-term consumption, and it is the most rate sensitive part of demand. Eg. The RBI raised risk weights on unsecured consumer credit in November 2023 to slow exactly this segment.
      The Fix: Use targeted macroprudential tools on unsecured lending before resorting to a policy rate hike that would also raise the cost of investment.

    Conclusion

    India enters 2026-27 with a strong quarter behind it and a weaker mix ahead. The thing that cannot be settled yet is whether inflation will rise faster than growth slows, because that decides whether the RBI tightens into a moderating economy. The Monetary Policy Committee’s October meeting is the first decision point. The monsoon’s September outcome and the rabi sowing that follows will decide the food inflation half of the equation.

    Key Facts about GDP Measurement

    1. New base year: The GDP base was revised from 2011-12 to 2022-23, with the new series released on 27 February 2026. The Consumer Price Index base moved to 2024 and the Index of Industrial Production base to 2022-23 alongside it.
    2. New data sources: GST data, the Public Financial Management System for central government accounts, e-Vahan for transport spending, and the Annual Survey of Unincorporated Sector Enterprises and the Periodic Labour Force Survey replaced proxy indicators.
    3. Refined deflation: Double deflation (deflating output and inputs separately) now applies in manufacturing and agriculture, and single deflation has been discontinued.
    4. Global alignment: The series aligns with the System of National Accounts 2008 and prepares for the transition to SNA 2025 by 2029-30.

    Challenges in GDP Growth

    1. Weak private investment: Capacity expansion depends on private capital formation, which has stayed subdued. Eg. Gross Fixed Capital Formation is around 30 per cent of GDP.
      The Fix: Scale the Production Linked Incentive scheme’s second phase and adopt Vietnam’s plug-and-play industrial park model to cut the time from approval to production.
    2. Skill mismatch: Skills produced by the education system do not match what industry demands, so rising participation adds less output. Eg. Only about half of graduates are employable.
      The Fix: Expand Industry 4.0 training and emulate Germany’s dual education and apprenticeship system.
    3. Participation gap: A large share of working-age women stays outside the labour force, capping the demographic dividend. Eg. The labour force participation rate is 59.3 per cent (2025), but the female rate is 40.0 per cent.
      The Fix: Deploy working women’s hostels and subsidised childcare on the model of Japan’s Womenomics.
    4. Jobless growth: Output growth is concentrated in sectors that employ few people. Eg. Services contribute about 55 per cent of GDP but employ under 30 per cent of the workforce.
      The Fix: Implement Employment Linked Incentives and study China’s township and village enterprises for rural labour absorption.
    5. Regulatory cost: Contract enforcement, clearance times and regulatory instability keep the cost of doing business above competitors. Eg. Logistics cost is near 8 per cent of GDP.
      The Fix: Emulate Singapore’s TradeNet single-window system to slash clearance times.

    [2021, GS3, 10 marks] Explain the difference between computing methodology of India’s Gross Domestic Product(GDP) before the year 2015 and after the year 2015.”
  • Subhash Chandra case: why are creditors set to recover only ₹6.5 cr. against ₹22,006 cr. claims?

    Why in the News

    The NCLT approved Subhash Chandra’s personal insolvency repayment plan, allowing creditors with ₹22,006.57 crore in admitted claims to recover just ₹6.25 crore, a 99.97% haircut.

    Core issue: The case highlights how personal insolvency under the IBC, 2016 works when a guarantor’s admitted liability is much larger than the assets available in their personal estate. Dissenting creditors, including HDFC Bank, are considering an appeal.

    How does personal guarantor insolvency work under the Insolvency and Bankruptcy Code, 2016?

    1. A personal guarantee is a promise to pay another’s debt: An individual undertakes to repay a borrower’s debt if the borrower defaults.
    2. The firm and the guarantor are separate legal persons: Proceedings against a company and against its personal guarantor are separate proceedings even when they arise from the same borrowing.
    3. The guarantor proposes, the creditors vote: In personal insolvency the first step is for the borrower to propose a repayment plan, which the creditors then vote on.
    4. Approval triggers a statutory discharge: Once the creditors and the NCLT approve the plan, Section 119 of the Code passes a discharge order giving the guarantor a fresh start.

    Why do the corporate and personal proceedings run in parallel?

    1. Section 60 sends the guarantor to the same tribunal: The IBC provides for insolvency of a personal guarantor of a corporate debtor to be dealt with by the NCLT where proceedings against the corporate debtor are pending.
    2. A guarantor’s liability is coextensive and independent: Contract law treats that liability as running alongside the principal borrower’s rather than only after it.
    3. A corporate process seeks a buyer, a personal process seeks a plan: Corporate insolvency resolves a firm’s debt by taking over its management and finding a buyer or revival plan, and failing that leads to liquidation.
    4. The personal order settles nothing for the firms: The founder’s personal insolvency does not extinguish the liabilities of the Essel linked firms that borrowed the money.

    Why does the 99.97 per cent haircut overstate what was lost?

    1. The comparison is against admitted claims, not realisable assets: The haircut measures the gap between claims admitted in the proceedings and the amount proposed for distribution.
    2. The disclosed estate was Rs 31.79 crore: The resolution professional assessed the guarantor’s disclosed personal assets at that figure.
    3. The tribunal applied a better off test: The NCLT considered whether creditors would recover more under the repayment plan than if the guarantor were pushed into bankruptcy.
    4. The guarantor disputes the claim base: His office has stated that he borrowed no money, and that the claim against him by the objectors to the plan is Rs 3,992 crore.

    How did the plan clear the creditors despite objections?

    1. The plan carried 80.814 per cent of voting share: The statutory threshold is more than three-fourths, so the requirement was met.
    2. No individual creditor holds a veto: A plan sanctioned by the tribunal binds every creditor covered by it, including those who voted against it.
    3. Five entities were alleged to be associates: Dissenting creditors argued those entities were connected to the founder and should not have been permitted to vote. The NCLT did not accept the objection.
    4. The Bench itself was divided: The original NCLT Bench differed over the plan, and a third judicial member decided the matter.

    What did the tribunal do with the net worth discrepancy?

    1. Earlier certificates showed a far larger figure: A 2017 net worth certificate furnished to RBL Bank put his net worth at about Rs 45,888 crore, and a 2018 certificate at about Rs 40,562 crore.
    2. Creditors sought a forensic audit: They asked for an examination of the gap between those certificates and the assets disclosed in the present proceedings.
    3. Suspicion was held not to be proof: The NCLT held that the creditors had not shown with evidence that specific assets were transferred, concealed or diverted to defraud them.
    4. A forensic audit is not a precondition: The tribunal held that such an audit is not mandatory before a repayment plan can be approved.

    What grounds remain if the creditors appeal?

    1. The appeal lies to the appellate tribunal: Creditors can challenge the order before the National Company Law Appellate Tribunal (NCLAT).
    2. The challenge must be legal or procedural: Available grounds include ineligible creditors being allowed to vote, the statutory majority being wrongly calculated, or the law being wrongly applied.
    3. A low recovery is not itself a ground: A creditor cannot overturn a plan merely because it considers the amount recovered too small.
    4. The associate votes are the strongest ground: If the appellate tribunal finds those votes were wrongly counted and the required majority was consequently not reached, it can interfere with the approval.
    5. The corporate borrowers stay exposed: Creditors can continue to pursue the principal borrowers through separate legal or insolvency proceedings.

    Is this outcome exceptional or the norm?

    1. 5,186 cases have produced 64 repayment plans: Since the personal guarantor provisions came into force, creditors have filed about that many cases and only 64 ended in a repayment plan.
    2. Recovery across those plans is about 1 per cent: Creditors recovered roughly that share of what they were owed in the cases that did reach a plan.
    3. The case is therefore representative: A near total haircut is the ordinary result of this regime rather than an outlier produced by one guarantor’s circumstances.

    Challenges to the personal guarantor insolvency regime

    1. Admitted claims bear no relation to the estate: A guarantor is admitted for the whole defaulted corporate debt, and the recovery pool is one individual’s property, so the ratio is guaranteed to look catastrophic. Eg. Guarantees securing multi-thousand crore project loans are routinely taken from promoters whose personal balance sheets are a fraction of that size.
      The Fix: Require lenders to record and periodically revalue the guarantor’s net worth against the guaranteed exposure, so the guarantee is priced as security rather than counted at face value.
    2. Voting power can sit with connected parties: The Code sets a voting threshold without a tested standard for excluding creditors related to the guarantor, so a majority can be assembled from within the group. Eg. Related party voting was the reason corporate insolvency law had to bar connected persons from the committee of creditors through Section 29A.
      The Fix: Extend a Section 29A style disqualification expressly to voting in personal guarantor repayment plans, with the burden of disclosure on the guarantor.
    3. Asset disclosure is self reported: The estate rests on what the individual declares to the resolution professional, who has limited power to trace assets held through family members or offshore structures. Eg. Benami holdings and trust structures sit outside the disclosure a resolution professional can compel.
      The Fix: Give the resolution professional statutory access to income tax, benami property and foreign asset reporting records for the guarantor and immediate family.
    4. The process is slow relative to the value at stake: A guarantor’s estate does not appreciate during the proceedings, and delay erodes the small recovery that exists. Eg. Corporate insolvency resolution has routinely overrun the 330 day outer limit the Code prescribes.
      The Fix: Set a hard outer timeline for personal guarantor cases with automatic escalation to the appellate tribunal on breach.
    5. Discharge closes the file without closing the debt: A discharge order releases the guarantor while the borrowing companies remain in default, so lenders keep the exposure and lose the security. Eg. Group structures allow the operating company, the borrower and the guarantor to fail in three separate forums on different timelines.
      The Fix: Require the corporate and personal proceedings arising from the same borrowing to be heard by a single Bench, so the two outcomes are decided against one record.

    Conclusion

    The regime was built to do two things at once. It gives an honest guarantor a fresh start, and it gives a lender a second claim on a defaulted loan. It cannot do both when the claim admitted is the whole debt and the estate is one person’s property. The marker to watch is whether the appellate tribunal treats disqualification of connected voters as a live standard, since that is the only part of this process a dissenting creditor can still reach.

    Back2Basics: Insolvency and Bankruptcy Board of India

    1. Establishment: Set up in 2016 as the regulator created by the Insolvency and Bankruptcy Code, 2016.
    2. Regulated entities: It regulates insolvency professionals, insolvency professional agencies and information utilities.
    3. Powers: It carries legislative, executive and quasi-judicial functions, framing regulations under the Code and enforcing them.
    4. Data role: It publishes case level outcomes of the insolvency process through periodic newsletters.

    [2017] Which of the following statements best describes the- term ‘Scheme for Sustainable Structuring of Stressed Assets (S4A)’, recently seen in the news?

    (a) It is a procedure for considering ecological costs of developmental schemes formulated by the Government.

    (b) It is a scheme of RBI for reworking the financial structure of big corporate entities facing genuine difficulties.

    (c) It is a disinvestment plan of the Government regarding Central Public Sector Undertakings.

    (d) It is an important provision in ‘The Insolvency and Bankruptcy Code’ recently implemented by the Government.

  • Reasons why GDP growth overshot expectations, and what lies ahead

    Why in the News

    India’s real Gross Domestic Product (GDP) grew 7.8 per cent in April to June, above the 7 per cent estimated by the Reserve Bank of India (RBI).

    Which sectors produced the 7.8 per cent print?

    1. Manufacturing accelerated to 9.2 per cent: The sector grew from 8.3 per cent a year earlier.
    2. Services grew at 10 per cent: The sector expanded from 8 per cent in the same quarter last year.
    3. Agriculture slowed to 3.6 per cent: Growth fell from 4.4 per cent a year earlier.
    4. The farm number still beat its own forecast: The Chief Economic Adviser assessed that agriculture fared better than expected in June, when the monsoon shortfall was high.

    What is holding up demand?

    1. Household spending grew 7.1 per cent: Private Final Consumption Expenditure rose from a growth rate of 6.8 per cent last year.
    2. Urban and rural proxies both performed: Indicators tracking demand in both segments held up over the last three months.
    3. Three rural income measures supported the number: Income transfers under PM Kisan, higher minimum support prices and steps to keep fertiliser affordable aided rural demand.

    Why does the investment number matter more than the headline?

    1. Gross Fixed Capital Formation jumped 11.9 per cent in real terms: This measure of additions to the economy’s fixed assets grew at double last year’s 5.8 per cent.
    2. The nominal increase was 20.4 per cent: Without adjusting for inflation, investment rose by that much.
    3. Investment’s share of GDP reached 34.3 per cent: The share climbed from 31.4 per cent a year earlier.
    4. That share is the threshold for sustaining high growth: The Chairman of the Economic Advisory Council to the Prime Minister has held that investment must rise to 34 to 35 per cent of GDP to sustain growth above 7 per cent.

    What could reverse the outcome?

    1. Crude oil prices carry a supply risk: Disruption to crude supply from the war between the United States and Iran will likely prevent prices falling materially and sustainably below 80 dollars a barrel.
    2. Export demand is the second order effect: Indian households have been partially shielded from higher energy prices, and other countries facing a demand hit would dim the prospects for India’s exports.
    3. El Nino is expected to peak in late 2026: Its implications for rainfall, crop outcomes and food inflation warrant close monitoring, per the Ministry of Finance’s monthly economic review.
    4. All three sectors contributed this quarter: The message from the data is resilience, since agriculture, manufacturing and services each added to growth despite the West Asia war.

    Challenges to sustaining the growth rate

    1. Crude import dependence transmits every price shock: India imports the large majority of the crude oil it consumes, so a price rise lands on the trade balance and on fuel inflation at the same time. Eg. The price surge after the Ukraine war in 2022 pushed Indian retail inflation above the 6 per cent upper tolerance band for three consecutive quarters.
      The Fix: Expand strategic petroleum reserve capacity and spread long term supply contracts across more than one producing region.
    2. The investment cycle is still publicly led: Central government capital spending has carried the recovery, and private corporate capital expenditure has followed later and unevenly. Eg. Central capital expenditure was raised sharply in successive post-pandemic budgets while private project announcements lagged.
      The Fix: Clear land acquisition, contract enforcement and approval delays that raise the fixed cost of starting a private project.
    3. Farm output remains rain dependent: Under half of India’s net sown area is irrigated, so a rainfall shortfall passes directly into crop output and food prices. Eg. The 2015 El Nino year cut kharif sowing and pushed pulse prices to record levels.
      The Fix: Expand micro irrigation coverage and hold larger buffer stocks in the pulses and oilseeds where price spikes originate.
    4. Services exports face demand and technology risk together: Growth in services exports depends on client spending abroad and on how much of the work automation absorbs. Eg. Global capability centres employ a large share of India’s services export workforce, and their scope of work is the part most exposed to automation.
      The Fix: Shift the export base towards higher value engineering and design work rather than volume based delivery.

    Conclusion

    Growth beat the projection because investment and services carried the quarter and agriculture did not. That composition has to repeat for the rest of the year, and two of its supports sit outside the domestic economy. The marker to watch is the next monetary policy review, where the central bank must either revise its full year projection upward or hold it against the energy and monsoon risks the government’s own economists have flagged.

    Back2Basics: Economic Advisory Council to the Prime Minister

    1. Status: An independent advisory body that is neither constitutional nor statutory, reconstituted in its current form in 2017.
    2. Mandate: Advises the Prime Minister on economic and related issues, particularly from a neutral and non-departmental viewpoint.
    3. Composition: Headed by a Chairman, with full time and part time members drawn from academia and policy practice.
    4. Support: It is serviced administratively by NITI Aayog.

    [2020, GS3, 10 marks] Define potential GDP and explain its determinants. What are the factors that have been inhibiting India from realizing its potential GDP?”

  • Why regulators are tightening the cybersecurity net around India’s financial sector

    Why regulators are tightening the cybersecurity net around India’s financial sector

    Why in the News

    The Securities and Exchange Board of India (SEBI) has introduced an IT Resilience Index for Market Infrastructure Institutions, converting cyber preparedness into a periodically computed score rather than a one time compliance certificate. The same circular aligns the regulator’s cyber incident reporting portal for regulated entities with a standardised Format for Incident Reporting Exchange (FIRE), a common template that lets an incident be reported in stages as it unfolds. This follows the Reserve Bank of India (RBI) framework for banks and financial institutions issued last month, which mandates board level oversight, a dedicated information technology risk committee and a six hour window to report a cyber incident. Both regulators are responding to artificial intelligence lowering the cost of committing fraud at scale, including deepfake voices used to bypass Know Your Customer (KYC) verification. The tension is that resilience is now scored by the institution being scored, on a six monthly cycle, against threats that move in hours.

    What is the IT Resilience Index?

    1. What it covers: It quantifies the information technology readiness of Market Infrastructure Institutions, meaning the stock exchanges, clearing corporations and depositories through which trading and settlement actually happen.
    2. The nine parameters: Availability and security carry a weight of 20 per cent each, and integrity, governance, reliability and monitoring, modularity and flexibility, and business continuity carry 10 per cent each. Scalability and a residual “others” parameter carry 5 per cent each.
    3. The reporting cycle: Each institution computes the index half yearly and files it within 60 days of the end of each half year. The filing carries a comparative analysis of two consecutive half years on a rolling basis together with the corrective action taken.
    4. When it applies: The framework takes effect from early 2027 and carries an early warning system with continuous monitoring to flag risks before they mature.

    Why is cyber readiness being converted into a score?

    1. The stated risk: Disruption, degraded performance or compromise of these systems can hit critical market operations and damage trust in the securities market itself.
    2. A score reaches the board: Resilience expressed as a number can be measured and benchmarked, which moves it from the technology function into boardroom accountability.
    3. Direction matters more than a snapshot: A comparative filing across two consecutive half years shows whether an institution is improving or slipping, which a point in time audit cannot establish.

    How is incident reporting being standardised?

    1. One template across regulated entities: The reporting portal now follows the FIRE format, so incidents arrive in a comparable structure rather than in each entity’s own narrative.
    2. Reporting follows the incident life cycle: The format carries initial reporting, intermediate updates and a final closure, and it accepts that some information will not be available at the first report.
    3. Two regulators, two clocks: The banking regulator fixes a hard outer deadline for reporting by banks, and the market regulator fixes a staged format for its own regulated entities.

    How is artificial intelligence changing both the threat and the response?

    1. Fraud now scales cheaply: Synthetic voice is being used to defeat customer verification, and complex scams are being run against critical financial services institutions rather than only against individuals.
    2. Breaches have already landed: Cybersecurity threats infiltrated a number of banks during 2026.
    3. Guidelines are pending: The market regulator has said it will shortly issue guidelines for the responsible use of artificial intelligence and machine learning.
    4. The regulator is also a user: Artificial intelligence models already flag suspicious trading patterns, and a team has been constituted to build models covering corporate investigations, extending surveillance from trade data to filed quarterly results.

    Why is the response shifting into the account holder’s own hands?

    1. The killswitch idea: The banking regulator has flagged a mechanism allowing a user to freeze all financial transactions in their accounts during an ongoing fraud.
    2. The securities market is examining the same tool: The market regulator is evaluating a comparable mechanism as part of its artificial intelligence guidelines.
    3. Compensation was widened first: In June the banking regulator revised its fraud compensation mechanism, enlarging the set of victims who can claim and bringing newer digital scams into the definition of fraud.

    Challenges to the IT Resilience Index

    1. The score is self computed: An institution scores its own controls and files the result, so a weak control can be scored generously without an independent check. Eg. Lapses in access and system controls at a Market Infrastructure Institution surfaced in the co-location proceedings against the National Stock Exchange, not through its own reporting. Fix. Require third party assurance of the score before it is filed, in the same way financial statements are audited.
    2. A half yearly cadence cannot track a live intrusion: An index computed twice a year describes a posture, not an event that unfolds within a trading session. Eg. The National Stock Exchange outage of February 2021 halted cash and derivatives trading for close to four hours. Fix. Pair the half yearly score with a continuous telemetry feed to the regulator’s monitoring desk.
    3. The riskiest dependencies sit outside the perimeter: Cloud providers, data centres and software vendors are shared across institutions, and their failure is not captured by any single institution’s score. Eg. The CrowdStrike update failure of July 2024 disabled Windows systems at banks and airlines across several countries at once. Fix. Score vendor and cloud concentration explicitly, and require a tested failover to an alternative provider.
    4. Disclosure competes with reputation: An institution’s first instinct in a breach is containment, and a reporting clock runs against that instinct. Eg. The 2016 malware compromise of a payment switch led to about 32 lakh debit cards being recalled, and it surfaced weeks after the breach began. Fix. Make timeliness and completeness of incident reporting a scored parameter, so silence costs the institution its index.

    Conclusion

    Cyber readiness has been turned into a score, on the reasoning that a number reaches a board in a way an audit finding does not. The weakness is that the entity being scored computes its own score. The marker to watch is the first round of comparative filings, since that is when it becomes clear whether the index is measuring behaviour or documentation.

    Matching Previous Year Question

    “[2022, GS3, 10 marks] What are the different elements of cyber security? Keeping in view the challenges in cyber security, examine the extent to which India has successfully developed a comprehensive National Cyber Security Strategy.”

  • Worries behind India’s robust GDP, inflation data

    Why in the News

    Six months into the West Asia war, India’s headline macroeconomic numbers have held up against the deterioration forecast for them. Gross Domestic Product (GDP) growth for the first quarter is put at 7 to 7.5 percent, retail inflation sits near the Reserve Bank of India (RBI) target of 4 percent, and the current account deficit is 0.3 percent of GDP. The forecasts had assumed the opposite, since the war was expected to raise crude oil prices and cut foreign investment, and El Nino conditions (a periodic warming of the eastern Pacific that shifts monsoon rainfall over India) threatened food production. The tension is that each of the three headline numbers rests on a support that can reverse within a quarter, so the resilience is a matter of composition rather than of structure.

    Why were the macro numbers expected to deteriorate?

    1. The war was expected to work through crude and capital: Higher crude oil prices and a reduction in foreign investment were the two channels analysts identified after the United States and Israel went to war with Iran.
    2. Inflation was projected to triple: The rate was expected to rise from 2 percent in 2025-26 to near 6 percent, moving from the lower end of the RBI’s comfort zone to its upper limit.
    3. The rupee carried the visible damage: The war exposed persistent weaknesses in the economy, expressed most sharply in the fall of the rupee’s exchange rate.
    4. Household consumption was asked to adjust: The Prime Minister appealed to citizens to stop gold purchases and reduce fuel consumption, among other measures.

    What is actually holding up the growth number?

    1. Monetary easing has begun to transmit: The repo rate, the rate at which the RBI lends to commercial banks, was cut by 125 basis points between December 2024 and December 2025, and transmission into faster growth typically takes a couple of quarters.
    2. Indirect tax cuts raised purchasing power: Cuts in the Goods and Services Tax in 2025 lowered prices and lifted economic activity.
    3. Exports to the United States recovered: India’s exports rose as the tariffs imposed by the United States were removed.
    4. Manufacturers produced ahead of demand: Firms front loaded production because they were anxious about future energy availability.
    5. The estimates cluster above 7 percent: A research database of 100 growth indicators points to 7 to 7.5 percent for April, May and June, and one domestic bank’s research team projects 8 percent.

    Why is headline inflation low, and what does the average conceal?

    1. The headline rate is contained but rising: Monthly retail inflation has moved up since October and remains near the RBI’s 4 percent target level.
    2. The restraint is not the usual kind: Inflation ordinarily stays muted because growth is muted, and here it has stayed muted despite supply pressures and with demand holding up.
    3. Goods inflation is already at 5.4 percent: Food inflation and non food goods inflation together averaged 5.4 percent year on year in July.
    4. Services inflation is doing the masking: Services inflation is at 2.5 percent, and a rise from that level, reflecting growth better, would push the headline number up quickly.

    How is the current account deficit being held at 0.3 percent of GDP?

    1. The current account measures net flows on trade: It is the net amount of money moving in or out of India as it trades goods and services with the world, and a country importing more than it exports runs a deficit on it.
    2. The goods side is deteriorating: The goods trade deficit is growing, which is the normal consequence of fast growth and costlier imports.
    3. Services and remittances are funding the gap: Rising services exports and remittances from Indians working abroad are offsetting the increase in the goods deficit.
    4. The funding source is itself uncertain: Services exports have grown at a softer pace this year, and the effect of artificial intelligence on services export growth is unsettled.

    What do the credit numbers signal beneath the growth rate?

    1. Credit growth is partly guaranteed rather than commercial: A new government credit guarantee scheme for small firms accounts for part of the rise in loans.
    2. Working capital demand reflects costlier inputs: Borrowing has risen because higher commodity prices have raised working capital needs.
    3. Gold loan growth is a stress marker: The proliferation of gold loans functions as an indicator of household financial distress rather than of expansion.
    4. Front loading borrows from the next quarter: Manufacturing brought forward can be followed by a lull, and agricultural growth can weaken if El Nino strengthens.

    Challenges to sustaining India’s growth and inflation mix

    1. Import dependence on crude oil transmits every external shock: India imports the large majority of the crude oil it consumes, so a price shock lands directly on the trade balance and on the fuel component of retail inflation. Eg. The 2022 crude price surge after the Ukraine war pushed retail inflation above the RBI’s 6 percent upper tolerance band for three consecutive quarters. Fix. Expand the strategic petroleum reserve and diversify long term crude contracts away from a single supplier region.
    2. Exchange rate depreciation feeds imported inflation: A weaker rupee raises the domestic price of imported fuel, edible oil, fertiliser and electronics regardless of domestic demand conditions. Eg. Edible oil prices in India track palm oil import costs from Indonesia and Malaysia, where India buys the bulk of its supply. Fix. Deepen the domestic oilseed and fertiliser production base so that the depreciation pass through covers a smaller import basket.
    3. Services led growth generates limited employment: The sector’s share of output far exceeds its share of jobs, so a growth rate driven by services does not translate into proportionate hiring. Eg. Information technology services contribute a large share of exports. They employ a small fraction of the non farm workforce. Fix. Tie production and export incentives to verified employment creation rather than to output or investment alone.
    4. Private capital expenditure has not led the cycle: Growth supported by rate cuts, tax cuts and front loaded production rests on policy stimulus rather than on a durable investment upturn. Eg. Central government capital expenditure has carried the investment cycle since the pandemic, with private corporate investment recovering later and unevenly. Fix. Resolve land, contract enforcement and clearance delays that raise the fixed cost of a new private project.

    Conclusion

    The headline numbers are steady because one sector is covering for the others. That is a composition rather than a structure, and a composition can change inside a quarter. The marker to watch is whether services inflation rises at the same time as services exports weaken, since that pairing would force the central bank to raise rates and take the growth number with it.

    Matching Previous Year Question

    “[2021, GS3, 10 marks] Explain the difference between computing methodology of India’s Gross Domestic Product(GDP) before the year 2015 and after the year 2015.”

  • ‘CAS is a move in the right direction, but the timing may not be right’

    Why in the News

    The Securities and Exchange Board of India (SEBI) has replaced the method used to fix closing prices on the stock exchanges with a Closing Auction Session (CAS), implemented at the start of this month. The earlier method took the volume weighted average price (VWAP), the average price of the last 30 minutes of trading, which a large order placed in the closing moments could tilt. The change follows the Jane Street episode, after which the regulator concluded that the earlier method could be moved in a participant’s favour. Traders hold that the direction of the change is right and the timing is not, since Indian markets carry far higher retail participation than the institution driven markets the mechanism was borrowed from.

    How does the Closing Auction Session work?

    1. Normal trading closes at 3.15 pm: Trading runs as usual until 3.15 pm, and all pending limit and market orders are carried forward into the CAS. Stop loss orders are removed from the system.
    2. Reference prices are computed through the session: Exchanges calculate reference prices from 3.15 pm to 3.30 pm.
    3. Order types narrow as the session runs: Market or limit orders may be placed between 3.20 pm and 3.25 pm (a market order executes at the prevailing price, a limit order executes only at the price stated by the trader). From 3.25 pm only limit orders are accepted.
    4. The close is randomised: The session ends at a random time between 3.27 pm and 3.30 pm. Derivatives continue to trade until 3.40 pm.

    Why did SEBI move away from the volume weighted average price method?

    1. The weakness in an average: A large quantity traded in the closing moments moves the average, so the preceding 30 minutes count for little in the final price.
    2. The trigger for the review: The regulator concluded after the Jane Street episode that the closing price under the earlier method could be tilted.
    3. Global practice: Auction based closes are already used in developed markets, including the United States and the United Kingdom.
    4. Institutional demand: Financial institutions and global players pitched the auction as the better mechanism for determining closing prices.

    What does the auction change for participants?

    1. Participation replaces dependence on a single print: The closing price is formed from orders placed in the auction rather than from a computed average, which makes price discovery more broad based.
    2. Orders are no longer tied to the closing price: A participant can place an order at a higher or lower price according to their own requirement, instead of matching at whatever the closing price turns out to be.

    Why are volumes in the session thin?

    1. Participants are still adjusting: The session is new, and a change in market structure is first thought over and played out with caution before it is used.
    2. The matching price is not visible: Price matching runs for five to seven minutes behind the scenes, so a participant does not know the price at which an order will match.
    3. Part execution is the likely outcome: An order placed two per cent away from the market carries no certainty that the full quantity will be executed, and under executions are the more likely result.
    4. The largest volume generators are absent: Arbitrage firms and proprietary trading firms are sitting out, since the session gives them neither the time nor the visibility to hedge in the futures and options (F&O) segment. They do not run unhedged positions.

    Why is the timing of the change contested?

    1. Market maturity: The Indian market is not yet mature enough for a mechanism designed for markets where participants have full information on when and how to participate.
    2. Retail share is higher than in comparable markets: India has much higher retail participation than other major markets, which are institution driven, and retail awareness of the new session is still at an early stage.
    3. A longer parallel run was possible: The session could have been run in simulation or in parallel with the earlier system for longer, giving participants time to get used to it before implementation.
    4. Small orders may not find a match: Most retail investors trade in small ticket sizes, so a large institutional order placed in the session is unlikely to be matched.
    5. Leverage pulls retail elsewhere: Retail traders prefer the derivatives segment over the auction because of the higher leverage available there.

    Conclusion

    The Closing Auction Session has been in force since the start of the month and is still evolving, which makes a comparison with the earlier method premature. Volumes remain low and the participants who generate most of them are staying out until they can hedge around the randomised close. The next test is whether participation broadens as the mechanism settles and awareness spreads at the retail level.

    Matching Previous Year Question

    “[2023] Consider the following markets : 1. Government Bond Market 2. Call Money Market 3. Treasury Bill Market 4. Stock Market How many of the above are included in capital markets? (a) Only one (b) Only two (c) Only three (d) All four ANSWER: (b)”

  • Chandra’s settlement comes as IBC turns 10, with bank haircuts at five-year high

    Why in the News

    The National Company Law Tribunal (NCLT) has approved a personal insolvency repayment plan under which Zee Group founder Subhash Chandra will pay Rs 6.5 crore against admitted claims of Rs 22,006.57 crore. That is a 99.97 per cent haircut, one of the highest in the history of the insolvency regime. It comes as the Insolvency and Bankruptcy Code, 2016 (IBC) completes ten years in force. Banks are considering an appeal before the National Company Law Appellate Tribunal (NCLAT). The dispute is whether the Code should be judged by what creditors recover or by whether a stressed asset is resolved at all.

    What is a “haircut” under the Insolvency and Bankruptcy Code, 2016?

    1. The term is not defined in the Code: The IBC nowhere defines a haircut. Banking practice uses the word for the percentage reduction in the value of an asset pledged as collateral, applied to protect the lender against loss.
    2. What the Code was enacted to do: The IBC was enacted in 2016 to rescue companies under financial stress or heavy debt through resolution and repayment to creditors.
    3. A creditor majority binds the minority: Once the required majority of creditors approves a repayment plan and the tribunal sanctions it, a dissenting creditor cannot walk away and demand a separate settlement.

    Why has the Chandra order revived the haircut debate?

    1. The size of the write down: The order of 25 August approved payment of Rs 6.5 crore to creditors, plus Rs 25 lakh towards the costs of the process.
    2. The liability arises from personal guarantees: Much of the admitted claim relates to personal guarantees and indemnities given for borrowings by companies associated with the Essel Group.
    3. The route is personal insolvency: The proceedings ran against the individual promoter as a personal guarantor rather than against a corporate debtor.
    4. Lenders are weighing a challenge: Banks are considering an appeal against the approval before the NCLAT.

    What does the recovery record under the Code look like?

    1. Cases resolved and value realised: Between 2021-22 and 2025-26, 1,077 cases were resolved under the IBC, with a realisation of Rs 2.47 lakh crore for creditors.
    2. The five year average: Average recovery against admitted claims across those five years was close to 29 per cent.
    3. The year wise trend: Recovery was 24 per cent in 2021-22, 39 per cent in 2022-23, 28 per cent in 2023-24 and 37 per cent in 2024-25, before falling to 20 per cent in 2025-26, the lowest in five years.
    4. What the figure means for a lender: A bank may hold claims running into thousands of crore rupees and receive only a fraction of what it is owed.

    Why do the banks contest the vote that approved the plan?

    1. The margin of approval: Twenty three creditors participated in the voting, and the plan was approved with 80.814 per cent of the votes cast in its favour.
    2. Every bank voted against: The banks that opposed the plan held a combined vote share of only 19.186 per cent.
    3. The related party allegation: Banks say at least five entities holding 61.78 per cent of the votes cast, all of which backed the plan, are linked to the debtor as associates or related parties.
    4. The exclusion sought: A trustee company argued that the votes of an investment company and its two subsidiaries should not have been counted. A resolution professional is the person appointed to manage the affairs of an entity under insolvency and to facilitate its resolution.
    5. The subsidiary argument: The debtor’s counsel argued that a parent company that is not itself an associate of the debtor cannot pass that classification to its downstream subsidiaries.
    6. The debtor’s response: Chandra’s office rejected the allegation as inaccurate. It said the entities referenced belonged to a relative whose business interests were separated in 2008-09, and that they do not qualify as associate entities under the Code.

    Is the Code meant to maximise recovery, or to resolve?

    1. The government’s position: The Ministry of Corporate Affairs holds that the primary objective of the Code is resolution and not recovery.
    2. Why claims are treated as the wrong benchmark: The Ministry told the standing committee on finance in December 2025 that the assets available on the ground are the better measure, since the market values what a company brings to the table and not what it owes.
    3. What an admitted claim contains: A claim often includes a non performing asset (NPA) that may be fully written off, the interest on that asset, and both a loan and the guarantee given against it.
    4. The value that is not counted: Realisation figures exclude the value that may come from equity holdings after a resolution.
    5. The indirect gain claimed: The Code is credited with creating credit discipline, which has contributed to reducing the gross non performing assets of banks.
    6. The banks’ counter: Banks argue that the problem lies in the valuation of stressed companies, that all assets should be included and properly valued, and that the process is opaque.
    7. The valuation mechanism in dispute: At least two valuers are appointed to give a fair value and a liquidation value, based on records and physical examination of the assets. The Chairman of the State Bank of India told the standing committee that valuation should reflect enterprise value instead of liquidation value.

    Challenges to the Insolvency and Bankruptcy Code, 2016

    1. Delay erodes the value a resolution can fetch: A stressed company loses value for every year it stays unresolved, so the price a resolution applicant will pay falls with time. Eg. Videocon Industries was resolved in 2021 at about five per cent of admitted claims, and the NCLAT stayed the approved plan on that ground. Fix. Tie admission to a fixed outer date from the default so the asset reaches the market before it is stripped of value.
    2. Liquidation remains a more common outcome than rescue: A large share of admitted cases ends in liquidation rather than in an approved resolution plan, which inverts the Code’s stated purpose. Eg. The Insolvency and Bankruptcy Board of India’s quarterly newsletters have consistently reported more closures by liquidation than by resolution. Fix. Extend the pre-packaged insolvency route, available to micro, small and medium enterprises since 2021, to larger firms so a rescue is negotiated before value is lost.
    3. The individual insolvency framework is only partly in force: Part III of the Code was notified in December 2019 for personal guarantors to corporate debtors alone, and the remaining provisions for individuals and partnership firms have not been brought into force. Eg. A defaulting individual who is not a personal guarantor has no route under the Code at all. Fix. Notify the remaining Part III provisions along with a designated adjudicating forum for individual cases.

    Conclusion

    The appeal now being prepared will decide whether the disputed votes were correctly counted, and that is the next milestone in this case. Valuation is the point on which the recovery and resolution positions turn, and shifting stressed asset valuation to enterprise value is still only a suggestion before the committee.

    Matching Previous Year Question

    “[2017] Which of the following statements best describes the- term ‘Scheme for Sustainable Structuring of Stressed Assets (S4A)’, recently seen in the news? (a) It is a procedure for considering ecological costs of developmental schemes formulated by the Government. (b) It is a scheme of RBI for reworking the financial structure of big corporate entities facing genuine difficulties. (c) It is a disinvestment plan of the Government regarding Central Public Sector Undertakings. (d) It is an important provision in ‘The Insolvency and Bankruptcy Code’ recently implemented by the Government. ANSWER: (b)”

  • Economy weathered West Asia shock. Now, reform for sustained growth (Op-ed by Sajjid Chinoy)

    Why in the News

    India’s gross domestic product (GDP) growth for the last quarter is expected to print close to 8 per cent, defying fears that the West Asia conflict had dented the economy. This follows a joint fiscal, monetary and regulatory stimulus through 2025, direct tax cuts, a Goods and Services Tax (GST) rationalisation, and an effective 150 basis point policy rate cut, combined with a swift diversification of energy imports during the conflict. The pickup is largely cyclical, and the investment rate, corporate capital expenditure (capex) and structural export and employment growth remain too weak to sustain the expansion once the stimulus fades.

    What explains India’s growth resilience through the West Asia conflict?

    1. A joint stimulus in 2025: Direct taxes were cut in February, GST was rationalised in September, and policy rates were cut by an effective 150 basis points along with regulatory easing in the financial sector.
    2. Non-oil export acceleration: Exports have picked up on the back of a near 15 per cent depreciation of the real effective exchange rate (REER), the trade weighted, inflation adjusted value of the rupee against a basket of currencies, since 2025, a reduction in United States tariffs, and resilient global growth.
    3. Swift energy diversification: India sourced crude from Russia and liquefied natural gas from the United States and Oman to prevent shortages, importing 17 per cent more energy than normal last quarter, while the government absorbed the bulk of the oil price shock through the fisc to insulate the private sector.

    Why does India’s investment rate remain a structural concern?

    1. Fixed investment stagnant: Fixed investment remains near its decadal average of 32 per cent of GDP and has not lifted despite rising public investment and real estate capex.
    2. Corporate capex has not picked up: Corporate capex continues to languish around 10 to 11 per cent of GDP, and balance sheets of the top 1,000 listed companies show no discernible pickup in 2025-26.
    3. Central capex is slowing: Central capex grew 30 per cent between 2020 and 2023, then slowed to 11 per cent in 2024 and just 1.6 per cent in 2025, as tax cuts absorbed fiscal space.
    4. State capex under pressure: Cash transfers on demand are pushing state capex growth below nominal GDP growth.
    5. Weak demand visibility: Capacity utilisation has stayed in the 75 to 76 per cent range for a decade, and rising Chinese overcapacity is discouraging corporate investment.

    Why are consumption and export growth not yet structural?

    1. Weaker growth than the earlier export led cycle: Post-pandemic private consumption and exports grew at about 5 per cent, against the 16 per cent export growth between 2003 and 2012 that had crowded in private capex.
    2. Service export growth has halved: Service export growth in nominal dollars has fallen to 8 per cent over the last year from 16 per cent over the previous four years, and employment across major IT firms has stayed flat.
    3. Employment mix is shifting toward self-employment: The Periodic Labour Force Survey shows India’s employment rate rising, but a significant share of new jobs are self-employed rather than salaried, even as the mix improved in 2025.
    4. Consumption is credit fuelled: Non-Banking Financial Company lending to households is growing at 20 per cent and unsecured personal lending momentum has risen to 25 per cent, on the back of rising household leverage.

    What must change for the growth cycle to become structural?

    1. Labour must become more competitive against capital: India’s capital-labour ratio has risen for over two decades, and reversing this needs education, skilling and health investment, alongside rationalising labour laws that raise the cost of labour.
    2. Exports need structural competitiveness: Goods exports have fallen from 17 per cent of GDP a decade ago to 11 per cent, and further gains need tariffs and non-tariff barriers rationalised and overregulation reduced.
    3. Private capex is the real crowding-in mechanism: Structurally higher consumption and exports are what would draw in a sustained private capex cycle, which in turn would crowd in foreign direct investment and stabilise the balance of payments.

    Conclusion

    The current cyclical strength, backed by clean corporate and financial balance sheets and a sustained agricultural surplus, is a bridge over the West Asia shock, not a destination. Unless investment, exports and employment turn structural, the growth cycle will not sustain once the fiscal and monetary stimulus fades, and the piece warns there is little time left to act given global automation, trade fragmentation and a fraying international order.

    Matching Previous Year Question

    No direct PYQ traced in the provided files.

  • FCNR(B) deposits push forex reserves to all-time high of $729 bn in August

    Why in the News

    The Reserve Bank of India’s concessional swap window for Foreign Currency Non-Resident (Bank), or FCNR(B), deposits has propelled India’s foreign exchange reserves to a record $729.33 billion as of 21 August, surpassing the previous all-time high of $728.49 billion recorded on 27 February, just a day before the United States and Israel struck Iran and touched off the West Asia conflict that drove global energy prices sharply higher. Reserves rose by $12.42 billion in the week ended 21 August alone, with FCNR(B) inflows of $65.4 billion accounting for most of the $72.85 billion that has entered India since three concessional swap windows opened on 8 June.

    What is driving reserves to a record, and what does the FCNR(B) window actually do?

    1. Scale of inflows: FCNR(B) deposits outstanding rose from $34.04 billion at the end of May to $65.4 billion by 21 August, since the window opened on 8 June, and reserves themselves jumped $12.42 billion in the week ended 21 August.
    2. Mechanism: Under the FCNR(B) scheme the central bank bears the full exchange rate risk on these non-resident deposits, since the money is held in foreign currency rather than converted into rupees, which let banks offer interest rates as high as 7.4 percent.
    3. Leveraged NRI participation: Non-resident Indians have also borrowed at lower interest rates abroad to deposit the proceeds into FCNR(B) accounts, earning returns of as much as 15 percent on the resulting spread.

    Why did reserves need rebuilding in the first place?

    1. The rupee was already under stress before the record: The rupee came under intense pressure from large foreign portfolio outflows, with $19 billion leaving Indian markets in 2025 and a further $24 billion in the first five months of 2026, pushing the currency to near 97 per dollar in mid-May.
    2. The West Asia conflict added an oil import shock: Since roughly 85 percent of India’s crude oil needs are met through imports, the conflict’s closure-driven spike in global energy prices raised the country’s import bill and added further pressure on the rupee just as reserves were near their earlier February high.
    3. The rupee remains down year-on-year despite the record reserves: The rupee closed at 95.39 per dollar on Friday, little changed from its 95.79 level on 4 June and still 8.1 percent weaker than a year earlier, showing the reserve build has stabilised rather than reversed the currency’s decline.

    What other measures accompanied the FCNR(B) window?

    1. Two additional swap windows: Announced alongside FCNR(B) on 5 June, swap facilities for Overseas Foreign Currency Borrowings and External Commercial Borrowings have together brought in $4.86 billion and $2.59 billion respectively since 8 June.
    2. Tax relief for foreign portfolio investors: The government removed capital gains and withholding taxes on foreign portfolio investment in government securities as part of the same package meant to pull in capital and support the rupee.
    3. An accelerated closure timeline: Because inflows arrived faster than expected, the RBI moved the FCNR(B) window’s closing date to 31 August, a month earlier than the originally announced 30 September deadline.

    Challenges to relying on FCNR(B)-driven reserve accumulation

    1. Weak currency response relative to precedent: The rupee has barely moved during this swap window, compared with the 2013 episode when the rupee rose 10.3 percent, from 67.6 to 61.3 per dollar, in the first 40 days after the RBI’s then-Governor introduced a similar FCNR(B) swap facility. Eg. The rupee moved from 95.79 to 95.39 per dollar between 4 June and 29 August this year, a fraction of the 2013 currency response to a comparable scheme. Fix. Pair reserve accumulation with structural measures that improve the current account, such as diversifying energy import sources, rather than treating swap-driven capital inflows alone as sufficient to support the currency.
    2. Reversal risk from leveraged hot money: A meaningful share of FCNR(B) inflows has been driven by non-resident Indians borrowing cheaply abroad to arbitrage into high-yield deposits, a flow that can reverse quickly once interest rate differentials narrow or the window closes. Eg. The window’s early closure on 31 August, a month ahead of schedule, was itself driven by inflows arriving faster than expected, which cuts both ways once the scheme ends and deposits mature. Fix. Stagger FCNR(B) maturities and monitor the redemption schedule closely to avoid a sudden reserve drawdown when large deposit tranches come due.

    Conclusion

    The FCNR(B) swap window has pushed India’s foreign exchange reserves past their previous February high to a record $729.33 billion, giving the Reserve Bank of India greater capacity to defend the rupee after a period of heavy foreign portfolio outflows and an oil price shock from the West Asia conflict. The rupee’s limited appreciation despite the record inflow, unlike the sharper rupee gains seen after the comparable 2013 swap window, signals the current build is cushioning rather than reversing currency pressure.

    Back2Basics: What are FCNR(B) deposits?

    1. FCNR(B) deposits are foreign currency accounts that non-resident Indians can hold with Indian banks, where the deposit and its returns stay denominated in the foreign currency rather than in rupees.
    2. The scheme shifts exchange rate risk onto the Reserve Bank of India rather than the depositor or the bank, which lets banks offer higher interest rates to attract inflows during periods of currency pressure.
    3. India last used a similar concessional FCNR(B) swap window in 2013, under then RBI Governor Raghuram Rajan, to stabilise the rupee following a sharp depreciation.

    Matching Previous Year Question

    No direct PYQ traced in the provided files (Pass 1: FCNR(B), forex reserves record — no match; Pass 2: balance of payments, current account — matches found were conceptually unrelated to a record reserves event).

  • A.P. to become third subsea hub on data centre buildout

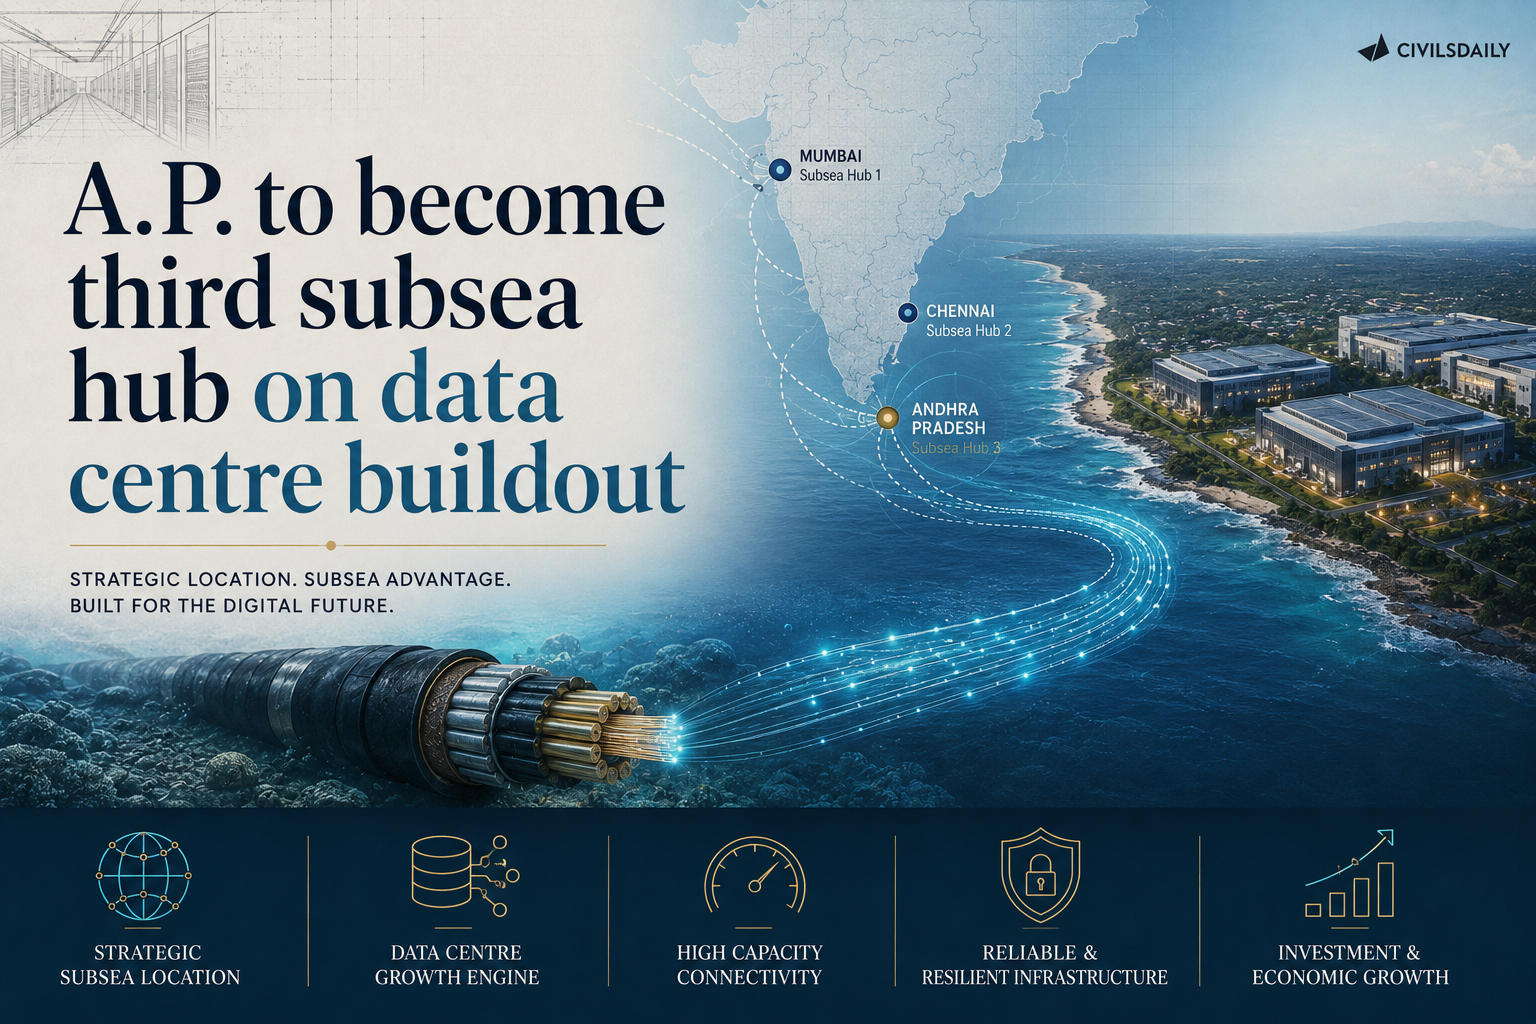
    A.P. to become third subsea hub on data centre buildout

    Why in the News

    Technology majors Microsoft and Google are building new subsea cable landing stations on the coast of Andhra Pradesh as part of an artificial intelligence linked data centre buildout in the State. Microsoft is part of a consortium with Lightstorm and the Singaporean telecom operator Singtel to land the 3,600 kilometre India Southeast Asia Submarine Cable System, while Google’s globe spanning America India Connect system will land at Visakhapatnam, where the company’s own data centre complex is coming up. Once complete, the buildout will give India, after Mumbai and Chennai, a third digital international gateway, even as a global shortage of fibre threatens to slow the inland network these projects still need.

    What is a subsea cable landing station?

    1. Definition: A subsea cable landing station is the facility where an undersea fibre optic cable comes ashore and connects to a country’s terrestrial network, carrying the bulk of international internet traffic.
    2. Global reliance: The overwhelming majority of the world’s international data traffic travels through such undersea cable systems rather than satellites, making landing stations critical infrastructure.
    3. India’s current concentration: India’s existing landing stations are concentrated in Mumbai and Chennai, leaving the country reliant on a small number of routes.

    What new cable infrastructure is being built off Andhra Pradesh’s coast?

    1. Microsoft’s consortium project: Microsoft, alongside Lightstorm and Singtel, is landing the 3,600 kilometre India Southeast Asia Submarine Cable System, expected to be ready for service in the fourth quarter of 2029.
    2. Google’s own system: Google’s America India Connect system will land at Visakhapatnam, alongside the data centre complex the company is building there as part of what a Google executive described as an artificial intelligence hub.

    What does this make Visakhapatnam?

    1. India’s third gateway: After Mumbai and Chennai, Visakhapatnam becomes India’s third digital international subsea gateway, connecting the country directly with Southeast Asia, Australia and the Middle East.
    2. A new corridor: Lightstorm’s chief executive has described the India Southeast Asia system, which also connects to Chennai, as providing a fresh corridor to South Asia from Singapore and Malaysia.

    Why are companies building on the east coast now?

    1. Ageing existing infrastructure: Most cables currently connecting India’s east coast are old, are already filled to capacity and are approaching the end of their working life.
    2. A search for resilience: Companies are also seeking to reduce the risk of relying on a single route by adding cables on India’s east coast, citing instability in West Asia as a reason to build in an alternate location.

    What inland infrastructure does this buildout require?

    1. A nationwide undertaking: Both projects require installing and lighting thousands of kilometres of new terrestrial fibre linking the coast to major cities, a scale one company executive described as spanning the entire country.
    2. A dedicated corridor: Lightstorm is expected to build a terrestrial corridor connecting Machilipatnam to Mumbai and Hyderabad, and Chennai to Hyderabad and Mumbai, with matching bandwidth.
    3. A global fibre shortage: Fibre, its components and its raw material are in short supply worldwide, including from Indian manufacturers, a constraint industry executives describe as unprecedented in over a decade.

    What will Google’s Visakhapatnam facility do?

    1. Focused on inference: The facility will focus on inference work rather than power intensive training runs, serving domestic enterprises and government agencies given the deep adoption of artificial intelligence across government service delivery.
    2. Power and water choices: Google is seeking to source as much renewable power for the project as possible and is using air cooling technology to minimise water use.

    Challenges to the subsea cable buildout

    1. A global fibre shortage: A worldwide shortage of fibre and its raw material, unprecedented in over a decade, could delay the inland network these projects still need. Eg. Industry executives report that fibre is out of stock across the globe, including from Indian manufacturers. Fix. Expand domestic fibre manufacturing capacity through targeted incentives so the inland rollout is not held back by global supply constraints.
    2. Physical vulnerability of undersea cables: Undersea cables remain exposed to accidental damage from fishing and anchoring activity and to disruption in contested waters. Eg. India’s existing east coast cables are already ageing and running close to capacity, leaving few redundant routes today. Fix. Build multiple, geographically separated landing points and routes, as the new Visakhapatnam gateway is itself intended to do, so a single cable fault cannot isolate India’s connectivity.
    3. Concentration of ownership with foreign firms: The new cable systems and the data centres they serve are being built and operated by foreign technology majors, so India’s expanding gateway capacity depends on the investment decisions of a small number of firms. Eg. Both the India Southeast Asia system and the America India Connect system are anchored by Microsoft and Google respectively rather than Indian carriers. Fix. Encourage Indian telecom operators to invest jointly in landing station capacity so gateway control is not concentrated entirely with foreign firms.

    Conclusion

    Andhra Pradesh’s coastline is emerging as India’s third major digital gateway, as Microsoft and Google build new subsea cable systems into Visakhapatnam alongside the data centres driving the region’s artificial intelligence buildout. Delivering on that promise depends on inland fibre rollout keeping pace despite a global supply crunch, and on India diversifying its cable landing points and ownership so its expanding digital infrastructure does not remain concentrated in a handful of ageing routes and foreign owned systems.

    [2023] “What is the status of digitalization in the Indian economy? Examine the problems faced in this regard and suggest improvements.”