Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS3-01.Indian Economy and issues relating to planning, mobilization of resources, growth, development and employment.

  • Investment question has a political answer

    Why in the News

    Private corporate investment in India remains considerably lower than the peak seen in the mid 2000s, even as large corporates hold substantial cash. Firms are deploying funds in financial assets rather than building physical assets such as factories, and are taking money out of the country rather than investing it here. The standard explanations offered for this are subdued domestic demand and global uncertainty. A political economy explanation is now advanced instead, locating the cause in how political power structures affect investment decisions. Centralisation of political power has been unmistakable after 2014, accompanied by fiscal centralisation and a reconfiguration of federal structures. The contested claim is that market concentration around a handful of “national champions” is not an accident of policy but is politically useful, which would make an investment revival costly to the current political settlement.

    What are “national champions”?

    1. Definition: A national champion is a large domestic business group that a government treats as the preferred vehicle for building strategic capacity, and that is favoured in policy design as a result.
    2. How the status is conferred: Preference operates through the terms of auctions, tariffs, incentive eligibility, clearances and access to public contracts rather than through an announced designation.
    3. The economic consequence: A handful of such groups now command far greater sway over the economy than before, which raises the entry barrier facing any firm attempting to compete with them.

    What does the investment slowdown actually look like?

    1. Cash-rich firms are not building: Large corporates hold funds but are not committing them to new capacity in India.
    2. Capital is leaving: Companies are taking money out of the country rather than investing it domestically.
    3. Investment is below its own peak: Private corporate investment remains considerably lower than the level reached in the mid 2000s.
    4. Financial assets over physical assets: Corporate India is more keen to deploy funds in financial assets than to use them for factories and plant.
    5. The standard explanations are incomplete: Subdued domestic demand and global uncertainty have been put forward, and neither accounts for why firms with the means to invest choose not to.

    Why does the concentration of political and market power deter private investment?

    1. Political and fiscal centralisation: Centralisation of political power after 2014 has been accompanied by greater fiscal centralisation and a reconfiguration of federal structures, including attempts to restrict the powers of states and, as a consequence, of regional parties. Eg. The Mines and Minerals (Development and Regulation) Amendment Act, 2026, amending the 1957 law under which the State owns the mineral and signs the lease while the Centre sets the rules and the royalty rate.
    2. Market concentration has moved in step: The rise of a handful of large companies, aided by policy, has given them far greater sway over the economy than ever before.
    3. One, patronage for smaller firms has dried up: The concentration of political power and the decline in the relative power of regional parties has ended the patronage and protection that were afforded to smaller and regional firms, who could rise up and become national players.
    4. Two, policy uncertainty and an uneven playing field: Higher barriers to entry and terms tilted towards larger corporates make it harder for new players to emerge, and firms will not invest if they fear the rules of the game can be arbitrarily changed or that they can be caught on the wrong side of policies. Policy credibility is what is at stake.
    5. Three, the fear of being muscled out: Investors fear that business success will be met by a hostile takeover by a national champion, so the question is not whether they are allowed to operate but whether they can stay in business and remain competitive over the next 10 to 20 years.

    Why would dispersing economic power be politically costly?

    1. Competition requires a rethink of the strategy: For the larger corporate sector to ramp up investment and for competition to emerge, the strategy of relying on a few national champions needs to be reconsidered.
    2. Dispersed economic power funds political opposition: A larger number of big private players would disperse rather than concentrate economic power, which would in turn increase the funding avenues available to Opposition parties.
    3. Economic competition feeds political competition: Weakening the concentration of economic power would possibly weaken the concentration of political power, so greater economic competition could lead to greater political competition.
    4. The two open questions: It is unsettled whether the current political structure creates the space for new players to safely invest and emerge as competitors to the national champions, or whether market concentration is itself politically useful.

    Why do the ingredients of an investment boom not produce one?

    1. The macroeconomic conditions are present: An undervalued exchange rate, depressed real wages and sustained public sector investment in infrastructure are all in place, alongside the demographic dividend.
    2. The same mix powered East Asia: This combination powered the rise of countries such as China and South Korea, where firms responded to it with large capacity additions.
    3. India’s firms are not responding: Firms are likely to remain hesitant and unsure about investing without a change in the approach, despite those conditions.
    4. Confidence, not capability, is binding: Investment decisions are taken only when investors think they have a fair chance of benefiting from them.
    5. The end state if nothing changes: The consequent absence of competition raises the possibility of an uncompetitive, high-cost economy.

    Challenges to the national champions strategy

    1. Concentration raises consumer and input costs: Dominant firms in a sector face little pressure to hold prices down, which raises costs for every downstream user. Eg. Telecom tariffs rose sharply after the sector consolidated into three private operators. Fix. Use the deal value threshold introduced by the Competition (Amendment) Act, 2023 to review acquisitions that current turnover tests miss.
    2. Policy-created advantage is hard to withdraw: Once a group builds capacity on the strength of an incentive, removing the incentive becomes a shock the government is reluctant to deliver. Eg. Most approved incentive under the Production Linked Incentive scheme for large-scale electronics manufacturing has flowed to a small group of mobile phone assemblers. Fix. Publish sunset dates and firm-level disbursement data with each incentive scheme so withdrawal is scheduled rather than negotiated.
    3. Concentrated bank exposure transmits firm risk to the system: Lending concentrated in a few large groups converts a single group’s distress into a banking problem. Eg. The corporate loan losses that produced the non-performing asset build-up of the 2010s were concentrated in a handful of infrastructure and metals groups. Fix. Enforce large exposure limits at group rather than borrower level and publish group-wise banking exposure.
    4. Bidding rules can favour incumbents: Net worth, prior experience and bank guarantee conditions in auctions and tenders can exclude new entrants before price is considered. Eg. Critical mineral block auctions have repeatedly failed for want of qualified bidders. Fix. Set qualification thresholds proportionate to block or contract size and allow consortium bidding for first-time entrants.
    5. Competition enforcement is slow relative to market speed: Investigations concluded years after conduct occurs cannot restore a market that has already tipped. Eg. Appeals against Competition Commission of India orders routinely run for several years before finality. Fix. Fund a dedicated appellate bench for competition matters with statutory disposal timelines.

    Conclusion

    The reluctance of cash-rich Indian firms to invest is being read as a political economy problem rather than a demand or global uncertainty problem. Concentrated political power, an uneven playing field and the fear of being displaced by a national champion together deny new entrants confidence in a 10 to 20 year horizon. Reversing that requires dispersing economic power, which carries political costs the current settlement has no incentive to accept. What remains unresolved is whether market concentration will be treated as a cost to growth or retained as a political asset.

    Industrial Policy and Private Investment in India

    1. What industrial policy does: It is the set of state interventions that shape which industries expand, through licensing, tariffs, incentives, public investment and ownership rules.
    2. The arc since Independence: The Industrial Policy Resolutions of 1948 and 1956 built a mixed economy with reserved public sector schedules, the licensing regime of the 1960s and 1970s restricted private entry, and the New Industrial Policy of 1991 abolished licensing for most sectors.
    3. India’s scale: Manufacturing contributes around 17 per cent of Gross Domestic Product against a 25 per cent target, and India accounts for about 2.8 per cent of global manufacturing output against China’s roughly 29 per cent.
    4. The current gap: Weak domestic private capital formation persists even as foreign investment rises, with cumulative Foreign Direct Investment crossing about $1.14 trillion between April 2000 and December 2025.

    Laws Governing Industry and Competition in India

    1. Industries (Development and Regulation) Act, 1951: The parent law for central regulation of scheduled industries, and the statutory basis of the industrial licensing regime.
    2. Monopolies and Restrictive Trade Practices Act, 1969: Regulated large business houses through asset thresholds to prevent economic concentration, and was repealed after those thresholds were removed post-1991.
    3. Competition Act, 2002: Replaced the 1969 Act, prohibits anti-competitive agreements and abuse of dominance, and establishes the Competition Commission of India to regulate combinations.
    4. Competition (Amendment) Act, 2023: Introduces a deal value threshold for merger review, a settlement and commitment framework, and shorter approval timelines.

    Government Initiatives for Industry and Investment

    1. Make in India (2014): Aims to raise manufacturing’s share of Gross Domestic Product towards 25 per cent, largely through ease of doing business measures.
    2. Production Linked Incentive scheme (2020): Covers 14 sunrise and strategic sectors with outcome-linked financial incentives paid on incremental output.
    3. National Manufacturing Mission: Announced in the 2025-26 Budget, targeting a 25 per cent Gross Domestic Product share and 143 million jobs by 2035, with a focus on solar photovoltaics, electric vehicle batteries, green hydrogen and wind.
    4. National Single Window System: Consolidates central and state clearances into a single application interface for investors.
    5. Invest India: The dedicated investment facilitation agency created after the Foreign Investment Promotion Board was abolished in 2017.

    Challenges in Industrial Policy and Private Investment

    1. Logistics and infrastructure costs: Power, transport and cluster gaps raise the operating cost of a new plant and lengthen its payback period. Eg. Logistics costs remain close to 8 per cent of Gross Domestic Product. Fix. Front-load the National Infrastructure Pipeline in states with the weakest evacuation and port connectivity.
    2. Land acquisition risk: Title complexity and local resistance delay projects long enough to destroy their business case. Eg. The POSCO steel project in Odisha was shelved after prolonged land disputes. Fix. Build titled and pre-cleared land banks with plug-and-play utilities before inviting investment.
    3. Tariff and trade shocks: External trade measures can remove an export market after capacity has been built for it. Eg. The 50 per cent United States tariff imposed in August 2025 hit roughly 55 per cent of India’s United States-bound exports. Fix. Diversify market access through trade agreements and deepen participation in global value chains.
    4. Workforce readiness for Industry 4.0: Adopting automation and artificial intelligence systems requires reskilling at a scale current training capacity cannot deliver. Eg. Only about 4.7 per cent of India’s workforce has formal skill training, against roughly 96 per cent in South Korea. Fix. Fund employer-led reskilling through the re-skilling fund created under the Industrial Relations Code, 2020.
    5. Import dependence in strategic inputs: Heavy reliance on imported electronics, semiconductors and pharmaceutical inputs exposes downstream manufacturers to supply shocks. Eg. Electronics assembly in India depends on imported display and chip components. Fix. Extend performance-linked incentives to component and materials manufacture rather than final assembly alone.

    Matching Previous Year Question

    “[2025, GS3, 15 marks] Discuss the rationale of the Production Linked Incentive (PLI) scheme. What are its achievements? In what way can the functioning and outcomes of the scheme be improved?”
  • What young want, and why creating good jobs is no longer optional

    Why in the News

    Almost 70 per cent of urban job seekers surveyed in Delhi said they were looking for a job that would place them on their ideal career path from the start, instead of settling for any job. The survey covered over 3,000 randomly sampled men and women, 24 years of age on average, living in middle-class residential areas of the capital, and was conducted in the summer of 2023. Their stated career goal was predominantly salaried or formal-sector employment. The Periodic Labour Force Survey (PLFS) for the same year records an urban labour market that cannot supply that goal, with less than 50 per cent of the urban workforce in salaried jobs. A follow-up experiment then exposed a random subset of the same job seekers to real-world job openings and salaries, and re-surveyed them a year later. Correcting their information lowered their expectations and left their aspirations untouched, so the contest is over who adjusts, the young or the labour market.

    What is the Periodic Labour Force Survey (PLFS)?

    1. Purpose: The PLFS is the official household survey that estimates how many people are working, seeking work or outside the labour force, and in what kind of work they are engaged.
    2. Nodal body: The National Sample Survey Office under the Ministry of Statistics and Programme Implementation conducts it and is the principal source of employment estimates in India.
    3. Activity status measures: Usual Status classifies a person by activity over the preceding 365 days, while Current Weekly Status treats a person as unemployed if they did not work even one hour in the reference week.

    What do young urban job seekers actually want from work?

    1. A career path, not a job: Almost 70 per cent said they wanted an opening that put them on their ideal career path from the start rather than any available job, and more men said this than women.
    2. Formal salaried work is the goal: The stated career goal was predominantly salaried or formal-sector employment rather than casual or own-account work.
    3. Women lean harder towards salaried jobs: More women job seekers aspired to salaried positions than men did.
    4. Only 14 per cent of women prefer self-employment: Just 14 per cent of the women interviewed said they would rather work for themselves.
    5. A third of men want to run enterprises: More than a third of the men wanted to start their own businesses.
    6. Public sector preference is a myth: A comparable share of these men and women were looking for private-sector salaried jobs, which cuts against the dominant narrative of a strong preference for government jobs.

    How far does the urban labour market fall short of those preferences?

    1. Salaried work is a minority outcome: Less than 50 per cent of India’s urban workforce holds a salaried job.
    2. It is scarcer still for the young: Merely one in every three employed 24-year-olds holds a salaried job, a lower share than for the workforce as a whole.
    3. Government jobs are a tenth of the market: No more than 10 per cent of the urban workforce is in the public sector or government jobs.
    4. The formal private sector is barely larger: Only about 15 per cent of the urban workforce is in the formal private sector.
    5. Self-employment is the largest single category: Of those working, 40 per cent are self-employed.
    6. Most self-employment is subsistence, not enterprise: An overwhelming majority of these businesses hire no worker at all and report an annual turnover of less than Rs 10 lakh, so the aspiration to build a firm meets a market of one-person shops.

    Why do salary expectations diverge from what these jobs actually pay?

    1. The occupations tested: Respondents were asked what they expected to earn as an accounts keeper, a primary school teacher, a data entry operator, a hospital attendant and an electrician, and each expectation was measured against actual PLFS earnings for the same occupation.
    2. Expectations run up to 40 per cent above reality: Job seekers expect up to 40 per cent higher salary than the earnings the PLFS records for the same work.
    3. Men are the more over-optimistic: Male job seekers expect almost Rs 8,000 more per month than the actual average earnings for these jobs.
    4. The gap widens for salaried work: For salaried jobs specifically, male job seekers expect Rs 8,500 more per month than actual earnings.
    5. The aggregate divergence exceeds 30 per cent: Taken together, salary expectations sit more than 30 per cent above reality, and the skew is sharper still among job seekers below 25 years of age, especially young men.
    6. Information and inexperience explain the gap: A lack of information or outright misinformation about openings and pay, combined with inexperience of the job market, are the two obvious sources of the misalignment.

    What did correcting job seekers’ information change, and what did it leave untouched?

    1. The design: A random subset of the 3,000 job seekers was informed about real-world job opportunities and salaries, and both the informed and the non-informed groups were re-surveyed twelve months later.
    2. Expectations fell: Accurate information significantly dampened labour-market expectations of landing the ideal job, relative to those who were not informed.
    3. Men disengaged first: Men in particular became less likely to report that they were on their ideal career path.
    4. Search effort fell with belief: That disillusionment was accompanied by a decline in men’s job-search intensity.
    5. The two exits from a failed search: As preferred job offers fail to materialise, job seekers adjust expectations downwards and either remain in the same jobs or leave the labour market and enrol at educational institutions.
    6. Aspirations did not move: The answer on whether aspirations changed is a clear no, since these men and women continued to aim for formal-sector jobs or dynamic entrepreneurship a year later, because aspirations are long-term goals and not easily malleable.
    7. High education costs make the expectation rational: Good-quality education is increasingly bought from private institutions at rising cost, so a high expected salary is not only aspirational but necessary to recover that outlay.

    Challenges to the Periodic Labour Force Survey

    1. Informal work is under-captured: Household surveys do not fully record home-based, gig and platform work in a workforce that is about 90 per cent informal. Eg. Delivery and ride-hailing riders working across two aggregators are frequently recorded as ordinary self-employed workers. Fix. Align the activity definitions with International Labour Organization and System of National Accounts practice so multi-job holders, freelancers and platform workers are counted separately.
    2. No skill mapping against job requirements: The survey does not match worker skills to the requirements of available jobs, so structural unemployment cannot be measured from it. Eg. The India Skills Report finding that only about half of graduates are employable has no counterpart in official survey data. Fix. Add a skills and job-requirement module so mismatch is measured rather than inferred.
    3. Rural data has been low frequency: Rural estimates were historically produced only once a year, so rural distress is visible with a long lag. Eg. A monsoon failure that pushes workers back into farm labour shows up only in the following annual round. Fix. Extend high-frequency quarterly or monthly rounds to rural areas rather than confining them to towns.
    4. Urban bias in the high-frequency rounds: The quarterly bulletins have been confined to urban areas, which under-measures the larger rural workforce. Eg. Quarterly urban unemployment rates are debated publicly while comparable rural numbers are unavailable. Fix. Publish a single integrated quarterly series covering both sectors on the same reference period.
    5. New job categories are missing: Gig, digital, start-up and green jobs are not adequately represented in the occupational classification the survey uses. Eg. Solar installation and battery recycling roles have no distinct occupational code. Fix. Integrate Employees’ Provident Fund Organisation, National Career Service and PLFS records so emerging job creation is tracked from administrative data as well.

    Conclusion

    Young urban job seekers want formal salaried careers and dynamic enterprise, and correcting their information about the market lowers what they expect to earn without changing what they want. That asymmetry places the burden of adjustment on the economy rather than on the young, and realising these aspirations requires a structural transformation that creates jobs with regular pay and benefits. The four Labour Codes are a step in that direction, and creating good jobs and genuine career paths, rather than jobs alone, is no longer optional. Failure carries a specific cost, which is the squandered potential of an entire generation.

    Employment and Unemployment in India

    1. What is measured: An unemployed person is of working age, that is 15 years and above, without work, currently available for work and actively seeking it in a reference period.
    2. Structure of the workforce: The Labour Force Participation Rate stood at 59.3 per cent in 2025, about 90 per cent of the workforce is informal, and nearly 58 per cent of salaried workers still lack a written contract.
    3. The absorption problem: Services drive most output growth but employ under 30 per cent of the workforce, while manufacturing contributes only about 16 to 18 per cent of Gross Domestic Product against roughly 26 per cent in China.
    4. Types of unemployment tested: Frictional, structural, cyclical, seasonal, disguised, voluntary and chronic unemployment are distinguished, with disguised unemployment concentrated in agriculture where marginal productivity approaches zero.

    Laws and Rules Governing Employment in India

    1. Code on Wages, 2019: Consolidates four wage laws, sets a statutory floor wage, and extends minimum wage cover beyond the roughly 30 per cent of workers it earlier reached.
    2. Industrial Relations Code, 2020: Merges three laws, raises the closure and retrenchment approval threshold from 100 to 300 workers, and gives fixed-term workers parity and gratuity after one year.
    3. Code on Social Security, 2020: Merges nine laws, defines gig and platform workers for the first time, and requires aggregators to contribute 1 to 2 per cent of turnover to a welfare pool.
    4. Occupational Safety, Health and Working Conditions Code, 2020: Consolidates 13 laws into one licence, one registration and one return, and caps hours at 8 to 12 daily and 48 weekly.
    5. Commencement of the four Codes: All four came into force on 21 November 2025, replacing a fragmented body of central labour legislation.
    6. Mahatma Gandhi National Rural Employment Guarantee Act, 2005: Guarantees 100 days of wage employment per rural household in a financial year.

    Government Initiatives for Employment Generation

    1. PM Viksit Bharat Rozgar Yojana: An employment-linked incentive approved in July 2025 with a Rs 99,446 crore outlay, targeting 3.5 crore jobs over two years.
    2. e-Shram Portal: A national database issuing Universal Account Numbers to unorganised workers and integrating access to more than 14 central schemes.
    3. PM Internship Scheme: Launched in 2024 to offer 1 crore internships in top companies over five years.

    Challenges in Employment Generation in India

    1. Lopsided structural change: India moved from agriculture to services without a job-rich manufacturing phase, so the sector that absorbs low-skilled labour elsewhere never scaled here. Eg. Manufacturing’s share of output has been stuck near 17 per cent against a 25 per cent policy target. Fix. Direct incentives to textiles, leather, food processing and electronics assembly, which absorb low and semi-skilled workers at scale.
    2. Capital-intensive investment bias: Investment flows to information technology and infrastructure rather than to labour-intensive activity, so output growth outruns job growth. Eg. Under the Production Linked Incentive scheme, most disbursed incentive has gone to large scale electronics assembly and pharmaceuticals, both capital intensive lines. Fix. Weight incentive schemes by jobs created per rupee of assistance rather than by output alone.
    3. Firms stay small to avoid compliance: Threshold-linked obligations reward staying under the size limit, which caps productivity and formal hiring. Eg. Micro, small and medium enterprises face more than 1,450 annual compliances costing Rs 13 to 17 lakh. Fix. Extend the Jan Vishwas approach of decriminalising minor compliance offences, which already covered 183 provisions across 42 central Acts.
    4. Skill deficit at both ends: Only about 4.7 per cent of the workforce has formal skill training, against roughly 96 per cent in South Korea, so employers and applicants describe different jobs. Eg. The Annual Status of Education Report 2023 found a quarter of rural youth aged 14 to 18 unable to read a Class 2 text. Fix. Tie curricula to Industry 4.0 and green job roles through mandatory industry-academia apprenticeship linkages.
    5. Women are kept out of paid work: Caregiving, domestic duties and mobility barriers hold female participation far below male participation. Eg. Urban female Labour Force Participation Rate stood at 25.8 per cent against 75.6 per cent for men in 2024. Fix. Enforce creche provision and workplace safety obligations already carried in the Codes.

    Matching Previous Year Question

    “[2023, GS3, 15 marks] Most of the unemployment in India is structural in nature. Examine the methodology adopted to compute unemployment in the country and suggest improvements.”

  • On interest rates, can’t be both dovish & hawkish

    Why in the News

    The Monetary Policy Committee of the Reserve Bank of India (RBI) voted unanimously at its last meeting to hold the benchmark repo rate at 5.25 per cent, in a policy read as more dovish than expected. The minutes of that same meeting, released a few days ago, point the other way. Members drawn from the central bank displayed a distinct hawkishness, and the Bank’s own inflation projections imply negative real interest rates on a forward basis. The divergence is the problem: a stance described as neutral cannot be reconciled with projections that would stimulate activity, nor with a growth assessment the Bank itself calls resilient.

    What is a monetary policy stance?

    1. What it signals: The stance states the direction of the committee’s next expected move on the policy rate. That signal is separate from the rate set on the day.
    2. Accommodative: The committee signals that the next move is a cut, or that liquidity will stay supportive of demand.
    3. Neutral: The committee commits to no direction and keeps both a cut and a hike open at the following meeting.
    4. Tightening or withdrawal of accommodation: The committee signals that the next move is a hike, or the removal of surplus liquidity from the system.

    What is the real interest rate?

    1. Definition: The real interest rate is the nominal policy rate less expected inflation, so it measures what a lender actually earns once prices have risen.
    2. Why the sign matters: A negative real rate makes money cheaper than the rate at which prices are rising, which pushes households and firms toward borrowing and spending.

    What did the last policy decision signal?

    1. The stance retained: The committee kept the stance neutral alongside that hold.
    2. The tone: The policy read as more dovish than many analysts had expected at the time.
    3. The inference drawn: Analysts concluded that rate hikes were not imminent, even with inflation projected above target.

    How do the minutes of the same meeting read differently?

    1. A reversal in signal: The minutes suggest the current situation is unlikely to be maintained over the near term, and the divergence from the policy statement is striking.
    2. The internal members hardened: That hawkishness came from the members drawn from the central bank, not from the committee as a whole.
    3. How far each went: An assessment by economists at the State Bank of India reads the Governor’s minutes statement as showing an inclination toward policy tightening, records a Deputy Governor calling for a possible rate hike later in the year, and notes an Executive Director stopping just short of the same call.
    4. A different objection from outside: External members of the committee drew attention instead to the real interest rate.

    Can a neutral stance sit with negative real interest rates?

    1. The projections: The Bank has pegged inflation at 5.9 per cent in the third quarter, 5.5 per cent in the fourth quarter, and 5.3 per cent in the first quarter of the next financial year.
    2. What they imply: Against a repo rate of 5.25 per cent, those projections put real interest rates in negative territory on a forward basis.
    3. What negative real rates do: They stimulate economic activity, which is a different setting from the stance the committee has adopted.
    4. What neutral is supposed to mean: The Governor has previously stated that a neutral stance implies no support for economic activity and no support for controlling inflation.
    5. The growth assessment compounds it: The Bank describes growth as resilient, supported by domestic demand, sustained expansion in manufacturing and services activity, and robust exports, which removes the case for a stimulative real rate.

    What does the same uncertainty look like at other central banks?

    1. A shared condition: Central banks across the world are grappling with uncertainty over inflation and over the course of monetary policy.
    2. The United States: The Federal Reserve maintained interest rates in July, and the path of policy after that remains unclear.
    3. The same gap between decision and minutes: The minutes of that Federal Reserve meeting record that several participants favoured an increase of 25 basis points in the target range.

    What will decide the next move?

    1. The October meeting: By the time the committee meets next in October, there should be more clarity on agriculture and on the trajectory of inflation.
    2. The projections as the signal: The Bank’s revised inflation projections will show what it expects of underlying price pressures going forward.
    3. The consequence: Those expectations are what would produce an adjustment in the policy rate.

    Challenges to India’s flexible inflation targeting framework

    1. A headline target moved by food: Food and beverages carry close to half the weight in the Consumer Price Index, so the target responds to harvests that no policy rate can influence. Eg. Vegetable price spikes pushed headline inflation above the upper tolerance band in 2023 and 2024. Core inflation stayed subdued through the same period. Fix. Publish an explicit core inflation reference alongside the headline target, so the committee’s tolerance for supply shocks is visible in advance.
    2. An ageing consumption basket: The index in use rests on a consumption pattern captured years ago, so the measured basket drifts from what households actually buy. Eg. Services such as data, health insurance and education are underweighted relative to current household spending. Fix. Fix a statutory revision cycle for the index base year so the measure and the target are reset together.
    3. Exchange rate pressure competes with the target: Rate decisions taken for domestic prices collide with the management of capital flows. Eg. Record foreign portfolio outflows in 2025-26 forced heavy intervention to steady the rupee. Fix. State an explicit order of priority between the inflation target and exchange rate smoothing in the policy statement.
    4. No fiscal counterpart to the target: The framework binds the central bank alone, with no matching commitment on borrowing. Eg. Heavy government borrowing keeps longer tenor yields elevated regardless of where the repo rate is set. Fix. Pair each five year target reset with a stated debt to gross domestic product path under the Fiscal Responsibility and Budget Management Act, 2003.
    5. Accountability stops at a report: A sustained breach obliges a report and nothing further. Eg. The report on a target breach goes to the Central Government and is not laid before Parliament. Fix. Require the report to be tabled in Parliament with a stated corrective path and a review date.

    Conclusion

    A unanimous hold read as dovish now sits alongside minutes that record internal calls for tightening and projections that imply negative real rates. The policy statement, the stance and the projections are describing three different settings, and only one of them can be the policy. The October meeting, with clearer information on agriculture and on the inflation trajectory, is where that inconsistency has to be resolved into either a rate move or a change of stance.

    “[2023] Consider the following statements :

    Statement-I: In the post-pandemic recent past, many Central Banks worldwide had carried out interest rate hikes.

    Statement-II: Central Banks generally assume that they have the ability to counteract the rising consumer prices via monetary policy means.

    Which one of the following is correct in respect of the above statements?

    (a) Both Statement-I and Statement-II are correct and Statement-II is the correct explanation for Statement-I

    (b) Both Statement-I and Statement-II are correct and Statement-II is not the correct explanation for Statement-I

    (c) Statement-I is correct but Statement-II is incorrect

    (d) Statement-I is incorrect but Statement-II is correct

  • Keep UPI free. Fund it from the savings it generates

    Why in the News

    Parliament has passed the Taxation and Other Laws (Amendment) Bill, 2026, rewriting Section 10A of the Payment and Settlement Systems Act, 2007. That section barred any charge on Unified Payments Interface (UPI) and RuPay transactions. The amendment replaces the bar with an enabling provision, letting the government notify in future which payment modes may carry a charge. No charge is imposed today. The tension is that the cost of running UPI is real and the state’s compensating outlay is shrinking. The only fee instrument available for recovering that cost would be levied on the smallest transactions in the economy.

    What is the Merchant Discount Rate?

    1. Definition: The Merchant Discount Rate (MDR) is the percentage of a transaction value that a merchant pays for accepting a digital payment, deducted before the money reaches the merchant’s account.
    2. Card world origin: It is an inheritance from card payments, with the card issuer, the acquiring bank and the network each taking a slice. A physical card, a terminal and credit default risk give the fee something real to recover.

    What has the amendment to Section 10A actually changed?

    1. From prohibition to permission: A statutory bar on charging has been converted into a discretionary power to allow charging on notified modes.
    2. The trigger moves to the executive: Imposing a charge no longer needs Parliament, only a notification.
    3. The status quo is unchanged today: No charge has been imposed on any mode as of the amendment.
    4. Why it still matters: A right protected by statute and a right held at executive discretion are different guarantees for a merchant deciding whether to accept digital payment.

    What has UPI become?

    1. Volume and value: In 2025-26 UPI carried over 24,000 crore transactions, roughly 66 crore a day, worth about ₹314 lakh crore.
    2. Share: It accounts for some 85 per cent of India’s digital retail payments and nearly half of the world’s real time payments.
    3. Ticket size: The average transaction is about ₹1,300, and 86 per cent of merchant payments are below ₹500.
    4. Who transacts: Payments at that size are made to the vegetable seller, the auto driver and the kirana shop, so a charge is a levy on the smallest transactions of the poorest rather than on commerce in the abstract.
    5. What was achieved: No other country has made real time digital payment free, instant and universal, and the transition pulled hundreds of millions of Indians into the formal economy.

    Why is UPI treated as public infrastructure rather than a company’s product?

    1. Most used digital public good: After Aadhaar gave every Indian a digital identity, UPI is the most visible piece of digital public infrastructure, and the citizen reaches for it many times a day rather than once.
    2. A protocol, not a platform: It is an open, protocol based public good, a shared language for money instead of any single firm’s product.
    3. What the protocol did to banking: Before UPI each bank ran its own closed application. UPI asked banks only to open their programming interfaces to a shared protocol, so any application can move money between any two accounts at any two banks.
    4. External validation: The model is being studied and adopted by other countries.

    Why is the Merchant Discount Rate the wrong instrument for UPI?

    1. The recoverable costs do not exist: The point of sale machine is the customer’s own phone, running on data he has already paid for. There is no card, no terminal, no credit risk, and settlement is instant.
    2. The work done test: Telecom interconnection regulation pays a network only for the work it actually performs, and the same test applies to a payment rail.
    3. The work actually performed: When A pays B, A’s bank makes a debit entry, the National Payments Corporation of India (NPCI) issues a settlement instruction, and B’s bank makes a credit entry. No cash moves at any point.
    4. What that work costs: NPCI runs the entire switch for about ₹500 crore a year, which is some two paise a transaction.

    The funding gap is real even where the fee is wrong

    1. Providers earn nothing directly: Banks and payment providers bear real costs, and under zero MDR they receive nothing from a UPI transaction itself.
    2. The bridge is being withdrawn: The government has covered the gap with an incentive, and the outlay is projected to fall to about ₹437 crore from about ₹3,631 crore two years ago.
    3. Traffic is moving the other way: The volume the incentive supports is multiplying and the incentive itself is shrinking. The shortfall widens each year without any policy decision being taken.

    Who actually captures the savings digitisation creates?

    1. Currency printing: The Reserve Bank spends some ₹5,000 crore to ₹6,400 crore a year merely printing currency notes, which is more than the government spends keeping UPI free, before storage and movement of cash is counted.
    2. Channel cost at the bank: A counter transaction costs a bank ₹40 to ₹50 and an automated teller machine (ATM) withdrawal costs ₹19 in interchange alone. A UPI transaction costs a small fraction of either.
    3. The float: By making an account as usable as cash, UPI keeps money in accounts rather than idle in pockets, and that low cost float is what banks earn a spread on and lend against.
    4. The mismatch: The beneficiary of digitisation is the state and the bank, and the party a merchant fee would tax is the merchant, so the instrument does not follow the benefit.

    What would a Merchant Discount Rate cost the transition?

    1. Price sensitivity: India is intensely price sensitive, and a digital payment costing even a rupee more than cash sends many users back to cash.
    2. Pass through at the counter: A merchant charged MDR passes it on as a stated surcharge for digital, or refuses digital payment altogether.
    3. Scale of the extraction: Even 0.3 per cent on merchant payments would take some ₹27,000 crore a year out of a thin margin retail economy.
    4. Reversal risk: Telling a hundred crore users that what was always free now costs money is the surest way to slow, and even reverse, a transition still forming, collecting a little and losing a great deal.
    5. A large merchant carve out will not hold: Confining the charge to large merchants offers no lasting protection, because thresholds slip and definitions widen.

    What funding model could cover the cost without charging the user?

    1. Return a share of the savings: The state, as steward of the public good and no longer obliged to print and move the cash UPI displaces, should return a small, defined share of its savings to those who run the rails.
    2. Formula, not discretion: The support should be transparent and formula based, funded specifically from savings in currency management.
    3. Not a subsidy: It is payment for value delivered, on the same principle by which the state pays a transmission company to carry electricity.
    4. The price stays off the citizen: The design keeps the charge out of sight of the user, so no price tag ever appears in front of the person paying.

    Challenges to keeping UPI free

    1. The support is a Budget line, not an entitlement: An annual allocation can be cut without any change in law, so the guarantee is only as durable as one fiscal year. Eg. The incentive allocation has been cut sharply across two consecutive Budgets. Fix. Convert the support into a formula linked to measured currency management savings, so the amount tracks the service rather than the fiscal cycle.
    2. Two applications carry most of the volume: Concentration lets a handful of private applications set the terms of access for banks and merchants. Eg. Two private applications account for roughly 80 per cent of UPI volume, and the market share cap on them has been deferred repeatedly. Fix. Fund interoperable merchant acquisition through smaller banks and the Bharat Interface for Money application to widen the base.
    3. Charged rails already run beside the free ones: Credit products routed over the same interface carry a fee, so the free character of the system is already partial. Eg. From June 2026 a merchant discount rate applies to large value RuPay credit on UPI transactions. Fix. Publish a single schedule stating exactly which flows carry a charge, so a merchant sees the boundary before accepting a payment.
    4. Fraud losses sit outside the pricing debate: The system’s real cost includes reimbursing victims, which no fee structure currently funds. Eg. Digital payment fraud losses have crossed ₹22,000 crore. Fix. Build a lagged credit window for high risk first time transfers, so a fraudulent transfer can be reversed before withdrawal.
    5. Downtime carries no consequence: Bank side outages take users off the network at peak hours with no compensation obligation. Eg. Server downtime at major banks has repeatedly disrupted time sensitive payments. Fix. Set a published per bank uptime standard with penalties credited directly to affected users.

    Conclusion

    The statutory prohibition on charging for UPI is gone and the power to permit a charge now sits with the executive, even though no charge exists today. The cost of running the rails is genuine and the compensating outlay is falling, so the funding question cannot be deferred much longer. The unresolved choice is between recovering that cost from the merchant, which taxes the smallest transactions and risks reversing adoption, and recovering it from the currency management savings the state already books because UPI exists.

    “[2018] Which one of the following best describes the term “Merchant Discount Rate” sometimes seen in news?

    (a) The incentive given by a bank to a merchant for accepting payments through debit cards pertaining to that bank.

    (b) The amount paid back by banks to their customers when they use debit cards for financial transactions for purchasing goods or services.

    (c) The charge to a merchant by a bank for accepting payments from his customers through the bank’s debit cards.

    (d) The incentive given by the Government to merchants for promoting digital payments by their customers through Point of Sale (PoS) machines and debit cards.

  • FDI policy rejig for border nations spur Rs 5k cr investment: DPIIT

    Why in the News

    A relaxation in India’s rules on investment from land bordering countries has drawn 29 foreign direct investment (FDI) proposals worth ₹4,895.65 crore up to 20 August 2026. The relaxation was notified in March 2026. It permits a foreign entity carrying non controlling beneficial ownership of up to 10 per cent from a land bordering country to invest through the automatic route. Press Note 3 of 2020 had required prior government approval for any such investment, however small that land border shareholding was. What is now tested is whether a shareholding threshold can separate incidental Chinese exposure inside a global fund from Chinese strategic control of an Indian asset.

    What is Press Note 3 of 2020?

    1. The restriction: Imposed in April 2020, it made government approval mandatory for investment from any country sharing a land border with India.
    2. Stated purpose: It was aimed at preventing opportunistic takeovers of Indian firms during the Covid-19 pandemic, and stayed in force amid heightened national security concerns after the Galwan clash later that year.
    3. Country neutral drafting: The framework named no country, and China is the largest source of investment among India’s land neighbours.
    4. Uneven bite: Entities of Bangladesh and Pakistan can invest only through the government route. Flows from Nepal, Myanmar, Bhutan and Afghanistan are very small as a share of India’s total foreign investment.

    What conditions does the relaxed route carry?

    1. Indian control retained: The majority shareholding and control of the investee entity must rest at all times with resident Indian citizens, or with resident Indian entities that are themselves owned and controlled by resident Indian citizens.
    2. Threshold is a ceiling, not a waiver: A land border holding above 10 per cent still routes the investment through government approval, so the automatic route covers only diluted exposure.
    3. Time bound clearance for named goods: A 60 day deadline was approved for clearing proposals from land bordering countries, including China, in capital goods, electronic capital goods, electronic components, polysilicon, and ingot wafer for solar cells.

    Where has the relaxed route drawn money from?

    1. Sectors: The proposals span information technology, artificial intelligence, information and communication, manufacturing, pharmaceuticals, data centres and transport services.
    2. Jurisdictions: They were reported by investors and entities based in Mauritius, the United States, the Republic of Korea, Japan, Singapore, Luxembourg and the Cayman Islands, among others.
    3. Stated gain: The government’s own assessment is that the reform gives investors greater certainty, cuts transaction time and strengthens ease of doing business in India.

    Where has the Centre gone further than the ownership threshold?

    1. A strategic sector joint venture: In July 2026 the Centre cleared a joint venture between Dixon Technologies (India) Limited and Vivo Mobile India Limited for manufacturing electronic devices and smartphones, one of the first major approvals to Chinese investment in a strategic sector.
    2. Entry into power tenders: The Finance Ministry in July allowed four Chinese power equipment manufacturers with factories in India to bid for government tenders on critical power projects.
    3. A procurement exemption: TBEA Energy, Nanjing Electric India, New Northeast Electric India and Taikai Electric (India) were exempted from the public procurement rule requiring entities from land bordering countries to register with the relevant Indian authority before bidding.
    4. What is at stake in that equipment: The four firms make transformers, wires, high voltage switchgear and gas insulated switchgear used in transmission lines. New Northeast Electric India lists at least 11 transmission line projects across India.

    Challenges to the revised land border investment framework

    1. Beneficial ownership is hard to trace through layers: A 10 per cent test presumes the ultimate holder is visible, which layered holding structures defeat. Eg. Several of the reported proposals came through Mauritius and the Cayman Islands. The ultimate holder is not on the local register in either jurisdiction. Fix. Require a declaration of the ultimate beneficial owner at every layer, verified against the significant beneficial ownership register maintained under the Companies Act, 2013.
    2. A shareholding cap does not bound influence: Control travels through contracts as much as through equity. Eg. A minority holder with board nomination rights or a sole technology licence can direct a joint venture without owning a majority. Fix. Test control by board composition and contractual veto rights, not by shareholding percentage alone.
    3. Screening capacity is spread thin: No single body owns the security review of an inbound proposal. Eg. Screening runs across the Department for Promotion of Industry and Internal Trade, the Ministry of Home Affairs and the administrative ministry, each with its own timeline. Fix. Constitute a standing inbound investment security review committee with a statutory disposal deadline.
    4. Technology dependence persists in the sectors being opened: Approval eases entry without changing who owns the process knowledge. Eg. India imports most of its polysilicon and ingot wafer requirement for solar cells. Fix. Tie approval in those goods to a phased technology transfer and a rising domestic sourcing commitment.
    5. The government route stays slow for everyone else: Only the notified goods got a deadline, so other proposals still face open ended review. Eg. Land border proposals outside the notified list have historically taken well over a year to clear. Fix. Extend the 60 day discipline to every proposal on the government route, with reasons recorded for any extension.

    Conclusion

    The relaxed framework has been operative since March 2026 and has produced 29 reported proposals in five months. Press Note 3 itself stays on the books for any land border holding above the threshold, so the restriction has been narrowed rather than withdrawn. The next milestone is disposal of proposals under the 60 day window for the notified goods, and whether the Dixon and Vivo clearance becomes a template for a wider, sector by sector opening.

    Foreign Direct Investment in India

    1. About: Foreign direct investment is cross border investment that establishes a lasting interest in an enterprise abroad, in the definition used by the Organisation for Economic Cooperation and Development.
    2. Routes: Most sectors permit 100 per cent foreign investment through the automatic route, and the remainder require prior government approval.
    3. Cumulative scale: India’s cumulative inflows crossed about $1.14 trillion between April 2000 and December 2025, with nearly 70 per cent of that arriving in the last decade.
    4. Recent flows: Gross inflows reached a three year high of $81 billion in 2024-25, led by services and manufacturing.

    Laws and Rules Governing Foreign Investment

    1. Foreign Exchange Management Act, 1999: The parent statute governing cross border transactions and capital account flows into and out of India.
    2. Foreign Exchange Management (Non-debt Instruments) Rules, 2019: Notified by the Finance Ministry, these fix sectoral caps, entry routes and pricing guidelines for equity investment.
    3. Consolidated FDI Policy Circular: A single compiled statement of sectoral policy, which Press Notes amend between editions.
    4. Competition Act, 2002: Acquisitions above notified thresholds need Competition Commission of India clearance.

    Challenges in Attracting Foreign Direct Investment

    1. Policy unpredictability: Rules that change mid cycle force investors to restructure entities already built. Eg. Repeated shifts in e-commerce foreign investment norms forced marketplace operators to redraw their seller structures. Fix. Publish a standstill period between the notification of a sectoral rule change and its taking effect.
    2. Land acquisition: Site control is the binding constraint on greenfield manufacturing. Eg. POSCO abandoned its Odisha steel project after a decade of unresolved land disputes. Fix. Build titled, pre cleared land banks held by state industrial corporations and offered on long lease.
    3. Geographic concentration: Inflows cluster in services and a few urban states. Eg. A handful of states absorb the bulk of equity inflows reported each year. Fix. Offer differential incentives for greenfield investment in aspirational districts.
    4. Intellectual property enforcement: Weak enforcement raises the risk premium on technology intensive investment. Eg. India remains on the United States Priority Watch List on intellectual property enforcement. Fix. Create dedicated commercial intellectual property benches with fixed disposal timelines.
    5. Clearance friction across governments: A central approval does not deliver the state permissions a project actually needs. Eg. The National Single Window System still does not carry every state level clearance. Fix. Make full state onboarding to the single window a condition for central infrastructure co-funding.

    Back2Basics: Department for Promotion of Industry and Internal Trade

    1. Parent ministry: It sits under the Ministry of Commerce and Industry. It was the Department of Industrial Policy and Promotion until internal trade was added in 2019.
    2. Policy mandate: It frames and administers the Consolidated FDI Policy and issues the Press Notes that amend it.
    3. Programmes run: It runs Startup India and Make in India, and maintains the National Single Window System.

    “[2020] With reference to Foreign Direct Investment in India, which one of the following is considered its major characteristic?

    (a) It is the investment through capital instruments essentially in a listed company.

    (b) It is a largely non-debt creating capital flow.

    (c) It is the investment which involves debt-servicing.

    (d) It is the investment made by foreign institutional investors in the Government securities.

  • Centre notifies key scheme to manufacture mobile phones

    Why in the News

    The Ministry of Electronics and Information Technology (MeitY) has notified the Mobile Phone Manufacturing Scheme (MPMS), a ₹62,500 crore programme incentivising domestic assembly of smartphones and greater local value addition. The Union Cabinet approved the scheme on 15 July 2026. It succeeds the Production Linked Incentive Scheme for Large Scale Electronics Manufacturing, which ran from 2020 to the last financial year and rewarded incremental handset output from any qualifying firm. The new scheme splits that single track in two, creating a separate and richer channel for brands owned by Indian citizens and holding their intellectual property in India. What is contested is whether incentive design alone can move India from assembling other countries’ brands to owning its own.

    Components of the Mobile Phone Manufacturing Scheme

    1. Two parts: The notification divides the scheme in two, one part incentivising mobile phone manufacturing and one part supporting Indian mobile phone brands.
    2. Part 1, the assembly incentive: A base incentive on assembly tapers from 2.75 per cent to 2.25 per cent across the five year tenure. Applicable rates run from 2.25 per cent to 5 per cent depending on the year and on incremental sales.
    3. The domestic sourcing add on: An additional 1.5 per cent is payable on domestic component sourcing, built up from individual component incentives ranging from 0.2 per cent to 0.5 per cent.
    4. Part 2, the Indian brand track: An Indian owned brand draws a flat 5 per cent incentive for the full tenure, plus a domestic design and research and development incentive of 3 per cent.

    How does a firm actually earn the incentive?

    1. Turnover gate: Mobile phone companies, including electronics contract manufacturers, need a turnover of ₹10,000 crore in 2025-26 to qualify. Electronics manufacturing services firms with 51 per cent Indian ownership qualify at ₹1,000 crore.
    2. Growth gate: Incentives are disbursed only on sales beyond 115 per cent of the previous financial year’s production. A unit that produced ₹10 crore worth of phones in the preceding year and ₹12 crore in the next draws incentive on ₹50 lakh alone.
    3. Sourcing condition: The 1.5 per cent additional incentive applies only where a firm sources domestically for at least a quarter of the phones it sells in that financial year.
    4. No earmarking: The corpus is fungible overall, so no amount is reserved for domestic players. Foreign phonemakers face a higher bar to draw incentive, and they draw it from the same pool.

    What does the scheme change for Indian brands?

    1. Ownership test: An Indian brand must be majority owned by Indian citizens and incorporated in India, with intellectual property and trademarks held locally.
    2. No sales floor: Indian brands are exempt from the minimum sales threshold that applies to other brands, and their baseline is fixed at 2025-26.
    3. Stated intent: The Union Minister for Electronics and Information Technology framed the shift as one of Indian brand, Indian design and Indian intellectual property.
    4. Discretionary channel: An empowered committee will make recommendations to the government on Indian brand applications for incremental incentives and for non fiscal support.

    What has the assembly led phase achieved, and where has it stopped?

    1. Import to export: Around 70 per cent to 75 per cent of phones sold in India were imports in 2014-15, and the country is now an exporter of finished handsets.
    2. Global position: India is the second largest phone manufacturer in the world, and practically all phones sold in the country are made in it.
    3. Shallow value: Domestic value addition in mobile phone manufacturing stands at 23 per cent, so most of the value in an Indian assembled handset is still created abroad.
    4. A ceiling exists: The benchmark set by Chinese phone assembly units is itself bounded, because components in electronics value chains crisscross the globe several times before a device is finished.

    What does the scheme set out to achieve by 2030-31?

    1. Production: Cumulative production, measured as the combined sale value of finished products, is targeted at ₹39 lakh crore by the end of the scheme.
    2. Exports: Cumulative exports over the same period are targeted at ₹5 lakh crore.
    3. Value addition: The stated goal is to double overall domestic value addition from a band of 18 per cent to 23 per cent up to a band of 35 per cent to 40 per cent.
    4. Employment: The Secretary of the Ministry of Electronics and Information Technology put direct job creation under the scheme at 60,000.

    Why does the government treat phone assembly as a gateway sector?

    1. Skill and technology spillover: Technology and skill transfer from handset lines is stated to enable adjacent hardware production, in laptops, tablets and smart watches.
    2. New device categories: The same capability base is expected to carry into gaming consoles, drone manufacturing and medical devices.
    3. Beyond electronics: Components and automobile windshields are named as further beneficiaries of the manufacturing ecosystem the sector builds.

    Challenges to the Mobile Phone Manufacturing Scheme

    1. Incentive concentrates in a few assemblers: A single fungible pool rewards volume, and volume already sits with a small set of contract manufacturers. Eg. Under the earlier electronics scheme, most disbursed incentive flowed to a handful of contract assemblers serving Apple and Samsung. Fix. Ring fence a defined tranche of the corpus for the Indian brand track instead of leaving the whole corpus open to competition.
    2. The turnover gate excludes the firms the scheme names: A ₹1,000 crore revenue floor sits above what the surviving Indian handset brands turn over. Eg. Micromax and Lava operate at a fraction of the revenue of the contract assemblers they would compete with for the same pool. Fix. Add a staged eligibility ladder with a lower entry threshold and a rising production commitment.
    3. The sourcing bonus has a thin supplier base to draw on: Displays, camera modules and application processors are not made in India at scale. Eg. Display panels and camera modules for handsets assembled in India are imported largely from China, South Korea and Vietnam. Fix. Sequence disbursement under the Electronics Component Manufacturing Scheme ahead of assembly incentive, so a supplier base exists before the bonus is claimed.
    4. A demand slump erases a year’s eligibility: Incentive accrues only above a fixed growth threshold over the prior year, so a flat year pays nothing. Eg. Covid disruption in 2020-21 left applicants under the earlier electronics scheme unable to meet their first year incremental production targets. Fix. Allow an unmet incremental target to be carried into the following year within the same tenure.
    5. Locally held intellectual property can be bought rather than built: The Indian brand test rests on registered ownership, which an assignment satisfies without design capability moving to India. Eg. Contract design houses in Shenzhen supply reference designs that brands across Asia rebadge as their own. Fix. Tie the design and research incentive to audited domestic engineering headcount and to patents filed from India.

    Conclusion

    The Mobile Phone Manufacturing Scheme has moved from Cabinet approval to notification, with operational guidelines issued on 21 August 2026 and a tenure running to 2030-31. The next milestone is the application round. Assemblers file against the turnover gate. Indian brands file separately for the brand track. Whether the second track becomes a genuine channel or a minority claim on a shared pool will be visible in the empowered committee’s first set of recommendations.

    “[2025, GS3, 15 marks] Discuss the rationale of the Production Linked Incentive (PLI) scheme. What are its achievements? In what way can the functioning and outcomes of the scheme be improved?”

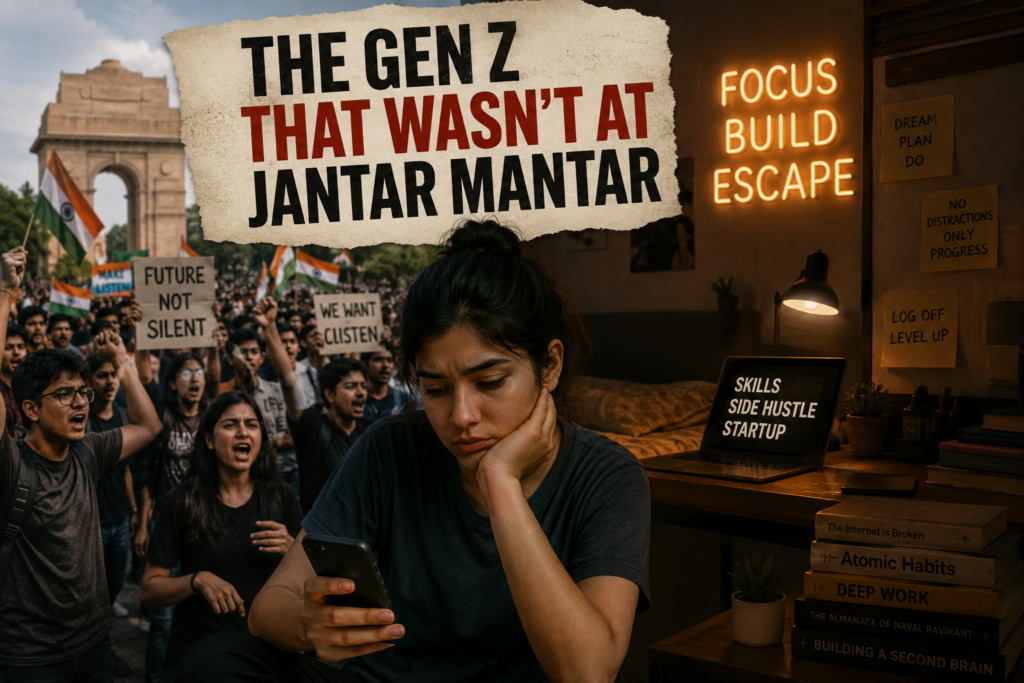
  • The Gen Z that wasn’t at Jantar Mantar

    Why in the News

    The Gen Z visible at the Jantar Mantar protest was young, articulate and quotable, and drew wide attention online. A far larger part of the same cohort was absent from those photographs, working as delivery riders, security guards, warehouse packers and unemployed graduates. The gap between the two groups sets up the question of whether a generation that has been given aspiration has also been given the means to act on it.

    What is the demographic dividend?

    1. The concept: A demographic dividend is the growth advantage a country gains when the share of its working age population rises relative to its dependent population. The advantage arises from a temporary shift in age structure, not from population size.
    2. Why it is conditional: The advantage converts into output only where the additional working age population is employed at rising productivity. Absent that, a larger workforce raises the number of job seekers without raising income.
    3. How India has used the term: For two decades the demographic dividend has been described as an asset that pays out automatically. A young population is better understood as capital advanced against a future that has to be built to repay it, and unlike a dividend, it can default.

    What is a reference group?

    1. The concept: A reference group is the set of people against whom an individual measures their own life, as set out by sociologist Robert Merton. Satisfaction depends on the comparison, not on the absolute level of income.
    2. What changed the group: A farmhand can now compare himself with a Dubai apartment or a weekend in Silicon Valley, delivered more reliably than a crop forecast.

    What is the capacity to aspire?

    1. The concept: The capacity to aspire, as framed by anthropologist Arjun Appadurai, is not merely wanting a different future. It is knowing the routes that lead to it.
    2. The asymmetry it exposes: The capacity to imagine has been democratised at internet speed. The capacity to navigate has not.

    What is the gig or platform economy?

    1. The arrangement: Work is allocated by a digital platform on a task by task basis, and the worker is classified as an independent partner rather than an employee. The platform can deactivate a worker without ever meeting him.
    2. What it prices: The platform prices risk more precisely than labour, so incentives rise when it rains rather than when skill accumulates.

    Which Gen Z was absent from the protest?

    1. The delivery rider: A 22 year old delivering dinner to someone watching the protest on a phone, financing a motorcycle on debt he does not fully understand.
    2. The security guard: A worker stationed outside a building, protecting a lifestyle he can see but cannot enter.
    3. The village youth: A young man who can watch a Stanford lecture for free and has no idea what job he will do next year, whose imagination has migrated while his life chances have not.
    4. The three the category quietly merges: A liberal arts student in Delhi, a warehouse packer outside Gurugram and a UPSC aspirant in Bihar are treated as one cohort because they were born within the same 15 years.
    5. What they actually share: They share visibility without access, not a common set of opportunities.

    Why has inequality become harder to bear without becoming larger?

    1. The level is not the change: India has never lacked inequality. What has changed is the technology of experiencing it.
    2. Comparison is no longer rationed: The farmer knew the landlord lived better. He did not begin breakfast watching the landlord’s holiday in the Maldives.
    3. The comparison set is now global: The smartphone has given a young population the entire planet to measure itself against.
    4. Consumption has become identity: The sneaker, the café and the start up vocabulary function as signifiers of having arrived rather than as possessions.
    5. The mismatch of speeds: Desire now travels at the speed of a 5G network. Social mobility still moves at the pace of a passenger train.

    Why does the platform economy break the link between work and status?

    1. The old bargain was legible: Selling labour converted time into standing over a working life, through tenure, wage progression and recognised skill.
    2. The mechanism was removed, not replaced: The platform economy dropped that conversion and substituted the vocabulary of entrepreneurship for it.
    3. Hours convert into more hours: A worker classified as a partner finds that additional hours produce additional hours rather than advancement, described as autonomy.
    4. Deactivation replaces dismissal: Loss of livelihood arrives as an algorithmic status change, without a hearing, a notice period or an identified decision maker.
    5. The scaffolding is missing: Aspiration has been mass produced without the institutions that let a person act on it.

    If a salary cannot deliver status, what does?

    1. A second economy opens: When the economic route to status narrows, an economy of dignity opens in its place.
    2. The substitutes on offer: Religion, nationalism, caste and an online tribe can supply the standing a salary does not.
    3. The switching cost is near zero: A young man cannot change his salary. He can change his avatar.
    4. The consequence for politics: A society that cannot offer its young enough ladders should not be surprised when identity begins to function as one.
    5. What the protest actually demonstrated: The protesters possessed something rarer than anger, which is a vocabulary for it. Most anger never reaches that stage.

    Why should the demographic dividend be read as a loan rather than a payout?

    1. A dividend is unconditional, a loan is not: Treating youth as an asset that pays out automatically removes the obligation to build the employment and training system that repays it.
    2. The default condition is identifiable: Loans default when the future they were advanced against is not built, which in this case means a labour market that cannot absorb the graduates it produces.
    3. The window is finite: The favourable age structure lasts for a fixed period, after which the dependency ratio rises again and the opportunity closes.
    4. The test is not happiness: The operative question is whether a generation believes the future is negotiable, not whether it reports itself content.
    5. The distinction that matters: Every generation tolerates hardship that looks like a corridor. The trouble begins when it starts looking like a closed room.
    6. The unfinished journey: The protesters had travelled from disappointment to language and from anger to demand. Millions of their contemporaries are still between the first two.

    Challenges to realising India’s demographic dividend

    1. Employability lags enrolment: Degree attainment has risen faster than the skills employers price, so unemployment rises with education level rather than falling. Eg. Urban youth unemployment in the 15 to 29 age group stood at 13.6% even as the overall unemployment rate stayed at 3.1%.
    2. The workforce is concentrated in low productivity work: A large share of workers remains in self employment and casual labour, where earnings do not accumulate into savings or standing. Eg. Self employment accounted for 56.2% of employment and casual labour for 20.2%.
    3. Agriculture holds labour it cannot pay for: The sector employs a share of the workforce far above its contribution to output, which caps rural incomes. Eg. Agriculture employs about 43% of the workforce and contributes around 15% to 16% of output.
    4. Female participation limits the size of the dividend: A dividend calculated on the working age population is not realised where half of it stays outside the labour force. Eg. Female labour force participation stood at 40.0% against 79.1% for men.
    5. Social security does not follow the worker: Platform and informal workers move between employers and locations faster than benefit entitlements can be established. Eg. Portable benefits for gig workers were introduced only through the e-Shram linkage under the four labour codes effective 21 November 2025.
    6. The dividend is unevenly distributed across States: States that completed the demographic transition earlier are ageing while the working age surge continues elsewhere, so the labour surplus and the job supply sit in different places. Eg. Kerala’s multidimensional poverty rate of 0.55% sits alongside Bihar’s 33.76%, and the two States are at opposite ends of the age structure.
    7. Aspiration outruns the migration corridor: Young workers who move for work enter cities without housing, portable schooling or urban welfare registration. Eg. Migrant workers were excluded from ration entitlements outside their home State until One Nation One Ration Card portability was rolled out.

    Conclusion

    The visible Gen Z at Jantar Mantar had converted disappointment into a demand, and that conversion is what made it photographable. The larger part of the cohort holds the same grievance without the vocabulary or the platform to state it, which is why absence rather than presence is the more accurate measure of the generation. The demographic dividend framing has obscured this by treating a young population as a payout rather than as a claim that must be earned. What remains unaddressed is the machinery that converts aspiration into mobility, namely employable skills, formal jobs and portable social protection.

    What is Inclusive Growth?

    1. About: Inclusive growth is economic growth that raises the incomes and capabilities of every group in the population, not only aggregate output.
    2. Rationale: It exists because headline growth can rise while the bottom half of the distribution gains little, leaving poverty, unemployment and inequality intact alongside a rising gross domestic product.
    3. The three domains it is studied across: Overall inequality, poverty, and unemployment.
    4. The three dimensions in the framework of the Organisation for Economic Co-operation and Development (OECD):
    5. Participation: All groups are able to contribute to the growth process.
    6. Benefit sharing: All groups gain from growth in proportion to their contribution.
    7. Equity: Historical disadvantages are actively redressed through policy.
    8. Where it entered Indian planning: The Eleventh Five Year Plan (2007 to 2012) was titled “Rapid and More Inclusive Growth” and the Twelfth Five Year Plan (2012 to 2017) was titled “Faster, Sustainable, and More Inclusive Growth”.

    Key Concerns Regarding Inclusive Growth

    1. Trickle down has not operated: Headline expansion in gross domestic product has not translated into proportionate gains for the bottom half of the distribution.
    2. Growth has been jobless in composition: High informal employment shares and structural underemployment persist alongside robust manufacturing and services output.
    3. Regional disparity accumulates: Gains concentrate within urban clusters and industrialised States, widening per capita income divergence across regions.
    4. Redistribution capacity is weak: The effective tax burden on ultra high net worth individuals is often lower than on middle income households, which limits the fiscal space for welfare intervention.
    5. Wealth inequality compounds across generations: Wealth transfers through inheritance in a way income does not, so the wealth distribution is more concentrated than the income distribution and stays that way.
    6. Group based exclusion cuts across income: Gender, caste, region and rural or urban location each produce separate deprivation patterns that an income only measure does not capture.

    Key Facts about India’s Youth and Labour Market

    1. Labour force participation: The labour force participation rate stands at 59.3%, with 79.1% for men and 40.0% for women.
    2. Worker population ratio: The worker population ratio stands at 57.4%, with 76.6% for men and 38.8% for women.
    3. Unemployment: The overall unemployment rate is 3.1%, at 2.4% in rural areas and 4.8% in urban areas.
    4. Youth unemployment: Unemployment in the 15 to 29 age group is 9.9%, down from 10.3% in 2024, with urban youth unemployment at 13.6% against 14.3% earlier.
    5. Employment composition: Self employment accounts for 56.2%, casual labour for 20.2% and regular wage or salaried employment for 23.6%.
    6. Income concentration: The top 10% capture 58% of national income and the bottom 50% earn 15%, per the World Inequality Report 2026.
    7. Wealth concentration: The top 10% hold 65% of national wealth and the top 1% alone holds 40%.
    8. Human development: India ranked 130 of 193 on the Human Development Index with a value of 0.685, and inequality erases 30.7% of that value, bringing the Inequality adjusted Human Development Index to 0.475.
    9. Multidimensional poverty: The national multidimensional poverty headcount fell from 29.17% in 2013-14 to 11.28% in 2022-23, with 24.82 crore people moving out of multidimensional poverty.

    Laws and Rules Governing Gig and Platform Work in India

    1. Code on Social Security, 2020: Provides the first statutory definition of a gig worker and a platform worker in Indian law and empowers the Centre to frame welfare schemes for them.
    2. It provides for an aggregator contribution towards a social security fund, set as a share of the aggregator’s annual turnover subject to a ceiling linked to payments made to workers.
    3. The four labour codes, effective 21 November 2025: Consolidate the earlier labour statutes and introduce a universal minimum wage floor, extend social security to gig workers and provide portable benefits through the e-Shram registry.
    4. Rajasthan Platform Based Gig Workers (Registration and Welfare) Act, 2023: The first State law dedicated to platform workers, providing for a welfare board, mandatory registration of workers and aggregators and a welfare fee levied on transactions.
    5. Karnataka platform based gig workers welfare law, 2025: Establishes a welfare board and a transaction level welfare fee, and provides for notice and a reasoned order before a worker is terminated from a platform.
    6. Unorganised Workers’ Social Security Act, 2008: The earlier framework for welfare schemes for unorganised sector workers, operating through National and State Social Security Boards.

    Government Initiatives for Youth Employment and Skilling

    1. Pradhan Mantri Kaushal Vikas Yojana 4.0 (2022 to 2026): The flagship short term skilling scheme, under which 1.4 crore youth have been trained.
    2. National Apprenticeship Promotion Scheme: Supports stipend linked apprenticeships in establishments, with over 10 lakh registered apprentices.
    3. e-Shram: The national database of unorganised and platform workers, used as the registry through which portable social security benefits are delivered.
    4. Pradhan Mantri Mudra Yojana: Provides collateral free credit to micro enterprises, with disbursement across 43 crore loans since 2015, largely to micro entrepreneurs and women.
    5. PM SVANidhi: Provides working capital loans to street vendors, with 68 lakh loans disbursed.
    6. Viksit Bharat Gramin Rozgar Adhiniyam, 2025: Replaces the earlier rural employment guarantee with a 125 day wage guarantee together with skill and livelihood diversification components, effective 1 July 2026.
    7. Pradhan Mantri Jan Dhan Yojana: Provides the basic banking access on which wage, benefit and credit delivery to young and informal workers rests, with 58.63 crore accounts.

    Challenges in Achieving Inclusive Growth in India

    1. The informal economy absorbs most new entrants: Job creation happens largely outside registered enterprises, where wages, hours and safety are unenforced. Eg. Around 56% to 57% of workers remain self employed rather than in wage employment.
    2. Regional divergence is widening rather than closing: Poorer States add the most working age population while investment concentrates in already industrialised States. Eg. Bihar records a multidimensional poverty headcount of 33.76% and Jharkhand 28.81%, against Kerala at 0.55%.
    3. The rural and urban gap persists in deprivation, not only income: Access to health, schooling and sanitation remains structurally weaker in rural areas. Eg. Rural multidimensional poverty stands at 15.96% against urban at 5.27%.
    4. Caste concentrates assets independently of policy: Ownership of productive wealth remains skewed towards groups that already held it. Eg. Upper castes, at just over a quarter of the population, control 88.4% of billionaire wealth and own nearly 55% of total wealth.
    5. Women’s work is undercounted and underpaid: Unpaid care work keeps women out of measured employment and depresses earnings when they enter it. Eg. Women earn about 61% of men’s hourly earnings excluding unpaid work, and only 32% when unpaid work is included.
    6. The tax system does not redistribute at the top: Low effective tax burdens on the very wealthy constrain the fiscal room for public services that would raise mobility. Eg. The World Inequality Report 2026 finds the effective tax burden on the very wealthy often lower than on middle income households.
    7. Human development trails income growth: Gains in output have not translated into proportionate gains in health, education and gender outcomes. Eg. India’s Gender Inequality Index value is 0.403 with a rank of 102, and the country falls in Group 5 on the Gender Development Index.

    Way Forward

    1. Tie skilling to placement outcomes rather than enrolment counts: Fund training providers on verified employment retention at six and twelve months instead of on numbers trained.
    2. Extend the platform worker welfare model nationally: Convert the State level transaction fee and welfare board design into a uniform national mechanism under the Code on Social Security, 2020 so benefits do not stop at a State border.
    3. Make social protection portable by default: Link e-Shram registration to health, accident and pension entitlements that travel with the worker across employers, platforms and States.
    4. Create a formal job track in labour intensive manufacturing and construction: Direct incentives towards sectors that absorb workers with school level education, rather than towards capital intensive sectors that add output without adding jobs.
    5. Raise female labour force participation through care infrastructure: Expand crèche provision, safe transport and hostel capacity, which are the binding constraints on entry rather than willingness to work.
    6. Publish district level youth employment data: Report youth unemployment and employment composition at the district level so the mismatch between where young workers live and where jobs are created becomes visible to planners.
    7. Strengthen redistribution at the top of the distribution: Widen the base for capital and inheritance related taxation to fund the education, health and urban services that determine mobility.

    “[2014, GS3, 12.5] “While we flaunt India’s demographic dividend, we ignore the dropping rates of employ ability.” What are we missing while doing so? Where will the jobs that India desperately needs come from? Explain”

  • RWAs a barrier, Govt may let high-income households compile own spending data

    Why in the News

    The Ministry of Statistics and Programme Implementation (MoSPI) is considering a separate diary based method of recording expenditure for high income households living in gated societies. The proposal answers a refusal rate that has climbed fastest at the top of the income distribution. It also splits a single national survey across two different collection methods.

    What is the Household Consumption Expenditure Survey?

    1. What it measures: The Household Consumption Expenditure Survey (HCES) records how much a household spends on goods and services over a reference period. It covers rural and urban households across the country.
    2. Who runs it: The National Statistics Office under MoSPI conducts it as a sample survey using tablets to record responses.
    3. What the output is used for: The spending shares it produces fix the weights of the Consumer Price Index (CPI) basket, which forms the basis of headline retail inflation. The Reserve Bank of India (RBI) looks at that inflation measure while deciding on interest rates, against a CPI target of 4% within a band of 2% to 6%.
    4. How often it runs: It was earlier conducted every five years. Two back to back rounds ran in 2022-23 and 2023-24 after an overhaul of methods, and the ministry now intends a round every three years or so.

    What is diary based data collection?

    1. The method: The household itself notes down the information as and when the relevant activity occurs, instead of answering a field official at the door. For the HCES this means jotting down monthly spending on different goods and services, ranging from food items to haircuts.
    2. The form it may take: The record need not be a physical diary. The ministry may allow such households to enter consumption expenditure details on an online portal.

    What is recall error in survey data?

    1. The defect: Recall error is the gap between what a household actually spent and what a respondent remembers spending when asked later. It rises with the length of the reference period and the number of items being recalled.
    2. Why the diary reduces it: A household writing an entry at the moment of purchase is not relying on memory at all. The error the interview method introduces is therefore absent from the diary record.

    How far has participation in official surveys fallen?

    1. Urban non response: The overall urban non response rate during the 2022-23 HCES rose to 9.8%, from 2.8% in the 75th round of the National Sample Survey conducted from July 2017 to June 2018.
    2. Rural non response: The rural rate rose to 4.1% over the same period, from 1.5%.
    3. The most affluent respondents: For the most affluent urban and rural respondents, the non response rate stood at 11% and 3.9% respectively.
    4. The earlier baseline: In the 2011-12 survey the corresponding figures for those groups were 3.3% and 1.3%.
    5. The scale of the last round: The most recent HCES, conducted from August 2023 to July 2024, surveyed 2.6 lakh households across the country, barring a few inaccessible villages in the Andaman and Nicobar Islands. It sought responses for a total of 405 goods and services.
    6. The next round: The next edition is expected to begin in mid-2027 and continue for about a year, with the diary method proposed only for richer households in gated societies on a pilot basis.

    Why do affluent households refuse to be surveyed?

    1. Physical exclusion by the association: Resident Welfare Associations (RWAs) have cited security as the reason for not permitting survey staff inside gated societies. Field officers already inform the district collector, local bodies and the police station to obtain permission and support before entry.
    2. Objection to the questions themselves: RWAs have objected to the sensitive and private nature of some questions asked in government surveys.
    3. Fear of onward sharing: RWAs have voiced the apprehension that the details may be shared with other government departments. MoSPI has stated that data privacy is paramount and that the data is anonymised.
    4. Inability to remember: Households have cited the difficulty of recalling expenditure details accurately during a door to door interview.
    5. Discomfort within the family: Residents have cited unease at answering certain questions in front of family members, such as expenditure on alcohol and cigarette consumption.
    6. No perceived reason to participate: MoSPI has recorded a lack of awareness of why these surveys matter for policy, which often leads to outright refusal. Eg. Residents of an affluent society in Gurugram refused to take part in the Time Use Survey.

    Why does refusal concentrated at the top distort national estimates?

    1. The sample shrinks: A rise in non response rates curtails the achieved sample size of a survey.
    2. The sample changes shape: Non responses drawn from one segment leave the final composition of the sample different from what was intended, which produces incorrect estimates from the exercise.
    3. Substitution moves the problem, it does not solve it: Where access failed, the ministry substituted the original residential society with a similar one, so the households actually surveyed are not the households the design selected.
    4. The refusal is not confined to one survey: Similar incidents have been reported from high rises in Bengaluru, Kolkata, Udaipur, Mumbai and Bhopal for the HCES, the Periodic Labour Force Survey, the Annual Survey of Unincorporated Sector Enterprises and the Urban Frame Survey.
    5. Policy is built on these numbers: Government policy is increasingly data and evidence driven, so a biased estimate leads to inappropriate conclusions and decisions that do not produce the desired result.

    What does international practice show about diary based expenditure surveys?

    1. United Kingdom: The Office for National Statistics runs the Living Costs and Food Survey, in which each adult in a selected household keeps a two week spending diary. The results feed the weights of the United Kingdom consumer price indices.
    2. United States: The Bureau of Labor Statistics runs the Consumer Expenditure Surveys in two parts, a quarterly interview component and a separate diary component in which households record purchases for two consecutive one week periods.
    3. Japan: The Statistics Bureau runs the Family Income and Expenditure Survey using a household account book kept by the household over a fixed period rather than a single recall interview.
    4. Australia: The Australian Bureau of Statistics collects a two week personal expenditure diary from household members in its Household Expenditure Survey, alongside a face to face interview.
    5. The limit of the evidence here: The proposal is defended on the ground that the diary method is used in other countries, without naming a country or a comparability finding from any of them.

    Can one survey run on two collection methods without breaking its own comparability?

    1. Two data sets, one estimate: The practical problem is how data compiled through two different methods will be stitched together into a single national estimate.
    2. The error is asymmetric by design: Data collected door to door from poorer households would carry higher recall error than diary based data supplied by richer households. The difference in the numbers would then reflect the method as much as the spending.
    3. The asymmetry runs the wrong way: India's survey samples are dominated by the low income group, so the method with the larger error would apply to most of the sample.
    4. Literacy sets the boundary: Lower literacy rates in the low income group mean only higher income households can be expected to follow the diary method correctly.
    5. The department's own position: MoSPI has stated that the integration of diary compiled data with the main survey is still being worked out and that the proposal is at a planning stage.

    Challenges to the diary based collection proposal

    1. No legal compulsion behind participation: Voluntary compliance is what has broken down, and a change of instrument does not create an obligation to respond. Eg. Residents of gated societies have simply stated that they do not want to participate in a survey, with no consequence following.
    2. Self reporting understates socially sensitive spending: Items respondents are reluctant to declare in front of family are also the items most likely to go unrecorded in a self kept diary. Eg. Expenditure on alcohol and cigarette consumption was named by RWAs as a category respondents avoid.
    3. A portal shifts the burden to the respondent: An online entry system asks an unpaid household to do the work a trained investigator was paid to do, which raises the risk of partial and abandoned records. Eg. The ministry already uses tablets for field recording, so the enumerator side of the process is not the bottleneck.
    4. A pilot on one income class cannot be validated: Without running both methods on the same households, there is no way to separate a method effect from a real difference in spending. Eg. The 2017-18 consumption expenditure survey was junked in November 2019 after its results were questioned on data quality grounds, showing how a contested method destroys the entire round.
    5. Privacy assurance rests on administrative practice: Anonymisation has been promised as a departmental assurance rather than as an enforceable statutory guarantee against onward sharing. Eg. RWAs specifically raised the fear that details would travel to other government departments.
    6. Class segregated methods invite challenge to the inflation number itself: A CPI weight derived from two collection systems can be contested on the ground that the two halves are not measuring the same thing. Eg. The food group weight in the CPI was cut sharply on the basis of the 2023-24 HCES, a revision that depends entirely on the survey being internally consistent.

    Conclusion

    The proposal is at the planning stage, with a diary based pilot intended for high income households in gated societies before the 2027-28 consumption expenditure survey begins. The problem it addresses is real, since non response among the most affluent urban respondents has reached 11% against 3.3% in 2011-12. The unresolved question is the one the ministry itself has flagged, namely how a diary record and a door to door interview can be combined into one estimate when they carry different recall error. Until that is settled, the fix repairs coverage at the cost of comparability.

    About India's Consumption and Price Statistics System

    1. What the Consumer Price Index measures: It captures the price change experienced by the average urban and rural household across food, housing, transport, healthcare, education, clothing and services. It is the closest approximation to the cost of living for a typical household.
    2. How the basket is organised: The CPI is built on 12 divisions of the Classification of Individual Consumption According to Purpose, 2018 (COICOP-2018), covering food and non-alcoholic beverages, pan, tobacco and narcotics, clothing and footwear, housing, water, electricity, gas and other fuels, furnishings and routine household maintenance, health, transport, information and communication, recreation, sport and culture, education, restaurants and accommodation services, and personal care, social protection and miscellaneous items.
    3. The weight of food: Food and non-alcoholic beverages carry a weight of about 36.75% in the CPI, revised down from 45.86%.
    4. The food price index: The Consumer Food Price Index (CFPI) is derived from Division 1 of COICOP-2018 and is published separately for rural, urban and combined series. Its sub components include cereals, milk, meat and fish, oils and fats, vegetables, fruits, pulses, spices and sugar.
    5. Headline against core: Headline inflation includes every item in the basket and swings with monsoons, global crude and supply disruptions. Core inflation strips out food and fuel to give a cleaner read of demand driven, sticky inflation.
    6. The wholesale index: The Wholesale Price Index (WPI), on a 2011-12 base, measures what the economy produces and trades at wholesale. Manufacturing alone accounts for about 64% of the WPI, and food articles at the farm gate together with food manufacturing account for only about 24%.
    7. How the two indices enter national accounts: Goods producing sectors such as agriculture, mining and manufacturing are deflated using the WPI, since their transactions occur at the wholesale level. Services sectors are deflated using CPI components or dedicated services price indices.
    8. Where consumption data feeds employment and enterprise statistics: The Periodic Labour Force Survey (PLFS), launched in 2017-18, tracks employment, workforce participation and unemployment. The Annual Survey of Unincorporated Sector Enterprises (ASUSE) captures output, employment, wages and value added in the informal business economy.

    Laws and Rules Governing Official Statistics in India

    1. Collection of Statistics Act, 2008: Provides the legal framework for the collection of statistics on economic, demographic, social, scientific and environmental matters by the Centre, States and local bodies.
    2. It empowers a statistics officer to require information and penalises wilful refusal or supply of false information.
    3. The Collection of Statistics (Amendment) Act, 2017 extended the framework to the erstwhile State of Jammu and Kashmir and clarified the Centre's powers over subjects in the Union and Concurrent Lists.
    4. Collection of Statistics Rules, 2011: Lay down the procedure for notification of a statistical survey, appointment of statistics officers, service of notices and the handling of returns.
    5. Census Act, 1948: Governs the conduct of the decennial Census and the appointment of census officers.
    6. It makes information given to a census officer confidential and inadmissible as evidence, a confidentiality guarantee the Collection of Statistics framework does not replicate in the same terms.
    7. Registration of Births and Deaths Act, 1969: Provides the civil registration system that supplies vital statistics independent of survey estimates.
    8. Digital Personal Data Protection Act, 2023: Governs the processing of digital personal data and shapes how identifiable household records collected in surveys may be stored and shared.
    9. Right to Information Act, 2005: Provides the route through which unit level survey data and methodology notes are sought from statistical agencies.

    Government Initiatives

    1. National Statistical Commission: Constituted in 2005 on the recommendation of the Rangarajan Commission, it advises on statistical priorities, standards and the release calendar of official statistics.
    2. eSankhyiki portal: A MoSPI platform that brings macro indicators and survey outputs into a single searchable data lake for public and departmental use.
    3. National Data and Analytics Platform: A NITI Aayog initiative to standardise and publish government datasets in machine readable form for researchers and administrators.
    4. Data Governance Quality Index: Scores ministries and departments on the quality of their administrative data systems, aimed at raising the reliability of data generated outside sample surveys.
    5. Revamped Periodic Labour Force Survey: From January 2025 the survey shifted to the calendar year, expanded its sample and moved to monthly reporting of key labour market indicators.
    6. Sustainable Development Goals National Indicator Framework: Maintained by MoSPI, it fixes the national indicators against which progress on the Sustainable Development Goals is reported.

    Key Facts about India's Statistical System

    1. National Statistics Day: Observed on 29 June, the birth anniversary of Prasanta Chandra Mahalanobis, recognised as the architect of India's sample survey system.
    2. World Statistics Day: Observed on 20 October, designated by the United Nations Statistical Commission.
    3. Origins of the survey system: The National Sample Survey was set up in 1950 on Mahalanobis's initiative, making India one of the earliest large scale household survey systems in the developing world.
    4. Institutional merger: The Central Statistics Office and the National Sample Survey Office were merged into the National Statistical Office in May 2019.
    5. International standards: India was among the first countries to subscribe to the International Monetary Fund's Special Data Dissemination Standard, in 1996.

    Back2Basics: National Sample Survey

    1. What it is: A nationwide, large scale sample survey system that collects household and enterprise data through successive rounds, each round running for a fixed period.
    2. Who runs it: The National Statistical Office under MoSPI, through a field operations wing with offices across the country.
    3. How rounds work: Each round carries a principal subject, such as consumption expenditure, employment and unemployment, health, education or land and livestock holdings, with subjects rotating across rounds.
    4. Design: It uses a stratified multi stage sample design covering rural and urban areas, with villages and urban blocks as first stage units and households as ultimate units.
    5. Why the round number matters: Round numbers identify the survey period, so the 75th round refers to the survey conducted from July 2017 to June 2018.

    Challenges in India's Official Statistical System

    1. The sampling frame ages between Censuses: Village lists and urban blocks used to draw samples are anchored to the last Census, so the frame drifts from reality as migration and new construction accumulate. Eg. The decennial Census due in 2021 was deferred, leaving the 2011 Census as the frame for over a decade of surveys.
    2. Base years lag the structure of the economy: An index built on an old base assigns weights drawn from a consumption or production pattern that no longer exists. Eg. The Wholesale Price Index still uses 2011-12 as its base year.
    3. Comparability breaks at every methodological revision: A redesigned questionnaire produces a series that cannot be compared with its own predecessor, which destroys the ability to measure change. Eg. The 2011-12 and 2022-23 consumption rounds used different questionnaire designs, so poverty change between them cannot be read off directly.
    4. Contested releases erode trust in the system: A withheld or discarded round leaves policy without a number and invites the charge that inconvenient results are suppressed. Eg. Two members of the National Statistical Commission resigned in January 2019 over the withholding of employment survey results.
    5. No updated official poverty line: Welfare targeting continues on a threshold fixed against a consumption pattern from an earlier decade. Eg. No official poverty line has been revised since the estimates based on 2011-12 data.
    6. Administrative data sits outside the statistical system: Rich transaction records held by other departments are not routinely used to validate or supplement survey estimates. Eg. Goods and Services Tax returns, e-Shram registrations and direct benefit transfer records are maintained in separate systems from the household survey series.
    7. Privacy law raises the cost of collection: Stricter obligations on identifiable personal data increase the compliance burden on an agency that collects household level detail at scale. Eg. The Digital Personal Data Protection Act, 2023 applies to digital personal data held by government bodies with limited carve outs.

    Way Forward

    1. Run both methods on the same households first: Conduct a calibration study in which a subset of households is covered by interview and diary together, so the method effect can be measured and adjusted before the two data sets are combined.
    2. Give the survey a statutory response obligation with a privacy guarantee: Invoke the notification powers under the Collection of Statistics Act, 2008 for the HCES, paired with a published confidentiality and anonymisation protocol that binds onward sharing.
    3. Shorten reference periods rather than change the respondent's job: Use shorter recall windows and item specific reference periods to cut recall error for the interview sample instead of relying on the diary alone.
    4. Publish non response by income group with every release: Report achieved sample and non response rates decile wise alongside each estimate, so users can see where the sample is thin.
    5. Negotiate access through housing federations rather than society by society: Build standing memoranda with apex RWA federations and municipal bodies so that field access does not depend on a fresh permission at every gate.
    6. Refresh the sampling frame on the 2027 Census: Rebuild urban blocks and rural village lists on the new Census the moment enumeration closes, so the diary pilot is drawn from a current frame.
    7. Use administrative data as a cross check: Validate high income consumption estimates against Goods and Services Tax turnover, card and digital payment aggregates and vehicle and property registration data, without linking them to individual households.

    Matching Previous Year Question

    “[2020] Consider the following statements: 1. The weightage of food in Consumer Price Index (CPI) is higher than that Wholesale Price Index (WPI). 2. The WPI does not capture changes in the prices of services, which CPI does. 3. Reserve Bank of India has now adopted WPI as its key measure of inflation and to decide on changing the key policy rates. Which of the statements given above is/are correct? (a) 1 and 2 only (b) 2 only (c) 3 only (d) 1, 2 and 3 | Answer: (a)”

  • Export payments in rupees get trade policy benefits

    Why in the News

    Two paragraphs of the Foreign Trade Policy 2023 were amended on 20 August 2026 so that exporters invoicing overseas sales in Indian rupees receive the same trade policy benefits as those realising payment in foreign currency. Rupee invoicing has been permitted for years without carrying equal benefit, and removing that mismatch shifts the constraint from India's own rulebook to whether foreign buyers will hold and pay in rupees.

    What is the Foreign Trade Policy 2023?

    1. About: The Foreign Trade Policy is the framework issued by the Directorate General of Foreign Trade setting out the rules, entitlements and obligations governing India's exports and imports.
    2. What its benefits are: Policy benefits include duty remission and duty exemption entitlements that lower the cost of inputs used in exported goods, claimed against realised export proceeds.
    3. Export obligation: Several of these entitlements are conditional on the exporter fulfilling a stated export obligation, measured against the value of realised proceeds.
    4. The 2023 version: The current policy has no end date and is amended continuously by notification rather than being replaced every five years.

    What is the Asian Clearing Union?

    1. About: The Asian Clearing Union is a regional payment arrangement established in 1974 to facilitate trade settlements and reduce repeated transfers of foreign exchange by periodically settling the net obligations of its members.
    2. Membership: It has nine members, Bangladesh, Bhutan, India, Iran, Maldives, Myanmar, Nepal, Pakistan and Sri Lanka, represented by their central banks or monetary authorities.

    What is a Special Rupee Vostro Account?

    1. About: A Special Rupee Vostro Account is a rupee account opened in an Indian bank by a correspondent bank of a partner country, through which international trade is invoiced, paid for and settled in rupees.
    2. Its purpose: The framework was implemented in view of the evolving dynamics of India's international trade, and it lets a foreign buyer pay in rupees without either side converting through a third currency.

    What exactly has changed in the Foreign Trade Policy?

    1. The stated purpose of the amendment: Two paragraphs of the Foreign Trade Policy 2023 were amended to align the provisions on denomination of export contracts and eligibility for policy benefits in respect of export realisation in Indian rupees with the Foreign Exchange Management (Manner of Receipt and Payment) Regulations, 2023.
    2. Denomination freed outside the Asian Clearing Union: For countries outside the Asian Clearing Union, export contracts and invoices may now be denominated in any foreign currency or in Indian rupees.
    3. Coverage: The amendments cover exports to all countries, with the applicable rules varying by destination.
    4. Two countries excepted: Eligible rupee payments for exports to any country other than Nepal and Bhutan will now qualify for trade policy benefits and count towards fulfilment of export obligations.
    5. Parity with foreign currency realisation: Rupee earnings received through approved banking channels are to be treated on par with export payments received in foreign currency.
    6. Lines of credit included: Exports financed through the Export-Import Bank of India or through Government of India lines of credit may also be invoiced in Indian rupees.

    Why were rupee realisations treated differently until now?

    1. Two rulebooks had drifted apart: The exchange control regulations permitted receipt in rupees while the trade policy did not extend the same benefit eligibility to those receipts, so the exporter chose the currency and lost the entitlement.
    2. The export obligation problem: An exporter claiming a duty exemption against an export obligation needed the realisation to count, and a rupee realisation that did not count left the obligation unfulfilled on paper.
    3. The Asian Clearing Union carve-out: Settlement among the nine members runs through the Union's own netting mechanism, which is why denomination rules for those destinations differ from the rest.
    4. The effect on behaviour: Faced with the risk of losing entitlements, exporters defaulted to dollar invoicing even where the counterparty was willing to pay in rupees.

    What does rupee invoicing do for India's external position?

    1. Reduces demand for foreign exchange in settlement: Every transaction invoiced in rupees is one that does not require the exporter or the buyer to source dollars, easing pressure on reserves.
    2. Removes a layer of conversion cost: Trade settled directly between two currencies avoids the spread paid twice when a third currency intermediates.
    3. Insulates counterparties under sanctions pressure: Rupee settlement lets trade continue with partners whose access to dollar clearing is restricted, which is why several Asian Clearing Union members matter here.
    4. Supports lines of credit as an export instrument: Invoicing Export-Import Bank of India and Government of India credit lines in rupees keeps both the financing and the payment inside one currency.
    5. Builds a rupee balance abroad: Settlement in rupees creates rupee holdings with foreign banks, which is the first condition for the currency being used beyond bilateral trade.

    Why does a rulebook change not by itself internationalise the rupee?

    1. Willingness sits with the counterparty: India can permit rupee invoicing and cannot make a foreign buyer accept payment in a currency it has no independent use for.
    2. A trade deficit limits the mechanism: Rupee settlement works most easily where flows are balanced, and India's persistent goods trade deficit means partners accumulate rupees faster than they can spend them.
    3. Idle balances need an investment outlet: A rupee balance held abroad is only attractive if it can be deployed in Indian government securities or corporate paper at a return the holder accepts.
    4. Currency weakness discourages holding: A depreciating currency is a poor store of value between invoice and use. Eg. The rupee was quoted at 95.71 to the dollar on the day the notification was issued.
    5. Convertibility remains partial: The rupee is convertible on the current account and only partially on the capital account, which limits what a foreign holder can do with a rupee balance.

    What challenges does rupee-denominated trade settlement face?

    1. Accumulated balances with no deployment route: Partners that sell more to India than they buy build rupee balances they cannot spend. Eg. Rupee balances held under vostro arrangements with Russia accumulated well beyond what Russian buyers could absorb in Indian goods.
    2. Exchange rate risk shifts to the foreign counterparty: A buyer paying in rupees carries the depreciation risk that the exporter previously bore. Eg. The rupee has weakened steadily against the dollar, having breached the 91 mark during 2025-26 and traded near 95.7 in August 2026.
    3. Thin rupee hedging markets offshore: A foreign counterparty cannot cheaply hedge a rupee exposure in the way it hedges a dollar one. Eg. Offshore non-deliverable forward markets in the rupee developed precisely because onshore hedging access is restricted for non-residents.
    4. Correspondent banking and compliance frictions: Opening and operating vostro accounts requires approvals and sanctions screening that smaller banks avoid. Eg. Trade with Asian Clearing Union member Iran has repeatedly stalled on the willingness of banks to handle the settlement leg.
    5. Interest rate and return disadvantage: Rupee balances earn less than the holder can obtain in reserve currency instruments unless a specific investment window is opened. Eg. Permission to invest surplus vostro balances in Indian government securities was extended precisely to address this gap.
    6. Documentation mismatch across regulations: Exporters must satisfy both exchange control and trade policy requirements, and any divergence between them creates a compliance risk. Eg. The present amendment exists only because eligibility rules under the Foreign Trade Policy had drifted from the Foreign Exchange Management (Manner of Receipt and Payment) Regulations, 2023.
    7. Uneven customer experience at the bank counter: Documentation demands and delays at authorised dealer banks slow cross-border remittances regardless of the currency chosen. Eg. A supervisory review found multiple documentation requirements and cases of delay in executing cross-border remittances, and banks were advised to publish a clear policy on documentation, charges, timelines and grievance redress.

    Conclusion

    The amendment removes an internal inconsistency rather than creating a new entitlement, since it makes a rupee realisation earn the same trade policy benefit and count towards the same export obligation as a dollar realisation. That closes the reason exporters had for avoiding rupee invoicing even where the buyer was willing. The notification has been issued by the Directorate General of Foreign Trade and is in effect, and the measure that follows is whether the Special Rupee Vostro Account framework generates enough deployable rupee balances abroad for foreign buyers to choose rupee settlement on their own account.

    India's External Sector

    1. What it covers: The external sector comprises merchandise and services trade, investment flows in both directions, external borrowing, remittances, foreign exchange reserves and the exchange rate that links them.
    2. Two accounts: The current account records trade in goods and services, primary income and transfers. The capital and financial account records investment and borrowing flows.
    3. Direct investment position: India held fifth position globally in foreign direct investment inflows with $28 billion in 2024, fourth position in announced greenfield projects, and fifth position in international project finance deals.
    4. Recent direction of flows: Net foreign direct investment turned negative for three consecutive months during 2025, with gross inflows staying strong while outward investment and repatriation rose.
    5. Currency pressure: The rupee breached the 91 mark against the dollar during 2025-26 and emerged as Asia's worst performing currency amid trade uncertainty.
    6. Energy in the import bill: India depends on imports for over 88% of its crude oil requirement and about half of its natural gas consumption, so the trade balance moves with global energy prices.
    7. Global backdrop: Global foreign direct investment fell 11% in 2024, and the share of foreign direct investment in global Gross Domestic Product fell from 5% in 2007 to under 1% in 2023-24.

    Laws and Rules Governing Foreign Trade and Payments in India

    1. Foreign Trade (Development and Regulation) Act, 1992: Provides for the development and regulation of foreign trade and is the statute under which the Foreign Trade Policy and the office of the Director General of Foreign Trade exist.
    2. Empowers the Central government to formulate and announce the export and import policy and to amend it by notification.
    3. Foreign Exchange Management Act, 1999: Governs all foreign exchange transactions, replacing a control-based regime with a management-based one and treating contraventions as civil rather than criminal.
    4. Foreign Exchange Management (Manner of Receipt and Payment) Regulations, 2023 prescribe the currencies and channels through which export proceeds may be received, the regulations the present amendment aligns the trade policy to.
    5. Customs Act, 1962: Governs the levy of customs duty, valuation, clearance of goods and the operation of duty exemption and remission schemes at the border.
    6. Customs Tariff Act, 1975: Prescribes the rates of import and export duty and provides for anti-dumping and countervailing measures.
    7. Special Economic Zones Act, 2005: Governs the establishment and operation of zones treated as outside the customs territory for duty purposes.
    8. Reserve Bank of India Master Directions on Export of Goods and Services: Prescribe realisation and repatriation periods, documentation and the role of authorised dealer banks in export transactions.

    Government Initiatives for Export Promotion

    1. Remission of Duties and Taxes on Exported Products: Refunds embedded central, state and local duties and taxes that are not otherwise rebated, at notified rates by tariff line.
    2. Rebate of State and Central Taxes and Levies: Provides rebate of embedded taxes specifically for exports of garments and made-ups.
    3. Advance Authorisation and Duty Free Import Authorisation: Allow duty free import of inputs physically incorporated in an export product, against a stated export obligation.
    4. Export Promotion Capital Goods scheme: Permits import of capital goods at zero duty against an export obligation linked to the duty saved.
    5. Interest Equalisation Scheme: Provided interest subvention on pre-shipment and post-shipment rupee export credit, particularly for micro, small and medium enterprises and for identified sectors.
    6. Districts as Export Hubs: Identifies products with export potential in each district and builds district-level export action plans and institutional support.
    7. Market Access Initiative: Funds participation in international trade fairs, buyer-seller meets and market studies to open new destinations.
    8. Trade Connect e-Platform: Brings exporters, Indian missions abroad, export promotion councils and banks onto a single digital interface for market and regulatory information.

    Back2Basics: Directorate General of Foreign Trade (DGFT)

    1. What it is: The agency responsible for formulating, implementing and amending India's Foreign Trade Policy.
    2. Parent ministry: It functions under the Department of Commerce in the Ministry of Commerce and Industry.
    3. Statutory basis: It operates under the Foreign Trade (Development and Regulation) Act, 1992.
    4. Core function: It issues the Importer Exporter Code, without which no person may import or export except as exempted.
    5. Entitlement administration: It grants authorisations and scrips under the duty exemption and duty remission schemes and monitors fulfilment of export obligations.
    6. Instrument of change: It amends the Foreign Trade Policy and the Handbook of Procedures through notifications, public notices and circulars.
    7. Trade facilitation role: It runs the online platform through which authorisations are applied for and issued, and it handles quality complaints and trade disputes involving Indian exporters and importers.

    Challenges in India's External Sector

    1. Structural merchandise trade deficit: Import demand for energy, electronics and gold consistently exceeds export earnings, which keeps the current account in deficit. Eg. Net oil and gas imports rose 43.4% in value to $57.8 billion in April to July of 2026-27 from $40.3 billion a year earlier.
    2. Concentration of imports in a few commodities: A price shock in one commodity transmits directly to the trade balance. Eg. Every one dollar per barrel increase in oil prices raises India's annual oil import bill by up to $2 billion, on annual imports of 1.8 to 2 billion barrels.
    3. Protectionism and tariff shocks in destination markets: Export access can be withdrawn by unilateral action outside any trade agreement. Eg. Tariffs on key goods surged to 50% in August 2025, disrupting exporter planning.
    4. Competition from alternative manufacturing destinations: Rivals offer faster approvals and wider free trade agreement networks to firms relocating supply chains. Eg. Vietnam, Indonesia and Mexico compete directly for near-shoring investment that India seeks.
    5. Volatility of portfolio capital: Portfolio flows reverse quickly and transmit directly to the exchange rate. Eg. Foreign portfolio investors recorded an outflow of Rs 1.66 lakh crore, equivalent to $18.9 billion, in 2025, the largest since such investment began.
    6. Rising outward investment and repatriation: Indian firms investing abroad and foreign firms repatriating profits both reduce net inflows even when gross inflows hold up. Eg. Foreign companies operating in India repatriated about $5 billion in October 2025, of which $3.3 billion followed a single initial public offering.
    7. Round-tripping and financialisation of investment flows: A large share of inflows originates from a few jurisdictions and increasingly arrives through funds rather than as direct industrial equity. Eg. Inflows routed through Mauritius and Singapore reflect tax arbitrage rather than fresh industrial capital.
    8. Exchange rate depreciation raising the external debt burden: A weaker rupee raises the rupee cost of servicing external liabilities without any new borrowing. Eg. The rupee emerged as Asia's worst performing currency during 2025-26 amid trade uncertainty.

    Way Forward

    1. Open deployment routes for accumulated rupee balances: Allowing surplus vostro balances into Indian government securities, corporate bonds and project financing gives foreign holders a reason to accept rupees.
    2. Expand bilateral local currency settlement arrangements: Agreements with major trading partners, negotiated alongside the vostro framework, are what convert a permission into actual volumes.
    3. Deepen onshore rupee hedging access for non-residents: A foreign buyer that can hedge a rupee payable onshore no longer needs a dollar invoice to manage currency risk.
    4. Keep the trade policy and exchange control rulebooks synchronised: A standing reconciliation between the Foreign Trade Policy and the exchange management regulations would prevent the mismatch this amendment had to correct.
    5. Fix the customer experience at authorised dealer banks: Publishing documentation requirements, charges, timelines and escalation routes on bank websites and at branches removes a practical barrier that no notification reaches.
    6. Diversify the export basket and destinations: Reducing dependence on a small number of markets and product lines is the durable answer to unilateral tariff action.
    7. Reduce the energy component of the import bill: Faster domestic oil and gas output, refining efficiency and electrification of transport address the largest single driver of the trade deficit.

    Matching Previous Year Question

    “No direct PYQ traced in the provided files (closest microtheme: Foreign Exchange,Currency Devaluation)”

  • Derivatives trader base falls for first time in four years in FY26

    Why in the News

    The number of individual traders participating in the equity derivatives market fell 19% to 78.6 lakh in 2025-26 from 98.1 lakh a year earlier, according to data released by the Securities and Exchange Board of India (SEBI) on 20 August 2026. A smaller market has not turned into a safer one, since the average loss carried by each loss-making trader rose to its highest level since the analysis began.

    What are equity derivatives?

    1. About: Equity derivatives are contracts whose value is derived from an underlying share or share index, settled at or before a stated expiry date rather than by delivery of the underlying at the time of trade.
    2. Futures and options: A futures contract obliges both sides to transact at an agreed price on expiry. An option gives the buyer the right without the obligation, in exchange for a premium paid upfront.
    3. Why losses concentrate here: A small premium controls a large notional exposure, so a modest adverse price move can erase the entire amount committed.
    4. Contract value: Each contract carries a minimum notional value fixed by the regulator, which sets the smallest position an individual can take.

    What is the extreme loss margin?

    1. About: The extreme loss margin is an additional margin collected over and above the standard margin, calibrated to cover losses outside the range that normal margining assumes.
    2. How it was used here: SEBI increased the extreme loss margin for expiry-day trading by 2%, raising the cost of holding a position on the day price movement is sharpest.

    What is a weekly expiry?

    1. About: A weekly expiry is a contract that settles at the end of a given week rather than at the end of a month, which multiplies the number of short-dated, low-premium contracts available to trade.
    2. How it was restricted: SEBI limited weekly expiries to one index per exchange, cutting the number of high-turnover expiry events in a week.

    What do SEBI’s two studies show about participation and losses?

    1. Participation: The individual trader base fell 19% to 78.6 lakh in 2025-26 from 98.1 lakh in 2024-25, the first fall in four years, against 42.74 lakh in 2021-22 when the analysis began.
    2. Share of losing traders: The proportion of traders who incurred losses declined marginally to 87.7% in 2025-26 from 90.9% in 2024-25, the lowest level recorded since 2021-22.
    3. Aggregate losses: Aggregate losses fell 18% year-on-year to Rs 91,685 crore in 2025-26, and still remained higher than the levels recorded between 2021-22 and 2023-24.
    4. Loss per trader: The average loss per loss-making trader rose to Rs 1.16 lakh from Rs 1.13 lakh in 2024-25, the highest average loss recorded since 2021-22.
    5. Who remains the largest cohort: Individual traders continued to account for the largest cohort in the derivatives market despite the decline in participation.
    6. What the studies are: The two studies cover the profitability and the trading behaviour of individual derivatives traders, and were released on 20 August 2026 by SEBI’s Department of Economic and Policy Analysis II.

    Why does a smaller trader base not amount to a safer market?

    1. The averages moved in opposite directions: Aggregate losses fell 18% while the average loss per loss-making trader rose to a five-year high, so the burden concentrated rather than eased.
    2. The improvement in the loss ratio is marginal: A fall from 90.9% to 87.7% still leaves close to nine in ten participants losing money.
    3. The remaining participants are the more exposed ones: Those who stayed after the curbs are the traders willing to meet a higher minimum contract value and a higher expiry-day margin.
    4. Aggregate losses are still above the pre-boom level: Even after an 18% decline, losses in 2025-26 exceeded the levels recorded between 2021-22 and 2023-24.

    What explains the fall in participation?

    1. Fewer weekly expiry events: SEBI limited weekly expiries to one index per exchange, removing several of the short-dated contracts that carried the highest retail turnover.
    2. A higher entry ticket: The minimum contract value was raised to Rs 15 lakh to Rs 20 lakh, which prices out the smallest participants.
    3. A costlier expiry day: The extreme loss margin for expiry-day trading was increased by 2%, raising the capital required to hold the most volatile positions.
    4. The regulator’s own caveat: SEBI cautioned against attributing the decline entirely to the regulatory measures, stating that participation had already begun moderating before their implementation.

    What does the persistence data reveal about trader behaviour?

    1. Losses do not by themselves deter continuation: The second study found that incurring losses did not necessarily discourage traders from continuing to participate in derivatives.
    2. Persistence weakened this year: Only about 57% of the traders who formed the 2024-25 cohort continued trading in 2025-26, against a long-term average of around 65%.
    3. Nearly half stopped: 43% of that cohort stopped trading during the year.
    4. Experience does not improve outcomes: In 2023-24, 91.6% of traders who had reported losses in both 2021-22 and 2022-23 also reported losses in 2023-24.
    5. The probability holds across the experience range: The probability of making losses remained above 90% across traders with one to five years of experience.

    What challenges does retail investor protection in the derivatives market face?

    1. Curbs raise the entry price without changing the odds: A higher minimum contract value screens out small participants rather than improving the outcomes of those who remain. Eg. The probability of making losses stayed above 90% across traders with one to five years of experience.
    2. Losses do not teach: Repeated loss-making does not reliably drive exit, so a behavioural remedy cannot be assumed. Eg. 91.6% of traders who lost money in both 2021-22 and 2022-23 lost money again in 2023-24.
    3. Unregistered advisers and finfluencers: Trading advice reaches retail participants through channels outside the registered investment adviser framework. Eg. SEBI has issued repeated orders against unregistered persons offering stock recommendations on social media platforms.
    4. Migration to unregulated venues: Tightening a regulated segment can push activity to opaque alternatives rather than out of speculation altogether. Eg. SEBI and the Reserve Bank of India have repeatedly warned against unauthorised electronic trading platforms offering leveraged contracts.
    5. Exchange revenue tied to the volumes being curbed: Transaction charges and the derivatives segment are a significant part of exchange income, which creates a tension with tighter product rules. Eg. Weekly index expiries generated the highest turnover days on Indian exchanges before being limited to one index per exchange.
    6. Investor grievance redress capacity: Losses from a legitimate but unsuitable product are not a grievance, so the redress machinery does not reach the harm being measured. Eg. Aggregate losses of Rs 91,685 crore in 2025-26 arose from lawful transactions on regulated exchanges.
    7. Measurement lag on a fast-moving market: Behaviour is analysed a full financial year after it occurs, so remedies address a market that has already changed. Eg. The studies released in August 2026 report on the year ended March 2026.

    “[2025] Consider the following statements:

    I. India accounts for a very large portion of all equity option contracts traded globally, thus exhibiting a great boom.

    II. India’s stock market has grown rapidly in the recent past, even overtaking Hong Kong’s at some point in time.

    III. There is no regulatory body either to warn small investors about the risks of options trading or to act on unregistered financial advisors in this regard.

    Which of the statements given above are correct?

    (a) I and II only

    (b) II and III only

    (c) I and III only

    (d) I, II and III