Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS3-02.Inclusive growth and issues therein

  • [28th November 2025] Hindu OpED Are the labour codes labour friendly

    PYQ Relevance

    [UPSC 2024] Discuss the merits and demerits of the four ‘Labour Codes’ in the context of labour market reforms in India. What has been the progress so far in this regard?

    Linkage: The article’s debate on worker protection vs. industry flexibility directly reflects the merits and demerits raised in this PYQ. It also covers the slow implementation and stakeholder resistance, matching the question’s focus on progress.

    Mentor’s Comment

    The introduction of India’s four consolidated labour codes has triggered a high-stakes national debate on whether they truly modernise labour regulation or dilute long-standing protections. This article dissects the core arguments expanding them into a UPSC-focused analytical framework. The aim is to help aspirants understand the political economy of labour reforms, their implications for workers and industry, and their place in India’s growth policy discourse.

    WHY IN THE NEWS?

    India’s four consolidated labour codes, wage, social security, industrial relations, and occupational safety, have reignited debate as trade unions accuse the government of diluting protections while industries argue they streamline a fragmented regulatory environment. The issue is significant because India has not attempted such a comprehensive codification since Independence, and the codes come at a time when informal workers form 93% of the workforce but only 7% receive social security. The codes also affect hiring, firing, job security, and collective bargaining, core issues shaping labour productivity and industrial peace.

    INTRODUCTION

    India’s labour market operates at the intersection of rapid economic modernization and persistent structural informality. The four new labour codes aim to consolidate 29 existing laws, reduce compliance rigidity, support ease of doing business, and expand social security. However, the reforms have triggered disagreements between trade unions, who fear erosion of worker rights, and industries, who seek flexibility to improve competitiveness. This article examines the institutional debates and policy implications emerging from the new codes.

    The Historical Context of Labour Law Reform

    1. Fragmented Legislation: Consolidated 29 separate laws, many framed in the 1940s-50s, marked by overlapping definitions, multiple inspections, and differing interpretations across states.
    2. Changing Labour Landscape: Witnessed rapid industrial growth, gig work, platforms, logistics, contract labour, and digital-era employment, demanding updated regulatory structures.
    3. Productivity Imperatives: Industries argue workers must be protected and empowered but rigidities must reduce to strengthen India’s global competitiveness.

    What Necessitated the Labour Codes?

    1. Regulatory Overlap: Multiple laws with inconsistent provisions complicated compliance and enforcement.
    2. Economic Modernisation Need: Traditional industry structure gave way to gig work, platform work, logistics, e-commerce and new forms of employment, requiring modern regulation.
    3. Social Protection Gap: Only 7% of workers covered by social security; informal economy workers remain largely unprotected.
    4. Investment Climate Concerns: Procedural delays in hiring/firing, disputes, and closures deterred global investment.

    Do the Labour Codes Promote or Restrict Worker Rights?

    1. Trade Union Concern-Reduced Security: Fears that fixed-term contracts, easier retrenchment thresholds, and union restrictions weaken bargaining power.
    2. Collective Bargaining Apprehension: Codes allow only a single negotiating union, potentially marginalising smaller unions.
    3. Industry Perspective-Greater Formalisation: Codification ensures predictable rules, reduces litigation, and encourages job creation.
    4. Worker Protection Measures: Codes extend minimum wage applicability, mandate formalised contracts, introduce new safety norms, and expand the definition of employees.

    How Will the Codes Impact Social Security and Gig Workers?

    1. Social Security Expansion: Gig and platform workers added under social security, but benefits remain contingent upon schemes and government implementation.
    2. Funding Challenges: Industry argues government and employees must co-contribute; trade unions insist government should shoulder primary responsibility.
    3. Small Share of Gig Workers: Currently form a small slice of the informal sector but rapidly growing; require future-ready welfare structures.

    Do the Codes Improve Industrial Relations and Productivity?

    1. Industry View: Ensures Stability
      • Predictability and ease of compliance strengthen investment climate and reduce industrial disputes.
    2. Trade Union View: Risk of Industrial Unrest
      • Dissatisfaction due to inadequate representation and perceived dilution of rights may trigger strikes.
    3. Flexibility vs. Protection Debate: Government seeks a balance between global competitiveness and worker protection.

    Will the Codes Expand Organised Employment?

    1. Industry Assertion: Broader wage definitions, coverage of establishments, and social security norms bring more workers under formal sector protections.
    2. Union Counterpoint: Without job stability, contract labour proliferation may worsen precarity.

    CONCLUSION

    India’s labour codes represent an ambitious attempt to modernise outdated labour laws, enhance productivity, and integrate India into global manufacturing networks. However, the success of these reforms will depend on transparent implementation, a balanced approach to worker protection, and sustained dialogue with trade unions. A labour ecosystem that provides both flexibility and security is essential for equitable and sustainable growth.
  • [15th November 2025] The Hindu Op-ED: Flexible inflation targeting, a good balance

    Mentor’s Comment

    The debate on India’s Flexible Inflation Targeting (FIT) framework is central to macroeconomic stability, especially as the Reserve Bank of India (RBI) undertakes the second quinquennial review after adopting FIT in 2016. This article decodes the logic, data trends, inflation-growth dynamics, concerns over inflation bands, and the evolving economic context, translated into UPSC-ready analysis with conceptual clarity.

    Introduction

    India adopted the Flexible Inflation Targeting (FIT) framework in 2016, giving statutory autonomy to the RBI for price stability. With the current inflation band of 4% ± 2% up for review in March 2026, economic debate has intensified on whether this band remains appropriate amid structural shifts, supply-side shocks, and the inflation-growth trade-off. The article evaluates India’s experience with FIT, evidence from inflation-growth relationships, and the question of acceptable inflation levels for sustained macroeconomic stability.

    Why in the News?

    The FIT framework is undergoing its second major review since its inception in 2016, making it a crucial moment for India’s monetary policy architecture. RBI has released a research discussion paper, its most comprehensive assessment yet, presenting long-term inflation-growth data, the first such empirical mapping since 1991. The debate is significant because India’s inflation has remained near the upper tolerance band, raising questions about whether 4% is still an appropriate central target or whether persistent supply shocks require rethinking the framework. The outcome of this review will shape India’s monetary autonomy, fiscal-monetary coordination, and growth stability over the coming decade.

    What makes inflation control central to monetary policy?

    1. Inflation as a regressive tax: Disproportionately burdens poorer households whose incomes are not hedged; erodes purchasing power.
    2. High inflation leading to misallocation of resources: Leads to volatile investments and misdirected economic decisions.
    3. Acceptable inflation evolves with context: The Chakravarty Committee (1985) recommended 5% as acceptable, but economic conditions have since changed.
    4. Institutional strengthening since 1994: Post-automatic monetisation era gave RBI functional autonomy; FIT (2016) gave statutory backing for price stability.

    How does India’s current FIT framework work?

    1. Inflation band of 4% ± 2%: Offers flexibility while anchoring expectations.
    2. Headline inflation as target: Encourages investment protection from supply shocks; aligns with international norms.
    3. Range-bound inflation despite shocks: India has broadly maintained inflation within the band, reflecting maturing policy credibility.
    4. Mechanism evolves with economic complexity: Framework still young, but institutional autonomy makes it robust.

    What should India target-headline inflation or core inflation?

    1. Headline inflation captures supply shocks: Essential in an economy where food inflation significantly affects households.
    2. Misconception on price behaviour: General price level (inflation) differs from relative price changes (e.g., wages, food).
    3. Milton Friedman example: Excess money supply raises general prices; changing relative prices without liquidity expansion cannot cause inflation.
    4. No liquidity expansion leading to no general inflation: Relative price movement alone insufficient to generate sustained inflation.

    What does long-term data reveal about inflation and growth?

    1. Quadratic inflation-growth curve (1991-2023): Presented in the article; first time excluding COVID years.
    2. Point of inflection = 3.98%: Growth rises with inflation to ~4%, then declines beyond it.
      1. Implication: India’s acceptable inflation level is just around 4%.
    3. Higher inflation hurts growth: Especially when supply constraints, fiscal stress, and external pressures coincide.

    How flexible should the inflation band be

    1. FIT performance so far: Delivered flexibility; monetary authorities operate near upper limit due to shocks.
    2. Risk of staying at the upper band: May undermine framework credibility.
    3. Policy navigation matters: India earlier faced high inflation in the 1970s-80s; monetisation of the deficit made it worse.
    4. Present framework avoids past mistakes: Moves away from fiscal dominance; prevents automatic deficit monetisation.

    What determines an acceptable level of inflation?

    1. Phillips Curve insights: Countries with higher income also see higher acceptable inflation levels.
    2. Empirical threshold near 4%: RBI paper’s curve suggests growth maximisation at around 4%.
    3. India-specific vulnerabilities: Supply shocks (food, fuel), climate variability, imported inflation, fiscal constraints.
    4. Need for robust expectations anchoring: Prevents wage-price spiral and demand misalignment.

    Conclusion

    India’s Flexible Inflation Targeting has broadly succeeded in stabilising inflation expectations while preserving monetary autonomy. Evidence from long-term inflation-growth dynamics reinforces that 4% remains an optimal central target, though India must build greater resilience to supply shocks and strengthen fiscal-monetary coordination. A credible, flexible, and data-driven FIT framework remains essential for India’s growth trajectory over the next decade.

    PYQ Relevance

    [UPSC 2024] What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.

    Linkage: This PYQ  is highly relevant as food inflation heavily shapes headline inflation under the Flexible Inflation Targeting (FIT) framework, highlighting the limits of the Reserve Bank of India’s (RBI) tools. It links to the review of the four-percent target and RBI’s role in managing supply-driven inflation.

  • [7th November 2025] The Hindu Oped: Redraw welfare architecture, place a UBI in the centre

    PYQ Relevance

    [UPSC 2015] In what way could replacement of price subsidy with Direct Benefit Transfer (DBT) change the scenario of subsidies in India? Discuss.

    Linkage: The shift from price subsidies to Direct Benefit Transfers (DBT) improved efficiency and targeting in welfare delivery. Universal Basic Income (UBI) is the next step in this evolution, moving from targeted transfers to universal, unconditional income support that ensures inclusion and economic stability.

    Mentor’s Comment

    As automation, artificial intelligence, and widening inequality reshape global economies, India faces an urgent need to rethink its welfare model. Universal Basic Income (UBI) , once dismissed as utopian, is emerging as a viable economic tool to balance growth with inclusion, stabilize consumption, and future-proof citizens against technology-driven disruptions.

    Introduction and Why in the News

    India’s wealth gap is at a 75-year high, and technological transformation is outpacing job creation. The article argues that a Universal Basic Income could act as a stabilizer for an economy characterized by automation-led job loss, consumption inequality, and welfare fragmentation. UBI thus represents both an economic necessity and moral evolution, a reform that can ensure social security while sustaining demand in an AI-driven economy.

    Understanding UBI in the Economic Context

    1. Concept: A periodic, unconditional cash transfer to all citizens, regardless of income or employment.
    2. Economic Foundation: Acts as a floor for consumption and stabilizer of demand during economic downturns.
    3. Rationale in India: Addresses inefficiencies, leakages, and exclusions in existing welfare subsidies and improves fiscal targeting through direct transfers.
    4. Global Relevance: Countries like Finland, Kenya, and Iran have experimented with variants of basic income to address automation shocks and inequality.

    Why India Needs a New Welfare Model

    • Automation and Jobless Growth:
      1. India’s labour-intensive sectors are losing relevance as AI and robotics replace routine work.
      2. A 2023 McKinsey Report estimates 40-45% of Indian jobs risk automation by 2030.
      3. Consumption Inequality: The top 10% hold over 40% of total income, weakening demand from lower strata, a key factor behind India’s K-shaped recovery post-COVID.
    • Fragmented Welfare Spending:
      1. Over 950 central schemes exist; only 20% reach intended beneficiaries (NITI Aayog, 2022).
      2. Rationalizing and merging subsidies could free 1-2% of GDP, enough to fund a phased UBI.

    Fiscal Feasibility and Implementation Models

    1. Budgetary Realignment: A UBI costing ₹7,500 per person annually = ~1% of GDP, fiscally manageable by pruning inefficient subsidies.
    2. Digital Readiness: India’s JAM Trinity (Jan Dhan-Aadhaar-Mobile) enables transparent Direct Benefit Transfers (DBT) to 450+ million beneficiaries.
    3. Phased Approach:
      • Start with vulnerable groups (elderly, women, informal workers) and expand gradually.
      • Link with automation tax or digital economy levy to ensure sustainability.
    4. Behavioral Economics View: Unconditional transfers improve human capital investment (nutrition, education) without creating disincentive to work, proven in Madhya Pradesh SEWA UBI Pilot, 2013.

    UBI as an Economic Stabilizer

    1. Counter-Cyclical Tool: Maintains aggregate demand in economic slowdowns; ensures liquidity among lower-income households.
    2. Productivity Boost: Financial security allows workers to upskill and pursue entrepreneurial ventures instead of insecure subsistence jobs.
    3. Gender Dividend: Recognizes unpaid care work and enhances female labour participation, a major economic multiplier.
    4. Rural Resilience: Ensures income continuity against climate shocks, agrarian distress, and market failures.

    Challenges in Adopting UBI

    1. Fiscal Trade-offs: High recurring costs could strain the fiscal deficit if not balanced by rationalization of subsidies.
    2. Inflationary Pressure: Sudden increase in liquidity may spike prices unless accompanied by supply-side reforms.
    3. Exclusion Risks via Aadhaar/DBT: Digital divide and authentication errors can replicate old exclusion patterns.
    4. Political Economy Resistance: Targeted benefits create patronage networks; universalization dilutes control, making reform politically sensitive.

    Global Insights for India

    Country Nature of UBI Trial Lessons
    Finland (2017-18) €560/month for unemployed Improved well-being, not joblessness
    Kenya Cash transfer for 12 years Increased small business formation
    Iran (2010) Universal transfer replacing subsidies Reduced poverty without fiscal collapse
    Brazil (Bolsa Família) Conditional transfer, near-universal Boosted literacy, health, consumption

    India can blend these experiences into a hybrid model: quasi-universal, fiscally prudent, and tech-enabled.

    Conclusion

    A Universal Basic Income is no longer a moral luxury, it is an economic inevitability in a future where automation, inequality, and climate shocks converge. By realigning subsidies and leveraging digital infrastructure, India can embed economic dignity into fiscal policy. UBI is not about welfare dependency, it is about stabilizing markets through empowered citizens.

  • Revisions in the Consumer Price Index (CPI)

    Why in the News?

    The Ministry of Statistics and Programme Implementation (MoSPI) has proposed major revisions in the Consumer Price Index (CPI) methodology, to be implemented in the new retail inflation series from February 2026.

    About the Consumer Price Index (CPI):

    • Overview: The CPI measures the average change over time in the prices paid by consumers for a fixed basket of goods and services typically consumed by households.
    • Purpose: It tracks retail inflation showing how the purchasing power of money changes due to price variations, and how living costs evolve across different population groups.
    • Components:
      • Food and Beverages: Cereals, pulses, vegetables, milk, meat, fish, sugar, and beverages.
      • Housing: Rent paid for rented houses and imputed rent for self-occupied dwellings.
      • Clothing and Footwear: Garments, textiles, footwear, and related goods.
      • Fuel and Light: LPG, kerosene, electricity, firewood, and other fuels.
      • Miscellaneous: Transport, communication, education, health, recreation, personal care, and other services.
    • Publishing Authority: The CPI is compiled and released by the Ministry of Statistics and Programme Implementation (MoSPI) through the National Statistical Office (NSO) every month.
    • Current Base Year: 2012, which is being revised to 2024 to reflect more recent household consumption patterns captured in the Household Consumption Expenditure Survey (HCES) 2023–24.
    • Coverage: Separate indices are compiled for Rural, Urban, and Combined (Rural + Urban) sectors to reflect diverse consumption and price patterns.
    • Types of CPI in India:
      1. CPI for Industrial Workers (CPI-IW): Base year 2016; tracks inflation for organized industrial workers; used for Dearness Allowance (DA) revisions.
      2. CPI for Agricultural Labourers (CPI-AL): Base year 1986–87; measures price changes faced by agricultural labourers.
      3. CPI for Rural Labourers (CPI-RL): Base year 1986–87; monitors inflation for rural households dependent on wage labour.
      4. CPI (Urban), CPI (Rural), and CPI (Combined): Base year 2012; represents national-level retail inflation and is the official measure of inflation in India.
    • Weightage: The relative importance (weight) of each component reflects its share in total household expenditure, for instance, food and beverages hold over 45%, while housing has 21.67% in urban CPI and 10.07% in all-India CPI.
    • Use and Importance:
      • Inflation Targeting: The Reserve Bank of India (RBI) uses CPI as the anchor for its Monetary Policy Framework, aiming for 4% ± 2% inflation.
      • Wage & Pension Adjustments: CPI is used to revise wages, pensions, and dearness allowances in both government and industrial sectors.
      • Policy Planning: It provides essential inputs for economic policy, poverty analysis, and fiscal decisions.
      • Economic Indicator: Serves as the primary indicator of cost of living, influencing interest rate decisions, tax indexation, and social welfare adjustments.

    Revisions in the Consumer Price Index (CPI)

    Revisions in the CPI:

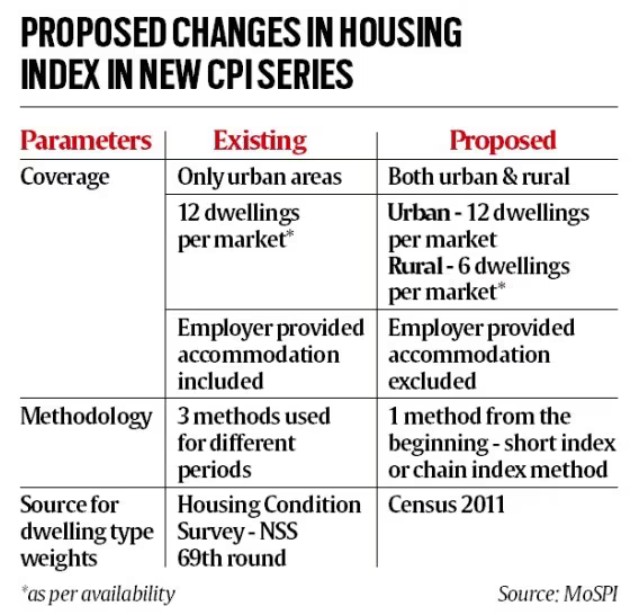
    • Monthly Rent Data: Collection every month for both rural & urban areas, replacing earlier six-monthly urban series.
    • Inclusion of Rural Housing: Covers imputed rents for owner-occupied rural dwellings.
    • Exclusion of Employer Housing: Removes HRA-based distortions from government/PSU quarters.
    • Expanded Sampling & IMF Alignment: Broader coverage, discontinuation of panel imputation, adoption of IMF-recommended rent index computation.
    • Weight Revision: Recalibrates housing share (currently 21.67 % urban; 10.07 % all-India) using new expenditure data.
    • Transparency: MoSPI discussion papers (2024-25) invite feedback on PDS treatment, housing index, and base methodology.

    Rationale & Impact:

    • Captures Post-Pandemic Rent Surge overlooked by the 2012 base.
    • Addresses Rural Under-coverage for two-thirds of India’s population.
    • Enhances RBI’s Inflation Targeting through more accurate rent data.
    • Aligns with Global Standards, strengthening CPI’s credibility as a comprehensive welfare and policy indicator.
    [UPSC 2020] Consider the following statements:
    1. The weightage of food in Consumer Price Index (CPI) is higher than that Wholesale Price Index (WPI).
    2. The WPI does not capture changes in the prices of services, which CPI does.
    3. Reserve Bank of India has now adopted WPI as its key measure of inflation and to decide on changing the key policy rates.
    Which of the statements given above is/are correct?
    Options: (a) 1 and 2 only* (b) 2 only (c) 3 only (d) 1, 2 and 3


  • What is Rangarajan Poverty Line?

    Why in the News?

    After the C. Rangarajan Committee (2014) set India’s last official poverty line, economists from the Reserve Bank of India (RBI) have now revisited and updated the estimates using new household consumption data from Household Consumption Expenditure Survey (HCES) 2022–23.

    Evolution of Poverty Measurement in India:

    1. Planning Commission (1962): ₹20 (rural) and ₹25 (urban) per month; excluded health and education.
    2. Dandekar & Rath Committee (1971): Calorie-based standard (2250 kcal/day).
    3. Y. K. Alagh Committee (1979): Calorie-linked poverty line (2400 kcal rural; 2100 kcal urban).
    4. Lakdawala Committee (1993): Introduced state-specific and composite consumption baskets.
    5. Tendulkar Committee (2009): Uniform basket for rural/urban; ₹816 rural and ₹1000 urban (2011–12); shifted from calorie to expenditure-based poverty.

    About C. Rangarajan Committee on Poverty Estimation:

    • Objective: To evolve a broader and realistic poverty metric incorporating food, health, education, clothing, and shelter costs, beyond calorie-based norms.
    • Overview: Formed by the Planning Commission in 2012, chaired by Dr. C. Rangarajan, former RBI Governor, to review India’s poverty measurement methodology.
    • Report Submission: Submitted in June 2014; became a major benchmark in the debate on India’s official poverty line and methodological framework.
    • Definition of Poverty: Based on Monthly Per Capita Expenditure (MPCE) ₹972 (rural) and ₹1,407 (urban) at 2011–12 prices, equating to ₹32/day (rural) and ₹47/day (urban).
    • Data & Methodology: Used Modified Mixed Reference Period (MMRP) consumption data with separate rural–urban baskets, adjusting for state-wise price differentials.
    • Poverty Estimate (2011–12): Found 29.5% of India’s population below the poverty line.
    • Key Revision over Tendulkar: Expanded consumption basket to include education, healthcare, rent, transport, and other essentials; replaced calorie-based with expenditure-based cost-of-living approach.

    RBI 2025 Update (DEPR Study):

    • Source & Method: Conducted by RBI’s Department of Economic & Policy Research (DEPR) using HCES 2022–23 data for 20 states; retained Rangarajan framework.
    • New Price Index: Created a Poverty Line Basket (PLB) index instead of CPI reflecting actual consumption inflation more accurately.
    • PLB Composition: Rural PLB had 57% food share (vs 54% in CPI); Urban PLB had 47% (vs 36% in CPI).
    • Key Findings:
      • Rural Odisha poverty fell from 47.8% → 8.6%; Urban Bihar from 50.8% → 9.1%.
      • Lowest Poverty: Himachal Pradesh (0.4% rural), Tamil Nadu (1.9% urban).
      • Highest Poverty: Chhattisgarh (25.1% rural; 13.3% urban).
    • Significance: Confirms broad-based poverty decline yet highlights regional disparities; renews calls for a new official poverty line reflecting modern consumption trends.
    [UPSC 2019] In a given year in India, official poverty lines are higher in some States than in others because
    Options: (a) poverty rates vary from State to State
    (b) price levels vary from State to State *
    (c) Gross State Product varies from State to State
    (d) quality of public distribution varies from State to State


  • [27th August 2025] The gender angle to India’s economic vulnerabilities

    PYQ Relevance

    [UPSC 2021] Examine the role of ‘Gig Economy’ in the process of empowerment of women in India.

    Linkage: The article highlights that India’s economic vulnerabilities are aggravated by its failure to integrate women into the workforce. While traditional women-dominated export sectors face instability due to tariff shocks, the gig economy offers a new pathway for empowerment. Platforms like Urban Company demonstrate how women can earn sustainable incomes (₹18,000–25,000/month) with safety, insurance, and skill development. Thus, the gig economy is not just an employment option but a structural enabler of women’s empowerment, mobility, and autonomy. However, as the article stresses, formalisation of gig work, targeted policy support, and social protections are vital to make this empowerment sustainable.

    Mentor’s Comment

    India’s economic rise is undeniable, valued at $4.19 trillion, it is poised to be the world’s third-largest economy. Yet, the proposed 50% U.S. tariffs on Indian exports highlight an uncomfortable truth: India’s growth story is fragile because it has failed to empower half its population. This article unpacks how gender imbalance in labour markets is no longer a social concern but an economic vulnerability.

    Introduction

    India’s ascent as a global economic power is being tested by external shocks such as U.S. tariff hikes targeting $40 billion worth of Indian exports. Unlike China, which diversified and scaled its manufacturing, India’s labour-intensive sectors, textiles, gems, leather, footwear, remain exposed. These are precisely the industries that disproportionately employ women. The looming disruption reveals a deeper structural weakness: India’s persistently low female labour force participation rate (FLFPR). What was once viewed as a social development challenge is now a core economic liability threatening the sustainability of India’s demographic dividend.

    The U.S. tariff shock and its economic implications

    1. Targeted exports: U.S. tariffs at 50% could shave off nearly 1% from India’s GDP, directly hitting sectors employing 50 million workers, many of them women.
    2. Comparative disadvantage: India could face a 30–35% cost disadvantage against competitors like Vietnam.
    3. Dependency: The U.S. absorbs 18% of India’s exports, exposing India’s lack of diversification.
    4. Employment vulnerability: An export decline of up to 50% could destabilise women-dominated industries.

    Women’s participation as India’s strategic liability

    1. Persistently low FLFPR: Stuck at 37–41.7%, far below China’s 60% and the global average.
    2. Lost GDP potential: IMF estimates closing the gender gap could boost India’s GDP by 27%.
    3. Cultural and systemic barriers: Patriarchal norms, unpaid care work, safety issues, poor public transport, and sanitation gaps keep women away from education and jobs.
    4. Urban stagnation: Urban female labour participation shows little improvement despite rising education levels.

    The ticking clock of India’s demographic dividend

    1. Demographic window: India’s working-age population outnumbers dependents, but this will close by 2045.
    2. Historical lessons: China, Japan, and the U.S. capitalised on their demographic peak to fuel growth; Southern Europe failed due to low female participation, resulting in stagnation.
    3. Risk of lost opportunity: Without women’s integration, India risks a slowdown before fully realising its demographic advantage.

    Lessons from global experiences in women’s empowerment

    1. U.S. during WWII: Women’s labour mobilised with equal pay and childcare.
    2. China’s post-1978 reforms: FLFPR at 60%, backed by state-supported childcare and education.
    3. Japan’s reforms: FLFPR rose from 63% to 70%, boosting GDP per capita by 4%.
    4. Netherlands model: Flexible part-time work with full benefits, relevant for India’s context.
    5. Common thread: Institutional investments in legal protections, skills, and care infrastructure.

    Emerging solutions and policy innovations within India

    1. Karnataka’s Shakti Scheme: Free bus travel boosted female ridership by 40%, improving access to jobs, education, and autonomy.
    2. Targeted fiscal policies: Tax incentives for female entrepreneurs, digital inclusion drives, and gender-skilling programmes.
    3. Gig economy empowerment: Urban Company employs 15,000+ women, offering ₹18,000–25,000/month along with maternity benefits and insurance.
    4. Public schemes: Rajasthan’s Indira Gandhi Urban Employment Guarantee Scheme generated 4 crore person-days of work, with 65% jobs for women, enabling many to work for the first time.

    Conclusion

    The U.S. tariff threat is a wake-up call, India’s economic fragility lies not just in external shocks but in internal neglect of women’s potential. Empowering women is no longer a matter of social justice but a strategic necessity for sustaining growth, harnessing the demographic dividend, and achieving global competitiveness. The choice is stark: invest in women and rise as a resilient power, or ignore them and remain vulnerable to shocks and stagnation.

  • 23% of PM Jan Dhan accounts inoperative

    Why in the news?

    The Government informed Parliament that 23% of the 56.04 crore PM Jan Dhan Yojana accounts are inoperative.

    About Pradhan Mantri Jan Dhan Yojana (PMJDY):

    • Launch: Introduced in 2014 as the world’s largest financial inclusion mission.
    • Objective: To provide banking to the unbanked, insurance to the unsecured, and credit to the unfunded.
    • Accounts: Basic Savings Bank Deposit (BSBD) accounts with zero balance, minimal paperwork, and e-KYC facility.
    • Benefits: RuPay debit card with accident insurance, overdraft, micro-insurance, and pension coverage.

    Key Features:

    • Access: Universal banking through branches and Business Correspondents.
    • Overdraft: Up to ₹10,000 for eligible account holders.
    • Insurance: Accident cover of ₹1 lakh (₹2 lakh for new accounts post-2018); life cover of ₹30,000 for accounts opened between August 2014–January 2015.
    • Interoperability: Enabled via RuPay cards and Aadhaar-linked platforms.
    • Post-2018 Expansion: Coverage extended to all unbanked adults, overdraft limit enhanced, and eligibility age increased from 60 to 65 years.
    • Direct Benefit Transfers: Strengthened subsidy delivery through the JAM Trinity (Jan Dhan–Aadhaar–Mobile).

    Do you know?

    As per the Reserve Bank of India (RBI) guidelines (2009), an account is considered dormant if no transaction occurs for over two years.


    [UPSC 2015] Pradhan Mantri Jan-Dhan Yojana’ has been launched for

    Options:

    (a) providing housing loan to poor people at cheaper interest rates

    (b) promoting women’s Self-Help Groups in backward areas

    (c) promoting financial inclusion in the country*

    (d) providing financial help to the marginalized communities


  • Financial Inclusion Index, 2025

    Why in the News?

    The Reserve Bank of India (RBI) has announced that the Financial Inclusion Index (FI-Index) for Financial Year (FY) 2025 has risen to 67.0, up from 64.2 in FY 2024.

    About Financial Inclusion Index (FI-Index):

    • Developer: Created by the Reserve Bank of India to assess the extent of financial inclusion in India.
    • First Release: Published in August 2021 for the financial year ending March 2021.
    • Coverage: Encompasses five key sectors—banking, investments, insurance, postal services, and pensions.
    • Scoring Scale: Ranges from 0 (total exclusion) to 100 (full inclusion).
    • Update Cycle: Updated annually in July; cumulative index with NO base year.
    • Indicators: Based on 97 indicators across all five sectors to ensure comprehensive assessment.
    • Key Parameters:
      1. Access (35%): Measures availability of financial infrastructure like bank branches, automated teller machines, and postal outlets.
      2. Usage (45%): Tracks frequency of use of services like savings, loans, insurance, and pension schemes.
      3. Quality (20%): Assesses financial literacy, consumer protection, equity, and service reliability.

    India’s Performance Over the Years:

    • March 2017: Index at 43.4, reflecting the initial phase of inclusion efforts.
    • March 2021: Rose to 53.9, due to the expansion of banking and digital infrastructure.
    • March 2024: Improved to 64.2, with broader access and increased adoption of financial services.
    • March 2025: Reached 67.0, driven by digital transactions, better service quality, and financial literacy campaigns.
    [UPSC 2016] The establishment of ‘Payment Banks’ is being allowed in India to promote financial inclusion. Which of the following statements is/are correct in this context?

    1. Mobile telephone companies and supermarket chains that are owned and controlled by residents are eligible to be promoters of Payment Banks

    2. Payment Banks can issue both credit cards and debit cards

    3. Payment Banks cannot undertake lending activities

    Options: (a) 1 and 2 only (b) 1 and 3 only* (c) 2 only (d) 1, 2 and 3


  • Concern over falling household savings in India – what can be done

    Why in the News?

    India’s household savings rate fell to 29.7% of GDP in 2022–23, the lowest level in 40 years, down from 34.6% in 2011–12.

    What led to the decline in household financial savings in India?

    • Rise in Consumption Expenditure: After the COVID-19 pandemic, households increased spending on consumer durables, travel, and lifestyle, reducing the capacity to save.
    • High Inflation: Persistent rise in prices of essentials like food, fuel, and healthcare eroded disposable income and limited savings.
    • Shift Towards Riskier Financial Assets: Investments in mutual funds and equities increased, with SIP contributions rising significantly, while traditional savings like fixed deposits declined.
    • Slow Income Growth and High Interest Rates (Fisher Effect): Stagnant wages and low nominal income growth, coupled with high interest rates and loan EMIs, reduced household savings potential.
    • Rising Household Debt: Household liabilities reached 6.4% of GDP in FY24, due to more borrowing for housing, education, and personal loans.
    • Reversal of COVID-Era Forced Savings: Savings spiked during lockdowns but dropped sharply as economic activity resumed and pent-up demand surged.

    Why is the shift to financial assets important for capital formation?

    • Improves Resource Mobilisation: Financial assets like deposits, mutual funds, and pension funds channel household savings into productive sectors, supporting investment and infrastructure growth.
    • Enhances Financial Intermediation and Efficiency: Financial institutions act as intermediaries, allocating savings to sectors with higher returns and productivity, ensuring efficient capital use. Eg: Banks mobilise savings into loans for MSMEs, which contribute significantly to employment and GDP.
    • Reduces Idle Capital and Boosts Formal Economy: Unlike physical assets (like gold and real estate), financial assets contribute to the formal economy, increasing credit availability and financial inclusion. Eg: Shift from gold to digital savings accounts increases liquidity and boosts credit growth in the economy.

    How has rising household debt impacted financial stability?

    • Increased Vulnerability to Economic Shocks: High debt levels reduce households’ ability to absorb income shocks (like job loss or medical emergencies), leading to loan defaults and stress on financial institutions. Eg: During the COVID-19 pandemic, many households defaulted on EMIs due to income loss, affecting NBFCs and banks.
    • Reduced Net Financial Savings: Growing liabilities shrink the net financial savings rate, limiting the funds available for productive investments and weakening domestic capital formation. Eg: In FY24, household liabilities rose to 6.4% of GDP while financial savings fell to 5.1%, a four-decade low.
    • Pressure on Banking and Credit Systems: High levels of unsecured loans (like personal and gold loans) increase credit risk, prompting regulatory tightening and affecting credit flow to the economy. Eg: RBI imposed stricter norms on personal loans in FY25 to prevent systemic risk from unsecured lending growth.

    What steps can improve savings among rural and low-income groups?

    • Promote Micro-Savings Products: Introduce low-ticket savings schemes tailored for daily or weekly contributions. Eg: The PM Jan Dhan Yojana encourages basic savings with zero-balance accounts.
    • Provide Government-Backed Guarantees and Incentives: Offer interest subsidies, insurance cover, or guaranteed returns to build trust among low-income savers. Eg: The Kisan Vikas Patra and Public Provident Fund (PPF) offer guaranteed returns with sovereign backing.
    • Expand Financial Literacy Campaigns: Run focused awareness drives on budgeting, saving, and investment options in local languages. Eg: RBI’s Financial Literacy Week and SEBI’s village workshops educate people on safe saving practices.
    • Leverage Digital and Fintech Solutions: Use mobile wallets, micro-investing apps, and digital payment systems to make saving more accessible. Eg: Platforms like Paytm Payments Bank and Airtel Payments Bank offer micro-savings and insurance.
    • Revamp and Strengthen Post Office Schemes: Modernise postal savings with better accessibility, digital interface, and doorstep banking. Eg: Rural Post Offices now offer core banking services, enabling safer and formal saving options.
    • Introduce Default Saving Options (Behavioral Nudges): Implement opt-out pension schemes or auto-enrollment in saving plans for informal workers. Eg: The Atal Pension Yojana encourages informal sector workers to save for retirement through auto-debits.

    Way forward: 

    • Develop a National Household Savings Strategy: Create a coordinated policy framework across ministries with clear targets, integrating financial literacy, product innovation, and social security measures for underserved populations.
    • Encourage Inclusive Fintech Innovations: Promote user-friendly micro-investing platforms, AI-driven financial guidance, and blockchain-based savings tools to enable secure, transparent, and accessible savings for rural and low-income households.

    Mains PYQ:

    [UPSC 2017] Among several factors for India’s potential growth, savings rate is the most effective one. Do you agree? What are the other factors available for growth potential?

    Linkage: The artilce explicitly state that India’s gross domestic savings rate fell to its lowest in four decades (29.7% of GDP in 2022-23). This question directly related to the importance of the savings rate for India’s growth, which aligns with the concern over falling household savings. 

  • India breaks into top 100 of SDG Index for the first time

    Why in the News?

    In a major milestone, India has ranked 99th out of 167 countries in the 2025 edition of the Sustainable Development Report (SDR), released by the UN Sustainable Development Solutions Network.

    What are Sustainable Development Goals (SDGs)?

    • Definition: SDGs are 17 global goals adopted by all UN member states in 2015 to end poverty, protect the planet, and promote peace and prosperity by 2030.
    • Core Focus: They balance economic growth, social inclusion and environmental sustainability for a better future.
    • Scope: The goals cover health, education, gender equality, clean water, economic growth, climate action, and governance.
    • Global Framework: They are part of the 2030 Agenda for Sustainable Development adopted by the UN.

    About Global SDG Rankings:

    • Report Publisher: The Sustainable Development Report is released annually by the UN Sustainable Development Solutions Network, led by Jeffrey Sachs.
    • Methodology: It ranks 167 countries using an SDG Index score out of 100 based on performance across all 17 goals.
    • Score Interpretation: A score of 100 means full achievement of all SDGs; lower scores show partial or poor implementation.
    • Data Sources: Rankings are based on a mix of social, economic, environmental, and governance indicators.
    • Global Patterns: European countries dominate top ranks; countries with conflict or debt rank lower.
    Note: In India, we also have our own SDG India Index released by NITI Aayog.

    Key Highlights of the Rankings:

    • India’s Rank 2025: India ranks 99th with a score of 67—its first time in the top 100.
    • Major Countries’ Ranking: China ranks 49th (74.4); the US ranks 44th (75.2) but is 193rd in SDG policy support.
    • Neighbourhood Comparison: Bhutan ranks 74th (70.5), Nepal 85th (68.6), Bangladesh 114th (63.9), Pakistan 140th (57), Sri Lanka 93rd, and Maldives 53rd.
    • Top Performers: Finland, Sweden, and Denmark lead the world in SDG achievement.
    • Areas of Progress: Global gains include access to electricity, mobile broadband, internet, and lower child mortality.
    • Major Setbacks: Challenges include rising obesity, declining press freedom, biodiversity loss, and growing corruption.
    • Target Gaps: Only 17% of SDG targets are on track to be achieved by 2030.
    [UPSC 2016] Consider the following statements:

    1. The Sustainable Development Goals were first proposed in 1972 by a global think tank called the ‘Club of Rome’.

    2. The Sustainable Development Goals have to be achieved by 2030.

    Which of the statements given above is/are correct?

    Options: (a) 1 only (b) 2 only * (c) Both 1 and 2 (d) Neither 1 nor 2