Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS2-19.Effect of policies and politics of developed and developing countries on India’s interests, Indian diaspora.

  • Saudi Arabia is facing a two-strait dilemma

    Why in the News

    Houthi forces have taken the Red Sea coast of Yemen and the Bab el-Mandeb strait, and their occupation of Perim Island gives them an unobstructed line of sight over commercial traffic through a channel carrying roughly 12 percent of global trade. The capture follows a Houthi declaration of a naval blockade of Saudi Arabia, itself a response to Saudi fighter jets damaging the runway at Sana’a airport to stop an Iranian aircraft landing without clearance. With the Strait of Hormuz already disrupted, Saudi Arabia had shifted its loading to the Red Sea port of Yanbu. A second closed strait therefore leaves the kingdom without an unobstructed sea route to its Asian buyers, and it has cut crude production in response.

    What is the Bab el-Mandeb strait?

    1. Bab el-Mandeb: It is the sole channel connecting the Red Sea to the Gulf of Aden, so it is the only sea route between the Arabian Sea and the Suez Canal.
    2. Perim Island: It sits inside the strait and divides it into two channels, so whoever holds the island observes and can engage traffic passing on either side.
    3. Closure reroutes rather than delays: A ship denied the strait cannot reach the Suez Canal at all and has to sail around the Cape of Good Hope instead.
    4. The two strait exposure: Saudi Arabia’s eastern terminals load through the Strait of Hormuz and its western terminal at Yanbu loads through Bab el-Mandeb, so its seaborne exports depend on two separate chokepoints.

    How did the Houthis take the strait?

    1. The war’s origin: Yemen’s civil war began in the aftermath of the Arab Spring and has flared up with renewed intensity.
    2. From threat to control: The Houthis had threatened the waterway with long range weapons for years, and now hold the coastline itself.
    3. The forces that failed to hold it: Saudi backed forces did not support the United Arab Emirates aligned factions deployed along the coast.
    4. Infighting compounded the gap: Internal infighting among those factions aggravated the failure, so the strait was seized with minimal resistance.
    5. What the blockade brought with it: Regular attacks on Saudi tankers in the Red Sea and on the kingdom’s oil related facilities have accompanied it.

    What has the blockade done to Saudi oil exports?

    1. The pipeline behind Yanbu: The port is supplied by the 1,200 km East West pipeline running from the eastern oilfields across the peninsula.
    2. Where that oil went: Nearly 70 percent of it moved to Asia through Bab el-Mandeb before the naval blockade began in July.
    3. The rerouting: Flows through the strait have dwindled sharply, and shipments have been redirected through the Suez Canal and around the African continent.
    4. The production cut: Crude output fell to 6.2 million barrels per day in August, the lowest level this year, against over 10 million in January.

    Why has external help not arrived?

    1. The American refusal: The United States promised intelligence and declined a Saudi request for direct involvement.
    2. The stated calculation: Washington does not wish to open another front, and any direct American or Western intervention would lead the Houthis to broaden their strikes.
    3. The electoral consideration: The resulting spike in global oil markets is what the US administration is keen to avoid ahead of the midterm elections in November.
    4. The Mecca Alliance partners: Pakistan and Turkey are reluctant to commit militarily except in the event of an invasion of Saudi Arabia, and are concerned about provoking the Houthis further.
    5. The precedent: Pakistan refused a Saudi request to join the Yemen war in 2015, notwithstanding the bilateral security agreement the two signed in 1982.

    What leverage have the Houthis and Iran gained?

    1. Demonstrated capability: When the United States targeted them in 2025, they were reported to have shot down several American drones and nearly hit a number of fighter jets.
    2. The next objective: They have begun moving to capture Marib, east of Sana’a, the centre of Yemen’s oil and gas industry.
    3. Why Marib matters: Taking it would strengthen their bargaining position in any negotiated settlement.
    4. Iran’s gain: Iran has added ending the blockade of Yemen to its conditions for a lasting settlement with the United States.
    5. The position this creates: Riyadh faces a reluctant United States, hesitant alliance partners and two contested maritime chokepoints at the same time.

    Challenges to Saudi Arabia’s seaborne export security

    1. Pipeline capacity sits below export volume: The East West pipeline moves only a part of the kingdom’s exports to the Red Sea, so shifting west cannot substitute for the eastern terminals. Eg. Ras Tanura on the Gulf coast remains the largest loading terminal and lies inside the Hormuz route.
      The Fix: Expand the interconnection between the eastern fields and the Red Sea terminals, and hold standing chartered tonnage for the longer route.
    2. Rerouting costs fall on the seller: A voyage around the Cape of Good Hope raises freight, crew and insurance on every cargo, and buyers on term contracts do not absorb it. Eg. War risk premiums on Red Sea transits rose steeply once shipping there came under attack from 2023.
      The Fix: Hold pre positioned floating storage and product stocks near Asian buyers, so a longer voyage does not interrupt contracted deliveries.
    3. A production cut is not quickly reversed: Shutting in wells to match reduced export capacity carries reservoir and restart costs, so output does not simply resume when the route reopens. Eg. Idle spare capacity has historically taken months to bring back to full rates after a deep cut.
      The Fix: Balance through storage rather than through shut ins, using domestic and leased overseas tank capacity to keep wells producing while shipments are constrained.
    4. Air defence cannot cover terminals and tankers together: Defending fixed oil facilities and moving tankers spread across a wide sea area needs different systems and far more of them. Eg. The 2019 strikes on the Abqaiq processing facility removed about half of Saudi crude output at a stroke.
      The Fix: Pair fixed site defence with escorted convoying on the Red Sea leg, so the tanker leg is not left to individual operators.
    5. The security guarantee is an expectation, not an obligation: The kingdom’s protection has rested on an American commitment that carries no treaty duty to act. Eg. The United States did not respond militarily to the 2019 strikes on Saudi oil facilities either.
      The Fix: Convert the arrangement into a written commitment with defined triggers, or build the indigenous capability the expectation currently substitutes for.

    Conclusion

    An oil exporter’s power rests on the certainty that its cargoes will sail, and that certainty now depends on a stretch of water held by a non state armed movement. Riyadh’s options have narrowed to conceding demands it has refused for years, or sustaining counterattacks long enough to reopen the route, with no external force willing to do either on its behalf. The unresolved tension is between a security posture built on an external guarantee and a guarantor that has declined to act. The marker to watch is Marib, since control of Yemen’s oil and gas centre would largely settle the balance in any negotiated outcome.

    Maritime chokepoints in global trade

    1. Chokepoint: It is a narrow channel on a major shipping route with no practical alternative nearby, so traffic concentrates there and a disruption at that one point affects the entire route.
    2. Strait of Hormuz: It connects the Persian Gulf to the Gulf of Oman and carries the seaborne exports of Saudi Arabia, Iraq, the United Arab Emirates, Kuwait, Qatar and Iran, the largest volume of oil and liquefied natural gas passing any single point in the world.
    3. Strait of Malacca: It links the Indian Ocean to the South China Sea and carries the bulk of the crude moving to China, Japan and South Korea, which is why energy planners in those countries treat it as a standing vulnerability.
    4. Suez Canal and its only alternative: The canal shortens the Asia to Europe route by thousands of nautical miles, and the sole alternative, the Cape of Good Hope, adds roughly two weeks to a voyage.

    Back2Basics: the Houthis

    1. Name: The movement calls itself Ansar Allah, and Houthi is the family name of its founding leadership.
    2. Origin: It emerged in the 1990s as a Zaidi revivalist movement in Saada province in northern Yemen.
    3. Control: It captured the capital Sana’a in 2014 and holds much of the country’s northwest, where a large share of Yemen’s population lives.
    4. External backing: Iran supplies weapons and technical support, which is what converts Houthi control of the strait into leverage for Tehran.

    Matching Previous Year Question

    “Ships from which of the following countries have to cross the Strait of Hormuz to reach out to the Indian Ocean? 1. Bahrain 2. Syria 3. Qatar 4. Egypt”
  • Pakistan’s westward turn – strategic depth or overstretch

    Why in the News

    Pakistan and Kuwait signed a defence cooperation agreement on 27 August 2026, the latest step in a rapidly expanding Pakistani strategic footprint in West Asia. It follows the Makkah Agreement of 7 August, under which Saudi Arabia, Türkiye and Pakistan agreed that an armed attack against one member would be regarded as an attack against all. Pakistan has also acted recently as an intermediary between Iran and the United States. What is new is not Pakistani involvement in West Asia, which is decades old, but its institutionalisation into standing commitments with a secretariat behind them. The contest is over what those commitments actually buy: strategic depth against India, or an overstretch that ties Pakistan into rivalries it cannot control.

    What is the Makkah Agreement?

    1. Signatories and the collective defence clause: Signed on 7 August among Saudi Arabia, Türkiye and Pakistan, it stipulates that an armed attack against one member would be regarded as an attack against all.
    2. The permanent secretariat in Saudi Arabia: At a meeting in Istanbul on 31 August, the three countries’ Foreign and Defence Ministers and military chiefs decided to establish a permanent secretariat in Saudi Arabia.
    3. The Secretary General post: A Pakistani will serve as its first Secretary General for three years.
    4. Interoperability and defence industrial cooperation: The three agreed to strengthen military interoperability and to pursue defence industrial cooperation, including joint technology development and production.

    What are the historical roots of Pakistan’s West Asian orientation?

    1. A dual identity from the start: From its inception Pakistan attempted to combine its South Asian geopolitical identity with that of a major Muslim power.
    2. The Cold War architecture: Pakistan, Iran and Türkiye were linked through the Central Treaty Organization (CENTO) and subsequently through the Regional Cooperation for Development.
    3. The 1971 defeat as the turning point: Pakistan’s defeat and dismemberment in 1971 pushed it towards the Arab world, as it sought to compensate for its diminished position in South Asia by emphasising its Islamic identity.
    4. The Lahore Islamic summit of 1974: The Islamic summit held in Lahore in 1974 marked the reorientation, and Pakistan simultaneously developed extensive military relationships with Saudi Arabia and the Gulf monarchies.

    What contradictions does the new arrangement already face?

    1. Houthi attacks as the first test: Renewed Houthi missile and drone attacks against Saudi Arabia created the first serious test of the Makkah pact.
    2. The Houthis have improved their position at sea: Their capture of Mocha port and Perim island has added to their capability to choke off Saudi shipping through the Bab al-Mandab.
    3. Closure of the Strait of Hormuz: With the Strait of Hormuz effectively closed by Iran, a frustrated Saudi Arabia may relaunch a full scale war against the Houthis.
    4. The collective defence clause dilemma: Such a war would create a major dilemma for Pakistan if Riyadh decided to invoke the collective defence provision of the Makkah agreement.
    5. Pakistan is holding five roles at once: It wants to be Saudi Arabia’s security partner, Türkiye’s strategic ally, Iran’s friend and interlocutor, Washington’s useful intermediary and a security provider to the Gulf monarchies, and these roles are compatible only when regional tensions are manageable.

    What does the westward turn give Pakistan against India?

    1. Defence in depth through a security network: A Pakistan embedded in a web of West Asian security relationships may acquire defence in depth.
    2. Saudi finance, Turkish technology and Gulf access: Saudi financial resources, Turkish defence technology and Pakistan’s expanding relationships with Gulf militaries can in theory increase Islamabad’s resilience in a confrontation with India.
    3. Türkiye’s position on Kashmir: Türkiye is Pakistan’s most vocal major supporter on Kashmir.
    4. Pakistan’s nuclear status as currency: Pakistan’s nuclear status enhances its strategic value to Arab states concerned about an unstable regional order created by a nuclear armed Israel’s policies.

    Why could the same turn weaken Pakistan against India?

    1. Pakistan’s India centric security establishment: Pakistan’s security establishment has historically concentrated overwhelmingly on India.
    2. The new commitments pull resources away: Diplomatic, military and intelligence resources now have to be devoted to Iran, Saudi Arabia, the Gulf, Yemen and the Red Sea, leaving fewer to concentrate on India.
    3. Entanglement is the price of entry: The deeper Pakistan becomes embedded in West Asian security arrangements, the harder it becomes to remain aloof from the region’s conflicts.
    4. The Riyadh versus Tehran choice: If the Houthi Saudi confrontation escalates, Islamabad may have to choose between honouring the credibility of its collective defence commitments and maintaining its relationship with Tehran, the Houthis’ principal ally.

    How should India read it?

    1. Exposure that comes with the new role: Pakistan’s growing West Asian role should not be interpreted in purely negative terms, because the same relationships expose it to some of the world’s most combustible rivalries.
    2. The Gulf states have their own stake in India: Saudi Arabia, the United Arab Emirates and the other Gulf states hold major economic and strategic relationships with India that they are unlikely to sacrifice for Pakistan.
    3. India’s response, deeper Gulf engagement: New Delhi should continue deepening those relationships as the counter to Pakistan’s expanding footprint in West Asia.

    Challenges to the Makkah Agreement

    1. A collective defence clause invites the very conflict it deters: A guarantee that is credible draws its guarantor into wars it did not choose, and a guarantee that is not credible is worthless. Eg. The pact’s first test arrived within weeks, through Houthi attacks on Saudi Arabia.
      The Fix: Define the triggering threshold in writing, naming what constitutes an armed attack and what response is owed, so the guarantee is bounded rather than open ended.
    2. The three signatories do not share an adversary: Türkiye, Saudi Arabia and Pakistan each face different threats, and a pact without a common opponent has no agreed contingency to plan against. Eg. Türkiye’s principal security concerns lie in the eastern Mediterranean and northern Syria, not in the Red Sea.
      The Fix: Restrict joint planning to the functional areas already agreed, meaning interoperability and defence industrial production, rather than to a shared war plan that does not exist.
    3. A permanent secretariat does not create a command: Standing staff can coordinate procurement and exercises, and none of that generates a force able to act on the clause. Eg. The secretariat’s first Secretary General holds a three year term with no operational forces assigned to the arrangement.
      The Fix: Establish a standing combined planning cell with earmarked national units, so the commitment has a force attached to it rather than an office.
    4. Pakistan’s fiscal position limits what it can actually provide: A security guarantor needs sustained defence spending, and Pakistan’s is constrained by repeated recourse to external financing. Eg. Pakistan has been a recurring borrower from the International Monetary Fund across successive programmes.
      The Fix: Convert the arrangement’s defence industrial pillar into Saudi and Turkish funded production inside Pakistan, so the commitment generates revenue rather than consuming it.
    5. The arrangement cuts across Pakistan’s Iran relationship: A pact aimed at protecting Saudi Arabia from an Iran aligned force is difficult to reconcile with an intermediary role between Tehran and Washington. Eg. Pakistan shares a long land border with Iran, across which both states have previously conducted strikes.
      The Fix: Keep the intermediary role at the level of the Foreign Ministry and separate from the pact’s military structures, so one function does not discredit the other.

    Conclusion

    The institutional step taken in August converts a long standing set of bilateral military relationships into a commitment Pakistan can be called on to honour, at a moment when the region is already at war. That is a different proposition from the financial and manpower arrangements it has run with the Gulf for fifty years, because those could be scaled back quietly and a collective defence clause cannot. For India the reading should be neither alarm nor relief, since the same arrangement that adds to Pakistan’s depth also adds to the claims on its attention. The marker to watch is whether Riyadh invokes the clause against the Houthis, because that is the point at which the commitment stops being a document.

    West Asia in India’s Foreign Policy

    1. Evolution of India’s West Asia policy: Guided after Independence by non alignment and a pro Arab position, it moved to full diplomatic ties with Israel in 1992, a Look West launch in 2005 centred on the Gulf Cooperation Council (GCC), and a Think West approach from 2014 extending to maritime security, counter terrorism and investment.
    2. The energy dependence: The region supplies nearly 60% of India’s crude and about 70% of its liquefied petroleum gas and liquefied natural gas needs.
    3. The economic weight: India GCC bilateral trade stood at $178 billion in FY 2024-25, making the GCC India’s largest trading partner bloc, and the region contributes about 38% of India’s global remittances.
    4. The human stake: A diaspora of about 10 million people works across the region, which makes West Asian stability a domestic political question in India.

    Back2Basics: Central Treaty Organization

    1. CENTO’s origin as the Baghdad Pact: A Cold War defence pact, originally the Baghdad Pact of 1955, renamed CENTO after Iraq withdrew in 1959.
    2. Membership: Its members were Iran, Türkiye, Pakistan and the United Kingdom, with the United States as an associate rather than a full member.
    3. Purpose, containment of Soviet expansion: It was built to contain Soviet expansion along its southern periphery, linking the North Atlantic Treaty Organization to the Southeast Asia Treaty Organization.
    4. Dissolution in 1979: It dissolved in 1979 after the Iranian Revolution, and Pakistan’s withdrawal followed.

    Matching Previous Year Question

    “[2025, GS2, 10 marks] With the waning of globalization, post-Cold War world is becoming a site of sovereign nationalism. Elucidate.”

  • Trump’s unusual threat to US Federal Reserve and why it matters to India

    Why in the News

    The US President has warned the Federal Reserve (Fed) to cut interest rates, and has said the United States would otherwise stop trading with countries against which it runs a trade deficit. A central bank’s rate decision is not normally tied to a trade threat, which is what makes the statement unusual. It follows US government debt crossing a record $40 trillion and a trade deficit that has widened despite a slew of tariffs on trade partners. Pressure that begins as a US fiscal problem therefore arrives in India as demands on trade terms. India and the United States have been negotiating a bilateral trade agreement since February 2025, and the framework they announced for an Interim Agreement has already unsettled farmers.

    What is the US Federal Reserve?

    1. The central bank of the United States: It sets US policy interest rates and is charged with keeping prices stable and employment high.
    2. Rate decisions sit outside the executive: They are taken by a committee whose members hold fixed terms, which is the arrangement that separates monetary policy from the government of the day.
    3. Its rates set the price of money worldwide: The yield on the US 10 year government bond is the benchmark against which global borrowing costs are priced.

    Why is the United States pressing for lower interest rates now?

    1. The debt stock has crossed a record: US government debt has passed $40 trillion.
    2. Debt measured against output: The Council on Foreign Relations puts the US debt to gross domestic product (GDP) ratio at 125%.
    3. Interest now costs as much as defence: International think tanks estimate the US government will spend a little over $1 trillion this fiscal year servicing interest on the debt, which matches its national defence spending.
    4. Borrowing costs are rising, not falling: Rising oil prices from the US-Iran war have made investors warier of the debt, pushing the 10 year yield towards 5%. A rate cut is the cheapest available relief on the interest bill.
    5. Tariffs did not close the gap: The trade deficit widened even after tariffs were imposed across trade partners, which removes the argument that tariffs alone would correct it.

    How does US fiscal pressure reach India?

    1. The template is the China deficit: Washington has narrowed its trade deficit with China to the lowest in two decades, and has begun pressing partners such as India to deliver the same.
    2. First front, market access: Steep market access demands are being pressed through the trade deal negotiations.
    3. Second front, investment diversion: Investment is being drawn out of India and into the United States.
    4. Third front, input origin: India is under pressure to lower its dependence on inputs originating in China.
    5. The stated ground for the third front: The US position is that China operates a “shadow transhipment network”. On that reading, routing Chinese goods through third countries widens the effective US trade deficit, displaces US domestic production, reduces GDP growth and lowers federal tax receipts.

    What has India already conceded?

    1. Energy purchases: India has stepped up energy imports from the United States.
    2. Tariff cuts across consumer goods: Duties have been lowered on a broad range of products of US interest, from motorcycles to whiskey.
    3. Tax concessions: A tax holiday has been extended to datacentres and to items needed to expand nuclear power production in India.
    4. The LPG shift is already measurable: The US share of India’s liquefied petroleum gas (LPG) imports has crossed 50% in the six months since the West Asia crisis began.

    What does the trade framework put at risk for Indian farmers?

    1. A negotiation already long running: India and the United States have been negotiating a bilateral trade agreement since February 2025.
    2. An interim step was announced: The two countries announced a framework for an Interim Agreement in February this year.
    3. The named exposure: Trade experts warn that lower customs duties on US imports would put direct pressure on Indian growers of apples, cotton, grapes, oranges, soybeans and walnuts. Each is a crop where US output is price competitive at the Indian border, so the duty is what currently holds the domestic price.
    4. The tension is live before any cut: The framework has created considerable tension among farmers while the duty lines themselves remain unchanged.

    Why is accommodation raising Indian costs rather than lowering them?

    1. Cotton sourcing rules reach Indian mills: US restrictions on the use of cotton originating in China’s Uyghur region have made Indian spinners the preferred supply, and fear of US scrutiny is pushing cotton prices higher.
    2. The price move is large: The Apparel Export Promotion Council (AEPC) reports cotton yarn prices up around 60%, from about Rs 250 a kg in early 2026 to about Rs 400 a kg currently.
    3. Exporters are asking for restriction, not liberalisation: Indian apparel exporters approached the Commerce and Industry Ministry and the Textile Ministry last month seeking regulation of cotton yarn exports to arrest the surge.
    4. The contradiction: Accommodating the United States on input origin has raised the cost base of the export sector the market access is meant to serve.

    Challenges to India in absorbing US trade pressure

    1. Concessions are hard to reverse: A duty cut granted to win market access becomes the baseline from which the next round of demands starts. Eg. The motorcycle and whiskey duty lines already conceded.
      The Fix: Bind each concession to a stated reciprocal commitment with a review date, so it lapses where the counterpart obligation is not met.
    2. Diversified energy sourcing has narrowed into dependence: Buying more from one supplier to ease a trade dispute concentrates a supply that was diversified precisely to reduce risk. Eg. The LPG share shift noted above occurred inside a single half year.
      The Fix: Set a ceiling on the share of any single crude or gas supplier in the import basket, reviewed annually against the diversification target.
    3. Cutting Chinese inputs raises the input bill: Indian manufacturing depends on Chinese intermediates, so removing them substitutes a costlier input rather than removing a cost. Eg. China supplies a large majority of India’s imports of active pharmaceutical ingredients, for which comparable domestic capacity does not exist.
      The Fix: Stage any input substitution requirement behind a domestic capacity milestone, so the switch follows the capability rather than preceding it.
    4. Farm liberalisation has no compensation channel: A duty cut lowers the price the grower receives, and no mechanism transfers the consumer gain back to the grower. Eg. Edible oil duty cuts held retail prices down and left domestic oilseed growers facing imported palm and soya oil at a lower landed cost.
      The Fix: Attach a price deficiency payment to any agricultural tariff line opened under a trade agreement, funded from the revenue the agreement is projected to generate.
    5. Monetary policy abroad sets India’s borrowing cost: A US yield near 5% pulls capital away from emerging markets whatever India’s own policy rate does. Eg. Foreign portfolio investors withdrew from Indian debt during earlier episodes of rising US Treasury yields.
      The Fix: Lengthen the maturity profile of government borrowing while domestic rates are low, so a later rise in global yields reprices a smaller share of the stock each year.

    Conclusion

    The pressure India is managing originates in the American fiscal position rather than in any Indian trade practice. That makes it insensitive to what India offers, since a concession which does not shrink the US deficit invites the next demand. Accommodation on those terms has no natural stopping point, and each round narrows the room available for the next. What to watch is whether the agreement under negotiation settles the agricultural tariff lines or leaves them to a later round.

    Back2Basics: Interim and early harvest trade agreements

    1. What it is: A partial trade agreement covering a limited set of tariff lines, concluded ahead of a full free trade agreement, so both sides bank early gains while the harder chapters continue.
    2. What it leaves out: Services, investment, government procurement and dispute settlement are typically deferred to the full agreement.
    3. The WTO condition: World Trade Organization (WTO) rules permit a preferential deal only where it covers substantially all trade between the parties, so an interim deal is defensible only as a stage in a wider agreement with a stated timetable.
    4. India’s use of the form: India signed the Economic Cooperation and Trade Agreement with Australia in 2022 as an interim deal ahead of a fuller Comprehensive Economic Cooperation Agreement.

    Matching Previous Year Question

    “[2025, GS3, 10 marks] What are the challenges before the Indian economy when the world is moving away from free trade and multilateralism to protectionism and bilateralism? How can these challenges be met?”

  • Dangerous phase

    Why in the News

    United States forces have struck five Iranian oil tankers in Gulf waters, citing Iranian attacks on U.S. warships in the region. Iran has answered with a ballistic missile attack on the Muwaffaq Salti U.S. air base in Jordan, and has promised a stronger response to every further U.S. strike. It has also declared a new restricted zone in the Strait of Hormuz, warning commercial ships against crossing it under American naval escort. The U.S. had until recently used intense military strikes and economic strangulation as separate tools, and is now applying both at once. The pressure has produced escalation instead of concessions, and the conflict has widened to Jordan, Saudi Arabia and the Red Sea.

    What has changed in the U.S. approach to Iran?

    1. Two instruments applied together: Military strikes and economic strangulation were used separately in the recent past to force Iran to surrender. They are now being used simultaneously as maximum pressure on Tehran.
    2. The blockade has closed the revenue line: The U.S. naval blockade has largely prevented Iran from exporting its oil.
    3. Escorted convoys have blunted the chokepoint: American naval escort for a limited number of ships out of the Strait of Hormuz has reduced the effect of Iran’s chokehold on global energy prices.

    Why has maximum pressure not produced concessions?

    1. Iran escalated rather than conceded: Iran attacked American warships outside the Persian Gulf in the knowledge that a stronger U.S. military response would follow.
    2. A reading of American domestic politics: Iran sees a window in the weeks before the U.S. midterm elections. The U.S. President remains politically weak at home.
    3. Strike capability has been rebuilt: The missile attack on U.S. bases in Jordan indicates capabilities that the U.S. President had claimed were destroyed.

    How far has the conflict spread beyond Iran and the U.S.?

    1. Saudi Arabia has been drawn in: Yemen’s Houthis, closely aligned with Tehran, launched an attack on Saudi Arabia and wounded dozens. Riyadh has vowed a response.
    2. A second maritime front: The Houthis control northern Yemen and parts of its Red Sea coast, and have enforced a naval blockade of Saudi Arabia’s western ports.
    3. A ground offensive inside Yemen: The Houthis have launched an offensive against the forces of Yemen’s Saudi-backed government in Taiz and Mocha.
    4. Two waterways at risk at once: The Strait of Hormuz and the Red Sea, the trade channel between Europe and Asia, are both flashpoints. The conflict now runs horizontally from Tehran to Jordan and from Riyadh to Bab-el-Mandeb.

    Challenges to a maximum pressure strategy

    1. Coercion without an exit ramp invites escalation: A campaign that offers no negotiated off-ramp leaves the target with escalation as its only remaining lever. Eg. The U.S. left the Joint Comprehensive Plan of Action (JCPOA), the 2015 nuclear agreement, in 2018 and reimposed sanctions, and Iran began exceeding the agreement’s enrichment limits from 2019.
      The Fix: Attach a stated and verifiable de-escalation offer to each coercive step, so compliance carries a defined and reversible reward.
    2. Energy prices transmit the conflict to uninvolved economies: A threat to a shipping chokepoint raises freight, war-risk insurance and crude costs for states with no part in the dispute. Eg. Attacks on shipping in the Red Sea from late 2023 pushed carriers to route around the Cape of Good Hope, adding roughly two weeks to Asia to Europe voyages.
      The Fix: Hold deeper strategic petroleum reserves and pre-contract alternative routings, so a closure is absorbed over months rather than priced within days.
    3. Aligned armed groups let the target strike elsewhere: Sanctions imposed on a state do not reach the armed groups that act with it. Eg. The September 2019 attack on Saudi Aramco’s Abqaiq and Khurais facilities halted about half of Saudi crude output for a period.
      The Fix: Combine weapons transfer interdiction with a regional maritime security arrangement that includes the Gulf states, rather than an escort force drawn only from Western navies.
    4. Inspection access closes before the fighting does: Coercion removes the monitoring that would verify any later agreement. Eg. Iran stopped implementing the Additional Protocol, its expanded inspection arrangement with the International Atomic Energy Agency (IAEA), in February 2021.
      The Fix: Ring-fence safeguards access from the coercive track, so inspections continue whatever the state of the political negotiation.

    Conclusion

    Neither side is placed to step back. Washington has committed to military and economic coercion at the same time and has no concession to show for it. Tehran has answered each strike with a wider one and gains from escalating during a period of unsettled American politics. The marker to watch is whether the new restricted zone is enforced against an escorted convoy, since that is the point at which a shipping war becomes a general one.

    Back2Basics: Strait of Hormuz

    1. Location: A narrow sea passage between Iran to the north and Oman and the United Arab Emirates to the south, linking the Persian Gulf with the Gulf of Oman and the Arabian Sea.
    2. Dimensions: Roughly 33 km wide at its narrowest point, with the designated shipping lanes about 3 km wide in each direction.
    3. Traffic: Close to a fifth of global petroleum liquids consumption moves through it, along with most of Qatar’s seaborne liquefied natural gas.
    4. Bypass routes: Saudi Arabia’s East-West pipeline to the Red Sea and the United Arab Emirates’ Habshan to Fujairah pipeline are the only routes that move Gulf crude to open sea without crossing the strait.

    Matching Previous Year Question

    “[2026] Ships from which of the following countries have to cross the Strait of Hormuz to reach out to the Indian Ocean? 1. Bahrain 2. Syria 3. Qatar 4. Egypt (a) 1 and 2 (b) 1 and 3 (c) 2 and 3 (d) 3 and 4 ANSWER: (b)”

  • Bogged down

    Bogged down

    Why in the News

    The tension is that the war’s declared objective and its actual battlefield no longer match, since the fighting now turns entirely on the Strait rather than on the nuclear programme.

    How did the war’s objective shift to the Strait?

    1. The stated aims have been displaced: The central focus of the war today is the Strait of Hormuz, not the nuclear facilities or the political order the campaign was launched to change.
    2. Iran chose the ground and Washington accepted it: Tehran forced the United States to fight over a problem it created rather than pursue Washington’s original objective, which is in itself a strategic victory for Iran.
    3. The chokehold has not been broken: Iran still maintains its control over the waterway, so the single condition the campaign now exists to remove remains in place.

    What has the escalation actually consisted of?

    1. Iran has crossed into attacks on military vessels: This is the first time in months that Iran has targeted United States warships, apparently seeking to break the naval blockade.
    2. The United States has crossed a red line in return: By striking Iranian oil tankers in retaliation, Washington extended the war to commercial shipping under Iranian flag.
    3. Six vessels struck in one round: The Islamic Revolutionary Guard Corps (IRGC), Iran’s parallel armed force reporting to the Supreme Leader, announced that it had struck six vessels in the Gulf, three tankers and three United States-linked ships, in retaliation for the American attacks on oil tankers, and vowed to expand strikes against United States ships.
    4. The exchange has spread to land targets: The return to American strikes triggered Iranian attacks on United States bases in Kuwait, Bahrain and Jordan.

    Why has economic warfare not changed Iran’s position?

    1. The policy shifted from strikes to pressure and then back: The United States President moved the focus of Iran policy to economic warfare last month, announcing new sanctions and tightening the United States Navy’s blockade of Iran’s ports. Unable to find a way out, Washington returned to strikes.
    2. The workaround was matched: The United States managed to get some oil tankers through the Strait via a southern route along the Omani coast, and Iran continued to target vessels taking that route.
    3. Economic pain has raised Iran’s risk appetite rather than lowered it: Iran has emerged more assertive despite its economic difficulties, and the more Washington seeks to trap it in an economic gridlock, the less risk-averse Tehran becomes.

    What does the absence of a theory of victory mean?

    1. Neither instrument has produced a change of position: Neither the military effort nor the economic warfare has forced Iran to alter its stance, and the Strait remains unsafe while the toll on the global economy mounts.
    2. Attrition has replaced strategy: The administration is ‘mowing the lawn’, a doctrine taken from the Israeli playbook that seeks to periodically degrade an adversary’s attack capability without attempting to defeat it.
    3. Iran is running its own attrition strategy: Tehran pursues ‘debasification’, pushing United States military presence away from its immediate periphery each time it retaliates.
    4. Both sides are chasing an outcome neither can reach: Each seeks escalation dominance, the ability to raise the level of force to a point the other cannot match, and the war therefore risks spiralling out of control.

    Challenges to reviving a negotiated framework

    1. The declared aim of regime change is incompatible with a negotiated outcome: No government negotiates the terms of its own removal, so the objective and the talks track cancel each other out. Eg. The talks channel collapsed within months of being opened while the military campaign continued.
      The Fix: Separate the nuclear file from the political objective and negotiate only the first, as the 2015 nuclear agreement did.
    2. Verification capacity has been destroyed along with the facilities: Strikes on nuclear sites remove the baseline against which any future inspection regime would measure compliance. Eg. Access for International Atomic Energy Agency inspectors has been the recurring breaking point since the Joint Comprehensive Plan of Action was agreed in 2015.
      The Fix: Restore inspector access as the first deliverable of any revived framework, before sanctions relief is discussed.
    3. American commitments carry a credibility discount: A negotiated framework abandoned once is harder to sell domestically in Tehran the second time. Eg. The United States withdrew from the Joint Comprehensive Plan of Action in 2018 despite Iranian compliance being certified.
      The Fix: Anchor any revived understanding in a United Nations Security Council resolution rather than in an executive arrangement that a change of administration can reverse.
    4. A pause that leaves the blockade in place gives Iran no reason to stop: Iran’s attacks on shipping are its only instrument against the economic siege, so a ceasefire on attacks alone asks it to surrender the leverage. Eg. Iranian targeting of the southern route began after the blockade of its ports was tightened.
      The Fix: Pair a halt to attacks on shipping with a defined easing of the port blockade, so each side gives up an instrument simultaneously.
    5. The costs land on third-party importers with no say in the war: Energy importers absorb the freight, insurance and price consequences of an unsafe Strait without being party to the dispute. Eg. India draws a large share of its crude oil imports from West Asian suppliers whose cargoes transit the Strait.
      The Fix: Convene the major Asian importers as a bloc to press both sides on the narrow question of shipping safety, separately from the nuclear dispute.

    Conclusion

    Six months of strikes and sanctions have moved neither Iran’s position nor the safety of the waterway. The war has produced an unresolved tension rather than a stalemate that can simply be held: the party with overwhelming military superiority cannot convert it into an outcome, and the party under economic siege grows less cautious the tighter the siege becomes. The talks track collapsed once and remains the only route either side has actually attempted, which is why its revival, rather than the next round of retaliation, is the development to watch.

    Back2Basics

    1. Strait of Hormuz: The sea passage connecting the Persian Gulf to the Gulf of Oman and the Arabian Sea, and the only maritime outlet for oil exported from the Gulf producers.
    2. Geography: It is about 33 km wide at its narrowest point, with inbound and outbound shipping lanes only a few kilometres wide, bounded by Iran on the northern shore and by Oman and the United Arab Emirates on the southern shore.
    3. Why it is a chokepoint: Roughly a fifth of the world’s seaborne oil moves through it, and there is no alternative sea route out of the Gulf, so a threat to the lane transmits directly into global crude prices.
    4. Bypass capacity: Pipelines run by Saudi Arabia to the Red Sea and by the United Arab Emirates to Fujairah can carry only a fraction of the volume that normally transits the Strait.

    [2018, GS2, 15 marks] In what ways would the ongoing US-Iran Nuclear Pact Controversy affect the national interest of India? How should India respond to this situation?

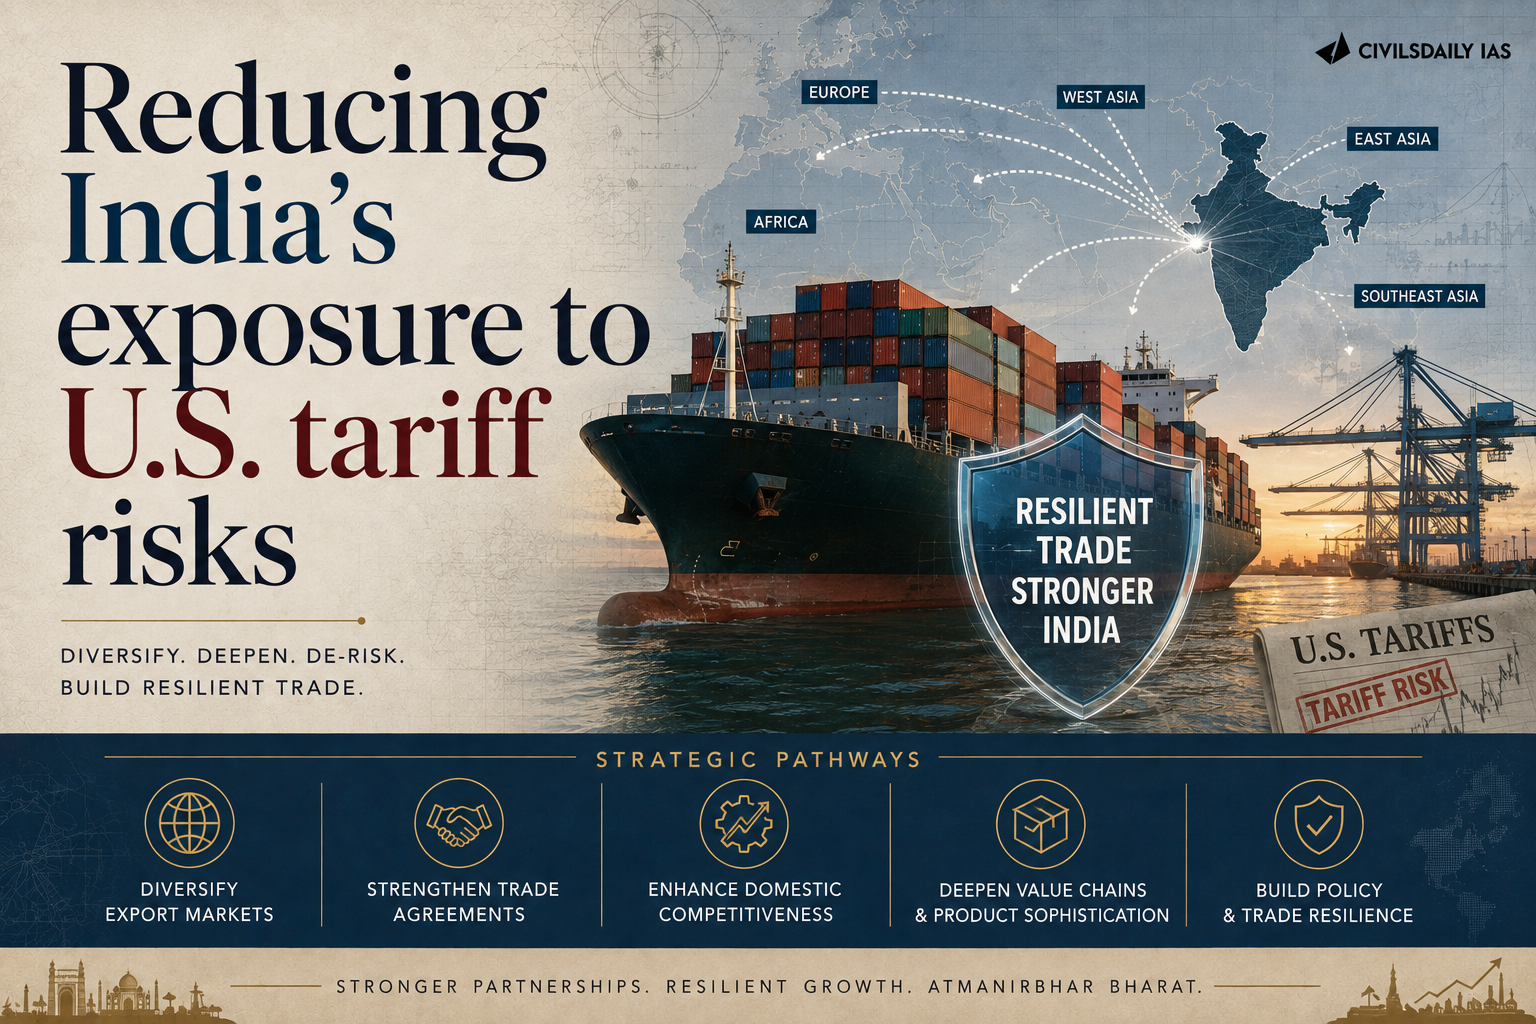
  • [3rd September 2026] The Hindu OpED: Reducing India’s exposure to U.S. tariff risks

    [3rd September 2026] The Hindu OpED: Reducing India’s exposure to U.S. tariff risks

    Question (2025 – GS2): “Energy security constitutes the dominant kingpin of India’s foreign policy, and is linked with India’s overarching influence in Middle Eastern countries.” How would you integrate energy security with India’s foreign policy trajectories in the coming years?
    Linkage: This question directly addresses the concept of energy security as a “kingpin” of foreign policy. The U.S. sanctions act forces India to navigate its sovereign energy import strategy (specifically from Russia) while attempting to shield its vital foreign policy trajectories and trade arrangements with Western partners from massive tariff penalties.

    Mentor comment

    The U.S. Senate has passed the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026, authorising tariffs of up to 100% on countries among the top five importers of Russian crude or gas. Combined with existing forced-labour tariffs, India’s cumulative U.S. tariff exposure could reach 110%. The Act exposes a conflict between India’s energy security strategy and its trade relationship with the United States.

    Why has Russian crude become a trade exposure rather than an energy choice?

    1. Diversification of supply produced concentration of risk: India moved towards Russian crude to reduce its import bill and gain room to manoeuvre amid global uncertainty, and that single decision now determines its tariff status in an unrelated market.
    2. The volumes are still rising: Imports nearly doubled within 2026, from 4.54 million metric tonnes (MMT) in January to 8.96 MMT in May.
    3. The cost is diplomatic before it is fiscal: Securing the supply has complicated the management of ties with the United States, which seeks to discourage these purchases, and the Russia sanctions legislation is the formal expression of that pressure.

    How does India’s cumulative tariff reach 110 per cent?

    1. A tariff was already imposed before this Bill: The United States applied forced labour tariffs on 60 countries, including India, under Section 301 of the Trade Act of 1974, adding a 10% tariff on India in place of an expired 10% duty levied under Section 122.
    2. The sanctions provision stacks on top: If the Russia sanctions legislation becomes law, the additional 100% authorisation takes India’s cumulative tariff to 110%, among the highest applied to any country.
    3. The comparator is also India’s competitor: China’s cumulative tariff would reach 112.5%, since both countries are major importers of Russian crude, so relative price competitiveness in the United States market shifts less than the absolute number suggests.

    What does a tariff confrontation cost the Indian economy?

    1. The method: Two global trade simulations were run using the Global Trade Analysis Project (GTAP) dataset and model, a general equilibrium framework that traces how a tariff shock in one market propagates through production, demand and trade flows in every other.
    2. The sanction scenario: Modelling a 110% United States tariff on India, with other countries facing forced labour tariffs and China facing 112.5%, India’s welfare declines by nearly $47 billion, and gross domestic product, output, domestic demand, exports and imports all contract.
    3. The trade contraction is the largest single effect: Aggregate exports fall by 5.1% and imports by 5.2%, reflecting disrupted trade flows and weaker economic activity. A prolonged tariff confrontation imposes substantial costs on India’s growth and trade performance.

    Does export diversification offset the shock?

    1. The second scenario changes only the destination mix: The same tariff environment was modelled alongside export diversification, proxied by a full India-European Union free trade agreement.
    2. The direction of the result reverses: Welfare improves by $26.3 billion, gross domestic product turns positive, and sectoral output and domestic demand recover by around 1%.
    3. Trade integration replaces the lost market: Aggregate exports rise by 3.1% and imports by a moderate 2.6%, indicating stronger production and deeper integration with alternative markets.
    4. The policy implication is separable from the oil question: Even if India continues procuring Russian crude for energy security, the adverse effects of the tariffs are mitigated to a large extent by diversifying where it exports.

    Why is diversification not a sufficient answer on its own?

    1. It depends on demand India does not control: Diversification works only to the extent that other markets can absorb additional Indian exports, and without adequate external demand it remains limited on paper.
    2. The United States cannot be written off: It remains one of India’s largest export destinations, so diversification is an addition to that market rather than a replacement for it.
    3. Domestic constraints cap the gain: Trade facilitation delays, non tariff barriers, weak logistics and standards, and a product mix concentrated in lower value goods all limit how much of a new market India can actually capture.

    Challenges to export diversification as a response to tariff risk

    1. A free trade agreement is not the same as realised exports: Tariff concessions deliver nothing where Indian exporters cannot meet the destination market’s standards and compliance requirements. Eg. Indian shrimp and spice consignments have faced repeated European Union border rejections over antibiotic and pesticide residue limits.
      The Fix: Fund accredited testing and certification laboratories at export clusters, so conformity assessment happens before shipment rather than at the importing port.
    2. Rules of origin can neutralise a preference: A partner country can grant duty free access and still block goods that use imported inputs beyond a stated value addition threshold. Eg. Indian electronics assembly relies heavily on imported components, which restricts qualification under strict origin rules.
      The Fix: Negotiate cumulation provisions that count inputs sourced from other partner economies towards the value addition requirement.
    3. Logistics cost erodes the tariff advantage: Higher freight and dwell times offset the duty saved when the alternative market is farther away than the one being replaced. Eg. Container dwell time and inland haulage costs remain a recognised drag on the delivered price of Indian goods.
      The Fix: Sequence dedicated freight corridor and port connectivity completion against the entry into force dates of the trade agreements being signed.
    4. Concentration simply moves rather than disappears: Replacing dependence on one large market with dependence on one large agreement reproduces the same vulnerability under a different flag. Eg. The exposure being addressed here arose precisely because a single destination carried a disproportionate share of Indian exports.
      The Fix: Set a ceiling share for any single destination in the export promotion strategy, and target Africa, Latin America and West Asia alongside the European Union.

    Conclusion

    The finding that matters here is that the loss is a function of market concentration rather than of the tariff itself. That reframes the policy problem: the question is not how to make the tariff go away, but how to make the destination mix wide enough that a tariff in any one market cannot set the direction of the whole economy. Trade agreements deliver that only when the supply side can use them, which means testing and certification capacity, faster clearance, and movement up the goods quality ladder have to be built before the agreements enter into force rather than after. The measure of success is not the number of agreements signed but the share of exports the largest single destination accounts for.

    About India-United States Trade and Investment Ties

    1. Scale of the relationship: Bilateral trade between the two countries stood at $149.84 billion in 2025-26.
    2. India runs a surplus, and it is narrowing: India’s trade surplus with the United States narrowed to $34.4 billion in 2025-26 from $40.89 billion in the previous financial year.
    3. Investment flows both ways: The United States is the third largest investor in India, with cumulative foreign direct investment inflows of $70.65 billion between 2000 and 2025.
    4. Indian capital in the United States: About 163 Indian companies operating there have created over $40 billion in tangible investments.

    Challenges in India-United States Relations

    1. Preferential access has already been withdrawn once: Trade concessions granted unilaterally can be revoked without negotiation, which makes them an unreliable base for export planning. Eg. The United States revoked India’s benefits under the Generalized System of Preferences in 2019, citing a lack of equitable access.
      The Fix: Convert the interim trade arrangement into a binding bilateral trade agreement, so market access rests on treaty commitment rather than on unilateral grant.
    2. Digital and data rules pull in opposite directions: Indian data localisation requirements conflict with the operating models of United States technology firms. Eg. The Digital Personal Data Protection Act, 2023 and its rules govern cross border transfer of personal data on terms those firms have contested.
      The Fix: Negotiate an adequacy style mutual recognition arrangement covering data transfer, so compliance is assessed once rather than jurisdiction by jurisdiction.
    3. Intellectual property standards remain contested: India is placed on the United States Priority Watch List for what is described as weak patent protection in pharmaceuticals. Eg. The dispute centres on Section 3(d) of the Patents Act, 1970, which bars patents on new forms of known substances without enhanced efficacy.
      The Fix: Run a standing bilateral working group on patent examination practice, so the disagreement is litigated technically rather than through annual watch list designations.
    4. Mobility restrictions hit India’s largest services export: Immigration and visa restrictions raise the cost of the delivery model on which Indian information technology services depend. Eg. A $100,000 fee on H-1B petitions materially changes the economics of onsite deployment.
      The Fix: Conclude a social security totalisation agreement and push services mobility commitments into the trade negotiation rather than treating them as an immigration matter.

    Back2Basics: Section 301 of the Trade Act of 1974

    1. What it is: A provision of United States trade law that allows the United States Trade Representative to act against a foreign country’s acts, policies or practices that are found to be unjustifiable or unreasonable and to burden United States commerce.
    2. What action it permits: It authorises retaliatory measures, including additional duties on imports from the country concerned, without requiring a prior finding by any multilateral body.
    3. Why it is contentious: Unilateral retaliation under it sits uneasily with the World Trade Organization dispute settlement system, which requires disputes to be adjudicated before countermeasures are applied.
    4. How India has encountered it: India has been the subject of Section 301 action before, including the investigation into its equalisation levy on digital services.
  • Russian oil imports fell 26% in Aug amid supply pressure, China factor

    Russian oil imports fell 26% in Aug amid supply pressure, China factor

    Why in the News

    India’s oil imports from Russia fell 26 per cent in August from the historic highs of July, driven by tighter Russian export availability and stronger competition from Chinese refiners, according to provisional tanker data. Those July highs were themselves a product of the shift in India’s import strategy since March 2026, when Strait of Hormuz disruptions tightened West Asian oil flows. The fall in Russian volumes was the primary reason for the over 8 per cent decline in India’s overall oil imports in the month, even as imports from Venezuela reached their highest monthly level since 2020. The open question is whether August is a temporary retreat or the start of a period in which Russian barrels become scarcer, costlier and harder for Indian refiners to secure.

    How sharp was the fall, and does the data show a structural retreat?

    1. The Russian volume: India imported 2.08 million barrels per day (bpd) of Russian oil in August, down 26.3 per cent from July’s record 2.82 million bpd, on vessel tracking data from the commodity market analytics firm Kpler.
    2. The total intake: India’s total oil imports stood at 4.62 million bpd in August, down 8.4 per cent from July’s 5.04 million bpd.
    3. Russia’s share: Moscow’s share of India’s crude imports declined to 45 per cent in August from 55.9 per cent in July.
    4. Domestic contribution: Maintenance shutdowns at a few Indian refineries also contributed to the lower crude intake.
    5. Kpler’s reading: The shift points to market normalisation rather than a structural retreat from Russian crude. Flows are expected to stabilise at 2.0 to 2.5 million bpd, so Russian oil remains the mainstay of India’s imports.

    Why are Russian barrels getting harder to move to India?

    1. Attacks on export infrastructure: Ukrainian attacks on Russia’s oil and gas infrastructure are a key reason for the pressure on Russian exports. Attacks on export infrastructure in the Black Sea have become a tangible threat to the navigation of energy tankers in the region.
    2. The Black Sea freight penalty: Moving a Suezmax tanker (a crude carrier sized to transit the Suez Canal fully loaded) from the Black Sea port of Novorossiysk to India’s west coast now costs about $20 million, or roughly $20 per barrel, compared with about $13 per barrel from the Baltic Sea ports.
    3. The Baltic seizure risk: Dispatches from the Baltic ports carry their own risk, since Russian tankers sailing around Europe face detention or seizure by European countries.
    4. The Arctic route favours China: Russian exporters are sending more vessels through the Northern Sea Route, for which August and September are the peak traffic months even in a normal year because ice is thinnest. Black Sea drone threats add to that pressure, and the Arctic routing makes China the most cost-competitive destination.

    Why is China competing harder for the same cargoes?

    1. Russia is exporting less: Moscow is trying to maximise domestic refinery production to meet domestic fuel demand amid the Ukrainian attacks on its energy infrastructure, which lowers the crude available for export to India and to everyone else.
    2. Iranian barrels have thinned: Iranian oil volumes available to Chinese refiners have fallen amid the Strait of Hormuz crisis, pushing Chinese buyers towards Russian cargoes.
    3. The question for the coming months: With Russia exporting less to India and overall, and China competing more aggressively for available cargoes, the issue is whether Russian barrels become scarcer, costlier and harder for Indian refiners to secure.

    How has the Hormuz crisis reshaped India’s import slate?

    1. The break in March 2026: India’s crude import strategy shifted sharply since March 2026 as Strait of Hormuz disruptions tightened West Asian oil flows and increased freight risks.
    2. The scale of the Gulf loss: About 40 per cent of India’s crude imports usually came through the Strait of Hormuz, and a large part of that supply has effectively been offline.
    3. Diversification beyond Russia: Russian crude remains the backbone of the import slate, and refiners have diversified aggressively towards African, North American and South American barrels to offset the drop from the Gulf.
    4. Venezuela’s return: Imports from Venezuela jumped 60.2 per cent over July to 350,000 bpd in August. India restarted Venezuelan imports a few months ago after nearly a year of zero imports, once the US allowed Caracas’s oil to flow into the global market.
    5. How Venezuelan oil was unlocked: After the US captured Venezuela’s then President in early January, the US President said Washington would take control of Caracas’s oil sector. A few commodity traders were then authorised by Washington to sell Venezuelan oil, previously under US sanctions, globally.

    Conclusion

    Russian crude still anchors India’s imports, and the August fall reads as normalisation rather than exit. The pressure is now on the supply side, in Russia’s own export capacity and in China’s bidding for the same barrels. The figure to watch is whether India’s Russian intake holds its recent range in September, when Arctic routing to China is at its seasonal peak.

    Back2Basics: Northern Sea Route

    1. What it is: An Arctic shipping lane along Russia’s Siberian coast, running from the Kara Sea in the west to the Bering Strait in the east, linking Europe with East Asia.
    2. Why it is seasonal: Sea ice makes it navigable mainly in late summer and early autumn, and outside that window ships need icebreaker escort.
    3. Why it matters: It cuts the Europe to East Asia distance substantially compared with the Suez Canal route, and Russia regulates transit through its own Northern Sea Route administration.

    [2025, GS2, 15 marks] “Energy security constitutes the dominant kingpin of India’s foreign policy, and is linked with India’s overarching influence in Middle Eastern countries.” How would you integrate energy security with India’s foreign policy trajectories in the coming years?”

  • Trump administration seeks to restrict internships for international students (CPT rules)Trump administration seeks to restrict internships for international students (CPT rules)

    Trump administration seeks to restrict internships for international students (CPT rules)Trump administration seeks to restrict internships for international students (CPT rules)

    Why in the News

    The Trump administration issued a memo, dated August 24, directing US universities to restrict Curricular Practical Training (CPT) work authorisations for international students. The Student and Exchange Visitor Program (SEVP), part of US Immigration and Customs Enforcement, said it had observed a rise in CPT authorisations that appear to violate the rule permitting CPT only where the training is an integral, curriculum-linked requirement. The memo warned that non-compliant institutions could lose certification to enrol foreign students, prompting the University of California, Los Angeles and the University of California, Berkeley to pause certain CPT applications.

    Why does the CPT restriction matter for Indian students?

    1. Indian students form a large share of the affected pool: Indian nationals are among the largest cohorts of international students in the United States, concentrated in graduate programmes in science, technology, engineering and business where CPT and its post-study counterpart, Optional Practical Training, are commonly used to gain early work experience.
    2. CPT often bridges study and full-time employment: Many international students use CPT internships to secure the practical experience and employer relationships that later translate into full-time job offers and sponsored work visas, so tighter CPT rules narrow that pathway at its earliest stage.
    3. Institutional caution creates immediate uncertainty: Universities such as UCLA and UC Berkeley pausing CPT applications while they review the guidance leaves currently enrolled students without a clear timeline for authorisations they may need for the coming term.

    Challenges the CPT tightening creates

    1. Ambiguity in what counts as curriculum-integral training: The memo does not precisely define the line between legitimate curriculum-linked internships and authorisations SEVP considers a violation, leaving universities to interpret the standard conservatively. Eg. UC Berkeley’s international office described the August 24 memo as “more narrow in focus” and “more restrictive in nature” than earlier guidance, without full clarity on the new threshold. Fix. SEVP could issue detailed, program-specific criteria for curriculum integration, developed in consultation with universities, rather than a general compliance warning.
    2. Institutional risk pushes universities toward blanket caution: Because non-compliance risks an institution’s certification to enrol any foreign student, universities have an incentive to pause CPT broadly rather than assess applications individually, even where most are legitimate. Eg. UCLA paused certain CPT authorisations altogether while it determines next steps, affecting students beyond those the memo specifically targets.

    What is Curricular Practical Training (CPT)?

    Work authorisation tied to the curriculum: Curricular Practical Training is a work authorisation available to international students on an F-1 visa that allows off-campus employment or internships considered an integral part of an established academic curriculum, distinct from Optional Practical Training, which applies mainly after a course of study is completed.

  • Can India build a strategic fuel system?

    Why in the News

    Disruptions related to West Asia have exposed a vulnerability in India’s energy security system. India imports large quantities of crude oil, liquefied natural gas (LNG) and liquefied petroleum gas (LPG), but its ability to store, move and release these fuels during a prolonged disruption differs sharply by fuel. Against this, the government is considering a decade long strategic fuel programme that would add about 28 MT (million tonnes) of crude oil storage, 9 MT of LNG storage and 4 MT of LPG storage. The programme remains under consideration and should be treated as a proposed target rather than committed capacity.

    What is India’s proposed strategic fuel storage programme?

    1. Scale of the proposal: The decade long programme would add about 28 MT of crude oil storage, 9 MT of LNG storage and 4 MT of LPG storage, roughly 41 MT of combined new capacity.
    2. Purpose: The reserves are intended to provide nearly two months of crude oil and LNG demand cover and about six weeks of LPG demand cover during a prolonged supply disruption.
    3. Status: The programme remains under consideration and is a proposed target, not committed capacity.

    How much strategic fuel storage does India already have?

    1. Crude storage is the most developed: Phase I of the Strategic Petroleum Reserve provides 5.33 MT of underground capacity, with actual storage of about 3.37 MT, or roughly 63 to 64 percent utilisation, across Visakhapatnam, Mangaluru and Padur. A further 6.5 MT has been approved under Phase II at Chandikhol and Padur.
    2. Execution has lagged on Chandikhol: Work on the Chandikhol project remains slow amid ongoing land acquisition requirements and the finalisation of commercial public private partnership frameworks.
    3. LPG storage is a fraction of the proposed target: The Visakhapatnam and Mangaluru caverns together provide about 0.14 MT of capacity, so a proposed 4 MT reserve would represent roughly a thirty fold increase in underground LPG capacity.
    4. Natural gas has no underground storage at all: India currently has no operational underground gas storage facility, and its gas security instead depends on domestic production, LNG imports, import terminals, commercial inventories and pipelines.
    5. Capacity is not the same as usable inventory: A facility has a physical capacity, but the fuel it actually holds can vary, and not all inventory is immediately accessible. During a crisis, the critical measure is how much fuel is available and at what withdrawal rate it can reach consumers.

    What does the proposed 9 MT of LNG storage actually mean?

    1. Regasification capacity is not the same as strategic inventory: India already has substantial LNG import and regasification infrastructure, but a regasification terminal’s capacity to convert LNG into natural gas does not itself constitute strategic inventory.
    2. LNG storage and underground gas storage work differently: LNG is stored as a cryogenic liquid at around 162 degrees Celsius below zero, requiring specialised insulated tanks and management of boil off gas. Underground gas storage instead regasifies the LNG first and injects the resulting natural gas into a depleted reservoir or cavern.
    3. A narrower stress test already exists: A study by the Petroleum and Natural Gas Regulatory Board (PNGRB) and the International Copper and Fertiliser (ICF) group examined how much additional LNG infrastructure would be needed to supply priority consumers for a stress period of 20 days by 2030, estimating a requirement of about 0.56 to 0.6 MT of LNG equivalent, achievable with roughly eight additional LNG tanks at a combined cost of about 1 billion dollars.
    4. The proposed reserve is an order of magnitude larger: Against the same study’s projection of roughly 58 MT of annual LNG imports, the proposed 9 MT works out to about 56 days of import cover, which is the basis for describing it as nearly two months of LNG import cover, not two months of India’s total gas consumption.

    Does all of India’s gas storage have to take the form of LNG tanks?

    1. A portfolio approach is possible: India could eventually use a combination of surface LNG tanks and underground natural gas storage rather than LNG tanks alone.
    2. A parallel proposal targets import terminals directly: A separate proposal from the Ministry of Petroleum and Natural Gas would require LNG import terminals to maintain storage capacity 10 percent above their normal operating requirement, with the additional capacity available to the government during supply or price disruptions.
    3. Depleted reservoirs offer the largest potential volumes: Depleted oil and gas reservoirs, which account for 74 percent of global working gas volume, could provide much larger volumes of underground gas storage, while salt caverns allow faster injection and withdrawal, making them more suited to shorter duration balancing.
    4. India has candidate geology but not yet usable storage: India’s sedimentary basins, including Krishna, Godavari, Cambay, Mumbai Offshore and Rajasthan, offer potential locations, but moving from geological potential to usable storage requires subsurface investigation, site selection, engineering, construction, testing, filling and pipeline integration. Rajasthan’s salt bearing formations have similarly been investigated for solution mined caverns, with suitability depending on depth, thickness, purity, geometry, groundwater and mechanical properties.

    What does the United States Strategic Petroleum Reserve show about storage as a system?

    1. Scale achieved through salt caverns: The United States Strategic Petroleum Reserve holds an authorised capacity of 714 million barrels across 60 salt caverns.
    2. Storage works only as part of an infrastructure system: The American reserve functions as an integrated network of caverns, pipelines, marine terminals and refineries, showing that strategic storage is fundamentally an infrastructure system and not simply an underground space.

    How mature are India’s crude and LPG storage systems?

    1. Crude is the most mature component: India already operates underground crude caverns and has developed the associated engineering capabilities.
    2. LPG presents a much larger scaling challenge: LPG storage is technically proven in India, but a proposed 4 MT reserve would require a substantial network of new caverns or other storage facilities, together with import terminals, pipelines, pumping systems and bottling infrastructure.
    3. The Mangaluru cavern illustrates the complexity involved: Underground construction requires geological and hydrogeological investigation, rock mechanics analysis and groundwater management, particularly where work takes place alongside operating surface facilities.

    How is India strengthening the logistics that move fuel once it is stored?

    1. India is investing to reduce reliance on foreign shipping: State run oil refiners and the Shipping Corporation of India plan to invest 1.5 to 2 billion dollars in a joint venture to acquire 59 ships.
    2. Sourcing is being diversified too: Indian Oil is expanding sourcing through new 2027 agreements with Algeria and increased purchases from the United States, while exploring direct stakes in Very Large Gas Carriers to secure greater control over its supply chain.
    3. New pipelines are expanding delivery, not storage: The PNGRB has authorised approximately 1,800 km of new LPG pipelines across six States, involving investment of around 0.7 billion dollars. These pipelines improve connections between supply sources and inland markets and reduce dependence on road movement, but they do not themselves add strategic storage.
    4. Every storage form depends on connectivity to be useful: Underground gas storage is useful only if it can inject into and withdraw from the gas grid at the required rate. LNG tanks are useful only when regasification and downstream pipelines can move the gas onward, and LPG caverns require connections to bottling and distribution systems.

    Who pays for building and running the strategic reserves?

    1. The reported cost remains unconfirmed: A reported 42 billion dollar programme, which the government has yet to confirm, combines infrastructure capital expenditure with the cost of purchasing and maintaining strategic fuel inventories, with more than half expected to go towards storage infrastructure and the balance towards purchasing and filling the reserves.
    2. A cess has been ruled out: Financing is a genuine challenge, and the government has rejected reports that a cess would be charged to pay for the reserves.
    3. Replenishment carries its own cost and risk: Stocks released during a crisis would need to be replenished, potentially when commodity and freight prices are higher, so the policy needs to settle who owns and finances the inventory, minimum stock obligations, emergency release authority, and who bears replenishment and price risk.
    4. A mixed commercial and strategic model could ease the burden: A model that combines commercial and strategic use of the same capacity could reduce the public financing burden, provided the commercially used capacity remains available during emergencies.

    Is storage capacity alone enough for India’s energy security?

    1. Building capacity is only part of the equation: A strategic reserve is effective only if India can access the fuel, transport it inland, and replenish stocks after a release.
    2. Energy security depends on an integrated framework: Reserves buy time, shipping brings the next cargo, pipelines deliver fuel inland, and governance decides how emergency releases are executed, so the real test of the programme is its ability to coordinate all these elements at once when a crisis hits.

    Conclusion

    India’s existing storage differs sharply by fuel, with crude the most developed, LPG a limited underground footprint, and natural gas without any operational underground facility. The proposed 28 MT of crude, 9 MT of LNG and 4 MT of LPG storage would mark a major expansion, but the programme remains under consideration, and its value will depend as much on shipping, pipelines and financing arrangements as on the storage capacity itself.

    Back2Basics: Petroleum and Natural Gas Regulatory Board (PNGRB)

    1. Governing law: PNGRB was set up under the Petroleum and Natural Gas Regulatory Board Act, 2006.
    2. Jurisdiction: It regulates the downstream petroleum and natural gas sector, including refining, processing, storage, transport, distribution, marketing and sale of petroleum products and natural gas, excluding production and exploration.
    3. Mandate: It authorises and lays down technical and safety standards for gas and LPG pipelines and city gas distribution networks, and protects consumer interests while promoting competitive markets.
    4. Relevance here: It is the regulator behind the LPG pipeline authorisations and the LNG stress test study referenced in this item.

    [2025] “Energy security constitutes the dominant kingpin of India’s foreign policy, and is linked with India’s overarching influence in Middle Eastern countries.” How would you integrate energy security with India’s foreign policy trajectories in the coming years?”

  • $100,000 fee for H-1B: The new legal route Trump is pursuing

    $100,000 fee for H-1B: The new legal route Trump is pursuing

    Why in the News

    The US Department of Homeland Security (DHS) has proposed a new $103,265 fee on H-1B visa petitions, using a rulemaking route after a court struck down an earlier attempt to impose the same fee. The earlier fee had relied on a presidential proclamation, which a US court found exceeded executive authority. The administration is now pursuing the same outcome through a formal DHS rulemaking process instead. The move directly affects Indian workers, who receive the largest single-country share of H-1B visas, and sets up a tension between the United States’ stated intent to restrict low-cost skilled immigration and its technology sector’s dependence on Indian software professionals.

    What is the new legal route, and why does it matter?

    1. Rulemaking instead of proclamation: DHS is now proposing the fee through the standard federal rulemaking process, which carries stronger legal footing than a presidential proclamation but takes longer and includes a public comment period.
    2. Same fee, different vulnerability: A fee approved through rulemaking is harder to strike down in court than one imposed by proclamation, since it follows the procedure Congress has authorised for agency rule changes.

    What is the impact on Indian workers?

    1. Concentration of exposure: Indian nationals receive the largest single-country share of H-1B visas each year, so a steep new fee disproportionately raises the cost of hiring or transferring Indian technology professionals to the United States.
    2. Employer cost shift: US employers typically bear the H-1B fee, not visa applicants. The increase is likely to reduce new H-1B filings for Indian applicants rather than being absorbed by individual workers directly.

    Conclusion

    The Department of Homeland Security’s shift to a rulemaking process to reimpose the $100,000-plus H-1B fee is a more durable attempt to restrict skilled immigration than the earlier proclamation. The outcome for Indian workers now depends on the rulemaking’s public comment period and eventual finalisation, not merely a court challenge.

    Back2Basics: H-1B visa

    1. The H-1B is a US non-immigrant visa category for foreign workers in speciality occupations, typically requiring at least a bachelor’s degree in a related field.
    2. It is issued under an annual numerical cap, allocated through a lottery when applications exceed the cap.
    3. Indian nationals have consistently received the largest single-country share of H-1B approvals, concentrated in information technology roles.

    “[2023, GS2, 10 marks] Indian diaspora has scaled new heights in the West. Describe its economic and political benefits for India.”