💥Join UPSC 2027,2028 Mentorship (August Batch) + XFactor Notes & Microthemes PDF

GS Paper: GS2-19.Effect of policies and politics of developed and developing countries on India’s interests, Indian diaspora.

  • Iran war pushes India’s oil & gas import bill up 43%

    Why in the News

    India’s net oil and gas imports rose 43.4 percent in value in April to July of the current financial year, to $57.8 billion from $40.3 billion a year earlier. Import volumes barely moved, so the increase is almost entirely a price effect created by supply tightness and stifled energy flows through the Strait of Hormuz. With 88.3 percent of crude requirement met by imports, India has prioritised supply security over price, and the cost of that choice lands on the trade balance.

    What are net oil and gas imports?

    1. How the figure is built: Net oil and gas imports are arrived at by deducting petroleum product exports from oil, natural gas and petroleum product imports.
    2. Why the deduction matters: India is a net exporter of petroleum products because of its refining capacity, so gross import figures overstate the true external drain.
    3. What it still includes: India also imports some petroleum products, notably liquefied petroleum gas, so the netting does not remove product imports entirely.
    4. Why it is the tracked number: It measures the actual foreign exchange outgo on energy, which is what feeds into the trade balance and the current account.

    What is the Petroleum Planning and Analysis Cell?

    1. What it is: The Petroleum Planning and Analysis Cell (PPAC) is the data and analysis body under the Ministry of Petroleum and Natural Gas. It compiles India’s official import, consumption, production and pricing statistics for petroleum and natural gas.

    What is liquefied natural gas?

    1. What it is: Liquefied natural gas (LNG) is natural gas, primarily methane, cooled to minus 162 degrees C so that it becomes liquid and can be shipped in cryogenic carriers. It must be regasified at a terminal in the importing country before use.
    2. How it is priced: Spot LNG in Asia is priced against the Japan Korea Marker, with Henry Hub and the Title Transfer Facility serving the American and European markets.

    What is liquefied petroleum gas?

    1. What it is: Liquefied petroleum gas (LPG) is propane and butane, produced as a byproduct of oil refining or natural gas processing, and used for domestic cooking, industrial heating and autogas.
    2. How it is priced: It is priced against the Saudi Aramco Contract Price, which is loosely linked to Brent crude.

    Why did the import bill rise 43 percent when volumes barely moved?

    1. Volumes were nearly flat: Oil and LNG imports were only marginally higher in volume terms across April to July.
    2. Crude price did the work: The average landed price of imported crude was about $106 per barrel in April to July, sharply higher than about $68 per barrel in the corresponding period of last year.
    3. Value rose without volume: The crude oil import bill surged by over 56 percent year on year to $63.4 billion even as volumes rose only slightly, to 81.9 million tonnes or about 600 million barrels, from 81.5 million tonnes.
    4. The stated priority: India has been prioritising supply security over price considerations, so it imported at extremely high rates rather than curtail volumes.
    5. Product trade moved the same way: Petroleum product export volumes fell while export value rose, and product import volumes fell faster than product import value, both reflecting high international prices.

    How did each component of the energy trade basket move?

    1. Crude oil imports, volume: 81.9 million tonnes against 81.5 million tonnes a year earlier, a rise of 0.5 percent.
    2. Crude oil imports, value: $63.4 billion against $40.5 billion, a rise of 56.5 percent.
    3. Petroleum product imports, volume: 9.0 million tonnes against 16.4 million tonnes, a fall of 45.1 percent.
    4. Petroleum product imports, value: $5.6 billion against $7.6 billion, a fall of 26.3 percent.
    5. LNG imports, volume: 11,867 million standard cubic metres against 11,269 million standard cubic metres, a rise of 5.3 percent.
    6. LNG imports, value: $5.6 billion against $4.5 billion, a rise of 24.4 percent.
    7. Petroleum product exports, volume: 16.5 million tonnes against 20.1 million tonnes, a fall of 17.9 percent.
    8. Petroleum product exports, value: $16.7 billion against $12.4 billion, a rise of 34.7 percent.
    9. Net oil and gas imports: $57.8 billion against $40.3 billion, a rise of 43.4 percent.

    How exposed is India’s energy basket to the Strait of Hormuz?

    1. Crude dependence: India depends on imports to meet over 88 percent of its crude oil requirement, and its dependence on imported oil for the four months ended July was 88.3 percent, almost flat year on year.
    2. Gas dependence: About half of India’s natural gas consumption is met by imports, brought in as LNG.
    3. Share routed through the strait: Around 40 percent of India’s crude oil imports, 60 percent of its LNG imports and 90 percent of its LPG imports came from West Asia through the strait.
    4. Where the disruption showed: Petroleum product imports declined 45.1 percent in volume to 9.0 million tonnes because supply of major products India imports, such as LPG, was hit by the West Asia conflict.
    5. Why exports fell: India’s petroleum product export volumes fell almost 18 percent year on year to 16.5 million tonnes as domestic fuel supplies were prioritised amid the global supply crunch.

    Why does an oil price shock transmit into the wider economy?

    1. The volume multiplier: India annually imports 1.8 to 2 billion barrels of oil, so every $1 per barrel increase raises the oil import bill by up to $2 billion on an annualised basis.
    2. Share of total imports: Energy imports are a major component of India’s overall imports, so any meaningful increase moves the aggregate import number.
    3. Trade balance and current account: A higher energy bill widens the merchandise trade deficit and feeds directly into the current account deficit.
    4. Inflation channel: Higher landed crude costs pass into transport and freight costs and into the prices of petroleum linked goods.
    5. Exchange rate channel: A larger dollar outgo on energy adds to demand for foreign exchange and weighs on the rupee’s exchange rate.

    Challenges to managing India’s oil and gas import bill

    1. Demand is price inelastic in the short run: Refiners cannot cut crude intake without cutting fuel supply, so a price shock passes straight into the bill. Eg. Crude import volumes rose 0.5 percent even as the crude bill rose 56.5 percent in April to July.
    2. Concentration of LPG sourcing: A single region supplies almost the entire LPG import basket, leaving no substitute route in a disruption. Eg. The West Asian share of India’s LPG imports moves entirely through the Strait of Hormuz, with no second corridor available if the strait closes.
    3. Fixed rupee excise blocks pass through of relief: Central excise duty is levied as a fixed amount per litre rather than as a percentage, so falling crude prices accrue to revenue rather than to consumers. Eg. When Brent fell from $80 to $60 per barrel in early 2025, Delhi petrol fell by only about Rs 2 to 3 per litre.
    4. Strategic reserve cover below international norms: The buffer available to ride out a supply interruption is short of the accepted benchmark. Eg. India’s total crude cover of 74 days sits below the International Energy Agency norm of 90 days of net import cover.
    5. No strategic reserve for gas at all: The gas basket has an operational buffer but no strategic cushion. Eg. India’s LNG storage tanks at regasification terminals give roughly 10 days of operational buffer, with no strategic LNG reserve in existence.
    6. Spot LNG volatility deters utilisation: When spot prices spike, importers switch to coal or fuel oil, stranding regasification capacity. Eg. India’s roughly 42.5 million tonnes per annum of LNG regasification capacity runs at 60 to 65 percent utilisation because switching becomes rational above $15 per MMBtu.
    7. Refinery configuration ties India to sour crude sources: Indian refineries have invested in desulphurisation capacity built around Middle Eastern grades, which limits how fast the basket can be re-sourced. Eg. Most Middle Eastern crude India buys is priced against Dubai and Oman, and Saudi, Iraqi and UAE grades track that benchmark.

    Conclusion

    India’s net oil and gas import bill rose to $57.8 billion in April to July from $40.3 billion a year earlier, a 43.4 percent increase driven almost wholly by price rather than volume. At 88.3 percent crude import dependence and with the West Asian shares of crude, LNG and LPG all routed through the Strait of Hormuz, a chokepoint disruption converts directly into a macroeconomic shock. The figures are provisional data from the Petroleum Planning and Analysis Cell, and the next reading will show whether the price effect persists once Hormuz flows normalise.

    About India’s Crude Oil Procurement and Pricing

    1. Who buys: State owned refiners account for 73 percent of India’s procurement through Indian Oil Corporation Limited, Bharat Petroleum Corporation Limited and Hindustan Petroleum Corporation Limited, with private refiners Reliance Industries and Nayara Energy accounting for 27 percent.
    2. How buying works: Each refiner independently forecasts demand two to three months ahead and negotiates bilaterally with suppliers such as Rosneft, Saudi Aramco and Iraq’s State Organisation for Marketing of Oil.
    3. How it is priced: All contracts are priced as Brent plus or minus a negotiated discount, and Middle Eastern grades track the Dubai and Oman benchmark.
    4. Where crude lands: Crude is received by tanker at Paradip, Mumbai, Kochi and Vadinar.
    5. Quality determines price: Sulphur content and American Petroleum Institute (API) gravity, the measure of a crude’s density, together determine refining cost and product yield, with sweet crude defined as sulphur content below 0.5 percent and sour crude requiring additional processing.

    Regulatory Framework Governing India’s Petroleum and Natural Gas Sector

    1. Ministry of Petroleum and Natural Gas: The apex policy body, which sets the framework for exploration, refining, marketing, pricing and strategic reserves, awards production sharing contracts, and exercises ownership over the public sector oil companies.
    2. Petroleum and Natural Gas Regulatory Board: Regulates refining, processing, storage, transportation, distribution, marketing and sale of petroleum products and natural gas, authorises City Gas Distribution networks, and determines pipeline tariffs on a common carrier basis.
    3. Directorate General of Hydrocarbons: The technical regulator for upstream exploration and production, which manages block allocations, monitors production sharing contracts, verifies reserves, approves field development plans and maintains the National Data Repository.
    4. Oil Industry Development Board: Funded by a statutory cess on domestic crude production, it finances oil industry development and wholly owns Indian Strategic Petroleum Reserves Limited, which operates the underground reserve caverns.
    5. Deregulated retail pricing: Petrol was deregulated in 2010 and diesel in 2014, so the Ministry does not directly set retail pump prices.

    Government Initiatives in the Petroleum and Gas Sector

    1. Strategic Petroleum Reserve: Phase I comprises 5.33 million tonnes of crude across three underground rock caverns at Visakhapatnam, Mangaluru and Padur, with a Phase II commercial cum strategic expansion under public private partnership models.
    2. Hydrocarbon Exploration and Licensing Policy, 2016: Replaced the earlier New Exploration Licensing Policy with a uniform licence covering all hydrocarbons, open acreage licensing and revenue sharing in place of production sharing.
    3. Administered Price Mechanism for domestic gas: The Ministry sets the administered price for domestic natural gas indexed monthly at 10 percent of the Indian Crude Basket price, following the Kirit Parikh Committee recommendations, subject to a floor and ceiling for legacy fields.
    4. Direct Benefit Transfer for LPG: LPG is subsidised through direct transfer, with Rs 300 per cylinder for Ujjwala beneficiaries.
    5. City Gas Distribution expansion: India’s city gas distribution network now covers 98 cities, supplying compressed natural gas for vehicles and piped natural gas for households from a mix of domestic gas and regasified LNG.

    Key Facts about Global Oil Benchmarks and India’s Reserves

    1. Brent crude: North Sea origin, 38 API and 0.37 percent sulphur, traded on the Intercontinental Exchange in London, accounting for 75 to 80 percent of global oil trade and serving as the reference against which all other grades are a premium or discount.
    2. West Texas Intermediate: Cushing, Oklahoma origin, 39.6 API and 0.24 percent sulphur, traded on the New York Mercantile Exchange, accounting for 15 to 20 percent of global trade and typically Brent minus $0 to $5 per barrel.
    3. Dubai and Oman: Persian Gulf origin, 31 to 33 API and 1.0 to 2.0 percent sulphur, traded on the Dubai Mercantile Exchange, accounting for 5 to 10 percent of global trade and typically Brent minus $5 to $15 per barrel.
    4. Why OPEC does not set the price: OPEC controls 40 percent of production but Brent sets 75 to 80 percent of global prices, since markets price oil hundreds of thousands of times a day while OPEC announces targets once and has no enforcement mechanism against quota cheating.
    5. Reserve position: India’s total crude cover is 74 days, made up of 9.5 days from the Strategic Petroleum Reserve and 64.5 days of oil marketing company commercial stocks, against the International Energy Agency norm of 90 days.
    6. LPG and LNG cover: LPG cavern capacity of about 140,000 tonnes gives roughly 22 days of cover against consumption of about 3 million tonnes a month, while LNG has about 10 days of operational buffer and no strategic reserve.
    7. Volatility of spot gas: The Japan Korea Marker swung from $3 per MMBtu in mid 2020 to $70 per MMBtu in August 2022.
    8. Committee recommendation on storage: The Parliamentary Standing Committee on Petroleum in December 2023 recommended equipping refineries with two to three days of smaller strategic storage at five to six additional locations, which could add 15 to 20 days of capacity.

    Back2Basics: Strait of Hormuz

    1. Location: A narrow sea passage connecting the Persian Gulf to the Gulf of Oman and onward to the Arabian Sea.
    2. Control: Iran controls the northern shore and seven of the eight islands in the strait, Oman controls the southern entrance, and the United States Fifth Fleet acts as the external guarantor of transit.
    3. Oil traffic: About 20 million barrels a day pass through it, amounting to 20 percent of global oil movement.
    4. Gas traffic: It carries 20 percent of global LNG trade, which makes closure hit gas hardest given Qatar’s dominance in LNG supply.
    5. Strategic character: It carries the highest concentration of energy flow of any maritime chokepoint in the world.

    Challenges in India’s Energy Security

    1. Stagnant domestic crude production: Falling domestic output pushes import dependence upward regardless of demand. Eg. Cess collections of the Oil Industry Development Board have declined in real terms because domestic crude production has stagnated.
    2. Regulatory conflict of interest: The same ministry sets the pricing environment and owns the companies whose losses that environment creates. Eg. The Ministry of Petroleum and Natural Gas simultaneously regulates the sector and holds ownership rights over Indian Oil Corporation Limited, Bharat Petroleum Corporation Limited and Hindustan Petroleum Corporation Limited.
    3. Gaps in the regulatory perimeter: No single regulator covers the full chain from wellhead to pump. Eg. The Petroleum and Natural Gas Regulatory Board has no jurisdiction over upstream exploration, wellhead gas pricing or LPG retail pricing.
    4. Upstream reservoir disputes slow output: Technical disputes between operators delay field development and carry royalty implications. Eg. The gas migration dispute between ONGC and Reliance Industries in the Krishna Godavari basin required adjudication by the Directorate General of Hydrocarbons.
    5. Chokepoint concentration across all three fuels: Crude, LPG and LNG share the same maritime chokepoint, so diversification of supplier does not diversify route. Eg. LPG moves with crude tankers or on dedicated carriers through the same Strait of Hormuz.
    6. Tax structure blunts price signals: Taxes form roughly 60 percent of the retail pump price, weakening the link between global prices and consumer behaviour. Eg. Delhi petrol at Rs 96 to 97 per litre carried Rs 13 of central excise and Rs 15 to 18 of State value added tax before the crisis.
    7. Storage build out lags the exposure: Reserve expansion depends on capital and cavern geology, both of which take years. Eg. Phase II of the Strategic Petroleum Reserve is being pursued through public private partnership because budgetary funding alone has not delivered the capacity.

    Way Forward

    1. Complete Phase II of the Strategic Petroleum Reserve: Bring the commercial cum strategic caverns on stream to move total cover towards the 90 day International Energy Agency norm.
    2. Adopt the refinery level storage recommendation: Implement the Parliamentary Standing Committee’s December 2023 proposal on refinery level storage, which remains a recommendation rather than sanctioned capacity.
    3. Create a strategic gas reserve: Extend the reserve architecture to LNG, which today has only an operational buffer at regasification terminals.
    4. Shift excise from a fixed levy to an ad valorem levy: This would let consumers receive part of the benefit when crude prices fall, restoring the price signal.
    5. Diversify sourcing away from a single chokepoint: Expand term contracts with Atlantic basin, West African and North American suppliers so that a Hormuz disruption does not strike crude, LNG and LPG supply simultaneously.
    6. Raise domestic production through open acreage: Accelerate block awards under the Hydrocarbon Exploration and Licensing Policy to arrest the decline in domestic output.
    7. Separate ownership from regulation: Move ownership of the public sector oil companies out of the administering ministry so that pricing policy is not set by their shareholder.

    “[2025, GS2, 15] “Energy security constitutes the dominant kingpin of India’s foreign policy, and is linked with India’s overarching influence in Middle Eastern countries.” How would you integrate energy security with India’s foreign policy trajectories in the coming years?”
  • Five years after Taliban takeover, life in Afghanistan marred by many struggles

    Why in the News

    Five years have passed since the Taliban entered Kabul on 15 August 2021, ending the United States led military presence and the Islamic Republic that had governed Afghanistan for two decades. The Taliban have converted military victory into durable control of institutions, borders and revenue, without converting it into recognition, economic recovery or rights for women. That gap defines the position every state now has to work around, including India.

    What is a de facto government?

    1. Definition: A de facto government is an authority that exercises effective control over a territory and its population without being formally recognised as its lawful government by other states. Control is a question of fact, recognition a question of law.
    2. What recognition does: Recognising a government endorses its authority to represent the state internationally, while withholding recognition does not deny that the state itself exists.
    3. Why states still transact: Border management, humanitarian delivery and consular work require dealing with whoever controls territory, which produces engagement without recognition.
    4. What non recognition costs the authority: It blocks the state’s seat at international organisations, access to central bank reserves held abroad and formal sovereign borrowing.

    What is the Islamic State-Khorasan Province?

    1. What it is: The Islamic State-Khorasan Province (ISKP) is the regional branch of the Islamic State operating in Afghanistan, Pakistan and parts of Central Asia, formed in 2015.
    2. Its relationship with the Taliban: It rejects the Taliban’s authority as insufficiently doctrinaire and is an armed rival rather than an ally, which is why the Taliban conduct operations against it.

    What has actually changed in Afghanistan’s security situation since 2021?

    1. The war ended: The most immediate change was the end of the war between the Taliban and the then Afghan government.
    2. The withdrawal and the collapse: The United States and NATO completed their military withdrawal in August 2021, and Afghan security forces collapsed soon afterwards.
    3. Consolidation of control: The Taliban control Afghanistan’s major government institutions, security forces and borders, and armed opposition groups have not been able to mount a significant nationwide challenge.
    4. No comparable conflict: There is now no nationwide armed conflict comparable to the fighting that took place before 2021.
    5. What it means on the ground: Roads previously affected by battles and checkpoints are generally more accessible, and the risk of being caught in clashes between the Taliban and government forces has fallen.

    Why has the end of the war not meant the end of violence?

    1. A surviving armed rival: The Islamic State-Khorasan Province remains active and has carried out attacks against civilians, Taliban officials and foreign nationals.
    2. Counter operations: The Taliban have carried out operations against the group, which makes the conflict internal rather than against a foreign force.
    3. Deteriorating relations with Pakistan: The two countries have repeatedly accused each other of allowing militant groups to operate from their territory.
    4. Frequency of border clashes: Clashes along the border have become more frequent since 2021.
    5. A reversal of the earlier relationship: Pakistan had been an important supporter of the Taliban for years, but since 2021 Islamabad’s concerns over militant attacks and border security have increasingly complicated relations with Kabul.

    How far have restrictions on women gone, and what do they cost in the long run?

    1. The initial assurance: When the Taliban took control in 2021 they said they would respect women’s rights under their interpretation of Islamic law.
    2. What followed: Restrictions on women have steadily increased rather than stabilised at the level announced.
    3. Education: Girls remain barred from secondary education and higher education.
    4. Employment and movement: Women have been excluded from many areas of employment and face restrictions on movement and on access to public spaces, affecting almost every aspect of participation in public life.
    5. The pipeline effect: Girls unable to complete school cannot move on to university or professional training, which means fewer women will enter professions such as medicine, teaching, journalism and public administration.

    Why is economic stability not the same as economic recovery?

    1. The pre 2021 base: International aid accounted for a significant part of government spending and economic activity before the takeover.
    2. The shock: The withdrawal of foreign troops and the sudden reduction in aid created a major economic shock, and there were fears that the Afghan economy could collapse.
    3. What the Taliban did instead: The administration increased domestic revenue collection, tried to expand trade with neighbouring countries, invested in infrastructure and attempted to raise economic activity within the country.
    4. The result: Afghanistan has achieved a degree of economic stability since the severe crisis that followed the takeover, but stability is not recovery.
    5. What stability leaves untouched: Poverty remains widespread, unemployment remains a major problem, and humanitarian assistance continues to be important for millions of Afghans.
    6. A new pressure: The country is dealing with the return of large numbers of Afghans from Pakistan and Iran, whose arrival has created additional pressure on housing, employment and public services.

    What do other countries’ positions show about the limits of non-recognition?

    1. The general position: The Taliban regime has not received widespread international recognition, and most countries continue to avoid formally recognising it as Afghanistan’s legitimate government.
    2. The stated grounds: The main concerns are restrictions on women, the absence of an inclusive political system, and questions about terrorism and human rights.
    3. Russia: Russia has formally recognised the Taliban regime, making it the outlier among major powers.
    4. China and the United Arab Emirates: Both have accepted Taliban appointed ambassadors, which is operational acceptance short of formal recognition.
    5. Western governments: Several Western governments have maintained contact with Taliban officials without extending recognition.
    6. The common driver: Countries have increasingly had to deal with the Taliban because they control Afghanistan, which shows that control eventually compels engagement even where it does not compel recognition.

    What explains India’s shift from distance to pragmatic engagement?

    1. The posture: India has followed a cautious but increasingly pragmatic approach towards the Taliban since they returned to power in August 2021.
    2. The line held: New Delhi did not recognise the Taliban regime, and has expanded diplomatic engagement without altering that position.
    3. Return of presence: India reopened its diplomatic mission in Kabul in 2022.
    4. Continuing assistance: India continued providing humanitarian assistance, including food, medicines and other supplies.
    5. The turning point: The engagement became more significant in 2025 with the visit of the Taliban Foreign Minister.
    6. Why Afghanistan matters: Security is one of India’s biggest concerns in relation to Afghanistan, and Pakistan is the other factor shaping the calculation.

    Challenges to India’s Afghanistan policy

    1. Engagement without recognition has no legal footing: Agreements reached with an unrecognised authority cannot be enforced or registered internationally. Eg. India’s diplomatic mission in Kabul, reopened in 2022, operates as a technical mission rather than a full embassy.
    2. Overland access runs through a hostile neighbour: India has no land route to Afghanistan that does not cross Pakistan. Eg. India’s wheat consignments to Afghanistan required specific Pakistani transit permission in 2022 for movement through the Wagah crossing.
    3. Dependence on a sanctioned transit route: The alternative sea and land corridor runs through Iran, which carries its own sanctions exposure. Eg. India’s ten year contract of May 2024 to operate the Shahid Beheshti terminal at Chabahar depends on a project specific sanctions exemption.
    4. Stranded development assets: India built infrastructure whose upkeep now depends on an authority it does not recognise. Eg. The Afghan Parliament building inaugurated in 2015 and the Afghan India Friendship Dam at Salma completed in 2016 both sit under Taliban administration.
    5. Reputational cost of engaging a rights violating authority: Expanded contact runs against India’s own stated positions on women’s rights. Eg. Girls in Afghanistan remain barred from secondary and higher education while diplomatic engagement expands.
    6. Competition from states willing to recognise: Recognition buys influence that engagement alone does not. Eg. Russia formally recognised the Taliban regime, and China and the United Arab Emirates accepted Taliban appointed ambassadors.
    7. Terrorism risk that engagement cannot eliminate: Groups hostile to India retain sanctuary regardless of the state of India Kabul relations. Eg. The Islamic State-Khorasan Province has attacked foreign nationals in Afghanistan, including a Sikh gurdwara in Kabul in June 2022.

    Conclusion

    Five years after the takeover, the Taliban hold Afghanistan’s institutions, borders and security forces, have arrested the economic collapse that was predicted, and face no nationwide armed challenge. They have not obtained recognition, have not converted stability into recovery, and have deepened rather than relaxed the restrictions that keep recognition out of reach. The unresolved question is whether states that must deal with a de facto authority can extract any change in its conduct through engagement alone, since Russia’s recognition and India’s non recognition have so far produced the same behaviour from Kabul.

    “[2013, GS2, 10] The proposed withdrawal of International Security Assistance Force (ISAF) from Afghanistan in 2014 is fraught with major security implications for the countries of the region. Examine in light of the fact that India is faced with a plethora of challenges and needs to safeguard its own strategic interests.”

  • [19th August 2026] The Hindu OpED: Beyond America: Gulf states must build a regional order past the US security umbrella

    Question (2022, GS2): “How will I2U2 (India, Israel, UAE and USA) grouping transform India’s position in global politics?” 
    Linkage: This question explores how India integrates into new regional frameworks that include Gulf states (UAE) and Israel, illustrating the evolving security and economic partnerships in West Asia.

    Mentor Comment

    The United States President has threatened, for the second time, to bomb Oman, a long standing American ally that hosted talks between Washington and Tehran before the war was launched on 28 February. The threat against an ally exposes a conflict between an American security architecture built on bases across the Persian Gulf and a war in which those bases have become the principal liability of the states that host them.

    What is the American security umbrella in the Persian Gulf?

    1. What it is: The American security umbrella is the arrangement under which the United States guarantees the external security of the Persian Gulf monarchies through forward deployed forces, basing agreements and arms sales, in exchange for regional access and stable energy flows.
    2. Physical form: Over the years the United States built military bases across the Persian Gulf, hosting naval, air and command elements on the territory of partner states.
    3. Strategic premise: The arrangement rested on the assumption that an American presence deters Iran and that hosting American forces raises rather than lowers a host state’s security.
    4. Companion policy: It was paired with a decades old policy of containing Iran through sanctions, isolation and force posture.
    5. What the war has done to it: The foundations of this security architecture have been shaken, since American bases have turned out to be a liability in the hour of need.

    What is the Strait of Hormuz?

    1. What it is: The Strait of Hormuz is the narrow waterway connecting the Persian Gulf to the Gulf of Oman and the Arabian Sea, bordered by Iran to the north and Oman and the United Arab Emirates to the south.
    2. Why it matters: One fifth of the world’s seaborne oil passed through the Strait before the war, which makes its closure a global energy event rather than a regional one.

    What is the Fifth Fleet?

    1. What it is: The United States Fifth Fleet is the naval formation responsible for the Persian Gulf, the Red Sea, the Arabian Sea and parts of the Indian Ocean, headquartered in Bahrain.
    2. Why its damage matters: Its headquarters is the command node of the American naval presence in the region, so damage to it is a loss of command capacity and not only of infrastructure.

    What is a cold peace?

    1. What it is: A cold peace is a settlement in which former adversaries stop fighting and maintain functional diplomatic and economic contact without reconciling their underlying political differences or building trust.
    2. Why it is proposed here: It is the achievable objective between the Arab states and Iran, since containment has failed and full normalisation is not available.

    What triggered the threat against Oman?

    1. Oman’s original role: Oman hosted the talks between Washington and Tehran before the war was launched on 28 February, making it the diplomatic venue rather than a party to the conflict.
    2. Oman’s continuing role: Since the failed escalation, Oman, under American influence, has been talking to Iran seeking a settlement.
    3. Why the effort stalled: Iran, having survived two rounds of American bombings, refused to offer major concessions.
    4. The consequence for Oman: American frustration deepened with Oman precisely because Muscat could not deliver an Iranian concession it never had the power to extract.
    5. The nature of the threat: This is the second time the American leader has threatened to attack Oman, and the threat now falls on an ally for failing to produce a face saving deal.
    6. What the threat reveals: Instead of reassuring allies whose territory has been struck, Washington is threatening them, which is the clearest signal of declining influence in the region.

    Why has the Strait of Hormuz not reopened?

    1. Who closed it: Iran closed the Strait after it was attacked, making closure a retaliatory instrument rather than a negotiating opening position.
    2. The claimed breakthrough: When the American leader backed down from a threatened escalation after 13 days of bombing on Iran in July, he said the two sides were close to a deal on reopening the Strait.
    3. Iran’s position: Iran never said that it had agreed to any deal with the United States over the Strait.
    4. Iran’s stated preconditions: Iran issued several demands as preconditions for any agreement, including releasing frozen funds and issuing sanctions relief.
    5. The claim against the traffic data: The American President has repeatedly claimed the Strait was open, while traffic through the waterway is nowhere near pre war levels.
    6. Scale of what is blocked: The waterway carried one fifth of the world’s seaborne oil before the war, so the gap between claimed and actual traffic is a measurable global supply loss.

    What has the war done to America’s regional military position?

    1. Bases damaged or destroyed: At least 15 American bases are either damaged or destroyed.
    2. The command node hit: The damaged facilities include the Fifth Fleet Headquarters in Bahrain.
    3. Net effect on presence: The damage has substantially reduced America’s strategic presence in the region.
    4. How Iran achieved it: Tehran turned the American basing network into a liability by repeatedly striking the bases and their host countries.
    5. Iran’s own survival: Iran survived two rounds of American bombings and remained able to refuse major concessions afterwards.
    6. Failure of coercive signalling: From day one of the war, American threats and rhetoric did little to advance Washington’s strategic goals or to deter Iran.

    Why has the presence meant to protect Gulf states become the source of their danger?

    1. Both propositions held simultaneously: The bases were the guarantee of Gulf security and the reason Gulf territory was struck, and the war has resolved that ambiguity against the hosts.
    2. Iran’s targeting logic: By striking the bases and the host countries together, Tehran converted the guarantee into a cost borne by the host rather than by the guarantor.
    3. The guarantor’s response: Washington neither restored deterrence nor reassured the hosts, and has instead threatened one of them with bombing.
    4. The asymmetry of exposure: The host state’s territory, population and economy absorb the retaliation while the guarantor’s homeland does not.
    5. Why the old bargain cannot simply be repaired: Reassurance would require a demonstrated capacity to deter Iranian strikes, which two rounds of bombing failed to establish.
    6. The unresolved dependence: Gulf states have no alternative security provider of comparable capability, so recognising the failure of the arrangement does not by itself produce a substitute.

    Why has the containment of Iran failed?

    1. The record of the war: Iran absorbed two rounds of American bombing and emerged able to hold the Strait closed and to set preconditions for talks.
    2. Coercion produced no concession: Threats and rhetoric from the first day of the war neither advanced American goals nor deterred Iranian action.
    3. The cost fell on third parties: Containment’s enforcement damaged the host states of American bases rather than the target of the policy.
    4. Diplomacy was subordinated to pressure: Oman’s mediation was conducted under American influence rather than as an independent regional initiative, which limited what it could offer Tehran.
    5. The policy’s own premise collapsed: A decades old policy of isolating Iran cannot be sustained when the isolating power’s regional presence has been substantially reduced.

    What would a new regional order require?

    1. Recognition of the strategic reality: Countries in the region confront a new strategic reality in which the foundations of the old security architecture have been shaken.
    2. Abandoning containment: Gulf states must recognise that the decades old policy of containing Iran has failed.
    3. Looking past the umbrella: To ensure their own security and regional stability, the Persian Gulf countries need to look beyond the American security umbrella.
    4. The organising principle: The new order must be founded on a cold peace between the Arab states and Iran, not on reconciliation or on alliance.
    5. Regional rather than external authorship: The foundations have to be laid by the regional states themselves, since the external guarantor has demonstrated both limited capability and limited commitment.

    How does the Gulf’s shifting security order affect India’s interests?

    1. Energy dependence: India imports over 85 percent of its crude oil, and a large share of West Asian supply transits the Strait of Hormuz, so a closed Strait raises both price and freight and insurance costs.
    2. Diaspora exposure: About 90 lakh Indians live and work in the Gulf Cooperation Council states, the largest concentration of Indians anywhere outside India.
    3. Remittance dependence: The Gulf accounts for a substantial share of India’s annual remittance inflows, which exceeded $125 billion in recent years and are the country’s most stable external receipt.
    4. Trade and connectivity stakes: The India Middle East Europe Economic Corridor and India’s trade agreement with the United Arab Emirates both assume a stable and navigable Gulf.
    5. Balancing act with Iran: India’s Chabahar port investment and its connectivity route to Central Asia through Iran sit alongside its deepening partnerships with the Gulf monarchies and Israel.
    6. Strategic preference: A cold peace between the Arab states and Iran serves India better than either containment or open conflict, since India maintains working relationships across all three blocs.

    Challenges to building a new Persian Gulf regional order

    1. Absence of a regional security institution: The Gulf has no inclusive security organisation covering both the Arab states and Iran, e.g. the Gulf Cooperation Council formed in 1981 explicitly excludes Iran and Iraq.
    2. Sectarian and dynastic rivalry: Competition between Riyadh and Tehran runs through proxy conflicts that outlast any bilateral thaw, e.g. the Yemen conflict continued despite the Saudi Iran normalisation agreement brokered in Beijing in March 2023.
    3. Capability dependence on external suppliers: Gulf militaries are built on American platforms, training and sustainment, so autonomy is limited by the equipment they already own, e.g. Patriot and THAAD air defence systems in Saudi Arabia and the United Arab Emirates depend on American logistics chains.
    4. Intra Gulf divergence: The Gulf Cooperation Council states do not share a single position toward Iran, e.g. the blockade of Qatar between 2017 and 2021 was driven partly by differing approaches to Tehran.
    5. Nuclear file unresolved: No verification framework governs Iran’s nuclear programme after the collapse of the earlier agreement, e.g. the Joint Comprehensive Plan of Action of 2015 ceased to constrain enrichment after the American withdrawal in 2018.
    6. Energy chokepoint vulnerability: Any settlement leaves the Strait of Hormuz physically controllable by one party, e.g. one fifth of the world’s seaborne oil transited the Strait before Iran closed it.
    7. External power competition: China and Russia have expanding interests in the region and no shared framework with the United States, e.g. China brokered the Saudi Iran agreement of 2023 without American involvement.
    8. Domestic legitimacy constraints: Gulf rulers face internal opposition to accommodation with Iran and to visible dependence on foreign forces, e.g. Bahrain’s own political fault lines were exposed during the unrest of 2011.

    Conclusion

    The war has produced a result the Gulf states cannot reverse: at least 15 American bases damaged or destroyed including the Fifth Fleet Headquarters in Bahrain, the Strait of Hormuz still functionally closed, and an American guarantor now threatening an ally rather than reassuring it. The decades old policy of containing Iran has failed, and no external power is positioned to replace the security architecture that failure has hollowed out. What remains unresolved is whether the Persian Gulf states can construct a regional order on a cold peace with Iran while their own militaries, economies and rivalries still run through the arrangement they must replace.

  • How US is building a case for ‘transhipment crackdown’ and why India may be at risk

    Why in the News

    A United States government report titled The Great Transhipment Scam: Global Evasion and Economic Costs names over 40 countries in a claimed shadow transhipment network and places India, Mexico, Canada and the European Union in Tier 1. The classification arrives while an India United States trade deal is under negotiation. The tension is between a tariff enforcement category built to catch origin fraud and a manufacturing model that legitimately imports Chinese components for domestic value addition.

    What is transhipment in trade enforcement?

    1. About: Transhipment in this context means routing goods of one origin through a third country so they enter the destination market under the third country’s tariff treatment.
    2. Why it matters: Origin determines the tariff rate, so mislabelling origin converts a high tariff good into a low tariff one.
    3. The legitimate case: Goods that undergo substantial transformation in the third country acquire that country’s origin lawfully under rules of origin.
    4. The disputed boundary: The report’s methodology does not separate origin fraud from genuine domestic value addition, which is where India’s exposure arises.

    What does the report actually claim?

    1. Tier 1 classification: India, Mexico, Canada and the European Union are placed in the highest risk tier.
    2. Volume estimate: About $67 billion of United States bound goods are estimated to be transhipped from China through top hubs, named as Mexico, India and Vietnam.
    3. Revenue estimate: The estimated tariff revenue loss is about $28 billion.
    4. Cluster naming: The report labels the Pune, Gujarat and Chennai industrial corridor as a cluster of concern.
    5. Institutional source: The estimates come from the Office of Trade and Economic Analysis within the United States Commerce Department.

    Why is India exposed despite genuine manufacturing?

    1. Component dependence: Indian electronics assembly imports a large share of components from China, so import content is high even where assembly is real.
    2. Measurement problem: A high Chinese import share can be read either as origin fraud or as an early stage manufacturing base, and the report does not distinguish the two.
    3. Scheme linkage: Production Linked Incentive driven assembly expanded exports faster than the domestic component base grew, which widens the gap the report treats as suspicious.
    4. Corridor concentration: Export clusters concentrate assembly activity geographically, which makes them visible in trade data as hubs.

    What enforcement instruments follow from such a report?

    1. Section 301 action: The United States Trade Representative can open an investigation and impose tariffs on a trading partner’s practices under Section 301 of the Trade Act, 1974.
    2. Trade deal clause: A transhipment clause can be written into the pending India United States trade agreement, binding India to origin verification obligations.
    3. Legal context: Reciprocal tariffs imposed earlier were struck down by the United States Supreme Court, which pushes enforcement toward statutory routes that survive judicial review.
    4. Secondary tariff route: Separate legislation permitting tariffs of up to 100 per cent on major buyers of Russian oil provides an additional pressure point.

    What is the counter argument to the report’s framing?

    1. Value addition versus routing: A country that imports components, assembles and exports is performing manufacturing, not evasion, when the transformation meets the origin threshold.
    2. Rules of origin already exist: Preferential and non preferential rules of origin provide a legal test for substantial transformation, so a new category adds pressure rather than clarity.
    3. Negotiating leverage: Naming a partner in a public report ahead of a trade negotiation functions as leverage over the terms of that negotiation.
    4. Bilateral drift: The instrument bypasses the multilateral dispute settlement route, which has been non functional since the Appellate Body lost quorum.

    Challenges to India’s export position

    1. Origin verification capacity: Certifying substantial transformation at scale requires customs documentation India’s exporters are not uniformly equipped for. e.g. disputes over certificates of origin under the India ASEAN agreement.
    2. Component import dependence: Domestic value addition in electronics remains low even as export volumes rise. e.g. mobile handset exports growing faster than domestic component sourcing.
    3. Dispute settlement vacuum: The World Trade Organization Appellate Body has been non functional since 2019, removing the appeal route against unilateral measures. e.g. appeals filed into the void by multiple members since then.
    4. Tariff exposure concentration: The United States is India’s largest single export market, so a unilateral measure has outsized effect. e.g. the disruption to Indian shrimp and steel exports during earlier tariff rounds.
    5. Rules of origin complexity: Each trade agreement carries a different origin threshold, raising compliance cost for the same exporter. e.g. differing value addition thresholds under India’s agreements with Japan and ASEAN.
    6. Retaliation limits: India’s counter tariff capacity is small relative to the market it would be retaliating against. e.g. the limited effect of India’s 2019 retaliatory tariffs on United States agricultural goods.

    Conclusion

    The report converts a measurement ambiguity, high Chinese import content in Indian assembly, into an enforcement category, and that conversion is what puts India at risk rather than any finding of fraud. The remedy runs through demonstrable domestic value addition, not through contesting the label. The next milestone is whether a transhipment clause appears in the text of the India United States trade agreement.

    Back2Basics: Rules of Origin

    1. Rules of origin are the criteria used to determine the country of origin of a product for the purpose of applying tariffs and trade measures.
    2. Non preferential rules of origin apply for most favoured nation tariffs, anti dumping duties and trade statistics.
    3. Preferential rules of origin apply under free trade agreements and decide whether a good qualifies for concessional duty.
    4. Substantial transformation is the core test, applied through a change in tariff classification, a regional value content threshold, or a specified processing operation.
    5. India tightened enforcement through the Customs (Administration of Rules of Origin under Trade Agreements) Rules, 2020, which placed the burden of proof on the importer.

    Way Forward

    1. Raise domestic value addition thresholds: Tie incentive disbursement to verified local content rather than to export value alone.
    2. Build an origin audit trail: Create a digital component provenance record for export clusters so transformation can be evidenced rather than asserted.
    3. Negotiate the clause narrowly: Confine any transhipment clause in the trade agreement to documented origin fraud, not to import content share.
    4. Deepen component manufacturing: Extend incentives to sub assemblies and passive components, since the exposure originates in the missing component layer.
    5. Diversify export destinations: Reduce single market concentration through the concluded agreements with the United Kingdom and the European Free Trade Association bloc.

    Matching Previous Year Question

    “[2025, GS3, 10 marks] What are the challenges before the Indian economy when the world is moving away from free trade and multilateralism to protectionism and bilateralism? How can these challenges be met?”

  • Strait of Hormuz transit collapses to two vessels a day as the naval blockade hardens

    Why in the News

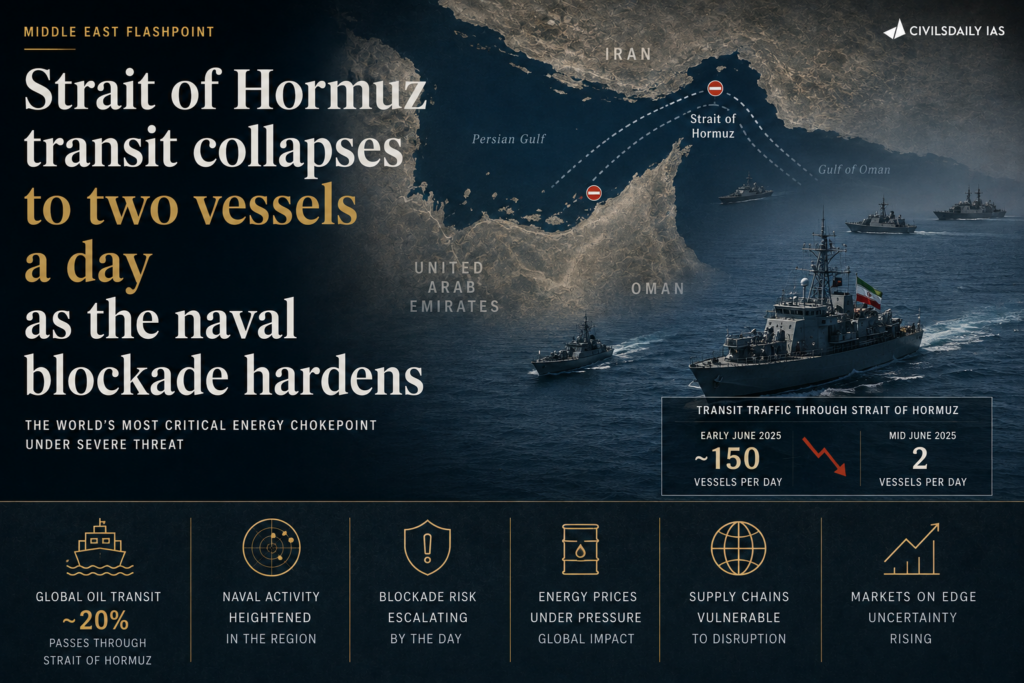
    Transit through the Strait of Hormuz fell to two vessels on Friday after two more ships were attacked in the waterway, against more than 130 crossings a day before the war began in February. The near standstill has turned Iran’s ability to close the strait into the decisive bargaining instrument of the war, and has pushed the United States to place cheaper fuel above nuclear denial as its first stated war aim.

    What is the Strait of Hormuz?

    1. Location: The strait connects the Persian Gulf to the Gulf of Oman and the Arabian Sea, with Iran on the northern shore and Oman’s Musandam peninsula and the United Arab Emirates on the southern shore.
    2. Dimensions: It narrows to about 21 nautical miles, with inbound and outbound traffic separated into lanes about two nautical miles wide each.
    3. Volume carried: About a fifth of global petroleum liquids consumption passes through it, along with a large share of the world’s seaborne liquefied natural gas.
    4. Why it cannot be bypassed: Gulf producers hold limited pipeline capacity that avoids the strait, so most Gulf crude has no alternative route to the open ocean.
    5. Legal position of the lanes: The shipping lanes lie inside the territorial seas of Iran and Oman, so passage rests on the transit passage regime rather than on high seas freedom of navigation.

    What is a maritime chokepoint?

    1. About: A chokepoint is a narrow channel on a high volume shipping route where traffic must converge and cannot be economically rerouted.
    2. Why it matters: Closure at a chokepoint raises freight and insurance costs across an entire trade, because the alternative is a far longer voyage or no voyage at all.

    What is a naval blockade?

    1. About: A naval blockade is the use of warships to prevent vessels from entering or leaving an adversary’s ports or coastline.
    2. Its object here: The United States blockade is aimed at stopping Iran from selling oil and at inflicting economic damage rather than at seizing territory.

    Who is the Abu Dhabi National Oil Company (ADNOC)?

    1. About: ADNOC is the state owned oil and gas company of the United Arab Emirates and one of the largest producers in the Gulf.
    2. Its role in the news: Two vessels affiliated to ADNOC were attacked while transiting the strait, and the UAE government blamed Iran for the attack.

    What is going dark on the Automatic Identification System?

    1. About: Merchant ships broadcast their identity and position through a transponder, and switching it off removes them from public tracking.
    2. Effect on the count: Vessel counts drawn from tracking data understate real traffic, because ships moving with transponders off are not recorded.

    How far has traffic through the strait actually fallen?

    1. Friday count: Two vessels passed through the waterway, a grain ship entering Iranian waters and an empty dry bulk ship moving in the opposite direction.
    2. A third movement: A separate empty liquefied petroleum products tanker was sailing into the Gulf through the strait on the same day.
    3. No crude at all: No crude oil shipments were visible on Friday.
    4. Preceding days: Nine vessels passed through on Thursday, up from five on Wednesday.
    5. Benchmark for the month: The August average stands at 12 vessels a day.
    6. Pre war benchmark: More than 130 ships traversed the strait daily before the war launched by the United States and Israel on Iran in February.
    7. Measurement caveat: Some ships may pass undetected with their transponders switched off, so the recorded figures are a floor rather than a full count.

    Why is control of the strait Iran’s main leverage?

    1. Analyst assessment: The principal Middle East analyst at a risk intelligence firm assessed that Iran’s ability to restrict shipping through the strait is its main source of leverage in negotiations, alongside the threat to regional energy infrastructure.
    2. A permission regime at sea: Iran has resumed attacks on ships it accuses of trying to transit the strait without its permission.
    3. Talks stalled: A senior Iranian source stated on Wednesday that there had been no progress in talks to build on the June agreement to end the war.
    4. Collapse of the ceasefire: The ceasefire renewed under the June deal has broken down, which preceded the resumption of attacks on shipping.
    5. Conditions for reopening: Iran has said it will not allow the waterway to reopen until economic sanctions are removed and frozen Iranian assets are released.
    6. Legislative backing: An Iranian parliamentary committee approved a plan for the strait on Thursday that bans the transit of United States, Israeli and other hostile countries’ assets and equipment.
    7. Attack on Emirati vessels: ADNOC said two of its vessels were attacked while transiting the strait on Thursday evening, and Iran made no immediate comment on the Emirati accusation.

    How has the closure reordered United States war aims?

    1. Stated reversal of priorities: The Vice President stated that goal number one is to keep oil and gas cheap for Americans and that goal number two is to ensure Iran never gets a nuclear weapon.
    2. The original justification: Preventing Iran from obtaining a nuclear weapon had been the consistently stated main reason for the war.
    3. Domestic pressure: The war is unpopular, the President’s approval rating is falling and midterm elections are due in November.
    4. Party calculation: Republicans fear that the war and the gasoline prices it has driven up will cost them control of Congress.
    5. Military constraint: The United States military burned through stockpiles of costly high technology missiles and is running low, which limits the option of resuming large scale attacks.
    6. Blockade endurance: The Defence Secretary stated that the navy can maintain the blockade indefinitely by rotating ships in and out of the region.
    7. Negotiating posture: The President described the approach as low keying it and only semi negotiating, days after saying an agreement to reopen the strait was imminent.
    8. Economic track: The Treasury Secretary announced measures of economic isolation without precedent, with further announcements expected next week.

    What do the positions of the other parties show about the cost of the closure?

    1. United Arab Emirates: Its state oil company had two vessels attacked in the strait and the government publicly blamed Iran, which shows that Gulf producers outside the war are absorbing its shipping costs.
    2. Iran: Its parliamentary committee converted the closure into a formal transit ban on the assets and equipment of hostile states, which shows the closure is now settled policy rather than episodic reprisal.
    3. United States: It has moved from strikes to a naval blockade of Iranian ports and a bar on Iranian oil sales, which shows the war has become an economic siege rather than a military campaign.
    4. Israel: It launched the war jointly with the United States in February and is named in Iran’s transit ban, which shows the strait is being used to impose costs directly on the belligerents.
    5. Limits of the evidence: These are the only national positions the reporting supplies, so the effect on Asian importers is documented through prices rather than through stated country positions.

    How exposed is India to a prolonged closure of the strait?

    1. Crude dependence: India imports over 85 percent of the crude oil it consumes and is the third largest crude importer in the world.
    2. Route concentration: Iraq, Saudi Arabia, the United Arab Emirates and Kuwait are among India’s largest suppliers, and cargoes from all four leave the Gulf through Hormuz.
    3. Gas contracts: Qatar supplies close to half of India’s liquefied natural gas under long term contracts, and every one of those cargoes transits the strait.
    4. Fertiliser inputs: Urea, ammonia and phosphatic raw material contracted from Oman, Saudi Arabia and Qatar move on the same route, which links the strait directly to the fertiliser subsidy bill.
    5. Seafarers: Indians form a large share of the global seafaring workforce and crew a substantial part of Gulf trade, so attacks on merchant shipping place Indian crews directly at risk.
    6. Price transmission: A sustained rise in crude prices widens the current account deficit, raises the oil import bill and feeds into domestic fuel and freight costs.
    7. Insurance and freight: War risk premiums on Gulf voyages rise sharply during a closure, which adds a cost to every cargo that does move.
    8. Remittances and diaspora: About nine million Indians live and work in the Gulf, so a prolonged war in the region carries an employment and remittance risk alongside the energy risk.

    Challenges to keeping the Strait of Hormuz open

    1. Narrow lanes inside territorial waters: The shipping lanes run through Iranian and Omani territorial seas, which lets a littoral state interfere with passage at short notice. e.g. Iranian forces seized the container ship MSC Aries near the strait in April 2024.
    2. Mines and fast attack craft: Sea mines and small armed boats can close a channel at very low cost against far more expensive warships. e.g. the mining of the frigate USS Samuel B. Roberts in 1988 triggered Operation Praying Mantis.
    3. Limited bypass pipeline capacity: Existing pipelines that avoid the strait can carry only a fraction of Gulf export volumes. e.g. Saudi Arabia’s East West pipeline to Yanbu and the Emirati line to Fujairah together fall well short of normal Hormuz throughput.
    4. Insurance and crew availability: War risk premiums and crew refusal can halt trade even where warships keep a route physically open. e.g. attacks on shipping in the Red Sea from late 2023 pushed premiums up several fold and diverted traffic around the Cape of Good Hope.
    5. Attribution difficulties in attacks at sea: Limpet mines and drones leave little evidence, which delays any collective response. e.g. the 2019 attacks on tankers near Fujairah were denied by Iran and never conclusively attributed.
    6. Escalation risk from convoy operations: Naval escorting draws external navies into direct contact with a littoral state’s forces. e.g. the reflagging of Kuwaiti tankers under Operation Earnest Will in 1987 led to repeated armed clashes.
    7. Thin strategic buffers for importers: Importing countries hold limited emergency stocks, so a closure of a few weeks becomes a fiscal event. e.g. India’s strategic petroleum reserves hold about 5.33 million tonnes, close to nine to ten days of imports.

    Conclusion

    Control of the Strait of Hormuz, and not the nuclear programme, now sets the terms of the war. Iran has converted a waterway into a bargaining instrument, and the United States has answered with a blockade it says it can sustain indefinitely and sanctions it says will be without precedent. Transit stands at two vessels a day against more than 130 before February, and reopening rests on sanctions relief and the release of frozen assets that neither side has conceded.

    Maritime Chokepoints and Global Energy Security

    1. About: A small number of narrow sea passages carry most of the world’s traded oil and gas, which makes energy security a function of a few points on the map.
    2. Strait of Hormuz: It carries roughly 20 million barrels of oil a day and the bulk of Qatari liquefied natural gas, and it has no adequate bypass.
    3. Strait of Malacca: It links the Indian Ocean to the South China Sea and carries a comparable volume of oil, mostly bound for China, Japan and South Korea.
    4. Bab el Mandeb: It connects the Gulf of Aden to the Red Sea and is the approach to the Suez Canal for Asia to Europe trade.
    5. Suez Canal and the SUMED pipeline: Together they move Gulf and Red Sea crude to the Mediterranean without the Cape route.
    6. Turkish Straits: The Bosphorus and the Dardanelles carry Russian and Caspian crude out of the Black Sea.
    7. Cape of Good Hope: It is the fallback route when Suez or Bab el Mandeb is unusable, adding roughly two weeks to an Asia to Europe voyage.
    8. India’s position: India is the third largest oil consumer and importer in the world, and its imports pass through Hormuz on the western side and Malacca on the eastern side.

    Legal Framework Governing Transit Through International Straits

    1. Article 3 of UNCLOS, 1982: Allows a coastal state a territorial sea of up to 12 nautical miles, which is why the Hormuz lanes fall within national waters.
    2. Article 37 of UNCLOS, 1982: Applies the transit passage regime to straits used for international navigation between one part of the high seas or an exclusive economic zone and another.
    3. Article 38 of UNCLOS, 1982: Grants all ships and aircraft the right of transit passage, which shall not be impeded.
    4. Article 39 of UNCLOS, 1982: Requires ships in transit passage to proceed without delay and to refrain from any threat or use of force against the bordering state.
    5. Article 44 of UNCLOS, 1982: Bars states bordering straits from hampering transit passage and from suspending it.
    6. Article 45 of UNCLOS, 1982: Applies non suspendable innocent passage to straits excluded from the transit passage regime.
    7. SUA Convention, 1988: Criminalises seizure of and violence against ships and obliges parties to prosecute or extradite offenders.
    8. Article 51 of the United Nations Charter: Preserves the right of individual and collective self defence against an armed attack, which is the ground invoked for naval action.

    Back2Basics: Strait of Hormuz

    1. Type: It is a maritime chokepoint and the only sea route from the Persian Gulf to the open ocean.
    2. Connects: It joins the Persian Gulf with the Gulf of Oman and further with the Arabian Sea and the Indian Ocean.
    3. Littoral states: Iran lies to the north, and Oman and the United Arab Emirates lie to the south.
    4. Width: Its narrowest point is about 21 nautical miles, roughly 39 kilometres.
    5. Key islands: Qeshm, Hormuz and Larak are Iranian, and Abu Musa and the Greater and Lesser Tunbs are held by Iran and claimed by the United Arab Emirates.
    6. Peninsula on the southern shore: The Musandam peninsula belongs to Oman and is separated from the rest of the country by Emirati territory.
    7. Users: Saudi Arabia, Iraq, the United Arab Emirates, Kuwait, Qatar, Bahrain and Iran export their oil and gas through it.
    8. Volume: It handles roughly a fifth of the world’s petroleum liquids consumption and about a fifth of global liquefied natural gas trade.

    Government Initiatives for India’s Energy Security

    1. Indian Strategic Petroleum Reserves: Underground caverns at Visakhapatnam, Mangaluru and Padur hold about 5.33 million tonnes of crude for emergency use, with a second phase planned at Chandikhol and Padur.
    2. Diversification of crude sources: Refiners have expanded purchases from Russia, West Africa, the United States and Latin America to reduce dependence on Gulf cargoes.
    3. Chabahar port and the International North South Transport Corridor: These provide a route to Central Asia and Russia that avoids the Suez and Hormuz corridors.
    4. India Middle East Europe Economic Corridor: A rail and shipping corridor announced in 2023 to link India to the Gulf and Europe with reduced maritime dependence.
    5. National Green Hydrogen Mission: Targets 5 million tonnes of annual green hydrogen production by 2030 to displace imported fossil fuel in industry and transport.
    6. Ethanol Blended Petrol Programme: Raises the ethanol share in petrol to cut crude import volumes and the import bill.
    7. Open Acreage Licensing Policy and the Hydrocarbon Exploration and Licensing Policy: Expand domestic exploration acreage to raise indigenous production.
    8. Maritime India Vision 2030 and Sagarmala: Expand port capacity, coastal shipping and shipbuilding to strengthen India’s own maritime logistics.

    Key Facts about World Maritime Chokepoints

    1. Hormuz volume: Roughly 20 million barrels of oil a day pass through the Strait of Hormuz.
    2. Malacca volume: The Strait of Malacca carries a comparable oil volume and is the shortest route between the Indian Ocean and the Pacific.
    3. Suez Canal: Opened in 1869 and nationalised in 1956, it links the Red Sea to the Mediterranean.
    4. Panama Canal: Opened in 1914, it links the Atlantic and the Pacific and is constrained by fresh water availability at Gatun Lake.
    5. Bab el Mandeb: Its name means the Gate of Tears, and it separates Yemen from Djibouti and Eritrea.
    6. Turkish Straits regime: Transit is governed by the Montreux Convention of 1936, which regulates warship passage into the Black Sea.
    7. India’s maritime footprint: About 95 percent of India’s trade by volume and 70 percent by value moves by sea.
    8. Observance: World Maritime Day is observed by the International Maritime Organization in the last week of September.

    Challenges in India’s Energy Security

    1. Import dependence in crude: More than four fifths of consumption is met by imports, so any supply shock transmits straight to the fiscal position. e.g. the oil import bill crossed 130 billion dollars in a single year when Brent averaged above 100 dollars a barrel in 2022 and 2023.
    2. Concentration of gas supply: A single supplier accounts for close to half of contracted liquefied natural gas imports. e.g. the long term Qatari contracts renewed in 2024 run to 2048 and all of that volume transits Hormuz.
    3. Thin emergency stocks: Strategic reserves cover only a few days of consumption against the 90 day norm followed by International Energy Agency members. e.g. India’s reserves at Visakhapatnam, Mangaluru and Padur total about 5.33 million tonnes.
    4. Payment and sanctions exposure: Sanctions on suppliers disrupt settlement channels and shipping insurance for Indian refiners. e.g. tightened sanctions on Russian crude in 2025 forced refiners to switch cargoes and payment routes at short notice.
    5. Fertiliser and petrochemical linkage: Gas priced off oil raises the urea subsidy and petrochemical feedstock costs at the same time. e.g. imported urea contracted at 390 dollars a tonne this year illustrates how a Gulf disruption reaches farm input prices.
    6. Domestic production stagnation: Crude and gas output from ageing fields has not risen with demand. e.g. Mumbai High and the Krishna Godavari basin have seen declining production profiles despite repeated bid rounds.
    7. Renewable intermittency and storage gap: Solar and wind capacity growth is not matched by storage, which keeps thermal and imported fuel in the base load. e.g. peak evening demand in northern States is still met largely by coal and imported gas.

    Way Forward

    1. Expand strategic petroleum reserves: Complete the Chandikhol and Padur phase two caverns and move coverage towards the 90 day international norm.
    2. Diversify supply and routes: Extend term contracts to non Gulf suppliers and build storage and refuelling arrangements outside the Hormuz corridor.
    3. Invest in bypass connectivity: Operationalise Chabahar, the International North South Transport Corridor and the India Middle East Europe Economic Corridor so a single chokepoint does not carry all trade.
    4. Strengthen naval escort and maritime domain awareness: Sustain deployments and the Information Fusion Centre for the Indian Ocean Region to protect Indian flagged and Indian crewed shipping.
    5. Support seafarers and shipping insurance: Extend war risk cover arrangements and evacuation protocols for Indian crews on Gulf routes.
    6. Accelerate demand substitution: Raise ethanol blending, electric mobility and green hydrogen use to cut the volume of crude that must be imported at all.
    7. Build a price shock buffer in the Budget: Maintain an explicit fiscal cushion for the fuel and fertiliser subsidy so a chokepoint closure does not force mid year expenditure cuts.

    “[2026] Ships from which of the following countries have to cross the Strait of Hormuz to reach out to the Indian Ocean?

    1. Bahrain

    2. Syria

    3. Qatar

    4. Egypt

    (a) 1 and 2

    (b) 1 and 3

    (c) 2 and 3

    (d) 3 and 4

  • India-Israel defence ties under scrutiny

    Why in the News

    An Amnesty International report alleges India sent at least 2,596 shipments of military equipment and components to Israel since the Gaza war began. An opinion piece argues the disclosure reflects the depth of a quarter-century strategic partnership rather than a sudden shift.

    What anchors the India-Israel defence partnership?

    • Kargil origin: The relationship’s foundation was the 1999 Kargil War, when Israel rapidly supplied ammunition, drones and precision-guided munitions.
    • Technology transfer: Unlike many Western suppliers, Israel has been willing to transfer sophisticated military technology to India.
    • Platforms: Israel is a major source of drones, missiles, radars and surveillance systems for India’s armed forces.

    Why does the Amnesty report matter if it signals no policy change?

    • Customer to contributor: The report suggests India is no longer only a buyer but a contributor to Israel’s defence supply chain.
    • Timing: The shipments occurred during one of Israel’s most internationally criticised military campaigns, sharpening the scrutiny.
    • No rupture: The disclosure underscores an existing trajectory rather than marking a new departure in policy.

    How has the partnership evolved beyond buyer and seller?

    • Make in India: Under the Make in India initiative, Israeli defence firms have set up joint ventures and local manufacturing in India.
    • Localised production: Drones, electronics, missile systems and components are now produced within India’s defence industrial base.
    • Two-way flow: Localisation lets India supply components back into Israel’s supply chain, not just import finished systems.

    What are the domestic and external consequences?

    • Domestic politics: Opposition elements sceptical of closer ties with Israel’s government may use the disclosures to embarrass the ruling party.
    • Limited traction: Public attention is focused elsewhere, on the student agitation over exam paper leaks, blunting the political impact.
    • Arab reaction: Some Gulf displeasure is likely, but Arab partners were probably already aware of the expanding links, and there is no unified Arab stance on Israel today.
    • Wider Muslim world: States such as Turkey and Malaysia may voice diplomatic outrage, but New Delhi is unlikely to change policy in response.

    Does the partnership pose an ethical dilemma?

    • Strategic value versus ethics: The report raises the ethics of joint weapons production with a government whose conduct in Gaza drew widespread global disapproval.
    • Palestinian cause: Deep defence ties sit against India’s traditional support for a two-state solution and the Palestinian cause.
    • Gulf balance: India must weigh the partnership against its energy, trade and diaspora interests across the Gulf.

    Conclusion

    The report confirms a mature strategic partnership rather than a rupture, and India is unlikely to change course. The unresolved question is the ethics of contributing to a defence supply chain during a condemned campaign, and how India squares this with its stated support for the Palestinian cause and its Gulf interests.

    Back2Basics: India-Israel relations

    • Multilateral track: India and Israel cooperate through the I2U2 grouping (India, Israel, UAE, US) and the India-Middle East-Europe Economic Corridor (IMEC).
    • Full ties: India established full diplomatic relations with Israel in 1992, four decades after recognising it in 1950.
    • Strategic partnership: Ties were elevated to a Strategic Partnership in 2017, the first visit by an Indian Prime Minister to Israel.

    PYQ Relevance

    [UPSC 2018] India’s relations with Israel have, of late, acquired a depth and diversity, which cannot be rolled back.” Discuss.

    Linkage: The PYQ examines the growing depth and strategic importance of India-Israel relations. Defence cooperation, technology partnerships and the Gaza conflict highlight both the opportunities and diplomatic challenges in the relationship.

  • Xi Jinping’s doctrine for a self-governing party

    Why in the News

    An opinion piece analyses the Communist Party of China’s doctrine of party self-governance, its anti-corruption drive, and the incoming 15th Five-Year Plan.

    What is China’s Five-Year Plan?

    1. Definition: A Five-Year Plan is China’s central blueprint setting economic and strategic priorities for a five-year cycle.
    2. 15th plan: The upcoming plan will set targets for technology self-reliance, growth, and security amid external pressure.

    Why does party self-governance matter?

    1. Centralised control: Tighter party discipline concentrates authority and reduces internal dissent.
    2. Anti-corruption as tool: The campaign doubles as a mechanism to enforce loyalty and remove rivals.
    3. Policy continuity: Party control over planning shapes China’s industrial and strategic trajectory that India must track.

    Conclusion

    China’s model fuses party discipline with long-range planning to sustain one-party control. The takeaway is that policy direction is set by the party, not the state.

  • [8th August 2026] The Hindu OpED: The changing logic of the India-US partnership

    PYQ Relevance
    [UPSC 2019]
    ‘What introduces friction into the ties between India and the United States is that Washington is still unable to find for India a position in its global strategy, which would satisfy India’s National self-esteem and ambitions’ Explain with suitable examples.
    Linkage: The PYQ examines the structural frictions in India-US ties arising from differences in strategic priorities and expectations. The article shows how the relationship is shifting from strategic convergence to reciprocal, transactional cooperation, reinforcing the PYQ’s concern over divergent expectations.

    Mentor’s Comment

    An analysis argues the India-US partnership now runs on ‘flexible realism’ rather than shared containment of China. The first decade of the India-U.S. partnership was propelled by shared concern over China’s rise, not by identical values. As Washington moves toward interest-based alliance building, India’s strategic relevance will depend less on China’s trajectory and more on India’s own economic, technological, and military weight. This is a test of how convincingly India can operationalise strategic autonomy through multi-alignment.

    What is the shift in the partnership’s logic?

    1. From convergence to reciprocity: The relationship is moving from a China driven strategic alignment to a value for value calculus.
    2. Tariff signal: Trump tariffs on Indian goods illustrate that shared interests no longer guarantee concessions.

    Why does the tariff dispute signal a deeper shift in American foreign policy, not merely a trade rift?

    1. Not an isolated trade dispute: The tariffs accompany demands for greater burden-sharing, tighter technology restrictions, and a more reciprocal approach to partnerships, indicating a policy pattern rather than a standalone measure.
    2. Flexible realism defined: This approach places national interest at the centre of foreign policy and treats trade, technology, industrial policy, and security as integrated instruments of statecraft.
    3. Departure from the post-Cold War order: Partnerships are judged by the tangible strategic and economic value they deliver, not by shared values or historical goodwill.
    4. Not a retreat from engagement: The approach recalibrates how the U.S. pursues its interests rather than signalling disengagement from global affairs.

    What strategic logic sustained the India-U.S. partnership over the past decade, and why can this convergence no longer be assumed?

    1. China as the organising driver: India’s growing strategic importance to the U.S. followed directly from China’s emergence as Washington’s principal strategic competitor.
    2. Convergence visible across domains: Defence cooperation, the Quad, technology partnerships, and supply-chain resilience all expanded on the back of this shared concern.
    3. Values were a backdrop, not the driver: Democratic values provided a favourable political context, but strategic convergence on China was the actual engine of cooperation.
    4. Assumption no longer holds: India can no longer assume that intensifying U.S.-China competition will automatically enhance its own strategic relevance.
    5. New basis of assessment: Washington will increasingly judge partners, including India, by reciprocal economic benefit, technological capability, and strategic contribution.

    How is the basis of the India-U.S. partnership shifting from convergence to complementarity?

    1. First phase defined: The initial phase of the relationship rested on strategic convergence driven by China’s rise.
    2. Second phase defined: The next phase depends on strategic complementarity, with each side contributing capabilities that reinforce the other.
    3. Substantive domains: Defence cooperation, critical technologies, resilient supply chains, and advanced manufacturing will matter for their own economic and strategic value, not only as tools to manage China.
    4. Net strategic effect: This evolution could make the partnership more balanced and resilient rather than weaker.
    5. Reframing India’s relevance: A more capable India becomes a more valuable partner for the U.S. and is also better placed to pursue its own strategic interests independently.

    Why is the shift happening now?

    1. Domestic priorities: Washington is prioritising reciprocal trade gains over grand strategy.
    2. Multipolar drift: A more contested global order weakens automatic alignment.

    What is India’s central challenge in this new phase of the relationship?

    1. Relevance must be self-generated: India’s strategic relevance must increasingly flow from its own economic dynamism, technological capability, defence preparedness, and diplomatic influence.
    2. From remaining relevant to becoming indispensable: The task is not just to stay useful in Washington’s calculus but to build the capabilities that make India an indispensable partner.
    3. Convergence still matters, but is insufficient alone: Shared concern over China will remain important but can no longer be the sole basis for sustaining momentum.
    4. Dual payoff: Building these capabilities would strengthen the India-U.S. partnership and reinforce India’s own strategic autonomy at the same time.

    How should India respond?

    1. Strategic autonomy: Preserve independent decision making rather than lock into one camp.
    2. Multi alignment: Deepen ties across the European Union, Japan, and the Global South.
    3. Strategic complementarity: Offer the US areas where Indian and American interests genuinely reinforce each other.

    Conclusion

    The tariffs mark a transition in American statecraft from strategic convergence to reciprocity-based partnership, and the India-U.S. relationship must transition correspondingly from a China-driven first phase to a capability-driven second phase. Strategic convergence around China will persist but can no longer be assumed sufficient on its own. India’s task is to build the economic, technological, and defence capabilities that make it an indispensable partner in its own right, using strategic autonomy and multi-alignment to convert this recalibration into greater agency rather than vulnerability.

  • US Withdraws from UNFCCC and IPCC

    Why in the News?

    US President Donald Trump has signed a presidential memorandum withdrawing the United States from 66 international organisations, including the United Nations Framework Convention on Climate Change (UNFCCC) and the Intergovernmental Panel on Climate Change (IPCC). This makes the US the first country to formally exit the UNFCCC.

    United Nations Framework Convention on Climate Change (UNFCCC)

    The UNFCCC is the foundational global treaty that governs international cooperation on climate change. It provides the legal and institutional framework under which global climate negotiations take place.

    Established

    • Adopted in 1992 at the Rio Earth Summit
    • Entered into force in 1994
    • Nearly universal membership among UN countries

    Key role

    • Organises annual Conference of Parties (COP) climate negotiations
    • Hosts the Paris Agreement, which aims to limit global warming
    • Establishes systems for
      • Emissions reporting
      • Transparency and accountability
      • Climate finance mechanisms
      • Carbon markets and rule making

    Legal implications of US withdrawal

    • Withdrawal takes effect one year after formal notice
    • Exit from UNFCCC automatically means exit from the Paris Agreement
    • US will no longer be a Party to COP negotiations
    • Can attend meetings only as an observer, without bargaining rights

    Intergovernmental Panel on Climate Change (IPCC)

    The IPCC is the UN body that assesses and synthesises global scientific research on climate change, its impacts, and mitigation and adaptation options.

    Functions

    • Produces comprehensive assessment reports
    • Provides scientific benchmarks for climate negotiations
    • Informs global and national climate policy

    Impact of US exit

    • Reduces US influence over global climate science assessments
    • Limits formal nomination of US experts to IPCC author teams
    • US scientists may still contribute as reviewers or through non government nominations
    [2009] The United Nations Framework Convention on Climate Change (UNFCCC) is an international treaty drawn at: 

    (a) United Conference on the Human Environment, Stockholm, 1972 

    (b) UN Conference on Environment and Development, Rio de Janeiro, 1992 

    (c) World Summit on Sustainable Development, Johannesburg, 2002 

    (d) UN Climate Change Conference, Copenhagen, 2009