Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS3-13.Infrastructure: Energy, Ports, Roads, Airports, Railways etc:

  • Can SHANTI Act override court on compensation for nuclear disasters, asks SC

    Why in the News

    A three judge Bench of the Supreme Court issued notice to the Union government and the Atomic Energy Regulatory Board (AERB) on whether the Sustainable Harnessing and Advancement of Nuclear Energy for Transforming India (SHANTI) Act, 2025 can bar constitutional courts from awarding fair compensation to victims of a nuclear accident. The Act caps operator and government liability and exempts suppliers, which sets a statutory ceiling against the constitutional power to award damages for a legal wrong. The Bench also asked whether Section 17(4), which lets the government appoint the AERB Chairperson and Members, creates a conflict of interest.

    What is the SHANTI Act, 2025?

    1. About: The Sustainable Harnessing and Advancement of Nuclear Energy for Transforming India (SHANTI) Act, 2025 is the statute that replaced the Civil Liability for Nuclear Damage Act, 2010 as the law governing liability for nuclear damage in India.
    2. Core function: It fixes who pays for a nuclear accident, how much they pay, and the outer financial limit of that obligation.
    3. Operator ceiling: Liability of the largest plant operator in India is capped at Rs 3,000 crore.
    4. Government residual liability: The Union government’s residual liability is capped at 300 million Special Drawing Rights, stated in the proceedings as about Rs 4,500 crore.
    5. Supplier position: Suppliers, manufacturers and similar entities are exempted from liability under the Act.
    6. Regulatory provision: Section 17(4) vests in the government the power to appoint the Chairperson and Members of the AERB.

    What are Special Drawing Rights (SDRs)?

    1. About: Special Drawing Rights are an international reserve asset created by the International Monetary Fund (IMF), whose value is set by a basket of major currencies.
    2. Use here: Nuclear liability ceilings are expressed in SDRs because international nuclear liability conventions use the unit, which keeps the ceiling insulated from movement in any single national currency.

    What is the doctrine of absolute liability?

    1. About: Absolute liability holds an enterprise carrying on a hazardous activity fully liable for harm caused by that activity, with no exceptions and no ceiling on the amount.
    2. Origin: The Supreme Court laid it down in the oleum gas leak case, M.C. Mehta v Union of India (1987), rejecting the older English rule that allowed defences such as an act of a stranger.
    3. Relevance to the case: The petitioners argue that capping the liability of a nuclear operator directly contradicts this settled principle.

    What is channelling of liability?

    1. About: Channelling means directing all legal liability for a nuclear accident to one named party, the operator, so that victims sue a single identified entity instead of tracing fault across the supply chain.
    2. The trade off: Channelling gives victims a quick and certain defendant, and it simultaneously insulates equipment suppliers from any claim for a defective part.

    Who is the Atomic Energy Regulatory Board (AERB)?

    1. About: The AERB is the national regulator for radiation and nuclear safety, constituted in 1983 under the powers of the Atomic Energy Act, 1962.
    2. Mandate: It frames safety codes, licenses nuclear installations and enforces radiation safety across nuclear and non nuclear users of radioactive material.
    3. Structural feature: It is a body created by executive notification rather than by a standalone statute, and it reports to the Atomic Energy Commission.

    What exactly did the Supreme Court ask?

    1. The compensation question: The Bench asked whether the statutory thresholds in the SHANTI Act preclude constitutional courts from determining a fair and just compensation after a nuclear mishap.
    2. The reasoning offered: The Chief Justice of India observed that a constitutional court can always grant suitable compensation against a legal tort, and that a cap imposed by Parliament does not by itself bar the courts.
    3. The regulator question: The Bench separately asked whether the power under Section 17(4) to appoint the AERB Chairperson and Members creates a conflict of interest.
    4. Parties noticed: Notice was issued to the Union government and the AERB on both issues.
    5. The petition: The challenge is to the provisions limiting the liability of operators, suppliers and manufacturers of nuclear installations.

    Why do the petitioners say the caps are inadequate?

    1. The Chernobyl comparison: The loss from the Chernobyl nuclear disaster has been estimated at between $235 billion and $700 billion.
    2. The Fukushima comparison: Cleanup costs at the Fukushima Daiichi nuclear power plant accident of 2011 in Japan have been estimated at approximately $400 billion to $445 billion.
    3. The mismatch: Against these magnitudes, the Act caps the largest Indian operator’s liability at Rs 3,000 crore.
    4. The residual cap: The government’s residual liability of 300 million Special Drawing Rights was described as ensuring that victims of death, injury or property damage cannot recover even a small fraction of actual losses.
    5. The supplier exemption: Exempting suppliers from any liability is argued to encourage manufacturers and suppliers to maximise profit without bearing accident risk.

    How does a liability cap change operator behaviour?

    1. The moral hazard argument: A known ceiling converts an unlimited risk into a budgeted cost, so the incentive to spend beyond that ceiling on safety falls away.
    2. The submission made: Petitioners argued that unless the court states that the liability of operators, suppliers and the government will be judicially determined regardless of the cap, operators and suppliers will cut corners that endanger lives.
    3. The precedent invoked: Indian law has held that a person running a hazardous industry bears absolute and unlimited liability for an accident arising from it.
    4. The claimed violation: Petitioners submitted that this principle has been clearly violated by the statutory ceiling.
    5. Concentration of exposure: With suppliers exempt and the operator capped, the residual cost of a large accident falls on the exchequer and on victims.

    Why is the regulator’s independence in question?

    1. Appointment power: Section 17(4) gives the government the power to appoint the Chairperson and Members of the AERB, and the government is also the promoter of nuclear power in India.
    2. Operator and regulator overlap: The AERB itself has a role connected to nuclear plants while also playing a significant role in regulating them.
    3. International benchmark: Petitioners submitted that this arrangement violates the principle of independence of the regulatory body laid down in international conventions.
    4. Long standing criticism: The absence of a statutorily independent nuclear regulator has been flagged in India for over a decade, including by the Comptroller and Auditor General.
    5. Consequence: A regulator dependent on the promoter for appointments has weaker authority to halt or penalise a plant it supervises.

    Does a liability cap serve investment or does it shift risk to victims?

    1. The investment rationale: The court observed that the limit may exist only to make the nuclear project more attractive to foreign investors.
    2. The counter position: Petitioners argued that investment should not come at the cost of the safety of thousands of lives.
    3. The design logic of caps: Nuclear vendors demand a liability ceiling because unlimited exposure makes an insurance market for the risk impossible to build.
    4. The distributional effect: A cap does not reduce the cost of an accident, it decides who absorbs the part of the cost above the ceiling.
    5. The constitutional question this raises: The dispute is whether Parliament can, by fixing a financial ceiling, foreclose the remedy a constitutional court can grant under Article 32 or Article 226.

    What alternative did the petitioners place before the court?

    1. Solar potential: The government’s own assessment puts India’s solar power potential at 3,343 gigawatts (GW) using 6 per cent of wasteland.
    2. Scale comparison: That potential is 14 times India’s peak power demand of 256 GW.
    3. Build time: Solar capacity can be built in about three months, against the multi year construction cycle of a nuclear plant.
    4. Cost comparison: The per unit cost of solar power was stated as one fifth that of nuclear energy.
    5. Risk comparison: Solar generation carries no comparable accident hazard, so it raises no liability question at all.

    Challenges to the SHANTI Act, 2025 framework

    1. Insurance market depth: The Indian Nuclear Insurance Pool has limited capacity, so even the capped liability may not be fully insurable domestically. e.g. the pool set up in 2015 was capitalised at only about Rs 1,500 crore at inception.
    2. Supplier exemption and quality control: Removing supplier liability weakens the commercial incentive to guarantee component quality. e.g. the supplier recourse clause of the 2010 law was the reason foreign vendors stayed away from Jaitapur and Kovvada for over a decade.
    3. Claims administration capacity: A nuclear claims process needs medical registries and long term follow up that India has struggled to sustain. e.g. Bhopal gas leak claims took decades of adjudication and revision of the settlement figure.
    4. Absence of a statutory regulator: The AERB derives authority from executive notification rather than its own Act. e.g. the Nuclear Safety Regulatory Authority Bill, 2011 lapsed and was never re enacted.
    5. Land acquisition and local consent: New reactor sites face sustained local opposition that liability caps do not address. e.g. the protests at Kudankulam delayed commissioning of the first unit by several years.
    6. Radioactive waste management: India has no operating deep geological repository for high level waste. e.g. spent fuel from operating reactors is stored on site in pools and in away from reactor storage facilities.
    7. Private entry and accountability: Opening the sector to private operators multiplies the number of entities whose safety culture the regulator must supervise. e.g. the sector so far has been run almost entirely by the Nuclear Power Corporation of India Limited and its joint ventures.

    Conclusion

    The dispute is whether a statutory financial ceiling can displace the constitutional power of a court to award compensation for a legal wrong. The Act does not reduce the cost of a nuclear accident, it decides who bears the part of that cost above the ceiling, and at present that is the victim and the exchequer. The measure has reached the stage of an enacted and operating law facing a constitutional challenge, having already replaced the Civil Liability for Nuclear Damage Act, 2010. The next milestone is the response of the Union government and the AERB to the notice issued on the compensation and Section 17(4) questions.

    Nuclear Energy in India

    1. About: Nuclear energy is generated by fission of heavy nuclei such as uranium 235 and plutonium 239, releasing heat that raises steam to drive a turbine.
    2. Three stage programme: India follows a three stage programme designed by the founder of its atomic energy programme, moving from pressurised heavy water reactors, to fast breeder reactors, to thorium based reactors.
    3. Resource logic: The design exists because India has modest uranium reserves and among the world’s largest thorium reserves, concentrated in the monazite sands of Kerala, Tamil Nadu and Odisha.
    4. Installed base: India operates around 24 nuclear power reactors with an installed capacity of about 8.18 GW, contributing roughly 3 per cent of total electricity generation.
    5. Stated target: The government has set a target of 100 GW of nuclear capacity by 2047 as part of the energy transition plan.
    6. Institutional structure: The Department of Atomic Energy administers the sector, NPCIL builds and operates plants, and the AERB regulates safety.
    7. Global position: India is among the few countries operating a closed fuel cycle with reprocessing, and it operates outside the Nuclear Non Proliferation Treaty while holding a safeguards agreement with the International Atomic Energy Agency.

    Constitutional and Statutory Framework Governing Nuclear Liability

    1. Entry 6 of the Union List: Places atomic energy and mineral resources necessary for its production exclusively with Parliament.
    2. Article 21: Guarantees the right to life, read to include a right to compensation for violation caused by a hazardous activity.
    3. Article 32: Empowers the Supreme Court to issue writs and award compensation for violation of fundamental rights.
    4. Article 226: Gives High Courts a parallel and wider writ power, including the award of compensation in public law.
    5. Article 48A and Article 51A(g): Direct the State and citizens respectively to protect and improve the environment.
    6. Article 253: Enables Parliament to legislate to implement international conventions, the basis for aligning Indian liability law with the Convention on Supplementary Compensation.
    7. Article 246 with Entry 13 of the Union List: Covers participation in international conferences and implementation of decisions taken there.

    Laws and Rules Governing Nuclear Energy in India

    1. Atomic Energy Act, 1962: Gives the Union exclusive control over atomic minerals, production and use of atomic energy, and the licensing of nuclear installations.
    2. Atomic Energy (Radiation Protection) Rules, 2004: Set radiation dose limits and licensing conditions for radiation facilities.
    3. Atomic Energy (Factories) Rules, 1996: Govern safety in factories handling radioactive material.
    4. Civil Liability for Nuclear Damage Act, 2010: Created a no fault liability regime channelled to the operator, with a right of recourse against the supplier.
    5. Section 17(b): Allowed the operator recourse against a supplier for a patent or latent defect, the clause foreign vendors objected to.
    6. Sustainable Harnessing and Advancement of Nuclear Energy for Transforming India (SHANTI) Act, 2025: Replaced the 2010 Act, capped operator and government liability and exempted suppliers.
    7. Draft rules under the Act: Released by the Department of Atomic Energy for public comment, with the comment window closing on 4 September 2026.
    8. Environment (Protection) Act, 1986: Provides the environmental clearance and pollution control regime applicable to nuclear installations.
    9. Disaster Management Act, 2005: Places nuclear and radiological emergencies within the national disaster response framework.
    10. Convention on Supplementary Compensation for Nuclear Damage: Ratified by India in 2016, providing a tier of international funds after national compensation is exhausted.

    Back2Basics: Atomic Energy Regulatory Board (AERB)

    1. Governing Act: Constituted under the powers conferred by the Atomic Energy Act, 1962.
    2. Year established: 1983, by an executive order of the Government of India.
    3. Headquarters: Mumbai.
    4. Reporting line: Reports to the Atomic Energy Commission, and its Chairperson is appointed by the government.
    5. Jurisdiction: Covers nuclear power plants, research reactors, fuel cycle facilities, and every industrial and medical user of radiation sources in India.
    6. Mandate: Frames safety codes and standards, grants consent at each stage from siting to decommissioning, conducts regulatory inspections and enforces compliance.
    7. Enforcement powers: Can suspend or cancel authorisation and direct shutdown of a facility that violates safety conditions.

    Government Initiatives in the Nuclear Sector

    1. Nuclear Energy Mission for Viksit Bharat: Announced with an outlay of about Rs 20,000 crore for research and development of small modular reactors, targeting five indigenously designed reactors by 2033.
    2. Bharat Small Reactors: Compact reactors planned for captive use by energy intensive industry, to be set up in partnership with private players on their own land.
    3. Three Stage Nuclear Programme: The long term plan to use natural uranium, then plutonium in fast breeder reactors, and finally the domestic thorium reserve.
    4. Prototype Fast Breeder Reactor at Kalpakkam: The stage two demonstration project built by Bharatiya Nabhikiya Vidyut Nigam Limited.
    5. Joint venture route: ASHVINI, the joint venture of NPCIL and NTPC, was created to add nuclear capacity using public sector balance sheets.
    6. Indian Nuclear Insurance Pool: Formed by general insurers with GIC Re to provide insurance cover for operator and supplier liability.
    7. Fleet mode construction: Bulk approval of ten pressurised heavy water reactors of 700 MW each to build in series and cut per unit cost.

    Key Facts about Nuclear Energy in India

    1. First reactor: Apsara, commissioned in 1956 at Trombay, was Asia’s first research reactor.
    2. First power station: The Tarapur Atomic Power Station in Maharashtra, commissioned in 1969, is India’s oldest nuclear power plant.
    3. Largest station: Kudankulam in Tamil Nadu, built with Russian cooperation, is India’s largest nuclear power station by capacity.
    4. Indigenous workhorse: The 700 MW pressurised heavy water reactor, first at Kakrapar in Gujarat, is the indigenous standard design.
    5. Fuel type: Indian pressurised heavy water reactors use natural uranium as fuel and heavy water as moderator and coolant.
    6. Safeguards status: India signed a safeguards agreement with the International Atomic Energy Agency in 2009 after the civil nuclear cooperation waiver.
    7. Sector regulator: AERB, with the Directorate of Radiation Safety in some States handling medical radiation sources.

    Challenges in India’s Nuclear Energy Sector

    1. Slow capacity addition: Nuclear capacity has grown far slower than the targets repeatedly announced. e.g. installed capacity remains near 8 GW against a 2047 target of 100 GW.
    2. Fuel supply constraint: Domestic uranium is limited and of low grade, forcing dependence on imports. e.g. India imports uranium from Kazakhstan, Russia, Canada, France and Uzbekistan under bilateral agreements.
    3. Cost and time overruns: Long gestation and heavy civil works push project costs well beyond estimates. e.g. the Prototype Fast Breeder Reactor at Kalpakkam has slipped many years past its original commissioning date.
    4. Public opposition and land acquisition: Communities near proposed sites resist acquisition and fear radiation exposure. e.g. the Jaitapur project in Maharashtra has faced sustained local opposition since 2010.
    5. Waste management gap: No permanent disposal route exists for high level radioactive waste. e.g. spent fuel remains in interim storage rather than a deep geological repository.
    6. Regulatory independence: The safety regulator lacks statutory autonomy from the promoter of the sector. e.g. the Comptroller and Auditor General flagged the AERB’s dependence on the Department of Atomic Energy in a 2012 performance audit.
    7. Liability and vendor hesitation: Uncertainty over the liability regime has stalled foreign built projects. e.g. the Kovvada and Jaitapur projects agreed with United States and French vendors have not reached financial close.
    8. Human resource pipeline: Reactor operations need specialised health physicists and reactor engineers trained over years. e.g. a fleet mode expansion to 100 GW would require a multiple of the current trained workforce.

    Way Forward

    1. Enact a statutory nuclear regulator: Replace the executive constituted AERB with an authority created by its own Act, with fixed tenure and financial autonomy.
    2. Index and review the liability ceiling: Provide a statutory mechanism to revise the operator and government caps periodically, so the figures do not lose meaning with inflation.
    3. Preserve judicial remedy expressly: Clarify that the statutory ceiling governs the no fault claim route and does not oust the writ jurisdiction of constitutional courts.
    4. Deepen the insurance pool: Expand the Indian Nuclear Insurance Pool with reinsurance support so the capped liability is genuinely backed by paid capacity.
    5. Build a claims administration system: Establish standing medical registries and a claims commissioner framework in advance rather than after an accident.
    6. Commit to a waste repository programme: Begin site characterisation for a deep geological repository with a published timeline.
    7. Balance the energy mix: Pair nuclear expansion with the far faster and cheaper solar build out, treating nuclear as firm baseload rather than the primary route to the clean energy target.

    Matching Previous Year Question

    “[2018, GS3, 15 marks] With growing energy needs should India keep on expanding its nuclear energy programme? Discuss the facts and fears associated with nuclear energy.”
  • Ethanol Debate: Should India Bring Back E10 Alongside E20?

    Why in the News

    A public campaign claiming that E20 petrol wrecks engines and empties fuel tanks faster has been answered with test evidence showing no increased engine wear. The rebuttal has exposed the question the blending debate has avoided, which is whether pushing the blend beyond 20 percent moves land and water from food to fuel.

    What is the Ethanol Blended Petrol Programme?

    1. About: The programme mandates the blending of ethanol, an alcohol produced from crops, into petrol sold by oil marketing companies. E20 denotes a fuel that is 20 percent ethanol by volume and 80 percent petrol.
    2. Origin: It was rolled out nationally from 2003 and expanded through the National Policy on Biofuels, 2018.
    3. Feedstock routes: Ethanol is produced from sugarcane juice, B heavy and C heavy molasses, maize, damaged food grains and surplus rice.
    4. Stated objectives: It aims to cut the crude oil import bill, reduce tailpipe emissions and give cane and grain growers an assured market.
    5. Price setting: Oil marketing companies buy ethanol at administered prices that differ by feedstock route rather than at a single market price.

    What is the distinction between green water and blue water?

    1. Green water: This is rainfall held in the soil and taken up by the crop, water the field would have received in any case.
    2. Blue water: This is water drawn from rivers, canals, groundwater pumps and wells. It is the scarce component, because withdrawing it denies the same unit to another user.

    What are Distillers Dried Grains with Solubles?

    1. About: These are the residual grain solids left over after ethanol is distilled from maize or rice.
    2. Where they go: They are sold as protein rich animal feed and compete directly with soybean meal in the same market.

    Why does the charge that E20 damages engines not hold up?

    1. Lower energy density is real: Ethanol carries about two thirds the energy of petrol. A litre of E20 therefore takes a vehicle slightly less far.
    2. The size of the penalty is small: Ethanol is only a fifth of the blend, so the energy loss is around 6 to 7 percent. The 30 percent figure circulating online is wrong.
    3. Emissions improve: Carbon monoxide and unburnt hydrocarbons fall on E20, which is an environmental gain.
    4. Domestic durability testing agrees: Testing by the Automotive Research Association of India (ARAI), the petroleum institute and Indian Oil found no increased wear attributable to the blend.
    5. The fear is misplaced, the concern is not: Loss of range is not a malfunction. The genuine problem lies elsewhere in the fleet.

    Which vehicles are the genuine exception to that record?

    1. Scale of the exposed fleet: India has roughly 75 million to 80 million two wheelers built before the BS4 norms that run on carburettors.
    2. Why a carburettor cannot adjust: A carburettor cannot sense the extra oxygen the blend carries. The engine then draws too little fuel for the air it takes in and runs hot.
    3. Seal degradation is a separate defect: Older rubber seals not rated for ethanol degrade on contact with the fuel. This happens irrespective of engine temperature.
    4. Retrofitting is cheap but slow: Replacing seals with ethanol compatible ones costs little. Covering 75 million to 80 million two wheelers happens one vehicle at a time and will take years.
    5. The protection fuel went missing: The original roadmap asked that a lower blend stay on sale for these vehicles. That fuel quietly vanished from the pumps.
    6. What restoring E10 would achieve: Selling E10 alongside E20 would protect the legacy fleet while the retrofit programme catches up. It would also lower total ethanol use rather than raise it.

    Why is the edible oil import gap a better target than the crude oil bill?

    1. Scale of the crude bill: India’s crude oil import bill runs at around Rs 11 lakh crore to Rs 12 lakh crore a year.
    2. Scale of the edible oil bill: The edible oil import bill is far smaller, at roughly Rs 1.6 lakh crore to Rs 1.75 lakh crore.
    3. What E20 actually saves: Ethanol at E20 trims only 3 to 4 percent of the crude bill.
    4. The edible oil gap is closeable: India already produces about 40 percent of its cooking oil and aims to reach 72 percent by financial year 2031.
    5. The test of a good target: A gap the government can close fully and then stop subsidising is worth more than one it can only reduce at the margin forever.

    How has the shift in feedstock turned a distant trade off into a direct one?

    1. Grain now dominates the feedstock mix: Maize supplies about half of India’s ethanol. Grains together supply nearly 67 percent.
    2. Direct competition for the same fields: Maize competes with soybean, groundnut and mustard for identical acreage.
    3. First pull, the administered price: Ethanol from maize is procured at a fixed price well above the sugarcane route. That keeps maize attractive whatever the open market pays.
    4. Second pull, the feed by product: The leftover grain from distillation is sold as animal feed and undercuts soybean meal.
    5. The oilseed farmer loses twice: Weaker meal prices drag down soybean prices. The grower loses on acreage and then again on price.

    Why do the water and climate claims not settle the case for a higher blend?

    1. The headline figure mixes two things: Quoted totals of thousands of litres of water per litre of ethanol combine green water and blue water into one alarming number.
    2. Only the blue component is scarce: Rain the crop would have received anyway does not represent a withdrawal from a contested source.
    3. Where the pressure actually falls: Cane in Maharashtra and Karnataka draws heavily on already stressed rivers, canals and groundwater.
    4. What the rule should measure: A water norm for ethanol should target blue water use, not the frightening aggregate.
    5. The climate evidence is unsettled: Indian life cycle studies do not agree on whether grain ethanol is cleaner than the alternatives once cultivation and processing are counted.
    6. Consequence for the green case: The environmental argument for going beyond E20 does not survive close scientific scrutiny.

    What does experience abroad show about the limits of high ethanol blends?

    1. United States, Oak Ridge National Laboratory: The laboratory ran 86 vehicles for a cumulative 10 million kilometres on blends up to E20 and found no increased wear in cars not rated for E20.
    2. United States, multiple blends at the pump: American pumps sell E10 and E15 side by side, so owners of older vehicles retain a compatible option. This is the design India’s roadmap intended and then lost.
    3. United States, Renewable Fuel Standard: The mandate fixes volumes of renewable fuel in transport fuel. Its corn ethanol component drew sustained criticism for raising feed and food grain prices.
    4. Brazil, the Proalcool programme: Brazil built blending on sugarcane and on flex fuel vehicles able to run on any blend up to pure ethanol. The fleet, rather than the fuel specification, absorbs changes in the blend.

    Why is holding at E20 not a costless option either?

    1. Cane arrears were cleared: Ethanol demand gave sugar mills the cash flow to settle sugarcane dues owed to farmers.
    2. Rural incomes rose: The programme lifted incomes and built an assured market for cane and grain growers.
    3. Distillery capacity was built for more: Capacity now in place was created on the expectation of blends above E20.
    4. Loans were taken against expected demand: Those investments carry debt to be serviced against demand a freeze would not deliver.
    5. The sugar surplus needs an outlet: Ethanol absorbs a structural sugar surplus that would otherwise depress domestic prices.
    6. Both sides belong in the reckoning: The honest course weighs the cost of holding against the cost of advancing, rather than assuming either away.

    Why should reversibility decide the sequence of policy moves?

    1. Instruments that can change within a season: The ethanol procurement price, the protection fuel at the pump, the water rules and the import duty on edible oil can all be altered and reversed if evidence turns.
    2. The one instrument that cannot: The blend level is not reversible on the same timescale.
    3. Why the blend locks in: Once land and water are committed to fuel, cropping patterns and distillery investment are built around that commitment.
    4. The sequencing principle: Prudence says to move the reversible instruments first and hold off on the irreversible one until a thorough cost benefit analysis is complete.
    5. What the recommendation amounts to: Restore E10 for the older fleet, correct the price and water distortions favouring maize, revisit the edible oil import duty, and hold at E20.

    Challenges to the Ethanol Blended Petrol Programme

    1. Feedstock concentration in water intensive crops: Cane and maize both carry heavy irrigation demand in already stressed basins. e.g. Latur in Maharashtra received drinking water by train during the 2016 Marathwada drought while cane crushing continued in the region.
    2. Diversion of food grain to fuel: Grain routed to distilleries competes with the public distribution and feed markets. e.g. the release of surplus rice by the Food Corporation of India to distilleries was repeatedly started and stopped between 2023 and 2024 as open market rice prices rose.
    3. Material compatibility in the legacy fleet: Older engines and fuel lines were never certified for a 20 percent blend. e.g. two wheelers manufactured before the BS4 norms of 2017 use carburettors and non compliant elastomer seals.
    4. Blending logistics and evacuation: Ethanol absorbs water and cannot move through existing multiproduct petroleum pipelines. e.g. supply moves by road tanker from distillery clusters in Uttar Pradesh and Maharashtra to deficit states in the south and the east.
    5. Second generation ethanol has not scaled: Cellulosic ethanol from crop residue remains commercially fragile. e.g. the Panipat second generation bioethanol refinery based on paddy straw has struggled with feedstock aggregation since its commissioning in 2022.
    6. Administered price distortion across routes: A fixed price above the cane route pulls acreage towards maize regardless of demand. e.g. maize acreage has expanded in Bihar and Madhya Pradesh at the expense of oilseeds.
    7. Consumer trust and labelling: Buyers cannot easily tell which blend they are purchasing or whether their vehicle is rated for it. e.g. the 2026 online campaign over E20 mileage produced public demands for a lower blend option at pumps.

    Conclusion

    The engine controversy was never the real argument. The decision that matters is the blend level itself, because procurement prices, water rules, the protection fuel and import duties can be reversed within a season while committed land, cropping patterns and distillery capacity cannot. Restoring E10 for the older fleet and holding at E20 until the food versus fuel trade off is properly costed keeps every reversible option open. The unresolved question is what India chooses to grow, and what it will not be able to take back.

    Biofuels and Ethanol Blending in India

    1. About: Biofuels are liquid or gaseous fuels produced from biomass and used to substitute petroleum products in transport.
    2. Categories: They run from first generation fuels made from food crops, to second generation fuels from agricultural residue, third generation fuels from algae and fourth generation fuels using carbon capture.
    3. Blending record: Average ethanol blending rose from 1.53 percent in financial year 2014 to 20 percent in 2025, achieved five years ahead of the 2030 target.
    4. Global standing: India is among the largest ethanol producers and consumers in the world, after the United States and Brazil.
    5. Scale of the fuel base: India consumes roughly 40 million tonnes of petrol a year, which sets the size of the ethanol requirement at any given blend.
    6. Claimed gains: Official statements place foreign exchange savings from ethanol blending at over Rs 1 lakh crore since 2014.
    7. Structural feature: Ethanol is the only large scale biofuel India has commercialised, while biodiesel and compressed biogas remain far below their targets.

    Laws and Rules Governing Biofuels in India

    1. National Policy on Biofuels, 2018: Categorises biofuels, widens the permitted feedstock list and sets indicative blending targets.
    2. 2022 amendment: Advanced the 20 percent ethanol blending target to the 2025 26 ethanol supply year and permitted additional feedstocks.
    3. Industries (Development and Regulation) Act, 1951: Provides the regulatory basis for distilleries and for the Centre’s control over industrial and denatured alcohol.
    4. Judicial position: A nine judge Bench of the Supreme Court held in October 2024 that “intoxicating liquor” under Entry 8 of the State List covers industrial alcohol, preserving State regulatory power.
    5. Essential Commodities Act, 1955: Enables control over the movement, storage and pricing of molasses and ethanol.
    6. Environment (Protection) Act, 1986: Governs distillery effluent standards, including zero liquid discharge norms for molasses based units.
    7. Motor Vehicles Act, 1988 and Central Motor Vehicles Rules, 1989: Set emission norms and material compatibility requirements for vehicles rated to run on E20.
    8. Bureau of Indian Standards specifications: IS 2796 governs motor gasoline and IS 15464 governs anhydrous ethanol, with a separate notified specification for E20 fuel.

    Back2Basics: National Policy on Biofuels, 2018

    1. Nodal ministry: Ministry of Petroleum and Natural Gas.
    2. Approval and revision: Approved by the Union Cabinet in 2018 and amended in 2022.
    3. Categorisation: Divides biofuels into Basic Biofuels, meaning first generation bioethanol and biodiesel, and Advanced Biofuels, meaning second generation ethanol, municipal solid waste to drop in fuels, third generation biofuels and bio compressed natural gas.
    4. Permitted raw materials for ethanol: Sugarcane juice, sugar beet, sweet sorghum, corn, cassava, damaged food grains such as wheat and broken rice, and rotten potatoes unfit for human consumption.
    5. Blending targets: 20 percent ethanol in petrol and 5 percent biodiesel in diesel by 2030, with the ethanol target later advanced to the 2025 26 supply year.
    6. Surplus grain clause: Allows use of surplus food grains for ethanol production with the approval of the National Biofuel Coordination Committee, chaired by the Minister of Petroleum and Natural Gas.
    7. Financial support: Provides viability gap funding for second generation ethanol refineries and additional incentives for advanced biofuels.

    Government Initiatives for Biofuels and Ethanol

    1. Ethanol Blended Petrol Programme, 2003: Mandates blending of ethanol in petrol supplied by oil marketing companies across notified states and Union Territories.
    2. Pradhan Mantri JI-VAN Yojana, 2019: Provides viability gap funding to commercial and demonstration second generation bioethanol projects using lignocellulosic biomass.
    3. SATAT initiative, 2018: Sustainable Alternative Towards Affordable Transportation invites entrepreneurs to set up compressed biogas plants and sell the output to oil marketing companies.
    4. GOBARdhan scheme: Converts cattle dung and agricultural waste into biogas and organic manure, targeted at rural households and dairy clusters.
    5. Ethanol Interest Subvention Scheme: Subsidises interest on loans taken by sugar mills and standalone distilleries to expand ethanol capacity.
    6. Global Biofuels Alliance: Launched at the G20 New Delhi Summit in September 2023 with India, the United States and Brazil as founding members, to accelerate global biofuel trade and technology transfer.
    7. National Mission on Edible Oils, Oil Palm, 2021, and the Oilseeds Mission: Target domestic self sufficiency in cooking oil, which is the competing claim on the same land the ethanol programme draws from.

    Key Facts about Ethanol Blending

    1. World Biofuel Day is observed on 10 August, marking the day in 1893 an engine was run on peanut oil by Rudolf Diesel.
    2. The Ethanol Supply Year runs from 1 November to 31 October, not the financial year.
    3. E20 is 20 percent ethanol by volume, E85 is 85 percent, and E100 denotes ethanol used as a standalone fuel.
    4. India achieved 20 percent average blending in 2025, five years ahead of the 2030 target set in the 2018 policy.
    5. Flex fuel vehicles are engineered to run on any blend up to E85 or E100 without modification.
    6. Ethanol procurement uses differential administered prices by feedstock route, with the sugarcane juice route priced highest among cane routes.
    7. The National Biofuel Coordination Committee clears the use of surplus food grains for ethanol.

    Challenges in the Biofuel Sector

    1. Biodiesel blending has barely moved: Against a 5 percent target, biodiesel blending has remained close to negligible. e.g. used cooking oil collection under the Repurpose Used Cooking Oil initiative covers only a fraction of India’s restaurant and hotel supply chain.
    2. Sugar cycle volatility disrupts contracts: Ethanol supply from cane is hostage to sugar availability decisions taken mid season. e.g. the 2023 restriction on diverting cane juice to ethanol was imposed to protect domestic sugar supply and stranded distillery offtake plans.
    3. Centre and State conflict over alcohol regulation: Regulatory authority over industrial alcohol is contested and affects distillery licensing. e.g. the Supreme Court’s nine judge ruling of October 2024 held that States retain power over industrial alcohol under Entry 8 of the State List.
    4. Compressed biogas offtake and evacuation: Plant commissioning lags the announced targets because feedstock aggregation and gas evacuation are unresolved. e.g. SATAT set a target of 5,000 compressed biogas plants and actual commissioning has run far behind.
    5. Water footprint of the feedstock base: Blending demand is concentrated in crops grown in drought prone tracts. e.g. Maharashtra’s cane belt draws on stressed groundwater in districts that carry recurring drought declarations.
    6. Vehicle fleet compatibility lag: Only recent vehicles are certified for the mandated blend. e.g. only vehicles manufactured from April 2023 are E20 material compliant, leaving the older fleet dependent on a lower blend that is no longer sold.
    7. Absence of a settled national life cycle assessment: Without an agreed carbon accounting method, the climate benefit claimed for each blend level cannot be verified. e.g. Indian studies differ on whether maize ethanol lowers emissions once fertiliser and processing energy are counted.

    Way Forward

    1. Restore a lower blend at the pump: Sell E10 alongside E20 nationally until the retrofit of pre BS4 two wheelers is substantially complete.
    2. Correct the administered price: Reprice ethanol by feedstock so that maize does not carry an artificial advantage over oilseeds.
    3. Regulate blue water, not aggregate water: Set distillery and feedstock water norms on measured groundwater and canal withdrawal, with metering at the distillery gate.
    4. Fund oilseed self sufficiency: Direct the incentive structure towards closing the edible oil import gap, which is smaller and fully closeable.
    5. Scale second generation ethanol: Build residue aggregation networks so that paddy straw and bagasse substitute for grain feedstock.
    6. Mandate flex fuel capability: Require new vehicles to be flex fuel rated so that future blend changes are absorbed by the fleet rather than by the fuel specification.
    7. Publish a national cost benefit study: Complete a transparent food versus fuel accounting, covering land, blue water and life cycle emissions, before any move to E27 or E30.

    “[2020] According to India’s National Policy on Biofuels, which of the following can be used as raw materials for the production of biofuels?
    1. Cassava
    2. Damaged wheat grains
    3. Groundnut seeds
    4. Horse gram
    5. Rotten potatoes
    6. Sugar beet
    Select the correct answer using the code given below:
    (a) 1, 2, 5 and 6 only
    (b) 1, 3, 4 and 6 only
    (c) 2, 3, 4 and 5 only
    (d) 1, 2, 3, 4, 5 and 6

  • Why India needs more power for AI, chips and datacentres

    Why in the News

    The Department of Atomic Energy released draft rules covering private participation, captive generation, licensing, safety oversight and nuclear liability under the SHANTI Act. The rules follow a stated target of 100 GWe of nuclear capacity by 2047 against an operating base of 8.7 GWe. The tension is between opening a sector historically closed to private capital and retaining state control over fissile material, safety and liability.

    What is the SHANTI Act?

    1. About: The SHANTI Act is the legislation passed last year that opens nuclear power generation to private participation, ending the state monopoly on reactor operation.
    2. What it changes: It creates a licensing route for private operators and permits captive nuclear generation for industrial users.
    3. What it retains: Fuel cycle control, safety regulation and the liability framework stay with the state.
    4. Status: Draft rules under the Act have been released, so the operating framework is now in the consultation stage rather than in force.

    What is a Small Modular Reactor?

    1. About: A Small Modular Reactor (SMR) is a reactor of up to about 300 MWe built from factory fabricated modules rather than constructed entirely on site.
    2. Why it matters: Factory fabrication shortens construction time and lowers the upfront capital block that makes large reactors hard to finance.

    Where does India’s nuclear capacity actually stand?

    1. Operating fleet: 25 reactors in operation with a combined capacity of 8.7 GWe.
    2. Under construction: 10 reactors adding about 8 GWe.
    3. Pre project stage: 10 further reactors accounting for about 66 GWe, which is where most of the 100 GWe target sits.
    4. Commissioning plan: Five new reactors are to be commissioned this decade.
    5. Backbone technology: Pressurised Heavy Water Reactors remain the mainstay of the operating fleet.

    What is the indigenous small reactor programme?

    1. Bharat Small Modular Reactor: A 200 MWe design (BSMR-200) intended for grid and captive industrial supply.
    2. Compact variant: A 55 MWe small modular reactor for smaller loads and remote siting.
    3. High temperature design: A 5 MWt high temperature gas cooled reactor aimed at hydrogen production through a thermochemical process.
    4. Deployment target: At least five indigenous small modular reactors operational by 2033.
    5. Mission funding: The Nuclear Energy Mission carries an outlay of Rs 20,000 crore.
    6. Site reuse: Retiring thermal plant sites are being studied for repurposing, since they already carry grid connection and cooling water access.

    Why is demand growth driving the target now?

    1. Datacentre load: Artificial intelligence and datacentre expansion require firm, round the clock power that intermittent renewables cannot supply alone.
    2. Capacity addition: Operational datacentre stock stands at 1.8 GW of information technology load, with about 500 MW projected to be added in 2026.
    3. Industrial decarbonisation: Semiconductor fabrication and green hydrogen electrolysis both need continuous low carbon power.
    4. Grid character: Nuclear supplies baseload, which is the specific gap left by a renewables heavy addition profile.

    Where does foreign collaboration fit?

    1. Russia: The existing large light water reactor partnership at Kudankulam is the deepest supplier relationship.
    2. United States: Collaboration is expected to centre on small modular designs rather than large units.
    3. France: Large reactor negotiations have run for over a decade without financial closure.
    4. Design economics: Foreign collaboration is shifting toward small modular reactors because large light water reactors carry costs India has not been able to close on.

    Challenges to the 100 GWe nuclear target

    1. Liability deterrence: Supplier liability provisions have kept foreign vendors from signing commercial contracts. e.g. the Jaitapur project’s unresolved negotiation with the French supplier since 2010.
    2. Construction schedule slippage: Indian reactors have historically overrun their commissioning schedules by years. e.g. the Kudankulam units commissioned well past their original dates.
    3. Land acquisition and local resistance: Reactor siting has triggered sustained local opposition. e.g. the prolonged protests at Kudankulam in Tamil Nadu.
    4. Fuel supply: Domestic uranium output is insufficient, leaving the fleet dependent on imported fuel under safeguards. e.g. supply agreements with Kazakhstan, Canada and Russia.
    5. Regulatory independence: The Atomic Energy Regulatory Board is not a statutory body independent of the Department of Atomic Energy. e.g. the Comptroller and Auditor General’s 2012 audit flagging this exact conflict.
    6. Cooling water availability: Reactor cooling depends on assured water, which climate stress is making less reliable. e.g. Hungary running the Paks plant at a quarter of capacity in 2026 because Danube levels fell.

    Conclusion

    The draft rules are the point at which the SHANTI Act stops being an enabling statute and becomes an operating framework, which is what private capital has been waiting for. The 100 GWe target is arithmetically dominated by reactors still at the pre project stage, so the binding question is licensing throughput rather than intent. The next milestone is the finalisation of the draft rules and the first private licence issued under them.

    Nuclear Energy in India

    1. Three stage programme: India’s programme runs from pressurised heavy water reactors using natural uranium, to fast breeder reactors using plutonium, to thorium based reactors exploiting India’s large thorium reserves.
    2. Thorium position: India holds among the world’s largest monazite bearing thorium reserves, concentrated in the beach sands of Kerala, Tamil Nadu and Odisha.
    3. Share of generation: Nuclear supplies about 3 per cent of India’s electricity generation.
    4. Institutional structure: The Department of Atomic Energy reports directly to the Prime Minister, and the Nuclear Power Corporation of India Limited operates the commercial fleet.
    5. Safeguards status: India operates a separated civil and military nuclear programme, with civil facilities placed under International Atomic Energy Agency safeguards after the 2008 waiver.

    Laws and Rules Governing Nuclear Energy

    1. Atomic Energy Act, 1962: Vests control of atomic minerals, fissile material and reactor operation in the central government. Reserved commercial nuclear generation to public sector entities until the SHANTI Act.
    2. Civil Liability for Nuclear Damage Act, 2010: Channels liability to the operator and creates a right of recourse against the supplier. Section 17(b) is the specific provision that foreign suppliers have objected to.
    3. Atomic Energy (Radiation Protection) Rules, 2004: Govern radiation safety, licensing of radiation installations and occupational exposure limits.
    4. SHANTI Act: Opens generation to private participation and provides for captive nuclear generation. Draft rules covering licensing, captive generation, safety oversight and liability were released on 14 August 2026.

    Government Initiatives

    1. Nuclear Energy Mission: Carries an outlay of Rs 20,000 crore for research and deployment of small modular reactors.
    2. Bharat Small Modular Reactor programme: Develops a 200 MWe indigenous design for grid and captive industrial supply.
    3. Nuclear Power Corporation of India fleet mode procurement: Approves multiple pressurised heavy water reactors together to compress procurement and construction timelines.
    4. India based Neutrino Observatory and allied research: Supports the domestic research base underpinning the three stage programme.

    Way Forward

    1. Finalise the liability rules: Settle supplier recourse in the notified rules so vendor contracts can reach financial closure.
    2. Make the regulator statutory: Give the Atomic Energy Regulatory Board statutory independence from the Department of Atomic Energy.
    3. Standardise the small reactor design: Freeze one design for repeat build so factory fabrication delivers its cost advantage.
    4. Use retiring thermal sites: Convert closed thermal plant land, which already has grid and water access, into small reactor sites.
    5. Publish a licensing timeline: Give applicants a defined statutory clock for licence decisions, since 66 GWe of the target sits in reactors not yet approved.

    Matching Previous Year Question

    “[2018, GS3, 15 marks] With growing energy needs should India keep on expanding its nuclear energy programme? Discuss the facts and fears associated with nuclear energy.”
  • Draft rules under the SHANTI Act open nuclear power to captive industrial use and a composite licence

    Why in the News

    The Department of Atomic Energy released draft rules under the Sustainable Harnessing and Advancement of Nuclear Energy for Transforming India (SHANTI) Act on 14 August 2026, opening nuclear power generation to private and captive users. Comments are invited until 4 September 2026.

    What is the SHANTI Act?

    • Replaces the earlier state monopoly framework with a licensing regime for non-government operators.
    • Covers private participation, captive generation, foreign reactor technology, safety and nuclear liability.
    • Provides a single composite licence for building, owning, operating and decommissioning a reactor.

    Key Provisions

    1. Captive nuclear power: Industries can generate nuclear electricity mainly for their own consumption.
    2. In-principle approval: Allows land acquisition and vendor negotiations before final licensing.
    3. Foreign technology: Imported designs must be certified by the regulator in the country of origin and already operational.
    4. Nuclear liability: Operators must maintain insurance or financial security; a Nuclear Liability Fund is proposed.
    5. Eligible users: Aluminium, cement, data centres, semiconductor fabs and Artificial Intelligence (AI) facilities.

    Key Concern

    • The country-of-origin certification may speed up safety approval but restrict technology sourcing to a few countries. Requiring continued support and retaining Intellectual Property Rights (IPR) with foreign developers could also limit technology transfer and indigenous reactor design.

    India’s Nuclear Programme

    • Stage 1: Pressurised Heavy Water Reactors (PHWRs) using natural uranium.
    • Stage 2: Fast Breeder Reactors (FBRs) using plutonium.
    • Stage 3: Thorium-based reactors using Uranium-233 (U-233).
    • Target: 100 GW nuclear capacity by 2047.

    Challenges

    • Supplier liability concerns
    • Limited regulatory independence
    • Land and public acceptance
    • Uranium and fuel constraints
    • Nuclear waste management
    • High project costs and long construction timelines

    Prelims Pointers

    • DAE: Department of Atomic Energy
    • AERB: Atomic Energy Regulatory Board
    • NPCIL: Nuclear Power Corporation of India Limited
    • BHAVINI: Bharatiya Nabhikiya Vidyut Nigam Limited
    • NPT: Nuclear Non-Proliferation Treaty
    • NSG: Nuclear Suppliers Group
    • India is not a signatory to NPT and received an NSG waiver in 2008.

    [2018, GS3, 15 marks] With growing energy needs should India keep on expanding its nuclear energy programme? Discuss the facts and fears associated with nuclear energy.”
    [2020]  In India, why are some nuclear reactors kept under “IAEA safeguards” while others are not ?

    a) Some use uranium and others use thorium
    b) Some use imported uranium and others use domestic supplies
    c) Some are operated by foreign enterprises and others are operated by domestic enterprises
    d) Some are State-owned and others are privately-owned

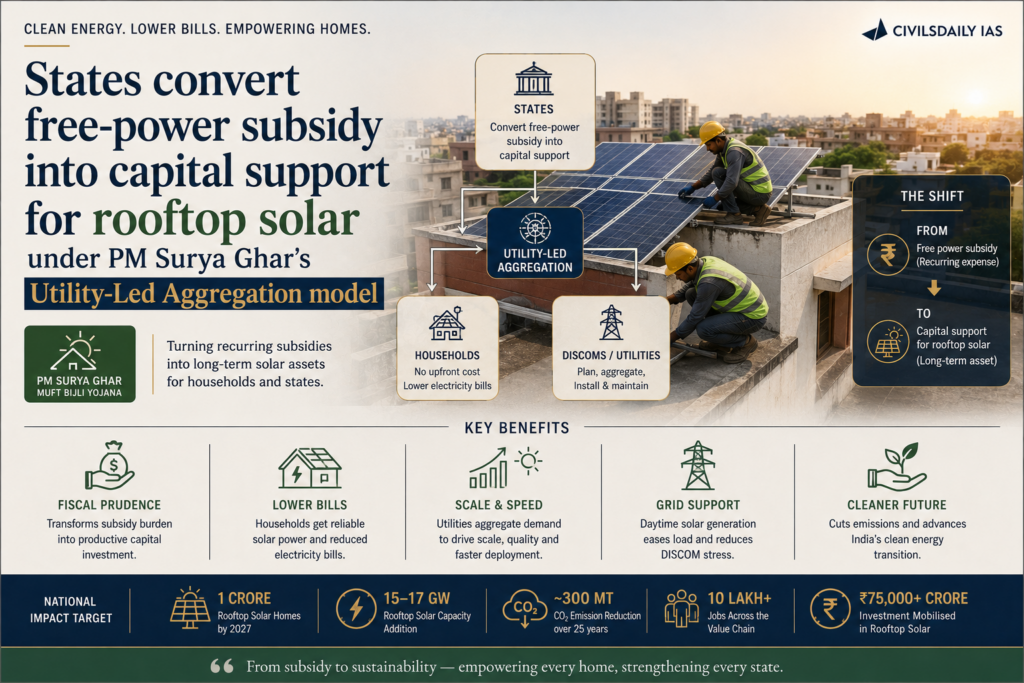
  • States convert free-power subsidy into capital support for rooftop solar under PM Surya Ghar’s Utility-Led Aggregation model

    Why in the News

    States such as Uttar Pradesh, Andhra Pradesh and Bihar are shifting recurring free-power subsidies towards one-time capital support for rooftop solar under the Utility-Led Aggregation (ULA) model.

    What is PM Surya Ghar Yojana?

    • Ministry: Ministry of New and Renewable Energy (MNRE)
    • Launch: 13 February 2024
    • Target: 1 crore households with grid-connected rooftop solar by March 2027.
    • Outlay: ₹75,021 crore.
    • Benefit: Up to 300 units of free electricity per month.
    • Central subsidy: ₹30,000/kW up to 2 kW, plus ₹18,000 for the third kW, capped at ₹78,000.
    • Eligibility: Household must have a suitable roof and grid connection.

    What is ULA?

    • Utility-Led Aggregation (ULA) is a model where the distribution company (DISCOM) aggregates household demand and arranges rooftop solar installations at scale.
    • States convert recurring electricity subsidies into one-time capital support for installing solar systems.

    Why the Shift?

    • Reduces recurring State subsidy burden.
    • Creates a 25-year generating asset.
    • Reduces DISCOM’s cost of supplying subsidised daytime electricity.
    • Aggregated procurement can reduce installation costs.

    Current Progress

    • 52 lakh households had installed rooftop systems by 13 August.
    • About 2 lakh of 30 lakh ULA installations are complete.
    • Target: 1 crore households by March 2027.

    Key Definitions

    • Rooftop Solar: Solar photovoltaic system installed on a building roof and connected to the electricity distribution network.
    • Net Metering: Allows surplus rooftop electricity exported to the grid to be adjusted against electricity consumed.
    • DISCOM: Distribution Company responsible for electricity distribution.
    • ALMM: Approved List of Models and Manufacturers for eligible solar modules.

    Challenges

    • Financial stress of DISCOMs
    • High upfront installation costs
    • Limited rooftop access for tenants and apartment residents
    • No battery-storage subsidy
    • Grid and transformer capacity constraints
    • Dependence on imported solar cells and wafers

    “[2025] Consider the following statements about ‘PM Surya Ghar Muft Bijli Yojana’:

    I. It targets installation of one crore solar rooftop panels in the residential sector.

    II. The Ministry of New and Renewable Energy aims to impart training on installation, operation, maintenance and repairs of solar rooftop systems at grassroot levels.

    III. It aims to create more than three lakhs skilled manpower through fresh skilling and up-skilling, under scheme component of capacity building.

    Which of the statements given above are correct?

    (a) I and II only

    (b) I and III only

    (c) II and III only

    (d) I, II and III.

  • How sustainable is India’s E20 push?

    Why in the news?

    The government has told Parliament that its ethanol blending programme has saved large sums of foreign exchange, while Opposition leaders have launched campaigns arguing that E20 harms vehicles and is being forced on people. The debate exposes a tension between the energy security and forex gains of blending 20 per cent ethanol into petrol and the costs it imposes on the country’s large legacy vehicle fleet and, potentially, on food security. The dispute now runs through disputed damage studies and feedstock diversion.

    What is E20?

    1. About: E20 is petrol blended with 20 per cent ethanol, meant to replace a fifth of transport petrol with domestically produced ethanol.
    2. Objective: The government targeted 10 to 11 billion litres of ethanol so that the money stays in the Indian economy rather than flowing out as a foreign exchange outgo on crude oil imports.

    What is ethanol and why does it affect engines?

    1. Polar solvent: Ethanol is a polar solvent that degrades older rubber compounds and plastics, hardening and cracking fuel hoses over time.
    2. Hygroscopic behaviour: Ethanol absorbs atmospheric moisture, and in parked vehicles the ethanol-water mixture separates and forms an acidic layer that corrodes tanks, damages fuel pumps, and clogs filters with sludge.

    What is the status of ethanol production?

    1. Capacity ramp-up: India’s distillery capacity now can produce some 18 to 20 billion litres from around 500 distilleries.
    2. Procurement contracted: For this ethanol year, which runs November to October, oil companies have contracted to procure some 10.5 billion litres of ethanol.
    3. Feedstock mix: Government figures show 45 per cent of ethanol for petrol blending will come from maize, Food Corporation of India (FCI) rice about 22 per cent, sugarcane juice 16 per cent, B-heavy molasses about 10 per cent, damaged foodgrains around 4.5 per cent, and C-heavy molasses 1.1 per cent.
    4. Maize expansion: India’s maize output grew 45 per cent in three years to 55 million tonnes in 2025-26, with more than 20 per cent of it going into ethanol.

    Will E20 spur corn imports from the United States?

    1. No import surge: There is no evidence of a surge in ethanol or maize imports in Ministry of Commerce statistics.
    2. Import ban: Direct ethanol import for petroleum blending is banned, even as the US corn lobby pushes India to increase corn imports.
    3. Sugar stocks stable: The closing stock of sugar was around 5 million tonnes and is expected to hold, indicating diversion to ethanol has not affected sugar availability.
    4. Conditional risk: In the event of monsoon failure, crop losses, and foodgrain shortages, diversion of FCI rice, sugarcane juice, and B-heavy molasses will come under stress. This raises the possibility of corn imports.

    Which vehicles are affected, and which are not?

    1. Newer fleet safe: Vehicles bought after April 2023, when the Bharat Stage 6 Phase 2 mandate took effect, were factory-engineered for E20 with ethanol-resistant elastomers, fluorinated fuel lines, upgraded pump seals, and recalibrated engine control units.
    2. Scale of newer fleet: These roughly 70 million vehicles are about 23 per cent of India’s active petrol fleet and face little cause for concern.
    3. Legacy fleet at risk: The remaining 77 per cent, nearly 240 million legacy two-wheelers and cars built for E5 or E10, are the genuine worry.

    Do the damage claims hold up? (the central tension)

    1. Consumer complaints: Consumer surveys by LocalCircles found 66 per cent of pre-2023 owners reporting mileage losses exceeding 10 per cent, and 55 per cent reporting increased maintenance.
    2. Institutional defence: IIT Kanpur’s Engine Research Laboratory maintains E20 causes no notable damage, with efficiency loss under 5 per cent, attributing most complaints to driving habits and traffic conditions.
    3. Field disputes: Independent mechanics and automotive communities dispute this, citing real-world fuel pump and injector failures traced to ethanol’s solvent and low-lubricity properties.
    4. Manufacturer data: The government told Parliament that one manufacturer serviced 2.84 crore vehicles in FY 2025-26, including about 1.5 crore legacy vehicles, without finding E20-linked engine damage, and reported an efficiency penalty of about 2 to 6 per cent in some E10-designed vehicles.

    Why has the rollout drawn criticism?

    1. Speed of transition: India reached the 10 per cent milestone in 2022 and ramped up to 20 per cent within three years, with very little information and advisories from manufacturers.
    2. Contrast with Brazil: Brazil’s transition to high ethanol levels happened over several decades in a stable manner, alongside vehicle modifications, taking the public into confidence.
    3. Information gap: The compressed rollout left legacy vehicle owners without clear guidance on effects and maintenance.

    Has ethanol blending eased the oil supply burden?

    1. Forex saving: The government said the programme has saved around 2 lakh crore rupees of foreign exchange and substituted some 32 million tonnes of crude oil imports.
    2. Import substitution: Substituting 10 billion litres of petrol with ethanol amounts to dispensing with about a month of crude imports.
    3. Price shielding claim: The government said that while crude prices rose 70 per cent during the war in West Asia, pump petrol prices rose only 7 to 8 per cent, though under-recoveries also increased.
    4. Cost ambiguity: Oil companies procure ethanol at around 70 rupees per litre, and with the base price of petrol at 55 to 60 per cent of the pump price, it is difficult to conclude independently that ethanol has kept prices down.

    Conclusion

    The central idea is that E20 delivers real forex and energy-security gains but shifts costs onto a legacy fleet of nearly 240 million vehicles whose damage claims remain contested between consumer surveys and institutional studies. What remains unresolved is a transparent, phased communication of effects and maintenance, and a food-security cushion if monsoon failure forces feedstock diversion. A Brazil-style stable transition would have taken the public into confidence.

    National Biofuel Policy: About

    1. About: The National Policy on Biofuels sets targets for blending ethanol in petrol and biodiesel in diesel to cut import dependence.
    2. Feedstock scope: It permits multiple feedstocks including sugarcane, damaged foodgrains, maize, and other surplus grains.
    3. Blending target: The policy advanced the 20 per cent ethanol blending target, which India pursued aggressively from 2022.

    Government Initiatives for Biofuels

    1. Ethanol Blended Petrol (EBP) Programme: Mandates blending of ethanol with petrol and drives procurement by oil companies.
    2. Pradhan Mantri JI-VAN Yojana: Supports second-generation ethanol from agricultural residues.
    3. SATAT initiative: Promotes compressed biogas as a transport fuel from waste and biomass.

    Key Facts about Ethanol Blending

    1. Ethanol year: Runs from November to October.
    2. Grades of molasses: B-heavy and C-heavy molasses are distinct sugar-industry by-products used as feedstock.
    3. BS6 Phase 2: Took effect in April 2023 and coincided with factory engineering of vehicles for E20.

    Challenges to the E20 push

    1. Legacy fleet damage: Corrosion, hose degradation, and pump failures in pre-2023 vehicles.
    2. Efficiency loss: Lower energy density reduces mileage, disputed in magnitude.
    3. Food-fuel conflict: Diversion of rice, maize, and sugar feedstock risks food security in a bad monsoon.
    4. Water intensity: Sugarcane and maize cultivation for ethanol strains groundwater.
    5. Consumer information deficit: Rapid rollout without adequate advisories.
    6. Cost transparency: Different tax and costing regimes obscure whether ethanol lowers pump prices.

    Way Forward

    1. Phased communication: Issue clear manufacturer advisories on effects and maintenance for legacy vehicles.
    2. Feedstock diversification: Expand second-generation ethanol from residues to reduce grain diversion.
    3. Food-security buffer: Build safeguards to pause grain diversion during monsoon failure.
    4. Independent testing: Commission transparent, independent studies on legacy-vehicle impacts.
    5. Consumer redress: Provide guidance and support for owners of affected pre-2023 vehicles.

    PYQ Relevance

    “[2020] According to India’s National Policy on Biofuels, which of the following can be used as raw materials for the production of biofuels?

    1. Cassava

    2. Damaged wheat grains

    3. Groundnut seeds

    4. Horse gram

    5. Rotten potatoes

    6. Sugar beet

    (a) 1, 2, 5 and 6 only

    (b) 1, 3, 4 and 6 only

    (c) 2, 3, 4 and 5 only

    (d) 1, 2, 3, 4, 5 and 6

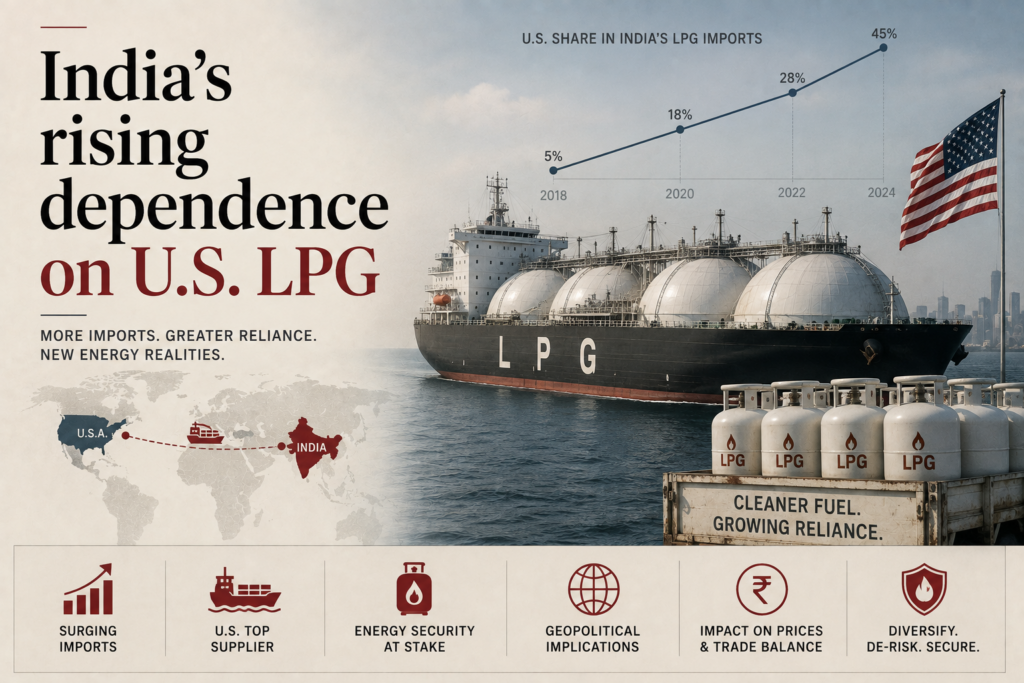
  • India’s rising dependence on U.S. LPG

    Why in the news?

    The Union Minister of Petroleum and Natural Gas stated that 67 per cent of India’s liquefied petroleum gas (LPG) now comes from the United States, a drastic shift from an earlier decision to source about 10 per cent of cooking gas there. The pivot, driven by the crisis in the Strait of Hormuz, exposes that LPG security cannot be anchored to a single geography while dependence on the United States carries risks of its own.

    What is Liquefied Petroleum Gas (LPG) and how is India’s supply structured?

    1. What it is: LPG is a mix of propane and butane used mainly as cooking gas in India. It is a politically volatile fuel because shortages carry direct social and political consequences.
    2. Import dependence: India, the world’s second largest importer of LPG, imports about 60 per cent of the LPG it consumes, with nearly 90 per cent of that passing through the Strait of Hormuz.
    3. Sourcing shift: State run refiners signed a long term deal for 2.2 million tonnes of United States LPG in 2026, raising the United States share to two thirds of imports.

    Why did India pivot to United States LPG?

    1. Hormuz disruption: Disruptions in the narrow Strait of Hormuz threatened the Gulf supply route through which most Indian LPG passes.
    2. Collapse in West Asian flows: India’s LPG imports from West Asia fell almost 85 per cent between February and June 2026.
    3. Partial offset: India replaced the lost flows by lifting imports from other sources, including the United States, from where June imports reached 0.77 million metric tonnes.
    4. Availability over price: Because cooking gas is politically sensitive, the priority is making it available rather than optimising cost, so costlier United States cargoes became attractive during the crisis.

    Why is overdependence on the United States risky?

    1. Energy as leverage: Relying more on a partner that views ties through the lens of national interest risks energy being used as a bargaining tool in bilateral trade talks.
    2. History of coercive tools: The United States has historically used financial sanctions, export controls, and technology denial as foreign policy tools, seen in Iran, Iraq, Cuba, North Korea, Syria, Russia, Venezuela, Myanmar, Libya, Sudan, and Afghanistan.
    3. Third country reach: The Lindsey O. Graham Sanctioning Russia and Iran Act of 2026, proposing tariffs of up to 100 per cent on the top five buyers of Russian oil and natural gas, is a non tariff trade barrier that can influence third country transactions.
    4. Monetary spillover: Import dependence complicates monetary policy, as elevated United States inflation could keep the Federal Reserve’s rates higher for longer, strengthening the dollar and raising the rupee cost of each cargo.

    Why does proximity pricing matter?

    1. Definition: Proximity pricing is a market benefit where goods cost less when bought from a nearby place. Shorter travel distance means lower shipping costs and faster delivery.
    2. Loss of distance advantage: United States shipments take 25 to 35 days against 5 to 10 days from the Gulf, so India loses the advantage of proximity pricing.
    3. Two price benchmarks: United States LPG is Mont Belvieu propane based, while West Asian supply follows the Saudi Aramco Contract Price, and the Gulf fuel is usually cheaper at the disembarking point due to the shorter distance.
    4. Temporary reversal: Geopolitical risk has temporarily inflated West Asian supply costs, with the Saudi Contract Price rising from about 543 dollars per tonne in February to around 790 dollars in June, making United States cargoes competitive despite the longer voyage.

    How does India balance availability with cost optimisation?

    1. The core trade off: For a politically volatile fuel, ensuring supply outweighs cost optimisation, so India accepted higher priced United States cargoes to cut supply risk.
    2. Residual exposure: India may have cut Hormuz risk, but remains exposed to commodity price, dollar, and freight risks.
    3. Under recovery pressure: If domestic prices are held down while global prices rise amid rupee depreciation, oil companies’ under recoveries expand, worsening fiscal and external sector stress.

    What are the challenges to India’s LPG security?

    1. Single supplier concentration: Two thirds reliance on one country recreates the concentration risk the pivot was meant to solve.
    2. Stagnant domestic output: LPG production has stayed nearly flat while consumption grows, widening the import gap.
    3. Chokepoint vulnerability: Heavy dependence on the Strait of Hormuz leaves Gulf sourced volumes exposed to any regional conflict.
    4. Fiscal drain: Accumulated under recoveries of state oil marketing companies exceeded Rs 59,000 crore as of 31 July 2026.
    5. Currency and freight risk: Dollar denominated pricing and long shipping routes expose landed costs to exchange rate and freight swings.
    6. Thin strategic reserves: India lacks large dedicated LPG strategic reserves to buffer sudden supply shocks.

    Conclusion

    Energy security is not about replacing one supplier with another but ensuring no single player holds all the cards. India must strengthen local production, bolster multiple supply chains, and build more strategic reserves. Australia offers a shorter Indo Pacific route outside Hormuz, though its export volumes remain small.

    Back2Basics

    Energy Security and LPG in India (Foundational Context)

    1. About: Energy security means assured availability of energy at affordable prices with resilience against supply shocks. LPG security is a subset covering cooking gas access for households.
    2. Scale: Public sector oil marketing companies serve 33.14 crore active domestic LPG customers, growing at a compound annual growth rate of 7.6 per cent between 2015 and 2026.
    3. Consumption gap: LPG production was 4.3 million metric tonnes against consumption of 6.5 million metric tonnes in the first quarter of FY27, with the 2026-27 consumption estimate at 34,692 thousand metric tonnes.

    Key Facts about India’s LPG Sector

    1. Oil marketing companies: Indian Oil, Bharat Petroleum, and Hindustan Petroleum are the three public sector oil marketing companies distributing LPG.
    2. PPAC: The Petroleum Planning and Analysis Cell tracks LPG consumption, customer base, and pricing data.
    3. Crisis production ramp up: At the peak of the crisis, oil marketing companies raised cumulative daily LPG production from 34,000 metric tonnes to 55,000 metric tonnes.
    4. Output jump: First quarter FY27 LPG production rose 35.73 per cent year on year to 4.26 million metric tonnes after refineries diverted propane and butane streams into the LPG pool.

    Government Initiatives for LPG and Energy Security

    1. Pradhan Mantri Ujjwala Yojana: Provides free LPG connections to women from below poverty line households to promote clean cooking.
    2. PAHAL (DBTL): Directly transfers LPG subsidy to beneficiary bank accounts to curb diversion.
    3. Strategic Petroleum Reserves: Underground crude storage to cushion supply disruptions.
    4. Ethanol Blending Programme: Reduces import dependence in the broader energy basket.
    5. Long term supply agreements: State refiner contracts diversifying LPG sourcing across geographies.

    Way Forward

    1. Boost domestic output: Maximise refinery LPG yield and invest in production capacity to narrow the import gap.
    2. Diversify suppliers: Spread sourcing across the Gulf, the United States, Australia, and others to avoid single supplier dependence.
    3. Expand strategic reserves: Build dedicated LPG storage to buffer sudden shocks.
    4. Hedge price and currency risk: Use financial instruments to manage commodity, dollar, and freight exposure.
    5. Secure alternate routes: Develop supply chains outside the Strait of Hormuz to reduce chokepoint vulnerability.

    PYQ Relevance

    [UPSC 2025] “Energy security constitutes the dominant kingpin of India’s foreign policy, and is linked with India’s overarching influence in Middle Eastern countries.” How would you integrate energy security with India’s foreign policy trajectories in the coming years?

    Linkage: The PYQ directly relates to energy security as a key driver of India’s foreign policy, especially in West Asia. India’s shift to US LPG highlights the need for supplier diversification, alternate routes and strategic autonomy in energy diplomacy.

  • For energy security, the way forward is not public or private, but both

    Why in the News

    India’s ethanol blending has reached 20%, ahead of the 2030 target. It has displaced 310 lakh tonnes of imported crude, saved over ₹1.90 lakh crore in foreign exchange and transferred over ₹1.6 lakh crore to farmers.

    What is the Ethanol Blended Petrol (EBP) Programme?

    • EBP: Ethanol Blended Petrol Programme blends ethanol, mainly produced from sugarcane and grains, with petrol.
    • E20: 20% ethanol blending has been achieved ahead of schedule.
    • Benefits: Reduces crude imports, supports farmers and lowers emissions.

    What are Strategic Petroleum Reserves (SPR)?

    • SPR: Strategic Petroleum Reserves are underground crude oil storage facilities used as an insurance against supply disruptions.
    • They provide a temporary buffer and must eventually be replenished.

    What has Ethanol Blending Achieved?

    • 20% blending achieved.
    • 310 lakh tonnes of crude imports displaced.
    • ₹1.90 lakh crore+ foreign exchange saved.
    • ₹1.6 lakh crore+ transferred to farmers.
    • 930 lakh tonnes+ CO₂ emissions avoided.

    Why Both Public and Private Players?

    • ONGC: Oil and Natural Gas Corporation, a major state-owned upstream producer.
    • OIL: Oil India Limited, another major state-owned upstream producer.
    • Public sector: Provides strategic control and supports national energy security.
    • Private sector: Brings capital, technology and efficiency into exploration, production and storage.
    • Balanced approach: India needs both strategic public capacity and competitive private participation.

    How Do Reserves and Domestic Production Complement Each Other?

    • SPR: Protects against sudden supply shocks.
    • Domestic production: Reduces imports over the life of an oil field.
    • Overseas stocks: Long-term suppliers could maintain crude stocks earmarked for India.
    • Exploration: Opening more offshore areas can expand domestic resources.

    Energy Security in India

    • Energy security means reliable and affordable energy supply with resilience against disruptions.
    • Four pillars:
      • Domestic production
      • Strategic reserves
      • Import diversification
      • Alternative fuels

      India’s high crude import dependence exposes it to global price shocks and disruptions in chokepoints such as the Strait of Hormuz and Bab el-Mandeb.

      Key Government Initiatives

      • EBP: Ethanol Blended Petrol Programme.
      • NBP: National Policy on Biofuels, 2018.
      • PM JI-VAN: Pradhan Mantri JI-VAN Yojana, promoting 2G (second-generation) ethanol from agricultural residues.
      • SATAT: Sustainable Alternative Towards Affordable Transportation, promoting compressed biogas.
      • SPR Programme: Strategic Petroleum Reserves Programme for crude oil security.

      [2025] Consider the following statements:

      Statement I: Of the two major ethanol producers in the world, i.e., Brazil and the United States of America, the former produces more ethanol than the latter.

      Statement II: Unlike in the United States of America, where corn is the principal feedstock for ethanol production, sugarcane is the principal feedstock for ethanol production in Brazil.

      Which one of the following is correct in respect of the above statements?

      (a) Both Statement I and Statement II are correct and Statement II is the correct explanation for Statement I

      (b) Both Statement I and Statement II are correct and Statement II is not the correct explanation for Statement I

      (c) Statement I is correct but Statement II is incorrect

      (d) Statement I is incorrect but Statement II is correct

    1. GEC third phase in final stages, up for Cabinet approval

      Why in the News?

      The government is in the final planning stages of the third phase of the intra-state Green Energy Corridor (GEC) and has sent the scheme to the Union Cabinet for approval. The phase carries an outlay of more than Rs 50,000 crore and targets the evacuation of about 135 gigawatts (GW) of renewable energy, marking a shift towards strengthening transmission from renewable-energy rich States.

      What is the Green Energy Corridor (GEC)?

      1. Renewable evacuation network: GEC is a scheme to build transmission infrastructure that carries electricity from renewable-energy rich areas to demand centres.
      2. Grid synchronisation: It links variable solar and wind generation with conventional power stations in the grid so that renewable power can be evacuated reliably from one location to another.

      What does GEC Phase III propose?

      1. Cabinet stage: The third phase has been sent to the Union Cabinet for final approval.
      2. Outlay: The scheme carries an outlay of more than Rs 50,000 crore.
      3. Evacuation target: The Ministry of New and Renewable Energy (MNRE) aims to evacuate about 135 GW of renewable energy in this phase.
      4. Focus area: The phase concentrates on augmenting intra-state transmission lines in renewable-energy rich States.

      Why have earlier phases faced delays?

      1. Right of way: Difficulty in securing right of way for transmission lines held up Phase I.
      2. Award delays: Delay in awarding project packages slowed progress.
      3. Forest clearances: Delays in forest clearances stalled work.
      4. Great Indian Bustard clearances: Clearances tied to the protection of the critically endangered Great Indian Bustard (GIB), whose habitat overlaps solar and wind zones in Rajasthan and Gujarat, delayed Phase I.
      5. State and regulatory issues: Non-participation of States during tendering, tender consultation and regulatory issues affected Phase II.

      Conclusion:

      GEC Phase III awaits Cabinet clearance and, if approved, will extend intra-state transmission capacity to evacuate about 135 GW of renewable power. With most Phase II packages already awarded and expected to complete within two years, the next milestone is Cabinet approval and the resolution of recurring right-of-way, forest and GIB clearance bottlenecks that have delayed earlier phases.

      Back2Basics: Green Energy Corridor (GEC) Scheme

      1. Ministry: Ministry of New and Renewable Energy.
      2. Objective: Build intra-state and inter-state transmission systems to evacuate renewable power.
      3. Structure: Implemented in phases, with intra-state components handled by State transmission utilities.
      4. Support: Funded through a mix of central grants, State contributions and multilateral loans.
      5. Beneficiaries: Renewable-energy rich States and the wider grid.

      About Renewable Energy Transmission in India

      1. Definition: Renewable energy transmission moves power generated from solar, wind and other renewable sources to consumption centres across States.
      2. Why it matters: Renewable generation is concentrated in a few resource-rich States, so evacuation infrastructure is essential to avoid stranded capacity.
      3. India’s standing: India is among the world’s largest renewable energy markets and has set large capacity addition targets for 2030.
      4. Structural feature: Variable renewable output requires grid balancing with conventional and storage capacity.

      Government Initiatives for Renewable Energy

      1. National Solar Mission: Promotes large-scale solar deployment under the National Action Plan on Climate Change.
      2. PM-KUSUM: Supports solar pumps and grid-connected solar for farmers.
      3. PM Surya Ghar: Muft Bijli Yojana: Promotes rooftop solar for households.
      4. Production Linked Incentive for solar modules: Builds domestic solar manufacturing capacity.
      5. Green Hydrogen Mission: Promotes production of green hydrogen using renewable power.

      Key Facts about India’s Renewable Energy Sector

      1. 2030 target: India aims for 500 GW of non-fossil fuel electricity capacity by 2030.
      2. Nodal ministry: Ministry of New and Renewable Energy.
      3. Grid operator: Grid Controller of India manages national load dispatch.
      4. Species overlap: The Great Indian Bustard is a critically endangered species whose habitat intersects renewable zones, driving clearance conditions.

      Challenges in Renewable Energy Transmission

      1. Land and right of way: Acquiring land and corridors for transmission lines is slow and contested.
      2. Clearance delays: Forest and wildlife clearances, including GIB-related conditions, hold up projects.
      3. State coordination: Uneven State participation in tendering and implementation delays intra-state work.
      4. Grid integration: Variable renewable output strains grid stability without adequate balancing.
      5. Financing and viability: Distribution company finances and cost recovery remain weak.
      6. Storage gap: Limited storage capacity constrains round-the-clock renewable supply.

      Way Forward

      1. Fast-track clearances: Streamline forest and wildlife clearances with mitigation for GIB habitat, including undergrounding of lines where feasible.
      2. Strengthen State participation: Improve incentives and coordination for State utilities in tendering.
      3. Expand storage: Scale up battery and pumped-hydro storage alongside transmission.
      4. Timely awards: Reduce delays in awarding and executing project packages.
      5. Grid modernisation: Invest in smart grids and forecasting to manage variable generation.

      PYQ Relevance

      [UPSC 2022] Do you think India will meet 50 percent of its energy needs from renewable energy by 2030? Justify your answer. How will the shift of subsidies from fossil fuels to renewables help achieve the above objective? Explain.

      Linkage: The PYQ examines India’s transition towards renewable energy and the challenges in achieving its 2030 targets. GEC Phase III strengthens renewable energy evacuation and grid infrastructure.
      This supports India’s 2030 renewable-energy targets.

    2. Gujarat port concessions near expiry, reopening the BOOT debate

      Why in the News

      Concessions for Gujarat’s Pipavav and Mundra ports near expiry, reopening the debate on the Build-Own-Operate-Transfer (BOOT) model and how India structures private port infrastructure.

      What is the BOOT model?

      1. Definition: Under Build-Own-Operate-Transfer (BOOT), a private operator finances, builds, and runs an asset for a fixed concession period, then transfers it back to the public authority.
      2. Application: Gujarat’s 1997 BOOT framework let private players develop ports like Mundra and Pipavav on state maritime board land.

      What is at stake as concessions expire?

      1. Asset transfer terms: Expiry forces a decision on renewal, renegotiation, or transfer of high-value operating ports.
      2. Investment signal: The treatment of expiring concessions shapes confidence for greenfield private ports such as Vizhinjam and Dhamra.
      3. Federal split: Major ports fall under the Centre while non-major ports like Gujarat’s fall under state maritime boards, complicating policy.

      “[2026] Consider the following statements with reference to the Sagarmala Programme of the Government of India :
      I. The Sagarmala Programme seeks to achieve port-led economic growth through cost-effective and sustainable coastal infrastructure.
      II. The success of the Sagarmala Programme is reflected in significant growth in coastal and inland waterway shipping, along with improved global port rankings.
      III. Sagarmala 2.0 aims to position India as global maritime innovation hub aligned with Atmanirbhar Bharat and Viksit Bharat 2047 visions.
      Which of the following relationships among the above statements is/are correct?
      1. Statement II validates the effectiveness of the strategies envisioned in statement I.
      2. Statement III extends the objectives of statement I by embedding them into a future-oriented innovation framework.
      3. Statement I contradicts statement III by focusing only on traditional infrastructure instead of modern innovation.
      Select the answer using the code given below:

      [A] 1 only

      [B] 1 and 2

      [C] 2 and 3

      [D] 3 only