Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Search results for: “”

  • Building an Atmanirbhar Philanthropy Ecosystem

    Why in the News

    Domestic private philanthropy in India, at over Rs 1.18 lakh crore a year, now exceeds foreign philanthropic inflows more than fivefold, even as FCRA compliance tightening disrupted a subset of NGOs. This reframes the FCRA debate from a dispute over foreign funding into a question of how to build a self reliant domestic philanthropy ecosystem.

    Has tighter FCRA regulation actually starved Indian civil society of foreign funds?

    1. Sovereign right: Every nation has the right and responsibility to regulate foreign capital flowing into organisations shaping public life; this is not unique to India nor illiberal.
    2. Reframed question: The real debate is not whether foreign funding should be regulated but whether regulation is proportionate, predictable and efficiently administered.
    3. Scale check: NITI Aayog’s NGO Darpan portal lists roughly six lakh voluntary organisations, of which only about 14,500 hold active FCRA registration.
    4. Inflows unshrunk: Foreign contributions have doubled over the decade, from about Rs 10,000 crore to around Rs 22,000 crore, showing the sector has not been starved of foreign money.

    Is FCRA’s problem the law itself or how it is administered?

    1. Real but narrow hardship: A small number of organisations faced delayed renewals, long processing times, or cancelled registrations, disrupting education, health, livelihood and rural development work. This is not true of the sector as a whole but is real for those affected.
    2. Uneven governance exposed: Many NGOs operate with exemplary governance while others had gone dormant or lacked documentation matching rising compliance expectations.
    3. Corporate parallel: Indian companies underwent a similar governance reckoning over three decades, where stronger governance initially felt like a burden before it became what won investor confidence.
    4. Proposed reform: A structured compliance path, deficiency notices, defined correction windows, clarification opportunities, and an independent appellate body would protect legal integrity while sparing genuine organisations avoidable disruption.
    5. FCRA 2.0: The newly launched FCRA 2.0 platform is framed as an opportunity to simplify compliance and move toward risk based supervision.

    What do international comparators show about regulating foreign funds and incentivising domestic giving?

    1. Regulatory comparators (limited detail): The US requires disclosure under its Foreign Agents Registration Act, and Australia and several European democracies run comparable disclosure regimes, though specific design features are not detailed.
    2. Singapore: Offers a 250% tax deduction for qualifying donations, a far larger incentive multiple than India’s.
    3. United Kingdom: Uses a Gift Aid top up mechanism, where the tax authority adds an amount to the donation based on the donor’s tax paid.
    4. United States: Allows carry forward provisions, letting donors carry unused deduction limits into future tax years.
    5. India’s proposed calibration: Raising the 80G deduction from 50% to 100% and lifting the income ceiling from 10% to 25% would signal similar intent without wholesale copying these regimes.

    Why has domestic giving overtaken foreign inflows as the sector’s main resource?

    1. Scale: Domestic private philanthropy now exceeds Rs 1.18 lakh crore a year, more than five times foreign inflows, per the Bain Dasra India Philanthropy Report 2026.
    2. Family philanthropy: Growing at double digit rates as a new generation of wealth creators treats giving as part of wealth stewardship.
    3. CSR channel: Corporate Social Responsibility now channels over Rs 40,000 crore a year into development, the second of three phases in India’s philanthropic evolution, after foreign reliance and before individual and family giving.
    4. Retail infrastructure: India’s over 220 million demat accounts, widespread SIP investing, and UPI penetration provide ready made rails for mass small ticket giving.

    What specific mechanisms could unlock India’s untapped domestic giving?

    1. HNI gap: High net worth individuals’ giving has lagged well behind their wealth growth, marking them as the largest pool of new domestic capital obtainable through policy.
    2. Tax deduction reform: Raising the 80G deduction to 100% and the ceiling to 25% of adjusted gross total income would cost the exchequer little while improving long term social capital flows.
    3. Equity donation route: A framework for donating appreciated listed shares to eligible charities, with a one to three year disposal window, could unlock wealth held in equity rather than cash.
    4. Mass small ticket giving: If even a fraction of households gave Rs 100 to Rs 1,000 a month through trusted digital platforms, millions of citizens could become active philanthropic partners.
    5. Social Stock Exchange: Proposed as a trusted national platform linking credible organisations to ordinary citizens through disclosure and measurable impact.

    Conclusion:

    Domestic philanthropy, not foreign funding, is now the dominant resource for India’s social sector, making the FCRA debate less about restricting inflows and more about building an accountable domestic ecosystem. What remains unresolved is calibrating regulation so genuine organisations are not treated like fraud cases, and converting proposed tax and market incentives, the 80G reform, the equity donation route, and the Social Stock Exchange, into actual growth in domestic giving. Foreign philanthropy is expected to keep mattering for research and innovation, but the goal is for it to complement rather than shape India’s social development.
  • Is Yashwant Varma still a judge?

    Why in the News?

    Parliament is set to take up, in the Monsoon Session, the report of the Judges (Inquiry) Act committee that investigated misbehaviour charges against former judge Yashwant Varma, who resigned in April 2026 after burnt currency notes were found at his residence. Three months later, he is still listed as a sitting judge by the Allahabad High Court and the Union Department of Justice, exposing a gap between judicial independence and judicial accountability.

    Why does the Constitution let judges resign without anyone’s acceptance?

    1. Resign at will power: Thirteen constitutional functionaries, including Supreme Court and High Court judges, may resign merely by writing to the specified authority, with no acceptance required.
    2. Contrast with legislators: Article 101(3)(b) and Article 190(3)(b) make resignation of MPs and MLAs subject to acceptance by the Speaker or Chairman, unlike judges.
    3. Judicial precedent: A five judge Constitution Bench in Union of India vs Gopal Chandra Misra (1978) unanimously held that a judge’s resignation takes effect ex proprio vigore, automatically, without needing acceptance.
    4. Purpose: The power shields judges from being coerced to continue in office, protecting judicial independence.
    5. Track record: At least 12 High Court judges have resigned since 2017, and one Supreme Court judge, Justice Dalveer Bhandari, resigned in 2012; these resignations were reportedly handled in compliance with the law.

    Is Varma still officially a judge on paper?

    1. Legal status: Varma ceased to be a judge on April 9, 2026, making any later listing of him as a sitting judge incorrect.
    2. Administrative lapse: The Allahabad High Court and the Department of Justice have continued to list him as a sitting judge for over three months.
    3. Bar record: His status at the Bar was reportedly changed to “active” and some dues and benefits as a sitting judge have reportedly stopped, showing the system elsewhere treats him as having exited office.
    4. Correction needed: It would be illegal for him to draw any salary or benefit as a sitting judge, and his name should be deleted from official lists.

    Does judicial accountability survive when the judge quits before removal?

    1. Statutory duty: The report concerns Varma’s conduct before resignation, so it must still be laid before both Houses and made public under the Judges (Inquiry) Act, 1968.
    2. Public interest: Citizens have a legitimate right to know whether the committee found proven misbehaviour against a judge of a constitutional court.
    3. If exonerated: If the report finds no misbehaviour, the matter ends there.
    4. If found guilty: The removal motion can no longer be moved because Varma no longer holds the office he would be removed from.
    5. Procedural gap: Under Section 6, the report is to be discussed together with the removal motion; since the motion lapses, the report itself cannot be discussed by Parliament under the Act.

    Can the resignation loophole be closed without amending the Constitution?

    1. Nature of the gap: Judges may resign at will before Parliament even takes up the removal motion, halting the entire accountability process.
    2. Preferred fix: The loophole should be closed through constitutional amendment, not executive or judicial reinterpretation.
    3. Design of fix: The amendment could make a judge’s resignation subject to acceptance during the pendency of removal proceedings.
    4. Who accepts: To protect judicial independence, that acceptance power should vest in the Chief Justice of India, not the President.
    5. Separate remedy for debate: If Parliament wants to discuss the report despite resignation, the 1968 Act itself would need to be amended to enable this.
    6. Rule of law caution: Interpreting constitutional or statutory silences to suit Parliament’s or the executive’s convenience would be against the rule of law.

    Conclusion:

    The resign at will power, designed to protect judicial independence, can be exploited to halt removal proceedings once they are underway, leaving accountability incomplete even when misconduct is established. Varma’s continued listing as a sitting judge is a correctable administrative error, but the deeper gap is structural: the Inquiry Committee report must still be tabled even though the removal motion has lapsed. Closing this requires a constitutional amendment vesting the CJI, not the President, with the power to accept a judge’s resignation while removal proceedings are pending

  • [21st July 2026] The Hindu OpED: Canada-India Defence Collaboration for a secure future 

    PYQ Relevance[UPSC 2015] What is the significance of Indo-US defence deals over Indo-Russian defence deals? Discuss with reference to stability in the Indo-Pacific region.
    Linkage: It examines India balancing defence partnerships amid strategic diversification. It has the same underlying theme of India diversifying defence-partner dependence, now with Canada as the partner in question.

    Mentor’s Comment

    Canada has committed to raising defence spending to 5% of GDP by 2035 and has since taken concrete steps to deepen defence cooperation with India, including a bilateral Defence Dialogue and a Critical Minerals Value Chain MoU signed in early 2026. The push is framed as a natural convergence of interests, but the stated driver is Canada’s own need to end reliance on a single supply-chain partner, raising the question of whether India is being positioned as a diversification option rather than an equal strategic partner.

    Why is Canada scaling up defence engagement with India at this specific moment?

    1. Rearmament trigger: Prime Minister Carney announced an ambitious plan to rebuild, rearm, and reinvest in the Canadian Armed Forces six weeks after his government was formed. He cited the rapidly evolving nature of war driven by drones, autonomous systems, and orbital weapons.
    2. Spending trajectory: Canada committed in 2025 to spend 5% of GDP on defence by 2035, and had already surpassed 2% of GDP by March 2026.This placed it among the ten largest economies in the world by defence spend.
    3. Rupture narrative: Prime Minister Mark Carney invoked his own January 2026 Davos speech describing a “rupture in the world order,” paired with Prime Minister Narendra Modi’s description of the present period as a “decade of crisis,” to frame urgency for new partnerships.
    4. Supply-chain motive stated directly: Canada launched a Defence Industrial Strategy explicitly so that it “does not rely on just one country” for defence supply chains, identifying the structural reason India is being courted now.

    What concrete institutional mechanisms anchor the bilateral defence relationship?

    1. Defence Advisers: Canada and India have accredited Defence Advisers in both Ottawa and Delhi.
    2. Defence Dialogue: Prime Ministers of both the countries have agreed to establish a Defence Dialogue to prioritise cooperation on shared interests and align capacities.
    3. Joint military exercises: Canadian and Indian navies have participated together in the Rim of the Pacific (RIMPAC) exercises and Talisman Sabre exercises.
    4. Institutional exchange: A delegation from India’s National Defence College visited Canada in June 2026, opening direct exchanges between Indian officers and Canadian military colleges and bases.
    5. Procurement reform: Canada established a national Defence Investment Agency to streamline military procurement and called on India to participate in co-development, subsystem manufacturing, and sustainment.
    6. Innovation investment: Canada is investing over half a billion dollars in next-generation aerospace technologies, including a drone innovation hub.

    What specific technology complementarities does Canada claim with India?

    1. Aerospace scale-matching: Canada is one of only a few countries with a full-spectrum aerospace sector; India’s domestic aviation industry is the third largest domestic market in the world.
    2. R&D versus manufacturing framing: Canada is positioned as a research and development powerhouse, while India is framed as focused on advancing innovation capacity and high-end manufacturing.
    3. Space capability convergence: Canada and India are described as part of a small group of countries with advanced space capabilities, with civilian space cooperation highlighted in a joint statement between the two Prime Ministers.
    4. Satellite and robotics complementarity: Canada’s strengths in advanced components for satellite technology and space robotics are claimed to complement India’s strengths in low-cost platforms.
    5. RADARSAT-naval link: Canada’s RADARSAT satellite constellation is presented as having application in advancing India’s naval capacity in the region, tying space technology directly to maritime security goals.

    Why have critical minerals become central to this defence partnership?

    1. Strategic framing: Critical minerals are described as the building block of defence technologies, positioned as a distinct area for partnership expansion beyond conventional defence hardware.
    2. West Asia linkage: The crisis in West Asia is cited as evidence that national security and economic security are now inextricably linked, used to justify treating minerals supply as a security issue.
    3. Canada’s reserve base: Canada holds geological reserves of 31 critical minerals ranging from cobalt to helium, the tenth largest reserves of rare earth elements, the third largest recoverable uranium resources, and 5% of the world’s tungsten reserves.
    4. Uranium production position: Canada is the second largest producer and exporter of uranium globally, accounting for 24% of global production in 2024.
    5. MoU as delivery mechanism: A Canada-India memorandum of understanding on the Critical Minerals Value Chain, signed during Carney’s February-March 2026 visit to India, is presented as the groundwork for integrating stable, resilient supply chains between the two countries.

    Does this reflect mutual strategic need, or Canada’s own diversification imperative framed as partnership?

    1. Diversification motive named only for Canada: The Defence Industrial Strategy’s stated purpose is that Canada does not rely on just one country. No equivalent single-partner dependence is named on India’s side.
    2. Asymmetric evidentiary weight: Canada’s motivations are backed by specific figures on GDP spend, mineral reserves, and production shares. India’s strategic rationale for the partnership is asserted through general phrases such as “reliable partners” and “national security goals,” without matching specificity.
    3. Complementarity asserted, not demonstrated: Claims that Canadian R&D strength complements Indian manufacturing scale, or that Canadian satellite components complement Indian low-cost platforms, are stated as fact without supporting data or named joint projects beyond the MoU and joint statement references.

    Conclusion

    Canada and India are natural defence partners bound by complementary strengths in technology, space, and critical minerals. But this points to a narrower reality: Canada’s own rearmament plan and its explicit strategy to end reliance on a single supply-chain partner are the primary drivers, with India positioned as a diversification option. What remains unaddressed is any comparably specific account of India’s independent strategic calculus in deepening this relationship, beyond general references to reliability and national security goals.

  • Why Inflation Is Rising in India

    Why in the News?

    India’s Wholesale Price Index (WPI) inflation climbed to 9.87% by June 2026, after staying negative or near zero for over a year. This reverses more than a decade of relatively low inflation. It appears, on the surface, to confirm the common belief that rising prices signal demand outpacing supply.

    Why has India’s WPI inflation surged sharply, and why does simple demand overheating not explain it?

    1. Wholesale Price Index (WPI): an index tracking price changes of goods at the wholesale stage, split into three sub-categories, primary articles, fuel and power, and manufactured products.
    2. Sharp reversal: WPI inflation stayed negative or close to zero until December 2025, then climbed sharply from March 2026 onward, reaching 9.87% by June 2026.
    3. Popular assumption: Conventional economic intuition treats rising prices as a sign of demand outpacing supply (overheating), and falling prices as the reverse.
    4. Composition of the jump: Fuel and power, and manufactured products, not primary articles, accounted for the dominant share of the WPI rise in the months leading up to June 2026.

    Why do primary commodity prices and manufactured goods prices respond differently to demand and supply?

    1. Kaleckian distinction: Economist Michal Kalecki argued that primary commodity prices are demand-determined, while industrial and manufactured prices are cost-determined.
    2. Primary commodities: Supply is largely fixed in the short run, shown as a vertical supply curve. A supply shock, such as a bad monsoon, shifts this curve and directly raises prices. This is demand-pull inflation.
    3. Manufactured goods: Firms typically operate below full capacity, so the supply curve is flat. A rise in demand is met by higher production, not higher prices.
    4. Markup pricing: Manufactured goods prices are set as a cost markup over production cost. Prices rise only when input costs rise, making this cost-push inflation rather than demand-pull inflation.

    What specifically pushed up food and manufactured goods prices in India’s current surge?

    1. Fuel and power drove manufactured inflation: Fuel and power prices moved almost one-to-one with manufactured goods inflation, confirming a cost-push channel.
    2. Wages ruled out as a driver: Indian workers largely lack bargaining power over wages, so wage costs are not treated as the factor pushing up manufactured prices.
    3. Monsoon failure drove food inflation: An inadequate monsoon, linked to the El Niño effect, hurt agricultural production and pushed up food prices through 2026.
    4. Historical pattern confirmed: Data spanning 1953-54 to 2025-26 show drought years consistently coinciding with sharp spikes in food article inflation, supporting the Kaleckian structuralist explanation.
    5. Not an absolute rule: Food inflation has also occurred in some non-drought years, suggesting demand-side pressure can independently raise food prices. A drought is a sufficient but not a necessary condition for food prices to soar.

    Is India’s current inflation surge purely an external shock, or has government policy made it worse?

    1. A tool that worked: The government previously held domestic pump prices steady despite rising global crude oil prices by cutting customs and excise duties on fuel.
    2. Tool withdrawn: This countercyclical duty-cut measure has since been withdrawn.
    3. Self-inflicted component: The withdrawal is identified as one of the primary reasons for the sharp rise in WPI inflation, turning part of what looks like an external oil-price shock into a domestic policy choice.
    4. Framework critique: The existing inflation-targeting framework is described as ill-suited to managing fuel-driven, cost-push inflation, since it is built to respond to demand-side pressure rather than cost-side pressure.

    What structural policy changes are proposed to control inflation going forward?

    1. Decouple food supply from the monsoon: Heavy investment in irrigation infrastructure is proposed to reduce agriculture’s dependence on rainfall, since continued dependence on the monsoon is called unscientific and anachronistic in the present technological era.
    2. Countercyclical indirect tax policy for fuel: Customs and excise duties on fuel should be systematically lowered when global crude prices rise and restored when prices fall, rather than applied inconsistently.
    3. Move beyond inflation targeting for cost-push inflation: A rule-based countercyclical duty policy is presented as a more effective response to oil-driven, cost-push inflation than the existing inflation-targeting framework, which is tuned to demand-side price pressure.

    Conclusion

    India’s WPI inflation surge is a cost-push and supply-shock phenomenon, not demand overheating. Food prices rose due to an inadequate monsoon, and manufactured goods inflation tracked global fuel costs almost one-to-one. The government’s withdrawal of a countercyclical duty-cut measure on fuel is identified as one of the primary reasons for the sharp WPI rise. This makes part of the current inflation surge a self-inflicted policy outcome rather than a purely external shock. Going forward, food security needs to be decoupled from monsoon dependence through irrigation investment. Also, fuel-price shocks need to be cushioned through a rule-based countercyclical indirect tax policy rather than the existing inflation-targeting approach.

    PYQ Relevance

    [UPSC 2024] What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.

    Linkage: The PYQ asks for the causes of persistent food inflation in India and evaluates whether RBI monetary policy is effective in controlling it. The article gives a structural, non-monetary explanation for food inflation (monsoon-driven supply shocks) and manufactured inflation (fuel cost pass-through). It argues that both are cost-push phenomena rather than demand/monetary phenomena. 

  • India’s Green Transition Is Missing Long-Duration Energy Storage

    Why in the News?

    India recorded its highest-ever electricity peak demand of 270.8 GW on May 21, exposing gaps in the country’s storage architecture during periods of low renewable generation. This has sharpened focus on long-duration energy storage (LDES), a category entirely absent from India’s current national storage planning framework despite its technologies and resource potential already existing.

    Why did India’s existing storage roadmap prove inadequate against actual demand patterns?

    1. Record peak demand: India recorded its highest-ever peak electricity demand of 270.8 GW on May 21. This is an increase of approximately 90 GW over the same period in 2019.
    2. Dual demand peaks: Power generators typically meet India’s summer daytime peak. Demand rises again at night, driven largely by air conditioner use, precisely when solar generation is unavailable.
    3. Roadmap’s duration ceiling: The 2026 Long-Term National Resource Adequacy Plan envisages 80 GW of battery energy storage and 94 GW of Pumped Hydroelectric Energy Storage (PHES) by FY2035-36. These translate to average discharge durations of roughly 4 hours and 6 hours, respectively.
    4. Adverse-weather gap: Four-to-six-hour storage can manage routine daily demand swings. It cannot sustain the grid through prolonged low-generation events such as heatwaves.

    What technologies make up India’s Long-Duration Energy Storage (LDES) landscape, and how do they compare?

    1. Definition: LDES refers to technologies that store energy and discharge it as power or thermal energy over extended periods, ranging from 8 hours to days, weeks, or seasons.
    2. Functional distinction: Short-duration storage systems discharge for under 8 hours and smooth intra-day demand fluctuations. LDES instead balances supply and demand over prolonged periods, eases grid congestion, and adds resilience.
    3. Pumped Hydroelectric Energy Storage (PHES): PHES remains the technology benchmark. It has mature infrastructure and an energy efficiency of 70-80%.
    4. Compressed-Air Energy Storage (CAES): CAES has a similar level of market readiness to PHES. Its efficiency is slightly lower, at 40-70%.
    5. Thermal and hydrogen storage: Thermal storage offers the longest discharge duration among developed technologies, around 200 hours, with 55-90% efficiency. Hydrogen-based storage can discharge for up to 1,000 hours but remains inefficient.
    6. Vanadium flow batteries and emerging tech: Vanadium flow batteries are commercially ready, come in different sizes, and deliver 80-85% efficiency across 10-24 hour durations. Iron-air batteries are an emerging technology still under development.

    Why do cost and site constraints limit LDES deployment despite its technical readiness?

    1. Duration-cost relationship: Longer discharge duration improves a technology’s economics. Storing more energy simultaneously raises total costs, making short-duration systems uncompetitive beyond six hours of discharge.
    2. Cheapest options: PHES and CAES are currently the most cost-effective and commercially viable LDES technologies, at $0.12/kWh and $0.10/kWh respectively, per a Pacific Northwest National Laboratory study.
    3. Site dependency of PHES: PHES needs two water reservoirs at different heights, adequate land, and sufficient height difference for water to generate force when released.
    4. Site dependency of CAES: CAES needs large underground spaces, such as salt caverns or depleted gas fields, that can safely hold high-pressure air without leaking.
    5. Site-flexible alternatives: Where such geological or land conditions are unavailable, hydrogen, thermal storage, or vanadium flow batteries are more suitable, since they depend less on specific land, water, or subterranean conditions.

    What do international institutional and regulatory models demonstrate about accelerating LDES investment?

    1. LDES Council (international industry body): This body brings together industry leaders, technology developers, investors, and policymakers to accelerate LDES innovation and commercialisation. It projects a significant decline in LDES costs by 2030.
    2. United States-Pacific Northwest National Laboratory: This research body, under the U.S. Department of Energy, benchmarked PHES and CAES as the most cost-effective LDES technologies at present.
    3. California-Public Utilities Commission: California’s primary utility regulator has set an LDES procurement target of 2 GW, to be deployed between 2031 and 2037.
    4. United Kingdom- investor revenue guarantee: The U.K. has launched a financial framework guaranteeing LDES projects a minimum revenue even in poor market conditions, to unlock investment and accelerate deployment.

    Where does India currently stand on LDES resource potential and deployment?

    1. PHES potential: A 2026 Central Electricity Authority report placed India’s PHES potential at about 267 GW.
    2. Planned PHES capacity: India plans to install PHES projects with an aggregate capacity of 100.8 GW by 2035-36. Of this, 11.6 GW is currently under construction.
    3. CO2 battery pilot: In early 2025, India launched a 160-MWh carbon dioxide battery storage system at NTPC Kudgi, Karnataka. It cycles carbon dioxide between liquid and gas phases and has an operational life exceeding 25 years.
    4. Vanadium flow pilot: India inaugurated its first MWh-scale vanadium redox flow battery system, a 3-MWh facility at NTPC Greater Noida.

    Why does India’s national storage planning still not recognise LDES as a category?

    1. Resource Adequacy Plan silence: The Long-Term National Resource Adequacy Plan acknowledges the general role of energy storage in grid reliability. It does not specifically recognise the need for LDES.
    2. National Electricity Plan silence: The National Electricity Plan projects capacities for battery energy storage systems and PHES. It provides no technology-specific assessments or deployment pathways for LDES.
    3. Capability-recognition gap: India already has a 267 GW PHES resource base and functioning LDES pilot projects. National planning documents do not treat LDES as a distinct storage category requiring its own targets or provisions.

    What policy and institutional measures would close India’s LDES planning gap?

    1. Framework integration: LDES should be incorporated into the Ministry of Power’s National Framework for Promoting Energy Storage Systems, with guidelines on its deployment and grid integration.
    2. Technology-specific planning: Future planning exercises should estimate LDES requirements and identify technologies suited to India’s extreme weather and geography, rather than treating storage as a single undifferentiated category.
    3. Clearances and regulatory classification: Faster environmental and land clearances, transmission alignment, and clear regulatory classification of LDES technologies are needed to unlock investment.
    4. Technology-agnostic incentives: The incentive structure, including subsidies and viability-gap funding, must be technology-agnostic and incentivise co-location with data centres. As the market matures, the focus must shift to long-term revenue contracts, tariff structures, and procurement frameworks.
    5. Capacity building: Dispatch centres need staff trained in optimal dispatch, multi-day charge-discharge decisions, and state-of-charge management across seasons, supported by clear protocols for LDES.

    Conclusion

    India’s storage roadmap treats energy storage as a short-duration, hourly balancing problem, while a renewables-heavy grid increasingly requires multi-day resilience. LDES technologies and resource potential already exist in India; what is missing is formal policy recognition, technology-specific planning, and an incentive architecture built around them. Unless LDES is written into national storage planning documents, India’s clean energy transition will remain dependent on favourable weather and market conditions rather than assured grid reliability.

  • White Gold: India’s Cotton Story

    Why in News?

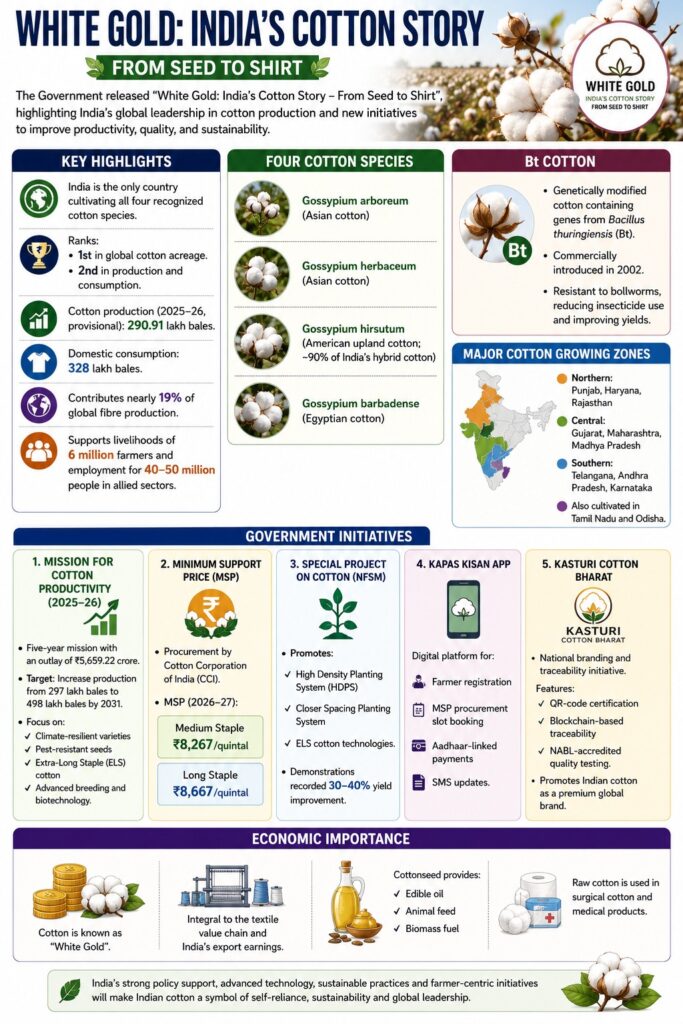
    The Government released “White Gold: India’s Cotton Story – From Seed to Shirt”, highlighting India’s global leadership in cotton production and new initiatives to improve productivity, quality, and sustainability.

    Key Highlights

    • India is the only country cultivating all four recognized cotton species.
    • Ranks: 1st in global cotton acreage. 2nd in production and consumption.
    • Cotton production (2025–26, provisional): 290.91 lakh bales.
    • Domestic consumption: 328 lakh bales.
    • Contributes nearly 19% of global fibre production.
    • Supports livelihoods of 6 million farmers and employment for 40–50 million people in allied sectors.

    Four Cotton Species

    • Gossypium arboreum (Asian cotton)
    • Gossypium herbaceum (Asian cotton)
    • Gossypium hirsutum (American upland cotton; ~90% of India’s hybrid cotton)
    • Gossypium barbadense (Egyptian cotton)

    Bt Cotton

    • Genetically modified cotton containing genes from Bacillus thuringiensis (Bt).
    • Commercially introduced in 2002.
    • Resistant to bollworms, reducing insecticide use and improving yields.

    Major Cotton Growing Zones

    • Northern: Punjab, Haryana, Rajasthan
    • Central: Gujarat, Maharashtra, Madhya Pradesh
    • Southern: Telangana, Andhra Pradesh, Karnataka
    • Also cultivated in Tamil Nadu and Odisha.

    Government Initiatives

    Mission for Cotton Productivity (2025–26)

    • Five-year mission with an outlay of ₹5,659.22 crore.
    • Target: Increase production from 297 lakh bales to 498 lakh bales by 2031.
    • Focus on: Climate-resilient varieties, Pest-resistant seeds, Extra-Long Staple (ELS) cotton, and Advanced breeding and biotechnology.

    Minimum Support Price (MSP)

    • Procurement by Cotton Corporation of India (CCI).
    • MSP (2026–27): Medium Staple: ₹8,267/quintal and Long Staple: ₹8,667/quintal

    Special Project on Cotton (NFSM)

    • Promotes: High Density Planting System (HDPS), Closer Spacing Planting System, and ELS cotton technologies.
    • Demonstrations recorded 30–40% yield improvement.

    Kapas Kisan App

    • Digital platform for Farmer registration, MSP procurement slot booking, Aadhaar-linked payments, and SMS updates.

    Kasturi Cotton Bharat

    • National branding and traceability initiative.
    • Features: QR-code certification, Blockchain-based traceability, and NABL-accredited quality testing.
    • Promotes Indian cotton as a premium global brand.

    Economic Importance

    • Cotton is known as “White Gold”.
    • Integral to the textile value chain and India’s export earnings.
    • Cottonseed provides: Edible oil, Animal feed, Biomass fuel, and Surgical cotton and medical products.

    [2020] “The crop is subtropical in nature. A hard frost is injurious to it. It requires at least 210 frost-free days and 50 to 100 centimeters of rainfall for its growth. A light well-drained soil capable of retaining moisture is ideally suited for the cultivation of the crop.” Which one of the following is that crop?

    a) Cotton
    b) Jute
    c) Sugarcane
    d) Tea

  • Core Industries Index (ICI) Revised Series

    Why in News?

    The Index of Core Industries (ICI) grew by 5% in June 2026, the highest growth in the last five months. The government also released a new ICI series with base year 2022–23, replacing the 2011–12 series.

    Key Highlights

    • Growth: ICI increased by 5% (YoY) in June 2026, up from 3.2% in May 2026.
    • Base Year Revised: Updated from 2011–12 to 2022–23.
    • Coverage Expanded: Iron ore has been added as the 9th core industry.
    • Methodology Updated: Sectoral weights and estimation methods have been revised.
    • Fastest Growing Sector: Iron ore (43.9% growth), largely due to a low statistical base.
    • Other sectors recording positive growth: Electricity: 9.8%, Cement: 9.8%, Steel: 4.6%, Coal: 1.4%
    • Sectors recording contraction: Crude Oil: –4.2%, Natural Gas: –7.4%, Refinery Products: –4.7%, Fertilisers: –3.3%

    About the Index of Core Industries (ICI)

    • Published by the Office of the Economic Adviser (OEA) under the Department for Promotion of Industry and Internal Trade (DPIIT).
    • Measures the performance of core industrial sectors.
    • Serves as a leading indicator of the Index of Industrial Production (IIP).
    • Accounts for about 40% of the weight in the IIP.
    • Nine Core Industries (Base Year 2022–23): Coal, Crude Oil, Natural Gas, Refinery Products, Fertilisers, Steel, Cement, Electricity, and Iron Ore (newly added)

      [2016] In the ‘Index of Eight Core Industries’, which one of the following is given the highest weight?

      (a) Coal Production

      (b) Electricity generation

      (c) Fertilizer production

      (d) Steel production.

    1. WTO Agreement on Fisheries Subsidies (AFS)

      Why in News?

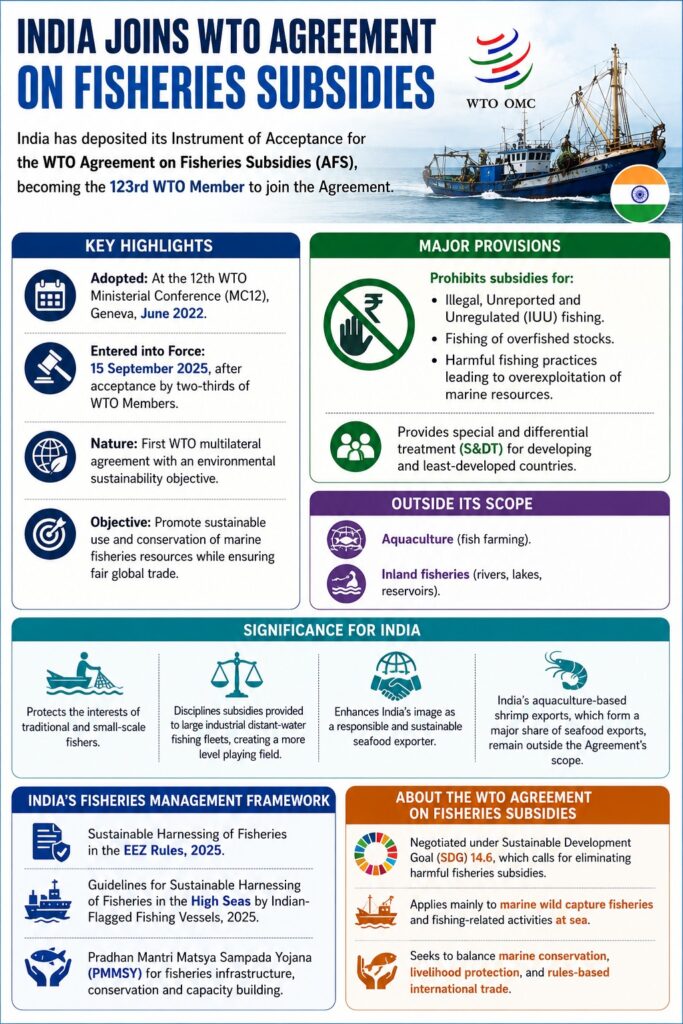
      India has deposited its Instrument of Acceptance for the WTO Agreement on Fisheries Subsidies (AFS), becoming the 123rd WTO Member to join the Agreement.

      Key Highlights

      • Adopted: At the 12th WTO Ministerial Conference (MC12), Geneva, June 2022.
      • Entered into Force: 15 September 2025, after acceptance by two-thirds of WTO Members.
      • Nature: First WTO multilateral agreement with an environmental sustainability objective.
      • Objective: Promote sustainable use and conservation of marine fisheries resources while ensuring fair global trade.

      Major Provisions

      • Prohibits subsidies for:
        • Illegal, Unreported and Unregulated (IUU) fishing.
        • Fishing of overfished stocks.
        • Harmful fishing practices leading to overexploitation of marine resources.
      • Provides special and differential treatment (S&DT) for developing and least-developed countries.

      What is Outside its Scope?

      • Aquaculture (fish farming).
      • Inland fisheries (rivers, lakes, reservoirs).

      Significance for India

      • Protects the interests of traditional and small-scale fishers.
      • Disciplines subsidies provided to large industrial distant-water fishing fleets, creating a more level playing field.
      • Enhances India’s image as a responsible and sustainable seafood exporter.
      • India’s aquaculture-based shrimp exports, which form a major share of seafood exports, remain outside the Agreement’s scope.

      India’s Fisheries Management Framework

      • Sustainable Harnessing of Fisheries in the EEZ Rules, 2025.
      • Guidelines for Sustainable Harnessing of Fisheries in the High Seas by Indian-Flagged Fishing Vessels, 2025.
      • Pradhan Mantri Matsya Sampada Yojana (PMMSY) for fisheries infrastructure, conservation and capacity building.

      About the WTO Agreement on Fisheries Subsidies

      • Negotiated under Sustainable Development Goal (SDG) 14.6, which calls for eliminating harmful fisheries subsidies.
      • Applies mainly to marine wild capture fisheries and fishing-related activities at sea.
      • Seeks to balance marine conservation, livelihood protection, and rules-based international trade.

      [2017] Consider the following statements:

      1. India has ratified the Trade Facilitation Agreement (TFA) of WTO.
      2. TFA is a part of WTO’s Bali Ministerial Package of 2013.
      3. TFA came into force in January 2016.

      Which of the statements given above is/are correct?

      [A] 1 and 2 only

      [B] 1 and 3 only

      [C] 2 and 3 only

      [D] 1, 2 and 3

    2. India Approves First Dengue Vaccine (QDENGA)

      Why in News?

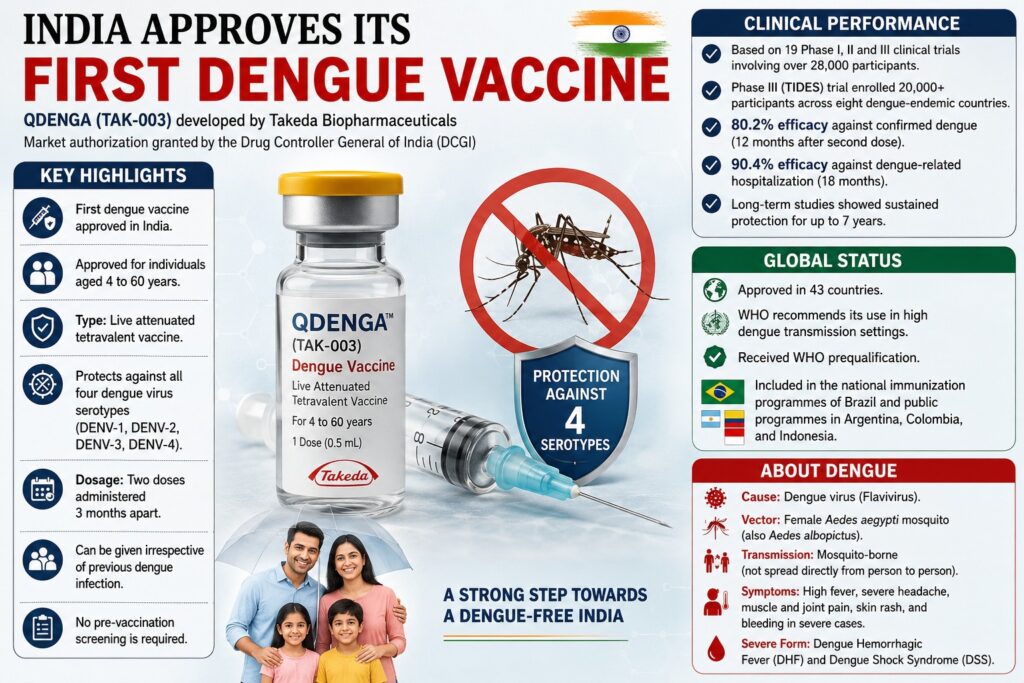
      India has approved its first dengue vaccine, QDENGA (TAK-003), developed by Takeda Biopharmaceuticals, after receiving market authorization from the Drug Controller General of India (DCGI).

      Key Highlights

      • First dengue vaccine approved in India.
      • Approved for individuals aged 4 to 60 years.
      • Type: Live attenuated tetravalent vaccine.
      • Protects against all four dengue virus serotypes (DENV-1, DENV-2, DENV-3, DENV-4).
      • Dosage: Two doses administered 3 months apart.
      • Can be given irrespective of previous dengue infection.
      • No pre-vaccination screening is required.

      Clinical Performance

      • Based on 19 Phase I, II and III clinical trials involving over 28,000 participants.
      • Phase III (TIDES) trial enrolled 20,000+ participants across eight dengue-endemic countries.
      • 80.2% efficacy against confirmed dengue (12 months after second dose).
      • 90.4% efficacy against dengue-related hospitalization (18 months).
      • Long-term studies showed sustained protection for up to 7 years.

      Global Status

      • Approved in 43 countries.
      • WHO recommends its use in high dengue transmission settings.
      • Received WHO prequalification.
      • Included in the national immunization programmes of Brazil and public programmes in Argentina, Colombia, and Indonesia.

      About Dengue

      • Cause: Dengue virus (Flavivirus).
      • Vector: Female Aedes aegypti mosquito (also Aedes albopictus).
      • Transmission: Mosquito-borne (not spread directly from person to person).
      • Symptoms: High fever, severe headache, muscle and joint pain, skin rash, and bleeding in severe cases.
      • Severe Form: Dengue Hemorrhagic Fever (DHF) and Dengue Shock Syndrome (DSS).

      [2023] ‘Wolbachia method’ is sometimes talked about with reference to which one of the following?

      [A] Controlling the viral diseases spread by mosquitoes.

      [B] Converting crop residues into packing material.

      [C] Producing biodegradable plastics.

      [D] Producing biochar from thermo- chemical conversion of biomass

    3. [20th July 2026] The Hindu OpED: The Stark Reality of the Missing Jobs for India’s Gen Z

      PYQ Relevance[UPSC 2014] While we flaunt India’s demographic dividend, we ignore the dropping rates of employability. What are we missing while doing so? Where will the jobs that India desperately needs come from? Explain.
      Linkage: The PYQ asks whether India is ignoring falling employability while flaunting its demographic dividend, and where future jobs will come from. It matches the article’s central tension between the demographic dividend narrative and the graduate unemployment reality.

      Mentor’s Comment

      Periodic Labour Force Survey (PLFS) 2023-24 data shows that unemployment among India’s Gen Z rises, not falls, with higher education. Also, most employed Gen Z workers hold no job contract or social security cover. This has exposed a widening gap between India’s celebrated demographic dividend and the actual quality of work available to its youngest working-age cohort.

      How Wide Is India’s Youth Employment Gap?

      1. Low participation: Labour Force Participation Rate (LFPR) for Gen Z stands at 41.7%, against 75% for Millennials, reflecting continued engagement in education as well as exit from the workforce.
      2. Rural-urban reversal: Rural Gen Z participation (44.1%) exceeds urban participation (37.2%), indicating urban youth delay labour market entry for education and training while rural youth enter earlier out of necessity.
      3. Unemployment gap across cohorts: Overall Gen Z unemployment is 11.9%, compared to just 2% among Millennials, showing the crisis is concentrated in the youngest cohort.
      4. Urban unemployment is sharper: Urban Gen Z unemployment rises to 17.1%, well above the national Gen Z average.
      5. Gender compounds urban unemployment: Urban young women face 22.6% unemployment, the highest among all sub-groups measured.

      How Does Gender Deepen the Employment Crisis for Gen Z?

      1. Domestic duties as exclusion: 27.1% of Gen Z women are engaged only in domestic duties, against just 0.32% of Gen Z men, pulling them out of the labour force altogether.
      2. Low regular wage employment for women: Only 4.7% of Gen Z women hold regular wage jobs, compared to 14.8% of Gen Z men.
      3. Male LFPR advantage: Male labour force participation stands at 59.3% in rural India and 51.3% in urban India, against just 28% and 21.1% respectively for young women.
      4. Structural, not just economic, barriers: Childcare burdens, safety concerns, mobility constraints, and social norms keep women out of paid work, independent of job availability.
      5. Demographic dividend undermined: A large share of young women outside the paid economy weakens the case that India is fully harnessing its demographic dividend.

      Why Does More Education Correlate with Higher Unemployment? 

      1. Graduate unemployment exceeds average: Among Gen Z men with graduate-level education or above, unemployment stands at 29%, and among Gen Z women at 36.9%, both far above the respective cohort averages.
      2. Inverted assumption: Education is expected to lower unemployment; instead, unemployment rises at the highest education levels, contradicting the standard human capital logic.
      3. Persists across cohorts: Millennial graduate unemployment is 5.2% for men and 13.8% for women, confirming the pattern is not unique to Gen Z alone but is sharper for Gen Z.
      4. Root cause is mismatch: The gap reflects a mismatch between what the education system produces and what the labour market demands, not merely a shortage of degree-holders.
      5. Technology reshapes demand: Automation and growing adoption of artificial intelligence are altering the nature of available jobs, widening the skill mismatch further.
      6. Risk of delay compounding: When higher education does not convert quickly into employment, frustration rises, family investment in education comes under strain, and confidence in the growth story weakens.

      Why Is Social Security Coverage a “Mirage” Even for Employed Gen Z?

      1. Low social security coverage: Only 20.1% of Gen Z individuals are covered by social security, leaving the vast majority without protection even when employed.
      2. Job contracts are rare: Just 14.1% of Gen Z workers have a formal job contract; among the 79.9% lacking social security, only 3.2% have a job contract.
      3. Contractual employment is the exception: Only 17.3% of Gen Z workers hold any form of contractual employment, meaning most enter the workforce without either a contract or social protection.
      4. Informalisation within formal employment: Recent years show growing evidence of informalisation of formal employment among Gen Z, meaning even formal-sector jobs are losing security features.
      5. Millennials are only marginally better: Only 26% of Millennials have a job contract and 28.6% are covered by social security, showing the informality problem extends across cohorts, not just Gen Z.
      6. Social cost visible: Large-scale labour protests by industrial and factory workers in Noida, Uttar Pradesh, demanding higher wages and better working conditions, reflect the frustration insecure and poorly protected employment can produce.

      Why Must India Treat Unemployment, Skilling, Women’s Work, and Informality as One Problem?

      1. Debate wrongly siloed: India’s jobs debate is usually discussed separately as unemployment, skilling, women’s work, and labour force participation, obscuring their common origin.
      2. Single connected failure: All four are facets of one connected failure of labour market transition, where education is prolonged but the bridge from education to work remains weak.
      3. Skilling alone is insufficient: Skill programmes have value but cannot substitute for actual job creation, since the binding constraint is demand for labour, not only its quality.
      4. Structural, not motivational, barrier for women: Women face structural barriers that keep them out of work or push them into unpaid roles, and even when employed, work is too often outside formal protection.
      5. Precondition for resolution: Expanding labour-intensive sectors, strengthening school-to-work pathways, aligning training with employer needs, and enabling women’s paid work through apprenticeships, hiring incentives, safe transport, and childcare support are named as the necessary conditions for change.

      Conclusion

      India’s demographic dividend is faltering not from a shortage of young workers but from a labour market unable to convert education into secure, well-paid work; unemployment rises rather than falls with higher education, and even the employed largely lack contracts or social security. Until labour-intensive job creation, skilling-employer linkages, and women’s structural access to work are addressed together rather than in silos, the demographic dividend will remain, in the article’s own words, a promise deferred.