💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Global Groupings and Conventions

Important International institutions, agencies and fora- their structure, mandate.

  • Washington Warns Allies: Choose Between Pax Silica and Beijing’s AI Bloc

    Why in the News

    A draft United States letter warns the 35 signatories of its artificial intelligence (AI) Opportunity Statement that signing up to Beijing’s competing framework will exclude them from the American led Pax Silica coalition. The demand converts a supply chain initiative into a test of exclusive alignment. Kazakhstan, a potential source of critical minerals that has joined both coalitions, is the immediate trigger.

    What is the Pax Silica initiative?

    1. About: Pax Silica was launched by Washington last year to secure supply chains for AI models, semiconductors and critical minerals.
    2. Purpose: It was built for the technology rivalry with Beijing, treating minerals and chips as the inputs that decide who builds the most capable AI.
    3. Membership: About two dozen countries have joined, including close allies Japan, Australia and South Korea.
    4. Legal character: The framework is not binding, so membership carries no treaty obligation.
    5. The new condition: Members that also join Beijing’s rival body face exclusion from the coalition.

    What is the AI Opportunity Statement?

    1. About: A United States statement signed in June by 35 countries that wish to align AI cooperation with Washington.
    2. Coverage: Its signatories include members of the Pax Silica framework and other countries outside it, and the draft warning letter is addressed to this full list.

    What is the World Artificial Intelligence Cooperation Organization?

    1. About: A rival body launched in July by the Chinese President as a challenge to United States influence over the AI sector.
    2. Its offer: It promotes China’s open weight technology, positioning access to models rather than access to chips as the basis of membership.

    What are open weight AI models?

    1. About: Models whose trained parameters are published for download, allowing anyone to run and adapt them on their own hardware.
    2. Why it matters strategically: Adoption does not require a continuing commercial relationship with the developer, so influence spreads without any agreement being signed.

    What does the draft letter actually demand?

    1. A binary choice: Dozens of countries are to be told they must pick sides in the AI race with China.
    2. The penalty: Signing Beijing’s competing framework means exclusion from the United States led coalition.
    3. The stated objective: Washington hopes to starve China of resources in the race to build the most sophisticated AI.
    4. Why that matters: The most capable models are treated as usable for military or economic dominance, which is what makes inputs a security question.
    5. The evidentiary basis: The warning rests on an internal draft and a United States official, not on a published policy.

    Why do critical minerals sit at the centre of the AI race?

    1. Minerals precede chips: Semiconductors, servers and power systems depend on rare earths, gallium, germanium and graphite before any model can be trained.
    2. Refining, not mining, is the chokepoint: China dominates the midstream separation and refining stages even for ore mined elsewhere.
    3. Export controls as leverage: Beijing has used licensing of gallium, germanium, graphite and rare earth magnets as a direct policy instrument.
    4. Why Kazakhstan matters: It is a key potential source of critical minerals, which is why its dual membership set off alarm in Washington.
    5. The self limiting problem: Excluding a supplier country does not create refining capacity anywhere else.

    What do the individual signatories’ positions show about the cost of forcing a choice?

    1. Kazakhstan, the hedger: It is the only country so far known to have joined both initiatives, using its mineral endowment to sell access to both blocs rather than choose.
    2. Japan, the equipment supplier: A Pax Silica member whose firms control critical semiconductor manufacturing equipment, photoresists and wafer materials that no bloc can replace quickly.
    3. South Korea, the memory chip producer: A Pax Silica member whose memory chip makers run large fabrication capacity inside China, so exclusivity carries a direct commercial cost.
    4. Australia, the mining leg: A Pax Silica member with rare earth deposits and a dedicated critical minerals financing facility, but with separation capacity that has historically depended on offshore processing.
    5. China, the rival architecture: Beijing counters chip and minerals leverage with the World Artificial Intelligence Cooperation Organization and freely downloadable models.
    6. United States, the coalition builder: Washington combines export controls on advanced chips with Pax Silica membership, and now with the threat of exclusion.

    Why does the exclusivity demand cut against the United States’ own supply goal?

    1. Suppliers gain from hedging: A mineral rich state earns more by selling access to both coalitions than by picking one.
    2. A framework with no enforcement: Pax Silica is not binding, so exclusion is the only available lever and it is a blunt one.
    3. Open weight models cannot be fenced: Chinese models spread by download, so denying a country coalition membership does not deny it Chinese technology.
    4. Refining dependence persists: The coalition can exclude a supplier and still find that separation and processing run through China.
    5. Retaliation risk: Beijing can curtail exports of critical minerals essential to advanced technology production while Western supply chains are still being built.

    Where does India stand in the AI and critical minerals contest?

    1. Minerals Security Partnership: India joined the Minerals Security Partnership in June 2023, a United States convened grouping to catalyse investment in critical mineral supply chains.
    2. National Critical Mineral Mission: Approved in January 2025 with an outlay of about 16,300 crore rupees, it targets exploration, recovery from tailings and overseas asset acquisition.
    3. IndiaAI Mission: Approved in March 2024 with about 10,371 crore rupees, covering compute capacity, datasets, foundation model support and safe AI.
    4. Summit diplomacy: India chaired the Global Partnership on Artificial Intelligence and hosted its summit in New Delhi in December 2023, and was named the next AI summit host after the Paris AI Action Summit of February 2025.
    5. The strategic autonomy problem: India sits in United States aligned mineral platforms and in BRICS and the Shanghai Cooperation Organisation alongside China, so an exclusivity demand of the Pax Silica kind directly conflicts with its standing position.

    Challenges to Pax Silica

    1. No enforcement mechanism: A framework that is not binding cannot police dual membership. e.g. Kazakhstan has joined both Pax Silica and the Chinese body without penalty so far.
    2. Substitution by the rival supplier: Excluded states can buy the same inputs and models from Beijing. e.g. China’s export licensing of rare earth magnets from April 2025 halted assembly lines at European car plants, demonstrating who controls the flow.
    3. Cost falls on allies first: Export control regimes hit allied firms’ revenues before they hit the target. e.g. Dutch lithography equipment makers lost a large share of their China sales after successive export restrictions.
    4. Midstream capacity cannot be built quickly: Mining new deposits does not solve separation and refining. e.g. Australian rare earth concentrate was long shipped to Malaysia for separation rather than processed at home.
    5. Price volatility deters new investment: Mineral projects need long horizons that commodity cycles destroy. e.g. lithium prices fell sharply from their 2022 peak, stalling announced projects worldwide.
    6. Open weight diffusion defeats membership rules: Model access spreads independently of any coalition. e.g. a Chinese open weight reasoning model released in January 2025 was downloaded and self hosted worldwide within weeks.
    7. Third country resistance to bloc politics: Middle powers resist being made to choose. e.g. several Global South states hold membership of both Western and Chinese digital and minerals platforms simultaneously.

    Conclusion

    The AI contest has moved from controlling exports of chips to controlling membership of coalitions, and the United States is testing whether exclusivity can be enforced on countries that hold the minerals. The instrument is weak, since Pax Silica binds no one, open weight models spread by download, and refining capacity stays with China regardless of who is excluded. Kazakhstan’s dual membership is the first demonstration that suppliers will hedge. For India, an exclusivity demand of this type collides directly with a foreign policy built on membership of competing platforms.

    “[2025] Consider the following statements:
    I. India has joined the Minerals Security Partnership as a member.
    II. India is a resource-rich country in all the 30 critical minerals that it has identified.
    III. The Parliament in 2023 has amended the Mines and Minerals (Development and Regulation) Act, 1957 empowering the Central Government to exclusively auction mining lease and composite license for certain critical minerals.
    Which of the statements given above are correct?
    (a) I and II only
    (b) II and III only
    (c) I and III only
    (d) I, II and III
  • Operationalizing the Australia–Canada–India Technology and Innovation Partnership

    Why in the News

    Australia, Canada and India are moving to operationalise the Australia–Canada–India Technology and Innovation Partnership (ACITI), announced at the G20 Summit in Johannesburg in November 2025. Expanding bilateral cooperation on AI, critical minerals and clean energy across the three countries has not yet converted into a coordinated trilateral delivery mechanism.

    Why does ACITI need to move beyond bilateral cooperation?

    • Canada–India convergence: Bilateral ties have deepened through CEPA negotiations, the Strategic Energy Partnership, and uranium supply and critical minerals cooperation.
    • Canada–Australia convergence: Carney’s March 2026 visit produced agreements spanning critical minerals, clean energy and emerging technologies.
    • Australia–India institutionalisation: ECTA (in force since December 2022) and the Comprehensive Strategic Partnership have embedded sector-driven cooperation.
    • Parallel tracks, no alignment: Each bilateral relationship has advanced independently without a shared framework linking them.
    • ACITI’s actual mandate: Consolidate existing bilateral progress rather than generate new cooperation from a blank slate.

    What complementary capabilities make trilateral cooperation viable?

    • Canada: AI research strength, clean technology, and CCUS regulatory experience.
    • Australia: Resource base, commercialisation capacity, and grid-scale battery storage operating experience.
    • India: Manufacturing scale, population-scale digital infrastructure, and downstream industrial demand.
    • Sectoral scope: AI governance, digital infrastructure, green hydrogen, battery storage, CCUS and critical minerals form a single interconnected agenda rather than separate silos.
    • Strategic logic: Energy security and industrial competitiveness are treated as mutually reinforcing, not independent, policy goals.

    Is the binding constraint capability or coordination?

    • Minerals: The binding constraint across gallium, germanium, indium, lithium and rare earths is refining and processing capacity, not resource availability.
    • AI governance: None of the three countries has binding AI legislation; all rely on voluntary, principles-based frameworks, producing convergence without harmonisation.
    • Digital infrastructure: Advanced national capability coexists with unresolved rural, remote and regional connectivity gaps in all three countries.
    • Financing: Commercialisation mechanisms to move projects beyond the pilot stage remain undeveloped.
    • Pattern: Capability exists at the national level; the mechanism to convert it into trilateral outcomes does not.

    What do country-specific positions demonstrate about where trilateral value can be added?

    • Gallium: Australia is scaling toward roughly 100 tonnes as a bauxite byproduct, Canada holds pilot-stage refining capacity near 40 tonnes, India targets nearly 10 tonnes with no active production, against China’s approximately 750 tonnes.
    • Lithium: Australia is the world’s largest producer, Canada ranks sixth in reserves and seventh in production while expanding refining, India is scaling demand through Jammu & Kashmir discoveries, but China retains dominant midstream refining capacity.
    • AI safety standards: Canada’s Accessible and Equitable Artificial Intelligence Systems standard, Australia’s Voluntary AI Safety Standard, and India’s evolving guidelines remain non-binding by design, avoiding overregulation at the cost of interoperability.
    • Grid storage: Australia’s Hornsdale Power Reserve demonstrates millisecond-scale grid stabilisation, offering a template for India’s over 90 GWh of storage projects underway and Canada’s hydro-based balancing capacity.
      • Each example shows division of labour by capability stage — extraction, refining, or downstream deployment — rather than uniform national strength.

    Can coordination be institutionalised given administrative and political constraints?

    • Innovation Working Group: Proposed to support financing access, industrial partnerships and cross-border markets for firms across the ecosystem.
    • Biannual dialogues: Proposed to tie meetings to specific deliverables, project pipelines, standards proposals, and regulatory coordination.
    • Standards coordination: Sector-specific dialogues with mutual recognition mechanisms are proposed for green hydrogen certification and mineral traceability.
    • Third-market collaboration: Joint engagement with Taiwan, South Korea and Japan is identified to improve bargaining power in downstream semiconductor markets.
    • Primary risk: Sustained political and industry engagement across three governments, not capability, is the binding implementation constraint.

    Conclusion

    ACITI’s core challenge is institutional conversion, not capability shortfall. Australia, Canada and India already possess complementary strengths across AI, energy and critical minerals, demonstrated through working bilateral relationships. What remains unresolved is a mechanism to translate fragmented bilateral initiatives into coordinated trilateral delivery. ACITI’s success will depend on moving from strategic alignment to implementation discipline — mobilising capital, securing long-term commercial commitments, and sustaining political support across all three governments.

  • [2nd June 2026] The Hindu OpED: IMEC is caught between commerce and geopolitics

    PYQ Relevance[UPSC 2022] How will I2U2 (India, Israel, UAE and USA) grouping transform India’s position in global politics?Linkage: The question focuses on emerging minilateral partnerships involving India, Israel and Gulf countries, which form the geopolitical foundation of IMEC. IMEC is the economic and connectivity manifestation of the same India-Middle East strategic architecture represented by I2U2.

    Mentor’s Comment

    The recent Iran-Israel conflict has renewed attention on the India-Middle East-Europe Economic Corridor (IMEC) by exposing the vulnerability of global trade routes such as the Strait of Hormuz and the Suez Canal. While the conflict strengthens the strategic case for alternative connectivity corridors like IMEC, it has simultaneously delayed the project’s implementation due to growing instability across West Asia.

    What is India-Middle East-Europe Economic Corridor (IMEC)?

    1. It is a planned multimodal transport and infrastructure network designed to connect India, the Arabian Gulf, and Europe. 
    2. Formalised via a Memorandum of Understanding (MoU) signed at the G20 Summit in New Delhi, the initiative aims to create a highly efficient ship-to-rail transit system. 
    3. It acts as a transparent, sustainable, and debt-free alternative to China’s Belt and Road Initiative (BRI) while significantly reducing the global reliance on traditional maritime chokepoints like the Suez Canal.

    How Has the Iran-Israel Conflict Exposed the Vulnerability of Existing Global Trade Routes?

    1. Military Vulnerability: The conflict challenged assumptions regarding technological and military superiority as guarantees of strategic success.
    2. Aircraft Losses: Reports indicate that 42 U.S. aircraft were reportedly lost or damaged during “Operation Epic Fury.”
    3. Missile Defence Stress: More than half of the inventories of Patriot, THAAD and Terminal High Altitude Area Defence interceptors were reportedly expended.
    4. Asymmetric Warfare: Iranian missile and drone capabilities imposed substantial costs on technologically superior adversaries.
    5. Trade Route Fragility: The conflict highlighted how disruptions in strategic chokepoints can generate global economic consequences.
    6. Hormuz Significance: Nearly 20 million barrels of crude oil move through the Strait of Hormuz every day.
    7. Global Share: The strait carries roughly one-third of global seaborne oil supplies.
    8. India’s Exposure: India imports around 88% of its crude oil requirements, making it highly vulnerable to disruptions.
    9. Economic Impact: Even temporary blockades can increase freight costs, insurance premiums, and energy prices globally.

    Why Has IMEC Gained Strategic Importance After the Conflict?

    1. Connectivity Diversification: Provides alternatives to vulnerable maritime chokepoints.
    2. Supply Chain Resilience: Reduces excessive dependence on the Suez Canal and Strait of Hormuz.
    3. Strategic Redundancy: Creates multiple transportation pathways during geopolitical crises.
    4. Economic Security: Enhances reliability of trade flows between India, West Asia and Europe.
    5. Geopolitical Necessity: Demonstrates the need for trade corridors that avoid conflict-prone regions.
    6. Regional Integration: Links major production centres, consumption markets and logistics hubs.

    What is the Structure and Design of IMEC?

    Eastern Corridor

    1. India-UAE Linkage: Connects India to West Asia through maritime routes linked with the UAE.
    2. Gateway Function: Serves as the entry point of the corridor into the Arabian Peninsula.

    Central Corridor

    1. Transit Route: Passes through UAE, Saudi Arabia, Jordan and Israel.
    2. Haifa Terminus: Ends at the Israeli port of Haifa on the Mediterranean coast.
    3. Multimodal Connectivity: Integrates ports, railways, logistics facilities and customs infrastructure.

    Western Corridor

    1. European Connection: Links Haifa to European ports through Mediterranean maritime routes.
    2. Market Access: Facilitates faster movement of goods into European markets.

    Infrastructure Components

    1. Rail Networks: Ensures seamless cargo movement across West Asia.
    2. Ports and Logistics: Strengthens multimodal transport efficiency.
    3. Energy Corridors: Supports electricity transmission and hydrogen trade.
    4. Digital Connectivity: Includes high-speed data cables and digital infrastructure.
    5. Green Transition: Integrates renewable energy and green hydrogen networks.

    How Does IMEC Compare with Other Connectivity Corridors?

    International North-South Transport Corridor (INSTC)

    1. Route Objective: Connects India with Russia and Europe through Iran.
    2. Strategic Purpose: Reduces dependence on the Suez Canal.
    3. Geographic Advantage: Provides shorter transit times to Eurasian markets.

    Belt and Road Initiative (BRI)

    1. Chinese Connectivity Model: Links Asia, Africa and Europe through infrastructure projects.
    2. Land Connectivity: Seeks alternatives to maritime chokepoints.
    3. Strategic Competition: Represents China’s connectivity vision, while IMEC serves as an alternative architecture.

    IMEC Distinction

    1. Multidimensional Design: Integrates trade, energy, digital and logistics connectivity.
    2. West Asian Focus: Traverses economically significant regions of the Arabian Peninsula.
    3. India-Europe Orientation: Establishes a dedicated connectivity route linking India with Europe.

    How Has the Conflict Delayed the Execution of IMEC?

    1. Gaza War Impact: The October 2023 Gaza conflict stalled implementation soon after IMEC’s announcement.
    2. Haifa Disruptions: The corridor’s Mediterranean endpoint became directly affected by regional instability.
    3. Iran-Israel Escalation: Renewed conflict increased uncertainty regarding infrastructure investments.
    4. Port Security Risks: UAE ports such as Jebel Ali and Fujairah faced repeated regional security concerns.
    5. Hormuz Dependency: Disruptions in the Strait of Hormuz affected broader maritime logistics.
    6. Investor Caution: Heightened geopolitical risks increased concerns regarding project viability and timelines.

    How Do Regional Political Divisions Threaten IMEC?

    1. Saudi-UAE Coordination: Successful implementation requires close strategic coordination among Gulf partners.
    2. Emerging Divergences: Differences have emerged regarding regional security and foreign policy priorities.
    3. OPEC Exit Decision: UAE announced plans to leave OPEC’s production framework, indicating policy divergence.
    4. Israel Security Cooperation: Growing defence cooperation between Israel and Gulf states adds complexity to regional diplomacy.
    5. Strategic Trust Requirement: Corridor success depends upon long-term political alignment among participating states.

    What Alternative Pathways Can Strengthen IMEC’s Viability?

    Oman-Centric Entry Routes

    1. Salalah Port: Offers access away from conflict-prone Hormuz waters.
    2. Duqm Port: Provides strategic logistics infrastructure on the Arabian Sea.
    3. Muscat Connectivity: Expands alternative maritime entry options.

    Mediterranean Alternatives

    1. Haifa Supplementation: Reduces excessive dependence on a single terminal.
    2. Egyptian Ports: Utilises established logistics ecosystems.
    3. Suez Economic Zone: Provides industrial and manufacturing support.
    4. Industrial Base: Hosts specialised facilities in green hydrogen, LNG, shipping and advanced manufacturing.

    Flexible Corridor Design

    1. Network Approach: Develops multiple routes rather than a single fixed corridor.
    2. Risk Mitigation: Ensures continuity despite regional disruptions.
    3. Strategic Adaptability: Allows route modifications during crises.

    What Role Can India Play in Advancing IMEC?

    1. Connectivity Leadership: Positions India as a major architect of transcontinental connectivity.
    2. Diplomatic Balancing: Maintains strong relations with Saudi Arabia, UAE, Israel and Europe simultaneously.
    3. Economic Integration: Expands trade access to Europe and West Asia.
    4. Strategic Autonomy: Diversifies supply chains beyond traditional routes.
    5. Infrastructure Cooperation: Encourages investments in logistics, digital and energy networks.
    6. India-Europe Engagement: Strengthened by Prime Minister Narendra Modi’s Europe visit in May 2026 and growing India-Europe connectivity cooperation.

    Conclusion

    The Iran-Israel conflict has reinforced the strategic necessity of IMEC by exposing the vulnerabilities of existing trade routes and energy chokepoints. At the same time, it has highlighted that connectivity projects cannot succeed through infrastructure alone; they require sustained political stability, regional cooperation and strategic trust. The future success of IMEC will depend on its ability to balance commercial objectives with the geopolitical realities of West Asia.

  • Behind government ban on sugar exports: Iran war, El Nino

    Why in the News?

    India has moved sugar from the “restricted” category to the “prohibited” category till September 2026, effectively banning exports at a time when global prices remain attractive. The decision marks a sharp shift from India’s recent role as a major sugar exporter, with shipments touching nearly 11 million tonnes annually. This is due to the fears of domestic shortages due to a weak monsoon risk from El Niño and fertiliser disruptions arising from the Iran-West Asia conflict.

    Why has India prohibited sugar exports despite adequate domestic stocks?

    1. Stock Preservation: Ensures sufficient domestic sugar availability amid uncertainty. India expects 279 lakh tonnes of production against 280 lakh tonnes of domestic consumption, leaving little surplus.
    2. Closing Stocks: Prevents depletion of reserves. Sugar closing stocks are projected at only 42.53 lakh tonnes, the lowest since 2016-17, compared to 143.33 lakh tonnes in 2018-19.
    3. Export Curtailment: Restricts outward shipments to avoid shortages. India exported nearly 11 million tonnes in earlier years, but exports for 2025-26 are estimated at only 6.5 lakh tonnes.
    4. Inflation Management: Reduces risk of food inflation. The government already faces pressure from fuel and fertilizer inflation, making sugar price volatility politically sensitive.
    5. Policy Shift: Reflects stronger precautionary intervention. Sugar has moved from the “restricted” category to “prohibited category”, representing a more stringent control regime.

    How can El Niño affect India’s sugar economy?

    1. Monsoon Disruption: Alters rainfall distribution. El Niño, caused by abnormal warming of the eastern equatorial Pacific Ocean, weakens monsoon circulation and raises risks of rainfall deficiency.
    2. Sugarcane Vulnerability: Affects water-intensive crops disproportionately. Sugarcane requires high water availability and remains sensitive to rainfall stress.
    3. Crop Timing: Creates risks for recently planted crops.
      1. In Uttar Pradesh, sugarcane planted during February-April 2025 will mature in 11-12 months, making it dependent on monsoon conditions.
      2. Nearly 75% sugarcane in Maharashtra belongs to the pre-season crop, planted between July-December, making rainfall variability significant.
    4. Climate Forecast: Increases uncertainty for agricultural planning. Global climate models indicate a 50% probability of El Niño conditions emerging during the second half of 2025.

    How has the Iran conflict influenced India’s sugar policy?

    1. Fertiliser Supply Risks and Production CostsInput Disruptions: 
      1. Sugarcane requires high doses of urea. Disruptions to Gulf-based supply chains, where 63% of India’s nitrogen fertilizer imports (urea/ammonia) originate, threaten to create shortages during the sowing season.
      2. Rising Costs: War risk insurance and higher freight rates have significantly increased the cost of imported raw materials for fertilizers, potentially lowering yields if farmers struggle to afford them
    2. Food Inflation Management: The government is monitoring the crisis through a special group of ministers to ensure domestic availability of sugar. This sector is  viewed as sensitive to inflation, particularly when international prices are lower than domestic ones, as noted in a March 2026 report.
    3. Geopolitical Linkage: Expands non-traditional security concerns. Agricultural decisions increasingly reflect developments in energy corridors and maritime chokepoints.

    Why are sugar stocks becoming a policy concern?

    1. Nine-Year Low: Indicates tightening domestic supply. Sugar closing stocks may decline to 42.53 lakh tonnes, the lowest in nearly a decade.
    2. Production-Consumption Gap: Limits export flexibility. Production of 279 lakh tonnes remains marginally below domestic demand of 280 lakh tonnes.
    3. Administrative Uncertainty: Raises concerns over reporting accuracy. Sugar mills file monthly P-II returns regarding stocks, but actual physical availability may vary.
    4. Precautionary Governance: Avoids crisis response later. The government seeks to prevent a sudden shortage that could force emergency imports.

    Does banning sugar exports improve food security or distort markets?

    Banning sugar exports is a double-edged policy that achieves short-term domestic stability at the cost of long-term economic efficiency. It simultaneously improves immediate food security and distorts agricultural markets.

    1. Improvement in Food Security: Ensures domestic affordability. Export restrictions shield consumers from price spikes.
      1. It shields local consumers
      2. It controls food inflation: Sugar is a key ingredient in processed foods. Controlling its price prevents a cascading inflationary effect on essential consumer goods.
      3. It ensures adequate buffer stock: Restricting exports ensures that the country maintains a reliable domestic supply, neutralizing risks from weather-induced crop failures.
    2. Depresses Farmer Income: Artificially capping domestic prices prevents sugarcane farmers and mills from profiting from lucrative global market premiums.
    3. Damages Trade Reliability: Abrupt policy shifts harm India’s reputation as a reliable global trade partner. It forces international buyers to permanently shift to competitors like Brazil or Thailand.
    4. Market Distortion: Encourages informal trade channels. Historically, excessive restrictions on commodities with high demand can incentivise smuggling.
    5. Discourages Sector Investment: Unpredictable export bans create policy uncertainty, which discourages private capital investment in modernizing refinery and storage infrastructure.

    How does the issue reflect the growing climate-geopolitics nexus in agriculture?

    The sugar crisis highlights the emerging climate-geopolitics nexus, where environmental shocks and geopolitical conflicts no longer act in isolation. Instead, they compound each other to threaten global food systems.

    1. The Multiplier Effect: Climate Shocks Meet Geopolitical Chokepoints
      1. Double Vulnerability: Extreme weather events (like erratic monsoons) shrink domestic sugar yields, while simultaneous conflicts in the Gulf disrupt the import of critical inputs like fertilizers.
      2. Chokepoint Dependency: Agriculture is bound to maritime corridors; a crisis in the Strait of Hormuz directly threatens the domestic supply of urea.
    2. From Subsidies to Security
      1. Weaponised Scarcity: Food and input supplies are increasingly used as geopolitical leverage. This forces nations to shift from open trade to defensive, protectionist policies.
      2. National Security Priority: Agricultural policies have shifted from simple farm-income management to a core pillar of national security. This is aimed to shield populations from externally driven food inflation.
    3. Institutional Overlap: The Need for Integrated Policy
      1. Breaking Silos: Managing modern agricultural stability requires synchronized actions across traditionally separate sectors:
        1. Ministry of Agriculture: Optimising crop patterns for climate resilience.
        2. Ministry of External Affairs: Securing alternative fertilizer corridors.
        3. Ministry of Commerce: Calibrating sudden, reactive export bans 

    Conclusion

    India’s sugar export ban reflects a precautionary response to converging risks from El Niño, fertiliser insecurity and inflation pressures. While the move strengthens short-term domestic food security, long-term resilience requires crop diversification, efficient water use, climate-resilient agriculture and stable trade policy.

    PYQ Relevance

    [UPSC 2024] Elucidate the importance of buffer stocks for stabilizing agricultural prices in India. What are the challenges associated with the storage of buffer stock? Discuss

    Linkage: The sugar export ban directly concerns buffer stocks, domestic availability and price stabilisation, core GS-3 themes under food security and agricultural markets. India prohibited sugar exports due to concerns over declining closing stocks and possible supply disruptions from El Niño and fertiliser shortages. This reflects the role of strategic stocks in preventing inflation and ensuring food security

  • BRICS Foreign Ministers’ Meeting 2026

    Why in the News

    Prime Minister Narendra Modi met several foreign ministers attending the BRICS Foreign Ministers’ Meeting in New Delhi during India’s 2026 chairship of the grouping.

    India’s 2026 BRICS Chairship

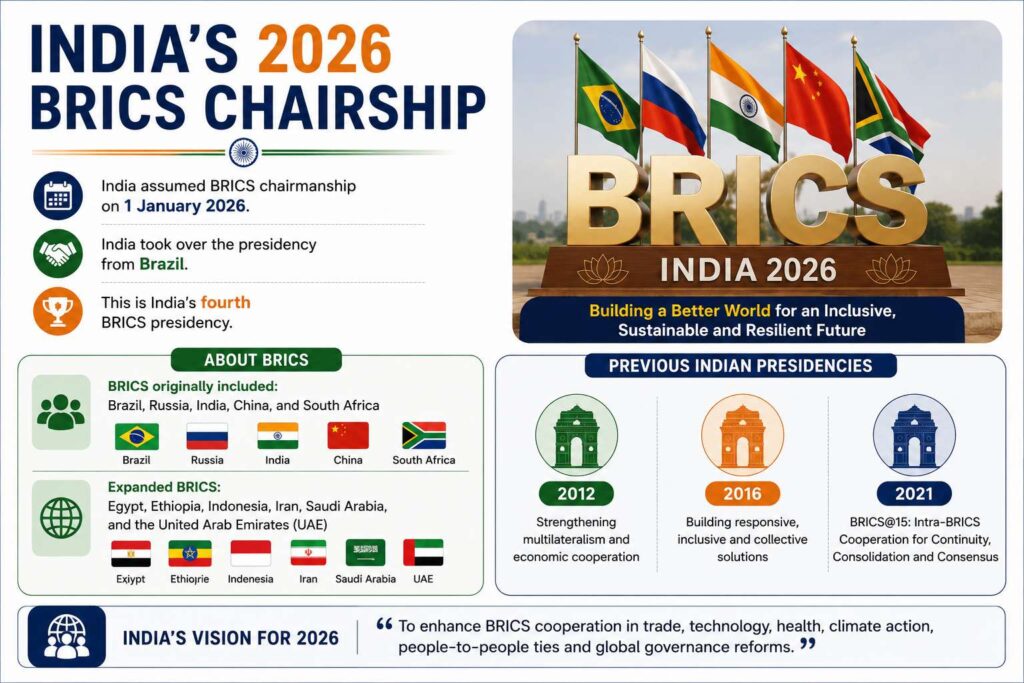
    • India assumed BRICS chairmanship on 1 January 2026.
    • India took over the presidency from Brazil.
    • This is India’s fourth BRICS presidency.

    About BRICS

    • BRICS originally included: Brazil, Russia, India, China, and South Africa
    • Expanded BRICS: Egypt, Ethiopia, Indonesia, Iran, Saudi Arabia, and the United Arab Emirates (UAE)

    India’s 2026 BRICS Chairship

    • India assumed BRICS chairmanship on 1 January 2026.
    • India took over the presidency from Brazil.
    • This is India’s fourth BRICS presidency.

    Previous Indian Presidencies

    • 2012
    • 2016
    • 2021
    [2025] Consider the following statements with regard to BRICS; 
    I. 16th BRICS Summit was held under the Chairmanship of Russia in Kazan. 
    II. Indonesia has become a full member of BRICS. 
    III. The theme of the 16th BRICS Summit was Strengthening Multiculturalism for Just Global Development and Security. 
    Which of the statements given above is/are correct? 
    [A] I and II [B] II and III [C] I and III [D] I only
  • [14th May 2026] The Hindu OpED: The Xi-Trump summit- shadow boxing on Iran

    Mentor’s Comment

    The Xi-Trump (China-USA) summit in Beijing (2026) has become geopolitically important as the U.S. faces growing difficulty in managing its confrontation with Iran. The conflict has become costly, unpopular, and difficult to resolve, pushing Washington to explore China’s help for a diplomatic exit. This marks a major shift from earlier U.S. resistance to China’s rise and resembles the 1972 Nixon-China diplomatic opening, where strategic cooperation helped solve larger geopolitical problems.

    Why is the Xi-Trump summit being compared to the 1972 Nixon-China breakthrough?

    1. Historical Parallel: The summit is compared with the 1972 Nixon-Mao meeting, which fundamentally altered Cold War geopolitics and enabled U.S.-China normalization.
    2. Strategic Bargaining: The 1972 summit involved reciprocal concessions, including U.S. recognition of the People’s Republic of China and downgrading Taiwan’s status in exchange for strategic cooperation.
    3. Current Context: Present negotiations similarly indicate transactional diplomacy, where Chinese cooperation on Iran could be exchanged for concessions on tariffs, technology restrictions, or Taiwan.
    4. Geopolitical Reordering: The summit may redefine strategic alignments amid intensifying great-power competition and regional instability in West Asia.

    How has the Iran crisis emerged as the central issue in the U.S.-China diplomacy?

    1. Strategic Deadlock: The U.S. seeks an exit from an increasingly costly and unpopular confrontation with Iran without appearing strategically weak.
    2. Hormuz Leverage: Iran retains strategic influence through the Strait of Hormuz, through which nearly 20% of global crude oil trade passes, creating risks of global energy disruption.
    3. Military Asymmetry: Iran has adopted asymmetric tactics instead of direct military confrontation. This increases costs for adversaries while avoiding conventional escalation.
    4. Domestic Political Pressure: The inability of the U.S. administration to secure a decisive outcome risks political consequences during domestic electoral cycles.

    Why has China emerged as Iran’s principal strategic anchor?

    1. Energy Dependence: China purchases more than 80% of Iranian oil exports, estimated at nearly $45 billion in 2025, making it Tehran’s largest economic partner.
    2. Trade Connectivity: Bilateral trade between China and Iran exceeds $9 billion, including dependence on Chinese industrial and technological inputs.
    3. Diplomatic Engagement: Iranian Foreign Minister Abbas Araghchi visited Beijing for consultations, signalling China’s increasing diplomatic role.
    4. Strategic Shielding: China, alongside Russia, has resisted Western-led pressure, including opposition to the U.S.-backed resolutions in the United Nations Security Council (UNSC).

    How has Iran responded to American pressure and negotiations?

    1. Negotiation Breakdown: Iran reportedly rejected a U.S. proposal after prolonged negotiations, indicating declining trust between Washington and Tehran.
    2. Escalatory Risks: The U.S. military option remains constrained due to fears of wider regional destabilisation and concerns over legal authorisation under the War Powers Act.
    3. Expanded Demands: Iran has reportedly increased demands involving security guarantees, sanctions relief, release of frozen assets, closure of U.S. military bases, and ceasefires in regional conflict zones.
    4. Strategic Confidence: Iran’s ability to sustain pressure despite sanctions reflects its confidence in alternative partnerships, particularly with China and Russia.

    Can China realistically mediate between the United States and Iran?

    1. Mediator Role: China possesses leverage due to its economic dependence relationship with Iran and growing diplomatic acceptance in West Asia.
    2. Transactional Diplomacy: Beijing may seek concessions on bilateral issues such as tariffs, sanctions, technology controls, and Taiwan in return for diplomatic assistance.
    3. Regional Stability Interest: Sustained conflict threatens Chinese energy security through rising oil prices and disruption of Gulf maritime routes.
    4. Calculated Neutrality: China may prefer limited mediation rather than deep intervention, preserving relations with all regional actors.

    What are the larger geopolitical implications of the summit?

    1. Great Power Politics: The summit reflects increasing interdependence between geopolitical rivals despite strategic competition.
    2. Multipolar Transition: China’s expanding diplomatic role indicates a gradual movement toward a more multipolar global order.
    3. Energy Security Risks: Prolonged instability in West Asia threatens global oil prices and maritime trade.
    4. Institutional Contestation: Divergence in the UNSC demonstrates weakening consensus among major powers on conflict resolution.

    Conclusion

    The Xi-Trump summit highlights the intersection of regional crises and great-power diplomacy. Iran has evolved from a regional security issue into a strategic bargaining chip in U.S.-China relations. Any durable resolution will depend on balancing coercive diplomacy with negotiated settlements while ensuring regional stability and uninterrupted energy flows.

    PYQ Relevance

    [UPSC 2018] In what ways would the ongoing US-Iran Nuclear Pact controversy affect the national interest of India? How should India respond to this situation?

    Linkage: The rising U.S.-Iran tensions have their impact on global oil supply, regional stability, and diplomacy. The PYQ links directly to India’s energy security, West Asia policy, and strategic balancing amid great-power rivalry

  • Indian Ocean Rim Association (IORA)

    Why in the News

    India’s Ministry of External Affairs, along with the IORA Secretariat, organised the 10th Indian Ocean Dialogue.

    About IORA

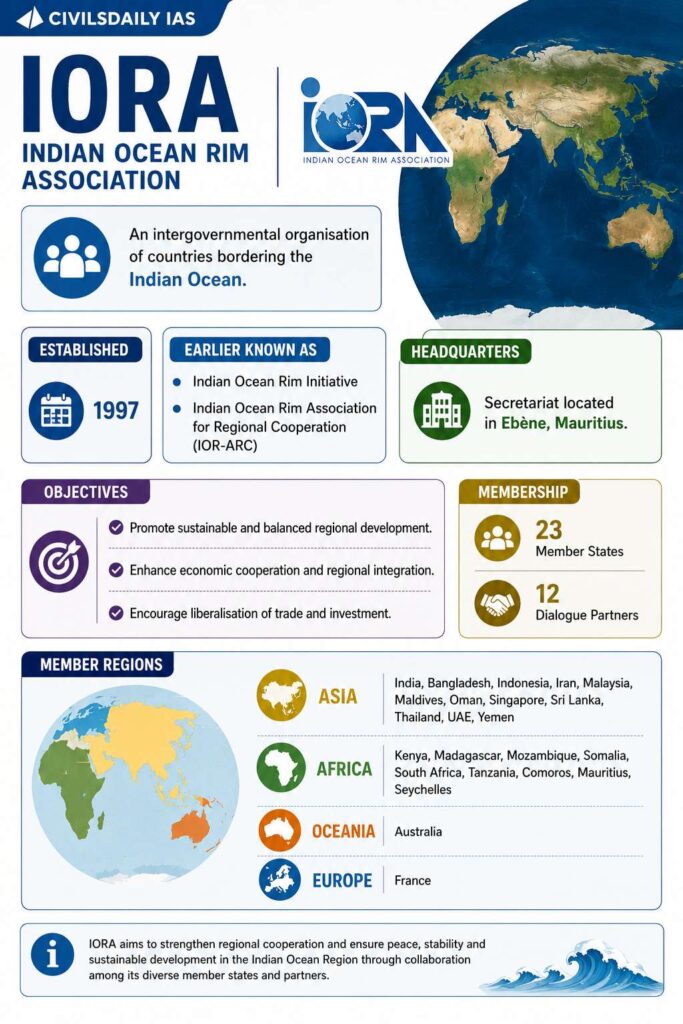
    • An intergovernmental organisation of countries bordering the Indian Ocean.
    • Established in 1997.
    • Earlier known as:
      • Indian Ocean Rim Initiative
      • Indian Ocean Rim Association for Regional Cooperation (IOR-ARC)

    Headquarters

    • Secretariat located in Ebène, Mauritius.

    Objectives

    • Promote sustainable and balanced regional development.
    • Enhance economic cooperation and regional integration.
    • Encourage liberalisation of trade and investment.

    Membership

    • 23 Member States
    • 12 Dialogue Partners

    Member Regions

    • Asia: India, Bangladesh, Indonesia, Iran, Malaysia, Maldives, Oman, Singapore, Sri Lanka, Thailand, UAE, Yemen
    • Africa: Kenya, Madagascar, Mozambique, Somalia, South Africa, Tanzania, Comoros, Mauritius, Seychelles
    • Oceania: Australia
    • Europe: France

    Dialogue Partners

    • China, EU, Germany, Italy, Japan, Russia, Saudi Arabia, South Korea, Türkiye, UK, US, Egypt
    [2015] With reference to ‘Indian Ocean Rim Association for Regional Cooperation (IOR-ARC)’, Consider the following statements: 
    1. It was established very recently in response to incidents of piracy and accidents of oil spills 
    2. It is an alliance meant for maritime security only 
    Which of the following statements given above is/are correct? 
    [A] 1 only [B] 2 only [C] Both 1 and 2 [D] Neither 1 nor 2
  • The toll of structural adjustments on the global south and a case for accountability

    Why in the News?

    A new paper published in BMJ Global Health (March 2026) has revived scrutiny of IMF and World Bank Structural Adjustment Programmes (SAPs), arguing that these institutions owe reparations to Global South countries for long-term socio-economic damage.

    What are Structural Adjustment Programmes (SAPs)?

    They are a set of economic mandates imposed by international financial institutions, principally the International Monetary Fund (IMF) and the World Bank, on developing nations. They are imposed as a strict prerequisite for securing new loans, refinancing existing debt, or avoiding sovereign default. 

    How did Structural Adjustment Programmes emerge in the Global South?

    1. Debt Crisis: Developing countries borrowed heavily during the 1970s for industrialization and imports. Rising interest rates by the U.S. Federal Reserve in the late 1970s sharply increased repayment burdens.
    2. Dollar-Denominated Loans: Countries borrowing in U.S. dollars faced rising repayment obligations due to currency depreciation beyond domestic control.
    3. IMF-World Bank Intervention: Financial assistance became conditional upon implementing structural economic reforms aimed at restoring macroeconomic stability.
    4. Debt Leverage: Creditor institutions used debt obligations to push policy reforms in exchange for access to loans and refinancing.
    5. Historical Context: SAPs coincided with the rise of market-oriented neoliberal economic policies globally.

    What were the major components of Structural Adjustment Programmes?

    1. Fiscal Austerity: Reduced public expenditure on healthcare, education, subsidies, and social security to reduce fiscal deficits.
    2. Privatization: Transferred state-owned enterprises and public services to private ownership.
    3. Trade Liberalization: Removed trade barriers and opened domestic markets to global competition.
    4. Deregulation: Reduced industrial regulations, labour protections, and capital controls.
    5. Currency Devaluation: Encouraged export competitiveness through exchange-rate reforms.
    6. Conditional Financing: Linked access to international loans with compliance to reform packages.

    How did SAPs affect economic growth in the Global South?

    1. Growth Slowdown: Economic growth reportedly declined sharply during adjustment periods. The Global South’s average growth rate fell from nearly 3.2% before SAPs to 0.7% during the 1980s-1990s.
    2. Income Loss: Developing countries collectively lost an estimated $480 billion annually in potential national income.
    3. Latin America: Real per capita income reportedly declined by 15% after 1980, recovering to previous levels only by 2006.
    4. Sub-Saharan Africa: Income levels reportedly fell sharply before eventual recovery decades later.
    5. Industrial Weakening: Liberalization exposed domestic industries to global competition before adequate institutional preparedness.
    6. Developmental Sovereignty: Reduced state capacity to pursue independent industrial policy.

    What social consequences emerged from Structural Adjustment Programmes?

    1. Healthcare Retrenchment: Public health expenditure cuts weakened medical infrastructure and service delivery.
    2. Education Cuts: Reduced state spending constrained human capital development.
    3. Child Mortality: SAP-linked effects reportedly contributed to 56.62 additional child deaths per 1,000 births in Sub-Saharan Africa.
    4. Maternal Mortality: Around 360 additional maternal deaths per 1,00,000 births were associated with SAP-linked reforms.
    5. Excess Mortality: Nearly 3,05,000 excess infant deaths reportedly occurred between 1986-2010 relative to pre-adjustment trends.
    6. User Fees: Privatization and reduced welfare spending increased costs of essential services.
    7. Food Inflation: Currency depreciation increased food prices and reduced affordability.

    Did SAPs reinforce historical patterns of economic dependency?

    1. Neo-Colonial Continuity: Critics argue SAPs reopened developing economies to exploitative global market structures.
    2. Labour Cost Compression: Reduced labour protections lowered production costs for multinational firms.
    3. Capital Flight: Liberalized financial systems facilitated outflows of profits.
    4. Profit Repatriation: Private capital reportedly extracted profits exceeding $250 billion annually.
    5. Trade Deregulation: Wealth transfers through tax avoidance reportedly exceeded $1 trillion annually.
    6. Domestic Reinvestment Loss: Economic surpluses were diverted away from national development priorities.

    Why is there a growing demand for accountability and reparations?

    1. Institutional Responsibility: IMF and World Bank are viewed as principal architects of adjustment policies.
    2. Public Service Losses: Compensation demands focus on healthcare, education, and welfare spending losses.
    3. Counterfactual Justice: Proposals estimate damages by comparing actual outcomes with hypothetical development without SAPs.
    4. Mortality Compensation: Reparative justice arguments extend to health and mortality impacts.
    5. Governance Imbalance: The Global North controls a disproportionate share of voting power within Bretton Woods institutions.
    6. Sovereign Immunity: Legal protections restrict lawsuits against international financial institutions.

    What reforms are suggested for global financial governance?

    1. Conditionality Reform: Eliminates rigid structural adjustment requirements tied to financial assistance.
    2. Institutional Democratization: Expands policy voice of developing countries within IMF and World Bank governance.
    3. Policy Sovereignty: Ensures aid recipients retain flexibility over domestic development choices.
    4. Alternative Financing: Expands access to institutions such as the New Development Bank (BRICS Bank) and the Asian Infrastructure Investment Bank (AIIB).
    5. Inclusive Development: Balances macroeconomic stability with social welfare investments.

    Conclusion

    The structural adjustment debate reflects a larger tension between macroeconomic stabilization and social justice. While fiscal discipline and market reforms can support economic efficiency, externally imposed conditionalities without domestic context risk undermining welfare and developmental autonomy. Future global financial governance requires balancing economic reform with equity, democratic participation, and sovereign policy space.

    PYQ Relevance

    [UPSC 2024] Examine the pattern and trend of public expenditure on social services in the post-reforms period in India. To what extent this has been in consonance with achieving the objective of inclusive growth?

    Linkage: The PYQ examines whether post-reform economic policies balanced fiscal reforms with social sector expenditure to ensure inclusive growth. IMF-World Bank structural adjustment policies are critiqued for reducing public spending on health, education and welfare. This highlights how austerity can undermine inclusive development outcomes.

  • Maritime security if of primordial importance to Indian Ocean Region

    Why in the News?

    The 10th Indian Ocean Dialogue (IOD) of the 23-member Indian Ocean Rim Association (IORA) was held in New Delhi on May 7-8, 2026, under the theme “Indian Ocean Region in a Transforming World.” India, as IORA Chair (2025-27), prioritised maritime security, blue economy, and innovation under its MAHASAGAR vision. The dialogue gains significance amid rising instability in West Asia and disruptions in key sea routes, bringing maritime security to the forefront of regional economic and strategic concerns.

    Key Facts about IORA

    1. Establishment: Formed in 1997.
    2. Members: Includes India, Australia, Bangladesh, Indonesia, Kenya, France, UAE, South Africa, Sri Lanka, and others.
    3. Chair: India currently chairs the grouping.
    4. 30th Anniversary Summit: Expected in 2027.

    What is the significance of the Indian Ocean Rim Association (IORA)?

    1. Regional Cooperation: Strengthens collaboration among 23 member states across the Indian Ocean littoral.
    2. Security Coordination: Facilitates dialogue on maritime safety, disaster response, and blue economy.
    3. Economic Integration: Supports trade, fisheries, tourism, and investment partnerships.
    4. Diplomatic Platform: Provides India a regional forum distinct from SAARC, BIMSTEC, and QUAD.
    5. Strategic Relevance: Enhances India’s role as a net security provider in the Indian Ocean.

    What are the major areas of cooperation under IORA?

    1. Maritime Safety: Strengthens regional response against piracy, trafficking, and maritime crime.
    2. Trade and Investment: Facilitates economic connectivity and regional commerce.
    3. Blue Economy: Supports sustainable fisheries, marine resources, and ocean-based economic activities.
    4. Disaster Risk Management: Enhances preparedness against cyclones, tsunamis, and coastal disasters.
    5. Tourism and Cultural Exchange: Encourages people-to-people linkages and regional cooperation.
    6. Women’s Economic Empowerment: Strengthens inclusive economic participation.

    What challenges limit the effectiveness of IORA?

    1. Institutional Weakness: Lacks enforcement mechanisms compared to stronger regional organisations.
    2. Geopolitical Rivalries: Competing interests among regional powers limit consensus.
    3. Limited Security Role: Functions primarily as a consultative platform rather than a defence grouping.
    4. Unequal Priorities: Member states possess different economic and security concerns.
    5. Fragmented Regionalism: Overlap with organisations such as BIMSTEC, ASEAN, QUAD, and IONS reduces cohesion.

    Why has maritime security become a critical concern in the Indian Ocean Region?

    1. Energy Security: Ensures uninterrupted supply of crude oil and LNG imports. India imports nearly 85% of its crude oil, much of which transits through the Indian Ocean.
      1. The region facilitates the transit of roughly 25% of global maritime oil trade.
    2. Trade Dependence: Facilitates movement of global commerce. Nearly 95% of India’s trade by volume and 68% by value moves through maritime routes.
    3. Strategic Chokepoints: Increases vulnerability due to disruptions near the Strait of Hormuz, Bab-el-Mandeb, and Malacca Strait, affecting shipping and insurance costs.
    4. Regional Livelihoods: Supports fisheries and coastal economies. Prolonged conflict affects fishermen’s livelihoods and food security.
    5. Inflationary Pressures: Raises fuel and logistics costs. Shipping disruptions increase prices of fertilizers, fuel, and food commodities.

    How has the West Asian conflict altered the maritime security architecture of the IOR?

    1. Red Sea Disruptions: Intensifies risks to global shipping due to attacks on vessels in strategic maritime routes.
      1. Operational Shifts: Major carriers like Maersk initially diverted most traffic around Africa’s Cape of Good Hope, a move that added 3,500 nautical miles and 10-14 days to transit.
      2. Spillover Events: In a striking expansion of the conflict, the U.S. sank the Iranian frigate IRIS Dena near Sri Lanka in March 2026, proving that “distance is no shield” from West Asian tensions.
    2. Hormuz Vulnerability: Creates uncertainty over oil transportation. Any blockade affects global energy markets.
      1. Supply Impact: The closure disrupted 20% of global oil supplies and nearly all international commercial shipping through the strait starting February 28, 2026.
      2. Price Volatility: Brent crude surged 10-13% to over $80-$82 per barrel within days. Analysts at J.P. Morgan and the IMF warning of potential $100 peaks and significant global inflation risks.
    3. Economic Consequences: Increases freight costs and insurance premiums, affecting regional economies.
      1. Insurance Surge: War-risk premiums for the Strait of Hormuz jumped from 0.2% to as high as 3% of a vessel’s value. For a large oil tanker, this adds tens of crores in cost for a single trip.
      2. Freight Rates: By April 2026, freight rates on Asia-Europe lanes remained 25-40% higher than pre-crisis levels.
    4. Supply Chain Risks: Disrupts movement of fertilizers and agricultural inputs, reducing agricultural productivity.
      1. Fertilizer Crisis: The Strait of Hormuz handles one-third of global seaborne fertilizer trade. Disruptions in 2026 have constricted trade in these inputs, directly threatening food security for IOR nations.
      2. Capacity Squeeze: The diversion around Africa has absorbed 5-7% of global container fleet capacity, creating a global equipment shortage that affects even routes not passing through the conflict zone.
    5. Humanitarian Impact: Limits fishing activity in conflict-prone maritime zones, affecting livelihoods.
      1. New Security Doctrine: In response, India unveiled its Indian Navy Maritime Security Strategy 2026 (INMSS-2026), moving from a defensive posture to a proactive one focused on safeguarding undersea infrastructure and countering hybrid maritime threats.

    How does maritime security align with India’s strategic vision?

    1. SAGAR Doctrine (Security and Growth for All in the Region): Strengthens maritime cooperation and regional stability.
    2. Indo-Pacific Vision: Expands India’s strategic engagement beyond South Asia.
    3. MAHASAGAR Policy: Enhances India’s maritime diplomacy and regional integration.
    4. Act East Policy: Strengthens eastern maritime connectivity.
    5. Defence Partnerships: Expands naval exercises such as MILAN and bilateral maritime cooperation.

    What measures are required to strengthen maritime security in the IOR?

    1. Maritime Domain Awareness: Expands satellite surveillance and information-sharing mechanisms.
    2. Naval Cooperation: Enhances coordinated patrols and joint exercises.
    3. Economic Resilience: Diversifies supply chains and shipping routes.
    4. Institutional Strengthening: Expands operational mandate of IORA.
    5. Blue Economy Governance: Ensures sustainable use of marine resources.

    Conclusion

    Maritime security in the Indian Ocean Region has evolved from a naval concern into a multidimensional economic and geopolitical issue. Regional instability, strategic chokepoints, and supply chain disruptions underline the need for stronger maritime cooperation. India’s leadership in IORA, coupled with its SAGAR vision, positions it as a key stakeholder in ensuring a secure, stable, and inclusive Indian Ocean order.

    PYQ Relevance

    [UPSC 2022] What are the maritime security challenges in India? Discuss the organisational, technical and procedural initiatives taken to improve maritime security

    Linkage: This PYQ directly overlaps with the article’s core theme of maritime security in the Indian Ocean Region (IOR), including threats from geopolitical conflicts, chokepoints, and regional cooperation. It also links to India’s maritime initiatives such as SAGAR, IORA, maritime domain awareness, and naval coordination, which are central to the article.

  • [2nd May 2026] The Hindu OpED: Abu Dhabi exits OPEC for an ascent of ‘peak oil’

    PYQ Relevance[UPSC 2018] The question of India’s Energy Security constitutes the most important part of India’s economic progress. Analyze India’s energy policy cooperation with West Asian Countries.Linkage: The UAE exit reshapes India’s relations with West Asia beyond OPEC framework. It is directly applicable to India-UAE ties, diversification, and long-term energy strategy.

    Mentor’s Comment

    The United Arab Emirates (UAE) formally exited OPEC on May 1, just before the Organization of the Petroleum Exporting Countries (OPEC) meeting, an unprecedented timing that surprised global markets. This marks a sharp shift from earlier years when the UAE only threatened to leave but remained within the cartel. The move comes amid the Strait of Hormuz blockade crisis, which disrupted Gulf oil exports, and reflects growing dissatisfaction with OPEC quota restrictions.

    Why did the UAE decide to exit OPEC despite being a major beneficiary?

    1. Quota Constraints: Limits production to 3.45 mbpd despite capacity expansion. This creates 1.5 mbpd idle capacity. Example: UAE’s grievance against Saudi-led output control
    2. Strategic Autonomy: Prioritizes national interest over cartel discipline; Ensures independent pricing and production decisions
    3. Economic Diversification: Requires higher oil revenues to fund AI, data centers, and post-oil investments. Example: Technology-driven economy push
    4. Geopolitical Assertion: Signals independence from Saudi dominance. Example: UAE distancing from Riyadh’s leadership in OPEC

    How does the concept of ‘Peak Oil Demand’ shape this decision?

    Peak oil demand refers to the point in time when global consumption of oil reaches its highest level and then begins to permanently decline. Unlike the traditional concept of “peak oil” (or peak supply), which suggests the world will run out of oil because it is a finite resource, peak oil demand occurs because consumers and industries stop wanting or needing as much of it.

    1. Demand Transition: Global oil demand approaching plateau; Reduces long-term value of reserves
    2. Revenue Maximisation: Incentivizes faster extraction before demand declines; Ensures monetisation of reserves
    3. Energy Transition Pressure: Accelerates shift to renewables and alternative fuels; Example: EV adoption and climate policies
    4. Short-term Volatility: War-driven oil spikes may destroy demand; Example: Iran war causing unsustainable price surges

    What are the geopolitical dimensions behind UAE’s move?

    1. Strait of Hormuz Crisis: Blockade disrupted exports; Highlighted vulnerability of Gulf oil routes
    2. Pipeline Advantage: Abu Dhabi’s Habshan-Fujairah pipeline bypasses Hormuz; Ensures supply continuity
    3. Saudi-UAE Rift: Growing divergence in political and economic priorities; Example: Competition for regional dominance
    4. Iran Conflict Context: UAE underrepresented in Jeddah diplomacy; Exit seen as assertion of independent foreign policy.

    How does this exit impact OPEC and global oil governance?

    1. Cartel Weakening: Departure of third-largest producer reduces cohesion; Challenges collective price control
    2. Market Fragmentation: Rise of independent producers like USA, Canada, Brazil; Reduces OPEC relevance
    3. Price Volatility: Reduced coordination may increase supply unpredictability; Impacts global markets
    4. Historical Turning Point: UAE becomes first major exit since Qatar (2019); Signals beginning of OPEC decline

    What are the implications for India’s energy security?

    1. Price Advantage: Increased supply competition may reduce oil prices; Benefits import-dependent India
    2. Strategic Partnership: Strengthens India-UAE energy ties; UAE is 4th-largest crude supplier
    3. Investment Opportunities: Encourages upstream investments in India; Enhances energy security
    4. Reduced Cartel Power: Weakens OPEC’s ability to dictate prices; Ends “May Day” shocks for India.

    Conclusion

    The UAE’s exit reflects a transition from cartel-based oil governance to competitive, national energy strategies. It underscores declining OPEC influence, evolving geopolitics, and the urgency of energy transition. The move may accelerate the fragmentation of global oil markets.