💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Economic Growth,LPG,Planning

  • Funds awaited, Govt showpiece deep-tech initiative hits pause

    Why in the News

    The government’s showpiece deep-tech fund has moved from selecting beneficiaries to inviting no new applications, because the money to make fresh offers has not arrived. The Technology Development Board (TDB), a statutory body under the Department of Science and Technology (DST) and the only agency now selecting beneficiaries for the Research, Development and Innovation (RDI) Fund, has stopped inviting applications after this month, citing “administrative reasons”.

    What is the RDI Fund, and why was it created?

    1. What it is: The RDI Fund lends to private firms and start-ups researching sunrise sectors such as quantum, space, robotics and artificial intelligence (AI). It is like a patient loan banks avoid.
    2. Why it was created: The Government set it up in November 2025 to finance technologies seen as crucial for the economy’s growth and strategic independence.
    3. Size and form: It promised Rs 1 lakh crore over six years, largely as low-cost, long-term loans. It sits under the Anusandhan National Research Foundation (ANRF), a statutory body under DST.
    4. Co-funding rule: A soft loan covers up to half of a project’s cost, so the company must raise the rest from non-government sources.
    5. The takeaway: The fund was meant to carry deep-tech firms from research to product, so a pause hits them when private money is scarcest.

    How far has the fund got, and where has it stalled?

    1. Custodian’s role: Only DST, the fund’s administrative custodian, can allot money to the agencies that pick borrowers.
    2. First round: TDB’s Rs 2,000 crore ran out in April, when 22 companies were offered soft loans.
    3. Beneficiaries: Approved firms include space ventures Agnikul Cosmos and GalaxEye, quantum start-up QuNu Labs, and robotics firms ideaForge and EndureAir.
    4. Second round stuck: TDB finalised 13 more firms in August but has not issued their letters of intent, the formal offer that comes before a loan.
    5. Money released: Nearly a year after launch, only the Rs 2,192 crore offered to first round firms has been made available.

    Why is the fund falling behind?

    1. Fund managers: Companies are chosen by agencies called Second Level Fund Managers (SLFMs). TDB and the Biotechnology Industry Research Assistance Council (BIRAC) under the Department of Biotechnology were nominated first.
    2. Delayed private managers: Applications from private SLFMs closed in January and a committee finalised its recommendations in May, yet appointments are still pending.
    3. BIRAC’s tax question: BIRAC, a non-profit company, has not begun selecting firms. Loans can convert into equity (a shareholding) earning taxable dividends, so BIRAC awaits a Finance Ministry tax ruling.
    4. Conflict of interest: An August investigation found 15 first-round recipients had investment ties to seven selection committee members. The members said they had recused themselves from appraising those firms.
    5. Target at risk: Industry expects the six-year target to be missed at this pace.

    Challenges

    1. Single-agency bottleneck: With the Biotechnology Industry Research Assistance Council (BIRAC) idle and no private Second Level Fund Managers (SLFMs), TDB alone picks borrowers, so a funding gap halts the scheme.
    2. Opaque pause: The notice cites only “administrative reasons”, so applicants cannot plan.
    3. Investor-linked selection: Committee members from the investment community can hold stakes in applicants, weakening trust.
    4. Matching capital burden: Early-stage deep-tech start-ups struggle to raise the private half of project cost.

    Way Forward

    1. Scheduled releases: DST should release allocated money to selecting agencies on a fixed schedule tied to approved rounds.
    2. Appoint private SLFMs: DST and ANRF should finalise the recommended private fund managers to spread the selection load.
    3. Tax ruling: The Finance Ministry should settle how loan-to-equity conversion is taxed.
    4. Disclosure norms: ANRF should publish committee members’ interests and recusals for every funding round.

    Conclusion

    The fund’s design is in place, but money and selecting agencies have not kept pace with applicants. Whether DST releases fresh money and private fund managers are appointed once invitations close will show if the flagship lending restarts.

    Key numbers

    1. DST allocation for the fund: Rs 23,000 crore (Rs 3,000 crore in last year’s Budget, Rs 20,000 crore this year).
    2. Applications: over 300 companies applied; about 100 appraised; 35 selected so far.
    3. Private SLFMs expected: 30 to 40 entities.

    Back2Basics: Anusandhan National Research Foundation (ANRF)

    1. Legal basis: Set up under the Anusandhan National Research Foundation Act, 2023.
    2. Mandate: Funds and coordinates research across universities, laboratories and industry.
    3. Governance: Its governing board is chaired by the Prime Minister.
    4. Predecessor: It subsumed the Science and Engineering Research Board (SERB).

    Matching Previous Year Question

    “[2026] In what way(s) does the Vizhinjam International Seaport represent a structural shift in India’s maritime trade and logistics policy? 1. By functioning exclusively as a domestic cargo hub to reduce reliance on coastal shipping and eliminate the need for foreign collaborations. 2. By focusing primarily on passenger cruise tourism and heritage shipping to increase Kerala’s profile as a maritime heritage destination. 3. By leveraging its natural deep draft and strategic location to reduce dependence on foreign trans-shipment ports, enhance revenue retention, and reposition India in regional maritime trade. Select the answer using the code given below: (a) 1 only (b) 1 and 2 (c) 2 and 3 (d) 3 only Answer: D”
  • Growth holds up for now. Inflation clouds outlook

    Why in the News

    Global agencies have raised their full year growth estimates for India to about 7 per cent. The upgrades follow the first quarter Gross Domestic Product (GDP) estimates. Those estimates recorded stronger economic momentum than expected. The same agencies expect that momentum to fade in the second half of the fiscal year. They also project average inflation of 5.1 per cent and a higher policy rate. The growth upgrade therefore arrives with the case for tighter money attached to it.

    Why have the growth forecasts been raised?

    1. Asian Development Bank: The bank now pegs growth at 7 per cent for the year. Its earlier forecast was 6.6 per cent.
    2. S&P Global: The agency forecasts the economy to grow at 7 per cent.
    3. Organisation for Economic Cooperation and Development (OECD): The OECD has raised its projection from 6.3 per cent to 7.1 per cent.
    4. Moody’s: The agency had earlier raised its growth forecast for the year to 7 per cent, up from 6 per cent.

    What is carrying growth in the first half?

    1. Conflict in West Asia: Concerns persist over economic activity being affected by the conflict in West Asia. Growth has held up through those concerns.
    2. Industrial production: The Index of Industrial Production (IIP), a volume measure of output in mining, manufacturing and electricity, grew at 6.3 per cent during April to July. Manufacturing grew at 7 per cent.
    3. Central capital spending: Capital expenditure by the Centre has surged by almost 30 per cent during April to July this year.
    4. Merchandise exports: Goods exports grew at 17.8 per cent during April to August. A weak currency aided that growth.

    Why is the second half expected to be weaker?

    1. Fading tax tailwinds: S&P Global expects growth to ease in the second half of the fiscal year as the tailwinds from sales tax rationalisation and income tax cuts diminish.
    2. Momentum into 2027: The OECD expects momentum to weaken before a gradual recovery takes place in 2027.
    3. Farm sector risk: The farm sector has emerged as a key area of risk. The Asian Development Bank states that an El Nino worse than expected could reduce agricultural output and raise food inflation across the wider region.

    What do the same forecasts imply for monetary policy?

    1. Price pressures: Price pressures are building up in the economy. Expectations of higher interest rates have gained traction.
    2. Inflation path and the policy rate: S&P Global expects inflation to average 5.1 per cent. It expects the Reserve Bank of India (RBI) to raise its policy rate by 25 basis points in the current fiscal year.
    3. A temporary rise in rates: The OECD projects India to raise policy rates temporarily to offset stronger inflationary pressures.
    4. The next decision point: The central bank’s monetary policy committee meets in a few weeks. The growth and inflation dynamics tilt the scales towards tighter policy.

    Conclusion

    Growth readings and price readings are now pointing in opposite directions. The upgrades rest on a first half that the forecasters themselves do not expect to repeat. What remains unsettled is whether output can hold its pace once borrowing costs rise and a poor farm season arrives together. The next monetary policy review is the first place that question gets tested.

    Back2Basics: India’s Inflation Targeting Framework

    1. The target: The government has retained a Consumer Price Index (CPI) inflation target of 4 per cent for the period April 2026 to March 2031.
    2. Legal basis: Section 45ZA of the Reserve Bank of India Act, 1934 requires the target to be reset every five years.
    3. Who sets the rate: A six member monetary policy committee sets the repo rate. The combined Consumer Price Index published by the National Statistical Office is the target measure.
    4. Accountability: A breach of the 2 to 6 per cent tolerance band for three consecutive quarters obliges the RBI to report to the government.

    Matching Previous Year Question

    “[2019, GS3, 10 marks] Do you agree with the view that steady GDP growth and low inflation have left the Indian economy in good shape? Give reasons in support of your arguments.”

  • A homegrown innovation ecosystem is taking root

    A homegrown innovation ecosystem is taking root

    Why in the News

    Three institutional foundations of an innovation economy are advancing together in India for the first time: public research, corporate research and development (R&D), and deep technology entrepreneurship. Technologies that once arrived through imports are increasingly being invented at home, in research institutions, in industry and in startups. Gallium Nitride (GaN) semiconductor technology, critical for advanced radar, space systems and next generation communications, is now being developed domestically in a tightly export controlled field. Affordable immunotherapies developed in India are expanding access to advanced cancer care at the same time. The tension is between volume and value. Patent filings are rising sharply, while the number of patents actually in force, the rate of commercialisation and national R&D spending remain far below those of the economies India is measured against.

    What are the three major institutional pillars shaping India’s emerging innovation ecosystem?

    1. Public Research Institutions: Government-supported institutions conduct foundational and long-gestation research. Eg: DRDO developed indigenous Gallium Nitride (GaN) technology.
    2. Corporate R&D: Private-sector industries increasingly invest in research and development. Eg:Jio Platforms has made significant patent filings in 5G and 6G technologies.
    3. Deep-Tech Entrepreneurship: Startups convert advanced research into commercial applications. Eg:AGNIT Semiconductors is commercialising indigenous GaN technology developed through IISc’s research ecosystem.

    What do the patent and R&D numbers actually show?

    1. Filing growth: Patent filings rose from just over 1,10,000 in 2024-25 to more than 1,43,000 in 2025-26, an increase of 30.2%.
    2. Domestic ownership of filings: Domestic applicants now account for almost seven in ten filings, so the growth is not driven by foreign applicants seeking protection in the Indian market.
    3. Patents in force, which is the real test: Patents in force in India stood at just over 2,40,000 in 2025, against 5.7 million in China, 3.5 million in the United States and 2.1 million in Japan on 2024 data. Patents in force counts rights that were granted and are still being maintained, so a wide gap against filings points to low grant rates, high abandonment, or both.
    4. The spending floor beneath all of it: India spends just under 1% of GDP on research and development, against about 2.4% in China and 3.5% in the United States.

    What is gallium nitride (GaN) and why is it strategic?

    1. What it is: Gallium Nitride is a semiconductor material that handles higher voltage, higher frequency and higher temperature than silicon, which is why it is used where power density and signal strength matter more than cost.
    2. Where it is used: It underpins monolithic microwave integrated circuits (MMICs), the single chip radio frequency circuits inside advanced radar, satellite links and next generation wireless equipment, and it is subject to export control for that reason.

    What does the GaN breakthrough show about the public research pillar?

    1. The breakthrough and where it happened: Scientists of the Defence Research and Development Organisation (DRDO) at the Solid State Physics Laboratory (SSPL) in Delhi and the Gallium Arsenide Enabling Technology Centre (GAETEC) in Hyderabad announced a breakthrough in making GaN MMICs in March 2023.
    2. Why it had to be built at home: The technical know how for these circuits was, by widely reported accounts, refused to India under the offset provisions of the Rafale fighter jet purchase from France.
    3. The club it joined: India is now one of seven countries to have mastered this technology, alongside China, France, Germany, Russia, South Korea and the United States.
    4. Transfer out of defence: DRDO is actively transferring GaN High Electron Mobility Transistor (HEMT) based MMIC technology, a transistor design that carries current through a very thin high mobility layer, for use in 5G and 6G wireless infrastructure, electric vehicle on board chargers and renewable energy inverter systems.
    5. The commercial end of the pipeline: AGNIT Semiconductors, a spin off from the Centre for Nano Science and Engineering (CeNSE) at the Indian Institute of Science, Bengaluru, is translating homegrown GaN technology into commercial applications.

    Is India moving from standard implementer to standard setter?

    1. The alliance and its target: The Bharat 6G Alliance (B6GA) has stated an aim of contributing 10% of global 6G patents by 2030.
    2. The filing base so far: Alliance members have made more than 7,700 patent filings across 5G and 6G technologies, including over 4,400 foreign filings.
    3. The caveat on those numbers: These are applications, not grants, and not declared standard essential patents, which are the patents a technical standard cannot be implemented without and which earn licensing revenue from every implementer.
    4. Participation in the standards body: Indian contributors made almost 3,000 technical contributions to the 3rd Generation Partnership Project (3GPP), the body that writes mobile communication standards, in the last year, a 15 fold increase over 2020.
    5. International filing rank: The World Intellectual Property Organization (WIPO) 2025 Patent Cooperation Treaty (PCT) rankings, which track a single international application route that reserves rights across member countries, placed Jio Platforms Limited 19th overall among international filers, a rise of more than 300 places and its first entry into the top 20.

    What has changed in the startup ecosystem?

    1. The capital commitment behind it: Members of the India Deep Tech Alliance (IDTA) have made deep technology commitments of more than $2.5 billion, alongside the central government’s Research, Development and Innovation (RDI) financing.
    2. Earth observation: Pixxel Space, founded by two alumni of the Birla Institute of Technology and Science, Pilani, has six satellites in orbit in hyperspectral imaging, which captures hundreds of narrow wavelength bands so materials can be identified rather than merely seen, with a full constellation of 18 to 24 planned.
    3. Launch vehicles: Skyroot Aerospace flew the Vikram-1 low earth orbit launch, and the Indian Institute of Technology Madras nurtured Agnikul Cosmos is working toward fully reusable launch vehicles.
    4. Affordable advanced medicine: ImmunoACT, incubated at the Indian Institute of Technology Bombay with the Tata Memorial Centre, developed NexCAR19, India’s first indigenous CAR-T cell therapy, in which a patient’s own immune cells are re engineered to attack cancer cells, delivered at a tenth of typical treatment costs.
    5. Preventable blindness: Bengaluru based Remidio Innovative Solutions, supported at early stage by the Biotechnology Industry Research Assistance Council (BIRAC), screens for diabetic retinopathy and glaucoma through smartphone enabled retinal imaging with artificial intelligence.

    Challenges to India’s homegrown innovation ecosystem

    1. Patent examination capacity: A grant depends on examiner throughput, so filings rising faster than examiner strength lengthen the wait rather than produce enforceable rights. Eg. The Controller General of Patents, Designs and Trade Marks administers patents, designs, trade marks and geographical indications through a single office.
      The Fix: Ring fence recruitment of technically qualified examiners to the patent stream and publish disposal data by technology field.
    2. The cost of keeping a patent in force: A granted patent lapses unless a renewal fee is paid every year, so a holder with no paying customer lets it go. Eg. The Patents Act, 1970 requires renewal fees annually from the third year across the twenty year term.
      The Fix: Defer renewal fees for publicly funded institutions and recognised startups until the patent earns its first revenue.
    3. Non standard transfer terms for publicly funded intellectual property: Each laboratory negotiates its own royalty and exclusivity terms, so a licensee faces a fresh negotiation at every institution. Eg. The Protection and Utilisation of Public Funded Intellectual Property Bill, 2008, drafted to settle exactly those terms, was never enacted.
      The Fix: Issue one standard licensing template with published royalty bands for every publicly funded laboratory.
    4. No public first customer for unproven technology: Procurement rules reward the lowest price and a record of prior supply, which a first time deep technology supplier cannot show. Eg. The Public Procurement (Preference to Make in India) Order, 2017 sets local content thresholds but creates no route for a technology with no supply history.
      The Fix: Reserve a share of ministry procurement for first of a kind indigenous technology with a relaxed prior experience condition.

    Conclusion

    India’s innovation constraint has moved. The question is no longer whether homegrown technology can be created, since a full pipeline from government laboratory to academic institution to commercial venture now exists in at least one strategic field. The open question is whether a right on paper can be turned into a product with a buyer, which is where filings, grants and revenue currently part company. The marker to watch is the share of filings that survive to become patents in force, because that one ratio tests grant capacity, commercial intent and maintenance funding at the same time.

    Government Initiatives for India’s research and innovation ecosystem

    1. Anusandhan National Research Foundation (ANRF): Established under the Anusandhan National Research Foundation Act, 2023 to seed and grow research in universities, colleges and research laboratories, with the larger share of its funding intended to come from non government sources.
    2. Startup India: Launched in 2016 under the Department for Promotion of Industry and Internal Trade, it gives recognised startups tax exemptions, self certification under labour and environment laws, and fast tracked patent examination with fee rebates.
    3. Fund of Funds for Startups: Operated by the Small Industries Development Bank of India (SIDBI), it invests in Alternative Investment Funds rather than in startups directly, so capital reaches ventures through professional fund managers.
    4. Atal Innovation Mission: Runs Atal Tinkering Labs in schools and Atal Incubation Centres in host institutions, working on the supply of innovators rather than on the funding of firms.
    5. Technology Development Board: Set up under the Technology Development Board Act, 1995 to provide loans and equity to companies commercialising indigenous technology.

    Back2Basics: Research, Development and Innovation (RDI) Scheme

    1. What it is: A central financing window for private sector led research in sunrise and strategic sectors, aimed at the stage private capital avoids.
    2. Size: A corpus of Rs 1 lakh crore was approved for it by the Union Cabinet in 2025.
    3. How the money moves: Funds flow through a special purpose fund to second level fund managers, who extend long tenure low or nil interest loans or take equity, rather than paying out direct grants.
    4. Who steers it: It is guided by the Governing Board of the Anusandhan National Research Foundation, so research financing and research promotion sit under one apex structure.

    [2026, GS3, 15] How are startups in India promoting entrepreneurship, innovation and employment? Discuss the global and domestic challenges in their working and suggest suitable measures to overcome these challenges.”

  • Why India must rethink the way it values skills, jobs and productive work

    Why in the News

    India has become the world’s fourth largest economy and is treated as the next engine of global growth. The assessment now placed against that record is that the country is drifting toward the middle income trap, where an economy exhausts its gains from cheap labour and rapid catch up and fails to move to productivity led growth. Weak job creation, stagnant wages, sluggish private investment and low productivity are named as reinforcing one another. Youth protests across the country are read as the visible sign of that distress. The two standard explanations, another round of market reform and a larger public spending push, both treat this as a supply or a demand problem. The argument placed against both is that the binding constraint is institutional, meaning social norms that decide how the market prices skills and how the State allocates resources.

    Why do the standard explanations of the slowdown fall short?

    1. The pro market reading: Economists trained in market orthodoxy call for a second round of reform on the scale of 1991, covering labour flexibility, agricultural reform, deregulation and infrastructure investment.
    2. The Keynesian reading: Economists in the Keynesian tradition locate the problem in weak aggregate demand and prescribe higher public spending, redistribution and social protection.
    3. What both miss: Each treats the constraint as one of supply or of demand. Institutions shaped by social norms decide both how markets set incentives and prices and how the State allocates resources and supplies public goods.

    What does the present pattern of growth look like?

    1. Jobless growth: Productivity gains stay concentrated in narrow capital intensive and skill intensive enclaves that generate little employment.
    2. Weak domestic demand: Private investment remains sluggish, wage growth is stagnant and household consumption is weak.
    3. Manufacturing has not absorbed labour: The sector has failed to generate enough jobs for the workforce moving out of agriculture.
    4. An uneven recovery: Growth after the pandemic favoured large corporations and the digital economy and left the informal sector barely touched.
    5. Inequality and low productivity together: Rising inequality alongside low productivity is the specific combination that makes the trap dangerous, since neither corrects the other.

    How do social norms distort what the market and the State each do?

    1. Competitiveness through cost cutting: Private capital, freer from regulation than at any earlier point, competes by cutting costs rather than by innovating.
    2. Knowledge does not travel: Firms have failed to absorb the knowledge that arrives with foreign direct investment (FDI). Productivity has risen neither through movement between sectors nor through innovation inside them.
    3. Capital is priced below labour: Heavy subsidy to capital lowers its price relative to labour in an economy with surplus labour, which pushes firms toward machines over workers.
    4. Innovation is thin: Research and development spending stands at 0.65% of GDP, and technology adoption remains weak rather than spontaneous.
    5. State capacity is low despite size: Government has grown in size, and the ability to deliver basic services such as health centres and schooling remains among the lowest anywhere.
    6. Spending is tilted toward the privileged: Mass education has been historically underfunded. Higher education for elites was subsidised.
    7. The elite bias carried into the growth pattern: That same bias produced service sector heavy growth after the reforms, letting upper castes monopolise better occupations and relegating low productivity work to others.

    What does India’s vocational training record show?

    1. Almost no formal skilling: Fewer than 3% of the workforce has any formal vocational education.
    2. Seats go unfilled: Roughly 14,000 Industrial Training Institutes (ITI) offer about 25 lakh seats, and actual intake is only about 48%.
    3. Placement is weak even for those who finish: The employment rate among graduates is 63%, against over 90% in many other countries.
    4. The system is badly run: Vocational training remains poorly managed and chronically underfunded, which follows from the long neglect of mass education.

    Why does the social valuation of skills decide productivity?

    1. Useful knowledge drives modern growth: Sustained growth rests on the coevolution of science, technology and the spread of “useful knowledge”, meaning the practical skills that let a society innovate, adapt and raise productivity. Eg. The economic historian Joel Mokyr, a Nobel laureate in economics, treats the diffusion of such knowledge as the taproot of entrepreneurial success.
    2. India privileged the abstract: University degrees command prestige. Courses training electricians, welders, machinists and carpenters do not.
    3. The hierarchy has a source: That ranking reflects centuries of caste based occupational stratification in which manual and artisanal work was systematically undervalued despite its role in industrial development.
    4. The visible result: Skilled manufacturing workers are chronically short even as millions of educated young people fail to find decent work.
    5. Valuation shapes choices before markets do: Social premiums attached to some occupations, visible in the marriage market, shape educational choices and occupational aspirations and therefore the allocation of labour.
    6. Official advice runs against the norm: The Chief Economic Adviser has urged young people to take up trades such as welding and plumbing rather than software jobs or management degrees.
    7. Labour intensity is falling: Data show a persistent decline in the labour intensity of production technology across sectors, including traditionally labour intensive ones, and artificial intelligence is expected to accelerate the trend.

    What separates the countries that escaped the trap from those that did not?

    1. South Korea: Escape came from building institutions capable of creating and diffusing useful knowledge across domains, not from building factories alone.
    2. China: Early state led industrialisation was paired with large investment in technical education, local manufacturing capability and technological learning, and earlier interventions in education and health laid the productive base.
    3. Brazil, Argentina, Thailand and the Philippines: All four failed to build or sustain such institutions and remain stuck in the middle income trap.
    4. The shared symptom of failure: In those four, as in India, large sections of the population depend on public transfers and handouts for the basic requirements of a decent living.

    What does productivism propose instead?

    1. The core shift: Productivism, proposed by the economist Dani Rodrik, moves policy attention from redistribution after the fact to the creation of productive employment.
    2. Where it parts from market orthodoxy: It gives government a leading role over markets in shaping economic opportunity rather than leaving that to prices alone.
    3. Its stated priorities: It places the real economy above finance, jobs above redistribution and production above consumption.
    4. Dignity as an economic output: An inclusive economy on this reading gives people social recognition as productive members of society, which requires changing the norms underpinning institutions rather than only the policy framework.

    Challenges to escaping the middle income trap

    1. Industrial policy without skilled labour stalls: Incentives for manufacturing cannot be used if the plants receiving them cannot staff skilled lines. Eg. Electronics units in India remain concentrated in final assembly rather than component fabrication.
      The Fix: Tie incentive disbursement to verified apprenticeship and skilling numbers at the receiving plant.
    2. Training is disconnected from employers: Curricula and equipment in public training institutes lag the technology used on the shop floor, so a certificate does not signal usable skill. Eg. Many public institutes still train on machine tools several generations behind those in contract manufacturing plants.
      The Fix: Give industry associations a decisive voice in course content and equipment upgrades at each institute, with annual revision.
    3. Skilling is measured as enrolment, not as employment: Targets reward seats filled and certificates issued rather than wages earned afterwards. Eg. Short duration certification under national skilling programmes has repeatedly recorded low conversion into formal jobs.
      The Fix: Shift reporting to wage outcomes after training, tracked through provident fund records.
    4. Cheap capital keeps displacing labour: Accelerated depreciation, concessional credit and duty exemptions lower the effective price of machinery against workers, so firms automate ahead of demand. Eg. Garment units have moved to automated cutting and spreading, with employment in the sector staying flat.
      The Fix: Rebalance the incentive structure toward employment linked support rather than capital linked support.
    5. State capacity limits the very services the strategy needs: Schooling and primary health are the inputs into a productive workforce and are delivered most thinly where they are needed most. Eg. Teacher and doctor vacancies persist across the districts with the youngest populations.
      The Fix: Fill sanctioned posts in the lowest performing districts first rather than distributing recruitment evenly.

    Conclusion

    The diagnosis places the binding constraint outside the familiar argument about how much the State should spend and how far markets should be freed. What follows from it is that a skilling target or a manufacturing incentive will not move productivity for as long as the social ranking of occupations stays where it is. The difficulty is that a norm of that kind is not amenable to a budget line or a notification. Whether policy can change the standing of skilled manual work, and not only its supply, is what decides where the economy settles.

    Back2Basics: Industrial Training Institutes

    1. What they are: Post school vocational institutions that train candidates in designated trades such as fitter, electrician, welder and machinist.
    2. Who runs them: They function under the Directorate General of Training in the Ministry of Skill Development and Entrepreneurship, and are set up by State governments and by private promoters.
    3. The qualification awarded: Trainees who clear the All India Trade Test receive the National Trade Certificate.
    4. Statutory anchor: Trade training and apprenticeship in these institutes operate within the framework of the Apprentices Act, 1961.

    Matching Previous Year Question

    “[2022, GS3, 15 marks] “Economic growth in the recent past has been led by increase in labour productivity.”Explain this statement. Suggest the growth pattern that will lead to creation of more jobs without compromising labour productivity.”

  • Economy weathered West Asia shock. Now, reform for sustained growth (Op-ed by Sajjid Chinoy)

    Why in the News

    India’s gross domestic product (GDP) growth for the last quarter is expected to print close to 8 per cent, defying fears that the West Asia conflict had dented the economy. This follows a joint fiscal, monetary and regulatory stimulus through 2025, direct tax cuts, a Goods and Services Tax (GST) rationalisation, and an effective 150 basis point policy rate cut, combined with a swift diversification of energy imports during the conflict. The pickup is largely cyclical, and the investment rate, corporate capital expenditure (capex) and structural export and employment growth remain too weak to sustain the expansion once the stimulus fades.

    What explains India’s growth resilience through the West Asia conflict?

    1. A joint stimulus in 2025: Direct taxes were cut in February, GST was rationalised in September, and policy rates were cut by an effective 150 basis points along with regulatory easing in the financial sector.
    2. Non-oil export acceleration: Exports have picked up on the back of a near 15 per cent depreciation of the real effective exchange rate (REER), the trade weighted, inflation adjusted value of the rupee against a basket of currencies, since 2025, a reduction in United States tariffs, and resilient global growth.
    3. Swift energy diversification: India sourced crude from Russia and liquefied natural gas from the United States and Oman to prevent shortages, importing 17 per cent more energy than normal last quarter, while the government absorbed the bulk of the oil price shock through the fisc to insulate the private sector.

    Why does India’s investment rate remain a structural concern?

    1. Fixed investment stagnant: Fixed investment remains near its decadal average of 32 per cent of GDP and has not lifted despite rising public investment and real estate capex.
    2. Corporate capex has not picked up: Corporate capex continues to languish around 10 to 11 per cent of GDP, and balance sheets of the top 1,000 listed companies show no discernible pickup in 2025-26.
    3. Central capex is slowing: Central capex grew 30 per cent between 2020 and 2023, then slowed to 11 per cent in 2024 and just 1.6 per cent in 2025, as tax cuts absorbed fiscal space.
    4. State capex under pressure: Cash transfers on demand are pushing state capex growth below nominal GDP growth.
    5. Weak demand visibility: Capacity utilisation has stayed in the 75 to 76 per cent range for a decade, and rising Chinese overcapacity is discouraging corporate investment.

    Why are consumption and export growth not yet structural?

    1. Weaker growth than the earlier export led cycle: Post-pandemic private consumption and exports grew at about 5 per cent, against the 16 per cent export growth between 2003 and 2012 that had crowded in private capex.
    2. Service export growth has halved: Service export growth in nominal dollars has fallen to 8 per cent over the last year from 16 per cent over the previous four years, and employment across major IT firms has stayed flat.
    3. Employment mix is shifting toward self-employment: The Periodic Labour Force Survey shows India’s employment rate rising, but a significant share of new jobs are self-employed rather than salaried, even as the mix improved in 2025.
    4. Consumption is credit fuelled: Non-Banking Financial Company lending to households is growing at 20 per cent and unsecured personal lending momentum has risen to 25 per cent, on the back of rising household leverage.

    What must change for the growth cycle to become structural?

    1. Labour must become more competitive against capital: India’s capital-labour ratio has risen for over two decades, and reversing this needs education, skilling and health investment, alongside rationalising labour laws that raise the cost of labour.
    2. Exports need structural competitiveness: Goods exports have fallen from 17 per cent of GDP a decade ago to 11 per cent, and further gains need tariffs and non-tariff barriers rationalised and overregulation reduced.
    3. Private capex is the real crowding-in mechanism: Structurally higher consumption and exports are what would draw in a sustained private capex cycle, which in turn would crowd in foreign direct investment and stabilise the balance of payments.

    Conclusion

    The current cyclical strength, backed by clean corporate and financial balance sheets and a sustained agricultural surplus, is a bridge over the West Asia shock, not a destination. Unless investment, exports and employment turn structural, the growth cycle will not sustain once the fiscal and monetary stimulus fades, and the piece warns there is little time left to act given global automation, trade fragmentation and a fraying international order.

    Matching Previous Year Question

    No direct PYQ traced in the provided files.

  • Investment question has a political answer

    Why in the News

    Private corporate investment in India remains considerably lower than the peak seen in the mid 2000s, even as large corporates hold substantial cash. Firms are deploying funds in financial assets rather than building physical assets such as factories, and are taking money out of the country rather than investing it here. The standard explanations offered for this are subdued domestic demand and global uncertainty. A political economy explanation is now advanced instead, locating the cause in how political power structures affect investment decisions. Centralisation of political power has been unmistakable after 2014, accompanied by fiscal centralisation and a reconfiguration of federal structures. The contested claim is that market concentration around a handful of “national champions” is not an accident of policy but is politically useful, which would make an investment revival costly to the current political settlement.

    What are “national champions”?

    1. Definition: A national champion is a large domestic business group that a government treats as the preferred vehicle for building strategic capacity, and that is favoured in policy design as a result.
    2. How the status is conferred: Preference operates through the terms of auctions, tariffs, incentive eligibility, clearances and access to public contracts rather than through an announced designation.
    3. The economic consequence: A handful of such groups now command far greater sway over the economy than before, which raises the entry barrier facing any firm attempting to compete with them.

    What does the investment slowdown actually look like?

    1. Cash-rich firms are not building: Large corporates hold funds but are not committing them to new capacity in India.
    2. Capital is leaving: Companies are taking money out of the country rather than investing it domestically.
    3. Investment is below its own peak: Private corporate investment remains considerably lower than the level reached in the mid 2000s.
    4. Financial assets over physical assets: Corporate India is more keen to deploy funds in financial assets than to use them for factories and plant.
    5. The standard explanations are incomplete: Subdued domestic demand and global uncertainty have been put forward, and neither accounts for why firms with the means to invest choose not to.

    Why does the concentration of political and market power deter private investment?

    1. Political and fiscal centralisation: Centralisation of political power after 2014 has been accompanied by greater fiscal centralisation and a reconfiguration of federal structures, including attempts to restrict the powers of states and, as a consequence, of regional parties. Eg. The Mines and Minerals (Development and Regulation) Amendment Act, 2026, amending the 1957 law under which the State owns the mineral and signs the lease while the Centre sets the rules and the royalty rate.
    2. Market concentration has moved in step: The rise of a handful of large companies, aided by policy, has given them far greater sway over the economy than ever before.
    3. One, patronage for smaller firms has dried up: The concentration of political power and the decline in the relative power of regional parties has ended the patronage and protection that were afforded to smaller and regional firms, who could rise up and become national players.
    4. Two, policy uncertainty and an uneven playing field: Higher barriers to entry and terms tilted towards larger corporates make it harder for new players to emerge, and firms will not invest if they fear the rules of the game can be arbitrarily changed or that they can be caught on the wrong side of policies. Policy credibility is what is at stake.
    5. Three, the fear of being muscled out: Investors fear that business success will be met by a hostile takeover by a national champion, so the question is not whether they are allowed to operate but whether they can stay in business and remain competitive over the next 10 to 20 years.

    Why would dispersing economic power be politically costly?

    1. Competition requires a rethink of the strategy: For the larger corporate sector to ramp up investment and for competition to emerge, the strategy of relying on a few national champions needs to be reconsidered.
    2. Dispersed economic power funds political opposition: A larger number of big private players would disperse rather than concentrate economic power, which would in turn increase the funding avenues available to Opposition parties.
    3. Economic competition feeds political competition: Weakening the concentration of economic power would possibly weaken the concentration of political power, so greater economic competition could lead to greater political competition.
    4. The two open questions: It is unsettled whether the current political structure creates the space for new players to safely invest and emerge as competitors to the national champions, or whether market concentration is itself politically useful.

    Why do the ingredients of an investment boom not produce one?

    1. The macroeconomic conditions are present: An undervalued exchange rate, depressed real wages and sustained public sector investment in infrastructure are all in place, alongside the demographic dividend.
    2. The same mix powered East Asia: This combination powered the rise of countries such as China and South Korea, where firms responded to it with large capacity additions.
    3. India’s firms are not responding: Firms are likely to remain hesitant and unsure about investing without a change in the approach, despite those conditions.
    4. Confidence, not capability, is binding: Investment decisions are taken only when investors think they have a fair chance of benefiting from them.
    5. The end state if nothing changes: The consequent absence of competition raises the possibility of an uncompetitive, high-cost economy.

    Challenges to the national champions strategy

    1. Concentration raises consumer and input costs: Dominant firms in a sector face little pressure to hold prices down, which raises costs for every downstream user. Eg. Telecom tariffs rose sharply after the sector consolidated into three private operators. Fix. Use the deal value threshold introduced by the Competition (Amendment) Act, 2023 to review acquisitions that current turnover tests miss.
    2. Policy-created advantage is hard to withdraw: Once a group builds capacity on the strength of an incentive, removing the incentive becomes a shock the government is reluctant to deliver. Eg. Most approved incentive under the Production Linked Incentive scheme for large-scale electronics manufacturing has flowed to a small group of mobile phone assemblers. Fix. Publish sunset dates and firm-level disbursement data with each incentive scheme so withdrawal is scheduled rather than negotiated.
    3. Concentrated bank exposure transmits firm risk to the system: Lending concentrated in a few large groups converts a single group’s distress into a banking problem. Eg. The corporate loan losses that produced the non-performing asset build-up of the 2010s were concentrated in a handful of infrastructure and metals groups. Fix. Enforce large exposure limits at group rather than borrower level and publish group-wise banking exposure.
    4. Bidding rules can favour incumbents: Net worth, prior experience and bank guarantee conditions in auctions and tenders can exclude new entrants before price is considered. Eg. Critical mineral block auctions have repeatedly failed for want of qualified bidders. Fix. Set qualification thresholds proportionate to block or contract size and allow consortium bidding for first-time entrants.
    5. Competition enforcement is slow relative to market speed: Investigations concluded years after conduct occurs cannot restore a market that has already tipped. Eg. Appeals against Competition Commission of India orders routinely run for several years before finality. Fix. Fund a dedicated appellate bench for competition matters with statutory disposal timelines.

    Conclusion

    The reluctance of cash-rich Indian firms to invest is being read as a political economy problem rather than a demand or global uncertainty problem. Concentrated political power, an uneven playing field and the fear of being displaced by a national champion together deny new entrants confidence in a 10 to 20 year horizon. Reversing that requires dispersing economic power, which carries political costs the current settlement has no incentive to accept. What remains unresolved is whether market concentration will be treated as a cost to growth or retained as a political asset.

    Industrial Policy and Private Investment in India

    1. What industrial policy does: It is the set of state interventions that shape which industries expand, through licensing, tariffs, incentives, public investment and ownership rules.
    2. The arc since Independence: The Industrial Policy Resolutions of 1948 and 1956 built a mixed economy with reserved public sector schedules, the licensing regime of the 1960s and 1970s restricted private entry, and the New Industrial Policy of 1991 abolished licensing for most sectors.
    3. India’s scale: Manufacturing contributes around 17 per cent of Gross Domestic Product against a 25 per cent target, and India accounts for about 2.8 per cent of global manufacturing output against China’s roughly 29 per cent.
    4. The current gap: Weak domestic private capital formation persists even as foreign investment rises, with cumulative Foreign Direct Investment crossing about $1.14 trillion between April 2000 and December 2025.

    Laws Governing Industry and Competition in India

    1. Industries (Development and Regulation) Act, 1951: The parent law for central regulation of scheduled industries, and the statutory basis of the industrial licensing regime.
    2. Monopolies and Restrictive Trade Practices Act, 1969: Regulated large business houses through asset thresholds to prevent economic concentration, and was repealed after those thresholds were removed post-1991.
    3. Competition Act, 2002: Replaced the 1969 Act, prohibits anti-competitive agreements and abuse of dominance, and establishes the Competition Commission of India to regulate combinations.
    4. Competition (Amendment) Act, 2023: Introduces a deal value threshold for merger review, a settlement and commitment framework, and shorter approval timelines.

    Government Initiatives for Industry and Investment

    1. Make in India (2014): Aims to raise manufacturing’s share of Gross Domestic Product towards 25 per cent, largely through ease of doing business measures.
    2. Production Linked Incentive scheme (2020): Covers 14 sunrise and strategic sectors with outcome-linked financial incentives paid on incremental output.
    3. National Manufacturing Mission: Announced in the 2025-26 Budget, targeting a 25 per cent Gross Domestic Product share and 143 million jobs by 2035, with a focus on solar photovoltaics, electric vehicle batteries, green hydrogen and wind.
    4. National Single Window System: Consolidates central and state clearances into a single application interface for investors.
    5. Invest India: The dedicated investment facilitation agency created after the Foreign Investment Promotion Board was abolished in 2017.

    Challenges in Industrial Policy and Private Investment

    1. Logistics and infrastructure costs: Power, transport and cluster gaps raise the operating cost of a new plant and lengthen its payback period. Eg. Logistics costs remain close to 8 per cent of Gross Domestic Product. Fix. Front-load the National Infrastructure Pipeline in states with the weakest evacuation and port connectivity.
    2. Land acquisition risk: Title complexity and local resistance delay projects long enough to destroy their business case. Eg. The POSCO steel project in Odisha was shelved after prolonged land disputes. Fix. Build titled and pre-cleared land banks with plug-and-play utilities before inviting investment.
    3. Tariff and trade shocks: External trade measures can remove an export market after capacity has been built for it. Eg. The 50 per cent United States tariff imposed in August 2025 hit roughly 55 per cent of India’s United States-bound exports. Fix. Diversify market access through trade agreements and deepen participation in global value chains.
    4. Workforce readiness for Industry 4.0: Adopting automation and artificial intelligence systems requires reskilling at a scale current training capacity cannot deliver. Eg. Only about 4.7 per cent of India’s workforce has formal skill training, against roughly 96 per cent in South Korea. Fix. Fund employer-led reskilling through the re-skilling fund created under the Industrial Relations Code, 2020.
    5. Import dependence in strategic inputs: Heavy reliance on imported electronics, semiconductors and pharmaceutical inputs exposes downstream manufacturers to supply shocks. Eg. Electronics assembly in India depends on imported display and chip components. Fix. Extend performance-linked incentives to component and materials manufacture rather than final assembly alone.

    Matching Previous Year Question

    “[2025, GS3, 15 marks] Discuss the rationale of the Production Linked Incentive (PLI) scheme. What are its achievements? In what way can the functioning and outcomes of the scheme be improved?”

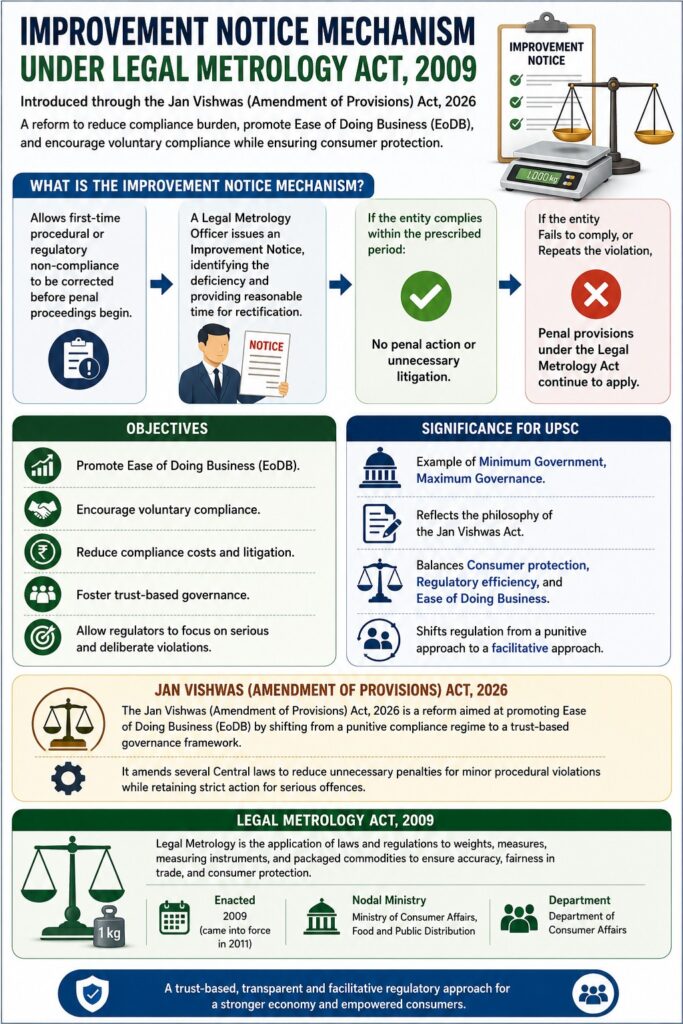
  • Government Introduces Improvement Notice Mechanism under the Legal Metrology Act

    Why in the news?

    The Department of Consumer Affairs has introduced the Improvement Notice mechanism under the Legal Metrology Act, 2009 through the Jan Vishwas (Amendment of Provisions) Act, 2026. The reform aims to reduce the compliance burden, promote Ease of Doing Business (EoDB), and encourage voluntary compliance while ensuring consumer protection.

    What is the Improvement Notice Mechanism?

    • It allows first-time procedural or regulatory non-compliance to be corrected before penal proceedings begin.
    • A Legal Metrology Officer issues an Improvement Notice, identifying the deficiency and providing reasonable time for rectification.
    • If the entity complies within the prescribed period:
      • No penal action or unnecessary litigation.
    • If the entity Fails to comply, or Repeats the violation, Penal provisions under the Legal Metrology Act continue to apply.

    Objectives

    • Promote Ease of Doing Business (EoDB).
    • Encourage voluntary compliance.
    • Reduce compliance costs and litigation.
    • Foster trust-based governance.
    • Allow regulators to focus on serious and deliberate violations.

    Significance for UPSC

    • Example of Minimum Government, Maximum Governance.
    • Reflects the philosophy of the Jan Vishwas Act.
    • Balances Consumer protection, Regulatory efficiency, and Ease of Doing Business
    • Shifts regulation from a punitive approach to a facilitative approach.

    Jan Vishwas (Amendment of Provisions) Act, 2026

    • The Jan Vishwas (Amendment of Provisions) Act, 2026 is a reform aimed at promoting Ease of Doing Business (EoDB) by shifting from a punitive compliance regime to a trust-based governance framework.
    • It amends several Central laws to reduce unnecessary penalties for minor procedural violations while retaining strict action for serious offences.

    Legal Metrology Act, 2009

    • Legal Metrology is the application of laws and regulations to weights, measures, measuring instruments, and packaged commodities to ensure accuracy, fairness in trade, and consumer protection.
    • Enacted: 2009 (came into force in 2011)
    • Nodal Ministry: Ministry of Consumer Affairs, Food and Public Distribution
    • Department: Department of Consumer Affairs

    [2022] In India which one of the following is responsible for maintaining for prices stability by controlling inflation?

    [A] Department of Consumer Affairs

    [B] Expenditure Management Commission

    [C] Financial Stability and Development Council

    [D] Reserve Bank of India

  • “Economic growth in the recent past has been led by increase in labour productivity.”Explain this statement. Suggest the growth pattern that will lead to creation of more jobs without compromising labour productivity.

    With 7% growth in 2025-26, India is one of the fastest-growing major economies and a bright spot on the global economy (IMF). A major driver of this performance has been the expansion in labour activity.

    Economic growth attributed to labour activity

    Demographic dividend – Median age of 28 and 65% working-age population (65%) has increased labour supply and productive capacity.

    Shift towards labour-intensive sectors: Growth in construction, retail, transportation, tourism, gig and platform economy

    Surge in self-employment – from 52% (2017) to 58% in 2024 (PLFS data)

    The government’s skilling push through Kaushal Vikas Yojana and the Skill India Mission improved workforce capabilities.

    India becoming the 3rd largest start-up ecosystem has generated new entrepreneurship-led employment.

    Rise of gig economy- Platform-based work has widened job opportunities.

    Labour Code reforms- consolidation of labour laws has improved hiring flexibility and EoDB.

    Other reasons

    GST reforms

    Ease of Doing Business reforms

    IBC

    PLI schemes

    However, this growth pattern is problematic due to

    Low productivity trap: Most new jobs are in informal, low-wage, low-productivity sectors.

    Disguised employment rising: Higher labour supply masks underemployment.

    Limited wage growth: High labour participation has not translated into better wages.

    Structural transformation incomplete: Manufacturing’s share in jobs and GDP remains stagnant.

    Suggested Growth Pattern to Create More Jobs Without Compromising Productivity

    Manufacturing-led, technology-enabled growth

    Expand labour-intensive manufacturing such as textiles, toys, leather, electronics assembly. Eg: PLI schemes for electronics, textiles.

    Use AI, robotics, lean production to improve productivity while expanding scale.

    MSME upgradation – Enable cluster-based development, digitalisation, easier credit. Eg: MSME Champions Scheme, ONDC for market linkages

    Skill-based job creation through programs like Skill India, PMKVY 4.0.

    Boost food processing, millets, horticulture, and FPO-based value chains.

    Employment in solar manufacturing, EV ecosystem, recycling, energy efficiency can raise both jobs and productivity.

    Strengthen urban employment ecosystems – Invest in urban infrastructure, housing, logistics, and city industrial clusters.

    Improve FLFPR through childcare support, flexible work, safety, and skilling.

    India’s recent growth has been driven more by labour mobilisation than by labour productivity. A shift towards manufacturing-led, technology-driven, and green growth is essential for Viksit Bharat 2047.