💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Economics

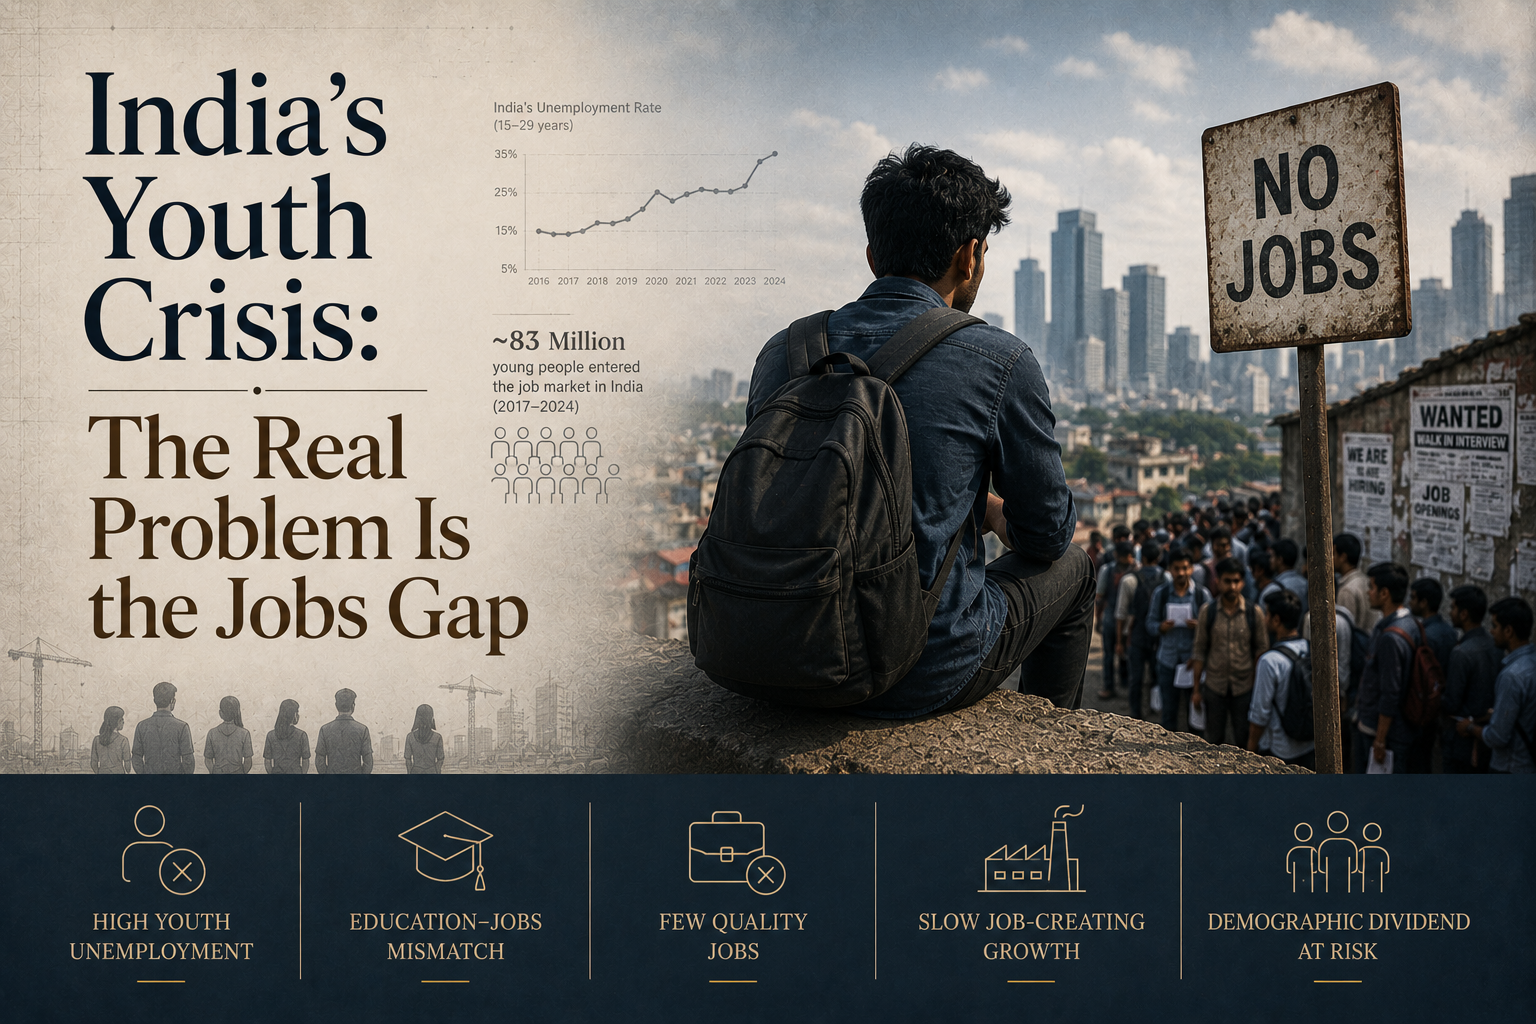
  • India’s youth crisis is about the absence of jobs, not just examination reform

    India’s youth crisis is about the absence of jobs, not just examination reform

    Question (2023, GS3): Most of the unemployment in India is structural in nature. Examine the methodology adopted to compute unemployment in the country and suggest improvements.
    Linkage: The editorial contends that youth agitations and demand for cheaper coaching address only the symptoms of the crisis, whereas the foundational issue is structural unemployment—the deep-seated absence of final job opportunities for qualified youths at the end of their preparation.

    Mentor comment

    The Hindu’s editorial argues that India’s youth unemployment problem is a jobs crisis, not merely an examination reform problem. The youth agitation that forced the resignation of the then Union Education Minister produced a government commitment to examination reform, including free online coaching for competitive examinations using India’s Digital Public Infrastructure. The editorial contends that cheaper coaching addresses only the preparation stage of the crisis, while the deeper problem is the absence of jobs at the end of that preparation.

    What does the data show about the scale of the crisis?

    1. Coaching costs have risen, not fallen: Private coaching now costs 16% of what an average Indian family spends on a child’s education, up from 12.5% in 2018. Nearly a quarter of that spending occurs during the higher secondary years, when students prepare for competitive examinations.
    2. Seat scarcity dwarfs coaching costs: Over 22 lakh candidates appeared for this year’s medical entrance examination for about 1.4 lakh undergraduate seats, with fewer than 10,000 of those seats at the top 50 colleges. The Joint Entrance Examination for engineering colleges shows a similar pattern.
    3. Undergraduate enrolment has fallen for the first time: For the first time since the All India Survey on Higher Education began in 2011, undergraduate enrolment fell by 93,322 in 2023-24, sharpest among young men.
    4. The fall is regionally concentrated: Uttar Pradesh recorded the steepest decline, with undergraduate enrolment down 1.53 lakh even as diploma enrolment rose 1.38 lakh, suggesting students are substituting away from degrees that do not lead to jobs.
    5. Formal, secure jobs remain rare among graduates: Periodic Labour Force Survey unit level data shows that of every 100 graduates aged 15 to 29 in 2025, only 26 held regular salaried employment, and only four held a salaried job with both a contract and social security.

    Why has growth not translated into jobs?

    1. Manufacturing has not absorbed graduates: Manufacturing, the sector best placed to absorb India’s college graduates, remains at around a sixth of gross value added, well short of the quarter of the economy the government has long promised.
    2. Private investment has retreated: Corporate investment fell from 17.3% of GDP in 2007-08 to 10.3% in 2024-25, unmoved by the cut in the corporate tax rate from 30% to 22% in 2019.
    3. Regulatory enforcement has turned selective: The editorial states that a regulatory and enforcement zeal that selectively targets enterprises has disproportionately affected medium sized companies, the segment best placed to generate jobs.

    Conclusion

    The youth employment crisis has two distinct ends: preparation for jobs, and the jobs themselves. Free coaching addresses only the first. The editorial’s position is that public investment in industrial capacity, export-disciplined industrial support, and a less selective regulatory posture toward medium sized enterprises would do more for youth employment than examination reform alone, citing Vietnam as a comparator that has used this route.

  • The fact is youth unemployment has a household cost

    Why in the News

    Periodic Labour Force Survey (PLFS) 2025 data records youth unemployment at 14.8 percent and a Not in Employment, Education or Training (NEET) rate of 40.1 percent among the tertiary-educated, and the argument advanced from this data is that graduate joblessness is a household-level economic cost, not only an individual setback. A young person’s inability to find work does not only reduce that person’s own income, it removes an income the household had budgeted around, often after the household had itself financed the degree that produced no job.

    What is the household cost, distinct from the individual one?

    1. Sunk cost of financing the degree: Households that borrow or spend savings to fund a graduate’s education absorb that cost with no return if the graduate cannot find matching work, a loss the individual unemployment rate does not price in.
    2. Deferred contribution to household income: A household budgets around the expectation that an educated young adult will begin contributing income at a certain age; unemployment past that age forces the household to keep supporting a wage-earner it had expected to become a net contributor.
    3. Compounding effect on savings for other dependants: Money a household would have redirected toward a younger sibling’s education, a parent’s healthcare, or retirement savings instead continues to support an unemployed graduate.
    4. Psychological and bargaining costs within the household: Prolonged dependence on parents past the expected age of self-sufficiency affects a young adult’s standing and decision-making power within the household, a dimension PLFS-style employment data cannot itself measure but that the 40.1 percent NEET rate among the tertiary-educated makes newly visible.

    How does the tertiary-educated NEET rate compare with the general NEET pattern?

    1. Tertiary-educated NEET rate far exceeds the general rate: At 40.1 percent, the NEET rate among India’s tertiary-educated youth is markedly higher than the NEET rate among youth without a degree, inverting the usual expectation that more education reduces the risk of disengagement from work.
    2. Concentration in urban, aspirational households: The households most likely to have financed a tertiary degree, and to therefore carry the sunk cost described above, are disproportionately urban and lower-middle income, the segment for whom a graduate’s income was budgeted as a route out of that bracket.

    Conclusion

    Youth unemployment at 14.8 percent and a 40.1 percent NEET rate among the tertiary-educated do not describe an individual labour market outcome alone. They describe a household that financed an investment in education and is not yet receiving the income return it planned around, a cost that persists in household budgets even where it does not appear in an individual’s own unemployment statistic.

    Youth unemployment in India

    1. About: Youth unemployment measures joblessness among the working-age population, typically 15 to 29 years, whose job search outcomes diverge sharply from the adult labour force.
    2. Rationale for tracking it separately: Youth unemployment behaves differently from the aggregate rate because young workers are more likely to be first-time job seekers with no accumulated informal-sector fallback, so a downturn hits them earliest and hardest.
    3. Recognised typology: Unemployment among India’s youth spans frictional joblessness during the transition from education to work, structural joblessness from a skills mismatch, and disguised underemployment in low-productivity family enterprises and agriculture.
    4. Jobless growth in services: Services drive the largest share of GDP growth but employ under 30 percent of the workforce, limiting the sector’s capacity to absorb new entrants.
    5. Skill deficit at graduation: Only about half of India’s graduates are assessed as readily employable, per employability surveys, pointing to a curriculum gap rather than a shortage of degree holders.
    6. Weak manufacturing absorption: Manufacturing contributes only 16 to 18 percent of GDP, well below the roughly 26 percent contribution in China, limiting the formal, labour-intensive job creation India’s youth bulge needs.
    7. Informality as the default outcome: Over 90 percent of India’s workforce remains informal, so even youth who do find work often find it without security, benefits, or a written contract.
    8. Female youth workforce deficit: Caregiving duties, domestic responsibilities, and mobility constraints keep young women out of paid employment at a much higher rate than young men.

    Challenges in addressing youth unemployment

    1. Survey methodology undercounts informal and gig work: PLFS-style surveys do not fully capture home-based, gig, or platform work within India’s overwhelmingly informal workforce. Eg. Platform-based delivery and ride-hailing work is not consistently classified in the survey’s job categories. Fix. Update survey instruments to explicitly capture gig, platform, and digital work categories, aligned with International Labour Organization and System of National Accounts definitions.
    2. Low-frequency rural data delays policy response: Rural employment data has historically been measured only annually, compared with quarterly urban estimates, masking rural distress in real time. Eg. A poor monsoon’s effect on rural non-farm employment often does not show up in national data until the following year’s release. Fix. Extend the quarterly PLFS survey design to rural areas at the same frequency as urban areas.
    3. Capital-intensive investment bias: Investment continues to flow toward capital-intensive sectors such as information technology and infrastructure rather than the labour-intensive sectors that absorb semi-skilled youth. Eg. Automation in manufacturing has reduced the labour intensity of new capacity even as output has grown. Fix. Direct production-linked incentives toward labour-intensive sectors such as textiles, leather, and food processing, alongside the existing electronics-focused schemes.
    4. Demographic dividend at risk of becoming a demographic trap: A youth bulge that cannot find work stops being an economic asset and starts becoming a fiscal and social liability as the cohort ages without having built savings or skills. Eg. State of Working India 2026 estimates 9.2 crore youth in the NEET category nationally. Fix. Expand the government’s employment-linked incentive schemes and apprenticeship mandates specifically targeted at the 21 to 29 age cohort.
    5. Weak coordination across employment data systems: Employees’ Provident Fund Organisation payroll data, the National Career Service portal, and PLFS survey data are not integrated, making it hard to track whether a given policy intervention is actually creating net new jobs. Eg. The Employment Linked Incentive scheme announced in 2025 tracks payroll additions but not whether they represent new jobs or reclassified existing ones. Fix. Build a single integrated employment data dashboard drawing on EPFO, NCS and PLFS data for real-time tracking.

    Back2Basics: NEET (Not in Employment, Education or Training)

    1. An internationally used labour-market indicator that counts young people who are neither working, studying, nor undergoing any training, distinct from the unemployment rate, which only counts those actively seeking work.
    2. Captures discouraged job seekers and those who have withdrawn from the labour force entirely, a population the standard unemployment rate does not measure.
    3. The State of Working India 2026 report estimates roughly 9.2 crore Indian youth in this category.

    Matching Previous Year Question

    “[2023, GS3, 15 marks] Most of the unemployment in India is structural in nature. Examine the methodology adopted to compute unemployment in the country and suggest improvements.”

  • The other ‘NEET’ that India needs to address

    Why in the News

    Fresh Periodic Labour Force Survey (PLFS) data on the Usual Employment and Unemployment Rate shows nearly 40 percent of Indian graduates aged 25 are unemployed, alongside an estimated 9.2 crore Indian youth falling into the Not in Employment, Education or Training (NEET) category. The State of Working India 2026 report situates this alongside India’s demographic dividend, the working-age population bulge the country has counted on as a growth advantage. A youth cohort large enough to drive growth is instead showing a graduate unemployment rate high enough to raise doubts about whether that dividend is being converted into productive work.

    What does the NEET measure capture that the unemployment rate does not?

    1. NEET counts withdrawal, not just joblessness: The unemployment rate only counts people actively seeking work; NEET (Not in Employment, Education or Training) also captures young people who have stopped searching or never entered education or the labour force, a group the standard unemployment rate misses entirely.
    2. 9.2 crore youth estimated in the NEET category: The State of Working India 2026 report’s estimate of 9.2 crore places the scale of youth disengagement well above what headline unemployment figures alone would suggest.
    3. Graduate unemployment concentrated among the young: Nearly 40 percent of 25-year-old graduates are unemployed, a rate far higher than unemployment among the working-age population as a whole, showing that a degree has not translated into a job for this cohort at the pace the labour market absorbs less-educated job seekers.
    4. Gender skew within the NEET population: Young women make up a disproportionate share of the NEET category, reflecting caregiving responsibilities and mobility constraints that keep them out of both education and paid work even when jobs exist locally.

    Why does graduate unemployment run higher than overall unemployment?

    1. Skill mismatch between degrees and job requirements: Employers report that a large share of graduates are not employable in the roles the formal sector is creating, because curricula have not kept pace with industry requirements.
    2. Weak absorption capacity in manufacturing: Manufacturing’s share of GDP has stayed well below the level needed to absorb a growing pool of educated job seekers into formal, better-paid work, pushing graduates toward informal or underemployed roles instead.
    3. Aspirational mismatch with available jobs: A graduate degree raises the reservation wage and the kind of work a job seeker will accept, so graduates wait longer for a suitable formal-sector opening rather than take the informal work a non-graduate would accept immediately.
    4. Delayed labour market entry compounds the count: Prolonged job searches by graduates keep them in the unemployed count for longer than less-educated job seekers, who exit into informal work faster even at lower wages.

    Conclusion

    The NEET count of 9.2 crore and the near-40 percent graduate unemployment rate among 25-year-olds point to a mismatch between what India’s education system produces and what its labour market currently absorbs. Closing that gap over the remaining years of India’s demographic dividend, rather than after it starts to narrow, is the reform window the data points to.

    Back2Basics: Periodic Labour Force Survey

    1. Conducted by the National Sample Survey Office (NSSO) under the Ministry of Statistics and Programme Implementation, the principal source of employment and unemployment data in India.
    2. Uses the Usual Status approach, based on a person’s activity over the preceding 365 days, alongside the Current Weekly Status approach for more recent snapshots.
    3. Was redesigned to provide quarterly urban estimates in addition to the earlier annual survey, though rural high-frequency coverage remains thinner.
    4. Feeds the official Unemployment Rate and Worker Population Ratio figures cited in Parliament and used for policy design.

    Matching Previous Year Question

    “[2023, GS3, 15 marks] Most of the unemployment in India is structural in nature. Examine the methodology adopted to compute unemployment in the country and suggest improvements.”

  • Did Press Note 3 relaxations help attract more FDI?

    Why in the News

    The government’s March 2026 relaxation of Press Note 3 (2020) now allows the automatic route for foreign investors from land-border-sharing countries where the resulting stake is below 10 percent. Press Note 3 (2020) had required prior government approval for any foreign direct investment from an entity based in, or beneficially owned by, a country sharing a land border with India, a restriction imposed after India’s border tensions with China. Since the relaxation, 29 Foreign Direct Investment (FDI) projects together worth ₹4,895.65 crore have been reported as raised through the automatic route. The scale of that inflow is now being tested against whether it represents genuine new investment or capital that was already structured to qualify.

    What is Press Note 3 and why was it imposed?

    1. Origin in 2020 border tensions: The Department for Promotion of Industry and Internal Trade issued Press Note 3 in April 2020 requiring government approval for FDI from any country sharing a land border with India, a category that in practice targets China.
    2. Stated rationale of opportunistic acquisition: The measure was framed as a safeguard against opportunistic takeovers of Indian companies whose valuations had fallen sharply during the COVID-19 pandemic.
    3. No de minimis threshold in the original rule: The 2020 version applied government-approval scrutiny regardless of the size of the resulting stake, so even a marginal shareholding increase by an investor linked to a bordering country required clearance.
    4. Applied to beneficial ownership, not just direct investment: The restriction reaches an investment structured through a third country if the ultimate beneficial owner is based in a bordering country, closing a routing loophole.

    What has the March 2026 relaxation changed?

    1. Automatic route restored below a 10 percent threshold: Investment from a bordering-country-linked entity resulting in a stake below 10 percent in the Indian company no longer requires prior government approval.
    2. Retains approval requirement above the threshold: Any investment crossing the 10 percent stake mark, or any greenfield or strategic-sector investment, continues to require case-by-case government clearance.
    3. 29 projects reported since relaxation: ₹4,895.65 crore in FDI has been reported as raised through the automatic route across 29 projects since the relaxation took effect.

    Did the relaxation actually attract more FDI?

    1. Reported inflow is modest against India’s total FDI base: ₹4,895.65 crore is a small fraction of India’s annual FDI inflow, so a Press Note 3 relaxation limited to sub-10 percent stakes has not shifted aggregate FDI in a way that will show clearly in headline balance-of-payments data.
    2. The 10 percent cap limits which capital responds: A relaxation confined below the threshold attracts portfolio-style minority stakes rather than the strategic or controlling investment that would signal deeper industrial commitment.
    3. Difficult to isolate the relaxation’s own effect: FDI flows respond to multiple factors simultaneously, including global interest rates and India’s own growth outlook, making it hard to attribute the 29 reported projects solely to the policy change.
    4. Sectoral destination of the reported inflow remains the open question: Whether the ₹4,895.65 crore has gone into manufacturing capacity or into financial and services stakes shapes how much the relaxation has actually served its stated industrial goal.

    Conclusion

    The Press Note 3 relaxation has produced a measurable but modest reported inflow, ₹4,895.65 crore across 29 projects, since March 2026. Whether this represents a genuine widening of investor participation from land-border-sharing countries or capital that was already positioned to enter below the new threshold will become clearer as more reporting cycles pass.

    Back2Basics: Press Note 3 (2020)

    1. Issued by the Department for Promotion of Industry and Internal Trade under the Foreign Direct Investment policy framework, not a standalone statute.
    2. Requires government approval for FDI from, or beneficial ownership traced to, any country sharing a land border with India: China, Pakistan, Bangladesh, Nepal, Bhutan, Myanmar, and Afghanistan.
    3. Applies to both fresh investment and a change in beneficial ownership of an existing investment resulting from a transfer.
    4. Enforced through the Reserve Bank of India’s foreign exchange reporting framework under the Foreign Exchange Management Act, 1999.

    Matching Previous Year Question

    “[2022] Which one of the following situations best reflects “Indirect Transfers” often talked about in media recently with reference to India ?
    (a) An Indian company investing in a foreign enterprise and paying taxes to the foreign country on the profits arising out of its investment
    (b) A foreign company investing in India and paying taxes to the country of its base on the profits arising out of its investment
    (c) An Indian company purchases tangible assets in a foreign country and sells such assets after their value increases and transfers the proceeds to India
    (d) A foreign company transfers shares and such shares derive their substantial value from assets located in India
    ANSWER: (d)”

  • How the Supreme Court ruling redefined ‘industry’

    Why in the News

    A nine-judge Constitution Bench of the Supreme Court revisited the definition of “industry” laid down in Bangalore Water Supply and Sewerage Board v. A. Rajappa (1978), examining how that definition interacts with the term “industry” as newly defined under the Industrial Relations Code, 2020. The 1978 ruling had given “industry” a wide, functional definition covering any organised activity involving cooperation between employer and employee for producing goods or services, regardless of profit motive. The Industrial Relations Code, 2020 narrows this definition by carving out specific exclusions. The Bench’s majority and minority opinions diverge on whether Parliament’s narrower statutory definition can override the Bangalore Water Supply test for constitutional purposes.

    What did the Bangalore Water Supply test originally hold?

    1. Triple test for “industry”: The 1978 ruling held that any activity involving systematic cooperation between an employer and workers to produce or distribute goods or services qualifies as an industry, irrespective of whether the entity is charitable, religious, sovereign, or run by the government.
    2. Sovereign function exception, narrowly read: The 1978 Bench exempted only inalienable sovereign functions of the State, such as legislation, defence, and the administration of justice, from the definition.
    3. Wide coverage of welfare and professional bodies: The test brought hospitals, educational institutions, and clubs employing staff within the definition of “industry,” extending industrial-dispute protections to their employees.
    4. Persistent legislative attempts to narrow it: Parliament had earlier attempted to codify a narrower definition through an amendment that was never brought into force, leaving the 1978 test operative for over four decades.

    What does the Industrial Relations Code, 2020 change?

    1. Statutory definition narrows the exclusions: The Industrial Relations Code, 2020 (the law consolidating the Trade Unions Act 1926, the Industrial Employment (Standing Orders) Act 1946 and the Industrial Disputes Act 1947 into a single code) defines “industry” with specific carve-outs for institutions engaged in charitable, social, or philanthropic services not for profit.
    2. Government departments performing sovereign functions excluded: The Code writes into statute an exclusion for departments discharging sovereign functions, aligning more closely with a narrower reading than the 1978 test.
    3. Domestic and hospital work carved out selectively: The Code excludes certain categories, such as purely domestic service, while leaving other categories, including some hospitals, to be decided case by case.

    Where do the majority and minority views diverge?

    1. Majority view on legislative competence: The majority holds that Parliament may legislatively define “industry” for the purposes of a labour statute, and that a narrower statutory definition prevails over the judicially evolved 1978 test within the Code’s own field of operation.
    2. Minority view on protective intent: The minority holds that a legislative narrowing of “industry” risks excluding workers in charitable, educational, and welfare institutions from industrial-dispute protections that the 1978 Bench extended to them.
    3. Divergence on precedent’s continuing force: The majority treats Bangalore Water Supply as persuasive but non-binding once Parliament legislates a definition, while the minority treats it as continuing to bind interpretation of undefined terms outside the Code’s specific carve-outs.

    Conclusion

    The ruling settles, for now, that Parliament’s statutory definition of “industry” under the Industrial Relations Code, 2020 governs disputes falling within the Code, narrowing the wide protective sweep the Bangalore Water Supply test had given workers across charitable, educational and welfare institutions for over four decades. Litigation over which specific institutions fall inside or outside the Code’s carve-outs is expected to continue as the Code is implemented.

    Back2Basics: Industrial Relations Code, 2020

    1. One of the four labour codes consolidating 29 central labour laws, this one merging the Trade Unions Act, 1926, the Industrial Employment (Standing Orders) Act, 1946, and the Industrial Disputes Act, 1947.
    2. Raises the threshold for prior government permission before layoffs, retrenchment or closure from 100 to 300 workers in an establishment.
    3. Introduces a statutory recognition mechanism for trade unions and a two-member negotiating council where no single union has majority membership.
    4. Notified but implemented in phases, with States framing their own rules under it.

    Matching Previous Year Question

    “[2024, GS3, 15 marks] Discuss the merits and demerits of the four ‘Labour Codes’ in the context of labour market reforms in India. What has been the progress so far in this regard?”

  • Centre plans to cap number of airports a single bidder can win in next privatisation round

    Why in the News

    The Ministry of Civil Aviation plans to cap the number of airports a single private bidder can win in the third round of airport privatisation. The round covers 11 airports grouped into five bundles: Amritsar-Kangra, Varanasi-Gaya-Kushinagar, Bhubaneswar-Hubballi, Raipur-Aurangabad, and Tiruchirapalli-Tirupati. The first two privatisation rounds concentrated a large share of India’s privatised airport traffic in two private groups. The cap sets up a tension between preventing bidder concentration and keeping the auction attractive to the handful of infrastructure players with the balance sheet to run an airport.

    What does the third privatisation round cover?

    1. Bundled bidding across five circuits: The Airports Authority of India (AAI) (the statutory body that owns, manages and privatises Indian civil airports) has grouped the 11 airports into five bundles rather than auctioning each separately, so a bidder wins or loses an entire regional cluster in one bid.
    2. Mix of trunk and regional airports: The bundles combine a higher-traffic anchor airport with smaller regional airports, so an operator absorbs a loss-making regional airport as part of winning the more viable one.
    3. Continuation of the Public-Private Partnership route: The round extends the Operation, Management and Development Agreement (OMDA) (the concession contract structure under which AAI leases an airport’s operations to a private developer for a fixed term while retaining ownership) model used in the first two rounds.
    4. Follows two prior privatisation rounds: Six airports were privatised in the first round and further airports in the second, before this third round was structured.

    Why is the Centre capping bidder concentration?

    1. Two private groups dominate the privatised airport map: One conglomerate operates several of India’s highest-traffic privatised airports won across the earlier rounds, while a second group holds a smaller cluster, leaving few large private operators outside these two.
    2. Concentration weakens the Centre’s post-award leverage: Where one bidder holds most privatised capacity, AAI has fewer credible alternative operators to discipline service standards or renegotiate terms.
    3. A cap widens the bidder base for smaller circuits: Limiting how many bundles a single group can win is intended to draw in operators who would otherwise not bid against an incumbent with deeper resources.
    4. Precedent from other infrastructure sectors: Sector regulators in ports and telecom have used similar concentration limits to prevent a single operator from controlling bottleneck infrastructure across regions.

    Challenges to the airport bidder cap

    1. Fewer bidders may qualify at all: Airport concessions require large upfront capital and aviation operating experience, a pool already limited to a handful of Indian infrastructure conglomerates. Eg. Only two or three consortia bid seriously in each of the first two rounds. Fix. Allow joint ventures and foreign strategic partners to combine capital and aviation expertise so more consortia can qualify.
    2. Regional airports could go unsold: A bundle pairing a loss-making regional airport with a viable one may see no bidder if the cap forces bidders away from the bundles they actually want. Eg. Kushinagar and Gaya carry limited passenger traffic and depend on the Varanasi bundle for viability. Fix. Offer viability gap funding for the weaker airport in each bundle rather than relying on cross-subsidy alone.
    3. Cap design risks being circumvented through related entities: A promoter group can bid through separate subsidiaries or affiliates that appear unconnected on paper. Eg. Beneficial-ownership opacity has complicated concentration limits in the telecom spectrum auctions. Fix. Define the cap by ultimate beneficial ownership, not by the bidding entity’s name.
    4. Slower privatisation pace: Restricting the largest, most capable bidders could stretch out the time needed to complete the round, delaying the capacity upgrades the smaller airports need.
    5. Revenue realisation may fall: A cap that keeps the highest bidder from taking every bundle it wants could produce lower aggregate concession fees than an uncapped auction would.

    Conclusion

    The Ministry of Civil Aviation is finalising the bidding norms for the third privatisation round, with the airport-count cap intended to correct the concentration that followed the first two rounds. The bid documents for the five bundles are expected to be released once the cap’s exact threshold is settled.

    Back2Basics: Airports Authority of India

    1. Statutory body under the Ministry of Civil Aviation, constituted under the Airports Authority of India Act, 1994.
    2. Owns, develops, and manages the majority of India’s civil airports, and leases select airports to private operators through the OMDA route.
    3. Also provides air navigation services across Indian airspace, a function it retains even at privatised airports.
    4. Earns revenue from aeronautical and non-aeronautical charges at the airports it directly operates.

    Matching Previous Year Question

    “[2024, GS3, 15 marks] What is the need for expanding the regional air connectivity in India? In this context, discuss the government’s UDAN Scheme and its achievements.”

  • Investment question has a political answer

    Investment question has a political answer

    Why in the News

    Private corporate investment in India remains considerably lower than the peak seen in the mid 2000s, even as large corporates hold substantial cash. Firms are deploying funds in financial assets rather than building physical assets such as factories, and are taking money out of the country rather than investing it here. The standard explanations offered for this are subdued domestic demand and global uncertainty. A political economy explanation is now advanced instead, locating the cause in how political power structures affect investment decisions. Centralisation of political power has been unmistakable after 2014, accompanied by fiscal centralisation and a reconfiguration of federal structures. The contested claim is that market concentration around a handful of “national champions” is not an accident of policy but is politically useful, which would make an investment revival costly to the current political settlement.

    What are “national champions”?

    • Definition: A national champion is a large domestic business group that a government treats as the preferred vehicle for building strategic capacity, and that is favoured in policy design as a result.
    • How the status is conferred: Preference operates through the terms of auctions, tariffs, incentive eligibility, clearances and access to public contracts rather than through an announced designation.
    • The economic consequence: A handful of such groups now command far greater sway over the economy than before, which raises the entry barrier facing any firm attempting to compete with them.

    What does the investment slowdown actually look like?

    • Cash-rich firms are not building: Large corporates hold funds but are not committing them to new capacity in India.
    • Capital is leaving: Companies are taking money out of the country rather than investing it domestically.
    • Investment is below its own peak: Private corporate investment remains considerably lower than the level reached in the mid 2000s.
    • Financial assets over physical assets: Corporate India is more keen to deploy funds in financial assets than to use them for factories and plant.
    • The standard explanations are incomplete: Subdued domestic demand and global uncertainty have been put forward, and neither accounts for why firms with the means to invest choose not to.

    Why does the concentration of political and market power deter private investment?

    • Political and fiscal centralisation: Centralisation of political power after 2014 has been accompanied by greater fiscal centralisation and a reconfiguration of federal structures, including attempts to restrict the powers of states and, as a consequence, of regional parties. Eg. The Mines and Minerals (Development and Regulation) Amendment Act, 2026, amending the 1957 law under which the State owns the mineral and signs the lease while the Centre sets the rules and the royalty rate.
    • Market concentration has moved in step: The rise of a handful of large companies, aided by policy, has given them far greater sway over the economy than ever before.
    • One, patronage for smaller firms has dried up: The concentration of political power and the decline in the relative power of regional parties has ended the patronage and protection that were afforded to smaller and regional firms, who could rise up and become national players.
    • Two, policy uncertainty and an uneven playing field: Higher barriers to entry and terms tilted towards larger corporates make it harder for new players to emerge, and firms will not invest if they fear the rules of the game can be arbitrarily changed or that they can be caught on the wrong side of policies. Policy credibility is what is at stake.
    • Three, the fear of being muscled out: Investors fear that business success will be met by a hostile takeover by a national champion, so the question is not whether they are allowed to operate but whether they can stay in business and remain competitive over the next 10 to 20 years.

    Why would dispersing economic power be politically costly?

    • Competition requires a rethink of the strategy: For the larger corporate sector to ramp up investment and for competition to emerge, the strategy of relying on a few national champions needs to be reconsidered.
    • Dispersed economic power funds political opposition: A larger number of big private players would disperse rather than concentrate economic power, which would in turn increase the funding avenues available to Opposition parties.
    • Economic competition feeds political competition: Weakening the concentration of economic power would possibly weaken the concentration of political power, so greater economic competition could lead to greater political competition.
    • The two open questions: It is unsettled whether the current political structure creates the space for new players to safely invest and emerge as competitors to the national champions, or whether market concentration is itself politically useful.

    Why do the ingredients of an investment boom not produce one?

    • The macroeconomic conditions are present: An undervalued exchange rate, depressed real wages and sustained public sector investment in infrastructure are all in place, alongside the demographic dividend.
    • The same mix powered East Asia: This combination powered the rise of countries such as China and South Korea, where firms responded to it with large capacity additions.
    • India’s firms are not responding: Firms are likely to remain hesitant and unsure about investing without a change in the approach, despite those conditions.
    • Confidence, not capability, is binding: Investment decisions are taken only when investors think they have a fair chance of benefiting from them.
    • The end state if nothing changes: The consequent absence of competition raises the possibility of an uncompetitive, high-cost economy.

    Challenges to the national champions strategy

    • Concentration raises consumer and input costs: Dominant firms in a sector face little pressure to hold prices down, which raises costs for every downstream user. Eg. Telecom tariffs rose sharply after the sector consolidated into three private operators. Fix. Use the deal value threshold introduced by the Competition (Amendment) Act, 2023 to review acquisitions that current turnover tests miss.
    • Policy-created advantage is hard to withdraw: Once a group builds capacity on the strength of an incentive, removing the incentive becomes a shock the government is reluctant to deliver. Eg. Most approved incentive under the Production Linked Incentive scheme for large-scale electronics manufacturing has flowed to a small group of mobile phone assemblers. Fix. Publish sunset dates and firm-level disbursement data with each incentive scheme so withdrawal is scheduled rather than negotiated.
    • Concentrated bank exposure transmits firm risk to the system: Lending concentrated in a few large groups converts a single group’s distress into a banking problem. Eg. The corporate loan losses that produced the non-performing asset build-up of the 2010s were concentrated in a handful of infrastructure and metals groups. Fix. Enforce large exposure limits at group rather than borrower level and publish group-wise banking exposure.
    • Bidding rules can favour incumbents: Net worth, prior experience and bank guarantee conditions in auctions and tenders can exclude new entrants before price is considered. Eg. Critical mineral block auctions have repeatedly failed for want of qualified bidders. Fix. Set qualification thresholds proportionate to block or contract size and allow consortium bidding for first-time entrants.
    • Competition enforcement is slow relative to market speed: Investigations concluded years after conduct occurs cannot restore a market that has already tipped. Eg. Appeals against Competition Commission of India orders routinely run for several years before finality. Fix. Fund a dedicated appellate bench for competition matters with statutory disposal timelines.

    Conclusion

    The reluctance of cash-rich Indian firms to invest is being read as a political economy problem rather than a demand or global uncertainty problem. Concentrated political power, an uneven playing field and the fear of being displaced by a national champion together deny new entrants confidence in a 10 to 20 year horizon. Reversing that requires dispersing economic power, which carries political costs the current settlement has no incentive to accept. What remains unresolved is whether market concentration will be treated as a cost to growth or retained as a political asset.

  • [24th August 2026] The Hindu OpED: Core concerns

    [24th August 2026] The Hindu OpED: Core concerns

    Question (2017, GS3): ““Industrial growth rate has lagged behind in the overall growth of Gross-Domestic-Product (GDP) in the post-reform period” Give reasons. How far the recent changes is Industrial Policy are capable of increasing the industrial growth rate?
    Linkage: The easing of the Manufacturing PMI to its lowest level since August 2021 due to weak domestic demand is a classic real-time symptom of industrial growth lagging behind overall economic expansion. It forces candidates to examine why Indian manufacturing struggles to maintain sustained momentum.

    Mentor Comment

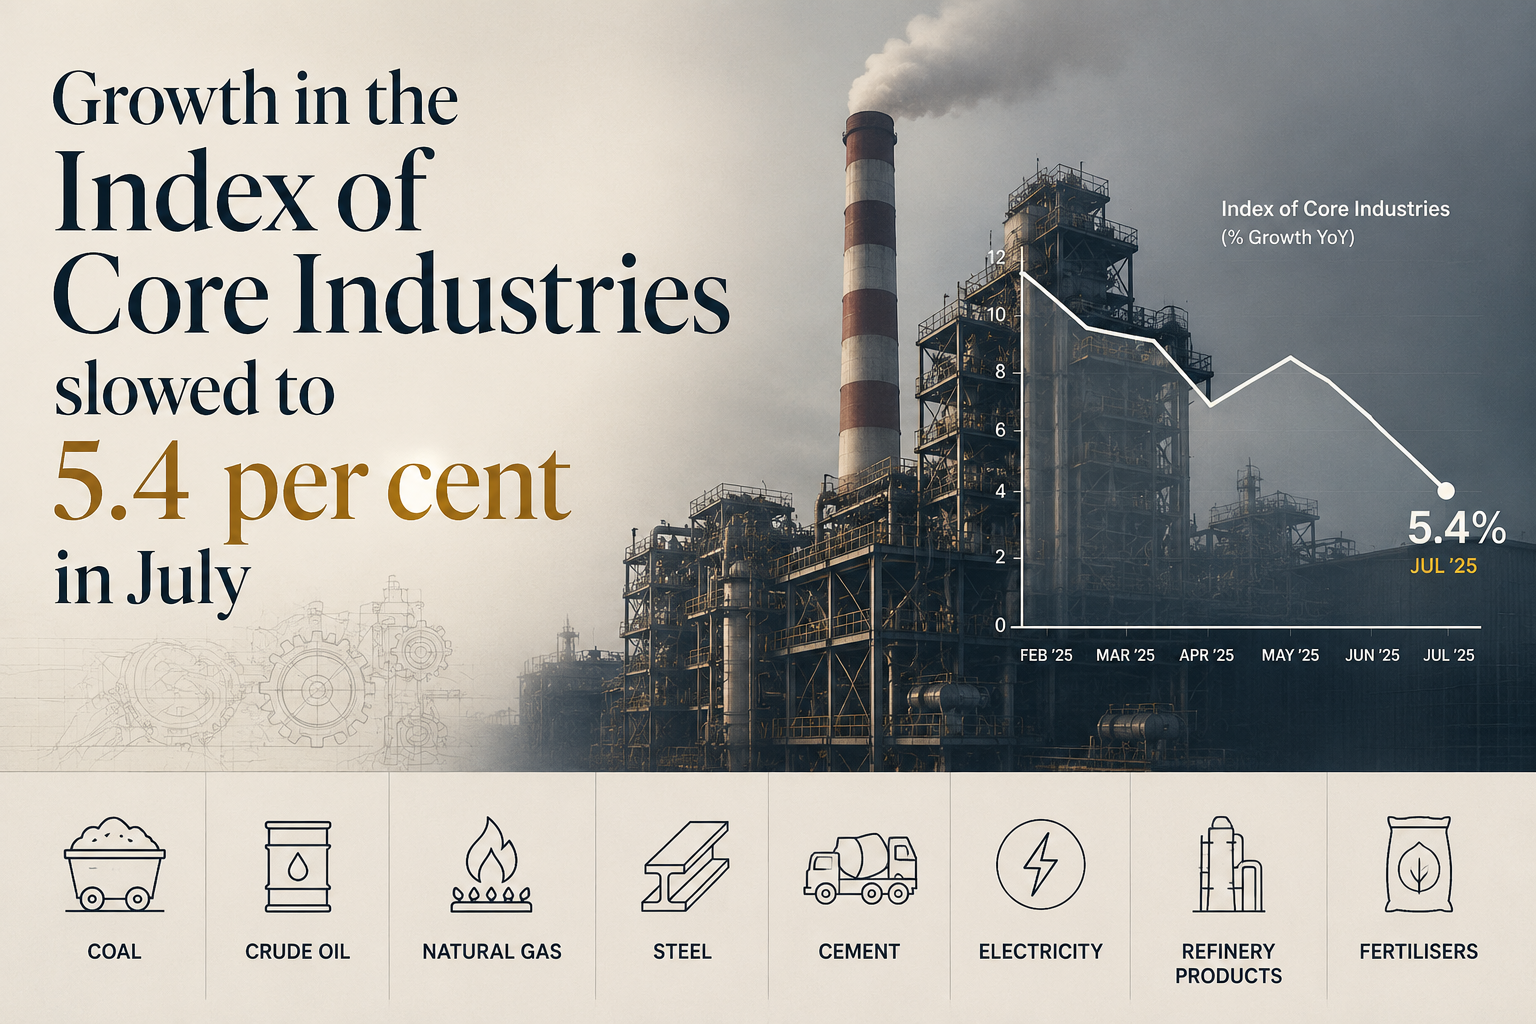
    Growth in the Index of Core Industries slowed to 5.4 per cent in July from 6 per cent in the previous month. The Manufacturing Purchasing Managers’ Index eased in the same month to its lowest level since August 2021, on weak domestic demand conditions. July’s core sector growth was still the second highest rate in the last seven months. The tension sits between that headline and its composition: a large part of the growth rests on a statistical low base effect, the two genuinely strong sectors are cement and electricity, and the domestic crude oil and natural gas sectors have contracted continuously for at least the last 14 months.

    What is the Index of Core Industries?

    • What it measures: The Index of Core Industries measures the combined production of the country’s core infrastructure industries, covering coal, crude oil, natural gas, refinery products, fertilisers, steel, cement and electricity.
    • Why it is watched: These industries carried a combined weight of about 40 per cent in the Index of Industrial Production, so the core index acts as an early read on industrial output before the fuller index is released.
    • Current series: The index is compiled on a revised new series, for which comparable data currently extends back only about 14 months.

    Why is the July core sector number weaker than it looks?

    • Growth rests on a low base: A large part of even this slower growth is based on a statistical low base effect, where a contraction in the corresponding month of the previous year makes the current month’s output look like expansion.
    • Coal illustrates the effect: The coal sector grew at an 11 month high of 7.6 per cent in July. That was measured against a contraction of 12.3 per cent in July of last year.
    • Refinery products repeat the pattern: The refinery products sector snapped a three month streak of contraction to grow at 2.7 per cent. This too was measured against a contraction in July 2025.
    • Iron ore’s strength is partly base driven: The iron ore sector grew at 29.5 per cent, slower than 44.5 per cent in June. Its comparison base is contractions of 16.4 per cent in June and 7.1 per cent in July of last year.
    • The headline flatters the trend: A rate that is second highest in seven months coexists with an easing demand signal, which means the ranking of the number matters less than what produced it.

    Which sectors are carrying the index and which are dragging it?

    • Steel has slowed sharply: The steel sector decelerated to 2.9 per cent in July from 5.6 per cent in June and 15.7 per cent in July of last year. This is a genuine slowdown rather than a base effect.
    • Hydrocarbons are a standing drag: The domestic crude oil and natural gas sectors have contracted continuously for at least the last 14 months for which the new series has data.
    • Electricity remains strong but is decelerating: The electricity sector grew at 9 per cent in July. That was slower than two consecutive months of double digit growth in May and June, which were lifted by prevalent heatwave conditions in many parts of the country.
    • Cement accelerated: The cement sector sped up to 13.1 per cent, the clearest genuine acceleration in the index.
    • The bright spots are only two: Within the core index, cement and electricity were the only two sectors reading as bright spots, and such positive trends were few and far between.

    Does the core sector number describe output or demand?

    • The two indicators point in opposite directions: The core index recorded its second highest growth in seven months in the same month that the Manufacturing Purchasing Managers’ Index fell to its lowest since August 2021.
    • They measure different things: The core index counts physical production in a set of infrastructure industries. The Manufacturing Purchasing Managers’ Index records what purchasing managers report about new orders and demand conditions.
    • A base effect can mask a contraction: A sector recovering from a deep fall registers a high growth rate at a low level of output, so a rate can rise even as demand conditions ease.
    • Weather and construction are not demand: The strongest readings came from electricity, lifted by heatwave conditions, and from cement, which tracks construction activity rather than broad consumer demand.
    • The forward reading is slack: Easing demand conditions were already being predicted by other indicators before the core sector data appeared, so the July slowdown was not a surprise.

    How is energy import dependence turning into a cost shock?

    • Import volumes are rising: India’s crude oil imports rose 13.3 per cent in volume terms in July. Liquefied Natural Gas (LNG) imports grew a more marginal 1.5 per cent.
    • Domestic supply is not filling the gap: Against the falling domestic base noted above, the economy’s appetite is being met from abroad rather than from home production.
    • The bill has jumped: High oil prices meant the crude oil import bill jumped 41 per cent in July, so a 13.3 per cent volume rise translated into a far larger payment outgo.
    • A tariff shock is queued behind it: The 100 per cent tariffs the United States is preparing to levy on countries such as India that import Russian oil will once again burden Indian exporters.
    • Blending has not yet displaced imports: Moving to 20 per cent ethanol blending has not yet impacted oil imports materially, so the substitution effect is not visible in the July numbers.

    Challenges to the Index of Core Industries as a growth signal

    • Base effects distort the headline rate: A contraction in the year ago month converts a modest recovery into a high growth print, which misleads on the level of output. Eg. Coal’s 11 month high of 7.6 per cent in July sat on a 12.3 per cent contraction in July of the previous year. Fix. Publish index levels and two year compound rates alongside the year on year rate in every release.
    • Coverage is narrow: The index tracks a small set of infrastructure industries and therefore misses most of the economy’s output. Eg. Services contribute over half of Gross Value Added and are entirely outside the core index. Fix. Publish the core index alongside a high frequency services activity indicator so the composite reading is visible.
    • Weights favour public sector heavy industries: The largest weights sit in sectors dominated by public enterprises and administered pricing, so the index responds to policy decisions as much as to market demand. Eg. Refinery products and electricity output move with administered allocation and tariff decisions. Fix. Rebase and reweight the index on a fixed cycle with published sensitivity of the headline to each sector’s weight.
    • Informal and small firm output is invisible: Production by micro and small enterprises is not captured, so a squeeze concentrated there does not register. Eg. Of about 64 million micro, small and medium enterprises, only around 14 per cent have access to formal credit and most stay outside statistical registers. Fix. Link the index to Goods and Services Tax e-way bill and electronic invoice data to capture small firm activity.
    • Provisional data is heavily revised: Early estimates are released on partial returns and are revised in later months, so a policy read taken on the first print can reverse. Eg. Iron ore’s July reading of 29.5 per cent followed a June figure of 44.5 per cent, a swing large enough to change the quarterly picture on revision. Fix. Publish a standing revision history for each sector so the reliability of the first print is visible.
    • It reads supply, not demand: The index counts what was produced, not what was bought, so it can rise while orders fall. Eg. July’s core growth of 5.4 per cent coincided with the Manufacturing Purchasing Managers’ Index at its weakest since August 2021. Fix. Present the core index and the demand side survey indicators in a single monthly dashboard rather than as separate releases.

    Conclusion

    The Indian economy looks set for a period of slack demand, higher costs and moderating growth. The July core sector reading does not contradict that: a large part of its growth is base driven, only cement and electricity grew genuinely strongly, and the sectoral spread set out above is narrow. The cost side is worsening independently, on the import bill and the tariff exposure already recorded. Whether the next few months show a genuine industrial recovery depends on domestic demand rather than on the base against which growth is measured.

    Industrial Growth in India

    • Manufacturing’s share is stuck: Manufacturing contributes around 17 per cent of Gross Domestic Product (GDP), far below the 25 per cent target set under Make in India.
    • Global standing: India holds about 2.8 per cent of global manufacturing output against China’s roughly 29 per cent, with domestic manufacturing output nearing $1 trillion in 2025-26.
    • Concentration: Maharashtra, Gujarat and Tamil Nadu account for about 40 per cent of net value added in manufacturing, and half the States have no operational Special Economic Zone.

    Government Initiatives for Industrial Growth

    • National Manufacturing Mission: Announced in the 2025-26 Budget, it unifies manufacturing policy and targets a 25 per cent GDP share with 143 million jobs by 2035.
    • Production Linked Incentive Scheme: Covers 14 sunrise and strategic sectors with outcome linked incentives, drawing over ₹1.76 lakh crore in committed investment as of March 2025.
    • Semiconductor Mission: A ₹76,000 crore framework under which 10 projects worth about ₹1.60 lakh crore have been approved.
    • Industrial Corridors Programme: India approved 11 corridors covering 32 projects, with 12 new industrial nodes cleared in 2024 for plug and play industrial cities.

    Challenges in Industrial Growth

    • Compliance load falls on small firms: Micro, small and medium enterprises face over 1,450 annual compliances, which consumes management time that would otherwise go into expansion. Eg. Annual compliance costs for such firms run to ₹13 lakh to ₹17 lakh. Fix. Adopt third party certification in place of repeat inspections, as the Ajay Shankar Committee recommended.
    • Regional concentration leaves capacity idle: Industrial value added clusters in three States, so national incentives do not translate into national capacity. Eg. Half of India’s States have no operational Special Economic Zone. Fix. Weight central incentive disbursal toward States below the national share of net value added.
    • Technology transition is slow in strategic segments: Domestic capability lags in electronics, semiconductors and renewable energy components, which keeps high value assembly abroad. Eg. India remains heavily dependent on imports for semiconductors and advanced electronic components. Fix. Extend Production Linked Incentives to upstream segments such as advanced materials and green hydrogen rather than final assembly alone.
    • Credit does not reach small manufacturers: Formal finance is unavailable to the great majority of small firms, so they cannot fund the fixed capital that raises productivity. Eg. The unmet credit demand of the micro, small and medium enterprise sector is estimated at about ₹20 lakh crore to ₹25 lakh crore. Fix. Expand cash flow based lending against Goods and Services Tax returns rather than collateral based assessment.
    • Trade barriers raise export uncertainty: Tariff action by large markets can remove the price advantage of an entire export segment without notice. Eg. The United States imposed a 50 per cent tariff in August 2025, hitting about 55 per cent of India’s exports to that market. Fix. Deepen global value chain participation through trade agreements and diversify destination markets under a China plus one strategy.
  • Triple test, adrift

    Why in the News

    On 20 August 2026, a nine judge Bench of the Supreme Court of India delivered a judgment on the correctness of the ruling in Bangalore Water Supply and Sewerage Board vs A. Rajappa (1978). That 1978 judgment laid down the “Triple Test” for what counts as an “industry” under Section 2(j) of the Industrial Disputes Act, 1947. The present Bench left the Triple Test standing for all pending disputes under the older Act. A majority of the same Bench also ruled that the 1978 judgment will not be a “sheet anchor” for interpreting Section 2(p) of the Industrial Relations Code, 2020. The tension is that Section 2(p) itself reproduces much of the Triple Test’s essence, so an interpretive framework has been severed from a provision that continues to embody it.

    What is the “Triple Test” on what counts as an “industry”?

    1. The three conditions: An activity qualifies as an industry where three conditions are met together: a systematic activity, employer-employee cooperation, and production or distribution of goods and services to satisfy human wants other than those that are purely religious or spiritual.
    2. Profit is irrelevant: Profit motive plays no part in the determination. What matters is the nature of the activity itself, so a loss making or non-commercial body can still be an industry.
    3. The single exclusion: Only “sovereign functions” stand outside the definition, which is a narrow carve out rather than a general exemption for the State.

    How did the reference reach a nine judge Bench?

    1. The origin: The Triple Test was laid down in the 1978 judgment, which read Section 2(j) of the Industrial Disputes Act, 1947 expansively.
    2. The doubt: A five judge Bench in State of U.P. vs Jai Bir Singh (2005) raised a doubt about that definition.
    3. The escalation: A seven judge Bench then sent the question to the current nine judge Bench.
    4. The statute changed while the reference was pending: The Industrial Disputes Act, 1947 was repealed on 21 November 2025, when the Industrial Relations Code, 2020 came into force.
    5. The Bench therefore faced two statutes: It had to decide the status of the Triple Test both for disputes still pending under the repealed Act and for interpretation of the successor provision, which is why the ruling splits along those two lines.

    What did the majority and the dissent hold?

    1. Pending disputes are unaffected: The Bench, led by the Chief Justice of India, left the Triple Test standing for all pending disputes under the older Industrial Disputes Act, 1947.
    2. The anchor was removed for the new Code: A majority of the nine judge Bench ruled that the 1978 judgment will not be a “sheet anchor” for interpreting Section 2(p) of the Industrial Relations Code, 2020.
    3. The dissent went further than disagreement: The dissenting opinion held that the reference itself was unnecessary and that the Triple Test requires no interference at all.
    4. The dissent was not isolated: That view was shared by three other judges on the Bench, so the split on the reference question was narrow rather than lopsided.

    Why does an expansive definition of “industry” matter more now than in 1978?

    1. The workforce has moved: Since 1978, and particularly after the liberalisation and privatisation reforms of 1991, a far higher number of workers have moved to the private sector, out of the security of public employment.
    2. Security no longer comes from the employer: For a worker outside public employment, statutory coverage rather than employment status is what provides protection.
    3. Definition decides access: Whether an establishment is an “industry” determines whether its workers can raise an industrial dispute at all, so the definition is the gateway to every protection that follows.
    4. Most of the workforce is outside formal protection: About 90 per cent of India’s workforce is informal, and nearly 58 per cent of salaried workers still lack a written contract.
    5. The expansive reading is therefore a bulwark: An expansive definition of industry is more necessary now than it was in 1978, precisely because the cushion of public employment has shrunk.

    Was the Triple Test a pro-labour device or a framework for industrial peace?

    1. It was not merely pro-labour: The Triple Test was not only a device for extending worker protection, though it is usually described that way.
    2. It brought restrictions with it: An expansive definition of industry brought with it not just the protections of the Industrial Disputes Act, 1947 but also its restrictions.
    3. The employer gained a defined route: It gave employers a regulated route to retrenchment and closure, rather than leaving those decisions to be contested without a framework.
    4. Workers accepted a limit in return: It carried a bar on workers striking at will, so the coverage came with a procedural discipline on industrial action.
    5. The net effect was industrial peace: In essence the Triple Test allowed for industrial peace rather than worker welfare alone, which is what makes its removal a loss to both sides rather than to one.

    Why is setting the 1978 judgment aside difficult to justify?

    1. The successor provision did not change the test: Section 2(p) of the Industrial Relations Code, 2020 does not move away from the Triple Test formula and reproduces much of its essence.
    2. The reasoning does not follow: It is therefore difficult to understand why the 1978 judgment has to be set aside when Section 2(p) itself comes up for interpretation.
    3. A framework, not just a precedent, was cut away: Severing that principle from the Code cuts away the interpretive framework that allowed such disputes to be resolved at all.
    4. Two footings now coexist: Pending disputes under the repealed Act will be decided on the Triple Test, and disputes under the Code will be decided without it as an anchor, on a definition that says much the same thing.
    5. The burden shifts to the lower courts: It is now incumbent upon courts and tribunals to ensure that a change of statute is not read as a change of intent, and they must do so with the anchor removed.

    Challenges to the definition of “industry” under the Industrial Relations Code, 2020

    1. Litigation will restart from zero: With the 1978 judgment displaced as the anchor, every category of establishment settled over four decades becomes arguable again. Eg. Hospitals, educational institutions and charitable bodies were brought within the definition on the strength of that judgment. Fix. Insert a statutory explanation to Section 2(p) listing the categories expressly included and excluded, so the question is settled by text rather than by fresh litigation.
    2. The “sovereign functions” exclusion has no statutory boundary: The carve out is judicially defined, so its width expands or contracts with each ruling rather than by legislative choice. Eg. Municipal and public utility bodies performing statutory duties have repeatedly contested their status as industries. Fix. Define sovereign functions in the Code by reference to a listed set of constitutional functions.
    3. Threshold changes shrink the protected group: Raising the retrenchment and closure approval threshold reduces how many workers the framework covers regardless of how “industry” is defined. Eg. The Industrial Relations Code, 2020 raises the closure and retrenchment threshold from 100 to 300 workers. Fix. Pair the higher threshold with a statutory retrenchment compensation escalator and a funded reskilling entitlement.
    4. Platform and contract work sits outside the frame: The employer-employee cooperation limb assumes an identifiable employer, which app-mediated and multi-layered contract work does not supply. Eg. Aggregator platforms classify workers as partners rather than employees, which places them outside the industrial dispute route. Fix. Deem an aggregator to be the principal employer for the purpose of dispute resolution where it controls pricing and task allocation.
    5. Two parallel regimes will run for years: Pending disputes under the repealed Act and new disputes under the Code will be decided on different interpretive footings for as long as the backlog lasts. Eg. Industrial disputes routinely take a decade or more to reach final decision. Fix. Issue a transitional provision directing that Section 2(p) be construed consistently with the settled position under Section 2(j) for a stated period.
    6. Tribunal capacity has not been strengthened: A framework that shifts interpretive burden to tribunals fails where those tribunals are understaffed and slow. Eg. Industrial tribunals and labour courts carry long standing vacancies alongside a large pending case load. Fix. Fill sanctioned tribunal posts on a fixed calendar and publish disposal timelines for industrial dispute references.

    Conclusion

    The nine judge Bench preserved the Triple Test where it no longer decides much and removed it where it would have decided most. The relationship between the successor provision and the test, set out above, is what makes that split hard to defend. The dissenting view, that the reference was unnecessary and the test required no interference, is the more coherent reading of a workforce that has moved into private employment since 1978 and needs an expansive definition more, not less. It now falls to courts and tribunals to ensure that a change of statute is not read as a change of intent, without the anchor that would have made that straightforward.

    “[2024, GS3, 15 marks] Discuss the merits and demerits of the four ‘Labour Codes’ in the context of labour market reforms in India. What has been the progress so far in this regard?”

  • Small transporters hit by compliance burden

    Why in the News

    The road transport industry, which carries nearly 70 per cent of India’s domestic freight, has been described as facing one of the most difficult periods in its history. Operating costs for commercial vehicles have risen sharply over the last few years. Freight rates have stayed largely stagnant over the same period. Vehicle location tracking devices, originally conceived for passenger safety and emergency response, have since been mandated for goods vehicles as well. Faults in integrating those devices with the VAHAN portal have left commercial vehicles stranded for weeks and in some cases months. The contest is between technology driven governance, which promises transparency and enforcement quality, and its implementation cost, which falls hardest on the small operators who have no margin left to absorb it.

    What is a Vehicle Location Tracking Device (VLTD)?

    1. Function: A Vehicle Location Tracking Device (VLTD) is an onboard unit that continuously transmits a vehicle’s position to a State level control centre over a mobile network. It carries emergency buttons that raise an alert to that centre.
    2. Original purpose: The device was conceived for passenger safety and emergency response, so that a distress signal from a bus or a cab could be located and acted on.
    3. Registration linkage: A fitted device must be registered against the vehicle on the VAHAN portal, the Ministry of Road Transport and Highways database that holds every vehicle’s registration record. A vehicle whose device does not map correctly to that record cannot complete its compliance formalities.

    Why has the road freight business turned financially unsustainable?

    1. Costs and earnings have moved apart: The gap between operational expenses and earnings has widened steadily. Freight rates have not tracked the rise in the cost of running a truck.
    2. Fuel dominates the cost sheet: Diesel alone accounts for nearly 60 per cent of a truck’s operating cost. Every rise in the pump price passes almost directly into the operator’s monthly outgo.
    3. Emission compliance added a new input: Operators have had to absorb the cost of AdBlue, the urea solution injected into the exhaust of Bharat Stage VI (BS-VI) vehicles to cut nitrogen oxide emissions. This is a recurring consumable that did not exist in the earlier cost structure.
    4. Every other input has escalated: Tyre prices, insurance premiums, spare parts, engine oil, lubricants, maintenance expenses, finance costs and statutory compliance charges have all risen together. Toll charges continue to rise alongside them.
    5. Margins have gone below cost for some: Many transporters operate on wafer thin margins simply to retain business. Some are running below their actual cost of operations.

    What has the compliance and enforcement layer added?

    1. Documentation load has grown: The burden of documentation, permits, fitness requirements and other regulatory compliances has increased substantially. Each of these carries its own fee, its own renewal cycle and its own downtime.
    2. Electronic challans have drawn allegations of misuse: The electronic challan was introduced to minimise human intervention and improve road safety. A growing number of transporters allege misuse of the system, producing avoidable penalties and harassment.
    3. Tracking devices were extended without a stated case: The VLTD mandate was extended to goods vehicles in the absence of clear operational necessity. A device designed around passenger distress response was applied to freight movement, adding a financial burden with no matching benefit to the operator.
    4. Integration failure converts compliance into downtime: Technical problems in integrating VLTD units with the VAHAN portal have left many commercial vehicles off the road for weeks and in some cases months.
    5. Downtime compounds financially: Each day a truck stays off the road means lost income, continuing loan repayment pressure and severe financial distress for the operator. The loan instalment does not pause because the portal did not accept the device.

    Does technology driven governance deliver transparency or only new hardship?

    1. The intent is not in dispute: Technology driven governance is welcome where it promotes transparency and efficiency. Both the electronic challan and the tracking mandate were framed in exactly those terms.
    2. Implementation is where the cost lands: A mandate is issued centrally and instantly, while its back end integration is completed unevenly across States and vendors. The operator carries the difference as idle capital.
    3. Enforcement quality decides the outcome: Enforcement must remain transparent, accountable and fair, so that genuine operators are not penalised alongside violators. An automated penalty with no accessible appeal converts a safety tool into a revenue tool.
    4. The burden is uniform, the capacity to bear it is not: A compliance charge set as a flat per vehicle amount is trivial for a large fleet and material for a single truck owner. The same rule therefore produces very different pressure across the sector.
    5. Digital mandates need a working failure route: No route exists for an operator whose device is fitted and paid for but not accepted by the database. The vehicle is treated as non compliant even where the failure is on the system side.

    Why are small operators and self-driving truck owners hit hardest?

    1. They absorb every shock directly: Small transport operators and self-driving truck owners are affected the most by these developments. They have no fleet across which to spread a stranded vehicle or a disputed penalty.
    2. The sector is structurally fragmented: Most road freight capacity sits with small, unorganised firms and single truck owners rather than large corporate fleets. Fragmentation leaves no bargaining power against shippers on freight rates.
    3. Finance costs bite first: Vehicle loans are serviced monthly regardless of utilisation. An operator with one or two trucks moves into default faster than a fleet operator with the same days of downtime.
    4. Highway amenities have not followed toll payments: Despite paying substantial toll charges, drivers continue to face a shortage of secure truck parking zones, clean toilets, rest areas and other basic highway amenities.
    5. Tolls are a rising fixed charge: Toll charges require rationalisation, since they now form a large and rising share of the per trip cost on tolled corridors. A rate that is not linked to service delivered is a pure cost addition.

    Challenges to the road freight compliance regime

    1. Freight rates are not cost linked: No mechanism ties freight rates to the actual cost of operating a truck, so input inflation is absorbed rather than passed on. Eg. The rise in diesel, tyre and insurance costs over recent years has not produced a matching rise in contracted freight rates. Fix. Base freight rates on scientific cost calculations that reflect actual operating expenses and are revised on a stated cycle.
    2. Device mandates run ahead of system readiness: A device is made compulsory before the registration database can reliably record it, so compliant operators are penalised for a back end fault. Eg. VLTD to VAHAN integration failures have kept commercial vehicles off the road for weeks and months. Fix. Tie the commencement of any device mandate to a certified integration test, and grant an automatic provisional clearance where the portal fails to accept a fitted device.
    3. Automated enforcement lacks a low cost appeal route: An electronic penalty is issued instantly while contesting it requires time and travel that a single truck owner cannot spare. Eg. Transporters allege misuse of the electronic challan system producing avoidable penalties. Fix. Provide a time bound online adjudication route with photographic evidence disclosure at the point of the challan.
    4. Compliance costs are not scaled to fleet size: Fees, permits and fitness requirements are set per vehicle, so the smallest operator carries the highest cost per rupee of turnover. Eg. Statutory compliance charges have escalated alongside tyre, insurance and finance costs for operators running one or two trucks. Fix. Introduce a graded fee structure and a single consolidated annual compliance filing for operators below a stated fleet threshold.
    5. Toll collection is not linked to service: Toll rates rise on schedule while wayside amenities on the same corridors remain absent. Eg. Drivers on tolled highways face a shortage of secure parking zones, clean toilets and rest areas. Fix. Make a stated wayside amenity standard a condition of toll revision on each stretch, audited before the next revision is notified.
    6. Overloading and safety enforcement fall on the driver, not the shipper: Penalties for overloading attach to the vehicle and the driver, leaving the consignor who loaded it untouched. Eg. Overloaded highways suffer rapid wear and tear while enforcement action is recorded against the transporter. Fix. Extend statutory liability for overloading to the consignor and the loading point operator.

    Conclusion

    The compliance burden on road freight has grown faster than the sector’s ability to pay for it, and the cost has settled on small operators and self-driving truck owners rather than on large fleets. The immediate cause is not the principle of technology driven governance but its implementation, where a mandate takes effect before the system that records it works. A comprehensive review of the road transport ecosystem is the stated demand, resting on three things: freight rates built on scientific cost calculations, rationalised tolls, and a relook at the compliance load. None of the three has been taken up.

    “[2014, GS3, 12 marks] National Urban Transport Policy emphasises on ‘moving people’ instead of ‘moving vehicles. Discuss critically the success of the various strategies of the Government in this regard.”