💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Economics

  • Economy weathered West Asia shock. Now, reform for sustained growth (Op-ed by Sajjid Chinoy)

    Why in the News

    India’s gross domestic product (GDP) growth for the last quarter is expected to print close to 8 per cent, defying fears that the West Asia conflict had dented the economy. This follows a joint fiscal, monetary and regulatory stimulus through 2025, direct tax cuts, a Goods and Services Tax (GST) rationalisation, and an effective 150 basis point policy rate cut, combined with a swift diversification of energy imports during the conflict. The pickup is largely cyclical, and the investment rate, corporate capital expenditure (capex) and structural export and employment growth remain too weak to sustain the expansion once the stimulus fades.

    What explains India’s growth resilience through the West Asia conflict?

    1. A joint stimulus in 2025: Direct taxes were cut in February, GST was rationalised in September, and policy rates were cut by an effective 150 basis points along with regulatory easing in the financial sector.
    2. Non-oil export acceleration: Exports have picked up on the back of a near 15 per cent depreciation of the real effective exchange rate (REER), the trade weighted, inflation adjusted value of the rupee against a basket of currencies, since 2025, a reduction in United States tariffs, and resilient global growth.
    3. Swift energy diversification: India sourced crude from Russia and liquefied natural gas from the United States and Oman to prevent shortages, importing 17 per cent more energy than normal last quarter, while the government absorbed the bulk of the oil price shock through the fisc to insulate the private sector.

    Why does India’s investment rate remain a structural concern?

    1. Fixed investment stagnant: Fixed investment remains near its decadal average of 32 per cent of GDP and has not lifted despite rising public investment and real estate capex.
    2. Corporate capex has not picked up: Corporate capex continues to languish around 10 to 11 per cent of GDP, and balance sheets of the top 1,000 listed companies show no discernible pickup in 2025-26.
    3. Central capex is slowing: Central capex grew 30 per cent between 2020 and 2023, then slowed to 11 per cent in 2024 and just 1.6 per cent in 2025, as tax cuts absorbed fiscal space.
    4. State capex under pressure: Cash transfers on demand are pushing state capex growth below nominal GDP growth.
    5. Weak demand visibility: Capacity utilisation has stayed in the 75 to 76 per cent range for a decade, and rising Chinese overcapacity is discouraging corporate investment.

    Why are consumption and export growth not yet structural?

    1. Weaker growth than the earlier export led cycle: Post-pandemic private consumption and exports grew at about 5 per cent, against the 16 per cent export growth between 2003 and 2012 that had crowded in private capex.
    2. Service export growth has halved: Service export growth in nominal dollars has fallen to 8 per cent over the last year from 16 per cent over the previous four years, and employment across major IT firms has stayed flat.
    3. Employment mix is shifting toward self-employment: The Periodic Labour Force Survey shows India’s employment rate rising, but a significant share of new jobs are self-employed rather than salaried, even as the mix improved in 2025.
    4. Consumption is credit fuelled: Non-Banking Financial Company lending to households is growing at 20 per cent and unsecured personal lending momentum has risen to 25 per cent, on the back of rising household leverage.

    What must change for the growth cycle to become structural?

    1. Labour must become more competitive against capital: India’s capital-labour ratio has risen for over two decades, and reversing this needs education, skilling and health investment, alongside rationalising labour laws that raise the cost of labour.
    2. Exports need structural competitiveness: Goods exports have fallen from 17 per cent of GDP a decade ago to 11 per cent, and further gains need tariffs and non-tariff barriers rationalised and overregulation reduced.
    3. Private capex is the real crowding-in mechanism: Structurally higher consumption and exports are what would draw in a sustained private capex cycle, which in turn would crowd in foreign direct investment and stabilise the balance of payments.

    Conclusion

    The current cyclical strength, backed by clean corporate and financial balance sheets and a sustained agricultural surplus, is a bridge over the West Asia shock, not a destination. Unless investment, exports and employment turn structural, the growth cycle will not sustain once the fiscal and monetary stimulus fades, and the piece warns there is little time left to act given global automation, trade fragmentation and a fraying international order.

    Matching Previous Year Question

    No direct PYQ traced in the provided files.
  • FCNR(B) deposits push forex reserves to all-time high of $729 bn in August

    Why in the News

    The Reserve Bank of India’s concessional swap window for Foreign Currency Non-Resident (Bank), or FCNR(B), deposits has propelled India’s foreign exchange reserves to a record $729.33 billion as of 21 August, surpassing the previous all-time high of $728.49 billion recorded on 27 February, just a day before the United States and Israel struck Iran and touched off the West Asia conflict that drove global energy prices sharply higher. Reserves rose by $12.42 billion in the week ended 21 August alone, with FCNR(B) inflows of $65.4 billion accounting for most of the $72.85 billion that has entered India since three concessional swap windows opened on 8 June.

    What is driving reserves to a record, and what does the FCNR(B) window actually do?

    1. Scale of inflows: FCNR(B) deposits outstanding rose from $34.04 billion at the end of May to $65.4 billion by 21 August, since the window opened on 8 June, and reserves themselves jumped $12.42 billion in the week ended 21 August.
    2. Mechanism: Under the FCNR(B) scheme the central bank bears the full exchange rate risk on these non-resident deposits, since the money is held in foreign currency rather than converted into rupees, which let banks offer interest rates as high as 7.4 percent.
    3. Leveraged NRI participation: Non-resident Indians have also borrowed at lower interest rates abroad to deposit the proceeds into FCNR(B) accounts, earning returns of as much as 15 percent on the resulting spread.

    Why did reserves need rebuilding in the first place?

    1. The rupee was already under stress before the record: The rupee came under intense pressure from large foreign portfolio outflows, with $19 billion leaving Indian markets in 2025 and a further $24 billion in the first five months of 2026, pushing the currency to near 97 per dollar in mid-May.
    2. The West Asia conflict added an oil import shock: Since roughly 85 percent of India’s crude oil needs are met through imports, the conflict’s closure-driven spike in global energy prices raised the country’s import bill and added further pressure on the rupee just as reserves were near their earlier February high.
    3. The rupee remains down year-on-year despite the record reserves: The rupee closed at 95.39 per dollar on Friday, little changed from its 95.79 level on 4 June and still 8.1 percent weaker than a year earlier, showing the reserve build has stabilised rather than reversed the currency’s decline.

    What other measures accompanied the FCNR(B) window?

    1. Two additional swap windows: Announced alongside FCNR(B) on 5 June, swap facilities for Overseas Foreign Currency Borrowings and External Commercial Borrowings have together brought in $4.86 billion and $2.59 billion respectively since 8 June.
    2. Tax relief for foreign portfolio investors: The government removed capital gains and withholding taxes on foreign portfolio investment in government securities as part of the same package meant to pull in capital and support the rupee.
    3. An accelerated closure timeline: Because inflows arrived faster than expected, the RBI moved the FCNR(B) window’s closing date to 31 August, a month earlier than the originally announced 30 September deadline.

    Challenges to relying on FCNR(B)-driven reserve accumulation

    1. Weak currency response relative to precedent: The rupee has barely moved during this swap window, compared with the 2013 episode when the rupee rose 10.3 percent, from 67.6 to 61.3 per dollar, in the first 40 days after the RBI’s then-Governor introduced a similar FCNR(B) swap facility. Eg. The rupee moved from 95.79 to 95.39 per dollar between 4 June and 29 August this year, a fraction of the 2013 currency response to a comparable scheme. Fix. Pair reserve accumulation with structural measures that improve the current account, such as diversifying energy import sources, rather than treating swap-driven capital inflows alone as sufficient to support the currency.
    2. Reversal risk from leveraged hot money: A meaningful share of FCNR(B) inflows has been driven by non-resident Indians borrowing cheaply abroad to arbitrage into high-yield deposits, a flow that can reverse quickly once interest rate differentials narrow or the window closes. Eg. The window’s early closure on 31 August, a month ahead of schedule, was itself driven by inflows arriving faster than expected, which cuts both ways once the scheme ends and deposits mature. Fix. Stagger FCNR(B) maturities and monitor the redemption schedule closely to avoid a sudden reserve drawdown when large deposit tranches come due.

    Conclusion

    The FCNR(B) swap window has pushed India’s foreign exchange reserves past their previous February high to a record $729.33 billion, giving the Reserve Bank of India greater capacity to defend the rupee after a period of heavy foreign portfolio outflows and an oil price shock from the West Asia conflict. The rupee’s limited appreciation despite the record inflow, unlike the sharper rupee gains seen after the comparable 2013 swap window, signals the current build is cushioning rather than reversing currency pressure.

    Back2Basics: What are FCNR(B) deposits?

    1. FCNR(B) deposits are foreign currency accounts that non-resident Indians can hold with Indian banks, where the deposit and its returns stay denominated in the foreign currency rather than in rupees.
    2. The scheme shifts exchange rate risk onto the Reserve Bank of India rather than the depositor or the bank, which lets banks offer higher interest rates to attract inflows during periods of currency pressure.
    3. India last used a similar concessional FCNR(B) swap window in 2013, under then RBI Governor Raghuram Rajan, to stabilise the rupee following a sharp depreciation.

    Matching Previous Year Question

    No direct PYQ traced in the provided files (Pass 1: FCNR(B), forex reserves record — no match; Pass 2: balance of payments, current account — matches found were conceptually unrelated to a record reserves event).

  • A.P. to become third subsea hub on data centre buildout

    A.P. to become third subsea hub on data centre buildout

    Why in the News

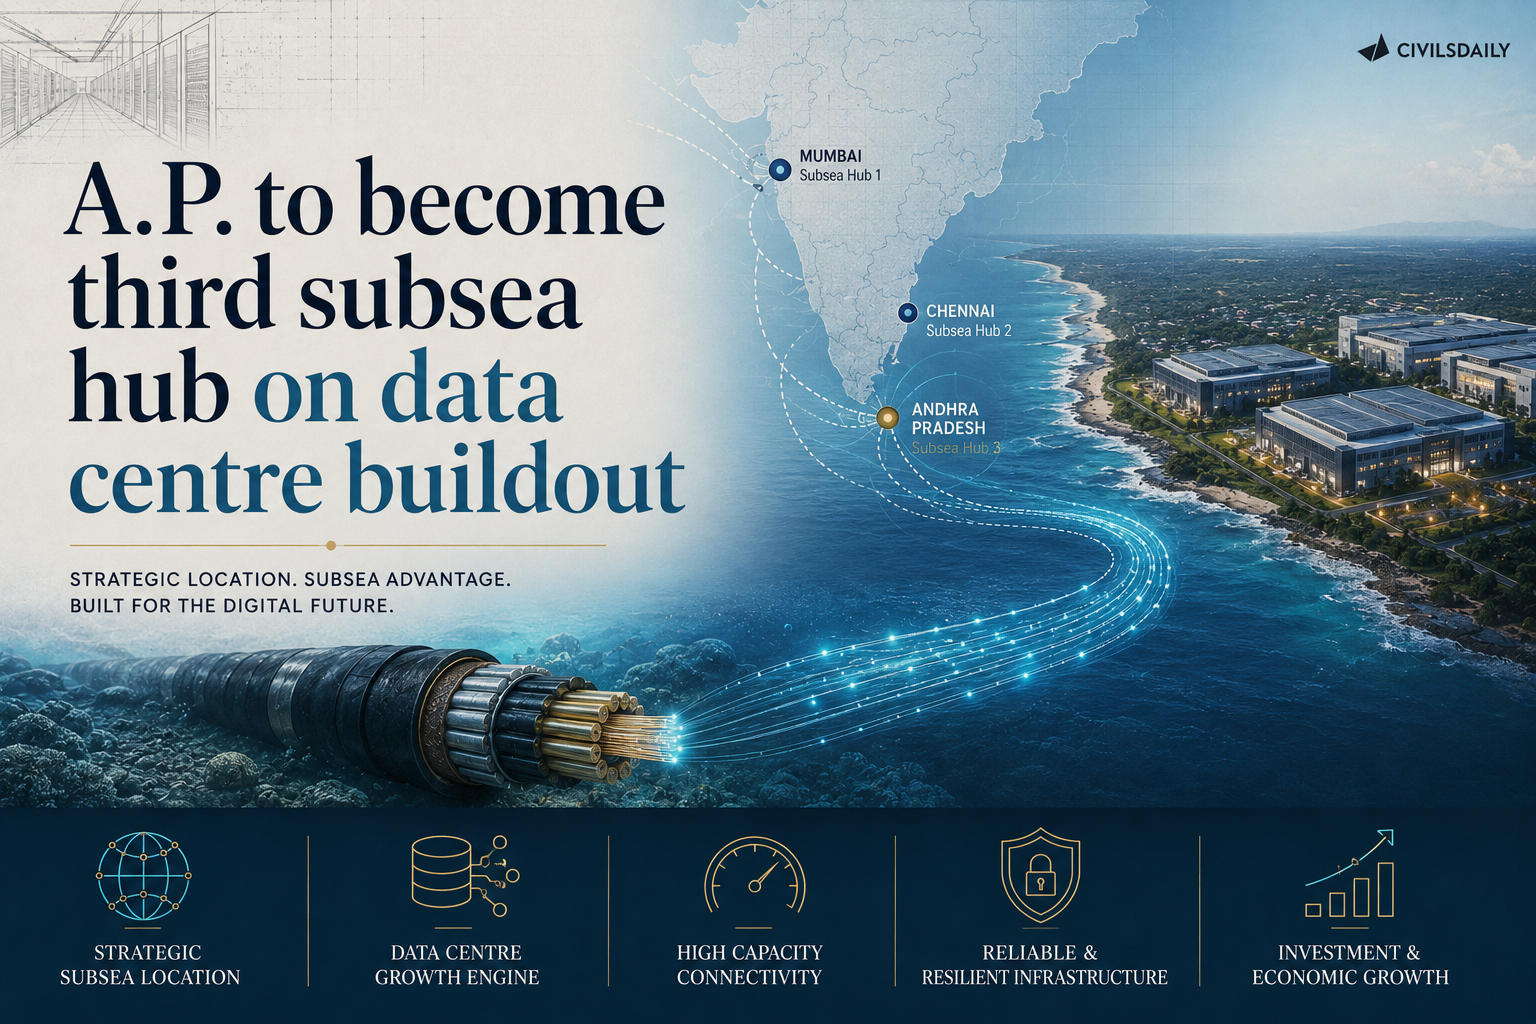
    Technology majors Microsoft and Google are building new subsea cable landing stations on the coast of Andhra Pradesh as part of an artificial intelligence linked data centre buildout in the State. Microsoft is part of a consortium with Lightstorm and the Singaporean telecom operator Singtel to land the 3,600 kilometre India Southeast Asia Submarine Cable System, while Google’s globe spanning America India Connect system will land at Visakhapatnam, where the company’s own data centre complex is coming up. Once complete, the buildout will give India, after Mumbai and Chennai, a third digital international gateway, even as a global shortage of fibre threatens to slow the inland network these projects still need.

    What is a subsea cable landing station?

    1. Definition: A subsea cable landing station is the facility where an undersea fibre optic cable comes ashore and connects to a country’s terrestrial network, carrying the bulk of international internet traffic.
    2. Global reliance: The overwhelming majority of the world’s international data traffic travels through such undersea cable systems rather than satellites, making landing stations critical infrastructure.
    3. India’s current concentration: India’s existing landing stations are concentrated in Mumbai and Chennai, leaving the country reliant on a small number of routes.

    What new cable infrastructure is being built off Andhra Pradesh’s coast?

    1. Microsoft’s consortium project: Microsoft, alongside Lightstorm and Singtel, is landing the 3,600 kilometre India Southeast Asia Submarine Cable System, expected to be ready for service in the fourth quarter of 2029.
    2. Google’s own system: Google’s America India Connect system will land at Visakhapatnam, alongside the data centre complex the company is building there as part of what a Google executive described as an artificial intelligence hub.

    What does this make Visakhapatnam?

    1. India’s third gateway: After Mumbai and Chennai, Visakhapatnam becomes India’s third digital international subsea gateway, connecting the country directly with Southeast Asia, Australia and the Middle East.
    2. A new corridor: Lightstorm’s chief executive has described the India Southeast Asia system, which also connects to Chennai, as providing a fresh corridor to South Asia from Singapore and Malaysia.

    Why are companies building on the east coast now?

    1. Ageing existing infrastructure: Most cables currently connecting India’s east coast are old, are already filled to capacity and are approaching the end of their working life.
    2. A search for resilience: Companies are also seeking to reduce the risk of relying on a single route by adding cables on India’s east coast, citing instability in West Asia as a reason to build in an alternate location.

    What inland infrastructure does this buildout require?

    1. A nationwide undertaking: Both projects require installing and lighting thousands of kilometres of new terrestrial fibre linking the coast to major cities, a scale one company executive described as spanning the entire country.
    2. A dedicated corridor: Lightstorm is expected to build a terrestrial corridor connecting Machilipatnam to Mumbai and Hyderabad, and Chennai to Hyderabad and Mumbai, with matching bandwidth.
    3. A global fibre shortage: Fibre, its components and its raw material are in short supply worldwide, including from Indian manufacturers, a constraint industry executives describe as unprecedented in over a decade.

    What will Google’s Visakhapatnam facility do?

    1. Focused on inference: The facility will focus on inference work rather than power intensive training runs, serving domestic enterprises and government agencies given the deep adoption of artificial intelligence across government service delivery.
    2. Power and water choices: Google is seeking to source as much renewable power for the project as possible and is using air cooling technology to minimise water use.

    Challenges to the subsea cable buildout

    1. A global fibre shortage: A worldwide shortage of fibre and its raw material, unprecedented in over a decade, could delay the inland network these projects still need. Eg. Industry executives report that fibre is out of stock across the globe, including from Indian manufacturers. Fix. Expand domestic fibre manufacturing capacity through targeted incentives so the inland rollout is not held back by global supply constraints.
    2. Physical vulnerability of undersea cables: Undersea cables remain exposed to accidental damage from fishing and anchoring activity and to disruption in contested waters. Eg. India’s existing east coast cables are already ageing and running close to capacity, leaving few redundant routes today. Fix. Build multiple, geographically separated landing points and routes, as the new Visakhapatnam gateway is itself intended to do, so a single cable fault cannot isolate India’s connectivity.
    3. Concentration of ownership with foreign firms: The new cable systems and the data centres they serve are being built and operated by foreign technology majors, so India’s expanding gateway capacity depends on the investment decisions of a small number of firms. Eg. Both the India Southeast Asia system and the America India Connect system are anchored by Microsoft and Google respectively rather than Indian carriers. Fix. Encourage Indian telecom operators to invest jointly in landing station capacity so gateway control is not concentrated entirely with foreign firms.

    Conclusion

    Andhra Pradesh’s coastline is emerging as India’s third major digital gateway, as Microsoft and Google build new subsea cable systems into Visakhapatnam alongside the data centres driving the region’s artificial intelligence buildout. Delivering on that promise depends on inland fibre rollout keeping pace despite a global supply crunch, and on India diversifying its cable landing points and ownership so its expanding digital infrastructure does not remain concentrated in a handful of ageing routes and foreign owned systems.

    [2023] “What is the status of digitalization in the Indian economy? Examine the problems faced in this regard and suggest improvements.”

  • Carney’s defiance is well thought out

    Carney’s defiance is well thought out

    Why in the News

    Canada’s Prime Minister has walked away from trade negotiations with the United States after Washington put forward terms that would have cost Canada its sovereignty, key industries, French language protections and its freedom to negotiate with other countries. He has also announced retaliatory tariffs matching the new United States tariffs dollar for dollar, stating that the Americans “asked too much and offered too little.” The move tests whether a middle power, an economy that sends roughly three quarters of its exports into a market ten times its size, can resist pressure from a dominant trading partner without folding, and it carries lessons for other countries, including India, that are negotiating their own terms with Washington.

    What calculations underlie the decision to walk away?

    1. Broad domestic backing: The stance draws support even from the opposition Conservative party, amid public frustration with the United States President’s repeated talk of making Canada the fifty first state.
    2. A contained tariff footprint: The new tariffs apply to only about 5 percent of Canada’s overall exports to the United States, worth roughly 20 billion dollars, limiting the immediate domestic cost of retaliation.
    3. A calculated bet on mutual damage: A breakdown in trade relations is expected to hurt the United States as well, so Canada does not need to win the confrontation outright, only to make the arithmetic politically painful in Washington.

    How exposed is the United States to a breakdown with Canada?

    1. A leading export destination: Canada is the largest export market for 26 American states and among the top three trading partners for 45 of the 50 states.
    2. Energy dependence: Canada supplies roughly 60 percent of America’s crude oil imports, and Canadian electricity helps power grids in New England and the upper Midwest.
    3. Critical inputs: Canadian potash is vital to American agriculture, while Canadian critical minerals feed strategically important American supply chains.

    Why is the timing unfavourable for Washington?

    1. Domestic economic strain: A stalemate with Iran has pushed United States gasoline prices above 4 dollars a gallon, while the 30 year Treasury yield has climbed above 5.3 percent, its highest level since 2007.
    2. Fiscal and political weakness: Federal debt has crossed 40 trillion dollars, and the United States President’s net approval rating has fallen to minus 26 percent, narrowing his room to absorb a prolonged trade standoff.

    What broader pattern does this defiance respond to?

    1. A repeated negotiating playbook: Governments from Mexico City to Brussels to Tokyo have spent the past year confronting an American administration that treats a signed trade agreement as an opening bid that can be revisited whenever it suits it, coercing partners with escalating tariff threats and demanding unilateral concessions.
    2. Prior diversification, not improvisation: The Canadian Prime Minister had earlier warned that middle powers must stand up or risk ending up “on the menu,” and spent close to a year building trade ties with China, the Gulf and Asia, including India, so that a closed door in Washington did not mean a locked room globally.

    Challenges to Canada’s defiance strategy

    1. Economic exposure to a sustained standoff: Canada still sends roughly three quarters of its exports to an economy ten times its own size, so a prolonged confrontation could cost jobs and growth even if it wins the political argument. Eg. Estimates cited alongside the retaliatory tariffs put up to 90,000 Canadian jobs at risk from a sustained trade confrontation. Fix. Continue diversifying export markets by deepening the trade ties already being built with China, the Gulf and Asia.
    2. A narrow tariff footprint limits leverage: The new tariffs cover only about 5 percent of Canada’s exports to the United States, so retaliation alone may be too small to force a reversal in Washington. Eg. Even a full breakdown leaves most of Canada’s three quarter dependence on the United States market untouched. Fix. Extend retaliation toward strategically sensitive sectors such as crude oil, electricity and critical minerals, where Canada supplies a large share of United States demand.
    3. Domestic political risk if pain outlasts patience: Sustained economic pain could erode the broad backing that currently underwrites the stance, including support from the opposition. Eg. Higher fuel and consumer prices from a prolonged standoff could shift Canadian public opinion before comparable pressure is felt in Washington. Fix. Time targeted relief for the sectors affected by the new tariffs so public patience holds through the standoff.

    Conclusion

    The decision to reject an unfavourable trade deal, backed by calculated retaliation and prior diversification of trade ties, is being read as proof that a middle power can resist pressure from a much larger economy without folding. Whether the strategy succeeds depends on whether Canada’s own economic pain stays contained and whether Washington’s vulnerabilities, from energy prices to approval ratings, bite hard enough to force a reversal. For India, still negotiating its own trade deal with Washington, the lesson is not to reject a deal outright but to know precisely which concessions it can never afford to make.

    [2025] What are the challenges before the Indian economy when the world is moving away from free trade and multilateralism to protectionism and bilateralism? How can these challenges be met?”

  • Economy is resilient, but risks remain

    Economy is resilient, but risks remain

    Why in the News

    The State of the Economy report, compiled by economists at the Reserve Bank of India (RBI), together with the finance ministry’s monthly economic review, has found that India’s underlying growth momentum held up through the first quarter of the financial year. Both readings point to firm household consumption, industrial output and credit growth even as global conditions stay unsettled. The outlook nonetheless remains clouded by continuing geopolitical and trade related uncertainty, volatile energy prices and a strengthening El Niño (a periodic warming of central and eastern Pacific Ocean waters that disrupts monsoon rainfall patterns), risks that could weigh on growth just as the National Statistics Office (NSO) prepares to release its first quarter Gross Domestic Product (GDP) estimate.

    What signals point to resilient domestic growth?

    1. Steady consumption indicators: E way bill generation has stayed firm, Goods and Services Tax (GST) revenues have remained healthy, and passenger vehicle, tractor and two wheeler sales have all been strong.
    2. Firm industrial output: The Index of Industrial Production (IIP), a measure of output across mining, manufacturing and electricity, rose 5.8 percent in the quarter, aided by the manufacturing sector, while electricity demand held steady.
    3. Corporate profitability and credit growth: Firms in both manufacturing and services reported improved operating profits, and bank credit has grown at a brisk pace across both industrial and retail lending.
    4. Monsoon recovery and exports: A recovery in the monsoon has supported kharif sowing, and exports excluding oil grew 12.8 percent in the first four months of the year, aided by the currency’s depreciation.
    5. Public capital spending: The Centre’s own expenditure grew by roughly 24 percent in the quarter, keeping public capital spending on track.

    What risks could weigh on this resilience?

    1. External uncertainty: Continuing geopolitical and trade related tensions, along with supply chain pressures, threaten to unsettle the momentum built up domestically.
    2. Volatile energy prices: Fluctuating global energy prices raise input costs across manufacturing and transport and feed inflation risk.
    3. A strengthening El Niño: A stronger El Niño could unsettle the rainfall gains that supported this quarter’s kharif sowing and rural demand.
    4. A cautious institutional tone: The finance ministry’s economic review itself notes that “recent years have been a time for hunkering down and battening down the hatches,” and expects coming years to be no exception.

    What does the growth trajectory imply for the GDP estimate?

    1. RBI’s own projection: At its August Monetary Policy Committee (MPC) meeting, the central bank projected 7 percent growth for the first quarter, a figure broadly matched by assessments from agencies such as Crisil and ICRA.
    2. The GDP release ahead: The National Statistics Office is set to release its first quarter GDP estimate shortly, with growth seen as likely to surprise on the upside even as the external environment continues to weigh on the outlook.

    Conclusion

    Domestic demand, industrial output and credit growth show the economy’s underlying momentum has held up, but persistent external risks, from trade tensions to volatile energy prices and a strengthening El Niño, mean policymakers cannot afford complacency. The National Statistics Office’s forthcoming GDP estimate will offer the first concrete test of whether this resilience is translating into headline growth, even as the external environment continues to demand a calibrated policy response.

    Back2Basics: What is the State of the Economy report?

    1. Publisher: It is a monthly assessment published in the Reserve Bank of India’s Bulletin, written by economists in the RBI’s Monetary Policy Department.
    2. Status: It carries a standard disclaimer that the views expressed are those of the authors and not necessarily those of the RBI.
    3. Purpose: It reviews high frequency indicators of growth, inflation and the external sector to assess the economy’s current momentum.

    [2021] “Explain the difference between computing methodology of India’s Gross Domestic Product(GDP) before the year 2015 and after the year 2015.”

  • PSU banks more efficient than private peers: EAC-PM

    PSU banks more efficient than private peers: EAC-PM

    Why in the News

    A paper by two economists for the Economic Advisory Council to the Prime Minister (EAC-PM), a body that advises the Prime Minister on economic policy questions, found that public sector banks (PSBs) are more efficient than private and foreign banks.

    Titled “Reforms, Efficiency, and Productivity of Indian Banking Sector in the Last Decade: DEA Approach”, the paper used Data Envelopment Analysis (DEA), a method that measures how far a unit could shrink its inputs while producing the same output, to compare 47 banks.

    What does the study find?

    1. PSBs improved significantly: During 2014-15 to 2025-26, PSBs recorded average efficiency of 88.53%, compared with 85.62% for private banks. Foreign banks led over the full period: Foreign banks had the highest 12-year average of 88.98%, but their efficiency declined from 95.86% in 2014-15. Most efficient banks:
    2. HSBC and JPMorgan Chase: 100% efficiency in all 12 years.
    3. HDFC Bank: 97.54% average efficiency among private banks.
    4. State Bank of India (SBI): 97.49%, highest among PSBs.
    5. DBS Bank India: Lowest single-year efficiency of 40.12% in 2021-22, linked to its merger with Lakshmi Vilas Bank.
    6. Impact of PSB mergers: PSBs were relatively less efficient than private banks during FY2019 to FY2022, partly due to the merger and rationalisation of branches, employees and business operations.

    Data Envelopment Analysis (DEA)

    1. DEA is a method for measuring the relative efficiency of units, here banks, that produce the same kind of output from different combinations of inputs.
    2. An efficiency score below 100% means the unit could reduce its inputs by that shortfall and still produce the same output. Eg. A score of 85% means the unit could cut inputs by 15% without any loss of output.

    “[2024] Consider the following statements:
    Statement-I: Syndicated lending spreads the risk of borrower default across multiple lenders.
    Statement-II: The syndicated loan can be a fixed amount/lump sum of funds, but cannot be a credit line.
    Which one of the following is correct in respect of the above statements?
    (a) Both Statement-I and Statement-II are correct and Statement-II explains Statement-I
    (b) Both Statement-I and Statement-II are correct, but Statement-II does not explain Statement-I
    (c) Statement-I is correct, but Statement-II is incorrect
    (d) Statement-I is incorrect, but Statement-II is correct

  • Rural India needs jobs, not wage guarantees

    Rural India needs jobs, not wage guarantees

    Why in the News

    An opinion piece argues that a new rural wage-guarantee scheme has recorded low uptake among the rural workforce, and contends this shows rural India needs durable, income-generating employment rather than a guaranteed-wage safety net. The scheme pays a guaranteed wage for a fixed number of days, which the piece contrasts with sectors such as food processing, renewable energy and small and medium enterprises (SMEs), which it argues could generate sustained employment rather than a temporary income floor. The tension is between a safety-net approach to rural distress and a growth-oriented approach that builds durable non-farm jobs.

    Why has the wage-guarantee scheme seen low uptake?

    1. Wage ceiling below market rates: Where the scheme’s guaranteed wage sits below prevailing local market wages for casual labour, workers have limited incentive to enrol, since informal market work pays more for the same effort.
    2. Seasonal mismatch: A fixed-day guarantee does not align well with the seasonal peaks in rural labour demand during sowing and harvest, when private demand for labour already absorbs much of the available workforce.

    What alternative does the piece propose?

    1. Food processing: Expanding food processing capacity near production zones can absorb rural labour in agro-processing roles that persist beyond a single season.
    2. Renewable energy: Rural solar and biomass energy projects can generate sustained local employment in installation, operation and maintenance roles.
    3. Small and medium enterprises: Supporting rural SMEs with credit and market access can create employment that grows with demand, rather than being capped at a fixed number of guaranteed days.

    Unemployment in India

    1. The International Labour Organization (ILO) defines an unemployed person as someone of working age, without work, currently available to work and actively seeking work in a reference period.
    2. India’s unemployment carries several distinct types: frictional, structural (a mismatch between workers’ skills and market demand), cyclical, seasonal, disguised (as in agriculture, where more people are employed than the work requires), and chronic.
    3. Over 90 percent of India’s workforce remains informal, which limits meaningful, secure job creation regardless of headline employment growth.
    4. Manufacturing contributes only about 16 to 18 percent of GDP, well below China’s roughly 26 percent, constraining the sector’s capacity to absorb surplus labour.

    Government Initiatives for Employment Generation

    1. Mahatma Gandhi National Rural Employment Guarantee Act (MGNREGA), 2005: Guarantees 100 days of rural wage employment a year to any adult member of a rural household, and is the specific scheme this op-ed’s wage-guarantee critique concerns.
    2. PM Vishwakarma: Provides collateral-free loans, skilling and toolkits to artisans across 18 traditional trades.
    3. PM Vishwakarma Rozgar Yojana / Employment Linked Incentive (ELI) scheme: Approved with an outlay of about 99,446 crore rupees, targeting 3.5 crore jobs over two years.
    4. e-Shram Portal: A national database that issues unorganised workers a Universal Account Number and links them to social security schemes.
    5. DAY-NRLM: Mobilises the rural poor into Self-Help Groups to build self-sustained livelihoods.

    Challenges in Unemployment

    1. Survey design undercounts informal and rural work: Household surveys do not fully capture home-based, gig or platform work within the roughly 90 percent informal workforce, and rural labour force surveys have historically run at a lower frequency than urban ones. Eg. Rural Periodic Labour Force Survey (PLFS) data was measured only annually for years, while urban data was collected quarterly, understating rural distress in real time. Fix. Move rural PLFS to the same quarterly frequency as urban surveys and explicitly incorporate underemployment into the headline definition.
    2. Capital-intensive growth limits absorption: Investment has flowed disproportionately toward information technology and infrastructure rather than labour-intensive sectors capable of absorbing low and semi-skilled workers. Eg. Services now drive the largest share of GDP growth while employing under 30 percent of the workforce, the jobless growth pattern this op-ed’s wage-guarantee critique responds to. Fix. Direct incentive schemes toward labour-intensive sectors such as textiles, leather, food processing and electronics assembly rather than capital-intensive ones alone.

    Conclusion

    The piece argues that a wage-guarantee scheme with low enrolment is evidence that rural India’s underlying problem is a shortage of durable jobs, not a shortage of a temporary income floor, and that policy should shift resources toward sectors capable of generating sustained rural employment.

    Back2Basics: Periodic Labour Force Survey (PLFS)

    1. The PLFS is India’s principal household survey for estimating employment and unemployment, conducted by the National Sample Survey Office (NSSO) under the Ministry of Statistics and Programme Implementation (MoSPI).
    2. It reports unemployment on three measures: Usual Status (activity over the preceding year), Current Weekly Status, and Current Daily Status, the last of which best captures underemployment.
    3. It has historically surveyed urban areas quarterly but rural areas only annually, a frequency gap that limits its ability to track rural distress as it develops.

    “[2023, GS3, 15 marks] Most of the unemployment in India is structural in nature. Examine the methodology adopted to compute unemployment in the country and suggest improvements.”

  • Gross FDI hit 15-year high of $30.7 billion in April-June 2026

    Gross FDI hit 15-year high of $30.7 billion in April-June 2026

    Why in the News

    Reserve Bank of India (RBI) data shows gross Foreign Direct Investment (FDI) inflows reached $30.7 billion in April-June 2026, the highest quarterly figure in fifteen years. Net FDI, which nets out repatriation and disinvestment by existing foreign investors, turned positive again in June 2026 at $1.3 billion, after a period of elevated repatriation had kept it depressed. Singapore, the Netherlands, the United States and Canada led the inflows, concentrated in manufacturing. The tension is between the strength of the gross inflow figure and the much smaller net figure, since heavy repatriation by existing foreign investors has been offsetting fresh inflows for several preceding quarters.

    What does the data show?

    1. Fifteen-year high in gross inflows: Gross FDI of $30.7 billion in a single quarter is the highest recorded in fifteen years, reversing a period of relatively subdued inflows.
    2. Net FDI turns positive: Net FDI turned positive in June 2026 at $1.3 billion, after running negative or near zero in preceding months.
    3. Source and sector concentration: Singapore, the Netherlands, the United States and Canada were the leading source countries, with manufacturing the leading destination sector.

    Why does the gap between gross and net FDI matter?

    1. Repatriation pressure: A large gap between gross and net FDI signals that existing foreign investors have been exiting or repatriating profits at a pace close to new inflows. This is a different signal from headline inflow growth alone.
    2. Policy implication: A durable improvement in net FDI, not gross inflows alone, is the more reliable indicator of investor confidence in staying invested in India over the medium term.

    Gross FDI vs Net FDI

    • Gross FDI: Fresh foreign investment entering India.
    • Net FDI: Gross inflows after accounting for repatriation and disinvestment.
    • A large gap between gross and net FDI indicates that substantial investment is also flowing out through existing investors.
    • Therefore, high gross FDI does not necessarily mean high net FDI.

    “[2022] Which one of the following situations best reflects “Indirect Transfers” often talked about in media recently with reference to India ?
    (a) An Indian company investing in a foreign enterprise and paying taxes to the foreign country on the profits arising out of its investment
    (b) A foreign company investing in India and paying taxes to the country of its base on the profits arising out of its investment
    (c) An Indian company purchases tangible assets in a foreign country and sells such assets after their value increases and transfers the proceeds to India
    (d) A foreign company transfers shares and such shares derive their substantial value from assets located in India

  • Fair pricing could help sustain UPI network

    Fair pricing could help sustain UPI network

    Why in the News

    The op-ed, by a NITI Aayog consultant, argues that the zero-Merchant Discount Rate (MDR) regime underpinning Unified Payments Interface (UPI)‘s free-to-use model is financially unsustainable, and proposes a differentiated pricing structure as the Department of Financial Services examines whether to restore MDR for high-threshold transactions or merchants. The piece is pegged to a Parliamentary Standing Committee on Finance report tabled this month, which cited an industry estimate of about Rs 20,700 crore in annual UPI operating costs against a Rs 2,000 crore government allocation under the zero-MDR regime.

    What is the fiscal problem with UPI’s current pricing model, and what does the op-ed propose?

    1. The cost-subsidy gap is large and quantified: The Parliamentary Standing Committee on Finance’s report cited industry estimates of roughly Rs 20,700 crore in annual UPI operating costs, against a government allocation of only Rs 2,000 crore under the zero-MDR regime, with banks and payment companies absorbing the balance.
    2. Two restructuring options are formally under examination: The Department of Financial Services is examining restoring MDR for certain high-threshold transactions or merchants, and separately, phasing out government support through a tiered incentive structure.
    3. The op-ed’s proposed principle is differentiated, not uniform, pricing: It argues for keeping UPI free for consumers and small merchants while allowing a capped MDR for larger commercial users and higher-value transactions, on the basis that a uniform rate would be negligible for a large retailer but consequential for a street vendor.
    4. The author’s own research links merchant ecosystem formalisation to UPI adoption: Citing research with Sharon Buteau, the op-ed states that more formalised merchant ecosystems are associated with higher UPI use, and that MDR design should be calibrated to where acceptance networks are still developing rather than applied uniformly.
    5. Aggregated payment data is proposed as a second, non-MDR revenue and policy tool: The op-ed cites PhonePe’s PulsePro and a recent MoU with the Ministry of Electronics and Information Technology (MeitY) to integrate UPI transaction metrics into PM GatiShakti for infrastructure and economic planning, arguing that privacy-safe aggregated payment signals have public value independent of any pricing decision.

    Conclusion

    The op-ed’s position is that UPI’s zero-MDR model has reached a fiscal limit documented by Parliament’s own Standing Committee, and that a threshold-based, differentiated MDR, protecting small merchants and consumers while pricing larger commercial transactions, is a more sustainable path than either continuing an unfunded subsidy or imposing a uniform fee that would slow onboarding in less-formalised markets.

    Back2Basics

    1. Merchant Discount Rate (MDR): The fee a merchant pays to their bank or payment service provider for accepting digital payments, historically waived to zero on UPI and RuPay debit card transactions in India since January 2020 to encourage adoption.
    2. Unified Payments Interface (UPI): A real-time payment system developed by the National Payments Corporation of India (NPCI) that enables instant interbank transactions through a single mobile application.

    “[2023, GS3, 10 marks] What is the status of digitalization in the Indian economy? Examine the problems faced in this regard and suggest improvements.”

  • NITI Aayog: Degrees like BA, B.Sc, B.Com have ‘weak job linkages’, need reforms

    NITI Aayog: Degrees like BA, B.Sc, B.Com have ‘weak job linkages’, need reforms

    Why in the News

    NITI Aayog has flagged that unemployment among graduates remains far higher than the national average, and that over-reliance on generic degrees such as BA, B.Sc and B.Com is contributing to the problem. The finding comes amid a renewed push to redesign India’s skilling architecture toward specialised, job-linked programmes.

    What does NITI Aayog’s assessment find?

    1. Most graduates work outside their field of study: Over 90% of India’s graduates are employed in roles not aligned with their qualifications.
    2. The disconnect is curriculum level: NITI Aayog states that curriculum in most institutions remains outdated and misaligned with evolving industry needs, producing degrees and diplomas with weak job linkages.
    3. The proposed direction is sector specific: The think tank makes the case for moving toward specialised, job-linked programmes in high-growth sectors such as green industries and electric vehicles, with greater emphasis on apprenticeships.

    Conclusion

    NITI Aayog’s assessment reframes graduate unemployment as a curriculum design problem rather than only a labour demand problem, and its recommendation is a shift from generic degrees toward sector-specific, apprenticeship-linked training in high-growth industries.

    “[2015, GS3, 12 marks] The nature of economic growth in India in recent times is often described as a jobless growth. Do you agree with this view? Give arguments in favour of your answer.”