💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Economics

  • [12th November 2025] The Hindu Op-ed: Exploited workers, a labour policy’s empty promises

    PYQ Relevance

    [UPSC 2024] Discuss the merits and demerits of the four ‘Labour Codes’ in the context of labour market reforms in India. What has been the progress so far in this regard?

    Linkage: Building directly on the same reform trajectory, the draft Shram Shakti Niti 2025 extends the labour codes’ framework of ease of doing business over worker protection. This highlights continued informalisation and weak enforcement.

    Mentor’s Comment

    India’s draft Shram Shakti Niti 2025 arrives at a critical juncture, when over 90% of India’s workforce is informal, and 11 million people endure modern slavery-like conditions. While the government calls it a “rights-driven, future-ready” labour vision grounded in “ancient Indian ethos”, the policy remains mired in contradictions. Behind its digital optimism and flexibility rhetoric lie deep structural issues, casualisation, exclusion of women, erosion of unions, and poor enforcement of safety norms. This article analyses how the draft Shram Shakti Niti 2025 attempts reform but risks widening inequality instead of bridging it.

    Introduction

    India’s labour force, the world’s largest after China, is undergoing unprecedented informalisation. A majority of workers remain without contracts, benefits, or occupational safety, particularly in construction, seafood, textiles, and stone quarrying. Against this backdrop, the government has unveiled the draft Shram Shakti Niti 2025, the first comprehensive labour and employment policy in independent India, aimed at aligning with India@2047 goals. Yet, its “future-ready” tone contrasts sharply with the daily struggles of India’s informal workers. The draft blends cultural nostalgia with digital platforms and flexible labour regimes, but experts warn that without strong safeguards, it may formalise exploitation under a new vocabulary of efficiency and empowerment.

    Why is the draft Shram Shakti Niti 2025 significant?

    1. First comprehensive labour policy: India has never had a single overarching labour and employment policy before; this is the first draft of its kind.
    2. Presented as “rights-driven” and “future-ready”: The draft positions itself as a framework for inclusive, dignified employment by 2047.
    3. Ground reality contrast: It appears while millions remain in debt bondage or unsafe informal work, revealing a sharp policy-practice gap.
    4. Cultural framing: It draws legitimacy from “ancient Indian ethos” and texts like Manusmriti, a move critics call regressive in a modern labour context.

    Does the draft empower workers or employers?

    1. Contractual and casual labour domination: In several sectors (textiles, seafood, stone quarries), workers are hired by middlemen without contracts, paid daily wages, and denied ESI or PF benefits.
    2. Employer-biased flexibility: The draft promotes “ease of doing business” but underplays enforcement of worker rights, effectively institutionalising job insecurity.
    3. Constitutional dilution: The framework overlooks Articles 14, 16 and 21, which guarantee equality, opportunity, and dignity, replacing them with moral and cultural justifications.
    4. ILO mismatch: The policy ignores obligations under ILO Conventions 42, 155, and 156, especially concerning maternity protection, safety, and gender equity.

    Can digital optimism bridge the informal-formal divide?

    1. Digital skilling and employment matching: The draft relies heavily on AI-driven National Career Service (NCS) and Skill India digital platforms, promising to reduce mismatches.
    2. Reality check: Digital literacy in India remains at 38%, and most informal workers, particularly women and the elderly, remain excluded from such systems.
    3. eSHRAM limitations: Despite over 30 crore registrations, payouts remain minimal and inconsistent, with large data gaps for unorganised workers.
    4. Algorithmic exclusion: Tech-based hiring may amplify caste and gender bias, lacking oversight on fairness, grievance redress, or algorithmic accountability.

    Does the draft align with constitutional and global standards?

    1. Constitutional inconsistency: Ignores equality provisions (Articles 14-16) and fails to guarantee dignity (Article 21) by sidelining unionisation and inspectorate powers.
    2. ILO and OECD compliance gap: India risks non-alignment with ILO Conventions 87 and 98 (freedom of association and collective bargaining) and OECD recommendations on equitable labour transitions.
    3. Rights to collective action: Tripartite bodies (state, employer, worker) are mentioned but not institutionally strengthened, weakening labour representation.

    What are the draft policy’s main areas of concern?

    1. Inspectorate dilution: Reduction in on-ground inspections under the garb of self-certification leads to unchecked safety violations.
    2. Gendered impact: While women’s participation is targeted to rise to 35% by 2047, no clear mechanism ensures safe, accessible, or equitable workplaces.
    3. Wage inequality and gig exclusion: Wage Code 2019 is silent on platform workers’ benefits, leaving gig labourers outside social protection systems.
    4. Union erosion: By promoting individual “digital dashboards” over collective negotiations, the draft undermines trade union power and collective action.

    What should guide India’s final labour framework?

    1. Universal social protection floor: Extend ESI, EPFO, and health coverage to informal and gig workers.
    2. Reinstate labour inspectorates: Institutionalise independent audits for occupational safety and minimum wage compliance.
    3. Gender-responsive budgeting: Make gender equity measurable through labour audits, wage reporting, and leadership representation.
    4. Digital inclusion safeguards: Ensure data privacy, algorithmic fairness, and accessibility for low-literacy workers.
    5. Constitutional morality over cultural ethos: Replace rhetoric with enforceable rights, ensuring compliance with Articles 14, 19, 21, and 23 (prohibition of forced labour).

    Conclusion

    The draft Shram Shakti Niti 2025 aspires to modernise India’s labour market, but its moral overtones and digital bias risk leaving the poorest behind. Without strong enforcement, union empowerment, and gender-sensitive safeguards, this “future-ready” vision may perpetuate rather than resolve inequality. India’s final policy must reflect constitutional morality, not cultural nostalgia, ensuring labour dignity remains the cornerstone of economic growth.
  • Centre notifies new Deep-Sea Fishing Rules

    Why in the News?

    The Centre has issued new rules for Deep-Sea Fishing within India’s Exclusive Economic Zone (EEZ) to enhance sustainability, digital governance, and fisher empowerment.

    About the New Deep-Sea Fishing Rules:

    • Objective: To enable a shift from near-shore to deep-sea fishing, expand exports, and adopt digitally monitored, eco-friendly fishing practices.
    • Key Features:
      • Domestic Priority: Fishermen Cooperatives and Fish Farmer Producer Organisations (FFPOs) get first rights to operate advanced deep-sea vessels.
      • Mother-and-Child Vessel Model: A large “mother” vessel supported by smaller “child” crafts for mid-sea transhipment– crucial for Andaman & Nicobar and Lakshadweep, which together hold ~49% of India’s EEZ.
      • Digital Access and Traceability: Mechanised vessels must secure Access Passes via the ReALCraft portal; linked with MPEDA and EIC for traceability, sanitary certification, and eco-labelling.
      • Foreign Vessel Ban: Absolute prohibition on foreign vessels operating in Indian EEZ to safeguard domestic and small-scale fishers.
      • Ban on Destructive Practices: LED-light fishing, pair trawling, and bull trawling banned; minimum legal catch sizes and Fisheries Management Plans (FMPs) to be developed with states.
      • Origin Status Recognition: Catches from India’s EEZ beyond the contiguous zone to be treated as “Indian origin” for customs, avoiding import treatment.
      • Capacity Building and Credit: Fisher training, processing, and export support integrated with PM Matsya Sampada Yojana (PMMSY) and Fisheries and Aquaculture Infrastructure Development Fund (FIDF).
      • Safety and Monitoring: Mandatory transponders, QR-coded Fisher IDs, and Nabhmitra-linked navigation; monitoring by Coast Guard and Navy.

    Back2Basics: Exclusive Economic Zone (EEZ)

    • Definition: Under the 1982 UN Convention on the Law of the Sea (UNCLOS), an EEZ extends 200 nautical miles (~370 km) from a coastal baseline, granting sovereign rights to exploit marine resources.
    • Rights of Coastal States: Include resource exploration, marine research, environmental protection, and installation of artificial structures.
    • Distinction from Territorial Sea: The territorial sea (12 nm) grants full sovereignty; the EEZ confers resource jurisdiction while preserving navigation and overflight rights of other nations.
    • Indian Context:
      • EEZ: Spans ~2.30 million km², one of the world’s largest, supporting fisheries, hydrocarbons, and seabed minerals.
      • Legal Framework: Governed by The Territorial Waters, Continental Shelf, EEZ and Other Maritime Zones Act, 1976, providing India’s legal basis for EEZ management.
  • Where states stand on revenue collections, before and after GST

    Introduction

    Introduced in 2017, the Goods and Services Tax (GST) replaced multiple indirect taxes at both Central and State levels, including excise duty, service tax, and VAT, creating a unified national tax framework. The recent data released by the Central Government for October 2025 indicates a 4.6% year-on-year increase in total revenue collection to ₹1,95,936 crore. However, the state-wise analysis has revealed an emerging concern: while some states have achieved strong revenue growth, others are struggling to reach even pre-GST revenue-to-GDP ratios.

    Why in the News

    The latest data on GST revenue collection highlights contrasting fiscal trajectories across Indian states. Despite record-high GST collections nationally, several states’ tax-to-GDP ratios remain lower than before 2017, indicating a possible erosion of state fiscal autonomy. The issue has gained attention because:

    1. Sixteen states and Union Territories now earn a smaller share of revenue from GST than pre-GST taxes.
    2. The aggregate revenue from subsumed taxes has declined from 6.1% of GDP in 2015-16 to 5.5% in 2023-24.
    3. The average GST-to-GDP ratio over the past seven years is 2.6%, below the pre-GST average of 2.8%.
    4. This reversal is significant as it questions the efficacy of India’s largest tax reform and the viability of fiscal federalism under GST.

    How did GST Change the Tax Landscape?

    1. Unified Tax Framework: GST subsumed indirect taxes such as excise duty, VAT, and service tax under a single national structure, simplifying compliance.
    2. Revenue Flow Shift: Revenue previously collected by states under independent taxes now flows through a shared GST mechanism, altering fiscal control.
    3. Increased Central Dependence: States became dependent on GST compensation cess and Centre’s transfers for revenue stability, altering fiscal autonomy.
    4. Short-term Gains: Initially, GST led to better compliance and formalization, resulting in short-term revenue surges.

    How Are States Performing After GST?

    1. Diverse Outcomes: According to PRS Legislative Research, state-level GST revenues continue to trail the pre-GST levels as a share of GSDP.
    2. Declining Tax-to-GDP Ratio: Aggregate revenue from subsumed taxes fell from 6.1% (2015-16) to 5.5% (2023-24).
    3. Below-Average GST Performance: The seven-year average GST-to-GDP ratio (2.6%) is lower than the pre-GST average (2.8%).
    4. Top Performers: Maharashtra, Karnataka, Gujarat, Tamil Nadu, and Haryana have shown robust post-GST growth in tax collection.
    5. Lagging States: J&K, Punjab, Chhattisgarh, Madhya Pradesh, and Odisha recorded revenue decline from subsumed taxes as a percentage of GSDP.

    Which States Have Been Worst Affected?

    1. Northeastern States: Mizoram, Nagaland, Sikkim, Meghalaya, and Manipur saw an improvement in tax-to-GSDP ratios.
    2. Northern and Central States: Jammu & Kashmir, Punjab, Madhya Pradesh, Chhattisgarh, and Odisha saw a decline in subsumed tax revenues.
    3. Urban-Rural Divide: Industrial and service-oriented states benefited, while agrarian and resource-dependent states witnessed fiscal compression.
    4. GST Compensation End: After 2022, when the GST compensation guarantee ended, fiscal stress intensified for states heavily reliant on the compensation mechanism.

    What Does the Data Reveal About Fiscal Federalism?

    1. Centre-State Revenue Imbalance: 20 out of 36 states/UTs now collect less than 40% of their revenue from GST, deepening fiscal asymmetry.
    2. Medium-term Fiscal Impact: The 15th Finance Commission projected a GST-to-GDP ratio of 7%, but current data reflects underperformance.
    3. Long-term Fiscal Risks: Declining state revenue autonomy may affect social spending and capital expenditure, widening regional disparities.
    4. Compliance Inefficiency: Multiple tax slabs, refund delays, and compliance burdens continue to affect smaller states’ GST efficiency.

    Conclusion

    The GST has achieved its unification objective but has not yet ensured revenue equity across states. While high-compliance, industrial states have benefited, smaller and agrarian states remain fiscally strained. The data underscores the need for recalibrating the GST architecture, simplifying slabs, improving IT infrastructure, and enhancing fiscal transfers, to align with the spirit of cooperative federalism and fiscal balance.

    PYQ Relevance

    [UPSC 2019] Enumerate the indirect taxes which have been subsumed in the Goods and Services Tax (GST) in India. Also, comment on the revenue implications of the GST introduced in India since July 2017.

    Linkage: It evaluates the impact of GST on Centre-State revenue balance and indirect tax structure post-2017.

  • [7th November 2025] The Hindu Oped: Redraw welfare architecture, place a UBI in the centre

    PYQ Relevance

    [UPSC 2015] In what way could replacement of price subsidy with Direct Benefit Transfer (DBT) change the scenario of subsidies in India? Discuss.

    Linkage: The shift from price subsidies to Direct Benefit Transfers (DBT) improved efficiency and targeting in welfare delivery. Universal Basic Income (UBI) is the next step in this evolution, moving from targeted transfers to universal, unconditional income support that ensures inclusion and economic stability.

    Mentor’s Comment

    As automation, artificial intelligence, and widening inequality reshape global economies, India faces an urgent need to rethink its welfare model. Universal Basic Income (UBI) , once dismissed as utopian, is emerging as a viable economic tool to balance growth with inclusion, stabilize consumption, and future-proof citizens against technology-driven disruptions.

    Introduction and Why in the News

    India’s wealth gap is at a 75-year high, and technological transformation is outpacing job creation. The article argues that a Universal Basic Income could act as a stabilizer for an economy characterized by automation-led job loss, consumption inequality, and welfare fragmentation. UBI thus represents both an economic necessity and moral evolution, a reform that can ensure social security while sustaining demand in an AI-driven economy.

    Understanding UBI in the Economic Context

    1. Concept: A periodic, unconditional cash transfer to all citizens, regardless of income or employment.
    2. Economic Foundation: Acts as a floor for consumption and stabilizer of demand during economic downturns.
    3. Rationale in India: Addresses inefficiencies, leakages, and exclusions in existing welfare subsidies and improves fiscal targeting through direct transfers.
    4. Global Relevance: Countries like Finland, Kenya, and Iran have experimented with variants of basic income to address automation shocks and inequality.

    Why India Needs a New Welfare Model

    • Automation and Jobless Growth:
      1. India’s labour-intensive sectors are losing relevance as AI and robotics replace routine work.
      2. A 2023 McKinsey Report estimates 40-45% of Indian jobs risk automation by 2030.
      3. Consumption Inequality: The top 10% hold over 40% of total income, weakening demand from lower strata, a key factor behind India’s K-shaped recovery post-COVID.
    • Fragmented Welfare Spending:
      1. Over 950 central schemes exist; only 20% reach intended beneficiaries (NITI Aayog, 2022).
      2. Rationalizing and merging subsidies could free 1-2% of GDP, enough to fund a phased UBI.

    Fiscal Feasibility and Implementation Models

    1. Budgetary Realignment: A UBI costing ₹7,500 per person annually = ~1% of GDP, fiscally manageable by pruning inefficient subsidies.
    2. Digital Readiness: India’s JAM Trinity (Jan Dhan-Aadhaar-Mobile) enables transparent Direct Benefit Transfers (DBT) to 450+ million beneficiaries.
    3. Phased Approach:
      • Start with vulnerable groups (elderly, women, informal workers) and expand gradually.
      • Link with automation tax or digital economy levy to ensure sustainability.
    4. Behavioral Economics View: Unconditional transfers improve human capital investment (nutrition, education) without creating disincentive to work, proven in Madhya Pradesh SEWA UBI Pilot, 2013.

    UBI as an Economic Stabilizer

    1. Counter-Cyclical Tool: Maintains aggregate demand in economic slowdowns; ensures liquidity among lower-income households.
    2. Productivity Boost: Financial security allows workers to upskill and pursue entrepreneurial ventures instead of insecure subsistence jobs.
    3. Gender Dividend: Recognizes unpaid care work and enhances female labour participation, a major economic multiplier.
    4. Rural Resilience: Ensures income continuity against climate shocks, agrarian distress, and market failures.

    Challenges in Adopting UBI

    1. Fiscal Trade-offs: High recurring costs could strain the fiscal deficit if not balanced by rationalization of subsidies.
    2. Inflationary Pressure: Sudden increase in liquidity may spike prices unless accompanied by supply-side reforms.
    3. Exclusion Risks via Aadhaar/DBT: Digital divide and authentication errors can replicate old exclusion patterns.
    4. Political Economy Resistance: Targeted benefits create patronage networks; universalization dilutes control, making reform politically sensitive.

    Global Insights for India

    Country Nature of UBI Trial Lessons
    Finland (2017-18) €560/month for unemployed Improved well-being, not joblessness
    Kenya Cash transfer for 12 years Increased small business formation
    Iran (2010) Universal transfer replacing subsidies Reduced poverty without fiscal collapse
    Brazil (Bolsa Família) Conditional transfer, near-universal Boosted literacy, health, consumption

    India can blend these experiences into a hybrid model: quasi-universal, fiscally prudent, and tech-enabled.

    Conclusion

    A Universal Basic Income is no longer a moral luxury, it is an economic inevitability in a future where automation, inequality, and climate shocks converge. By realigning subsidies and leveraging digital infrastructure, India can embed economic dignity into fiscal policy. UBI is not about welfare dependency, it is about stabilizing markets through empowered citizens.

  • Govt panel working on New SEZ Norms for Exporters to Access Domestic Market

    Why in the News?

    A government panel comprising officials from the Commerce and Industry Ministry, NITI Aayog, and exporters is drafting new Special Economic Zone (SEZ) norms to revive manufacturing and support exporters hit by steep U.S. tariffs in 2025.

    Back2Basics: Special Economic Zones (SEZs) in India

    • Overview: Duty-free enclaves treated as foreign territory for trade, designed to boost exports, investment, and employment.
    • Legal Framework: Governed by the SEZ Act, 2005 and SEZ Rules, 2006 with single-window clearances and liberal FDI norms.
    • Policy Evolution: Introduced in 2000, replacing Export Processing Zones (EPZs) to strengthen export-led industrialization.
    • Objectives: Promote export growth, foreign and domestic investment, and infrastructure creation.
    • Incentives: Include duty-free imports, tax holidays, zero-rated GST, and ECB up to $500 million annually.
    • Scale: As of 2025, India has 276 operational SEZs– notably GIFT City (Gujarat), SEEPZ (Mumbai), and Noida SEZ.
    • Reform Outlook: The Development of Enterprise and Service Hubs (DESH) Bill 2022 aims to evolve SEZs into flexible, multi-use economic hubs linking domestic and global value chains.

    Need for SEZ Norms Revision:

    • U.S. Tariff Impact: Recent U.S. tariff hikes on gems, jewellery, and textiles have reduced price competitiveness of India’s SEZ-based exporters, leading to production losses.
    • Export Decline: SEZ exports dropped to $172 billion (FY25), with domestic sales stagnating at 2%, exposing overdependence on foreign markets.
    • Idle Capacity & Job Losses: Fluctuating export demand left labour and machinery underutilised; reforms aim to let SEZs meet domestic orders during downturns.
    • Global Benchmarking: Indian SEZs lag China and Vietnam in scale, policy stability, and productivity, prompting structural reform for competitiveness.
    • Revenue Balance: The government seeks industry relief while safeguarding tax revenues, given SEZs’ extensive tax exemptions.

    Proposed SEZ Reforms under Review:

    • Reverse Job Work Permission: SEZs may be allowed to accept domestic processing contracts to use idle capacity during off-peak seasons.
    • DTA Sales Flexibility: Partial permission for direct domestic sales, with duty adjustments to protect local manufacturers.
    • Simplified De-notification Rules: Faster conversion of non-performing SEZs into industrial parks or enterprise hubs.
    • Sectoral Support: Gems and jewellery exporters seek moratoriums, longer export obligations, and interest relief.
    • Integration with DESH Bill (2022): Adoption of hybrid zone model for both exports and domestic production under the Development of Enterprise and Service Hubs framework.
    [UPSC 2010] The SEZ Act, 2005 which came into effect in February 2006 has certain objectives. In this context, consider the following:
    1. Development of infrastructure facilities. 2. Promotion of investment from foreign sources. 3. Promotion of exports of services only.
    Which of the above are the objectives of this Act?
    Options: (a) 1 and 2 only* (b) 3 only (c) 2 and 3 only (d) 1,2 and 3

    [UPSC 2016] Recently, India’s first ‘National Investment and Manufacturing Zone’ was proposed to be set up in-
    Options: (a) Andhra Pradesh* (b) Gujarat (c) Maharashtra (d) Uttar Pradesh


  • Madras HC calls Cryptocurrency ‘Property’

    Why in the News?

    In a historic first for India, the Madras High Court has recognized cryptocurrency as “property” under Indian law, providing judicial validation to digital assets long trapped in a regulatory grey zone.

    What is Cryptocurrency?

    • Overview: Cryptocurrency is a digital or virtual currency that uses cryptography for security, making it difficult to counterfeit or double-spend.
    • Nature: It is decentralized, operating on blockchain technology — a distributed ledger maintained across a network of computers.
    • Key Features: Pseudonymity, transparency, global accessibility, and independence from central banks.
    • Examples: Bitcoin (BTC), Ethereum (ETH), Ripple (XRP), and others.
    • Function: Used as a medium of exchange, store of value, or investment asset, depending on its design and acceptance.

    Case Details:

    • Case Title: Rhutikumari vs Zanmai Labs Pvt. Ltd. (WazirX Operator) — Madras High Court, October 25, 2025.
    • Context: WazirX froze the petitioner’s account after a $230 million crypto hack (July 2024), even though her assets (3,532 XRP) were unrelated to the theft.
    • Petitioner’s Argument: Her cryptocurrency holdings constituted private property wrongfully frozen without due process.
    • Respondent’s Defence: The freeze was a security measure, and disputes should be referred to Singapore arbitration.
    • Court’s Decision: Justice N. Anand Venkatesh ruled that cryptocurrencies, though intangible, qualify as property since they can be owned, possessed, transferred, and enjoyed.
    • Order: WazirX directed to deposit ₹9.56 lakh in escrow until arbitration concludes.
    • Precedents Cited:
      • Ruscoe v. Cryptopia Ltd (New Zealand): Crypto assets recognized as property held in trust.
      • AA v. Persons Unknown (UK): Bitcoin acknowledged as an asset capable of ownership and protection.

    Legal Implications of the Ruling:

    • Recognition of Ownership Rights: Establishes that cryptocurrency holders have property rights enforceable under Indian civil law.
    • Investor Protection: Enables crypto investors to seek injunctions, escrow relief, and proprietary claims in disputes with exchanges.
    • Liability of Exchanges: Exchanges can be held accountable for wrongful freezing or security failures; “force majeure” cannot justify loss of investor assets.
    • Insolvency Proceedings: Cryptocurrencies can now be treated as assets of an estate, strengthening recovery mechanisms in bankruptcy or liquidation.
    • Judicial Precedent: First Indian ruling to recognise crypto as legally protectable property, likely to influence future regulatory and tax interpretation.

    Legal Status of Cryptocurrency in India (as of 2025):

    • Legality: Cryptocurrencies are not legal tender but are legal to hold, trade, and invest within a regulated framework.
    • Taxation:
      • Classified as Virtual Digital Assets (VDAs) under the Finance Act, 2022.
      • 30% tax on gains; 1% TDS on trades above threshold limits.
    • Regulatory Oversight:
      • RBI: Monitors systemic risk; does not recognize crypto as currency.
      • SEBI: Supervises investment-related aspects.
      • FIU-IND: Enforces anti–money laundering compliance under PMLA (2023 extension).
    • Judicial Framework: Supreme Court (2020) struck down the 2018 RBI ban, enabling continued operation of exchanges.
    • RBI Policy Direction:
      • Promotes Digital Rupee (CBDC) as a regulated alternative.
      • Allows limited banking access to compliant crypto entities under strict KYC/AML rules.

    Conclusion:

    • Crypto is legal to own and trade, taxable as VDA, non-tender, and subject to compliance norms.
    • The Madras High Court ruling elevates its status from a digital asset to a judicially recognized form of property, filling a key legal gap in India’s crypto regulation.
    [UPSC 2020] Discuss how emerging technologies and globalisation contribute to money laundering. Elaborate measures to tackle the problem of money laundering both at national and international levels?

    [UPSC 2019] What is Cryptocurrency? How does it affect global society? Has it been affecting Indian society also?


  • Fully Accessible Route (FAR) of Investment

    Why in the News?

    In 2025, foreign investors have invested only about ₹69,000 crore ($7.8 billion) nearly half than expected, into Indian government bonds, even though the rules were made simpler and more flexible under the Fully Accessible Route (FAR) to attract more investment.

    What is Fully Accessible Route (FAR)?

    • Overview: A special investment framework launched by the Reserve Bank of India (RBI) in March 2020 to attract foreign investment in Indian government securities (G-secs).
    • Purpose: Aims to liberalise India’s debt market, enhance foreign participation, and integrate it with global financial systems.
    • Eligible Investors: Open to Foreign Portfolio Investors (FPIs), Non-Resident Indians (NRIs), and Overseas Citizens of India (OCIs) without investment caps.
    • Key Feature: Permits unlimited foreign investment in designated government bonds with free buy–sell access and no quantitative ceiling.
    • Liquidity & Integration: Designed to improve bond market depth, diversify funding sources, and boost India’s visibility in global debt indices.
    • Repatriation Freedom: Allows investors to repatriate capital and profits freely to their home countries.
    • Global Milestone: In June 2024, JP Morgan included 29 Indian G-secs under FAR in its Emerging Market Bond Index (EMBI), marking India’s debut in major global bond benchmarks.

    Comparison with Other Routes:

    1. Medium Term Framework (MTF): Allows foreign investment in G-secs but with limits and conditions on exposure and tenure.
    2. Voluntary Retention Route (VRR): Permits FPIs to invest in G-secs provided they retain investments for a minimum period, ensuring stable long-term inflows.

    Complementary Function: FAR, MTF, and VRR operate together, providing flexibility in investment terms and balancing market stability with foreign access.

    Why were higher inflows expected?

    • Projected Inflows: Index inclusion in 2024–25 was expected to attract $20–25 billion from global institutional and index-tracking investors.
    • Attractiveness Factors: India’s 7% stable yields, macroeconomic strength, and favourable risk–return ratio made it a promising destination for long-term capital.
    • Actual Outcome: Only $10.7 billion flowed in during 2024-25: well below expectations.
    • Key Reasons:
      • Global monetary uncertainty: investors awaited clarity on the US Federal Reserve’s rate policy.
      • Domestic caution: RBI removed 14- and 30-year bonds from FAR in 2024 to reduce volatility.
      • Geopolitical tensions and FPI withdrawals from equities reduced investor appetite.
    • Significance: Despite lower inflows, FAR remains a structural reform strengthening India’s position as a globally accessible and competitive bond market.
    [UPSC 2024] Consider the following statements:

    1. In India, Non-Banking Financial Companies can access the Liquidity Adjustment Facility window of the Reserve Bank of India.

    2. In India, Foreign Institutional Investors can hold the Government Securities (G-Secs).

    3. In India, Stock Exchanges can offer separate trading platforms for debts.

    Which of the statements given above is/are correct?

    Options: (a) 1 and 2 only (b) 3 only (c) 1, 2 and 3 (d) 2 and 3 only*


  • [3rd November 2025] The Hindu Op-ed: Cruising ahead, India’s shipping sector needs help from the government to thrive

    PYQ Relevance

    [UPSC 2021] Investment in infrastructure is essential for more rapid and inclusive economic growth. Discuss in the light of India’s experience.

    Linkage: This question assesses the role of infrastructure investment in driving inclusive and sustainable economic growth, a core theme under GS Paper III. It directly links to the article’s discussion on India’s renewed focus on port-led development and maritime self-reliance as catalysts for national growth and strategic autonomy.

    Mentor’s Comment

    The article highlights India’s renewed focus on its maritime and shipping sector, a domain long overshadowed by globalisation-led neglect and privatisation. As the government signals intent to revive indigenous shipping strength, the discussion becomes crucial for UPSC aspirants studying issues of economic infrastructure, logistics, Atmanirbhar Bharat, and India’s maritime strategy under GS Paper 3 (Infrastructure: Transport and Shipping).

    Introduction & Why in the News

    At the India Maritime Week, Prime Minister Narendra Modi underlined that shipping is not merely a business but a strategic national asset. This marks a policy shift, after decades of liberalisation and privatisation which weakened India’s domestic fleet and shipbuilding capacity. With the pandemic exposing India’s dependence on foreign-owned ships, the government has now initiated fresh investments, port reforms, and fleet strengthening measures to make Indian shipping globally competitive once again.

    Reclaiming India’s Maritime Strength

    1. Decline under Liberalisation: Over two decades of globalisation and privatisation led to weakened domestic shipping, with the Shipping Corporation of India (SCI) losing state backing and market share.
    2. Loss of Strategic Autonomy: Reliance on foreign ships reduced India’s ability to secure trade routes and logistics during crises.
    3. Pandemic Wake-up Call: COVID-19 disruptions exposed this overdependence, renewing calls for self-reliance and fleet revival.

    How Government Policies Shaped the Sector’s Decline

    1. Privatisation and Reduced Support: The ideological shift toward liberalisation led to reduced state ownership and limited investment in domestic capacity.
    2. Withdrawal of Favourable Policies: Earlier advantages like first rights to transport India’s oil were withdrawn, eroding SCI’s competitiveness.
    3. Diluted Strategic Intent: Shipping became treated as a commercial, not strategic, enterprise unlike in major maritime nations such as China or South Korea.

    The Post-Pandemic Realisation: Shipping as Strategic Infrastructure

    1. Strategic Leverage: Post-COVID, the government realised that control over shipping fleets = control over supply chains, a critical factor during disruptions or wars.
    2. National Interests and Protectionism: As Western nations turned protectionist, India reoriented towards building indigenous capacity to ensure secure maritime logistics.
    3. New Investments Announced: Major port-related projects and transshipment hubs like Chennai and Kolkata were revived to strengthen domestic capabilities.

    Reforms and Initiatives: Building Self-Reliant Maritime Power

    1. Port-Led Development: Under the landlord model, India’s ports now share revenue with private players, encouraging efficiency and foreign participation.
    2. Transshipment Hubs: Development of Chennai and Kolkata projects reflects India’s ambition to capture cargo movement currently routed via Colombo or Singapore.
    3. Shipbuilding Incentives: Moves toward strengthening shipbuilding and ship repair capacity ensure domestic employment and reduce outflow of forex.
    4. Indian Seafarer Training: Focus on education and skill development enables Indian crew to compete internationally and serve domestic fleet expansion needs.

    Private Sector Role and Strategic Leverage

    1. Private Shipping Companies: Encouraged to register ships in India and operate via local subsidiaries to enhance fleet size.
    2. Financial Autonomy: SCI’s balance sheet strengthening and port reforms attract new investors.
    3. Insurance and Ancillary Services: Government aims to extend support to marine insurance, finance, and logistics for creating a complete maritime ecosystem.

    Conclusion

    India’s renewed emphasis on shipping marks a strategic reassertion of maritime sovereignty. As the government invests in ports, fleet expansion, and seafarer training, the focus must remain on integrating private capacity with national goals. True maritime power will come not from tonnage alone, but from strategic control over logistics, shipbuilding, and manpower. With sustained policy backing, India can transform from a cargo-dependent nation to a maritime leader.

  • Decoding India’s projected GDP

    Why in the News

    Union Minister Piyush Goyal stated that India will become a $30 trillion economy in 20-25 years, emphasising India’s “strength-to-strength” growth and the vision of matching the US economy in scale. However, an analysis of India’s GDP trajectory and exchange rate trends over the past 25 years suggests that this goal appears overstated unless the rate of economic growth increases substantially. The divergence between nominal GDP growth and exchange rate depreciation is central to understanding why India may fall short of this projection.

    How is the Size of an Economy Measured?

    1. Gross Domestic Product (GDP): Represents the total annual value of goods and services produced within a country.
    2. Nominal GDP: Expressed in current prices and domestic currency (rupees).
    3. Conversion to USD: For global comparison, GDP in rupees is divided by the exchange rate (₹ per $).
    4. Example: India’s nominal GDP in FY 2024 is ₹330 trillion, translating to about $3.9 trillion at an exchange rate of ₹84.6 per USD.
    5. Comparative Context: The US GDP in 2024 is estimated at $41 trillion, nearly 10 times India’s size.

    Where Does the Divergence in GDP Projection Arise?

    1. Historical Growth (25 years):
      • India’s nominal GDP grew at a compound annual growth rate (CAGR) of 10.3%.
      • The rupee depreciated by 3.08% per year.
      • This combination would yield a net dollar GDP growth of around 7.2% CAGR, resulting in a $31.9 trillion economy by 2048.
    2. Recent Growth (past 11 years):
      • India’s nominal GDP CAGR dropped to 8.2%.
      • The rupee’s depreciation averaged 3.08%, giving a dollar GDP CAGR of just 5.1%.
      • Under this trend, India’s GDP would reach only $17.4 trillion by 2048.
    3. Key Finding: The long-term projection is highly sensitive to assumptions. Small changes in growth or currency value lead to large differences in dollar GDP outcomes.

    Why is the $30 Trillion Target Difficult to Achieve?

    1. Slowing Growth Momentum: India’s nominal GDP growth rate has weakened since 2014, reflecting post-pandemic structural and demand-side constraints.
    2. Exchange Rate Depreciation: The rupee has steadily weakened over time, eroding the USD value of India’s output despite growth in rupee terms.
    3. Inflation Differential: India’s higher inflation compared to advanced economies results in faster currency depreciation, reducing the global GDP value.
    4. Projection Assumptions: To achieve $30 trillion, India must sustain a nominal GDP CAGR of ~11% and limit currency depreciation below 2.5%, a historically rare combination.

    Is the $30 Trillion Vision Still Useful?

    1. Aspirational Benchmark: The projection serves as a long-term vision anchor for policy and investment decisions, guiding structural reforms.
    2. Strategic Optimism: Such forecasts reflect confidence in India’s demographics, industrial potential, and service exports.
    3. Policy Implication: Even if unattained, the projection pushes economic governance to focus on productivity, export competitiveness, and rupee stability.

    What Needs to Change for Realising the Vision?

    1. Sustained High Growth: Requires double-digit nominal growth through manufacturing diversification, digital economy expansion, and logistics reforms.
    2. Rupee Stability: Demands foreign investment confidence, fiscal discipline, and stronger current account performance.
    3. Inflation Control: Stable inflation curbs depreciation and maintains global competitiveness.
    4. Structural Reforms: Continued focus on labour, land, and capital market reforms to support long-term productivity.

    Conclusion

    India’s $30 trillion projection embodies the nation’s growth ambition, but economic realism demands higher productivity, policy consistency, and exchange rate stability. Without stronger structural momentum, India may remain well below that figure by mid-century. The aspiration, however, serves as a strategic motivator to deepen reforms and strengthen global competitiveness.

    Value Addition

    Potential vs. Actual GDP

    • Concept: Potential GDP is the highest level of economic output a country can sustain without triggering inflation. Actual GDP is the output the economy is currently producing.
    • Analytical Insight: India’s $30 trillion projection represents potential GDP, based on the assumption of sustained double-digit nominal growth, efficient use of labour, and strong capital formation. However, actual GDP growth depends on real-world constraints such as productivity levels, policy bottlenecks, and infrastructure capacity.
    • Example: Between 2003-08, India’s actual growth (9%) was close to potential, driven by investment and exports. Post-2014, growth averaged ≈6-6.5%, showing an increasing gap due to slowing manufacturing, skill mismatch, and weak private investment.

    Nominal vs. Real Growth Distinction

    • Concept: Nominal GDP measures total output using current prices (includes inflation). Real GDP adjusts for inflation, showing actual growth in production volume.
    • Analytical Insight: A rise in nominal GDP may overstate economic progress if inflation is high or the rupee depreciates. Thus, even with strong nominal growth, India’s dollar GDP may stagnate or fall in global rankings.
    • Example: In FY2023-24, India’s nominal GDP grew by 9.6% in rupee terms, but the rupee’s depreciation from ₹79 to ₹83 per USD meant real GDP in dollar terms grew only 5%. This illustrates how inflation and currency value distort perceptions of “growth.”

    PYQ Relevance

    [UPSC 2020] Define potential GDP and explain its determinants. What are the factors that have been inhibiting India from realizing its potential GDP?

    Linkage: The PYQ tests conceptual clarity on potential GDP, its determinants, and growth constraint. This is a recurring UPSC theme reflecting India’s long-term economic health and reform needs.


  • Revisions in the Consumer Price Index (CPI)

    Why in the News?

    The Ministry of Statistics and Programme Implementation (MoSPI) has proposed major revisions in the Consumer Price Index (CPI) methodology, to be implemented in the new retail inflation series from February 2026.

    About the Consumer Price Index (CPI):

    • Overview: The CPI measures the average change over time in the prices paid by consumers for a fixed basket of goods and services typically consumed by households.
    • Purpose: It tracks retail inflation showing how the purchasing power of money changes due to price variations, and how living costs evolve across different population groups.
    • Components:
      • Food and Beverages: Cereals, pulses, vegetables, milk, meat, fish, sugar, and beverages.
      • Housing: Rent paid for rented houses and imputed rent for self-occupied dwellings.
      • Clothing and Footwear: Garments, textiles, footwear, and related goods.
      • Fuel and Light: LPG, kerosene, electricity, firewood, and other fuels.
      • Miscellaneous: Transport, communication, education, health, recreation, personal care, and other services.
    • Publishing Authority: The CPI is compiled and released by the Ministry of Statistics and Programme Implementation (MoSPI) through the National Statistical Office (NSO) every month.
    • Current Base Year: 2012, which is being revised to 2024 to reflect more recent household consumption patterns captured in the Household Consumption Expenditure Survey (HCES) 2023–24.
    • Coverage: Separate indices are compiled for Rural, Urban, and Combined (Rural + Urban) sectors to reflect diverse consumption and price patterns.
    • Types of CPI in India:
      1. CPI for Industrial Workers (CPI-IW): Base year 2016; tracks inflation for organized industrial workers; used for Dearness Allowance (DA) revisions.
      2. CPI for Agricultural Labourers (CPI-AL): Base year 1986–87; measures price changes faced by agricultural labourers.
      3. CPI for Rural Labourers (CPI-RL): Base year 1986–87; monitors inflation for rural households dependent on wage labour.
      4. CPI (Urban), CPI (Rural), and CPI (Combined): Base year 2012; represents national-level retail inflation and is the official measure of inflation in India.
    • Weightage: The relative importance (weight) of each component reflects its share in total household expenditure, for instance, food and beverages hold over 45%, while housing has 21.67% in urban CPI and 10.07% in all-India CPI.
    • Use and Importance:
      • Inflation Targeting: The Reserve Bank of India (RBI) uses CPI as the anchor for its Monetary Policy Framework, aiming for 4% ± 2% inflation.
      • Wage & Pension Adjustments: CPI is used to revise wages, pensions, and dearness allowances in both government and industrial sectors.
      • Policy Planning: It provides essential inputs for economic policy, poverty analysis, and fiscal decisions.
      • Economic Indicator: Serves as the primary indicator of cost of living, influencing interest rate decisions, tax indexation, and social welfare adjustments.

    Revisions in the Consumer Price Index (CPI)

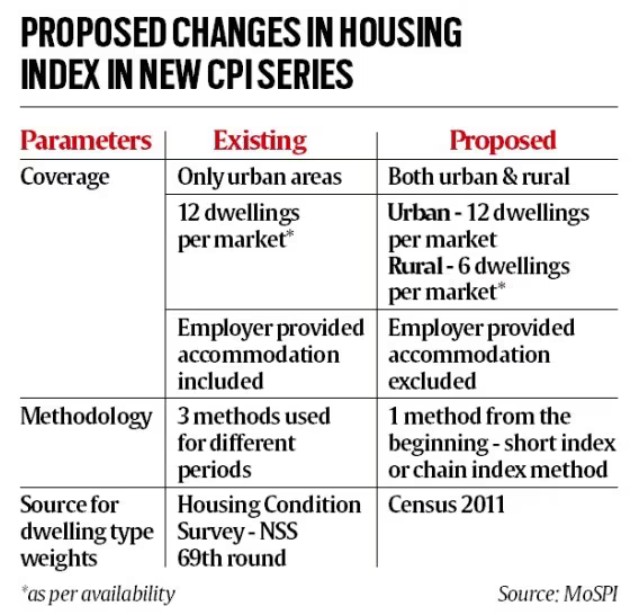
    Revisions in the CPI:

    • Monthly Rent Data: Collection every month for both rural & urban areas, replacing earlier six-monthly urban series.
    • Inclusion of Rural Housing: Covers imputed rents for owner-occupied rural dwellings.
    • Exclusion of Employer Housing: Removes HRA-based distortions from government/PSU quarters.
    • Expanded Sampling & IMF Alignment: Broader coverage, discontinuation of panel imputation, adoption of IMF-recommended rent index computation.
    • Weight Revision: Recalibrates housing share (currently 21.67 % urban; 10.07 % all-India) using new expenditure data.
    • Transparency: MoSPI discussion papers (2024-25) invite feedback on PDS treatment, housing index, and base methodology.

    Rationale & Impact:

    • Captures Post-Pandemic Rent Surge overlooked by the 2012 base.
    • Addresses Rural Under-coverage for two-thirds of India’s population.
    • Enhances RBI’s Inflation Targeting through more accurate rent data.
    • Aligns with Global Standards, strengthening CPI’s credibility as a comprehensive welfare and policy indicator.
    [UPSC 2020] Consider the following statements:
    1. The weightage of food in Consumer Price Index (CPI) is higher than that Wholesale Price Index (WPI).
    2. The WPI does not capture changes in the prices of services, which CPI does.
    3. Reserve Bank of India has now adopted WPI as its key measure of inflation and to decide on changing the key policy rates.
    Which of the statements given above is/are correct?
    Options: (a) 1 and 2 only* (b) 2 only (c) 3 only (d) 1, 2 and 3