💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Economics

  • Rupee is Asia’s worst performing currency

    Introduction

    The Indian Rupee has depreciated 4.3% against the US Dollar in 2025, making it Asia’s worst-performing currency. Analysts warn that the INR may slide to ₹90 per USD if the India-US trade deal does not materialise soon. The rupee’s movement is now driven more by global dollar strength than by domestic fundamentals. Persistent capital outflows, a rising trade deficit, U.S. tariffs, and a surge in gold imports have intensified pressure on the domestic currency.

    Why This Matters: Rupee Hits Asia’s Lowest Position

    The rupee’s sharp 4.3% calendar-year depreciation marks one of the steepest declines among Asian currencies. This contrasts sharply with the appreciation seen in much of the Asian currency complex, led by the Chinese Yuan through strong intervention by China’s central bank. The situation is aggravated by India’s record $41.7 billion trade deficit, U.S. tariff shocks, and a gold price spike that spurred a 200% rise in ETF investments. The worsening outlook raises concerns of the rupee breaching ₹90 per USD, a level not previously approached in recent years.

    Drivers Behind the Rupee’s Depreciation

    1. Global Dollar Strength: Dollar appreciation of 3.6% over two months increased pressure on most Asian currencies, including the INR.
    2. External Shocks:
      1. U.S. tariffs on Indian goods directly added stress.
      2. High precious metal prices increased import bills.
    3. Capital Outflows: The current account remains “benign”, but the depreciation is driven by capital flight, not trade fundamentals.
    4. Comparative Weakness: INR weakened more than IDR (2.9%) and PHP (1.3%), marking a distinct underperformance.

    Rupee’s Position Relative to Asian Peers

    1. Underperformance vs. China and Indonesia: Specialists note that while Indonesian Rupiah and Chinese Yuan have depreciated, INR weakened further.
    2. Better Than Structurally Weak Majors: INR still fares better than the Japanese Yen and Korean Won, which face domestic policy constraints.
    3. Asian Currency Complex Trend: Most Asian currencies appreciated, driven by Chinese intervention through PBOC/SAFE signalling.

    Market Movements and Recent Lows

    1. New Lows Recorded: Rupee touched 88.8 per USD on 21 November 2025, breaking earlier RBI-supported levels.
    2. Intraday Weakness: Fell further to 89.66, signalling intense currency-market stress.
    3. Partial Recovery: Rupee recovered to 89.22 by Tuesday, though still significantly weaker on a monthly basis.

    Trade Deficit and Macro Pressures Intensifying Rupee Weakness

    1. Record Trade Deficit: October witnessed a $41.7 billion merchandise trade deficit triggered by tariff hikes.
    2. Gold Import Surge:
      1. Gold imports spiked to $14.72 billion in October.
      2. Gold ETF demand rose by 200% due to soaring global prices.
    3. Twin External Shocks: Tariffs + gold price rise combine with geopolitical uncertainty to pressure the currency.

    Impact of the U.S. Tariffs and Policy Changes

    1. 50% Tariff Imposed by U.S.: Direct impact on India’s export competitiveness, worsening the trade deficit.
    2. Cumulative Effect on Rupee: Tariffs + gold imports + dollar strength + capital outflows create a compounding depreciation effect.
    3. Forward Outlook: Without a trade deal with the U.S., the rupee may breach ₹90 per USD.

    Conclusion

    The rupee’s position as Asia’s worst-performing currency signals deeper stresses in India’s external sector. The depreciation stems from global dollar dominance, tariff shocks, capital outflows, and rising import bills. While partial recoveries occur, the broader trajectory depends heavily on the India-US trade negotiations and management of external vulnerabilities. Ensuring macroeconomic stability will require coordinated steps in trade policy, forex management, and domestic economic resilience.

    PYQ Relevance

    [UPSC 2018] How would the recent phenomena of protectionism and currency manipulations in world trade affect macroeconomic stability of India?

    Linkage: It is directly linked to GS-3: External Sector, as it examines how tariffs and currency moves affect India’s macroeconomic stability. It is relevant for understanding exchange-rate volatility, CAD pressures, and global protectionist trends.
  • Capital Gains Accounts (Second Amendment) Scheme, 2025

    Why in the news? 

    The Ministry of Finance has notified the Capital Gains Accounts (Second Amendment) Scheme, 2025, introducing major changes to the existing Capital Gains Account Scheme (CGAS), 1988. The amendments aim to modernise processes, expand banking access, and increase clarity for taxpayers seeking capital gains exemptions.

    About Capital Gains Account Scheme (CGAS), 1988

    • Launched by the Central Government in 1988.
    • Objective: To help taxpayers claim exemptions on long-term capital gains when reinvestment cannot be completed before the ITR filing due date.
    • Linked mainly to Section 54, 54F, and related provisions of the Income Tax Act.

    Why CGAS is Needed?

    • Exemption requires reinvestment of capital gains within:
      • 2 years (purchase of property)
      • 3 years (construction of property)
    • If this period extends beyond the ITR filing deadline, the taxpayer can temporarily deposit unutilised gains in CGAS to keep the exemption claim valid.

    Important Conditions

    • Deposit must be made before filing Income Tax Return.
    • Money deposited is treated as reinvested for exemption.
    • If the amount is not utilised within the stipulated period, it becomes taxable long-term capital gains in that year.
    • Only long-term capital gains qualify — short-term gains are NOT eligible.

    Who Can Deposit in CGAS?

    • Any person with long-term capital gains, including: Individuals, HUFs, Companies, Firms, Trusts, and Any eligible taxpayer seeking exemption
    • Mainly used by property sellers who need more time to reinvest.

    Capital Gains Accounts (Second Amendment) Scheme, 2025 — Key Changes

    • Expansion of Authorized Banks: Previously limited mostly to Public Sector Banks + IDBI Bank.
      • Now extended to 19 private and small finance banks at all non-rural branches.
    • Non-rural branch condition: Branch must be located in an area with population ≥ 10,000 (2011 Census).
      • Rural branches cannot open CGAS accounts.
    • Wider Definition of Electronic Payments: Electronic deposits can now be made through: Credit cards, Debit cards, Net banking, IMPS, UPI, RTGS, NEFT and BHIM Aadhaar Pay.This modernises the earlier narrow definition of “electronic mode”.
    • Online Closure of CGAS Accounts (From April 1, 2027): Closure requests can be submitted electronically using:
      • Digital Signature (DSC)
      • Electronic Verification Code (EVC)
      • Earlier: Closure only through physical branches.
    • Clarification on Effective Date of Deposit: For cheque/DD/electronic transfers, the date of receipt of the payment instrument along with account application at the Deposit Office is treated as the effective date.Removes ambiguity around last-day deposits for tax exemption.
    • Electronic Statements Permitted: Banks can now issue electronic statements instead of physical passbooks.
      • Aligns CGAS with general digital banking norms.
    •  Extension of CGAS to Section 54GA: CGAS can now be used for exemptions under Section 54GA:

      • Relates to capital gains arising from shifting an industrial undertaking from an urban area to a Special Economic Zone (SEZ).
      • Broadens applicability beyond property-related reinvestments.
    Consider the following statements: (2025)

    I. Capital receipts create a liability or cause a reduction in the assets of the Government. 

    II. Borrowings and disinvestment are capital receipts. 

    III. Interest received on loans creates a liability of the Government. 

    Which of the statements given above are correct? 

    (a) I and II only 

    (b) II and III only 

    (c) I and III only 

    (d) I, II and III

  • Labour codes: what changes for workers and employers

    Introduction

    The four labour codes, Code on Wages, Code on Social Security, Industrial Relations Code, and Occupational Safety, Health and Working Conditions Code, aim to simplify compliance for industries, expand social security to workers, and improve ease of doing business. However, labour being a concurrent subject, implementation depends on states, and concerns have emerged about job security, worker rights, and the impact on collective bargaining.

    Why in the News

    The government has notified the implementation of four labour codes after over five years of deliberation and the consolidation of 29 central labour laws. This marks the first time India will operate under a uniform nationwide wage system and a consolidated social security architecture. While the reforms promise simplified compliance and a push for manufacturing efficiency, trade unions warn of reduced strike power, easier employee termination, and increased precarity for informal workers, making it one of the most debated labour reforms in recent times.

    Labour Codes and the Changing Labour Landscape

    1. Consolidation of 29 laws into four codes to create uniformity and remove overlapping provisions.
    2. Target shift from penal to compliance-based enforcement, especially for small firms and first-time offences.
    3. Push for economies of scale in manufacturing, signalling alignment with global production norms.

    Code on Wages: What changes for employees and employers?

    1. Uniform definition of wages: It ensures consistency in minimum wage calculation across states and sectors.
    2. Mandated national floor wage: It enables states to set minimum wages only above the national baseline.
    3. Time-bound wage payment: within 2 days of resignation/termination and 7 days of completion of the wage period.
    4. Broader coverage for all employees irrespective of industry or wage threshold.
    5. Overtime provisions strengthened: capped at 48 hours weekly, 12 hours daily shift duration permitted with breaks.

    Code on Social Security: Is the social net expanding?

    1. Unified ecosystem of social security: It covers unorganised, informal, gig, and platform workers for the first time.
    2. National Social Security Board: For recommendations, registration, schemes, and funding decisions.
    3. Corporate Co-contribution: Corporates may co-contribute to gig/platform worker benefits but funding split still unclear.
    4. ESIC expansion: Applies to sectors previously exempt; plantation workers included voluntarily.
    5. Formalisation incentive through maternity benefits, gratuity reforms, and inclusion of fixed-term employees.

    Industrial Relations Code: Does it limit collective bargaining?

    1. Stricter strike rules: 60-day notice before strike and prohibition of strike in the next 14 days of conciliation.
    2. Increase in threshold: Threshold for prior permission for layoffs raised from 100 to 300 workers, enabling easier hiring-firing.
    3. Negotiating Union provision: Only unions with 51% membership can negotiate; multi-union negotiation councils for fragmented memberships.
    4. Push for stable industrial climate: It is criticised for shrinking bargaining space for workers.

    OSH Code: Will workplace safety improve?

    1. Standardised norms: Across industries norms for working hours, workplace safety, and facility obligations.
    2. Mandatory free annual health check-ups: For workers in notified industries.
    3. Women allowed in all sectors and night shifts: subject to safety conditions.
    4. Increased accountability for establishments: In case of handling hazardous activities and migrant labour.

    Conclusion

    The labour codes aim to simplify compliance and strengthen India’s labour market to support manufacturing-led growth. However, concerns persist regarding job security, collective bargaining, and implementation across states. Successful outcomes depend on balancing economic flexibility with worker protection and ensuring that reforms lead to formalisation without vulnerability.

    PYQ Relevance

    [UPSC 2024] Discuss the merits and demerits of the four ‘Labour Codes’ in the context of labour market reforms in India. What has been the progress so far in this regard?

    Linkage: Growth driven mainly by labour productivity has led to GDP rising without proportional job creation. This links to the four Labour Codes, which seek higher productivity and flexibility, but face concerns on whether they will create jobs while protecting workers.

  • Excessive dependence: On India’s external trade landscape

    Introduction

    India recorded a historic goods trade deficit in October ($41.68 billion), following a sharp rise from September’s $32.15 billion deficit. The decline in exports, driven largely by the U.S.’s steep tariffs, coincides with an abnormal spike in gold and silver imports, rupee depreciation, and heavy portfolio outflows. The article highlights how India’s dependence on the U.S. market has exposed it to both economic and diplomatic vulnerabilities, raising questions about whether the shift in trade patterns is structural or a temporary response to external shocks.

    Why in the News

    India’s record October trade deficit of $41.68 billion, the sharpest ever, signals a significant disruption in its external trade landscape. Exports plunged due to the U.S.’s sudden 50% tariffs, critical because the U.S. is India’s largest export market, while gold imports tripled and silver inflows rose fivefold, creating an unprecedented import spike.

    A Rising Trade Deficit and What It Reveals

    1. Record Deficit ($41.68 bn): Reflects a sequential deterioration from September’s $32.15 bn deficit, signalling a disturbing shift.
    2. Export Fall (-11.8% YoY): Goods exports dropped to $34.38 bn (from $38.98 bn in 2024), driven primarily by U.S. tariffs.
    3. Heavy Import Surge: Driven by a dramatic rise in bullion inflows and the use of cheaper imported intermediates.

    Why the U.S. Tariffs Hit India Hard

    1. 50% Tariff Shock: Imposed in August, directly affecting sectors for which the U.S. has been India’s major market since 2018-19.
    2. Large Market Dependence: The U.S. remains the biggest buyer of India’s textiles, yarn, readymade garments, and engineering goods.
    3. Export Decline (-9% YoY): Overall exports to the U.S. contracted sharply in October.

    What Is Driving the Surge in Gold and Silver Imports?

    1. Gold Imports Tripled: Rising from $4.92 bn (last October) due to economic uncertainty.
    2. Silver Imports Up Fivefold: Indicates hedging behaviour rather than seasonal demand.
    3. Rupee Weakening (₹85.6 to ₹88.4): Encouraged investors to seek bullion as a safe asset.

    Sector-Wise Export Stress

    1. Cotton Yarn & Handlooms (-13.31%): Major labour-intensive sector hit due to tariff-led slowdown.
    2. Man-Made Yarn (-11.75%): Reflects weakening competitiveness.
    3. Readymade Garments (-12.88%): Particularly vulnerable to U.S. demand contraction.
    4. Engineering Goods (-16.71%): Hit despite being a major export strength area.

    Is the Import Surge a Structural Pattern?

    1. Cheaper Intermediate Goods: Firms increasingly rely on imported inputs to maintain export competitiveness.
    2. Depreciating Rupee: Makes imports costlier but also signals reduced domestic sourcing.
    3. Need for HS-Chapter Analysis: A breakdown by commodity and source country will clarify which imports are rising structurally.

    Government Measures and Their Limitations

    1. Export Promotion (₹25,060 crore over 6 years): Centre has stepped in to cushion exporters.
    2. RBI Relief Measures: Target tariff-affected exporters.
    3. Too Early to Call It Structural: Realignment of supply chains and market diversification could take years.

    Geopolitical Shifts and Bilateral Trade Dynamic

    1. India-U.S. Bilateral Trade Agreement: If concluded soon, October’s deficit spike may be temporary.
    2. Russian Imports Down (-27.73%): Sharp drop indicates effort to reduce crude dependence.
    3. U.S. Imports Up (13.89%): Suggests attempt to ease American concerns over trade imbalance.

    Conclusion

    India’s record trade deficit underscores the risks of concentrated export dependence and volatile imports driven by economic uncertainty. While the current shift may be partly reactionary, persistent decline in labour-intensive exports and rising reliance on imported intermediates signal deeper structural weaknesses. Managing this transition will require sustained policy intervention, diversification of markets, and a recalibration of India’s trade portfolio to mitigate vulnerability.

    PYQ Relevance

    [UPSC 2018] How would the recent phenomena of protectionism and currency manipulations in world trade affect macroeconomic stability of India?

    Linkage: The U.S. tariff shock and rupee weakening in the article directly mirror the PYQ’s theme, showing how protectionism and currency swings widen India’s trade deficit. Together, they illustrate the resulting stress on India’s macroeconomic stability.

  • Growing unchecked, no guardrails: On Cryptocurrency

    INTRODUCTION

    India’s crypto ecosystem is witnessing rapid expansion, with millions of users participating through exchanges that operate in a regulatory grey zone. Even though cryptocurrencies are not recognised as legal tender, trading continues unchecked through global and domestic platforms. Simultaneously, enforcement agencies report increasing difficulty in conducting investigations, seizing digital assets, and identifying crypto flows due to lack of disclosure norms, anonymous digital wallets, and absence of a comprehensive cryptocurrency law.
    As the RBI continues to caution against private crypto assets on grounds of financial instability, the mismatch between rapid adoption and weak regulatory architecture is emerging as a major economic and governance challenge.

    WHY IN THE NEWS? 

    The Indian crypto industry is projected to grow from $2.6 billion in 2024 to $15 billion by 2035, showing unprecedented expansion despite lack of regulatory oversight. This contrast, booming investments vs. near-absence of guardrails, has placed the industry at the centre of policy debate. Law-enforcement agencies have flagged that crypto-linked frauds, pump-and-dump schemes, and money-laundering networks are rising, while agencies lack legal backing and technical capability to tackle cases, making the issue urgent and nationally significant.

    Understanding Cryptocurrencies and Exchanges

    What are cryptocurrencies?

    • Decentralised Digital Assets: Built on blockchain, enabling encrypted, irreversible peer-to-peer transactions.
    • No Government Backing: Value based purely on demand-supply and market sentiment.
    • Popular Coins: Bitcoin, Ethereum; Indian users largely rely on global exchanges.
    • Not Legal Tender in India: Cannot be used for officially recognised payment obligations.

    What are crypto exchanges?

    • Online Trading Platforms: Allow users to buy, sell, hold crypto.
    • Wide Accessibility: Millions of Indians use both domestic and offshore exchanges.
    • India’s Absence of Recognition: Exchanges operate as digital intermediaries without formal regulatory status.

    How Crypto Scams Proliferate in India

    What mechanisms drive frauds?

    1. Pump-and-Dump Rackets: Influencers artificially inflate coin prices before exiting.
    2. Social Media-Driven Scams: Fraudsters lure users through WhatsApp/Telegram channels promising unrealistic returns.
    3. Disappearing Exchanges: Operators collect deposits and shut down overnight.
    4. Lack of Investor Awareness: Complex technology makes retail investors vulnerable.

    Magnitude of India’s Crypto Adoption

    How large is the user base?

    • 11 Million Global Crypto Holders: India hosts one of the world’s largest user bases.
    • 7 Million Indian Users (approx. 7%): Indicating wide penetration despite lack of backing.
    • ₹45,000 Crore Transaction Volume: Public adoption remains high regardless of regulatory uncertainty.
    • Young Demography: Primarily 18-35 age group investing through mobile apps.

    Why Does RBI Oppose Private Crypto Assets?

    What risks concern the central bank?

    1. Threat to Monetary Stability: Crypto bypasses sovereign currency systems, undermining control.
    2. Capital Flight Risks: Easy cross-border transferability allows funds to move outside the formal system.
    3. Volatility Concerns: Extreme price swings harm financial stability and investor protection.
    4. IMF FSR Context: RBI flags that widespread crypto usage could weaken monetary transmission and destabilise macroeconomic foundations.

    Why Crypto Investigations Are a Minefield in India

    What obstructs law-enforcement agencies?

    1. Disclosing Data
      1. Opaquely Stored User Data: Off-shore exchanges hide ownership/trade history.
      2. No Mandatory Registration: Agencies struggle to compel disclosure.
      3. Jurisdictional Challenges: Crypto platforms operate globally.
    2. Wallet Complexities
      1. Self-Custody Wallets: Google/MetaMask wallets controlled solely by users; agencies cannot freeze.
      2. Unregulated Cross-Border Flows: Enable illegal transfers with no paper trail.
    3. Seizing Digital Assets
      1. Technical Restrictions: Investigators require passphrases; non-cooperation prevents seizure.
      2. Custodial Limitations: No authorised secure government platform for holding crypto.
      3. High-Risk Volatility: Digital assets fluctuate, affecting value during investigations.
    4. Legal Blocks
      1. No Comprehensive Law: India lacks a crypto-specific statute.
      2. Ambiguity for Officers: Enforcement provisions unclear; actions challenged in court.
      3. Regulatory Vacuum: Agencies rely on IT Act, PMLA,insufficient for decentralised tech.
    5. Technical Snag
      1. Privacy Coins (e.g., Monero): High anonymity and advanced obfuscation algorithms.
      2. Untraceable Transactions: Blockchain mixers complicate forensic trails.

    Should Individuals Invest in Crypto?

    What risks do investors face?

    1. High Market Volatility: No asset backing; price fluctuations extreme.
    2. Unregulated Exchanges: Shutdowns lead to permanent loss of funds.
    3. Cyberattacks and Hacks: Wallets vulnerable to phishing and malware attacks.
    4. RBI and Global Position: Institutions including the IMF, RBI, European regulators warn of structural risks.

    CONCLUSION

    India’s crypto sector is expanding rapidly without an accompanying regulatory architecture. While blockchain offers transformative potential, the risks of fraud, volatility, and money-laundering remain high. Strengthening legal frameworks, mandating registration of exchanges, and improving cross-border cooperation will be essential before mainstreaming digital assets. Balancing innovation with stability remains the core policy challenge.

    PYQ Relevance

    [UPSC 2021] Discuss how emerging technologies and globalisation contribute to money laundering. Elaborate measures to tackle the problem of money laundering both at national and international levels.

    Linkage: This PYQ fits because the article shows how crypto and global digital platforms enable anonymous cross-border laundering. It also matches the article’s focus on legal gaps and enforcement challenges in tackling such flows.

  • [15th November 2025] The Hindu Op-ED: Flexible inflation targeting, a good balance

    Mentor’s Comment

    The debate on India’s Flexible Inflation Targeting (FIT) framework is central to macroeconomic stability, especially as the Reserve Bank of India (RBI) undertakes the second quinquennial review after adopting FIT in 2016. This article decodes the logic, data trends, inflation-growth dynamics, concerns over inflation bands, and the evolving economic context, translated into UPSC-ready analysis with conceptual clarity.

    Introduction

    India adopted the Flexible Inflation Targeting (FIT) framework in 2016, giving statutory autonomy to the RBI for price stability. With the current inflation band of 4% ± 2% up for review in March 2026, economic debate has intensified on whether this band remains appropriate amid structural shifts, supply-side shocks, and the inflation-growth trade-off. The article evaluates India’s experience with FIT, evidence from inflation-growth relationships, and the question of acceptable inflation levels for sustained macroeconomic stability.

    Why in the News?

    The FIT framework is undergoing its second major review since its inception in 2016, making it a crucial moment for India’s monetary policy architecture. RBI has released a research discussion paper, its most comprehensive assessment yet, presenting long-term inflation-growth data, the first such empirical mapping since 1991. The debate is significant because India’s inflation has remained near the upper tolerance band, raising questions about whether 4% is still an appropriate central target or whether persistent supply shocks require rethinking the framework. The outcome of this review will shape India’s monetary autonomy, fiscal-monetary coordination, and growth stability over the coming decade.

    What makes inflation control central to monetary policy?

    1. Inflation as a regressive tax: Disproportionately burdens poorer households whose incomes are not hedged; erodes purchasing power.
    2. High inflation leading to misallocation of resources: Leads to volatile investments and misdirected economic decisions.
    3. Acceptable inflation evolves with context: The Chakravarty Committee (1985) recommended 5% as acceptable, but economic conditions have since changed.
    4. Institutional strengthening since 1994: Post-automatic monetisation era gave RBI functional autonomy; FIT (2016) gave statutory backing for price stability.

    How does India’s current FIT framework work?

    1. Inflation band of 4% ± 2%: Offers flexibility while anchoring expectations.
    2. Headline inflation as target: Encourages investment protection from supply shocks; aligns with international norms.
    3. Range-bound inflation despite shocks: India has broadly maintained inflation within the band, reflecting maturing policy credibility.
    4. Mechanism evolves with economic complexity: Framework still young, but institutional autonomy makes it robust.

    What should India target-headline inflation or core inflation?

    1. Headline inflation captures supply shocks: Essential in an economy where food inflation significantly affects households.
    2. Misconception on price behaviour: General price level (inflation) differs from relative price changes (e.g., wages, food).
    3. Milton Friedman example: Excess money supply raises general prices; changing relative prices without liquidity expansion cannot cause inflation.
    4. No liquidity expansion leading to no general inflation: Relative price movement alone insufficient to generate sustained inflation.

    What does long-term data reveal about inflation and growth?

    1. Quadratic inflation-growth curve (1991-2023): Presented in the article; first time excluding COVID years.
    2. Point of inflection = 3.98%: Growth rises with inflation to ~4%, then declines beyond it.
      1. Implication: India’s acceptable inflation level is just around 4%.
    3. Higher inflation hurts growth: Especially when supply constraints, fiscal stress, and external pressures coincide.

    How flexible should the inflation band be

    1. FIT performance so far: Delivered flexibility; monetary authorities operate near upper limit due to shocks.
    2. Risk of staying at the upper band: May undermine framework credibility.
    3. Policy navigation matters: India earlier faced high inflation in the 1970s-80s; monetisation of the deficit made it worse.
    4. Present framework avoids past mistakes: Moves away from fiscal dominance; prevents automatic deficit monetisation.

    What determines an acceptable level of inflation?

    1. Phillips Curve insights: Countries with higher income also see higher acceptable inflation levels.
    2. Empirical threshold near 4%: RBI paper’s curve suggests growth maximisation at around 4%.
    3. India-specific vulnerabilities: Supply shocks (food, fuel), climate variability, imported inflation, fiscal constraints.
    4. Need for robust expectations anchoring: Prevents wage-price spiral and demand misalignment.

    Conclusion

    India’s Flexible Inflation Targeting has broadly succeeded in stabilising inflation expectations while preserving monetary autonomy. Evidence from long-term inflation-growth dynamics reinforces that 4% remains an optimal central target, though India must build greater resilience to supply shocks and strengthen fiscal-monetary coordination. A credible, flexible, and data-driven FIT framework remains essential for India’s growth trajectory over the next decade.

    PYQ Relevance

    [UPSC 2024] What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.

    Linkage: This PYQ  is highly relevant as food inflation heavily shapes headline inflation under the Flexible Inflation Targeting (FIT) framework, highlighting the limits of the Reserve Bank of India’s (RBI) tools. It links to the review of the four-percent target and RBI’s role in managing supply-driven inflation.

  • Recently awarded GI Tags

    Why in the News?

    The Geographical Indications (GI) Registry under the Ministry of Commerce and Industry granted GI recognition to multiple traditional products across India, including Ambaji Marble (Gujarat), Panna Diamond (Madhya Pradesh), and Lepcha Instruments (Sikkim).

    GI Tag/Product

    Details

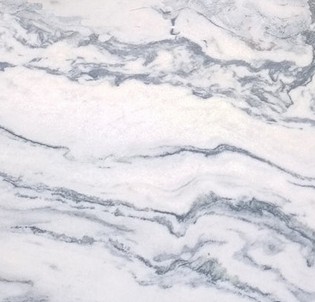
    Ambaji White Marble (Gujarat)

    • Known for pure white color, high calcium content, and durability
    • Sourced from Ambaji Shaktipeeth, Banaskantha
    • Used in Dilwara Temples and Ayodhya Ram Temple
    • Applied by Ambaji Marbles Quarry and Factory Association
    • Contains calcium oxide and silicon oxide, enhancing strength
    • Exported for temple use in USA, New Zealand, and UK
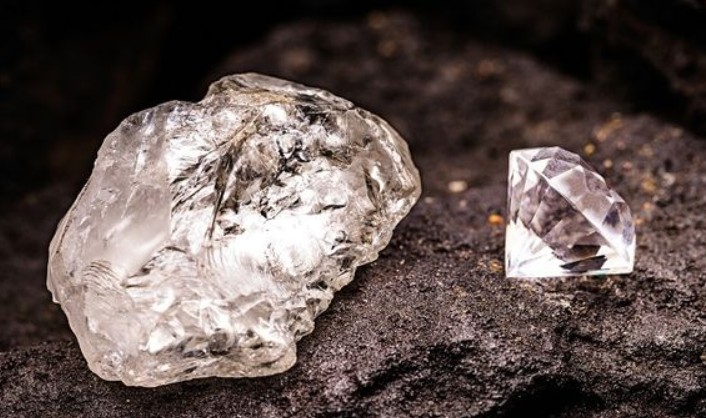
    Panna Diamond (Madhya Pradesh)

    • Application by Collectorate (Diamond Branch), Panna
    • Features a light green tint and weak carbon line
    • Managed by NMDC’s Diamond Mining Project
    • Supported by Padma Shri Rajni Kant (GI Man of India)
    • Enhances traceability, authenticity, and export potential
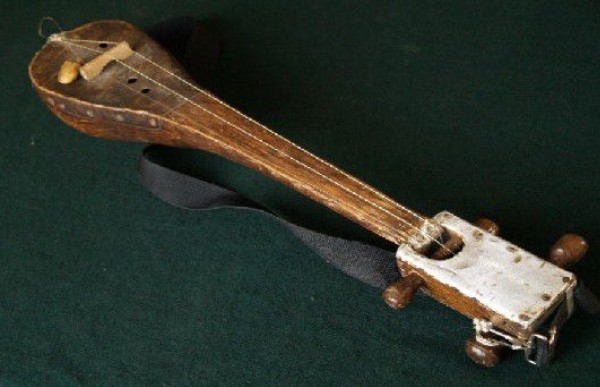
    Sikkim Lepcha Tungbuk

    • Traditional three-string musical instrument of Lepcha tribe
    • Holds cultural and spiritual importance in Lepcha music
    • GI granted on Nov 5, 2025 under Musical Instrument category
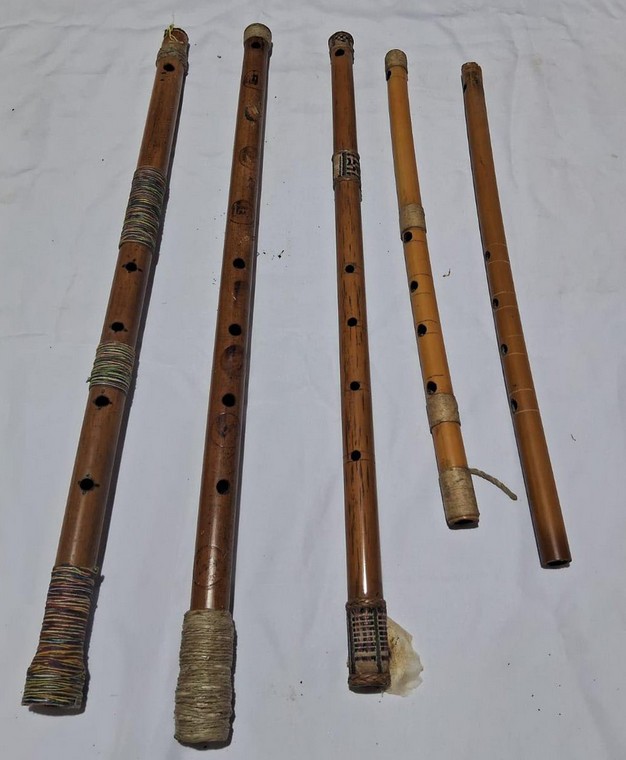
    Sikkim Lepcha Pumtong Pulit

    Bamboo flute central to Lepcha folk traditions
    • Symbol of Lepcha cultural identity and heritage
    • Preserves traditional instrument-making and youth cultural continuity
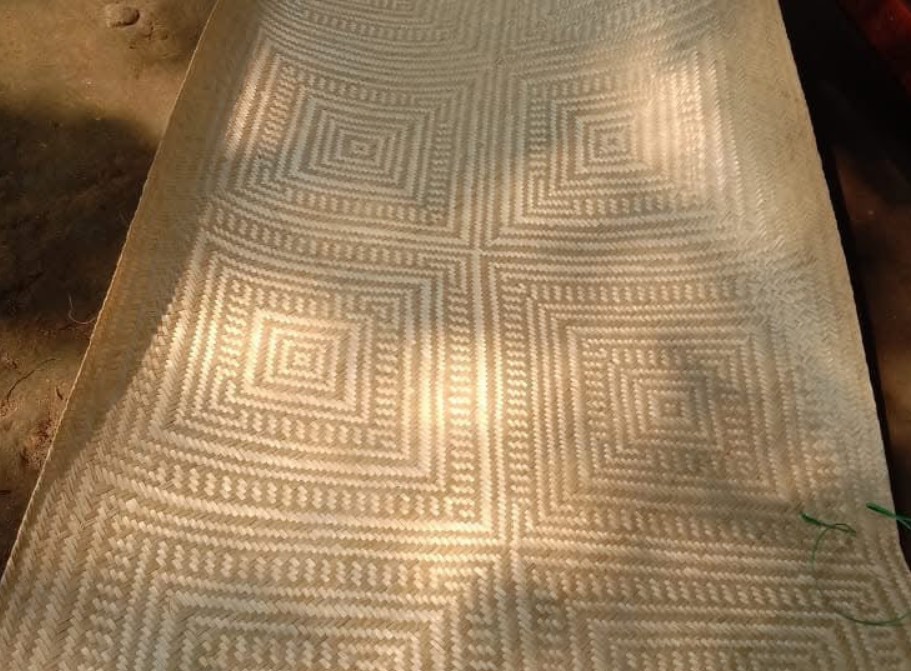
    Kannadippaya (Kerala)

    Traditional bamboo mat crafted by Kerala artisans
    • Recognized for eco-friendly material and handwoven design
    • Boosts rural cooperative income and craft heritage branding
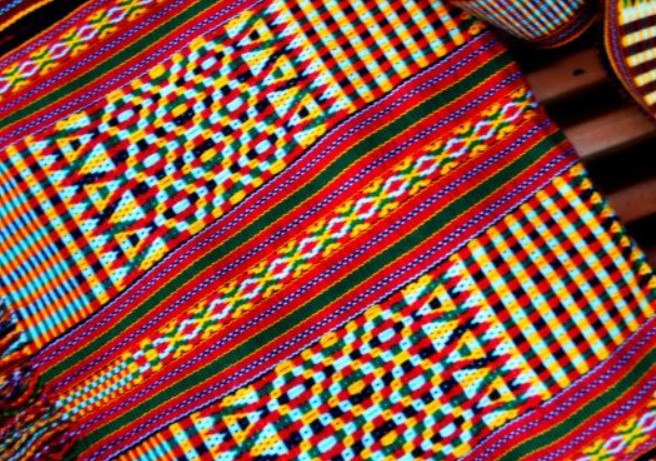
    Apatani Textile (Arunachal Pradesh)

    • Handwoven by Apatani tribe of Ziro Valley
    • Features geometric motifs and natural dye usage
    • Represents sustainable tribal textile craftsmanship
    Marthandam Honey (Tamil Nadu)


    • Produced in Kanyakumari district
    • Known for unique floral aroma, high medicinal value
    • Supports local beekeeping and biodiversity-based livelihoods
    Bodo Aronai (Assam)

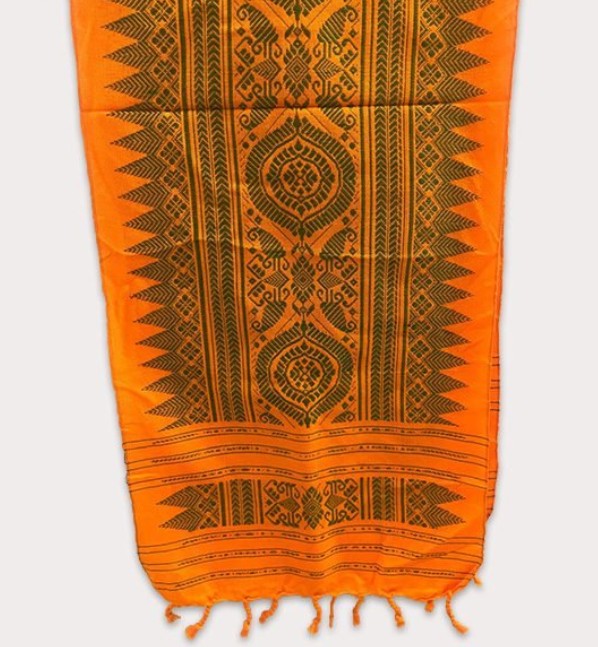
    • Traditional handwoven scarf of the Bodo community
    • Symbol of honor, identity, and ceremonial respect
    • Made using handspun cotton/silk with tribal patterns
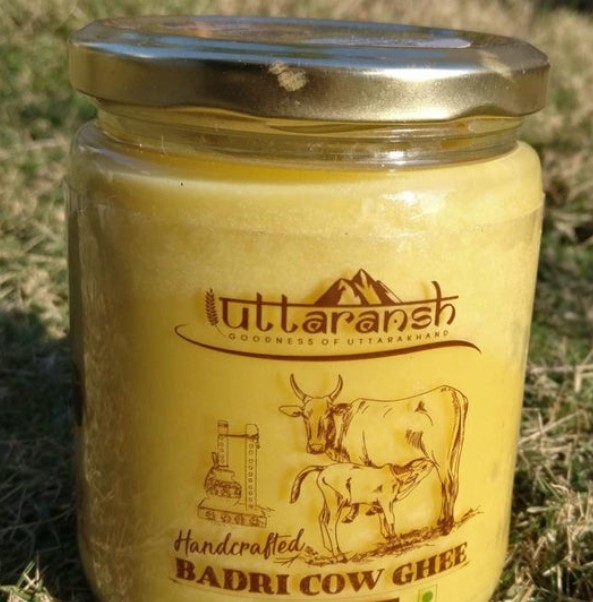
    Bedu & Badri Cow Ghee (Uttarakhand)

    • Produced from indigenous hill cow breeds
    • Known for nutritional richness and purity from high-altitude regions
    • Promotes mountain organic economy and heritage dairy products


    [UPSC 2018] Consider the following pairs:
    Craft. Heritage of
    1. Puthukkuli shawls Tamil Nadu
    2. Sujni embroidery Maharashtra
    3. Uppada Jamdani saris Karnataka
    Which of the pairs given above is/are correct?
    Options: (a) 1 only (b) 1 and 2 (c) 3 only (d) 2 and 3*


  • Urgent update: India needs to revise its CPI urgently

    Introduction

    The October retail inflation data exposed severe inaccuracies in India’s Consumer Price Index (CPI). While headline inflation appeared to fall to just 0.25%, the lowest since January 2012, the decline stemmed from a statistical anomaly, not real deflation. A collapse of 3.7% in the food and beverages index, driven largely by errors in price tracking during a month of actual food inflation (9.7%), dragged the entire CPI downwards. With outdated 2012 weights, GST-era distortions, and wide gaps between measured and perceived inflation, the CPI no longer mirrors reality. The article argues for urgent revision because the index now affects interest rate decisions, welfare planning, and fiscal strategy.

    Why in the news 

    Retail inflation for October collapsed to 0.25%, a 13-year low, appearing at first as a major success. But this fall was driven not by cheaper food but by a historic 3.7% contraction in the food and beverages category, despite actual food inflation touching 9.7%, the highest of the year. This sharp disconnect, caused by outdated weights and flawed price capture, marks one of the most serious statistical discrepancies in India’s CPI since its creation. With RBI’s interest rate decisions tied to CPI, this mismatch between measured inflation and lived inflation has become a significant policy challenge.

    What triggered the inflation anomaly in October 2025?

    1. Historic contraction in food index: The food and beverages category fell 3.7%, the largest drop since the 2012 CPI basket was created.
    2. Actual food inflation 9.7%: Prices in October rose steeply, showing complete divergence between data and reality.
    3. High weightage (46%): Because food accounts for nearly half of CPI, the flawed contraction pulled the entire index downward.
    4. Vegetable prices rising: The fall did not reflect market behaviour; vegetables had been getting costlier.
    5. Statistical anomaly: Not a reflection of cheaper food but a reflection of outdated measurement methods.

    Why is India’s CPI no longer accurate or representative?

    1. Outdated base year (2012): Consumption patterns, e-commerce, GST era changes, lifestyle shifts, none are captured.
    2. Misaligned weights: Household spending patterns have transformed; food no longer holds the same share.
    3. GST impact shows inconsistently: Only clothing and footwear showed inflation lower than last year due to GST cuts, not genuine price movement.
    4. Inconsistent category behaviour: Fuel, housing, tobacco, and miscellaneous inflation was higher than last year, contradicting the headline figure.
    5. Price capture errors: Data is often collected from markets that do not reflect actual consumer behaviour.

    What is the policy significance of this mismatch between CPI and real inflation?

    1. RBI’s rate decisions distorted: RBI surveyed households and found perceived inflation at 7.4%, far above the official CPI.
    2. Risk of wrong interest-rate moves: The RBI Monetary Policy Committee (MPC) uses CPI as its benchmark; incorrect CPI can lead to wrong rate cuts/holds.
    3. Poor signalling to markets: Bond markets, banks, and investors rely on accurate inflation forecasting.
    4. Impact on welfare schemes: Index-linked subsidies, pensions, and poverty estimates become inaccurate.
    5. Misleading economic narrative: Inflation is reported as low while households experience severe price stress.

    Why is a new CPI series urgently required

    1. Mismatch with GST regime: The GST tax cuts have altered category prices but CPI weights do not capture this.
    2. Structural change in Indian consumption: Electronics, services, digital expenses, mobility, none adequately represented.
    3. Incorrect urban-rural representation: Spending patterns in rural India have changed substantially.
    4. Temporary factors skewing data: GST rate cuts temporarily depress inflation readings, masking real trends.
    5. Government acknowledgment: Ministry of Statistics has confirmed work on a new CPI series.

    What is expected from the upcoming CPI revision?

    1. Greater accuracy: The new index will reduce the gap between statistical inflation and lived inflation.
    2. Improved weightages: Food weight may be reduced; services weight may rise.
    3. Better policy coordination: More accurate inflation data for monetary and fiscal decisions.
    4. Alignment with global practices: Frequent re-basing, digital data capture, and dynamic weighting.
    5. Timeline: Expected from the next financial year, improving CPI reliability.

    Conclusion

    India’s inflation measurement system is now at a breaking point. The October anomaly exposes the urgent need to modernize the CPI to reflect contemporary consumption and inflation realities. With monetary policy, welfare spending, and economic narratives relying on CPI, statistical distortions can lead to severe policy missteps. A revised CPI, updated, accurate, and GST-aligned, is essential for credible macroeconomic governance.

    Value Addition

    Consumer Price Index (CPI)

    • Definition: The Consumer Price Index (CPI) is a measure of the average change over time in the prices paid by consumers for a representative basket of consumer goods and services. The CPI measures inflation as experienced by consumers in their day-to-day living expenses.
    • Released by: National Statistical Office (NSO) under the Ministry of Statistics and Programme Implementation (MoSPI).
    • Frequency of release: Monthly, usually around the 12th of every month for the previous month.
    • What is included in the CPI basket:
      • Food & Beverages, Housing, Fuel & Light, Clothing & Footwear, and Miscellaneous services (education, health, transport, communication, recreation, personal care, etc.).
    • Weightage (CPI Combined, 2012 base year):
      • Food & Beverages: ~46%
      • Housing: ~10%
      • Fuel & Light: ~7%
      • Clothing & Footwear: ~6%
      • Miscellaneous: ~31%.

    PYQ Relevance

    [UPSC 2024] What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.

    Linkage: This PYQ is relevant because food inflation, CPI accuracy, and monetary policy are core GS-III themes repeatedly tested by UPSC. The article shows how flawed CPI weights hid real food inflation, directly weakening RBI’s ability to target inflation.

  • Low taxes spur buying but jobs and incomes will have to grow

    Introduction

    India’s economy is witnessing strong domestic demand supported by lower income tax and GST rates, easing inflation, a healthy monsoon, and lower interest rates. However, external uncertainties, high U.S. tariffs on Indian exports, and weak goods-export momentum pose headwinds. While consumption, services exports, and government capital expenditure show strength, India’s long-term growth will depend on sustained job creation and rising household incomes.

    Why in the News? 

    India’s domestic demand is rebounding strongly due to lower income taxes, GST rationalisation, easing inflation, and a good monsoon, marking a sharp contrast to earlier quarters of weak consumption. The IMF upgrading India’s GDP projection for FY25-26 from 6.4% to 6.6% signals strong resilience despite external headwinds. However, goods exports face pressure from U.S. reciprocal tariffs, and income growth has not kept pace with consumption, making it crucial to assess how India can sustain growth without widening inequalities.

    What is driving the current revival in domestic demand?

    1. Lower income tax & GST rates: Supported domestic demand as rationalisation reduced consumer burden.
    2. Good monsoon: Enabled agricultural stability, boosting rural purchasing power.
    3. Lower inflation & interest rates: Created favourable consumption conditions in the first half of the year.
    4. Higher government capital expenditure: Surged by 40%, strengthening infrastructure demand and pushing growth.
    5. Higher disbursements by Food & Public Distribution: Supported rural consumption and safety nets.

    How is India’s export performance shaping up?

    1. Non-oil goods exports grew 7% in the first half of the year, with overall goods exports rising 10%.
    2. Electronics exports increased 10% in the same period, indicating success of PLI-supported segments.
    3. Items like gems & jewellery, carpets, leather slowed due to global weak demand.
    4. High U.S. tariffs: India’s exports to the U.S. are facing pressure, especially textiles and electronics.
    5. Risk of global consolidation: Export growth may moderate due to volatility in global capital flows.

    What is the role of India’s services exports?

    1. Services remain the big buffer: Annual growth projected at around 10%, providing stability.
    2. IT services: Still robust despite global slowdown.
    3. Travel, transport, logistics, professional services: Showing strong expansion post-pandemic.
    4. CAGR of services exports (FY20-FY25): Strong performance contributed substantially to overall GDP.

    Why is investment activity picking up?

    1. Government capital expenditure +40%: Major driver of infrastructure formation.
    2. Private sector investment: Modest but improving, with pickup in power, cement, construction, pharma, and logistics.
    3. Lower interest rates: Created enabling conditions for investment in the second half of the year.
    4. High forex reserve ($690 billion): A comfort factor for foreign investors.

    Why must jobs and household incomes grow now?

    1. Strong consumption without matching income growth is unsustainable.
    2. Sticky unemployment risks weakening domestic demand.
    3. Labour-intensive sectors (textiles, leather, small manufacturing) face export pressure due to high U.S. tariffs.
    4. Structural reform need: India requires higher household income growth, MSME support, and labour-market reforms to sustain growth.
    5. Long-term challenge: Services-led growth creates fewer jobs, while global slowdown limits export-driven job creation.

    Conclusion

    India’s growth momentum is increasingly anchored in strong domestic demand supported by rationalised taxes, a good monsoon and inflation moderation. However, sustaining this trajectory requires broad-based income growth, job creation, and resilience in export sectors affected by global uncertainty. Without strengthening labour-intensive sectors and expanding household purchasing power, India’s growth revival may lose steam.

    PYQ Relevance

    [UPSC 2015] The nature of economic growth in India in recent times is often described as jobless growth. Do you agree? Give arguments in favour of your answer.

    Linkage: Such articles recur because growth-jobs imbalance is a persistent structural issue in India, making it a favorite UPSC theme. The article directly reflects the GS-3 question on “jobless growth” as consumption rises but employment and incomes lag. It helps analyze why India’s recent growth remains demand-led but not job-led, a core UPSC economic concern.

  • New Royalty Rates of Critical Minerals

    Why in the News?

    The Union Cabinet approved the rationalisation of royalty rates for graphite, caesium, rubidium, and zirconium to strengthen India’s domestic mineral base and reduce import dependency.

    About the New Royalty Rates:

    The Union Cabinet has approved revised ad valorem royalty rates (percentage of average sale price) for four key minerals- graphite, caesium, rubidium, and zirconium, under the Mines and Minerals (Development and Regulation) Act, 1957.
    Graphite:
    4% of ASP (average sale price) for graphite with <80% fixed carbon content.
    2% of ASP for graphite with ≥80% fixed carbon content.
    Caesium and Rubidium: 2% of ASP based on metal content in the ore produced.
    Zirconium: 1% of ASP.
    Earlier, graphite alone was taxed on a per-tonne basis; now, all four follow a price-linked structure.
    The new rates aim to reduce import dependency, stimulate exploration, and encourage fair bidding in critical mineral block auctions.

    What is Royalty?

    • Definition: It is a payment made by a mining company to the government, the sovereign owner of natural resources, for the right to extract and sell minerals.
    • Legal Basis in India: The Mines and Minerals (Development and Regulation) Act, 1957 (MMDR Act) is the principal statute regulating mineral development, licensing, and royalty payments in India.
    • Types of Royalty Systems:
      • Unit-based (per tonne): Fixed payment per quantity extracted.
      • Ad valorem: A fixed percentage of the sale value of the mineral (now used for most critical minerals).
      • Profit-based: A share of net revenue or profits after deductions.
    • Purpose: Ensures the state earns equitable returns from resource extraction while maintaining regulatory control and public ownership of mineral wealth.

    Royalty Governance: Legal and Administrative Framework

    • Authority:
      • The Central Government, through the Ministry of Mines, determines and revises royalty rates.
      • The Union Cabinet approves new rates; these are later notified by the Ministry.
    • Legal Basis: The Second Schedule of the MMDR Act lists royalty rates for each mineral.
    • Collection:
      • Royalty is paid by leaseholders or miners to the state government under central law.
      • Rates are periodically revised to align with market fluctuations and strategic priorities.
    • Calculation Example: Royalty = IBM-published Sale Price × Royalty Rate (%) × Quantity Produced.

    Default Royalty Rates in India:

    • For minerals not listed separately in the Second Schedule, a default royalty rate of 12% of the average sale price (ASP) applies under the MMDR Act.
    • However, for critical and strategic minerals, the government has rationalised rates downward (1–4%) to:
      • Attract private investment in exploration.
      • Ensure competitive auctions.
      • Promote domestic production of minerals vital to EVs, semiconductors, and renewable energy.
    • The shift from uniform high rates to graded, mineral-specific rates reflects a move toward a market-responsive and technology-driven resource policy.
    [UPSC 2025] Consider the following statements:
    I. India has joined the Minerals Security Partnership as a member.
    II. India is a resource-rich country in all the 30 critical minerals that it has identified.
    III. The Parliament in 2023 has amended the Mines and Minerals (Development and Regulation) Act, 1957 empowering the Central Government to exclusively auction mining lease and composite license for certain critical minerals.
    Which of the statements given above are correct?
    (a) I and II only (b) II and III only (c) I and III only * (d) I, II and III