💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Food Processing Sector

  • [29th September 2026] The Hindu OpED: Tackling food loss and waste: India’s opportunity

    [29th September 2026] The Hindu OpED: Tackling food loss and waste: India’s opportunity

    Question (2025, GS3 – 10 Marks): Elaborate the scope and significance of supply chain management of agricultural commodities in India.
    Linkage: This is the most direct conceptual match. It requires candidates to analyze the entire farm-to-fork value chain, identifying where losses occur, why cooling/storage alone is insufficient, and how integrated supply chain management can prevent loss across both rural and urban nodes.

    [2011] With what purpose is the Government of India promoting the concept of “Mega Food Parks”?
    1. To provide good infrastructure facilities for the food processing industry.
    2. To increase the processing of perishable items and reduce wastage.
    3. To provide emerging and eco-friendly food processing technologies to entrepreneurs.
    Select the correct answer using the code given below:
    (a) 1 only (b) 1 and 2 only (c) 2 and 3 only (d) 1, 2 and 3

    Mentor Comment

    India has measured farm-to-retail loss more rigorously than any other country, yet the measurement stops where waste begins. Retail, restaurant and household waste is unmeasured, so no target or accountability can be set for it. The ambition is a triple win on food security, emissions and incomes. The missing precondition is a connected national framework that pairs downstream data with financing. Surat’s 50-tonne-a-day plant shows the model works. Its five-year run without national replication shows that models exist and execution is the constraint. Loss reduction also shifts the problem rather than solves it. Better storage and cooling cut farm-gate loss, but the surplus reaches cities where segregation, collection and treatment capacity are weak. Unless municipalities build markets for compost and biogas, recovered value stays unrealised.

    Why in the News

    The International Day of Awareness of Food Loss and Waste (29 September) has renewed a call for India to move from individual interventions to a connected national approach with financing at its core.

    What are food loss and food waste, and why do they matter?

    1. What they are: Food loss is produce spoiled between farm and shop through poor storage, drying or transport. Food waste is food thrown away by shops, restaurants and households.
    2. Hidden cost: Wasted food is like a leaking tank: the land, water and energy used to grow it are lost too.
    3. Triple win: Cutting both strengthens food security, eases pressure on natural resources and emissions, and raises incomes and productivity.
    4. The takeaway: India grows enough to feed its people, so every tonne saved is food gained without extra land or water.

    What evidence does India have, and what is missing?

    1. A global first: India alone has run three national post-harvest loss surveys, tracking losses from farm to retail. The Ministry of Food Processing Industries (MoFPI) runs them, and a fourth round is under way.
    2. Global reporting: The surveys feed India’s Food Loss Index reporting under the Sustainable Development Goals (SDGs), which tracks losses before food reaches retail.
    3. The blind spot: Waste data for retail, hotels and restaurants, and households remain far less developed, so policy cannot target them.

    Why are wholesale markets an overlooked opportunity?

    1. Waste at the mandi: The Food and Agriculture Organization (FAO) and the National Council of Agriculture Marketing Boards (COSAMB) found a major wholesale market can generate up to 100 tonnes of organic waste daily.
    2. Landfill burden: In some cities, a fifth of urban organic waste reaches landfills, where rotting food releases methane, a potent greenhouse gas.
    3. A resource base: Nationally, this waste totals about 3.5 million tonnes a year. Treated, it could offset about 3.3 million tonnes of carbon dioxide equivalent (a common greenhouse gas measure).
    4. Surat model: A 50-tonne-a-day bio-CNG plant (compressed biogas for vehicles) in Surat has run through a private-sector partnership for over five years. Municipalities and market committees can adapt it.

    What should a connected national approach include?

    1. Mainstreaming: Loss and waste belong in agricultural planning, food-processing strategy, climate action and investment decisions.
    2. Targeted finance: Affordable money should reach storage, drying, cooling and processing for farmers, producer organisations and small firms, with traceability systems tracking produce.
    3. Circular approach: Surplus food can be redistributed and residues turned into compost, biogas or energy.
    4. Hotspot finance: The FAO and the Small Industries Development Bank of India (SIDBI) are matching food-loss hotspots, where most produce is lost, with climate-resilient technologies. SIDBI finances small firms to adopt them.
    5. Package of Practices: The FAO is preparing a “Package of Practices” helping cities measure, prevent, reduce, redistribute and valorise (extract value from) waste.

    Challenges

    1. Split responsibility: Loss and waste cut across farm, food processing, urban and climate policy, so no single agency owns the problem.
    2. Isolated pilots: The Surat plant and similar models remain one-offs without a national framework.
    3. Costly technology: Cooling, drying and storage equipment is expensive for small farmers and enterprises.
    4. Poor segregation: Mixed market and city waste cannot be composted or converted to biogas, so it is landfilled.

    Way Forward

    1. Consumer-end surveys: MoFPI should extend loss surveys to retail, hotels, restaurants and households.
    2. Hotspot-linked credit: SIDBI and banks should scale credit for small firms at identified loss hotspots.
    3. Market waste plants: Market committees should set up segregation and bio-CNG units at major markets.

    Conclusion

    India has the technology and working models to cut food loss, but they remain pilots without finance at scale. Whether the next survey round extends to the consumer end will show if loss reduction enters urban and climate policy.

    Key numbers

    1. Loss surveys (MoFPI): 45 commodities (2005-07), 45 (2012-14), 54 (2020-22).
    2. Carbon value of market waste: close to $30 million in credits a year.
    3. Surat plant: cuts methane-related emissions by about 7,500 tonnes a year.

    Schemes and Initiatives for Food Loss Reduction

    1. Pradhan Mantri Kisan SAMPADA Yojana (PMKSY): MoFPI’s scheme funds cold chains, Mega Food Parks and processing units.
    2. Operation Greens: Extended from tomato, onion and potato to 22 perishable crops to curb price swings and losses.
    3. Agriculture Infrastructure Fund: A Rs 1 lakh crore facility for post-harvest and market infrastructure.
    4. World’s Largest Grain Storage Plan: Launched in 2023, it builds godowns at Primary Agricultural Credit Society (PACS) level.
  • Elaborate on the policy taken by the government of India to meet the challenges of the food processing sector.

    Food processing refers to the transformation of raw agricultural commodities into value-added, marketable, and storable products through physical, chemical, or biological methods. India’s FPS is projected to grow from USD $billion (2023) to $700 billion by 2030.

    Challenges of the Food Processing Sector in India

    Low Level of Processing – Only ~10% of total agricultural produce is processed (vs 60-70% in developed countries).

    Post-harvest losses of 15-20% due to shortage of cold-storage, and transport infrastructure.

    Fragmented Supply Chain – 86% of farmers are small/marginal – limits aggregation

    High Logistics Cost of 13-14% of GDP (vs 8-9% in developed countries).

    Delay in project implementation – Eg- only 25 out of 42 approved Mega Food Parks operational

    Regulatory & Compliance Issues – Complex FSSAI norms and licensing delays discourage small processors.

    Micro and small units struggle to access formal credit, collateral, and working capital.

    Skill gap – Only 3% of the food processing workforce is formally trained

    Quality & Safety Gaps – Inconsistent adherence to food safety standards, and limited testing infrastructure. Eg- Rejection of Indian exports by EU.

    Negligible R&D (<0.5% of sectoral GVA) – stall innovation in packaging and product design.

    Policy Measures Taken by the Government of India

    The food processing sector has been recognized as a ‘sunrise sector‘ and a key priority industry under the ‘Make in India’ initiative.

    PM-Kisan SAMPADA (2016) – Central Sector Scheme to build a modern processing ecosystem from farm-gate to retail.

    Mega Food Parks Scheme – Provides land, utilities, common facilities, effluent plants, R&D labs.

    PM Formalisation of Micro Food Processing Enterprises (PM-FME) – Provides 40% credit-linked subsidy, branding support, and training for 2 lakh micro units under the One District One Product (ODOP) approach.

    Production Linked Incentive Scheme (PLISFPI) to boost domestic manufacturing.

    Agriculture Infrastructure Fund (AIF) – A fund for financing warehouses, cold storage, packhouses, and primary processing units.

    Operation Greens (TOP to TOTAL) – Price stabilization fund for tomato, onion, potato, now expanded to all perishable crops

    100% FDI in food processing and 100% FDI under Government route for retail of food produced in India.

    e-NAM Integration – Linking mandis for better price discovery, quality grading, and seamless movement of produce.

    Krishi Udan and Krishi Rail schemes – to ease out freight rates enabling smooth movement of perishables.

    Food processing included under PSL to improve access to affordable credit.

    National Makhana Board to globally position Indian superfoods like makhana.

    Infrastructure Status (HLIS) – Food parks are included in Harmonized List of Infrastructure – enables concessional loans.

    Collaboration with Invest India for FDI facilitation, market access, regulatory assistance.

    Budgetary Push – MoFPI budget 2024-25 increased by 30.19%, reflecting policy priority.

    Way Forward

    Develop Smart Food Processing Hubs using IoT, AI, and blockchain

    Zero-Waste Processing using circular economy models. Eg- converting fruit peels to bio-plastics

    Cluster-Based Development under One District One Product (ODOP) model

    Regulatory Simplification – Create a single-window clearance system

    Develop export-oriented zones with plug & play infra, market intelligence systems & customized packaging

    Effective implementation of these interventions can position India as a global food processing hub.

  • What are the challenges and opportunities of food processing sector in the country? How can income of the farmers be substantially increased by encouraging food processing?

    Food processing refers to the transformation of raw agricultural commodities into value-added, marketable, and storable products through physical, chemical, or biological methods.

    Challenges of the Food Processing Sector in India

    Low Level of Processing – Only ~10% of total agricultural produce is processed (vs 60-70% in developed countries).

    Post-harvest losses of 15-20% due to shortage of cold-storage, and transport infrastructure.

    Fragmented Supply Chain – 86% of farmers are small/marginal – limits aggregation

    High Logistics Cost of 13-14% of GDP (vs 8-9% in developed countries).

    Delay in project implementation – Eg- only 25 out of 42 approved Mega Food Parks operational

    Regulatory & Compliance Issues – Complex FSSAI norms and licensing delays discourage small processors.

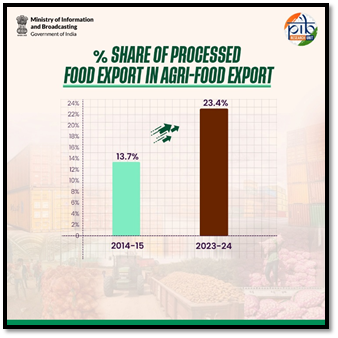
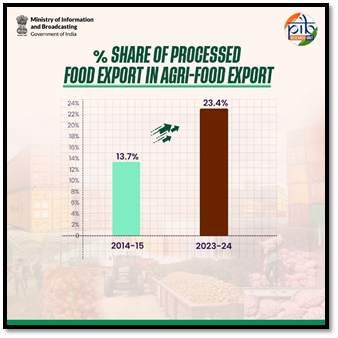
    Low Exports – 16% of India’s agri-exports are processed products, compared to 25% in the US and 49% in China.

    Micro and small units struggle to access formal credit, collateral, and working capital.

    Skill gap – Only 3% of the food processing workforce is formally trained

    Quality & Safety Gaps – Inconsistent adherence to food safety standards, and limited testing infrastructure. Eg- Rejection of Indian exports by EU.

    Negligible R&D (<0.5% of sectoral GVA) – stall innovation in packaging and product design

    Opportunities of Food Processing Industry in India

    Large agricultural base

    Second-largest producer of fruits and vegetables.

    Wide product spectrum – Includes dairy, fruits & vegetables, meat, fisheries, beverages, ready-to-eat (RTE), and organic foods.

    Lifestyle Shift – 65% of Indians under 35, rising incomes, urbanization & busy lifestyles have boosted demand for ready-to-eat & processed foods.

    Rapid growth in Organised retail and “shopping mall culture”- better supply chain management. Eg- D-mart

    Export potential – India exports processed foods to 200+ countries

    Nearly 70% of food processing units operate in the unorganised MSME sector – generate rural employment and entrepreneurship.

    Increasing Farmers’ Income through Food Processing

    Encourages production of horticulture, millets, oilseeds, spices – create new income sources beyond cereals.

    Strengthening FPOs – Processors procure directly from FPOs, giving assured prices and eliminating middlemen. Eg- Sahyadri FPO in Maharashtra

    Employment generation – rural non-farm jobs in grading, sorting, packaging, logistics, and processing units.

    Promotion of women entrepreneurship – Eg- Lijjat Papad

    Zero-Waste Processing using circular economy models. Eg- converting fruit peels to bio-plastics

    As India moves forward under the Make in India vision, the food processing industry will continue to be a key driver of economic growth, ensuring food security, quality, and global competitiveness.

  • Elaborate the scope and significance of the food processing industry in India

    India’s food processing sector is projected to grow from $307 billion (2023) to $700 billion by 2030, driven by rising demand, technological change, and strong policy support.

    Scope of the Food Processing Industry in India

    Large agricultural base

    India is the world’s largest producer of milk, spices, pulses, millets,

    Wide product spectrum – Includes dairy, fruits & vegetables, meat, fisheries, beverages, ready-to-eat (RTE), and organic foods.

    Lifestyle Shift – 65% of Indians under 35, rising incomes, urbanization & busy lifestyles have boosted demand for ready-to-eat & processed foods.

    Rapid growth in Organised retail and “shopping mall culture”– better supply chain management. Eg- D-mart

    Export potential – India exports processed foods to 200+ countries

    Nearly 70% of food processing units operate in the unorganised MSME sector – generate rural employment and entrepreneurship.

    Significance of the Food Processing Industry

    Demand for horticulture, poultry, fisheries, spices, and nutri-cereals supports diversification away from rice-wheat systems.

    Strengthens food security – Processing improves food availability, safety, nutrient retention and supports a resilient supply chain.

    Reduces post-harvest losses (15-20% of perishable losses annually) – processing improves shelf life and reduces wastage.

    Doubling farmer’s income – Value addition ensures better price realisation.

    Investment – Eg- Recent,World Food India attractedinvestment by global, domestic giants like Coca-Cola

    Boosts employment generation – Food processing creates one of the highest employment multipliers, across harvesting, sorting, packaging, and logistics.

    Drives industrialisation of rural economy – Mega Food Parks, agro-processing clusters, and cold chains stimulate local industry and logistics networks.

    Foreign exchange earnings through exports improve India’s trade balance and economic growth.

    As India moves forward under the Make in India vision, the food processing industry will continue to be a key driver of economic growth, ensuring food security, quality, and global competitiveness.

  • Examine the scope of the food processing industries in India. Elaborate the measures taken by the government in the food processing industries for generating employment opportunities.

    India’s food processing sector is projected to grow from $307 billion (2023) to $700 billion by 2030, driven by rising demand, technological change, and strong policy support.

    Scope of the Food Processing Industry in India

    Large agricultural base

    Second-largest producer of fruits and vegetables.

    Wide product spectrum – Includes dairy, fruits & vegetables, meat, fisheries, beverages, ready-to-eat (RTE), and organic foods.

    Lifestyle Shift – 65% of Indians under 35, rising incomes, urbanization & busy lifestyles have boosted demand for ready-to-eat & processed foods.

    Rapid growth in Organised retail and “shopping mall culture”- better supply chain management. Eg- D-mart

    Export potential – India exports processed foods to 200+ countries

    Nearly 70% of food processing units operate in the unorganised MSME sector – generate rural employment and entrepreneurship.

    Challenges of the Food Processing Sector in India

    Low Level of Processing – Only ~10% of total agricultural produce is processed (vs 60-70% in developed countries).

    Post-harvest losses of 15-20% due to shortage of cold-storage, and transport infrastructure.

    Fragmented Supply Chain – 86% of farmers are small/marginal – limits aggregation

    High Logistics Cost of 13-14% of GDP (vs 8-9% in developed countries).

    Delay in project implementation – Eg- only 25 out of 42 approved Mega Food Parks operational

    Regulatory & Compliance Issues – Complex FSSAI norms and licensing delays discourage small processors.

    Low Exports – 16% of India’s agri-exports are processed products, compared to 25% in the US and 49% in China.

    Micro and small units struggle to access formal credit, collateral, and working capital.

    Skill gap – Only 3% of the food processing workforce is formally trained

    Quality & Safety Gaps – Inconsistent adherence to food safety standards, and limited testing infrastructure. Eg- Rejection of Indian exports by EU.

    Negligible R&D (<0.5% of sectoral GVA) – stall innovation in packaging and product design

    Measures taken by government

    The food processing sector has been recognized as a ‘sunrise sector‘ and a key priority industry under the ‘Make in India’ initiative.

    PM-Kisan SAMPADA (2016) – Central Sector Scheme to build a modern processing ecosystem from farm-gate to retail.

    Mega Food Parks Scheme – Provides land, utilities, common facilities, effluent plants, R&D labs.

    PM Formalisation of Micro Food Processing Enterprises (PM-FME) – Provides 40% credit-linked subsidy, branding support, and training for 2 lakh micro units under the One District One Product (ODOP) approach.

    Production Linked Incentive Scheme (PLISFPI) to boost domestic manufacturing.

    Operation Greens (TOP to TOTAL) – Price stabilization fund for tomato, onion, potato, now expanded to all perishable crops

    100% FDI in food processing and 100% FDI under Government route for retail of food produced in India.

    e-NAM Integration – Linking mandis for better price discovery, quality grading, and seamless movement of produce.

    Food processing included under PSL to improve access to affordable credit.

    National Makhana Board to globally position Indian superfoods like makhana.

    Infrastructure Status (HLIS) – Food parks are included in Harmonized List of Infrastructure – enables concessional loans.

    Collaboration with Invest India for FDI facilitation, market access, regulatory assistance.

    As India moves forward under the Make in India vision, the food processing industry will continue to be a key driver of economic growth, ensuring food security, quality, and global competitiveness.

    Land Reforms

  • SAPLING Dialogue 2026 Concludes

    Why in the news?

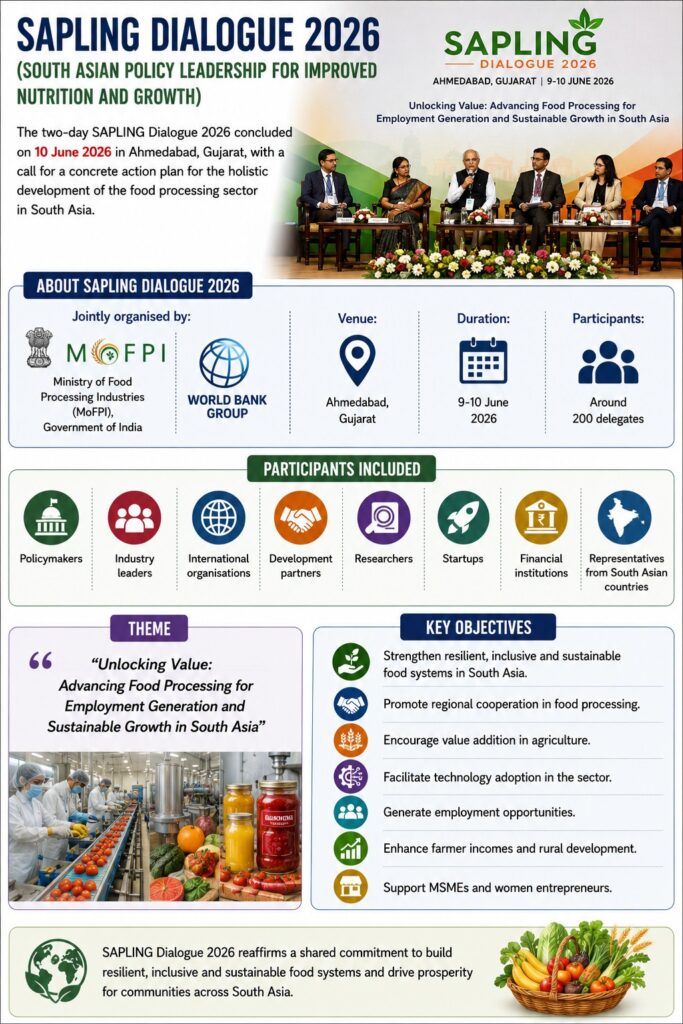
    The two-day SAPLING (South Asian Policy Leadership for Improved Nutrition and Growth) Dialogue 2026 concluded on 10 June 2026 in Ahmedabad, Gujarat, with a call for a concrete action plan for the holistic development of the food processing sector in South Asia.

    About SAPLING Dialogue 2026

    • Jointly organised by: Ministry of Food Processing Industries (MoFPI), Government of India and World Bank Group
    • Venue: Ahmedabad, Gujarat
    • Duration: 9-10 June 2026
    • Participants: Around 200 delegates.

    Participants Included

    • Policymakers, Industry leaders, International organisations, Development partners, Researchers, Startups, Financial institutions, and Representatives from South Asian countries

    Theme

    “Unlocking Value: Advancing Food Processing for Employment Generation and Sustainable Growth in South Asia”

    Key Objectives

    • Strengthen resilient, inclusive and sustainable food systems in South Asia.
    • Promote regional cooperation in food processing.
    • Encourage value addition in agriculture.
    • Facilitate technology adoption in the sector.
    • Generate employment opportunities.
    • Enhance farmer incomes and rural development.
    • Support MSMEs and women entrepreneurs.

    [2023] Consider the following statements with reference to India:
    1. According to the Micro, Small and Medium Enterprises Development (MSMED) Act, 2006, the ‘medium enterprises’ are those with and machinery between is crore and 25 crore.
    2. All bank loans to the Micro, Small and Medium Enterprises qualify under the priority sector.
    Which of the statements given above is/are correct?

    [A] 1 only

    [B] 2 only

    [C] Both 1 and 2

    [D] Neither 1 nor 2

  • With what purpose is the Government of India promoting the concept of “Mega Food Parks”

    With what purpose is the Government of India promoting the concept of “Mega Food Parks”?
    1. To provide good infrastructure facilities for the food processing industry.
    2. To increase the processing of perishable items and reduce wastage.
    3. To provide emerging and eco-friendly food processing technologies to entrepreneurs.
    Select the correct answer using the code given below: