💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Sectoral Regulatory Bodies

  • [26th September 2026] The Hindu OpED: The case for accountable lottery regulation in India

    [26th September 2026] The Hindu OpED: The case for accountable lottery regulation in India

    Question (2019, GS2 – 10 Marks): “From the resolution of contentious issues regarding distribution of legislative powers by the courts, ‘Principle of Federal Supremacy’ and ‘Harmonious Construction’ have emerged. Explain.
    Linkage: The B.R. Enterprises judgment is a classic example of harmonious construction and reading down a statute. The Supreme Court harmonized Union List Entry 40 (Lotteries organized by the Government of India or a State) and State List powers with Article 301 (Freedom of Trade and Commerce) to prevent discriminatory protectionism between states.

    Mentor Comment

    Prohibition of a vice with persistent demand removes legal supply and leaves the demand intact. The Lotteries (Regulation) Act, 1998 lets a State organise a lottery and lets a State prohibit lotteries organised by others. B.R. Enterprises vs State of U.P. (1999) read that second power down, so a State may exclude other States’ lotteries only by abandoning its own and becoming wholly lottery free. Faced with that trade off between revenue and regulatory control, two large States chose total prohibition and forfeited the option of running an accountable public lottery. The contest is between a State’s interest in supervising what is sold inside its territory and a legal rule built as an all or nothing choice.

    What does the Lotteries (Regulation) Act, 1998 provide?

    1. Legislative competence: Government organised lotteries fall under Entry 40 of the Union List.
    2. Section 4: The Act permits States to organise lotteries subject to the conditions in Section 4. Section 4 also permits a State to sell tickets directly, or through distributors or agents.
    3. Section 5: Section 5 empowers a State to prohibit lotteries organised by other States inside its territory.
    4. Section 6: Section 6 empowers the Union government to prohibit a lottery in violation of Sections 4 and 5.

    What harms do lotteries carry?

    1. Regressive burden: Lotteries disproportionately burden poorer households. They encourage a household to stake scarce income on a remote chance of reward.
    2. Compulsive play: Rapid draws and instant games encourage compulsive play and loss chasing.
    3. Distorted risk perception: Giant jackpots distort the perception of risk.
    4. Sales practices: Credit sales, opaque odds and manipulative advertising compound these harms.
    5. What the harms justify: These are arguments for stringent regulation, not necessarily for prohibition.

    What does a prohibition produce instead?

    1. Illegal channels: A ban pushes players towards smuggled tickets, offshore portals and unlicensed numbers betting such as matka, satta and single digit rackets.
    2. Absence of safeguards: These enterprises operate through cash agents and mule accounts. They carry no audits, no age restrictions, no secured prize funds and no effective remedy against fraud.
    3. Revenue forgone: Governments lose lottery surpluses and Goods and Services Tax (GST) revenue.
    4. Livelihoods and enforcement: Legitimate vendors, many of them poor or disabled, lose their livelihoods. Enforcement costs rise at the same time.
    5. The paradox of protection: A state seeking to protect the vulnerable leaves them at the mercy of unaccountable operators.

    Is the state’s paternalism applied evenly across classes?

    1. Permitted speculation: An affluent citizen can day trade, use leveraged derivatives or speculate in crypto assets. The risk of ruinous losses in those markets is no bar to entry.
    2. No competence test: The state does not test competence before admitting a retail trader to these markets. Securities trading involves skill, and derivatives support hedging and price discovery.
    3. The regulator’s own finding: The Securities and Exchange Board of India (SEBI) found that the vast majority of day traders, and of traders in futures and options, incurred losses.
    4. Why markets are legal: Financial markets are legal because risks are disclosed, intermediaries are regulated and fraud is punished. Adult choice is preserved alongside those safeguards.
    5. Application to lotteries: Lotteries can follow the same principle, with more stringent safeguards appropriate to games of chance.

    What does international practice show about regulating rather than banning?

    1. United States prohibition, 1920 to 1933: The United States imposed prohibition through the Eighteenth Amendment and the Volstead Act. It suppressed legal supply and left demand intact.
    2. What the ban produced: Prohibition fuelled a lucrative black market controlled by violent syndicates. Bootlegging corrupted public institutions, deprived governments of excise revenue and imposed heavy enforcement costs.
    3. The repeal: The Twenty First Amendment repealed prohibition, on the recognition that a regulated and taxed market causes fewer harms than an unenforceable ban.
    4. Controlled legality is the norm: Lotteries are legal in nearly four fifths of countries, with surpluses allocated transparently to education, health care, sports, welfare or infrastructure. Blanket prohibition survives mainly in countries enforcing strict Sharia based gambling prohibitions, such as Saudi Arabia, Iran and Brunei, and in closed ideological regimes such as Cuba.
    5. The public operator model: Nearly 70 per cent of lottery jurisdictions follow the public operator model. A government body, statutory authority or State owned company runs the lottery, and private firms supply retail and technology services.
    6. The concession model: The State regulates the lottery and grants operating rights to a private concessionaire.
    7. Federal practice: Lotteries operate in 45 of the 50 United States and Washington DC, in all 10 Canadian provinces and three territories, in all six Australian States and both mainland territories, and in all 16 German Lander.
    8. Cross border sales: Authorisation in one jurisdiction does not confer the right to sell in another. Cross border sales require the destination jurisdiction’s consent or its participation in a cooperative arrangement.
    9. Pooling without losing control: Powerball in the United States, Lotto 6/49 in Canada, the Australian lottery blocs and Germany’s national lottery bloc, the DLTB, let participating jurisdictions pool players and prizes without surrendering regulatory autonomy.

    What does Indian law do to a State that wants to regulate rather than ban?

    1. Res extra commercium: Settled Supreme Court jurisprudence treats gambling, including State organised lotteries, as res extra commercium, meaning an activity outside the protection of Article 19(1)(g), the fundamental right to trade, and of Article 301, the freedom of trade across India.
    2. The alcohol parallel: A parallel doctrine applies to potable alcohol and allows a State to restrict or prohibit consignments from outside its territory.
    3. Why the all or nothing rule is hard to justify: A State directly oversees its own lottery administration. Its oversight of another State’s operations inside its territory is necessarily indirect, and it still bears the local enforcement burden.
    4. The choice two States made: Tamil Nadu in 2003 and Karnataka in 2007 chose total prohibition. Both gave up the option of running accountable public lotteries of their own.
    5. How many States run lotteries: A Lok Sabha reply of 14 March 2023 identified nine States operating lotteries: Arunachal Pradesh, Goa, Kerala, Maharashtra, Mizoram, Nagaland, Punjab, Sikkim and West Bengal.
    6. The fiscal context: Persistent State fiscal stress makes the widespread preference for prohibition worth reconsidering.

    What would an accountable alternative look like?

    1. First amendment, to Section 5: Parliament should clarify that Section 5 applies whether or not the prohibiting State organises a lottery of its own. The consent of the destination State should be decisive, subject to uniform treatment.
    2. Uniform treatment: A State must either admit all outside lotteries or exclude them all.
    3. Second amendment, a new Section 4A: A new Section 4A should authorise two or more States to establish a common lottery by agreement, pooling players, prizes, technology and costs.
    4. Why compulsory access is no remedy: Smaller States, especially in the northeast, face exclusion from larger markets. Compulsory access is not the remedy for that exposure.
    5. Departmental operation: Marketing agents supply guaranteed revenue. Departmental operation is more transparent and opens retail distribution to small vendors, persons with disabilities, women’s self help groups and cooperatives. That widens livelihood opportunities and limits intermediary capture.
    6. The Kerala record: Kerala earned Rs 2,883.80 crore from its lottery in the 2023 to 2024 financial year. That total is Rs 1,129.71 crore in net lottery revenue and Rs 1,754.09 crore in State Goods and Services Tax.
    7. Where the surplus goes: Kerala channels its lottery surpluses into health care and welfare. Its model is a useful template for reform rather than the only one.

    Conclusion

    A vice with persistent demand does not disappear when the state withdraws the legal channel. The transaction moves to operators who keep no accounts and answer to no regulator. The real choice for a State is therefore between an auditable public supplier and an untraceable illegal one. Current law forces that choice into an all or nothing form, so a State that wants to shut out unaccountable outside operators must first shut down its own accountable one, and it is that single provision that has to change first.

    Betting and Gambling Regulation in India

    1. Scale of the market: The online betting and gaming market was valued at 5.02 billion dollars in 2024 to 2025. It is projected to reach 10.77 billion dollars by 2030.
    2. User base: India has over 517 million online gamers, of whom 155 million play money based games. India accounts for 20 per cent of the global gaming user base.
    3. Split jurisdiction: Gambling is a State subject, and online gaming has been brought under the Union. That split produces persistent legal friction.
    4. The skill and chance test: In Dr. K.R. Lakshmanan v. State of Tamil Nadu (1996) the Court established the predominance of skill test. Horse racing qualified as a game of skill on that test.

    Government Initiatives

    1. Promotion and Regulation of Online Gaming Act, 2025: The Act prohibits online money games, meaning real money betting, and permits e sports and social games.
    2. Online Gaming Authority of India: A central regulator under the Ministry of Electronics and Information Technology classifies games, issues digital certificates and handles enforcement.
    3. Blocking duty on intermediaries: Amendments to the information technology intermediary guidelines require an intermediary to block any platform flagged as a money game by the Authority.
  • SEBI eases settlement, overhauls PMS

    Why in the News

    The Securities and Exchange Board of India (SEBI) has approved a new settlement framework for entities facing enforcement proceedings. The new norms replace the Settlement Proceedings Regulations, 2018 and are aimed at reducing the regulator’s own discretion. The same decision approved a common advertisement code for market intermediaries and a comprehensive overhaul of the Portfolio Managers Regulations. The contested point is whether widening the settlement route prices a violation below the harm it caused.

    What is a settlement proceeding before SEBI?

    1. Closure without a finding: An entity facing enforcement proceedings pays a computed amount and the matter closes without an adjudicated finding against it. The show cause notice starts the period within which an application may be filed.
    2. The deciding body: A High Powered Committee examines the application and retains the power to reject it. Settlement is an option the regulator grants rather than a right the applicant holds.
    3. Exclusions under the 2018 regulations: The Settlement Proceedings Regulations, 2018 excluded whole categories of violation from the route, including those involving significant market impact, substantial investor losses and threats to market integrity.

    What changes in the settlement framework?

    1. A formula in place of an assessment: SEBI has introduced a new formula for calculating settlement amounts. The calculation now drives the figure rather than a case by case assessment.
    2. A fast track below a threshold: A case may be settled without reference to the High Powered Committee where the calculated amount is below Rs 10 lakh. Small matters therefore close without a committee sitting.
    3. A longer filing window: The deadline for filing a settlement application runs to 90 days from the date of the show cause notice, against 60 days earlier.
    4. Statutory anchoring: The new regulations are aligned with provisions introduced in the Securities Contracts (Regulation) Act, 1956. Those provisions supply a statutory framework for settlement and related mechanisms.

    What changes for portfolio managers and for market advertising?

    1. The Portfolio Managers Regulations overhaul: SEBI approved a comprehensive overhaul of the regulations governing portfolio management services (PMS), the business of running a client’s securities portfolio under a discretionary or advisory mandate. The stated aims are expanding the industry, easing compliance requirements, consolidating the regulations and removing outdated provisions.
    2. The competitiveness objective: The reforms seek to make the business more competitive by improving operational flexibility and simplifying compliance. Consolidation replaces a set of separately amended provisions with one instrument.
    3. A common advertisement code: A single advertisement code will apply to market intermediaries and regulated entities across the securities market. Its stated purpose is to simplify and standardise advertising practices.

    Challenges to the new settlement framework

    1. A settlement produces no adjudicated finding: A matter closed by settlement leaves no ruling for the market to read, so conduct at the margin stays untested. Eg. The objection put to the regulator was that a violator could settle by paying less than the impact caused, and the answer given was that the high powered committee retains the discretion to reject an application.
      The Fix: Publish a reasoned order for every settled matter above a stated value, recording the conduct and the calculation applied.
    2. Unresolved proceedings carry their own cost: An enforcement matter left open for years freezes an entity’s corporate actions whatever the eventual finding. Eg. The National Stock Exchange (NSE) brought its over Rs 22,200 crore public issue to listing only after a decade long regulatory and legal overhang.
      The Fix: Publish a standing disposal timeline for enforcement matters, so speed does not depend on the entity choosing to settle.
    3. A rupee threshold is not indexed: A fast track limit set in rupees covers a changing share of matters as values and participation rise. Eg. The minimum investment in bonds on online bond platforms has been cut to Rs 10,000 to widen retail participation.
      The Fix: Tie the fast track threshold to a published index with automatic revision, so the committee’s caseload stays a policy choice.
    4. Framework changes reprice a business before they are notified: A proposal on how a regulated business earns its revenue moves prices on the day it is published. Eg. An Insurance Regulatory and Development Authority of India (IRDAI) consultation paper, ‘Recalibrating Economics of Insurance Distribution’, triggered heavy selling in insurance distribution stocks.
      The Fix: Publish a dated implementation calendar with every consultation paper, so a regulated entity prices the change rather than the announcement.

    Conclusion

    Board approval is not notification. The framework’s effect turns on the calculation formula and on how many matters bypass the committee once the regulations are in force. The regulator has traded a case by case judgement for a published rule. That is the trade it describes as reducing its own discretion. The thing to watch is the share of enforcement matters disposed through the fast track route in the first full year, and whether a reasoned order is published for the rest.

    Matching Previous Year Question

    “[2013, GS2, 10 marks] The product diversification of financial institutions and insurance companies, resulting in overlapping of products and services strengthens the case for the merger of the two regulatory agencies, namely SEBI and IRDA. Justify.”

  • Irdai proposes specific caps on insurance commission

    Why in the News

    The Insurance Regulatory and Development Authority of India (IRDAI) has proposed specific caps on insurance commissions, in place of the single overall expense ceiling that governs distribution cost today. A consultation paper also proposes significantly lower overall expense limits for insurers, with a glide path for bringing down commissions and management expenses. The proposal reverses the approach of the Insurance Regulatory and Development Authority of India (Payment of Commission) Regulations, 2023, which withdrew product specific commission caps and left commission to be paid under a board approved policy within an insurer’s overall expense ceiling. The contested point is whether distribution cost is better disciplined by one aggregate ceiling the insurer manages, or by product level caps the regulator sets.

    What is the expense of management limit?

    1. What the limit covers: Expenses of management are the commission and operating expenses an insurer charges against its business. The limit is expressed as a share of premium.
    2. Why the ceiling exists: Every rupee of distribution and administration cost is a rupee not available for policyholder benefits, so a ceiling protects the return the buyer gets.
    3. The 2023 shift: Product specific commission caps were withdrawn and each insurer was left to fix commission through a board approved policy, inside the aggregate ceiling.
    4. What an aggregate ceiling cannot do: A single ceiling says nothing about how the expense is distributed across products and channels. An insurer can load cost onto one product and still stay within the limit.

    What do the proposed commission caps do?

    1. The basis of the cap: Caps are proposed by segment, line of business, distribution channel, product complexity, and the effort involved in selling and servicing the product.
    2. Agents on shorter tenure individual plans: For individual non linked plans, participating or non participating, and unit linked plans with a policy term of up to five years, first year commission for an agent is capped at 6.25 per cent.
    3. Other distribution entities: The same plans carry a 5 per cent cap on first year commission for other distribution entities, including corporate agents, brokers and composite brokers.
    4. The channel split: The same product therefore carries a different permitted acquisition cost depending on who sells it.

    What changes on the overall expense limits?

    1. Lower ceilings: The paper proposes a significant reduction in the overall expense of management limits that insurers work within.
    2. A phased reduction: The cut in commissions and management expenses is to come through a glide path rather than at once.
    3. Why phasing matters: An immediate cut would strand distribution agreements and agent payouts already written on current terms.

    Why is distribution cost a regulatory question at all?

    1. The cost is recovered from premium: Commission and management expense come out of what the policyholder pays, so a higher distribution cost lowers the return on the policy.
    2. Front loaded payouts reward the sale: A high first year commission pays for the act of selling rather than for servicing the policy over its term, which is the incentive structure behind mis selling and policy churning.
    3. Lapses destroy both sides of the contract: A policy sold to earn a first year commission lapses more often, and a lapsed policy leaves the buyer without protection and the insurer without a book.
    4. Trust decides market width: Insurance penetration in India remains low, so the terms on which a product is sold decide whether the market deepens or the buyer withdraws.

    Challenges to capping insurance commissions

    1. A cap moves the cost rather than removing it: Where the commission head is capped, the same payment can reappear as rewards, incentives, reimbursements or marketing support. Eg. Payments to a bank distributor can be routed under heads such as marketing or infrastructure support rather than as commission.
      The Fix: Bring every payment to a distributor, under whatever head, into a single reported remuneration figure disclosed product by product.
    2. Differentiated caps steer sales toward the better paying product: A cap that varies by segment and complexity gives a distributor a reason to recommend the product that pays more rather than the one that fits. Eg. Two products sold to the same customer can carry different payouts under the proposed structure.
      The Fix: Require a suitability record for every sale, stating why the recommended product matches the buyer’s stated need.
    3. Bank led distribution sells to a captive customer: A bank selling insurance to its own depositor faces little competitive check on what it recommends, whatever the commission rate is. Eg. Mis selling of unit linked and single premium policies at bank counters is a standing grievance before the insurance ombudsman.
      The Fix: Publish channel wise complaint and persistency data for every insurer, so the distribution channel carrying the problem is identifiable.
    4. A percentage cap bites hardest where the ticket size is small: The agent servicing low premium rural policies earns least from a cap expressed in percentage terms, so the least profitable business is served last. Eg. The individual agent remains the primary life insurance channel outside metropolitan markets.
      The Fix: Allow a higher cap for policies below a stated premium threshold, so low value business remains viable to sell and service.

    Conclusion

    The regulator is moving back from an aggregate ceiling the insurer manages to caps it sets itself, because an aggregate limit never governed where the money went inside it. Whether the buyer is better off depends on which heads a payout can be shifted into once the commission head is capped. The proposal is at the consultation stage, so the next step is the comment period. The final regulations are where it will become clear how long insurers get to reach the lower limits, and whether the disclosure obligation on distributor payments is tightened alongside the caps.

    Back2Basics: Insurance Regulatory and Development Authority of India

    1. Governing Act: IRDAI is a statutory body established under the Insurance Regulatory and Development Authority Act, 1999.
    2. Headquarters: It has been headquartered at Hyderabad since 2001.
    3. Composition: It is headed by a chairperson, with whole time members and part time members appointed by the central government.
    4. Mandate: It regulates the insurance and reinsurance business, licenses insurers and intermediaries, and protects the interests of policyholders.

    Matching Previous Year Question

    “[2013, GS2, 10 marks] The product diversification of financial institutions and insurance companies, resulting in overlapping of products and services strengthens the case for the merger of the two regulatory agencies, namely SEBI and IRDA. Justify.”

  • SC seeks clarity on FSSAI’s warning label norms

    Why in the News

    The Supreme Court has questioned the Food Safety and Standards Authority of India (FSSAI), the statutory food regulator, on how it proposes to determine whether a packaged food is “high” in sugar, salt or fat for the purpose of front of pack warning labels. The regulator had proposed such labels a month earlier, after the Court questioned its reluctance to introduce them. Its affidavit sets the thresholds by reference to the Dietary Guidelines for Indians, 2024 issued by the ICMR National Institute of Nutrition, without stating the triggering level itself. The Court described food safety as a cause of “national interest” and said it would pass a detailed order seeking further information from stakeholders. A warning label operates entirely through the number that switches it on, and that number is the one part of the proposal not yet on record.

    What is a front of pack warning label?

    1. Where it sits, and why that matters: It is a mark printed on the front of a package rather than inside the nutrition panel on the back, so a purchaser sees the risk before choosing to read anything.
    2. The form proposed: A red hexagonal warning would appear on the front of the pack.
    3. The trigger proposed: It would apply where a product is found to be high in two or more of the specified nutrients of concern, namely added fat, added sugar and salt.

    What did the Court ask that the affidavit does not answer?

    1. The threshold question: A two judge Bench asked how the regulator would fix the level beyond which a packaged food is classified as high in sugar, salt or fat.
    2. Whether any standard exists at all: The Bench asked directly whether guidelines had been laid down for making that determination.
    3. The answer on record: The Additional Solicitor General, appearing for the Centre and the regulator, said the regulator was adhering to the guidelines issued by the ICMR National Institute of Nutrition.
    4. A dietary guideline is not a labelling standard: Those guidelines advise individuals on what to eat. A labelling rule needs a numeric limit stated per unit of food, which a manufacturer can apply and an inspector can test.

    How did the case reach this point?

    1. The petition behind it: The proceeding is a public interest litigation filed by non profit organisations seeking warning labels that indicate high levels of salt, sugar and saturated fats.
    2. The regulator moved only under scrutiny: The proposal for prominent red warnings marked a regulatory pivot, and it arrived after judicial questioning rather than from the regulator’s own standard setting cycle.
    3. The Court’s stated ground: The Bench said it had undertaken its own study, asked the regulator to treat its directions seriously, and grounded its concern in the health of the population and of growing children in particular.

    Challenges to front of pack warning labels

    1. The threshold decides the policy, and it is the contested part: Industry attention concentrates on the cut off rather than on the label, because a lenient limit leaves most products unmarked. Eg. An earlier Indian proposal offered an Indian Nutrition Rating awarding stars, which public health bodies criticised for rewarding marginal reformulation instead of warning about risk.
      The Fix: Notify numeric limits per 100 g for solids and per 100 ml for liquids, separately for each nutrient, so the standard is testable rather than advisory.
    2. A two nutrient trigger lets single nutrient products pass: A food extremely high in one nutrient alone would carry no mark at all. Eg. A sugar sweetened beverage low in fat and salt escapes a label that requires two breaches.
      The Fix: Apply one warning mark for each nutrient breached, so the label scales with the risk rather than with the count of risks.
    3. Enforcement reaches only the packaged segment: Loose and unbranded food sold without a package falls outside any labelling rule. Eg. Fried snacks and sweets sold by weight carry no nutrition declaration whatsoever.
      The Fix: Pair the label with mandatory menu and point of sale declarations for chain food outlets, where the product is standardised and traceable.
    4. A label changes purchase only if it is understood: Nutrient information fails where the reader cannot convert a figure into a judgement. Eg. Chile adopted a black octagonal mark carrying the words “high in” in 2016 precisely because numeric panels were going unread.
      The Fix: Test the mark for comprehension among low literacy consumers before notification, and pair it with restrictions on marketing such products to children.

    Conclusion

    The regulator has conceded the principle and left the operative part open. A warning is a binary statement, so it cannot be issued out of advice about balanced diets, it needs a limit written per unit of food. What follows is that the useful output of this litigation is not a further affidavit accepting labels but a notified numeric standard, with a compliance date and a named enforcement authority behind it. Until that exists, the label is a design and not a rule.

    Matching Previous Year Question

    “[2016] With reference to pre-packaged items in India, it is mandatory to the manufacturer to put which of the following information on the main label, as per the Food Safety and Standards (Packaging and Labelling) Regulations, 2011? 1. List of ingredients including additives 2. Nutrition information 3. Recommendation, if any, made by the medical profession about the possibility of any allergic reactions 4. Vegetarian/non-vegetarian Select the correct answer using the code given below. (a) 1, 2 and 3 (b) 2, 3 and 4 (c) 1, 2 and 4 (d) 1 and 4 only ANSWER: (c)”

  • Why does India’s food safety system need a Clint Eastwood?

    Why does India’s food safety system need a Clint Eastwood?

    Why in the News

    India’s food safety regulation fails at disclosure and enforcement rather than at data collection. Between May and July a Maharashtra Food and Drug Administration drive led by a 2005 batch Indian Administrative Service officer inspected 3,137 restaurants, issued 764 improvement notices and shut 165 eateries.

    What is FoSCoS?

    1. The regulator’s integrated digital platform: The Food Safety Compliance System (FoSCoS) is the Food Safety and Standards Authority of India’s single platform for licensing, inspections, laboratory results and penalties, with the compliance chain digitised and connected.
    2. The designed sequence: A violation is found, a laboratory test is ordered, results are analysed, an audit is conducted, adjudication follows, a penalty issues and the establishment is closed.
    3. The record is held, never published: The platform accumulates violation data that never reaches the person choosing where to eat.

    Why does the enforcement chain stall?

    1. The design is a series of checkpoints: A violation sits in audit, then in adjudication, then in enforcement.
    2. No step carries a closing clock: Each checkpoint can hold a file indefinitely, so a violation is never formally disposed of.
    3. The system has more blockers than doers: The count of officers who can stop a file exceeds the count who can conclude one, so enforcement resumes only when a senior officer personally drives it.

    What did the Maharashtra drive actually demonstrate?

    1. A crackdown is not a system: The drive produced closures at a scale the routine machinery had not, using powers the routine machinery already held.
    2. A folk hero is evidence of failure: Celebrating an enforcement officer amounts to conceding that the enforcement design does not work without one.
    3. The output is not durable: An enforcement wave attached to one officer’s posting ends with that posting, and the platform returns to recording violations nobody acts on.

    What do the disclosure regimes elsewhere show?

    1. Singapore publishes the result where the customer stands: Inspections and rules resemble India’s. A failed inspection produces a rating displayed on the storefront and online.
    2. The pressure that works is commercial: The owner fears customers who see a failed grade and walk away, not the inspector or the fine. Revenue falls the same week and the problem is fixed at once.
    3. Denmark and Australia publish within days: Violations become public within days and the media carries them.
    4. Publication also disciplines the regulator: A lenient district looks bad against a neighbouring district’s published record, so an official cannot let files sit unseen.

    Why would publication work where inspection has not?

    1. The system is built for the wrong user: The compliance chain is designed for the convenience of the regulator, and the customer, who bears the risk, sees none of its output.
    2. Automatic publication is the specific proposal: Violation data should go public online within 48 hours, in food delivery apps and in restaurant windows, so a customer knows before ordering.
    3. A working regulator is invisible: Countries with published hygiene ratings generate no news coverage of their food safety enforcers, because enforcement there is routine rather than exceptional.

    Where else would published regulatory data change behaviour?

    1. Real estate: Buyers cannot tell whether a building was flagged for structural problems. Municipal violation history displayed in property listings would move demand away from flagged buildings and force developers to remedy them.
    2. Television channels: Official data exists on complaints against news channels for fake news, hate speech and bias, and never appears at the point where a viewer chooses a channel.
    3. Schools: Education departments inspect schools and record violations that parents never see while comparing institutions.
    4. Hospitals: Data on doctor complaints, disciplinary action and malpractice cases is held and withheld, so a patient chooses on reputation alone.

    Challenges to the food safety regulator’s enforcement design

    1. Testing capacity and procedure are the weak link: An enforcement order stands only if the sampling and laboratory chain behind it survives challenge. Eg. The 2015 national recall order on Maggi noodles was set aside by the Bombay High Court in August 2015, partly over how the samples had been tested.
      The Fix: Accredit a referral laboratory for every zone and publish its sample turnaround time against a fixed standard.
    2. Penalties are capped in absolute rupees: A ceiling fixed in the statute does not scale with the turnover of the business penalised. Eg. Section 52 of the Food Safety and Standards Act, 2006 caps the penalty for sub-standard food at Rs 5 lakh.
      The Fix: Link the penalty for a repeat violation to declared annual turnover rather than to a flat statutory ceiling.
    3. Most food businesses are registered rather than licensed: Small operators below a turnover threshold need only registration, which carries a lighter inspection and record obligation. Eg. Street food vendors and small eateries fall almost entirely into the registration category.
      The Fix: Extend a simplified published hygiene grade to registered outlets, so the lighter compliance route still produces a visible signal.
    4. The regulator sets standards and does not enforce them: Designated officers and food safety officers are appointed and paid by State commissioners, so the national platform records violations that no national authority can act on. Eg. An enforcement drive in one State changes nothing about a chain’s outlets in the next State.
      The Fix: Publish State-wise enforcement counts and pendency on the platform, so a State’s inaction is visible against its neighbours.

    Conclusion

    The instrument that would change behaviour is already built and already loaded, and it is pointed at the regulator instead of at the customer. Disclosure converts a compliance record into a commercial consequence, which is the one pressure a restaurant answers within the week. What is worth watching is whether any State food safety commissioner makes publication automatic and time-bound rather than discretionary, since the platform holding the data is national and the decision to open it is not.

    Laws and Rules Governing Food Safety Regulation

    1. Food Safety and Standards Act, 2006: Consolidated the earlier food laws into a single statute and created the Food Safety and Standards Authority of India as the standard-setting regulator.
    2. It repealed the Prevention of Food Adulteration Act, 1954, which had governed food adulteration for five decades.
    3. Food Safety and Standards (Licensing and Registration of Food Businesses) Regulations, 2011: Split food businesses into registration and licensing categories by turnover and scale of operation.
    4. Food Safety and Standards (Labelling and Display) Regulations, 2020: Fixed the mandatory declarations and the display obligations for food service establishments.
    5. Consumer Protection Act, 2019: Created the Central Consumer Protection Authority, which acts against misleading advertisements and unsafe goods independently of the food regulator.

    Government Initiatives for Food Safety

    1. Eat Right India: The regulator’s national movement combining regulatory measures, industry self-compliance and consumer awareness on safe and healthy food.
    2. Food Safety Training and Certification (FoSTaC): Mandatory training and certification of food safety supervisors for licensed food businesses.
    3. Clean Street Food Hub and Eat Right Station certification: Audited hygiene certification for street food clusters and railway stations.
    4. BHOG, Blissful Hygienic Offering to God: Hygiene certification programme for places of worship that prepare and distribute prasad.

    [2018] Consider the following statements:

    1. The Food Safety and Standards Act, 2006 replaced the Prevention of Food Adulteration Act, 1954.

    2. The Food Safety and Standard Authority of India (FSSAI) is under the charge of Director General of Health Services in the Union Ministry of Health and Family Welfare.

    Which of the statements given above is/are correct?

    (a) 1 only

    (b) 2 only

    (c) Both 1 and 2

    (d) Neither 1 nor 2

  • Step up regulation

    Step up regulation

    Question (2024, GS2 – 15 Marks): “In a crucial domain like the public healthcare system, the Indian State should play a vital role to contain the adverse impact of marketisation of the system. Suggest some measures through which the State can enhance the reach of public healthcare at the grassroots level.”
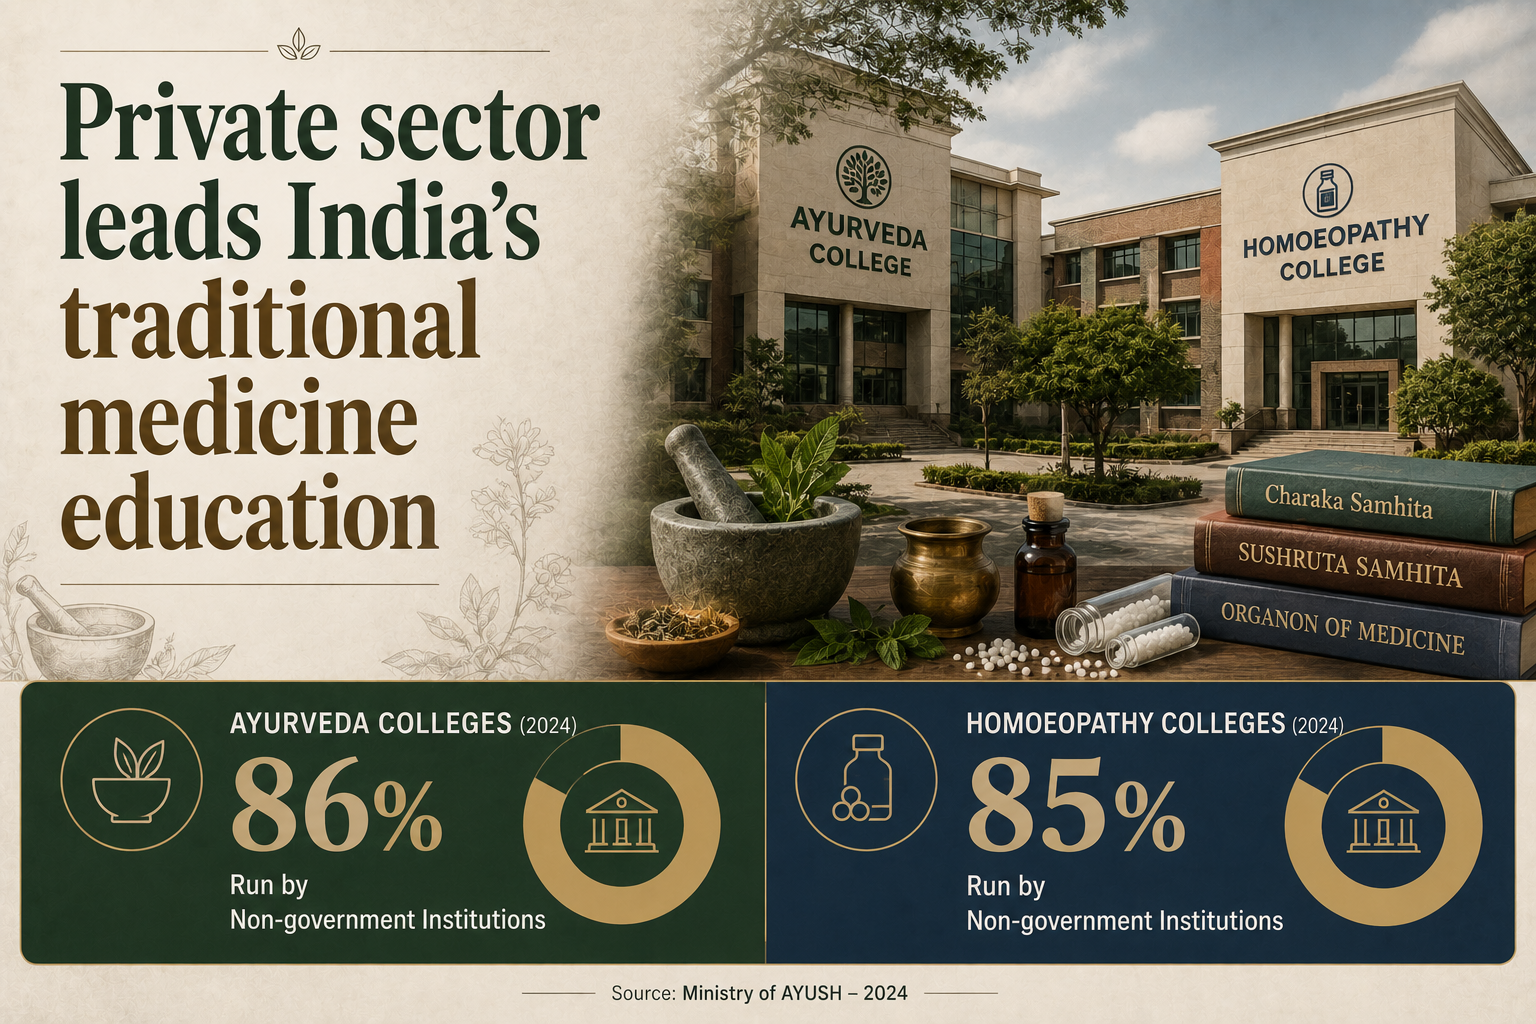
    Linkage: The fact that non-government institutions account for 85–86% of AYUSH colleges is a stark example of the “marketisation” of healthcare education. The incentive of private players to “maximise student intake without matching increases in faculty and laboratory infrastructure” illustrates the precise “adverse impacts” of market-led growth that the state must step in to regulate.

    Mentor Comment

    Non-government institutions accounted for 86 per cent of Ayurveda colleges and 85 per cent of homoeopathy colleges in 2024, according to government data. Permitted seats rose by 43 per cent and total admission capacity by 25 per cent between 2021 and 2024. The Centre’s AYURGYAN allocation for AYUSH education, training, research, innovation and capacity building increased nearly sixfold over the same period, AYUSH being the group of systems covering Ayurveda, Yoga and Naturopathy, Unani, Siddha and Homoeopathy. Through that expansion the sector’s regulators have been denying permissions and grading colleges poorly. The tension is that private led growth carries an incentive to maximise student intake without matching increases in faculty and laboratory infrastructure, and the regulatory answer to it arrives one inspection at a time.

    How fast has AYUSH education expanded, and who is running it?

    1. The private sector runs the great majority of colleges: Non-government institutions accounted for 86 per cent of Ayurveda and 85 per cent of homoeopathy colleges in 2024.
    2. Seats grew faster than institutions: Permitted seats rose by 43 per cent and total admission capacity by 25 per cent between 2021 and 2024.
    3. Public funding rose alongside private capacity: The AYURGYAN allocation increased nearly sixfold over the same period.
    4. The private sector is leading the build out: The expansion of AYUSH medical education infrastructure is being driven by non-government institutions rather than by State run colleges.

    Why do the quality questions differ from those in allopathic education?

    1. The allopathic concern is narrower: Debate there has been confined to whether institutions adequately prepare students for evidence-based practice.
    2. AYUSH raises two questions at once: The first is the quality of training delivered, and the second is what students are being trained to practise.
    3. The evidence base is itself in question: Tougher quality control does not settle the separate question of the evidence backing AYUSH medicinal systems.

    Do the quality problems predate the current expansion?

    1. A 2005 audit found widespread deficiencies: The Comptroller and Auditor General found insufficient hospital beds, outpatient services or staff to be widespread among homoeopathy colleges.
    2. Bed occupancy ranged from 1 per cent to 71 per cent: The same audit recorded that spread across the colleges it examined.
    3. Faculty shortfalls exceeded half the requirement: A 2020 article in the Journal of Ayurveda and Integrative Medicine reported that many institutions fell short by more than 50 per cent of the teaching staff required by the standards then in force.

    What are the regulators finding now?

    1. The Ayurveda regulator has denied 17 permissions: As of 21 August the National Commission for Indian System of Medicine (NCISM) had listed 17 Ayurveda colleges, all private, whose permissions it had denied.
    2. Several denials were for obstructing the process itself: The stated reason in several cases was non-compliance with the inspection process.
    3. The homoeopathy regulator graded 41 per cent of colleges lowest: The National Commission for Homoeopathy placed that share at the bottom grade, including nearly half of all private institutions.
    4. The recorded failures are specific and repeated: They include inadequate or disputed faculty strength, failures in inspection requirements and student intake numbers, and allegations of fictitious faculty.

    What incentive does private led expansion create?

    1. Intake is the revenue lever: Expansion led by private institutions is accompanied by an incentive to maximise student intake while holding faculty size and laboratory infrastructure at existing levels.
    2. A court has recorded the practice: The Karnataka High Court in Hillside Ayurveda Medical College (2023) acknowledged that educational institutions are often guilty of admitting excess students for financial gains.
    3. The regulatory response is retrospective: Permission withheld after an inspection corrects a college that has already been built and has already admitted students.
    4. Causation is not yet established: It is premature to infer that the rapid expansion has amplified these problems, and the persistent non-compliance is established on its own.

    Challenges to regulating AYUSH medical education

    1. Faculty can be produced on paper: A college can satisfy a faculty norm on inspection day by listing teachers who do not actually teach there. Eg. Aadhaar linked biometric attendance was introduced in allopathic medical colleges precisely because faculty were being shown only for inspections.
      The Fix: Extend biometric and payroll linked faculty verification to every AYUSH college and publish the verified roll monthly.
    2. Approval and assessment sit with the same body: A regulator that grants permission to a college also rates it, so a poor rating is a verdict on its own earlier approval. Eg. Allopathic regulation separated the two, creating a distinct Medical Assessment and Rating Board under the National Medical Commission.
      The Fix: Split permission and rating into separate boards with published criteria, on the model already used in allopathic regulation.
    3. Seats are cheaper to add than laboratories: Where fees are capped, a college raises revenue by raising intake rather than by improving what it teaches with. Eg. Private professional education in India has produced capitation fee litigation running from T.M.A. Pai Foundation (2002) onward.
      The Fix: Link seat sanction to an audited per student cost of teaching and clinical infrastructure rather than to floor space and declared faculty strength.
    4. Clinical exposure is measured by beds, not patients: An attached hospital can meet a bed norm without meeting an occupancy norm, so a student can qualify with very little clinical contact. Eg. Minimum standard requirements for AYUSH colleges specify bed numbers, which a college can satisfy with wards that stay largely empty.
      The Fix: Make verified average bed occupancy and outpatient footfall a condition of annual permission renewal.
    5. Efficacy sits outside the regulator’s remit: A regulator can enforce faculty and infrastructure norms without settling whether the therapy being taught works. Eg. Research on Ayurvedic medicine is largely funded and evaluated by the Central Council for Research in Ayurvedic Sciences, a body under the same ministry that promotes the system.
      The Fix: Route efficacy trials for AYUSH therapies through independently assessed, pre-registered protocols outside the promoting ministry.

    Conclusion

    AYUSH education can expand meaningfully only when capacity growth is matched by quality assurance. Stronger faculty verification, independent assessment, outcome based accreditation and evidence based research can ensure that expansion delivers credible, high quality healthcare education.

    Back2Basics: National Commission for Indian System of Medicine

    1. Governing Act: Established under the National Commission for Indian System of Medicine Act, 2020 as the statutory regulator for Indian systems of medicine.
    2. Predecessor: It replaced the Central Council of Indian Medicine, which had regulated the sector since 1970.
    3. Jurisdiction: It covers education and practice in Ayurveda, Unani, Siddha and Sowa-Rigpa.
    4. Structure: It works through autonomous boards handling education standards, assessment and rating of institutions, and ethics and registration of practitioners.
  • Why is FSSAI tightening the rules on food claims?

    Why in the News

    The Food Safety and Standards Authority of India (FSSAI) has issued more than 150 notices to food companies in recent months over misleading advertisements, false claims and labelling non compliance. Mondelez India has withdrawn certain health and nutrient comparison claims for Bournvita and removed the related advertisements from e-commerce platforms. The regulator has extended its scrutiny beyond the physical package to online marketplaces and food service establishments. A claim can be withdrawn on notice years after consumers have already acted on it, which is what makes the reach of this enforcement contested.

    What is a health claim, and what is a nutrient comparison claim?

    1. Health claim: A statement suggesting that a product helps deliver a particular health outcome. It can create expectations beyond what the product’s ingredient composition or the available evidence justifies.
    2. Nutrient comparison claim: A claim that positions a product’s nutrient content against another product or against a reference, such as a comparative calcium benefit.
    3. What the regulator governs: Food regulation is not limited to whether a product contains permitted ingredients. It also governs how a product’s nutritional qualities and benefits are communicated.

    Which claims and companies are under scrutiny?

    1. The companies served notices: The list includes Nestlé India, PepsiCo, Coca-Cola India, Abbott India, Red Bull India, Danone India, Mondelez India, Ferrero India and Kenvue.
    2. Bournvita: The product came under public scrutiny in 2023 over its sugar content and its claims about nutritional benefits. The present action does not establish that the product is unsafe, it questions whether particular claims are adequately supported.
    3. Amway India: The company removed “100%” from its “100% Pure Coconut Oil” packaging and promotional material. It also dropped the “Energy Drink” descriptor from its caffeinated XS products.
    4. Juza Foods: The Kerala based company agreed to withdraw claims of immunity, stronger bones and comparative calcium benefits from its baby food products.

    Why has the regulator targeted the word “100%”?

    1. The advisory: In May 2025 FSSAI advised food businesses to stop using “100%” on food labels, packaging and promotional material.
    2. The reasoning: The regulator held that such language conveys a false sense of absolute purity or superiority to consumers.
    3. Why absolute words matter: Words such as “pure”, “natural”, “healthy”, “immunity-boosting” and “100%” influence a purchase before the consumer examines the nutrition panel or the ingredient list.

    Why has enforcement moved to e-commerce?

    1. Notices beyond the shelf: Notices have gone to online marketplaces as well as to restaurants and other food businesses.
    2. Online pages carry different content: An online product page can carry claims, images and promotional language that differ from what appears on the physical package.
    3. How consumers now decide: A purchase is often made off an online banner or product description rather than off the label read in a shop.

    What does the crackdown still leave unaddressed?

    1. Withdrawal comes late: A company can remove a claim after receiving a notice, and consumers may already have encountered that claim for years.
    2. Messaging survives across platforms: An advertisement can disappear from one platform and its messaging remain present elsewhere.
    3. Listings change faster than checks: Online listings change rapidly, which makes sustained monitoring necessary rather than one time correction.
    4. Compliance is episodic: The regulator’s task is to make compliance routine rather than a temporary response to regulatory scrutiny.

    Conclusion

    The shift being sought is from broad marketing language to claims that can be demonstrated. This matters as India confronts rising obesity and unhealthy diets, and FSSAI has linked its food safety messaging to that wider push for healthier eating. For a consumer, a health claim on a food packet remains a claim and not a guarantee.

    Matching Previous Year Question

    “[2015, GS2, 12 marks] For achieving the desired objectives, it is necessary to ensure that the regulatory institutions remain independent and autonomous. Discuss in the light of the experiences in recent past.”

  • SEBI’s ITRI: Global test for India’s future-ready financial architecture

    SEBI’s ITRI: Global test for India’s future-ready financial architecture

    Why in the News

    The Securities and Exchange Board of India (SEBI) has introduced an IT Resilience Index (ITRI) to assess the technological robustness of Market Infrastructure Institutions (MIIs), meaning stock exchanges, depositories and clearing corporations. The index responds to growing global concern about outages and cyberattacks at systemically important financial market infrastructure. It follows comparable resilience frameworks already adopted by regulators in the United Kingdom, the European Union, the United States, Singapore, Hong Kong and Australia. The tension is between certifying resilience on paper through a scored index and ensuring MIIs make the operational investment the index is meant to incentivise.

    What does the ITRI assess?

    1. Nine weighted parameters: The index scores each market infrastructure institution across nine parameters covering system uptime, cyber-incident preparedness, disaster recovery capability and related technology governance measures.
    2. Comparative design: SEBI has drawn on resilience frameworks used by regulators in the United Kingdom, the European Union, the United States, Singapore, Hong Kong and Australia in constructing the index.

    Why has SEBI shifted from compliance-checking to a quantitative resilience score for MIIs?

    • Systemic-risk trigger: Rising technological dependence in capital markets means even minutes of disruption at an MII can affect millions of investors and billions of rupees in trades.
    • Regulatory foundation: SEBI’s 2015 circular first classified MIIs as systemically important, mandating a robust cybersecurity framework.
    • Boardroom shift: Retail participation through online platforms, algorithmic trading volumes, and faster settlement cycles have made technology reliability inseparable from market efficiency.
    • Global first: ITRI is among the first attempts by any regulator to design a resilience barometer as measurable as capital adequacy is for banks.

    How does ITRI’s weighting structure reflect SEBI’s risk-prioritisation approach?

    • Nine-parameter design: ITRI rests on nine parameters, each weighted by a systemic-risk hierarchy, with sub-parameters to be defined by the Industry Standards Forum of MIIs.
    • Highest-weighted parameters: Availability and security carry the highest weight, at 20% each, as the first line of defence for market functioning.
    • Recovery-focused weighting: Business Continuity and Reliability carries 10% weight, reflecting a regulatory shift from preventing failures to absorbing shocks and recovering quickly.
    • Growth-risk calibration: Scalability carries only 5% weight, reflecting SEBI’s view that rapid market growth does not yet pose an immediate stability risk.
    • Early Warning System: MIIs will build an Early Warning System to detect parameter deterioration before it causes performance issues or disruptions.

    What do global resilience frameworks show about the alternatives to a single numeric index?

    • United Kingdom — FCA/PRA: Operational resilience rules require institutions to identify important business services and demonstrate recovery capability from severe shocks, without a single numeric score.
    • European Union — DORA: The Digital Operational Resilience Act functions as a regulatory rulebook rather than a numerical scorecard.
    • United States: No single resilience index exists for exchanges; technology resilience is embedded into general regulatory oversight instead.
    • Singapore — Monetary Authority of Singapore: Technology risk guidelines are considered particularly relevant to India given comparably high digital financial penetration and large retail investor bases.
    • Hong Kong: Cyber resilience assessment frameworks use measurable maturity levels, making them the closest structural parallel to SEBI’s numeric approach.

    Can a single numeric score capture resilience across MIIs with different technology architectures?

    • Architecture heterogeneity: Stock exchanges, clearing corporations and depositories operate different technology architectures and functions, raising doubts about a common index applying uniformly.
    • Weight uncertainty: Questions remain on the statistical estimation of the assigned weights, finalised through Technical Advisory Committee discussions rather than validated outage data.
    • Provisional status: The current weights are a starting framework that SEBI may have to refine using actual outage data, cyber incidents and stress tests.
    • Pace mismatch: Technology risks evolve faster than regulatory frameworks, making the index vulnerable to obsolescence even as it is being implemented.
    • Investment burden: Building automated monitoring systems, continuous testing and redundant infrastructure requires substantial investment from MIIs.

    Back2Basics: Market Infrastructure Institutions (MIIs)

    1. MIIs are the entities that provide the trading, clearing and settlement backbone of the securities market: stock exchanges, depositories and clearing corporations.
    2. They are classified as systemically important, since their failure or compromise can disrupt trading and settlement across the entire market rather than a single participant.
    3. SEBI regulates MIIs under the SEBI (Stock Exchanges and Clearing Corporations) Regulations and the SEBI (Depositories and Participants) Regulations.

    Conclusion

    SEBI’s ITRI converts technology resilience from a compliance checklist into a quantitative, weighted score, a model most global regulators have not attempted. Whether this scoring approach works depends on unresolved questions: the statistical basis of the weights, the comparability of a single index across MIIs with different architectures, and whether a high score actually translates into faster recovery during an actual technology shock. Until validated against real incident data, ITRI remains a measurement framework rather than a proven resilience guarantee.

    “[2015, GS2, 12 marks] For achieving the desired objectives, it is necessary to ensure that the regulatory institutions remain independent and autonomous. Discuss in the light of the experiences in recent past.”

  • Centre moves to simplify medical device regulations

    Why in the News

    The Ministry of Health and Family Welfare has proposed amendments to Rule 44 and Rule 63 of the Medical Devices Rules, 2017, adding the European Union to the list of jurisdictions whose regulatory approval India recognises for faster market entry. The Medical Devices Rules, 2017 currently grant an expedited licensing route in India to devices already approved by a short list of recognised foreign regulators, such as the US Food and Drug Administration. Adding the European Union’s regulatory approval to that recognised list extends the fast-track route to a much larger set of globally marketed devices.

    What do Rule 44 and Rule 63 currently govern?

    1. Rule 44, predicate device and approval-based licensing: Rule 44 of the Medical Devices Rules, 2017 sets out the conditions under which a device already approved in a recognised foreign jurisdiction can secure an Indian manufacturing or import licence through a faster review, rather than a full fresh evaluation.
    2. Rule 63, licensing timelines and reliance on foreign approval: Rule 63 governs the timelines and documentary requirements for import licences, with reliance on foreign regulatory approval used to compress India’s own review period for devices from recognised jurisdictions.
    3. Currently recognised jurisdictions are limited: The existing fast-track list includes major regulators such as the US Food and Drug Administration, but has not included the European Union’s regulatory framework, requiring EU-approved devices to go through India’s standard, longer review.

    Why add the European Union to the recognised list?

    1. The EU covers a large share of globally marketed devices: A significant share of medical devices sold worldwide first secure approval under the European Union’s regulatory framework, so recognising EU approval widens the pool of devices eligible for India’s fast-track route considerably.
    2. Reduces duplicate testing for already-approved devices: Recognising EU approval avoids re-running clinical and safety evaluations in India for a device that has already cleared a comparably rigorous regulatory process abroad.
    3. Intended to speed access to newer medical technology: A faster licensing route is expected to bring newer diagnostic and treatment devices to the Indian market sooner than the standard review timeline would allow.

    Conclusion

    The proposed amendments to Rule 44 and Rule 63 extend India’s fast-track medical device licensing route to European Union-approved devices, alongside the jurisdictions already recognised. The amendments are at the proposal stage, with the next step being their formal notification under the Medical Devices Rules, 2017.

    Back2Basics: Medical Devices Rules, 2017

    1. Notified under the Drugs and Cosmetics Act, 1940, the Medical Devices Rules, 2017 created a dedicated regulatory framework for medical devices, distinct from the drug-licensing framework they had earlier been regulated under.
    2. Classify devices by risk into four classes, A to D, with review stringency rising with the device’s risk class.
    3. Are administered by the Central Drugs Standard Control Organisation, the national regulator for drugs and medical devices.
    4. Recognise approval from specified foreign regulators to allow an expedited licensing route for devices already cleared in those jurisdictions.

    Matching Previous Year Question

    “[2015, GS2, 12 marks] For achieving the desired objectives, it is necessary to ensure that the regulatory institutions remain independent and autonomous. Discuss in the light of the
    experiences in recent past.”

  • When the inspector leaves: Can food safety become a daily habit?

    Why in the News

    Food safety compliance in Maharashtra has risen sharply since inspection drives intensified in May, with more than 3,000 inspections producing 165 licence suspensions and 750 improvement notices between 25 May and 31 July. The Food and Drug Administration (FDA) drive follows the appointment of a new State Commissioner, and restaurant associations have been sending compliance reminders to members in response. The Food Safety and Standards Authority of India (FSSAI) separately revised its turnover based licensing categories with effect from 1 April this year. Compliance that improves when inspections intensify is not compliance embedded in daily operation, and the regulatory question is whether safe practice survives once the drive ends.

    What is the Food Safety and Standards Authority of India (FSSAI)?

    1. A statutory regulator under the health ministry: FSSAI is an autonomous body under the Ministry of Health and Family Welfare, established under the Food Safety and Standards Act, 2006 to protect and promote public health through food regulation.
    2. Its core powers: It frames standards for food products, regulates their manufacture, storage, sale and import, and grants licences to food businesses based on compliance with those standards.
    3. Enforcement is shared with the States: FSSAI sets standards centrally, and inspection, sampling and prosecution are carried out by State food safety commissioners and their food safety officers.

    What do the revised turnover based licensing slabs require?

    1. Registration for the smallest businesses: Food businesses with an annual turnover of up to Rs 1.5 crore must obtain FSSAI registration.
    2. State licence for the middle tier: Businesses with a turnover between Rs 1.5 crore and Rs 50 crore require a State FSSAI licence.
    3. Central licence at the top: Businesses with turnover above Rs 50 crore require a Central FSSAI licence.
    4. The slabs are a proxy for reach, not risk: The distinction matters because India’s food sector ranges from small local vendors and retailers to large restaurants, manufacturers, importers and exporters, and turnover is the only variable the tiering uses.
    5. The licensed base is already large: FSSAI has issued around 26,000 licences across Maharashtra, Gujarat, Goa and Madhya Pradesh, covering five-star restaurants as well as importers and exporters handling essential commodities through various ports.
    6. A licence establishes presence, not practice: A licence establishes that a business sits within the regulatory system. It does not establish that safe practices are being consistently followed.

    What do the Maharashtra inspection figures show?

    1. Statewide drive since May: More than 3,000 inspections were conducted across Maharashtra between 25 May and 31 July, which is the whole period since the drive began.
    2. Statewide outcomes: Those inspections resulted in 165 licence suspensions and 750 improvement notices, so the great majority of adverse findings were correctable rather than disqualifying.
    3. Pune leads on complaints: Pune recorded the highest number of complaints among the State’s divisions, which is what directed the drive’s field effort towards that division.
    4. Pune division activity: Between 25 May and 19 August the Pune division alone saw 691 inspections, with 53 licences suspended and 408 improvement notices issued.
    5. The regional baseline: Inspections in the western region identified around 2,300 improvement notices last year, and those findings arose even among larger and licensed businesses.
    6. The trigger was administrative: Inspection drives intensified after a new Maharashtra FDA Commissioner took charge in May, which ties the enforcement level to a posting rather than to a system.

    Why does compliance rise with inspection intensity and fall without it?

    1. The checklist does not verify itself: A refrigerator may have to be maintained at a prescribed temperature, an employee may have to follow a hygiene protocol and an outlet may have to maintain a register. The existence of a checklist does not guarantee that any of it happens when an inspector is absent.
    2. Enforcement is treated as preventive health by the regulator: The State FDA Commissioner has framed food safety as part of the non-communicable disease burden, on the position that a significant portion of that burden comes from what is consumed.
    3. Established operators run their own parallel systems: A 90-year-old Pune restaurant carries out pest control twice a month, checks refrigerator temperatures, cooking oil registers and staff training, and maintains hand-wash stations, exhaust systems and insect-proof doors and windows.
    4. Industry associations act as a second layer: The Pune Restaurants and Catering Association has been circulating compliance reminders and double-checking member compliance with both FDA and FSSAI requirements.
    5. The industry asks for proportionality, not leniency: The association has urged a “rational” approach in which minor compliance issues attract time to correct rather than public shaming, with the distinction drawn between a correctable deficiency and a violation that poses a public health risk.
    6. The stated goal is sustained compliance: The association’s own position is that the real challenge is sustained compliance without making the system dependent on periodic crackdowns.

    Why is training not producing behaviour change?

    1. Certification is not a precondition to a licence: Food safety training and certification, known as FoSTaC, is not currently mandatory before a food licence is issued, so an operator can be licensed before being trained.
    2. Awareness of the requirement is itself missing: Many food operators lack awareness of food safety laws and do not know that FoSTaC exists.
    3. Training risks becoming a document: Businesses must actually understand and implement what they have been taught, or the certificate becomes another compliance document rather than a mechanism for changing behaviour.
    4. The regulator’s own diagnosis agrees: The FSSAI regional director for the western region identifies lack of awareness and education as the major cause of non-compliance.
    5. Outreach has been substantial: Over the past three to four years FSSAI has trained street vendors, students and other groups to detect adulteration, with around 10,000 street food vendors trained in Mumbai and over 60 officer-led training programmes on street hygiene.
    6. Visible practice has shifted at the margin: Vendors are reported using headgear, steel chopping boards and smarter waste disposal methods, alongside farmer-connect programmes linking food businesses and farmers.

    Should enforcement be a numbers game or risk-based?

    1. Visibility works, delay undoes it: A former FSSAI Chief Executive Officer holds that visible and credible action of the kind seen in Maharashtra can change behaviour, and that long delays between violation detection and final accountability weaken deterrence.
    2. Violations are not equal in risk: Not all violations pose the same health risk, so regulatory effort should be prioritised rather than spread evenly across the licensed base.
    3. Prioritisation should follow hazard, not visibility: Effort should target foods, establishments and supply chains with the highest risk, including microbial and chemical hazards that are not always visible during an inspection.
    4. The remedy set is procedural: Faster case adjudication, credible evidence, proportionate penalties and transparency about outcomes are what convert detection into deterrence.
    5. Transparency must cover acquittals too: Outcomes should be published including where allegations do not hold, so publicity is not itself the penalty.

    What do international results show about restaurant focused food safety?

    1. Restaurants are a concentrated transmission point: Food is prepared in large quantities and served to many people, so an outlet level failure reaches a population rather than a household.
    2. Los Angeles County, United States, graded hygiene publicly: A publicly displayed restaurant hygiene grading system was introduced in 1998, and foodborne-disease hospitalisations were compared against trends elsewhere in California.
    3. The measured effect was large and durable: After adjustment for baseline temporal and geographic trends, the grading programme was associated with a 13.1 per cent reduction in foodborne-disease hospitalisations in the first year, sustained over two years.
    4. Training and systems show similar gains: A 2022 systematic review and meta-analysis of food safety interventions in catering establishments found a 28.6 per cent reduction in microbial contamination, from interventions involving food-handler training and food safety systems.
    5. The pathogen list is specific: Restaurant level food safety has been effective against norovirus, Salmonella Typhi which causes typhoid fever, Shiga toxin-producing E. coli which affects the kidney, Shigella which infects the intestinal lining, hepatitis A which affects the liver, and Listeria monocytogenes and Campylobacter which trigger gut infection.

    What does the detection and laboratory gap add?

    1. Elaborate rules, weak implementation: India’s food safety regulations are elaborate, and implementation is weakened by poor enforcement, manpower shortages, inspection capacity limits, delayed test results and lack of coordination among agencies.
    2. A violation must be provable, not merely observed: The capacity to detect and establish a violation is a separate constraint from the capacity to inspect, and it sits with accredited testing laboratories.
    3. Delay destroys the deterrent: A regulator can inspect a food business, and if laboratory results are delayed or enforcement action takes too long, the deterrent effect is weakened.
    4. Manpower limits targeting: If inspection teams do not have the manpower to identify the highest-risk businesses and supply chains, the existence of detailed rules matters little.
    5. The requirement is a shift in approach: The recommendation is to move from a reactive, routine approach to a risk-based system focused on high-risk foods, supply chains and repeat violators, supported by robust laboratory infrastructure, advanced analytical capacity and speedy access to test results.

    What lies beyond kitchen hygiene?

    1. The definition of food safety is wider than the kitchen: Food safety is not merely about clean kitchens, pest control or properly stored ingredients. It also concerns what consumers are told about food and how products are marketed.
    2. Deceptive practice is a safety question: The convenor of Nutrition Advocacy in Public Interest (NAPi), a network of public health professionals working on nutrition policy, holds that food safety means protection from deceptive practices by food manufacturers.
    3. The data gap on ultra-processed foods: Immediate action is needed to assess risks and generate data about consumption of ultra-processed foods in India.
    4. Two consumer protections remain pending: Front-of-Pack Labelling (FOPL) and tighter restrictions on marketing of ultra-processed and high-fat, sugar and salt (HFSS) foods have not been notified.
    5. Regulatory gaps defeat the compliance drive: Major regulatory gaps of this kind will defeat the purpose of normalising clean dining, because the risk migrates from preparation to composition.
    6. The product mix keeps moving: Complexity is increasing as the food industry expands into nutraceuticals and functional foods, which sit between food and medicine in the standards framework.

    Challenges to the Food Safety and Standards Authority of India

    1. No statutory definition of high-fat, salt and sugar foods: FSSAI has not precisely defined the HFSS category, so restrictions cannot be enforced against a class of products that has no legal boundary. Eg. The Indian Nutrition Rating star scheme has been under consultation without notification. Fix. Notify threshold values for salt, sugar and fat per 100 grams first, and attach the labelling scheme to those thresholds.
    2. Laboratory capacity limits prosecution: A limited number of notified food laboratories causes delays in sample analysis, and a delayed report weakens the case at trial. Eg. Sample results in adulteration cases routinely arrive after the statutory reporting window. Fix. Accredit private laboratories under the National Accreditation Board for Testing and Calibration Laboratories to a published turnaround standard and pay them per sample.
    3. Approval delays for new formulations: Lengthy approval of proprietary food formulations delays market entry and pushes products into the unregulated segment. Eg. Nutraceutical and functional food products face repeated re-submission. Fix. Introduce a deemed approval on lapse of a notified timeline, with post-market surveillance replacing pre-market delay.
    4. Weak enforcement allows recurring adulteration: Poor field monitoring lets known adulteration patterns persist across cycles. Eg. Cases of synthetic milk and spurious honey recur across States. Fix. Publish a State-wise repeat violator register so a business cannot re-register under a fresh licence after suspension.
    5. Industry resistance to disclosure: Packaged food makers resist front-of-pack labelling on the expectation that it reduces sales, and consultation stretches indefinitely. Eg. Debate continues between star ratings and clearer warning labels of the Nutri-Score type. Fix. Fix a statutory deadline for notification, with the warning label design applying by default if no consensus design is notified by that date.
    6. Marketing to children is unregulated: Endorsements associate unhealthy products with aspiration at an age when food preference is formed. Eg. Celebrity endorsement of high sugar beverages remains permitted. Fix. Prohibit celebrity and cartoon endorsement of products crossing the HFSS thresholds once those thresholds are notified.

    Conclusion

    Maharashtra’s inspection drive has produced a measurable rise in compliance, and the drive itself is tied to a change of Commissioner rather than to a permanent system. The current status is that FSSAI’s revised turnover based licensing slabs are in force from 1 April this year, with Front-of-Pack Labelling and restrictions on HFSS marketing still pending notification. The next milestone is whether FoSTaC certification is made a precondition to licensing and whether enforcement is reorganised around risk rather than inspection count. The evidence from graded hygiene systems elsewhere shows that a design change in how compliance is displayed and adjudicated moves outcomes more than the number of inspections does.

    Matching Previous Year Question

    “[2015, GS2, 12 marks] For achieving the desired objectives, it is necessary to ensure that the regulatory institutions remain independent and autonomous. Discuss in the light of the experiences in recent past.”