💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS3

  • FCNR(B) deposits push forex reserves to all-time high of $729 bn in August

    Why in the News

    The Reserve Bank of India’s concessional swap window for Foreign Currency Non-Resident (Bank), or FCNR(B), deposits has propelled India’s foreign exchange reserves to a record $729.33 billion as of 21 August, surpassing the previous all-time high of $728.49 billion recorded on 27 February, just a day before the United States and Israel struck Iran and touched off the West Asia conflict that drove global energy prices sharply higher. Reserves rose by $12.42 billion in the week ended 21 August alone, with FCNR(B) inflows of $65.4 billion accounting for most of the $72.85 billion that has entered India since three concessional swap windows opened on 8 June.

    What is driving reserves to a record, and what does the FCNR(B) window actually do?

    1. Scale of inflows: FCNR(B) deposits outstanding rose from $34.04 billion at the end of May to $65.4 billion by 21 August, since the window opened on 8 June, and reserves themselves jumped $12.42 billion in the week ended 21 August.
    2. Mechanism: Under the FCNR(B) scheme the central bank bears the full exchange rate risk on these non-resident deposits, since the money is held in foreign currency rather than converted into rupees, which let banks offer interest rates as high as 7.4 percent.
    3. Leveraged NRI participation: Non-resident Indians have also borrowed at lower interest rates abroad to deposit the proceeds into FCNR(B) accounts, earning returns of as much as 15 percent on the resulting spread.

    Why did reserves need rebuilding in the first place?

    1. The rupee was already under stress before the record: The rupee came under intense pressure from large foreign portfolio outflows, with $19 billion leaving Indian markets in 2025 and a further $24 billion in the first five months of 2026, pushing the currency to near 97 per dollar in mid-May.
    2. The West Asia conflict added an oil import shock: Since roughly 85 percent of India’s crude oil needs are met through imports, the conflict’s closure-driven spike in global energy prices raised the country’s import bill and added further pressure on the rupee just as reserves were near their earlier February high.
    3. The rupee remains down year-on-year despite the record reserves: The rupee closed at 95.39 per dollar on Friday, little changed from its 95.79 level on 4 June and still 8.1 percent weaker than a year earlier, showing the reserve build has stabilised rather than reversed the currency’s decline.

    What other measures accompanied the FCNR(B) window?

    1. Two additional swap windows: Announced alongside FCNR(B) on 5 June, swap facilities for Overseas Foreign Currency Borrowings and External Commercial Borrowings have together brought in $4.86 billion and $2.59 billion respectively since 8 June.
    2. Tax relief for foreign portfolio investors: The government removed capital gains and withholding taxes on foreign portfolio investment in government securities as part of the same package meant to pull in capital and support the rupee.
    3. An accelerated closure timeline: Because inflows arrived faster than expected, the RBI moved the FCNR(B) window’s closing date to 31 August, a month earlier than the originally announced 30 September deadline.

    Challenges to relying on FCNR(B)-driven reserve accumulation

    1. Weak currency response relative to precedent: The rupee has barely moved during this swap window, compared with the 2013 episode when the rupee rose 10.3 percent, from 67.6 to 61.3 per dollar, in the first 40 days after the RBI’s then-Governor introduced a similar FCNR(B) swap facility. Eg. The rupee moved from 95.79 to 95.39 per dollar between 4 June and 29 August this year, a fraction of the 2013 currency response to a comparable scheme. Fix. Pair reserve accumulation with structural measures that improve the current account, such as diversifying energy import sources, rather than treating swap-driven capital inflows alone as sufficient to support the currency.
    2. Reversal risk from leveraged hot money: A meaningful share of FCNR(B) inflows has been driven by non-resident Indians borrowing cheaply abroad to arbitrage into high-yield deposits, a flow that can reverse quickly once interest rate differentials narrow or the window closes. Eg. The window’s early closure on 31 August, a month ahead of schedule, was itself driven by inflows arriving faster than expected, which cuts both ways once the scheme ends and deposits mature. Fix. Stagger FCNR(B) maturities and monitor the redemption schedule closely to avoid a sudden reserve drawdown when large deposit tranches come due.

    Conclusion

    The FCNR(B) swap window has pushed India’s foreign exchange reserves past their previous February high to a record $729.33 billion, giving the Reserve Bank of India greater capacity to defend the rupee after a period of heavy foreign portfolio outflows and an oil price shock from the West Asia conflict. The rupee’s limited appreciation despite the record inflow, unlike the sharper rupee gains seen after the comparable 2013 swap window, signals the current build is cushioning rather than reversing currency pressure.

    Back2Basics: What are FCNR(B) deposits?

    1. FCNR(B) deposits are foreign currency accounts that non-resident Indians can hold with Indian banks, where the deposit and its returns stay denominated in the foreign currency rather than in rupees.
    2. The scheme shifts exchange rate risk onto the Reserve Bank of India rather than the depositor or the bank, which lets banks offer higher interest rates to attract inflows during periods of currency pressure.
    3. India last used a similar concessional FCNR(B) swap window in 2013, under then RBI Governor Raghuram Rajan, to stabilise the rupee following a sharp depreciation.

    Matching Previous Year Question

    No direct PYQ traced in the provided files (Pass 1: FCNR(B), forex reserves record — no match; Pass 2: balance of payments, current account — matches found were conceptually unrelated to a record reserves event).
  • Govt. eases norms for defence exports, licences

    Why in the News

    The Defence Ministry has simplified its Defence Export Standard Operating Procedure (SOP) and overhauled the Open General Export Licence (OGEL) framework to help Indian defence manufacturers access global markets faster. Stakeholder consultation with concerned ministries and government agencies has been dispensed with for exports of non-lethal defence items to most destinations, though safeguards continue for sensitive countries, and the same consultation requirement has been removed altogether for exports linked to international tenders and exhibitions.

    What has changed under the revised Export SOP?

    1. Reduced consultation for non-lethal exports: Stakeholder consultation with concerned ministries and agencies is no longer required for exporting non-lethal defence items to most destinations, though safeguards remain in force for sensitive countries.
    2. No consultation for tenders and exhibitions: The same consultation requirement has been dropped for exports of all items meant for international tenders and exhibitions, letting Indian companies pursue overseas opportunities faster.

    How has the OGEL framework been restructured?

    1. Consolidated procedures: Three separate OGEL SOPs, covering major platforms and equipment, parts and components, and intra-company technology transfer, have been merged into a single framework.
    2. Longer validity and wider country coverage: OGEL validity has been extended from two years to three, and its country coverage expanded from 41 countries to all countries except those designated negative or sensitive.
    3. A new licence category for long-term contracts: Indian companies with long-term contracts or agreements with foreign original equipment manufacturers can now obtain an OGEL for eligible items tied to that specific manufacturer, with validity aligned to the underlying contract.
    4. Expanded item coverage: OGEL eligibility now extends to civil-end-use exports of specified small-calibre arms components and protective equipment.

    Challenges to the liberalised export and licensing regime

    1. Diversion risk from wider country coverage: Extending OGEL coverage to all countries except a negative list raises the risk that dual-use or sensitive items reach unintended end users through re-export or transhipment. Eg. Widened general licensing regimes elsewhere have previously required retrofitted end-use verification systems after initial liberalisation exposed gaps, as seen in tightened United States Commerce Control List enforcement following early Export Administration Regulations liberalisation. Fix. Pair the wider OGEL coverage with mandatory post-export end-use certification audits for a sample of shipments to non-treaty destinations.
    2. Consultation removal versus oversight continuity: Dispensing with stakeholder consultation for non-lethal exports speeds approvals but removes a cross-ministry check that previously caught destination-specific concerns before shipment. Eg. Non-lethal classification itself can be contested, since components with civil and military dual use, such as certain protective equipment, may be misclassified at the exporter’s discretion. Fix. Retain a post-facto sampling audit by the Department of Defence Production even where pre-export consultation is waived.

    Conclusion

    The Defence Ministry’s overhaul of the Export SOP and the OGEL framework liberalises licensing timelines, validity and country coverage for Indian defence exporters while explicitly retaining safeguards for sensitive countries and technologies. The stated intent is to let Indian manufacturers respond faster to international tenders and deepen co-production ties with foreign original equipment manufacturers.

    Back2Basics: What is an Open General Export Licence (OGEL)?

    1. An OGEL is a standing, one-time authorisation that lets an eligible exporter self-generate export authorisations for multiple consignments of specified defence items without seeking a separate approval for every individual shipment.
    2. It is administered by the Defence Ministry’s Department of Defence Production and covers major platforms and equipment, parts and components, and intra-company technology transfers.
    3. Its use remains subject to end-destination safeguards, so items bound for negative or sensitive countries continue to require case-by-case authorisation outside the OGEL route.

    Matching Previous Year Question

    No direct PYQ traced in the provided files.

  • Problem with ethanol blending isn’t sugar — it’s reliance on grains; the way forward (Op-ed by Harish Damodaran)

    Why in the News

    India’s ethanol blended petrol (EBP) programme, an arrangement under which oil marketing companies blend ethanol into petrol to progressively raise the blending ratio, was designed primarily to help sugar mills earn an additional revenue stream so they could pay cane farmers on time. For the current supply year ending October 2026, grain based feedstock accounts for 759.8 crore litres, or 72.5 percent, of the 1,048.3 crore litres of ethanol allocated among distilleries, against 288.5 crore litres, or 27.5 percent, from sugarcane based feedstock. What began as a sugar-support programme has become a grain-dependent one, and the article argues this reversal, not sugar diversion, is the programme’s real problem.

    What is the Ethanol Blended Petrol (EBP) programme?

    1. About: The EBP programme requires oil marketing companies to blend ethanol into petrol at a rising target ratio, currently 20 percent under the E20 standard, to cut crude oil imports and support farm incomes.
    2. Feedstock: Ethanol can be produced from sugarcane derived molasses and juice, or from cereal grains such as maize and rice, through milling, starch extraction, fermentation, distillation and dehydration to 99.9 percent pure alcohol.
    3. Original design: The programme was conceived to give sugar mills a secondary revenue stream so they could clear cane payment dues to farmers, and was later extended to maize farmers as an additional demand source.

    How did the feedstock mix shift from sugarcane to grain?

    1. The molasses-only phase, till 2017-18: All ethanol supplied to oil marketing companies came from C-heavy molasses, the final byproduct of cane juice processing left after mills had recovered all economically extractable sugar.
    2. The B-heavy and direct-juice phase, from 2018-19: Mills began producing ethanol from intermediate B-heavy molasses and directly from cane juice or syrup, incentivised by higher government-set prices for ethanol from these routes, which let mills divert sucrose before it was even crystallised into sugar. Ethanol supplies to oil marketing companies rose from 38 crore litres in 2013-14 to 190 crore litres in 2018-19, and blending rose from 1.6 percent to 4.9 percent over the same period.
    3. The grain takeover, 2018-19 onward: Standalone grain-based distilleries, running on maize or on surplus and damaged rice sourced from the Food Corporation of India (FCI) or the open market, expanded independently of the sugar season. By 2023-24, grain-based feedstock supplied 402 crore litres, or 59.7 percent, of the 673 crore litre total that helped achieve 14.6 percent average blending, a reversal the article calls the tail wagging the dog.
    4. Current supply year, 2025-26: Of the 1,048.3 crore litres allocated to hit the E20 target, 759.8 crore litres, or 72.5 percent, is from grains and only 288.5 crore litres, or 27.5 percent, is from sugarcane-based feedstock, against a backdrop of September-ending sugar stocks projected at a 17-year low.

    Why is rice, not maize, now the likely mainstay feedstock?

    1. Maize supply risk: El Nino conditions are expected to persist through the first half of next year, raising doubts about maize availability for ethanol in 2026-27 even as sugarcane diversion is curtailed.
    2. Rising reliance on FCI rice: The government allocated 5.2 million tonnes of surplus FCI rice to ethanol distilleries for 2025-26, raised to 7.2 million tonnes in July; at 450 to 460 litres of ethanol per tonne, that yields only 325 to 330 crore litres, well short of the roughly 1,050 crore litres needed to sustain E20.
    3. Rice is water-intensive and underpriced for this use: FCI rice is sold to ethanol distilleries at Rs 23.2 per kg, with a reserve price of Rs 21 per kg for fully broken grains, against a retail market price of Rs 40 per kg for normal rice and Rs 30 per kg for broken rice, and rice is a water-guzzling crop to be diverting toward fuel at scale.
    4. Distillery capacity outpaces demand: Distillers have built an aggregate ethanol production capacity of nearly 2,000 crore litres, against 421 crore litres in 2014 and current annual offtake of 1,050 crore litres, and it is this installed capacity, not farmer need, that is driving the push for even higher blending standards such as E22, E25, E27 and E30.

    What effect has the programme had on maize farmers, and what is at risk if grain reliance deepens further?

    1. Maize price gains: With ethanol demand added to poultry and livestock feed demand, wholesale maize prices in India rose from a Rs 13.8 to Rs 17.8 per kg range in 2021 to a Rs 22.1 to Rs 24.5 range in 2024, benefiting maize growers the way the programme once benefited cane farmers.
    2. A rice-driven repeat of the same trade-off: Sustaining current blending targets without sugar or adequate maize would require earmarking still more FCI rice, a shift the article argues is difficult to justify given rice’s water footprint and its underpriced diversion from the food security stock.

    Way Forward

    1. Discourage standalone grain distilleries reliant on FCI rice: The government should end this diversion route and push distillers toward less water-intensive grains such as bajra and jowar, which carry 58 to 62 percent recoverable starch and can yield 380 to 400 litres of ethanol per tonne, comparable to maize, letting millet farmers gain the same price benefit maize growers have seen.
    2. Stop chasing blending targets ahead of schedule: The EBP programme was already succeeding at 10 to 15 percent blending, and the article notes the government’s own chief economic adviser has suggested reverting to the E10 standard, an argument the piece endorses as pragmatic rather than a retreat.

    Back2Basics: What is the E10/E20 standard?

    1. E10 and E20 denote the percentage of ethanol blended into petrol, so E20 petrol contains 20 percent ethanol against 80 percent petrol by volume.
    2. India crossed the E10 blending average in 2021-22 and reached the E20 national average in the current 2025-26 supply year, years ahead of the original 2030 target set for E20.
    3. Government notified fuel standards now extend beyond E20 to E22, E25, E27 and E30, reflecting distillery capacity built well beyond current ethanol offtake.

    Matching Previous Year Question

    PrelimsPYQ.csv: “In the context of alternative sources of energy, ethanol as a viable bio-fuel can be obtained from:” (2009, Microtheme: Biofertilizers/Fuels, Subject: Environment)

  • Policy mistakes, not ethanol, behind sugar price rise (Editorial)

    Why in the News

    Retail sugar prices have risen from an average of Rs 45 to Rs 65 per kg within a month, and the increase is being widely blamed on the ethanol blended petrol programme. Only 27.5 percent of the ethanol supplied by distilleries to oil marketing companies in 2025-26 came from sugarcane juice and molasses, with the balance from cereal grains, and the roughly 3 million tonnes of sugar diverted for ethanol is close to a tenth of the year’s 30.9 million tonne gross production. Similar or larger diversions in the four preceding sugar years did not cause comparable price spikes, which places the blame elsewhere.

    Is ethanol actually responsible for the price spike?

    1. Small diversion share: The estimated 3 million tonnes of sugar diverted to ethanol production is close to a tenth of the 30.9 million tonne gross sugar output for the year ending September 2026.
    2. No precedent for a price link: The four preceding sugar years saw diversions of 3.5 million tonnes, 2.4 million tonnes, 4.3 million tonnes and 3.6 million tonnes respectively, all without triggering a comparable price spiral.
    3. Feedstock mix has shifted away from sugar already: Only 27.5 percent of ethanol supplied to oil marketing companies in 2025-26 came from sugarcane juice and molasses, with the rest from cereal grains, so the programme is no longer primarily a sugar diversion story.

    What actually explains the price spurt?

    1. A large output shortfall: Gross sugar production for the year came in well below the initial 34.4 million tonne projection made at the start of crushing in November, a shortfall of 3.5 million tonnes.
    2. A late government response: Mills in Uttar Pradesh and Maharashtra were struggling to get cane and shutting down crushing operations by February, but the shortfall was not addressed until exports were banned only in mid-May.
    3. Panic measures after prices soared: From July, as a deficient June monsoon raised concerns about cane yields for 2026-27, the government imposed a 400 tonne stock limit with a 30 day holding cap on all dealers and ordered mills to furnish details of bulk buyers who purchased 500 tonnes or more.

    What should the government have done instead?

    1. Keep the import window open: Rather than banning exports, the government could have cut the tariff on raw and white sugar imports from 100 percent to zero by April, when most mills had stopped crushing.
    2. Rely on market intelligence over controls: The sugar industry runs on government-set controls, from cane pricing to how much a mill may sell in a given month, a control structure this crisis exposed as failing to anticipate and balance supply and demand.

    Conclusion

    The editorial’s central claim is that the sugar price rise is a policy failure, rooted in a delayed response to an anticipated output shortfall and a subsequent set of panic controls, not a consequence of the ethanol blending programme. The remedy it points to, opening the import window through tariff cuts rather than export bans and stock limits, remains untested by the government to date.

    Matching Previous Year Question

    PrelimsPYQ.csv: “Statement I: Of the two major ethanol producers in the world, i.e., Brazil and the United States of America, the former produces more ethanol than the latter. Statement II: Unlike in the United States of America, where corn is the principal feedstock for ethanol production, sugarcane is the principal feedstock for ethanol production in Brazil.” (2025, Microtheme: Biofertilizers/Fuels, Subject: Environment)

  • Government to introduce fortnightly sugar allocation

    Why in the News

    The Centre has decided to replace the existing monthly sugar quota system with a fortnightly allocation system from September. A physical verification of sugar stocks at mills found that many mills held stocks well beyond their declared monthly returns, that some mills engaged in short selling by selling less sugar than their monthly allocation, and that sugar sold at the start of a month was in some cases lifted by buyers only at the month’s end. The move tightens a monitoring system the government found could be gamed under a monthly cycle.

    Why did the government find the monthly quota system inadequate?

    1. Stock under-declaration: Physical verification showed many mills were holding stocks in excess of what they had declared in their monthly returns to the government.
    2. Short selling: Some mills sold less sugar than the quantity actually allocated to them under the monthly quota, without any monthly-cycle mechanism to catch the shortfall quickly.
    3. Delayed lifting by buyers: In some cases sugar sold by a mill early in the month was dispatched or lifted by the buyer only near the end of the month, defeating the purpose of a monthly release schedule.

    What does the new fortnightly system require?

    1. Split sale mandate: Mills must sell at least 40 percent of their fortnightly allocation in the first week and the remaining balance in the second week.
    2. Faster dispatch: Mills have been directed to dispatch sold sugar within a week of sale, closing the gap that allowed delayed lifting under the monthly system.
    3. Closer monitoring: A fortnightly cycle lets the government track the demand supply position more frequently, respond faster to market changes, and release additional quota where needed.

    Challenges to the fortnightly allocation system

    1. Compliance burden on mills: A fortnightly reporting and dispatch cycle roughly doubles the administrative and logistical load mills previously carried under a monthly system. Eg. Mills must now furnish dispatch proof and stock declarations twice as often, straining smaller mills with limited administrative staff. Fix. Phase in stricter reporting first for mills previously flagged for under-declaration or short selling, rather than applying the full compliance load uniformly from day one.
    2. Enforcement capacity: The scheme depends on the government’s ability to verify declarations at the mill level frequently enough to catch violations before the next cycle begins. Eg. The August verification exercise that triggered this shift was itself a one-time physical check, not a standing monitoring mechanism. Fix. Institutionalise periodic third-party stock audits rather than relying on ad hoc verification drives.

    Conclusion

    The fortnightly allocation system is a direct administrative response to mill-level under-declaration, short selling and delayed dispatch uncovered during stock verification. Crushing for the new sugar year begins on 15 October, with production of 10 lakh tonnes expected in October and 45 lakh tonnes in November, and mills are free to sell without restriction through October.

    Matching Previous Year Question

    No direct PYQ traced in the provided files.

  • [28th August 2026] The Hindu OpED: New-age fires

    [28th August 2026] The Hindu OpED: New-age fires

    Question (2024, GS3): “What is disaster resilience? How is it determined? Describe various elements of a resilience framework. Also mention the global targets of the Sendai Framework for Disaster Risk Reduction (2015-2030).”
    Linkage: The lack of a “distinct safety regime” for highly vulnerable environments like ICUs represents a core gap in India’s disaster resilience framework. This question challenges candidates to describe how to move from a structural vulnerability to a resilient system using global standards like the Sendai Framework.

    Mentor Comment

    India’s fire risk profile has shifted over the past 15 years from industrial facilities, large offices and mass gatherings toward residential buildings, hotels and hospitals, with electrical fires, driven by heavier appliance use, overloaded circuits and poor maintenance, now predominant. Intensive Care Units are especially vulnerable because of their oxygen rich environments, and this month back to back fires struck neonatal Intensive Care Units in Amravati, Maharashtra, and Chhindwara, Madhya Pradesh. Despite a string of near identical incidents since the 2024 Jhansi fire in which 18 newborns died, ICU fires have still not produced a single, distinct safety regime for the units most at risk.

    What happened in this month’s neonatal ICU fires?

    1. Amravati: The fire was extinguished within 30 minutes, but smoke proved fatal for three babies who were already being treated for complications, with a faulty ventilator suspected as the cause.
    2. Chhindwara: A short circuit in a warmer at the district hospital’s Neonatal Intensive Care Unit triggered a fire in which three newborns, only days old, suffered burns.

    Why should ICU fires be treated as a distinct safety category?

    1. They are sealed spaces that fill with smoke fast: Intensive Care Units are sealed compartments where smoke accumulates quickly, and in a Neonatal Intensive Care Unit patients cannot evacuate on their own, making regular evacuation drills essential.
    2. A safer design already exists on paper: A best case setup includes three independent exits, with at least two allowing horizontal evacuation, automatic sprinklers, independent power lines for major equipment, oxygen cylinder supports positioned away from electrical sockets, and fire drills held every two years.

    What regulatory response has followed past ICU fires?

    1. A professional body called for mandatory certification: Following an earlier Neonatal Intensive Care Unit fire in Delhi, the National Neonatology Forum called for mandatory fire safety certification for Neonatal Intensive Care Unit equipped hospitals, regular power audits and analogue addressable alarms.
    2. A named evacuation protocol followed: The same push produced a standard evacuation protocol, now known as RACE, for Rescue, Alarm, Confine, and Extinguish or Evacuate.
    3. New national guidelines offer a starting point: The 2026 National Guidelines on Fire and Life Safety in Healthcare Facilities can serve as a starting point for building ICU and Neonatal Intensive Care Unit specific safety standards.

    What risk do post fire investigations typically miss?

    1. Electrical harmonics is a largely unaudited factor: Neonatal Intensive Care Unit equipment is packed with electronic components that draw distorted current, which can silently overheat neutral wiring, transformers and loose connections without ever tripping a circuit breaker.
    2. Generic findings may be hiding the real cause: Post fire reports that cite generic “short circuits” or “technical faults” may be missing this harmonic driven degradation entirely, leaving the underlying risk unaddressed even after an inquiry closes the case.

    Challenges to ICU fire safety

    1. Fire safety certification is not uniformly enforced: Many hospitals, particularly outside metro cities, operate without a valid fire safety no objection certificate or lapse on renewal. Eg. Investigations after major hospital fires, including the Jhansi Neonatal Intensive Care Unit fire in which 18 newborns died, have repeatedly found expired or absent fire clearances. Fix. Link a hospital’s fire safety certificate renewal to its registration and accreditation status, so a lapsed certificate automatically suspends the facility’s licence to operate.
    2. Backup power for critical equipment is often shared, not independent: Ventilators, warmers and monitors frequently run off the same power lines as general hospital load, so a single fault can cut life support equipment. Eg. A suspected equipment fault caused this month’s Amravati Neonatal Intensive Care Unit fire. Fix. Mandate a dedicated, separately fused power line for every ICU bed’s life support equipment, independent of the hospital’s general electrical circuit.
    3. Frontline staff are rarely trained for ICU specific evacuation: Evacuating patients who cannot move on their own requires drilled procedures that most hospital staff never practise. Eg. Regular ICU evacuation drills remain the exception rather than the norm even at accredited hospitals nationally. Fix. Make a biennial ICU evacuation drill, as already recommended for Neonatal Intensive Care Units, a mandatory condition of hospital accreditation across all critical care units, not only newborn wards.

    Conclusion

    ICU and Neonatal Intensive Care Unit fires have recurred at roughly the same scale and for the same reasons since the 2024 Jhansi fire, with certification calls and evacuation protocols repeatedly following each incident without preventing the next one. Treating ICU fires as a distinct safety category, backed by independent power lines, harmonics audits and enforced certification, is what remains to convert a decade of incident specific responses into a standing safety regime.

  • Echoes of past, warning for future

    Echoes of past, warning for future

    Why in the News

    A flash flood in Nepal’s Bhotekoshi Trishuli river system has killed more than 350 people, left several hundred more missing, and damaged 35 motorable bridges, 45 suspension bridges and about 40 kilometres of roads across the affected corridor, Nepalese authorities said. Satellite imagery analysed by global agencies, including the Indian Space Research Organisation, points to a glacier collapse or rock and ice avalanche in Tibet that briefly blocked the river before a sudden, destructive release downstream. An earthquake was initially suspected as the trigger, but subsequent analysis has not supported that theory. The exact sequence, whether an ice block broke away from the glacier or a lake within the glacier breached, remains contested, and the disaster is the latest in a run of Himalayan cascade events that repeated monitoring gaps have failed to prevent.

    What is a Glacial Lake Outburst Flood?

    1. About: A Glacial Lake Outburst Flood is the sudden, large scale release of water when a lake formed by a melting glacier breaches, either because a block of glacial ice or rock falls into it or because accumulated stress in its containing moraine gives way.
    2. Mechanism: The resulting wave can overtop and breach the lake’s frontal moraine, releasing water, rock and debris that erode river banks, uproot trees and trigger further landslides as it moves downstream.
    3. A related event type: A cascade can also begin without a lake, when a large block of glacial ice or rock breaks away and falls directly into a river, as is currently suspected in the Nepal disaster.

    What is understood so far about what caused the Nepal disaster?

    1. A rock and ice avalanche is the leading explanation: The event is currently understood to have been triggered by a large block of glacier breaking off in the upper reaches of the Bhotekoshi river, known as the Trishuli in its lower course, though what caused the break is not yet clear.
    2. Heavy rainfall has been ruled out: No heavy rainfall was recorded in the area, which rules out an extratropical Western Disturbance as the trigger despite north India and the Himalayan region being under its influence at the time.
    3. The earthquake reading was reclassified: The United States Geological Survey first reported a 4.4 magnitude earthquake, then revised its assessment to say the seismic signal, later corrected to 5.2 magnitude, was generated by a glacial collapse and debris flow rather than an actual earthquake.
    4. Scientists are divided on the exact mechanism: One glaciologist has pointed out that no ice blocks are visible in videos of the disaster and suggested a breach in a “supra glacial lake” (a lake that forms within a glacier rather than at its foot, increasingly common as glaciers melt under climate change) as the more likely cause, a view a former national disaster management official has echoed.

    How does the Nepal disaster compare with past Himalayan cascade disasters?

    1. Kedarnath, 2013: Unusually heavy rainfall melted the Chorabari glacier and swelled the Mandakini river, causing flash floods and landslides across Uttarakhand, Himachal Pradesh and western Nepal that left nearly 6,000 people presumed dead, the most devastating of the four.
    2. Chamoli, 2021: A rock and ice avalanche broke away from a glacier, an estimated 27 million cubic metres of material, and fell into the Rishiganga river in Uttarakhand, killing more than 200 people.
    3. Sikkim, 2023: The collapse of nearly 14.7 million cubic metres of frozen moraine into the South Lhonak glacial lake generated a 20 metre high wave that breached the lake’s frontal moraine, releasing about 50 million cubic metres of water, eroding roughly 270 million cubic metres of sediment and triggering 45 secondary landslides that killed at least 55 people.
    4. Dharali, 2025: Days of continuous rain combined with terrain at nearly 6,900 metres above sea level triggered mudslides, debris slides and flash floods in Uttarakhand that killed at least 69 people.

    Why does the Himalayan region keep producing these cascading disasters?

    1. The ecosystem is already destabilised: A glaciologist heading a Himalayan research organisation’s Cryosphere group has described the entire Himalayan region as “out of balance” because of population pressure and climate change, with newer areas being exposed as glaciers retreat.
    2. A single trigger becomes a multi hazard chain: What begins as one event, extreme rainfall, a landslide or a lake overflow, quickly compounds into a chain reaction of bank erosion, added debris and further landslides, because the surging water in a narrow mountain valley has no way to disperse until the terrain flattens.
    3. The region is also earthquake prone: The Himalaya is among the most seismically dangerous regions in the world, and Nepal itself suffered a 7.2 magnitude earthquake in 2015, so rainfall, a landslide or seismic activity can each independently trigger a similar cascade.

    What early warning cooperation exists across the Himalayan region?

    1. Two regional mechanisms already exist: The World Meteorological Organisation’s South Asia Hydromet Forum brings together the region’s meteorological and hydrological agencies, while the South Asia Flash Flood Guidance System provides regional flood forecasting and guidance.
    2. These systems remain under scaled for the risk: Both need to be scaled up to allow greater sharing of data, forecasting expertise and early warning systems among Himalayan countries, since the current disaster crossed from Tibet into Nepal without any shared alert reaching people downstream in time.
    3. India and China share common ground despite other differences: The two countries are often aligned in climate negotiations despite their broader geopolitical disagreements, a common outlook that has not yet been converted into a shared India China Nepal early warning system for glacial and flood risk.

    Challenges to Himalayan glacier and flood monitoring

    1. The scale of what needs monitoring is enormous: The Indian Himalaya alone holds nearly 7,500 glacial lakes and about 15,000 glaciers, only some of which are tracked through remote sensing. Eg. Ground verification requires site visits that are feasible only between July and September because of terrain and weather. Fix. The National Disaster Management Authority’s National GLOF Risk Mitigation Programme, launched after the Sikkim disaster with an outlay of Rs 150 crore, is installing early warning systems at high risk glacial lakes across Sikkim, Uttarakhand, Arunachal Pradesh, Himachal Pradesh, Jammu and Kashmir and Ladakh, though it currently covers only 195 lakes against thousands identified.
    2. Early warning carries its own risk of being ignored or causing panic: Forecasting a glacier collapse accurately remains extremely difficult, and a warning that proves false can be counterproductive if residents who lack alternatives choose not to move regardless. Eg. Communities living near glacial lakes have historically stayed in place through repeated flood warnings because they have nowhere else to go. Fix. Pair early warning systems with pre identified relocation sites and compensation, so a warning carries a real alternative rather than only an instruction to move.
    3. Construction in vulnerable zones continues unchecked: Dams and hydropower projects sited in glacial and flood prone terrain are consistently among the first structures destroyed in these events. Eg. A hydropower project in Sikkim was pulverised by the 2023 South Lhonak glacial lake outburst flood. Fix. Enforce construction codes that bar large dams and settlements from mapped high risk zones and require glacier health assessments before project clearance.

    Conclusion

    The exact cause of the Nepal flood is still being verified, but it fits an established pattern of Himalayan cascade disasters that recur every few years across India and Nepal. What remains unresolved is less the mechanism of any single event than the region’s continuing gaps in glacier monitoring, construction regulation in vulnerable terrain and cross border early warning, none of which past disasters have closed.

    PYQ

    [2014] “Bring out the relationship between the shrinking Himalayan glaciers and the symptoms of climate change in the Indian sub-continent.”

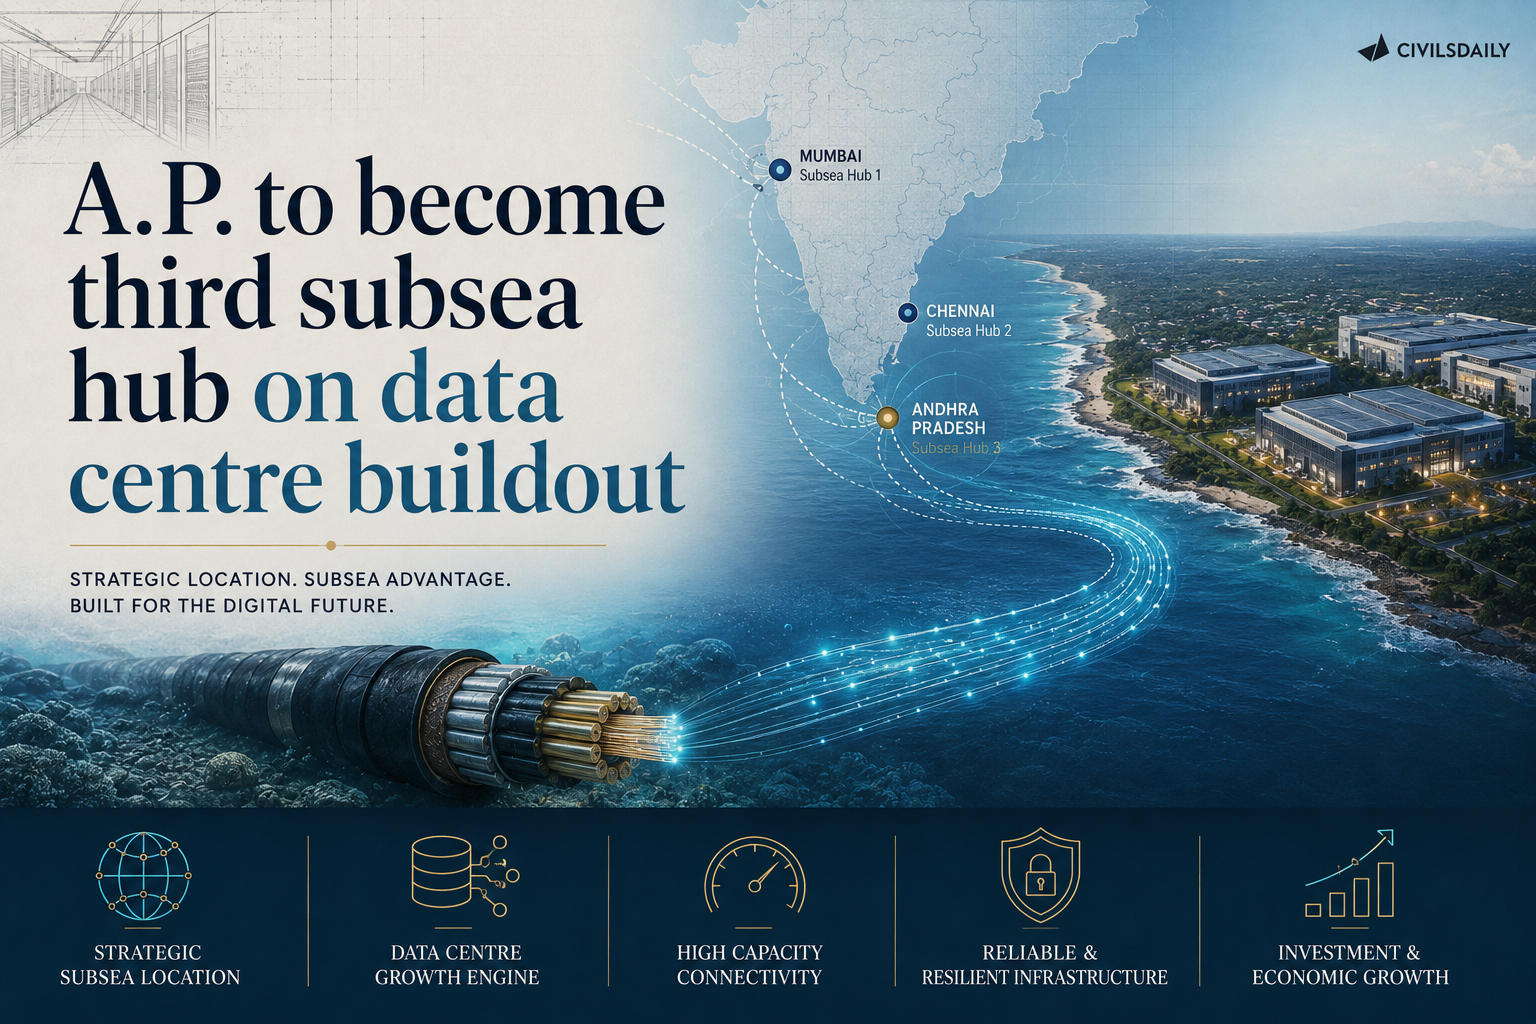
  • A.P. to become third subsea hub on data centre buildout

    A.P. to become third subsea hub on data centre buildout

    Why in the News

    Technology majors Microsoft and Google are building new subsea cable landing stations on the coast of Andhra Pradesh as part of an artificial intelligence linked data centre buildout in the State. Microsoft is part of a consortium with Lightstorm and the Singaporean telecom operator Singtel to land the 3,600 kilometre India Southeast Asia Submarine Cable System, while Google’s globe spanning America India Connect system will land at Visakhapatnam, where the company’s own data centre complex is coming up. Once complete, the buildout will give India, after Mumbai and Chennai, a third digital international gateway, even as a global shortage of fibre threatens to slow the inland network these projects still need.

    What is a subsea cable landing station?

    1. Definition: A subsea cable landing station is the facility where an undersea fibre optic cable comes ashore and connects to a country’s terrestrial network, carrying the bulk of international internet traffic.
    2. Global reliance: The overwhelming majority of the world’s international data traffic travels through such undersea cable systems rather than satellites, making landing stations critical infrastructure.
    3. India’s current concentration: India’s existing landing stations are concentrated in Mumbai and Chennai, leaving the country reliant on a small number of routes.

    What new cable infrastructure is being built off Andhra Pradesh’s coast?

    1. Microsoft’s consortium project: Microsoft, alongside Lightstorm and Singtel, is landing the 3,600 kilometre India Southeast Asia Submarine Cable System, expected to be ready for service in the fourth quarter of 2029.
    2. Google’s own system: Google’s America India Connect system will land at Visakhapatnam, alongside the data centre complex the company is building there as part of what a Google executive described as an artificial intelligence hub.

    What does this make Visakhapatnam?

    1. India’s third gateway: After Mumbai and Chennai, Visakhapatnam becomes India’s third digital international subsea gateway, connecting the country directly with Southeast Asia, Australia and the Middle East.
    2. A new corridor: Lightstorm’s chief executive has described the India Southeast Asia system, which also connects to Chennai, as providing a fresh corridor to South Asia from Singapore and Malaysia.

    Why are companies building on the east coast now?

    1. Ageing existing infrastructure: Most cables currently connecting India’s east coast are old, are already filled to capacity and are approaching the end of their working life.
    2. A search for resilience: Companies are also seeking to reduce the risk of relying on a single route by adding cables on India’s east coast, citing instability in West Asia as a reason to build in an alternate location.

    What inland infrastructure does this buildout require?

    1. A nationwide undertaking: Both projects require installing and lighting thousands of kilometres of new terrestrial fibre linking the coast to major cities, a scale one company executive described as spanning the entire country.
    2. A dedicated corridor: Lightstorm is expected to build a terrestrial corridor connecting Machilipatnam to Mumbai and Hyderabad, and Chennai to Hyderabad and Mumbai, with matching bandwidth.
    3. A global fibre shortage: Fibre, its components and its raw material are in short supply worldwide, including from Indian manufacturers, a constraint industry executives describe as unprecedented in over a decade.

    What will Google’s Visakhapatnam facility do?

    1. Focused on inference: The facility will focus on inference work rather than power intensive training runs, serving domestic enterprises and government agencies given the deep adoption of artificial intelligence across government service delivery.
    2. Power and water choices: Google is seeking to source as much renewable power for the project as possible and is using air cooling technology to minimise water use.

    Challenges to the subsea cable buildout

    1. A global fibre shortage: A worldwide shortage of fibre and its raw material, unprecedented in over a decade, could delay the inland network these projects still need. Eg. Industry executives report that fibre is out of stock across the globe, including from Indian manufacturers. Fix. Expand domestic fibre manufacturing capacity through targeted incentives so the inland rollout is not held back by global supply constraints.
    2. Physical vulnerability of undersea cables: Undersea cables remain exposed to accidental damage from fishing and anchoring activity and to disruption in contested waters. Eg. India’s existing east coast cables are already ageing and running close to capacity, leaving few redundant routes today. Fix. Build multiple, geographically separated landing points and routes, as the new Visakhapatnam gateway is itself intended to do, so a single cable fault cannot isolate India’s connectivity.
    3. Concentration of ownership with foreign firms: The new cable systems and the data centres they serve are being built and operated by foreign technology majors, so India’s expanding gateway capacity depends on the investment decisions of a small number of firms. Eg. Both the India Southeast Asia system and the America India Connect system are anchored by Microsoft and Google respectively rather than Indian carriers. Fix. Encourage Indian telecom operators to invest jointly in landing station capacity so gateway control is not concentrated entirely with foreign firms.

    Conclusion

    Andhra Pradesh’s coastline is emerging as India’s third major digital gateway, as Microsoft and Google build new subsea cable systems into Visakhapatnam alongside the data centres driving the region’s artificial intelligence buildout. Delivering on that promise depends on inland fibre rollout keeping pace despite a global supply crunch, and on India diversifying its cable landing points and ownership so its expanding digital infrastructure does not remain concentrated in a handful of ageing routes and foreign owned systems.

    [2023] “What is the status of digitalization in the Indian economy? Examine the problems faced in this regard and suggest improvements.”

  • Carney’s defiance is well thought out

    Carney’s defiance is well thought out

    Why in the News

    Canada’s Prime Minister has walked away from trade negotiations with the United States after Washington put forward terms that would have cost Canada its sovereignty, key industries, French language protections and its freedom to negotiate with other countries. He has also announced retaliatory tariffs matching the new United States tariffs dollar for dollar, stating that the Americans “asked too much and offered too little.” The move tests whether a middle power, an economy that sends roughly three quarters of its exports into a market ten times its size, can resist pressure from a dominant trading partner without folding, and it carries lessons for other countries, including India, that are negotiating their own terms with Washington.

    What calculations underlie the decision to walk away?

    1. Broad domestic backing: The stance draws support even from the opposition Conservative party, amid public frustration with the United States President’s repeated talk of making Canada the fifty first state.
    2. A contained tariff footprint: The new tariffs apply to only about 5 percent of Canada’s overall exports to the United States, worth roughly 20 billion dollars, limiting the immediate domestic cost of retaliation.
    3. A calculated bet on mutual damage: A breakdown in trade relations is expected to hurt the United States as well, so Canada does not need to win the confrontation outright, only to make the arithmetic politically painful in Washington.

    How exposed is the United States to a breakdown with Canada?

    1. A leading export destination: Canada is the largest export market for 26 American states and among the top three trading partners for 45 of the 50 states.
    2. Energy dependence: Canada supplies roughly 60 percent of America’s crude oil imports, and Canadian electricity helps power grids in New England and the upper Midwest.
    3. Critical inputs: Canadian potash is vital to American agriculture, while Canadian critical minerals feed strategically important American supply chains.

    Why is the timing unfavourable for Washington?

    1. Domestic economic strain: A stalemate with Iran has pushed United States gasoline prices above 4 dollars a gallon, while the 30 year Treasury yield has climbed above 5.3 percent, its highest level since 2007.
    2. Fiscal and political weakness: Federal debt has crossed 40 trillion dollars, and the United States President’s net approval rating has fallen to minus 26 percent, narrowing his room to absorb a prolonged trade standoff.

    What broader pattern does this defiance respond to?

    1. A repeated negotiating playbook: Governments from Mexico City to Brussels to Tokyo have spent the past year confronting an American administration that treats a signed trade agreement as an opening bid that can be revisited whenever it suits it, coercing partners with escalating tariff threats and demanding unilateral concessions.
    2. Prior diversification, not improvisation: The Canadian Prime Minister had earlier warned that middle powers must stand up or risk ending up “on the menu,” and spent close to a year building trade ties with China, the Gulf and Asia, including India, so that a closed door in Washington did not mean a locked room globally.

    Challenges to Canada’s defiance strategy

    1. Economic exposure to a sustained standoff: Canada still sends roughly three quarters of its exports to an economy ten times its own size, so a prolonged confrontation could cost jobs and growth even if it wins the political argument. Eg. Estimates cited alongside the retaliatory tariffs put up to 90,000 Canadian jobs at risk from a sustained trade confrontation. Fix. Continue diversifying export markets by deepening the trade ties already being built with China, the Gulf and Asia.
    2. A narrow tariff footprint limits leverage: The new tariffs cover only about 5 percent of Canada’s exports to the United States, so retaliation alone may be too small to force a reversal in Washington. Eg. Even a full breakdown leaves most of Canada’s three quarter dependence on the United States market untouched. Fix. Extend retaliation toward strategically sensitive sectors such as crude oil, electricity and critical minerals, where Canada supplies a large share of United States demand.
    3. Domestic political risk if pain outlasts patience: Sustained economic pain could erode the broad backing that currently underwrites the stance, including support from the opposition. Eg. Higher fuel and consumer prices from a prolonged standoff could shift Canadian public opinion before comparable pressure is felt in Washington. Fix. Time targeted relief for the sectors affected by the new tariffs so public patience holds through the standoff.

    Conclusion

    The decision to reject an unfavourable trade deal, backed by calculated retaliation and prior diversification of trade ties, is being read as proof that a middle power can resist pressure from a much larger economy without folding. Whether the strategy succeeds depends on whether Canada’s own economic pain stays contained and whether Washington’s vulnerabilities, from energy prices to approval ratings, bite hard enough to force a reversal. For India, still negotiating its own trade deal with Washington, the lesson is not to reject a deal outright but to know precisely which concessions it can never afford to make.

    [2025] What are the challenges before the Indian economy when the world is moving away from free trade and multilateralism to protectionism and bilateralism? How can these challenges be met?”

  • Economy is resilient, but risks remain

    Economy is resilient, but risks remain

    Why in the News

    The State of the Economy report, compiled by economists at the Reserve Bank of India (RBI), together with the finance ministry’s monthly economic review, has found that India’s underlying growth momentum held up through the first quarter of the financial year. Both readings point to firm household consumption, industrial output and credit growth even as global conditions stay unsettled. The outlook nonetheless remains clouded by continuing geopolitical and trade related uncertainty, volatile energy prices and a strengthening El Niño (a periodic warming of central and eastern Pacific Ocean waters that disrupts monsoon rainfall patterns), risks that could weigh on growth just as the National Statistics Office (NSO) prepares to release its first quarter Gross Domestic Product (GDP) estimate.

    What signals point to resilient domestic growth?

    1. Steady consumption indicators: E way bill generation has stayed firm, Goods and Services Tax (GST) revenues have remained healthy, and passenger vehicle, tractor and two wheeler sales have all been strong.
    2. Firm industrial output: The Index of Industrial Production (IIP), a measure of output across mining, manufacturing and electricity, rose 5.8 percent in the quarter, aided by the manufacturing sector, while electricity demand held steady.
    3. Corporate profitability and credit growth: Firms in both manufacturing and services reported improved operating profits, and bank credit has grown at a brisk pace across both industrial and retail lending.
    4. Monsoon recovery and exports: A recovery in the monsoon has supported kharif sowing, and exports excluding oil grew 12.8 percent in the first four months of the year, aided by the currency’s depreciation.
    5. Public capital spending: The Centre’s own expenditure grew by roughly 24 percent in the quarter, keeping public capital spending on track.

    What risks could weigh on this resilience?

    1. External uncertainty: Continuing geopolitical and trade related tensions, along with supply chain pressures, threaten to unsettle the momentum built up domestically.
    2. Volatile energy prices: Fluctuating global energy prices raise input costs across manufacturing and transport and feed inflation risk.
    3. A strengthening El Niño: A stronger El Niño could unsettle the rainfall gains that supported this quarter’s kharif sowing and rural demand.
    4. A cautious institutional tone: The finance ministry’s economic review itself notes that “recent years have been a time for hunkering down and battening down the hatches,” and expects coming years to be no exception.

    What does the growth trajectory imply for the GDP estimate?

    1. RBI’s own projection: At its August Monetary Policy Committee (MPC) meeting, the central bank projected 7 percent growth for the first quarter, a figure broadly matched by assessments from agencies such as Crisil and ICRA.
    2. The GDP release ahead: The National Statistics Office is set to release its first quarter GDP estimate shortly, with growth seen as likely to surprise on the upside even as the external environment continues to weigh on the outlook.

    Conclusion

    Domestic demand, industrial output and credit growth show the economy’s underlying momentum has held up, but persistent external risks, from trade tensions to volatile energy prices and a strengthening El Niño, mean policymakers cannot afford complacency. The National Statistics Office’s forthcoming GDP estimate will offer the first concrete test of whether this resilience is translating into headline growth, even as the external environment continues to demand a calibrated policy response.

    Back2Basics: What is the State of the Economy report?

    1. Publisher: It is a monthly assessment published in the Reserve Bank of India’s Bulletin, written by economists in the RBI’s Monetary Policy Department.
    2. Status: It carries a standard disclaimer that the views expressed are those of the authors and not necessarily those of the RBI.
    3. Purpose: It reviews high frequency indicators of growth, inflation and the external sector to assess the economy’s current momentum.

    [2021] “Explain the difference between computing methodology of India’s Gross Domestic Product(GDP) before the year 2015 and after the year 2015.”