💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Economics

  • Small Hydro Power (SHP) Development Scheme

    Why in the news?

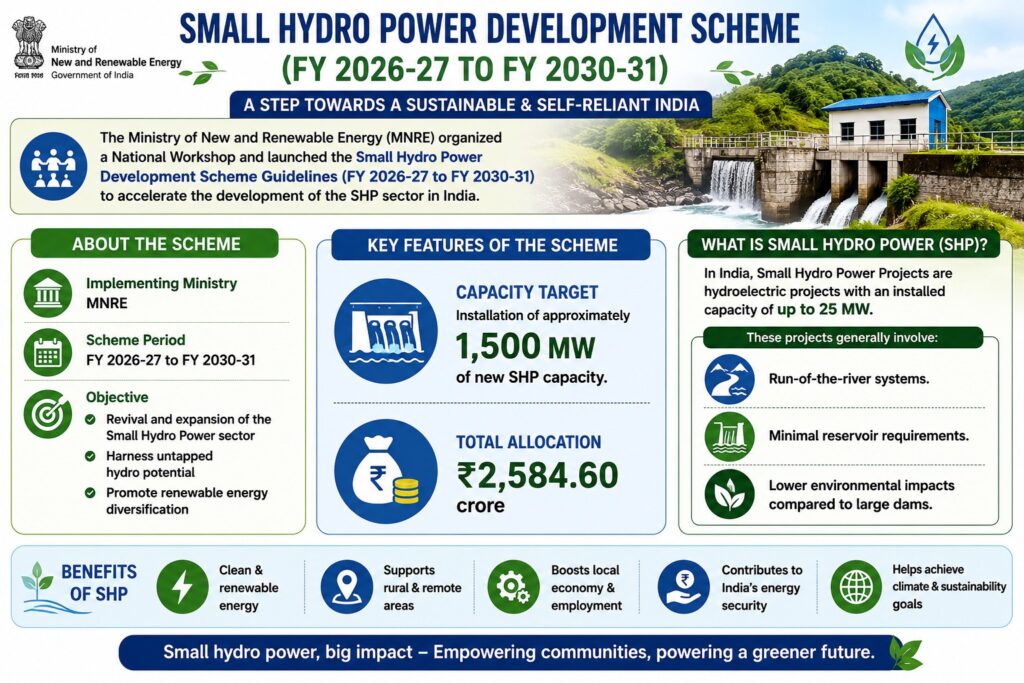
    The Ministry of New and Renewable Energy (MNRE) organised a National Workshop and launched the Small Hydro Power Development Scheme Guidelines (FY 2026-27 to FY 2030-31) to accelerate the development of the SHP sector in India.

    About the Small Hydro Power Development Scheme

    • Implementing Ministry: MNRE
    • Scheme Period: FY 2026-27 to FY 2030-31
    • Objective:
      • Revival and expansion of the Small Hydro Power sector.
      • Harness untapped hydro potential.
      • Promote renewable energy diversification.
    • Capacity Target: Installation of approximately 1,500 MW of new SHP capacity.
    • Total allocation: ₹2,584.60 crore
    • In India, Small Hydro Power Projects are hydroelectric projects with an installed capacity of up to 25 MW
    • These projects generally involve:
      • Run-of-the-river systems.
      • Minimal reservoir requirements.
      • Lower environmental impacts compared to large dams.

    [2024] Recently, the term “pumped-storage hydropower” is actually and appropriately discussed in the context of which one of the following?

    [A] Irrigation of terraced crop fields

    [B] Lift irrigation of cereal crops

    [C] Long duration energy storage

    [D] Rainwater harvesting system

  • Infrastructure at the Core of India’s Development (PIB)

    Why in the news?

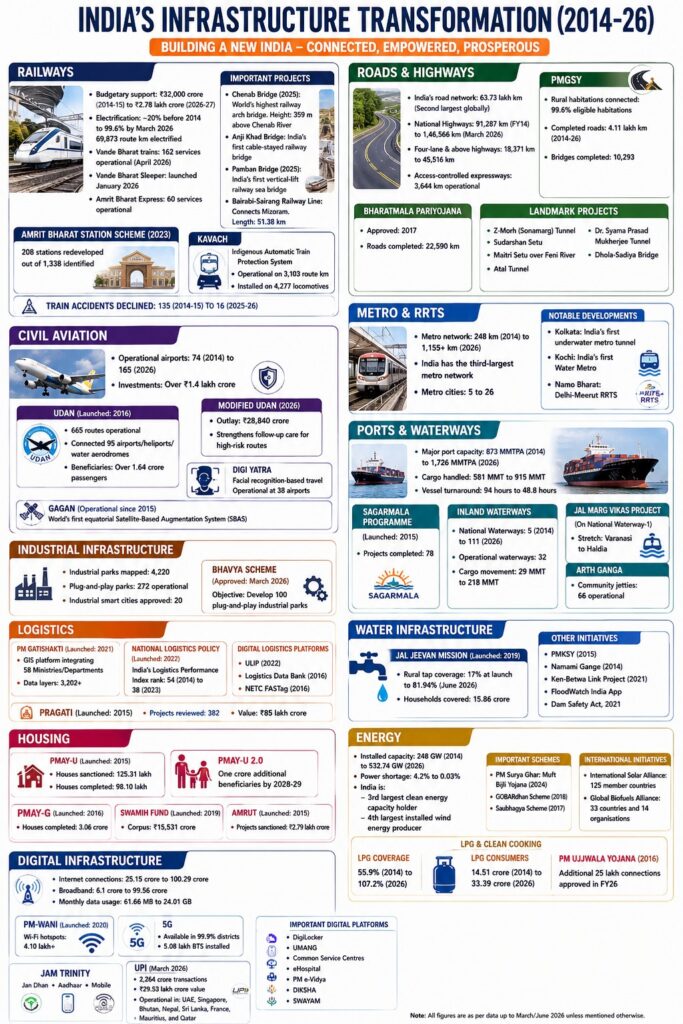
    The Government highlighted major infrastructure achievements over the past 12 years across transport, logistics, water, housing, energy, and digital sectors, emphasizing their role in achieving Viksit Bharat 2047.

    1. Railways

    • Railway budgetary support increased from ₹32,000 crore (2014-15) to ₹2.78 lakh crore (2026-27).
    • Railway electrification:
      • About 20% before 2014
      • 99.6% by March 2026
      • 69,873 route km electrified.
    • Vande Bharat trains: 162 services operational (April 2026).
    • Vande Bharat Sleeper: launched in January 2026.
    • Amrit Bharat Express: 60 services operational.
    • Mumbai-Ahmedabad High-Speed Rail Corridor
      • Length: 508 km
      • Design speed: 320 kmph.
    • Amrit Bharat Station Scheme (2023): 208 stations redeveloped out of 1,338 identified.
    • Kavach:
      • Indigenous Automatic Train Protection System.
      • Operational on 3,103 route km.
      • Installed on 4,277 locomotives.
    • Train accidents declined from 135 (2014-15) to 16 (2025-26).

    Important Railway Projects

    • Chenab Bridge (2025): World’s highest railway arch bridge. Height: 359 m above Chenab River.
    • Anji Khad Bridge: India’s first cable-stayed railway bridge.
    • Pamban Bridge (2025): India’s first vertical-lift railway sea bridge.
    • Bairabi-Sairang Railway Line: Connects Mizoram. Length: 51.38 km.

    Roads and Highways

    • India’s road network: 63.73 lakh km and Second largest globally.
    • National Highways:
      • 91,287 km (FY14)
      • 1,46,566 km (March 2026).
    • Four-lane and above highways: 18,371 km to 45,516 km.
    • Access-controlled expressways: 3,644 km operational.

    PMGSY

    • Rural habitations connected: 99.6% eligible habitations.
    • Completed roads: 4.11 lakh km (2014-26).
    • Bridges completed: 10,293.

    Bharatmala Pariyojana

    • Approved: 2017.
    • Roads completed: 22,590 km.

    Landmark Projects

    • Z-Morh (Sonamarg) Tunnel, Sudarshan Setu, Maitri Setu over Feni River, Atal Tunnel, Dr. Syama Prasad Mukherjee Tunnel, Dhola-Sadiya Bridge.

    2. Civil Aviation

    • Operational airports: 74 (2014) and 165 (2026).
    • Investments: Over ₹1.4 lakh crore.

    UDAN

    • Launched: 2016.
    • Routes operational: 665 routes.
    • Connected: 95 airports/heliports/water aerodromes.
    • Beneficiaries: Over 1.64 crore passengers.
    • Modified UDAN (2026): Outlay: ₹28,840 crore.

    Digi Yatra

    • Facial recognition-based travel.
    • Operational at 38 airports.

    GAGAN

    • Operational since 2015.
    • World’s first equatorial Satellite-Based Augmentation System (SBAS).

    3. Metro and RRTS

    • Metro network: 248 km (2014) to 1,155+ km (2026).
    • India has the third-largest metro network.
    • Metro cities: 5 to 26.

    Notable Developments

    • Kolkata: India’s first underwater metro tunnel.
    • Kochi: India’s first Water Metro.
    • Namo Bharat: Delhi-Meerut RRTS.

    4. Ports and Waterways

    • Major port capacity: 873 MMTPA (2014) to 1,726 MMTPA (2026).
    • Cargo handled: 581 MMT to 915 MMT.
    • Vessel turnaround: 94 hours to 48.8 hours.

    Sagarmala Programme

    • Launched: 2015.
    • Projects completed: 78.

    Inland Waterways

    • National Waterways: 5 (2014) to 111 (2026).
    • Operational waterways: 32.
    • Cargo movement: 29 MMT to 218 MMT.

    Jal Marg Vikas Project

    • On National Waterway-1.
    • Stretch: Varanasi to Haldia.

    Arth Ganga

    • Community jetties: 66 operational.

    5. Industrial Infrastructure

    • Industrial parks mapped: 4,220.
    • Plug-and-play parks: 272 operational.
    • Industrial smart cities approved: 20.

    BHAVYA Scheme

    • Approved: March 2026.
    • Objective: Develop 100 plug-and-play industrial parks.

    6. Logistics

    PM GatiShakti

    • Launched: 2021.
    • GIS platform integrating: 58 Ministries/Departments.
    • Data layers: 3,202+.

    National Logistics Policy

    • Launched: 2022.
    • India’s Logistics Performance Index rank: 54 (2014) to 38 (2023).

    Digital Logistics Platforms

    • ULIP (2022).
    • Logistics Data Bank (2016).
    • NETC FASTag (2016).

    PRAGATI

    • Launched: 2015.
    • Projects reviewed: 382.
    • Value: ₹85 lakh crore.

    7. Water Infrastructure

    Jal Jeevan Mission

    • Launched: 2019.
    • Rural tap coverage: 17% at launch to 81.94% (June 2026).
    • Households covered: 15.86 crore.

    Other Initiatives

    • PMKSY (2015), Namami Gange (2014), Ken-Betwa Link Project (2021, FloodWatch India App, and Dam Safety Act, 2021.

    8. Housing

    PMAY-U

    • Launched: 2015.
    • Houses sanctioned: 125.31 lakh.
    • Houses completed: 98.10 lakh.
    • PMAY-U 2.0: One crore additional beneficiaries by 2028-29.

    PMAY-G

    • Launched: 2016.
    • Houses completed: 3.06 crore.

    SWAMIH Fund

    • Launched: 2019.
    • Corpus: ₹15,531 crore.

    AMRUT

    • Launched: 2015.
    • Projects sanctioned: ₹2.79 lakh crore.

    9. Energy

    • Installed capacity: 248 GW (2014) to 532.74 GW (2026).
    • Power shortage: 4.2% to 0.03%.

    Renewable Energy

    India is: 3rd largest clean energy capacity holder and 4th largest installed wind energy producer.

    Important Schemes

    • PM Surya Ghar: Muft Bijli Yojana (2024).
    • GOBARdhan Scheme (2018).
    • Saubhagya Scheme (2017).

    International Initiatives

    • International Solar Alliance: 125 member countries.
    • Global Biofuels Alliance: 33 countries and 14 organisations.

    10. LPG and Clean Cooking

    • LPG coverage: 55.9% (2014) to 107.2% (2026).
    • LPG consumers: 14.51 crore to 33.39 crore.

    PM Ujjwala Yojana

    • Launched: 2016.
    • Additional 25 lakh connections approved in FY26.

    11. Digital Infrastructure

    • Internet connections: 25.15 crore to 100.29 crore.
    • Broadband:6.1 crore to 99.56 crore.
    • Monthly data usage: 61.66 MB to 24.01 GB.

    PM-WANI

    • Launched: 2020.
    • Wi-Fi hotspots: 4.10 lakh+.

    5G

    • Available in 99.9% districts.
    • 5.08 lakh BTS installed.

    JAM Trinity

    • Jan Dhan, Aadhaar and Mobile.

    UPI

    • March 2026: 2,264 crore transactions and ₹29.53 lakh crore value.
    • Operational in UAE, Singapore, Bhutan, Nepal, Sri Lanka, France, Mauritius, and Qatar.

    Important Digital Platforms

    • DigiLocker, UMANG, Common Service Centres, eHospital, PM e-Vidya, DIKSHA, SWAYAM.

    [2025] Consider the following statements:
    I. Indian Railways have prepared a National Rail Plan (NRP) to create a future ready railway system by 2028.
    II. Kavach’ is an Automatic Train Protection system, development in collaboration with Germany.
    III. ‘Kavach’ system consists of RFID tags fitted on track in station section.
    Which of the statements given above are not correct?

    [A] I and II only

    [B] II and III only

    [C] I and III only

    [D] I, II and III

  • The boost centre’s solar power schemes need

    Why in the News?

    India’s flagship decentralised solar schemes, PM Surya Ghar Yojana and PM-KUSUM, have achieved only about 13 GW capacity against a target of 40 GW. This has prompted the Parliamentary Estimates Committee to examine implementation bottlenecks.

    Background

    1. Solar Dominance: Solar power now accounts for nearly 30% of India’s installed electricity generation capacity.
    2. Rapid Capacity Addition: India added more than 50 GW of solar capacity during the last two years.
    3. Global Position: India added more solar power in 2025 than any country except China.

    Why is Decentralised Solar Power Becoming Central to India’s Energy Transition?

    Decentralised solar power (DRE) generates electricity at or near the point of consumption rather than relying on large, centralized power plants. This approach eliminates long-distance transmission losses and empowers local communities by providing affordable, continuous, and reliable energy

    1. Rising Electricity Demand: Increasing temperatures, urbanisation and economic growth are pushing electricity demand upwards.
    2. Land Constraints: Availability of land for large utility-scale solar parks is becoming increasingly limited.
    3. Climate Resilience: Distributed generation strengthens energy security during periods of high demand and climatic stress.
    4. Peak Demand Management: Solar power significantly contributed to meeting daytime peak demand during April-May 2026.
    5. Hydropower Constraints: Hydropower capacity expansion has stagnated, reducing its ability to meet incremental demand.
      1. Stagnating Share: Hydropower’s share in India’s installed power capacity has declined from around 25% in the early 1990s to about 10% today, despite growth in overall electricity demand.
      2. Limited Capacity Addition: India added only about 5 GW of large hydropower capacity between 2014 and 2024, compared to over 100 GW of solar capacity during the same period.
      3. Current Capacity: India’s installed hydropower capacity stands at roughly 48-49 GW, while solar capacity has crossed 100 GW.
      4. Climate Vulnerability: Erratic monsoons, changing river flows, environmental clearances, rehabilitation issues, and long gestation periods have slowed hydropower expansion.
      5. Energy Transition Implication: With hydropower unable to expand rapidly enough to meet rising demand, solar, particularly decentralised solar, is increasingly expected to meet incremental electricity requirements.

    What are the Key Features of PM Surya Ghar Yojana and PM-KUSUM?

    PM Surya Ghar Yojana

    1. Household Coverage: Targets rooftop solar installation in 1 crore households.
    2. Free Electricity: Provides electricity benefits of up to 300 units per month.
    3. Capital Subsidy: Offers direct subsidy support for rooftop solar equipment.
    4. Decentralised Generation: Encourages household-level electricity production and grid integration.

    Progress

    TargetAchievement
    1 crore households connected40.52 lakh households
    30 GW installed capacity12 GW

    PM-KUSUM

    The Pradhan Mantri Kisan Urja Suraksha evam Utthan Mahabhiyan (PM-KUSUM) is an initiative by the Ministry of New and Renewable Energy (MNRE). It provides farmers with heavy subsidies for solar agricultural pumps and solar power plants, designed to generate income, provide daytime irrigation, and replace expensive diesel or grid power

    1. Farmer-Centric Design: Supports farmers in establishing decentralised solar infrastructure.
    2. Solar Plants on Unused Land: Enables installation of small solar plants on unused agricultural land.
    3. Solar Water Pumps: Supports both standalone and grid-connected solar irrigation pumps.
    4. Additional Income: Allows sale of surplus electricity to the grid.
    5. Cost Reduction: Reduces diesel and conventional electricity expenses.

    Progress

    TargetAchievement
    14 lakh solar water pumps10.9 lakh
    2.5 lakh solar irrigation pumps15,000
    30 GW decentralised solar capacity1.2 GW

    How Successful Have These Flagship Programmes Been?

    1. Combined Budget: Approximately ₹95,000 crore.
    2. Combined Capacity Created: About 13 GW as of 31 May 2026.
    3. Target Capacity: 40 GW by the end of the current financial year.
    4. Achievement Gap: Only around one-third of the targeted capacity achieved.
    5. PM-KUSUM Delay: Initially targeted for completion by 2022 but extended until the end of the current financial year due to pandemic-related disruptions.
    6. Best Performing Component: Standalone off-grid solar water pumps under PM-KUSUM.

    How is Performance Highly Uneven Across States?

    PM Surya Ghar Better Performers

    StateInstallationsHouseholds ConnectedSubsidy (₹ crore)
    Gujarat6,81,1809,77,7549,277
    Maharashtra6,04,5229,42,37823,149
    Uttar Pradesh5,62,6565,77,10319,095
    Kerala2,52,8032,58,959382
    Rajasthan2,15,8422,23,06630,597

    PM Surya Ghar Underperformers

    StateInstallationsHouseholds ConnectedSubsidy (₹ crore)
    West Bengal1,6951,7581,868
    Punjab14,47016,64120,693
    Karnataka19,79330,39527,725
    Bihar20,27220,90515,405
    Tamil Nadu72,98885,74315,701

    How Do Power Subsidies Affect Solar Adoption?

    1. Distorted Economic Incentives: Free or highly subsidised electricity reduces the financial attractiveness of investing in rooftop solar systems.
    2. Reduced Payback Benefits: Consumers receiving subsidised electricity perceive limited savings from solar installations, resulting in lower adoption rates.
    3. High Upfront Cost Sensitivity: Households are less willing to incur substantial initial costs for solar systems when electricity is already available at little or no cost.
    4. Subsidy-Driven Consumer Behaviour: Existing subsidy regimes encourage continued dependence on grid electricity rather than self-generation through rooftop solar.
    5. Policy Contradiction: Simultaneous promotion of rooftop solar and provision of free electricity creates conflicting incentives for consumers.
    6. Official Recognition: The Ministry of New and Renewable Energy informed the Parliamentary Estimates Committee that free electricity schemes have emerged as a major constraint to PM Surya Ghar implementation.

    Evidence from States

    1. Punjab: Provides 300 free units to households and free electricity for agricultural tubewells; annual power subsidy expenditure exceeds ₹20,000 crore.
    2. Karnataka: Electricity subsidy bill stands at approximately ₹27,000 crore.
    3. Tamil Nadu: Electricity subsidy expenditure is around ₹15,700 crore.

    Why Does the Upfront Cost Remain the Biggest Barrier?

    1. High Initial Investment: Solar installations often require investment of several lakh rupees.
    2. Delayed Returns: Benefits accrue gradually through reduced electricity bills and sale of surplus power.
    3. Affordability Challenge: Many households and farmers struggle to mobilise upfront capital despite long-term savings.
    4. Credit Constraints: Access to affordable financing remains limited.
    5. Committee Recommendation: Parliamentary Estimates Committee recommended mechanisms that reduce upfront payment burdens.

    Why Have Some States Succeeded Despite Offering Subsidised Power?

    1. Additional Incentives: Gujarat, Rajasthan and Uttar Pradesh supplemented central support with state-level incentives.
    2. Policy Convergence: State support reduced effective installation costs.
    3. Consumer Confidence: Additional incentives improved economic viability.
    4. Administrative Efficiency: Faster approvals and implementation improved adoption rates.
    5. Evidence of Success: These states account for nearly 70% of the total rooftop solar installations achieved under PM Surya Ghar.

    What are the Long-Term Economic Benefits of Decentralised Solar Power?

    1. Subsidy Rationalisation: Reduces long-term dependence on recurring electricity subsidies.
    2. Fiscal Savings: Full implementation of PM Surya Ghar could save approximately ₹75,000 crore annually in electricity-related expenditure.
    3. Consumer Empowerment: Converts consumers into electricity producers.
    4. Grid Stability: Reduces transmission losses and distribution burden.
    5. Energy Security: Diversifies generation sources and reduces fuel dependence.
    6. Climate Commitments: Supports India’s renewable energy and net-zero objectives.

    What is the Growing Link Between Solar Power and Electricity Demand?

    1. Demand Surge: Rising temperatures are increasing electricity consumption.
    2. Climate Variability: Lower rainfall forecasts may reduce hydropower availability.
    3. Summer Demand Peaks: Solar generation is increasingly meeting daytime peak loads.
    4. Future Energy Mix: Solar is expected to become India’s second-largest source of electricity generation, overtaking hydropower.
    5. Decentralisation Advantage: Distributed generation can cushion local supply-demand imbalances.

    Conclusion

    India’s clean energy transition increasingly depends on decentralised solar generation alongside utility-scale renewable projects. While PM Surya Ghar and PM-KUSUM have demonstrated their transformative potential, persistent barriers such as high upfront costs and distortionary electricity subsidies continue to constrain adoption. Bridging this gap through targeted incentives, affordable financing and subsidy reforms will determine whether decentralised solar power can become a major pillar of India’s energy security and climate strategy.

    PYQ Relevance

    [UPSC 2020] Describe the benefits of deriving electric energy from sunlight in contrast to the conventional energy generation. What are the initiatives offered by our Government for this purpose?

    Linkage: The PYQ focuses on solar energy as a sustainable alternative to conventional power sources and government efforts to promote its adoption. PM Surya Ghar and PM-KUSUM are among India’s flagship initiatives for promoting decentralised solar energy. The article evaluates their achievements, implementation challenges, and significance for India’s energy security and clean energy transition.

  • Zojila Tunnel

    Why in the news?

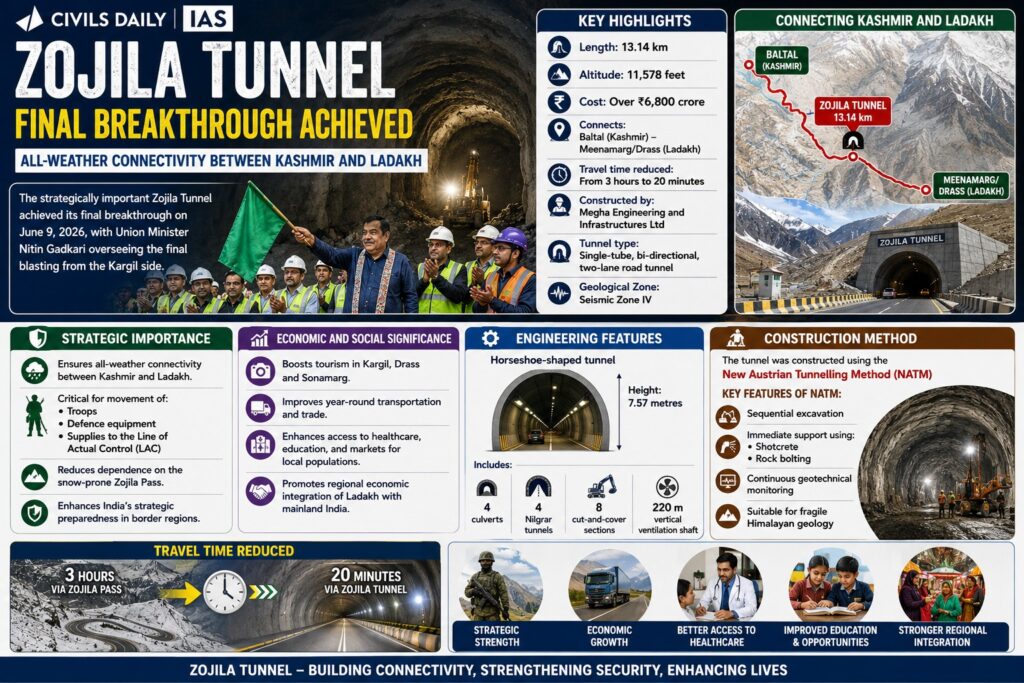
    The strategically important Zojila Tunnel achieved its final breakthrough on June 9, 2026, with Union Minister Nitin Gadkari overseeing the final blasting from the Kargil side. The tunnel will provide all-weather connectivity between Kashmir and Ladakh.

    Key Highlights

    • Length: 13.14 km
    • Altitude: 11,578 feet
    • Cost: Over ₹6,800 crore
    • Connects: Baltal (Kashmir) and Meenamarg/Drass (Ladakh)
    • Travel time reduced: From 3 hours to 20 minutes
    • Constructed by: Megha Engineering and Infrastructures Ltd
    • Tunnel type: Single-tube, bi-directional, two-lane road tunnel
    • Geological Zone: Seismic Zone IV

    Strategic Importance

    • Ensures all-weather connectivity between Kashmir and Ladakh.
    • Critical for the movement of Troops, Defence equipment, and Supplies to the Line of Actual Control (LAC)
    • Reduces dependence on the snow-prone Zojila Pass.
    • Enhances India’s strategic preparedness in border regions.

    Construction Method

    • The tunnel was constructed using the: New Austrian Tunnelling Method (NATM)

    Key features of NATM:

    • Sequential excavation
    • Immediate support using: Shotcrete and Rock bolting
    • Continuous geotechnical monitoring
    • Suitable for fragile Himalayan geology

    Q. With reference to India’s projects on connectivity, consider the following statements::
    1. East-West Corridor under Golden Quadrilateral Project connects Dibrugarh and Surat.
    2. Trilateral Highway connects Moreh in Manipur and Chiang Mai in Thailand via Myanmar.
    3. Bangladesh- China- India- Myanmar Economic Corridor connects Varanasi in Uttar Pradesh with Kunming in China.
    How many of the above statements are correct?

    [A] Only one

    [B] Only two

    [C] All three

    [D] None

  • [8th June 2026] The Hindu OpED: From borderland to India’s strategic resource frontier

    Mentor’s Comment

    India’s search for critical minerals has brought the Northeast into the national strategic spotlight. Government narratives increasingly portray states such as Arunachal Pradesh, Manipur, Meghalaya, and Mizoram as resource-rich frontiers capable of supporting India’s clean energy transition and industrial ambitions. This highlights a significant shift in how India views the Northeast. Traditionally it was framed through the lens of borders, security, insurgency, and connectivity.

    Why is the Northeast Emerging as India’s Strategic Resource Frontier?

    1. Critical Mineral Demand: Expanding demand for lithium, cobalt, graphite, nickel, and rare earth elements is reshaping global industrial and geopolitical competition.
    2. Energy Transition: Batteries, electric vehicles, renewable energy technologies, and energy storage systems depend heavily on critical minerals.
    3. Technological Manufacturing: Semiconductors and advanced manufacturing require secure access to strategic minerals.
    4. Defence Applications: Defence technologies increasingly rely on mineral-intensive supply chains.
    5. Strategic Autonomy: Reduces dependence on external suppliers and strengthens supply-chain resilience.
    6. Resource Potential: Geological surveys indicate significant mineral potential across several Northeastern states.

    How Has Government Discourse on the Northeast Changed?

    1. Borderland Narrative: The Northeast was historically discussed through issues of insurgency, territorial security, border management, and connectivity.
    2. Security-Centric Approach: Infrastructure projects were often justified as instruments of strategic access and territorial integration.
    3. Resource Frontier Narrative: The region is increasingly portrayed as a source of strategic minerals critical for national development.
    4. Expanded Strategic Significance: Discussions now combine security, resource access, industrial policy, and geopolitical competitiveness.
    5. National Economic Integration: Resource development is becoming central to how the region is represented in national policymaking.

    What Is the Scale of Critical Mineral Exploration in the Northeast?

    1. Exploration Expansion: Geological Survey of India undertook 43 critical mineral exploration projects in northeastern states during the 2022-23, 2023-24 and 2024-25 field seasons.
    2. Minerals Covered: Exploration focused on graphite, vanadium, lithium, rare earth elements, nickel and cobalt.
    3. Geographical Spread: Activities expanded across Arunachal Pradesh, Meghalaya, Assam, Nagaland and Manipur.
    4. Manipur Projects: Recent exploration initiatives involve nickel, cobalt and chromium deposits.
    5. Long-Term Potential: Geological surveys have consistently pointed toward significant mineral prospects in the region.

    Why Does the ‘Resource Frontier’ Narrative Oversimplify the Northeast’s Reality?

    1. Frontier Concept: The term suggests empty spaces waiting for discovery, development, and extraction.
    2. Historical Assumption: Frontiers are often portrayed as regions awaiting integration into the national economy.
    3. Social Reality: The Northeast already contains complex social, political, cultural, and economic systems.
    4. Existing Institutions: Local governance structures, customary institutions, and traditional land-management systems are already deeply embedded.
    5. Identity and Memory: Land carries historical, cultural, and political significance beyond its economic value.
    6. Political Meaning: Resource extraction enters territories that already possess established histories and institutions.

    Why Are Land and Ownership Questions Central to Resource Development?

    1. Customary Land Systems: Many communities maintain long-standing customary ownership arrangements.
    2. Authority Structures: Land is closely linked to local political authority and governance.
    3. Identity Linkages: Ownership often forms part of community identity and historical memory.
    4. Representation Concerns: Resource decisions raise questions regarding who participates in decision-making.
    5. Trust Deficit: Development projects are frequently assessed through local perceptions of trust and inclusion.
    6. Beyond Economics: Land debates encompass social legitimacy, rights, and political recognition.

    How Do Existing Regional Conflicts Influence Resource Politics?

    1. Manipur Experience: Years of violence and displacement have intensified debates over land and territorial arrangements.
    2. Ecological Vulnerability: Communities increasingly raise concerns regarding environmental impacts of extraction.
    3. Ownership Disputes: Resource projects often intersect with unresolved questions of land rights.
    4. Political Inclusion: Communities evaluate projects through the lens of representation and participation.
    5. Conflict Sensitivity: Resource development in fragile regions may acquire meanings beyond economic development.

    Can Resource Development Create New Governance Challenges?

    1. Institutional Capacity: Extraction may proceed faster than institutions capable of managing its consequences.
    2. Uneven Development: The Northeast has historically experienced uneven infrastructure and economic growth.
    3. Connectivity Mismatch: Infrastructure projects have sometimes emerged without corresponding economic ecosystems.
    4. Participation Deficit: Strategic priorities have often overshadowed local participation and consultation.
    5. Social Risks: Rapid extraction may reproduce tensions if benefits are unevenly distributed.
    6. Governance Imperative: Resource development requires strong institutions, transparency, and social safeguards.

    Why Is Inclusion as Important as Extraction?

    1. Benefit Sharing: Local communities seek meaningful economic participation.
    2. Employment Opportunities: Resource projects can address long-standing developmental deficits.
    3. Political Legitimacy: Inclusive governance strengthens acceptance of projects.
    4. Community Ownership: Participation improves trust and reduces conflict.
    5. Sustainable Development: Long-term success depends on balancing strategic objectives with local aspirations.

    Conclusion

    The Northeast’s emergence as a critical mineral hub presents India with a strategic opportunity to strengthen resource security, support the energy transition, and reduce external dependence. However, the region cannot be treated merely as a repository of minerals waiting for extraction. Sustainable success will depend on reconciling national developmental priorities with local aspirations, customary land rights, ecological safeguards, and participatory governance. The real challenge is not only to extract resources from the Northeast, but to ensure that its people become equal stakeholders in the region’s transformation from a borderland to a strategic resource frontier.

  • Centre scraps capital gains, interest tax on FII govt bond investments to pull foreign funds

    Why in the News?

    The Union Government promulgated the Income-tax (Amendment) Ordinance, 2026, which received President Droupadi Murmu’s assent on June 5, 2026. The ordinance completely exempts Foreign Institutional Investors (FIIs) from capital gains tax and withholding tax on interest income earned from Indian government securities, effective from April 1, 2026. The move seeks to attract large foreign debt inflows, address a projected $50-60 billion Balance of Payments (BoP) gap, and support rupee stability amid weak portfolio and FDI inflows.

    How Has The Tax Treatment Of Foreign Investors Changed?

    Previous Tax Regime

    1. Long-Term Capital Gains Tax (LTCG): FIIs paid 12.5% tax on gains from bonds held for more than 12 months.
    2. Short-Term Capital Gains Tax (STCG): FIIs paid 30% tax on short-term gains.
    3. Withholding Tax: Foreign investors paid nearly 20% tax on interest income from government bonds.
    4. Global Comparison: India’s withholding tax was among the highest globally after the concessional 5% rate expired in 2023.
    5. Gross Taxation: Non-resident investors paid withholding tax on gross interest income and could not offset losses against past gains.

    New Tax Regime

    1. Capital Gains Exemption: The government has completely scrapped both Long-Term Capital Gains (LTCG) and Short-Term Capital Gains (STCG) taxes on investments made by FIIs in government bonds.
    2. Interest Income Exemption: The government has also scrapped the withholding tax (Tax Deducted at Source) that FIIs were required to pay on their interest income derived from government debt instruments/bonds.
    3. Coverage: Applies to investments through the General Route and Fully Accessible Route (FAR).
    4. Effective Date: Changes become effective from April 1, 2026 following Presidential assent to the ordinance amending the Income Tax Act, 2025.
    5. Institutional Coverage: Benefits extend to FIIs and the Bank for International Settlements (BIS).

    Why Is India Seeking Greater Foreign Debt Inflows?

    1. Balance of Payments Pressure
      1. BoP Deficit: India may face a $50-60 billion BoP deficit in FY27.
      2. External Financing Need: Sustained capital inflows are necessary to finance the deficit without exerting pressure on foreign exchange reserves.
    2. Rupee Stability
      1. Exchange Rate Stress: The rupee had nearly breached the ₹97 per US dollar level recently.
      2. Recent Recovery: Rupee strengthened from ₹95.79/$ on Thursday to ₹94.94/$ on Friday.
      3. Currency Support: Higher debt inflows increase foreign exchange supply and support currency stability.
    3. Weak Portfolio and FDI Flows
      1. Equity Outflows: FPIs have withdrawn approximately $28 billion from Indian equities in FY26.
      2. FDI Moderation: Net FDI inflows have weakened, increasing reliance on alternative capital sources.

    How Large Could The Potential Foreign Inflows Be?

    1. Expected Debt Inflows
      1. Axis Bank Estimate: Tax exemptions could attract $45-50 billion into government debt markets over the next two years.
      2. BoP Gap Financing: Such inflows could bridge a major portion of the projected external financing requirement.
    2. Untapped Market Potential
      1. Current Holdings: FIIs hold only ₹3.75 lakh crore.
      2. Total Market Size: Government securities outstanding amount to ₹112.42 lakh crore.
      3. Foreign Share: Foreign participation remains limited at 3.34%.
    3. Global Investor Appeal
      1. Tax Neutrality: Aligns India more closely with major sovereign bond markets.
      2. Yield Attraction: Indian government bonds offer relatively attractive yields compared to many developed markets.

    What Additional Measures Have Been Taken To Liberalize Government Bond Investments?

    1. Expansion Of Fully Accessible Route (FAR) Securities
      1. Coverage Expansion: RBI is considering inclusion of all new issuances of 15-year, 30-year and 40-year government bonds under FAR.
      2. Accessibility: Ensures unrestricted foreign investment in a larger segment of sovereign debt.
    2. Removal Of Investment Restrictions
      1. Short-Term Investment Limits: Proposed removal of caps on short-duration investments.
      2. Concentration Limits: Removal of concentration restrictions on FII investments.
      3. Individual Security Limits: Greater flexibility for investors across government securities.
    3. Complementary RBI Measures
      1. Overseas Borrowing: RBI eased norms for state-owned enterprises to borrow abroad.
      2. Foreign Currency Deposits: Banks allowed greater mobilization of foreign currency deposits.
      3. Objective: Strengthens overall foreign capital inflow architecture.

    How Can Greater Debt Inflows Benefit The Indian Economy?

    1. External Sector Stability
      1. BoP Financing: Ensures financing of current account and capital account gaps.
      2. Reserve Protection: Reduces pressure on foreign exchange reserves.
    2. Rupee Appreciation
      1. Forex Supply: Higher inflows increase dollar availability.
      2. Exchange Rate Support: Reduces depreciation pressures on the rupee.
    3. Bond Market Development
      1. Market Depth: Broadens investor base in government securities.
      2. Liquidity: Enhances trading activity and price discovery.
    4. Lower Borrowing Costs
      1. Demand Expansion: Increased demand for government bonds may lower yields over time.
      2. Fiscal Benefit: Reduces government borrowing costs.
    5. Global Financial Integration
      1. Market Confidence: Signals policy commitment to capital market reforms.
      2. International Participation: Improves India’s standing in global bond markets.

    What Risks And Concerns Remain?

    1. Dependence On Portfolio Flows
      1. Volatility Risk: Debt inflows can reverse quickly during global financial stress.
      2. External Vulnerability: Excessive reliance on foreign capital may increase exposure to global shocks.
    2. Revenue Implications
      1. Tax Foregone: Government sacrifices tax revenues to attract foreign investment.
      2. Cost-Benefit Question: Actual inflows must justify revenue losses.
    3. Monetary Management Challenges
      1. Liquidity Effects: Large inflows may complicate liquidity and exchange-rate management.
      2. Sterilization Costs: RBI may need intervention to manage excess forex inflows.
    4. Structural Constraints
      1. Investment Decisions: Tax incentives alone may not overcome concerns relating to regulations, global risk appetite, and geopolitical uncertainties.

    Conclusion

    Amid global economic uncertainty and pressure on India’s external sector, the reform seeks to attract foreign capital, support the rupee, and deepen the sovereign debt market. It aligns with India’s broader aspiration of becoming a $5 trillion economy and a globally integrated financial powerhouse while ensuring macroeconomic stability.

    PYQ Relevance

    [UPSC 2016] Justify the need for FDI for the development of the Indian economy. Why is there a gap between MOUs signed and actual FDIs? Suggest remedial steps for increasing actual FDIs in India

    Linkage: The PYQ examines policy measures undertaken by the government to attract foreign capital and strengthen investment inflows. The reform uses tax incentives to attract foreign capital and deepen India’s debt market.

  • E85 Fuel Rollout in India

    Why in the news?

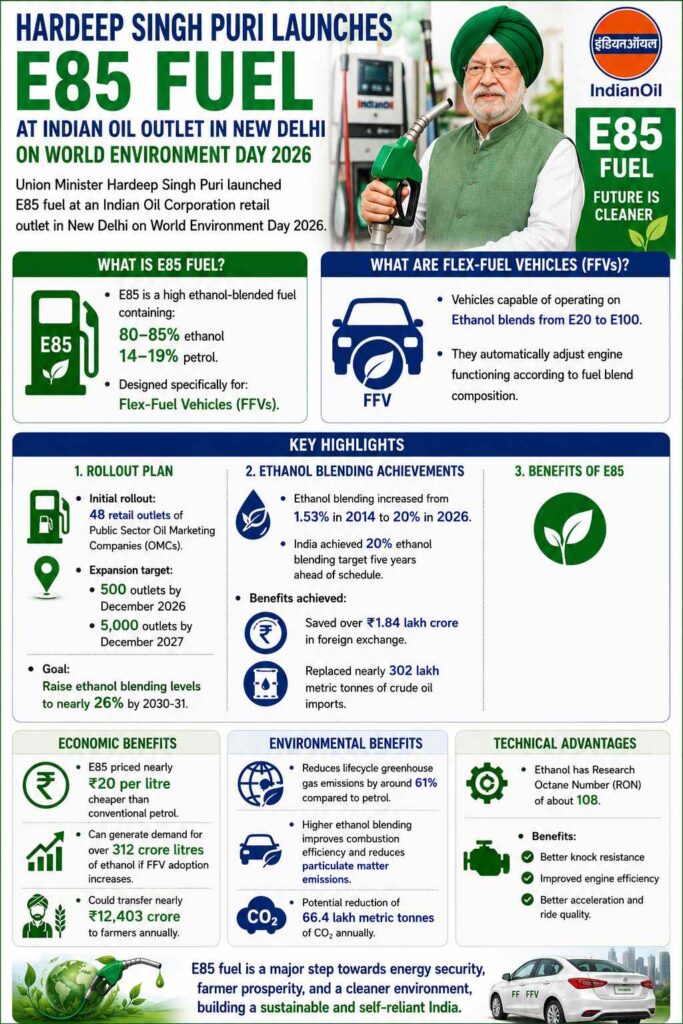
    Hardeep Singh Puri launched E85 fuel at an Indian Oil Corporation retail outlet in New Delhi on World Environment Day 2026.

    What is E85 Fuel?

    • E85 is a high ethanol-blended fuel containing: 80–85% ethanol and 14–19% petrol.
    • Designed specifically for: Flex-Fuel Vehicles (FFVs).

    What are Flex-Fuel Vehicles (FFVs)?

    • Vehicles capable of operating on: Ethanol blends from E20 to E100.
    • They automatically adjust engine functioning according to fuel blend composition.

    Rollout Plan

    • Initial rollout: 48 retail outlets of Public Sector Oil Marketing Companies (OMCs).
    • Expansion target: 500 outlets by December 2026. 5,000 outlets by December 2027.
    • Goal: Raise ethanol blending levels to nearly 26% by 2030-31.

    Ethanol Blending Achievements

    • Ethanol blending increased from 1.53% in 2014 to 20% in 2026.
    • India achieved 20% ethanol blending target five years ahead of schedule.
    • Benefits achieved:
      • Saved over ₹1.84 lakh crore in foreign exchange.
      • Replaced nearly 302 lakh metric tonnes of crude oil imports.

    Benefits of E85

    Economic Benefits

    • E85 priced nearly ₹20 per litre cheaper than conventional petrol.
    • Can generate Demand for over 312 crore litres of ethanol if FFV adoption increases.
    • Could transfer Nearly ₹12,403 crore to farmers annually.

    Environmental Benefits

    • Reduces lifecycle greenhouse gas emissions by: Around 61% compared to petrol.
    • Higher ethanol blending: Improves combustion efficiency and Reduces particulate matter emissions.
    • Potential reduction: 66.4 lakh metric tonnes of CO₂ annually.

    [2025] Consider the following statements:
    Statement I: Of the two major ethanol producers in the world, i.e., Brazil and the United States of America, the former produces more ethanol than the latter.
    Statement II: Unlike in the United States of America where corn is the principal feedstock for ethanol production, sugarcane is the principal feedstock for ethanol production in Brazil.
    Which one of the following is correct in respect of the above statements?

    [A] Both Statement I and Statement II are correct and Statement II explains Statement I

    [B] Both Statement I and Statement II are correct but Statement II does not explain Statement I

    [C] Statement I is correct but Statement II is not correct

    [D] Statement I is not correct but Statement II is correct

  • Niveshak Shivir by IEPFA and SEBI

    Why in the news?

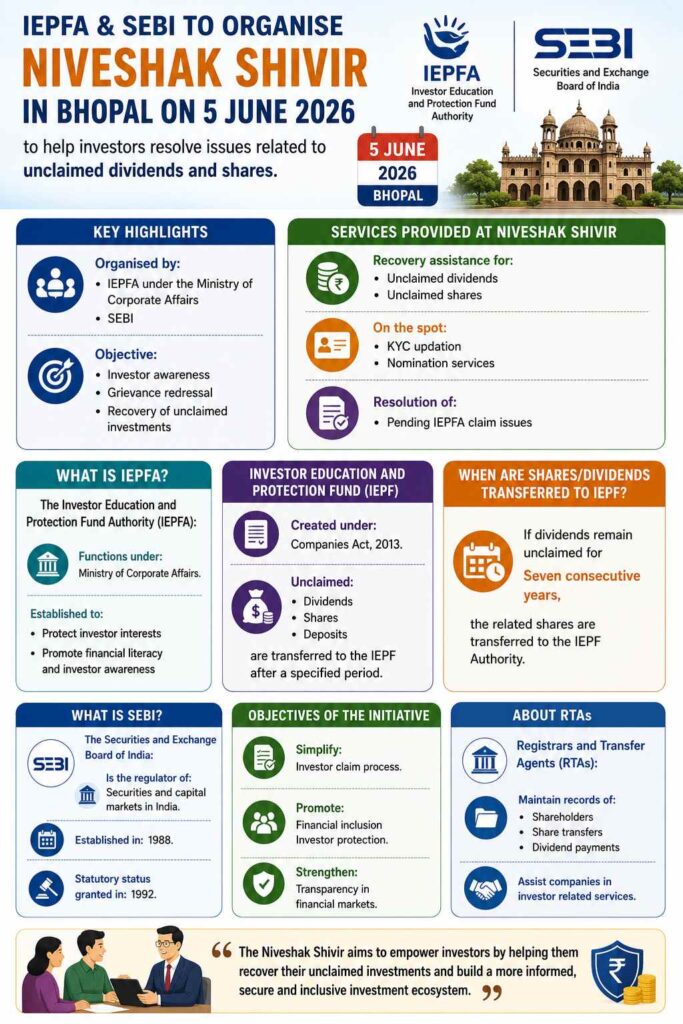
    Investor Education and Protection Fund Authority and Securities and Exchange Board of India will organise a Niveshak Shivir in Bhopal on 5 June 2026 to help investors resolve issues related to unclaimed dividends and shares.

    Key Highlights

    • Organised by:
      • IEPFA under the Ministry of Corporate Affairs
      • SEBI.
    • Objective:
      • Investor awareness
      • Grievance redressal
      • Recovery of unclaimed investments.

    Services Provided at Niveshak Shivir

    • Recovery assistance for:
      • Unclaimed dividends
      • Unclaimed shares.
    • On the spot:
      • KYC updation
      • Nomination services.
    • Resolution of:
      • Pending IEPFA claim issues.

    What is IEPFA?

    The Investor Education and Protection Fund Authority (IEPFA):

    • Functions under: Ministry of Corporate Affairs.
    • Established to:
      • Protect investor interests.
      • Promote financial literacy and investor awareness.

    Investor Education and Protection Fund (IEPF)

    • Created under: Companies Act, 2013.
    • Unclaimed: Dividends, Shares, and Deposits are transferred to the IEPF after a specified period.

    When are Shares/Dividends Transferred to IEPF?

    • If dividends remain unclaimed for Seven consecutive years, the related shares are transferred to the IEPF Authority.

    What is SEBI?

    The Securities and Exchange Board of India:

    • Is the regulator of Securities and capital markets in India.
    • Established in 1988.
    • Statutory status granted in 1992.

    Objectives of the Initiative

    • Simplify Investor claim process.
    • Promote:
      • Financial inclusion
      • Investor protection.
    • Strengthen: Transparency in financial markets.

    About RTAs

    Registrars and Transfer Agents (RTAs):

    • Maintain records of:
      • Shareholders
      • Share transfers
      • Dividend payments.
    • Assist companies in investor-related services.

    [2025] Consider the following statements:
    I. India accounts for a very large portion of all equity option contracts traded globally thus exhibiting a great boom.
    II. India’s stock market has grown rapidly in the recent past even overtaking Hong Kong’s at some point of time.
    III. There is no regulatory body either to warn the small investors about the risks of options trading or to act on unregistered financial advisors in this regard.
    Which of the statements given above are correct?

    [A] I and Il only

    [B] II and III only

    [C] I and III only

    [D] I, II and III

  • The future of India’s chip industry

    Why in the News?

    Recently, NITI Aayog Frontier Tech Hub report was released and it assesses the country’s readiness for chip manufacturing. India has approved its first semiconductor fabrication unit at Dholera and launched a ₹76,000 crore India Semiconductor Mission. But, the report finds that the domestic ecosystem is still not equipped to meet national demand.

    How Has India Built the Foundations of a Semiconductor Ecosystem?

    1. Policy Priority: Semiconductor manufacturing has been identified as a strategic national priority.
    2. India Semiconductor Mission (ISM): Operates with a corpus of ₹76,000 crore.
    3. Financial Support: Provides incentives for fabs, compound semiconductor facilities, packaging units, design initiatives, and research.
    4. Capital Subsidies: Major projects receive capital support of up to 50%.
    5. Production Incentives: Several projects receive production-linked and output-linked incentives.
    6. Dholera Fab: India’s first semiconductor fabrication facility is expected to become operational by 2028.
    7. Ecosystem Development: Multiple packaging and testing facilities have been approved.

    India Semiconductor Mission

    1. The India Semiconductor Mission (ISM) is a specialized, independent business division within the Digital India Corporation under the Ministry of Electronics and Information Technology (MeitY). 
    2. It was launched in 2021 with an original financial outlay of ₹76,000 crore.
    3. Its core purpose is to build a vibrant, sustainable semiconductor and display ecosystem to transition India from a chip consumer into a global electronic manufacturing and design hub.

    Core Schemes & Financial Support: The initiative operates as a single-window nodal agency that evaluates proposals and distributes a 50% fiscal subsidy on a pari-passu basis across critical segments:

    1. Semiconductor Fabs: Financial backing to set up silicon-based wafer fabrication plants.
    2. Display Fabs: Incentives for building TFT LCD or AMOLED display manufacturing units.
    3. Compound Semiconductors & ATMP: Support for Silicon Photonics, Sensors, and Assembly, Testing, Marking, and Packaging (ATMP/OSAT) plants.
    4. Design Linked Incentive (DLI): Financial and infrastructure support for domestic fabless companies developing Integrated Circuits and Systems on Chips (SoCs).

    ISM 2.0

    1. Announced in the latest 2026 Union Budget, ISM 2.0 drives local supply chain self-sufficiency. 
    2. It receives a targeted ₹1,000 crore budgetary provision for FY 2026-27 alongside an overall ₹8,000 crore layout for the modified manufacturing program. 

    Key targets include:

    1. Upstream Supply Chains: Localizing production of specialty gases, chemicals, and lithography tools.
    2. Indian IP & Processors: Scaling indigenous open-source RISC-V processors like DHRUV64 under the Digital India RISC-V (DIR-V) programme to secure digital sovereignty.
    3. Talent Pyramid: Training over 85,000 to 100,000 engineers via the Chips to Startup (C2S) program and dedicated SMART Labs.
    4. NITI Aayog Roadmap: Aligning with the NITI Frontier Tech Hub’s newly released “Future of India’s Semiconductor Industry” roadmap to target a $100-110 billion domestic market by 2030.

    Why Does the Report Argue That India Remains Semiconductor-Dependent?

    1. Import Dependence: India depends almost entirely on external suppliers, importing an estimated $15+ billion in electronics hardware. Major suppliers include China, Hong Kong, Taiwan, and Singapore
    2. Domestic Supply Gap: India’s semiconductor ecosystem cannot fully meet domestic demand. The domestic semiconductor ecosystem is largely limited to Assembly, Testing, Marking, and Packaging (ATMP) rather than full-scale fabrication.
    3. Electronics Vulnerability: Growth in electronics manufacturing remains dependent on external suppliers.
    4. National Security Concerns: Defence systems rely on imported semiconductor components.
    5. Supply-Chain Risks: Geopolitical disruptions could affect access to critical technologies and components.

    What Structural Challenges Limit India’s Semiconductor Manufacturing Ambitions?

    1. Time-Intensive Manufacturing Cycle
      1. Long Gestation Period: Semiconductor fabs generally require 4-5 years before commercial production.
      2. Yield Optimisation: Reliability and quality improvement continue for several quarters after production begins.
    2. Technological Complexity
      1. Equipment Dependence: More than 50 specialised equipment categories are required.
      2. Global Supplier Concentration: Critical manufacturing tools are controlled by a limited number of international firms.
    3. Capital Intensity
      1. High Investment Requirements: Semiconductor manufacturing demands massive upfront capital expenditure.
      2. Financial Risks: Long project cycles increase uncertainty for investors.
    4. Skill Requirements
      1. Advanced Expertise: Requires highly skilled engineers, designers, and process specialists.
      2. Technology Gaps: Domestic capabilities remain under development.

    Should India Replicate the Entire Global Semiconductor Value Chain?

    India should not replicate the entire global semiconductor value chain, as doing so is financially impractical and technologically inefficient. The global semiconductor industry is highly fragmented, capital-intensive, and reliant on decades of hyper-specialization across different countries.

    1. Selective Strategy: The report discourages attempts to replicate the complete global manufacturing spectrum.
      1. Example: Instead of trying to build complex extreme ultraviolet (EUV) lithography machines (a sector monopolized by ASML in the Netherlands), India is focusing on specific nodes (like 28nm and above) that serve automotive and consumer electronics markets.
    2. Capital Efficiency: Setting up a single advanced semiconductor fabrication plant (fab) can cost upwards of $10 billion to $20 billion. Replicating the entire chain would require hundreds of billions of dollars.
      1. Example: By directing capital toward Assembly, Testing, Marking, and Packaging (ATMP) and Outsourced Semiconductor Assembly and Test (OSAT) facilities, such as the Tata Electronics facilities, India can enter the manufacturing ecosystem faster and at a fraction of the cost of a leading-edge logic fab.
    3. System-Level Differentiation: Emphasises strategic specialisation rather than broad replication.
      1. Example: India houses nearly 20% of the world’s semiconductor design engineers. By utilizing the Design-Linked Incentive (DLI) scheme, local startups can design specialized, proprietary chips for Artificial Intelligence (AI), 5G communications, and Internet of Things (IoT) devices, establishing a unique global niche.
    4. Resource Optimisation: Supports targeted investments in high-potential segments.

    Why Does the Report Advocate a Shift Towards Mature and Strategic Nodes?

    Semiconductor nodes represent the transistor size, with advanced (3-7nm) focusing on density for high-end computing and mature nodes (28nm+) offering reliability for industrial use. The report advocates shifting toward mature and strategic nodes because they cost significantly less to build, have higher market demand in India, and directly secure critical industries like defense and automotive.

    1. Technological Feasibility: India currently lacks the manufacturing ecosystem, equipment base, and process expertise required for competitive production at advanced 3-7 nanometre nodes.
    2. Capital Efficiency: Mature-node semiconductor facilities require significantly lower investment and entail lower commercial risks than cutting-edge fabrication plants.
    3. Market Demand: Mature-node chips continue to dominate demand in automobiles, industrial machinery, consumer electronics, power systems, and telecommunications equipment.
    4. Strategic Utility: Domestic production of mature semiconductors can strengthen supply-chain resilience in defence, telecom, automotive, and critical infrastructure sectors.
    5. Comparative Advantage: Compound semiconductors offer niche opportunities where India can develop specialised capabilities without directly competing in the most advanced fabrication segments.
    6. Faster Capability Creation: Focusing on mature technologies enables quicker ecosystem development, workforce training, and industrial scaling than pursuing frontier-node manufacturing.

    Why Can Semiconductor Packaging Become India’s Most Viable Entry Point into the Global Semiconductor Industry?

    1. Lower Capital Requirement: Packaging and testing facilities require substantially lower investment than semiconductor fabrication plants, making entry easier for India.
    2. Technological Accessibility: Packaging operations involve lower technological complexity than advanced-node chip fabrication, reducing entry barriers.
    3. Workforce Advantage: India’s large pool of engineers and technical professionals can support labour-intensive assembly, testing, and packaging operations.
    4. Faster Capacity Expansion: Packaging facilities can be established and scaled more quickly than fabrication units, enabling rapid ecosystem development.
    5. Import Substitution Potential: Domestic packaging capabilities can reduce dependence on foreign assembly and testing services in high-volume semiconductor segments.
    6. Global Value Chain Integration: Packaging provides a practical route for India to participate in international semiconductor supply chains without mastering frontier-node manufacturing.
    7. Foundation for Ecosystem Growth: A strong packaging industry can create demand for ancillary industries, skills, logistics networks, and future fabrication investments.

    What Does “Sovereign Design and Research Capability” Mean for India?

    1. Design Leadership: Moves beyond manufacturing toward intellectual-property creation.
    2. R&D Excellence: Strengthens indigenous innovation capabilities.
    3. AI Integration: Promotes application of Artificial Intelligence in semiconductor engineering.
    4. Deep Capabilities: Supports transition from service-led design activities to original technology creation.
    5. Architectural Innovation: Encourages development of differentiated semiconductor systems and integration technologies.

    How Should India Structure Future Semiconductor Investments?

    1. Second Phase of ISM: Future policy support is under consideration.
    2. Investment Requirement: The report estimates $45-60 billion over a ten-year period.
    3. Bankability Focus: Recommends prioritising projects with clearer commercial viability.
    4. Risk Management: Encourages investment in segments with stronger return potential.
    5. Targeted Expansion: Supports gradual ecosystem deepening rather than large-scale expansion across all segments.

    Which International Partnerships Are Critical for India’s Semiconductor Strategy?

    1. Strategic Partners: Identifies the United States, Japan, European Union, and South Korea as priority partners.
    2. Technology Access: Facilitates acquisition of critical manufacturing tools.
    3. Lifecycle Support: Strengthens equipment servicing and maintenance.
    4. Knowledge Transfer: Expands access to advanced manufacturing practices.
    5. Packaging Advantage: Leverages India’s workforce and packaging ecosystem.

    What Are the Broader Strategic Implications for India?

    1. Economic Security: Reduces dependence on external technology suppliers.
    2. Supply-Chain Resilience: Protects against geopolitical disruptions.
    3. National Security: Supports defence and critical infrastructure requirements.
    4. Industrial Competitiveness: Strengthens electronics manufacturing.
    5. Technological Sovereignty: Enhances control over critical technologies.
    6. Global Positioning: Improves India’s role in future technology ecosystems.

    Conclusion

    India’s semiconductor strategy is entering an execution phase where success will depend less on replicating the entire global value chain and more on building competitive strengths in areas aligned with domestic capabilities. The NITI Aayog report advocates a pragmatic approach centred on mature-node manufacturing, semiconductor packaging, design innovation, and strategic international partnerships. By prioritising commercially viable segments while gradually deepening technological capabilities, India can strengthen supply-chain resilience, reduce strategic vulnerabilities, and establish itself as a credible participant in the global semiconductor ecosystem.

    PYQ Relevance

    [UPSC 2025] India aims to become a semiconductor manufacturing hub. What are the challenges faced by the semiconductor industry in India? Mention the salient features of the Indian Semiconductor Mission

    Linkage: The PYQ tests understanding of high-technology manufacturing, industrial policy, technological self-reliance, and strategic sectors. The article evaluates India’s semiconductor strategy through the NITI Aayog report, highlighting challenges in fabrication, supply chains, investment, and skills while assessing the future direction of the India Semiconductor Mission
  • How land pooling solves acquisition woes

    Why in the News?

    Rajasthan has announced its first-ever land pooling scheme, signalling a major shift in the way urban land is assembled for infrastructure and development projects.

    What is land pooling?

    Land pooling is a land acquisition strategy where landowners voluntarily hand over their land parcels to a government agency or development authority. The authority consolidates (pools) the land, builds modern infrastructure and then returns a smaller but highly developed portion of the land back to the original owners.

    How does land pooling work?

    1. Pooling: Landowners voluntarily transfer their fragmented, irregular plots to a central authority to create one continuous tract.
    2. Infrastructure Development: The authority reserves a percentage of the total land to build roads, utilities, parks, and public services.
    3. Reconstitution: The authority reorganises the remaining land into a planned layout of commercial, residential, and industrial plots.
    4. Return: Each landowner receives back a physically smaller but highly developed plot equipped with modern amenities and significantly higher market value.

    Example

    Gujarat Town Planning (TP) Model

    1. Land Contribution: Landowners typically contribute about 25-40% of their land.
    2. Land Return: Approximately 60-75% of land is returned as serviced plots.
    3. Integrated Development: Combines land assembly, infrastructure provision, cost recovery, and urban planning within a single framework.

    How is land pooling governed in India?

    Land pooling in India is governed through a decentralized framework managed primarily by individual state governments, rather than a single central federal law. The structural and legal governance framework breaks down into four primary tiers:

    1. Constitutional Authority: Under the Constitution of India, Land and Colonisation fall explicitly under the State List (List II, Seventh Schedule).
    2. State-Specific Legislative Acts
      1. The Mechanism: States enact standalone Town Planning Acts or Urban Development Acts that provide the legal backbone for land pooling.
      2. Examples: Notable examples include the Gujarat Town Planning and Urban Development Act, 1976, and the Andhra Pradesh Capital Region Development Authority Act, 2014, which laid out the legal rules for building the city of Amaravati.
    3. Execution by Development Authorities
      1. The Mechanism: State governments delegate the actual implementation and policing of land pooling schemes to specialized Urban Development Authorities.
      2. The Power: Entities like the Delhi Development Authority (DDA) or the Mumbai Metropolitan Region Development Authority (MMRDA) are legally authorized to notify zones for pooling, verify land titles, collect landowner consensus, and re-allot reconstituted plots.
    4. Judicial Oversight and Grievance Redressal
      1. The Mechanism: State pooling policies mandatorily incorporate dedicated dispute resolution tribunals, appellate authorities, or arbitrators.

    How Has Traditional Land Acquisition Become a Constraint to Urban Infrastructure Development?

    1. Procedural Complexity: Land acquisition has historically been lengthy, litigation-prone, and administratively challenging.
    2. Post-2013 Cost Escalation: The Right to Fair Compensation and Transparency in Land Acquisition, Rehabilitation and Resettlement Act, 2013 increased compensation, rehabilitation, and resettlement obligations.
    3. Financial Burden: Higher compensation requirements have significantly increased project costs.
    4. Implementation Gap: Planned infrastructure often remains under-executed due to inability to mobilise land.
    5. Urbanisation Pressure: Expanding cities require large-scale land assembly for roads, public facilities, housing, and economic infrastructure.

    Why Is Land Pooling Considered More Equitable Than Compulsory Acquisition?

    1. Participatory Planning: Landowners remain stakeholders rather than losing ownership entirely.
    2. Reduced Displacement: Limits physical displacement compared to conventional acquisition.
    3. Value Capture: Landowners benefit from appreciation in land value after infrastructure development.
    4. Financial Sustainability: Infrastructure costs are recovered through incremental development charges rather than large upfront expenditure.
    5. Social Acceptance: Voluntary participation reduces resistance and legal disputes.
    6. Environmental Protection: Facilitates planned development while preserving environmentally sensitive areas.

    Why Is Gujarat Considered India’s Most Successful Land Pooling Model?

    1. Historical Evolution: Land pooling was introduced nearly 100 years ago.
    2. Legal Foundation: Formalised under the Gujarat Town Planning and Urban Development Act, 1976.
    3. Large-Scale Implementation: More than 1,000 sq. km. has been planned through TP schemes.
    4. Geographical Coverage: Implemented across Ahmedabad, Surat, Rajkot, Vadodara, and Gandhinagar.
    5. Institutional Continuity: Strong legal backing and administrative experience enabled long-term success.
    6. Urban Expansion: Facilitated orderly peripheral growth and infrastructure provision.

    Why Has Maharashtra Recently Revived Interest in Land Pooling?

    1. Statutory Limitations: Existing legal provisions were not adequately updated for TP schemes.
    2. Recent Adoption: The model has gained momentum in Pune and the Mumbai Metropolitan Region Development Authority (MMRDA).
    3. Peripheral Development: Supports infrastructure creation and serviced land development in expanding urban regions.
    4. Growth Management: Provides an alternative to fragmented urban expansion.

    Why Land Pooling Initiatives like Guwahati Face Difficulties?

    1. Institutional Challenges
      1. Legal Gaps: The Guwahati Metropolitan Development Authority Act, 1985 lacked clarity on land appropriation percentages and institutional responsibilities.
      2. Implementation Ambiguity: Development scheme preparation procedures remained inadequately specified.
    2. Land Records Challenges
      1. Manual Records: Land records were not digitised.
      2. Record Mismatch: Discrepancies existed between revenue records and actual ground conditions.
    3. Administrative Solutions
      1. Existing Map Utilisation: Authorities retained existing maps instead of conducting extensive joint surveys.
      2. Revenue-Based Allocation: Final plot allocation was based on land area recorded in revenue documents.
      3. Time Efficiency: Reduced scheme preparation time.
    4. Contribution Adjustment
      1. Reduced Contribution: Private landowners contributed only 12-15% of land.
      2. Comparison: Conventional schemes generally require 35–45% land contribution.
      3. Infrastructure Focus: Contributed land was primarily used for road development.

    How Is Rajasthan Attempting to Make Land Pooling More Viable?

    1. Statutory Recognition: Land pooling provisions already existed since 2016.
    2. Implementation Push: Rajasthan is now operationalising the framework.
    3. Land Value Reforms: Modifications are being made to land-value calculations.
    4. Cost Sharing: Government has absorbed part of the development cost.
    5. Financial Equity: Reduces burden on participating landowners.
    6. Stakeholder Acceptance: Makes participation more attractive.

    What Factors Will Determine the Success of Future Land Pooling Schemes?

    1. Stakeholder Trust: Requires convincing landowners of long-term benefits.
    2. Legislative Clarity: Ensures certainty regarding rights, obligations, and compensation.
    3. Digital Land Records: Improves transparency and reduces disputes.
    4. Flexible Contribution Models: Allows adaptation to local realities.
    5. Institutional Capacity: Strengthens planning authorities and implementation agencies.
    6. Equitable Financial Models: Distributes costs and benefits fairly.
    7. Context-Specific Design: Avoids one-size-fits-all approaches.

    Conclusion

    Land pooling represents a shift from a compensation-centric model of land acquisition to a partnership-based model of urban development. The experiences of Gujarat, Maharashtra, Guwahati, and Rajasthan demonstrate that success depends less on the concept itself and more on institutional capacity, legal clarity, digitised land records, and equitable benefit-sharing. As India’s urbanisation accelerates, land pooling can become a critical instrument for balancing infrastructure needs with property rights and inclusive development.

    Value Addition

    Land Pooling vs Land Acquisition

    DimensionLand AcquisitionLand Pooling
    OwnershipGovernment acquires landLandowners retain stake
    CompensationMonetary paymentReconstituted serviced plots
    ParticipationCompulsoryVoluntary
    DisplacementHigherLower
    LitigationHighRelatively lower
    Cost BurdenUpfront government expenditureShared through value capture
    Benefit SharingLimitedBroader and participatory

    PYQ Relevance

    [UPSC 2024] What were the factors responsible for the successful implementation of land reforms in some parts of the country? Elaborate.

    Linkage: The question focuses on land governance, fair land distribution, and factors that make land reforms successful. Land pooling is a modern land reform approach that uses voluntary participation, clear land records, and shared benefits to support planned development.