💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Economics

  • Centre doubles import duty on gold, silver; move is criticised as retrograde

    Why in the News?

    India has doubled the effective import duty on gold and silver from nearly 9.2% to 18.4%. The decision came amid concerns over the impact of the West Asia crisis on India’s external sector and soon after the Prime Minister urged citizens to reduce gold purchases to conserve foreign exchange.

    How has the government changed the import duty structure on gold and silver?

    1. Customs Duty Revision: The government increased basic customs duty on gold and silver from 5% to 10%.
    2. AIDC Increase: The Agriculture Infrastructure and Development Cess (AIDC) increased from 1% to 5%.
    3. IGST Continuity: The Integrated Goods and Services Tax (IGST) remains 3% on the assessable value.
    4. Effective Tax Burden: The cumulative effective tax burden increased from around 9.2% to 18.4%, including customs duty, cess, insurance, freight cost, and IGST.
    5. Immediate Implementation: The revised rates came into force through official notifications issued on 13 May, without prior consultation.

    Why did the government increase import duty on precious metals?

    The government increased the import duty on gold and silver to defend India’s macroeconomic balance against external shocks by prioritizing non-discretionary resource allocations.

    1. Current Account Deficit (CAD): Reducing import volumes directly curbs the widening Current Account Deficit to keep the trade balance within sustainable limits.
    2. Foreign Exchange Conservation: India aims to preserve forex reserves and rupee stability, especially amid geopolitical uncertainty.
    3. West Asia Crisis: Regional instability threatens oil prices, logistics chains, and shipping routes, increasing vulnerability for a crude oil-import dependent economy.
    4. Import Prioritisation: The government appears to prioritise foreign exchange for essential imports such as:
      1. Crude Oil
      2. Fertilisers
      3. Industrial Raw Materials
      4. Defence Requirements
      5. Critical Technologies
      6. Capital Goods
    5. Demand Management: Gold is treated as a consumption and investment good, unlike strategic imports necessary for production.

    Why are the gems and jewellery industry opposing the decision?

    1. Export Cost Escalation: Exporters argue that expensive imported gold raises production costs, reducing competitiveness in international markets.
    2. Working Capital Blockage: Exporters now face bank guarantees of ₹28-30 lakh per kg of duty-free gold, creating liquidity stress.
    3. MSME Vulnerability: MSMEs constitute nearly 80% of Gems and Jewellery Export Promotion Council (GJEPC) membership, making the sector particularly vulnerable.
    4. Employment Risks: Higher costs could reduce export orders and employment in a labour-intensive sector.
    5. Export Disruption: Industry stakeholders warn of lower shipments during a period already marked by trade disruption due to the West Asia crisis.

    Can higher import duties reduce gold imports effectively?

    1. Historical Experience: India’s past experience indicates that higher gold tariffs often fail to proportionately reduce imports.
    2. Persistent Demand: Cultural demand for gold in India remains high due to:
      1. Marriage Expenditure
      2. Household Savings
      3. Investment Demand
      4. Inflation Hedge
    3. Price Transmission: Higher tariffs often increase domestic gold prices rather than reduce demand.
    4. Import Resilience: Despite global gold prices doubling in recent years, imports have not fallen proportionately.
    5. Limited Elasticity: Demand for gold in India demonstrates low price elasticity, limiting tariff effectiveness.

    Does a higher duty increase smuggling and informal trade?

    1. Smuggling Incentives: Large differences between domestic and international prices create incentives for illegal gold inflows.
    2. Historical Precedent: India witnessed higher gold smuggling during earlier phases of elevated import duties.
    3. Revenue Leakage: Smuggling reduces formal tax collection and weakens customs enforcement.
    4. Informal Economy Expansion: Illegal channels strengthen hawala networks and black-market transactions.
    5. Policy Trade-off: Excessively high tariffs may undermine the original objective of reducing imports.

    How important is West Asia for India’s gems and jewellery trade?

    1. Diamond Export Share: West Asia accounts for nearly 18% of India’s diamond exports during the first nine months of FY 2025-26.
    2. Import Dependence: Around 68% of India’s rough diamond imports originate from the UAE and Israel.
    3. Trade Vulnerability: Regional instability directly affects supply chains, shipping, insurance costs, and export demand.
    4. Strategic Dependence: The sector remains deeply linked to West Asian trade networks.

    What concerns have been raised regarding policy transparency?

    1. Complex Taxation Structure: Multiple amendments and notifications complicate duty calculations.
    2. Ease of Doing Business Issues: Frequent tariff changes increase compliance burdens for traders and exporters.
    3. Predictability Deficit: Sudden duty revisions reduce policy certainty for investment planning.
    4. Administrative Complexity: Multi-layered taxation may weaken transparency in customs administration.

    What are the Policy Alternatives to Import Duty Hike?

    1. Gold Monetisation Scheme (GMS): Mobilises idle household gold through bank deposits, reducing dependence on fresh imports.
    2. Sovereign Gold Bonds (SGBs): Provides gold-linked returns without physical purchase, lowering demand for imported gold.
    3. Financial Savings Alternatives: Encourages investment in mutual funds, fixed deposits, equities, and pension schemes, reducing gold dependence as a savings tool.
    4. Recycling of Domestic Gold: Strengthens refining and reuse of existing gold stock, reducing import needs.
    5. Formalisation of Gold Trade: Improves hallmarking, digital tracking, and compliance, reducing smuggling and increasing tax collection.

    Conclusion

    The increase in gold and silver import duties shows India’s effort to protect foreign exchange reserves and manage external economic pressures during global uncertainty. However, past experience suggests that very high duties on gold may increase smuggling, disrupt markets, and hurt exports. A balanced approach, combining moderate tariffs with alternatives like digital or financial gold investments, may work better in the long run.

    PYQ Relevance

    [UPSC 2017] Account for the failure of the manufacturing sector in achieving the goal of labour-intensive exports rather than capital-intensive exports. Suggest measures for more labour-intensive rather than capital-intensive exports

    Linkage: The article links directly to this PYQ because the gems and jewellery sector is a labour-intensive export industry, and higher gold import duties can reduce its global competitiveness. It also highlights the challenge of balancing trade policy with export growth and MSME employment.
  • Bharat Maritime Insurance Pool (BMIP)

    Why in the News

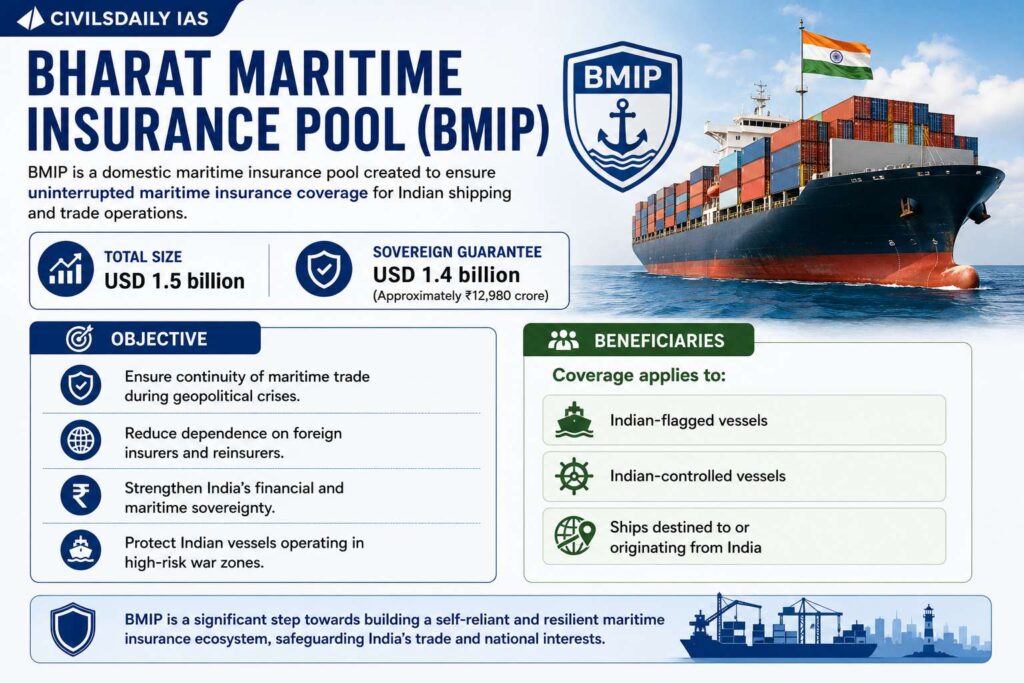
    The Department of Financial Services under the Ministry of Finance launched the Bharat Maritime Insurance Pool (BMIP) worth USD 1.5 billion amid rising geopolitical tensions in West Asia.

    About Bharat Maritime Insurance Pool (BMIP)

    • BMIP is a domestic maritime insurance pool created to ensure uninterrupted maritime insurance coverage for Indian shipping and trade operations.
    • Total Size: USD 1.5 billion
    • Sovereign Guarantee: USD 1.4 billion
    • Approximately ₹12,980 crore

    Objective

    • Ensure continuity of maritime trade during geopolitical crises.
    • Reduce dependence on foreign insurers and reinsurers.
    • Strengthen India’s financial and maritime sovereignty.
    • Protect Indian vessels operating in high-risk war zones.

    Beneficiaries

    • Coverage applies to:
      • Indian-flagged vessels
      • Indian-controlled vessels
      • Ships destined to or originating from India
    [2024] Consider the following statements: 
    Statement-I Sumed pipeline is a strategic route for Persian Gulf oil and Natural gas shipments to Europe. 
    Statement-II: Sumed pipeline connects the Red Sea with the Mediterranean Sea. 
    Which one of the following is correct in respect of the above statements? 
    [A] Both Statement-I and Statement-II are correct and Statement-II explains Statement-I 
    [B] Both Statement-I and Statement-II are correct, but Statement-II does not explain Statement-I 
    [C] Statement-I is correct, but Statement-II is incorrect 
    [D] Statement-I is incorrect, but Statement-II is correct
  • Why saving forex could hamper India’s growth

    Why in the News?

    The Prime Minister of India recently asked Indians to use fewer imports, like oil and fertilizers, to save the country’s foreign exchange (forex). While India has a huge “safety net” of over $640 billion in reserves, some experts are worried. They argue that cutting imports too much might actually hurt our industrial growth, since many factories depend on imported parts. The big question now is: should India focus on hoarding cash or boosting production?

    How are forex reserves linked to India’s economic growth?

    Foreign exchange (forex) reserves act as a high-speed engine and a safety net for India’s economic growth. Their link to growth is both protective (preventing crashes) and productive (enabling industrial expansion).

    1. Sustaining Industrial Output (Import Financing)
      1. Energy & Raw Materials: India imports roughly 85% of its crude oil and large quantities of fertilizers and electronics.
      2. Growth Link: Healthy reserves ensure that factories never stop running due to a lack of dollars to pay for these essential inputs. As of May 2026, India’s reserves provide an import cover of approximately 11 to 12 months, keeping industrial production stable despite global supply shocks
    2. Balance of Payments (BoP): Reflects all economic transactions between India and the rest of the world. Forex reserves increase when inflows exceed outflows through the current account and capital account.
      1. Current Account Deficit (CAD): Occurs when imports exceed exports. India generally runs a CAD because of dependence on crude oil, gold, electronics and industrial inputs.
      2. Capital Account Surplus: Compensates for CAD through Foreign Direct Investment (FDI), Foreign Portfolio Investment (FPI), external borrowings and remittances, helping maintain reserve adequacy.
    3. Stabilizing the “Price of Growth” (Rupee Stability)
      1. Controlling Inflation: When the rupee weakens, imports like oil become expensive, causing “imported inflation.”
      2. Growth Link: The RBI uses reserves to intervene in the market, selling dollars when the rupee falls too fast (as it did when the rupee crossed ₹95/$ in May 2026). This stability keeps costs predictable for businesses and protects the purchasing power of citizens.
    4. Example: India’s reserves provide an import cover of several months, unlike the 1991 Balance of Payments crisis, when reserves had fallen to levels sufficient for only weeks of imports.

    Why has conserving forex become a policy concern?

    1. Import Dependence: India imports nearly 80-85% of crude oil requirements, making oil the largest source of forex outflow.
    2. Commodity Vulnerability: Global disruptions such as the Russia-Ukraine conflict increased energy and fertilizer prices, worsening import bills.
    3. Edible Oil Imports: India depends significantly on imports of palm, soybean and sunflower oils, creating recurring pressure on forex.
    4. Fertilizer Dependence: Though food grain production is self-sufficient, agriculture remains dependent on imported fertilizer inputs.
    5. Trade Deficit Pressure: Persistent trade deficits increase vulnerability to global shocks and currency depreciation.

    Why could excessive forex conservation slow India’s growth?

    1. Consumption Compression: Reducing spending on imported goods lowers aggregate demand, affecting production and employment.
    2. Industrial Dependence on Imports: Indian manufacturing depends heavily on imported machinery, components, chemicals and intermediate goods.
    3. Multiplier Effects: Lower demand reduces business expansion, private investment and job creation.
    4. Growth Slowdown: Reduced imports of productive inputs may weaken sectors dependent on global value chains.
    5. Investment Sentiment: Weak domestic demand discourages domestic and foreign investors from expanding production.
    6. Example: Cutting imports indiscriminately may reduce economic dynamism rather than merely reducing forex outflows.

    Can India realistically replace imported goods in the short term?

    1. Crude Oil Constraint: India cannot quickly substitute imported crude because domestic energy production remains limited.
    2. Fertilizer Dependence: Natural resources required for fertilizer production, such as potash and phosphates, remain import-dependent.
    3. Intermediate Goods Dependence: Electronics, semiconductors and industrial machinery require imported components.
    4. Cost Consideration: Domestic substitutes often remain costlier or technologically inferior in the short run.
    5. Time Lag: Import substitution requires industrial capacity, technology transfer and infrastructure expansion.
    6. Example: India is food self-sufficient but still relies heavily on imported fertilizers to sustain agricultural productivity.

    What explains the relationship between the rupee and forex reserves?

    1. Currency Intervention: RBI sells dollars to stabilise the rupee during depreciation pressures.
    2. Exchange Rate Impact: Higher imports increase dollar demand, weakening the rupee.
    3. Inflation Transmission: A weaker rupee raises import costs, especially for oil, increasing inflation.
    4. Reserve Buffer: Forex reserves function as insurance against global financial shocks and capital flight.
    5. Example: RBI interventions during global volatility periods help moderate sharp exchange-rate movements.

    What should be India’s long-term strategy to manage forex sustainably?

    1. Production Enhancement: Strengthens manufacturing competitiveness through Make in India and industrial reforms.
    2. Export Diversification: Expands high-value exports in electronics, pharmaceuticals and services.
    3. Productivity Growth: Increases efficiency through technology adoption and logistics improvements.
    4. Import Rationalisation: Reduces avoidable imports while preserving productive imports.
    5. Energy Transition: Expands renewable energy and biofuel production to reduce crude oil dependence.
    6. Domestic Capability: Strengthens fertilizer, semiconductor and critical mineral ecosystems.
      1. Example: Production-linked incentive (PLI) schemes seek to reduce import dependence in sectors like electronics and solar manufacturing.

    Conclusion

    India’s forex reserves remain a critical macroeconomic buffer, but external strength cannot substitute for domestic growth momentum. Excessive emphasis on conserving forex through reduced consumption risks weakening demand, investment and productivity. A sustainable solution lies not merely in spending less foreign exchange, but in earning more through exports, higher productivity and stronger domestic production capacity.

    PYQ Relevance

    [UPSC 2017] Among several factors for India’s potential growth, savings rate is the most effective one. Do you agree? What are the other factors available for growth potential?

    Linkage: The PYQ examines whether higher savings alone can drive economic growth. This is similar to the debate on conserving foreign exchange versus expanding production and investment. The article extends this logic by arguing that growth depends not only on saving forex, but also on productivity, manufacturing and demand creation

  • Gold Monetisation Scheme (GMS)

    Why in the News

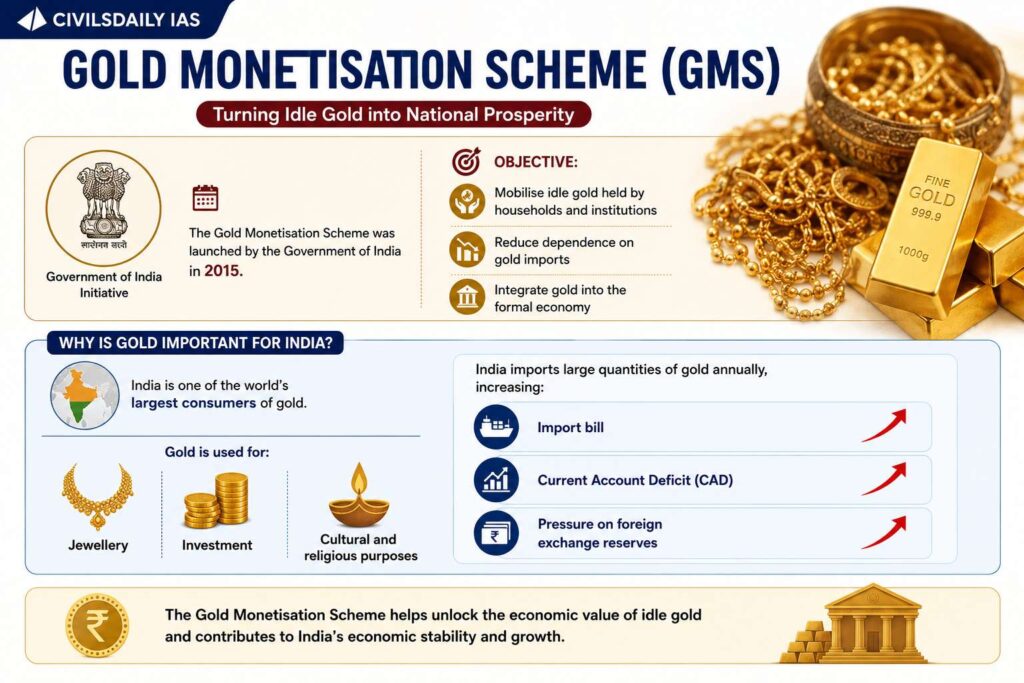
    The jewellery industry, led by the All India Gem and Jewellery Domestic Council, has called for revitalising the Gold Monetisation Scheme (GMS) to reduce gold imports and ease pressure on India’s foreign exchange reserves.

    About Gold Monetisation Scheme (GMS)

    • The Gold Monetisation Scheme was launched by the Government of India in 2015
    • Objective:
      • Mobilise idle gold held by households and institutions
      • Reduce dependence on gold imports
      • Integrate gold into the formal economy

    Why is Gold Important for India?

    • India is one of the world’s largest consumers of gold.
    • Gold is used for:
      • Jewellery
      • Investment
      • Cultural and religious purposes
    • India imports large quantities of gold annually, increasing:
      • Import bill
      • Current Account Deficit (CAD)
      • Pressure on foreign exchange reserves
    [2016] Which of the following is/are the purpose/purposes of Government’s ‘Sovereign Gold Bond Scheme’ and ‘Gold Monetization Scheme’?:
    1. To bring the idle gold lying with Indian households into the economy.
    2. To promote FDI in the gold and jewellery sector. 3.To reduce India’s dependence on gold imports.
    Select the correct answer using the code given below:
    [A] 1 only [B] 2 and 3 only [C] 1 and 3 only [D] 1, 2 and 3
  • Prevalence of fake currency till a reality post-demonetisation

    Why in the News?

    Nearly a decade after demonetisation was projected as a major strike against black money and fake currency, new NCRB and Parliamentary data show that counterfeit currency continues to circulate in India. The issue has become significant because fake ₹500 notes have sharply increased, Gujarat alone accounted for more than half of counterfeit currency seizures between 2017 and 2024, and counterfeit ₹2,000 notes rose despite being introduced after demonetisation.

    Why was demonetisation expected to curb fake currency?

    1. Currency Replacement: Demonetisation invalidated old ₹500 and ₹1,000 notes and introduced redesigned currency with enhanced security features.
    2. Financial Disruption: Intended to eliminate counterfeit stock accumulated by criminal and terror networks.
    3. Formalisation of Economy: Encouraged banking transactions and digital payments to reduce cash dependency.
    4. Security Objective: Sought to weaken terror financing channels dependent on fake Indian currency notes (FICN).
    5. Governance Goal: Intended to reduce black money circulation and illicit cash transactions.

    What do recent data reveal about counterfeit currency trends?

    1. Persistent Counterfeit Circulation: NCRB data show counterfeit currency seizures worth more than ₹54.61 crore across States.
    2. Peak Seizures in 2022: Fake currency seizures reached ₹382.6 crore, the highest level in recent years and over 85% linked to Gujarat.
    3. Sharp Rise After Demonetisation: Counterfeit ₹2,000 notes nearly doubled compared to 2017 despite being newly introduced after demonetisation.
    4. Continued Fake ₹500 Notes: Fake ₹500 notes seized in 2024 were nearly four times the level recorded in 2016.
    5. Pandemic Disruption: Currency seizures fell temporarily in 2020 (₹92 crore) during COVID-19 restrictions but later surged.
    6. Banking Detection: Banks detected counterfeit notes worth nearly ₹40.26 crore between 2020-21 and 2024-25, averaging roughly 2 lakh fake notes annually.

    Why does the rise in fake ₹500 and ₹2,000 notes matter?

    1. Security Failure: Indicates criminal networks adapted rapidly even after redesigned currency introduction.
    2. Post-Demonetisation Counterfeiting: Fake ₹2,000 notes, introduced after 2016, emerged in large numbers, questioning technological safeguards.
    3. ₹500 Dominance: Fake ₹500 notes formed a major share of seizures because the denomination remained widely used even after the withdrawal of ₹2,000 notes from circulation in May 2023.
    4. Banking Penetration: Counterfeit notes entering banks indicate that fake currency penetrated formal financial channels
    5. Economic Trust Deficit: Sustained counterfeiting weakens public confidence in cash transactions.

    Why has Gujarat emerged as the major hub of counterfeit currency seizures?

    1. High Seizure Concentration: Gujarat accounted for ₹355.72 crore, more than half of India’s total counterfeit currency seizures (2017-2024).
    2. Geographical Significance: Coastal access and trade routes may increase vulnerabilities to smuggling and organised criminal activity.
    3. Extraordinary Spike in 2022: Gujarat alone contributed to more than 85% of counterfeit currency seized nationally.
    4. Inter-State Pattern: Maharashtra and Karnataka followed Gujarat with seizures worth approximately ₹100 crore and ₹50 crore, respectively.
    5. Enforcement Question: Raises concerns regarding whether high seizures indicate stronger policing or higher counterfeit circulation.

    Has demonetisation achieved its objectives regarding fake currency?

    1. Partial Success: Immediate withdrawal disrupted counterfeit stock based on old ₹500 and ₹1,000 notes.
    2. Limited Long-Term Impact: Rising fake currency in new denominations suggests only temporary gains.
    3. Digitalisation Outcome: India witnessed growth in digital transactions, reducing some dependence on cash.
    4. Black Money Limitation: Cash-based black money adapted through alternative channels.
    5. Institutional Challenge: Persistent counterfeiting suggests the need for continuous currency security upgrades.

    What are the broader economic and security implications of counterfeit currency?

    1. Terror Financing: Fake currency supports unlawful activities and cross-border terror financing.
    2. Inflationary Distortion: Counterfeit money artificially increases cash circulation.
    3. Monetary Credibility: Reduces trust in sovereign currency and payment systems.
    4. Banking Burden: Increases costs of verification and counterfeit detection.
    5. Internal Security Threat: Strengthens organised crime and hawala networks.

    What measures can strengthen India’s anti-counterfeit framework?

    1. Currency Security Enhancement: Ensures frequent upgrades in watermarking, microprinting, and security threads.
    2. AI-Based Detection: Facilitates real-time identification of counterfeit notes in ATMs and banks.
    3. Border Surveillance: Strengthens monitoring of smuggling routes and cross-border criminal networks.
    4. Financial Intelligence Coordination: Supports coordination among RBI, NCRB, FIU-IND, DRI, NIA, and State police.
    5. Digital Payments Expansion: Reduces excessive cash dependence and counterfeit vulnerability.
    6. Public Awareness: Ensures citizen awareness regarding security features of currency notes.

    Conclusion

    The persistence of counterfeit currency despite demonetisation indicates that currency replacement alone cannot eliminate the challenge of fake money. While the 2016 exercise disrupted old counterfeit networks temporarily and accelerated digital transactions, rising seizures of fake new-series notes reveal institutional and technological gaps. A sustained strategy based on advanced currency security features, stronger inter-agency coordination, border vigilance, financial intelligence, and reduced cash dependency is necessary to protect monetary credibility and internal security.

    PYQ Relevance

    [UPSC2022] Give out the major sources of terror funding in India and the efforts being made to curtail these sources. In the light of this, also discuss the aim and objective of the ‘No Money for Terror (NMFT)’ Conference recently held at New Delhi in November 2022.

    Linkage: Counterfeit currency is a major source of terror financing, often linked with hawala, organised crime, and cross-border networks. The article directly relates to illicit financial flows and internal security.

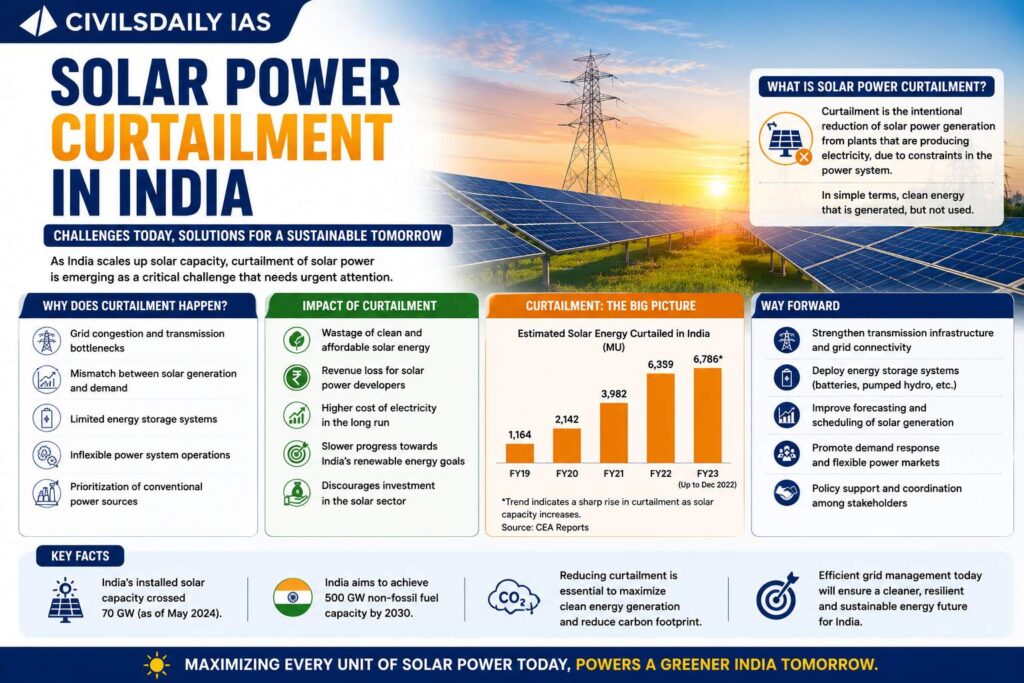
  • Solar Power Curtailment in India 

    Why in the News

    India witnessed record electricity demand in April 2026, yet large amounts of solar power had to be curtailed due to grid stress, transmission bottlenecks, and surplus daytime generation.

    What is Solar Curtailment?

    • Solar curtailment refers to the reduction of electricity generation from solar plants by grid operators to maintain grid stability and prevent overload.
    • Even though renewable energy has “must-run” status in India, it can still be reduced under emergency or technical conditions.

    Record Curtailment

    • April 2026 solar curtailment:
      • 693.81 GWh
    • January to March 2026 combined:
      • 399.34 GWh
    • This means April alone recorded around 74% higher curtailment than the previous three months combined.

    Main Reasons Behind Curtailment

    • Grid Stability Concerns: Rapid increase in solar generation during daytime created excess electricity supply. The grid struggled to absorb this sudden surge.
    • Transmission Constraints: Major solar-producing States like Rajasthan and Gujarat Faced:
      • Transformer overloading
      • Transmission congestion
      • Heavy underdrawal of electricity
    • Demand-Supply Timing Mismatch
      • Daytime: Electricity prices crashed to nearly ₹1.5/unit
      • Night-time: Solar unavailable. Prices rose close to ₹10/unit ceiling
    • This highlights the need for energy storage systems.

    What is Emergency TRAS (Tertiary Reserves Ancillary Services)?

    • It is a mechanism used by the power grid operator to maintain stability during emergency situations.
    • Under Emergency TRAS:
      • Renewable energy plants are instructed to reduce generation temporarily.
      • They receive financial compensation for the lost generation.
    [2025] Consider the following statements about ‘PM Surya Ghar Muft Bijli Yojana’: 
    I. It targets installation of one crore solar rooftop panels in the residential sector. 
    II. The Ministry of New and Renewable Energy aims to impart training on installation, operation, maintenance and repairs of solar rooftop systems at grassroot levels. 
    III. It aims to create more than three lakhs skilled manpower through fresh skilling, and upskilling, under scheme component of capacity building. 
    Which of the statements given above are correct? 
    [A] I and II only [B] I and III only [C] II and III only [D] I, II and III
  • [7th May 2026] The Hindu OpED: Understanding inequality in India’s growth story  

    PYQ Relevance[UPSC 2017] What are the salient features of ‘inclusive growth’? Has India been experiencing such a growth process? Analyze and suggest measures for inclusive growth.Linkage: The article directly examines whether India’s post-reform growth has remained inclusive, especially amid widening urban-rural and class-based consumption inequality. It links strongly with GS-III themes of inclusive growth, welfare distribution, labour reforms, poverty, inequality measurement, and human development disparities.

    Mentor’s Comment

    India’s growth story is increasingly being questioned for its uneven distribution of gains. The assumption that inequality in India is moderate when compared globally is being challenged now. The Household Consumer Expenditure Survey (HCES) 2023-24 data states that inequality, especially in urban India and in non-food consumption, is far deeper than commonly estimated. While India has emerged as one of the fastest-growing economies, consumption patterns reveal widening disparities between rural and urban India, between rich and poor, and within social classes themselves. The top 10% in urban India account for 27% of total non-food expenditure, while the richest urban households spend nearly nine times more than the poorest rural households. 

    Why does measuring inequality in India remain methodologically complex?

    1. Multiple Dimensions: Inequality exists across income, wealth, consumption expenditure, and access to opportunities.
    2. Data Limitations: India lacks reliable and frequent income and wealth datasets. Consumption expenditure therefore becomes the primary proxy for measuring inequality.
    3. Methodological Changes: HCES 2023-24 introduced methodological modifications, making comparison with previous NSSO rounds difficult.
    4. Measurement Variations: World Bank estimates place India’s Gini coefficient at 0.25, while HCES-based estimates suggest a higher overall consumption inequality of 0.29.
    5. Sectoral Disaggregation: Urban inequality appears significantly higher once rural-urban and food-non-food distinctions are separately examined.
    6. Consumption Bias: Food expenditure shows lower inequality because food remains a basic necessity across classes.

    How does food and non-food expenditure reveal hidden inequality?

    1. Food Equality Effect: Food expenditure inequality remains relatively lower due to survival-driven consumption patterns.
    2. Non-Food Polarisation: Non-food expenditure shows significantly higher inequality in both urban and rural India.
    3. Urban Concentration: Urban non-food expenditure inequality is the highest among all categories.
    4. HCES Findings:
      1. Food expenditure Gini coefficient: approximately 0.25
      2. Non-food expenditure Gini coefficient: approximately 0.35-0.36
      3. Overall expenditure inequality: approximately 0.29
    5. Consumption Diversification: Richer households spend disproportionately on healthcare, education, digital services, transport, luxury goods, and recreation.
    6. Structural Indicator: Rising non-food inequality reflects unequal access to quality human development indicators.

    Why is urban India emerging as the epicentre of inequality?

    1. Growth Concentration: Most high-growth sectors are urban-centric, including finance, IT, services, logistics, and professional sectors.
    2. Urban Advantage: Mean urban expenditure exceeds the all-India average, while rural expenditure remains below it.
    3. Consumption Gap: Urban non-food Monthly Per Capita Expenditure (MPCE) stands at nearly 1.51 times the all-India average.
    4. Rural Lag: Rural non-food MPCE remains significantly lower at nearly 0.78 of the all-India average.
    5. Top-Decile Dominance: The richest 10% in urban India contribute nearly 27% of total non-food expenditure.
    6. Bottom-Decile Marginalisation: The same metric remains only around 4.5 times lower in rural India, indicating sharper urban inequality.
    7. Extreme Contrast: Mean MPCE of the richest urban decile is nearly nine times that of the poorest rural decile.
    8. Spatial Disparity: Urban prosperity increasingly coexists with informal labour vulnerability and rising living costs.

    How does class-based inequality deepen India’s growth paradox?

    1. Consumption-Based Class Divide: Inequality increasingly reflects divergence between spending classes rather than only interpersonal differences.
    2. Urban Professional Gains: Since the 1980s, urban owners, managers, and professionals have disproportionately benefited from economic growth.
    3. Stagnation of Informal Labour: Informal workers, agricultural labourers, and small farmers experienced comparatively limited gains.
    4. Class Inequality Persistence: Welfare expansion has not substantially reversed within-class inequality in urban India.
    5. Growth-Inequality Nexus: Economic liberalisation accelerated aggregate growth but also intensified concentration of gains.
    6. Non-Food Expenditure Concentration: Around 67% of non-food expenditure inequality arises from within-decile disparities.
    7. Food Expenditure Contribution: Nearly 33% of food expenditure inequality arises from within-decile disparities.
    8. Structural Dualism: India simultaneously experiences high-growth enclaves and low-income consumption traps.

    Why can lower inequality estimates produce misleading policy outcomes?

    1. Underestimation Risk: Consumption-based estimates may underestimate actual inequality because the richest households are often underrepresented in surveys.
    2. Policy Misalignment: Lower inequality estimates may weaken welfare urgency and social protection interventions.
    3. Welfare Retrenchment Concerns: Reduction in employment guarantees and labour protections could disproportionately affect informal workers.
    4. Poverty-Inequality Overlap:
      1. Around one-fourth of the richest 10% benefited from PMGKAY.
      2. Around 13% of them reportedly accessed BPL cards.
    5. Targeting Errors: Welfare leakages reveal institutional weaknesses in beneficiary identification.
    6. Social Stability Risks: Persistent inequality may intensify social fragmentation, urban distress, and political dissatisfaction.

    How does rural-urban disparity shape India’s development trajectory?

    1. Rural Consumption Constraint: Rural expenditure remains heavily food-oriented with limited discretionary spending.
    2. Urban Service Expansion: Urban economies benefit from greater access to finance, technology, education, and infrastructure.
    3. Human Capital Divide: Access to quality healthcare and education remains highly unequal across regions.
    4. Migration Pressures: Rural distress fuels migration toward cities without proportional employment generation.
    5. Regional Imbalance: Growth remains concentrated in select urban clusters and metropolitan regions.
    6. Development Asymmetry: Economic expansion has not ensured balanced regional transformation.

    Conclusion

    India’s growth story reflects a structural paradox where rapid economic expansion coexists with widening consumption inequality, especially in urban India and non-food expenditure. The findings from HCES 2023-24 indicate that economic gains remain concentrated among higher-income groups, while informal workers, rural households, and vulnerable classes continue to face limited upward mobility.

  • With 12 plants in phase one, India’s chip making mission sets sights on next frontier

    Why in the News? 

    The Union Cabinet approved two new semiconductor units in Gujarat (totaling 12 projects under Phase-I) under the India Semiconductor Mission (ISM) to boost domestic manufacturing. These include India’s first commercial Gallium Nitride (GaN)-based display facility by Crystal Matrix Limited and an OSAT unit by Suchi Semicon.

    Why Is India’s Semiconductor Push Considered a Strategic Turning Point?

    1. Strategic Autonomy: Reduces dependence on imported semiconductors used in telecom, defence, automobiles, AI systems, and consumer electronics.
    2. Supply Chain Security: Strengthens resilience after global chip shortages disrupted automobile, electronics, and industrial production during the COVID-19 period.
    3. Geopolitical Relevance: Positions India as an alternative manufacturing destination amid US-China technological decoupling and “China+1” diversification.
    4. Economic Value Addition: Expands domestic value addition in electronics manufacturing, which has remained heavily import-dependent despite growth in assembly operations.
    5. Technology Sovereignty: Facilitates indigenous capability in advanced manufacturing sectors such as AI chips, display drivers, sensors, power electronics, and compound semiconductors.
    6. Employment Generation: Supports high-skilled jobs in fabrication, packaging, design, testing, materials, and semiconductor equipment manufacturing.
    7. Industrial Ecosystem Expansion: Strengthens downstream sectors including smartphones, EVs, telecom equipment, defence electronics, medical devices, and industrial automation.

    What Is the India Semiconductor Mission (ISM)?

    Institutional Framework

    1. India Semiconductor Mission (ISM): Functions under the Ministry of Electronics and Information Technology (MeitY) as the nodal agency for semiconductor and display ecosystem development.
    2. Financial Support: Provides fiscal incentives for semiconductor fabs, display fabs, Assembly, Testing, Marking, and Packaging (ATMP)/Outsourced Semiconductor Assembly and Test (OSAT) facilities, compound semiconductors, and design-linked incentives.
    3. Strategic Objective: Ensures domestic semiconductor manufacturing capability across critical technology sectors.

    Key Components

    1. Semiconductor Fabrication: Supports wafer fabrication facilities for integrated circuit manufacturing.
    2. ATMP/OSAT Ecosystem: Facilitates assembly, testing, marking, packaging, and outsourced semiconductor services.
    3. Display Manufacturing: Expands domestic production of display drivers and display-related semiconductor components.
    4. Design Ecosystem: Supports fabless semiconductor startups and chip design innovation.
    5. Supply Chain Development: Encourages ecosystem creation in chemicals, gases, substrates, machinery, and clean-room technologies.

    Which Semiconductor Projects Have Been Approved Under Phase-I?

    Sl.No.Project NameDetails
    1.Tata Electronics Semiconductor Fab, GujaratInvestment: Involves approximately ₹91,000 crore investment.Technology Node: Targets 28-nanometre chip manufacturing capacity.Production Scale: Plans production of nearly 50,000 wafers across 28-nanometre to 110-nanometre technologies.Strategic Importance: Establishes India’s first commercial-grade chip foundry.Commercial Timeline: Expected commencement of commercial chip production from February next year.
    Tata Electronics Semiconductor Assembly Unit, AssamInvestment: Involves nearly ₹27,000 crore investment.Production Focus: Manufactures around 48 million chips daily for electronics, automotive, and telecom sectors.Regional Importance: Expands high-technology manufacturing to Northeast India.
    HCL-Foxconn Semiconductor Unit, Uttar PradeshInvestment: Includes nearly ₹3,700 crore investment.Production Capacity: Plans production of approximately 20,000 wafers per month.Technology Application: Focuses on display driver chips used in smartphones, laptops, vehicles, and industrial systems.Operational Timeline: Expected to begin operations by March 2026.
    Kaynes Semiconductor Unit, GujaratInvestment: Involves approximately ₹3,300 crore investment.Technology Focus: Produces chips for industrial applications.Production Capacity: Targets nearly 60 lakh chips per day.
    CG Semi OSAT Facility, GujaratTechnology Focus: Provides semiconductor assembly and testing services.Strategic Role: Strengthens India’s backend semiconductor manufacturing ecosystem.
    ISMC Semiconductor Facility, KarnatakaInvestment: Estimated at nearly ₹22,900 crore.Technology Focus: Targets advanced semiconductor fabrication capabilities.
    3D Glass Solutions, OdishaTechnology Focus: Establishes India’s first advanced 3D chip packaging unit.Strategic Importance: Enhances advanced semiconductor packaging capability using indigenous technologies.
    Advaned System Package Technologies (ASPT), Andhra PradeshTechnology Partnership: Collaborates with South Korea’s APACK Co. Ltd.Production Focus: Manufactures advanced semiconductor packaging products.
    Continental Device India (CDIL), PunjabTechnology Focus: Manufactures discrete semiconductors including power electronics components.Industrial Importance: Supports EVs, renewable energy systems, and industrial electronics.
    Crystal Matrix Laboratories, GujaratInvestment: Involves approximately ₹3,068 crore.Production Focus: Manufactures semiconductor substrates and materials

    Why Is Semiconductor Manufacturing Critical for India’s Economy?

    1. Electronics Manufacturing Expansion
      1. Import Reduction: India imports a major share of semiconductor requirements despite becoming a major electronics assembly hub.
      2. Domestic Value Addition: Semiconductor manufacturing increases local value addition beyond assembly operations.
      3. Export Competitiveness: Strengthens India’s role in global electronics exports.

    Strategic and National Security Importance

    1. Defence Electronics: Supports indigenous missile systems, radars, drones, communication systems, and surveillance infrastructure.
    2. Critical Infrastructure: Ensures supply security for telecom networks, power grids, and digital infrastructure.
    3. Cyber Security: Reduces vulnerabilities associated with excessive import dependence.

    Emerging Technology Integration

    1. Artificial Intelligence: Supports AI accelerators, edge computing, and data-centre infrastructure.
    2. Electric Vehicles: Enables production of power semiconductors and automotive chips.
    3. 5G and Telecom: Strengthens telecom equipment manufacturing ecosystem.
    4. Renewable Energy: Supports solar inverters, battery management systems, and smart-grid technologies.

    What Structural Challenges Continue to Constrain India’s Semiconductor Ambitions?

    1. Capital Intensity
      1. High Investment Requirement: Semiconductor fabs require investments running into billions of dollars with long gestation periods.
      2. Technology Upgradation: Rapid obsolescence demands continuous reinvestment.
    2. Technological Dependence
      1. Foreign Technology Reliance: India remains dependent on external partners for advanced process technologies and equipment.
      2. Limited IP Ownership: Indigenous semiconductor intellectual property ecosystem remains underdeveloped.
    3. Infrastructure Constraints
      1. Power Reliability: Semiconductor fabs require uninterrupted high-quality power supply.
      2. Water Availability: Wafer fabrication is highly water-intensive.
      3. Logistics Ecosystem: Semiconductor manufacturing requires sophisticated supply-chain precision.
    4. Skilled Workforce Gaps
      1. Talent Shortage: India requires specialised semiconductor engineers, fabrication experts, and materials scientists.
      2. Research Deficit: Limited semiconductor-focused R&D ecosystem constrains innovation.
    5. Global Competition
      1. Subsidy Race: Competes against aggressive semiconductor incentives in the US, China, Taiwan, South Korea, Japan, and the EU.
      2. Economies of Scale: Established global players possess technological and market advantages.

    How Can India Strengthen Its Semiconductor Ecosystem Further?

    1. Ecosystem Development
      1. Ancillary Manufacturing: Expands domestic production of chemicals, gases, wafers, substrates, and semiconductor machinery.
      2. Cluster-Based Development: Facilitates integrated semiconductor manufacturing zones.
    2. Research and Innovation
      1. R&D Investment: Strengthens semiconductor research institutions and university-industry collaboration.
      2. Design Capability: Expands indigenous fabless chip design ecosystem.
    3. Human Resource Development
      1. Skill Ecosystem: Develops semiconductor-focused engineering and vocational programmes.
      2. Global Talent Partnerships: Facilitates collaboration with international semiconductor experts.
    4. International Partnerships
      1. Technology Collaboration: Expands strategic partnerships with trusted semiconductor economies.
      2. Supply Chain Integration: Integrates India into resilient global semiconductor networks.

    Conclusion

    India’s semiconductor mission marks a transition from assembly-led electronics manufacturing to strategic technology production. Phase-I approvals indicate movement toward an integrated semiconductor ecosystem spanning fabrication, packaging, display technologies, and materials. Long-term success will depend on ecosystem depth, skilled workforce creation, infrastructure reliability, technological partnerships, and sustained policy support.

    PYQ Relevance

    [UPSC 2017] Account for the failure of the manufacturing sector in achieving the goal of labour-intensive exports rather than capital-intensive exports. Suggest measures for more labour-intensive rather than capital-intensive exports

    Linkage: The semiconductor mission reflects India’s attempt to strengthen high-technology manufacturing and reduce import dependence under industrial policy reforms. The topic links with challenges in manufacturing competitiveness, technology ecosystems, skilled labour, global value chains, and Make in India-led industrial growth.

  • [6th  May 2026] The Hindu OpED: RE meets global electicity demand for the first time

    PYQ Relevance[UPSC 2015] To what factors can the recent dramatic fall in equipment costs and tariff of solar energy be attributed? What implications does the trend have for the thermal power producers and the related industry?
    Linkage: The question examines the reasons behind declining solar energy costs and its impact on conventional thermal power generation. The article shows that cheaper solar and wind energy enabled renewables to meet global electricity demand growth for the first time, reducing coal dependence globally.

    Mentor’s Comment

    The global energy transition reached a historic turning point in 2025 as renewable energy (RE) met almost the entire rise in global electricity demand for the first time. This marks a sharp departure from the fossil fuel-led growth pattern that dominated industrial expansion for over two centuries. However, the article simultaneously exposes a major contradiction in India’s energy transition: while renewable electricity capacity is rising rapidly, dependence on imported crude oil, LNG, and LPG from West Asia remains deeply entrenched. The closure of the Strait of Hormuz during the Iran-Israel conflict highlighted India’s strategic vulnerability, causing spikes in crude prices, disruptions in LNG supply, and pressure on domestic energy security.

    Why Is the Global Renewable Energy Transition Being Considered a Historic Turning Point?

    1. Historic Shift: Renewable energy met almost the entire increase in global electricity demand in 2025 for the first time in history.
    2. Electricity Growth: Global electricity generation increased by nearly 850 terawatt-hours (TWh) in 2025.
      1. Solar Contribution: Solar energy alone contributed 636 TWh of additional electricity generation.
      2. Wind Contribution: Wind energy added another 204 TWh globally.
      3. Other Renewables: Additional renewable sources contributed nearly 23 TWh.
    3. Fossil Fuel Decline: Coal generation fell by 67 TWh globally, while oil generation declined by 12 TWh.
      1. Structural Change: Expanded electricity demand no longer required a corresponding increase in fossil fuel consumption.
      2. Energy Transition Milestone: Coal generation declined in absolute terms globally for the first time despite rising electricity demand.
    4. Cost Decline: Sharp reductions in solar panel costs, battery storage prices, and grid integration costs accelerated renewable adoption.
    5. China’s Role: China recorded a 5% rise in electricity demand while simultaneously expanding clean energy generation significantly.
      1. China’s Solar Expansion: Solar energy generation in China rose by nearly 40% compared to 2024.
      2. China’s Wind Expansion: Wind generation in China increased by nearly 14%.
    6. Demand Coverage: Solar energy alone met almost two-thirds of the increase in China’s electricity demand.

    Why Does Fossil Fuel Dependence Continue Despite Rapid Renewable Expansion?

    1. Absolute Demand Growth: Global electricity demand continued rising faster than renewable expansion for most of the last two decades.
    2. Base Load Dependence: Coal and gas remained essential for stable baseload electricity supply.
    3. Industrial Dependence: Heavy industries, transport, and petrochemicals continued relying on fossil fuels.
    4. Energy Storage Constraints: Battery storage infrastructure remains insufficient for complete renewable substitution.
    5. Grid Limitations: Renewable integration requires advanced transmission and balancing infrastructure.
    6. India’s Energy Mix: Coal remains India’s dominant energy source despite renewable growth.
      1. Energy Composition: Coal accounts for nearly 60.21% of India’s energy sources.
      2. Renewable Share: Renewables constitute around 29.83% of India’s energy mix.
      3. Oil Dependence: India imports nearly 89% of its crude oil requirements.
      4. Natural Gas Dependence: India imports around 47% of its natural gas needs.
      5. Coal Imports: India imports approximately 26% of coal despite being the world’s third-largest coal producer.

    How Did the West Asian Conflict Expose India’s Energy Vulnerabilities?

    1. Geopolitical Shock: The Iran-Israel conflict triggered the closure of the Strait of Hormuz in March 2026.
    2. Strategic Importance: The Strait handles a major share of global oil and gas shipments.
    3. Import Exposure: India imports significant crude supplies from Qatar, UAE, and Saudi Arabia.
      1. Crude Import Decline: India’s crude imports fell by 17% year-on-year in March 2026.
      2. Import Volume: Crude imports dropped to 18.9 million tonnes compared to 22.8 million tonnes in March 2025.
    4. Price Shock: Indian basket crude prices increased from $72.47 per barrel in March 2025 to $113.49 per barrel in March 2026.
    5. Inflationary Impact: Rising crude prices increased import bills and inflationary pressure.
    6. Domestic Shortfall: Domestic natural gas production declined by 4.9%.
    7. Import Compensation: LNG imports rose by 20.5% to offset supply shortages.
    8. Record LNG Imports: India’s LNG imports reached 27 million metric tonnes in 2024-25, the highest on record. LPG imports rose to 18 million metric tonnes in 2025-26 from 16.48 million metric tonnes in 2020-21.
    9. PMUY Expansion: Pradhan Mantri Ujjwala Yojana (PMUY) increased LPG access from 62% of households in 2016 to nearly 100% by 2025.
    10. Retail Price Increase: LPG cylinder prices increased by ₹60 after the conflict began.
    11. Fiscal Burden: India allocated nearly ₹30,000 crore to oil marketing companies in FY 2025-26 to cushion LPG losses.

    Why Has Renewable Capacity Growth Not Yet Ensured Energy Independence?

    1. Electricity vs Total Energy: Renewable growth primarily addresses electricity generation, not transport fuels or industrial fuels.
    2. Infrastructure Lag: Renewable capacity addition takes years to translate into stable energy supply.
      1. Storage Gap: Large-scale battery storage systems remain expensive and underdeveloped.
      2. Capacity Utilisation: Solar and wind generation remain intermittent and weather-dependent.
    3. Immediate Supply Constraints: Fossil fuel systems continue providing emergency and peak-load energy support.
    4. Short-Term Dependence: During the Hormuz crisis, India relied on coal and gas infrastructure instead of renewables.
    5. Import Continuity: India accelerated LNG and LPG imports from alternate suppliers during the disruption.
    6. Energy Security Challenge: Renewable growth has reduced emissions intensity but not eliminated fossil fuel import dependence.
    7. Transition Complexity: Clean electricity expansion alone cannot ensure strategic energy autonomy.

    How Is India Responding to the Emerging Energy Security Challenge?

    1. Renewable Expansion: India’s renewable energy capacity increased by over 210% during the last decade.
    2. Capacity Addition: Renewable energy accounted for nearly 89% of India’s new capacity additions in FY 2024-25.
    3. Diversification Strategy: India increased procurement from alternate fossil fuel suppliers.
    4. Domestic Prioritisation: Domestic energy users received supply prioritisation during disruptions.
    5. Coal Maximisation: Existing coal infrastructure operated at higher output levels during the crisis.
    6. Gas Infrastructure Use: Existing gas facilities were used to stabilise short-term supply.
    7. Strategic Reserves: India expanded focus on petroleum reserve management.
    8. Energy Diplomacy: Greater emphasis emerged on diversified import partnerships.
    9. Grid Modernisation: Renewable integration requires stronger transmission networks and storage systems.
    10. Battery Ecosystem: India is accelerating battery manufacturing and storage infrastructure development.

    What Are the Major Implications for India’s Energy Transition and Climate Strategy?

    1. Climate Significance: Renewable growth reduced global dependence on fossil fuels for incremental electricity demand.
    2. Energy Security Lesson: Clean energy transition without import diversification remains strategically vulnerable.
    3. Economic Risk: Fossil fuel import shocks increase inflation and current account pressures.
    4. Geopolitical Exposure: India’s energy dependence links domestic stability with West Asian geopolitics.
    5. Policy Contradiction: Renewable capacity leadership coexists with high fossil fuel import dependence.
    6. Transition Requirement: Energy transition must include storage, grid reform, green hydrogen, and transport electrification.

    Conclusion

    The global energy transition reached a historic milestone in 2025 as renewables met the entire rise in electricity demand for the first time. However, India’s continued dependence on imported crude oil, LNG, and LPG highlights that renewable expansion alone cannot ensure energy security. India must combine clean energy growth with storage, grid reforms, strategic reserves, green hydrogen, and import diversification to achieve secure and resilient decarbonisation.

  • India may expand LNG storage to manage future supply crisis

    Why in the News?

    The disruption of Liquefied Natural Gas (LNG) supplies due to tensions in the Strait of Hormuz has revived concerns about India’s energy security. India, which depends heavily on LNG imports for nearly half its gas requirements, lacks adequate storage infrastructure. This has prompted discussions on expanding LNG storage capacity to cushion future supply shocks.

    Why is India considering expanding LNG storage capacity now?

    1. Geopolitical Disruption: Closure of the Strait of Hormuz halted LNG cargo flows; no shipment reached India for over two months.
    2. Critical Dependence: Around 50% of India’s natural gas demand is met through LNG imports.
    3. Chokepoint Vulnerability: Nearly 60% of LNG imports pass through the Strait of Hormuz, exposing supply chains to geopolitical risks.
    4. First Major Shock: This disruption was earlier considered “extremely improbable” but has now materialised.
    5. Policy Shift: Moves away from minimal storage model toward strategic reserves, similar to crude oil reserves.

    What is the current status of LNG storage infrastructure in India?

    1. Limited Storage Capacity: India has only 23 LNG tanks across terminals.
    2. Company Share: Petronet LNG accounts for 10 tanks, indicating concentrated capacity.
    3. Terminal Distribution: Dahej terminal (Gujarat) has 8 tanks; Kochi has 2 tanks.
    4. Operational Limitation: Tanks designed for regasification operations, not long-term storage.
    5. Consumption Ratio: One LNG tank holds approximately one LNG shipment, while daily consumption equals 1.25 tanks/day.

    Why is LNG storage expansion challenging in India?

    1. Cryogenic Requirement: LNG must be stored at extremely low temperatures (-162°C), increasing complexity.
    2. High Capital Cost: Construction is significantly more expensive than conventional fuel storage.
    3. Time-Intensive Projects: New tanks require at least 3 years for completion.
    4. Land Constraints: Coastal land availability limits expansion of terminals.
    5. Regulatory Delays: Multiple approvals slow down infrastructure development.

    How does LNG storage compare with India’s crude oil reserves?

    1. Strategic Oil Reserves: India maintains strategic petroleum reserves (SPR) for crude oil.
    2. LNG Gap: No equivalent strategic LNG reserves exist.
    3. Policy Asymmetry: Oil security planning is institutionalised; gas security remains market-driven.
    4. Operational Focus: LNG storage currently supports continuous supply, not emergency buffering.
    5. Need for Transition: Shift required toward strategic LNG stockpiling model.

    What are the economic and sectoral implications of LNG disruptions?

    1. Supply Prioritisation: Gas diverted to transportation and households, industries faced rationing.
    2. Industrial Impact: Reduced gas availability affected manufacturing output.
    3. Price Volatility: LNG shortages lead to increased global spot prices.
    4. Import Diversification Limits: India attempted alternative sourcing but faced constraints.
    5. Energy Transition Risk: Gas-based economy plans disrupted due to unreliable supply.

    What role are key institutions like Petronet LNG playing?

    1. Capacity Expansion Plans: Petronet LNG plans to increase storage capacity by ~70%.
    2. New Infrastructure: Proposal to add two additional tanks at Dahej terminal.
    3. Land Assessment: Ongoing feasibility checks for expansion.
    4. Strategic Awareness: Industry stakeholders acknowledging need for resilience.
    5. Execution Timeline: Projects remain in planning phase; timelines uncertain.

    Conclusion

    India’s LNG vulnerability highlights a structural gap in energy security architecture. Expanding LNG storage capacity is essential to reduce exposure to geopolitical disruptions, ensure industrial stability, and support long-term energy transition goals. A strategic shift toward integrated gas security planning is required.

    PYQ Relevance

    [UPSC 2018] Access to affordable, reliable, sustainable and modern energy is the sine qua non to achieve Sustainable Development Goals (SDGs). Comment on the progress made in India in this regard.

    Linkage: LNG storage gaps highlight India’s vulnerability in ensuring reliable and affordable energy access, a core component of SDG-linked energy security. Expanding LNG storage strengthens energy infrastructure resilience, directly aligning with UPSC focus on energy security and sustainable growth.