💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Economics

  • The challenge for India’s renewables surge: Storage

    Why in the News?

    India’s renewable energy capacity has expanded rapidly, with renewables contributing more than half of India’s installed power capacity for the first time. However, this growth has exposed a major challenge: energy storage. As renewable energy use increases, inadequate storage systems are creating concerns over grid stability and reliable electricity supply. The issue has become more important as India aims to achieve 500 GW renewable energy capacity by 2030, but storage infrastructure remains insufficient.

    How does inadequate storage undermine India’s renewable energy transition?

    1. Intermittency Problem: Solar generation ceases after sunset, while wind output fluctuates according to weather conditions. This creates instability in electricity availability.
    2. Demand-Supply Mismatch: Electricity demand often peaks during evening hours, whereas solar generation remains concentrated during daytime, creating temporal imbalance.
    3. Grid Stability Risks: Large-scale renewable integration without storage increases frequency fluctuations and voltage instability, affecting grid reliability.
    4. Renewable Curtailment: Surplus renewable electricity often remains unused during periods of excess generation due to inadequate storage infrastructure.
    5. Thermal Dependence: Limited storage necessitates continued dependence on thermal power plants for balancing electricity demand.

    Why has energy storage become central to India’s power transition?

    1. Renewable Expansion: Renewable energy now accounts for more than half of India’s installed power capacity, indicating a structural shift in the energy mix.
    2. 2030 Energy Target: India aims to achieve 500 GW of renewable energy capacity by 2030, making storage essential for effective grid integration.
    3. Peak Demand Management: Storage systems release electricity during high-demand periods, reducing shortages and supply disruptions.
    4. Energy Security: Domestic storage capacity reduces dependence on imported fossil fuels and strengthens energy resilience.
    5. Net-Zero Pathway: Reliable storage facilitates deeper renewable penetration and supports long-term decarbonisation commitments.

    What are the major energy storage technologies available to India?

    1. Pumped Hydro Storage (PHS)
      1. Operating Mechanism: Stores electricity by pumping water to an elevated reservoir during surplus generation and releasing it through turbines during peak demand.
      2. Established Technology: Represents the most mature and widely deployed large-scale storage technology globally.
      3. Installed Capacity: India currently possesses nearly 7.2 GW of pumped hydro storage capacity.
      4. Future Expansion: The Central Electricity Authority (CEA) projects nearly 94 GW of PHS capacity by 2035-36.
      5. Key Advantage: Ensures long-duration storage and utility-scale grid balancing.
    2. Battery Energy Storage Systems (BESS)
      1. Technology Base: Primarily relies on Lithium-Ion Phosphate (LFP) batteries, recognised for declining costs, higher efficiency and longer life cycles.
      2. Operating Mechanism: Stores electricity during surplus renewable generation and discharges power when output declines.
      3. Current Capacity: India currently possesses nearly 0.27 GW battery storage capacity.
      4. Projected Requirement: Battery storage requirement is projected to reach nearly 80 GW by 2035-36.
      5. Auction Momentum: Around 10,658.94 MW / 28,739.32 MWh of BESS capacity remains under implementation.
      6. Pipeline Expansion: Nearly 22,347.15 MW / 69,836.70 MWh projects remain under tendering.
    3. Emerging Storage Technologies
      1. Concentrated Solar Thermal Storage: Uses mirrors to concentrate sunlight and heat molten salts, enabling electricity generation during non-solar hours.
      2. Compressed-Air Energy Storage: Stores compressed air underground during excess generation and releases it to produce electricity during peak demand.
      3. Flywheel Energy Storage: Stores rotational kinetic energy and supports short-duration grid frequency regulation.
      4. Gravity Energy Storage: Converts gravitational potential energy into electricity by lifting and lowering heavy masses.

    Why is India falling short in energy storage deployment?

    1. Slow Deployment Pace: Storage installation has not kept pace with rapid renewable capacity expansion.
    2. Import Dependence: India imports nearly 75-80% of lithium-ion cells, creating supply-chain vulnerability.
    3. High Cost Structure: Battery systems account for nearly 90% of total storage project costs, affecting affordability.
    4. Policy Gaps: Long-term resource adequacy planning for storage remains insufficient.
    5. Critical Mineral Dependence: Dependence on imported lithium, cobalt and rare earth minerals exposes India to geopolitical risks.

    How prepared is India institutionally for large-scale renewable integration?

    1. CEA Planning: The National Electricity Plan (NEP) projects a requirement of nearly 47 GW / 188 GWh battery storage and 94 GW / 676 GWh pumped hydro capacity by 2035-36.
    2. Transmission Expansion: Grid infrastructure requires substantial expansion for integrating variable renewable energy.
    3. Power System Flexibility: Smart grids, flexible thermal generation and demand-side management remain necessary.
    4. Domestic Manufacturing Push: Production Linked Incentive (PLI) schemes seek to strengthen indigenous battery manufacturing capacity.

    How does India compare globally in energy storage deployment?

    1. Pumped Hydro Leadership: China leads globally with nearly 360 GW installed PHS capacity, while India remains significantly behind.
    2. Battery Storage Growth: Global battery storage capacity reached nearly 270 GW, with projections of 1,080 GW by 2030.
    3. Chinese Dominance: China accounts for nearly 60% of global battery storage deployment, followed by Europe, Australia and the United States.
    4. Regional Momentum: Rapid deployment increasingly supports renewable-heavy grids worldwide.

    What are the policy alternatives for strengthening India’s storage ecosystem?

    1. Domestic Manufacturing: Strengthens battery ecosystems through PLI incentives and domestic mineral processing.
    2. Critical Mineral Strategy: Ensures secure overseas access to lithium, cobalt and nickel reserves.
    3. Market Mechanisms: Facilitates storage viability through time-of-day pricing and ancillary service markets.
    4. Hybrid Renewable Projects: Integrates solar, wind and storage for round-the-clock electricity supply.
    5. Research and Innovation: Supports emerging technologies such as sodium-ion and solid-state batteries.
    6. Regulatory Reforms: Ensures long-term procurement frameworks and storage deployment certainty.

    Conclusion

    India’s renewable energy transition now depends not only on increasing generation capacity but also on strengthening energy storage systems. Rapid expansion of solar and wind power without adequate storage can undermine grid stability and energy reliability. Expanding battery storage, pumped hydro capacity and domestic manufacturing, along with regulatory support, will be critical to ensuring a stable, secure and sustainable clean energy transition.

    Government Policies and Schemes Supporting Energy Storage in India
    National Framework for Promoting Energy Storage Systems (2023): It provides the overall policy framework for integrating energy storage into generation, transmission and distribution systems. It recognises storage as a key enabler of renewable energy integration.
    PLI Scheme for Advanced Chemistry Cell (ACC) Battery Storage (2021): Supports domestic battery manufacturing through a ₹18,100 crore Production Linked Incentive (PLI) programme. Targets establishment of 50 GWh ACC battery manufacturing capacity to reduce import dependence on lithium-ion batteries.
    Viability Gap Funding (VGF) Scheme for Battery Energy Storage Systems (BESS): Provides financial support to make battery storage commercially viable and accelerate grid-scale deployment of BESS projects. Operational guidelines were issued in 2024.
    Tariff-Based Competitive Bidding (TBCB) Guidelines for BESS (2022): Enables transparent procurement of storage capacity by power distribution companies and improves investor confidence.
    Energy Storage Obligation (ESO): Mandates power utilities to integrate a minimum share of energy storage alongside renewable procurement to ensure grid reliability and peak balancing.
    Green Energy Corridor Programme: Expands transmission infrastructure to facilitate integration of renewable energy and storage systems into the national grid.
    ISTS Charges Waiver for Renewable + Storage Projects: Waives inter-state transmission charges for co-located renewable energy and storage projects, improving project viability.

    PYQ Relevance

    [UPSC 2022] Do you think India will meet 50 percent of its energy needs from renewable energy by 2030? Justify your answer. How will the shift of subsidies from fossil fuels to renewables help achieve the above objective? Explain

    Linkage: The PYQ tests understanding of India’s renewable energy transition, structural bottlenecks and policy support required for achieving energy targets. The article expands the debate beyond renewable generation to issues of grid stability, intermittency and reliable power supply.
  • [16th May 2026] The Hindu OpED: Productivity, and not just growth, for Viksit Bharat

    PYQ Relevance[UPSC 2023] Faster economic growth requires increased share of the manufacturing sector in GDP, particularly of MSMEs. Comment on the present policies of the Government in this regard.Linkage: Tests understanding of manufacturing-led growth, productivity enhancement, MSMEs, industrial policy, and employment generation. India’s growth cannot sustain without productive manufacturing expansion and scalable firms, highlighting the “missing middle” problem.

    Mentor’s Comment

    The debate on India’s growth model has gained significance as the Economic Survey 2025-26 places manufacturing at the centre of India’s next development phase. This signals a shift from growth-led optimism to productivity-led structural reform. This marks a contrast with the post-pandemic period, where India relied heavily on strong domestic demand, macroeconomic stability, and services-led growth. The issue is significant because despite being among the fastest-growing major economies, India continues to face manufacturing inefficiencies, labour concentration in low-productivity agriculture, and rising firm-level distress.

    Why is economic growth alone insufficient for achieving Viksit Bharat?

    1. Macroeconomic Stability: India maintained relatively high growth with subdued inflation, gradual fiscal consolidation, and a stable financial sector, ensuring post-pandemic resilience.
    2. Growth Limitation: Sustained long-term growth requires higher productivity in labour, capital, and production systems, not merely aggregate GDP expansion.
    3. Structural Reform Requirement: Transition to Viksit Bharat demands activation of all growth engines through institutional reforms, efficient resource allocation, and productivity enhancement.
    4. Productivity Imperative: Growth without productivity gains risks declining competitiveness, weak income expansion, and stagnation in employment generation.

    Why has manufacturing failed to become the bridge for structural transformation in India?

    1. Manufacturing Deficit: India’s structural transformation remains skewed as services expanded rapidly without proportional manufacturing deepening, limiting labour absorption.
    2. Employment Challenge: Manufacturing failed to absorb surplus labour from agriculture at scale, unlike successful East Asian industrialisation experiences.
    3. Low Productivity Concern: Manufacturing productivity remains below potential despite infrastructure expansion and policy support.
    4. Economic Survey Observation: The Economic Survey 2025-26 identifies manufacturing as central to sustaining growth and employment generation, particularly for large-scale workforce absorption.
    5. Structural Instability: Overdependence on services weakens long-term resilience because services alone cannot generate broad-based productivity gains across the economy.

    How does India’s firm structure constrain productivity growth?

    1. Fragmented Enterprise Base: India’s manufacturing ecosystem consists of large numbers of small, low-productivity firms and relatively few scalable medium-sized enterprises.
    2. Missing Middle Problem: Weak emergence of medium and large firms contrasts sharply with East Asian economies, where industrial growth was driven by competitive export-oriented firms.
    3. Scaling Constraint: Regulatory complexity, labour rigidities, and financing barriers prevent efficient firms from expanding.
    4. Efficiency Loss: Weak firm dynamism restricts efficient factor allocation and slows productivity improvement.
    5. Labour Misallocation: A substantial workforce remains in low-productivity agriculture, reducing economy-wide productivity growth.

    How do zombie firms undermine economic efficiency and productivity?

    1. Zombie Firms: Economically unviable firms continue operations despite weak fundamentals, preventing efficient reallocation of labour and capital.
    2. Creative Destruction Failure: Productivity growth weakens when newer productive firms fail to replace inefficient firms.
    3. Capital Lock-in: Zombie firms absorb disproportionate shares of debt and assets, reducing credit availability for productive enterprises.
    4. Research Evidence: The paper “Zombie Firms in Emerging Markets: Survival and Funding Mechanisms” (2025) highlights that zombie firms account for a relatively small share of firms but disproportionately hold larger shares of debt and assets.
    5. Financial Distress Persistence: Deterioration begins before firms become classified as zombies, and bank-financed firms remain distressed longer and relapse more often.
    6. Equity Financing Advantage: Equity-financed firms display relatively greater resilience and sustainable recovery.

    Why is inefficient financial intermediation emerging as a structural challenge?

    1. Credit Misallocation: Financial systems often sustain inefficient firms instead of facilitating market exit.
    2. Institutional Weakness: Weak insolvency resolution and delayed restructuring reduce productivity-enhancing capital movement.
    3. Crowding-Out Effect: Lending to distressed firms restricts credit access for innovative and productive firms.
    4. Regulatory Constraint: Slow business exit mechanisms weaken industrial competitiveness and productivity growth.

    What manufacturing-led strategy is required for Viksit Bharat?

    1. Scale Expansion: India requires deeper manufacturing expansion capable of generating employment and productivity simultaneously.
    2. Global Value Chains (GVCs): Stronger integration into global production networks ensures export competitiveness and industrial upgrading.
    3. Trade Barrier Rationalisation: Lower frictions strengthen competitiveness and facilitate participation in global manufacturing systems.
    4. Infrastructure Efficiency: Continued infrastructure investment must focus on efficiency gains, not only physical expansion.
    5. Business Dynamism: Productive firms require easier growth conditions, while inefficient firms require smoother exit mechanisms.
    6. Regulatory Simplification: Reduced compliance burdens facilitate industrial scaling and formalisation.
    7. Credit Access: Better financial allocation strengthens investment in productive sectors.
    8. Research and Development: Innovation capacity improves productivity and technological competitiveness.

    How can productivity become the foundation of India’s long-term development model?

    1. Factor Productivity: Higher efficiency in labour and capital utilisation ensures sustainable growth.
    2. Structural Transformation: Labour movement from low-productivity agriculture to higher-productivity manufacturing and services strengthens income generation.
    3. Competitive Industrialisation: Manufacturing productivity enhances exports, wages, and employment resilience.
    4. Institutional Reform: Efficient insolvency systems, financial reforms, and business facilitation strengthen long-term competitiveness.
    5. Viksit Bharat Goal: Growth provides momentum, but productivity determines whether India can sustain high-income transition by 2047.

    Conclusion

    India’s post-pandemic growth performance provides a strong foundation for Viksit Bharat. However, the next phase of development depends on whether growth translates into higher productivity, competitive manufacturing, efficient resource allocation, and stronger business dynamism. Sustained prosperity will require India to move beyond GDP expansion toward a productivity-led development model rooted in structural reforms and industrial competitiveness.

  • Why spike in crude oil price will test the economy

    Why in the News?

    The sudden spike in global crude oil prices due to the intensifying West Asia crisis has reintroduced a familiar vulnerability in India’s macroeconomic landscape. Brent crude crossing the psychological threshold of $100 per barrel again raises concerns over inflation, trade deficits, fiscal stress, and slowing growth. The impact is already becoming visible domestically, with petrol and diesel prices witnessing an upward revision in India.

    Why has the recent rise in crude oil prices become a major concern for India?

    1. West Asia Crisis: Escalation of geopolitical tensions in West Asia has pushed crude prices upward and revived fears of supply disruptions.
    2. Psychological Threshold: Crude oil prices crossed the $100 per barrel mark again after years of relative moderation, triggering concerns over inflation and fiscal stress.
    3. High Import Dependence: India imports nearly 85% of its crude oil requirement, making the economy highly vulnerable to external price shocks.
    4. Economy-Wide Transmission: Higher crude prices affect fuel costs, transportation, food inflation, industrial production, trade deficit, currency stability, and fiscal expenditure simultaneously.
    5. Historical Vulnerability: India’s periods of macroeconomic stress, especially inflation and widening external imbalances, have often coincided with sustained crude price surges.

    How have crude oil prices historically influenced India’s macroeconomic performance?

    1. Growth Linkage: India witnessed stronger growth during phases of lower crude prices. Between 2014-16, crude declined sharply, creating fiscal and inflationary space.
    2. High-Price Impact: During 2006-08, when oil prices remained elevated, India faced higher inflationary pressures and macroeconomic vulnerabilities.
    3. Data Trend: Indian Express data shows crude prices moved from $113.5/barrel (2011-12) to nearly $46.2/barrel (2015-16), easing inflationary pressures.
    4. Growth Effect: Higher crude prices reduce disposable income and increase production costs, thereby moderating economic growth.
    5. Recent Stability: Since 2014, global crude prices largely remained below $100/barrel, allowing India to manage inflation and growth more effectively.

    How do higher crude oil prices transmit inflation across the economy?

    1. Fuel Inflation: Petrol and diesel prices rise directly when crude prices increase.
    2. Cost-Push Inflation: Transportation costs increase, raising prices of food items, manufactured goods, logistics, and services.
    3. Wholesale Inflation: Higher energy input costs increase Wholesale Price Index (WPI) inflation.
    4. Consumer Inflation: Fuel inflation eventually transmits into Consumer Price Index (CPI) inflation through higher daily consumption costs.
    5. Historical Evidence: During periods of elevated crude prices, inflation consistently remained higher than periods of low oil prices.
    6. Policy Concern: Persistent inflation complicates the task of the Reserve Bank of India (RBI) in maintaining its inflation target of 4% (+/-2%).

    Relevant Data 

    1. 2011-12: Crude oil basket at $113.5/barrel; wholesale inflation at 8.95%.
    2. 2015-16: Crude oil basket declined to $46.2/barrel; wholesale inflation turned negative at -3.65%.
    3. 2022–23: Crude oil at $93.4/barrel; wholesale inflation rose to 9.41%.

    How do rising crude prices affect India’s trade balance and exchange rate?

    1. Import Bill Expansion: Higher crude prices increase India’s oil import expenditure significantly.
    2. Trade Deficit: Since petroleum imports constitute a major share of imports, rising crude widens the trade deficit.
    3. Current Account Pressure: Persistent trade deficits increase Current Account Deficit (CAD) risks.
    4. Currency Depreciation: Higher dollar demand for oil imports weakens the rupee against the US dollar.
    5. Data: Trade deficit as a percentage of GDP moved from -10.07% (2011-12) to -5.62% (2015-16) as crude prices moderated.
    6. Exchange Rate Impact: Rupee depreciation further raises import costs, creating a feedback loop of imported inflation.

    Why do rising crude oil prices strain government finances?

    1. Fiscal Deficit Pressure: Governments face pressure to reduce fuel taxes or increase subsidies during periods of high fuel prices.
    2. Subsidy Burden: LPG, fertiliser, and welfare expenditures rise indirectly due to higher energy costs.
    3. Borrowing Requirement: Higher expenditure increases government borrowing requirements.
    4. Debt Servicing: Increased borrowing adds long-term fiscal stress.
    5. Evidence: Fiscal deficit remained elevated during years of higher oil prices and improved relatively during lower-price periods.
    6. Recent Concern: Fiscal consolidation efforts may become difficult if crude sustains above $100/barrel.

    Can India absorb another prolonged crude oil shock?

    1. Improved Resilience: India today possesses stronger foreign exchange reserves, diversified import partners, and better inflation management mechanisms.
    2. Strategic Petroleum Reserve (SPR): India maintains reserves to cushion short-term supply disruptions.
    3. Diversified Sourcing: Increased imports from countries such as Russia have reduced immediate supply vulnerabilities.
    4. Persistent Vulnerability: Structural dependence on imported fossil fuels continues to expose India to geopolitical shocks.
    5. Energy Transition Constraint: Renewable energy expansion remains insufficient to immediately replace petroleum dependence.

    What are the broader implications for India’s economic growth?

    1. Consumption Slowdown: Rising fuel costs reduce household disposable income.
    2. Industrial Costs: Energy-intensive sectors face higher operational expenses.
    3. Investment Impact: Business uncertainty increases amid inflation and cost pressures.
    4. Growth Moderation: Elevated crude prices historically coincide with slower growth momentum.
    5. Double Challenge: India faces the simultaneous challenge of controlling inflation while sustaining economic growth.

    Conclusion

    The present crude oil surge represents more than a temporary price increase; it is a structural stress test for India’s macroeconomic stability. Inflation management, fiscal prudence, exchange-rate stability, and growth sustainability will depend on how long elevated crude prices persist. India’s long-term resilience lies in accelerating energy diversification while reducing structural dependence on imported fossil fuels.

    PYQ Relevance

    [UPSC 2018] How would the recent phenomena of protectionism and currency manipulations in world trade affect macroeconomic stability of India?

    Linkage: The PYQ tests understanding of how external global shocks affect India’s macroeconomic stability. A rise in crude oil prices widens India’s trade deficit, current account deficit, imported inflation, and exchange-rate pressures. Similar to protectionism or currency shocks, oil-price volatility represents an external economic vulnerability.

  • How tax relief on bond investments will help FPIs

    Why in the News?

    India is reportedly considering reducing the withholding tax on foreign portfolio investors (FPIs) investing in bonds from nearly 20% to the earlier concessional 5% rate. The move comes amid external vulnerabilities, especially rising crude oil prices, pressure on the current account deficit (CAD), and global uncertainty.

    How do bonds function as a financial instrument?

    1. Bond: A bond is a fixed-income financial instrument through which governments or companies borrow money from investors for a fixed period at a predetermined interest rate.
    2. Issuer-Investor Relationship: The bond issuer receives capital upfront, while the investor receives periodic interest payments (coupon) and repayment of principal at maturity.
    3. Government Securities (G-Secs): Bonds issued by the government to finance fiscal expenditure and public borrowing requirements.
    4. Corporate Bonds: Bonds issued by companies to raise funds for business expansion, infrastructure, or debt refinancing.
    5. Fixed Returns: Bonds generally provide relatively predictable returns compared to equities because they carry fixed interest obligations.

    What is meant by bond investment?

    1. Debt Investment: Bond investment refers to investing money in debt instruments in return for regular interest income and capital repayment at maturity.
    2. Interest Income: Investors earn periodic returns through coupon payments.
    3. Capital Appreciation: Bond prices may rise if interest rates decline, allowing investors to sell at higher prices.
    4. Portfolio Diversification: Institutional investors use bonds to reduce volatility and balance high-risk equity exposure.
    5. Sovereign Debt Market: In India, foreign investors primarily invest in government securities and rupee-denominated bonds.

    How do external sector pressures increase the need for foreign capital inflows?

    1. Current Account Vulnerability: Rising crude oil prices increase India’s import bill and widen the current account deficit, creating pressure on the external account.
    2. Forex Reserve Stability: Higher FPI inflows into debt markets strengthen foreign exchange reserves and improve India’s ability to manage external shocks.
    3. Capital Flow Requirement: Foreign debt inflows provide non-inflationary financing and reduce pressure on domestic borrowing requirements.
    4. Global Uncertainty: Volatile global financial conditions require India to maintain attractive investment conditions to sustain capital inflows.

    How does high withholding tax reduce India’s attractiveness for global bond investors?

    1. Tax Burden: Withholding tax directly reduces post-tax returns because it is deducted at source before income reaches foreign investors.
      1. Withholding Tax (WHT): Tax deducted at source on payments such as interest, dividends, royalties, and fees before remittance to recipients. Its purpose is to ensure upfront tax collection and reduce evasion.
    2. Relative Disadvantage: India’s withholding tax reverted to nearly 20% after July 2023, making India a relatively high-tax jurisdiction for global bond investors.
    3. Transaction Costs: Higher taxes reduce risk-adjusted returns and increase the effective cost of investing in Indian debt markets.
    4. Regulatory Frictions: Complex tax claims under Double Taxation Avoidance Agreements (DTAAs) increase compliance costs for FPIs.
    5. Liquidity Constraints: Tax deductions lock investor capital temporarily until refunds or tax credits are processed.

    What was India’s earlier concessional withholding tax regime?

    1. Policy Shift in 2012: India introduced a concessional 5% withholding tax in 2012 on interest earned by foreign investors from government securities and specified rupee-denominated bonds under Section 194LD of the Income Tax Act.
    2. Investment Incentive: The concessional regime ensured better post-tax returns and improved India’s attractiveness to global investors.
    3. Expiry of Regime: The concessional tax structure expired in July 2023, after which taxation reverted to approximately 20%.
    4. Policy Reconsideration: The government is now evaluating a restoration of lower rates to revive overseas debt inflows.

    How do international tax structures shape global capital allocation?

    1. Comparative Taxation: Global investors allocate capital by comparing post-tax yields across jurisdictions.
    2. United States: Imposes approximately 30% withholding tax on foreign investors.
    3. Germany: Imposes nearly 26.4% withholding tax.
    4. France: Applies nearly 25% withholding tax.
    5. China: Maintains roughly 10% withholding tax.
    6. Hong Kong and Singapore: Do not impose withholding tax on foreign bond investors, increasing market competitiveness.
    7. Tax Competitiveness: Jurisdictions with lower tax burdens attract larger foreign debt participation.

    How important are FPIs for India’s bond market?

    The RBI defines FPI as any investment made by a non-resident entity in transferable financial assets (such as equity shares, corporate bonds, government securities, or mutual funds) without seeking operational or management control over the underlying company. An FPI can hold a maximum of less than 10% of the total paid-up equity capital of a single listed Indian company.

    1. Debt Market Participation: FPIs hold a relatively small share of India’s government debt market but their exposure is increasing.
    2. Global Bond Index Inclusion: India’s inclusion in the JPMorgan Government Bond Index-Emerging Markets (GBI-EM) has increased investor interest in Indian sovereign debt.
    3. Investment Cap: The Reserve Bank of India (RBI) permits FPI investment up to 6% of outstanding government securities stock.
    4. Sharp Rise in Investments: FPI investment in dated government securities increased from $30.6 billion (March 2024) to $43.2 billion (March 2025).

    What are the possible macroeconomic gains from lowering withholding tax?

    1. Higher Capital Inflows: Improves overseas participation in Indian debt markets.
    2. Exchange Rate Stability: Supports rupee stability by improving foreign exchange availability.
    3. Borrowing Cost Efficiency: Larger investor participation can lower sovereign borrowing costs.
    4. Bond Market Deepening: Strengthens liquidity and improves depth of India’s debt market.
    5. Global Financial Integration: Facilitates smoother integration with international capital markets after bond index inclusion.

    What concerns may arise from excessive dependence on FPI debt flows?

    1. Capital Flight Risk: Portfolio investments remain sensitive to global interest rates and geopolitical uncertainty.
    2. External Vulnerability: Sudden reversals can weaken the rupee and intensify external sector stress.
    3. Tax Revenue Trade-off: Lower withholding tax may reduce short-term tax collections.
    4. Market Volatility: Excessive foreign participation may amplify bond yield fluctuations.

    Conclusion

    Reducing withholding tax on bond investments can strengthen India’s attractiveness as a debt investment destination at a time of external uncertainty and rising financing requirements. However, durable gains require balancing tax competitiveness with macroeconomic stability, prudent capital flow management, and deeper domestic bond market reforms.

    PYQ Relevance

    [UPSC 2018] How would the recent phenomena of protectionism and currency manipulations in world trade affect macroeconomic stability of India?

    Linkage: The PYQ tests understanding of external sector stability, capital flows, exchange rate management, and macroeconomic resilience in a globalised economy. Higher bond inflows can improve forex reserves, rupee stability, and financing of the current account deficit, directly affecting macroeconomic stability.

  • 3 old thermal power sites chosen for new nuclear power projects

    Why in the News?

    As of mid-2026, India is actively advancing its strategy to repurpose retiring coal-fired power plants into nuclear power stations.A high-level workshop hosted by the Central Electricity Authority (CEA) confirmed the identification of 3-4 sites for conversion to host nuclear units. This strategy is part of a larger plan to identify up to 10 retired thermal sites for conversion to help achieve 100 GWe of nuclear capacity by 2047. This represents a massive shift from 8.8 GWe to 100 GWe.

    How does repurposing thermal power sites strengthen India’s nuclear expansion strategy?

    1. Existing Land Availability: Facilitates faster project execution through pre-acquired industrial land. This reduces delays arising from land acquisition disputes. The evaluation framework prescribed a minimum land requirement of 340 hectares for nuclear facilities.
    2. Water Infrastructure: Ensures access to cooling water infrastructure already available at thermal stations. Water availability emerged as a key criterion during site selection.
    3. Grid Connectivity: Supports rapid integration into electricity transmission networks due to pre-existing evacuation infrastructure at thermal sites.
    4. Ageing Coal Fleet: Addresses the challenge of thermal plants exceeding operational life. The panel specifically examined plants older than 40 years or nearing retirement.
    5. Emission Reduction: Facilitates decarbonisation by replacing carbon-intensive coal power with low-emission baseload electricity.
    6. Brownfield Development Model: Reduces costs and procedural bottlenecks compared to entirely new nuclear sites.

    Why has nuclear power become central to India’s long-term energy transition?

    1. Net-Zero Commitments: Supports India’s transition toward low-carbon electricity generation while maintaining energy security.
    2. Baseload Electricity: Ensures stable electricity supply unlike intermittent renewable sources such as solar and wind.
    3. Capacity Expansion Imperative: India plans expansion from 8.8 gigawatt-electric (GWe) to 100 GWe by 2047. This reflects a nearly 11-fold increase in nuclear generation capacity.
    4. Growing Energy Demand: Supports rising electricity demand from urbanisation, industrialisation, electric mobility, and digital infrastructure.
    5. Energy Diversification: Reduces overdependence on imported fossil fuels and volatile global energy markets.

    What institutional and policy mechanisms are enabling this transition?

    1. SHANTI Act, 2025: Expands private sector participation in nuclear operations and fuel-chain management while maintaining public-sector oversight over sensitive activities.
    2. Inter-Agency Coordination: Strengthens institutional cooperation through involvement of the CEA, Atomic Energy Regulatory Board (AERB), and Nuclear Power Corporation of India Limited (NPCIL).
    3. Site Selection Committee: Facilitates scientific evaluation through a subcommittee of the Standing Site Selection Committee, constituted in January 2025.
    4. 17-Point Evaluation Checklist: Ensures technical scrutiny of:
      1. Accessibility
      2. Water availability
      3. Seismotectonic conditions
      4. Meteorology
      5. Population profile
      6. Surrounding settlements
    5. Retrofitting Strategy: Supports reuse of retiring infrastructure rather than relying exclusively on greenfield nuclear projects.

    Why are exclusion-zone norms emerging as a major obstacle?

    An exclusion zone is a mandatory safety bubble around a nuclear plant where human habitation is legally prohibited to protect the public in an emergency. However, repurposing old coal plants into nuclear hubs is difficult because local communities have already built homes right up to these existing industrial borders.

    1. Mandatory Exclusion Radius: Requires a minimum 1-km exclusion zone around reactor sites where habitation and economic activity remain prohibited.
    2. Settlement Constraints: Creates implementation barriers as some shortlisted thermal sites have existing settlements nearby.
    3. Population Challenge: One shortlisted site reportedly has 15-20 families living within the mandatory exclusion area, affecting project feasibility.
    4. Conditional Viability: One project becomes feasible only if exclusion requirements reduce from 1 km to 700 metres.
    5. Site Identification Constraint: Restricts availability of suitable inland nuclear locations despite existing industrial infrastructure.
    6. Policy Proposal: Government is considering reducing exclusion-zone requirements for future nuclear plants.

    Can Small Modular Reactors (SMRs) address India’s site constraints?

    Small Modular Reactors (SMRs) are advanced, compact nuclear fission reactors that generate up to 300 MWe of electricity per unit, which is roughly one-third the output of a traditional large-scale nuclear plant. They are specifically designed to be built efficiently in factories and transported by truck, train, or ship to a designated site for quick assembly.

    1. Compact Design: Requires smaller land parcels and lower cooling-water requirements.
    2. Flexibility: Facilitates deployment at constrained industrial sites unsuitable for large conventional reactors.
    3. Repurposing Potential: Strengthens prospects for converting old thermal power infrastructure into clean energy hubs.
    4. Scalability: Supports phased capacity addition rather than large upfront investment.
    5. Policy Relevance: Government assessments indicate some shortlisted thermal sites may eventually suit Small Modular Reactors (SMRs) better than conventional reactors.

    What are the broader concerns associated with nuclear expansion in India?

    While the transition to nuclear energy offers a clear path toward zero-carbon baseload power; scaling up capacity to 100 GWe introduces complex regional and systemic vulnerabilities. These concerns cross environmental, financial, regulatory, and public domains.

    1. Environmental and Operational Constraints:
      1. Nuclear reactors require continuous, massive volumes of water for cooling. Deploying reactors at inland, retired coal plant sites risks acute water conflicts with local agriculture and urban centers, especially during peak summer droughts.
      2. Long-Term Waste Disposal: India’s expanding nuclear footprint will significantly increase the volume of high-level radioactive waste.
      3. Radiation and Disaster Risks: Despite advanced passive safety systems, concerns persist regarding:
        1. potential radiation leaks
        2. ecological contamination
        3. robustness of emergency evacuation protocols in highly populated surrounding areas
    2. Economic and Regulatory Hurdles:
      1. High Capital Cost: Involves long gestation periods and substantial upfront investments.
      2. Regulatory Delays: Slows implementation due to multi-layered environmental and safety clearances.
    3. Social and Public Friction:
      1. Deep-Rooted Public Resistance: Historical projects like Kudankulam and Jaitapur have faced years of intense local protests over forced displacement, loss of farming land, and perceived health risks.
      2. Exclusion-Zone Displacement: Forcing a 1-km or even a reduced 700-meter safety boundary inside established industrial brownfields means the government must legally evict existing families and ban surrounding economic activities.

    Conclusion

    Repurposing old thermal power plants for nuclear generation reflects a strategic convergence of energy transition, industrial asset reuse, and long-term electricity security. The initiative can accelerate nuclear expansion through brownfield infrastructure advantages. However, exclusion-zone regulations, water constraints, and regulatory bottlenecks remain critical implementation challenges. The success of this model may shape India’s ability to reconcile decarbonisation with rising energy demand.

    PYQ Relevance

    [UPSC 2017] Give an account of the growth and development of nuclear science and technology in India. What is the advantage of fast breeder reactor programme in India?

    Linkage: The PYQ tests understanding of India’s nuclear energy ecosystem, indigenous nuclear programme, reactor technology, and long-term energy strategy. Evolving nuclear strategies such as repurposing retired thermal plants will help in India’s planned expansion of nuclear power from 8.8 GWe to 100 GWe by 2047

  • Tax Relief on Bond Investments and FPIs

    Why in the News?

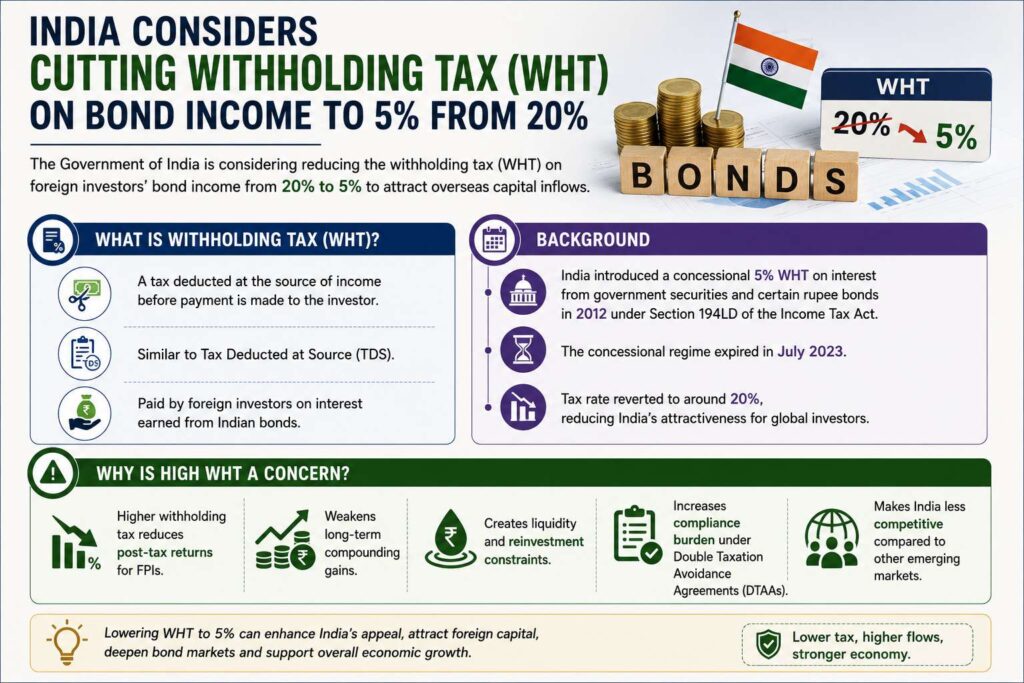
    The Government of India is considering reducing the withholding tax (WHT) on foreign investors’ bond income from 20% to 5% to attract overseas capital inflows.

    What is Withholding Tax (WHT)?

    • A tax deducted at the source of income before payment is made to the investor.
    • Similar to Tax Deducted at Source (TDS).
    • Paid by foreign investors on interest earned from Indian bonds.

    Background

    • India introduced a concessional 5% WHT on interest from government securities and certain rupee bonds in 2012 under Section 194LD of the Income Tax Act.
    • The concessional regime expired in July 2023.
    • Tax rate reverted to around 20%, reducing India’s attractiveness for global investors.

    Why is High WHT a Concern?

    Higher withholding tax:

    • Reduces post-tax returns for FPIs.
    • Weakens long-term compounding gains.
    • Creates liquidity and reinvestment constraints.
    • Increases compliance burden under Double Taxation Avoidance Agreements (DTAAs).

    How Will Tax Reduction Help FPIs?

    • Improve effective yields on Indian bonds.
    • Increase attractiveness of Indian debt markets.
    • Encourage foreign capital inflows.
    • Support forex reserves and external stability.

    Global Comparison

    • Countries imposing WHT on foreign investors:
      • United States: 30%
      • Germany: 26.4%
      • France: 25%
      • China: 10%
    • No WHT: Hong Kong and Singapore

    FPIs in India’s Debt Market

    • FPIs hold a limited share of India’s government debt market.
    • Investments increased after inclusion in global bond indices such as:
      • JPMorgan Government Bond Index-Emerging Market
    • RBI cap on FPI investment in government securities:
      • 6% of outstanding stock
    [2019] Which of the following is issued by registered foreign portfolio investors to overseas investors who want to be part of the Indian stock market without registering themselves directly? 
    (a) Certificate of Deposit 
    (b) Commercial Paper 
    (c) Promissory Note 
    (d) Participatory Note
  • Repurposing Old Thermal Plants for Nuclear Power

    Why in the News?

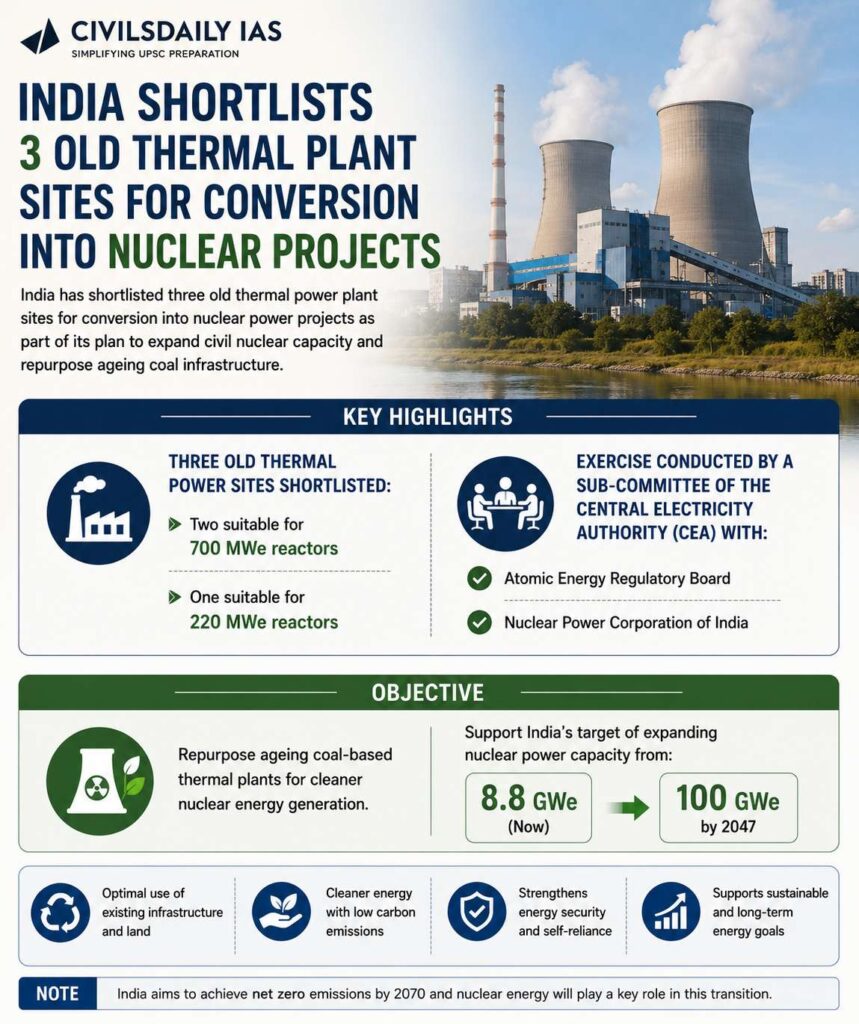
    India has shortlisted three old thermal power plant sites for conversion into nuclear power projects as part of its plan to expand civil nuclear capacity and repurpose ageing coal infrastructure.

    Key Highlights

    • Three old thermal power sites shortlisted:
      • Two suitable for 700 MWe reactors
      • One suitable for 220 MWe reactors
    • Exercise conducted by a sub-committee of the Central Electricity Authority (CEA) with:
      • Atomic Energy Regulatory Board
      • Nuclear Power Corporation of India

    Objective

    • Repurpose ageing coal-based thermal plants for cleaner nuclear energy generation.
    • Support India’s target of expanding nuclear power capacity from:
      • 8.8 GWe to 100 GWe by 2047.

    Why Old Thermal Sites?

    Advantages include:

    • Existing land and water availability
    • Existing transmission and infrastructure
    • Reduction in emissions from old coal plants
    • Support for clean energy transition

    SHANTI Act, 2025

    • Opened parts of the nuclear sector to private participation.
    • Allowed private role in operations and fuel management.

    Site Selection Criteria

    • Water availability
    • Land availability
    • Seismic safety
    • Population density
    • Meteorological conditions
      • Sites in Seismic Zone V or near active faults were excluded.

    What is Exclusion Zone?

    • Mandatory safety zone around nuclear reactors where habitation and economic activity are restricted.
    • Current Norms: Around 1 km radius for nuclear plants.
    • Proposed Changes
      • 700 MWe reactors: reduce from 1 km to 700 m
      • 220 MWe reactors: reduce to 500 m
    • Proposal has received in-principle approval from:
      • AERB
      • Department of Atomic Energy (DAE)

    Small Modular Reactors (SMRs)

    • Officials noted that repurposed thermal sites may be more suitable for:
      • Small Modular Reactors (SMRs)
      • Smaller nuclear projects
    [2013] Which one among the following industries is the maximum consumer of water in India? 
    (a) Engineering
    (b) Paper and pulp
    (c) Textiles
    (d) Thermal power
  • India’s Exports Grow Despite West Asia Crisis

    Why in the News?

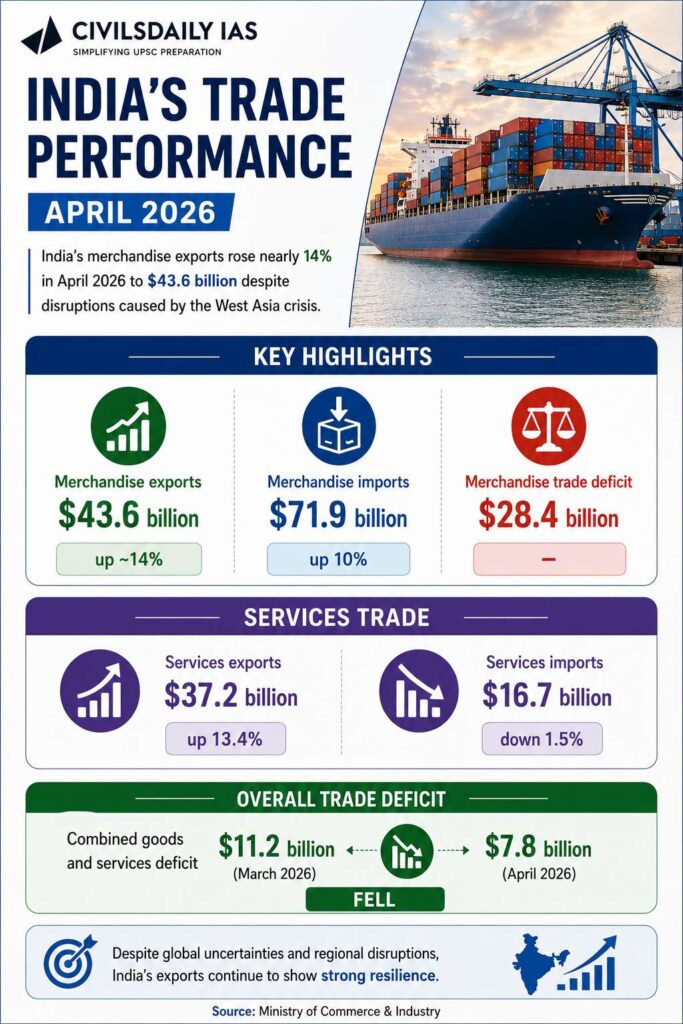
    India’s merchandise exports rose nearly 14% in April 2026 to $43.6 billion despite disruptions caused by the West Asia crisis.

    Key Highlights

    • Merchandise exports: $43.6 billion (up ~14%)
    • Merchandise imports: $71.9 billion (up 10%)
    • Merchandise trade deficit: $28.4 billion
    • Services Trade
      • Services exports: $37.2 billion (up 13.4%)
      • Services imports: $16.7 billion (down 1.5%)

    Overall Trade Deficit: The combined goods and services deficit fell from $11.2 billion to $7.8 billion.

    Reasons for Export Growth

    1. Diversification of export markets
    2. Higher global commodity prices
    3. Strong supply chain resilience

    Strong Export Growth To

    • Tanzania
    • Sri Lanka
    • Singapore
    • Bangladesh
    • Vietnam

    Impact of the West Asia Crisis

    • Exports to West Asia fell by ~28%.
    • Imports from West Asia fell by ~31.6%.
    • Reasons:
      • War-related disruptions
      • Shipping concerns
      • Energy market instability

    UAE and U.S. Trade

    • Exports to United Arab Emirates declined sharply.
    • Exports to the United States grew modestly.

    Important Concepts

    • Merchandise Trade: Trade in physical goods like petroleum, machinery, textiles, and electronics.
    • Services Trade: Trade in IT, banking, consulting, tourism, etc.
    • India usually runs:
      • Trade deficit in merchandise
      • Trade surplus in services
    [2020] With reference to the international trade of India at present, which of the following statements is/are correct? 
    1.India’s merchandise exports are less than its merchandise imports. 2.India’s imports of iron and steel, chemicals, fertilisers and machinery have decreased in recent years.
    3.India’s exports of services are more than its imports of services.
    4.India suffers from an overall trade/current account deficit.
    Select the correct answer using the code given below:
    a) 1 and 2 only b) 2 and 4 only c) 3 only d) 1, 3 and 4 only
  • Capital flight and pressure on the rupee

    Why in the News?

    The Indian Rupee is under intense depreciatory pressure. This is driven by significant capital outflows and surging global oil prices. This situation is particularly critical because, unlike previous cycles, capital flight is occurring based on the mere expectation of future interest rate hikes in developed economies, rather than actual hikes. This “pre-emptive” exit by foreign investors, coupled with a sharp rise in LPG and petrol prices, has triggered domestic hardships and a reverse migration of workers. The scale of the problem is highlighted by the fact that even without a formal change in U.S. Federal Reserve or Bank of England rates (currently held at 3.75% since December 2025), the Indian external account is facing a “taper tantrum” style exodus. This threatens the stability of India’s post-pandemic recovery and widening the Current Account Deficit to unsustainable levels.

    How do global geopolitical shifts trigger domestic capital flight?

    1. Geopolitical Hostilities: Promotes risk-aversion among foreign investors due to conflict in the Persian Gulf and the closure of the Strait of Hormuz.
    2. Capital Outflows: Leads to the liquidation of Indian assets as investors seek “safe haven” currencies, primarily the U.S. Dollar.
    3. Currency Weakening: Results in the depreciation of the Rupee relative to major currencies, increasing the cost of imports.

    Why is the current pressure on the rupee different from previous episodes of depreciation?

    1. Pre-emptive Capital Flight: Reflects investor withdrawal before actual foreign interest rate hikes, unlike earlier periods where monetary tightening had already occurred.
    2. Geopolitical Trigger: Emerges from uncertainty generated by hostilities in the Persian Gulf and fears regarding the closure of the Strait of Hormuz, a critical oil transit route.
    3. Double Vulnerability: Combines rising oil prices and capital outflows, placing simultaneous pressure on India’s currency and external account.
    4. Sharp Contrast with Earlier Trends: Occurs despite the U.S. Federal Reserve and Bank of England not raising rates, signalling a shift toward expectation-driven financial behaviour.
    5. Domestic Spillover: Rising LPG and petrol prices have increased hardship among working households and reportedly triggered reverse migration of workers back to villages.

    Can we compare the present situation with the 2013 ‘Taper Tantrum’?

    1. Taper Tantrum Parallel: Mirrors the 2013 episode, when expectations of reduced quantitative easing by the U.S. Federal Reserve caused sharp capital withdrawals from emerging markets.
    2. Expectation-Driven Exit: Demonstrates how the mere anticipation of tighter monetary policy, rather than actual policy implementation, can trigger capital outflows.
    3. Historical Similarity: Repeats a pattern where global financial sentiment rapidly alters investor behaviour in emerging economies.
    4. Critical Difference: Current outflows appear to be happening even earlier, before any formal signal of rate hikes has materialised.
    5. External Account Risk: Suggests India may face stronger pressure if future rate increases actually occur.

    Why does capital flight create pressure on the rupee?

    1. Capital Outflows: Foreign investors reduce holdings in Indian financial assets during periods of uncertainty. This reduces demand for the rupee and increases demand for foreign currencies.
    2. Exchange Rate Depreciation: Reduced foreign capital inflows weaken the rupee because investors convert rupee-denominated assets into dollars and other reserve currencies.
    3. Interest Rate Differential: Investment decisions depend on comparative returns between India and advanced economies. Higher expected returns abroad reduce the attractiveness of emerging markets.
    4. External Vulnerability: India remains vulnerable due to dependence on foreign capital to finance its current account deficit.

    How does capital flight occur through interest rate differentials?

    1. Interest Rate Differential: Determines investor preference based on comparative returns between Indian assets and foreign financial markets.
    2. Return Calculation: Requires Indian investments to compensate investors for inflation risk and currency depreciation risk in addition to nominal returns.
    3. Foreign Monetary Tightening: Encourages investors to reduce holdings of Indian assets if foreign rates rise and returns abroad become relatively attractive.
    4. Currency Depreciation: Occurs when foreign investors liquidate rupee-denominated assets and convert holdings into stronger reserve currencies such as the U.S. Dollar.
    5. Emerging Market Vulnerability: Exposes economies like India because dependence on external capital increases sensitivity to global financial conditions.

    How are geopolitical tensions in West Asia aggravating India’s external vulnerabilities?

    1. Strait of Hormuz Risk: Closure concerns regarding the Strait of Hormuz have heightened uncertainty because nearly one-third of global seaborne crude oil passes through the route.
    2. Crude Oil Prices: Rising oil prices increase India’s import bill because India imports nearly 85% of its crude oil requirement.
    3. Current Account Deficit (CAD): Higher oil imports widen the CAD by increasing expenditure on imports relative to exports.
    4. Inflationary Pressure: Expensive crude increases fuel and transport costs, thereby raising inflation across sectors.
    5. Investor Sentiment: Global uncertainty encourages investors to shift capital toward safer assets such as U.S. treasury securities.

    How does monetary policy uncertainty complicate exchange rate management?

    1. Inflation Persistence: Prolonged geopolitical conflict increases energy prices, thereby sustaining inflation.
    2. Central Bank Dilemma: Monetary authorities face a trade-off between controlling inflation and supporting growth.
    3. Interest Rate Transmission: Higher interest rates strengthen currency attractiveness but may slow economic growth.
    4. Policy Signalling: Ambiguity regarding future global monetary policy creates volatility in exchange rate markets.
    5. Example:  U.S. Federal Reserve: Delayed response to inflation after the pandemic contributed to uncertainty regarding future tightening.

    Why are current policy responses insufficient to address structural vulnerabilities?

    1. Moral Suasion: Appeals to reduce gold and petroleum consumption may temporarily reduce import demand but do not resolve structural imbalances.
    2. Import Duties: Increase in import duties on gold seeks to reduce non-essential imports and conserve foreign exchange.
    3. RBI Intervention: Restrictions on certain foreign exchange derivative contracts aim to reduce excessive currency speculation.
    4. Structural Limitation: Temporary measures cannot fully offset persistent vulnerabilities arising from oil dependence and foreign capital reliance.
    5. External Dependence: Rising foreign interest rates may intensify pressure on India despite domestic interventions.

    What are the long-term implications for India’s macroeconomic stability?

    1. Exchange Rate Volatility: Persistent rupee depreciation increases import costs and external debt burden.
    2. Inflation Risk: Imported inflation weakens household purchasing power and increases cost of living.
    3. Growth Concerns: High interest rates to stabilize the rupee may reduce investment and economic expansion.
    4. External Sector Stress: Wider current account deficits may weaken investor confidence.
    5. Financial Stability: Sudden capital outflows increase volatility in equity and bond markets.

    Conclusion

    India’s current external sector stress reflects more than routine rupee depreciation. The combination of geopolitical uncertainty, rising oil prices, and expectation-driven capital flight has exposed underlying vulnerabilities in the economy. Temporary measures such as derivative restrictions and gold import duties may moderate immediate pressures, but sustained stability requires reducing structural dependence on imported energy and volatile foreign capital.

    PYQ Relevance

    [UPSC 2018] How would the recent phenomena of protectionism and currency manipulations in world trade affect macroeconomic stability of India?

    Linkage: The PYQ tests understanding of how global trade distortions (protectionism, currency depreciation/manipulation) affect India’s macroeconomic stability, capital flows, inflation, exports, and exchange rate management. It is directly linked because the article discusses how global uncertainty and anticipated foreign monetary tightening are weakening the rupee through capital flight

  • Wholesale Inflation Rises to 3.5-Year High

    Why in the News

    India’s wholesale inflation, measured by the Wholesale Price Index (WPI), rose to 8.3% in April 2026, the highest level in nearly 3.5 years, mainly due to rising crude oil and natural gas prices amid the West Asia crisis.

    What is Wholesale Inflation?

    • Wholesale inflation measures changes in prices of goods at the wholesale or producer level before they reach consumers.
    • In India, it is measured through the Wholesale Price Index (WPI).
    • Released by the Ministry of Commerce and Industry.

    Key Data Highlights

    • WPI inflation:
      • March 2026: 3.9%
      • April 2026: 8.3%
    • Highest since October 2022.

    Major Drivers of Inflation

    Crude Oil and Natural Gas Prices

    • Inflation in crude oil and natural gas reached 67.2% in April 2026.
    • Highest level in 46 months.
    • Reasons:
      • West Asia geopolitical tensions
      • Supply uncertainty
      • Rising global energy prices
    • Fuel and Power Inflation: Fuel and power inflation rose to 24.7% in April 2026.
    • Driven by:
      • Rise in mineral oil prices
      • Higher transportation and logistics costs
    • Imported Inflation: Rising global commodity prices increased India’s import costs.

    What is Base Effect?

    • Base effect means current inflation appears higher because prices were unusually low in the previous year.
    • Since crude oil and natural gas witnessed deflation last year, current price increases appear statistically sharper.

    Core Difference between WPI and CPI

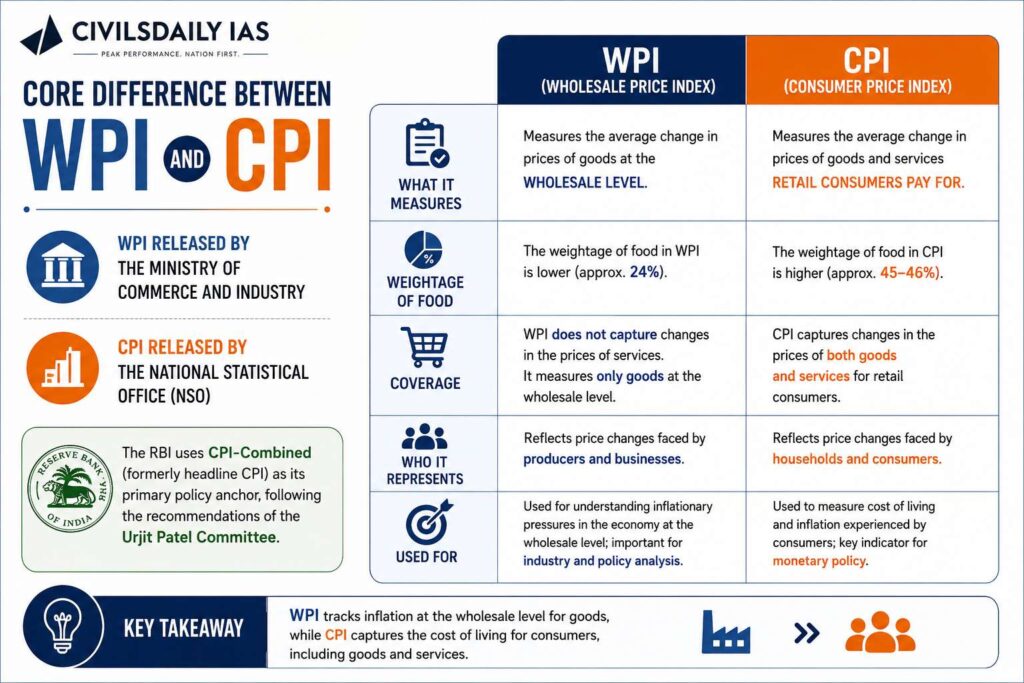
    • WPI Released by the Ministry of Commerce and Industry 
    • CPI Released by the National Statistical Office (NSO)
    • The weightage of food in Consumer Price Index (CPI) is higher than that in Wholesale Price Index (WPI). CPI has a significantly higher weightage for food (approx. 45-46%) compared to WPI (approx. 24%).
    • The WPI does not capture changes in the prices of services, which CPI does. WPI measures only goods at the wholesale level, while CPI includes both goods and services for retail consumers.
    • The RBI uses CPI-Combined (formerly headline CPI) as its primary policy anchor, following the recommendations of the Urjit Patel Committee.
    [2020] Consider the following statements: 
    1.The weightage of food in the Consumer Price Index (CPI) is higher than that in the Wholesale Price Index (WPI). 
    2.The WPI does not capture changes in the prices of services, which the CPI does. 
    3.The Reserve Bank of India uses WPI as its key measure of inflation to decide changes in policy rates. 
    Which of the statements given above is/are correct? 
    [A] 1 and 2 only [B] 2 and 3 only [C] 1 and 3 only [D] 1, 2 and 3