💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Geography

  • A Himalayan tragedy

    Why in the News

    Scientists investigating the flash flood on the Bhotekoshi river in Nepal have attributed it to a sturzstrom, a high speed rock and ice avalanche near Langtang Lirung on the Nepal China border, rather than to a glacial lake outburst flood (GLOF). The reattribution matters because a flood on the same river in July of the previous year, which also occurred without rainfall, was concluded to be a glacial lake outburst flood, and that conclusion shaped what was being watched for. The flood struck at around 8.40 a.m. and has left more than 600 dead and close to 2,500 missing, including foreign nationals, mostly from India. What is now contested is whether a monitoring and warning system built around glacial lakes can see a hazard that begins as a bedrock and ice collapse.

    What is a sturzstrom?

    1. The definition: A massive rock avalanche in which a large volume of rock suddenly collapses and travels at extremely high speed over a long distance.
    2. Its high mountain form: Where the collapsing rock is mixed with ice, snow, firn and frozen soil, the same event is described as a rock and ice avalanche.
    3. Why the runout is so long: Pressure and friction inside the moving mass generate meltwater, which lubricates the mass and its base, reduces resistance and carries the debris much further than a dry rockslide would.
    4. How it ends: As it descends it takes in more ice, snow, rock, soil and water, and can transform into a massive debris flow before depositing its material.

    Why was the glacial lake explanation set aside?

    1. The precedent pointed the other way: A rainless flood on the Bhotekoshi in July of the previous year was concluded by scientists to be associated with a glacial lake outburst flood, so that was the first hypothesis tested.
    2. The velocity did not fit: The speed and ferocity of this flood, which washed away villages across three districts, Rasuwa, Nuwakot and Dhading, prompted experts to examine it from a different angle.
    3. The onset signature differs: A lake breach releases a stored volume over a measurable period, while this flood arrived with no such build up recorded at downstream gauges.
    4. It has no Nepali precedent: No comparable disaster involving a sturzstrom had been recorded in Nepal before this event.

    What does the transboundary geography add to the problem?

    1. The source area straddles the border: Nepalese and Chinese authorities have concluded that the source lay in the Langtang Lirung area, and identifying the exact collapse point and which side of the boundary it sat on may not be possible.
    2. The trigger was a compound event: Satellite imagery shared by the Chinese side pointed to a combination of an ice avalanche, permafrost movement and a rockslide, with the rockslide on the Chinese side and its impact extending into Nepal.
    3. The avalanche began in Nepal: A senior divisional hydrologist at Nepal’s Department of Hydrology and Meteorology states the avalanche originated on Nepalese territory very close to the boundary and induced flooding that crossed into China, damaging both sides.
    4. The channel is itself transboundary: The location identified is the Lhende Khola, a high altitude river rising in Gyirong County in Tibet and flowing south into Nepal as a tributary of the Bhotekoshi and Trishuli systems.
    5. The corridor carries trade and pilgrims: Rasuwagadhi in Rasuwa is the checkpoint through which most of Nepal’s trade with China passes, and from May to September hundreds of pilgrims cross there into Tibet for the Kailash Mansarovar pilgrimage, with Indians the largest share.

    How far did early warning and climate attribution actually get?

    1. The systems worked and still failed: Experts state that early warning systems were activated as intended but were rendered ineffective by the speed of the flood.
    2. The structural difficulty is the terrain: The head of the United Nations Office for Disaster Risk Reduction (UNDRR) has said the event again showed how fragile mountain ecosystems are and how hard it is to build early warning in mountain environments.
    3. Attribution stops short of a direct link: Scientists have not ruled out a role for climate change and point to rising temperatures warming the Himalayas and accelerating glacier melt, without directly linking this disaster to global warming.
    4. Access is limiting the assessment itself: The International Federation of Red Cross and Red Crescent Societies (IFRC) reports that remoteness combined with damaged infrastructure is obstructing both damage assessment and the delivery of assistance, with around 93,000 people estimated to be affected.

    What does the 2021 Chamoli comparison establish?

    1. The mechanism has an Indian precedent: The 2021 Chamoli disaster in Uttarakhand began with a bedrock failure beneath a glacier, which triggered a rock and ice avalanche that transformed into a debris flow and flood.
    2. It is described the same way in the literature: Chamoli has been scientifically described as a rock and ice avalanche and, in some literature, explicitly as a sturzstrom.
    3. The scale of material involved: Research found that more than 25 million cubic metres of rock and ice broke loose high in the Uttarakhand Himalaya before moving rapidly downstream.
    4. The comparison narrows the watch list: Two events of the same mechanism a few years apart in the same mountain system establish an unstable rock and ice slope, not only a moraine dammed lake, as a recurring source of catastrophic flooding.

    Challenges to early warning in high mountain catchments

    1. The monitored hazard is the wrong hazard: Warning networks in the Himalaya are built around glacial lake inventories and lake level telemetry, which observe nothing at an unstable rock and ice face. Eg. Nepal’s national hazard inventories catalogue glacial lakes by area and moraine condition, with no equivalent register of unstable rock and ice faces. Fix. Add slope stability and permafrost monitoring at identified rock and ice faces to the existing glacial lake inventories.
    2. Lead time collapses to minutes: A sturzstrom accelerates and reaches settlements in the time a lake outburst would take to build, so a warning chain designed for hours has nothing to work with. Eg. Riverside towns such as Betrawati in Nuwakot were buried on the same morning the collapse occurred. Fix. Move from advisory dissemination to automatic siren triggering at gauge stations, removing the human decision step from the chain.
    3. The hazard does not respect the border: The collapse zone straddles the Nepal China boundary, so neither state’s monitoring network alone observes the full source area. Eg. The trigger was established only from satellite imagery shared by the Chinese side. Fix. Put the Lhende Khola and comparable transboundary catchments under a standing data sharing arrangement with agreed real time thresholds.
    4. Exposure is concentrated in the valley floor: Trade routes, hydropower works, bazaars and pilgrimage traffic all occupy the same narrow corridor a debris flow uses. Eg. The Rasuwagadhi corridor carries most of Nepal’s China trade and the seasonal Kailash Mansarovar pilgrimage. Fix. Apply a debris flow runout based building line along these corridors rather than a flood return period line drawn from rainfall records.
    5. Assessment capacity fails exactly when it is needed: Remote terrain and destroyed access mean the size of the disaster is unknown for weeks, which delays both relief and reconstruction decisions. Eg. Officials state the full scale of damage may take weeks or months to assess. Fix. Pre position aerial survey and satellite tasking agreements so a post event damage assessment does not depend on ground access.

    Conclusion

    The scientific account of this flood has moved from a glacial lake outburst to a sturzstrom originating on an unstable rock and ice slope near the Nepal China border. That shift changes what has to be monitored, since a lake inventory does not observe a bedrock face, and it places the source area inside a boundary zone neither country monitors alone. Search and rescue continues with more than 15,000 personnel deployed. The next milestone is the joint Nepalese and Chinese determination of the exact collapse point, which will decide whether transboundary monitoring of that catchment is put in place.

    Back2Basics: Glacial Lake Outburst Flood (GLOF)

    1. What it is: The sudden release of water held in a glacial lake, which sends a large volume downstream in a short period.
    2. How the lake forms: Meltwater collects behind a moraine ridge or an ice dam left by a retreating glacier, so the impounding structure is loose debris or ice rather than rock.
    3. What breaches it: Overtopping by an avalanche or landslide into the lake, seepage that erodes the moraine from within, or failure of the ice dam itself.
    4. Why it is tracked in the Himalaya: Glacier retreat is adding to both the number and the volume of these lakes, which is why national inventories monitor them and why they were the first explanation tested for this flood.

    Matching Previous Year Question

    “[2021, GS1, 10 marks] Differentiate the causes of landslides in the Himalayan region and Western Ghats. (150 words) हिमालय क्षेत्र तथा पश्चिमी घाटों में भू-स्खलनों के विभिन्न कारणों का अंतर स्पष्ट कीजिए। (150 शब्दों में उत्तर दीजिए)”
  • Congress-ruled states to move court against new mines law

    Why in the News

    State governments where the Congress is in power are preparing to challenge the Mines and Minerals (Development and Regulation) Amendment Act, 2026 in the Supreme Court, on the ground that it undermines the rights of the States. The Act, passed by the House on 13 August 2026, seeks to curb the power of States to levy taxes on mineral rights and mineral bearing lands. That power was confirmed as belonging to the States by a nine judge Bench two years ago, so the dispute is over whether Parliament can legislate away a taxing entry the Court has read as independent.

    What is the Mines and Minerals (Development and Regulation) Act, 1957?

    1. What it is: The Mines and Minerals (Development and Regulation) Act, 1957, referred to as the MMDR Act, is the parent law governing every mineral in India except petroleum and natural gas.
    2. The core split it creates: The State Government owns the mineral in its territory. The Central Government decides the rules, fixes the royalty rate for major minerals and, for some categories, conducts the auction.
    3. How a block reaches a miner: Someone auctions the block, the State signs the lease, and the company mines. The State signs the lease in every case, including where the Centre ran the auction.
    4. Where the money goes: Royalty, dead rent and the auction premium go to the State in every case, with offshore blocks the only exception.

    What is the current status of State taxing power over minerals in India?

    1. The settled position since 2024: A nine judge Bench of the Supreme Court in Mineral Area Development Authority v Steel Authority of India, decided eight to one in 2024, held that States hold an independent power under Entry 50 of the State List to levy taxes on mineral rights, and that the MMDR Act does not take that power away.
    2. The distinction the ruling rests on: Royalty is not a tax. It is consideration paid to the State as the owner of the mineral, which is why a State levy on mineral rights is a separate and additional exercise of power.
    3. What the ruling overturned: India Cement v State of Tamil Nadu (1990), which had held royalty to be a tax and State cesses on royalty to be beyond State competence, stands overruled.
    4. The recovery window: States may recover past dues from 1 April 2005, in instalments spread over twelve years beginning 1 April 2026, without interest or penalty on the earlier period.
    5. What the ruling did not give the States: It conferred a power to tax mineral rights, not a power to fix the royalty rate. Royalty rates for major minerals continue to be set centrally under the Second Schedule to the MMDR Act.
    6. What the 2026 amendment now does to that position: The Act passed on 13 August 2026 seeks to curb the power of States to levy taxes on mineral rights and mineral bearing lands, which is the power the 2024 ruling had recognised.

    Constitutional Provisions Related to Mineral Rights and Legislative Competence

    1. Entry 54, Union List: Regulation of mines and mineral development, to the extent that Parliament by law declares such Union control to be expedient in the public interest.
    2. Entry 23, State List: Regulation of mines and mineral development, expressly made subject to the provisions of Entry 54 of the Union List.
    3. Entry 50, State List: Taxes on mineral rights, subject to any limitations imposed by Parliament by law relating to mineral development.
    4. Entry 49, State List: Taxes on lands and buildings, the entry under which States tax mineral bearing land.
    5. Entry 55, Union List: Regulation of labour and safety in mines and oilfields.
    6. Article 297: Vests in the Union all lands, minerals and other things of value underlying the ocean within the territorial waters, the continental shelf and the exclusive economic zone.
    7. Article 246: Distributes legislative power between Parliament and the State legislatures across the three Lists.
    8. Article 265: Provides that no tax shall be levied or collected except by authority of law.
    9. Article 131: Confers original jurisdiction on the Supreme Court in a dispute between the Government of India and one or more States, the route through which a State sues over a central statute.

    What is royalty on minerals?

    1. What it is: Royalty is the payment a lessee makes to the owner of the mineral for the mineral removed or consumed, calculated mostly on an ad valorem basis on the average sale price published by the Indian Bureau of Mines.
    2. Who sets it and who receives it: The Centre fixes the rate for major minerals through the Second Schedule to the MMDR Act, and the State fixes it for minor minerals. The State Government receives it in both cases.

    What is a minor mineral?

    1. The statutory definition: Section 3(e) of the MMDR Act names building stones, gravel, ordinary clay and ordinary sand as minor minerals, and allows the Centre to notify any other mineral as minor. Everything not notified as minor is a major mineral, defined negatively with no positive list.
    2. Who controls them: Section 15 gives States exclusive power to frame minor mineral rules and to fix minor mineral royalty, so the Centre’s power over minor minerals is limited to deciding what enters the category.

    What does the Mines and Minerals (Development and Regulation) Amendment Act, 2026 change?

    1. The core change: The Act seeks to curb the power of States to levy taxes on mineral rights and on mineral bearing lands.
    2. The scope claimed for it: The Centre states that it is seeking to regulate only major minerals such as coal, limestone, iron ore, copper and manganese.
    3. What is stated to be left untouched: The States would continue to have powers over 49 minor minerals.
    4. The stated purpose: The Union Minister of Mines told the Rajya Sabha that the legislation does not seek to interfere with the autonomy or revenue rights of States, and that it aims only to ensure uniform mineral rates across the country.
    5. The stage it has reached: The Act was passed by the House on 13 August 2026.

    Which States are challenging the Act and on what ground?

    1. The States on board: Karnataka, Telangana and Himachal Pradesh are already committed to challenging the amendment Act in the Supreme Court.
    2. The State still being negotiated: The Congress is in talks with its ally the Jharkhand Mukti Morcha to get the Jharkhand government to join the challenge.
    3. The stated ground: The party alleges that the law undermines the rights of the States.
    4. The demand short of litigation: The Karnataka Deputy Chief Minister urged the Centre to withdraw the amendment Act, objecting to its restrictive provisions.
    5. The federal framing from Kerala: The Kerala Chief Minister stated that the amendments to the Act are against federal principles.

    How can a State challenge a central law?

    1. The original suit route: A State may institute an original suit against the Government of India in the Supreme Court under Article 131, which is the route available where the dispute involves a question on which a legal right of the State depends.
    2. The writ route is not open to a State in the same way: Article 32 is a remedy for enforcement of fundamental rights, and a State is not a person entitled to fundamental rights, so a State ordinarily proceeds under Article 131 rather than Article 32.
    3. Why the choice of route matters here: An Article 131 suit frames the matter as a Centre State dispute over legislative competence rather than as a grievance of an affected mining company.
    4. The competence question that will be argued: The dispute turns on whether the 2026 Act is a limitation of the kind Entry 50 permits Parliament to impose, or an extinguishing of the entry itself.
    5. The precedent that will be relied on: The 2024 nine judge ruling held that the MMDR Act as it then stood did not take away the Entry 50 power, which leaves open whether a later Act can impose limitations that empty it.

    Major debates surrounding State taxation of mineral rights

    1. Ownership against regulation: The State owns the mineral and receives the royalty, while the Centre fixes the rate and writes the rules, so the party bearing the social and environmental cost of mining does not set the price of it.
    2. Competing readings of one entry: Entry 50 is read either as a State power with a boundary Parliament may draw, or as a power Parliament may narrow until nothing is left of it.
    3. A tax entry against a regulatory entry: Entry 54 of the Union List is a regulatory entry over mineral development, and the question is whether a regulatory power carries with it the power to restrict a taxing entry in the State List.
    4. Two landmark rulings in tension: India Cement (1990) treated royalty as a tax and denied State competence, and Mineral Area Development Authority (2024) treated royalty as consideration and affirmed it, so the sector has operated under opposite rules within one generation.
    5. Uniform rates against fiscal autonomy: Uniform mineral rates across the country lower input cost volatility for steel, aluminium, cement and power, and remove a revenue instrument from the States where those minerals lie.
    6. The retrospective recovery question: Permitting recovery of dues from 1 April 2005 in instalments from 1 April 2026 exposes mineral users to a large accumulated liability, which is the practical trigger for legislative intervention.
    7. The empirical gap the dispute turns on: There is no agreed estimate of what the recovered dues and future State levies would add to the delivered cost of coal, iron ore and limestone, so both the revenue claim and the input cost claim rest on projections.

    Challenges to the new mineral taxation framework

    1. A single change alters two revenue streams at once: Curbing taxes on mineral rights and on mineral bearing lands touches Entry 50 and Entry 49 together, so States lose both an activity based and a property based levy. Eg. Several mineral States had begun framing levies immediately after the 2024 ruling recognised the Entry 50 power.
    2. Litigation freezes revenue planning on both sides: States cannot budget on a levy under challenge, and miners cannot provide for a liability that may be extinguished. Eg. Karnataka, Telangana and Himachal Pradesh have already committed to moving the Supreme Court against the Act.
    3. Uniform national rates ignore differences in deposit quality: A single rate across States taxes a high grade and a low grade deposit identically, which penalises the State with the harder ore body. Eg. Iron ore grades differ sharply between Odisha, Karnataka and Goa, with different beneficiation costs.
    4. The retrospective window collides with the amendment: Recovery of dues from 1 April 2005 was to start in instalments from 1 April 2026, the same period in which the curbing Act was passed. Eg. The twelve year instalment schedule the Court allowed begins precisely when the new restriction takes effect.
    5. The distinction between royalty and tax remains contestable in practice: A State levy structured on the royalty amount can be characterised as a tax on mineral rights or as a levy on land, which invites classification disputes at every notification. Eg. District Mineral Foundation contributions are already computed on the royalty amount rather than on sale value.
    6. Mining States bear the externalities regardless of the tax outcome: Land degradation, dust pollution, groundwater disruption and displacement fall on the district whether or not the State can levy. Eg. The mineral belt overlaps the Fifth Schedule tribal belt almost exactly.
    7. Investment decisions stall while competence is unsettled: Long gestation mining projects require certainty on the total payment stack over a fifty year lease. Eg. A mining lease under the MMDR Act runs for fifty years, far longer than the litigation cycle over the levy.

    Conclusion

    The Mines and Minerals (Development and Regulation) Amendment Act, 2026 has been passed by the House on 13 August 2026 and seeks to curb State powers to tax mineral rights and mineral bearing lands. The next step is a challenge in the Supreme Court, with Karnataka, Telangana and Himachal Pradesh committed and Jharkhand still under negotiation, and the source states no date for filing. The dispute is not about who owns the mineral, which is settled, but about whether a taxing entry in the State List can be narrowed by a central law made under a regulatory entry in the Union List. Until that is answered, the sector operates with two revenue claims on the same rupee.

    “[2025] Consider the following statements:

    Statement I: In India, State Governments have no power for making rules for grant of concessions in respect of extraction of minor minerals even though such minerals are located in their territories.

    Statement II: In India, the Central Government has the power to notify minor minerals under the relevant law.

    Which one of the following is correct in respect of the above statements?

    (a) Both Statement I and Statement II are correct and Statement II explains Statement I

    (b) Both Statement I and Statement II are correct but Statement II does not explain Statement I

    (c) Statement I is correct but Statement II is not correct

    (d) Statement I is not correct but Statement II is correct |

  • Steel mills face margin squeeze as global coking coal prices rise

    Why in the News

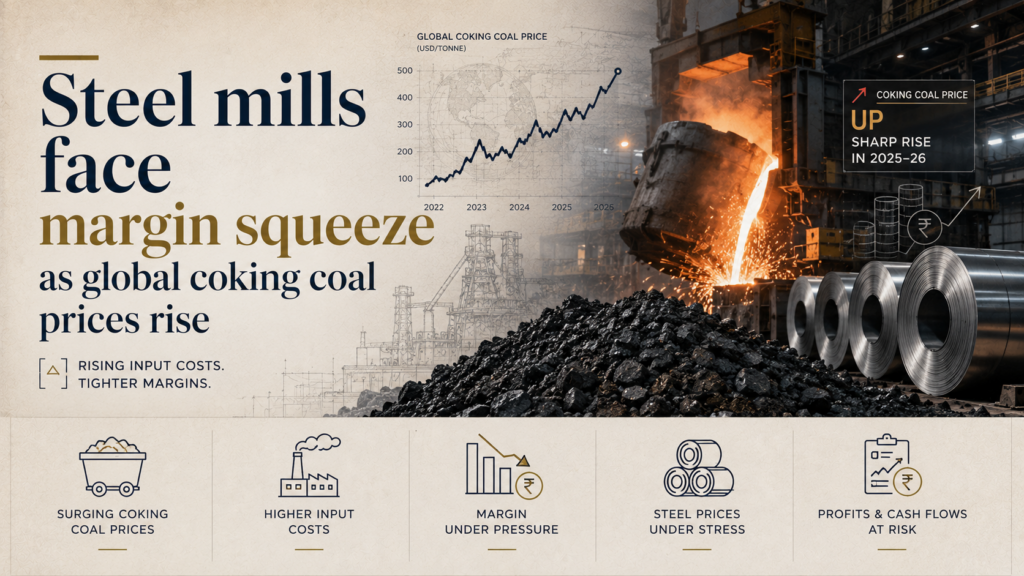
    Premium hard coking coal has averaged $236 per metric ton freight on board Australia in the first seven months of 2026, a jump of 25 percent over last year. Indian steelmakers import 95 percent of their coking coal and face competition from cheap Chinese steel at the selling end, so the input shock cannot be passed on to buyers.

    What is coking coal and why does it decide steelmaking costs?

    1. Definition: Coking coal is a low ash, low sulphur coal that is baked into coke, the carbon source that both fuels the blast furnace and chemically strips oxygen from iron ore. It is not interchangeable with the thermal coal used in power stations.
    2. Share of cost: Coking coal accounts for nearly 40 percent of steel production costs, which makes its price the single largest swing factor in a mill’s margin.
    3. Import dependence: India meets 95 percent of its coking coal needs through imports, with at least half shipped from Australia.
    4. Cost transmission: For blast furnace based steelmakers, every $10 a ton increase in coking coal prices adds approximately $7 to $9 per metric ton to steelmaking costs.

    What does freight on board (FOB) Australia mean?

    1. Price basis: Freight on board (FOB) is the price of the cargo at the loading port, before ocean freight and insurance are added. The $236 per metric ton benchmark is therefore the Australian port price, not the delivered Indian cost.

    Why have global coking coal prices risen this year?

    1. Australian supply disruptions: Output interruptions at Australian mines removed tonnage from a market where India sources at least half its requirement.
    2. Slower ramp up at new mines: New Australian capacity has come on stream more slowly than expected, so the supply gap was not filled.
    3. Middle East conflict: The conflict in the Middle East provided price support across the seaborne coal complex.
    4. Shanxi accident: A large accident at a coal mine in Shanxi, China removed further tonnage from the market in the most recent phase of the price rise.
    5. Benchmark movement: Premium hard coking coal averaged $236 per metric ton FOB Australia over the first seven months of 2026, 25 percent above the previous year, on the metallurgical coal and coke market assessment of the consultancy CRU.
    6. Outlook for the rest of the year: Costs are likely to remain high in the second half of 2026, partly due to the loss of supply following the Shanxi coal mine disaster, on the assessment of BMI, a unit of Fitch Solutions.

    How does the price rise transmit into Indian mills’ balance sheets?

    1. Direct cost pass through: Each $10 a ton rise in coking coal adds $7 to $9 per metric ton to blast furnace steelmaking cost, on the estimate of an executive at a large steel mill.
    2. Volume exposure widens the hit: Coking coal imports are expected to rise by 2 million to 3 million tons in 2026-27, from 64 million tons a year earlier, on the estimate of the commodities consultancy BigMint, so the higher price applies to a larger tonnage.
    3. Freight adds on top of the cargo price: Trade flows have tightened with high demand from India and higher diesel, freight and insurance costs, on the assessment of Moody’s Ratings, raising the delivered cost above the FOB benchmark.
    4. Margin compression is already reported: Executives at three leading steelmakers report squeezed margins with little headroom to raise steel prices.

    Why can Indian mills not pass the cost on to buyers?

    1. Cheap Chinese steel sets the ceiling: Competition from cheap Chinese steel leaves little headroom to raise domestic steel prices even as input costs rise.
    2. Tariffs have not stopped the inflow: Shipments from China have increased despite import tariffs on some grades, so the trade remedy has not restored pricing power.
    3. Demand is strong but price inelastic: Domestic demand is buoyant on the back of infrastructure spending and strong economic growth, and that demand is being served at prices anchored by imports.
    4. Cost push and price ceiling combine: The squeeze operates from both ends at once, on the input side by coking coal and on the output side by import competition.

    What does the squeeze mean for India’s steel capacity expansion?

    1. Capital expenditure at risk: Squeezed margins could impede investment and delay capacity expansion at a time when Indian steelmakers are stepping up spending.
    2. Demand case remains intact: The expansion plans are driven by infrastructure led domestic demand and strong economic growth, so a delay is a supply side failure rather than a demand failure.
    3. Import bill widens: Rising coking coal import volumes alongside rising prices widen the trade exposure of a sector already dependent on a single dominant supplier.

    What do the source geographies of India’s coking coal reveal about its exposure?

    1. Australia, the anchor supplier: Australia ships at least half of India’s coking coal and is expected to continue doing so, which makes an Australian supply interruption an Indian cost event.
    2. China, both a supply and a competition risk: The Shanxi mine accident tightened coking coal supply, and rising Chinese steel shipments simultaneously cap Indian mills’ selling prices.
    3. Russia, a discount that has faded: Russian coal accounted for 24 percent of India’s coking coal imports in recent years, and the discounts on it have diminished over the past two years.
    4. Mozambique and the United States, the diversification margin: Imports from Russia, Mozambique and the United States are all set to rise as India spreads its sourcing.
    5. The Middle East, a freight channel rather than a supply channel: The United States and Iran war raises diesel, freight and insurance costs on seaborne routes rather than removing coal tonnage.

    Challenges to India’s coking coal supply security

    1. Extreme import concentration: A 95 percent import share with at least half from one country leaves no domestic buffer against a single supplier’s disruption. e.g. Australian supply disruptions in 2026 alone lifted the premium hard coking coal benchmark to an average of $236 per metric ton.
    2. Domestic coking coal is largely unusable raw: Indian coking coal carries high ash content and needs washing and blending with imported low ash coal before it can enter a blast furnace. e.g. the Jharia coalfield in Jharkhand holds India’s only significant prime coking coal deposits and still cannot substitute imports without beneficiation.
    3. No pricing power at the selling end: Import competition caps steel prices, so cost shocks are absorbed in the margin rather than recovered from the customer. e.g. Chinese shipments into India rose in 2026 despite import tariffs on some grades.
    4. Freight and insurance are a second, uncorrelated shock: Shipping cost spikes hit the delivered price even when the cargo price is stable. e.g. the United States and Iran war raised diesel, freight and insurance costs on the routes carrying Indian bound coal.
    5. Capacity expansion is the first casualty: Compressed margins delay the capital expenditure cycle rather than current output, so the damage appears years later. e.g. Indian mills stepping up spending to serve infrastructure driven demand now face investment decisions taken under a squeezed margin.
    6. The scrap based alternative route is supply constrained: Electric arc and induction furnace steelmaking avoids coking coal but depends on scrap that India does not generate in sufficient volume. e.g. India continues to import ferrous scrap despite the Steel Scrap Recycling Policy, 2019.

    Conclusion

    India’s steel sector faces a cost shock it cannot pass on, because a 95 percent import dependence on coking coal sits alongside a domestic price ceiling set by cheap Chinese steel. Coking coal is set to remain expensive through the second half of 2026 following the Shanxi supply loss, and import volumes are projected to rise by 2 million to 3 million tons in 2026-27. The immediate risk is not to current production but to the capacity expansion India needs to meet infrastructure led demand. Reducing the exposure requires domestic beneficiation capacity and a wider supplier base, neither of which can be built within a single price cycle.

    Steel Sector in India

    1. Global standing: India is the world’s largest crude steel producer after China and the world’s largest producer of direct reduced iron, also called sponge iron.
    2. Two production routes: The blast furnace and basic oxygen furnace route depends on coking coal and iron ore, and the electric arc furnace, induction furnace and direct reduced iron route depends on scrap, natural gas or non coking coal.
    3. Policy target: The National Steel Policy, 2017 targets 300 million tonnes of crude steel capacity and per capita finished steel consumption of 158 kg by 2030-31.
    4. Structural dependence: India holds large thermal coal reserves but very limited prime coking coal, so the raw material constraint is qualitative rather than quantitative.
    5. Trade position: India moved to being a net importer of finished steel in recent years, which is why import competition now shapes domestic pricing.

    Government Initiatives for the Steel Sector

    1. Production Linked Incentive Scheme for Specialty Steel: Approved in 2021 to incentivise domestic manufacture of value added grades such as coated steel, high strength steel and electrical steel that India otherwise imports.
    2. Mission Purvodaya: Launched in 2020 to build an integrated steel hub in eastern India, drawing on the iron ore and coal belt of Odisha, Jharkhand, West Bengal, Chhattisgarh and Andhra Pradesh.
    3. Steel Scrap Recycling Policy, 2019: Sets up a framework of registered scrapping centres to raise domestic scrap availability and reduce reliance on imported scrap and on coking coal based production.
    4. Domestically Manufactured Iron and Steel Products Policy: Provides preference to domestically manufactured iron and steel in government procurement, to anchor demand for local mills.
    5. Steel Import Monitoring System: Requires advance registration of steel imports so that the government has near real time visibility of import volumes, grades and prices.
    6. Mission Coking Coal: A Ministry of Coal initiative to raise domestic raw coking coal production and washing capacity so that the import share falls over time.
    7. Green Steel Taxonomy: Notified in 2024 to define and star rate low emission steel, creating a domestic standard ahead of carbon border measures in export markets.

    Key Facts about Coking Coal and Indian Steel

    1. Jharia coalfield: Located in Jharkhand, it holds India’s only significant reserves of prime coking coal and has been affected by long running underground mine fires.
    2. Ash content problem: Indian coking coal typically carries ash levels well above the imported grades, which is why it must be washed and blended rather than used directly.
    3. Coke, not coal, enters the furnace: Coking coal is converted to metallurgical coke in coke ovens before charging into the blast furnace.
    4. Administering ministry: The steel sector is administered by the Ministry of Steel and coal by the Ministry of Coal, which is why coking coal policy sits across two ministries.
    5. Non coking coal use: The sponge iron route uses non coking coal, which India produces domestically in large volumes, and is the reason India leads the world in direct reduced iron.

    “[2020, GS1, 15 marks] Account for the present location of iron and steel industries away from the source of raw material, by giving examples.”

  • Monsoon revived, but why there’s cloud over the farm

    Why in the News?

    The southwest monsoon’s revival in July, despite a strengthening El Nino, has sharply narrowed the gap in area sown under kharif crops this season. The relief exposes a deeper tension between a recovering kharif and the mounting risks to the rabi season and to food inflation from El Nino’s lagged effect and a surge in global vegetable oil prices.

    Why did a sowing gap open and how did July reverse it?

    1. Weak start: Rainfall in June was 38 percent below the long period average, making it the sixth driest June in India since 1901, with not a single low pressure system forming.
    2. Early shortfall: By 6 July farmers had planted only 350.85 lakh hectares, which was 20.8 percent below the 442.80 lakh hectares sown in the same period of 2025.
    3. July turnaround: In July the country recorded four low pressure systems against a normal of three. These moved slowly, producing about 24 affected days against a normal of 14, lifting all India July rainfall to 2.4 percent above the average.
    4. Recovery: By 7 August the 967.92 lakh hectares covered was only 1.8 percent lower than last year, with the pulses gap down to 1.8 percent, cotton to 0.4 percent, and oilseeds exceeding last year’s level.

    What is El Nino and why does its effect lag?

    1. Definition: El Nino is the abnormal warming of surface waters in the central and eastern Pacific Ocean off Peru and Ecuador that suppresses monsoon rainfall over India.
    2. Lagged impact: El Nino’s effect on rainfall and temperatures comes with a lag of one to two months and can play out over five to six months or more.
    3. Current phase: It intensified from a weak to moderate phase in June into a moderate to strong event in July, and global agencies expect it to turn very strong during October to December.

    Why is the worst not yet over?

    1. Late kharif needs rain: Crops need rainfall during August and early September for flowering and grain formation that determine yields. Meteorological Department has predicted a fresh low pressure system around 12 August.
    2. Delayed hit: Because El Nino’s rainfall suppressing effect lags, its worst impact is still to come.
    3. Rabi at risk: A strengthening El Nino raises temperatures, and a short warm winter harms wheat, mustard and potato yields, so the real threat is to the rabi season.

    What does the FAO Food Price Index show?

    1. Index high: The United Nations Food and Agriculture Organization (FAO) food price index touched 131.1 points in July, up 1 percent from July 2025 and the highest since the 131.4 of January 2023, a three and a half year high. This means food prices are now at their highest level in about 3½ years.
    2. Vegetable oils drive it: The vegetable oils index reached 195.7 points, up 17.3 percent year on year and the highest since June 2022.
    3. Mixed components: The cereals index was 113.8 points, up 6.9 percent, while dairy fell 24.8 percent, sugar fell 8 percent, and meat rose just 0.8 percent.
    4. Causes: The rise is attributed to El Nino, heatwave hit crop yields in Europe, and supply disruptions from conflicts in West Asia and Ukraine.

    Why are vegetable oils the real concern for India?

    1. Import exposure: The combined value of India’s imports of oilseeds, pulses and cotton was close to 25 billion dollars in 2025-26, which El Nino could push to a new high.
    2. Biofuel diversion: Firming vegetable oil prices stem mainly from diversion of palm, rapeseed and soyabean oil toward biofuel as petroleum prices harden.
    3. Fuel substitution: These oils are used to make fatty acid methyl esters, a substitute for petroleum diesel, linking food and fuel markets.
    4. Buffer available: The government held 92.6 million tonnes of rice and wheat on 1 July against a required minimum of 41.1 million tonnes, plus over 4 million tonnes of pulses, which can be offloaded to contain inflation.

    Conclusion

    The July monsoon revival has rescued the kharif season, cutting the sowing gap to under 2 percent even as El Nino strengthened. The central worry has shifted to the rabi season and to food inflation, since El Nino’s temperature and rainfall effects lag and global vegetable oil prices are at multi year highs. Ample public grain stocks give the government room to manage food inflation, but the rabi outlook and edible oil import bill remain the open risks.

    Back2Basics:

    Foundational Context: Climate Change and Food Security

    1. About: Food security means reliable physical and economic access to sufficient, safe and nutritious food, which climate variability directly threatens.
    2. Tropical vulnerability: Tropical countries face greater exposure because agriculture is rain dependent and heat sensitive.
    3. India context: A large share of India’s cropped area is rainfed, tying output to monsoon performance.
    4. Transmission channels: Erratic rainfall, heat stress, pest incidence and global price shocks each transmit climate risk to food systems.

    FAO Food Price Index

    1. Convening body: Published by the United Nations Food and Agriculture Organization (FAO).
    2. What it measures: A weighted average of world prices of a basket of food commodities against a base period value taken as 100 for 2014 to 2016.
    3. Components: Tracks separate indices for cereals, vegetable oils, dairy, meat and sugar.
    4. Frequency: Released monthly.
    5. Recent reading: Touched 131.1 points in July, a three and a half year high.

    Government Initiatives for Agriculture and Edible Oils

    1. National Mission on Edible Oils Oil Palm: Mission to raise domestic oil palm and edible oil production and cut import dependence.
    2. PM-AASHA: Umbrella scheme assuring remunerative prices to farmers, especially for oilseeds and pulses.
    3. Price Stabilisation Fund: Buffer stock mechanism to moderate volatility in pulses and other commodities.
    4. Minimum Support Price: Price assurance to encourage sowing of pulses and oilseeds.

    Key Facts about the Monsoon and Kharif Season

    1. Sixth driest June: June 2026 was the sixth driest June since 1901.
    2. July rainfall: All India July rainfall was 2.4 percent above the long period average.
    3. Import bill: Oilseeds, pulses and cotton imports neared 25 billion dollars in 2025-26.
    4. Grain stocks: 92.6 million tonnes of rice and wheat held on 1 July against a 41.1 million tonne minimum.

    Challenges in Indian Agriculture

    1. Rainfall dependence: A large rainfed area leaves output exposed to monsoon swings.
    2. Import reliance: High dependence on imported edible oils and pulses exposes India to global prices.
    3. Climate volatility: El Nino and heatwaves disrupt both kharif and rabi seasons.
    4. Price transmission: Global food and fuel price shocks feed domestic inflation.
    5. Storage and logistics: Post harvest losses and uneven buffer management persist.
    6. Yield gaps: Low productivity in pulses and oilseeds constrains self sufficiency.

    Way Forward

    1. Raise oilseed output: Expand area and yields under the edible oils mission to cut imports.
    2. Diversify cropping: Promote pulses and climate resilient varieties in rainfed regions.
    3. Strengthen buffers: Use public grain and pulse stocks proactively to contain inflation.
    4. Improve forecasting: Sharpen monsoon and El Nino forecasting for sowing decisions.
    5. Invest in irrigation: Extend micro irrigation to reduce rainfall dependence.

    PYQ Relevance

    [UPSC 2023] Discuss the consequences of climate change on the food security in tropical countries.

    Linkage: The PYQ directly addresses the impact of climate change and climatic variability on food security in tropical countries. El Niño, erratic monsoons, heat stress and global food prices show how climate risks affect India’s kharif, rabi and food inflation.

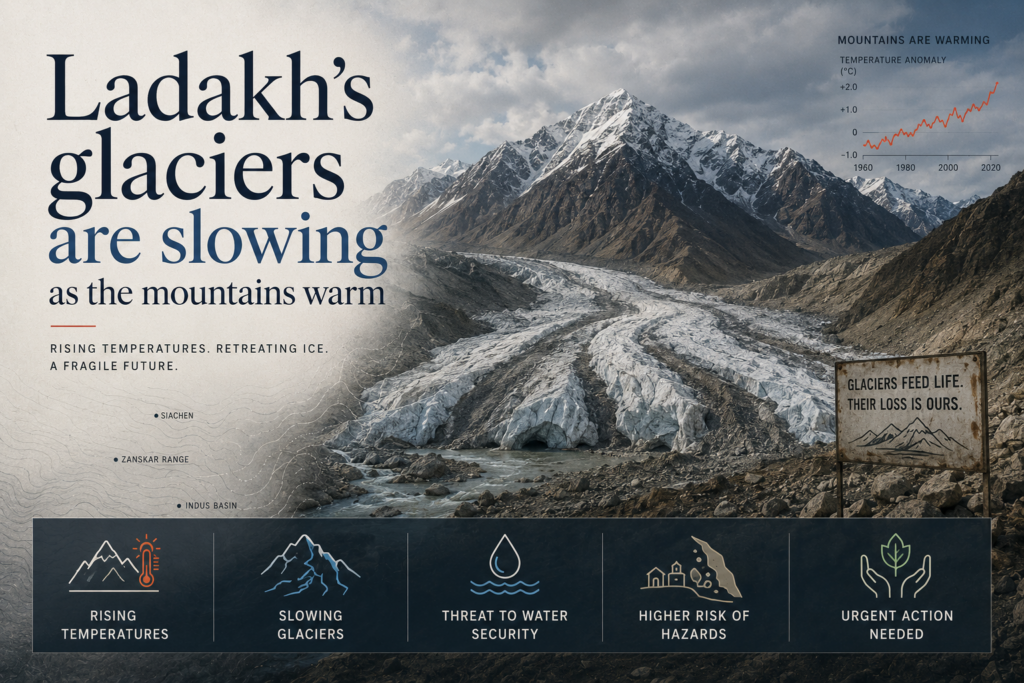
  • Ladakh’s glaciers are slowing as the mountains warm

    Why in the News?

    A new study in the journal The Cryosphere reports that glaciers in the Zanskar region of Ladakh are moving more slowly than they did 30 years ago, as sustained warming thins them and reduces their driving force. The slowdown carries long term implications for the Indus basin, where glacier melt sustains river flows during dry summer months.

    Why are the Zanskar glaciers slowing down?

    1. Thinning mechanism: When a glacier loses more ice than it gains over many years it becomes thinner, and thinner ice exerts less driving force, causing it to flow more slowly.
    2. Warming link: The study connects mass loss, thinning and reduced flow, showing that thinning is not only a consequence of warming but also weakens the glacier’s ability to move.
    3. Downstream effect: Slower flow means the lower parts of a glacier receive less replenishment from higher elevations, making continued shrinkage more likely.
    4. Local variation: Glacier geometry, debris cover and conditions at the snout influence how quickly each glacier responds.

    What is peak water?

    1. Definition: Peak water is the point at which increased melting from a shrinking glacier temporarily raises river runoff before the water supply begins to decline.
    2. Why it matters: More melting may boost flows in the near term, but once glaciers lose a substantial fraction of their stored ice, their meltwater contribution to rivers is expected to drop.

    What did the study find?

    1. Study design: The researchers examined how glacier flow changed from 1992 to 2023 across 12 glaciers in the Zanskar Himalaya using satellite derived surface velocities.
    2. Velocity decline: Glaciers slowed by 2.4 metres per year per decade on average.
    3. Faster thinning: The pace of surface thinning increased from around 0.22 metres per year between 2000 and 2005 to around 0.57 metres per year between 2015 and 2020.
    4. Sample caveat: The 12 glaciers studied are representative, but the Zanskar basin hosts around 1,755 glaciers, so caution is needed before extending the findings to all of Ladakh.

    What are the implications for the Indus basin?

    1. Summer flows: Glacier melt contributes significantly to Indus river flows during the dry summer months, so long term storage decline threatens that supply.
    2. Multiple dependencies: River flows also depend on snowfall, rainfall, groundwater and water management, so slowing glaciers alone will not immediately cause shortages.
    3. Sectors at risk: Continued thinning and slowdown signal declining long term water storage, with implications for water security, agriculture, hydropower and downstream ecosystems in coming decades.

    Why do the study’s own limitations qualify its conclusions?

    1. Sub surface blind spot: Satellite surface velocity observations cannot directly reveal processes beneath the glacier, such as subglacial hydrology or basal sliding, which strongly influence motion.
    2. Data gaps: Long term field measurements of ice thickness, mass balance and bed conditions remain limited in the region, making full attribution of observed changes difficult.
    3. Exceptions to the trend: Some glaciers can temporarily accelerate due to increased meltwater at the bed, glacier surges, or interactions with proglacial lakes.

    What does the global comparison show?

    1. European Alps and Alaska: Similar glacier slowdowns have been reported, driven by the same thinning and reduced driving stress mechanism.
    2. Canadian Arctic and Andes: These regions show comparable slowdowns linked to warming.
    3. Tibetan plateau: Parts of the plateau display the same dominant mechanism of thinning leading to slower flow.
    4. Shared lesson: Glacier slowdown is becoming widespread globally, though local glacier characteristics still shape individual behaviour.

    Conclusion

    The study establishes that Zanskar glaciers are not only losing mass but slowing down, with thinning reducing their capacity to move and replenish lower reaches. This points to a long term decline in stored water that will eventually reduce Indus basin flows after a phase of peak water. The findings underscore the need for sustained ground based monitoring to validate satellite data and to prepare downstream communities for shifting water availability.

    Back2Basics:

    Foundational Context: The Cryosphere and Himalayan Glaciers

    1. About: The cryosphere comprises the frozen parts of the Earth, including glaciers, snow cover, permafrost and ice, that store and release freshwater.
    2. Third Pole: The Hindu Kush Himalaya holds the largest ice mass outside the polar regions and is often called the Third Pole.
    3. Function: Himalayan glaciers act as natural reservoirs, releasing meltwater in warmer months to sustain rivers, agriculture and ecosystems in otherwise arid areas.
    4. Climate indicator: High altitude glaciers respond distinctly to warming, making them valuable natural indicators of environmental change.

    The Zanskar Region and Indus Basin

    1. Location: The Zanskar region lies in Ladakh and hosts some of the largest and most extensive glaciers in the Himalaya.
    2. Climatic setting: Its glaciers receive most of their snowfall from mid latitude westerly disturbances during winter and sit at high altitude.
    3. Indus basin: The Indus rises in the Tibetan plateau and flows through Ladakh, with glacier melt feeding its dry season flows.
    4. Significance: The basin supports water security, agriculture and hydropower across northern India and beyond.

    Key Facts about Himalayan Glacier Monitoring

    1. Study journal: The findings appear in the journal The Cryosphere.
    2. Zanskar glacier count: The basin hosts around 1,755 glaciers, of which 12 were studied.
    3. Observation record: The study covers more than 30 years, from 1992 to 2023.
    4. Peak water: A key concept describing the temporary runoff increase before long term decline.

    Challenges in Glacier Conservation and Monitoring

    1. Data scarcity: Long term field measurements of ice thickness and mass balance are limited in high altitude terrain.
    2. Warming pace: Rising temperatures accelerate thinning and mass loss.
    3. Black carbon: Soot deposition on ice lowers reflectivity and speeds melting.
    4. Glacial lake hazards: Meltwater expansion raises the risk of glacial lake outburst floods.
    5. Downstream dependence: Millions rely on glacier fed rivers, amplifying the impact of any decline.

    Way Forward

    1. Expand ground monitoring: Add measurements of ice thickness, mass balance and meltwater discharge to validate satellite data.
    2. High altitude weather stations: Install continuous observation stations to capture varied mountain climate conditions.
    3. Basin water planning: Prepare Indus basin water management for the eventual decline after peak water.
    4. Reduce black carbon: Cut regional emissions that hasten glacier melt.
    5. Regional cooperation: Share transboundary glacier and river data across the basin.

    PYQ Relevance

    [UPSC 2020] How will the melting of Himalayan glaciers have a far-reaching impact on the water resources of India?

    Linkage: The PYQ directly relates to the impact of Himalayan glacier melt on India’s water resources. Zanskar glacier slowdown and thinning highlight the emerging risks to Indus basin flows, water security and long-term freshwater availability.

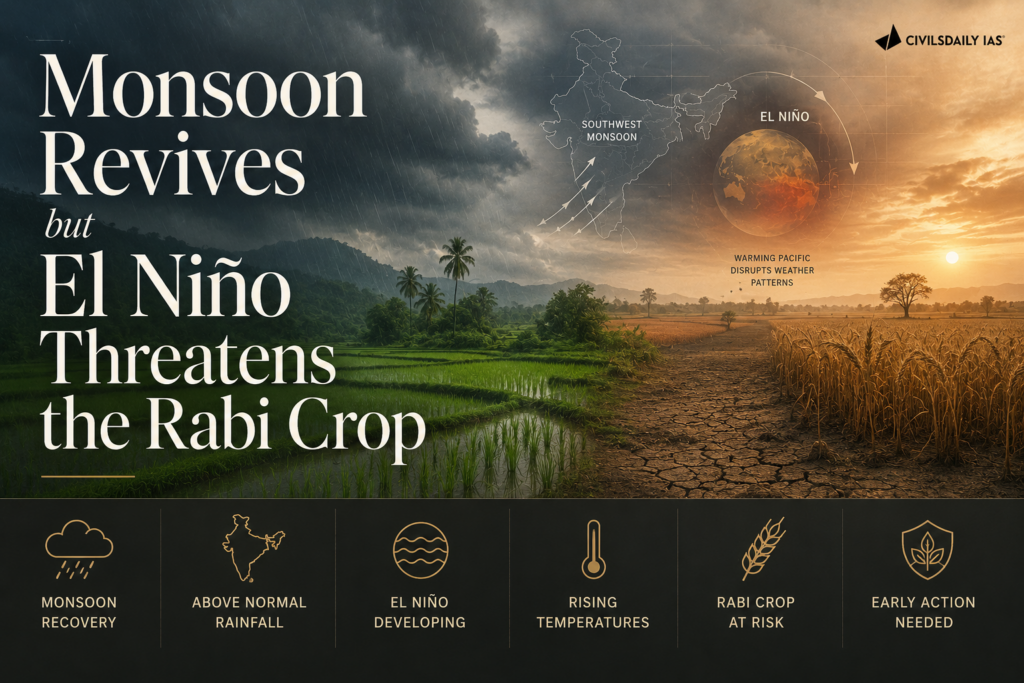
  • Monsoon revives but El Nino threatens the rabi crop

    Why in the News

    The southwest monsoon has revived, cutting the seasonal deficit to 11.5%, but warns that a possible El Nino threatens the rabi crop and keeps urea supply in focus.

    What is El Nino?

    1. Definition: El Nino is the abnormal warming of the central and eastern Pacific that weakens the Indian monsoon and disrupts rainfall.
    2. Crop link: A weak or erratic monsoon reduces soil moisture and reservoir storage needed for the winter rabi crop.

    Why does the rabi outlook matter?

    1. Food and prices: Wheat and other rabi crops shape food inflation and buffer stocks.
    2. Input dependence: Adequate urea and irrigation are needed to protect rabi output if rainfall falters.
    3. Recovery is partial: A narrowed deficit does not remove the risk that late-season El Nino conditions bring.

    Conclusion

    A recovering monsoon eases the kharif outlook but leaves rabi exposed to El Nino. The next milestone is confirmation of El Nino conditions before the rabi season.

    PYQ Relevance

    [UPSC 2015]How far do you agree that the behavior of the Indian monsoon has been changing due to humanizing landscapes? Discuss.

    Linkage: The PYQ explores changing monsoon behaviour and its impact on Indian agriculture. El Niño-induced rainfall variability shows how climatic and human factors can alter monsoon patterns and crop outcomes.

  • Strategic stockpiling of critical minerals under the National Critical Mineral Mission

    Why in the News

    India committed Rs 500 crore in 2025 towards critical mineral stockpiling under the National Critical Mineral Mission (NCMM). The commitment exposes a tension between long gestation domestic mining and the immediate supply risk that flows from dependence on China for processed minerals and rare earth elements.

    What is the National Critical Mineral Mission (NCMM)?

    1. Mandate: The NCMM is a scheme launched in 2025 to build a framework for self reliance across the critical mineral value chain, from exploration to processing.
    2. Stockpiling seed: It allocated Rs 500 crore in 2025 towards building strategic reserves of critical minerals.

    What are critical minerals and rare earth elements?

    1. Critical minerals: These are minerals essential to the economy and national security whose supply faces a high risk of disruption, such as lithium and cobalt.
    2. Rare earth elements (REEs): These are a set of 17 metallic elements used in permanent magnets, electronics and defence systems, most of which are refined in China.

    Why must a reserve hold processed minerals and not raw ores?

    1. Refining lead time: Converting raw ore into usable inputs needs onshore capacity with a long lead time, so raw stock is of little use during a shock.
    2. Composition rule: A reserve must hold refined rare earth oxides, processed minerals and finished components such as permanent magnets.
    3. Midstream gap: India’s midstream refining capacity is nascent, so supply agreements must cover intermediate goods rather than raw material.
    4. Storage integrity: Refined oxides are sensitive to moisture and oxidation, requiring climate controlled and nitrogen atmosphere warehousing.
    5. Rotation cycle: Reserves cannot stay static, so the government must release older stock into the market while procuring fresh supplies.

    What do international frameworks show about coordinated stockpiling?

    1. Quad Critical Minerals Initiative Framework: The Quadrilateral Security Dialogue (Quad) launched this USD 20 billion framework in 2025 to fortify regional supply chains.
    2. G7 Evian summit 2026: The Group of Seven (G7) reiterated a commitment to establishing a standards based market for critical minerals.
    3. Modelling caution: If seven major economies simultaneously built six month reserves, aggregate demand could consume 34% of annual global cobalt supply and 10% of lithium supply.

    Why can uncoordinated stockpiling worsen the shortage it aims to solve?

    1. Demand inflation: Uncoordinated buying inflates global demand and deepens the very shortages stockpiling is meant to ease.
    2. Volatility risk: It heightens the price volatility that a reserve is supposed to hedge against.
    3. Limits of price floors: A guaranteed minimum purchase price addresses underinvestment but rarely addresses scarcity.
    4. Dynamic price bands: A band with a floor near USD 12,000 and a ceiling near USD 30,000 triggers coordinated buying below the floor and releases above the ceiling.

    What are the challenges to critical mineral stockpiling?

    1. Capital intensity: Specialised storage demands heavy and continuous capital expenditure, commercial expertise and multi stakeholder involvement.
    2. Material decay: Reserves risk technological obsolescence and physical decay unless constantly rotated. (Nickel and cobalt powders or precursor materials must be constantly tested and rotated back into active commercial supply chains before their chemical integrity drops.)
    3. Access in friend shoring: Collaboration with industrialised powers requires hedging mechanisms so access matches the size of India’s contribution.
    4. Delayed releases: Reserve releases can be blocked by vetoes, so pre agreed market and geopolitical triggers are needed to automate them.
    5. Sidelining of emerging economies: Larger consumers can crowd out India unless minimum guaranteed allocation baselines are fixed.
    6. China concentration: China dominates the mining and processing of several rare earths, giving it leverage over prices and export flows. Past export restrictions on gallium, germanium, and graphite demonstrated how Beijing’s dominance allows it to instantly manipulate global export flows and drive up input costs for rival manufacturing nations.

    Conclusion

    India’s optimal strategy is to join a coordinated stockpiling platform, potentially housed within the G7, which also covers Quad members. This lets India tap a mature ecosystem without bearing the full cost of independent reserves, provided it secures staggered procurement, automatic release triggers and guaranteed allocation baselines.

    Back2Basics:

    National Critical Mineral Mission (NCMM)

    1. Nodal ministry: Ministry of Mines.
    2. Launched: 2025.
    3. Aim: self reliance across the critical mineral value chain covering exploration, mining, processing and recycling.
    4. Coverage: domestic exploration, overseas asset acquisition, stockpiling and building a processing ecosystem.
    5. Stockpiling outlay: Rs 500 crore seeded in 2025.

    PYQ Relevance

    “[2026] Which of the following statements about Rare Earth Elements (REEs) and Critical Minerals is/are correct?
    1. Modern technological innovations including Artificial Intelligence, robotics and space exploration extensively utilise Rare Earth Elements (REEs).
    2. China has the highest share in mining of REEs followed by India.
    3. The Government of India launched the National Critical Mineral Mission (NCMM) in 2025 to establish a robust framework for self-reliance in the critical mineral sector.
    4. Rare Earth Elements are a set of 13 metallic elements.
    (a) 1 and 3 only
    (b) 3 only
    (c) 1, 3 and 4
    (d) 1, 2 and 4

  • Why Kerala is particularly vulnerable to landslides

    Why in the News?

    Fresh landslides in Kerala, following the earlier Wayanad disaster, have renewed attention on why the state is so slide-prone. The explanation separates the terrain and soil conditions that make slopes unstable from the rainfall events that actually trigger a slide.

    What is the difference between conditioning and triggering factors?

    1. Conditioning factors: These are the standing features that make a slope prone to failure, such as steep gradients, weathered soil and geology. A steep gradient is a slope angle that has a high incline or is very vertical, making the ground less stable and more likely to slide or fall down.
    2. Triggering factors: These are the immediate events that set off a slide, above all intense or prolonged rainfall.
    3. Combined effect: A slope must be both predisposed by conditioning factors and hit by a trigger for a landslide to occur.

    Why is Kerala especially vulnerable?

    1. Western Ghats terrain: Steep slopes of the Western Ghats provide the gradient that makes failure possible.
    2. Weathered soil: Deeply weathered, loose soil on these slopes loses cohesion when saturated.
    3. Extreme rainfall: Short bursts of very heavy rain, worsened by climate change, act as frequent triggers.

    How is landslide risk being mapped?

    1. Landslide Atlas: The ISRO National Remote Sensing Centre’s Landslide Atlas (1998-2022) maps slide-prone zones across India.
    2. Hazard zonation: Such mapping identifies high-risk areas for planning and early warning.
    3. Planning use: Zonation data can guide construction limits and evacuation planning in vulnerable districts.

    Conclusion

    Kerala’s landslides result from predisposing terrain and soil combined with increasingly extreme rainfall triggers. Distinguishing conditioning from triggering factors clarifies where and when slides occur. Hazard zonation using the ISRO Landslide Atlas is the basis for prevention and early warning.

    Back2Basics

    National Landslide Risk Management Strategy (NLRMS), 2019 (NDMA)

    The National Landslide Risk Management Strategy (2019), prepared by the National Disaster Management Authority (NDMA), is India’s first comprehensive framework for reducing landslide risk through prevention, preparedness, mitigation, and capacity building.

    Key Pillars

    1. Hazard Mapping: Prepare national and state-level Landslide Hazard Zonation (LHZ) maps; Identify and monitor vulnerable slopes.
    2. Monitoring & Early Warning: Install rainfall- and ground movement-based monitoring systems; Develop Landslide Early Warning Systems (LEWS).
    3. Mitigation Measure: Slope stabilization, retaining walls, rock bolting, drainage improvement, and bio-engineering; Afforestation and regulated hill cutting.
    4. Land-use Planning: Restrict construction, quarrying, and infrastructure projects in high-risk zones; Integrate hazard maps into master plans.
    5. Capacity Building: Train local authorities, engineers, and communities; Conduct awareness campaigns and mock drills.
    6. Emergency Response: Strengthen search-and-rescue, evacuation plans, and post-landslide recovery.
    7. Research & Technology: Use GIS, Remote Sensing, LiDAR, drones, and satellite monitoring for landslide assessment; Promote research on landslide prediction and climate impacts.

    PYQ Relevance

    [UPSC 2021] Differentiate the causes of landslides in the Himalayan region and Western Ghats.

    Linkage: The PYQ focuses on the causes and mitigation of landslides and slope instability. It explains how steep gradients increase slope failure risk and the need for scientific slope management.

  • How common are cloudbursts in India?

    Why in the News?

    Flash floods triggered by a cloudburst struck Pahalgam in Anantnag on 12 July. Last week, the India Meteorological Department (IMD) rejected claims that cloudbursts caused the recent floods in Assam and Nagaland. The two events have renewed attention on the scientific definition of a cloudburst and its frequent misuse in public discourse.

    What counts as a cloudburst under the IMD’s definition?

    1. Threshold: The IMD defines a cloudburst as 10 centimetres or more of rainfall in an hour over a small area of around 20 to 30 square kilometres.
    2. Scale comparator: Indore receives about 1,062 millimetres of rain in an average year, so a single cloudburst can dump close to 10% of a full year’s rainfall in 60 minutes.
    3. Related category: Some scientists have proposed a mini cloudburst category for 5 centimetres of rain in an hour over the same area, since local topography can make even this devastating.

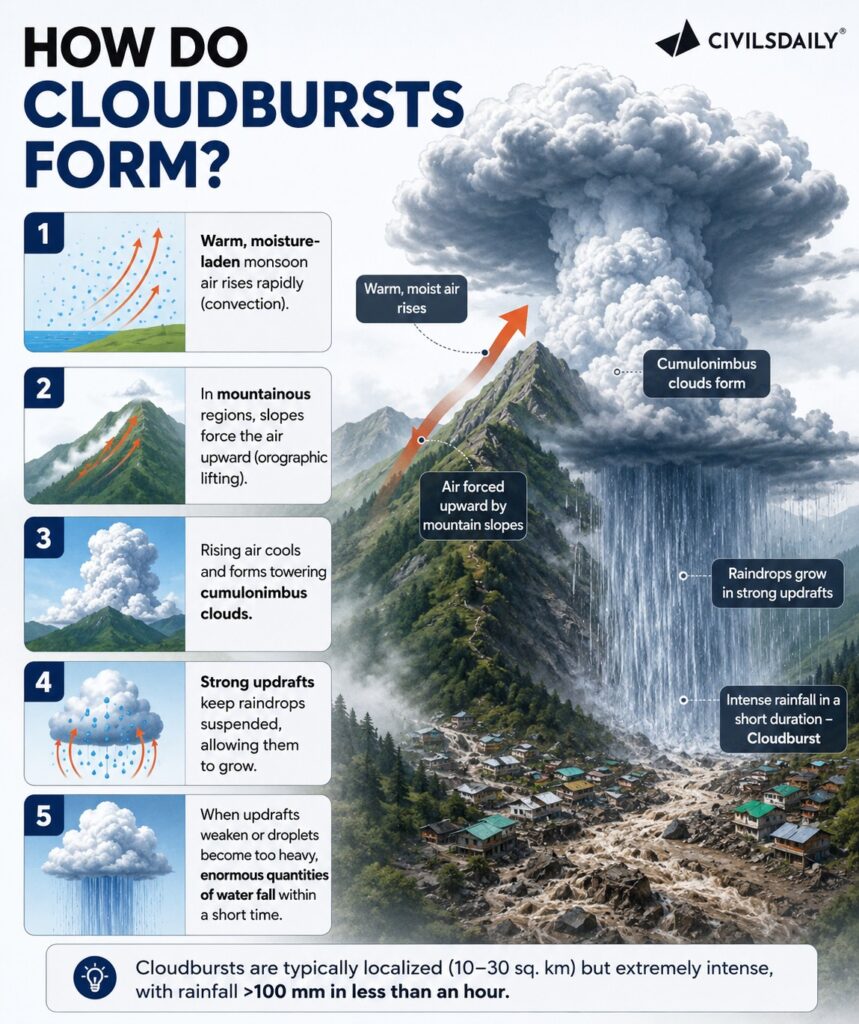
    How does a cloudburst form?

    1. Initial lift: Warm, moist air rises rapidly through convection, and in mountainous terrain this rise is intensified by orographic lifting, where monsoon winds are forced upward by steep slopes.
    2. Cloud growth: As the rising air cools, water vapour condenses into towering cumulonimbus clouds that can reach up to 15 kilometres in height.
    3. Suspension: Strong upward currents keep forming raindrops suspended in the cloud for longer instead of letting them fall immediately.
    4. Discharge: When the weight of accumulated water exceeds what the updraft can hold, or the updraft weakens, the suspended water falls in one release rather than as steady rain.

    How common are cloudbursts in India, and why are they hard to count?

    1. Historical count: Parliament was told in 2019 that the IMD recorded only around 30 cloudburst incidents between 1970 and 2016, a figure many experts consider an underestimate.
    2. Rising frequency: Global warming increases the amount of moisture the atmosphere can hold, making cloudbursts more frequent even though they remain rare compared with ordinary heavy rain.
    3. Monitoring gap: Most cloudbursts occur in remote, high altitude regions where rain gauges and weather stations are sparse, so an event even a few kilometres from a monitoring station may go officially unrecorded despite causing large scale destruction downstream.
    4. Regional concentration: Uttarakhand, Himachal Pradesh, and Jammu and Kashmir have reported a recent surge in events described locally as cloudbursts, particularly in July and August.

    Does the label obscure accountability for poor planning?

    1. Blame diffusion: Calling a heavy downpour a cloudburst turns it into a singular, unforeseeable act of nature, which is harder to do when the stated cause is heavy rain combined with poor drainage.
    2. Dharali precedent: During the 2025 Dharali floods in Uttarakhand, initial reports blamed a cloudburst, but meteorological data later showed the rainfall rate was well below the cloudburst threshold. The underlying causes were illegal construction on riverbeds, deforestation that left soil vulnerable to erosion, and the absence of drainage infrastructure along new all weather roads.
    3. Assam and Nagaland claims: The IMD last week rejected reports that cloudbursts caused recent floods in Assam and Nagaland, including the Upper Assam floods.
    4. Accountability questions avoided: Had the Dharali downpour genuinely been a cloudburst, officials could have avoided questions about why the state permitted construction in high risk zones and why early warning systems failed.

    Why are cloudbursts difficult to forecast?

    1. Model resolution: Weather models estimate average conditions across grid cells, while a cloudburst occurs over an area smaller than a single cell, so detecting one requires high resolution models needing computing power not always available.
    2. Speed of formation: Cloudbursts develop and strike quickly, unlike cyclones or monsoon systems that can be tracked for weeks, leaving forecasters far less data to work with.
    3. Terrain interference: Doppler weather radars emit and receive beams that mountains can block, creating blind spots in exactly the high altitude terrain where cloudbursts are most common.
    4. Sparse instrumentation: Rugged terrain also means fewer automatic weather stations, leaving fewer ground sensors to feed real time data into short term prediction.

    What is India doing to improve cloudburst forecasting?

    1. Nowcasting: The IMD is developing nowcasting technology to issue short term alerts every few hours rather than long range forecasts.
    2. Mission Mausam: Under the government’s Mission Mausam programme, India plans to more than double its radar network from about 40 radars currently and use artificial intelligence to better predict hyperlocal events.
    3. Persistent limits: Even with better technology, a cloudburst is expected to remain harder to predict than a typical rainstorm because of how localised and fast forming it is.

    Conclusion

    A cloudburst is a specific meteorological event defined by the IMD’s own rainfall threshold, not a synonym for any destructive downpour. Attributing flood damage to a cloudburst without checking recorded rainfall data lets authorities treat the disaster as an unforeseeable act of nature rather than examine illegal construction, deforestation and drainage failure. India’s forecasting improvements under Mission Mausam target the science of prediction, but they do not by themselves fix the planning failures the label has repeatedly been used to obscure.

    Back2Basics:

    Mission Mausam

    1. Nodal ministry: Ministry of Earth Sciences.
    2. Launch year: 2024.
    3. Aim: Improve weather and climate forecasting through expanded observation networks, high performance computing and artificial intelligence based prediction.
    4. Key features: Expansion of Doppler weather radar coverage, next generation satellites, and impact based forecasting for more precise, localised warnings.

    PYQ Relevance

    [UPSC 2024] What is the phenomenon of ‘cloudbursts’? Explain.

    Linkage: The PYQ explains cloudbursts, their causes, and forecasting challenges. It updates the topic with IMD clarifications, Mission Mausam, and disaster accountability.

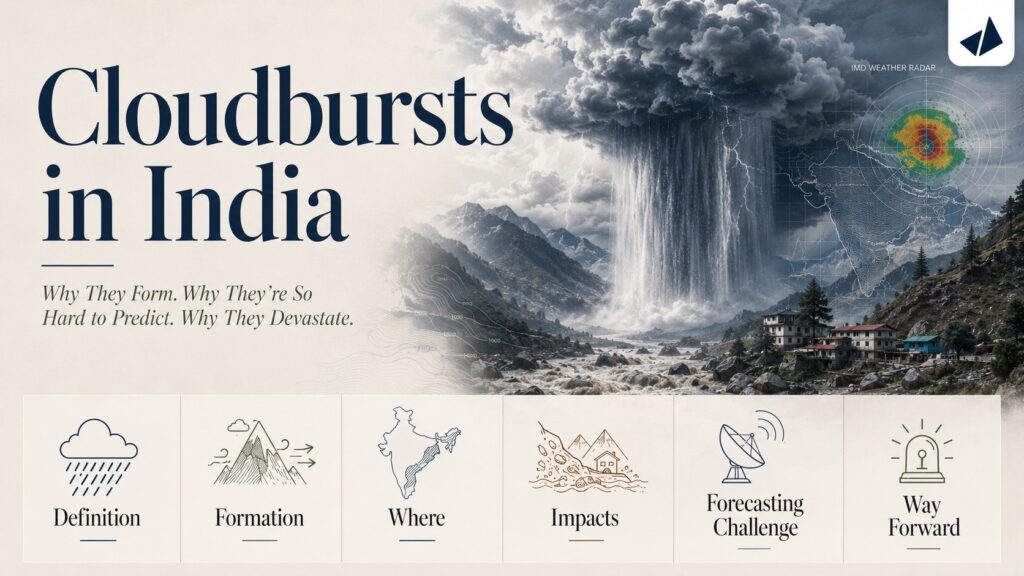
  • Cloudbursts in India

    Why in News?

    Recent flash floods in Himalayan States have brought cloudbursts into focus. The IMD has clarified that many reported “cloudbursts” do not meet its scientific definition, highlighting the need for accurate terminology and better disaster planning.

    What is a Cloudburst?

    • According to the India Meteorological Department (IMD), a cloudburst is 100 mm (10 cm) or more rainfall in one hour over a 20 to 30 sq. km area.
    • Key Features
      • Highly localized and short-duration event.
      • Causes sudden flash floods and landslides due to rapid runoff.
      • Much rarer than normal heavy monsoon rainfall.
      • Mini-cloudburst (proposed): Some scientists suggest a category of 50 mm rainfall in one hour over the same area, as it can also cause severe damage.

    How Common are Cloudbursts in India?

    • Cloudbursts are rare, but their frequency is increasing due to global warming, as warmer air can hold more moisture.
    • IMD recorded around 30 cloudbursts between 1970 and 2016, though experts believe many events went unrecorded.
    • Most occur in remote Himalayan regions, where monitoring stations are sparse.
    • Frequently reported in Uttarakhand, Himachal Pradesh, Jammu & Kashmir, Assam, and the Northeast, especially during July-August.

    How Do Cloudbursts Form?

    Why are Cloudbursts Difficult to Forecast?

    • Highly localized, smaller than weather model grid sizes.
    • Develop rapidly, leaving very little lead time.
    • Mountains block Doppler Weather Radar signals, creating blind spots.
    • Limited Automatic Weather Stations (AWS) in high-altitude areas reduce real-time observations.
    • Hyperlocal prediction requires high-resolution models and massive computing power.

    What is India Doing?

    • IMD Nowcasting for short-term weather alerts.
    • Mission Mausam to strengthen hyperlocal forecasting.
    • Expansion of the Doppler Weather Radar (DWR) network.
    • Installation of more Automatic Weather Stations (AWS).
    • Use of Artificial Intelligence (AI) for improved weather prediction and early warnings.

    Challenges

    • Sparse observation network in mountainous terrain.
    • Radar blind spots due to topography.
    • Limited computing capacity for hyperlocal models.
    • Growing climate change-induced extreme rainfall.
    • Weak enforcement of land-use regulations.

    [2026] Which of the following statements with regard to India’s indigenous new high resolution weather model, the ‘Bharat Forecast System,’ is/are correct?
    1. Its objective is to generate forecasts at the Panchayats cluster level.
    2. It was developed by IIT Delhi.
    Select the answer using the code given below:

    [A] 1 only

    [B] 2 only

    [C] Both 1 and 2

    [D] Neither 1 nor 2