💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: SubsidiesXAgriculture

  • In MP, probe into how farmers’ identities were used to sell cheap moong to govt at a profit

    In MP, probe into how farmers’ identities were used to sell cheap moong to govt at a profit

    Why in the News

    Madhya Pradesh’s Economic Offences Wing (EOW) has booked three computer operators running procurement terminals at cooperative societies in Raisen district for an alleged moong procurement fraud. The operators are alleged to have used the land records of farmers who had never registered to sell under the support price scheme, created procurement registrations in the names of acquaintances, bought moong on the open market at low prices, and sold it to the government at the Minimum Support Price (MSP). The alleged scheme ran across three societies in Badi tehsil over two procurement seasons and netted roughly Rs 13.3 lakh. The criminal case follows two internal cooperative department inquiries. The tension is that the price floor worked exactly as designed while the registration step that decides who may claim it did not, and it has surfaced during sustained farmer protests in the State over moong procurement and MSP implementation.

    What is the Minimum Support Price and how does procurement work?

    1. Minimum Support Price: It is a price floor announced by the Centre for selected crops, so a registered grower is assured a stated rate irrespective of what the open market pays that day.
    2. Who fixes it: The Commission for Agricultural Costs and Prices recommends the level for each season and the Centre announces it.
    3. Coverage against actual purchase: The floor covers 22 crops, and assured physical procurement at scale is concentrated overwhelmingly in wheat and rice, so for other crops a declared floor binds only where an agency actually buys.
    4. The registration step: A grower must first register the land on which the crop was raised, and the produce is then weighed against that registration at a procurement centre before payment is released.

    How was the registration system allegedly turned into a trade?

    1. Operator access to land records: Every operator at a cooperative society has access to the land records of all farmers in the area that centre serves, including those who own plots but have never registered to sell through the support price scheme.
    2. Fraudulent registration: Agricultural land that no farmer had registered was allegedly registered by the accused in the names of their acquaintances, and moong was then weighed through those registrations.
    3. The purchase leg: The moong weighed at the centres was allegedly bought from local markets at a lower price, so the registration manufactured a seller who had grown nothing.
    4. How it surfaced: Farmers in the Raisen hinterland found they had apparently sold moong to the government without ever growing it, registering it or taking it to a procurement centre. Fake registrations were collected and witnesses questioned during the EOW’s complaint verification.

    What do the case figures show about the size of the margin?

    1. Dehri Kala registrations: Entries of 8.095 hectares and a further 4.532 hectares allegedly yielded 151.524 quintals procured at the 2025 support price of Rs 8,682 a quintal, a payout of Rs 13,15,531 against about Rs 4,54,572 spent acquiring the moong, a margin of Rs 8,60,959.
    2. Registration in an accused’s own name: Another operator registered 3.523 hectares in his own name and procured 42.276 quintals for Rs 3,67,040, against an estimated Rs 1,26,828 of cost, a profit of Rs 2,40,212.
    3. Bharkachh Kala registrations: Entries of 3.428 hectares yielded 41.136 quintals worth Rs 3,57,142 against an estimated Rs 1,23,408 of cost, clearing Rs 2,33,734.
    4. How the figures were built: Investigators compared the procurement receipts against prevailing mandi rates for moong of comparable quality at Bareli over the same window.

    Why did the price gap make the fraud worth running?

    1. The spread: Bareli mandi rates for moong swung from as low as Rs 1,500 a quintal to as high as Rs 8,800 depending on grade, against a fixed support price of Rs 8,558 in the 2024 to 2025 season and Rs 8,682 the following season.
    2. A fixed price against a variable one: The support price does not vary by grade while the mandi rate does, so every lot bought below the floor converts into a guaranteed margin at the procurement centre.
    3. The alternative route: The Agricultural Produce Market Committee (APMC) told investigators that the procurement route was never the only option open to the farmers whose names were used, since farmers can independently sell their produce.
    4. The political setting: The case has surfaced during sustained farmer protests in Madhya Pradesh over moong procurement and the implementation of the support price.

    Challenges to MSP procurement

    1. Identity is verified at payment, not at registration: The system checks who is paid but not whether the registered grower actually raised the crop on the registered plot. Eg. Land never registered by any farmer was allegedly registered in the names of acquaintances across three societies in Badi tehsil.
      The Fix: Tie every registration to farmer authenticated consent and to a field or satellite verified sowing record for that survey number before weighing is allowed.
    2. The operator is both data entry and gatekeeper: One terminal operator can create a registration, accept the produce and trigger the payment, so no independent step exists to fail. Eg. All three accused in Raisen ran procurement terminals at the societies where the registrations were made.
      The Fix: Separate registration, weighing and payment authorisation across three roles, with the cooperative society secretary countersigning first time registrations.
    3. Procurement concentrated in wheat and rice: For crops outside that core the floor operates in short seasonal windows with thin agency capacity, which is where leakage collects. Eg. Maize in Punjab routinely sells below its support price for want of a procurement agency.
      The Fix: Publish crop wise and district wise procurement capacity before each season so a grower knows whether the floor will actually be available.
    4. Grade based price variation invites arbitrage: A single flat support price against a wide mandi range for the same crop creates a standing incentive to buy low grade produce and present it at the centre. Eg. Bareli rates ranged from Rs 1,500 to Rs 8,800 a quintal against one fixed floor.
      The Fix: Apply published quality parameters with graded deductions at the weighing stage rather than one undifferentiated rate.
    5. Detection depends on the farmer noticing: A farmer who never intended to sell has no reason to check the procurement record, so a fraudulent entry in his name can sit undisturbed for a full season. Eg. The Raisen farmers learned of the sales only when the entries were traced back to them.
      The Fix: Send an automatic message to the registered land holder at the moment a registration is created against his survey number, not after payment.

    Conclusion

    The failure here is not in the price but in the claim on it. A floor enforced correctly at the counter is still capturable by whoever controls the record of who is entitled to walk up to it, and that record sits with the same operator who processes the transaction. The case is at the investigation stage, with three operators booked after two departmental inquiries. What to watch is whether the response stays confined to a criminal case against three terminal operators or extends to separating registration from procurement across the State’s cooperative societies.

    Back2Basics: Agricultural Produce Market Committee

    1. What it is: It is a statutory market body constituted by a State government to regulate wholesale trade in notified agricultural produce within a defined market area.
    2. Legal basis: Each State’s own Agricultural Produce Market Committee Act governs it, so market rules, fees and the list of notified commodities vary across States.
    3. What it does: It licenses traders and commission agents, runs the regulated market yard or mandi, and records the sale price and volume of each transaction.
    4. Why its record matters: The mandi rate it publishes is the reference price against which an alleged support price diversion can be measured.

    Matching Previous Year Question

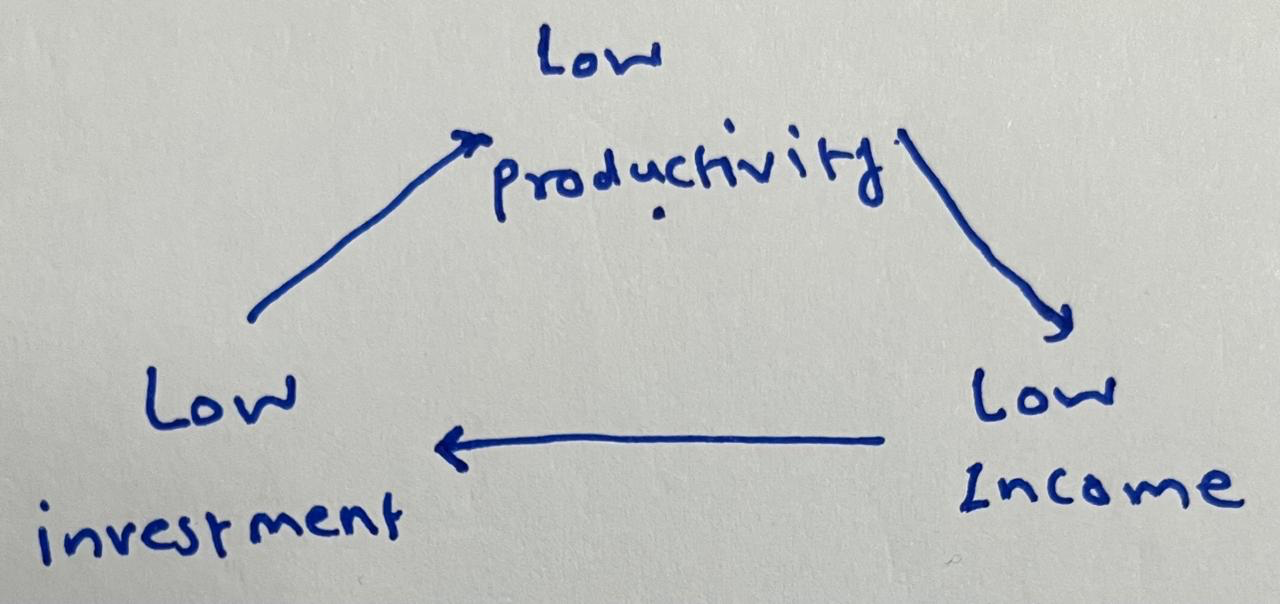
    “[2018, GS3, 10 marks] What do you mean by Minimum Support Price (MSP)? How will MSP rescue the farmers from the low-income trap?”
  • India contracts 17 lakh tonnes of urea at $390 a tonne, a fraction of the April tender price

    Why in the News?

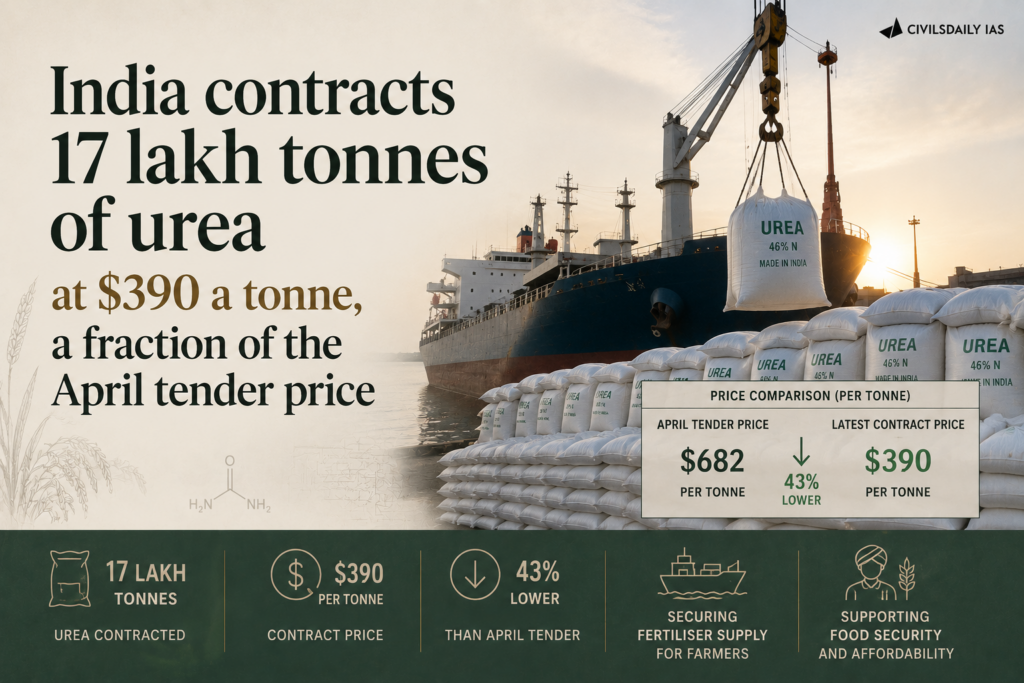
    India has contracted 17 lakh tonnes (1.7 mt) of imported urea at landed prices of $390.25 to $393.65 per tonne, marking a ~58% drop from the peak rates of $935 to $959 per tonne seen in the April 2026 tender. This sharp collapse highlights how heavily India’s fertiliser subsidy bill depends on external factors, ranging from West Asian energy disruptions to Chinese inventory accumulation.

    Global Urea Import Tender Mechanism

    • Nominated State Agencies: Import tenders are invited by designated state-owned canalising agencies like Rashtriya Chemicals and Fertilizers (RCF) and Indian Potash Limited (IPL).
    • Landed Price (CFR): Offers are quoted on a landed basis—covering both material cost and ocean freight to destination ports. This shifts shipping risk to the supplier.
    • Geographical Distribution: Tenders split required tonnages between the East Coast and West Coast to optimize port discharge and domestic logistics.
    • Market Signals: Bids from multiple global traders (e.g., Ameropa Group) establish the benchmark. High oversubscription indicates a loose global supply market.

    Price Trajectory & Global Supply Dynamics

    1. April Peak ($935–$959/tonne): Driven by peak war risk premiums, high global fuel prices, and Strait of Hormuz shipping anxieties.
    2. May Moderation ($444.9–$449.3/tonne): Easing immediate supply shocks.
    3. July/August Drop ($390.25–$393.65/tonne): Triggered by:
      • China’s Surplus Inventory: Domestic in-plant inventories in China surged 76% year-on-year, turning it into a major swing supplier.
      • Re-routed Supplies: Iranian material reaching markets through China.
      • Alternative Sourcing: Diversification of LNG feedstock by agencies like GAIL and IOC away from Hormuz transit routes toward the US, Oman, Norway, Angola, Congo, Indonesia, and Trinidad.

    Current Supply & Demand Position

    • Adequate Reserves: Imports reached 25.08 lakh tonnes in Q1 (April–June 2026) compared to 8.38 lakh tonnes in the previous year.
    • Domestic Production: Expanded to 71.53 lakh tonnes in Q1 2026.
    • Cropping Seasons Covered: Sufficient availability reported across both the ongoing Kharif (monsoon) season and upcoming Rabi (winter/spring) sowing.

    Challenges in India’s Fertiliser Policy

    • Subsidy Exposure: Urea sells at a statutorily controlled Maximum Retail Price (MRP), meaning any surge in landed cost directly increases the exchequer’s subsidy burden.
    • Nutrient Imbalance: Controlled urea pricing versus decontrolled phosphatic and potassic nutrients encourages over-application of nitrogen (N), skewing the ideal 4:2:1 (N:P:K) ratio.
    • Phosphate Vulnerability: While urea and LNG supply sources have been widened, Di-ammonium Phosphate (DAP) and raw intermediates (phosphoric acid, ammonia, sulphur) remain vulnerable to concentrated import sources and price spikes.
    • Feedstock Dependence: Domestic plants remain tied to imported LNG, linking production costs directly to international gas trends.

    Statutory & Regulatory Framework

    • Essential Commodities Act, 1955: Empowers the Union Government to regulate production, stock limits, supply, and pricing of fertilisers.
    • Fertiliser (Control) Order, 1985 & Movement Control Order, 1973: Governs quality standards, dealer registrations, and inter-state distribution.
    • New Urea Policy, 2015: Promotes energy efficiency in production units and mandates 100% Neem Coating of domestic urea to prevent industrial diversion.
    • Nutrient Based Subsidy (NBS) Scheme, 2010: Provides a fixed annual per-kg subsidy on N, P, K, and S for decontrolled fertilisers (DAP, MOP, Complex).
    • Direct Benefit Transfer (DBT): Releases subsidies to manufacturers only after Aadhaar-authenticated point-of-sale (PoS) transactions at retail outlets.

    Key Government Initiatives

    • PM PRANAM: Encourages States to reduce chemical fertiliser usage by sharing the resulting subsidy savings.
    • One Nation One Fertiliser: Standardises all subsidised crop nutrients under the single Bharat brand.
    • Nano Urea: Liquid alternative developed by IFFCO to lower overall bulk tonnage requirements.
    • Plant Revivals: Reactivation of closed units (Ramagundam, Gorakhpur, Sindri, Barauni, Talcher) to boost domestic capacity.
    • Coal Gasification: Talcher plant designed to produce urea using coal gasification rather than natural gas, cutting gas import reliance.

    Key Concepts

    • Urea: Solid nitrogenous fertiliser (carbamide) carrying 46% Nitrogen—the highest among solid fertilisers.
    • Di-ammonium Phosphate (DAP): Phosphatic fertiliser containing 18% Nitrogen and 46% Phosphorus.
    • Fertiliser Association of India (FAI): Industry body (est. 1955) providing production, import, and consumption stats for supply planning.
    • Muriate of Potash (MOP): Fully import-dependent nutrient; India has no commercial potash reserves.

    [2020] With reference to chemical fertilizers in India, consider the following statements:
    1. At present, the retail price of chemical fertilizers is market-driven and not administered by the Government.
    2. Ammonia, which is an input of urea, is produced from natural gas.
    3. Sulphur, which is a raw material for Phosphoric acid fertilizer, is a by-product of oil refineries.
    Which of the statements given above is/are correct?
    (a) 1 only
    (b) 2 and 3 only
    (c) 2 only
    (d) 1, 2 and 3
    Answer: (b)”

  • Why the Iran war didn’t cause a fertiliser crisis

    Why in the News?

    The United States-Israel versus Iran war and the effective closure of the Strait of Hormuz triggered a severe global energy supply shock, yet India’s urea supply held up. Government-pushed diversification of liquefied natural gas (LNG) sourcing lifted urea output to 71.5 lakh tonnes in April-June 2026, up 5.4% year-on-year. The contrast is that the same proactiveness was not replicated for phosphatic fertilisers, leaving di-ammonium phosphate and complex fertilisers exposed.

    What are the main fertiliser nutrients?

    1. Nutrient roles: Urea supplies nitrogen (N); di-ammonium phosphate (DAP) supplies phosphorus (P); muriate of potash (MOP) supplies potassium (K). Complex fertilisers blend N, P, K and sulphur (S).
    2. Feedstock links: Urea depends on natural gas as feedstock. DAP and complex fertilisers depend on phosphoric acid, sulphur and ammonia.

    What kept urea supply stable through the shock?

    1. Feedstock disruption: Before the war, 53-54% of India’s LNG imports came from Qatar and the United Arab Emirates. Shipping blockades and strikes on liquefaction infrastructure broke these contracts.
    2. Sourcing pivot: The government pushed public firms to diversify LNG sourcing, buying more from the United States, Oman, Nigeria, Angola and others. This pivot to the spot market meant higher prices but secured supply.
    3. Output recovery: Urea production fell to 17.5 lakh tonnes in March 2026 from 24.7 lakh tonnes a year earlier, then recovered to 25.4 lakh tonnes by June. Cumulative April-June output of 71.5 lakh tonnes exceeded the previous year.
    4. Import surge: India imported 25.1 lakh tonnes of urea in April-June 2026, up from 8.4 lakh tonnes a year earlier. Higher import costs were not passed on to farmers.

    Why did DAP and complex fertilisers stay tight?

    1. Sulphur bottleneck: Sulphur is needed to make sulphuric acid, which breaks down rock phosphate into phosphoric acid. Without both acids, there can be no DAP, single super phosphate or complex fertilisers.
    2. Price spike: Sulphur landed prices reached about $1,100 per tonne against a normal $150-250 range. The spike predated the war, worsened by Ukrainian drone strikes on Russian refineries.
    3. Phosphoric acid costs: Imported phosphoric acid prices rose from $1,055 per tonne in early 2025 to $1,700 for the July-September 2026 quarter. This steady climb squeezed domestic manufacturers.
    4. No diversification: Unlike urea, phosphatic fertiliser sourcing was not widened. Reduced domestic output was combined with lower imports.

    What is the El Nino monsoon factor?

    1. Rainfall deficit: El Nino-induced monsoon deficiency left June-July all-India rainfall 12.6% below normal. Kharif sowing area fell 2.9% from last year.
    2. Subdued demand: Weak rainfall reduced fertiliser offtake, easing pressure on supply. This contrasts with the surplus monsoon scrambles of 2024 and 2025.

    What are the challenges to fertiliser security?

    1. Import dependence: India depends heavily on imports for sulphur, phosphoric acid and ammonia. Concentrated West Asian sources leave it exposed to conflict.
    2. Subsidy pressure: Shielding farmers from higher costs inflates the fertiliser subsidy bill beyond budget estimates. Sustaining it requires additional provisions for DAP and complex fertilisers.
    3. Single-choke geography: Much feedstock still transits the Strait of Hormuz. A single choke point can disrupt multiple nutrients at once.
    4. Phosphate concentration: Few global suppliers dominate phosphoric acid and sulphur. Price-setting power rests with them during shortages.
    5. Election-linked stocking: Upcoming State elections raise pressure to guarantee rabi-season supply. Political timelines complicate purely economic supply planning.

    Conclusion

    Proactive supply-side management, chiefly LNG diversification and pre-emptive urea imports, insulated India’s nitrogen supply from the worst energy shock in decades. The unresolved vulnerability is phosphatic and complex fertilisers, where sulphur and phosphoric acid sourcing was not diversified and prices continue to climb.

    Back2Basics

    1. Urea: Nitrogen fertiliser made from natural gas; the most consumed fertiliser in India and heavily subsidised.
    2. DAP: Di-ammonium phosphate, a phosphorus source dependent on imported phosphoric acid.
    3. Nutrient Based Subsidy: Regime under which non-urea fertilisers (DAP, MOP, complex) receive a fixed per-nutrient subsidy.
    4. Urea pricing: Sold at a statutory notified price with the gap met by subsidy under the Department of Fertilizers.
    5. Key choke point: Strait of Hormuz, the transit route for much of India’s LNG and fertiliser feedstock.

    The New Urea Policy 2015:

    1. It aims to maximize domestic production, promote energy efficiency in manufacturing units, and rationalize government subsidy burdens.

    Core Objectives

    1. Boost Domestic Output: Increase indigenous manufacturing capacity to reduce reliance on foreign imports.
    2. Energy Conservation: Set strict specific energy consumption targets for production units to lower carbon footprints.
    3. Subsidy Rationalization: Streamline financial support and cut down government expenditure on the sector.

    Key Measures

    1. Neem Coating: Mandated all domestic producers to coat 100% of subsidized urea with neem oil, stopping illegal diversion to non-agricultural sectors.
    2. Energy Grouping: Categorized gas-based plants into distinct groups to fix realistic and progressive energy efficiency norms.
    3. Protected Pricing: Ensured continuous and timely supply of fertilizer to farmers without increasing the retail price

    PYQ Relevance

    [UPSC 2023] What are the direct and indirect subsidies provided to farm sector in India? Discuss the issues raised by the World Trade Organization (WTO) in relation to agricultural subsidies.

    Linkage: UPSC has consistently examined agricultural subsidies, their fiscal implications, and India’s compliance with WTO rules. The article shows how rising global fertiliser and LNG prices increase India’s subsidy burden while the government continues to shield farmers through subsidised urea and nutrient-based support for non-urea fertilisers

  • Madhya Pradesh farmers march to Bhopal demanding 100% moong procurement at MSP

    Why in News?

    Around 2,000 Madhya Pradesh farmers under the Samyukt Kisan Morcha marched to Bhopal demanding 100% moong procurement at Minimum Support Price (MSP), against the current 25% cap under the central Price Support Scheme, along with fixes to fertiliser distribution.

    Key Highlights

    1. Scale: Around 2,000 farmers marched to Bhopal.
    2. Organiser: March organised under the Samyukt Kisan Morcha banner.
    3. Demand: 100% moong procurement at MSP, against the current 25% cap.
    4. Scheme cited: Current cap operates under the central Price Support Scheme.
    5. Additional demand: Fixes to fertiliser distribution.

    What is the Price Support Scheme (PSS)?

    1. A component of the PM-AASHA (Pradhan Mantri Annadata Aay Sanrakshan Abhiyan).
    2. Implemented by the Department of Agriculture & Farmers Welfare.
    3. Provides physical procurement of notified pulses, oilseeds and copra at the Minimum Support Price (MSP) when market prices fall below MSP.
    4. Procurement is undertaken by Central Nodal Agencies in coordination with State governments.

    What is Minimum Support Price (MSP)?

    1. MSP is the minimum price at which the government purchases crops from farmers to protect them from sharp price declines.
    2. Recommended by the Commission for Agricultural Costs and Prices (CACP) and announced by the Central Government.
    3. MSP is currently announced for 23 crops.

    “[2018, GS3, 10 marks] What do you mean by Minimum Support Price (MSP)? How will MSP rescue the farmers from the low-income trap?”
    [2020] Consider the following statements:

    1.In the case of all cereals, pulses and oil-seeds, the procurement at Minimum Support Price (MSP) is unlimited in any State/UT of India.
    2.In the case of cereals and pulses, the MSP is fixed in any State/UT at a level to which the market price will never rise.

    Which of the statements given above is/are correct?
    a) 1 only
    b) 2 only
    c) Both 1 and 2
    d) Neither 1 nor 2

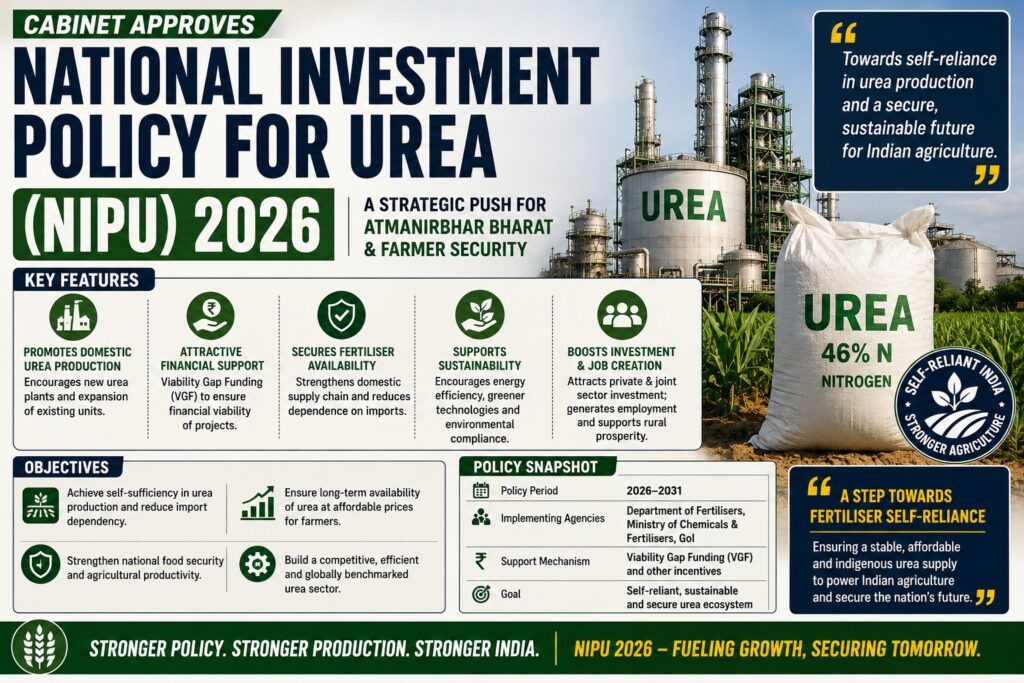
  • Cabinet’s National Investment Policy for Urea (NIPU) 2026

    Why in the News?

    The Union Cabinet has approved the National Investment Policy for Urea (NIPU) 2026, restructuring the return framework for urea manufacturers to attract fresh investment in domestic capacity. This comes against an annual urea subsidy bill of Rs 1,42,175.74 crore for 2025-26.

      What are the Pillars of the National Investment Policy for Urea (NIPU) 2026?

      1. Aim: The policy aims to encourage the establishment of new gas-based urea manufacturing plants across the country to reduce dependence on imports and bridge the gap between domestic production and demand.
      2. The National Investment Policy for Urea-2026 (NIPU-2026) rests on three core pillars: cost separation, assured returns, and foreign exchange risk mitigation.
      3. Return band: The policy sets a Return on Equity (ROE) band of 12 to 16 percent for new urea manufacturing investment.
      4. Cost restructuring: It restructures how production costs are calculated and reimbursed to manufacturers.
      5. Subsidy delivery: Distribution continues through Direct Benefit Transfer (DBT), credited after retailers confirm sale to farmers.
      6. Self-reliance objective: The stated goal is to reduce India’s dependence on imported urea by making domestic capacity commercially viable.

      Why does urea self-reliance remain unresolved despite this policy?

      1. Subsidy scale: The current annual subsidy bill of Rs 1,42,175.74 crore reflects the price gap between controlled retail urea prices and actual production cost.
      2. Investment history: Previous urea policy revisions have not sufficiently attracted new private investment in domestic plants.
      3. Import dependence: India continues to import a share of its urea requirement despite decades of subsidy support to domestic units.
      4. Farmer price link: Retail urea prices remain fixed for farmers regardless of the ROE band offered to manufacturers.

      Conclusion

      The National Investment Policy for Urea 2026 targets manufacturer incentives rather than farm gate prices, betting that better returns on investment will draw the domestic capacity that decades of subsidy alone did not. Whether the 12 to 16 percent ROE band is sufficient to shift investment decisions remains to be tested against actual capacity additions.

      Value Addition:

      Urea Subsidy Scheme:

      Urea fertiliser subsidy in India is a central government scheme where the state fixes a low Maximum Retail Price (MRP) of ₹242 per 45-kg bag for farmers, while the government pays the remaining high production or import cost directly to manufacturers.

      Scheme Mechanics

      1. Fixed MRP: Farmers pay a low, controlled price of ₹242 per 45-kg bag (excluding taxes and neem-coating charges).
      2. Government Payout: The center pays the difference between the actual high cost of making or importing urea and the low selling price directly to the factory owners.
      3. Control: The Ministry of Chemicals and Fertilizers manages the policy and distribution across the country.

      PYQ Relevance

      [UPSC 2023] What are the direct and indirect subsidies provided to farm sector in India? Discuss the issues raised by the World Trade Organization (WTO) in relation to agricultural subsidies.

      Linkage: The PYQ examines India’s fertiliser subsidy regime and related WTO concerns. NIPU 2026 reforms urea subsidies to boost domestic production while retaining farmer subsidies, linking directly to agricultural subsidy debates.

      1. What do you mean by Minimum Support Price (MSP)? How will MSP rescue the farmers from the low-income trap?

        MSP is the government-declared assured floor price at which the government procures specific agricultural crops from farmers, through agencies like FCI, NAFED and state procurement bodies.

        Announced before the sowing season based on recommendations of the Commission for Agricultural Costs and Prices (CACP)

        Intended to cover the cost of production + reasonable margin (50% over A2+FL cost)

        Notified for 23 crops (22 mandated crops andFRP for sugarcane)

        Role of MSP in rescuing farmers from the Low-Income Trap

        Predictability – Assured pricing helps farmers plan crop investments, buy better inputs and adopt new technologies.

        Crop diversification through higher MSPs for nutri-cereals and oilseeds. Eg- higher MSP hikes for millets in recent years

        Improved creditworthiness of farmers due to MSP-backed income – Reduce dependence on moneylenders.

        Enhances Food Security through the Public Distribution System (PDS)

        Strengthens Rural Economy – higher rural demandmultiplier effect on rural economy

        Benchmark for private buyers: If traders offer prices below MSP, farmers can opt to sell to government agencies instead.

        Limitations of MSP

        Effective mainly for wheat and rice in states like Punjab, Haryana, MP, UP

        MSP growth has not kept pace with rising production costs. (CRISIL Report)

        Limited Reach – only 6% farmers benefitted (Shanta Kumar committee)

        94% of the total agri and allied sector output is outside MSP support.

        Limited storage capacity has resulted in huge piling of stocks in FCI warehouses.

        Way Forward

        Shift towards Regenerative Agriculture Incentives – Eg- DBT for farmers adopting soil-friendly inputs, micro-irrigation, and low-carbon practices

        Price Deficiency Payment (MP’s Bhavantar Bhugtan Yojana)

        MSP 2.0 based on 3 D’s – Decentralisation, Diversification and Digital Procurement.

        MSP can act as a meaningful income stabiliser only when it is complemented by efficient procurement, strong market linkages, and inclusive access

      2. What are the direct and indirect subsidies provided to farm sector in India? Discuss the issues raised by the World Trade Organization(WTO) in relation to agricultural subsidies.

        The total government subsidy for food and fertilizers for the fiscal year 2025-26 is budgeted at It constitutes around 2% of India’s GDP and 21% of farmer’s income.

        Direct subsidies –

        These involve direct budgetary support or cash transfers to farmers and agricultural institutions.

        Income support schemes –

        PM-KISAN

        Raythu bandhu Scheme of Telangana

        MSP For 23 crops to ensure Income Security

        Interest subvention through Kisan Credit Cards – KCC)

        Crop insurance premium subsidy under PMFBY (Pradhan Mantri Fasal Bima Yojana)

        Indirect subsidies to the farm sector

        These reduce production costs or guarantee revenue without direct cash payment:

        Fertiliser subsidy – Subsidised urea, DAP and other fertilisers under the Nutrient Based Subsidy

        Subsidy on agricultural infrastructure

        PM-KUSUM – Subsidy for Solar Pumps

        PMFBY – Subsidy for Micro Irrigation

        Agriculture Infrastructure Fund (AIF) – Credit-linked subsidy for cold storage

        Gramin Bhandaran Yojana – Support for rural godowns and storage

        Power & irrigation subsidy

        Free or highly subsidised electricity for irrigation pumps

        Subsidised canal and micro-irrigation schemes (Eg- PMKSY)

        Seed and mechanisation subsidy – Eg- Sub Mission on Agriculture Mechanisation

        Research & Extension services – Funding to ICAR, Krishi Vigyan Kendras (KVKs)

        Issues raised by WTO regarding India’s agricultural subsidies

        Subsidy Classification by WTO

        Green Box – Allowed (non-trade distorting). Eg- extension, infrastructure

        Blue Box – Production-limiting subsidies

        Amber Box – Trade-distorting subsidies. (10% of output) Eg- MSP, input subsidies

        Trade-distorting support – MSP, fertiliser, power & irrigation subsidies classified as Amber Box. May exceed 10% de-minimis limit for developing countries

        WTO decision (Nairobi, 2015) prohibits export subsidies. India’s sugar export incentives were challenged & ruled WTO-inconsistent

        Transparency issues – Allegations of under-reporting or delayed reporting of subsidies

        Environmental concerns – overuse of fertilisers and groundwater, causing Soil degradation, Groundwater depletion and Ecological stress

        The sustainable path for ensuring farmer welfare remains protected includes gradual shift towards Green-Box-compliant support such as direct income transfers, infrastructure creation, R&D, crop insurance and climate-resilient agriculture.