💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS3

  • Ground control

    Why in the News

    Nine employee associations of the Indian Space Research Organisation (ISRO) have written to the chairman seeking clarity on staff strength, recruitment and the outsourcing of core functions. The letter was sent on the day the agency recorded its largest success of the year, the launch of its first geosynchronous imaging satellite, EOS-05, on the Geosynchronous Satellite Launch Vehicle (GSLV). The grievance follows from the Indian Space Policy of April 2023, which signalled that ISRO would eventually stop building commercial satellites and launch vehicles and would concentrate on exploratory missions. ISRO has stated that it will not be privatised or reduced, and the Indian National Space Promotion and Authorisation Centre (IN-SPACe), the body set up to enable private participation, has stated that the agency will not be diminished and that only industry’s role must grow. Neither institution has addressed the concern the letter actually raises, which is the loss of jobs. The underlying question is whether the sector’s direction still matches its founding principle, that space technology is an instrument of social development rather than a contest for prestige.

    What does the Indian Space Policy, 2023 set out?

    1. A division of roles: The policy separates the space sector into ISRO, IN-SPACe and NewSpace India Limited, and assigns each a distinct function instead of leaving all of them with ISRO.
    2. ISRO’s redefined remit: ISRO is to move out of routine operational and commercial production of satellites and launch vehicles, and towards research and development in advanced technologies and exploratory missions.
    3. IN-SPACe as the single window: IN-SPACe authorises and supervises the space activities of private entities, so a company deals with one authorising body rather than with the operator of the launch infrastructure.
    4. NewSpace India Limited as the commercial arm: The public sector company under the Department of Space is responsible for commercialising space technologies and platforms developed with public money.

    What are the employee associations asking for?

    1. Staff strength and recruitment: The associations want stated numbers on sanctioned strength and future recruitment, since a shrinking mandate implies a shrinking establishment.
    2. Outsourcing of core functions: The letter distinguishes contracting out manufacturing from contracting out functions the agency treats as core, and seeks clarity on where that line now falls.
    3. The institutional replies avoid the question: Both the agency and the authorisation body have answered on the agency’s continued existence, which was not what was asked.
    4. The timing is the point: The grievance surfaced on a day of technical success, which indicates that the concern is about the institution’s trajectory and not about its capability.

    Which vision of the space programme is the sector following?

    1. The founding principle: The programme was built on a refusal to be drawn into space races and on the use of space technology as a tool for social development, meaning communication, weather and resource mapping for domestic needs.
    2. The competing image: The alternative is space as an emblem of national power, membership of a small club of space faring countries, and a proliferation of startups as evidence of arrival.
    3. The 2035 test the sector is being set: If the sector is to be a source of export earnings and a nucleus of value added services that absorbs skilled labour and creates jobs, hard choices taken now may be justified.
    4. Where the line falls: Joining a bandwagon driven by billionaire ambition and notions of conquest is a different objective from either, and the case for restructuring collapses if that is what it delivers.

    What does the comparison with NASA show?

    1. The budget gap: The National Aeronautics and Space Administration (NASA) operates on $24.4 billion against the Department of Space’s Rs 13,705 crore, roughly 16 times larger.
    2. NASA also contracted: NASA’s budget fell from 0.7% of American gross domestic product in 1966 to 0.1% now, so its own shift to contracting out followed a sustained loss of fiscal share.
    3. Its establishment shrank with it: NASA’s civil service headcount fell from about 36,000 at the peak of the Apollo programme to about 14,000 today, which is the trajectory ISRO’s employees are reading against.
    4. The unaddressed comparator: China’s space programme has not been seriously reckoned with in India’s planning, and it is the one operating at a scale and cadence that directly bears on India’s position.

    Is the new private base the same as the old one?

    1. ISRO never made everything itself: Unlike NASA in its early years, which designed and made every component, ISRO has always had a manufacturing relationship with private industry, including Walchandnagar Industries and Larsen and Toubro.
    2. The entrants are of a different type: The current activity is not established companies building on decades of manufacturing experience but new entrants funded by foreign capital that may not stay.
    3. The business model has shifted: Most new entrants are interested in satellite data as a service rather than in building hardware, which is a different industrial base from the one that supplied the agency.
    4. The transferable capability is therefore narrower: A vendor base built on data services cannot absorb the manufacturing functions ISRO is being asked to shed.

    Challenges to ISRO’s restructuring

    1. In house capability is easy to lose and slow to rebuild: Skills that live in the hands of a small number of engineers disappear once the work is contracted out and the staff are not replaced. Eg. Cryogenic engine development took India close to two decades to master after external supply was cut off.
      The Fix: Ring fence a defined set of critical technologies as retained in house capability, with recruitment sanctioned against them irrespective of outsourcing elsewhere.
    2. The private demand base is thin: A domestic space economy built on data services has few anchor customers other than government departments, so private capacity depends on public orders it is meant to replace. Eg. Earth observation demand in India is dominated by central and State government users.
      The Fix: Commit an anchor procurement volume for satellite data and launch services over a fixed multi year period, so private capacity is built against contracted demand.
    3. Foreign capital in the entrant base is mobile: Startups funded by capital that can exit quickly cannot be relied on to hold strategic capability through a downturn. Eg. Global space venture funding has moved sharply between years, tightening after periods of expansion.
      The Fix: Condition the transfer of any strategic technology on domestic ownership thresholds and on a minimum period of operation in India.
    4. Transferring a launch vehicle is harder than transferring a design: Handing production of a vehicle to industry moves drawings but not the accumulated process knowledge that makes a launch repeatable. Eg. The Small Satellite Launch Vehicle technology transfer to industry involved an extended period of hand holding rather than a clean handover.
      The Fix: Structure every technology transfer with a defined number of jointly executed missions before the agency withdraws.
    5. The regulatory body is also the promoter: IN-SPACe both promotes private participation and authorises it, so the function that grants approvals is the function measured on how many approvals it grants. Eg. Authorisation and promotion sit within one body rather than in separate agencies.
      The Fix: Separate the authorisation function into a statutory regulator with its own appointment process, leaving promotion with the existing body.

    Conclusion

    The agency’s technical record is not what is in question, and a successful launch is precisely why the staffing letter is difficult to dismiss. What is unresolved is that two institutions have given assurances about the agency’s survival while declining to state what happens to the people inside it, and an assurance that avoids the question asked is not an answer. The concrete thing to watch is whether the Department of Space publishes a transparent policy stating sanctioned staff strength, the recruitment pipeline and the specific functions that will remain in house.

    Back2Basics: Geosynchronous Satellite Launch Vehicle

    1. What it is: A three stage Indian launch vehicle designed mainly to place communication and other heavier satellites into geosynchronous transfer orbit.
    2. Its stages: It uses a solid first stage with liquid strap on boosters, a liquid second stage, and an indigenous cryogenic upper stage.
    3. Why the cryogenic stage matters: Cryogenic propulsion burns liquid hydrogen with liquid oxygen at very low temperatures, giving the high efficiency needed for the final push to a high orbit, and India developed it after external supply was withheld.
    4. Its record: The vehicle has a higher failure rate than India’s Polar Satellite Launch Vehicle, which is why each successful GSLV flight is treated as a significant outcome.

    [2026] Consider the following statements about involvement of private entities in India’s space programme:

    1. IN-SPACe is an autonomous agency formed to facilitate participation of private entities.

    2. Agnikul Cosmos launched the world’s first flight using 3D-printed rocket engine.

    3. Skyroot Aerospace has developed liquid fuel for GSLV.

    (a) 1 only

    (b) 2 and 3 only

    (c) 1 and 2 only

    (d) 1, 2 and 3
  • SC refuses extension for Aravalli panel to submit final report

    Why in the News

    The Supreme Court has refused a six month extension sought by the high powered committee it appointed to define the Aravalli hills and range, and has directed the panel to submit its final report by 30 November. The committee was constituted to evolve a uniform definition of the ecologically fragile Aravalli hills and range and to recommend measures to regulate future mining. A three judge Bench headed by the Chief Justice of India observed that the panel appeared to be waiting for the Chief Justice’s retirement, which falls on 9 February 2027, and made clear that no further extension would be granted. The Bench also directed the panel to work continuously, to file interim reports on urgent issues, and to hear all stakeholders including tribal communities in Rajasthan and Gujarat. The tension is that a definition still unsettled after repeated extensions is the same definition that determines where mining may lawfully continue in the meantime.

    What is the high powered committee tasked with?

    1. Composition: It is a five member panel constituted by the Supreme Court and headed by the Director General of the Indian Council of Forestry Research and Education (ICFRE), the Union government’s forestry research body.
    2. First task, the definition: It must evolve a single uniform definition of what counts as the Aravalli hills and the Aravalli range, applicable across the States the range runs through.
    3. Second task, mining regulation: It must recommend the measures by which future mining in the defined area is to be regulated.

    Why does a definition decide what can be mined?

    1. Protection follows the boundary: Restrictions on mining and construction attach to land identified as Aravalli, so the extent of the definition is the extent of the protection.
    2. State practice has diverged: The range runs across Delhi, Haryana, Rajasthan and Gujarat, and in the absence of one national test each State has applied its own criteria to identify protected hills.
    3. The dispute is about elevation and landform: The competing tests turn on how much a landform must rise above the surrounding ground before it qualifies as an Aravalli hill, and a stricter threshold removes large stretches from protection.
    4. The interim period is the live cost: Mining approvals continue to be processed while the definition is pending, so delay is not neutral between the parties.

    What has the Court directed the panel to do?

    1. A hard deadline: The final report is due by 30 November, with the matter listed for hearing on 2 December, by which time the report is expected to have been filed.
    2. Interim reporting: The panel must submit interim reports on specific issues that require immediate consideration rather than holding everything back until the full exercise is complete.
    3. Stakeholder hearings: The panel must hear all stakeholders before finalising its recommendations, including tribal communities in Rajasthan and Gujarat whose land and livelihood the definition affects.
    4. No further extension: The Bench recorded that the six month request would not be entertained and that no further extension would follow.

    Challenges to regulating mining in the Aravallis

    1. Illegal mining outruns enforcement: Leases are policed by State mining departments with small field staff, so extraction continues outside sanctioned boundaries and at night. Eg. The Supreme Court has repeatedly had to intervene in Aravalli mining in Haryana, including through orders restraining mining in the range’s Haryana stretch.
      The Fix: Mandate satellite based volumetric monitoring of every lease, with quarterly comparison of extracted volume against the approved mining plan.
    2. Definitional ambiguity is exploited at the margin: Where a landform’s status is arguable, the developer’s classification prevails until challenged, which converts a mapping question into a licensing loophole. Eg. Construction has advanced on Aravalli land in Faridabad on the basis that the plots were not classified as forest.
      The Fix: Publish the finalised boundary as a single geo referenced map notified in the gazette, so classification is not decided plot by plot.
    3. Land use change destroys the hill even without mining: Real estate and quarry backfilling flatten the same ridges that mining regulation is meant to protect, and neither is governed by mining law. Eg. Farmhouse and residential development has expanded steadily on the Aravalli fringes around the National Capital Region.
      The Fix: Attach the mining definition to the State land use plans as well, so the same boundary governs building permissions.
    4. The ecological function is not priced into any clearance: The range checks the eastward spread of the Thar desert and recharges groundwater, services that no mining lease valuation accounts for. Eg. Groundwater levels in the districts flanking the range have fallen faster than the State averages.
      The Fix: Require a hydrological and dust dispersion impact assessment specific to the range before a lease is granted, not a generic mining environmental clearance.
    5. Restoration obligations are rarely enforced after closure: Reclamation of a mined pit is a lease condition that lapses once the operator exits, leaving abandoned pits and unstable slopes. Eg. Disused quarries across the range have filled with water and remain unrehabilitated.
      The Fix: Hold a restoration bond sized to the assessed reclamation cost, released only after independent certification that the site has been restored.

    Conclusion

    The Court has converted an open ended technical exercise into a dated one, which is the only lever available to it while the substantive question remains with the committee. The unresolved position is that protection of the range currently depends on a definition that does not yet exist, so every month of delay is a month in which the weakest interpretation operates by default. The concrete things to watch are the interim reports the panel now owes, and the hearing on 2 December at which the recommendations on regulating mining will first be tested.

    Back2Basics: The Aravalli Range

    1. What it is: One of the world’s oldest fold mountain ranges, formed in the Proterozoic era and heavily eroded, so it survives as broken ridges rather than a continuous chain.
    2. Extent: It runs roughly 690 km from Delhi in the northeast through Haryana and Rajasthan to Gujarat in the southwest.
    3. Highest point: Guru Shikhar on the Mount Abu massif in Rajasthan, at about 1,722 metres, is the highest peak of the range.
    4. Ecological role: It acts as a barrier to the eastward advance of the Thar desert and as a groundwater recharge zone for the plains on either side.

    Matching Previous Year Question

    “[2025, GS3, 15 marks] Mineral resources are fundamental to the country economy and these are exploited by mining. Why is mining considered an environmental hazard? Explain the remedial measures required to reduce the environmental hazard due to mining.”

  • Lucknow air cleanest, Indore’s second best among cities with million-plus people

    Why in the News

    Lucknow has been ranked first among million plus population cities in Swachh Vayu Sarvekshan 2026, the annual air quality ranking run under the National Clean Air Programme (NCAP). Indore was placed second and Jabalpur third in the same category of 47 cities. The rankings were declared in Delhi and the awards were distributed by the chairperson of the National Green Tribunal (NGT). Municipal wards that improved their air quality were honoured for the first time this year. The tension sits in the scoring itself: improvement in particulate matter (PM) 10 concentrations carries a weight of only 2.5%, so a city can top the ranking while its air remains above the national standard.

    What is Swachh Vayu Sarvekshan?

    1. What it ranks: It is an annual assessment of cities under the National Clean Air Programme, scoring the actions a municipal body has taken to improve air quality rather than the air quality it has achieved.
    2. How cities are grouped: Cities and towns are placed in three population based categories, those with a million plus population, those between 3 lakh and 10 lakh, and those below 3 lakh, so a small town is not ranked against a metropolis.
    3. What is scored: The parameters cover waste management, road dust control, dust from construction and demolition waste, reduction in vehicular pollution and reduction in industrial pollution. Reduction in PM 10 concentrations carries a weight of 2.5%.
    4. What the winners receive: The top three in each category receive cash prizes and mementos, ranging from Rs 1.50 crore for the first place in the million plus category down to Rs 12.5 lakh for the third place in the smallest category.

    Which cities topped the ranking, and which trailed it?

    1. Million plus population category: Lucknow first with Rs 1.50 crore, Indore second with Rs 1 crore, and Jabalpur third with Rs 50 lakh.
    2. Cities of 3 lakh to 10 lakh: Rourkela first with Rs 75 lakh, Firozabad and Guntur sharing second place with Rs 50 lakh, and Amravati third with Rs 25 lakh.
    3. Cities below 3 lakh: Kalinga Nagar first with Rs 37.5 lakh, Angul second with Rs 25 lakh, and Talcher third with Rs 12.5 lakh.
    4. The bottom of the largest category: Chennai, Jamshedpur, Kota, Kolkata and Madurai were placed in the bottom five of the 47 million plus cities.
    5. The two largest cities: Delhi ranked 30th and Mumbai 37th in the same category.

    What did the top ranked cities actually do?

    1. Lucknow’s interventions: The city deployed electric vehicles in its waste collection fleet, used mechanised sweepers to manage road dust, and cleared legacy waste dumps.
    2. Jabalpur’s interventions: The city ran a waste to energy plant, achieved full collection of waste with scientific disposal, mechanised street sweeping and promoted electric vehicles.
    3. The common thread is municipal solid waste and dust: Both winning profiles are built on services a municipal body directly controls, and neither turns on industrial or vehicular emission sources.
    4. Indore’s standing: Indore, ranked India’s cleanest city for seven years until 2025, converted that solid waste management capacity into second place on air quality.

    Challenges to the Swachh Vayu Sarvekshan ranking

    1. Effort is scored, outcomes are not: With actual PM 10 reduction weighted at 2.5%, the survey ranks the interventions a city reports rather than the air its residents breathe. Eg. Lucknow topped the category while its annual PM 10 concentration stood at 137 micrograms per cubic metre against the national standard of 60.
      The Fix: Raise the weight on measured concentration decline and make the award conditional on continuous ambient monitoring data rather than on activity reports.
    2. The measured pollutant is the coarser one: The survey and the programme centre on PM 10, while PM 2.5 is the fraction that penetrates deep into the lungs and drives the health burden. Eg. Road dust suppression lowers PM 10 sharply without touching combustion sources that generate PM 2.5.
      The Fix: Score PM 2.5 concentration decline as a separate parameter with its own weight, so combustion sources cannot be scored around.
    3. A city boundary is not an airshed: Pollution crosses municipal limits, so a city’s ranking reflects sources it does not control alongside those it does. Eg. Delhi’s winter concentrations rise with stubble burning in neighbouring States and with emissions from thermal plants outside the city.
      The Fix: Move the assessment unit to the airshed, ranking a cluster of local bodies jointly and funding them against a common source apportionment study.
    4. Self reported action invites inflation: Cities score themselves on activities such as sweeping frequency and dust suppression that no independent agency verifies. Eg. Mechanised sweeper deployment is recorded as procurement rather than as operating hours on the road.
      The Fix: Require third party verification of a random sample of claimed interventions before the cash award is released.
    5. Baselines flatter the already polluted: A city that started from a very high concentration records a large percentage decline while remaining far above the standard. Eg. Lucknow’s PM 10 fell 45.2% from 250 micrograms per cubic metre in 2017-18, and is still more than twice the standard.
      The Fix: Score cities against the absolute standard as well as against their own baseline, so meeting the norm rather than improving on a bad start is what wins.

    Conclusion

    A ranking that scores what a municipal body did, and barely scores what happened to the air, will reward administrative activity long before it rewards clean air. The gap is visible in this year’s own result, where the winning city remains far outside the national standard. What to watch is whether the weight given to measured concentration is raised in the next survey, and whether the ward level awards introduced this year are backed by ward level monitoring data.

    Back2Basics: National Clean Air Programme

    1. What it is: A national framework launched in January 2019 by the Union Ministry of Environment, Forest and Climate Change to cut particulate pollution in cities that fail the national ambient air quality standards.
    2. Which cities it covers: It covers non attainment cities, meaning cities that did not meet the standards over a five year period, along with million plus cities, taking in 131 urban areas.
    3. The target: The original goal of a 20% to 30% reduction in particulate concentrations by 2024 against a 2017 baseline was revised to a 40% reduction by 2025-26.
    4. How it is funded: Million plus cities receive air quality grants routed through the Fifteenth Finance Commission, while the remaining cities are funded through the programme’s own allocation.

    [2022, GS3, 10 marks] Discuss in detail the photochemical smog emphasizing its formation, effects and mitigation. Explain the 1999 Gothenburg Protocol.”

  • Global watchdog says rise of ‘digital hawala’ is aiding money laundering, terror financing

    Why in the News

    The latest report of the Financial Action Task Force (FATF), the inter-governmental body that sets the global standards against money laundering and terrorist financing, identifies the fusion of virtual assets with the traditional hawala system as one of the most significant developments in underground banking. The report is titled “Investigating Professional Money Laundering, Underground Banking, and the Use of Hawala and Other Similar Service Providers”. Nearly 70 per cent of surveyed jurisdictions have reported the integration of new technologies into such networks. The uses run from routine money laundering to the financing of terrorist organisations. The difficulty this creates is that a system built on trust between operators has acquired the speed and reach of digital finance without acquiring any of its supervision.

    What is “digital hawala”?

    1. The underlying system: Hawala is a centuries-old value transfer arrangement in which an operator in one country pays out to a recipient on the instruction of an operator in another, and the two settle their standing balance later between themselves.
    2. What makes it digital: “Digital hawala” covers the spectrum of technologies that facilitate the coordination, execution, settlement or concealment of these transactions.
    3. What has changed: Virtual assets now supply a settlement layer to a network that previously balanced its books through cash and trade alone.

    What are the six configurations the report identifies?

    1. Digital coordination with traditional settlement: Operators use encrypted messaging applications, shared ledgers and online platforms to communicate instructions, recruit clients and couriers, and maintain records, and settlement between them still moves through cash or trade.
    2. Digital customer interface: The client faces a mobile wallet or a fintech application, and settlement between operators again happens via cash or trade.
    3. Virtual asset-based settlement: Stablecoins are used to settle balances between operators directly, replacing the cash leg of the arrangement.
    4. Integration with formal digital infrastructure: Funds are moved through payment service providers, fintech platforms and virtual International Bank Account Numbers (IBANs), which are account identifiers issued without a physical branch relationship behind them.
    5. Artificial intelligence based tools: These automate transaction structuring, route value dynamically through mule accounts, and convert between currency and cryptocurrency at high speed.
    6. “Hawala” apps: These are bundled digital ecosystems combining messaging, cloud storage, social media, Virtual Asset Service Providers (VASPs), lending applications and gaming platforms in one product.

    Why do these configurations make detection harder?

    1. Speed and opacity rise together: The configurations make transactions faster, more opaque and more complex than the courier and ledger version they build on.
    2. The network gets larger and more durable: Digitisation expands both the reach of a network and its resilience, so removing one operator no longer breaks the chain.
    3. Digitisation is a catalyst and not a replacement: Traditional settlement mechanisms persist alongside the new layers rather than disappearing under them.
    4. Cash remains the pressure point: Cash stays critical at the collection and exit points, which is where an investigation still has a physical trail to find.

    What does the Turkiye case show about terror financing?

    1. The network’s purpose: Turkiye uncovered a “digital hawala” network financing the Islamic State of Iraq and the Levant (ISIL).
    2. The seizures: Raids in 2023 on a self-described ISIL “administrative officer” produced about $57,250 in cash, followed by a further $554,000.
    3. The evidence trail: Investigators recovered “hawala” notebooks alongside digital transfer receipts, so the paper ledger and the digital layer were running in parallel.
    4. The cover used: A jeweller and two mobile phone shops operated as fronts, and the transfers themselves were disguised as charity donations.

    Challenges to countering digital hawala

    1. Token settlement clears outside supervised payment rails: Balances settled in stablecoins move on public blockchains that no single national payments regulator oversees. Eg. FATF’s periodic reviews have found most assessed jurisdictions only partly compliant with its Travel Rule for virtual asset transfers.
      The Fix: Enforce originator and beneficiary information requirements on every registered Virtual Asset Service Provider, which in India are reporting entities under the Prevention of Money Laundering Act, 2002.
    2. Mule accounts scatter the trail across thousands of holders: Automated routing splits a single transfer across accounts opened in other people’s names, so no account shows an abnormal balance. Eg. The Indian Cyber Crime Coordination Centre has identified mule accounts as the standard cash-out layer in online fraud networks.
      The Fix: Require banks to share mule account indicators in near real time through a common registry rather than case by case after a complaint.
    3. Cooperation moves slower than the transaction: Formal evidence requests between countries take months while a chain of transfers completes in minutes. Eg. FATF’s 2024 mutual evaluation of India recorded delays in concluding money laundering prosecutions despite a broadly compliant legal framework.
      The Fix: Use the Egmont Group channel between financial intelligence units for immediate operational exchange, reserving formal treaty requests for trial-admissible evidence.
    4. The fronts are ordinary licensed businesses: Jewellers, phone dealers and travel agents handle high cash turnover legitimately, so the anomaly is invisible in the trading pattern itself. Eg. Dealers in precious metals and stones are treated as designated non-financial businesses under the FATF standards precisely because of this exposure.
      The Fix: Extend beneficial ownership disclosure and threshold reporting to these trades, and audit compliance rather than relying on registration alone.
    5. The regulated perimeter lags the product: Bundled applications combining messaging, lending and gaming fit no single licensing category, so no regulator holds clear jurisdiction over them. Eg. Application stores continue to host unregistered lending and wallet products that operate across borders.
      The Fix: Adopt an activity-based test that applies value transfer obligations to any product that moves value, whatever licence category it claims.

    Conclusion

    Underground banking has not been displaced by digital finance, it has absorbed it. Enforcement is left holding a mandate built for couriers and ledgers against a network that settles in tokens and routes itself automatically. Two things decide whether that gap closes. The first is whether virtual asset supervision reaches operators who never register, and the second is whether financial intelligence units can exchange information at the speed a transfer actually moves. The next marker is India’s follow-up reporting under the FATF mutual evaluation process, where the treatment of virtual asset service providers is the specific item under assessment.

    Back2Basics

    1. What it is: FATF is the inter-governmental standard setter on money laundering, terrorist financing and proliferation financing, established in 1989 at the G7 summit in Paris.
    2. How it works: Its Secretariat is housed at the Organisation for Economic Co-operation and Development in Paris, and its standards are the 40 Recommendations that member states are assessed against.
    3. Its enforcement tool: It maintains two public lists, jurisdictions under increased monitoring and high-risk jurisdictions subject to a call for action, which affect a listed country’s access to international finance.
    4. India’s position: India has been a full member since 2010, and is also a member of the Asia/Pacific Group on Money Laundering.

    Matching Previous Year Question

    “[2026, GS3, 15 marks] Discuss counterfeit currency and money laundering as major sources of terror funding in India. State the actions being taken at International level to check these menaces. Highlight the role of Financial Action Task Force (FATF) and methods of compliance by its member states in preventing terror funding.”

  • US share in India’s LPG imports surged to over 50% from under 10%

    Why in the News

    The share of the United States in India’s liquefied petroleum gas (LPG) imports has crossed 50 per cent in the six months since the West Asia conflict began, against less than 10 per cent in the preceding six months. The war began with United States and Israeli strikes on Iran in late February, and it halted vessel movement through the Strait of Hormuz. India’s import basket had been dominated by Gulf suppliers, so the loss of that route forced a substitution rather than a fall in demand. The tension is that a supply system built on a short haul from four Gulf sellers has been replaced inside six months by a long haul from a single seller. The concentration has moved rather than dissolved.

    Why did a shipping chokepoint translate into an LPG shock?

    1. The route’s function: The Strait of Hormuz is a narrow waterway connecting the Persian Gulf with the Gulf of Oman and the Arabian Sea, and it is the primary evacuation route for energy supplies from the wider Gulf region.
    2. Its global weight: The strait accounted for a fifth of world oil and liquefied natural gas (LNG) flows, so its closure was a global disruption before it was an Indian one.
    3. India’s exposure through it: About 90 per cent of India’s LPG imports came from West Asia through the strait, against about 40 per cent of crude oil imports and 60 per cent of LNG imports.
    4. Why LPG was hit hardest: Movement through the strait effectively covered around 54 per cent of India’s total LPG consumption, so one blocked route touched more than half the cooking fuel base.

    How did India’s LPG import basket change in six months?

    1. Overall volumes: India’s total LPG imports in the six months to August fell 43.1 per cent from the preceding six months, to 7.14 million tonnes.
    2. United States: Supplies surged 281.1 per cent to 3.78 million tonnes for a 53 per cent share, against about 993,000 tonnes and a 7.9 per cent share in September to February.
    3. United Arab Emirates: Volumes crashed 79.8 per cent to about 958,000 tonnes, and the share of the pre-war leading supplier fell to 13.4 per cent from 37.8 per cent.
    4. Qatar: Volumes plummeted 84.7 per cent to about 405,000 tonnes, and the share shrank to 5.7 per cent from 21.1 per cent.
    5. Kuwait: Volumes fell 81.7 per cent to about 346,300 tonnes, and the share contracted to 4.9 per cent from 15.1 per cent.
    6. Saudi Arabia: Volumes fell 76.1 per cent to about 423,700 tonnes, and the share dropped to 5.9 per cent from 14.1 per cent.

    Why did the United States become the fallback supplier?

    1. Pre-existing scale: Washington was the largest LPG exporter worldwide before the crisis, so it was the only seller with spare volumes at the scale India needed.
    2. Price position: United States propane was already cheaper than Asian supplies before the war, which made the switch commercially defensible and not only an emergency measure.
    3. Availability over distance: With no nearby alternative, India accepted a higher delivered cost to bring cargoes from further away, because keeping cooking gas available was the operative priority.
    4. The precedent it follows: The redirection mirrors the earlier flow of Russian crude barrels to India, where a disrupted market was replaced by whichever seller could load immediately.

    What does the episode reveal about India’s energy import dependence?

    1. The dependence baseline: India imports over 88 per cent of its oil, 60 per cent of its LPG and about 50 per cent of its natural gas, so a routing disruption anywhere becomes a domestic supply question.
    2. Concentration is the real exposure: Four Gulf sellers on one waterway meant a single closure removed most of the basket at once, and no diversification existed to absorb it.
    3. Substitution has a time cost: Rebuilding half the basket around one distant supplier took six months of scrambling, which is the lead time a chokepoint closure imposes on an importer.
    4. The dependence is unresolved: American flows are expected to stay strong until West Asian supply normalises, and no clarity exists on when that will happen.

    Challenges to India’s LPG supply security

    1. The long haul carries a freight and transit penalty: A United States cargo takes far longer to reach an Indian port than a Gulf cargo, and the added voyage cost sits on every tonne landed. Eg. American propane bound for Asia moves through the Panama Canal, where transit slots were rationed during the drought-driven draft restrictions of 2023 and 2024.
      The Fix: Contract a share of American volumes on delivered terms with an alternative Cape of Good Hope routing priced into the contract.
    2. Import and bottling infrastructure is concentrated on one coast: India’s very large gas carrier berths and bottling capacity sit largely on the western seaboard, built around short Gulf voyages and rapid turnarounds. Eg. The major LPG import terminals cluster at west coast ports such as Kandla, Mundra and Sikka.
      The Fix: Expand east coast import capacity and extend LPG pipeline evacuation on the model of the Paradip-Haldia-Durgapur line.
    3. Administered retail prices push the shock onto the exchequer: Domestic cylinder prices are held stable, so a higher landed cost is absorbed by oil marketing companies or by the Budget rather than by the consumer. Eg. The targeted subsidy paid per cylinder under the Pradhan Mantri Ujjwala Yojana sits on top of a capped base price.
      The Fix: Move the subsidy fully to a direct transfer indexed to the import price, so the fiscal cost is visible and bounded rather than carried on company balance sheets.
    4. India holds no strategic reserve for cooking gas: Emergency stocks exist for crude oil alone, so an LPG disruption has to be managed through spot buying at the worst available price. Eg. The Indian Strategic Petroleum Reserves caverns at Visakhapatnam, Mangaluru and Padur store crude oil and not LPG.
      The Fix: Build dedicated pressurised or refrigerated LPG storage at the major import terminals with a mandated minimum cover in days of consumption.
    5. Substitution away from cylinders is only partial: Piped natural gas and electric cooking reach a limited share of households, so LPG demand cannot be shifted quickly when imports tighten. Eg. City gas distribution networks operate only in geographical areas awarded through bidding rounds by the Petroleum and Natural Gas Regulatory Board.
      The Fix: Accelerate piped connections inside already awarded city gas areas and tie household conversion targets to the licence conditions.

    Conclusion

    India has replaced a blocked route rather than reduced a dependence. The basket is now anchored on one distant seller in place of four near ones, and the switch was completed at speed because no stock cushion existed to buy time. The status is that American cargoes are expected to hold their share until West Asian supply normalises. The marker to watch is whether the Gulf share recovers once traffic through the Strait of Hormuz resumes, or whether contracts written during the disruption lock in a permanently longer supply line.

    Matching Previous Year Question

    “[2025, GS2, 15 marks] “Energy security constitutes the dominant kingpin of India’s foreign policy, and is linked with India’s overarching influence in Middle Eastern countries.” How would you integrate energy security with India’s foreign policy trajectories in the coming years?”

  • C. Rangarajan flags fewer regional rural banks as ‘a step in the wrong direction’

    Why in the News

    A former Reserve Bank of India (RBI) Governor has criticised the consolidation of Regional Rural Banks (RRBs), calling it “a step in the wrong direction”. The consolidation has left one RRB in each State, and in one State the sponsoring commercial bank absorbed the RRB outright. The stated purpose of the exercise is operational viability and economies of scale. The objection is that scale removes the local and regional character that was the reason for creating these banks in the first place. A second claim runs alongside it: the alternative local lender, the small finance bank (a bank licensed to take deposits and lend, required to direct 75 per cent of its lending to priority sector borrowers and half its loan book to small-ticket loans), has not been allowed to expand.

    What are Regional Rural Banks?

    1. Origin: RRBs were set up under the Regional Rural Banks Act, 1976 to lend to small and marginal farmers, agricultural labourers, rural artisans and small entrepreneurs.
    2. Ownership: Each RRB is jointly held by the Centre, the sponsoring commercial bank and the State government, in a 50:35:15 shareholding.
    3. Design logic: Each bank was confined to a defined group of districts. That local presence was the design feature meant to push credit to borrowers a national bank would not reach.

    How far has the consolidation gone?

    1. Two decades of amalgamation: The Centre has consolidated RRBs since 2005 to improve operational viability and capture economies of scale, according to a written reply in the Lok Sabha in July 2025.
    2. The first phase: Between 2005 and 2010 the number of RRBs fell from 196 to 82, and later phases reduced it further.
    3. One State-One RRB: The latest phase cut the number from 43 to 28, with effect from 1 May 2025.
    4. Absorption by the sponsor: In one State the sponsoring bank absorbed the RRB into itself rather than merging it with another RRB.

    Why is the loss of local character the objection?

    1. Local character was the justification: RRBs were created on the premise that a bank rooted in a defined area would distribute credit more evenly than a national bank operating from outside it.
    2. Scale erases the distinguishing feature: A single State-level entity lends across an entire State. Its credit decisions move away from the cluster of districts the bank was built around.
    3. Merger into universal banks is the endpoint: Once the local and regional character is gone, these banks may eventually be merged into universal banks, which removes the category altogether.

    What has India’s institutional answer to credit gaps been?

    1. A sequence of institutional experiments: Credit delivery to vulnerable and weaker sections has been extended through bank nationalisation, priority sector credit, RRBs, Local Area Banks, self-help groups and small finance banks.
    2. The default response is a new institution: Each time a gap appeared, the response was to create a new institution rather than to repair the existing one.
    3. Structure alone does not deliver: Creating an institution is not by itself the answer, since the underlying problem continues after the institution exists.
    4. Execution decides the outcome: The record of small finance banks shows that the spirit in which management takes on the mandated task is what separates performance from form.

    Why are small finance banks not filling the gap?

    1. The number is too small: Only 11 small finance banks are in operation, which is not enough to meet unmet credit needs.
    2. Same conditions as universal banks: A small finance bank has to satisfy the same set of regulatory conditions as a universal bank, without the balance sheet that makes those conditions affordable.
    3. No incentive to enter: A promoter not driven by other considerations has little reason to set up such a bank on those terms.
    4. The regulator has been asked to act: The RBI has been urged to find ways to incentivise the setting up of more small finance banks.
    5. Graduation is not the objection: The ambition of a small finance bank to become a universal bank is not itself a problem, and these banks have performed well in the areas they were required to serve.

    Challenges to Regional Rural Banks

    1. Dependence on the sponsor bank: An RRB draws its technology, senior management and treasury operations from its sponsoring commercial bank, so its autonomy is nominal. Eg. Core banking platforms in most RRBs are maintained by the sponsor bank rather than by the RRB itself.
      The Fix: Move RRB technology and treasury functions to a shared national utility, so operational capacity does not depend on one sponsor’s willingness.
    2. Thin capital and repeated recapitalisation: Capital has to be infused by three shareholders in a fixed ratio, so one shareholder’s fiscal stress stalls the entire infusion. Eg. The Centre approved a recapitalisation package of ₹10,890 crore for RRBs in 2021, with its own share at ₹5,445 crore.
      The Fix: Permit an RRB that meets the capital adequacy floor to raise capital from the market instead of waiting for all three shareholders to agree.
    3. Concentration in crop lending: RRB loan books are weighted towards agriculture, so a single bad season hits borrower income and asset quality at the same time. Eg. Farm loan waivers announced by State governments leave RRBs holding written-off loans while awaiting State reimbursement.
      The Fix: Cap the share of any single sector in an RRB’s loan book and expand lending to rural non-farm enterprises.
    4. Deposits raised locally are not lent locally: RRBs collect rural deposits and park surpluses through the sponsor bank’s treasury rather than converting them into local advances. Eg. Uttar Pradesh and Bihar carry among the lowest credit-deposit ratios in the country despite dense rural branch networks.
      The Fix: Tie an RRB’s branch expansion approvals to its credit-deposit ratio in the districts it already operates in.

    Conclusion

    Consolidation has settled the question of viability and left the question of reach open. A bank that is no longer local cannot claim the mandate that justified creating it, and a State-level entity is not a substitute for a lender that knows its districts. The regulator now has to decide whether rural credit is delivered by fewer and larger institutions or by more and smaller ones. Nothing in the current licensing terms pushes a new entrant towards the second answer.

    Matching Previous Year Question

    “[2013] Which of the following grants/grant direct credit assistance to rural households? (1). Regional Rural Banks (2). National Bank for Agriculture and Rural Development (3). Land Development Banks Select the correct answer using the codes given below. (a) 1 and 2 only (b) 2 only (c) 1 and 3 only (d) 1, 2 and 3 ANSWER: (c)”

  • There are large inconsistencies between GDP and other economic indicators: says Garg

    Why in the News

    A former Finance Secretary has questioned the credibility of India’s latest Gross Domestic Product (GDP) estimates. The objection is not to the level of growth reported but to the absence of a transparent bridge between the old 2011-12 base series and the new 2022-23 base series. The new series has cut the size of the economy for 2024-25 by ₹12.70 lakh crore. The Ministry of Statistics and Programme Implementation (MoSPI) has explained the reduction as the result of a new methodology, wider coverage and improved data. Wider coverage normally raises the nominal size of an economy rather than reducing it. That is the inconsistency now in dispute.

    What is the 2022-23 base year GDP series?

    1. The base year: The base year is the reference year whose price structure is used to strip inflation out of nominal output. Real growth is measured against that fixed set of prices.
    2. What the revision changes: The new series moves the base from 2011-12 to 2022-23. It also changes the data sources and the indices used to estimate output.
    3. The back-series: A back-series recomputes earlier years on the new base. Without one, estimates on the old and new bases cannot be compared year on year.

    Why does the new series need a back-series?

    1. There is no bridge between the two series: No published concordance links the 2011-12 base estimates to the 2022-23 base estimates. A user cannot see which part of the change comes from the new base and which from the new data.
    2. A published timetable is the test of intent: MoSPI has been asked to release a back-series covering 2011-12 to 2021-22 and to fix a date for doing so. The absence of any such programme indicates the issue is not being treated as pressing.

    Why has a wider dataset produced a smaller economy?

    1. The size of the cut: GDP for 2024-25 was reduced by ₹12.70 lakh crore. The revision to the first quarter of 2025-26 is part of that same larger change.
    2. Coverage cuts the other way: Better coverage adds activity to the estimate and raises nominal GDP. A revision that widens coverage and lowers the level is unexplained by that argument.
    3. An earlier overstatement is one reading: The old system may have overstated output through errors such as double counting. On this reading the new series is a correction.
    4. A deliberate write-down is the other: Output may have been overstated to produce stronger growth numbers and then written down under cover of a new series. No evidence of deliberate manipulation was offered for this reading.
    5. The official account is contested: The Centre’s explanation for the reduction has been described as “officialese, obfuscatory” and as shedding no light on the change.

    What does the deflator gap indicate?

    1. The arithmetic does not close: Consumer inflation runs above 4 per cent and producer price inflation at about 9 per cent. The GDP deflator (the economy-wide price index used to convert nominal output into real output) implied by the latest estimates is about 2.5 per cent.
    2. The price data behind it is not public: The underlying price series used to build the deflator has not been disclosed. The real growth number cannot be checked without it.
    3. Double deflation was applied without the data to support it: Double deflation values a sector’s inputs and its outputs at separate price indices. Indian manufacturing data is not granular enough to sustain that treatment.
    4. Parallel running is the suggested safeguard: The older system should be run alongside the new one until the new methodology stabilises.

    Why is the statistical system’s independence part of this dispute?

    1. The divergence is not noise: Weakness in household incomes, employment, consumption and sentiment has persisted while the headline growth number has not weakened. That divergence cannot be dismissed as statistical noise, particularly where an outcome is politically sensitive.
    2. The data infrastructure needs rebuilding: India’s statistical infrastructure requires massive modernisation before its outputs can be defended on technical grounds alone.
    3. Freedom from political direction is the precondition: The system can produce reliable numbers only where there is no political interest in results running in a particular direction. Statisticians need greater freedom from political control for that to hold.

    What does the GDP number leave out?

    1. GDP is not a measure of welfare: Aggregate output says nothing about how the gains from that output are distributed.
    2. The income leg is missing: India does not adequately publish the income side of the national accounts. That side shows how value added is divided between labour, corporations and government.
    3. Growth alone will not lift per capita income: Per capita GDP remains low. The requirement is 9 to 10 per cent growth together with more effective redistribution and lower unproductive government expenditure.

    Challenges to India’s new GDP series

    1. No comparable time series exists: A rebased series without recomputed earlier years cannot support any statement about long-run growth. Eg. The 2015 shift to the 2011-12 base was followed by an official back-series only in 2018, and it revised the earlier decade’s growth rates downward.
      The Fix: Publish the 2011-12 to 2021-22 back-series alongside a documented concordance showing which data source replaced which.
    2. Single deflation distorts manufacturing value added: Indian national accounts have long applied one price index to both a sector’s output and its inputs. Eg. When input prices fall faster than output prices, single deflation records a rise in real value added that did not occur.
      The Fix: Publish the separate input and output price indices used for each manufacturing sub-sector, so the deflation method can be audited.
    3. The informal sector is estimated rather than measured: Output of unincorporated enterprises is extrapolated from formal-sector indicators. Eg. The MCA-21 corporate database used to estimate private corporate output was found to contain dormant and untraceable companies.
      The Fix: Anchor the informal sector estimate to the Annual Survey of Unincorporated Sector Enterprises rather than to a corporate filings database.
    4. Benchmark surveys are dated or withheld: Consumption and employment weights depend on large sample surveys that are not released on a fixed cycle. Eg. The 2017-18 Consumer Expenditure Survey was withheld from publication, leaving the consumption basket anchored to 2011-12 for over a decade.
      The Fix: Fix a statutory release calendar for benchmark surveys, with the release date set independently of the government of the day.

    Conclusion

    The dispute is about verifiability, not about the level of growth. A national accounts estimate that cannot be compared with its own past is not a series, and no methodological note substitutes for that comparison. The statistical system settles this by publishing the recomputed earlier years and the price data behind them, not by explaining itself. Until it does, each quarterly release will be argued over rather than used.

    Matching Previous Year Question

    “[2021, GS3, 10 marks] Explain the difference between computing methodology of India’s Gross Domestic Product(GDP) before the year 2015 and after the year 2015.”

  • ISRO’s role is by no means diminishing: space officials

    ISRO’s role is by no means diminishing: space officials

    Why in the News

    Nine Indian Space Research Organisation (ISRO) employee associations have written a joint letter dated 4 September seeking written clarification on whether the government intends to transfer the agency’s launch vehicle and satellite manufacturing to private firms.

    What did the employee associations actually ask?

    1. Whether the position is an approved decision: They asked whether the stated future of ISRO not manufacturing launch vehicles represents an approved Space Commission decision.
    2. What happens to the workforce: They asked what would happen to sanctioned strength and recruitment over the next five to 10 years.
    3. Whether they will be consulted: They asked whether the associations would be consulted before irreversible decisions are taken.
    4. Where the letter went: It was addressed to the Secretary, Department of Space and Chairman, ISRO, and copied to the Confederation of Central Government Employees and Workers.

    What is the official position on ISRO’s role?

    1. The role is stated as undiminished: IN-SPACe’s chairman said the direction is not a smaller ISRO but a larger Indian space ecosystem, with ISRO pushing the technological frontier.
    2. Privatisation is denied outright: ISRO’s clarification stated that the agency will neither be privatised nor have its importance reduced.
    3. Transfer is distinguished from withdrawal: Handing over a mature technology does not amount to leaving that domain, on the agency’s stated reasoning.
    4. Ownership stays public: Critical national space infrastructure will remain owned by the government.

    How is the division of labour defined?

    1. The 2020 reforms set the structure: The reforms were aimed at expanding the overall ecosystem, with IN-SPACe authorising non-government participation and NewSpace India Limited (NSIL) commercialising mature capabilities.
    2. Industry takes the mature end: Industry is to increasingly manufacture and scale launch vehicles and satellites whose technology is settled.
    3. The agency keeps the unsettled end: ISRO is to concentrate on advanced research and development, scientific and strategic missions, and infrastructure too complex for private developers.
    4. The policy instrument: The arrangement is described as an ISRO-led national space ecosystem, institutionalised through the Indian Space Policy 2023.

    What does the reform record show so far?

    1. Firm formation: India now has over 450 space start-ups, against a handful in 2020.
    2. The revenue target: The space economy is roughly $8.4 billion and the stated aim is to grow it to $44 billion by 2033.
    3. The retained programmes: The Bharatiya Antariksh Station by 2035 and an Indian crewed lunar mission by 2040 are named as the missions ISRO itself will build toward.

    Why could employees only raise this as associations?

    1. They are outside the industry definition: Department of Space employees are exempted from the statutory definition of industry.
    2. They cannot unionise: That exemption means they cannot form trade unions to bargain on employment terms.
    3. The available channel is narrower: They organise instead as service associations recognised under the Central Civil Services (Recognition of Service Associations) Rules, 1993, which permits representation rather than negotiation.

    Challenges to an ISRO-led national space ecosystem

    1. Government remains the anchor customer: Private launch and satellite demand is thin, so firms depend on public orders for volume. Eg. NewSpace India Limited awarded the Polar Satellite Launch Vehicle industrial production contract for five vehicles to a Hindustan Aeronautics Limited and Larsen and Toubro consortium in 2022.
      The Fix: Publish a multi-year public launch and satellite procurement calendar, so firms can size capacity against committed demand rather than announcements.
    2. Technology transfer terms decide whether industry can compete: A transferred design without production know-how and test infrastructure leaves the recipient dependent on the agency. Eg. ISRO transferred the Small Satellite Launch Vehicle technology to Hindustan Aeronautics Limited in 2025.
      The Fix: Attach test facility access and a defined hand-holding period to every transfer agreement, with milestones the recipient must independently clear.
    3. Long-gestation capital is scarce: Launch and propulsion ventures need patient capital across development cycles that outlast most venture fund horizons. Eg. The Union Budget for 2024-25 announced a Rs 1,000 crore venture capital fund for the space sector for this reason.
      The Fix: Route that fund through milestone-linked tranches tied to qualification tests, rather than as equity at a single valuation point.
    4. Foreign investment rules still differ by segment: Investment caps vary across launch vehicles, satellites and components, which complicates raising capital for an integrated firm. Eg. The 2024 foreign direct investment revision set different automatic-route thresholds for satellite manufacturing, launch vehicles and component supply.
      The Fix: Publish a single classification note stating which activity falls in which segment, so a firm knows its cap before it raises capital.

    Conclusion

    Both sides agree that industry should build what is settled and the agency should build what is not. The disagreement is over where that boundary currently sits and who has the authority to move it. The workforce question the associations raised is the one neither reply engaged with. Until the Department of Space states its recruitment intent in numbers, the assurance rests on stated direction rather than on anything an employee can verify.

    Back2Basics

    1. NewSpace India Limited: The commercial arm of the Department of Space, incorporated in March 2019 as a central public sector enterprise.
    2. Predecessor: It took over the commercial role earlier held by Antrix Corporation, which now handles a narrower marketing mandate.
    3. Business model: It operates on a demand-driven model, owning and operating satellites and launches for identified customers rather than only marketing surplus capacity.
    4. Headquarters: It is based in Bengaluru and reports to the Department of Space.

    [2026] Consider the following statements about involvement of private entities in India’s space programme:

    1. IN-SPACe is an autonomous agency formed to facilitate participation of private entities.

    2. Agnikul Cosmos launched the world’s first flight using 3D-printed rocket engine.

    3. Skyroot Aerospace has developed liquid fuel for GSLV.

    (a) 1 only (b) 2 and 3 only (c) 1 and 2 only (d) 1, 2 and 3
  • No provision in Forest Rights Act to obtain gram sabha consent for projects: Ministry

    No provision in Forest Rights Act to obtain gram sabha consent for projects: Ministry

    Why in the News

    The Union Ministry of Tribal Affairs has told the Union Ministry of Power that the Scheduled Tribes and Other Traditional Forest Dwellers (Recognition of Forest Rights) Act, 2006 carries no provision for obtaining gram sabha consent for Stage-II forest clearance. It added that such matters do not fall within its purview.

    How does gram sabha consent for forest clearance actually work?

    1. The requirement sits in the diversion rules, not in the Act: The Forest Rights Act, 2006 carries no language on gram sabha consent for diverting forest land to non-forest purposes. The Union government’s rules under the Forest (Conservation) Act, 1980 require that all processes under the Forest Rights Act be completed before a diversion certificate is issued.
    2. Step one, identify and recognise: The guidelines require potential claimants under the Forest Rights Act to be identified, and their rights to be recognised where they apply.
    3. Step two, vest the rights: Recognised rights are then vested in the holders before the diversion proposal can move.
    4. Step three, obtain the no-objection certificate: The concerned gram sabhas then issue a no-objection certificate on the proposal to divert that forest land for the stated purpose. This certificate is what is commonly called gram sabha consent for forest clearance.

    What is the Ministry of Tribal Affairs’ stated position?

    1. The communication is dated and specific: The Ministry stated on 31 August that there is no provision for obtaining gram sabha consent for Stage-II forest clearance in the Forest Rights Act, 2006 or the rules made under it.
    2. It disclaims jurisdiction: It concluded that such matters therefore do not fall under its purview.
    3. The Act says otherwise on responsibility: The Forest Rights Act explicitly names the Ministry of Tribal Affairs as the nodal ministry responsible for the law’s implementation.
    4. The disclaimer has a record behind it: The Ministry has previously claimed no role in the Nicobar mega-infrastructure project and in Forest Rights Act implementation cases in Madhya Pradesh, Karnataka and other States, arguing that the Act assigns implementation to State and Union Territory governments.

    Why is that position contested?

    1. The requirement is not free-standing: The no-objection certificate is demanded because the diversion rules make completion of the Forest Rights Act processes a precondition. A ministry that owns the Act’s implementation cannot disown the precondition built on it.
    2. No alternative authority exists: The position leaves no ministry able to settle a disputed consent, which is the objection recorded by a Supreme Court advocate who formerly advised the Ministry of Tribal Affairs under both governments.
    3. The timing sharpens the gap: The disclaimer was issued while a parliamentary committee proposal to lower the consent standard is live and awaiting inter-ministerial examination.

    What did the parliamentary committee propose, and why?

    1. The report is dated: The Parliamentary Standing Committee on Public Undertakings reported on NHPC Limited on 3 August, and the Power Ministry’s deliberations with the Tribal Affairs Ministry followed from it.
    2. The delay figure: Based on discussions with NHPC officials, the committee recorded an average forest clearance time of 106 months for under-construction projects.
    3. The bottleneck it identified: It found the requirement that all concerned gram sabhas consent to be the single most critical bottleneck.
    4. The stalled project named: The Teesta-IV hydroelectric project is indefinitely stalled because consent from a small minority of gram panchayats remains pending.
    5. The proposed dilution: The committee endorsed NHPC’s recommendation for a qualified super-majority, meaning consent from 70 to 75 per cent of affected gram sabhas, for large hydropower projects of national importance. It asked the Power Ministry to examine the feasibility of that proposal with the Ministry of Tribal Affairs.

    Challenges to gram sabha consent under the Forest Rights Act

    1. Consent can be recorded without a real assembly: Resolutions are produced without quorum or without convening the habitation actually affected. Eg. Villagers of Hariharpur, Salhi and Fatehpur alleged forged gram sabha consent for the Parsa coal block in the Hasdeo Aranya forests of Chhattisgarh.
      The Fix: Require a video record and a habitation-wise attendance roll for every consent resolution, uploaded before the diversion certificate is issued.
    2. Rights recognition lags, so the assembly may hold no title: Community forest resource rights remain unrecognised across most eligible villages, which weakens the standing of the body being asked to consent. Eg. Recognition of community forest resource rights has advanced in Maharashtra and Odisha and stalled across most other States.
      The Fix: Complete community forest resource recognition across the affected district before a diversion proposal is admitted for consideration.
    3. The rules have already moved consent later in the sequence: Consent now arrives after a project has an in-principle approval, which reduces it to a formality. Eg. The Van (Sanrakshan Evam Samvardhan) Rules, 2022 removed the gram sabha consent step from the stage preceding in-principle approval.
      The Fix: Restore the consent step ahead of in-principle approval, so no project is sanctioned before the affected assembly has been heard.
    4. Compliance is certified by the authority pushing the project: The State administration both promotes the project and certifies that the statutory process was followed. Eg. The environment ministry accepts the State’s compliance certificate at the final clearance stage without independent verification.
      The Fix: Route the compliance certificate through the State tribal welfare department, accompanied by a published list of recognised claimants.

    Conclusion

    Two positions now stand directly against each other. The statute names one ministry as responsible for its implementation, and that ministry says the consent question is not its business. Nothing in the system supplies an alternative authority to settle a contested consent, so a disputed resolution has no forum. That gap matters most now, because a proposal to lower the consent standard is live and no ministry has claimed the authority to rule on it.

    [2021] At the national level, which ministry is the nodal agency to ensure effective implementation of the Scheduled Tribes and Other Traditional Forest Dwellers (Recognition of Forest Rights) Act, 2006?

    (a) Ministry of Environment, Forest and Climate Change

    (b) Ministry of Panchayati Raj

    (c) Ministry of Rural Development

    (d) Ministry of Tribal Affairs”

  • Aiming for drug-free India by 2029, Shah outlines roadmap based on four pillars

    Aiming for drug-free India by 2029, Shah outlines roadmap based on four pillars

    Why in the News

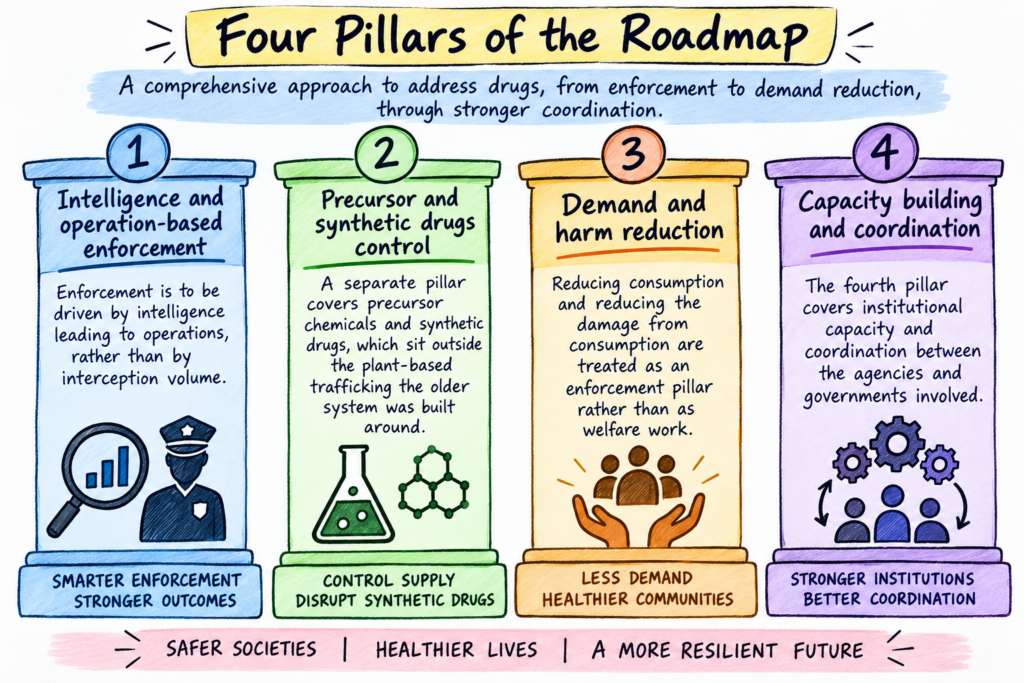
    The Union Home Minister has released a three-year roadmap and a vision document for narcotics control, targeting a drug-free India by 2029. The roadmap declares 2026-29 a mission-mode period and shifts enforcement doctrine from seizure-centric action to network-centric enforcement.

    What is the doctrinal shift the roadmap announces?

    1. From seizures to networks: Enforcement moves from seizure-centric action to network-centric enforcement aimed at kingpins, associates, distributors and suppliers.
    2. Investigation runs both ways: Cases are to be worked bottom-to-top and top-to-bottom, so a street-level recovery is pursued upward to the financier and a financier is pursued downward to distribution.
    3. Three stated outcomes: The strategy is to be judged on supply reduction, demand reduction and harm reduction.

    What makes the 2026-29 period different from earlier drives?

    1. Mission mode with owners: Every goal is to carry a timeline and a responsible ministry, so a missed target has a named holder.
    2. Measurement is built in: Goals carry measurable outcomes, quarterly reviews and result-based accountability.
    3. The stated contrast: Action before 2014 is described as taken in bits and pieces and in silos, limited to small seizures.
    4. The seizure record cited: From 2004 to 2014, 26 lakh kg of narcotic and psychotropic substances were seized. From 2014 to July 2026 the figure was over 1.19 crore kg.

    What institutional machinery already exists?

    1. A four-tier coordination mechanism: The Narco Coordination Centre (NCORD) mechanism was created in 2019 and operates at the executive, State and district levels.
    2. Dedicated State-level task forces: Anti-Narcotics Task Forces have been constituted in every State and Union Territory, with local police linked into the national strategy.
    3. A joint decision forum: A Joint Coordination Committee was formed in 2019 for Central agencies and State governments to act together on major drug networks, their international connections and operational gaps.
    4. The central agency was rebuilt: The Narcotics Control Bureau has been strengthened through cadre reorganisation and an increase in manpower, zonal presence and operational capability.

    What does the demand side of the strategy rest on?

    1. A national helpline: The MANAS helpline on 1933 was introduced to support persons with drug addiction.
    2. Four interventions linked to enforcement: Awareness, treatment, rehabilitation and livelihood opportunities have been tied into the anti-narcotics campaign rather than run separately from it.

    Challenges to a drug-free India by 2029

    1. Synthetic drugs move production inside the country: Precursor chemicals diverted from a large legitimate pharmaceutical industry let manufacture happen domestically, so border interdiction misses the source. Eg. Mephedrone manufacturing units have been dismantled in Gujarat, Maharashtra and Rajasthan in successive operations.
      The Fix: Place named precursor chemicals under end-use licensing, with mandatory sales reporting by manufacturers to the Narcotics Control Bureau.
    2. Maritime consignments dwarf land recoveries: Container traffic carries volumes that drone and border interdiction cannot match. Eg. Nearly 3,000 kg of heroin was seized in a single consignment at Mundra Port, Gujarat, in September 2021.
      The Fix: Extend risk-based non-intrusive container scanning to every major port instead of sample checking.
    3. Consumption is punishable, which deters treatment-seeking: A user who comes forward risks prosecution for the act that brought them to treatment. Eg. Section 27 of the Narcotic Drugs and Psychotropic Substances Act, 1985 punishes consumption, and the immunity under Section 64A applies only to an addict who volunteers for treatment.
      The Fix: Make the Section 64A immunity operate automatically on enrolment in a recognised de-addiction facility, certified by the facility rather than by the police.
    4. Demand reduction sits in a different ministry: Treatment and rehabilitation are run outside the ministry running enforcement, so targets and review cycles do not align. Eg. The Nasha Mukt Bharat Abhiyaan, launched in 2020, is run by the Ministry of Social Justice and Empowerment.
      The Fix: Bring demand reduction targets into the same quarterly review as enforcement targets, reported in a single format.

    Conclusion

    Counting seizures measures effort, and dismantling networks measures result. The second is far harder to demonstrate from public data, because a network that stops operating produces no headline recovery. Nothing announced commits the government to publishing the baseline against which the 2029 target will be judged. Whether the vision document’s targets and the findings of the quarterly reviews are placed in the public domain is the marker to watch.

    Back2Basics

    1. Narcotics Control Bureau: The apex coordinating agency for drug law enforcement in India, functioning under the Ministry of Home Affairs.
    2. Statutory basis: It was constituted in 1986 under Section 4(3) of the Narcotic Drugs and Psychotropic Substances Act, 1985.
    3. Function: It coordinates action between Central and State enforcement agencies and collects and disseminates drug trafficking intelligence.
    4. International role: It is India’s nodal point for obligations under the United Nations drug control conventions and for liaison with foreign drug enforcement agencies.

    [2018, GS3, 15 marks] India’s proximity to two of the world’s biggest illicit opium-growing states has enhanced her internal security concerns. Explain the linkages between drug trafficking and other illicit activities such as gunrunning, money laundering and human trafficking. What counter-measures should be taken to prevent the same?”