💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Economics

  • Issues in the Phased Manufacturing Policy

    The Production Linked Incentive Scheme, though ambitious in its goal suffers from several fundamental issues. The article discuses such issues.

    Background of the Phased Manufacturing Policy

    • The Phased Manufacturing Programme (PMP) incentivised the manufacture of low value accessories initially, and then moved on to the manufacture of higher value components.
    • This was done by increasing the basic customs duty on the imports of these accessories or components.
    • The PMP was implemented with an aim to improve value addition in the country.
    • Recently, 16 firms in the mobile manufacturing sector were approved for the Production Linked Incentive (PLI) scheme to transform India into a major mobile manufacturing hub.
    • The PLI comes on the back of a phased manufacturing programme (PMP) that began in 2016-17.

    Issues to consider

    1) More imports and less value addition in India

    • Firms such as Apple, Xiaomi, Oppo, and OnePlus have invested in India, but mostly through their contract manufacturers.
    • As a result, production increased from $13.4 billion in 2016-17 to $31.7 billion in 2019-20.
    • But factory-level production data from the Annual Survey of Industries (ASI) shows that more than 85% of the inputs were imported.
    • UN data for India, China, Vietnam, Korea and Singapore (2017-2019), show that except for India, all countries exported more mobile phone parts than imports.
    • More export than import by these countries indicate the presence of facilities that add value to these parts before exporting them.
    • India, on the other hand, imported more than it exported.
    • Therefore, while the PMP policy increased the value of domestic production, improvement in local value addition remains low.
    • The new PLI policy offers an incentive subject to thresholds of incremental investment and sales of manufactured goods.
    • Thus, focus remains on increasing value of domestic production, and not local value addition.

    2) Shift from China unlikely

    • India produced around 29 crore units of mobile phones for the year 2018-19; 94% of these were sold in the domestic market.
    • This implies that much of the incremental production and sales under the PLI policy will have to be for the export market.
    • Recently, a study by Ernst & Young showed that if the cost of production of a mobile phone is say 100 (without subsidies), then the effective cost (with subsidies and other benefits) of manufacturing mobile phone in China is 79.55, Vietnam, 89.05, and India (including PLI), 92.51.
    • So, it may be premature to expect a major chunk of mobile manufacturing to shift from China to India.

    3) PLI doesn’t strengthen the current export competitiveness

    • India’s mobile phone exports grew from $1.6 billion in 2018-19 to $3.8 billion in 2019-20, but per unit value declined from $91.1 to $87, respectively.
    • This shows that our export competitiveness seems to be in mobiles with lower selling price.
    • However, for foreign firms chosen under the PLI policy, the incentive will be at and above ₹15,000 ($204.65).
    • So, it is clear that the PLI policy does not strengthen our current export competitiveness in mobile phones.

    4) Absence of domestic firms

    • Domestic firms have been nearly wiped out from the Indian market.
    • So, their ability to take advantage of the PLI policy and grab a sizeable domestic market share seems difficult.
    • Domestic firms may have the route of exporting cheaper mobile phones to other low-income countries.
    • However, their performance in the last couple of years has not been promising.

    5) Importance of supply chain colocation

    • The six component firms that have been given approval under the ‘specified electronic components segment’do not complete the mobile manufacturing ecosystem.
    • For example, when Samsung set up shop in Vietnam, it relied heavily on its Korean suppliers which co-located with it to produce intermediate inputs, so much so that 63 among Samsung’s 67 suppliers then were foreign.
    •  Though Samsung is invested hugely in India, it has not colocated its supply chain in the country.
    • So, the foreign firms chosen under the PLI policy should be encouraged to colocate their supply ecosystems in the country.

    6) Complaint at WTO against PMP

    • In September 2019, Chinese Taipei contested the raise in tariffs under the PMP.
    • If the PMP is found to be World Trade Organization (WTO) non-compliant, then we may be flooded with imports of mobile phones.
    • This might make the local assembly of mobile phones unattractive.
    • This will affect the operations of the mobile investments done under the PMP.

    Conclusion

    The PMP policy, since 2016-17 has barely been helpful in raising domestic value addition in the industry even though value of production expanded considerably.

    B2BASICS

  • What is Debt-to-GDP Ratio?

    India’s public debt ratio, which remarkably remained stable at about 70% of the GDP since 1991, is projected to jump by 17 percentage points to almost 90% a/c to IMF.

    Try this PYQ:

    Q.Consider the following statements:

    1. Most of India’s external debt is owed by governmental entities.
    2. All of India’s external debt is denominated in US dollars.

    Which of the statements given above is/are correct?

    (a) 1 only

    (b) 2 only

    (c) Both 1 and 2

    (d) Neither 1 nor 2

    Why such a spike?

    • The increase in public spending, in response to COVID-19, and the fall in tax revenue and economic activity, will make public debt jump by 17 percentage points to almost 90% of GDP.

    What is Debt-to-GDP Ratio?

    • The Debt-to-GDP ratio is the ratio between a country’s government debt and its gross domestic product (GDP).
    • It measures the financial leverage of an economy.
    • A country able to continue paying interest on its debt-without refinancing, and without hampering economic growth, is generally considered to be stable.
    • A country with a high debt-to-GDP ratio typically has trouble paying off external debts (also called “public debts”), which are any balances owed to outside lenders.
    • In such scenarios, creditors are apt to seek higher interest rates when lending. Extravagantly high debt-to-GDP ratios may deter creditors from lending money altogether.
    • A low debt-to-GDP ratio indicates an economy that produces and sells goods and services sufficient to pay back debts without incurring further debt.
    • Geopolitical and economic considerations – including interest rates, war, recessions, and other variables – influence the borrowing practices of a nation and the choice to incur further debt.
  • The RBI tunes in to the economy

    The article analyses the recent changes signalled by the RBI in its policymaking.

    Changes in the economic policymaking

    • Recently the U.S. Fed declared that the Fed will not let inflation stand in the way of maximising employment.
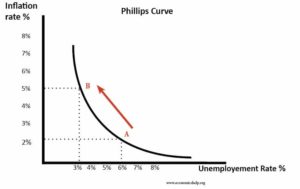
    • The reason for this was that the Phillips Curve, the relationship between inflation and unemployment, may no longer hold in the U.S. economy.
    • This is significant, given that the Anglo-American economics has been dominated by Phillips Curve.

    Why there was need for change in inflation targeting

    • Data show that the model that currently guides India’s inflation control strategy may be quite irrelevant.
    • This is seen in the recent behaviour of inflation.
    • We know that output contracted by more than 23% in the first quarter of this year.
    • Despite this staggering decline the inflation rate did not change,
    • This was contrary to experience that inflation reflects an ‘over heating’ economy, one growing too fast in relation to its potential.
    • This view represents the RBI’s official understanding of inflation, and presumably forms the basis of its policy of inflation targeting.
    • It was endorsed by the Government of India when it legislated the modern monetary policy framework to enable the RBI to pursue inflation targeting.
    • If the Phillips Curve, which the RBI’s approach internalises, exists, inflation should have decreased as India’s economy contracted during the lockdown.
    • The current inflation targeting mechanism had been imagined with developing economies in mind.
    • Inflation targeting mechanism is based on the idea that food prices are an important determinant of inflation along with imported inflation.
    • Accordingly, a macroeconomic contraction need not lower inflation.

    Role of food prices in India

    • A recent working paper of the RBI’s research department suggested that a more eclectic model than the one that underlies inflation targeting does a better job of forecasting inflation in India.
    • This model accepts a role for food prices, a possibility that is missed when embracing economic models developed in the western hemisphere, where food prices have stopped trending upwards over half a century ago.

    Conclusion

    The RBI shifting away from its rigid inflation targeting policy is in tune with the time and signals that the central bank is finally alive to India’s economy.


    Back2Basics: What is Philips Curve?

    • The Phillips curve is an economic concept, stating that inflation and unemployment have a stable and inverse relationship.
    • The theory claims that with economic growth comes inflation, which in turn should lead to more jobs and less unemployment.
    • However, the original concept has been somewhat disproven empirically due to the occurrence of stagflation in the 1970s, when there were high levels of both inflation and unemployment.

  • Places in news: Zojila Tunnel

    Union Transport Ministry has launched the first blasting for construction-related work at the Zojila tunnel that will provide all-year connectivity between Srinagar valley and Leh.

    These days various Himalayan passes and tunnels are overwhelmingly seen in news. Open your Atlas and try to spot all of them for now and once before the exam.

    Zojila Tunnel

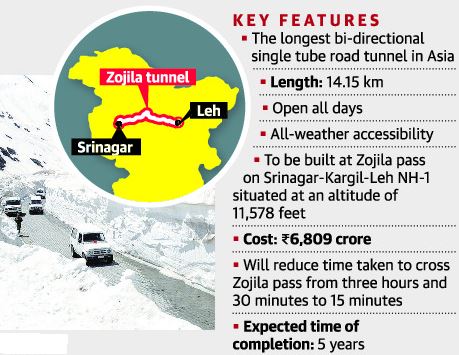
    • The Zojila is set to be Asia’s longest bi-directional tunnel.
    • It will connect Srinagar, Dras, Kargil and Leh via a tunnel through the famous Zojila Pass.
    • Located at more than 11,500 feet above sea level, the all-weather Zojila tunnel will be 14.15 km long and ensure road connectivity even during winters.
    • It will make the travel on the 434-km Srinagar-Kargil-Leh Section of NH-1 free from avalanches, enhance safety and reduce the travel time from more than 3 hours to just 15 minutes.
    • The speed limit inside the tunnel is likely to be the same as in the Atal tunnel – 80 kmph.

    Its significance

    • The project holds strategic significance as Zojila Pass is situated at an altitude of 11,578 feet on the Srinagar-Kargil-Leh National Highway and remains closed during winters due to heavy snowfall.
    • At present, it is one of the most dangerous stretches in the world to drive a vehicle and this project is also geo-strategically sensitive.
  • Feasibility of Export Driven Growth for India

    To aim for achieving high growth rate by focusing only on the domestic consumption and domestic demand could result in failure. The article argues for the focus on export to achieve the objective of growth.

    Domestic-demand led growth and its limitations

    • The debate in India has focused on domestic-demand led growth.
    • But there is no known model of domestic demand/consumption-led growth, anywhere that has delivered quick, sustained, and high rates of economic growth for developing countries.
    • India’s GDP growth of over 6 per cent after 1991 was associated with real export growth of about 11 per cent.
    • Moreover, domestic-demand led growth requires more public spending, tax cuts, private investment, and/or financial sector reforms: which is not feasible in the present context due to pandemic.
    • Consumption growth will be limited by the fact that household debt has grown rapidly in the last few years.
    • Consumption now can grow only if incomes grow.
    • Government spending could be a short run option, but COVID has limited that possibility.

    Why India should not follow advanced countries’ fiscal policies

    • India’s interest rates are not at zero and are unlikely to be so because of persistent inflation.
    • India’s borrowing is still considered risky which is reflected in ratings.
    • The favourable interest rate-growth differential that supports expansionary policy in the advanced countries is absent in India.
    • India may well have scope for expansionary fiscal policy in the short run but not as a medium run growth strategy.

    Why India should focus on export

    • Given all the above factors, India does not have the luxury of abandoning export orientation because the alternatives are so limited.
    • India’s market is too small to sustain any kind of serious import substitution strategy.
    • Small size of the market makes it difficult to offer investors the domestic market as bait and incentivising them to export.
    • India’s big, unexploited opportunities are in unskilled labour exports.
    • India is vastly under-exporting relative to its labour force.
    • Because China’s wages are rising as it has become richer, it has vacated about $140 billion in exports in unskilled-labour intensive sectors.
    • Post-COVID, the move of investors away from China will probably accelerate to hedge against supply chain disruptions.
    • India did not take advantage of the first China opportunity, now, a second opportunity stemming from geo-politics should be seized by India.
    • As India contemplates atmanirbharta, two deeper advantages of export orientation are always worth remembering.
    • 1) Foreign demand will always be bigger than domestic demand for any country.
    • 2) If domestic producers are competitive internationally, they will be competitive domestically and domestic consumers and firms will also benefit.

    Why openness of ecnonomy is important

    • Exploiting this opportunity in unskilled exports requires more not less openness.
    • To be internationally competitive, many parts and components have to be imported from so many different sources.
    • One indicator is the foreign or import contribution to exports.
    • China and Vietnam at the time of their export boom in textiles and clothing suggests that exports were highly dependent on imports (between 40 and 45 per cent).
    • In contrast, India’s import share is about 16 per cent.
    • Achieving Chinese and Vietnamese levels of success will therefore require greater imports and openness.

     Way forward

    • Export success will require genuine easing of costs of trading and doing business in India.
    • In the case of clothing, a key policy change in India will be to eliminate tariffs on all inputs. 
    • It will also require signing free trade agreements with Europe that still impose high duties on India’s clothing export, while Bangladeshi and Vietnamese exports which enjoy preferential access to world markets.

    Consider the question “As India contemplates atmanirbharta, we should not forget that export dynamism is essential for the rapid and sustained high economic growth. Comment.”

    Conclusion

    In sum, resisting the misleading allure of the domestic market, India should zealously boost export performance and deploy all means to achieve that. Pursuing rapid export growth in manufacturing and services should be an obsession with self-evident justification.

  • Dilution of efficiency based principles and its implications for finacial markets

    The article discusses the themes of the recently published books by Viral Acharya and Urjit Patel. Both the books deal with the issues with the financial markets in India

    Context

    • Two recently published books by Viral Acharya and Urjit Patel throws light on the issues with India’s finance market and role of RBI and the government.

    Importance of financial markets

    • Banks along with bond and equity markets oversee the matching of savers with borrowers.
    • Without financial markets, businesses would be restricted to investing out of retained earnings alone.
    • The financial markets have to satisfy the return appetites of savers while minimising their risk exposure.

    Undue preference to fiscal interest of the government

    • A major theme of Acharya’s book is the rampant subjugation of the financial and monetary infrastructure to the fiscal interests of the government.
    • Consider, for example, the conduct of monetary policy.
    • Since bank assets are marked to market, cuts in interest rates induce treasury gains for banks that effectively recapitalises them.
    • Consequently, rate cuts are preferred by governments needing to inject capital into public sector banks (PSBs).
    • For the same reasons, liquidity injections, which raise bond prices, are preferred to liquidity absorptions.
    • Fiscal compulsions of government can induce liquidity policies that have the opposite effect on the rate-setting by the MPC.
    • This contradiction is further complicated by the fact that the RBI is also the debt management agency for the government.
    • As a debt management agency, RBI’s key tasks is to sell government bonds at the highest possible price.
    • Pressures for regulatory forbearance in recognising NPAs often arise from the government wanting to avoid having to recapitalise PSBs.
    • The sameexplains the fact that stock exchanges in India having a 30-day disclosure norm for registered borrowers who default on their bank loans.
    • The standard in developed capital markets is immediate disclosure.
    • But that would induce an overnight rating downgrade of the concerned borrower thereby triggering additional capital provisioning needs for the lending bank.

    Conflict in government owning the PSBs

    • Patel’s book deals with conflicts inherent in the state owning the banks that control about three-fourth of total banking assets in India.
    • The primary problem with PSBs is that governments have used them as tools for macroeconomic management.
    • PSBs are regularly used for resource mobilisation to finance fiscal deficits.
    • The government often announces credit policies rather than having the banks allocate credit based on risk-return management criteria.
    • PSBs are the favoured instrument for meeting employment targets, supporting farmers through loan write-offs, etc.

    What are the implications of government owning PSBs

    • This kind of state interface naturally induces extreme levels of moral hazard in the behaviour of both debtors and creditors.
    • PSBs are not incentivised to exercise due diligence since they expect regulatory forbearance and recapitalisation in the event of rising NPAs.
    • The dilution of efficiency-based principles for banking has implications for all borrowers.
    • Creditworthy borrowers pay the risk premia to cover the riskiness due to unhealthy borrowers.
    • The worsening risk pool of borrowers is partly to blame for the fact that long term borrowing rates have remained stubbornly high despite repeated rate cuts by the MPC over the past 18 months.

    3 Problems and 3 Reforms

    Problems

    • There are three obvious problems with the existing architecture.
    • The first is the state ownership of banks.
    • The second is the chronically high fiscal deficit run by the consolidated public sector.
    • The third is the widespread perception that market regulators work under close government direction. 

    Reforms

    • Dealing with this will require, at a minimum, three reforms.
    • First, there has to be a wholehearted attempt at privatisation of PSBs.
    • Second, the RBI needs to be relieved of its public debt management role.
    • Third, the RBI has to be empowered to act independently of the government.

    Conclusion

    The growth of firms, which is a key driver of productivity and growth, requires well-functioning financial markets. India has a lot of work to do.


    Back2Basics: How cuts in interest rates induce treasury gains for banks?

    • Falling rates across the debt markets increase the demand for instruments that pay higher interest.
    • At this stage, prices of bonds which banks had bought when interest rates were high rise.
    • Hence, the value of government securities that banks have bought for the SLR requirement rises.
    • This increases profits as banks record the market value of these securities in their books.
    • Under this process, called marking to market, organisations record profits/losses in their books on a daily basis without actually booking any profit or loss.
    • So, more SLR bonds the bank holds, the higher its mark-to-market profit.
    • The other reasons bank profits rise when interest rates fall are pick-up in growth as companies borrow at lower rates as well as improvement in liquidity.

    Source:-

    https://www.businesstoday.in/moneytoday/banking/banks-to-make-huge-treasury-gains-on-bonds-on-rbi-rate-cut/story/193552.html

  • Explained: Auction theory

    This year, the Nobel Prize for Economics was awarded to Paul R Milgrom and Robert B Wilson for “improvements to auction theory and inventions of new auction formats”.

    Do you remember the 2G spectrum scam, Coalgate scam etc. that rocked the nation? Can you relate this auction theory for bidding public assets to private entities?

    What is Auction?

    • Essentially, it is about how auctions lead to the discovery of the price of a commodity.
    • Auction theory studies how auctions are designed, what rules govern them, how bidders behave and what outcomes are achieved.
    • When one thinks of auctions, one typically imagines the auction of a bankrupt person’s property to pay off his creditors.
    • Indeed, this is the oldest form of auction. This simple design of such an auction — the highest open bidder getting the property (or the commodity in question) — is intuitively appealing as well.

    Evolving definitions of auction

    • Over time, and especially over the last three decades, more and more goods and services have been brought under auction.
    • The nature of these commodities differs sharply. For instance, a bankrupt person’s property is starkly different from the spectrum for radio or telecom use.
    • Similarly, carbon dioxide emission credits are quite different from the spot market for buying electricity, which, in turn, is quite different from choosing which company should get the right to collect the local garbage.
    • In other words, no one auction design fits all types of commodities or seller.

    The Auction Theory

    Three key variables need to be understood before we move to actual propositions.

    (1) Rules of the auction

    • Imagine participating in an auction. Your bidding behaviour is likely to differ if the rules stipulate open bids as against closed/sealed bids.
    • The same applies to single bids versus multiple bids, or whether bids are made one after another or everyone bids at the same time.

    (2) Commodity or service

    • The second variable is the commodity or service being put up for auction. In essence, the question is how each bidder values an item.
    • This is not always easy to ascertain. In terms of telecom spectrum, it might be easier to peg the right value for each bidder because most bidders are likely to put the spectrum to the same use.
    • This is called the “common” value of an object.

    (3) Uncertainty

    • The third variable is uncertainty.
    • For instance, which bidder has what information about the object, or even the value another bidder associates with the object.

    The theory

    • Wilson developed the theory for auctions of objects with a common value — a value which is uncertain beforehand but, in the end, is the same for everyone”.
    • Wilson showed what the “winner’s curse” is in an auction and how it affects bidding.
    • As shown in the illustration, it is possible to overbid — $50 when the real value is closer to $25. In doing so, one wins the auction but loses out in reality.
    • Milgrom “formulated a more general theory of auctions that not only allows common values but also private values that vary from bidder to bidder”.
    • He analysed the bidding strategies in a number of well-known auction formats, demonstrating that a format will give the seller higher expected revenue when bidders learn more about each other’s estimated values.

    Significance of Auction theory

    • Throughout history, countries have tried to allocate resources in various ways.
    • Some have tried to do it through political markets, but this has often led to biased outcomes. For Ex: The rationing of essential goods worked in State-controlled economies. People who were close to the bureaucracy and the political class came out ahead of others.
    • Lotteries are another way to allocate resources, but they do not ensure that scarce resources are allocated to people who value it the most.
    • Auctions, for a good reason, have been the most common tool for thousands of years used by societies to allocate scarce resources.
    • When potential buyers compete to purchase goods in an auction, it helps sellers discover those buyers who value the goods the most.
    • Further, selling goods to the highest bidder also helps the seller maximise his or her revenues. So, both buyers and sellers benefit from auctions.
    • Whether it is the auction of spectrum waves or the sale of fruits and vegetables, auctions are at the core of allocation of scarce resources in a market economy.

    What are the criticisms levelled against auctions and what are the economists contribution?

    1.Issue of Winner’s Curse

    • The most common one is that auctions can lead buyers to overpay for resources whose value is uncertain to them.
    • This criticism, popularly known as the ‘winner’s curse’, is based on a study that showed how buyers who overpaid for U.S. oil leases in the 1970s earned low returns. Dr. Wilson was the first to study this matter.
    • The rational bidders may decide to underpay for resources in order to avoid the ‘winner’s curse’, and Dr. Wilson argued that sellers can get better bids for their goods if they share more information about it with potential buyers

    2.Auction formats

    • Economists traditionally working on auction theory believed that all auctions are the same when it comes to the revenues that they managed to bring in for sellers. The auction format, in other words, did not matter.
    • This is known as the ‘revenue equivalence theorem’.
    • But Dr. Milgrom showed that the auction format can actually have a huge impact on the revenues earned by sellers.
    • The most famous case of an auction gone wrong for the seller was the spectrum auction in New Zealand in 1990.
    • In what is called a ‘Vickrey auction’, where the winner of the auction is mandated to pay only the second-best bid, a company that bid NZ$1,00,000 eventually paid just NZ$6 and another that bid NZ$70,00,000 only paid NZ$5,000.
    • In particular, Dr. Milgrom showed how Dutch auctions, in which the auctioneer lowers the price of the product until a buyer bids for it, can help sellers earn more revenues than English auctions.
    • In the case of English auctions, the price rises based on higher bids submitted by competing buyers. But as soon as some of the bidders drop out of the auction as the price rises, the remaining bidders become more cautious about bidding higher prices.

    Conclusion

    • The contributions of Dr. Milgrom and Dr. Wilson have helped governments and private companies design their auctions better.
    • This has, in turn, helped in the better allocation of scarce resources and offered more incentives for sellers to produce complex goods.
  • [pib] Rashtriya Kamdhenu Aayog

    Rashtriya Kamdhenu Aayog (RKA) has started a nationwide campaign to celebrate “Kamdhenu Deepawali Abhiyan” this year on the occasion of Deepawali festival.

    Try this PYQ:

    Q.Consider the following statements:

    1. Agricultural soils release nitrogen oxides into the environment.
    2. Cattle release ammonia into the environment.
    3. Poultry industry releases reactive nitrogen compounds into the environment.

    Which of the statements given above is/are correct?

    (a) 1 and 3 only

    (b) 2 and 3 only

    (c) 2 only

    (d) 1, 2 and 3

    Rashtriya Kamdhenu Aayog (RKA)

    • RKA has been constituted by PM for the conservation, protection and development of cows and their progeny and for giving direction to the cattle development programmes.
    • It is a high powered permanent body to formulate policy and to provide direction to the implementation of schemes related to cattle so as to give more emphasis on livelihood generation.

    Why need RKA?

    • Livestock economy sustains nearly 73 million households in rural areas.
    • Even though, the country is the largest producer of milk, the average milk yield in India is only 50% of the world average.
    • The low productivity is largely due to deterioration in genetic stock, poor nutrition and unscientific management.
  • Economic recovery and its discontents

    The article highlights the measures taken by the RBI in the recent MPC meeting to assure the buyers of the Government bonds and ensuring the policy rate transmission.

    Dealing with the rate transmission issue and why it matters

    • The gap between the repo rate and the average lending rate of banks is at a record high.
    • So, the RBI and the MPC focused on improving rate transmission.
    • This gap can be broken up into two parts:
    • The first is the gap between the RBI-set repo rate and the rate at which the government of India borrows (the GSec yield).
    • It is also called the “term premium” can be influenced by the RBI’s actions.
    • The second is the gap between the GSec yield and the rate at which individuals or private firms borrow.
    • This gap reflects risk aversion in the financial system and a lack of capacity.
    • The RBI has avoided directly influencing the term premium, perhaps to maintain its credibility and independence, staying clear of accusations that it is financing the government’s fiscal deficit.
    • However, unless the rate at which the government borrows comes down borrowing costs for the whole economy will stay elevated.

    Challenge of Balance-of-Payment surplus (i.e. excess dollars)

    • Over the past few months, the country’s foreign currency reserves have been growing at an unprecedented rapid pace.
    • This means that India is getting far more dollars than it needs. Three factors are responsible for this.
    • 1) Some short-term factors responsible are weak imports and a faster normalisation of exports.
    • 2) There have also been structural shifts in India’s economic policy which point to a persistent BoP surplus.
    • In addition to low energy prices, policies supporting Atmanirbhar Bharat mean lower imports and the push towards making India a participant in global value chains mean higher exports.
    • 3) At the same time, India’s capital account is being opened up: The special-category government of India bonds, for example.

    Why BoP surplus is opportunity

    • When the excess dollar inflows turn into a deluge, as they have over the past six months, the supply of rupees in the domestic economy also becomes excessive.
    • If the RBI can direct this surplus into government bonds, it can maintain its independence and credibility, and at the same time achieve its target of rate transmission.

    Measures by the RBI to assure the bond market

    • The buyers of government bonds need to feel reassured of not getting hurt by the volatility in bond prices.
    • When bond prices rise, the yields fall, and vice versa.
    • Banks parking trillions of rupees with the RBI at 3.35 per cent overnight would earn nearly 6 per cent if they bought government bonds.
    • That they did not was because they were afraid of the bond prices falling, which would offset the gains from higher rates.
    • The increase in the Hold-To-Maturity limits by the RBI  by one year to March 2022, has assured the banks that they need not fear booking interim losses if bond prices are volatile.
    • The announcement that the RBI would purchase state and central government bonds on the market (even if in small sizes) would provide further comfort.
    • The change in assessment of inflation should help buyers of government bonds take the risk.
    • Banks or other bond investors that refrained from purchasing government bonds because they felt the RBI would increase interest rates at some point to comply with its legal mandate, would be reassured by this clear communication.
    • The targeted refinancing operations (TLTRO) should help bring down borrowing rates in the targeted industries.

    Conclusion

    Economic challenges may persist for the foreseeable future. The economic scars of the last six months are likely to take time to heal. The RBI and the MPC, which have been proactive, creative and accommodative so far, may have to stay so for a while longer.

  • Issues with the MSP in the age of surplus production

    The author analyses the inefficiencies in the MSP regime while comparing it with the sugar sector and the milk sector. The recent agri-reform in the opinion of the author could help to make the Indian agriculture more efficient.

    MSP system Vs. Market-driven system

    • MSP regime was the creation of the era of scarcity in the mid-1960s.
    • Indian agriculture has, since then, turned the corner from scarcity to surplus.
    • In a surplus economy, unless we make agriculture demand-driven, the MSP route can spell financial disaster.
    • This transition is about changing the pricing mix — how much of it should be state-supported and how much market-driven.
    • The new laws are trying to increase the relative role of markets without dismantling the MSP system.
    • Currently, no system is perfect, be it the one based on MSP or that led by the markets, but the MSP system is much more costly and inefficient.
    • The market-led system will be more sustainable provided we can “get the markets right”.

    Issues with the MSP

    • A perusal of the MSP dominated system of rice and wheat shows that the stocks with the government are way above the buffer stock norms.
    • The economic cost (to FCI) of procured rice comes to about Rs 37/kg and that of wheat is around Rs 27/kg.
    • No wonder, market prices of rice and wheat are much lower than the economic cost incurred by the FCI.
    • So, grain stocks with the FCI cannot be exported without a subsidy[i.e. export below the cost], which invites WTO’s objections.
    • The FCI’s burden is touching Rs 3 lakh crore which is not reflected in the Central budget as the FCI is asked to borrow more and more.
    • The FCI can reduce costs if it uses policy instruments like “put options”.

    2 Lessons: from sugarcane and milk pricing

    1) Populism resulted in making sugar industry globally non-competitive

    • In the case of sugarcane, the government announces a “fair and remunerative price” (FRP) [not MSP]to be paid by sugar factories [not paid by the Government].
    • While some states like Uttar Pradesh announces its own “state advised price” (SAP).
    • The sheer populism of SAP has resulted in cane arrears amounting to more than Rs 8,000 crore, with large surpluses of sugar that can’t be exported.
    • This sector has, consequently, become globally non-competitive.
    • Unless sugarcane pricing follows the C Rangarajan Committee’s recommendations the problems of the sugar sector will not go away.

    2) Success story of milk sector

    • In the case of milk co-operatives, pricing is done by the company in consultation with milk federations.
    • It is more in the nature of a contract price.
    • It competes with private companies, be it Nestle, Hatsun or Schreiber Dynamix dairies.
    • The milk sector has been growing at a rate two to three times higher than rice, wheat and sugarcane.
    • Today, India is the largest producer of milk — 187 million tonnes annually.

    So, how the recent reforms will help the farmers

    •  As a result of changes in farm laws in the next three to five years companies will be encouraged to build efficient supply lines somewhat on the lines of milk.
    • These supply lines — be it with farmers producer organisations (FPOs) or through aggregators — will, of course, be created in states where these companies find the right investment climate.
    • These companies will help raise productivity, similar to what has happened in the poultry sector.
    • Milk and poultry don’t have MSP and farmers do not have to go through the mandi system paying high commissions, market fees and cess.

    Conclusion

    The pricing system has its limits in raising farmers’ incomes. More sustainable solutions lie in augmenting productivity, diversifying to high-value crops, and shifting people out of agriculture to high productivity jobs elsewhere, the recent reforms are the steps in this direction.


    Back2Basic: What is MSP

    • Minimum Support Price (MSP) is a form of market intervention by the Government of India to insure agricultural producers against any sharp fall in farm prices.
    • The minimum support prices are announced by the Government of India at the beginning of the sowing season for certain crops on the basis of the recommendations of the Commission for Agricultural Costs and Prices (CACP).
    • The minimum support prices are a guarantee price for their produce from the Government.
    • The major objectives are to support the farmers from distress sales and to procure food grains for public distribution.
    • In case the market price for the commodity falls below the announced minimum price due to bumper production and glut in the market, government agencies purchase the entire quantity offered by the farmers at the announced minimum price.

    What are ‘put options’

    • Put options give holders of the option the right, but not the obligation, to sell a specified amount of an underlying security at a specified price within a specified time frame.
    • Put options are available on a wide range of assets, including stocks, indexes, commodities, and currencies.
    • Put option prices are impacted by changes in the price of the underlying asset, the option strike price, time decay, interest rates, and volatility.
    • Put options increase in value as the underlying asset falls in price, as volatility of the underlying asset price increases, and as interest rates decline.
    • They lose value as the underlying asset increases in price, as volatility of the underlying asset price decreases, as interest rates rise, and as the time to expiration nears.