💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: RBIxFunctions

  • India’s real rate moment, the cost of delay

    India’s real rate moment, the cost of delay

    Mentor comment

    The Reserve Bank of India (RBI) has held the repo rate at 5.25% as Consumer Price Index (CPI) inflation rose to 4.82% in August from 4.45% in July, the third consecutive month above the 4% target. Food inflation stands higher at 5.95%, and core inflation has risen to around 4.2%, which places price pressure beyond food alone. The August policy kept a neutral stance and projected inflation for the financial year 2026 to 2027 at around 5%. The latest reading has already moved past that projected trajectory for the year. The tension is that a repo rate which looks restrictive in nominal terms is delivering steadily less restraint in real terms, and it is doing so at a point when credit growth and output growth are both strong rather than weak.

    What is the ex ante real policy rate?

    1. Definition: The ex ante real policy rate is the repo rate less the inflation the economy expects over the period ahead, not the inflation already recorded in the last print.
    2. Why the distinction matters: Monetary policy operates through expected inflation, so subtracting yesterday’s inflation from today’s policy rate gives a number the economy is not actually responding to.
    3. The zero point: A repo rate of 5.25% held while inflation expectations move toward 5.25% leaves an ex ante real policy rate of approximately zero.
    4. What zero changes: A comfortably positive real policy rate and a zero real policy rate are two different monetary environments, even where the nominal rate on the screen has not moved.

    How close is India to a zero real rate?

    1. Headline drift above target: Inflation at 4.82% in August, up from 4.45% in July, is the third straight month above the RBI’s 4% target.
    2. Food and core moving together: Food inflation at 5.95% sits well above the headline, and core inflation at around 4.2% shows the pressure is broadening rather than concentrating in one basket.
    3. Projection already overtaken: The RBI projected inflation for the financial year 2026 to 2027 at around 5% at the August policy, and the latest print has moved beyond that average trajectory within weeks.
    4. Market expectations of tightening: The one year Overnight Indexed Swap (OIS) rate, the fixed rate at which market participants exchange a floating overnight rate over a year and therefore a direct read of expected future policy rates, is around 6%.
    5. The conditional statement: Sustained momentum in domestic prices combined with an external shock takes India into a zero real interest rate environment.

    What external pressures are pushing inflation up?

    1. West Asian conflict: Renewed conflict in West Asia has disrupted shipping through the Strait of Hormuz, the channel through which a large share of seaborne crude moves out of the Gulf.
    2. Crude above $100: Brent crude has moved above $100 a barrel with prices approaching $110.
    3. Currency channel: A weaker rupee raises the domestic price of every imported input irrespective of the dollar price.
    4. Global commodity prices: Elevated commodity prices worldwide compound the oil effect across the import basket.
    5. Monsoon uncertainty: The monsoon remains an independent source of risk to the food component, which is already the fastest rising part of the index.

    Why are rising inflation and negative real returns on bank deposits influencing household financial savings and gold demand?

    • Gold as an inflation hedge: Gold is often viewed as a store of value during periods of high inflation and economic uncertainty. Eg: If households expect inflation to remain high, they may increase purchases of gold jewellery or gold ETFs.
    • Higher inflation expectations reinforce the shift: If households expect prices to rise further, they may prefer holding assets whose value they believe can better preserve purchasing power. Eg: Reduce excess cash holdings.
    • Evidence from India: RBI research on the 2010-13 high-inflation period found that real returns on household financial savings weakened while demand for gold increased. The study estimated a 0.83 correlation between gold imports and household inflation expectations during the period.

    Should a supply driven price rise trigger a monetary response?

    1. The case against acting: A central bank should not raise rates simply because oil prices have increased, since a supply shock raises measured prices without excess demand behind it.
    2. The case for acting: A temporary price rise becomes permanent once it is embedded in expectations, wages, prices and credit, and that is the risk a central bank cannot leave untested.
    3. Demand is not weak: Gross Domestic Product (GDP) growth is running at 7.8%, so the standard argument that a falling real rate simply revives a slack economy does not describe current conditions.
    4. Amplification rather than neutralisation: A falling real rate stimulates demand and credit where the economy is operating below capacity. With demand already healthy and the shock coming from supply and expectations, the same mechanism amplifies inflation instead.

    Why does a near zero real rate not reach borrowers and savers alike?

    1. Credit growth: Bank credit grew 19.1% year on year at the end of August and remains exceptionally strong.
    2. Deposit growth and its composition: Deposits grew 17.8% at the end of August, the fastest pace in a decade, and much of that reflects foreign currency inflows under the RBI’s special Foreign Currency Non Resident Bank, or FCNR(B), mobilisation scheme, under which banks raise dollar denominated deposits from non residents on concessional terms. It does not establish that domestic households have become more willing to hold conventional deposits.
    3. Credit deposit ratio: The ratio stood at around 80.3% at the end of August, so banks face strong credit demand while competing for stable domestic deposits.
    4. Savers have exits: Households hold alternatives to bank deposits in mutual funds and equities, and a falling real return on deposits shifts them toward market linked assets, gold and other inflation hedges.
    5. The recorded precedent: RBI research on the earlier inflation episode found that rising inflation and inflation expectations cut the real return on household financial savings. Real returns on savings instruments turned negative across 2010 to 2013, household financial savings weakened, and gold demand rose, with the correlation between gold imports and household inflation expectations estimated at 0.83 over that period.

    Challenges to the ex ante real policy rate as a policy guide

    1. Expectations are estimated, not observed: The ex ante real rate rests on an inflation expectation that no market price reports directly, so the rate the committee acts on is itself a judgement. Eg. The RBI’s Inflation Expectations Survey of Households has run persistently above realised inflation.
      The Fix: Publish a single headline expectations series alongside each policy statement, so the real rate the committee is acting on is visible to the market.
    2. Supply shocks distort the signal: An imported price rise lifts measured inflation with no excess demand behind it, so a rate response tightens domestic activity that did not cause the problem. Eg. The 2022 conflict in Ukraine pushed Indian headline inflation past 7% on energy and edible oil alone.
      The Fix: State the persistence test on core inflation separately from the headline print in the policy rationale, and act on the former.
    3. Transmission lags defeat timing: A repo change reaches lending and deposit rates over several quarters, so a move calibrated to today’s reading lands on a different economy. Eg. The external benchmark linked lending rate regime was introduced in October 2019 because pass through under the marginal cost of funds based lending rate was slow and partial.
      The Fix: Extend external benchmark linking to the loan categories still priced off the marginal cost of funds based lending rate.
    4. Fiscal borrowing sets a competing rate: Heavy government issuance holds the term structure up, so the policy rate is not the only rate deciding the cost of credit. Eg. Benchmark ten year government securities have traded above the policy corridor irrespective of the stance the RBI announced.
      The Fix: Anchor annual borrowing to the announced debt to GDP path, so that the policy rate rather than issuance volume drives the cost of longer term credit.

    Conclusion

    The direction of the next move is settled. Inflation is rising toward the policy rate while growth and credit both remain strong, which leaves the policy rate doing less real work each month it is held. Timing is the instrument still in the RBI’s hands, and a timely 25 basis point adjustment ultimately costs less than a delayed 50 basis point correction. What to watch is whether the Monetary Policy Committee acts on the expectations reading or waits for a further headline print to confirm it.

    What is Monetary Policy?

    1. About: Monetary policy is the process by which the RBI controls money supply, interest rates and credit to achieve price stability, growth and financial stability.
    2. Statutory framework: The Monetary Policy Framework Agreement of 2015 made inflation targeting the primary objective, and the CPI Combined series compiled by the National Statistical Office is the target measure.
    3. Target and committee: The 4% target with a band of plus or minus 2 percentage points has been retained for the April 2026 to March 2031 period, and a six member Monetary Policy Committee sets the repo rate.
    4. Accountability trigger: A breach of the 2% to 6% band for three consecutive quarters obliges the RBI to submit a report to the government explaining the failure and the corrective action.

    Matching Previous Year Question

    [2024] What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.
  • After US Fed and others, will RBI also raise interest rates in Oct?

    Why in the News

    The Federal Open Market Committee (FOMC), the rate setting panel of the US central bank, has raised the federal funds rate target range by 25 basis points to 3.75% to 4%, its first increase in three years. The decision reversed the expectation that a new Chair at the helm of the Federal Reserve would push forward the US President’s agenda of lower interest rates, and all 12 FOMC members, including the new Chair, voted for the increase. The move is one of several, with the European Central Bank, the UAE and Bahrain all raising rates within days. The tension now sits with India. The Reserve Bank of India (RBI) is mandated to hold consumer price inflation at 4%, retail inflation has run above target for three straight months, and its Monetary Policy Committee (MPC) meets from 5 to 7 October.

    What is the Monetary Policy Committee (MPC)?

    1. What it is: The statutory committee of the Reserve Bank of India that decides the repo rate, the rate at which the central bank lends to commercial banks against government securities.
    2. Its mandate: It is required to target consumer price inflation of 4%, within a tolerance band of 2% to 6%.
    3. How the rate works: A higher repo rate raises the cost of funds for banks, which passes into lending rates and is intended to compress demand and with it price pressure.

    Why did the US Federal Reserve raise rates?

    1. The stated inflation reason: The FOMC said “inflation remains elevated” and that the decision to increase rates will support a “timelier return” to the 2% inflation target, closing with the line that the Committee “will deliver price stability”.
    2. The growth reading behind it: The FOMC described US economic activity as expanding at a “solid” pace, with domestic spending resilient, productivity growth strong and capital investment robust.
    3. The labour market reading: Job gains have kept pace with the workforce and the unemployment rate has changed little, which removes the usual argument against tightening.
    4. The political objection: The White House called the decision “rather unfortunate” and said it was not backed by a “particularly compelling economic case”, which the unanimous vote nonetheless overrode.

    What does the wider round of rate decisions show?

    1. The Gulf economies: The central banks of the UAE and Bahrain both raised their main interest rates by 25 basis points, to 3.9% and 4.5% respectively, mirroring the US decision.
    2. Japan at a three decade high: The Bank of Japan is widely expected to raise interest rates to 1.25%, the highest in 31 years, on the reading that risks to Japanese inflation are skewed to the topside.
    3. The drivers named for Japan: A weak yen raising import prices, no resolution in sight to the West Asia conflict or to traffic through the Strait of Hormuz, and strong artificial intelligence demand adding to goods and services prices.
    4. The euro area: The European Central Bank raised interest rates by 25 basis points, noting that upward price pressures caused by the West Asia conflict are set to keep inflation “well above target for an extended period”.
    5. The exception: The Bank of England left its policy rate unchanged at 3.75%, so the tightening round is broad rather than universal.

    What is happening to prices in India?

    1. Across every measure: In August, inflation for households, wholesalers and producers all increased, so the pressure is not confined to the retail basket.
    2. The headline number: The Consumer Price Index (CPI) rose 4.82% in August, the third straight month above the 4% target, though still inside the tolerance band.
    3. The near term projection: Some economists see CPI inflation jumping to 5.7% in September.
    4. The central bank’s own path: The RBI expects CPI inflation to average 4.7% in July to September, 5.9% in October to December, 5.5% in January to March 2027 and 5.3% in April to June 2027, so its own forecast breaches the upper tolerance band in the current quarter.

    Has price pressure become generalised, and does the MPC accept that?

    1. The MPC’s August reading: The Committee said in August that there were “little signs of” a generalisation of price pressures, which is the reading that supported holding the rate.
    2. The contrary assessment: The Group Chief Economic Adviser of the State Bank of India holds that the process of generalisation of price pressures has already started.
    3. The projected peak on that view: CPI inflation may cross the 6.5% mark before dropping to less than 6% in early 2027, which places it outside the tolerance band rather than merely above target.
    4. The prescription that follows: A 25 basis point increase at each of the October and December MPC meetings, followed by a pause to take stock against incoming data.

    Challenges to a rate hike by the RBI

    1. Supply driven price pressure: The increase is coming through imported energy and the West Asia conflict, and a policy rate acts on domestic demand rather than on an external supply shock. Eg. Retail inflation in India spiked in 2022 after crude and edible oil prices rose, and the repo rate was raised by 250 basis points over the following year without the shock itself abating.
      The Fix: Pair the rate action with supply measures on the affected commodities, such as duty adjustments and buffer releases, so the instrument matches the source of the pressure.
    2. Transmission lag: Policy rate changes reach lending and deposit rates over several quarters, so an October increase acts on prices well after the projected peak has passed. Eg. Banks repriced external benchmark linked loans within a quarter during the 2022 tightening while deposit rates moved far more slowly.
      The Fix: Expand the share of loans linked to an external benchmark so the increase reaches borrowers in the quarter it is announced.
    3. Cost to growth and to borrowers: A higher repo rate raises the cost of housing and working capital loans at a time when the price shock is already compressing household budgets. Eg. Home loan instalments rose across banks through the 2022 to 2023 tightening cycle.
      The Fix: Sequence the increase in two smaller steps with a stated pause, so borrowers and firms can price the path rather than the level alone.
    4. Limited currency benefit: Raising rates while major central banks are raising theirs leaves the interest differential roughly unchanged, so the rupee gains little support from the move. Eg. The rupee weakened through 2022 despite repeated repo rate increases, because the Federal Reserve was tightening faster.
      The Fix: Rely on reserve management and rupee settlement arrangements for exchange rate support, rather than loading that job onto the policy rate.

    Conclusion

    The question is no longer whether India is an exception to a global tightening round, since every major central bank except one has moved in the same direction within a week. It is whether the MPC accepts that price pressure has generalised, which is the reading it rejected in August and which its own forecast for October to December now strains. The decision window is 5 to 7 October, and a 25 basis point increase would be the first in three and a half years and would take the repo rate to 5.5%.

    Back2Basics: Federal Open Market Committee (FOMC)

    1. What it is: The monetary policy body of the US Federal Reserve System, which sets the target range for the federal funds rate.
    2. Composition: Twelve voting members, comprising the seven members of the Board of Governors, the President of the Federal Reserve Bank of New York, and four other regional Reserve Bank presidents serving on rotation.
    3. Frequency: It holds eight scheduled meetings a year and issues a statement with each decision.
    4. What the federal funds rate is: The rate at which US banks lend reserve balances to each other overnight, which anchors short term borrowing costs across the dollar system.

    Matching Previous Year Question

    “[2017] Which of the following statements is/are correct regarding the Monetary Policy Committee (MPC)? 1. It decides the RBI’s benchmark interest rates. 2. It is a 12-member body including the Governor of RBI and is reconstituted every year. 3. It functions under the chairmanship of the Union Finance Minister. Select the correct answer using the code given below: (a) 1 only (b) 1 and 2 only (c) 3 only (d) 2 and 3 only Answer: (a)”

  • RBI moves to define revolving credit for the first time and bar non-banks from offering it

    Why in the News

    The Reserve Bank of India (RBI) has proposed the first ever regulatory definitions of a term loan and revolving credit, and any facility failing the term loan test would become revolving credit that non-banking financial companies can no longer offer. Revolving credit is the instrument that carried formal finance into rural India, where income is seasonal and expenses run months ahead of receipts. The regulator is now weighing that inclusion gain against the risk of debt recycling through digital credit lines.

    What is revolving credit?

    1. About: Revolving credit comes with a pre approved credit limit against which a borrower can draw, repay and reuse without applying afresh each time.
    2. Contrast with a term loan: A normal term loan is sanctioned once and repaid in fixed instalments, and the limit is not restored after repayment.
    3. Function for the borrower: It works as a financial buffer, letting households, farmers and small entrepreneurs manage short term cash needs, emergencies and income fluctuations.
    4. Function for the lender: It provides recurring income streams, better utilisation of existing credit infrastructure and higher returns on assets through repeated usage.

    Why does rural India need revolving rather than term credit?

    1. Weight in the economy: Rural India contributes 46 to 50 percent of gross domestic product, and its income is largely seasonal.
    2. The cash flow mismatch: Farmers incur expenses on seeds, fertilisers, labour and irrigation months ahead of the income stream, and structural rigidity in the formal credit framework does not match that timing.
    3. What revolving credit does: It bridges the gap by supplying liquidity as and when it is required rather than in a single sanctioned tranche.
    4. Protective function: It acts as a shield against financial shocks and against informal loan sharks.
    5. The instruments it produced: The Kisan Credit Card (KCC), overdraft facilities, self help group credit lines, microfinance linked loans and, increasingly, digital credit products.
    6. Beyond the farm: Rural micro enterprises depend on flexible working capital, and the self help group and bank linkage programme supported by NABARD has created one of the world’s largest community based credit ecosystems.

    What has the Kisan Credit Card delivered?

    1. Introduction: The KCC scheme was introduced in 1998-99 as the principal form of revolving credit in rural areas.
    2. Widening scope: It expanded beyond crop cultivation to allied activities such as dairy, fisheries and animal husbandry.
    3. Current spread: More than 7.72 crore KCCs are active nationwide.
    4. Who holds them: The majority of beneficiaries are small and marginal farmers.
    5. Broader effect: The share of rural households accessing institutional credit channels such as the KCC has risen significantly.

    How have non-banking financial companies become the main channel?

    1. Why they entered: Small ticket unsecured revolving loans carry higher interest rates on higher risk, so the untapped rural market offered both volume and yield.
    2. Product spread: Non-banking financial companies (NBFCs) expanded revolving credit through consumer credit lines, digital loans, merchant finance, working capital loans to micro, small and medium enterprises, and fintech partnerships.
    3. Last mile role: They became a pillar of last mile credit delivery in rural and semi urban areas where banks face high transaction costs, lack of collateral and information asymmetry.
    4. Scale: More than 9,000 registered NBFCs operate in India, the vast majority in the Base Layer, with overall outstanding credit of Rs 58.61 lakh crore by mid-2026.
    5. Composition of the rural footprint: It is driven by microfinance institutions, gold loan companies, vehicle financiers, and lenders to micro, small and medium enterprises and small ticket retail borrowers.
    6. The gap in it: Agriculture remains a relatively small component of overall NBFC lending.

    What does the microfinance data show?

    1. Portfolio outstanding now: The portfolio outstanding of the microfinance sector, comprising NBFC microfinance institutions and small finance banks, stood at Rs 2.77 lakh crore as at March-end 2026.
    2. The two preceding years: It was Rs 3.35 lakh crore a year earlier and Rs 3.78 lakh crore as at March-end 2024.
    3. Rate of contraction: Total microfinance portfolio outstanding fell by about 17 percent year on year to Rs 2.77 lakh crore by March 2026, per the SIDBI-Equifax report.
    4. Geographic concentration: The top five States, Bihar, Uttar Pradesh, Tamil Nadu, West Bengal and Karnataka, account for 57 percent of total portfolio outstanding.
    5. What the numbers indicate: A two year contraction of over a quarter in the portfolio, concentrated in five States, signals asset quality stress rather than a policy induced slowdown.

    What is the RBI proposing to change?

    1. First ever definitions: The RBI is proposing an amendment that defines term loan and revolving credit for the first time.
    2. The term loan test: A term loan may be disbursed in one or more tranches, but repayment must follow a fixed schedule.
    3. The reuse bar: Once repaid, the credit limit cannot be restored or reused.
    4. The residual category: Any facility that does not meet this definition will be treated as revolving credit.
    5. The operative restriction: Revolving credit, so defined, is what NBFCs can no longer offer.

    Why is the RBI concerned?

    1. Evergreening: The regulator has repeatedly flagged the rapid growth of unsecured retail credit, particularly through fintech and NBFC partnerships offering high risk products as revolving credit.
    2. Masked indebtedness: It remains sceptical of forms of revolving credit where repayment patterns conceal the true level of household indebtedness.
    3. Ease outpacing discipline: Technology has made borrowing easier and faster than financial discipline, and multiple borrowings through various applications with weak due diligence have elevated risk.
    4. Underwriting by algorithm: Some digital platforms relied on algorithms and alternative data without sufficient assessment of repayment capacity.
    5. Purpose of the borrowing: Unlike farm or business revolving credit, many digital credit lines financed consumption rather than income generation.
    6. Official assessment: The latest Economic Survey acknowledged the critical role of NBFCs in inclusion while warning that unchecked expansion can weaken household balance sheets.

    Can the restriction be tightened without pushing borrowers back to informal lenders?

    1. The regulator’s mandate: The RBI must tread a delicate balance between financial inclusion and financial stability, and both claims are legitimate.
    2. The case against a blanket bar: A blanket restriction may be counterproductive, since the microfinance space has historically been underserved and lending is already muted on asset quality pressures and limited funding access.
    3. The instruments at stake: The KCC and similar instruments are essential for growth, while unchecked and easy accessibility through digital platforms and consumer finance channels creates fresh vulnerability.
    4. The real policy problem: The challenge is to identify credit that helps in income generation and separate it from credit that finances consumption, since the two carry different repayment logic.
    5. The failure mode: Excessive regulatory tightening may push borrowers back towards informal lenders, defeating the very purpose of financial inclusion.

    Challenges to Revolving Credit in Rural India

    1. Debt recycling: A revolving limit lets a borrower repay one obligation by drawing on another without the stress becoming visible. e.g. a household clearing one digital credit line by drawing on a second application in the same month.
    2. Multi lending and over indebtedness: Several lenders extending limits to the same household produce a repayment burden none of them has measured. e.g. the microfinance portfolio contracting by about 17 percent year on year to Rs 2.77 lakh crore by March 2026.
    3. Geographic concentration of risk: A localised shock hits a disproportionate share of the sector’s book. e.g. Bihar, Uttar Pradesh, Tamil Nadu, West Bengal and Karnataka holding 57 percent of microfinance portfolio outstanding.
    4. Consumption financing: Credit that funds consumption creates no repayment capacity of its own. e.g. digital credit lines used for durables and lifestyle spending rather than for working capital.
    5. Weak underwriting: Alternative data and algorithmic scoring substitute for an assessment of cash flow. e.g. platforms sanctioning limits without verifying seasonal farm income.
    6. Exclusion of tenant cultivators: Revolving farm credit is tied to land records, so the actual cultivator is often ineligible. e.g. oral lessees who cannot produce title to obtain a Kisan Credit Card.
    7. Delinquency and capital cost: Unchecked expansion raises delinquencies and capital requirements together, so profitability depends entirely on risk controls. e.g. small finance banks tightening disbursement after the microfinance portfolio fell from Rs 3.78 lakh crore in March 2024.

    Conclusion

    Revolving credit solved a timing problem that term lending could not, which is why the Kisan Credit Card, self help group credit lines and NBFC credit lines became the core of rural financial inclusion. The RBI is now proposing the first regulatory definitions of a term loan and revolving credit, with the effect that non-banks would be barred from the residual revolving category. The stated concern is evergreening and masked household indebtedness through fintech linked digital credit rather than farm or enterprise credit. The measure is at the proposal stage, and its success will be judged by whether the definitional line separates income generating credit from consumption credit, since a blanket restriction would return underserved borrowers to informal lenders.

    “[2014, GS3, 12.5 marks] “In the villages itself no form of credit organization will be suitable except the cooperative society.”-All India Rural Credit Survey. Discuss this statement in the background of agricultural finance in India. What constraints and challenges do financial institutions supplying agricultural finance face? How can technology be used to better reach and serve rural clients?”

  • RBI’s MPC Minutes Signal a Turn from Easing to Tightening

    Why in the News

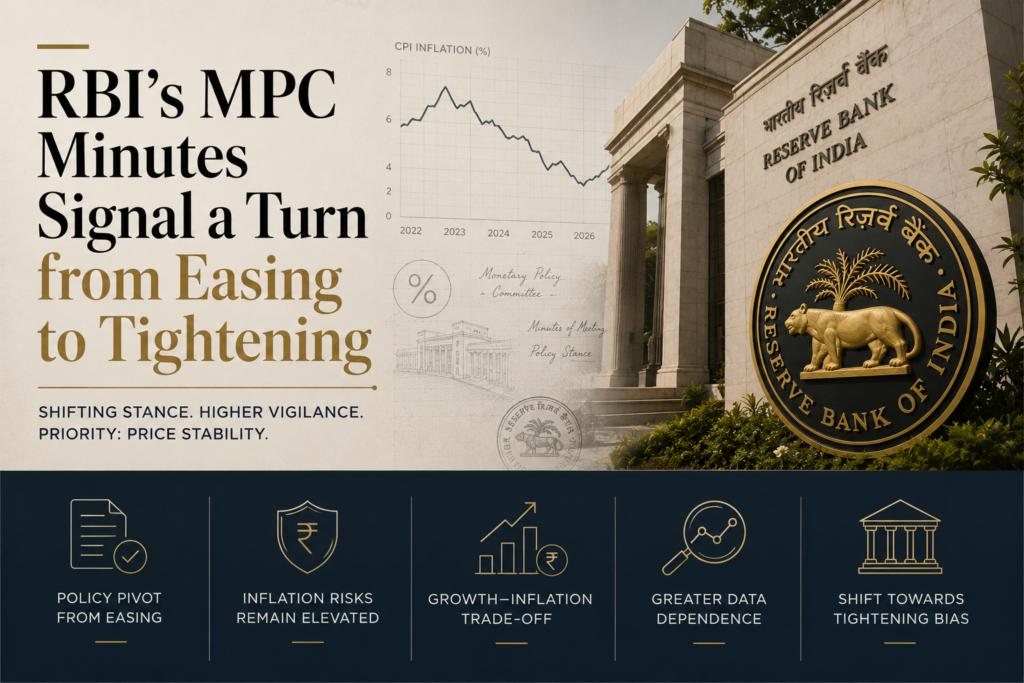
    The August 2026 MPC minutes show growing concern over rising inflation. Although the repo rate was kept unchanged at 5.25%, some members see a possible rate hike later in 2026-27 as inflation is projected to peak at 5.9% in Q3.

    MPC: Key Prelims Facts

    • Legal basis: RBI Act, 1934, amended in 2016.
    • Composition: 6 members
      • 3 from RBI
      • 3 external members appointed by the Central Government.
    • Chairperson: RBI Governor.
    • Voting: One vote per member; Governor has a casting vote in case of a tie.
    • Minutes: Published on the 14th day after the meeting.
    • Mandate: Set the policy repo rate to achieve the inflation target.

    August 2026 Policy Review

    • Repo rate: 5.25%, unchanged.
    • Growth forecast: Raised from 6.6% to 6.7%.
    • Inflation forecast: Lowered from 5.1% to 5%.
    • Q3 inflation projection: 5.9%.
    • Inflation is expected to decline after the Q3 peak, supporting the decision to wait rather than tighten immediately.

    Core Inflation

    • Core inflation = CPI inflation excluding food and fuel.
    • It captures relatively persistent, demand-driven price pressures that monetary policy can influence.
    • Core excluding precious metals additionally removes gold and silver, preventing bullion price movements from distorting the underlying inflation signal.

    Second-Round Inflation Effects

    • A first-round shock, such as higher oil prices, can spread through the economy:
    • Higher oil prices → higher input costs → higher production costs → higher prices of goods/services → broader inflation
    • This transmission is called a second-round effect.

    De-Anchoring of Inflation Expectations

    • When households and firms stop believing inflation will return to the 4% target, they may:
    • Expect high inflation → demand higher wages/prices → firms raise prices → inflation becomes self-sustaining
    • This is why MPC members are closely watching expectations and generalisation of price pressures.

    Why a Rate Hike May Be Difficult

    • Supply shocks: Interest rates cannot directly increase oil supply or food production.
    • Transmission lag: Monetary policy affects the economy with a time lag.
    • Food weight: Food shocks can substantially raise headline CPI.
    • Growth trade-off: Higher rates can weaken investment and consumption.
    • Exchange rate: Rate differentials and rupee depreciation can affect imported inflation.
    • Fiscal/administered prices: Taxes, MSP and administered fuel prices lie largely outside MPC control.
    • Changing CPI basket: Changes in CPI weights can affect historical comparisons.

    “[2024, GS3, 10 marks] What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.”

    [2017] Which of the following statements is/are correct regarding the ‘Monetary Policy Committee (MPC)?
    1. It decides the RBI’s benchmark interest rates.
    2. It is a 12-member body including the Governor of RBI and is reconstituted every year.
    3. It functions under the chairmanship of the Union Finance Minister.
    Select the correct answer using the code given below:

    [A] 1 only

    [B] 1 and 2 only

    [C] 3 only

    [D] 2 and 3 only

  • Centre approves 1 billion Rs 10, Rs 20 polymer banknotes

    Why in News?

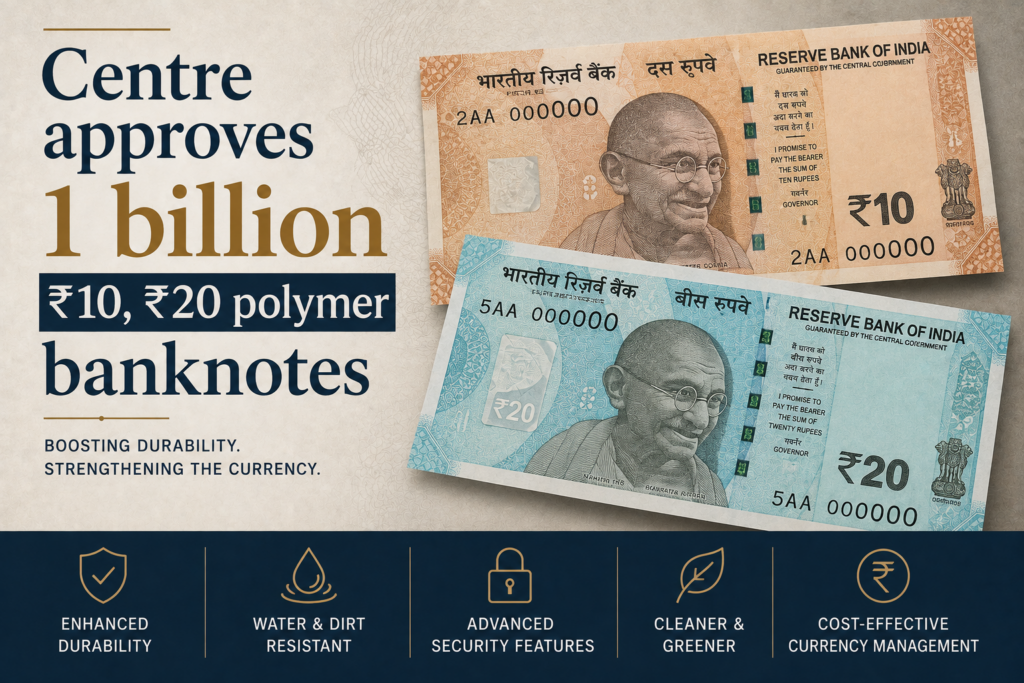
    Government approved 1 billion polymer notes each of ₹10 and ₹20 for field trials, following an RBI proposal under Section 25 of the RBI Act, 1934.

    What are Polymer Banknotes?

    • Made from a thin plastic film instead of cotton-paper.
    • More durable, moisture-resistant and hygienic.
    • Offer enhanced anti-counterfeiting features.
    • Have a longer circulation life, reducing replacement needs.

    Government Approval

    • Denominations: ₹10 and ₹20.
    • Quantity: 1 billion each.
    • Will circulate alongside paper notes.
    • Regular issuance will depend on successful field trials.
    • Procurement is at an initial stage, so cost and timeline are not yet fixed.

    Why Polymer Notes?

    • Longer life → lower replacement costs.
    • Higher security → difficult to counterfeit.
    • Better durability → resistant to dirt, water and wear.
    • Global precedent → used by several countries.

    Currency Management: Key Facts

    • RBI: Sole issuer of banknotes, except ₹1 note.
    • Government of India: Issues coins and ₹1 note.
    • Section 22, RBI Act: RBI’s sole right to issue banknotes.
    • Section 24: Specifies permissible denominations.
    • Section 25: Design, form and material require Central Government approval on RBI recommendation.
    • Coinage Act, 2011: Governs coins and ₹1 note.

    Back2Basics: RBI

    • Established under RBI Act, 1934; began operations in 1935.
    • Nationalised in 1949.
    • Functions as India’s central bank and monetary authority.
    • Manages currency, monetary policy, banking and payment systems.

    [2025] Which of the following are the sources of income for the Reserve Bank of India?
    I. Buying and selling Government bonds
    II. Buying and selling foreign currency
    III. Pension fund management
    IV. Lending to private companies
    V. Printing and distributing currency notes
    Select the correct answer using the code given below.

    [A] I and II only

    [B] II, III and IV

    [C] I, III, IV and V

    [D] I, II and V

  • Can banks lock phone for loan default? What RBI’s new rules say

    Why in the News

    The Reserve Bank of India (RBI) has issued a comprehensive set of rules governing how commercial banks recover unpaid loans, coming into force on January 1, 2027. The framework introduces India’s first detailed regulation of technology-based restrictions on mobile phones financed through bank loans, balancing lenders’ recovery rights against borrower protection.

    What is the RBI’s new loan-recovery framework?

    1. Comprehensive recovery rules: The framework governs the conduct of banks and outsourced recovery agents in recovering unpaid loans, and applies to all commercial banks.
    2. Board-governed process: It makes recovery a board-governed process rather than a purely operational function, requiring a documented recovery policy.
    3. Effective date: It comes into force on January 1, 2027.

    Can banks now lock a financed phone?

    1. Only for device loans: Technology-based restrictions can be used only where the loan specifically financed that smartphone, tablet or laptop.
    2. Disclosure required: The loan agreement must clearly disclose these restrictions in advance.
    3. 30-day threshold: No restriction can be activated until the account is 30 days past due, despite notices to the borrower.
    4. Gradual escalation: Restrictions must be introduced gradually.
    5. 60-day limit for full lock: Complete restrictions can be imposed only after 60 days of non-payment, and outgoing calls cannot be blocked before that.

    What safeguards protect borrowers?

    1. Essential functions protected: Banks cannot disable incoming calls, SMS services or emergency functions.
    2. Work not disrupted: Restrictions must not interfere with activities necessary for the borrower’s work or employment.
    3. Visibility: Borrowers must be able to view the status of restrictions on their device at any time.
    4. Fast restoration: Once overdue amounts are paid, functionality must be restored within one hour.
    5. Compensation: Where restoration is delayed by the bank, compensation of Rs 250 per hour is payable until access is restored, subject to a ceiling equal to the loan amount.
    6. Data protection: Banks and third-party technology providers are barred from accessing personal data stored on borrowers’ devices.

    How are recovery agents regulated?

    1. Fixed contact hours: Agents can contact borrowers only between 8 am and 7 pm, unless the borrower requests otherwise.
    2. Identification: They must identify themselves through identity cards and authorisation letters and carry copies of notices issued by the bank.
    3. Certification: Only certified individuals can undertake recovery work.
    4. Background checks: Banks must conduct background verification before appointing agents and periodically thereafter.

    How are banks held accountable?

    1. Call recording: Banks must record recovery-related calls, keep records for at least six months and inform borrowers that conversations are recorded.
    2. No aggressive incentives: Recovery targets and incentive structures should not encourage aggressive behaviour.
    3. Grievance redressal: Every bank must set up a dedicated grievance redressal mechanism for recovery complaints, detailed in loan documents and communications.
    4. Direct responsibility: Banks are made directly responsible for the conduct of outsourced recovery personnel.

    Why were fresh directions issued?

    1. Retail lending boom: India’s retail lending market has expanded rapidly, driven by digital loans, unsecured personal credit and Buy Now Pay Later products.
    2. Device financing: Growth in financing for smartphones and consumer electronics raised the practice of remotely disabling devices.
    3. Rising complaints: Complaints about harassment by recovery agents and aggressive collection practices have grown.

    Conclusion

    The RBI has converted loan recovery from an operational function into a board-governed, rights-based process, and for the first time regulated the remote disabling of financed devices. The framework takes effect on January 1, 2027, and its impact will depend on how banks build recovery policies, certify agents and enforce the device-restriction safeguards. The next milestone is compliance readiness across all commercial banks before the effective date.

    Back2Basics: Reserve Bank of India (RBI)

    1. Type: Central bank and monetary authority of India.
    2. Established: 1935, nationalised in 1949.
    3. Governing Acts: RBI Act, 1934 and Banking Regulation Act, 1949.
    4. Headquarters: Mumbai.
    5. Core functions: Monetary policy, currency issue, banker to the government, banking regulation and supervision, and management of foreign exchange.

    What are the RBI’s Functions?

    1. About: The RBI is India’s central bank, established in 1935, responsible for monetary policy, currency issuance and financial system regulation.
    2. Rationale: It exists to maintain price stability, ensure adequate credit flow and safeguard the stability of the banking and payments system.
    3. Regulatory scope: It regulates commercial banks on liquidity of assets, branch expansion, mergers, winding-up and, increasingly, conduct towards customers.

    Statutory Framework Governing Bank Regulation

    1. Reserve Bank of India Act, 1934: Establishes the RBI and its monetary and regulatory powers.
    2. Banking Regulation Act, 1949: Empowers the RBI to license, supervise and regulate banks, including branch expansion, mergers and winding-up.
    3. Payment and Settlement Systems Act, 2007: Provides for RBI regulation of payment systems, including digital lending rails.
    4. Consumer Protection Act, 2019: Reinforces borrower rights against unfair practices.

    Government and RBI Initiatives for Borrower Protection

    1. Fair Practices Code for Lenders: Sets standards for transparency and conduct in lending.
    2. RBI Integrated Ombudsman Scheme: Provides a single redressal window for customer complaints against banks and lenders.
    3. Digital Lending Guidelines, 2022: Regulate loan disbursal, data use and recovery by digital lenders.
    4. RBI Retail Direct and Financial Literacy programmes: Improve borrower awareness and protection.

    Key Facts about RBI Regulation of Banks

    1. Effective date of new recovery rules: January 1, 2027.
    2. Compensation cap: Rs 250 per hour for delayed restoration, ceiling equal to the loan amount.
    3. Recovery contact window: 8 am to 7 pm.
    4. Record retention: At least six months for recovery calls.

    Challenges in Loan Recovery and Retail Lending

    1. Agent harassment: Aggressive and coercive collection practices remain widespread.
    2. Digital coercion: Remote disabling of financed devices can cut borrowers off from work and emergencies.
    3. Data misuse: Access to personal data on devices raises privacy risks.
    4. Over-leverage: Rapid unsecured and Buy Now Pay Later lending raises default risk.
    5. Enforcement gaps: Outsourced agents are hard to monitor and hold accountable.
    6. Grievance delays: Weak redressal leaves borrowers without timely remedy.

    Way Forward

    1. Enforce certification: Ensure only verified, certified agents undertake recovery.
    2. Audit device restrictions: Independently audit compliance with the 30-day and 60-day safeguards.
    3. Strengthen redressal: Make grievance mechanisms accessible and time-bound.
    4. Protect data: Enforce the bar on accessing personal data with strict penalties.
    5. Promote responsible lending: Tighten underwriting for unsecured and device-linked credit.

    PYQ Relevance

    [2013] The Reserve Bank of India regulates the commercial banks in matters of

    (1) liquidity of assets

    (2) branch expansion

    (3) merger of banks

    (4) winding-up of banks.

    Select the correct answer using the codes given below:

    (a) 1 and 4 only

    (b) 2, 3 and 4 only

    (c) 1, 2 and 3 only

    (d) 1, 2, 3 and 4

  • RBI holds repo rate; core versus headline inflation debate

    Why in the News

    The Reserve Bank of India (RBI) held the repo rate at 5.25%. Economists are divided over whether the central bank is anchoring policy to headline CPI or to core inflation, which strips out food and fuel.

    What is core inflation?

    1. Definition: Core inflation measures price change after removing volatile food and fuel components, showing the underlying, persistent trend.
    2. Why it matters: Monetary policy affects demand-driven prices, not a monsoon-driven food spike, so core is a cleaner signal for interest-rate decisions.

    Why is the anchor contested?

    1. Mandate is headline: The RBI’s legal target is headline retail inflation around 4%, not core, so leaning on core risks appearing to shift the goalpost.
    2. Food weight is large: Food is a large share of India’s consumption basket, so ignoring it understates the inflation households actually face.
    3. Credibility risk: Frequent redefinition of the operative measure weakens the predictability that anchors inflation expectations.

    Conclusion

    The rate hold reflects a judgement that underlying price pressure is easing even as headline stays elevated. The next milestone is whether food inflation cools enough to align headline with the target.

    PYQ Relevance

    [UPSC 2024] What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.
    Linkage: The PYQ examines the limits of monetary policy in controlling persistent food-driven inflation. The debate over headline versus core inflation highlights how the RBI balances its inflation mandate with supply-side food shocks.

  • RBI holds the repo rate for a fourth straight review

    Why in the News

    The Reserve Bank of India (RBI) kept its repo rate unchanged at 5.25% for a fourth consecutive Monetary Policy Committee (MPC) meeting. The decision exposes the tension between reviving growth through cheaper credit and defending price stability while inflation sits above target.

    What is the Monetary Policy Committee (MPC)?

    1. Statutory body: The MPC is the six member committee that sets the benchmark repo rate to keep retail inflation within a legislated band.
    2. Mandate: It is tasked with holding Consumer Price Index (CPI) inflation at 4%, within a tolerance range of 2% to 6%.

    Why has the RBI chosen to hold rather than cut?

    1. Inflation above target: Retail inflation has stayed above the 4% midpoint, removing headroom for a rate cut.
    2. Geopolitical spillover: The bank flagged the West Asia conflict and crude price risk as reasons to preserve policy space.
    3. External buffer: Protecting foreign exchange reserves and the rupee against capital outflows outranked a growth focused easing.

    What are the risks in a prolonged hold?

    1. Growth drag: A sustained high rate raises borrowing costs for firms and households and can slow investment.
    2. Transmission gap: Banks may not pass rate signals through fully, weakening the policy’s real economy effect.
    3. Fiscal friction: Elevated rates raise the government’s own interest burden on fresh borrowing.

    Conclusion

    The RBI is prioritising price and currency stability over a growth stimulus while inflation remains above target. The next MPC review will turn on whether inflation cools back toward 4% and whether the external environment stabilises.

    Back2Basics: Repo Rate

    1. Definition: The rate at which the RBI lends short term funds to commercial banks against securities.
    2. Function: It is the primary tool of monetary policy transmission; a higher repo rate raises the cost of money and cools demand.

    Matching Previous Year Question

    “[2017] Which of the following statements is/are correct regarding the Monetary Policy Committee (MPC)?
    1. It decides the RBI’s benchmark interest rates.
    2. It is a 12-member body including the Governor of RBI and is reconstituted every year.
    3. It functions under the chairmanship of the Union Finance Minister.
    Select the correct answer using the code given below:
    (a) 1 only
    (b) 1 and 2 only
    (c) 3 only
    (d) 2 and 3 only
    Answer: (a)”

  • RBI Monetary Policy Committee holds the repo rate at 5.25%

    Why in the News

    The Monetary Policy Committee (MPC) of the Reserve Bank of India (RBI) has kept the policy repo rate unchanged at 5.25%, balancing inflation risks against the need to support economic growth amid global uncertainties.

    What is the Monetary Policy Committee (MPC)?

    • Statutory body: Constituted under the Reserve Bank of India Act, 1934 (amended in 2016).
    • Composition: Six members:
      • Three RBI members: Governor (Chairperson), Deputy Governor in charge of Monetary Policy, and one RBI nominee.
      • Three external members: Appointed by the Central Government.
    • Decision-making: Each member has one vote; in case of a tie, the Governor has a casting vote.
    • Mandate: Maintain Consumer Price Index (CPI) inflation at 4%, with a tolerance band of 2% to 6%.

    What did the MPC decide?

    • Repo rate unchanged: Retained at 5.25%.
    • Policy stance: Continues to remain neutral.
    • Liquidity corridor:
      • Standing Deposit Facility (SDF): 5.0%
      • Marginal Standing Facility (MSF): 5.5%
      • Bank Rate: 5.5%
    • Growth outlook: Real GDP growth projected at 6.7%.
    • Inflation outlook: CPI inflation rose to 4.4% in June 2026, crossing the 4% target after remaining below it for 16 months.

    Why did the MPC maintain the status quo?

    • Global uncertainties: Rising crude oil prices and geopolitical tensions in West Asia pose inflation risks.
    • Monsoon concerns: An El Nino driven deficient monsoon could increase food inflation.
    • Data dependent approach: The MPC prefers to wait for clearer inflation and growth signals before changing policy rates.

    Back2Basics: Reserve Bank of India (RBI)

    • Established: 1935 under the Reserve Bank of India Act, 1934.
    • Functions: Monetary authority of India, Banker to the Government, Banker to banks, Regulator and supervisor of the banking system, and Manager of foreign exchange reserves.
    • Major monetary policy instruments: Repo Rate, Standing Deposit Facility (SDF), Marginal Standing Facility (MSF), Cash Reserve Ratio (CRR), Statutory Liquidity Ratio (SLR), Open Market Operations (OMOs)

    “[2017] Which of the following statements is/are correct regarding the Monetary Policy Committee (MPC)?
    1. It decides the RBI’s benchmark interest rates.
    2. It is a 12-member body including the Governor of RBI and is reconstituted every year.
    3. It functions under the chairmanship of the Union Finance Minister.
    Select the correct answer using the code given below:
    (a) 1 only
    (b) 1 and 2 only
    (c) 3 only
    (d) 2 and 3 only

  • RBI tightens transparency norms on bulk deposit rates, allows LCR linked pricing

    Why in the News?

    The RBI has mandated daily disclosure of bulk deposit interest rates while allowing LCR-linked differential pricing. The move follows the MSRDC interest payment controversy, which exposed opaque pricing practices for large depositors.

    What are the new RBI norms?

    • Banks must publish bulk deposit rates daily.
    • Interest rates must be uniform for deposits of the same amount accepted on the same day.
    • Differential rates are allowed only under the Liquidity Coverage Ratio (LCR) framework.
    • Applicable to bulk deposits, wholesale funding, and rupee deposits of non-residents.

    What is the Liquidity Coverage Ratio (LCR)?

    • A Basel III liquidity standard ensuring banks hold sufficient High Quality Liquid Assets (HQLA) to meet 30-day stressed cash outflows.
    • Minimum LCR in India: 100%.
    • Current run-off rate: 12.5% (including 2.5% for digital deposits).

    What triggered the reform?

    • A bank allegedly disguised ₹45 crore paid to MSRDC as marketing expenditure during 2023–25.
    • The irregularity was detected through an internal audit, leading to a vigilance probe and the resignation of the bank’s chairman.

    Key Challenges

    • Hidden arrangements may still require internal audits to detect.
    • Daily disclosures cannot eliminate all off-book incentives.
    • Digital deposits may require periodic revision of run-off rates.
    • Stronger oversight of deposits by government entities is needed.

    Conclusion

    The RBI’s reforms improve transparency and fairness in bulk deposit pricing by replacing opaque negotiations with a rule-based disclosure system, though effective supervision remains critical.

    Value Addition

    • Liquidity Coverage Ratio (LCR) = High Quality Liquid Assets (HQLA) ÷ Net Cash Outflows (30 days) × 100. Minimum requirement: 100%
    • High Quality Liquid Assets (HQLA): Cash, RBI balances, and Government Securities (G-Secs)
    • Basel III: Introduced after the 2008 Global Financial Crisis. Strengthens capital adequacy, liquidity, and bank resilience.
    • Bulk Deposits: Large-value deposits accepted from corporates, institutions, trusts, and government entities, carrying higher liquidity risk than retail deposits.

    [2015] Basel III Accord’ or simply ‘Basel III’ often seen in the news, seeks to

    (a) develop national strategies for the conservation and sustainable use of biological diversity

    (b) improve banking sector’s ability to deal with financial and economic stress and improve risk management

    (c) reduce the greenhouse gas emissions but places a heavier burden on developed countries

    (d) transfer technology from developed countries to poor countries to enable them to replace the use of chlorofluorocarbons in refrigeration with harmless chemicals