💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Economics

  • Steel mills face margin squeeze as global coking coal prices rise

    Why in the News

    Premium hard coking coal has averaged $236 per metric ton freight on board Australia in the first seven months of 2026, a jump of 25 percent over last year. Indian steelmakers import 95 percent of their coking coal and face competition from cheap Chinese steel at the selling end, so the input shock cannot be passed on to buyers.

    What is coking coal and why does it decide steelmaking costs?

    1. Definition: Coking coal is a low ash, low sulphur coal that is baked into coke, the carbon source that both fuels the blast furnace and chemically strips oxygen from iron ore. It is not interchangeable with the thermal coal used in power stations.
    2. Share of cost: Coking coal accounts for nearly 40 percent of steel production costs, which makes its price the single largest swing factor in a mill’s margin.
    3. Import dependence: India meets 95 percent of its coking coal needs through imports, with at least half shipped from Australia.
    4. Cost transmission: For blast furnace based steelmakers, every $10 a ton increase in coking coal prices adds approximately $7 to $9 per metric ton to steelmaking costs.

    What does freight on board (FOB) Australia mean?

    1. Price basis: Freight on board (FOB) is the price of the cargo at the loading port, before ocean freight and insurance are added. The $236 per metric ton benchmark is therefore the Australian port price, not the delivered Indian cost.

    Why have global coking coal prices risen this year?

    1. Australian supply disruptions: Output interruptions at Australian mines removed tonnage from a market where India sources at least half its requirement.
    2. Slower ramp up at new mines: New Australian capacity has come on stream more slowly than expected, so the supply gap was not filled.
    3. Middle East conflict: The conflict in the Middle East provided price support across the seaborne coal complex.
    4. Shanxi accident: A large accident at a coal mine in Shanxi, China removed further tonnage from the market in the most recent phase of the price rise.
    5. Benchmark movement: Premium hard coking coal averaged $236 per metric ton FOB Australia over the first seven months of 2026, 25 percent above the previous year, on the metallurgical coal and coke market assessment of the consultancy CRU.
    6. Outlook for the rest of the year: Costs are likely to remain high in the second half of 2026, partly due to the loss of supply following the Shanxi coal mine disaster, on the assessment of BMI, a unit of Fitch Solutions.

    How does the price rise transmit into Indian mills’ balance sheets?

    1. Direct cost pass through: Each $10 a ton rise in coking coal adds $7 to $9 per metric ton to blast furnace steelmaking cost, on the estimate of an executive at a large steel mill.
    2. Volume exposure widens the hit: Coking coal imports are expected to rise by 2 million to 3 million tons in 2026-27, from 64 million tons a year earlier, on the estimate of the commodities consultancy BigMint, so the higher price applies to a larger tonnage.
    3. Freight adds on top of the cargo price: Trade flows have tightened with high demand from India and higher diesel, freight and insurance costs, on the assessment of Moody’s Ratings, raising the delivered cost above the FOB benchmark.
    4. Margin compression is already reported: Executives at three leading steelmakers report squeezed margins with little headroom to raise steel prices.

    Why can Indian mills not pass the cost on to buyers?

    1. Cheap Chinese steel sets the ceiling: Competition from cheap Chinese steel leaves little headroom to raise domestic steel prices even as input costs rise.
    2. Tariffs have not stopped the inflow: Shipments from China have increased despite import tariffs on some grades, so the trade remedy has not restored pricing power.
    3. Demand is strong but price inelastic: Domestic demand is buoyant on the back of infrastructure spending and strong economic growth, and that demand is being served at prices anchored by imports.
    4. Cost push and price ceiling combine: The squeeze operates from both ends at once, on the input side by coking coal and on the output side by import competition.

    What does the squeeze mean for India’s steel capacity expansion?

    1. Capital expenditure at risk: Squeezed margins could impede investment and delay capacity expansion at a time when Indian steelmakers are stepping up spending.
    2. Demand case remains intact: The expansion plans are driven by infrastructure led domestic demand and strong economic growth, so a delay is a supply side failure rather than a demand failure.
    3. Import bill widens: Rising coking coal import volumes alongside rising prices widen the trade exposure of a sector already dependent on a single dominant supplier.

    What do the source geographies of India’s coking coal reveal about its exposure?

    1. Australia, the anchor supplier: Australia ships at least half of India’s coking coal and is expected to continue doing so, which makes an Australian supply interruption an Indian cost event.
    2. China, both a supply and a competition risk: The Shanxi mine accident tightened coking coal supply, and rising Chinese steel shipments simultaneously cap Indian mills’ selling prices.
    3. Russia, a discount that has faded: Russian coal accounted for 24 percent of India’s coking coal imports in recent years, and the discounts on it have diminished over the past two years.
    4. Mozambique and the United States, the diversification margin: Imports from Russia, Mozambique and the United States are all set to rise as India spreads its sourcing.
    5. The Middle East, a freight channel rather than a supply channel: The United States and Iran war raises diesel, freight and insurance costs on seaborne routes rather than removing coal tonnage.

    Challenges to India’s coking coal supply security

    1. Extreme import concentration: A 95 percent import share with at least half from one country leaves no domestic buffer against a single supplier’s disruption. e.g. Australian supply disruptions in 2026 alone lifted the premium hard coking coal benchmark to an average of $236 per metric ton.
    2. Domestic coking coal is largely unusable raw: Indian coking coal carries high ash content and needs washing and blending with imported low ash coal before it can enter a blast furnace. e.g. the Jharia coalfield in Jharkhand holds India’s only significant prime coking coal deposits and still cannot substitute imports without beneficiation.
    3. No pricing power at the selling end: Import competition caps steel prices, so cost shocks are absorbed in the margin rather than recovered from the customer. e.g. Chinese shipments into India rose in 2026 despite import tariffs on some grades.
    4. Freight and insurance are a second, uncorrelated shock: Shipping cost spikes hit the delivered price even when the cargo price is stable. e.g. the United States and Iran war raised diesel, freight and insurance costs on the routes carrying Indian bound coal.
    5. Capacity expansion is the first casualty: Compressed margins delay the capital expenditure cycle rather than current output, so the damage appears years later. e.g. Indian mills stepping up spending to serve infrastructure driven demand now face investment decisions taken under a squeezed margin.
    6. The scrap based alternative route is supply constrained: Electric arc and induction furnace steelmaking avoids coking coal but depends on scrap that India does not generate in sufficient volume. e.g. India continues to import ferrous scrap despite the Steel Scrap Recycling Policy, 2019.

    Conclusion

    India’s steel sector faces a cost shock it cannot pass on, because a 95 percent import dependence on coking coal sits alongside a domestic price ceiling set by cheap Chinese steel. Coking coal is set to remain expensive through the second half of 2026 following the Shanxi supply loss, and import volumes are projected to rise by 2 million to 3 million tons in 2026-27. The immediate risk is not to current production but to the capacity expansion India needs to meet infrastructure led demand. Reducing the exposure requires domestic beneficiation capacity and a wider supplier base, neither of which can be built within a single price cycle.

    Steel Sector in India

    1. Global standing: India is the world’s largest crude steel producer after China and the world’s largest producer of direct reduced iron, also called sponge iron.
    2. Two production routes: The blast furnace and basic oxygen furnace route depends on coking coal and iron ore, and the electric arc furnace, induction furnace and direct reduced iron route depends on scrap, natural gas or non coking coal.
    3. Policy target: The National Steel Policy, 2017 targets 300 million tonnes of crude steel capacity and per capita finished steel consumption of 158 kg by 2030-31.
    4. Structural dependence: India holds large thermal coal reserves but very limited prime coking coal, so the raw material constraint is qualitative rather than quantitative.
    5. Trade position: India moved to being a net importer of finished steel in recent years, which is why import competition now shapes domestic pricing.

    Government Initiatives for the Steel Sector

    1. Production Linked Incentive Scheme for Specialty Steel: Approved in 2021 to incentivise domestic manufacture of value added grades such as coated steel, high strength steel and electrical steel that India otherwise imports.
    2. Mission Purvodaya: Launched in 2020 to build an integrated steel hub in eastern India, drawing on the iron ore and coal belt of Odisha, Jharkhand, West Bengal, Chhattisgarh and Andhra Pradesh.
    3. Steel Scrap Recycling Policy, 2019: Sets up a framework of registered scrapping centres to raise domestic scrap availability and reduce reliance on imported scrap and on coking coal based production.
    4. Domestically Manufactured Iron and Steel Products Policy: Provides preference to domestically manufactured iron and steel in government procurement, to anchor demand for local mills.
    5. Steel Import Monitoring System: Requires advance registration of steel imports so that the government has near real time visibility of import volumes, grades and prices.
    6. Mission Coking Coal: A Ministry of Coal initiative to raise domestic raw coking coal production and washing capacity so that the import share falls over time.
    7. Green Steel Taxonomy: Notified in 2024 to define and star rate low emission steel, creating a domestic standard ahead of carbon border measures in export markets.

    Key Facts about Coking Coal and Indian Steel

    1. Jharia coalfield: Located in Jharkhand, it holds India’s only significant reserves of prime coking coal and has been affected by long running underground mine fires.
    2. Ash content problem: Indian coking coal typically carries ash levels well above the imported grades, which is why it must be washed and blended rather than used directly.
    3. Coke, not coal, enters the furnace: Coking coal is converted to metallurgical coke in coke ovens before charging into the blast furnace.
    4. Administering ministry: The steel sector is administered by the Ministry of Steel and coal by the Ministry of Coal, which is why coking coal policy sits across two ministries.
    5. Non coking coal use: The sponge iron route uses non coking coal, which India produces domestically in large volumes, and is the reason India leads the world in direct reduced iron.

    “[2020, GS1, 15 marks] Account for the present location of iron and steel industries away from the source of raw material, by giving examples.”

  • RBI moves to define revolving credit for the first time and bar non-banks from offering it

    Why in the News

    The Reserve Bank of India (RBI) has proposed the first ever regulatory definitions of a term loan and revolving credit, and any facility failing the term loan test would become revolving credit that non-banking financial companies can no longer offer. Revolving credit is the instrument that carried formal finance into rural India, where income is seasonal and expenses run months ahead of receipts. The regulator is now weighing that inclusion gain against the risk of debt recycling through digital credit lines.

    What is revolving credit?

    1. About: Revolving credit comes with a pre approved credit limit against which a borrower can draw, repay and reuse without applying afresh each time.
    2. Contrast with a term loan: A normal term loan is sanctioned once and repaid in fixed instalments, and the limit is not restored after repayment.
    3. Function for the borrower: It works as a financial buffer, letting households, farmers and small entrepreneurs manage short term cash needs, emergencies and income fluctuations.
    4. Function for the lender: It provides recurring income streams, better utilisation of existing credit infrastructure and higher returns on assets through repeated usage.

    Why does rural India need revolving rather than term credit?

    1. Weight in the economy: Rural India contributes 46 to 50 percent of gross domestic product, and its income is largely seasonal.
    2. The cash flow mismatch: Farmers incur expenses on seeds, fertilisers, labour and irrigation months ahead of the income stream, and structural rigidity in the formal credit framework does not match that timing.
    3. What revolving credit does: It bridges the gap by supplying liquidity as and when it is required rather than in a single sanctioned tranche.
    4. Protective function: It acts as a shield against financial shocks and against informal loan sharks.
    5. The instruments it produced: The Kisan Credit Card (KCC), overdraft facilities, self help group credit lines, microfinance linked loans and, increasingly, digital credit products.
    6. Beyond the farm: Rural micro enterprises depend on flexible working capital, and the self help group and bank linkage programme supported by NABARD has created one of the world’s largest community based credit ecosystems.

    What has the Kisan Credit Card delivered?

    1. Introduction: The KCC scheme was introduced in 1998-99 as the principal form of revolving credit in rural areas.
    2. Widening scope: It expanded beyond crop cultivation to allied activities such as dairy, fisheries and animal husbandry.
    3. Current spread: More than 7.72 crore KCCs are active nationwide.
    4. Who holds them: The majority of beneficiaries are small and marginal farmers.
    5. Broader effect: The share of rural households accessing institutional credit channels such as the KCC has risen significantly.

    How have non-banking financial companies become the main channel?

    1. Why they entered: Small ticket unsecured revolving loans carry higher interest rates on higher risk, so the untapped rural market offered both volume and yield.
    2. Product spread: Non-banking financial companies (NBFCs) expanded revolving credit through consumer credit lines, digital loans, merchant finance, working capital loans to micro, small and medium enterprises, and fintech partnerships.
    3. Last mile role: They became a pillar of last mile credit delivery in rural and semi urban areas where banks face high transaction costs, lack of collateral and information asymmetry.
    4. Scale: More than 9,000 registered NBFCs operate in India, the vast majority in the Base Layer, with overall outstanding credit of Rs 58.61 lakh crore by mid-2026.
    5. Composition of the rural footprint: It is driven by microfinance institutions, gold loan companies, vehicle financiers, and lenders to micro, small and medium enterprises and small ticket retail borrowers.
    6. The gap in it: Agriculture remains a relatively small component of overall NBFC lending.

    What does the microfinance data show?

    1. Portfolio outstanding now: The portfolio outstanding of the microfinance sector, comprising NBFC microfinance institutions and small finance banks, stood at Rs 2.77 lakh crore as at March-end 2026.
    2. The two preceding years: It was Rs 3.35 lakh crore a year earlier and Rs 3.78 lakh crore as at March-end 2024.
    3. Rate of contraction: Total microfinance portfolio outstanding fell by about 17 percent year on year to Rs 2.77 lakh crore by March 2026, per the SIDBI-Equifax report.
    4. Geographic concentration: The top five States, Bihar, Uttar Pradesh, Tamil Nadu, West Bengal and Karnataka, account for 57 percent of total portfolio outstanding.
    5. What the numbers indicate: A two year contraction of over a quarter in the portfolio, concentrated in five States, signals asset quality stress rather than a policy induced slowdown.

    What is the RBI proposing to change?

    1. First ever definitions: The RBI is proposing an amendment that defines term loan and revolving credit for the first time.
    2. The term loan test: A term loan may be disbursed in one or more tranches, but repayment must follow a fixed schedule.
    3. The reuse bar: Once repaid, the credit limit cannot be restored or reused.
    4. The residual category: Any facility that does not meet this definition will be treated as revolving credit.
    5. The operative restriction: Revolving credit, so defined, is what NBFCs can no longer offer.

    Why is the RBI concerned?

    1. Evergreening: The regulator has repeatedly flagged the rapid growth of unsecured retail credit, particularly through fintech and NBFC partnerships offering high risk products as revolving credit.
    2. Masked indebtedness: It remains sceptical of forms of revolving credit where repayment patterns conceal the true level of household indebtedness.
    3. Ease outpacing discipline: Technology has made borrowing easier and faster than financial discipline, and multiple borrowings through various applications with weak due diligence have elevated risk.
    4. Underwriting by algorithm: Some digital platforms relied on algorithms and alternative data without sufficient assessment of repayment capacity.
    5. Purpose of the borrowing: Unlike farm or business revolving credit, many digital credit lines financed consumption rather than income generation.
    6. Official assessment: The latest Economic Survey acknowledged the critical role of NBFCs in inclusion while warning that unchecked expansion can weaken household balance sheets.

    Can the restriction be tightened without pushing borrowers back to informal lenders?

    1. The regulator’s mandate: The RBI must tread a delicate balance between financial inclusion and financial stability, and both claims are legitimate.
    2. The case against a blanket bar: A blanket restriction may be counterproductive, since the microfinance space has historically been underserved and lending is already muted on asset quality pressures and limited funding access.
    3. The instruments at stake: The KCC and similar instruments are essential for growth, while unchecked and easy accessibility through digital platforms and consumer finance channels creates fresh vulnerability.
    4. The real policy problem: The challenge is to identify credit that helps in income generation and separate it from credit that finances consumption, since the two carry different repayment logic.
    5. The failure mode: Excessive regulatory tightening may push borrowers back towards informal lenders, defeating the very purpose of financial inclusion.

    Challenges to Revolving Credit in Rural India

    1. Debt recycling: A revolving limit lets a borrower repay one obligation by drawing on another without the stress becoming visible. e.g. a household clearing one digital credit line by drawing on a second application in the same month.
    2. Multi lending and over indebtedness: Several lenders extending limits to the same household produce a repayment burden none of them has measured. e.g. the microfinance portfolio contracting by about 17 percent year on year to Rs 2.77 lakh crore by March 2026.
    3. Geographic concentration of risk: A localised shock hits a disproportionate share of the sector’s book. e.g. Bihar, Uttar Pradesh, Tamil Nadu, West Bengal and Karnataka holding 57 percent of microfinance portfolio outstanding.
    4. Consumption financing: Credit that funds consumption creates no repayment capacity of its own. e.g. digital credit lines used for durables and lifestyle spending rather than for working capital.
    5. Weak underwriting: Alternative data and algorithmic scoring substitute for an assessment of cash flow. e.g. platforms sanctioning limits without verifying seasonal farm income.
    6. Exclusion of tenant cultivators: Revolving farm credit is tied to land records, so the actual cultivator is often ineligible. e.g. oral lessees who cannot produce title to obtain a Kisan Credit Card.
    7. Delinquency and capital cost: Unchecked expansion raises delinquencies and capital requirements together, so profitability depends entirely on risk controls. e.g. small finance banks tightening disbursement after the microfinance portfolio fell from Rs 3.78 lakh crore in March 2024.

    Conclusion

    Revolving credit solved a timing problem that term lending could not, which is why the Kisan Credit Card, self help group credit lines and NBFC credit lines became the core of rural financial inclusion. The RBI is now proposing the first regulatory definitions of a term loan and revolving credit, with the effect that non-banks would be barred from the residual revolving category. The stated concern is evergreening and masked household indebtedness through fintech linked digital credit rather than farm or enterprise credit. The measure is at the proposal stage, and its success will be judged by whether the definitional line separates income generating credit from consumption credit, since a blanket restriction would return underserved borrowers to informal lenders.

    “[2014, GS3, 12.5 marks] “In the villages itself no form of credit organization will be suitable except the cooperative society.”-All India Rural Credit Survey. Discuss this statement in the background of agricultural finance in India. What constraints and challenges do financial institutions supplying agricultural finance face? How can technology be used to better reach and serve rural clients?”

  • Transmission Constraints Emerge as the Binding Limit on India’s Renewable Expansion

    Why in the News

    Insufficient transmission lines have emerged as a major obstacle to India’s renewable energy expansion, with many solar projects being curtailed during daylight hours, a rating agency assessment released on 19 August 2026 found. The constraint has shifted the binding limit on India’s energy transition from how fast capacity can be built to how much of it the grid can actually carry, and new project bidding has collapsed in response.

    What is curtailment of renewable power?

    1. Forced reduction of output: Curtailment occurs when a power generator is forced to reduce or stop producing electricity because of oversupply and grid congestion, even though the plant is capable of generating.
    2. Why solar is hit hardest: Solar output peaks in the middle of the day, when several projects on the same corridor feed in simultaneously and demand is not correspondingly high, so the surplus cannot be evacuated.
    3. What it costs the generator: A curtailed unit is generation permanently lost, since sunlight cannot be stored without additional storage capacity, and the fixed cost of the asset continues to accrue against a smaller output.
    4. Scale of the problem: Around 37% of renewable energy capacity at substations affected by curtailment in the northern, western and southern regions operates under short term access arrangements, and this capacity faces 30% to 50% curtailment during the day.

    What is Temporary General Network Access?

    1. Short term use of spare grid capacity: Temporary General Network Access (T-GNA) is a short term arrangement that allows a renewable energy project to use available capacity on the inter-State transmission system, typically for periods ranging from a single time block to about 11 months.
    2. Why it is precarious: T-GNA gives no firm entitlement to evacuate power, so projects operating under it are particularly vulnerable to curtailment, which raises their operational costs and, on prolonged use, reduces the supplier’s revenues.

    What is the inter-State transmission system?

    1. The national transmission backbone: The inter-State transmission system is the network of high voltage lines and substations that carries power across State boundaries, planned centrally and operated as a single national grid, on which access rights are allotted separately from generation approvals.

    What is a Power Purchase Agreement?

    1. The contract that makes a project bankable: A Power Purchase Agreement (PPA) is the long term contract under which a distribution company or intermediary agrees to buy a defined quantity of power from a generator at an agreed tariff, and without a signed PPA a project has no assured revenue stream against which lenders will disburse.

    What is firm and dispatchable renewable energy?

    1. Renewable power with an assured supply obligation: Firm and dispatchable renewable energy (FDRE) is renewable generation contracted with an obligation to supply a specified quantum during specified hours, achieved by combining solar, wind and storage, so that the buyer receives a guaranteed profile rather than whatever the weather delivers.

    What is round the clock renewable power?

    1. Renewable supply across all 24 hours: Round the clock (RTC) power is a contracting structure in which the developer commits to supply renewable energy across every hour of the day at a specified availability, again by combining complementary sources with storage.

    How severe is the curtailment, region by region?

    1. The affected regions: Curtailment at substations has been recorded in the northern, western and southern regions, the three regions carrying the bulk of India’s solar and wind capacity.
    2. Share on temporary access: Around 37% of renewable capacity at affected substations across these three regions operates under T-GNA.
    3. The daily loss: Capacity operating under T-GNA faces 30% to 50% curtailment during daylight hours.
    4. Western region: About 55% of the affected capacity in western India was under T-GNA, and peak curtailment reached 8,617 MW as of 6 August 2026.
    5. Northern region: The corresponding peak curtailment figure for the northern region was 5,573 MW.
    6. What the concentration means: The western region, which hosts the largest solar and wind clusters, is also the region most dependent on temporary access, so the two vulnerabilities compound rather than offset.

    Why has new capacity bidding collapsed even as construction continues?

    1. Construction pipeline remains large: More than 150 GW of renewable projects were under construction as of 30 June 2026.
    2. Awards have fallen sharply: After 40.6 GW was awarded in 2024-25, awards fell to 14.7 GW in 2025-26 and stood at only 4.7 GW through 10 August 2026.
    3. Contracts awarded but not signed: Between 40 GW and 45 GW of capacity with bids already awarded remained without signed PPAs as of April 2026.
    4. Delays in firming PPAs: Delays in converting awarded bids into signed PPAs are identified as an impediment independent of the transmission constraint.
    5. Land acquisition: Land acquisition for both generation sites and transmission corridors continues to stall projects.
    6. Distribution company finances: The financial position of distribution companies limits their willingness to sign long term purchase obligations at all, since a new PPA adds a fixed payment liability to a stressed balance sheet.
    7. The bidding mix is changing: New bidding is shifting toward firm and dispatchable renewable energy and round the clock power, which require storage and therefore carry a higher tariff than plain solar.

    Is the binding constraint on India’s energy transition generation capacity or grid capacity?

    1. The generation side is not the problem: More than 150 GW is under construction and renewable energy including large hydro is projected to account for more than 35% of electricity generation by 2029-30, against 22% in 2024-25.
    2. The evacuation side is: Capacity is being commissioned faster than transmission corridors are being built, which is why up to half of the output of projects on temporary access is being discarded during the hours it is generated.
    3. The market has already priced the constraint: New awards fell from 40.6 GW to 4.7 GW in eighteen months, which is the developer response to a corridor that cannot carry what is already built.
    4. Storage is the second missing input: Timely execution of intra-State and inter-State transmission infrastructure, along with greater storage capacity, is identified as critical to sustaining renewable additions, because a line that is congested at noon is idle at night.
    5. Why this reframes the target: A target expressed in installed capacity measures what has been built, while a target expressed in share of generation measures what actually reaches consumers, and curtailment is precisely the gap between the two.

    How is transmission and renewable infrastructure financed in India?

    Source: Backgrounder, Infrastructure Financing.docx

    1. Why bank lending failed: Commercial banks funded 25 to 30 year infrastructure assets with one to three year deposits, and this asset liability mismatch produced stressed assets crossing Rs 10 lakh crore in Indian banking by 2017.
    2. National Bank for Financing Infrastructure and Development: Established in 2021 under a dedicated Act of Parliament as India’s first dedicated infrastructure development finance institution, providing non recourse long term financing with 20 to 30 year tenors that match infrastructure asset life.
    3. Its scale: As of December 2025 it had sanctioned approximately Rs 3.03 lakh crore and disbursed approximately Rs 1.09 lakh crore.
    4. Partial Credit Enhancement: It partially guarantees bonds issued by infrastructure companies and special purpose vehicles, upgrading their credit rating from BBB to AA or AAA so that insurance companies and pension funds can participate, with the first such facility sanctioned in February 2026.
    5. Sector specific development finance institutions: REC and PFC finance power generation, transmission and distribution by raising long term bonds and lending to State electricity boards and private power companies.
    6. POWERGRID InvIT: The first Infrastructure Investment Trust in the power sector, set up in 2020, with proceeds channelled into new and under construction transmission projects.
    7. How an InvIT recycles capital: The sponsor transfers only the right to collect revenues for a defined concession period and receives upfront capital which it reinvests in new projects, while ownership is never transferred and the asset reverts at the end of the concession.
    8. The SEBI safeguard: SEBI requires a minimum of 80% of InvIT assets to be in completed operational projects, which protects investors from construction risk, and InvITs may raise debt up to 49% of asset value.
    9. Infrastructure Risk Guarantee Fund: Announced in the 2026-27 Budget, it provides partial guarantees to lenders financing infrastructure projects, covering a portion of the loss on default so that lenders extend credit where they previously refused, while the partial cover preserves due diligence incentives.
    10. Sovereign green bonds: Issued by the Government of India since 2022-23 with proceeds ring fenced for renewable energy, clean transport and sustainable water management, establishing a sovereign benchmark for long term green paper.
    11. The recycling logic: The architecture is designed so that the government builds, the asset stabilises and generates revenue, the asset is monetised through an InvIT, and the capital returns to fund the next tranche of the National Infrastructure Pipeline without a fresh budget allocation each cycle.
    12. Monetisation targets: The National Monetisation Pipeline 2.0, announced in February 2026, targets Rs 16.72 lakh crore including private sector investment of Rs 5.8 lakh crore over 2025-26 to 2029-30, nearly three times the first pipeline’s target.

    Challenges to India’s Renewable Energy Expansion

    1. Transmission build lags generation build: A solar park can be commissioned in about a year while a high voltage corridor takes several years, so the two cannot be commissioned in step. e.g. peak curtailment in western India reached 8,617 MW as of 6 August 2026 on capacity that was already generating.
    2. Temporary access gives no firm evacuation right: Projects on T-GNA can be curtailed at the system operator’s discretion, which makes their revenue unpredictable and their debt harder to service. e.g. around 37% of affected capacity across three regions runs on T-GNA and faces 30% to 50% daytime curtailment.
    3. Storage capacity is inadequate to absorb the midday surplus: Without batteries or pumped hydro the same corridor is congested at noon and underused at night. e.g. the shift in new bidding toward firm and dispatchable and round the clock contracts is itself an admission that plain solar without storage no longer clears.
    4. Distribution company finances limit offtake: Loss making distribution utilities avoid signing new long term purchase obligations irrespective of tariff. e.g. 40 GW to 45 GW of awarded capacity remained without signed PPAs as of April 2026.
    5. Right of way and land acquisition for transmission corridors: Transmission lines cross many districts and require sustained land and forest clearances along the whole route. e.g. land acquisition is named alongside transmission constraints as an independent impediment to project completion.
    6. Geographic concentration of resource: Solar and wind resources are concentrated in a few States while demand centres lie elsewhere, so the transition is dependent on long distance evacuation. e.g. the western and northern regions together account for the two largest curtailment figures recorded.
    7. Tariff pressure from cheap early bids: Projects awarded at very low tariffs in earlier competitive rounds have thin margins that curtailment erases entirely. e.g. the collapse of awards from 40.6 GW in 2024-25 to 4.7 GW through August 2026 shows developers withdrawing rather than bidding lower.
    8. Grid stability with high variable renewable share: A grid carrying more than 35% renewable generation needs inertia, frequency response and balancing reserves that thermal plants currently supply. e.g. must run thermal capacity has to be retained and paid for even as it operates at low plant load factors.
    9. Module and cell supply chain dependence: Domestic content requirements raise capital costs while imported modules expose projects to trade policy shocks. e.g. changes in duty on imported solar cells and modules have repeatedly reset project economics after bids were submitted.
    10. Delayed payments to generators: Payment delays by distribution utilities strain developer working capital independently of curtailment. e.g. the late payment surcharge rules had to be framed specifically to enforce a payment discipline that contracts alone did not achieve.

    Conclusion

    India’s renewable programme has moved past the point where generation capacity is the constraint, and the evidence for that is a 150 GW construction pipeline coexisting with up to 50% daytime curtailment on capacity that is already running. The market has responded not by building more but by bidding less, with awards falling from 40.6 GW to 4.7 GW in eighteen months, and by shifting toward firm and dispatchable contracts that price the constraint into the tariff. Whether renewable energy reaches more than 35% of generation by 2029-30 now depends on the execution of intra-State and inter-State transmission lines and on storage capacity, not on the pace of solar commissioning.

    “[2022, GS3, 15 marks] Do you think India will meet 50 percent of its energy needs from renewable energy by 2030 ? Justify your answer. How will the shift of subsidies from fossil fuels to renewables help achieve the above objective? Explain.”

  • SEBI’s Closing Auction Session: Better Price Discovery, and the First Manipulation Case

    Why in the News

    The Closing Auction Session (CAS), introduced by the Securities and Exchange Board of India (SEBI) on 3 August 2026 to replace the average based method of fixing stock market closing prices, has raised mutual fund participation from 5% to 7% earlier to 25%. Within ten days of launch the regulator imposed a Rs 3.7 crore penalty on two entities for manipulating the same window, which exposes the trade off at the centre of the reform, that concentrating price discovery into a single transparent auction also concentrates the target for manipulation.

    How does the Closing Auction Session work?

    1. A fixed auction window: CAS is an official 20 minute auction held between 3:15 p.m. and 3:35 p.m., during which the exchange collects buy and sell orders from participants instead of executing continuous trades.
    2. A blind auction: Participants cannot see the full order book during the window, which prevents an order placed at the last instant from being priced against a visible book.
    3. Matching at the equilibrium price: At the end of the window all orders are matched at a single equilibrium price, defined as the price at which the maximum number of shares can be traded.
    4. Deferred execution: In contrast to continuous trading, where bids and offers match instantly, an auction can only result in a trade after the exchange ends it, which allows more time for supply and demand to find a new equilibrium.

    What is the Volume Weighted Average Price?

    1. An average of executed trades: The Volume Weighted Average Price (VWAP) is the average price of trades executed over a defined period, weighted by the quantity traded at each price, and it was the basis on which exchanges earlier fixed the closing price from the last 30 minutes of continuous trading.
    2. Why an average is vulnerable: Because it averages trades that have already happened, a few large trades placed at the end of the period can pull the average disproportionately without any change in the underlying supply and demand.

    What is order imbalance?

    1. The gap between buy and sell interest: Order imbalance is the gap between cumulative buy quantity and cumulative sell quantity at different price levels within the auction, and a low imbalance indicates that the discovered price represents a more stable consensus.

    What is tracking error?

    1. Deviation of a fund from its benchmark: Tracking error is the extent to which an index fund's or exchange traded fund's return diverges from the return of the index it is meant to replicate, and it widens when the closing price used to value the fund differs from the price at which the index is computed.

    Why did SEBI replace the VWAP based closing price?

    1. The closing price is a reference, not a number: The closing price of a security is used for portfolio valuation, index computation, derivative settlement, mutual fund net asset value calculation and institutional investment decisions, so it must reflect the expectations of both buyers and sellers.
    2. The old method's weakness: Exchanges determined the closing price largely through the VWAP of trades in the last 30 minutes of continuous trading, and a few large last minute trades could disproportionately affect the final average, creating the possibility of price distortion.
    3. When distortion was worst: The vulnerability was concentrated on large event days, specifically index rebalancing days and derivative expiry days, when order flow is heavily one sided.
    4. The measured evidence: For NIFTY 50 stocks, volatility in the last half hour exceeded the volatility observed between 09:15 and 14:30 by 1.8 times on MSCI index rebalancing days and by 1.5 times on FTSE index rebalancing days in 2024.
    5. The conceptual shift: CAS converts closing price determination from passive averaging of past trades into dynamic demand and supply discovery, and reduces price noise while improving the information efficiency of Indian equity markets.
    6. The regulatory gain: The SEBI Chairperson stated that CAS provides the regulator with greater capability to identify manipulation than the earlier VWAP based system.

    What does the spread of closing auctions across major exchanges establish about the model?

    1. The peer group: With this move the National Stock Exchange and the Bombay Stock Exchange have joined NASDAQ, the New York Stock Exchange, the London Stock Exchange, Euronext, the Hong Kong Stock Exchange, Singapore Exchange, the Tokyo Stock Exchange and the Australian Securities Exchange, all of which fix closing prices by auction.
    2. United States, NASDAQ Closing Cross: A single price auction at the close that publishes indicative closing prices and order imbalance information in the minutes before the cross, so that participants can supply liquidity against a visible imbalance.
    3. United States, New York Stock Exchange Closing Auction: Designated Market Makers publish imbalance information before the close and are obliged to offset residual imbalance, which places an accountable intermediary inside the auction.
    4. United Kingdom, London Stock Exchange: A closing auction with a randomised end to the uncrossing phase, so that no participant can time an order to the exact final instant.
    5. Hong Kong Stock Exchange: Reintroduced its Closing Auction Session in 2016 with price limits and a random closing period, after an earlier version launched in 2008 was suspended in 2009 following manipulation concerns, which is the closest precedent for India's present position.
    6. Japan, Tokyo Stock Exchange: Uses the Itayose single price call auction method to determine the closing price, matching all eligible orders at one price.
    7. Australian Securities Exchange: Runs a single price closing auction with a randomised start, again to defeat last instant order timing.
    8. What the set demonstrates: Closing auctions were initially adopted to achieve efficient price discovery and have since become a liquidity event in their own right, with the volume share of closing auctions increasing across both Europe and America.

    Who gains from a cleaner closing price?

    1. Passive funds first: India's passive funds, which have expanded from a relatively small base to a multi crore asset base driven by exchange traded funds and index funds, are likely to be the biggest beneficiaries initially, because they depend on accurate closing prices to replicate benchmarks.
    2. Mutual funds have already moved: The SEBI Chairperson stated that mutual funds' participation rate in CAS has risen sharply to 25%, compared with 5% to 7% earlier.
    3. Large orders execute without leaking information: The auction allows large investors to participate anonymously and execute at a commonly discovered price, which reduces information leakage and the price impact that usually accompanies large orders placed close to market closing time.
    4. Foreign institutional capital: Foreign investors managing billions of dollars prefer markets with predictable closing mechanisms, so aligning India with international practice can improve institutional inflows into Indian equities.
    5. Better execution technology: Execution algorithms that analyse order imbalance, liquidity patterns and equilibrium prices push Indian markets toward institutional quality trading practices.
    6. A stronger valuation benchmark: A well functioning CAS makes the closing price a stronger valuation benchmark by incorporating the bid spread, order imbalance, liquidity and investor conviction, rather than only executed trade prices.

    Does concentrating price discovery into one window reduce manipulation or relocate it?

    1. The case that it reduces manipulation: Matching at a single equilibrium price with a blind order book removes the ability of a few late trades to pull an average, and the regulator gains a complete record of every order placed and cancelled inside the window.
    2. The case that it relocates manipulation: Concentrating the entire closing price determination into 20 minutes creates one high value target, and the first enforcement action arrived within ten days of launch.
    3. The evidence for the second reading: The alleged manipulation involved placing very large orders and cancelling them within seconds, a technique that works precisely because the auction aggregates orders before matching them.
    4. What actually changed: The manipulation did not disappear, it became visible, since the regulator could identify the pattern from the order and cancellation record in a way the VWAP system did not permit.
    5. The unresolved part: Detection after the event does not prevent the closing price on that day from being distorted, and the closing price then flows into index computation, net asset values and derivative settlement before the enforcement order is issued.

    What did SEBI's first CAS manipulation order find?

    1. The penalty and the entities: SEBI imposed a penalty of Rs 3.7 crore on Copthall Mauritius Investment Ltd. and Mansi Share and Stock Broking Private Ltd. and barred them from the market for allegedly manipulating trades during the CAS.
    2. The date and the context: The alleged violations occurred on 13 August 2026, the day on which weekly derivative contracts linked to the Sensex expired.
    3. The reference price rule: SEBI fixes the maximum permitted deviation from the reference price at 3% within the CAS.
    4. The buy side conduct: One entity placed large buy orders constituting at least 85% of all buy orders made in the minutes before the Sensex closed, all of them above the 3% deviation mark, and simultaneously cancelled its latest buy order.
    5. The sell side conduct: The other entity placed large sell orders across eight Sensex constituents totalling about 12.65 lakh shares, of which more than seven lakh shares were placed 2.5% below the reference price and 4.6 lakh shares below 1%, and cancelled them within four to five seconds.
    6. The alleged effect: The manipulation led to three price spikes.
    7. The alleged motive: SEBI's preliminary findings state that placing and then cancelling these large buy and sell orders allowed the noticees to avoid losses or wrongfully profit from positions in derivative trades that would otherwise have expired worthless.
    8. The stage of proceedings: The noticees have been given 21 days to respond to the interim order.
    9. The regulator's stated posture: The SEBI Chairperson stated that anyone manipulating the CAS would face strict and immediate action, that CAS exists for transparency, and that those who think they can manipulate CAS in order to discredit it are mistaken.

    Challenges to the Closing Auction Session

    1. Cash and derivative markets close at different times: Cash market closing prices are set through CAS while equity derivatives continue trading beyond the window, creating a temporary gap between spot and futures prices. e.g. on Sensex weekly expiry days the mismatch is largest, and it was on the 13 August 2026 expiry that the first manipulation case arose.
    2. Arbitrage strategies lose their reference: Arbitrage traders who price the spot against the future cannot do so cleanly when one leg is settled by auction and the other by continuous trading. e.g. cash and carry arbitrage positions built on a VWAP close now carry an unhedged residual through the auction window.
    3. Algorithmic and institutional models were built on the old mechanism: Institutional traders and algorithmic firms must rebuild strategies that assumed a VWAP based close, factoring in auction imbalances, indicative prices and real time order flow. e.g. SEBI itself stated that the problem is a lack of understanding, because algorithms and other players historically based their models on the old mechanism.
    4. Index levels jumped across the auction in early sessions: Participants raised concerns over the sharp difference between index levels recorded before CAS and after the auction on the first two trading days, though SEBI ruled out foul play. e.g. this gap appeared immediately after the 3 August 2026 launch, before participation had stabilised.
    5. Illiquid securities cannot generate a representative price: The efficiency of CAS depends on sufficient order participation, and in less liquid securities limited buy and sell orders may produce a closing price that does not represent broader market sentiment. e.g. this is why the mechanism was launched only for stocks with futures and options contracts rather than the whole cash market.
    6. Retail investors do not recognise the new closing price: For many retail investors the closing price has traditionally meant the last traded price or a VWAP figure, so intraday traders and derivative participants may find the auction price confusing. e.g. an investor comparing a broker application's last traded price with the official closing price on the same screen sees two different numbers.
    7. Order cancellation is a manipulation channel the auction structure enables: Large orders placed to shift the indicative equilibrium and then withdrawn before matching are the classic auction manipulation technique. e.g. the 13 August 2026 case involved sell orders cancelled within four to five seconds of being placed.
    8. The 3% deviation band can itself be gamed: A cap on deviation from the reference price becomes a target that orders cluster against rather than a limit they respect. e.g. all of the buy orders in the first enforcement case were placed above the 3% deviation mark.
    9. Derivative expiry concentration magnifies the stake: Restricting the number of weekly expiries per exchange concentrated open interest into fewer expiry days, so the value riding on a single closing price rose. e.g. the alleged manipulation was targeted at derivative positions that would otherwise have expired worthless.
    10. Enforcement is after the fact: An interim order issued days later cannot restore a distorted closing price that has already flowed into net asset values, index levels and settlement. e.g. the Rs 3.7 crore order came with a 21 day response window, long after the 13 August settlement had been completed.

    Conclusion

    CAS replaces a passively computed average with an actively discovered equilibrium, and on the evidence of the first three weeks it is working as intended, with mutual fund participation quadrupling and the regulator able to reconstruct manipulation from the order record in a way the VWAP system did not allow. What the first enforcement case shows is that the reform relocates manipulation rather than eliminating it, moving it from a diffuse 30 minute average into a concentrated 20 minute auction where it is more consequential but also more visible. The correct test of the mechanism is not the volatility of its first fortnight but measurable improvement in market quality, specifically lower tracking errors, reduced closing price variance, narrower spreads, improved liquidity and stronger price efficiency.

    India's Securities Market

    1. What it is: The securities market is the set of institutions through which companies and governments raise capital by issuing securities and through which those securities are subsequently traded, valued and settled.
    2. Two segments: The primary market handles fresh issuance through public offers and private placements, while the secondary market handles trading of already issued securities on exchanges.
    3. Regulatory architecture: SEBI regulates the securities market, the RBI regulates the government securities and money markets, and the Insurance Regulatory and Development Authority of India and the Pension Fund Regulatory and Development Authority regulate the institutional investors that participate in it.
    4. Two national exchanges: The Bombay Stock Exchange, established in 1875, is Asia's oldest stock exchange, and the National Stock Exchange, which began operations in 1994, introduced screen based nationwide electronic trading.
    5. Global standing in derivatives: India accounts for a very large share of equity option contracts traded globally, and the National Stock Exchange has ranked as the world's largest derivatives exchange by number of contracts traded for several consecutive years.
    6. Dematerialised holding: Securities are held in electronic form through two depositories, the National Securities Depository Limited and the Central Depository Services Limited, established under the Depositories Act, 1996.
    7. Settlement cycle: India moved to a T plus 1 settlement cycle for all listed equities by January 2023, becoming one of the first large markets to do so, and has since introduced an optional same day settlement segment.
    8. Rising retail and passive participation: Growth in demat account openings, systematic investment plans and index linked products has made passive funds a structurally important source of demand, which is why the accuracy of the closing price now carries system wide consequences.
    9. Investor protection funds: Exchanges maintain Investor Protection Funds and SEBI operates an Investor Protection and Education Fund funded partly from disgorged amounts and penalties.

    Laws and Rules Governing India's Securities Market

    1. Securities and Exchange Board of India Act, 1992: Constitutes SEBI as a statutory body and gives it the powers to protect investor interests, promote market development and regulate the securities market.
    2. Section 11 confers the general power to regulate, and Section 11B the power to issue directions, including the interim orders under which market access is barred.
    3. Section 15HA provides the penalty for fraudulent and unfair trade practices, and Section 15J sets the factors for determining the quantum of penalty.
    4. Securities Contracts (Regulation) Act, 1956: Governs the recognition and regulation of stock exchanges, the definition of securities and the listing of securities.
    5. Securities Contracts (Regulation) Rules, 1957: Prescribe minimum public shareholding requirements and the conditions for continued listing.
    6. Depositories Act, 1996: Provides for the dematerialisation of securities and the constitution and regulation of depositories and depository participants.
    7. Companies Act, 2013: Governs public issues, prospectus disclosure, related party transactions and corporate governance obligations of listed companies.
    8. SEBI (Prohibition of Fraudulent and Unfair Trade Practices relating to Securities Market) Regulations, 2003: Prohibit manipulative and deceptive devices, including placing orders with no intention of executing them, which is the provision under which order and cancellation manipulation is pursued.
    9. SEBI (Prohibition of Insider Trading) Regulations, 2015: Prohibit trading on unpublished price sensitive information and require listed companies to maintain structured digital databases of such information.
    10. SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015: Fix continuous disclosure, board composition and related party approval requirements for listed entities.
    11. SEBI (Substantial Acquisition of Shares and Takeovers) Regulations, 2011: Govern open offers on acquisition of control or of specified shareholding thresholds.
    12. SEBI (Intermediaries) Regulations, 2008: Govern registration and conduct of brokers, merchant bankers and other intermediaries, under which broking entities are proceeded against.
    13. Prevention of Money Laundering Act, 2002: Applies know your customer and beneficial ownership obligations to market intermediaries and foreign portfolio investors.

    Key Facts about SEBI and India's Exchanges

    1. CAS was launched on 3 August 2026, initially for stocks having futures and options contracts, and runs from 3:15 p.m. to 3:35 p.m.
    2. SEBI fixes the maximum deviation from the reference price within the CAS at 3%.
    3. Mutual fund participation in CAS rose to 25% from 5% to 7% earlier within the first weeks of operation.
    4. SEBI released its study on retail and non retail participation in the derivatives market for 2025-26 on 20 August 2026.
    5. An earlier SEBI study flagged that over 90% of trades by retail investors in the derivatives segment resulted in losses.
    6. SEBI's measures to curb excessive derivatives volatility include increasing lot sizes and limiting the number of expiries per exchange, while the Union Budget raised the Securities Transaction Tax on the segment.
    7. SEBI was established as a non statutory body in April 1988 and given statutory status by the SEBI Act, 1992 with effect from 30 January 1992.
    8. SEBI's headquarters is at the Bandra Kurla Complex in Mumbai, with regional offices in New Delhi, Kolkata, Chennai and Ahmedabad.
    9. Appeals against SEBI orders lie to the Securities Appellate Tribunal, and from there to the Supreme Court on a question of law.
    10. National Investors' Day, marking investor awareness, and the Investor Protection and Education Fund are both instruments through which SEBI discharges its investor protection mandate.

    Back2Basics: Securities and Exchange Board of India

    1. Governing Act: Constituted under the Securities and Exchange Board of India Act, 1992.
    2. Year established: Set up as an administrative body in April 1988 and given statutory powers with effect from 30 January 1992.
    3. Administrative ministry: Functions under the Department of Economic Affairs, Ministry of Finance.
    4. Threefold mandate: To protect the interests of investors in securities, to promote the development of the securities market, and to regulate the securities market.
    5. Composition: A Chairperson, two members from among officials of the Union Ministries dealing with finance and law, one member from the RBI, and five other members appointed by the Union Government, of whom at least three are whole time members.
    6. Appointment: The Chairperson and members are appointed by the Union Government, and the Chairperson can be removed only on the grounds specified in the Act.
    7. Jurisdiction: Covers stock exchanges, depositories, brokers, merchant bankers, mutual funds, foreign portfolio investors, credit rating agencies, listed companies and investment advisers.
    8. Quasi legislative power: Frames regulations binding on all market participants without requiring prior parliamentary approval, subject to laying before Parliament.
    9. Quasi judicial power: Conducts inquiries, passes interim and final orders, imposes monetary penalties, bars entities from the market and orders disgorgement of unlawful gains.
    10. Quasi executive power: Investigates, conducts search and seizure with the approval of a designated court, and calls for records from any person associated with the securities market.
    11. Appellate route: Its orders are appealable to the Securities Appellate Tribunal, a statutory tribunal constituted under the same Act.

    Challenges in India's Securities Market

    1. Retail losses concentrated in derivatives: Retail participation has grown fastest in the segment where retail outcomes are worst. e.g. a SEBI study found that over 90% of trades by retail investors in the futures and options segment led to losses.
    2. Speed advantage of co-located algorithmic trading: Firms with exchange co-located servers execute in fractions of the time available to other participants, raising questions of unequal access. e.g. the National Stock Exchange co-location matter, in which SEBI passed disgorgement orders, ran for years before resolution.
    3. Manipulation in small and mid cap counters: Thin float and low liquidity make price manipulation cheap in smaller listed companies. e.g. SEBI's action against Dhenu Buildcon Infra Ltd. for allegedly creating a Rs 1,000 crore unsecured loan through 46 transactions over eight days and converting part of it into equity through preferential allotment, leaving six entities with 99.70% of outstanding equity.
    4. Unregistered investment advice through digital channels: Social media based tip providers operate outside the registered investment adviser framework. e.g. SEBI has repeatedly issued orders against finfluencers running paid advisory channels without registration.
    5. Enforcement timelines outrun market timelines: Investigation, interim order, final order and appeal can take years while the price effect is realised in minutes. e.g. an interim order carrying a 21 day response window is issued after the affected settlement is complete.
    6. Corporate governance failures at listed entities: Related party transactions and fund diversion continue to surface after the fact. e.g. the Central Bureau of Investigation registered a case against Gensol Engineering Limited, Gensol EV Lease Limited and their promoters for allegedly causing a loss of Rs 672.74 crore to the Indian Renewable Energy Development Agency Limited.
    7. Concentration risk from passive investing: As index funds grow, index inclusion and rebalancing decisions move prices independently of company fundamentals. e.g. volatility on MSCI and FTSE rebalancing days for NIFTY 50 stocks ran 1.8 times and 1.5 times the normal session volatility in 2024.
    8. Cross border and offshore derivative exposure: Positions built through offshore derivative instruments and foreign entities complicate beneficial ownership tracing. e.g. the first CAS manipulation order named a Mauritius domiciled investment entity.
    9. Investor grievance redress capacity: The volume of complaints from a rapidly widening retail base outpaces the capacity of the online dispute resolution and grievance mechanisms. e.g. the SCORES platform and the Online Dispute Resolution portal were both introduced in response to backlogs rather than in anticipation of them.

    Way Forward

    1. Align the derivative and cash market close: Extend an auction based or reference linked close to the derivatives segment, so that the spot and futures legs settle against a consistent price and the expiry day arbitrage gap closes.
    2. Publish indicative equilibrium prices and imbalance during the window: Adopt the NASDAQ and New York Stock Exchange practice of disseminating indicative prices and order imbalance, so that participants can supply liquidity against a visible imbalance rather than trade blind.
    3. Randomise the auction close: Follow the London Stock Exchange and Australian Securities Exchange practice of a randomised uncrossing moment, so that an order timed to the final instant cannot determine the outcome.
    4. Penalise order and cancellation patterns directly: Frame an explicit order to trade ratio and cancellation threshold for the auction window, so that placing large orders with no intention of execution is actionable on the pattern itself rather than only on proof of derivative gain.
    5. Phase the extension to illiquid securities: Extend CAS beyond futures and options eligible stocks only where a minimum order participation threshold is demonstrated, so that thin counters are not given a closing price that no consensus supports.
    6. Run a structured transition programme for algorithmic participants: Publish auction microstructure documentation and offer a simulated environment, since the regulator has itself identified model dependence on the old mechanism as the core adjustment problem.
    7. Invest in retail investor communication: Explain through exchange and broker interfaces why the last traded price and the official closing price now differ, so that the change does not itself become a source of mistrust.
    8. Publish a market quality dashboard: Report tracking error, closing price variance, bid ask spreads and auction liquidity on a rolling basis, so that CAS is evaluated on the metrics the reform was designed to improve rather than on daily volatility.

    Matching Previous Year Question

    “[2025] Consider the following statements: I. India accounts for a very large portion of all equity option contracts traded globally, thus exhibiting a great boom. II. India's stock market has grown rapidly in the recent past, even overtaking Hong Kong's at some point in time. III. There is no regulatory body either to warn small investors about the risks of options trading or to act on unregistered financial advisors in this regard. Which of the statements given above are correct? (a) I and II only (b) II and III only (c) I and III only (d) I, II and III Answer: (a)”

  • Early Closure of the FCNR(B) Swap Window and the Cost of Absorbing Dollars

    Why in the News

    The Reserve Bank of India (RBI) advanced the closure of the Foreign Currency Non-Resident (Bank), or FCNR(B), swap window by a month, and the RBI Governor defended the move on 19 August 2026 as a calibrated and data driven response rather than a reversal. The decision exposes a shift in the objective of India's forex defence, from maximising dollar inflows to managing the rising domestic cost of absorbing them.

    What is the FCNR(B) deposit and what was the swap window?

    1. The deposit: FCNR(B) deposits allow non residents to hold money in an Indian bank in the foreign currency itself, so the depositor faces no rupee exchange risk on the principal.
    2. Permanent availability: These deposits are available at all times and are a standing category of non resident deposit, not a temporary scheme.
    3. The temporary swap facility: In June 2026 the RBI opened a temporary window allowing banks to swap these foreign currency deposits with the central bank, with the RBI bearing the full currency risk on them.
    4. What the window did: By taking the currency risk off bank balance sheets, the facility made it commercially attractive for banks to mobilise fresh foreign currency deposits and convert them into rupee resources.

    What are External Commercial Borrowings?

    1. Foreign currency loans to Indian entities: External Commercial Borrowings (ECBs) are commercial loans raised by eligible Indian resident entities from recognised non resident lenders, governed by RBI limits on amount, maturity, end use and all in cost.

    What are Overseas Foreign Currency Borrowings?

    1. Bank borrowing abroad: Overseas Foreign Currency Borrowings (OFCBs) are foreign currency funds raised abroad by Indian banks themselves, typically through their overseas branches, and brought back to support domestic foreign currency lending and liquidity.

    What is sterilisation?

    1. Neutralising the rupee side of a dollar purchase: Sterilisation is the operation by which a central bank absorbs the rupee liquidity it releases when it buys foreign currency, using instruments such as open market sales of government securities or cash reserve ratio changes, so that the forex purchase does not add to domestic money supply.
    2. Why it has a cost: The central bank earns a low return on the dollars it holds and pays a higher domestic rate on the instruments used to absorb the rupees, and that spread is the sterilisation cost, which rises the longer the position is held.

    Why did the RBI advance the closure of the window?

    1. Inflows exceeded expectations: Inflows had been stronger than the RBI and most market participants had expected, so the quantity objective of the facility was met ahead of schedule.
    2. Diminishing marginal utility of each dollar: The Governor stated that there is a diminishing marginal utility of every dollar that is swapped, because each additional dollar adds less to an already adequate reserve and inflow position.
    3. Rising marginal cost: At the same time there is an increasing marginal cost, because the rupee liquidity created has to be sterilised for a longer period, and that cost accumulates with the size and duration of the position.
    4. A decision from strength: The closure was taken from a position of strength rather than under stress, and forms part of the RBI's wider external sector management.
    5. Not a reversal: The Governor stated that it would not be correct to call it a U turn, that it is rather a calibration, and that the move demonstrated the central bank's ability to remain flexible and data dependent amid rapidly changing conditions.

    Does an early closure amount to a policy reversal or a calibration?

    1. The criticism: Remarks made after the Monetary Policy Committee meeting of 5 August 2026 were read by the market as ruling out an early closure, so bringing the date forward within two weeks was read as a reversal of stated guidance.
    2. The defence on wording: The Governor pointed to the use of the words as of now in the statement that there was no proposal to advance the last date, which conditioned the guidance on the information available at that moment.
    3. The defence on process: The RBI had also said it would keep stakeholders informed of any decision, which on the central bank's reading indicated that an early closure had not been ruled out.
    4. The underlying trade off: Data dependence requires a central bank to change course when the data changes, while forward guidance requires it to keep its word, and the two objectives pull against each other whenever conditions move faster than the guidance horizon.
    5. Why the distinction matters commercially: Banks and depositors price fixed tenure instruments against the announced window, so an advanced closure imposes a real cost on those who planned against the earlier date, regardless of how the change is described.

    What do the three schemes mean for India's balance of payments?

    1. The combined expectation: The RBI expects the three schemes together, FCNR(B), ECBs and OFCBs, to attract at least $80 billion.
    2. What the number signals: The Governor stated that this reflects the country's strong macroeconomic fundamentals and would further strengthen the balance of payments.
    3. The channel: All three are capital account inflows, so they finance the current account deficit and add to reserves without requiring an improvement in the trade balance itself.
    4. The currency backdrop: The rupee stood at 95.76 to the United States dollar and the Indian basket crude oil price at $92.11 a barrel as of 18 August 2026, which is the pressure the inflows are being mobilised against.
    5. The market backdrop: The Sensex closed at 76,909.68, down 325.78 points or 0.42%, and the Nifty at 24,078.30, down 76.60 points or 0.32%, on the day the remarks were made.

    What did the Governor prescribe for Indian banks to reach global scale?

    1. The stated ambition: The Prime Minister has set out the objective of having an Indian bank among the world's top five, and the Governor stated that Indian banks have the scale and ability to achieve a larger global footprint and are on the right path.
    2. Governance and institutional strength: Banks must continue improving governance and institutional strength and build a sound risk management culture.
    3. Customer trust: They must sustain good customer service and retain customer trust, which the Governor listed as a distinct requirement rather than a consequence of the others.
    4. Technology and cost: They need to invest continuously in technology, reduce costs, improve efficiency and expand their reach.
    5. People: They must continuously train and equip their staff to adapt nimbly to a growing economy and a fast evolving financial system.
    6. On mergers: Asked whether bank mergers would hasten the process, the Governor said what is needed is a good, strong banking system with healthy competition, that the government merged a few banks earlier, and that whether there is a case for further mergers is a call the government can take.

    Challenges to the RBI's Forex Inflow Schemes and External Sector Management

    1. Sterilisation cost accumulates on the central bank's own balance sheet: Every dollar absorbed requires rupee liquidity to be withdrawn at a domestic rate higher than the return earned on reserves, and the spread is a direct cost. e.g. sustained open market sales of government securities to absorb liquidity push up domestic yields at the same time as the government is running a large borrowing programme.
    2. The inflows are debt creating, not equity: ECBs, OFCBs and FCNR(B) deposits all create a repayment obligation in foreign currency, unlike foreign direct investment, so they improve the balance of payments today at the cost of a redemption cliff later. e.g. the $34 billion FCNR(B) mobilisation of 2013 produced a concentrated redemption in late 2016 that the RBI had to manage through a pre announced forward book.
    3. Currency risk transfers to the central bank, not away from the system: Under the swap facility the RBI bears the full currency risk, so a sharp rupee depreciation converts a banking sector exposure into a public balance sheet loss. e.g. with the rupee at 95.76 to the dollar, every further rupee of depreciation raises the rupee cost of returning the same dollar principal.
    4. Guidance reversals raise the risk premium on future schemes: Advancing a closure date after indicating no such proposal makes participants discount the next announced window. e.g. banks that had built deposit mobilisation campaigns around the original closure date carry stranded acquisition costs.
    5. Inflows can reverse faster than they arrived: Non resident deposits and portfolio linked borrowings respond to interest rate differentials and can exit within a quarter. e.g. foreign portfolio investors withdrew a record of about Rs 1.66 lakh crore from Indian markets in 2025.
    6. Oil dominates the current account the schemes are financing: India imports the bulk of its crude requirement, so a rise in the crude price widens the deficit faster than capital inflows can be mobilised. e.g. the Indian basket price at $92.11 a barrel on 18 August 2026 sits well above the levels around which recent import bills were budgeted.
    7. Tariff shocks can undercut the export side simultaneously: Trade restrictions imposed by a major partner reduce export earnings at the same time as capital inflows are being courted. e.g. the imposition of tariffs of up to 50% on Indian goods by the United States in August 2025 hit textiles and auto components, which are labour intensive export earners.
    8. Concentration of banking scale can weaken competition: Pursuing a top five global bank through further mergers reduces the number of competing lenders, which the Governor himself flagged by insisting on healthy competition. e.g. the amalgamation of ten public sector banks into four with effect from 1 April 2020 cut the number of public sector banks from 27 in 2017 to 12.

    Conclusion

    The early closure of the FCNR(B) swap window is best read not as a change of view on the rupee but as the point at which the RBI judged the marginal cost of absorbing another dollar to exceed its marginal benefit. With the three schemes expected to deliver at least $80 billion, the quantity objective is largely met, and the residual task is managing the sterilisation cost of the liquidity already created. The open question is whether the communication cost of advancing an announced date will raise the price of the next facility the RBI needs to open.

    India's External Sector: Capital Flows and the Rupee

    Source: Backgrounder, External Sector_ FDI,FPI, Weakening Rupee against Dollar.docx

    1. Foreign Direct Investment: Foreign Direct Investment (FDI) is investment made to acquire a lasting interest and significant control over an enterprise, defined as 10% or more of the post issue paid up equity capital of a listed company, or any stake in an unlisted company.
    2. Foreign Portfolio Investment: Foreign Portfolio Investment (FPI) is investment in financial assets for short term financial gain without control, defined as less than 10% of the paid up equity capital of a listed company.
    3. Divergent stability: FDI is long term, strategic and often tied to physical assets such as factories, while FPI is highly liquid, passive and prone to sudden reversals during global stress.
    4. Split regulation: FDI is regulated primarily by the RBI under the Foreign Exchange Management Act and by the Department for Promotion of Industry and Internal Trade through the Consolidated FDI Policy, while FPI is regulated by the Securities and Exchange Board of India under the SEBI (Foreign Portfolio Investors) Regulations, 2019.
    5. FDI entry routes: Investment enters either through the automatic route, requiring no prior approval and only reporting to the RBI, or the government approval route requiring prior clearance, for example food retail and defence above 74%.
    6. Prohibited sectors: FDI is barred in atomic energy, gambling and lotteries, chit funds and Nidhi companies, real estate other than townships and special economic zones, and tobacco.
    7. Recent flow stress: Net FDI turned negative for three consecutive months even as gross inflows remained strong, driven by higher outward direct investment by Indian companies and high repatriation by foreign companies operating in India.
    8. The harvest phase: Many investments made in the early 2000s have reached a stage where funds prioritise profit booking over expansion, so repatriation rises without any deterioration in the investment climate.
    9. Portfolio outflow scale: FPIs recorded a record outflow of about Rs 1.66 lakh crore, roughly $18.9 billion, in 2025, the largest since FPI investment began in India.
    10. Financialisation of FDI: A growing share of FDI is routed through Alternative Investment Funds rather than direct industrial equity, so headline FDI increasingly behaves like volatile portfolio money and delivers less technology transfer.
    11. Round tripping: A large share of inflows still originates from Mauritius and Singapore, which points to tax arbitrage rather than fresh industrial capital and inflates the headline number relative to its productive impact.

    Statutory and Regulatory Framework Governing India's External Sector

    1. Foreign Exchange Management Act, 1999: Replaced the earlier control based regime and governs all current and capital account transactions, with the RBI as the administering authority.
    2. Section 6 of the Foreign Exchange Management Act, 1999: Empowers the RBI, in consultation with the Union Government, to specify the permissible classes of capital account transactions and the limits on them, which is the source of the FCNR(B), ECB and OFCB frameworks.
    3. Reserve Bank of India Act, 1934: Vests the RBI with the management of the country's foreign exchange reserves and with the issue and regulation of currency.
    4. Foreign Exchange Management (Deposit) Regulations, 2016: Govern non resident deposit accounts, including the FCNR(B), Non-Resident External and Non-Resident Ordinary categories.
    5. External Commercial Borrowings Master Direction of the RBI: Fixes eligible borrowers, recognised lenders, minimum average maturity, all in cost ceilings and permitted end uses for ECBs.
    6. Prevention of Money Laundering Act, 2002: Applies reporting and beneficial ownership requirements to cross border financial flows through banks and market intermediaries.
    7. SEBI (Foreign Portfolio Investors) Regulations, 2019: Govern registration, categorisation and investment limits for foreign portfolio investors in Indian securities.
    8. Consolidated FDI Policy of the Department for Promotion of Industry and Internal Trade: Codifies sectoral caps, entry routes and conditionalities for foreign direct investment.

    Government and Central Bank Initiatives to Manage External Sector Stress

    Source: Backgrounder, External Sector_ FDI,FPI, Weakening Rupee against Dollar.docx

    1. Open market operation purchases of government securities: A programme of about Rs 2 trillion in open market purchases, conducted in tranches, was used to offset the domestic cash crunch caused by portfolio investors pulling out of Indian equities.
    2. Dollar rupee swap and forex sales: A $10 billion dollar rupee swap auction, alongside direct sale of dollars, was used to prevent the rupee from crashing through a threshold level during a period of dollar shortage.
    3. Trade diversification through free trade agreements: The India European Union Free Trade Agreement and the India United Kingdom Comprehensive Economic and Trade Agreement are being used to reduce dependence on a single dominant export market.
    4. National Single Window System: Integrates 32 central departments and more than 25 States into a unified clearance portal to reduce approval delays that deter foreign investors.
    5. Jan Vishwas amendments: Decriminalisation of a large set of minor industry offences and removal of imprisonment for technical violations, aimed at reducing the perception of regulatory risk.
    6. New labour codes: Nationwide implementation of the four labour codes to simplify compliance on wages and social security for foreign investors.
    7. Beneficial ownership screening: Stricter beneficial ownership checks and portal upgrades to ensure incoming FDI brings permanent technology rather than tax arbitrage capital.

    Key Facts about India's Foreign Exchange Framework

    1. The rupee stood at 95.76 to the United States dollar and the Indian basket crude oil price at $92.11 a barrel as of 18 August 2026.
    2. The three schemes of FCNR(B), ECBs and OFCBs are together expected to attract at least $80 billion.
    3. India follows a managed float exchange rate regime, in which the rupee's external value is market determined and the RBI intervenes only to curb excessive volatility, not to defend a level.
    4. India's exchange rate arrangement is classified by the International Monetary Fund on the basis of observed intervention behaviour, not on any officially announced peg.
    5. The Foreign Exchange Management Act, 1999 replaced the Foreign Exchange Regulation Act, 1973, converting foreign exchange violations from criminal offences into civil contraventions.
    6. Non resident Indians hold rupee denominated deposits through Non-Resident External and Non-Resident Ordinary accounts, and foreign currency denominated deposits through FCNR(B) accounts.
    7. Portfolio investors withdrew a record of about Rs 1.66 lakh crore, roughly $18.9 billion, from Indian markets in 2025.
    8. Foreign direct investment is defined at a threshold of 10% or more of the post issue paid up equity capital of a listed company, the internationally standard cut off separating direct from portfolio investment.

    Back2Basics: India's Foreign Exchange Reserves

    1. What they are: Foreign exchange reserves are external assets held and controlled by the RBI that are readily available to finance a balance of payments gap and to intervene in the currency market.
    2. Four components: Reserves comprise foreign currency assets, gold, Special Drawing Rights held with the International Monetary Fund, and the Reserve Tranche Position with the Fund.
    3. Foreign currency assets: The largest component, held mainly in sovereign bonds, treasury bills and deposits with other central banks and the Bank for International Settlements, denominated chiefly in United States dollars, euros, pounds sterling and yen.
    4. Gold: Held partly domestically and partly in custody abroad, and revalued periodically, so movements in the gold price alone change the headline reserve number without any transaction.
    5. Special Drawing Rights: An international reserve asset created by the International Monetary Fund, allocated to members in proportion to their quota, whose value is set from a basket of five currencies comprising the United States dollar, euro, Chinese renminbi, Japanese yen and pound sterling.
    6. Reserve Tranche Position: The portion of a member's quota subscription paid in reserve assets, which the member may draw on from the Fund without conditions.
    7. Adequacy measures: Reserve adequacy is judged by the number of months of imports covered, by the ratio of reserves to short term external debt on residual maturity, and by the ratio of reserves to broad money.
    8. The forward book: The RBI's net forward position in the currency market is disclosed separately, because outstanding forward sales are a claim on future reserves that the headline number does not capture.
    9. Custody and disclosure: Reserve data are published weekly in the RBI's Weekly Statistical Supplement, with the currency composition disclosed with a lag in the half yearly report on foreign exchange reserves.

    Challenges in India's External Sector

    Source: Backgrounder, External Sector_ FDI,FPI, Weakening Rupee against Dollar.docx

    1. Protectionism and policy shocks abroad: Tariff escalation and trade fragmentation divert capital toward friend shoring hubs or back to home markets. e.g. tariffs rising to 50% on key Indian goods in August 2025 directly hit export oriented manufacturing in textiles and automobiles.
    2. Competing destinations with faster approvals: Rival economies offer quicker clearances and wider free trade agreement networks for near shoring investors. e.g. Vietnam, Indonesia and Mexico have absorbed a large share of the China plus one relocation that India was positioned to attract.
    3. Policy unpredictability: Frequent regulatory pivots undermine investor trust in the stability of the rules. e.g. retrospective taxation disputes and changes in e-commerce marketplace rules in 2025 sustained a perception of high regulatory risk.
    4. Cumbersome approvals: Land and environmental clearances remain a bottleneck for greenfield investment. e.g. roughly 200 FDI proposals faced delays as of August 2025 because of screening requirements, and legacy cases such as the abandoned $12 billion POSCO project continue to define the land risk narrative.
    5. Skill mismatch in frontier sectors: Only about 5% of India's workforce is formally skilled, with acute shortages in wafer fabrication and artificial intelligence roles. e.g. semiconductor and electric vehicle investors face a talent gap that constrains how much high value FDI India can absorb.
    6. Weak contract enforcement: Long drawn arbitration and a backlog in commercial courts raise the perceived exit risk for investors. e.g. multi year tax arbitration such as the Cairn Energy dispute is repeatedly cited as evidence of an unpredictable legal exit.
    7. Round tripping and financialisation: A large share of inflows originates in low tax jurisdictions and an increasing share is routed through Alternative Investment Funds rather than industrial equity. e.g. persistent concentration of inflows from Mauritius and Singapore points to tax arbitrage rather than fresh productive capital.
    8. Weak external demand: Cooling global orders discourage export oriented investment in labour intensive sectors. e.g. purchasing managers' index readings in April 2025 recorded a sharp cooling in Indian export orders.

    Way Forward

    1. Publish a sterilisation cost disclosure: Report the carrying cost of intervention alongside the reserve number, so that decisions to open or close swap windows can be evaluated against a visible fiscal and balance sheet cost.
    2. Pre announce redemption management for debt creating inflows: Publish the maturity profile of FCNR(B), ECB and OFCB obligations and the forward cover arranged against them, so that a redemption cliff is priced in advance rather than discovered.
    3. Attach conditions and horizons to guidance: State the data conditions under which a stated window date could change at the time the guidance is issued, so that a data driven adjustment is not read as a reversal.
    4. Rebalance toward equity inflows: Reduce the reliance on debt creating flows by removing sectoral entry frictions and completing single window clearances, so that the same balance of payments support carries no repayment obligation.
    5. Diversify export markets through concluded agreements: Operationalise the European Union and United Kingdom trade agreements at the level of standards, rules of origin and customs procedure, so that the current account improves rather than being financed by capital.
    6. Deepen the onshore rupee derivatives market: Widen participation in exchange traded currency futures and the non deliverable forward segment, so that hedging demand is met onshore and the RBI is not the residual bearer of currency risk.
    7. Reduce the oil exposure structurally: Expand strategic petroleum reserve capacity, ethanol blending and electric mobility so that a $90 a barrel oil price does not automatically translate into an external financing requirement.
    8. Strengthen banks before consolidating them: Prioritise governance, risk management culture and technology investment, as the Governor set out, over amalgamation, so that scale is built on institutional strength rather than on balance sheet addition.

    Matching Previous Year Question

    “[2018, GS3, 15 marks] How would the recent phenomena of protectionism and currency manipulations in world trade affect macroeconomic stability of India?”
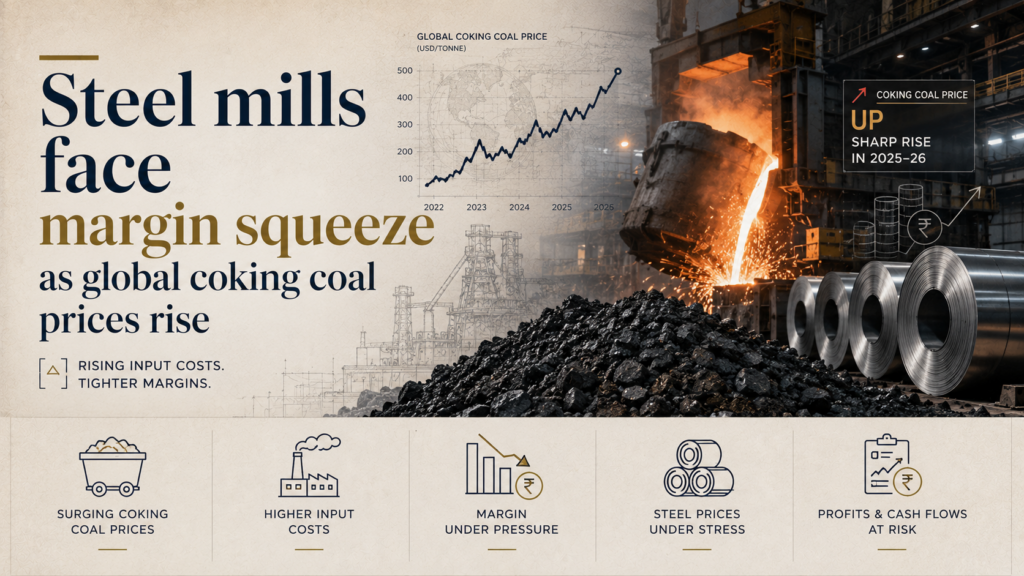
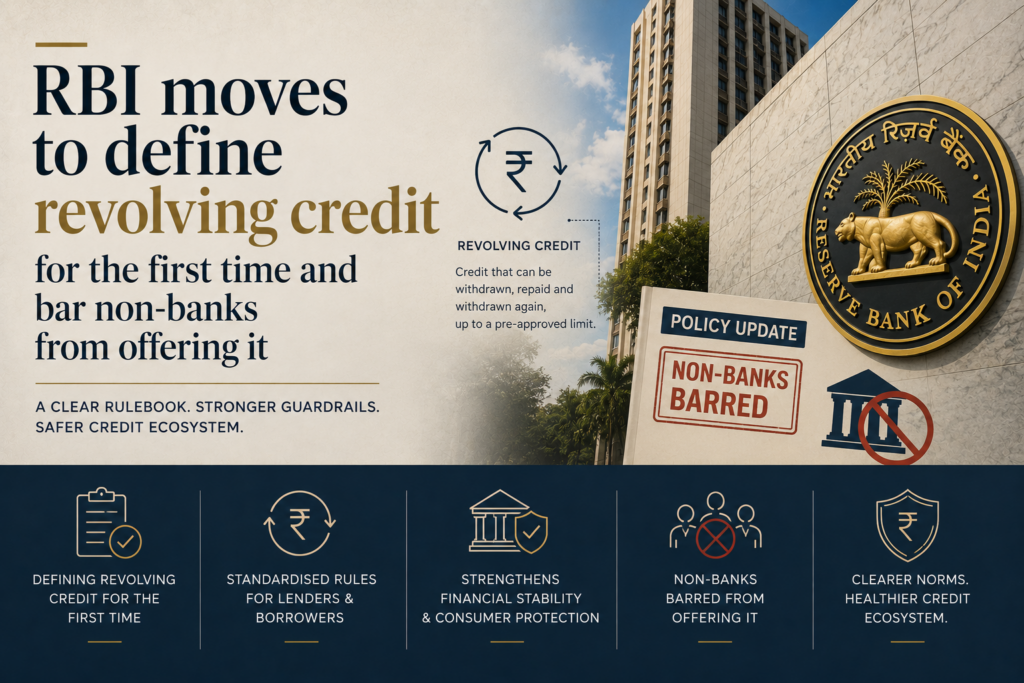
  • RBI’s MPC Minutes Signal a Turn from Easing to Tightening

    Why in the News

    The August 2026 MPC minutes show growing concern over rising inflation. Although the repo rate was kept unchanged at 5.25%, some members see a possible rate hike later in 2026-27 as inflation is projected to peak at 5.9% in Q3.

    MPC: Key Prelims Facts

    • Legal basis: RBI Act, 1934, amended in 2016.
    • Composition: 6 members
      • 3 from RBI
      • 3 external members appointed by the Central Government.
    • Chairperson: RBI Governor.
    • Voting: One vote per member; Governor has a casting vote in case of a tie.
    • Minutes: Published on the 14th day after the meeting.
    • Mandate: Set the policy repo rate to achieve the inflation target.

    August 2026 Policy Review

    • Repo rate: 5.25%, unchanged.
    • Growth forecast: Raised from 6.6% to 6.7%.
    • Inflation forecast: Lowered from 5.1% to 5%.
    • Q3 inflation projection: 5.9%.
    • Inflation is expected to decline after the Q3 peak, supporting the decision to wait rather than tighten immediately.

    Core Inflation

    • Core inflation = CPI inflation excluding food and fuel.
    • It captures relatively persistent, demand-driven price pressures that monetary policy can influence.
    • Core excluding precious metals additionally removes gold and silver, preventing bullion price movements from distorting the underlying inflation signal.

    Second-Round Inflation Effects

    • A first-round shock, such as higher oil prices, can spread through the economy:
    • Higher oil prices → higher input costs → higher production costs → higher prices of goods/services → broader inflation
    • This transmission is called a second-round effect.

    De-Anchoring of Inflation Expectations

    • When households and firms stop believing inflation will return to the 4% target, they may:
    • Expect high inflation → demand higher wages/prices → firms raise prices → inflation becomes self-sustaining
    • This is why MPC members are closely watching expectations and generalisation of price pressures.

    Why a Rate Hike May Be Difficult

    • Supply shocks: Interest rates cannot directly increase oil supply or food production.
    • Transmission lag: Monetary policy affects the economy with a time lag.
    • Food weight: Food shocks can substantially raise headline CPI.
    • Growth trade-off: Higher rates can weaken investment and consumption.
    • Exchange rate: Rate differentials and rupee depreciation can affect imported inflation.
    • Fiscal/administered prices: Taxes, MSP and administered fuel prices lie largely outside MPC control.
    • Changing CPI basket: Changes in CPI weights can affect historical comparisons.

    “[2024, GS3, 10 marks] What are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.”

    [2017] Which of the following statements is/are correct regarding the ‘Monetary Policy Committee (MPC)?
    1. It decides the RBI’s benchmark interest rates.
    2. It is a 12-member body including the Governor of RBI and is reconstituted every year.
    3. It functions under the chairmanship of the Union Finance Minister.
    Select the correct answer using the code given below:

    [A] 1 only

    [B] 1 and 2 only

    [C] 3 only

    [D] 2 and 3 only

  • First talks begin on retailing E10 petrol alongside E20 amid the blending row

    Why in the News

    Early exploratory discussions have begun within the government and the fuel industry on whether E10 petrol can be retailed alongside E20, which is currently the only standard petrol variant sold across the country. The trigger is a policy success that has produced a consumer problem: India reached 20 percent ethanol blending five years ahead of the original deadline, which pushed the entire retail network onto a fuel that most vehicles on the road were never certified for. The question now is whether a national fuel supply chain built for a single base grade can be reopened to two.

    What is the Ethanol Blended Petrol (EBP) Programme?

    1. About: The Ethanol Blended Petrol Programme requires oil marketing companies to blend ethanol into petrol at a mandated percentage before sale, so that a share of transport fuel demand is met from domestically produced ethanol.
    2. Administering ministry: Run by the Ministry of Petroleum and Natural Gas, with the Ministry of Road Transport and Highways on vehicle compatibility and the Department of Food and Public Distribution on feedstock supply.
    3. Policy basis: Formalised under the National Policy on Biofuels, 2018, which sets the indicative blending target and defines permitted feedstocks.
    4. Objectives: Reduce crude oil import dependence, cut foreign exchange outgo, provide an assured market for surplus sugarcane and foodgrain, and lower tailpipe carbon monoxide and hydrocarbon emissions.
    5. Beneficiaries: Sugarcane and maize farmers, sugar mills and distilleries, and vehicle owners through the retail fuel price.
    6. Achievement: India reached 20 percent ethanol blending in petrol in 2025, five years ahead of the original target, and the milestone has been credited with displacing about 310 lakh tonnes of crude and saving roughly Rs 1.9 lakh crore in foreign exchange.

    What is E20 petrol?

    1. Composition: E20 is a blend of 80 percent petrol and 20 percent ethanol by volume.
    2. Current status: It is the only standard petrol variant sold across the country, and a notification of 17 February 2026 requires all States and Union Territories to sell E20 at a minimum Research Octane Number of 95 from 1 April 2026.

    What is E10 petrol?

    1. Composition: E10 is a blend of 90 percent petrol and 10 percent ethanol by volume.
    2. Why it is at issue: Older vehicles, particularly two wheelers, were certified for E10 petrol, and E10 was the base retail grade until the network shifted entirely to E20.

    What are Bharat Stage 6 phase two norms?

    1. Definition: Bharat Stage 6 phase two is the second stage of India’s sixth generation vehicle emission standard, which tightened real driving emission and on board diagnostic requirements for vehicles manufactured from April 2023.
    2. Relevance here: Full E20 material compatibility was mandated under these norms, which is why April 2023 is the dividing line between compliant and non compliant vehicles.

    Components of the Ethanol Blended Petrol Programme, by lifecycle stage

    Component and official instrument (lifecycle stage)Intervention and official numbersPrimary stakeholder
    Permitted feedstock list under the National Policy on Biofuels, 2018 (feedstock and input)Allows ethanol from sugarcane juice, sugar and sugar syrup, B heavy molasses, C heavy molasses, damaged foodgrain, maize and surplus rice; no per unit figure attaches to this componentSugarcane and maize farmers, sugar mills
    Ethanol Interest Subvention Scheme (financing)Interest subvention on loans for setting up new distilleries and expanding existing molasses based and grain based capacity; the release states the subvention period, not a fixed outlay per plantDistilleries and sugar mills
    Pradhan Mantri JI-VAN Yojana (plant or asset build, advanced biofuels)Viability gap funding for second generation ethanol projects using lignocellulosic feedstock such as agricultural residueTechnology developers and oil marketing companies
    Administered ethanol procurement price (production and pricing)Differential ex mill prices fixed by the Cabinet Committee on Economic Affairs for each feedstock route, highest for the sugarcane juice route and lowest for the C heavy molasses routeSugar mills and distilleries
    Long term offtake agreements by oil marketing companies (distribution and evacuation)Assured purchase of tendered ethanol volumes for each ethanol supply year, which runs from November to OctoberOil marketing companies and distilleries
    E20 as the base retail grade (offtake and demand)20 percent blending achieved in 2025, five years ahead of the 2030 target; minimum Research Octane Number of 95 required for E20 sold from 1 April 2026Vehicle owners

    What has triggered the rethink on a lower blend?

    1. The consumer complaint: Opposition to E20 has come from several quarters, with claims of notable reduction in mileage and engine component wear in older vehicles whose engines were not designed for higher ethanol blends.
    2. The government’s position on mileage: The drop in mileage in older vehicles would be 3 to 5 percent at most, and would be outweighed by E20’s benefits as a superior fuel.
    3. The government’s position on engine damage: Claims that E20 could damage engine components have been consistently rejected.
    4. The parliamentary figure: A reduction in fuel economy of 2 to 6 percent depending on vehicle category and vintage has been stated in Parliament.
    5. The absence of choice: Questions have been raised on why motorists are not offered a choice between pure petrol, E10 and E20, and some Opposition leaders have taken up the same point.
    6. The first official break: A co authored opinion article published on 17 August 2026 by the Chief Economic Adviser called for a lower ethanol petrol blend such as E10 to be made available alongside E20. The views were personal, and it is the first instance of a high ranking government official publicly calling for more petrol options.
    7. The stated rationale for restoring E10: Restoring a lower blend at the pumps alongside the option to buy E20 would calm public concern, lower total ethanol use instead of raising it, and protect the existing fleet while the retrofit programme catches up.

    Which vehicles are actually affected?

    1. The compliance line: Petrol vehicles manufactured and sold after April 2023 are considered fully E20 compliant, since this was mandated under Bharat Stage 6 phase two emission norms.
    2. What that leaves out: All vehicles currently being sold are E20 compliant, but most vehicles sold prior to 2023 are not.
    3. The scale of the gap: Of about 310 million petrol vehicles in use, only about 70 million built after April 2023 carry factory certified E20 compatibility.
    4. How long the legacy fleet stays on the road: The permissible life of a petrol vehicle in the National Capital Region is 15 years, which means cars manufactured in 2022 can be in use until 2037 under current norms.
    5. The most exposed category: The discussions were initiated specifically with older vehicles, particularly two wheelers, that were certified for E10 petrol, in mind.

    Why is retailing E10 alongside E20 a logistical problem?

    1. A parallel supply chain: Retailing E10 and E20 simultaneously requires a complex, parallel supply chain stretching from refineries to pumps.
    2. The volume distinction: Two or three premium petrol variants already coexist with the base fuel, and their consumption is minuscule compared with base petrol, so offering small volumes alongside E20 is manageable. Retailing E10 in large volumes is a different problem, since the existing chain has shifted entirely to E20.
    3. Underground storage is the binding constraint: Most retail outlets use single or dual underground tanks, so adding E10 alongside E20 would require replacing them with a dual tank system for petrol at thousands of pumps.
    4. Dispensing equipment: Outlets would additionally need separate dispensers for the base fuel.
    5. The government’s July position: Offering multiple grades of base fuel across the country would create an “enormous logistical challenge”, raise costs and reduce operational efficiencies in India’s complex fuel retail network.
    6. The sunk investment argument: The shift to E20 required massive investments already made, and reverting to a lower blend would not be prudent.
    7. Where the talks stand: The discussions are described as “preliminary” and as “keeping the older vehicles in mind”, are being held on technical and non technical aspects of the fuel retail supply chain, and no concrete conclusions have been arrived at.

    Where does the blending success pull against the consumer?

    1. A target met is not a fleet protected: Reaching 20 percent blending five years early moved the entire retail network onto a fuel that roughly four fifths of the petrol fleet was never certified for.
    2. The choice question has no cheap answer: Restoring choice requires physical infrastructure at thousands of outlets, so the demand for choice and the cost of supplying it move in opposite directions.
    3. Lower blend means lower ethanol demand: Restoring E10 would lower total ethanol use, which cuts against the assured offtake that distilleries and sugar mills invested against.
    4. Retrofit is the alternative to reversal: Protecting the existing fleet through a retrofit programme leaves E20 intact but transfers the cost from the fuel network to the vehicle owner.
    5. The time horizon is fixed by vehicle life: With 2022 vehicles running until 2037, the mismatch persists for over a decade regardless of which route is chosen.

    Challenges to the Ethanol Blended Petrol Programme

    1. Legacy fleet incompatibility: The bulk of vehicles on the road predate the E20 mandate. e.g. of about 310 million petrol vehicles in use, only about 70 million built after April 2023 carry factory certified E20 compatibility.
    2. Fuel economy loss: Ethanol has lower energy density than petrol, so the same volume delivers fewer kilometres. e.g. the government puts the drop at 3 to 5 percent in older vehicles, and a range of 2 to 6 percent by category and vintage has been stated in Parliament.
    3. Water footprint of feedstock: Sugarcane based ethanol carries a heavy irrigation demand in water stressed regions. e.g. sugarcane in Maharashtra’s Marathwada draws heavily on groundwater while occupying a small share of the cropped area.
    4. Food versus fuel diversion: Grain routed to distilleries competes with food and feed use. e.g. surplus rice from the Food Corporation of India and maize have been diverted to ethanol, tightening maize supply for the poultry feed industry.
    5. Fuel quality disputes: Contamination claims undermine public confidence in the blend. e.g. chloride and moisture contamination claims were raised against E20 in 2026 and rejected by state oil marketing companies after pan India testing.
    6. Supply chain rigidity: The retail network has been optimised for a single base grade. e.g. restoring E10 would require dual underground tanks and separate dispensers at thousands of outlets.
    7. Geographic concentration of distillery capacity: Ethanol production clusters in a few States, requiring long haul movement. e.g. Uttar Pradesh, Maharashtra and Karnataka account for the bulk of capacity, so deficit States in the east and north east draw on long distance tanker movement.
    8. Material compatibility in older engines: Ethanol acts on certain elastomers and metals used in pre 2023 fuel systems. e.g. rubber fuel lines and aluminium components in older two wheelers were specified against E10, not E20.

    What do other countries’ dual grade fuel markets show?

    1. Brazil: Mandates a high anhydrous ethanol blend in gasoline, raised to 30 percent in 2025, and sells hydrous ethanol as a separate grade at the same forecourt for its flex fuel fleet. The design feature is that the vehicle fleet was converted to flex fuel first, and the fuel grade followed.
    2. United States: E10 is the de facto base gasoline, with E15 and E85 offered at selected stations rather than universally. The design feature is that higher blends are optional and geographically limited, so no station is forced to carry every grade.
    3. Thailand: Retails gasohol E10, E20 and E85 simultaneously through its state fuel retailer network. The design feature is a differential excise structure that prices higher blends below lower ones, so demand shifts by price rather than by mandate.
    4. Germany: Sells Super E10 alongside a Super E5 protection grade, retained specifically for vehicles not certified for the higher blend. The design feature is the legal obligation on larger stations to keep the lower blend available, which is the arrangement now being examined in India.
    5. France: Retails SP95-E10 alongside SP98, with the lower ethanol grade preserved for older vehicles, and publishes a vehicle compatibility list so owners can check before filling. The design feature is that consumer information was issued as a public compatibility register, not left to manufacturers.

    Conclusion

    India met its 20 percent blending target five years early, and the cost of that speed is a national retail network carrying a single fuel grade that most of the vehicle fleet was never certified for. Discussions on retailing E10 alongside E20 are at a preliminary stage with no conclusions reached, and the binding constraint is physical, being underground tank and dispenser capacity at thousands of outlets rather than ethanol availability. The next development to watch is whether the government converts the current exploratory talks into a formal feasibility study, since the mismatch persists until the pre 2023 fleet ages out around 2037.

  • Why corporate investment has not revived despite tax cuts and cheap credit

    Source: The Hindu, Page 10, Text & Context
    Published: 19 August 2026

    Why in the News

    Corporate investment as a share of Gross Domestic Product (GDP) has fallen to about 9 percent from a peak of 17.3 percent, and has not returned even to the low levels recorded during the Global Financial Crisis. A corporate tax cut from 30 percent to 22 percent and a sustained low interest rate regime failed to reverse the decline, which points to a constraint that cost side policy does not touch.

    What does corporate investment as a share of GDP measure?

    1. Definition: It measures the value of new fixed assets created by companies, such as plant, machinery and buildings, expressed as a proportion of the economy’s total output.
    2. Why the ratio is used: Expressing investment as a share of output strips out inflation and growth in the size of the economy, so a fall in the ratio means investment is growing slower than output.
    3. What it signals: Corporate investment builds the future productive capacity of the economy, so a sustained decline in the ratio caps the growth rate the economy can sustain later.
    4. Data source used here: The trend is drawn from the Database on Indian Economy maintained by the Reserve Bank of India (RBI).

    What are animal spirits?

    1. Definition: Animal spirits, a term used by John Maynard Keynes, refers to the level of confidence with which firms hold their expectations about future profits.
    2. How it acts: High confidence pushes the expected profitability schedule outward and raises investment at every level of cost, and pessimism about the future pulls it inward.

    What is the principle of increasing risk?

    1. Definition: The principle of increasing risk, proposed by Michal Kalecki, holds that the cost of borrowing rises as a firm takes on more loans in proportion to its own funds committed to a project.
    2. Its consequence: The system is rigged against small capitalists even where small and large firms hold the same blueprint of a technology, because access to capital begets more capital.

    What is the Prowess database?

    1. Definition: Prowess is a firm level database of Indian companies compiled from their audited annual accounts, used for panel studies of corporate performance.
    2. Use in this analysis: The study draws a balanced panel of listed manufacturing firms from Prowess to compare profitability and interest costs across firm sizes.

    What is autonomous expenditure?

    1. Definition: Autonomous expenditure is spending that does not depend on the current level of income or profit in the economy, so it can rise when private demand is falling.
    2. Why it matters here: Government expenditure is the principal autonomous component, which is why it can create demand actively rather than merely responding to demand that already exists.

    How has corporate investment moved since 2000?

    1. The take off: Corporate investment took off in 2004, jumping almost four percentage points from 6.5 percent to 10.3 percent of GDP.
    2. The peak: It rose further during the growth years to a peak of 17.3 percent.
    3. The crisis fall: It fell during the Global Financial Crisis, then began a steady revival.
    4. The break point: The revival ran until demonetisation hit the economy in 2016, after which the decline has been continuous.
    5. Where it stands: The share is now about 9 percent, and has not returned even to the low levels recorded during the Global Financial Crisis.

    Why is demonetisation treated differently from the other shocks?

    1. Nature of the shock: The global economic crisis was an external shock beyond India’s control, and demonetisation was a self inflicted shock.
    2. Depth of the fall: The post 2016 decline has taken the share below the crisis era floor, which the external shock itself never did.
    3. Covid is not the explanation: Covid arrived in 2020-21 as another external shock, and the decline in investment had started a few years earlier.
    4. Two channels of damage: Demonetisation pushed the expected profitability schedule inward both because immediate profitability declined and because the credibility of future policy steps became suspect.
    5. The casualty at the margin: The fall was severe enough to push small firms below the cost of credit curve altogether, forcing many out of business, which is what happened to many micro, small and medium enterprises (MSMEs) in this period.

    What three factors determine a firm’s investment decision?

    1. Expected profitability: The profit a firm expects from selling the goods the new factory will produce, assessed over the whole life of the asset.
    2. Confidence in that expectation: The certainty with which the firm can predict those profit rates over the factory’s lifetime, which sets the position of the profitability schedule.
    3. Cost of credit: The price of borrowing, which matters once the planned investment exceeds the firm’s own available funds.
    4. How profitability varies with size: Most industries have economies of scale, so larger equipment, factories and workspaces carry higher profit rates than smaller ones, and expected profitability rises with the size of the investment.
    5. Where that stops: Each firm has an upper limit to how much it can sell, set by its share in the total market, and investment beyond that point leaves part of the factory idle.
    6. Two channels for the interest rate: A firm that does not build can park its funds in an interest bearing asset, so expected profitability must exceed the market interest rate, and a firm that borrows faces a cost of credit that is flat up to its own capital and rises steadily thereafter.

    Why does firm size change what constrains investment?

    1. Small firms: With very low levels of own capital the cost of credit curve starts rising far sooner, and it cuts the upper portion of the profitability curve.
    2. Their binding constraint: Investment by such firms is constrained by the availability of credit, and their interest costs are correspondingly high.
    3. Large firms: Their own capital is high enough that the cost curve cuts the profitability curve on its vertical portion.
    4. Their binding constraint: Such firms are limited by the market rather than by finance, and interest costs are not consequential for them.
    5. The structural implication: The same technology blueprint yields different investment outcomes purely because of the firm’s existing access to capital.

    What does the firm level data show?

    1. The sample: A balanced panel of 1,224 listed manufacturing firms between 2000 and 2024, drawn from the Prowess dataset and grouped into three sizes.
    2. Size definition: Median capital stock is Rs 14.5 crore for small firms, Rs 156.8 crore for medium firms and Rs 1,745.9 crore for large firms, all measured in 2011-12 prices.
    3. The profitability gradient: Smaller firms have lower profitability than larger firms, with the median rate of profit rising across the three size classes.
    4. The interest cost gradient: Smaller firms carry higher interest costs than larger firms, with median interest costs falling as size rises.
    5. What it confirms: The asymmetry predicted by the theory, that small firms are credit constrained and large firms are demand constrained, holds by and large for the Indian manufacturing sector.

    Why did a tax cut and cheap credit fail to revive investment?

    1. The tax cut: The corporate tax rate was cut from 30 percent to 22 percent, alongside a low interest rate regime followed by the Reserve Bank of India.
    2. No effect on small firms: A fall in the interest rate does not revive investment among smaller firms once their expected profitability has collapsed below the cost of credit.
    3. No effect on large firms: A large firm is not constrained by credit in the first place, so cheaper credit has no impact on its investment decision.
    4. The general result: Cost side policy interventions, including tax cuts, do not have much expansionary impact on investment, because neither group’s binding constraint is the cost of funds.
    5. What the failure reveals: Both groups are ultimately held back by expected demand, and cheapening the supply of capital does nothing to create that demand.

    What would shift expected profitability outward?

    1. The required direction: What is needed is to push the profitability curve outward, which raises investment by both small and large firms simultaneously.
    2. The only instrument that does it: This can be achieved only if government expenditure acts as an autonomous stimulus.
    3. The mechanism: Such expenditure creates demand actively, and rising demand pushes the profitability curves outward for firms of every size.
    4. The fiscal implication: It requires giving up on being a fiscal hawk, since the stimulus has to be sustained rather than symbolic.
    5. The political signal being read: The same conclusion is drawn from the youth protesting on the streets asking for gainful employment.

    Challenges to reviving corporate investment in India

    1. Weak capacity utilisation: Firms do not add capacity while existing plants run below their rated output. e.g. manufacturing capacity utilisation tracked by the Reserve Bank of India has hovered around the mid seventies in percentage terms for extended periods.
    2. Credit constraint on small firms: Formal lenders price small borrowers out or lend against collateral they lack. e.g. the credit gap for micro, small and medium enterprises runs into lakhs of crores against their assessed requirement.
    3. Policy uncertainty: Abrupt changes damage the confidence component of investment decisions independently of the direct cost. e.g. the retrospective amendment to tax cross border share transfers after the Vodafone ruling deterred investors until it was withdrawn in 2021.
    4. Weak household demand: Consumption growth caps the sales any firm can plan for. e.g. the collapse in employment generation under the rural employment guarantee programme in April to July 2026 cut rural purchasing power directly.
    5. Land and clearance delays: Project timelines stretch well beyond the investment appraisal horizon. e.g. large steel and refinery projects in Odisha and Maharashtra have taken over a decade from announcement to commissioning.
    6. Legacy stressed assets: Bank and corporate balance sheets recovering from earlier defaults limit fresh risk appetite. e.g. the twin balance sheet problem of the mid 2010s suppressed both credit supply and corporate borrowing for years.
    7. Import competition in inputs: Cheaper imported inputs and finished goods reduce the return on domestic capacity creation. e.g. domestic solar module manufacturers competed against imported cells until duties and incentives were introduced.

    Conclusion

    Corporate investment has fallen to about 9 percent of GDP from a peak of 17.3 percent and remains below its Global Financial Crisis floor, with the decline dating from 2016 rather than from Covid. A corporate tax cut from 30 percent to 22 percent and a low interest rate regime failed because neither addresses the binding constraint, since small firms are held back by credit access and large firms by the size of the market. Pushing expected profitability outward requires government expenditure acting as an autonomous stimulus, which means abandoning fiscal hawkishness rather than repeating cost side concessions.

    Foundational Context: What is Capital Formation?

    1. About: Capital formation is the addition to the stock of physical assets in an economy in a given period, measured in the national accounts as Gross Fixed Capital Formation (GFCF).
    2. Rationale: It exists as a distinct measure because current output can either be consumed or used to create productive capacity, and only the second raises future output.
    3. Named typology, by the investing sector:
    4. Public sector capital formation: Investment by the Central and State governments and by public sector enterprises, largely in infrastructure.
    5. Private corporate sector capital formation: Investment by registered companies in plant, machinery and structures, which is the measure this item tracks.
    6. Household sector capital formation: Investment by households and unincorporated enterprises, dominated by residential construction.
    7. Related measure: The investment rate is Gross Fixed Capital Formation expressed as a share of Gross Domestic Product, and the incremental capital output ratio measures how much investment is needed to produce one additional unit of output.

    Key Concerns Regarding Capital Formation in India

    1. Private investment has not replaced public investment: Central capital expenditure has risen sharply while private corporate investment has stagnated, so the recovery rests on one leg.
    2. Household investment is concentrated in real estate: A large share of household capital formation is residential construction, which adds less to productive capacity than plant and equipment.
    3. Financing depth for small firms: The corporate bond market is accessible only to highly rated large issuers, leaving small firms dependent on bank credit at high spreads.
    4. Crowding out concern: Sustained government borrowing to fund the stimulus can raise interest rates and reduce private investment, which is the standard counter argument to an expenditure led revival.
    5. Measurement lag: Private corporate investment is estimated with a significant lag and revised substantially, which delays the recognition of a turning point in the cycle.

    Statutory Framework Governing Fiscal Policy and Public Investment

    1. Article 112: Requires the Annual Financial Statement of estimated receipts and expenditure to be laid before Parliament for every financial year.
    2. Article 266: Establishes the Consolidated Fund of India and the Public Account, from which expenditure may be made only under authority of law.
    3. Article 292: Empowers the Union to borrow upon the security of the Consolidated Fund of India within limits fixed by Parliament.
    4. Article 293: Governs State borrowing and requires the consent of the Union where a State is indebted to it.
    5. Article 280: Provides for the Finance Commission, whose recommendations determine the vertical and horizontal sharing of Union taxes.
    6. Fiscal Responsibility and Budget Management Act, 2003: Sets statutory fiscal targets and requires the government to lay fiscal policy statements before Parliament.
    7. Section 4: Prescribes the fiscal deficit and debt targets and the grounds on which they may be deviated from.
    8. Section 7: Requires the Finance Minister to review and report on the trends in receipts and expenditure to Parliament.

    Laws and Rules Governing Corporate Finance and Small Firm Credit

    1. Companies Act, 2013: Governs incorporation, capital raising, disclosure and audit obligations of companies, which is the source of the accounts used in firm level databases.
    2. Micro, Small and Medium Enterprises Development Act, 2006: Defines the three enterprise categories and provides for delayed payment remedies for small suppliers.
    3. Section 15 and Section 16: Require payment to a micro or small enterprise within a specified period and provide for compound interest on delay.
    4. Insolvency and Bankruptcy Code, 2016: Provides a time bound resolution process for corporate debtors, which determines how quickly stressed capital is redeployed.
    5. Factoring Regulation Act, 2011, amended in 2021: Widened the set of lenders permitted to undertake factoring, easing receivables financing for small firms.
    6. Reserve Bank of India Act, 1934: Provides the statutory basis for monetary policy, including the inflation targeting framework that governs the interest rate regime.
    7. Fiscal Responsibility and Budget Management Rules, 2004: Prescribe the formats and the quarterly review obligations under the parent Act.

    Back2Basics: Demonetisation of 2016

    1. What it was: The withdrawal of legal tender status from the existing Rs 500 and Rs 1,000 currency notes, announced on 8 November 2016.
    2. Legal basis: Effected through a notification under Section 26(2) of the Reserve Bank of India Act, 1934, on the recommendation of the Central Board of the Reserve Bank of India.
    3. Stated objectives: Curbing unaccounted money, countering counterfeit currency and terror financing, and accelerating the shift to digital payments.
    4. Replacement currency: New Rs 500 and Rs 2,000 notes were introduced, and the Rs 2,000 note was later withdrawn from circulation in 2023.
    5. Return of notes: The Reserve Bank of India subsequently reported that the overwhelming majority of the demonetised currency was returned to the banking system.
    6. Judicial position: A Constitution Bench of the Supreme Court upheld the decision by a 4 to 1 majority in January 2023, holding that the process followed did not suffer from a legal infirmity.
    7. Economic effect recorded here: It marks the point after which corporate investment as a share of Gross Domestic Product began a continuous decline, and it pushed many micro, small and medium enterprises out of business.

    Government Initiatives

    1. Production Linked Incentive schemes: Pay incentives on incremental sales of goods manufactured in India across sectors including electronics, pharmaceuticals and automobiles, aimed at drawing private capital into manufacturing capacity.
    2. National Infrastructure Pipeline and the National Monetisation Pipeline: Set out a project pipeline for public infrastructure investment and a route to recycle operating public assets into fresh capital expenditure.
    3. PM Gati Shakti National Master Plan: Coordinates infrastructure planning across ministries to reduce logistics cost and project delay, both of which enter the investment appraisal of private firms.
    4. Emergency Credit Line Guarantee Scheme: Provided fully guaranteed collateral free credit to micro, small and medium enterprises to keep credit constrained firms solvent.
    5. Credit Guarantee Fund Trust for Micro and Small Enterprises: Guarantees collateral free bank lending to small firms, addressing the security requirement that keeps them off formal credit.
    6. Trade Receivables Discounting System (TReDS): An electronic platform allowing small suppliers to discount invoices owed by large buyers, easing the working capital squeeze.
    7. Corporate tax rate reduction: The concessional rate regime introduced for domestic companies, and a lower concessional rate for new manufacturing companies, intended to raise post tax returns on new capacity.

    Key Facts about Investment in the Indian Economy

    1. Peak investment rate: India’s overall gross fixed capital formation rate peaked in the years before the Global Financial Crisis, in step with the corporate investment peak of 17.3 percent recorded here.
    2. Corporate tax rates: The headline domestic corporate tax rate was reduced from 30 percent to 22 percent, with a lower concessional rate offered to new manufacturing companies.
    3. Monetary framework: India adopted flexible inflation targeting in 2016, with the target set at 4 percent and a tolerance band of plus or minus 2 percentage points.
    4. Micro, small and medium enterprises: The sector accounts for roughly 30 percent of Gross Domestic Product and about 45 percent of exports.
    5. Crowding out effect: The proposition that government borrowing raises interest rates and thereby reduces private investment, which is the standard objection to an expenditure led revival.
    6. Data sources: The Database on Indian Economy of the Reserve Bank of India for macro aggregates, and firm level databases such as Prowess for company accounts.

    Challenges in Reviving the Investment Cycle

    1. Demand uncertainty: Firms will not commit to long lived assets without visibility on sales. e.g. consumer durables makers deferred capacity additions through successive years of weak rural demand.
    2. Fiscal space for the stimulus: A sustained expenditure push runs against the statutory deficit path. e.g. the Fiscal Responsibility and Budget Management Act, 2003 targets constrain the size of a discretionary stimulus.
    3. Transmission of rate cuts: Policy rate reductions reach small borrowers slowly and incompletely. e.g. lending rates for small firms have historically moved far less than the repo rate in the same period.
    4. Skill and labour mismatch: New capacity requires skilled workers who are not available at scale. e.g. semiconductor and electronics assembly investments have flagged shortages of trained technicians.
    5. Land acquisition cost and delay: Assembling contiguous land for large plants remains the slowest step. e.g. industrial projects across several States have stalled for years at the land acquisition stage.
    6. Global trade uncertainty: Export oriented capacity decisions are hostage to tariff shifts abroad. e.g. punitive tariffs of 50 percent on Indian goods disrupted the export calculus for entire product lines.
    7. Concentration of profitability: Profits accrue disproportionately to large firms, which are the very firms not constrained by finance. e.g. the firm level panel shows median profitability rising and interest costs falling as firm size increases.

    Way Forward

    1. Use expenditure as the lead instrument: Direct sustained public expenditure at demand creating heads so that expected profitability rises for firms of every size rather than only for the largest.
    2. Target employment intensive spending: Prioritise programmes that put income directly in the hands of households, since that is what converts stimulus into the sales firms plan around.
    3. Fix credit access rather than credit price: Expand guarantee backed and receivables based lending to small firms, whose constraint is availability rather than the interest rate.
    4. Restore policy predictability: Avoid abrupt, economy wide interventions, since the confidence component of the investment decision recovers far slower than the immediate profitability component.
    5. Complete the public capital expenditure pipeline: Convert announced infrastructure projects into commissioned assets on schedule, so that the demand impulse is actually delivered.
    6. Report investment data faster: Shorten the lag and revision cycle in private corporate investment estimates so that a turning point is identified in time to act on it.

    Matching Previous Year Question

    “[2026] Which one of the following best describes the ‘Crowding Out Effect’ in the context of fiscal policy?
    (a) A situation where private investment increases due to increased Government spending
    (b) A situation where Government borrowing leads to higher interest rates, which reduces private investment
    (c) A situation where an increase in taxes leads to increased private sector investment
    (d) A situation where Government spending has no impact on aggregate demand
    Answer: (b)”

  • New PNG Connections Get a Gas Boost: Extra 200 SCM Allocation

    Why in the News

    From 1 September, eligible City Gas Distributors (CGDs) will receive an additional 200 Standard Cubic Metres (SCM) of cheaper Administered Price Mechanism (APM) gas for every new billed domestic Piped Natural Gas (PNG) connection.

    APM Natural Gas

    • Administered Price Mechanism (APM): Domestic gas from nomination fields of national oil companies, priced by the government.
    • Generally cheaper than imported Liquefied Natural Gas (LNG).
    • Piped Natural Gas (PNG) and Compressed Natural Gas (CNG) receive priority allocation.
    • Price is linked to the Indian crude basket, with a floor and ceiling.

    City Gas Distribution

    • City Gas Distribution (CGD): Pipeline network supplying gas to households, industries, commercial users and vehicles.
    • Geographical areas are awarded through competitive bidding by the Petroleum and Natural Gas Regulatory Board (PNGRB).

    Piped Natural Gas

    • Piped Natural Gas (PNG): Natural gas supplied directly through pipelines and metered like a utility.
    • Provides an alternative to Liquefied Petroleum Gas (LPG) cylinders for households.

    New Incentive

    • 200 SCM of APM gas for every incremental billed domestic PNG connection.
    • Effective 1 September.
    • Aims to reduce LNG sourcing costs and accelerate household PNG adoption.
    • Benefit is linked to actual billed connections, not merely network expansion.

    Key Challenges

    • Right-of-way and road-cutting permissions
    • High household connection costs
    • Competition from subsidised LPG
    • Limited domestic APM gas availability
    • Volatile imported LNG prices
    • Natural gas remains outside Goods and Services Tax (GST)
    • Low viability in remote and low-demand areas

    Foundational Context: The Natural Gas Sector in India

    1. Share in the energy mix: Natural gas accounts for roughly 6 percent of India’s primary energy mix, against a stated national target of raising it to 15 percent by 2030.
    2. Import dependence: India imports about half of its natural gas requirement in the form of liquefied natural gas, delivered through regasification terminals on the west and east coasts.
    3. Two price regimes: Domestically produced gas from nomination fields is sold at the administered price, while gas from deepwater, ultra deepwater and high pressure high temperature fields and imported gas are sold at market linked prices.
    4. Allocation priority: Domestic piped natural gas for households and compressed natural gas for transport hold first priority in the allocation of administered price gas.
    5. Network build out: Successive bidding rounds by the sector regulator have authorised city gas distribution networks covering the overwhelming majority of India’s population across more than 300 geographical areas.
    6. National gas grid: Trunk transmission pipelines are being extended into the eastern and north eastern regions to create a single national gas grid with a unified tariff.

    Statutory Framework Governing the Gas Sector

    1. Petroleum and Natural Gas Regulatory Board Act, 2006: Establishes the sector regulator and gives it authority over downstream refining, processing, storage, transportation, distribution and marketing of petroleum products and natural gas.
    2. Section 16 of the Petroleum and Natural Gas Regulatory Board Act, 2006: Provides for authorisation of entities to lay, build, operate or expand city gas distribution networks.
    3. Section 32 of the Petroleum and Natural Gas Regulatory Board Act, 2006: Provides that appeals against the regulator’s decisions lie to the Appellate Tribunal for Electricity, with a statutory disposal timeline of 90 days.
    4. Oilfields (Regulation and Development) Act, 1948: Governs the regulation of oilfields and the grant of mining leases for petroleum and natural gas.
    5. Petroleum and Natural Gas Rules, 1959: Prescribe the terms for grant of exploration licences and mining leases for petroleum and natural gas.
    6. Petroleum Act, 1934 and the Petroleum Rules, 2002: Govern the import, transport, storage and production of petroleum and the safety conditions attached to them.

    Back2Basics: Petroleum and Natural Gas Regulatory Board (PNGRB)

    1. Governing Act: The Petroleum and Natural Gas Regulatory Board Act, 2006.
    2. Established: Constituted in 2007 under that Act, functioning under the Ministry of Petroleum and Natural Gas.
    3. Jurisdiction: Regulates downstream activities only, covering refining, processing, storage, transportation, distribution, marketing and sale of petroleum products and natural gas.
    4. Exclusion from its remit: It does not regulate upstream exploration or production, which falls to the Directorate General of Hydrocarbons and the Ministry directly.
    5. Core functions: Protecting consumer interest, ensuring competitive markets for gas, authorising city gas distribution networks and pipelines, and fixing transportation tariffs.
    6. First instance adjudication: The Board is the first instance forum for disputes on tariffs, access and authorisation.
    7. Appellate forum: Appeals lie to the Appellate Tribunal for Electricity (APTEL) under Section 32 of the Act.

    Government Initiatives

    1. City Gas Distribution bidding rounds: Successive rounds conducted by the regulator to authorise distributors for new geographical areas, with minimum work programme commitments on domestic connections, compressed natural gas stations and pipeline length.
    2. Pradhan Mantri Urja Ganga: The Jagdishpur to Haldia and Bokaro to Dhamra pipeline project extending the gas grid to eastern India.
    3. North East Gas Grid: A capital grant supported trunk pipeline network connecting the eight north eastern States to the national gas grid.
    4. Sustainable Alternative Towards Affordable Transportation (SATAT): Promotes compressed biogas production and its sale through the existing fuel retail network as a substitute for compressed natural gas.
    5. Unified tariff for natural gas pipelines: A zonal tariff structure that lowers the delivered cost of gas for consumers located far from the source, aiding the eastern and southern build out.
    6. Hydrocarbon Exploration and Licensing Policy and Open Acreage Licensing Policy: Provide a uniform licence for all hydrocarbons and allow bidders to carve out their own exploration blocks, aimed at raising domestic production.

    Key Facts about India’s Gas Sector

    1. Nodal ministry: The Ministry of Petroleum and Natural Gas.
    2. Regulator: The Petroleum and Natural Gas Regulatory Board, constituted in 2007.
    3. Upstream technical arm: The Directorate General of Hydrocarbons, which oversees exploration and production.
    4. Administered price basis: Since April 2023 the administered price has been set at a fixed percentage of the Indian crude basket price, subject to a floor and a ceiling, following the recommendations of the Kirit Parikh Committee.
    5. Gas in the primary energy mix: About 6 percent, against the target of 15 percent by 2030.
    6. Compressed natural gas and domestic piped gas: Both receive 100 percent of their requirement from administered price gas under the priority allocation policy.

    “[2019] Consider the following statements:
    1. Petroleum and Natural Gas Regulatory Board (PNGRB) is the first regulatory body set up by the Government of India.
    2. One of the tasks of PNGRB is to ensure competitive markets for gas.
    3. Appeals against the decisions of PNGRB go before the Appellate Tribunals for Electricity.
    Which of the statements given above are correct?
    (a) 1 and 2 only
    (b) 2 and 3 only
    (c) 1 and 3 only
    (d) Neither 1 nor 2

  • Government explores routing gold monetisation through jewellers after bank scheme’s weak record

    Why in the News

    The government is in talks with jewellers on a gold monetisation route in which jewellers accept household gold and the deposit is held in a demat account, with interest paid on the value deposited. The bank based Gold Monetisation Scheme of 2015 mobilised only 38 tonnes by March 2025 against household holdings placed well upwards of 20,000 tonnes, so the redesign turns on who households trust with their gold rather than on the return offered.

    How would the proposed jeweller led gold monetisation route work?

    1. Point of deposit: A depositor would take physical gold to the nearest jeweller rather than to a bank branch.
    2. Record of holding: The scheme would be implemented through demat accounts, in the same way as shares, and the gold deposit would be reflected in the depositor’s demat account.
    3. Return to the depositor: The depositor would earn interest on the value of the gold deposited.
    4. Role of the jeweller: Jewellers would assume a key role in mobilising gold, becoming the contact point that banks occupy in the existing scheme.
    5. Stage of the proposal: Discussions with large industry players have been constructive and a scheme could be announced soon.

    What is a demat account?

    1. Definition: A dematerialised, or demat, account holds securities in electronic form with a depository, removing the need for a physical certificate.
    2. Application here: Holding a gold deposit in a demat account makes the claim transferable and tradable in electronic form, which physical gold in a bank vault is not.

    Why is the government revisiting gold monetisation now?

    1. Currency pressure: The exchange rate is under pressure from several factors at once.
    2. Fuel prices: Elevated fuel prices following the West Asia crisis have widened the import bill.
    3. Equity market sentiment: Investor concerns about the domestic stock market have weighed on capital inflows.
    4. Gold imports: Elevated gold imports are the third source of pressure, with imports reaching $71.98 billion in 2025-26 against about $35.02 billion in 2022-23, per Ministry of Commerce and Industry data.
    5. Industry signal: The chairman of the All India Gems and Jewellery Domestic Council stated that the government has communicated that it is serious about the proposal and has assured implementation as swiftly as it can be done.

    What did the bank based scheme of 2015 achieve?

    1. Mobilisation record: The scheme launched in 2015 mobilised just 38 tonnes of gold by March 2025, according to government data.
    2. Scale of the untapped stock: There is no official estimate of gold held by Indian households, and experts place the figure significantly upwards of 20,000 tonnes.
    3. The identified failure point: Families are more comfortable dealing with their family jewellers on matters concerning gold and silver, and that comfort is missing when banks play that role.
    4. The stated design change: The big shift in the current proposal is moving the collection point beyond banks, per the President of the India Bullion and Jewellers Association.

    Components of the Gold Monetisation Scheme, 2015, along the deposit lifecycle

    Component (lifecycle stage)Intervention and official termsPrimary stakeholder served
    Collection and Purity Testing Centre (input and assaying)Depositor’s raw gold is tested for purity at a Bureau of Indian Standards certified centre and converted into a standard equivalent before the deposit is acceptedHousehold depositor
    Short Term Bank Deposit (financing, short tenure)Tenure of 1 to 3 years, accepted by the bank on its own account, with the interest rate decided by the bank itselfDepositor and the accepting bank
    Medium Term Government Deposit (financing, medium tenure)Tenure of 5 to 7 years, accepted by banks on behalf of the Central government, at an interest rate of 2.25 percent per annumCentral government and the depositor
    Long Term Government Deposit (financing, long tenure)Tenure of 12 to 15 years, accepted on behalf of the Central government, at an interest rate of 2.50 percent per annumCentral government and the depositor
    Refinery and deployment (use of mobilised gold)Mobilised gold is refined and lent to jewellers as metal loans or used to reduce fresh import demandJewellery manufacturers and the external account
    Tax treatment (redemption)Deposits are exempt from capital gains tax, wealth tax and income tax on the interest and the appreciationHousehold depositor
    Current status of the componentsThe medium and long term government deposit components were discontinued from 26 March 2025, leaving only the short term bank deposit at the discretion of banksCentral government

    What would monetisation at scale do for the economy?

    1. Value of a partial mobilisation: Monetising just 10 percent of the gold held would be worth around $400 billion, according to a part time member of the Economic Advisory Council to the Prime Minister (EAC-PM).
    2. Comparison with foreign capital: India’s gross foreign direct investment is about $80 billion, so that gold would be equivalent to five years of foreign direct investment inflows.
    3. External account effect: Locked up gold, once monetised, can make India a trade account surplus nation.
    4. Consumption and investment effect: The change would increase domestic consumption and force companies to invest more.
    5. Savings channel: Investment depends on either domestic or global savings, and adding frozen domestic savings to liquid savings alongside continuing foreign capital would make a much larger pool available for investment.

    Why does routing gold through jewellers solve one problem and create another?

    1. The trust problem is real: Households deal with a family jeweller across generations, and the bank counter never acquired that standing, which is the single clearest explanation for 38 tonnes in ten years.
    2. The proposal is described as a win-win only in theory: The depositor earns interest and the system unlocks idle metal, and both outcomes depend on the intermediary honouring the deposit.
    3. Supervision moves to a lightly regulated node: A bank accepting a deposit is a regulated entity under banking law, and a jeweller accepting gold is not supervised in the same way.
    4. Purity assessment shifts: In the bank route, purity is established at a certified Collection and Purity Testing Centre, and a jeweller led route puts assaying and the customer relationship in the same hands.
    5. The demat layer is the safeguard being relied on: Holding the claim electronically creates a record of the deposit, and it does not by itself secure the physical metal held by the collecting jeweller.

    Challenges to gold monetisation in India

    1. Sentimental and social value of gold: Household gold is largely ornamental and passed down, so melting it for a deposit is resisted regardless of the interest offered. e.g. wedding jewellery in most Indian households is treated as inalienable rather than as a financial asset.
    2. Competing use as loan collateral: Households increasingly pledge gold rather than deposit it, since a loan preserves ownership of the ornament. e.g. gold backed loans reached about Rs 5.4 lakh crore by June 2026.
    3. Low return relative to price appreciation: Interest of a little over two percent is negligible against expected gold price gains. e.g. the Medium Term Government Deposit paid 2.25 percent while gold prices rose several fold over the scheme’s life.
    4. Fear of tax scrutiny: Depositing undeclared gold exposes the holder to questions on the source of the holding. e.g. income tax rules on unexplained investments deter deposits of inherited and undocumented holdings.
    5. Thin collection infrastructure: The number of certified collection and purity testing centres and refiners is small relative to the geography. e.g. large parts of rural India have no Bureau of Indian Standards certified assaying centre within reach.
    6. Loss of the ornament itself: The deposit requires the ornament to be melted into standard gold, which is irreversible. e.g. antique and regionally distinctive designs cannot be recovered once assayed and melted.
    7. Bank incentive problem: Banks earn little from accepting and deploying gold deposits, so branch level effort has been minimal. e.g. the medium and long term components were discontinued from 26 March 2025 after weak uptake.

    Conclusion

    The government is in talks with jewellers on a monetisation route in which household gold is deposited with a jeweller, held in a demat account and paid interest, after the bank based scheme of 2015 mobilised only 38 tonnes by March 2025 against holdings placed above 20,000 tonnes. The redesign correctly identifies trust in the family jeweller, rather than the return on the deposit, as the binding constraint, and it moves the collection point to an intermediary that is not supervised like a bank. Discussions are described as constructive and a scheme could be announced soon; the source states no announcement date.

    Foundational Context: Gold in India’s Economy

    1. Consumption scale: India is among the world’s two largest consumers of gold, alongside China, and imports almost all the gold it consumes.
    2. Household stock: Indian households are estimated to hold upwards of 20,000 tonnes of gold, which is larger than the official reserves of most central banks.
    3. External account weight: Gold is consistently among the top items in India’s import bill after crude oil, and gold imports reached $71.98 billion in 2025-26.
    4. Duty sensitivity: Import duty changes on gold move the split between formal imports and smuggling, which is why duty rates are treated as a customs enforcement issue as much as a revenue one.
    5. Financialisation objective: Public policy on gold has one consistent aim, which is to shift household savings out of physical metal into financial instruments backed by gold.

    Laws and Rules Governing Gold in India

    1. Bureau of Indian Standards Act, 2016: Provides the statutory basis for standardisation and for mandatory hallmarking of precious metal articles.
    2. Hallmarking Regulations and the HUID: Require every hallmarked gold article to carry a six digit alphanumeric unique identification number, traceable to the certified hallmarking centre.
    3. Foreign Trade (Development and Regulation) Act, 1992: Empowers the Central government to set the import policy for gold, including the channels and agencies through which it may be imported.
    4. Customs Act, 1962 and the Customs Tariff Act, 1975: Provide for the levy of import duty on gold and for confiscation and penalty in cases of smuggling and misdeclaration.
    5. Foreign Exchange Management Act, 1999: Governs the permissible modes of gold import and the treatment of gold in cross border transactions.
    6. Securities and Exchange Board of India (Vault Managers) Regulations, 2021: Regulate the vault managers who store the underlying gold against Electronic Gold Receipts traded on stock exchanges.
    7. Gold (Control) Act, 1968: Restricted private holding of gold bullion and was repealed in 1990, which is what allowed the later deposit and monetisation schemes to be built.
    8. Income-tax Act, 1961: Governs the treatment of unexplained investments and the tax exemptions specifically extended to deposits under the Gold Monetisation Scheme.

    “[2016] What is/are the purpose/purposes of Government’s ‘Sovereign Gold Bond Scheme’ and ‘Gold Monetization Scheme’?
    1. To bring the idle gold lying with Indian households into the economy.
    2. To promote FDI in the gold and jewellery sector
    3. To reduce India’s dependence on gold imports
    Select the correct answer using the code given below.
    (a) 1 only
    (b) 2 and 3 only
    (c) 1 and 3 only
    (d) 1, 2 and 3