The PM Electric Drive Revolution in Innovative Vehicle Enhancement (PM E-DRIVE) Scheme was launched in September 2024 and implemented from October 2024.
Its implementation has been extended up to 31 March 2028, with a total outlay of ₹11,900 crore.
Key Highlights
Implemented on a pan-India basis.
Supports:
EV demand incentives
Charging infrastructure
E-buses
Vehicle testing agencies
Domestic EV manufacturing and localisation
Targets approximately 28.30 lakh EVs.
26.59 lakh EVs sold as of June 2026.
Promotes cleaner mobility and reduction of transport-related environmental impacts.
EV Categories Covered
e-2Ws
e-3Ws, including registered e-rickshaws, e-carts and L5
e-Ambulances
e-Trucks
e-Buses
EV charging infrastructure
Upgradation of vehicle testing agencies
e-2W Incentive
Incentive: ₹2,500/kWh
Maximum incentive: ₹5,000 per vehicle
Applicable to vehicles priced up to ₹1.5 lakh ex-factory.
Allocation: ₹2,767 crore.
Target: 45.79+ lakh registered e-2Ws.
e-3Ws
Target sales for registered e-3W L5 achieved.
L5 sub-component closed on 26 December 2025.
Support for e-rickshaws and e-carts continues until March 2028.
E-Buses and Charging Infrastructure
₹4,391 crore allocated for 14,028 e-buses.
14,000 e-buses allocated as of August 2026.
13,800 e-buses allocated to seven cities: Delhi, Bengaluru, Hyderabad, Mumbai, Ahmedabad, Pune, and Surat
₹2,000 crore earmarked for nationwide EV Public Charging Stations (EV PCS).
₹851 crore approved for 8,147 chargers to 3 oil marketing companies and 10 States as of 28 September 2026.
₹780 crore allocated for modernisation and upgradation of vehicle testing agencies.
Demand Incentive Mechanism
Eligible buyers receive an upfront reduction in purchase price through e-vouchers.
The incentive amount is subsequently reimbursed to the Original Equipment Manufacturer (OEM) by the Ministry of Heavy Industries (MHI).
Domestic EV Manufacturing
Supports India’s domestic EV manufacturing ecosystem.
Promotes localisation of EV models.
Registered OEMs have obtained certificates of compliance with the Phased Manufacturing Programme (PMP) from MHI testing agencies.
Upgraded testing agencies will be equipped to handle new and emerging technologies.
Prelims Quick Revision
Launch: September 2024
Implementation: October 2024
Extended until:31 March 2028
Total outlay:₹11,900 crore
EVs supported: approximately 28.30 lakh
EVs sold: 26.59 lakh as of June 2026
e-2W incentive: ₹2,500/kWh, capped at ₹5,000/vehicle
e-2W price ceiling: ₹1.5 lakh ex-factory
₹2,000 crore for nationwide EV public charging stations
₹780 crore for vehicle testing agency modernisation
UPSC Prelims Trap
PM E-DRIVE is not limited to EV purchase incentives; it also covers charging infrastructure, e-buses and testing agencies.
The ₹2,500/kWh e-2W incentive is subject to a ₹5,000 per vehicle cap.
₹4,391 crore relates to e-buses, while ₹2,000 crore is earmarked for EV public charging stations.
L5 e-3W support and e-rickshaw/e-cart support should not be treated as identical sub-components: the L5 target was achieved and that segment closed on 26 December 2025, while support for e-rickshaws and e-carts continues until March 2028.
August 2026 recorded a historic fuel crossover in India’s passenger vehicle market. Data from the Federation of Automobile Dealers Associations (FADA), the apex body of vehicle dealers that compiles retail registration data, showed that the share of new vehicles in the alternative fuels category reached 41.95 per cent against petrol’s 40.85 per cent, the first time the former has overtaken the latter. The crossover follows a steady five year decline in the fossil fuel share of all registrations. The tension inside the number is that the alternative fuels category combines compressed natural gas, hybrid and electric vehicles, and in the car segment the shift has gone mainly to gas rather than to electricity.
What counts as an alternative fuel in this data?
FADA’s definition: The alternative fuels category combines compressed natural gas (CNG), hybrid and electric vehicles into a single share.
Two of the three are still fossil fuels: CNG and liquefied petroleum gas (LPG) are fossil fuels, and their advantage over petrol and diesel is significantly lower emissions rather than zero emissions.
Hybrids straddle the categories: A hybrid car runs on petrol combined with CNG or LNG, so a rise in its share moves a vehicle out of the petrol column without removing it from fossil fuel use.
How far has the overall fuel mix actually shifted?
Fossil fuels still dominate: Petrol and diesel accounted for 83.5 per cent of the roughly 82 lakh vehicles registered from January to March 2026.
The five year fall: That is a drop of 11.5 percentage points from the same period in 2021, when petrol and diesel accounted for over 95 per cent of the 57 lakh vehicles then registered.
Electric vehicles overall: Electric vehicles accounted for 10.6 per cent of total registrations.
What the aggregate conceals: A granular reading of the sub categories shows that the headline electric share is driven by particular segments rather than by a uniform shift.
Which segments are driving electric adoption?
Two wheelers carry the volume: The two wheeler segment accounts for over 70 per cent of all new vehicles registered in the country, so its mix moves the national figure.
A step change in two wheelers: The electric share in two wheelers jumped from 6.4 per cent in 2025 to 9.1 per cent in 2026 up to August, after only marginal year on year increases before that.
A first for petrol two wheelers: This is the first time the share of two wheelers running on petrol has come down to the 90 per cent mark, and that fall pulled the all category petrol and diesel share well below 85 per cent this year.
Three wheelers have already transitioned: Of the roughly 9.8 lakh three wheelers registered till August 2026, 60.5 per cent were electric, and the petrol and diesel share in the segment halved from nearly 30 per cent in 2021 to under 15 per cent in 2026.
Gas is receding there too: The share of three wheelers using CNG or LPG has also come down this year, and the segment accounts for only 4 per cent of all vehicles sold.
Why are cars the laggard in this transition?
Cars are the second largest segment: Cars account for the second biggest share of vehicles after two wheelers, so the car mix decides how much the headline crossover means.
The headline fall is real: The share of petrol and diesel cars dropped from 86 per cent in 2021 to 61.6 per cent in 2026.
Gas, not electricity, replaced them: That decline is accounted for mainly by hybrid cars running on petrol with CNG or LNG rather than by electric cars.
Hybrid share has plateaued: The share of hybrid electric vehicles has stayed fairly constant since 2023 at around eight per cent.
Electric growth is slow here: Sale of electric cars is progressing, and it is much slower than the growth in vehicles using CNG or LPG.
Challenges to electric vehicle adoption in India
Charging density decides car buying: A car buyer without home charging or a reliable public network defaults to a fuel that can be refilled in minutes, which is why CNG is winning the switch. Eg. India’s public charging network remains concentrated in a handful of metropolitan corridors while CNG retail outlets are far more widely distributed. The Fix: Mandate charging provision in new building codes and tie highway charger density targets to national highway concession agreements.
Battery inputs are imported: Cell manufacture depends on lithium, cobalt, nickel and graphite that India does not produce at scale, so the cost base sits outside the country. Eg. The lithium block identified at Reasi in Jammu and Kashmir has been put to auction and is far from production. The Fix: Run the National Critical Mineral Mission alongside overseas asset acquisition and mandatory battery recycling targets, so recovered material offsets imported feedstock.
The emissions gain depends on the grid: An electric vehicle charged on a coal heavy grid shifts emissions from the tailpipe to the power plant rather than removing them. Eg. Coal remains the largest source of electricity generation in India by a wide margin. The Fix: Pair electric vehicle incentives with time of day tariffs that push charging into hours of high renewable generation.
Resale value and financing are unresolved: Uncertainty about battery life depresses the second hand price of an electric car, and lenders price that uncertainty into the loan. Eg. Battery replacement cost can approach a large share of an older electric car’s residual value. The Fix: Mandate a standardised battery state of health certificate at resale, so the residual value rests on a measured figure rather than on a guess.
Demand tracks the subsidy window: Electric two wheeler sales have moved with the opening and tapering of central purchase incentives rather than with underlying preference. Eg. Electric two wheeler volumes fell sharply after the subsidy rate under the second phase of the Faster Adoption and Manufacturing of Electric Vehicles scheme was reduced in 2023. The Fix: Shift support from purchase subsidies to permanent structural levers such as differential road tax, registration fee waivers and scrappage linked credits.
Conclusion
The crossover is real, and its composition is the substantive finding. India is moving off petrol and diesel fastest in the segments where the vehicle is cheap, the daily range is short and the duty cycle is predictable, which is why three wheelers are past 60 per cent electric and cars are not. For cars the transition so far is a substitution within the fossil fuel family rather than an electrification. The measure to watch is the electric share of car registrations, which will move only once charging infrastructure is dense enough to remove the range calculation from the purchase decision.
Back2Basics: Vahan portal
What it is: Vahan is the national vehicle registration database of the Ministry of Road Transport and Highways, developed with the National Informatics Centre.
Coverage: It consolidates registration records filed by Regional Transport Offices across States and Union Territories onto a single platform.
Why it is used as data: Its public dashboard reports registrations by fuel type, vehicle category and State, which makes it the standard source for fuel mix analysis.
Its limit: It records registrations rather than sales, so unregistered vehicles and jurisdictions outside its coverage fall outside the count.
Matching Previous Year Question
“[2025] Consider the following types of vehicles:
I. Full battery electric vehicles
II. Hydrogen fuel cell vehicles
III. Fuel cell electric hybrid vehicles
How many of the above are considered as alternative (powertrain) vehicles?
(a) Only one
(b) Only two
(c) All the three
(d) None
Answer: (c)”
NITI Aayog has released the India Electric Mobility Index (IEMI) 2025, which ranks States and Union Territories on the development of the electric mobility ecosystem and on the adoption of electric vehicles (EVs). Delhi topped the index, followed by Maharashtra and Karnataka. Those two are the only large States among the top performers, out of seventeen. The index therefore records a concentration rather than a diffusion: the territories doing best are small, dense and administratively compact, while most of the country’s population lives in States that the index places in its middle tiers.
What is the India Electric Mobility Index?
What it measures: It is a composite index assessing the policy framework and the implementation outcomes for electric mobility at the State level.
Who built it: NITI Aayog developed the index in collaboration with World Resources Institute (WRI) India.
Its three themes: Transport electrification progress carries 50% weight, charging infrastructure readiness 30%, and EV research and innovation status 20%.
Coverage: It scores all 36 States and Union Territories on a common 100 point scale.
What does the overall ranking show?
The spread: Composite scores range from 10 to 84, with a median of 40, so half the country sits at or below two fifths of the achievable score.
The leaders: Delhi scored 84, followed by Maharashtra at 78, Karnataka at 73, Chandigarh at 71 and Goa at 65.
Movement against the 2024 index: Delhi and Maharashtra held the top two positions, Karnataka moved to third by overtaking Chandigarh, and Goa climbed ten places to fifth.
The largest single gain: Madhya Pradesh moved from twenty third rank to seventh.
How have the large States performed?
Only two in the top tier: Maharashtra and Karnataka are the only large States among the top performers, out of seventeen large States assessed.
The frontrunner band: Eight large States scored between 50 and 64, namely Tamil Nadu, Madhya Pradesh, Odisha, Andhra Pradesh, Telangana, Haryana, Rajasthan and Uttar Pradesh.
The emerging band: Seven large States scored between 35 and 49, namely Chhattisgarh, West Bengal, Bihar, Kerala, Jharkhand, Punjab and Gujarat.
What the distribution implies: The States carrying the largest vehicle populations sit in the middle bands, so national electrification outcomes are decided where the index scores are weakest.
Where do the three themes diverge?
Transport electrification, the heaviest theme: Delhi, Chandigarh and Maharashtra were the only territories qualifying as top performers on it. It evaluates market absorption, consumer acceptance and demand side momentum, meaning how effectively electric vehicles are actually being adopted.
Charging readiness has a different leader: Karnataka recorded the highest score nationwide at 97, followed by Goa at 92 and Maharashtra at 91.
What charging readiness captures: The charger to vehicle ratio, subsidies for charging infrastructure, building bye laws for charging, and power availability.
Research and innovation: Delhi achieved the top score of 94 on this theme.
The divergence matters: A State can lead on chargers and trail on adoption, since infrastructure readiness is scored independently of vehicles actually registered.
Challenges to State led electric mobility
Distribution company capacity: Charging load falls on distribution utilities already carrying losses, so sanctioned load and feeder capacity cap how fast chargers can be added. Eg. Several State distribution companies carry aggregate technical and commercial losses above 20%. The Fix: Ring fence a concessional EV charging tariff and fund feeder upgrades from the State electric mobility policy corpus.
Subsidy dependence: Registrations track State and central purchase incentives and fall when a scheme window narrows. Eg. Electric two wheeler sales dipped after the FAME II demand incentive was reduced in mid 2023. The Fix: Shift from an upfront purchase subsidy to a road tax and registration fee waiver that runs for the life of the vehicle.
Geographic concentration of chargers: Chargers cluster in a few metropolitan pockets, leaving intercity corridors and smaller towns unserved. Eg. The index’s leading territories are small and dense, where covering the whole jurisdiction is far easier than across a large State. The Fix: Make charging points at fixed intervals a condition of national and State highway concession agreements.
Battery supply and end of life handling: Cells and the lithium, cobalt and nickel behind them are largely imported, and recycling capacity remains thin. Eg. India imports the overwhelming share of the lithium ion cells it consumes. The Fix: Enforce the recycling and extended producer responsibility targets under the Battery Waste Management Rules, 2022 alongside domestic cell manufacturing incentives.
Generation mix limits the climate gain: An electric vehicle’s emissions follow the electricity that charges it, so the benefit shrinks where coal dominates supply. Eg. Coal still supplies close to three quarters of India’s electricity generation. The Fix: Align charging tariffs to time of day slots that coincide with solar generation hours.
Conclusion
The index measures readiness, and readiness is not the same as transition. Its top ranks are held by territories small enough for a single administration to cover with chargers and incentives, which is not the problem a large State faces. The unresolved tension is that the States with the most vehicles to convert have the least fiscal room to subsidise the conversion and the weakest distribution utilities to power it. Watch whether the next edition shows movement in the frontrunner band of large States, because that band is where the national outcome is actually decided.
Back2Basics
World Resources Institute India: An independent research organisation working on climate, energy, cities, water and sustainable mobility, operating as the India arm of a global research body.
Role here: It provided the research collaboration for the composite index, including the indicator design behind the three themes.
Urban mobility work: It supports Indian cities on bus transport planning, road safety and electric mobility transition programmes.
Matching Previous Year Question
“The adoption of electric vehicles is rapidly growing worldwide. How do electric vehicles contribute to reducing carbon emissions and what are the key benefits they offer compared to traditional combustion engine vehicles?”
Alternative fuel vehicles outsold petrol cars in India’s passenger vehicle market for the first time in August 2026. Compressed natural gas (CNG), hybrid and electric vehicles together accounted for 41.95 percent of passenger vehicle retail sales against petrol’s 40.85 percent. The month also set a volume record across every segment, with 24,23,201 units retailed in all. The crossover was reported in the monthly retail registration data of the Federation of Automobile Dealers Associations (FADA). Petrol remains the largest single fuel in the market, so the crossover is three powertrains adding up rather than one substitute displacing petrol.
What does the August 2026 retail data show across segments?
A record month by volume: Total retail sales reached 24,23,201 units, a rise of 17.51 percent year on year. Two wheelers, passenger vehicles, commercial vehicles, tractors and three wheelers each set a fresh August record.
Growth was uneven across segments: Wheeled construction equipment grew 31.45 percent, two wheelers 19.69 percent, passenger vehicles 16.14 percent and commercial vehicles 14.45 percent. Three wheelers grew 8.64 percent and tractor sales were effectively flat at 0.84 percent.
Segment volumes set new marks: Two wheelers retailed 17,14,610 units, the best August since 2018. Passenger vehicles crossed the four lakh mark in an August for the first time at 4,02,398 units, and commercial vehicles came in at 90,769 units.
The lighter commercial categories led: Light commercial vehicles grew 15.32 percent year on year, heavy commercial vehicles 13.98 percent and medium commercial vehicles 10.38 percent. Dealers attribute the demand to infrastructure execution, mining and logistics linked to e-commerce, alongside steady financing.
Sales fell against the previous month: Retails were 6.48 percent lower than in July 2026. The seasonal monsoon lull and a festival calendar that shifted Ganesh Chaturthi and pushed Onam linked buying into September account for the fall.
Dealer stock is building: Passenger vehicle inventory rose by a further five days over the end of July to about 38 to 40 days, against the 21 day benchmark the dealers’ body recommends. Higher stock than the previous month was reported by 56 percent of passenger vehicle dealers.
Why does the change in fuel mix matter more than the volume record?
The alternative fuel share is three distinct powertrains:CNG vehicles accounted for 25.28 percent of passenger vehicle sales, hybrids 9.04 percent and electric vehicles 7.63 percent. CNG alone is more than three times the electric share.
No single alternative fuel has replaced petrol: Petrol is still the largest individual fuel in the segment. The threshold crossed is a share of the market held collectively, not a substitution of one fuel by another.
Running cost is the stated driver: Dealers attribute the movement of petrol buyers towards CNG, hybrids and electric vehicles to running cost economics rather than to purchase price.
Ethanol blending has become a demand factor: Continuing consumer hesitation around the E20 transition, the shift to petrol blended with 20 percent ethanol, is nudging buyers away from petrol. Part of the shift is avoidance of an uncertain fuel rather than preference for a new powertrain.
How far has electrification moved beyond passenger cars?
Electric two wheelers crossed a tenth of their market: Their share reached 10.68 percent against 7.66 percent a year earlier. It was the first time the 10 percent mark was crossed in a non festival month.
Electric commercial vehicles hit a record share: Their share rose to an all time high of 5.18 percent from 2.06 percent a year earlier, with monthly volumes setting a fresh record.
Three wheelers are already structurally electric:Electric penetration in the three wheeler segment stands at 65.30 percent. Electrification there has stopped being a transition and become the default.
Challenges to the shift to alternative fuel vehicles
Charging access lags electric vehicle sales: Public charging remains concentrated in large cities and on a few highway corridors, so buyers without private parking carry the highest switching cost. Eg. The PM Electric Drive Revolution in Innovative Vehicle Enhancement (PM E-DRIVE) scheme, notified in 2024, set aside about Rs 2,000 crore of its outlay specifically for public charging infrastructure.
CNG supply is geographically uneven: The fuel is dense in a few city gas distribution areas and thin elsewhere, which caps how far its cost advantage can travel. Eg. Delhi and Gujarat hold a large share of India’s CNG stations while much of eastern India remains sparsely covered.
Hybrid incentives vary by State: Hybrids sit outside most electric vehicle subsidy schemes, so their running cost advantage depends on where the vehicle is registered. Eg. Uttar Pradesh waived the registration tax on strong hybrid vehicles in 2024, a concession most States do not offer.
Battery manufacture depends on imported inputs: Cell manufacturing and the lithium, cobalt and graphite feeding it are largely imported, so electric vehicle prices track external supply. Eg. The National Critical Mineral Mission, launched in 2025, was created to secure exactly these inputs.
A share built on hesitation can reverse: Buyers moving away from petrol over blending concerns can move back once those concerns are answered. Eg. E20 petrol was rolled out across the country by 2025 amid disputes over fuel efficiency and engine compatibility in vehicles built for lower blends.
Way Forward
Expand public charging infrastructure: Tie charging point rollout targets to electricity distribution licence areas, so coverage follows the grid rather than following sales volumes.
Ensure wider CNG availability: Make station rollout milestones an enforceable condition of every city gas distribution licence rather than a projected commitment.
Create uniform hybrid incentives: Settle one national treatment of hybrids in the motor vehicle tax structure so the segment is not priced by State discretion.
Strengthen domestic battery value chains: Link production linked incentive disbursal for cells to domestic value addition milestones rather than to assembly volumes.
Build evidence based consumer confidence: Publish independent test results on efficiency loss and material compatibility by vehicle vintage, so the choice rests on evidence rather than uncertainty.
Conclusion
The fuel mix has moved ahead of the infrastructure that has to support it. The festival quarter is the next test, when discounting and volume peak together and dealer stock is either absorbed or deepens. The second marker is whether the alternative fuel share holds once the ethanol blending question is settled, because a share built partly on avoidance is not the same as a share built on preference.
Back2Basics: Federation of Automobile Dealers Associations (FADA)
What it is: FADA is the apex national body of automobile retail dealers in India, representing dealerships across vehicle segments.
What its data measures: It compiles retail sales from vehicle registration records at regional transport offices. Its figures therefore track vehicles sold to customers, not vehicles dispatched from factories to dealerships.
Why the distinction matters:Manufacturer dispatch numbers can rise while retail sales stall, with the difference sitting as unsold stock at dealerships. FADA’s monthly inventory reading is what exposes that gap.
[2025] Consider the following types of vehicles:
I. Full battery electric vehicles
II. Hydrogen fuel cell vehicles
III. Fuel cell electric hybrid vehicles
How many of the above are considered as alternative (powertrain) vehicles?
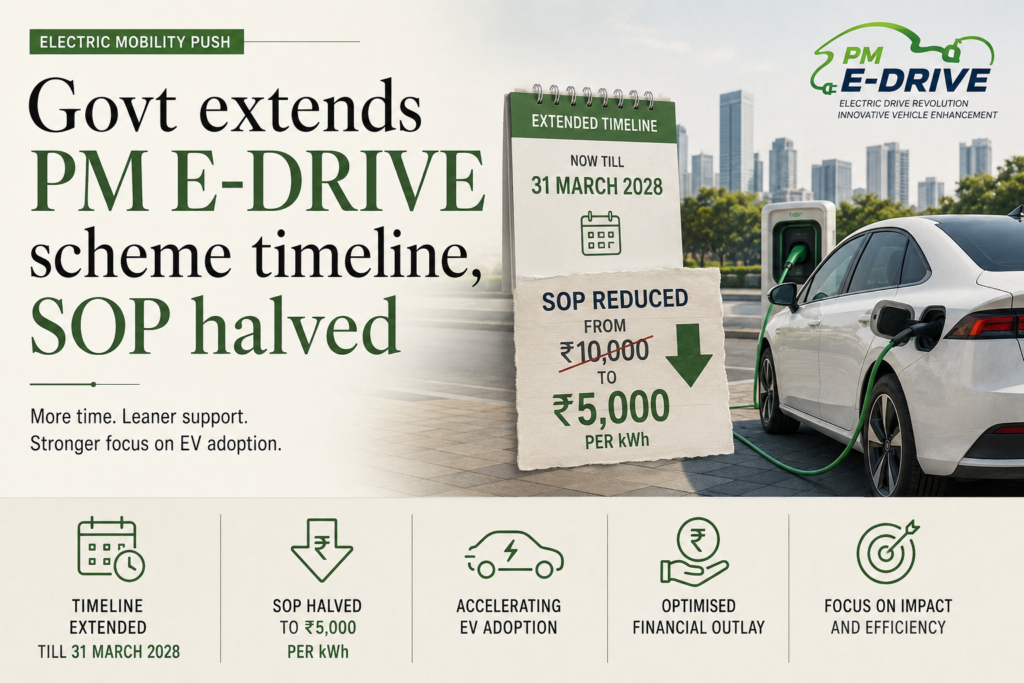
The Centre has extended the PM Electric Drive Revolution in Innovative Vehicle Enhancement (PM E-DRIVE) Scheme for electric two wheelers till 31 March 2028 and halved the per unit incentive to Rs 2,500 per kilowatt hour from Rs 5,000 earlier. The move signals a planned tapering of demand support as electric two wheeler costs fall and the market matures.
What is the PM E-DRIVE Scheme?
What it is: PM E-DRIVE is the central scheme providing demand incentives and support infrastructure for electric mobility, administered by the Ministry of Heavy Industries. It succeeds the earlier FAME programme as the main demand side push for electric vehicles.
Outlay and duration: It carries an outlay of Rs 11,900 crore and is implemented from 1 April 2024 till 31 March 2028.
Two wheeler support: For electric two wheelers, the scheme sets a total fund support of Rs 2,767 crore from the Ministry of Heavy Industries.
What has changed?
Timeline extended: The electric two wheeler segment has been extended till 31 March 2028.
Incentive halved: The per unit incentive is cut to Rs 2,500 per kilowatt hour from Rs 5,000 per kilowatt hour earlier.
Per vehicle cap lowered: The incentive is capped at Rs 5,000 per vehicle, down from Rs 10,000 per vehicle in FY 2024-25.
Eligibility window: Registered electric two wheelers can avail the Rs 2,500 per kilowatt hour incentive for the period between 1 April 2025 and 31 March 2028.
Price ceiling: The maximum ex factory price for an electric two wheeler to qualify is Rs 1.5 lakh.
Lower of two limits: The incentive is limited to the specified cap or 15 per cent of the ex factory price of the electric two or three wheeler, whichever is lower, and is subject to periodic review as vehicle costs fall.
Back2Basics: PM E-DRIVE Scheme
Ministry: Ministry of Heavy Industries.
Launch year: 2024, implemented from 1 April 2024 to 31 March 2028.
Outlay: Rs 11,900 crore.
Aim: Accelerate adoption of electric vehicles and build charging and testing infrastructure.
Beneficiaries: Buyers of electric two, three, and heavier vehicles, state transport undertakings, and charging infrastructure providers.
Government Initiatives for Electric Mobility
FAME India (Phase I and II): Earlier demand incentive scheme for electric and hybrid vehicles.
PLI Auto Scheme: Production Linked Incentive for advanced automotive technology products.
PLI ACC Battery Scheme: Incentive for domestic advanced chemistry cell battery manufacturing.
Vehicle Scrappage Policy: Phasing out unfit vehicles to spur cleaner replacements.
e-AMRIT portal: A one stop information platform on electric vehicles.
Key Facts about PM E-DRIVE
Successor scheme: PM E-DRIVE succeeds FAME II as the flagship electric mobility scheme.
Incentive metric: Support is calculated per kilowatt hour of battery capacity.
Segment coverage: Covers electric two wheelers, three wheelers, buses, trucks, and ambulances, plus charging infrastructure.
Challenges to Electric Vehicle Adoption
Charging infrastructure gap: Public charging networks remain thin outside major cities.
Battery import dependence: Reliance on imported cells and critical minerals raises cost and supply risk.
High upfront cost: Purchase prices stay above comparable petrol vehicles despite incentives.
Range and grid strain: Range anxiety and grid readiness limit uptake in some segments.
Recycling burden: End of life battery disposal needs robust recycling systems.
Incentive dependence: Demand remains sensitive to the level and continuity of subsidies.
“[2023, GS3, 15 marks] The adoption of electric vehicles is rapidly growing worldwide. How do electric vehicles contribute to reducing carbon emissions and what are the key benefits they offer compared to traditional combustion engine vehicles?”
[2025] With reference to India, consider the following pairs: Organization Union Ministry 1. The National Automotive BoardMinistry of Commerce and Industry 2. The Coir BoardMinistry of Heavy Industries 3. The National Centre for Trade InformationMinistry of Micro, Small and Medium Enterprises How many of the above pairs are correctly matched?
India’s electric mobility transition is gathering momentum as adoption rises and circular economy principles enter industrial policy. India’s policy has advanced the recycling tier of circularity through scrappage but neglected the higher priority reuse tier, exposing a gap where structurally sound vehicles are scrapped rather than retrofitted.
What is the circular economy hierarchy?
Definition: The circular economy is built on a hierarchy that prioritises reducing resource consumption, then reusing existing assets, and only recycling materials once products have genuinely reached the end of their useful life.
Reuse versus recycle: Recycling recovers materials after a product becomes waste, while reuse preserves functionality before the asset becomes waste. Reuse sits higher in the hierarchy.
What is vehicle retrofitment?
What it is: Retrofitment replaces the internal combustion engine, fuel system, and related components of an existing vehicle with an electric powertrain, while retaining the core vehicle structure.
Why it counts as reuse: By keeping a structurally sound chassis and body in service, it preserves and extends the value already embedded in the asset rather than recovering value only after the vehicle becomes waste.
How far has India progressed on recycling?
Rules framework: The Motor Vehicles (Registration and Functions of Vehicle Scrapping Facility) Rules, 2021, and the Environment Protection (End of Life Vehicles) Rules, 2025, strengthened responsible vehicle recycling and material recovery.
Facilities on ground: As of January 2026, 129 Registered Vehicle Scrapping Facilities were operational across 21 States and Union Territories.
Vehicles processed: About 4.3 lakh vehicles had been processed through these facilities, building a formal ecosystem for recycling and resource recovery.
Why does retrofitment matter?
Per vehicle waste: A single two wheeler generates approximately 90 kilograms of recyclable material and 18 kilograms of landfill waste when scrapped.
Fleet scale burden: Scaled across India’s fleet of about 30 crore vehicles, a scrap first approach would generate 2.7 crore tonnes of recyclable material and 0.54 crore tonnes of landfill waste.
SDG alignment: Retrofitment supports United Nations Sustainable Development Goal 12 on responsible consumption and production by reducing material demand and waste.
Old but sound: A vehicle can be old yet retain a strong chassis, intact body, and years of service life, making retrofitting more circular than scrapping.
What is the three pathway vehicle hierarchy?
First pathway, continued use: Vehicles that remain safe, compliant, and efficient should keep operating with routine maintenance, since age alone should not trigger removal.
Second pathway, retrofitment: Vehicles with sound structure but ageing or polluting powertrains can be converted to electric through certified processes, extending life while cutting emissions.
Third pathway, scrappage: Vehicles with compromised safety, severe structural degradation, accident damage, or significant corrosion proceed to scrappage and recycling.
The missing middle path
Not a competition: Retrofitment is not a competing strategy to scrappage but the missing middle path that policy has not focused on yet.
Condition over age: Treating every ageing vehicle as a disposal candidate overlooks the chance to extend asset life while accelerating electrification.
Public acceptance: A condition assessed transition would make scrappage more acceptable, as citizens would see that older vehicles are assessed for transformation rather than dismissed indiscriminately.
What are the challenges to a reuse led EV transition?
Certification gap: Retrofitment needs robust certified conversion technology and testing standards to ensure safety.
Cost and financing: Conversion costs can rival buying a new two wheeler, limiting uptake without incentives.
Battery supply dependence: Electric powertrains depend on imported cells and critical minerals, a supply chain vulnerability.
Policy bias toward scrappage: Existing incentives favour scrappage and new vehicle purchase, leaving reuse unsupported.
Skilled workforce shortage: A trained network of certified retrofit workshops is largely absent at scale.
End of life battery waste: Retrofitted vehicles eventually generate battery waste requiring recycling infrastructure.
Conclusion
India’s transport transition is a question of resource efficiency, not a contest between new electric vehicles and older ones. Adopting an age assessed pathway that distinguishes continued use, retrofitment, and scrappage would align the transition with genuine circular economy principles. This would prevent waste before it is created and confine recycling to vehicles that have truly reached the end of their useful life.
What is Circular Economy? (Foundational Context)
About: A circular economy keeps materials and products in use for as long as possible, extracting maximum value before recovery and regeneration, in contrast to the linear take, make, dispose model.
Rationale: It exists to cut resource extraction, greenhouse gas emissions, and waste while sustaining economic value.
Named hierarchy: It rests on reduce, reuse, and recycle in that order of priority, with reduce and reuse ranked above recycling.
Key Concerns Regarding the Circular Economy
Recycling bias: Policy attention concentrates on recycling while the higher value reduce and reuse tiers are neglected.
Informal sector dominance: Much recycling occurs in the informal sector with poor environmental and safety standards.
Extended producer responsibility gaps: Enforcement of producer take back obligations remains weak.
Data deficits: Weak material flow data limits measurement of circularity outcomes.
Back2Basics: Sustainable Development Goal 12
What it is: SDG 12 is the goal on responsible consumption and production within the 2030 Agenda for Sustainable Development.
Adopted: It was adopted by United Nations member states in 2015.
Focus: It targets sustainable consumption patterns, resource efficiency, and reduced waste generation.
Relevance: Vehicle retrofitment directly advances its call for better resource efficiency and reduced waste.
Government Initiatives for EVs and Circularity
PM E-DRIVE Scheme: Provides demand incentives for electric two and three wheelers and other electric vehicles.
FAME India Scheme: Faster Adoption and Manufacturing of Electric Vehicles, supporting demand and charging infrastructure.
Vehicle Scrappage Policy: Encourages phasing out of unfit and polluting vehicles through registered scrapping facilities.
PLI schemes: Production Linked Incentives for advanced chemistry cell batteries and automobiles.
Way Forward
National vehicle hierarchy: Adopt a framework treating vehicles by condition rather than age alone.
Certified retrofit ecosystem: Standardise conversion technology and expand certified workshops.
Incentivise reuse: Extend fiscal support to retrofitment on par with scrappage and new purchase.
Strengthen battery circularity: Build reverse logistics and recycling for end of life batteries.
Skilling: Train technicians for certified electric powertrain conversion.
“[2025] Consider the following statements:
Statement I: Circular economy reduces the emissions of greenhouse gases.
Statement II: Circular economy reduces the use of raw materials as inputs. Statement III: Circular economy reduces wastage in the production process.
Which one of the following is correct in respect of the above statements?
(a) Both Statement II and Statement III are correct and both of them explain Statement I
(b) Both Statement I and Statement II are correct and Statement I explains Statement II
(c) Only one of the Statements II and III is correct and that explains Statement I
(d) Neither Statement II nor Statement III is correct
Question (2023, GS3): “The adoption of electric vehicles is rapidly growing worldwide. How do electric vehicles contribute to reducing carbon emissions and what are the key benefits they offer compared to traditional combustion engine vehicles?
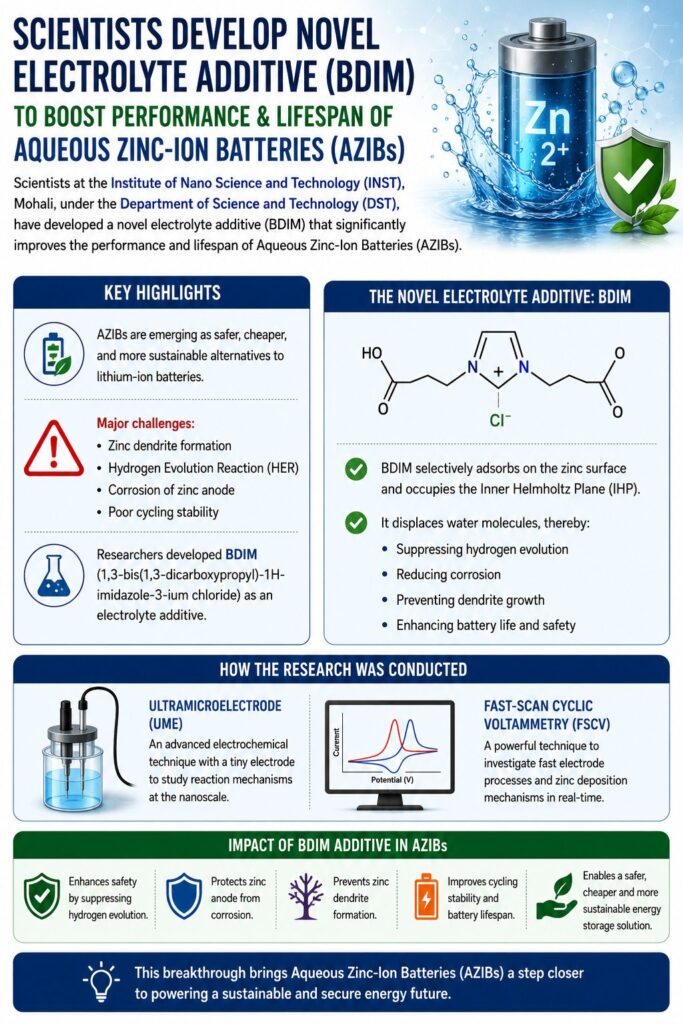
Scientists at the Institute of Nano Science and Technology (INST), Mohali, under the Department of Science and Technology (DST), have developed a novel electrolyte additive (BDIM) that significantly improves the performance and lifespan of Aqueous Zinc-Ion Batteries (AZIBs).
Key Highlights
AZIBs are emerging as safer, cheaper, and more sustainable alternatives to lithium-ion batteries.
Major challenges:
Zinc dendrite formation
Hydrogen Evolution Reaction (HER)
Corrosion of zinc anode
Poor cycling stability
Researchers developed BDIM (1,3-bis(1,3-dicarboxypropyl)-1H-imidazole-3-ium chloride) as an electrolyte additive.
BDIM selectively adsorbs on the zinc surface and occupies the Inner Helmholtz Plane (IHP).
It displaces water molecules, thereby:
Suppressing hydrogen evolution
Reducing corrosion
Preventing dendrite growth
Enhancing battery life and safety
Researchers used: Ultramicroelectrode (UME) and Fast-Scan Cyclic Voltammetry (FSCV) to study zinc deposition mechanisms.
Significance
Extends battery lifespan without costly material redesign.
Improves safety and reliability of rechargeable batteries.
Supports large-scale renewable energy and grid-storage applications.
Can reduce maintenance costs of energy-storage infrastructure.
Prelims Facts
AZIB Electrolyte: Water-based, making it non-flammable and safer than lithium-ion batteries.
Inner Helmholtz Plane (IHP): Region near the electrode surface where electrochemical reactions occur.
Hydrogen Evolution Reaction (HER): Undesirable side reaction that reduces battery efficiency.
Consider the following types of vehicles:
I. Full battery electric vehicles
II. Hydrogen fuel cell vehicles
III. Fuel cell electric hybrid vehicles
How many of the above are considered as alternative (powertrain) vehicles?
In the context of electric vehicle batteries, consider the following elements:
I. Cobalt
II. Graphite
III. Lithium
IV. Nickel
How many of the above usually make up battery cathodes?