Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Search results for: “”

  • Did Press Note 3 relaxations help attract more FDI?

    Why in the News

    The government’s March 2026 relaxation of Press Note 3 (2020) now allows the automatic route for foreign investors from land-border-sharing countries where the resulting stake is below 10 percent. Press Note 3 (2020) had required prior government approval for any foreign direct investment from an entity based in, or beneficially owned by, a country sharing a land border with India, a restriction imposed after India’s border tensions with China. Since the relaxation, 29 Foreign Direct Investment (FDI) projects together worth ₹4,895.65 crore have been reported as raised through the automatic route. The scale of that inflow is now being tested against whether it represents genuine new investment or capital that was already structured to qualify.

    What is Press Note 3 and why was it imposed?

    1. Origin in 2020 border tensions: The Department for Promotion of Industry and Internal Trade issued Press Note 3 in April 2020 requiring government approval for FDI from any country sharing a land border with India, a category that in practice targets China.
    2. Stated rationale of opportunistic acquisition: The measure was framed as a safeguard against opportunistic takeovers of Indian companies whose valuations had fallen sharply during the COVID-19 pandemic.
    3. No de minimis threshold in the original rule: The 2020 version applied government-approval scrutiny regardless of the size of the resulting stake, so even a marginal shareholding increase by an investor linked to a bordering country required clearance.
    4. Applied to beneficial ownership, not just direct investment: The restriction reaches an investment structured through a third country if the ultimate beneficial owner is based in a bordering country, closing a routing loophole.

    What has the March 2026 relaxation changed?

    1. Automatic route restored below a 10 percent threshold: Investment from a bordering-country-linked entity resulting in a stake below 10 percent in the Indian company no longer requires prior government approval.
    2. Retains approval requirement above the threshold: Any investment crossing the 10 percent stake mark, or any greenfield or strategic-sector investment, continues to require case-by-case government clearance.
    3. 29 projects reported since relaxation: ₹4,895.65 crore in FDI has been reported as raised through the automatic route across 29 projects since the relaxation took effect.

    Did the relaxation actually attract more FDI?

    1. Reported inflow is modest against India’s total FDI base: ₹4,895.65 crore is a small fraction of India’s annual FDI inflow, so a Press Note 3 relaxation limited to sub-10 percent stakes has not shifted aggregate FDI in a way that will show clearly in headline balance-of-payments data.
    2. The 10 percent cap limits which capital responds: A relaxation confined below the threshold attracts portfolio-style minority stakes rather than the strategic or controlling investment that would signal deeper industrial commitment.
    3. Difficult to isolate the relaxation’s own effect: FDI flows respond to multiple factors simultaneously, including global interest rates and India’s own growth outlook, making it hard to attribute the 29 reported projects solely to the policy change.
    4. Sectoral destination of the reported inflow remains the open question: Whether the ₹4,895.65 crore has gone into manufacturing capacity or into financial and services stakes shapes how much the relaxation has actually served its stated industrial goal.

    Conclusion

    The Press Note 3 relaxation has produced a measurable but modest reported inflow, ₹4,895.65 crore across 29 projects, since March 2026. Whether this represents a genuine widening of investor participation from land-border-sharing countries or capital that was already positioned to enter below the new threshold will become clearer as more reporting cycles pass.

    Back2Basics: Press Note 3 (2020)

    1. Issued by the Department for Promotion of Industry and Internal Trade under the Foreign Direct Investment policy framework, not a standalone statute.
    2. Requires government approval for FDI from, or beneficial ownership traced to, any country sharing a land border with India: China, Pakistan, Bangladesh, Nepal, Bhutan, Myanmar, and Afghanistan.
    3. Applies to both fresh investment and a change in beneficial ownership of an existing investment resulting from a transfer.
    4. Enforced through the Reserve Bank of India’s foreign exchange reporting framework under the Foreign Exchange Management Act, 1999.

    Matching Previous Year Question

    “[2022] Which one of the following situations best reflects “Indirect Transfers” often talked about in media recently with reference to India ?
    (a) An Indian company investing in a foreign enterprise and paying taxes to the foreign country on the profits arising out of its investment
    (b) A foreign company investing in India and paying taxes to the country of its base on the profits arising out of its investment
    (c) An Indian company purchases tangible assets in a foreign country and sells such assets after their value increases and transfers the proceeds to India
    (d) A foreign company transfers shares and such shares derive their substantial value from assets located in India
    ANSWER: (d)”
  • How the Supreme Court ruling redefined ‘industry’

    Why in the News

    A nine-judge Constitution Bench of the Supreme Court revisited the definition of “industry” laid down in Bangalore Water Supply and Sewerage Board v. A. Rajappa (1978), examining how that definition interacts with the term “industry” as newly defined under the Industrial Relations Code, 2020. The 1978 ruling had given “industry” a wide, functional definition covering any organised activity involving cooperation between employer and employee for producing goods or services, regardless of profit motive. The Industrial Relations Code, 2020 narrows this definition by carving out specific exclusions. The Bench’s majority and minority opinions diverge on whether Parliament’s narrower statutory definition can override the Bangalore Water Supply test for constitutional purposes.

    What did the Bangalore Water Supply test originally hold?

    1. Triple test for “industry”: The 1978 ruling held that any activity involving systematic cooperation between an employer and workers to produce or distribute goods or services qualifies as an industry, irrespective of whether the entity is charitable, religious, sovereign, or run by the government.
    2. Sovereign function exception, narrowly read: The 1978 Bench exempted only inalienable sovereign functions of the State, such as legislation, defence, and the administration of justice, from the definition.
    3. Wide coverage of welfare and professional bodies: The test brought hospitals, educational institutions, and clubs employing staff within the definition of “industry,” extending industrial-dispute protections to their employees.
    4. Persistent legislative attempts to narrow it: Parliament had earlier attempted to codify a narrower definition through an amendment that was never brought into force, leaving the 1978 test operative for over four decades.

    What does the Industrial Relations Code, 2020 change?

    1. Statutory definition narrows the exclusions: The Industrial Relations Code, 2020 (the law consolidating the Trade Unions Act 1926, the Industrial Employment (Standing Orders) Act 1946 and the Industrial Disputes Act 1947 into a single code) defines “industry” with specific carve-outs for institutions engaged in charitable, social, or philanthropic services not for profit.
    2. Government departments performing sovereign functions excluded: The Code writes into statute an exclusion for departments discharging sovereign functions, aligning more closely with a narrower reading than the 1978 test.
    3. Domestic and hospital work carved out selectively: The Code excludes certain categories, such as purely domestic service, while leaving other categories, including some hospitals, to be decided case by case.

    Where do the majority and minority views diverge?

    1. Majority view on legislative competence: The majority holds that Parliament may legislatively define “industry” for the purposes of a labour statute, and that a narrower statutory definition prevails over the judicially evolved 1978 test within the Code’s own field of operation.
    2. Minority view on protective intent: The minority holds that a legislative narrowing of “industry” risks excluding workers in charitable, educational, and welfare institutions from industrial-dispute protections that the 1978 Bench extended to them.
    3. Divergence on precedent’s continuing force: The majority treats Bangalore Water Supply as persuasive but non-binding once Parliament legislates a definition, while the minority treats it as continuing to bind interpretation of undefined terms outside the Code’s specific carve-outs.

    Conclusion

    The ruling settles, for now, that Parliament’s statutory definition of “industry” under the Industrial Relations Code, 2020 governs disputes falling within the Code, narrowing the wide protective sweep the Bangalore Water Supply test had given workers across charitable, educational and welfare institutions for over four decades. Litigation over which specific institutions fall inside or outside the Code’s carve-outs is expected to continue as the Code is implemented.

    Back2Basics: Industrial Relations Code, 2020

    1. One of the four labour codes consolidating 29 central labour laws, this one merging the Trade Unions Act, 1926, the Industrial Employment (Standing Orders) Act, 1946, and the Industrial Disputes Act, 1947.
    2. Raises the threshold for prior government permission before layoffs, retrenchment or closure from 100 to 300 workers in an establishment.
    3. Introduces a statutory recognition mechanism for trade unions and a two-member negotiating council where no single union has majority membership.
    4. Notified but implemented in phases, with States framing their own rules under it.

    Matching Previous Year Question

    “[2024, GS3, 15 marks] Discuss the merits and demerits of the four ‘Labour Codes’ in the context of labour market reforms in India. What has been the progress so far in this regard?”

  • Centre plans to cap number of airports a single bidder can win in next privatisation round

    Why in the News

    The Ministry of Civil Aviation plans to cap the number of airports a single private bidder can win in the third round of airport privatisation. The round covers 11 airports grouped into five bundles: Amritsar-Kangra, Varanasi-Gaya-Kushinagar, Bhubaneswar-Hubballi, Raipur-Aurangabad, and Tiruchirapalli-Tirupati. The first two privatisation rounds concentrated a large share of India’s privatised airport traffic in two private groups. The cap sets up a tension between preventing bidder concentration and keeping the auction attractive to the handful of infrastructure players with the balance sheet to run an airport.

    What does the third privatisation round cover?

    1. Bundled bidding across five circuits: The Airports Authority of India (AAI) (the statutory body that owns, manages and privatises Indian civil airports) has grouped the 11 airports into five bundles rather than auctioning each separately, so a bidder wins or loses an entire regional cluster in one bid.
    2. Mix of trunk and regional airports: The bundles combine a higher-traffic anchor airport with smaller regional airports, so an operator absorbs a loss-making regional airport as part of winning the more viable one.
    3. Continuation of the Public-Private Partnership route: The round extends the Operation, Management and Development Agreement (OMDA) (the concession contract structure under which AAI leases an airport’s operations to a private developer for a fixed term while retaining ownership) model used in the first two rounds.
    4. Follows two prior privatisation rounds: Six airports were privatised in the first round and further airports in the second, before this third round was structured.

    Why is the Centre capping bidder concentration?

    1. Two private groups dominate the privatised airport map: One conglomerate operates several of India’s highest-traffic privatised airports won across the earlier rounds, while a second group holds a smaller cluster, leaving few large private operators outside these two.
    2. Concentration weakens the Centre’s post-award leverage: Where one bidder holds most privatised capacity, AAI has fewer credible alternative operators to discipline service standards or renegotiate terms.
    3. A cap widens the bidder base for smaller circuits: Limiting how many bundles a single group can win is intended to draw in operators who would otherwise not bid against an incumbent with deeper resources.
    4. Precedent from other infrastructure sectors: Sector regulators in ports and telecom have used similar concentration limits to prevent a single operator from controlling bottleneck infrastructure across regions.

    Challenges to the airport bidder cap

    1. Fewer bidders may qualify at all: Airport concessions require large upfront capital and aviation operating experience, a pool already limited to a handful of Indian infrastructure conglomerates. Eg. Only two or three consortia bid seriously in each of the first two rounds. Fix. Allow joint ventures and foreign strategic partners to combine capital and aviation expertise so more consortia can qualify.
    2. Regional airports could go unsold: A bundle pairing a loss-making regional airport with a viable one may see no bidder if the cap forces bidders away from the bundles they actually want. Eg. Kushinagar and Gaya carry limited passenger traffic and depend on the Varanasi bundle for viability. Fix. Offer viability gap funding for the weaker airport in each bundle rather than relying on cross-subsidy alone.
    3. Cap design risks being circumvented through related entities: A promoter group can bid through separate subsidiaries or affiliates that appear unconnected on paper. Eg. Beneficial-ownership opacity has complicated concentration limits in the telecom spectrum auctions. Fix. Define the cap by ultimate beneficial ownership, not by the bidding entity’s name.
    4. Slower privatisation pace: Restricting the largest, most capable bidders could stretch out the time needed to complete the round, delaying the capacity upgrades the smaller airports need.
    5. Revenue realisation may fall: A cap that keeps the highest bidder from taking every bundle it wants could produce lower aggregate concession fees than an uncapped auction would.

    Conclusion

    The Ministry of Civil Aviation is finalising the bidding norms for the third privatisation round, with the airport-count cap intended to correct the concentration that followed the first two rounds. The bid documents for the five bundles are expected to be released once the cap’s exact threshold is settled.

    Back2Basics: Airports Authority of India

    1. Statutory body under the Ministry of Civil Aviation, constituted under the Airports Authority of India Act, 1994.
    2. Owns, develops, and manages the majority of India’s civil airports, and leases select airports to private operators through the OMDA route.
    3. Also provides air navigation services across Indian airspace, a function it retains even at privatised airports.
    4. Earns revenue from aeronautical and non-aeronautical charges at the airports it directly operates.

    Matching Previous Year Question

    “[2024, GS3, 15 marks] What is the need for expanding the regional air connectivity in India? In this context, discuss the government’s UDAN Scheme and its achievements.”

  • Investment question has a political answer

    Investment question has a political answer

    Why in the News

    Private corporate investment in India remains considerably lower than the peak seen in the mid 2000s, even as large corporates hold substantial cash. Firms are deploying funds in financial assets rather than building physical assets such as factories, and are taking money out of the country rather than investing it here. The standard explanations offered for this are subdued domestic demand and global uncertainty. A political economy explanation is now advanced instead, locating the cause in how political power structures affect investment decisions. Centralisation of political power has been unmistakable after 2014, accompanied by fiscal centralisation and a reconfiguration of federal structures. The contested claim is that market concentration around a handful of “national champions” is not an accident of policy but is politically useful, which would make an investment revival costly to the current political settlement.

    What are “national champions”?

    • Definition: A national champion is a large domestic business group that a government treats as the preferred vehicle for building strategic capacity, and that is favoured in policy design as a result.
    • How the status is conferred: Preference operates through the terms of auctions, tariffs, incentive eligibility, clearances and access to public contracts rather than through an announced designation.
    • The economic consequence: A handful of such groups now command far greater sway over the economy than before, which raises the entry barrier facing any firm attempting to compete with them.

    What does the investment slowdown actually look like?

    • Cash-rich firms are not building: Large corporates hold funds but are not committing them to new capacity in India.
    • Capital is leaving: Companies are taking money out of the country rather than investing it domestically.
    • Investment is below its own peak: Private corporate investment remains considerably lower than the level reached in the mid 2000s.
    • Financial assets over physical assets: Corporate India is more keen to deploy funds in financial assets than to use them for factories and plant.
    • The standard explanations are incomplete: Subdued domestic demand and global uncertainty have been put forward, and neither accounts for why firms with the means to invest choose not to.

    Why does the concentration of political and market power deter private investment?

    • Political and fiscal centralisation: Centralisation of political power after 2014 has been accompanied by greater fiscal centralisation and a reconfiguration of federal structures, including attempts to restrict the powers of states and, as a consequence, of regional parties. Eg. The Mines and Minerals (Development and Regulation) Amendment Act, 2026, amending the 1957 law under which the State owns the mineral and signs the lease while the Centre sets the rules and the royalty rate.
    • Market concentration has moved in step: The rise of a handful of large companies, aided by policy, has given them far greater sway over the economy than ever before.
    • One, patronage for smaller firms has dried up: The concentration of political power and the decline in the relative power of regional parties has ended the patronage and protection that were afforded to smaller and regional firms, who could rise up and become national players.
    • Two, policy uncertainty and an uneven playing field: Higher barriers to entry and terms tilted towards larger corporates make it harder for new players to emerge, and firms will not invest if they fear the rules of the game can be arbitrarily changed or that they can be caught on the wrong side of policies. Policy credibility is what is at stake.
    • Three, the fear of being muscled out: Investors fear that business success will be met by a hostile takeover by a national champion, so the question is not whether they are allowed to operate but whether they can stay in business and remain competitive over the next 10 to 20 years.

    Why would dispersing economic power be politically costly?

    • Competition requires a rethink of the strategy: For the larger corporate sector to ramp up investment and for competition to emerge, the strategy of relying on a few national champions needs to be reconsidered.
    • Dispersed economic power funds political opposition: A larger number of big private players would disperse rather than concentrate economic power, which would in turn increase the funding avenues available to Opposition parties.
    • Economic competition feeds political competition: Weakening the concentration of economic power would possibly weaken the concentration of political power, so greater economic competition could lead to greater political competition.
    • The two open questions: It is unsettled whether the current political structure creates the space for new players to safely invest and emerge as competitors to the national champions, or whether market concentration is itself politically useful.

    Why do the ingredients of an investment boom not produce one?

    • The macroeconomic conditions are present: An undervalued exchange rate, depressed real wages and sustained public sector investment in infrastructure are all in place, alongside the demographic dividend.
    • The same mix powered East Asia: This combination powered the rise of countries such as China and South Korea, where firms responded to it with large capacity additions.
    • India’s firms are not responding: Firms are likely to remain hesitant and unsure about investing without a change in the approach, despite those conditions.
    • Confidence, not capability, is binding: Investment decisions are taken only when investors think they have a fair chance of benefiting from them.
    • The end state if nothing changes: The consequent absence of competition raises the possibility of an uncompetitive, high-cost economy.

    Challenges to the national champions strategy

    • Concentration raises consumer and input costs: Dominant firms in a sector face little pressure to hold prices down, which raises costs for every downstream user. Eg. Telecom tariffs rose sharply after the sector consolidated into three private operators. Fix. Use the deal value threshold introduced by the Competition (Amendment) Act, 2023 to review acquisitions that current turnover tests miss.
    • Policy-created advantage is hard to withdraw: Once a group builds capacity on the strength of an incentive, removing the incentive becomes a shock the government is reluctant to deliver. Eg. Most approved incentive under the Production Linked Incentive scheme for large-scale electronics manufacturing has flowed to a small group of mobile phone assemblers. Fix. Publish sunset dates and firm-level disbursement data with each incentive scheme so withdrawal is scheduled rather than negotiated.
    • Concentrated bank exposure transmits firm risk to the system: Lending concentrated in a few large groups converts a single group’s distress into a banking problem. Eg. The corporate loan losses that produced the non-performing asset build-up of the 2010s were concentrated in a handful of infrastructure and metals groups. Fix. Enforce large exposure limits at group rather than borrower level and publish group-wise banking exposure.
    • Bidding rules can favour incumbents: Net worth, prior experience and bank guarantee conditions in auctions and tenders can exclude new entrants before price is considered. Eg. Critical mineral block auctions have repeatedly failed for want of qualified bidders. Fix. Set qualification thresholds proportionate to block or contract size and allow consortium bidding for first-time entrants.
    • Competition enforcement is slow relative to market speed: Investigations concluded years after conduct occurs cannot restore a market that has already tipped. Eg. Appeals against Competition Commission of India orders routinely run for several years before finality. Fix. Fund a dedicated appellate bench for competition matters with statutory disposal timelines.

    Conclusion

    The reluctance of cash-rich Indian firms to invest is being read as a political economy problem rather than a demand or global uncertainty problem. Concentrated political power, an uneven playing field and the fear of being displaced by a national champion together deny new entrants confidence in a 10 to 20 year horizon. Reversing that requires dispersing economic power, which carries political costs the current settlement has no incentive to accept. What remains unresolved is whether market concentration will be treated as a cost to growth or retained as a political asset.

  • What young want, and why creating good jobs is no longer optional

    Why in the News

    Almost 70 per cent of urban job seekers surveyed in Delhi said they were looking for a job that would place them on their ideal career path from the start, instead of settling for any job. The survey covered over 3,000 randomly sampled men and women, 24 years of age on average, living in middle-class residential areas of the capital, and was conducted in the summer of 2023. Their stated career goal was predominantly salaried or formal-sector employment. The Periodic Labour Force Survey (PLFS) for the same year records an urban labour market that cannot supply that goal, with less than 50 per cent of the urban workforce in salaried jobs. A follow-up experiment then exposed a random subset of the same job seekers to real-world job openings and salaries, and re-surveyed them a year later. Correcting their information lowered their expectations and left their aspirations untouched, so the contest is over who adjusts, the young or the labour market.

    What is the Periodic Labour Force Survey (PLFS)?

    • Purpose: The PLFS is the official household survey that estimates how many people are working, seeking work or outside the labour force, and in what kind of work they are engaged.
    • Nodal body: The National Sample Survey Office under the Ministry of Statistics and Programme Implementation conducts it and is the principal source of employment estimates in India.
    • Activity status measures: Usual Status classifies a person by activity over the preceding 365 days, while Current Weekly Status treats a person as unemployed if they did not work even one hour in the reference week.

    What do young urban job seekers actually want from work?

    • A career path, not a job: Almost 70 per cent said they wanted an opening that put them on their ideal career path from the start rather than any available job, and more men said this than women.
    • Formal salaried work is the goal: The stated career goal was predominantly salaried or formal-sector employment rather than casual or own-account work.
    • Women lean harder towards salaried jobs: More women job seekers aspired to salaried positions than men did.
    • Only 14 per cent of women prefer self-employment: Just 14 per cent of the women interviewed said they would rather work for themselves.
    • A third of men want to run enterprises: More than a third of the men wanted to start their own businesses.
    • Public sector preference is a myth: A comparable share of these men and women were looking for private-sector salaried jobs, which cuts against the dominant narrative of a strong preference for government jobs.

    How far does the urban labour market fall short of those preferences?

    • Salaried work is a minority outcome: Less than 50 per cent of India’s urban workforce holds a salaried job.
    • It is scarcer still for the young: Merely one in every three employed 24-year-olds holds a salaried job, a lower share than for the workforce as a whole.
    • Government jobs are a tenth of the market: No more than 10 per cent of the urban workforce is in the public sector or government jobs.
    • The formal private sector is barely larger: Only about 15 per cent of the urban workforce is in the formal private sector.
    • Self-employment is the largest single category: Of those working, 40 per cent are self-employed.
    • Most self-employment is subsistence, not enterprise: An overwhelming majority of these businesses hire no worker at all and report an annual turnover of less than Rs 10 lakh, so the aspiration to build a firm meets a market of one-person shops.

    Why do salary expectations diverge from what these jobs actually pay?

    • The occupations tested: Respondents were asked what they expected to earn as an accounts keeper, a primary school teacher, a data entry operator, a hospital attendant and an electrician, and each expectation was measured against actual PLFS earnings for the same occupation.
    • Expectations run up to 40 per cent above reality: Job seekers expect up to 40 per cent higher salary than the earnings the PLFS records for the same work.
    • Men are the more over-optimistic: Male job seekers expect almost Rs 8,000 more per month than the actual average earnings for these jobs.
    • The gap widens for salaried work: For salaried jobs specifically, male job seekers expect Rs 8,500 more per month than actual earnings.
    • The aggregate divergence exceeds 30 per cent: Taken together, salary expectations sit more than 30 per cent above reality, and the skew is sharper still among job seekers below 25 years of age, especially young men.
    • Information and inexperience explain the gap: A lack of information or outright misinformation about openings and pay, combined with inexperience of the job market, are the two obvious sources of the misalignment.

    What did correcting job seekers’ information change, and what did it leave untouched?

    • The design: A random subset of the 3,000 job seekers was informed about real-world job opportunities and salaries, and both the informed and the non-informed groups were re-surveyed twelve months later.
    • Expectations fell: Accurate information significantly dampened labour-market expectations of landing the ideal job, relative to those who were not informed.
    • Men disengaged first: Men in particular became less likely to report that they were on their ideal career path.
    • Search effort fell with belief: That disillusionment was accompanied by a decline in men’s job-search intensity.
    • The two exits from a failed search: As preferred job offers fail to materialise, job seekers adjust expectations downwards and either remain in the same jobs or leave the labour market and enrol at educational institutions.
    • Aspirations did not move: The answer on whether aspirations changed is a clear no, since these men and women continued to aim for formal-sector jobs or dynamic entrepreneurship a year later, because aspirations are long-term goals and not easily malleable.
    • High education costs make the expectation rational: Good-quality education is increasingly bought from private institutions at rising cost, so a high expected salary is not only aspirational but necessary to recover that outlay.

    Challenges to the Periodic Labour Force Survey

    • Informal work is under-captured: Household surveys do not fully record home-based, gig and platform work in a workforce that is about 90 per cent informal. Eg. Delivery and ride-hailing riders working across two aggregators are frequently recorded as ordinary self-employed workers. Fix. Align the activity definitions with International Labour Organization and System of National Accounts practice so multi-job holders, freelancers and platform workers are counted separately.
    • No skill mapping against job requirements: The survey does not match worker skills to the requirements of available jobs, so structural unemployment cannot be measured from it. Eg. The India Skills Report finding that only about half of graduates are employable has no counterpart in official survey data. Fix. Add a skills and job-requirement module so mismatch is measured rather than inferred.
    • Rural data has been low frequency: Rural estimates were historically produced only once a year, so rural distress is visible with a long lag. Eg. A monsoon failure that pushes workers back into farm labour shows up only in the following annual round. Fix. Extend high-frequency quarterly or monthly rounds to rural areas rather than confining them to towns.
    • Urban bias in the high-frequency rounds: The quarterly bulletins have been confined to urban areas, which under-measures the larger rural workforce. Eg. Quarterly urban unemployment rates are debated publicly while comparable rural numbers are unavailable. Fix. Publish a single integrated quarterly series covering both sectors on the same reference period.
    • New job categories are missing: Gig, digital, start-up and green jobs are not adequately represented in the occupational classification the survey uses. Eg. Solar installation and battery recycling roles have no distinct occupational code. Fix. Integrate Employees’ Provident Fund Organisation, National Career Service and PLFS records so emerging job creation is tracked from administrative data as well.

    Conclusion

    Young urban job seekers want formal salaried careers and dynamic enterprise, and correcting their information about the market lowers what they expect to earn without changing what they want. That asymmetry places the burden of adjustment on the economy rather than on the young, and realising these aspirations requires a structural transformation that creates jobs with regular pay and benefits. The four Labour Codes are a step in that direction, and creating good jobs and genuine career paths, rather than jobs alone, is no longer optional. Failure carries a specific cost, which is the squandered potential of an entire generation.

  • [24th August 2026] The Hindu OpED: Core concerns

    [24th August 2026] The Hindu OpED: Core concerns

    Question (2017, GS3): ““Industrial growth rate has lagged behind in the overall growth of Gross-Domestic-Product (GDP) in the post-reform period” Give reasons. How far the recent changes is Industrial Policy are capable of increasing the industrial growth rate?
    Linkage: The easing of the Manufacturing PMI to its lowest level since August 2021 due to weak domestic demand is a classic real-time symptom of industrial growth lagging behind overall economic expansion. It forces candidates to examine why Indian manufacturing struggles to maintain sustained momentum.

    Mentor Comment

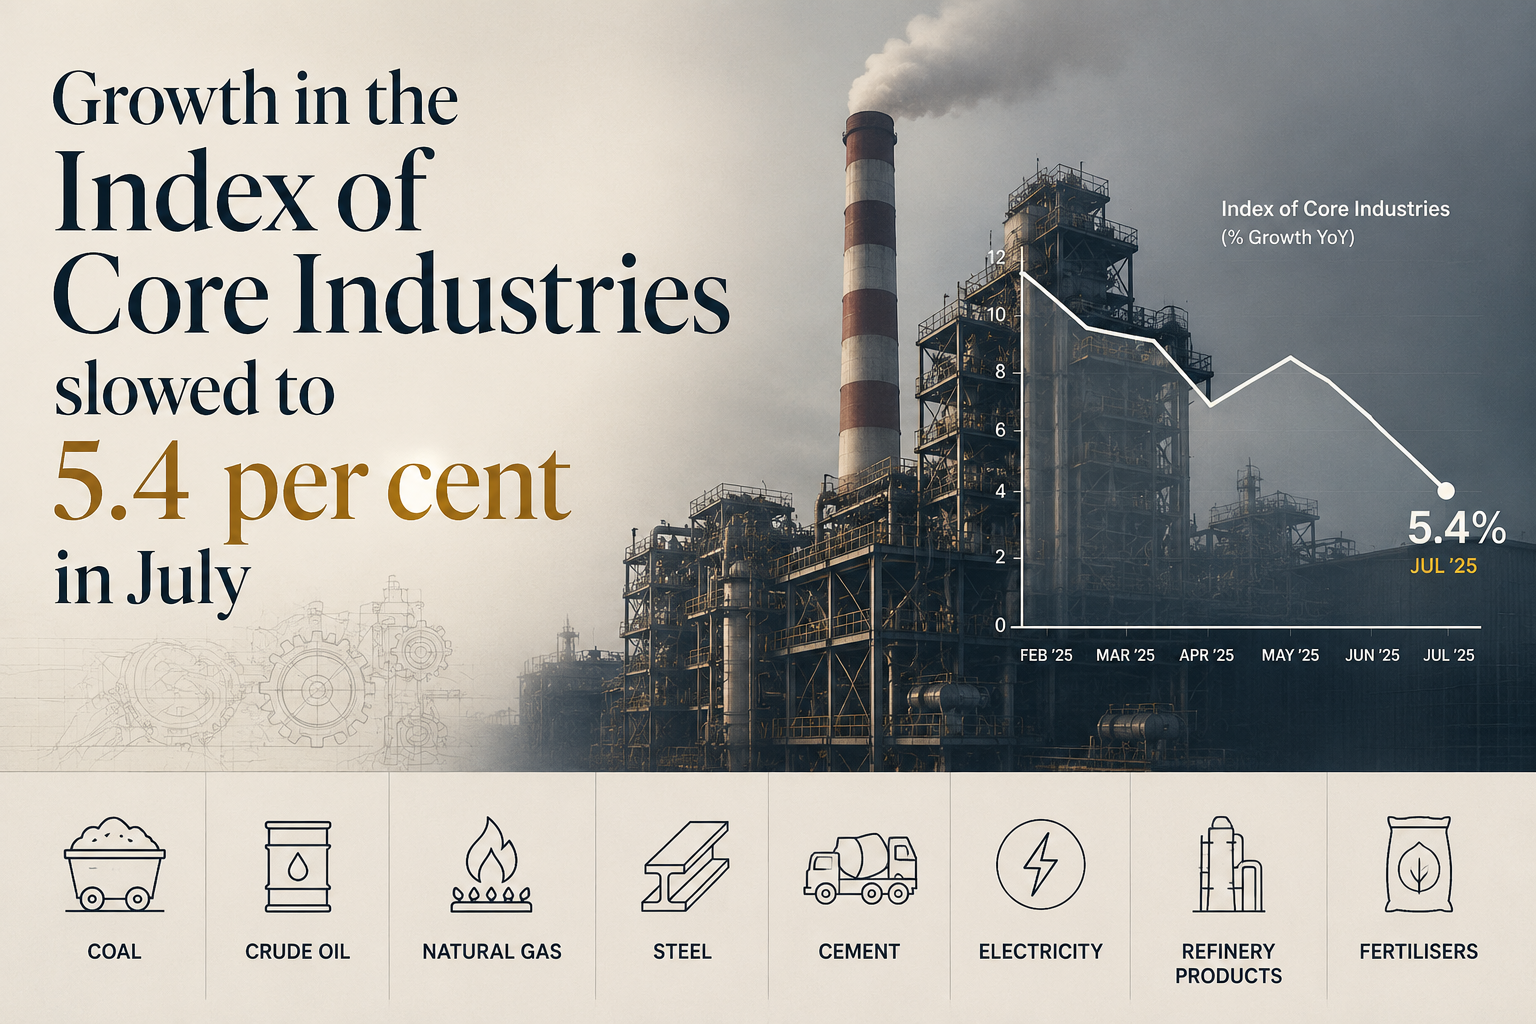
    Growth in the Index of Core Industries slowed to 5.4 per cent in July from 6 per cent in the previous month. The Manufacturing Purchasing Managers’ Index eased in the same month to its lowest level since August 2021, on weak domestic demand conditions. July’s core sector growth was still the second highest rate in the last seven months. The tension sits between that headline and its composition: a large part of the growth rests on a statistical low base effect, the two genuinely strong sectors are cement and electricity, and the domestic crude oil and natural gas sectors have contracted continuously for at least the last 14 months.

    What is the Index of Core Industries?

    • What it measures: The Index of Core Industries measures the combined production of the country’s core infrastructure industries, covering coal, crude oil, natural gas, refinery products, fertilisers, steel, cement and electricity.
    • Why it is watched: These industries carried a combined weight of about 40 per cent in the Index of Industrial Production, so the core index acts as an early read on industrial output before the fuller index is released.
    • Current series: The index is compiled on a revised new series, for which comparable data currently extends back only about 14 months.

    Why is the July core sector number weaker than it looks?

    • Growth rests on a low base: A large part of even this slower growth is based on a statistical low base effect, where a contraction in the corresponding month of the previous year makes the current month’s output look like expansion.
    • Coal illustrates the effect: The coal sector grew at an 11 month high of 7.6 per cent in July. That was measured against a contraction of 12.3 per cent in July of last year.
    • Refinery products repeat the pattern: The refinery products sector snapped a three month streak of contraction to grow at 2.7 per cent. This too was measured against a contraction in July 2025.
    • Iron ore’s strength is partly base driven: The iron ore sector grew at 29.5 per cent, slower than 44.5 per cent in June. Its comparison base is contractions of 16.4 per cent in June and 7.1 per cent in July of last year.
    • The headline flatters the trend: A rate that is second highest in seven months coexists with an easing demand signal, which means the ranking of the number matters less than what produced it.

    Which sectors are carrying the index and which are dragging it?

    • Steel has slowed sharply: The steel sector decelerated to 2.9 per cent in July from 5.6 per cent in June and 15.7 per cent in July of last year. This is a genuine slowdown rather than a base effect.
    • Hydrocarbons are a standing drag: The domestic crude oil and natural gas sectors have contracted continuously for at least the last 14 months for which the new series has data.
    • Electricity remains strong but is decelerating: The electricity sector grew at 9 per cent in July. That was slower than two consecutive months of double digit growth in May and June, which were lifted by prevalent heatwave conditions in many parts of the country.
    • Cement accelerated: The cement sector sped up to 13.1 per cent, the clearest genuine acceleration in the index.
    • The bright spots are only two: Within the core index, cement and electricity were the only two sectors reading as bright spots, and such positive trends were few and far between.

    Does the core sector number describe output or demand?

    • The two indicators point in opposite directions: The core index recorded its second highest growth in seven months in the same month that the Manufacturing Purchasing Managers’ Index fell to its lowest since August 2021.
    • They measure different things: The core index counts physical production in a set of infrastructure industries. The Manufacturing Purchasing Managers’ Index records what purchasing managers report about new orders and demand conditions.
    • A base effect can mask a contraction: A sector recovering from a deep fall registers a high growth rate at a low level of output, so a rate can rise even as demand conditions ease.
    • Weather and construction are not demand: The strongest readings came from electricity, lifted by heatwave conditions, and from cement, which tracks construction activity rather than broad consumer demand.
    • The forward reading is slack: Easing demand conditions were already being predicted by other indicators before the core sector data appeared, so the July slowdown was not a surprise.

    How is energy import dependence turning into a cost shock?

    • Import volumes are rising: India’s crude oil imports rose 13.3 per cent in volume terms in July. Liquefied Natural Gas (LNG) imports grew a more marginal 1.5 per cent.
    • Domestic supply is not filling the gap: Against the falling domestic base noted above, the economy’s appetite is being met from abroad rather than from home production.
    • The bill has jumped: High oil prices meant the crude oil import bill jumped 41 per cent in July, so a 13.3 per cent volume rise translated into a far larger payment outgo.
    • A tariff shock is queued behind it: The 100 per cent tariffs the United States is preparing to levy on countries such as India that import Russian oil will once again burden Indian exporters.
    • Blending has not yet displaced imports: Moving to 20 per cent ethanol blending has not yet impacted oil imports materially, so the substitution effect is not visible in the July numbers.

    Challenges to the Index of Core Industries as a growth signal

    • Base effects distort the headline rate: A contraction in the year ago month converts a modest recovery into a high growth print, which misleads on the level of output. Eg. Coal’s 11 month high of 7.6 per cent in July sat on a 12.3 per cent contraction in July of the previous year. Fix. Publish index levels and two year compound rates alongside the year on year rate in every release.
    • Coverage is narrow: The index tracks a small set of infrastructure industries and therefore misses most of the economy’s output. Eg. Services contribute over half of Gross Value Added and are entirely outside the core index. Fix. Publish the core index alongside a high frequency services activity indicator so the composite reading is visible.
    • Weights favour public sector heavy industries: The largest weights sit in sectors dominated by public enterprises and administered pricing, so the index responds to policy decisions as much as to market demand. Eg. Refinery products and electricity output move with administered allocation and tariff decisions. Fix. Rebase and reweight the index on a fixed cycle with published sensitivity of the headline to each sector’s weight.
    • Informal and small firm output is invisible: Production by micro and small enterprises is not captured, so a squeeze concentrated there does not register. Eg. Of about 64 million micro, small and medium enterprises, only around 14 per cent have access to formal credit and most stay outside statistical registers. Fix. Link the index to Goods and Services Tax e-way bill and electronic invoice data to capture small firm activity.
    • Provisional data is heavily revised: Early estimates are released on partial returns and are revised in later months, so a policy read taken on the first print can reverse. Eg. Iron ore’s July reading of 29.5 per cent followed a June figure of 44.5 per cent, a swing large enough to change the quarterly picture on revision. Fix. Publish a standing revision history for each sector so the reliability of the first print is visible.
    • It reads supply, not demand: The index counts what was produced, not what was bought, so it can rise while orders fall. Eg. July’s core growth of 5.4 per cent coincided with the Manufacturing Purchasing Managers’ Index at its weakest since August 2021. Fix. Present the core index and the demand side survey indicators in a single monthly dashboard rather than as separate releases.

    Conclusion

    The Indian economy looks set for a period of slack demand, higher costs and moderating growth. The July core sector reading does not contradict that: a large part of its growth is base driven, only cement and electricity grew genuinely strongly, and the sectoral spread set out above is narrow. The cost side is worsening independently, on the import bill and the tariff exposure already recorded. Whether the next few months show a genuine industrial recovery depends on domestic demand rather than on the base against which growth is measured.

    Industrial Growth in India

    • Manufacturing’s share is stuck: Manufacturing contributes around 17 per cent of Gross Domestic Product (GDP), far below the 25 per cent target set under Make in India.
    • Global standing: India holds about 2.8 per cent of global manufacturing output against China’s roughly 29 per cent, with domestic manufacturing output nearing $1 trillion in 2025-26.
    • Concentration: Maharashtra, Gujarat and Tamil Nadu account for about 40 per cent of net value added in manufacturing, and half the States have no operational Special Economic Zone.

    Government Initiatives for Industrial Growth

    • National Manufacturing Mission: Announced in the 2025-26 Budget, it unifies manufacturing policy and targets a 25 per cent GDP share with 143 million jobs by 2035.
    • Production Linked Incentive Scheme: Covers 14 sunrise and strategic sectors with outcome linked incentives, drawing over ₹1.76 lakh crore in committed investment as of March 2025.
    • Semiconductor Mission: A ₹76,000 crore framework under which 10 projects worth about ₹1.60 lakh crore have been approved.
    • Industrial Corridors Programme: India approved 11 corridors covering 32 projects, with 12 new industrial nodes cleared in 2024 for plug and play industrial cities.

    Challenges in Industrial Growth

    • Compliance load falls on small firms: Micro, small and medium enterprises face over 1,450 annual compliances, which consumes management time that would otherwise go into expansion. Eg. Annual compliance costs for such firms run to ₹13 lakh to ₹17 lakh. Fix. Adopt third party certification in place of repeat inspections, as the Ajay Shankar Committee recommended.
    • Regional concentration leaves capacity idle: Industrial value added clusters in three States, so national incentives do not translate into national capacity. Eg. Half of India’s States have no operational Special Economic Zone. Fix. Weight central incentive disbursal toward States below the national share of net value added.
    • Technology transition is slow in strategic segments: Domestic capability lags in electronics, semiconductors and renewable energy components, which keeps high value assembly abroad. Eg. India remains heavily dependent on imports for semiconductors and advanced electronic components. Fix. Extend Production Linked Incentives to upstream segments such as advanced materials and green hydrogen rather than final assembly alone.
    • Credit does not reach small manufacturers: Formal finance is unavailable to the great majority of small firms, so they cannot fund the fixed capital that raises productivity. Eg. The unmet credit demand of the micro, small and medium enterprise sector is estimated at about ₹20 lakh crore to ₹25 lakh crore. Fix. Expand cash flow based lending against Goods and Services Tax returns rather than collateral based assessment.
    • Trade barriers raise export uncertainty: Tariff action by large markets can remove the price advantage of an entire export segment without notice. Eg. The United States imposed a 50 per cent tariff in August 2025, hitting about 55 per cent of India’s exports to that market. Fix. Deepen global value chain participation through trade agreements and diversify destination markets under a China plus one strategy.
  • Sealed for 70 years, what BHU found inside 22 boxes from a Varanasi dig

    Sealed for 70 years, what BHU found inside 22 boxes from a Varanasi dig

    Why in the News

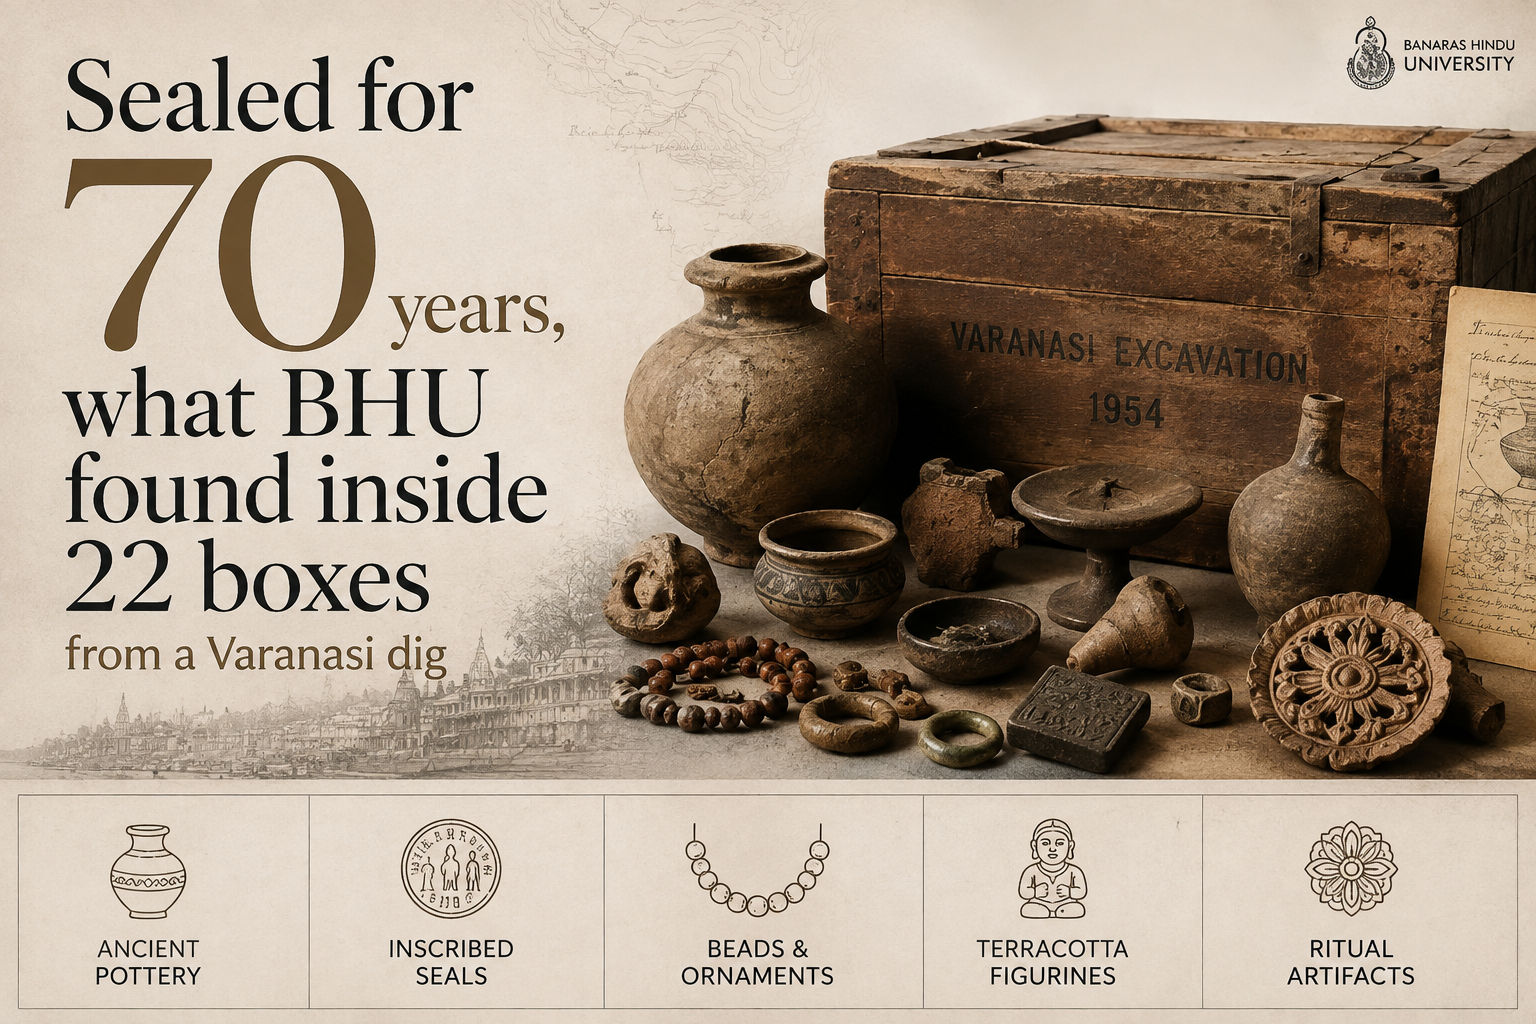
    Banaras Hindu University (BHU) opened 22 boxes on 20 August 2026 that had lain unopened for nearly 70 years, and found more than 10,000 artefacts, including painted black pottery believed to be nearly 3,000 years old.

    What is the Rajghat archaeological site?

    1. Location: Rajghat lies on the north-eastern edge of Varanasi, near the confluence of the Ganga and the Varuna rivers.
    2. Significance: It is one of the most important archaeological sites in the middle Ganga Valley.
    3. Historical identity: The area was part of ancient Varanasi, which served as the capital of the Kashi kingdom, also known as the Kashi Mahajanapad.
    4. Chronology: Archaeologists have divided the history of the site into six cultural periods, beginning around 800 BC and continuing up to the medieval period.

    What did the 22 boxes contain?

    1. The artefact count: The boxes held more than 10,000 artefacts in total.
    2. The dating anchor: Among them is painted black pottery believed to be nearly 3,000 years old.
    3. The object categories: The boxes contain sculptures, ancient coins, tools, stamp seals and objects made of copper, ivory and bone.
    4. A separate photographic archive: They also held around 3,000 glass slides and more than 5,000 photographic negatives documenting archaeological sites across India, including Rajghat, Manjhi, Ratnagiri, Ajanta and Ellora.
    5. Rare images within the archive: The photographs include rare images of idols of Vishnu, Shiva and Buddha, which are being examined and will be restored as part of the department’s conservation work.
    6. The condition of the containers: The trunks were found in an advanced state of deterioration, which makes the recovery and preservation of the material inside particularly significant.

    Why do the seals and inscriptions matter?

    1. Inscribed seals are present: Several of the seals recovered bear inscriptions, including some written in the Brahmi script.
    2. Who will read them: Researchers specialising in epigraphy at BHU will study them, and experts from other universities may be consulted where specialised expertise is required.
    3. What they can establish: The inscriptions can help researchers understand the scripts, systems of governance, and trade and economic systems of the periods in which they were used.
    4. Seals settled the site’s identity earlier: During the earlier excavations, seals and sealings bearing the name ‘Varanasi’ were found, and these findings helped establish the site’s connection with ancient Varanasi.

    Why did the material stay unstudied for 70 years?

    1. The site was found by accident: The first archaeological remains at Rajghat were discovered in 1939 during the expansion of the Kashi railway station, and were sent to the ASI for examination.
    2. The excavation ran for twelve years: Excavations were carried out jointly by the ASI and BHU between 1957 and 1969, under the supervision of BHU Professor A K Narain and the archaeologist T N Roy.
    3. What the excavations found: They unearthed remains of ancient settlements, including structures believed to be houses, terracotta objects, seals and other artefacts, which allowed researchers to trace the development of human settlement at Rajghat over several centuries.
    4. Documentation stopped short of study: Professor Narain documented the excavations in four volumes, and a large part of the material recovered was not studied in detail.
    5. The techniques did not exist then: The Vice-Chancellor noted that the objects were excavated at a time when advanced scientific techniques for archaeological research were not available in India.

    What happens to the material now?

    1. Three research teams have been formed: The department has constituted three specialised research teams to conserve and document the material.
    2. The stated purpose: The department has undertaken advanced research on its archaeological collections to allow scholars to reassess historical chronologies and produce new insights into ancient Indian civilisation.
    3. A parallel recovery is already under way: A month earlier, experts opened a box containing a human skeleton recovered from the same site, which had also remained sealed for around 70 years.
    4. Ancient DNA work has begun: A team specialising in ancient DNA collected samples from that skeleton for genetic and bio-archaeological analysis.
    5. What that analysis is expected to yield: The analysis is expected to provide clues about the people who lived in Varanasi around 1,000 years ago.

    “[2024] Consider the following information:

    Archaeological Site :: State :: Description

    1. Chandraketugarh : Odisha : Trading Port town

    2. Inamgaon : Maharashtra : Chalcolithic site

    3. Mangadu : Kerala : Megalithic site

    4. Salihundam : Andhra Pradesh : Rock-cut cave shrines

    In which of the above rows is the given information correctly matched?

    (a) 1 and 2 only

    (b) 2 and 3 only

    (c) 3 and 4

    (d) 1 and 4

  • The personalised vaccine that could cut skin cancer death risk

    The personalised vaccine that could cut skin cancer death risk

    Why in the News

    A new personalised cancer vaccine, intismeran, administered alongside the immunotherapy drug Keytruda, has been shown in Phase 3 results to reduce the risk of death from the recurrence and spread of skin cancer.

    How does intismeran work?

    1. Step one, read the tumour: The therapy begins by identifying the mutations, called neoantigens, in a sample of the patient’s own tumour.
    2. Step two, build the instruction set: A vaccine is then made of synthetically developed messenger RNA (mRNA), a single stranded molecule that carries genetic instructions from DNA in the cell nucleus and tells the cell which proteins to make. Each treatment consists of mRNA coding for 34 such neoantigens.
    3. Step three, administer and translate: Once administered, the body generates these proteins from the mRNA instructions.
    4. Step four, present to the immune system: The body then presents those proteins to the immune system, which is trained to recognise them as belonging to the cancer.

    Why must a cancer vaccine be personalised?

    1. Neoantigens exist only on cancer cells: Neoantigens are proteins found only on the cancerous cells, which the body’s immune system can be trained to recognise.
    2. They differ from patient to patient: These neoantigens vary from person to person, so they become an identifier for that individual’s cancer and cannot be mass produced as a single formulation.
    3. The principle is the same as any vaccine: A vaccine for an infectious disease contains the antigen from a pathogen, the proteins or lipids that train the immune system to recognise and fight it, and this therapy contains cancer neoantigens instead.
    4. The benefit is immunological memory: The cancer’s fingerprint enters the immune system’s memory, so if the cancer returns the body can recognise it immediately and mount a response, prolonging recurrence free survival.
    5. A decade of work behind one result: Work on this approach has run for around a decade, and this is the first clinical breakthrough.

    What did the Phase 3 study find?

    1. Death risk from recurrence fell: When the vaccine was given with Keytruda, the risk of death owing to recurrence of skin cancer went down by 49 per cent.
    2. Death risk from spread fell further: The risk of death owing to the cancer spreading went down by 59 per cent.
    3. The comparison arm matters: Both results are measured against treatment with Keytruda alone, not against no treatment.
    4. The comparison arm is already strong: Keytruda (pembrolizumab, a checkpoint inhibitor that blocks the PD-1 receptor cancer cells use to switch off the immune response against them) has over the years been shown to be much more effective in treating certain cancers than traditional chemotherapy, so the gain sits on top of an established benchmark.
    5. Side effects were mild: The most common side effects noted in the study were fatigue, injection site pain and chills.

    What does this mean for India?

    1. Reason one, the disease is rare here: Melanoma is one of the most common types of cancer in the caucasian population, and is not commonly seen among Indians.
    2. The share is a fraction of a per cent: Globocan, short for Global Cancer Observatory, an online platform that maintains cancer statistics, shows that melanoma accounts for only 0.26 per cent of all cancer cases in India and 0.17 per cent of deaths.
    3. Reason two, cost: Most patients in India are unable to afford Keytruda even with patient assistance programmes, and a combination therapy compounds a barrier that already exists for the immunotherapy alone.
    4. Access to immunotherapy is already narrow: A real world study from Tata Memorial Hospital showed that only 1.6 per cent of the patients who need such immunotherapy are able to access it.

    Challenges to personalised mRNA cancer vaccines

    1. Every dose is a separate manufacturing run: The vaccine must be sequenced, designed and produced per patient, so the process cannot be batched and the turnaround competes with tumour progression. Eg. Each treatment encodes 34 neoantigens specific to one person’s tumour. Fix. Build automated, closed-system manufacturing units co-located with cancer centres, on the model already used for cell therapy production.
    2. Cost scales with individualisation: A therapy that cannot be mass produced carries no volume discount, so the price gap over a standard drug widens rather than narrows with adoption. Eg. Even the standard companion immunotherapy reaches only 1.6 per cent of Indian patients who need it. Fix. Negotiate outcome linked pricing, where payment is tied to recurrence free survival achieved rather than to doses supplied.
    3. Cold chain requirements restrict reach: mRNA products require ultra-low temperature storage and transport, which most Indian district level oncology facilities do not have. Eg. Covid-19 mRNA vaccines were never widely deployed in India partly for this reason. Fix. Extend the cold chain built for the universal immunisation programme with ultra-low temperature capacity at regional cancer centres before such therapies are introduced.
    4. Tumours can escape the target: Cancer cells can lose the targeted antigen over time, which is the known failure mode of antigen directed immunotherapy. Eg. Relapse through antigen escape is documented in CAR-T cell therapy for blood cancers. Fix. Design vaccines against multiple conserved neoantigens and pair them with checkpoint inhibitors, so escape from one target does not end the response.
    5. Regulatory pathways assume a fixed product: Approval systems are built to assess an identical formulation across a trial population, while each dose here differs by design. Eg. India’s biotechnology approvals are already split across the Department of Biotechnology, the drug regulator and the environment ministry. Fix. Create a platform approval route that licenses the manufacturing process and the design algorithm rather than each individual product.
    6. The evidence is disease specific: The result is established for melanoma alone, and benefit in the cancers that dominate India’s burden is not demonstrated. Eg. Melanoma is 0.26 per cent of Indian cancer cases while breast, oral and cervical cancers account for the bulk. Fix. Prioritise Indian participation in trials of the same platform for oral, breast and cervical cancers, so approval evidence is generated on the local disease profile.

    Conclusion

    A personalised mRNA vaccine has for the first time produced a meaningful clinical benefit in cancer, cutting the risk of death from recurrence by 49 per cent and from spread by 59 per cent when added to an existing immunotherapy. The result validates the principle that a therapy can be built against each patient’s own tumour mutations rather than against a disease in general. For India the immediate impact is limited, because melanoma is rare here and the companion drug reaches under two per cent of the patients who need it. The question that remains open is whether the platform is extended to the cancers that actually dominate India’s disease burden.

    “[2022, GS3, 15 marks] What is the basic principle behind vaccine development? How do vaccines work? What approaches were adopted by the Indian vaccine manufacturers to produce COVID-19 vaccines?”

  • What India can learn from EU’s AI reset

    What India can learn from EU’s AI reset

    Why in the News

    The European Union’s Artificial Intelligence (AI) Omnibus entered into force on 27 July 2026 and changes parts of the European Union Artificial Intelligence Act, 2024 (EU AI Act). It extends some deadlines, simplifies some compliance requirements and gives regulators and companies more time to prepare for the high-risk AI rules.

    What is the EU AI Act’s risk-based framework?

    1. The organising principle: The Act sorts AI systems by the level of risk they pose and attaches obligations to each tier. The regulatory burden rises with the potential for harm rather than with the technology used.
    2. The prohibited tier: Some AI practices are prohibited outright under the Act. No compliance route is available for a practice in this category.
    3. The high-risk tier: High-risk systems face strict obligations before and during deployment. These are the obligations whose preparation deadlines the Omnibus has extended.
    4. General-purpose models: General-purpose AI models, meaning models trained broadly and adaptable to many downstream tasks rather than built for one application, came under a specific set of rules. They are governed separately from the risk tiers that apply to particular deployments.

    What does the AI Omnibus change, and why now?

    1. The instrument and its date: The AI Omnibus entered into force on 27 July 2026. It amends parts of the AI Act rather than replacing the framework.
    2. Deadlines extended: Some compliance deadlines under the Act have been pushed back. Regulators and companies have more time to prepare for the high-risk AI rules.
    3. Compliance simplified: Some compliance requirements have been simplified. The obligations themselves remain in place at their existing levels.
    4. The reason stated: Implementation of the original framework proved difficult in practice. The Omnibus is the EU’s response to that implementation experience rather than to a change in the risk assessment.
    5. How it is characterised: The change is an admission that AI is changing faster than laws can normally change. It demonstrates that even a carefully designed regulation must be capable of adjustment.

    What are the five lessons for India?

    1. Regulation must be capable of learning: Technology changes and risks change, so regulators must have the ability to review and adjust rules. Regulation should be treated as a continuing process rather than a single enactment.
    2. Regulation needs an escape valve: Rules work only where regulators and companies have the capacity to implement them. India should consider regulatory sandboxes and regular reviews of AI rules, and sunset mechanisms could make regulation more responsive.
    3. Compliance cost decides who can compete: Large technology companies can hire lawyers, engineers and auditors, and start-ups cannot always do so. Excessive compliance costs could unintentionally favour large companies and reduce competition.
    4. Simplification must not mean deregulation: Reducing paperwork is different from reducing safeguards. AI can create serious risks involving privacy, discrimination, manipulation and opaque decision-making, and simpler regulation must not mean weaker protection.
    5. Institutional maturity is the fifth lesson: The EU has shown that even a major regulatory framework can be revised after enactment. Regulatory maturity means recognising when rules are not working and changing them.

    Where does India’s AI governance currently stand?

    1. A different path so far: India has focused on responsible AI, innovation and sector-specific governance rather than creating a comprehensive AI law. Sectoral regulators apply existing mandates to AI within their own domains.
    2. Flexibility carries a cost: Flexibility can be useful and it should not become uncertainty. Businesses need clarity, citizens need protection and regulators need clear responsibilities.
    3. The proportionality principle India would need: The regulatory burden should depend on potential harm. The greater the risk to people and society, the stronger the safeguards should be.
    4. The assets India brings: India has a large digital population and experience with digital public infrastructure. It also has a growing technology sector and experience in deploying digital services at scale.
    5. The institutions available to build on: The IndiaAI Mission can play an important role in an adaptive Indian model of AI governance. Regulatory sandboxes, sectoral regulators, research institutions and industry bodies can carry the rest.

    Is regulation genuinely a trade-off against innovation?

    1. The framing the debate defaults to: The debate over AI is often presented as a choice between regulation and innovation. That framing treats every safeguard as a cost to be traded away.
    2. Why the framing is wrong: The choice is false because unregulated deployment carries its own costs in privacy, discrimination and opaque decision-making. The challenge is to design regulation that makes innovation safer and more trusted.
    3. What the EU revision actually demonstrates: The EU relaxed timelines and paperwork and did not relax the substantive safeguards. The revision therefore tests the trade-off framing and does not confirm it.
    4. The asymmetry the framing hides: Compliance cost falls hardest on the smallest firms, so heavy regulation reduces competition and light regulation reduces protection. India must create a framework that protects citizens while allowing experimentation, and be capable of changing as technology changes.

    Challenges to a risk-based AI law in India

    1. Risk tiers age faster than statutes: A fixed list of prohibited and high-risk uses is overtaken by capabilities that did not exist when the list was drawn. Eg. General-purpose models required a separate rule set in the EU Act after the original risk-tier design was settled. Fix. Place the risk classification in delegated rules subject to a mandatory periodic review rather than in the parent statute.
    2. Regulatory capacity is the binding constraint: Enforcement requires auditors and technical staff who can inspect model behaviour, and those skills are scarce in the public sector. Eg. Implementation difficulty is the stated reason the EU extended its own high-risk deadlines. Fix. Build a shared technical audit facility under the IndiaAI Safety Institute that sectoral regulators can draw on.
    3. Algorithmic bias reproduces existing exclusion: Models trained on historical data encode the patterns of that data, including patterns of discrimination. Eg. An automated recruitment system built at Amazon was found to downgrade applications from women. Fix. Mandate pre-deployment bias testing and published audit results for any system used in employment, credit or welfare decisions.
    4. The accountability gap in automated decisions: It is often unclear who is answerable for an AI-driven decision, the developer, the deployer or the administrator. Eg. A welfare eligibility system can deny a benefit without producing a reason the applicant can contest. Fix. Impose a statutory right to an explanation and to human review for any automated decision affecting a legal right or entitlement.
    5. Compute and data concentration: AI capability is concentrated in a few advanced economies, which leaves other countries as consumers rather than creators of the technology. Eg. India’s response has been a national compute grid of over 38,000 graphics processing units under the IndiaAI Mission. Fix. Treat compute, datasets and models as shared developmental resources with subsidised access for start-ups and researchers.

    Conclusion

    The EU has demonstrated that a comprehensive AI framework can be enacted and then revised when implementation shows it is not working, and the AI Omnibus of 27 July 2026 is that revision. Its lesson for India is not that regulation should be lighter but that it should be capable of learning, proportionate to harm, affordable for small firms and explicitly separate from deregulation. India has no comprehensive AI law and has the digital public infrastructure, the sectoral regulators and the IndiaAI Mission to build an adaptive one. What remains unresolved is whether India converts its current flexibility into a stated framework with clear responsibilities, or leaves it as uncertainty that businesses and citizens both bear.

    Government Initiatives on Artificial Intelligence

    1. IndiaAI Mission, 2024: Approved with an outlay of ₹10,371 crore and implemented by IndiaAI under the Ministry of Electronics and Information Technology. Its stated vision is making AI in India and making AI work for India, delivered through seven pillars.
    2. IndiaAI Compute and AIKosh: The compute pillar operates a national AI compute grid with over 38,000 graphics processing units at up to 40 per cent lower cost for eligible users. AIKosh is the national dataset repository with over 3,000 datasets and 243 models across 20 sectors.
    3. IndiaAI Foundation Models and FutureSkills: The foundation models pillar supports indigenous multimodal models built by entities including Sarvam AI and Gnani AI. FutureSkills funds fellowships and AI labs with a focus on Tier-2 and Tier-3 cities.
    4. Safe and Trusted AI: This pillar covers bias mitigation, privacy, explainability and AI governance, and it established the IndiaAI Safety Institute as a national trust framework. NITI Aayog’s Responsible AI for All initiative runs alongside it on public discourse and ethical audits.
    5. Language and access platforms: Digital India Bhashini provides speech and translation tools across 22 Indian languages, and Project Vaani has assembled a 150,000 hour Indian speech dataset. India hosted the India AI Impact Summit 2026 at Bharat Mandapam, the first major global AI summit in the Global South.

    “[2026] Which of the following statements with regard to Large Language Models (LLMs) used in machine learning is/are correct?

    1. LLMs assign probabilities to the next possible words and then pick the one with the highest probability.

    2. LLMs process data through mathematical optimization to minimise prediction errors.

    3. LLMs produce unbiased outputs.

    (a) 1 only

    (b) 1 and 2 only

    (c) 2 and 3 only

    (d) 1, 2 and 3

  • What changes when AI moves from reading viral genomes to designing them?

    Why in the News

    Researchers at Stanford University and the Arc Institute used Artificial Intelligence (AI) to design complete genomes of bacteriophages, viruses that infect bacteria. Of 285 AI-generated designs physically synthesised and tested in the laboratory, 16 produced functioning phages, and some overcame bacterial resistance that had defeated the original virus. Humans have been synthesising viral genomes and deliberately modifying viruses for decades, so what is new is not the physical manufacture of a virus. AI has entered the design stage of biology, deciding what the genome should be rather than executing a design a human specified. The tension is that the same capability that could transform antimicrobial resistance research, vaccines and therapeutics could also accelerate harmful biological engineering.

    What is a genome language model?

    1. What it is: A genome language model is a machine learning system trained on genetic sequence data rather than on text, and the two used in this experiment were Evo 1 and Evo 2.
    2. How it works: The principle resembles a large language model, except that instead of learning patterns in words, it learns patterns in DNA.
    3. What it reads: It studies the genetic alphabet of A, C, G and T across vast numbers of genomes, and then generates new genetic sequences from the patterns it has learned.
    4. How it was specialised: For this experiment the models were further trained on thousands of bacteriophage genomes related to ΦX174, so the sequences they generated stayed within a known biological family.

    What did the Stanford-Arc experiment actually do?

    1. The design step was handed over: The scientists already knew the ΦX174 genome and already knew how to synthesise viral DNA and recover functioning phages. What changed was who, or what, proposed the genome.
    2. The output was constrained, not open-ended: AI did not invent a completely unrelated virus from nothing. It generated previously unseen ΦX174-like whole genomes within a known biological framework.
    3. The build step was conventional: Scientists selected some of these sequences, physically manufactured the DNA and introduced it into E. coli. Where the genetic instructions were biologically coherent, the bacterial machinery produced new phage particles.
    4. The yield: Of the 285 designs tested, 16 succeeded in producing functioning phages.
    5. Some designs beat the natural virus: Combinations of AI-designed phages overcame resistance in E. coli strains against which the original ΦX174 failed.
    6. The most significant result was combinatorial: An AI-designed phage successfully combined a viral protein with other genetic changes in a way conventional engineering had struggled to achieve, which suggests the system can identify multiple genetic changes that work together across an entire genome.

    How did biology get from reading genomes to writing them?

    1. Phages are old and abundant: Bacteriophages, literally “bacteria eaters”, have been known for more than a century and are among the most abundant biological entities in nature.
    2. Reading came first: In 1977, one particularly small phage, ΦX174, became the first complete DNA genome to be sequenced.
    3. Writing came next: By the early 2000s, scientists had shown that viral genetic material could be synthesised from known sequence information and used to recover functioning viruses.
    4. Deliberate modification followed: The controversial influenza gain-of-function experiments of 2011-12 showed that genetic changes could modify important properties such as transmission in experimental animals.
    5. The unresolved dilemma: That research highlighted a dilemma that remains open, since the same science that can improve pandemic preparedness may also create biosafety and biosecurity risks.
    6. Design is the fourth step: The progression runs from reading viral genomes, to writing them, to modifying them, and now to AI helping decide what should be written.

    What does this open up in medicine?

    1. Phage therapy is the nearest application: Antibiotic resistance is steadily eroding conventional treatment options, and bacteriophages offer another way of killing bacteria.
    2. Specificity is the limitation: A phage effective against one bacterial strain may fail against another, and bacteria can also develop resistance to phages.
    3. The search model has limits: Researchers have traditionally searched nature and phage libraries for suitable candidates, or modified existing viruses, which caps the available options at what already exists.
    4. The question changes: Generative biology moves medicine from asking whether the needed phage can be found to asking whether it can be designed.
    5. The applications extend well beyond phages: AI can assist the design of vaccine antigens, antibodies, therapeutic proteins and the viral vectors used to deliver genetic treatments, and may eventually help optimise oncolytic viruses that selectively attack cancer cells.
    6. The real shift is broader than viruses: The larger revolution is AI becoming capable of designing biological function, rather than AI making viruses.

    Is the simplicity of the target a safeguard, or is the risk the acceleration?

    1. The reassuring reading: ΦX174 is an exceptionally simple bacteriophage, while dangerous human viruses are vastly more complicated.
    2. Human pathogens are harder targets: They must negotiate receptor binding, host range, tissue tropism, replication, immune escape and transmission, each of which is a separate design problem.
    3. Complexity is not a defence: Human scientists already understand much about these determinants, and decades of virology, reverse genetics and gain-of-function research have linked many genetic changes to viral behaviour.
    4. AI does not need to rediscover virology: Its power lies in integrating what humanity already knows, examining vastly more combinations than humans can explore manually, and accelerating the path from hypothesis to experimental design.
    5. The concern is capability amplification: The relevant question is not whether an untrained individual can ask today’s chatbot to generate a pandemic virus. It is whether increasingly capable AI could make a knowledgeable and well-equipped laboratory substantially more effective at designing biological systems.
    6. A low success rate is a temporary comfort: The yield reported above is low, but digital systems can generate enormous numbers of candidates, so a low success rate is reassuring only while the number of attempts remains small.

    How must biosecurity change?

    1. Current screening looks for resemblance: Traditional DNA-synthesis screening often asks whether an ordered sequence resembles a known pathogen or toxin.
    2. Resemblance fails against generated sequences: A previously unseen sequence generated inside a known family may not resemble anything on a watchlist while still doing the same thing.
    3. Screening must move to function: In the age of generative biology, screening must also consider what a sequence might actually do, not simply whether it looks dangerous.
    4. Over-restriction has its own cost: Claude Fable 5 was initially deployed with strong safeguards around biology, chemistry and cybersecurity, and legitimate scientific work could sometimes trigger a fallback to a less capable model.
    5. The correction points to graduated access: Those safeguards have since been refined to reduce false-positive biology fallbacks while more sensitive capabilities remain restricted, which points toward graduated, auditable access under institutional and security controls.
    6. Model refusal is not a strategy: Biosecurity cannot rest entirely on what an AI model agrees or refuses to answer, so safeguards are needed throughout the chain: AI systems, DNA-synthesis providers, laboratories and institutional biosafety oversight.

    Why does this matter for India?

    1. Frontier AI becomes scientific infrastructure: If frontier AI becomes central to drug discovery, genomics, vaccines, protein engineering and experimental design, access to advanced AI becomes part of national scientific infrastructure.
    2. Sufficiency and compulsion are different things: Smaller and specialised models will be sufficient for many tasks, but a country should choose a small model because it is sufficient, not be forced to use one because somebody else owns the frontier.
    3. Restricted access compounds over time: If researchers elsewhere receive trusted access to highly capable biomedical models while Indian scientists depend on restricted public versions, the disadvantage accumulates across drug discovery, vaccines and antimicrobial resistance.
    4. The investment exists but needs a scientific arm: India is already investing through the IndiaAI Mission and indigenous foundation-model programmes, and that ambition should extend to scientific and biomedical AI, secure compute and high-quality datasets.
    5. Trusted access needs a framework: Legitimate researchers need a defined route to stronger capabilities, which requires an institutional trusted-access framework rather than case by case negotiation with model providers.
    6. The two goals are not separable: AI sovereignty without biosecurity would be reckless, and biosecurity without AI sovereignty could leave the country scientifically dependent.

    Challenges to AI-designed genomes

    1. Sequence screening cannot see intent: Order screening matches against known pathogen sequences, so a generated sequence within a benign-looking family passes even where its function is hazardous. Eg. Screening protocols built around named agents on an export control list match those names, so a functionally equivalent sequence outside the list is not flagged. Fix. Require DNA-synthesis providers to run function prediction alongside sequence matching, with a reporting duty on flagged orders.
    2. Automated laboratories compress the safety window: Combining generative design with robotic experimentation shortens the interval in which oversight can intervene. Eg. Future systems may compress months or years of literature review, modelling and experimental planning into much shorter cycles. Fix. Mandate institutional biosafety committee sign-off at the design stage rather than only before physical synthesis.
    3. Volume defeats low success rates: A weak per-attempt success rate becomes a strong aggregate capability once attempts are cheap and unlimited. Eg. The design pool in this experiment was generated computationally, so the number of candidates was bounded by compute rather than by laboratory effort. Fix. Impose volume-based reporting thresholds on synthesis orders from a single requester within a stated period.
    4. Model safeguards obstruct legitimate research: Blunt refusal policies block the research they were meant to protect, which pushes scientists toward unsupervised alternatives. Eg. Legitimate scientific queries triggered fallback to a less capable model under initial biology safeguards. Fix. Operate tiered credentials, where verified institutional researchers receive higher-capability access under audit logging.
    5. Governance is nationally fragmented: Biosecurity rules stop at borders while synthesis orders and model access do not. Eg. The 2011-12 gain-of-function controversy produced divergent national moratoria rather than a common standard. Fix. Negotiate a common minimum synthesis-screening standard through the Biological Weapons Convention review process.
    6. India lacks a biosecurity institution for generative biology: Existing oversight bodies were designed for genetically modified organisms and field trials, not for computational design of pathogens. Eg. The Genetic Engineering Appraisal Committee and the Review Committee on Genetic Manipulation are structured around organism release rather than sequence design. Fix. Create a statutory biosecurity review function covering generative design, synthesis orders and model access, reporting jointly to the Department of Biotechnology and the Ministry of Electronics and Information Technology.

    Conclusion

    The experiment does not show that AI can casually manufacture dangerous human viruses. It shows something more precise: computers are beginning to move from analysing biological information towards proposing biological designs that scientists can physically build, a capability that serves therapeutic research and harmful engineering alike. The answer is neither prohibition nor unrestricted access, but controlled acceleration, with safeguards rising as capability and risk rise. The unresolved question is no longer whether AI should be allowed to understand biology, but how to govern it once understanding biology becomes the ability to design it.

    Back2Basics: IndiaAI Mission

    1. What it is: The IndiaAI Mission is the national artificial intelligence programme approved in 2024 with an outlay of ₹10,371 crore, implemented by IndiaAI under the Ministry of Electronics and Information Technology.
    2. Its stated vision: “Making AI in India and Making AI Work for India”, built around seven pillars covering compute, applications, datasets, foundation models, skills, startup financing and safe and trusted AI.
    3. Compute pillar: It operates a national AI compute grid with over 38,000 graphics processing units, offering up to 40 per cent lower compute costs to eligible users.
    4. Safety arm: The IndiaAI Safety Institute is its national trust framework, covering bias mitigation, privacy, explainability and AI governance.

    Matching Previous Year Question

    “[2026] Which of the following statements with regard to genetic medicine is/are correct? 1. Genetic medicines correct/compensate for the faulty genes responsible for disease. 2. Engineered viruses and lipid nanoparticles are used as carriers of the genetic medicine. 3. Genetic medicines alter the entire DNA sequence. (a) 1 only (b) 2 and 3 only (c) 1 and 2 only (d) 1, 2 and 3 ANSWER: C”