💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Subject: Economics

  • Harvest the Odisha story to ensure food security


    IT-led transformation: Odisha's KALIA shows the way- The New Indian Express

    Central idea 

    Odisha’s agricultural transformation, exemplified by a shift from scarcity to surplus, stands as a model for climate-resilient and equitable food security. The state’s success lies in empowering small and marginal farmers, embracing crop diversification, and proactively addressing climate vulnerabilities.

    Key Highlights:

    • Odisha’s Agricultural Transformation: From importing rice to recording its highest food grain production in 2022, focusing on small and marginal farmers, and tripling average rice yield in two decades.
    • Resilience and Sustainability: Odisha’s proactive approach to climate change, developing a comprehensive Climate Change Action Plan covering various sectors, implementing climate-resilient cultivation practices, and adopting innovative measures for crop monitoring.
    • Social Protection: Odisha’s partnership with the United Nations World Food Programme, ranking as the top state in the National Food Security Act for 2022, and collaboration on food security, livelihood, and climate resilience initiatives.

    Key Challenges:

    • Climate Vulnerability: Odisha’s susceptibility to climate change impacts, including cyclones, floods, and droughts, posing risks to livelihoods and infrastructure.
    • Implementation Hurdles: The need for effective implementation of climate-resilient practices at the ground level, overcoming potential challenges in executing the Climate Change Action Plan.
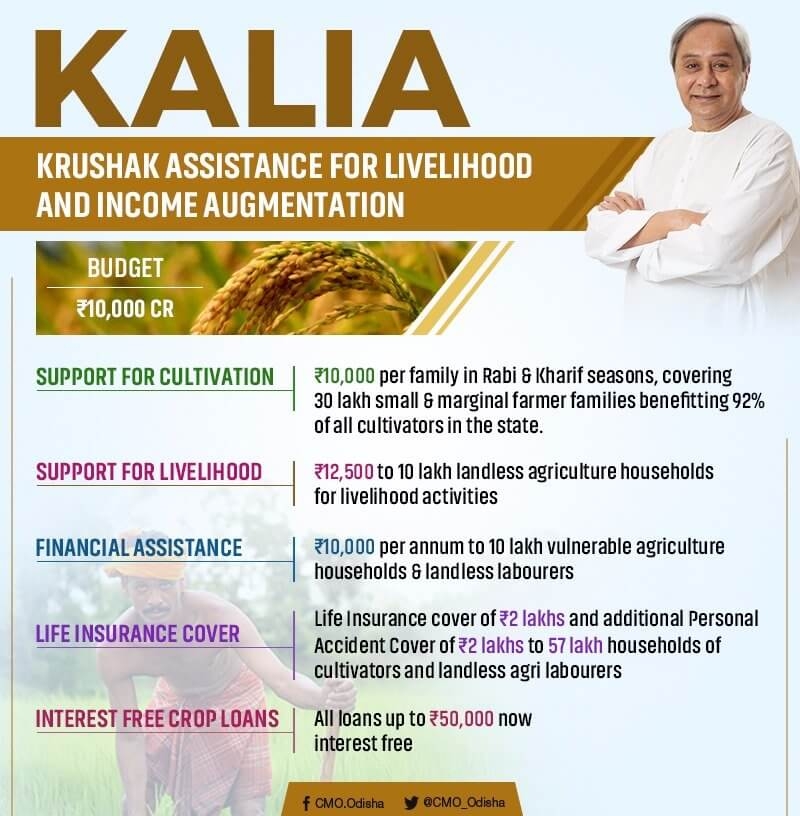
    Kalia Scheme Odisha

    Key Terms and Phrases:

    • Krushak Assistance for Livelihood and Income Augmentation (KALIA)
    • Odisha Millet Mission
    • Climate-resilient cultivation practices
    • Crop Weather Watch Group
    • Integrated farming
    • Zero-input-based natural farming
    • Biometric technology in the Targeted Public Distribution System
    • Rice fortification
    • National Food Security Act

    Key Quotes:

    • Odisha Chief Minister Naveen Patnaik: “Zero Hunger” goal commitment at the United Nations World Food Programme headquarters.
    • Anu Garg: “Odisha’s transformative journey presents a unique development model for other States in the context of the challenges of global climate change.”

    Key Statements:

    • Odisha’s transition from food grain scarcity to surplus, climate-proofing agricultural systems, and ensuring food and nutrition security for vulnerable populations.

    Key Examples and References:

    • Use of biometric technology in the Targeted Public Distribution System in Rayagada district.
    • Rice fortification initiatives in Gajapati district.

    Key Facts and Data:

    • Odisha’s contribution to India’s rice production, ranking as the top state in the National Food Security Act for 2022.

    Critical Analysis:

    • Odisha’s success in achieving surplus production and resilience can serve as a model for other states facing similar challenges.
    • The effectiveness of climate-resilient practices and the Climate Change Action Plan in mitigating climate risks need continuous evaluation.

    Way Forward:

    • Scaling Successful Initiatives: Expanding successful schemes like KALIA and promoting crop diversification to enhance resilience.
    • Technological Integration: Continued integration of technology in agriculture for monitoring, early warning systems, and precision farming.
    • International Collaboration: Strengthening partnerships with international organizations for knowledge exchange and resource mobilization.
  • Controversy over Germany’s Debt Brake Rule

    Central Idea

    • On November 15, Germany’s constitutional court declared the government’s reallocation of €60 billion to a “climate and transformation fund” (KTF) as unlawful.

    Understanding the Debt Brake Rule

    • Definition and Purpose: The debt brake rule caps government borrowing and restricts the federal government’s fiscal deficit to 0.35% of GDP, while prohibiting deficit spending by Germany’s 16 regions.
    • Enactment: This rule was incorporated into German law in 2009 by a coalition, mirroring the EU’s Stability and Growth Pact and the 2012 Fiscal Compact Treaty.

    Legal Challenge and Its Implications

    • Opposition’s Argument: It argued that climate change and energy transition investments, being long-term, shouldn’t be funded by the debt brake’s emergency exemption, which was specific to COVID-19 relief.
    • Government’s Defense: The government contended that the reallocated funds addressed economic consequences of the pandemic by linking investment shortfalls to COVID-19’s economic impact.

    Germany’s Post-2009 Economic Performance

    • Mixed Outcomes: Germany experienced growth and budget surpluses in the last decade, benefiting from low-interest policies of the ECB.
    • Zero-Deficit Budget: The government achieved a zero-deficit budget, promoting it as an ideal approach for the EU during a sovereign debt crisis.
    • Challenges and Criticisms: A cooling economy highlighted under-investment in infrastructure. Critics urged for expansionary fiscal measures, while others favored higher taxation. Chancellor Angela Merkel emphasized the need to avoid burdening the younger generation with debt.
    • Pandemic Response: In 2020, the debt brake rule was suspended for pandemic-related borrowing, with plans for reinstatement.
  • Calibrating a strategy for India’s future growth

    India's economic growth may slow down to 7.3 per cent in 2019: Moody's -  The Hindu BusinessLine

    Central idea

    The passage discusses India’s growth prospects amidst global challenges, emphasizing the need for a recalibrated growth strategy due to deglobalization trends. It highlights the shift from an export-led approach, focusing on domestic drivers and the importance of sustaining domestic savings and investment rates for a 7% plus real growth.

    Key Highlights:

    • Growth Projections: India’s growth for 2023-24 projected by RBI at 7%, IMF and World Bank at 6.3%. Strong performance in the first two quarters supports the likelihood of meeting the RBI’s projection.
    • Deglobalization Impact: Geopolitical conflicts and deglobalization trends pose challenges, affecting supply chains, international settlements, and global demand for exports.
    • Export-led Growth Shift: India’s export-led growth strategy faces challenges as the share of GDP from exports fluctuates, prompting a need for a recalibrated growth strategy.

    Key Challenges:

    • Dependence on Global Exports: Challenges arise from reduced global demand, disruptions in supply chains, and geopolitical conflicts impacting international settlements.
    • Domestic Savings Concerns: A decline in household sector savings poses a risk to India’s growth potential, potentially affecting resources available for government and corporate investment.

    Key Terms and Phrases:

    • Deglobalization: Movement away from global interconnectedness.
    • Incremental Capital-Output Ratio (ICOR): The amount of capital required for an additional unit of output, influencing achievable growth.
    • Periodic Labour Force Survey (PLFS): Source of data on employment trends and ratios.

    Key Quotes:

    • “Many ongoing geopolitical conflicts… have created a climate of sanctions.”
    • “India will have to rely relatively more on domestic growth drivers.”
    • “Facilitating absorption of productivity-enhancing technologies… would add to overall growth.”

    Key Examples and References:

    • Export Growth: Fluctuations in export share from 2003-04 to 2022-23 highlight the challenges of sustaining an export-led growth strategy.
    • Labour Force Trends: PLFS data indicates an increase in the worker population ratio but emphasizes the need for high non-agricultural growth to absorb released labor from agriculture.

    Key Facts and Data:

    • Nominal Saving Rate: Estimated at 29% in 2022-23, highlighting the critical role of domestic savings.
    • Nominal Investment Rate: Around 29% in 2022-23, with a need to increase to 35% for sustained growth.

    Critical Analysis:

    • Dependency on Global Conditions: The passage stresses the impact of changing global conditions on India’s growth strategy, urging a shift towards domestic drivers.
    • Savings and Investment Link: Emphasizes the importance of domestic savings in supporting a 7% plus real growth, highlighting concerns about a fall in household sector savings.

    Way Forward:

    • Enhanced Employment Strategies: Allocation of resources for training and skilling India’s growing working-age population is crucial.
    • Climate-Friendly Growth: Mitigate adverse impacts on potential growth by emphasizing service sector growth, known for being relatively climate-friendly.
    • Fiscal Responsibility: Adherence to fiscal responsibility targets is critical for sustaining growth, reducing the fiscal deficit, and managing debt-to-GDP ratios.
  • 3 reasons why the RBI has held interest rates steady

    RBI MPC may maintain the status quo on August 10; comment on inflation,  growth trajectory to be in focus | Mint

    Central idea 

    The RBI’s recent monetary policy decision maintains a cautious stance, driven by concerns over persistent food inflation and global central banks signaling higher interest rates. Despite a positive economic outlook, challenges include incomplete transmission of past rate hikes and potential risks from interconnectedness between banks and non-banks.

    Key Highlights:

    • The Reserve Bank of India (RBI) maintained its pause on monetary policy and retained the withdrawal-of-accommodation stance.
    • Reasons for the decision include ongoing concerns about inflation, particularly in critical food items, despite a recent decrease.
    • Influences from systemically important central banks, such as the US Federal Reserve and the European Central Bank, impact India’s monetary policy.

    Key Challenges:

    • Persistent risks from food inflation, driven by factors like an uneven monsoon and global food supply uncertainties.
    • Impact of higher interest rates signaled by central banks like the US Federal Reserve and the European Central Bank on India’s economy.
    • Incomplete transmission of past rate hikes into lending rates poses challenges for the RBI.

    Key Terms:

    • Monetary Policy Committee (MPC): A committee responsible for framing India’s monetary policy.
    • Core CPI Inflation: Consumer Price Index inflation excluding volatile food and fuel components.
    • Macroprudential Tools: Measures used by central banks to ensure the stability of the financial system.

    Key Phrases:

    • “The battle against inflation is far from over.”
    • “Systemically important central banks signal higher-for-longer interest rates.”
    • “Transmission of past rate hikes into lending rates remains incomplete.”

    Key Quotes:

    • “The RBI expects consumer inflation at 5.4 per cent this fiscal, while our forecast is slightly higher at 5.5 per cent.” (Authors)
    • “The RBI Governor flagged increasing interconnectedness between banks and non-banks, raising the possibility of stress contagion.” (RBI Governor)

    Key Statements:

    • “Despite rate increases, bank credit growth has sustained over 15 per cent this fiscal, unchanged from last year.”
    • “India will continue to be a growth outperformer among large economies this fiscal.”

    Key Examples and References:

    • Influence of US Federal Reserve and European Central Bank’s higher interest rates on global monetary policies.
    • RBI’s use of measures like an incremental cash reserve ratio and open market sales to manage liquidity.

    Key Facts and Data:

    • RBI’s forecast for consumer inflation: 5.4 per cent.
    • GDP growth forecast lifted to 7 per cent for the fiscal year.

    Critical Analysis:

    • Emphasizes ongoing concerns about inflation, particularly in critical food items.
    • Highlights the impact of global central banks’ policies on India’s monetary decisions.
    • Raises the challenge of incomplete transmission of rate hikes into lending rates.

    Way Forward:

    • Monitor and address risks related to food inflation and global interest rate dynamics.
    • Continue using measures like liquidity management and macroprudential tools for financial stability.
    • Assess and manage potential challenges arising from the interconnectedness of banks and non-banks.
    • Anticipate and address the impact of rising interest rates on India’s economy.
  • Ethanol Production Policy: New Directive on Sugarcane Usage

    sugarcane ethanol

    Central Idea

    • The Ministry of Consumer Affairs, Food and Public Distribution issued a directive to sugar mills and distilleries, not to use sugarcane juice or syrup for ethanol production in the ethanol year 2023-2024.

    No Sugarcane Juice for Ethanol Production

    • Continuation of Existing Supplies: The directive allows the continued supply of ethanol from B-Heavy molasses based on existing offers received by Oil Marketing Companies (OMCs).
    • Regulatory Oversight: The Department of Food and Public Distribution, responsible for monitoring sugar production and availability, implements this directive under the Sugar (Control) Order.

    Rationale behind the Directive

    • Ensuring Sugar Availability: The government’s decision aims to ensure sufficient sugar availability in India, considering the lower sugar production in the country.
    • Food vs. Fuel Consideration: Businesses highlighted this move as a balance between food security and fuel production.
    • Impact on Ethanol Blending Targets: The directive is significant in the context of India’s goal of achieving 20% ethanol blending by the 2025-2026 ethanol year.

    Implications for Industry

    • ISMA’s Response: The Indian Sugar Mills Association (ISMA) is assessing the implications of the order.
    • Effect on Domestic Sugar Supply: Industry sources indicate that this decision will ensure adequate sugar supply domestically, especially with reduced sugarcane production in states like Maharashtra and Karnataka.
    • Impact on Ethanol Blending Program: The restriction is likely to affect the ethanol blending program, which is a key component of India’s renewable energy strategy.
    • Consequences for Ethanol-Only Units: Facilities dedicated solely to ethanol production may face challenges due to this new policy.

    Conclusion  

    • The directive represents a strategic decision by the Indian government to prioritize domestic sugar availability over ethanol production from sugarcane.
    • Monitoring the impact of this directive on both the sugar industry and the ethanol blending program will be crucial in the coming years.
  • SC affirms “Group of Companies’ Doctrine

    Central Idea

    • The Supreme Court has issued a landmark ruling, expanding the scope of arbitration agreements to include non-signatories under specific conditions.
    • This ruling centers on the “group of companies” doctrine within the framework of arbitration agreements.

    ‘Group of Companies’ Doctrine

    Details
    Essence Non-signatory entities in a corporate group can be bound by an arbitration agreement if part of the same group as a signatory.
    Basis on Mutual Intent Relies on the mutual intention to bind both signatories and non-signatory group members.
    Arbitration as a Tool Offers an alternative to court litigation, with enforceable decisions by neutral arbitrators.
    Root in International Jurisprudence Based more on international arbitration practices than domestic law.
    Indian Legal Precedent Established by Chloro Controls India Pvt. Ltd. v. Severn Trent Water Purification Inc. case (2013).
    Criteria for Application Set by the Indian Supreme Court, includes mutual intent, relationship between entities, common subject matter, transaction nature, and contract performance.
    Objective Aims to prevent dispute fragmentation in complex, multi-party transactions.
    Recent Supreme Court Ruling Clarified conditions under which non-signatories can be bound by arbitration agreements, focusing on legal relationships and demonstrated intentions.
  • Centre’s Ethanol Policy Shift: Impact on Sugar and Ethanol Industries

    Central Idea

    • The Centre has taken significant steps to increase domestic sugar availability, including banning sugar exports and restricting the diversion of sugar for ethanol production.
    • On December 7, the Ministry of Consumer Affairs, Food and Public Distribution directed mills and distilleries not to use sugarcane juice/syrup for ethanol production.

    Ethanol Blended Petrol (EBP) Programme

    • Programme’s Success: The EBP programme, a key achievement of the government, has seen ethanol blending with petrol increase from 1.6% in 2013-14 to 11.8% in 2022-23.
    • Feedstock Diversification: The success is attributed to diversifying feedstocks, including C-heavy molasses, B-heavy molasses, sugarcane juice/syrup, and grains.

    Ethanol Production from Different Feedstocks

    • C-heavy Molasses: Traditionally used for ethanol production, yielding 220-225 litres of ethanol per tonne.
    • B-heavy Molasses: Provides higher ethanol yield (290-320 litres per tonne) compared to C-heavy molasses.
    • Direct Fermentation of Sugarcane: Fermenting the entire sugarcane without sugar extraction yields 80-81 litres of ethanol per tonne.

    Centre’s Ethanol Blending Scheme: Food vs. Fuel Debate

    • Increased Ethanol Production Post-2017: The use of B-heavy molasses and sugarcane juice/syrup, along with new substrates like surplus rice, broken grains, and maize, boosted ethanol production.
    • Differential Pricing Policy: The government incentivized ethanol production from non-C-heavy molasses feedstocks with higher prices.
    • Impact on Industry: Companies like Triveni Engineering & Industries Ltd (TEIL) adapted to multiple feedstocks, including grain during the off-season.

    Challenges and Setbacks for the Industry

    • Directive’s Impact: The December 7 directive is a setback, especially for companies with capacities to produce ethanol from cane juice/syrup.
    • Tender for Ethanol Supply: The OMCs’ tender for 825 crore litres of ethanol for 2023-24 might be affected, particularly the 135 crore litres from sugarcane juice/syrup.
    • Uncertainty in Pricing: The Centre has not announced prices for various ethanol feedstocks for 2023-24, despite the ethanol supply year aligning closer to the sugar year.

    Sugar Supply Concerns and Policy Implications

    • Low Sugar Stocks: The 2022-23 sugar year ended with low stocks, prompting the government to prioritize domestic sugar supply.
    • Uncertain Production Forecasts: The National Federation of Cooperative Sugar Factories predicts a decrease in sugar production for 2023-24.
    • Government’s Prioritization: The latest decisions reflect the government’s focus on domestic supply and consumer needs over exports and fuel production.

    Conclusion

    • Shift in Government Policy: The Centre’s recent actions indicate a shift towards prioritizing domestic sugar availability over ethanol production.
    • Broader Implications: These decisions impact both the sugar and ethanol industries, reflecting the complex balance between food security and renewable energy initiatives.
  • Strategic Auction of Critical Mineral Blocks  

    Critical Mineral

    Central Idea

    • The Centre is auctioning twenty blocks of critical minerals for commercial mining by the private sector.
    • These blocks contain lithium ore and 10 of the 30 minerals declared as “critical” by the government in July.

    What are Critical Minerals?

    • Critical minerals are elements that are crucial to modern-day technologies and are at risk of supply chain disruptions.
    • These minerals are used in making mobile phones, computers, batteries, electric vehicles, and green technologies like solar panels and wind turbines.
    • Minerals such as antimony, cobalt, gallium, graphite, lithium, nickel, niobium, and strontium are among the 22 assessed to be critical for India.
    • Many of these are required to meet the manufacturing needs of green technologies, high-tech equipment, aviation, and national defence.
    • List of critical minerals includes:
    1. Identified Minerals: The assessment resulted in a list of 30 critical minerals, including antimony, beryllium, cobalt, copper, lithium, nickel, rare earth elements, silicon, tin, titanium, tungsten, and others.
    2. Fertilizer Minerals: Two minerals critical for fertilizer production, phosphorous and potash, are also included.

    Significance of Lithium Ore Auction

    • First Instance: This auction marks the first time that rights for lithium ore mining are being offered to private parties in India.
    • Other Critical Minerals: The blocks also include nickel, copper, molybdenum, and rare earth elements (REEs), crucial for various industries.

    Location and Rights of Mineral Blocks

    • Distribution: The 20 blocks are spread across eight states, including Tamil Nadu, Odisha, Bihar, Uttar Pradesh, Gujarat, Jharkhand, Chhattisgarh, and Jammu & Kashmir.
    • Types of Licenses: Four blocks are for a Mining License (ML), allowing immediate mining post-clearance. The remaining 16 blocks are for a Composite License (CL), permitting further exploration before potentially converting to an ML.
    • Approvals Required: Licensees must obtain various approvals, including forest clearance and environmental clearance.
    • Forest Land: Approximately 17% of the total concession area, or 1,234 hectares, is forest land.

    Reserve Estimates and Key Minerals

    • Lithium Reserves: The two lithium reserve blocks, one each in J&K and Chhattisgarh, are auctioned for CL.
    • Nickel and Copper Reserves: Nickel ore reserves are found in Bihar, Gujarat, and Odisha, with the Odisha block also containing copper reserves.

    India’s Current Mineral Imports

    • Lithium Imports: In FY23, India imported 2,145 tonnes of lithium carbonate and lithium oxide, costing Rs 732 crore.
    • Nickel and Copper Imports: The country imported 32,000 tonnes of unwrought nickel and 1.2 million tonnes of copper ore, costing Rs 6,549 crore and Rs 27,374 crore, respectively.
    • Import Dependence: India relies entirely on imports for lithium and nickel, and 93% for copper.

    Post-Auction Plans and Policy Initiatives

    • Future Auctions: A second tranche of critical mineral blocks, including new lithium reserves in Rajasthan and Jharkhand, is expected.
    • Geological Surveys: The Geological Survey of India is conducting 125 projects to explore critical mineral reserves.
    • Centre of Excellence: A recommendation to establish a Centre of Excellence for Critical Minerals aims to develop a complete value chain in the country.

    Conclusion

    • The auction of critical mineral blocks is a significant step towards reducing India’s reliance on imported minerals, particularly lithium, nickel, and copper.
    • This initiative aligns with the #AatmanirbharBharat vision and is expected to bolster India’s position in vital industries like battery manufacturing and electric vehicles.
    • The success of these auctions will be crucial in shaping India’s resource independence and industrial future.
  • To venture or not to venture: Emerging compressed biogas sector lucrative for enterpreneurs but present dilemmas

    Central idea 

    Entrepreneurs in India’s Compressed Biogas (CBG) sector face challenges in feedstock disparities, operational complexities, and financial vulnerabilities. The three-day training by the Centre for Science and Environment highlights the sector’s need for robust mechanisms in feedstock pricing, market creation, and sustainable practices.

    Key Highlights:

    • Budding entrepreneurs in the compressed biogas (CBG) space in India are grappling with the viability of the sector despite government support.
    • The CBG industry faces challenges such as feedstock availability, varying prices, and complex plant operations due to multiplicity of feedstock.
    • The profitability of CBG production is impacted by fixed or one-off take prices irrespective of feedstock prices, leading to financial vulnerability.
    • A fair and robust pricing mechanism for feedstock is crucial for the long-term availability and sustainability of the CBG sector.
    • Sustainability involves creating a market for CBG and ensuring the sustainable disposal of the by-product, fermented organic manure (FOM).

    Key Challenges:

    • Feedstock Availability: Disparities in feedstock availability across regions pose a challenge, leading to the exploration of growing dedicated energy crops.
    • Multiplicity of Feedstock: Handling multiple feedstocks adds complexity to plant operations, increasing capital and operating costs.
    • Varying Feedstock Prices: The fixed or one-off take price of CBG regardless of feedstock prices makes the business financially volatile.
    • Market Creation for FOM: Sustainability requires creating a market for FOM, the by-product, necessitating innovation in market development.

    Key Terms and Phrases:

    • Compressed Biogas (CBG)
    • Feedstock Pricing Mechanism
    • Fermented Organic Manure (FOM)
    • Market Development Assistance
    • Anaerobic Digestion
    • Technology Selection
    • Multiplicity of Feedstock
    • Cluster Approach
    • Community-Driven Models
    • Voluntary Carbon Market

    Key Quotes and Anecdotes:

    • “Choice and availability of feedstock is one among many concerns, with entrepreneurs exploring the possibility of growing dedicated energy crops.”
    • “Multiplicity of feedstock adds to the complexities in plant operation, resulting in larger investments towards capital and operating costs.”
    • “Fair and robust pricing mechanism for feedstock is needed for the long-term availability and visibility of the feedstock supply chain.”
    • “Sustainability involves creating a market for CBG and equally important sustainable disposal of the by-product, fermented organic manure (FOM).”

    Key Statements:

    • The CBG sector struggles with challenges such as feedstock availability, varying prices, and complex plant operations due to multiplicity of feedstock.
    • The industry needs to shift from being cost-sensitive to cost-aware for long-term viability and operational sustainability.
    • A proactive approach by industry stakeholders is crucial to developing a robust mechanism for feedstock pricing, off-take, and market creation for FOM.

    Key Examples and References:

    • The state of Uttar Pradesh is implementing a catchment area approach for CBG units, defining specific areas for supply chain coordination.

    Key Facts and Data:

    • The CBG sector requires a collective approach to address challenges and create a healthy competition among stakeholders.
    • Entrepreneurs in the CBG sector need to exercise caution in technology and feedstock selection to ensure sustainability.

    Critical Analysis:

    • The CBG sector’s complexity lies in numerous variables along the value chain, requiring a shift from cost sensitivity to cost awareness for long-term viability. A fair feedstock pricing mechanism and innovative market development for by-products are essential for sustainability. Capacity-building initiatives are crucial for entrepreneurs to make informed decisions in this evolving sector.

    Way Forward:

    • Collaborative Approach: Industry stakeholders should collaborate to develop robust mechanisms for feedstock pricing, off-take, and FOM market creation.
    • Cluster Approach: Adopting a cluster approach can provide visibility to feedstock availability, eliminating competing demands from neighboring CBG producers.
    • Community-Driven Models: Community engagement and ownership of feedstock suppliers, such as farmer-producer organizations, can enhance sustainability.
    • Technological Awareness: Entrepreneurs must prioritize awareness and proper guidance in technology selection to avoid compromising plant performance and product quality.
    • Sustainability Focus: The CBG industry needs to focus on sustainable disposal and application of by-products to prevent environmental challenges and ensure further expansion.

    The training program successfully achieved its objective of providing necessary considerations to entrepreneurs, indicating a need for more capacity-building initiatives in the CBG sector.

  • C Raja Mohan writes: Why India cannot afford to repeat its nuclear weapons mistakes with AI

    The Future of AI: How AI Is Changing the World | Built In

    Central idea 

    The article explores parallels between the nuclear and AI revolutions, emphasizing the shared challenges in governance, geopolitical dynamics, and the need for international cooperation. It underscores the importance of learning from India’s nuclear history to navigate the AI landscape, highlighting potential pitfalls such as exceptionalism.

    Key Highlights:

    • Historical Parallels: Drawing comparisons between the nuclear and AI revolutions.
    • Global Challenges: Identifying shared issues in managing geopolitical rivalry and preventing misuse.
    • US-China Dynamics: Highlighting the significance of agreements between the superpowers in AI governance.
    • International Governance Proposals: Discussing the idea of an “International Agency for Artificial Intelligence” (IAAI) and the role of the Global Partnership for Artificial Intelligence (GPAI).
    • Lessons for India: Emphasizing the importance of learning from India’s nuclear history in navigating the AI landscape.

    Key Challenges:

    • Advancements Amid Concerns: Addressing the rapid progress in AI despite calls for restrictions.
    • US-China Competition: Exploring the impact of US measures to slow China’s AI development.
    • Exceptionalism Risks: Warning against India’s tendency to adopt a “third way” and claim exceptionalism in AI development.

    Key Terms and Phrases:

    • Geopolitics of AI: Examining the political dynamics surrounding artificial intelligence.
    • Arms Control Agreements: Exploring proposals for limiting military applications of AI.
    • Private Sector Role: Recognizing the increasing importance of the private sector in AI research.
    • S&T Sector Reform: Addressing efforts to reform Science and Technology sectors in India.

    Key Quotes:

    • The AI revolution threatens an even bigger catastrophe — machines taking over from humanity and enslaving them.”
    • “US-China agreements on AI are viewed as critical for the management of the new technological revolution.”
    • “Building strong domestic capabilities in AI is critical to making the best out of international cooperation.”

    Key Statements:

    • Disarmament Realities: Acknowledging the shift from disarmament idealism in nuclear weapons to the challenges of AI governance.
    • Strategic Partnerships: Emphasizing the need for India to capitalize on its partnership momentum with the US in critical technologies.
    • Caution Against Exceptionalism: Highlighting the risks of India proclaiming exceptionalism in AI development.

    Key Examples and References:

    • Superpower Dominance: Drawing parallels between the US-Soviet dominance in the nuclear age and the current US-China dominance in AI.
    • International Agencies: Referencing the International Atomic Energy Agency (IAEA) and the proposed International Agency for Artificial Intelligence (IAAI).
    • Missed Opportunities: Citing historical instances of India missing opportunities in technological cooperation with the US.

    Key Facts and Data:

    • GPAI Membership: Noting that the Global Partnership for Artificial Intelligence (GPAI) comprises 28 members.
    • India’s Hosting Role: Highlighting India’s role in hosting the GPAI summit in Delhi.
    • IAEA Establishment: Providing the year of establishment for the International Atomic Energy Agency (IAEA) as 1957.

    Critical Analysis:

    • Learning from History: Encouraging India to reflect on historical mistakes and actively engage in the global AI landscape.
    • Balancing Progress and Ethics: Acknowledging the challenges of balancing technological progress with ethical considerations and international cooperation.
    • Provocative Perspectives: Recognizing the thought-provoking comparison between the nuclear and AI revolutions.

    Way Forward:

    • Leveraging Partnerships: Encouraging India to leverage its partnership with the US in AI and emerging technologies.
    • Strengthening Domestic Capabilities: Advocating for a focus on building robust domestic capabilities in AI, involving the private sector.
    • Avoiding Exceptionalism: Advising against the temptation of adopting a “third way” and promoting international cooperation and norms in AI development.