Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS3-12.Effects of liberalization on the economy, changes in industrial policy and their effects on industrial growth

  • NITI Aayog: Trade Watch Quarterly

    NITI Aayog: Trade Watch Quarterly

    Why in the News?

    NITI Aayog released the 9th edition of Trade Watch Quarterly for Q1 FY27 (April-June 2026), analysing global and Indian trade trends with a special focus on metals and ores.

    Key Highlights

    • Global goods trade: $13.7 trillion in H1 2026, up 12.5% YoY.
    • Global services trade: grew 10.5%.
    • India’s total trade: $506.9 billion in Q1 FY27, up 15.5% YoY.
    • India saw strong merchandise exports in:
      • Mineral fuels
      • Electrical machinery
      • Nuclear reactors
      • Iron and steel
      • Vehicles

    Metals and Ores

    • Metals exports: $34.8 billion (2025).
    • Iron and steel, articles of iron and steel, and aluminium contributed around 78% of metals exports.
    • Metals and ores imports rose from $32.2 billion (2015) to $60.5 billion (2025).
    • Key import-dependent minerals include:
      • Copper
      • Lithium
      • Cobalt
      • Nickel

    Digitally Delivered Services

    • Exports increased from $277 billion (2024) to $317 billion (2025).
    • India became the 4th-largest DDS exporter, after the US, UK and Ireland.

    Trade Diversification

    • Tanzania and South Africa emerged among India’s top 10 export markets.
    • Imports from Latin America and West Africa increased.
    • Northeast Asia, West Asia-GCC and ASEAN together account for around half of India’s imports.
    • Exports to FTA partners increased 36.3%, while imports rose 10%.

    Policy Significance

    • MMDR Amendment Act, 2026 can support exploration and investment in critical minerals.
    • EU CBAM increases the need for competitive, low-carbon steel and aluminium exports.
    • Priorities include:
      • Domestic mineral exploration
      • Recycling of critical minerals
      • Value addition
      • Renewable energy access
      • Lower logistics and financing costs
      • Export-market diversification

    Important Full Forms

    • NITI: National Institution for Transforming India
    • DDS: Digitally Delivered Services
    • FTA: Free Trade Agreement
    • MMDR: Mines and Minerals (Development and Regulation)
    • CBAM: Carbon Border Adjustment Mechanism
    • GCC: Gulf Cooperation Council

    Prelims Quick Revision

    • Trade Watch Quarterly: NITI Aayog publication.
    • Latest edition: 9th edition, Q1 FY27.
    • India’s total trade: $506.9 billion.
    • Metals and ores imports: $60.5 billion in 2025.
    • India: 4th-largest digitally delivered services exporter.
  • SEMICON India 2026: Building India’s Semiconductor Ecosystem

    SEMICON India 2026: Building India’s Semiconductor Ecosystem

    Why in the News?

    SEMICON India 2026 will be inaugurated at Yashobhoomi, Dwarka, with the theme “Silicon to Systems: Building the Ecosystem.”

    Key Highlights

    • India’s electronics production rose from ₹1.9 lakh crore (2014-15) to ₹13.11 lakh crore (2025-26).
    • Electronics exports increased from ₹38,000 crore to ₹4.24 lakh crore.
    • Mobile phone production rose to ₹6.27 lakh crore.
    • India now manufactures 99.2% of the mobile phones it uses.
    • Electronics manufacturing supports around 2.5 million jobs.

    Semicon India Programme

    • Semicon 1.0 (2021): ₹76,000 crore outlay.
    • Semicon 2.0 (2026): ₹1,27,500 crore outlay.
    • Six focus areas:
      • Chip design
      • Semiconductor equipment and materials
      • Fabrication facilities
      • Advanced packaging
      • Research and development
      • Talent development
    • 12 semiconductor projects approved across 6 states, with investments exceeding ₹1.64 lakh crore.
    • 3 facilities have started commercial production.

    Semiconductor Talent

    • Target: 85,000 skilled semiconductor engineers.
    • Chips to Startup Programme deployed Electronic Design Automation (EDA) tools across 320 institutions.
    • More than 68,000 students trained.
    • 211 chips taped out by 75 institutions by April 2026.
    • Seven chips fabricated, including nodes down to 12 nm.

    ChipIN Centre

    • Established at C-DAC under the Chips to Startup and Design Linked Incentive programmes.
    • Provides access to chip-design tools, fabrication services and training.
    • Reached 1 lakh+ engineers from 500+ organisations.

    International Dimension

    • India joined the Pax Silica coalition in 2026.
    • Focus: securing the global silicon supply chain, including critical minerals, fabrication and advanced AI systems.

    Important Full Forms

    • SEMICON: Semiconductor-related industry exhibition/platform
    • EDA: Electronic Design Automation
    • C-DAC: Centre for Development of Advanced Computing
    • C2S: Chips to Startup
    • DLI: Design Linked Incentive
    • MSME: Micro, Small and Medium Enterprises

    Prelims Quick Revision

    • Semicon India Programme: launched in 2021.
    • Semicon 1.0: ₹76,000 crore.
    • Semicon 2.0: ₹1,27,500 crore.
    • ChipIN Centre: C-DAC.
    • Semiconductor ecosystem includes design + fabrication + packaging + testing + equipment/materials + talent.
  • A blueprint to create productive jobs, a lesson from Tiruppur

    Why in the News

    The Prime Minister’s Independence Day address placed manufacturing power first among the seven Saptadhara streams meant to carry India towards a Viksit Bharat, and tied that effort to harnessing the potential of India’s youth. Research at the Indian Council for Research on International Economic Relations (ICRIER) answers the question that follows, which is which manufacturing sector can actually deliver jobs at the scale India needs, and its answer is textiles and apparel. The evidence offered is the Tiruppur knitwear cluster, an organically grown ecosystem that supports over a million livelihoods, set against the PM MITRA parks announced in 2021 to replicate it, of which only one appears operational. The tension is that India has closed its tariff gaps with competitors and still cannot convert that access into exports, because the binding constraint is not market access but the absence of the cluster ecosystem around the factory.

    Why is India’s job problem one of composition and of job quality?

    1. The size of the workforce: India had 61.6 crore employed persons aged more than 15 years in 2025.
    2. Agriculture’s share of employment: Agriculture still accounted for 43 per cent of employment against 12.1 per cent in manufacturing, per PLFS 2025.
    3. The arithmetic of any shift: Even a 1 percentage point shift in employment from agriculture to manufacturing would involve moving a large number of workers.
    4. The stated target has not been met: The governing alliance had promised to create 2 crore jobs every year, and the outcome is nowhere near that.
    5. Youth unemployment: Unemployment among those aged 15 to 29 was 9.9 per cent, rising to 13.6 per cent in urban areas, per PLFS 2025.
    6. Youth outside employment, education and training: 25 per cent of that age group were neither in employment nor in education or training.
    7. The gender gap in participation: Female labour force participation was 40 per cent, against 79.1 per cent for men.
    8. Student agitations over paper leaks: The recent student agitations over paper leaks reflected the underlying position that respectable formal sector jobs remain scarce even after a basic education.
    9. The PLFS usual status measure: The PLFS usual status measure counts people who worked for a long part of the year and also those who undertook economic activity for at least 30 days during the year.
    10. The limit of the employment count: Being counted as employed does not mean holding a regular or formal job.
    11. Regular formal employment with social security: Economic security requires regular formal employment carrying social security benefits such as the Employees’ Provident Fund (EPF) and Employees’ State Insurance (ESI).

    Why does apparel fit the gap better than the frontier sectors?

    1. Labour absorption in apparel: The apparel sector is labour intensive and employs women in large numbers.
    2. Training time for production roles: Workers can be trained in short periods, about 60 days for specific production roles, which is what allows a cluster to scale its workforce quickly.
    3. Fit with India’s skill distribution: Chip making, artificial intelligence and other advanced technologies serve a highly skilled workforce, while the majority of India’s labour force is at the bottom end of the skill distribution.
    4. The cost of a job is lower: Textiles and apparel offer higher employment intensity at relatively low cost, which is the path China, Bangladesh and Vietnam followed.

    Is the $100 billion export target achievable, and what do the international comparisons show about market access?

    1. The headline target: India has set a target of $100 billion in textiles and apparel exports by 2030, from $36 billion today.
    2. The apparel share of the target: $40 billion of that is for apparel exports specifically, from $15.7 billion today.
    3. Exporters do not accept the date: Interactions with exporters suggest the targets are not grounded in current realities and are more likely to be achieved by 2035, not 2030.
    4. The capacity gap behind the target: Closing it means building capacity of a scale that does not exist, not raising utilisation at existing units.
    5. The tariff gap has already closed: India has recently closed the tariff gaps with competitors such as Bangladesh and Vietnam in major markets including the EU and the UK.
    6. The India Japan agreement of 2011: Under the India Japan agreement of 2011, India’s apparel exports to Japan fell from $229 million in 2013 to $203 million in 2024.
    7. Market access without capacity: Market access alone does not ensure exports, and India needs the scale and capacity to tap free trade agreements before a concession converts into shipments.

    What made Tiruppur work, and what did its environmental crisis show about collective capacity?

    1. Tiruppur’s knitwear exports: Tiruppur’s knitwear exports rose from $3.3 billion in 2020-21 to $5.3 billion in 2024-25, per the Tiruppur Exporters Association in 2026.
    2. Share of India’s knitwear exports: The cluster accounts for about 68 per cent of India’s knitwear exports.
    3. The cluster’s employment base: It supports the livelihoods of more than a million workers, around 70 per cent of them women.
    4. The whole chain sits in one place: Within roughly 20 km, yarn, knitting, dyeing, printing, stitching, finishing, packaging and dispatch are woven into one production ecosystem, with nearly 20,000 units operating across the different stages.
    5. The ecosystem effect of density: Firms specialise, workers specialise, and thousands of jobs are created around a common market, which is the ecosystem effect the argument rests on.
    6. Institutions and common infrastructure built over decades: Entrepreneurs, industry associations and government built the institutions and common infrastructure over decades. The Tiruppur Exporters Association and the South India Hosiery Manufacturers Association built collective capabilities, and infrastructure such as the Netaji Apparel Park supported expansion.
    7. The Madras High Court’s 2011 zero liquid discharge order: The Madras High Court’s 2011 order applied to units failing to meet zero liquid discharge (ZLD) norms, meaning norms requiring that no effluent leave the unit as liquid waste.
    8. The response was collective, not firm by firm: The cluster invested more than Rs 850 crore in common effluent treatment infrastructure.
    9. Collective financing of the effluent plant: A single firm could not have financed that plant, which is the clearest demonstration that the cluster’s value lies in what its firms can do jointly.

    What is a cluster ecosystem?

    1. The cluster ecosystem: A concentration of firms in one trade inside a small geography, together with the suppliers, contractors, traders and service providers each of them draws on. A single factory then operates inside a supply chain it does not have to own.
    2. Why proximity lowers cost: Each stage of production is bought from a neighbouring specialist rather than built in house, so a firm carries only the stage it is good at. The cost and the time of moving material between stages fall close to nil.
    3. The shared labour pool: A workforce trained in that trade accumulates in one place, so a unit can add or shed capacity without training workers from scratch, and a worker can change employer without changing town.
    4. Collective capability: Facilities no single firm could finance become viable once the cost is spread across thousands of units. Eg. Tiruppur’s common effluent treatment infrastructure, built by the cluster after a court order.

    What still constrains Tiruppur?

    1. Dependence on migrant labour: The cluster depends heavily on migrant workers from Odisha, Jharkhand, Bihar and elsewhere.
    2. Housing is the retention problem: Worker housing and retention are named as the important challenges in taking the cluster to its next million jobs.
    3. The cluster’s planned upgrade path: The cluster plans to move into man made fibres, technical textiles and high value sustainable manufacturing to expand both exports and employment.

    Why has the national attempt to replicate it stalled?

    1. The seven PM MITRA parks announced in 2021: The government announced seven PM MITRA parks in 2021 as the instrument for creating more such clusters.
    2. Operational status of the parks: Only one park appears operational, at Warangal, and the others are still in the planning stages.
    3. The execution pace against the export target: Such a pace in the execution of even good ideas does not inspire confidence that the $100 billion export target can be reached, and it limits the speed at which jobs can be created.
    4. One cluster cannot carry a national target: Tiruppur alone cannot deliver the target, and India needs many more clusters of the same kind.

    Challenges to the PM MITRA parks model

    1. A greenfield park has to create the ecosystem a cluster inherits: Tiruppur’s advantage is the density of specialised units around a common market, and a new park begins with land and utilities alone. Eg. Nearly 20,000 specialised units in one cluster took decades to assemble.
      The Fix: Anchor each park on an existing textile concentration so tenants arrive with supplier relationships already in place, rather than siting parks to distribute them across states.
    2. Land and clearances drive the timeline more than the incentive does: The scheme’s outlay is committed at announcement while state level land transfer, environmental clearance and utility connection decide the commissioning date. Eg. Roughly 70 per cent of infrastructure project delays in India stem from complex land acquisition processes.
      The Fix: Make the release of central assistance conditional on dated state milestones for land handover and clearances, so delay has a financial consequence.
    3. Common effluent capacity is the binding utility for textiles: Dyeing and processing are the stages that cannot start without treatment capacity, and they are also the stages that create the most jobs per unit of investment. Eg. Tiruppur had to build more than Rs 850 crore of common effluent treatment infrastructure after a court order, long after the cluster had grown.
      The Fix: Commission the zero liquid discharge plant before tenant allotment rather than after, so processing units can begin operating from the first year.
    4. Worker housing is treated as outside the park: A labour intensive park draws migrant workers who need housing at the same moment the units need staff, and housing is rarely part of the industrial park’s own scope. Eg. Worker housing and retention are the named constraints on Tiruppur’s next million jobs.
      The Fix: Include rental worker housing within the park’s own master plan and viability gap funding, treating it as production infrastructure rather than welfare.

    Conclusion

    The evidence assembled here says the binding constraint on labour absorbing manufacturing is executional rather than strategic. India already has a demonstrated model, a closed tariff gap with its competitors and a stated national target, and the one instrument built to convert all three into jobs has produced a single operating park in five years. Whether the remaining six parks reach commissioning, and on what dated schedule, is the marker that will decide whether the $100 billion target slips to the exporters’ 2035 or fails altogether.

    Manufacturing Sector in India

    1. Share of GDP: Manufacturing contributes around 17 per cent of GDP, against a policy target of 25 per cent.
    2. Share of global manufacturing output: India holds about 2.8 per cent of global manufacturing output, compared with China’s roughly 29 per cent.
    3. The size of output: Manufacturing output is projected to reach approximately $1 trillion in FY 2025-26.
    4. What incentives have drawn: The Production Linked Incentive (PLI) scheme had drawn over Rs 1.76 lakh crore across 14 sectors as of March 2025.

    Government Initiatives for Manufacturing

    1. Make in India (2014): Seeks to raise manufacturing’s share of GDP from around 17 per cent toward 25 per cent through ease of doing business reforms.
    2. Atmanirbhar Bharat (2020): Promotes self sufficiency, local industry and reduced import dependence without closing the economy off to the world.
    3. Production Linked Incentive Scheme (2020): Covers 14 sunrise and strategic sectors, including textiles, with outcome linked financial incentives paid on incremental production.
    4. National Manufacturing Mission: A Budget mission targeting a 25 per cent GDP share and 143 million jobs by 2035, unifying policy across clean and sustainable manufacturing.
    5. National Logistics Policy: Aims to cut logistics costs and improve supply chain efficiency, which is a direct input into export competitiveness.
    6. Industrial corridors: Eleven approved corridors bundle infrastructure to support clustered industrial development, with 12 new industrial nodes approved in 2024.

    Back2Basics: PM MITRA Parks

    1. What the name stands for: Pradhan Mantri Mega Integrated Textile Region and Apparel parks, administered by the Ministry of Textiles.
    2. The design idea: Each park brings spinning, weaving, processing, dyeing, printing and garmenting onto a single site, so a garment can be produced end to end within one location.
    3. The vision it implements: The 5F vision, meaning Farm to Fibre to Factory to Fashion to Foreign, which treats the textile value chain as a single continuum from cotton to export.
    4. How they are built: Each park is developed by a Special Purpose Vehicle owned jointly by the central and the concerned state government, with central support for development capital and for the first units to begin production.

    Matching Previous Year Question

    “[2025, GS3, 15 marks] Discuss the rationale of the Production Linked Incentive (PLI) scheme. What are its achievements? In what way can the functioning and outcomes of the scheme be improved?”

  • Elephant in the room in meetings with Xi, Putin: India’s manufacturing challenges

    Why in the News

    India’s manufacturing base, and not its diplomacy, is the binding constraint on the economic agenda of this weekend’s BRICS summit in New Delhi. The Prime Minister meets the Russian President ahead of the summit and the Chinese President over the weekend, and the consequential part of both conversations is bilateral and economic. India’s difficulty in each case is not the size of its trade deficit. It is the narrowness of what India is able to sell.

    What does the trade profile with Russia reveal about what India can sell?

    1. Exports are a fraction of imports: India’s exports to Russia remain below $5 billion against imports of $63.8 billion in the year to March 2025.
    2. The gap and its composition: The deficit is nearly $59 billion, and Russian oil and other natural resources dominate what India buys.
    3. The market is not the limitation: Russia is a substantial market for manufactured goods, so the shortfall lies on the supply side.
    4. Industrial promotion is under way: The first India Russia international industrial trade fair was held in Delhi this week, and both leaders are to visit it.

    What does China’s export record to Russia show about the size of the gap?

    1. The scale of the comparison: China exported about $103 billion of goods to Russia in 2025.
    2. The composition is the real point: Those exports run from cars and machinery to electronics and industrial equipment, which are exactly the categories India cannot supply at comparable scale.

    How does the same weakness appear in the trade with China?

    1. A larger deficit on a larger base: Bilateral trade reached about $151 billion in the year to March 2026, and India’s deficit rose to roughly $112 billion.
    2. The asymmetry is reversed: China sells manufactured goods, and increasingly the intermediate and capital goods that Indian manufacturers themselves need.
    3. The policy response so far: Delhi is responding to Beijing’s demand that India end its restrictions on commerce with China.

    Why does the goal of economic security collide with what Indian industry needs?

    1. Chinese inputs are embedded in Indian production: They run through electronics, machinery, chemicals, auto components and pharmaceutical inputs, and they feed India’s own exports of manufactured goods.
    2. The two objectives pull apart: The political aim of cutting dependence runs against the commercial need for cheap and increasingly sophisticated inputs at scale.
    3. One weakness, two symptoms: Limited manufacturing strength shows up as an inability to export to a large market in one relationship, and as import dependence in the other.

    Can diplomacy compensate for weak manufacturing?

    1. What negotiation can actually deliver: Payment mechanisms, investment targets and trade agreements are all negotiable, and political warmth cannot substitute for competitive products.
    2. The older ambition against the present agenda: India’s call to democratise the global economic order dates to the Cold War years. The immediate bilateral ask is that Russia and China buy more, invest more and help build Indian productive capacity.
    3. What closing the gap requires: Sustained economic reform, simpler regulation, greater competitiveness, less corruption, deeper domestic supply chains and a stronger manufacturing ecosystem.
    4. Investment follows attractiveness, not persuasion: The world is not short of capital or technology, and India is not near the top of the destinations they go to.
    5. Why the bilateral overshadows the multilateral: BRICS, like the Shanghai Cooperation Organisation (SCO), has become a venue for high level political engagement and bilateral problem solving.

    Challenges to widening India’s manufacturing base

    1. Firms stay small, and stay small for long: A size distribution dominated by tiny units leaves few producers able to take on a large export order. Eg. Most registered manufacturing units in India employ fewer than ten workers.
      The Fix: Make support conditional on growth in employment and turnover rather than on staying below a small unit threshold.
    2. Duties on inputs tax the exporter: Tariffs on intermediate goods raise the cost of the components a finished goods exporter has to buy. Eg. Duties on electronic components have been cut in successive Budgets precisely because they raised assembly costs.
      The Fix: Move to a single low duty band on intermediate and capital goods, and reserve protection for finished goods alone.
    3. Logistics cost eats the margin: Dependence on road freight and long dwell time at ports raise the delivered price of Indian goods. Eg. The National Logistics Policy of 2022 was framed around bringing logistics cost as a share of output closer to competitor levels.
      The Fix: Tie port and freight corridor funding to published turnaround and transit time targets.
    4. Assembly has grown faster than component making: Incentives have drawn in final assembly without a domestic base in parts, so import content stays high. Eg. Mobile phone exports have risen sharply, with display panels and battery cells still largely imported.
      The Fix: Condition incentive payouts on a rising schedule of domestic value addition rather than on output value alone.

    Conclusion

    The agenda for this week is bilateral, and the constraint on it is domestic. Persuasion can open a market, and it cannot supply the goods that would fill one. What India’s economic diplomacy is worth therefore turns on decisions taken by its own economic policymakers rather than on commitments extracted from partners. The test worth watching is whether the industrial reform agenda moves at all once the summit season ends.

    Matching Previous Year Question

    “[2025, GS3, 15 marks] Discuss the rationale of the Production Linked Incentive (PLI) scheme. What are its achievements? In what way can the functioning and outcomes of the scheme be improved?”

  • Market turbulence is here to stay, may deepen

    Why in the News

    Indian equity markets closed lower with the Sensex down 1.08 per cent, and the weakness ran across small and midcap indices as well. The fall follows a run of external shocks rather than a domestic slowdown, since the economy is growing at a fairly healthy rate. The Sensex has lost roughly 12 per cent since the beginning of this year. Brent crude has touched $100 a barrel as the conflict in West Asia expands, and the rupee has slipped past the 95 mark against the dollar. The tension is that the drivers of the sell off sit outside the reach of domestic policy. The instruments available to answer them act on demand at home.

    What has actually moved in Indian markets?

    1. Index and breadth both weakened: The Sensex closed down 1.08 per cent and the fall extended to small and midcap indices rather than staying confined to large caps.
    2. Volatility rose sharply: The India VIX (an index of the volatility the options market expects in the Nifty over the next 30 days) rose almost 7 per cent.
    3. The decline is not a single session event: The Sensex has fallen by roughly 12 per cent since the beginning of this year.
    4. Information technology led the weakness: Concerns have mounted over the sector’s long term growth prospects, given the rapid deployment of artificial intelligence.
    5. Asian peers did not move together: The Nikkei was down 0.2 per cent. The Kospi was up 1.4 per cent.

    Why has investor sentiment weakened despite a healthy growth rate?

    1. The West Asian conflict has widened: Attacks by the Iran backed Houthis on energy facilities and infrastructure in Saudi Arabia mark an escalation and raise concerns over energy supplies.
    2. Crude has returned to triple digits: Brent crude oil has touched $100 a barrel, levels last seen in July.
    3. India’s own import cost has risen faster: The Indian crude oil basket surged to $108.91 per barrel as on 8 September, according to the Petroleum Planning and Analysis Cell.
    4. The currency has broken a psychological level: The Indian rupee has slipped past the 95 mark against the dollar.
    5. Foreign investors have turned sellers: Foreign investors have taken out $1.3 billion from the stock markets in September so far.
    6. The transmission runs through three channels: Higher prices act on the external balance, on the currency and on inflation together rather than one at a time.

    What does the global rate environment do to India’s policy room?

    1. The US central bank has signalled a harder stance: Remarks by the US Federal Reserve chairman at the recent Jackson Hole meeting were read as hawkish, raising expectations of an aggressive policy stance.
    2. A rate increase is now priced for the coming week: The odds of an interest rate hike at next week’s meeting have risen on those remarks.
    3. Sovereign yields elsewhere have repriced: The US 10 year bond yield is around 4.8 per cent and Japanese yields are hovering near 2.9 per cent, which narrows the return advantage of holding Indian assets.
    4. The domestic decision arrives into a softening economy: The Reserve Bank of India’s Monetary Policy Committee meets early next month with expectations of a move towards tightening. Growth momentum that surpassed expectations in the first quarter is expected to moderate in the second half of the year.

    Challenges to macroeconomic stability from sustained market turbulence

    1. Imported energy costs pass through to domestic prices: An expensive crude basket raises the import bill and feeds into freight and manufacturing costs within a quarter. Eg. India meets over 85 per cent of its crude oil requirement through imports.
      The Fix: Expand strategic petroleum reserve capacity and widen term supply contracts beyond West Asian sellers, so a regional escalation does not move the whole basket at once.
    2. A weaker currency raises the cost of external borrowing: Depreciation increases the rupee cost of servicing dollar denominated debt taken on by Indian firms. Eg. External commercial borrowings are raised largely in dollars and repaid out of rupee earnings.
      The Fix: Tighten hedging requirements on unhedged foreign currency exposure of corporate borrowers, so depreciation does not convert into balance sheet stress.
    3. Portfolio flows reverse faster than they arrive: Foreign portfolio investment tracks interest rate differentials rather than domestic earnings, so an outflow can begin before any local data changes. Eg. The taper tantrum of 2013 produced heavy outflows and a sharp rupee fall within weeks of a single central bank statement.
      The Fix: Deepen domestic institutional demand through retirement and insurance flows, so a foreign exit is absorbed rather than amplified.
    4. Defending the currency raises the cost of credit at home: A policy rate increase aimed at the exchange rate also raises borrowing costs for firms already facing weak demand. Eg. Micro, small and medium enterprises borrow largely at floating rates, so pass through reaches them first.
      The Fix: Pair any tightening with a targeted refinance line for small borrowers, so the rate defence does not fall hardest on the segment least able to absorb it.

    Conclusion

    Market weakness is no longer traceable to domestic growth. Its drivers are a war premium on oil, a harder rate path abroad and portfolio flows that respond to both. Domestic instruments act on demand at home and cannot offset an imported price shock. What remains unresolved is whether policy defends the currency or supports output, since a single rate decision cannot do both.

    Back2Basics

    1. What it is: The Indian basket of crude oil is a weighted average of the prices of the grades India actually imports, not a traded contract in its own right.
    2. What it averages: It combines sour grades of the Oman and Dubai type with the sweet Brent dated grade, weighted by the share of each in India’s import mix.
    3. Who compiles it: The Petroleum Planning and Analysis Cell, an attached office of the Ministry of Petroleum and Natural Gas, publishes it.
    4. Why it is used: It is the reference price for estimating the oil import bill and for tracking the cost of the crude that Indian refiners actually buy.

    Matching Previous Year Question

    “[2018, GS3, 15.0 marks] How would the recent phenomena of protectionism and currency manipulations in world trade affect macroeconomic stability of India?”

  • DGFT opens an Application Programming Interface facility for the Certificate of Origin on the Trade Connect ePlatform

    Why in News

    The Directorate General of Foreign Trade (DGFT), the trade regulator under the Ministry of Commerce and Industry, introduced an Open Application Programming Interface (API) facility for the Certificate of Origin (CoO) on its Trade Connect ePlatform on 7 September 2026.

    What it does

    1. Open API for the Certificate of Origin: An Application Programming Interface (API) lets one software system request data from another automatically. The facility lets an exporter’s own software connect directly to the CoO portal. Certificate applications then flow through without manual entry on the government site.
    2. Certificate of Origin defined: A Certificate of Origin is a document that certifies the country in which goods were produced. It decides tariff treatment under trade agreements. A preferential CoO unlocks lower duty under a trade pact. A non preferential CoO only states origin without a duty concession.
    3. Trade Connect ePlatform: The Trade Connect ePlatform is a single window hub of trade information and services. It gives exporters tariff data, certification rules, buyer information and trade event listings. It integrates Indian Missions, Export Promotion Councils and Commodity Boards on one system.
    4. Target users: The facility is aimed at Micro, Small and Medium Enterprises (MSME) exporters. Automated filing cuts the compliance time for repeat exporters.

    Static Context

    1. Paperless issuance: The CoO platform runs as a single point of issuance and validation for both preferential and non preferential certificates. It replaced physical certificate counters with a secure electronic process.
    2. eCoO 2.0: DGFT earlier upgraded the system to eCoO 2.0, which added back to back certificate issuance for re exported goods.
    3. Governing setup: DGFT functions under the Ministry of Commerce and Industry. It administers the Foreign Trade Policy and issues the Importer Exporter Code.

    [2025] What are the challenges before the Indian economy when the world is moving away from free trade and multilateralism to protectionism and bilateralism? How can these challenges be met? (GS3, 10 marks)

  • Carney’s defiance is well thought out

    Carney’s defiance is well thought out

    Why in the News

    Canada’s Prime Minister has walked away from trade negotiations with the United States after Washington put forward terms that would have cost Canada its sovereignty, key industries, French language protections and its freedom to negotiate with other countries. He has also announced retaliatory tariffs matching the new United States tariffs dollar for dollar, stating that the Americans “asked too much and offered too little.” The move tests whether a middle power, an economy that sends roughly three quarters of its exports into a market ten times its size, can resist pressure from a dominant trading partner without folding, and it carries lessons for other countries, including India, that are negotiating their own terms with Washington.

    What calculations underlie the decision to walk away?

    1. Broad domestic backing: The stance draws support even from the opposition Conservative party, amid public frustration with the United States President’s repeated talk of making Canada the fifty first state.
    2. A contained tariff footprint: The new tariffs apply to only about 5 percent of Canada’s overall exports to the United States, worth roughly 20 billion dollars, limiting the immediate domestic cost of retaliation.
    3. A calculated bet on mutual damage: A breakdown in trade relations is expected to hurt the United States as well, so Canada does not need to win the confrontation outright, only to make the arithmetic politically painful in Washington.

    How exposed is the United States to a breakdown with Canada?

    1. A leading export destination: Canada is the largest export market for 26 American states and among the top three trading partners for 45 of the 50 states.
    2. Energy dependence: Canada supplies roughly 60 percent of America’s crude oil imports, and Canadian electricity helps power grids in New England and the upper Midwest.
    3. Critical inputs: Canadian potash is vital to American agriculture, while Canadian critical minerals feed strategically important American supply chains.

    Why is the timing unfavourable for Washington?

    1. Domestic economic strain: A stalemate with Iran has pushed United States gasoline prices above 4 dollars a gallon, while the 30 year Treasury yield has climbed above 5.3 percent, its highest level since 2007.
    2. Fiscal and political weakness: Federal debt has crossed 40 trillion dollars, and the United States President’s net approval rating has fallen to minus 26 percent, narrowing his room to absorb a prolonged trade standoff.

    What broader pattern does this defiance respond to?

    1. A repeated negotiating playbook: Governments from Mexico City to Brussels to Tokyo have spent the past year confronting an American administration that treats a signed trade agreement as an opening bid that can be revisited whenever it suits it, coercing partners with escalating tariff threats and demanding unilateral concessions.
    2. Prior diversification, not improvisation: The Canadian Prime Minister had earlier warned that middle powers must stand up or risk ending up “on the menu,” and spent close to a year building trade ties with China, the Gulf and Asia, including India, so that a closed door in Washington did not mean a locked room globally.

    Challenges to Canada’s defiance strategy

    1. Economic exposure to a sustained standoff: Canada still sends roughly three quarters of its exports to an economy ten times its own size, so a prolonged confrontation could cost jobs and growth even if it wins the political argument. Eg. Estimates cited alongside the retaliatory tariffs put up to 90,000 Canadian jobs at risk from a sustained trade confrontation. Fix. Continue diversifying export markets by deepening the trade ties already being built with China, the Gulf and Asia.
    2. A narrow tariff footprint limits leverage: The new tariffs cover only about 5 percent of Canada’s exports to the United States, so retaliation alone may be too small to force a reversal in Washington. Eg. Even a full breakdown leaves most of Canada’s three quarter dependence on the United States market untouched. Fix. Extend retaliation toward strategically sensitive sectors such as crude oil, electricity and critical minerals, where Canada supplies a large share of United States demand.
    3. Domestic political risk if pain outlasts patience: Sustained economic pain could erode the broad backing that currently underwrites the stance, including support from the opposition. Eg. Higher fuel and consumer prices from a prolonged standoff could shift Canadian public opinion before comparable pressure is felt in Washington. Fix. Time targeted relief for the sectors affected by the new tariffs so public patience holds through the standoff.

    Conclusion

    The decision to reject an unfavourable trade deal, backed by calculated retaliation and prior diversification of trade ties, is being read as proof that a middle power can resist pressure from a much larger economy without folding. Whether the strategy succeeds depends on whether Canada’s own economic pain stays contained and whether Washington’s vulnerabilities, from energy prices to approval ratings, bite hard enough to force a reversal. For India, still negotiating its own trade deal with Washington, the lesson is not to reject a deal outright but to know precisely which concessions it can never afford to make.

    [2025] What are the challenges before the Indian economy when the world is moving away from free trade and multilateralism to protectionism and bilateralism? How can these challenges be met?”
  • How the Supreme Court ruling redefined ‘industry’

    Why in the News

    A nine-judge Constitution Bench of the Supreme Court revisited the definition of “industry” laid down in Bangalore Water Supply and Sewerage Board v. A. Rajappa (1978), examining how that definition interacts with the term “industry” as newly defined under the Industrial Relations Code, 2020. The 1978 ruling had given “industry” a wide, functional definition covering any organised activity involving cooperation between employer and employee for producing goods or services, regardless of profit motive. The Industrial Relations Code, 2020 narrows this definition by carving out specific exclusions. The Bench’s majority and minority opinions diverge on whether Parliament’s narrower statutory definition can override the Bangalore Water Supply test for constitutional purposes.

    What did the Bangalore Water Supply test originally hold?

    1. Triple test for “industry”: The 1978 ruling held that any activity involving systematic cooperation between an employer and workers to produce or distribute goods or services qualifies as an industry, irrespective of whether the entity is charitable, religious, sovereign, or run by the government.
    2. Sovereign function exception, narrowly read: The 1978 Bench exempted only inalienable sovereign functions of the State, such as legislation, defence, and the administration of justice, from the definition.
    3. Wide coverage of welfare and professional bodies: The test brought hospitals, educational institutions, and clubs employing staff within the definition of “industry,” extending industrial-dispute protections to their employees.
    4. Persistent legislative attempts to narrow it: Parliament had earlier attempted to codify a narrower definition through an amendment that was never brought into force, leaving the 1978 test operative for over four decades.

    What does the Industrial Relations Code, 2020 change?

    1. Statutory definition narrows the exclusions: The Industrial Relations Code, 2020 (the law consolidating the Trade Unions Act 1926, the Industrial Employment (Standing Orders) Act 1946 and the Industrial Disputes Act 1947 into a single code) defines “industry” with specific carve-outs for institutions engaged in charitable, social, or philanthropic services not for profit.
    2. Government departments performing sovereign functions excluded: The Code writes into statute an exclusion for departments discharging sovereign functions, aligning more closely with a narrower reading than the 1978 test.
    3. Domestic and hospital work carved out selectively: The Code excludes certain categories, such as purely domestic service, while leaving other categories, including some hospitals, to be decided case by case.

    Where do the majority and minority views diverge?

    1. Majority view on legislative competence: The majority holds that Parliament may legislatively define “industry” for the purposes of a labour statute, and that a narrower statutory definition prevails over the judicially evolved 1978 test within the Code’s own field of operation.
    2. Minority view on protective intent: The minority holds that a legislative narrowing of “industry” risks excluding workers in charitable, educational, and welfare institutions from industrial-dispute protections that the 1978 Bench extended to them.
    3. Divergence on precedent’s continuing force: The majority treats Bangalore Water Supply as persuasive but non-binding once Parliament legislates a definition, while the minority treats it as continuing to bind interpretation of undefined terms outside the Code’s specific carve-outs.

    Conclusion

    The ruling settles, for now, that Parliament’s statutory definition of “industry” under the Industrial Relations Code, 2020 governs disputes falling within the Code, narrowing the wide protective sweep the Bangalore Water Supply test had given workers across charitable, educational and welfare institutions for over four decades. Litigation over which specific institutions fall inside or outside the Code’s carve-outs is expected to continue as the Code is implemented.

    Back2Basics: Industrial Relations Code, 2020

    1. One of the four labour codes consolidating 29 central labour laws, this one merging the Trade Unions Act, 1926, the Industrial Employment (Standing Orders) Act, 1946, and the Industrial Disputes Act, 1947.
    2. Raises the threshold for prior government permission before layoffs, retrenchment or closure from 100 to 300 workers in an establishment.
    3. Introduces a statutory recognition mechanism for trade unions and a two-member negotiating council where no single union has majority membership.
    4. Notified but implemented in phases, with States framing their own rules under it.

    Matching Previous Year Question

    “[2024, GS3, 15 marks] Discuss the merits and demerits of the four ‘Labour Codes’ in the context of labour market reforms in India. What has been the progress so far in this regard?”

  • [24th August 2026] The Hindu OpED: Core concerns

    [24th August 2026] The Hindu OpED: Core concerns

    Question (2017, GS3): ““Industrial growth rate has lagged behind in the overall growth of Gross-Domestic-Product (GDP) in the post-reform period” Give reasons. How far the recent changes is Industrial Policy are capable of increasing the industrial growth rate?
    Linkage: The easing of the Manufacturing PMI to its lowest level since August 2021 due to weak domestic demand is a classic real-time symptom of industrial growth lagging behind overall economic expansion. It forces candidates to examine why Indian manufacturing struggles to maintain sustained momentum.

    Mentor Comment

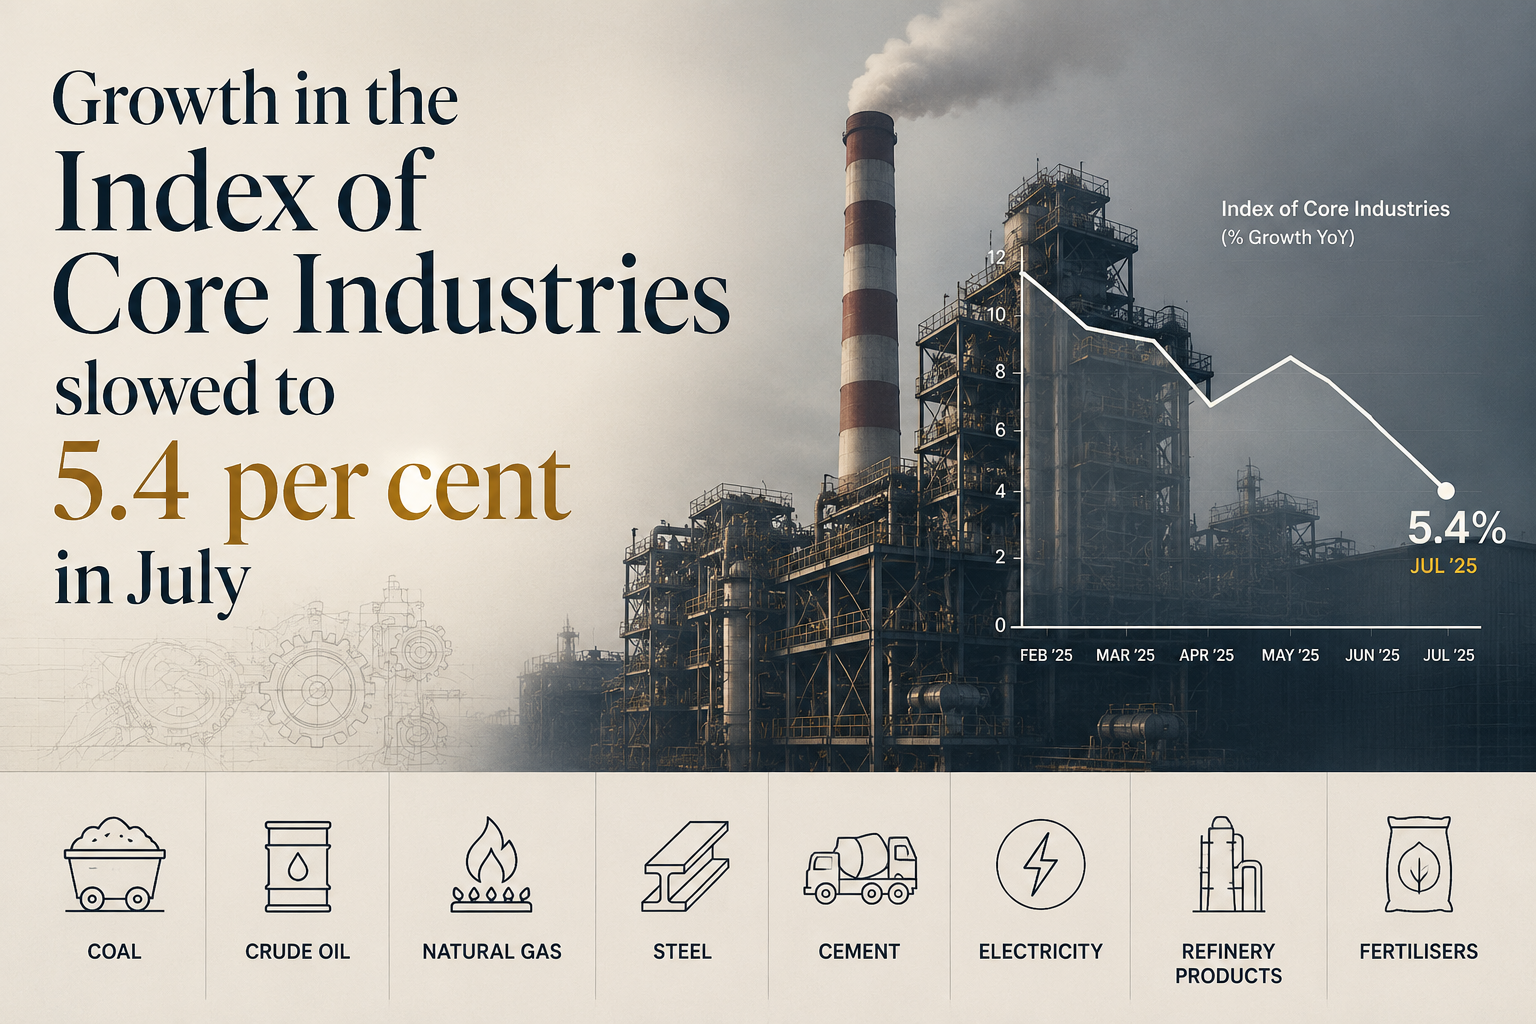
    Growth in the Index of Core Industries slowed to 5.4 per cent in July from 6 per cent in the previous month. The Manufacturing Purchasing Managers’ Index eased in the same month to its lowest level since August 2021, on weak domestic demand conditions. July’s core sector growth was still the second highest rate in the last seven months. The tension sits between that headline and its composition: a large part of the growth rests on a statistical low base effect, the two genuinely strong sectors are cement and electricity, and the domestic crude oil and natural gas sectors have contracted continuously for at least the last 14 months.

    What is the Index of Core Industries?

    • What it measures: The Index of Core Industries measures the combined production of the country’s core infrastructure industries, covering coal, crude oil, natural gas, refinery products, fertilisers, steel, cement and electricity.
    • Why it is watched: These industries carried a combined weight of about 40 per cent in the Index of Industrial Production, so the core index acts as an early read on industrial output before the fuller index is released.
    • Current series: The index is compiled on a revised new series, for which comparable data currently extends back only about 14 months.

    Why is the July core sector number weaker than it looks?

    • Growth rests on a low base: A large part of even this slower growth is based on a statistical low base effect, where a contraction in the corresponding month of the previous year makes the current month’s output look like expansion.
    • Coal illustrates the effect: The coal sector grew at an 11 month high of 7.6 per cent in July. That was measured against a contraction of 12.3 per cent in July of last year.
    • Refinery products repeat the pattern: The refinery products sector snapped a three month streak of contraction to grow at 2.7 per cent. This too was measured against a contraction in July 2025.
    • Iron ore’s strength is partly base driven: The iron ore sector grew at 29.5 per cent, slower than 44.5 per cent in June. Its comparison base is contractions of 16.4 per cent in June and 7.1 per cent in July of last year.
    • The headline flatters the trend: A rate that is second highest in seven months coexists with an easing demand signal, which means the ranking of the number matters less than what produced it.

    Which sectors are carrying the index and which are dragging it?

    • Steel has slowed sharply: The steel sector decelerated to 2.9 per cent in July from 5.6 per cent in June and 15.7 per cent in July of last year. This is a genuine slowdown rather than a base effect.
    • Hydrocarbons are a standing drag: The domestic crude oil and natural gas sectors have contracted continuously for at least the last 14 months for which the new series has data.
    • Electricity remains strong but is decelerating: The electricity sector grew at 9 per cent in July. That was slower than two consecutive months of double digit growth in May and June, which were lifted by prevalent heatwave conditions in many parts of the country.
    • Cement accelerated: The cement sector sped up to 13.1 per cent, the clearest genuine acceleration in the index.
    • The bright spots are only two: Within the core index, cement and electricity were the only two sectors reading as bright spots, and such positive trends were few and far between.

    Does the core sector number describe output or demand?

    • The two indicators point in opposite directions: The core index recorded its second highest growth in seven months in the same month that the Manufacturing Purchasing Managers’ Index fell to its lowest since August 2021.
    • They measure different things: The core index counts physical production in a set of infrastructure industries. The Manufacturing Purchasing Managers’ Index records what purchasing managers report about new orders and demand conditions.
    • A base effect can mask a contraction: A sector recovering from a deep fall registers a high growth rate at a low level of output, so a rate can rise even as demand conditions ease.
    • Weather and construction are not demand: The strongest readings came from electricity, lifted by heatwave conditions, and from cement, which tracks construction activity rather than broad consumer demand.
    • The forward reading is slack: Easing demand conditions were already being predicted by other indicators before the core sector data appeared, so the July slowdown was not a surprise.

    How is energy import dependence turning into a cost shock?

    • Import volumes are rising: India’s crude oil imports rose 13.3 per cent in volume terms in July. Liquefied Natural Gas (LNG) imports grew a more marginal 1.5 per cent.
    • Domestic supply is not filling the gap: Against the falling domestic base noted above, the economy’s appetite is being met from abroad rather than from home production.
    • The bill has jumped: High oil prices meant the crude oil import bill jumped 41 per cent in July, so a 13.3 per cent volume rise translated into a far larger payment outgo.
    • A tariff shock is queued behind it: The 100 per cent tariffs the United States is preparing to levy on countries such as India that import Russian oil will once again burden Indian exporters.
    • Blending has not yet displaced imports: Moving to 20 per cent ethanol blending has not yet impacted oil imports materially, so the substitution effect is not visible in the July numbers.

    Challenges to the Index of Core Industries as a growth signal

    • Base effects distort the headline rate: A contraction in the year ago month converts a modest recovery into a high growth print, which misleads on the level of output. Eg. Coal’s 11 month high of 7.6 per cent in July sat on a 12.3 per cent contraction in July of the previous year. Fix. Publish index levels and two year compound rates alongside the year on year rate in every release.
    • Coverage is narrow: The index tracks a small set of infrastructure industries and therefore misses most of the economy’s output. Eg. Services contribute over half of Gross Value Added and are entirely outside the core index. Fix. Publish the core index alongside a high frequency services activity indicator so the composite reading is visible.
    • Weights favour public sector heavy industries: The largest weights sit in sectors dominated by public enterprises and administered pricing, so the index responds to policy decisions as much as to market demand. Eg. Refinery products and electricity output move with administered allocation and tariff decisions. Fix. Rebase and reweight the index on a fixed cycle with published sensitivity of the headline to each sector’s weight.
    • Informal and small firm output is invisible: Production by micro and small enterprises is not captured, so a squeeze concentrated there does not register. Eg. Of about 64 million micro, small and medium enterprises, only around 14 per cent have access to formal credit and most stay outside statistical registers. Fix. Link the index to Goods and Services Tax e-way bill and electronic invoice data to capture small firm activity.
    • Provisional data is heavily revised: Early estimates are released on partial returns and are revised in later months, so a policy read taken on the first print can reverse. Eg. Iron ore’s July reading of 29.5 per cent followed a June figure of 44.5 per cent, a swing large enough to change the quarterly picture on revision. Fix. Publish a standing revision history for each sector so the reliability of the first print is visible.
    • It reads supply, not demand: The index counts what was produced, not what was bought, so it can rise while orders fall. Eg. July’s core growth of 5.4 per cent coincided with the Manufacturing Purchasing Managers’ Index at its weakest since August 2021. Fix. Present the core index and the demand side survey indicators in a single monthly dashboard rather than as separate releases.

    Conclusion

    The Indian economy looks set for a period of slack demand, higher costs and moderating growth. The July core sector reading does not contradict that: a large part of its growth is base driven, only cement and electricity grew genuinely strongly, and the sectoral spread set out above is narrow. The cost side is worsening independently, on the import bill and the tariff exposure already recorded. Whether the next few months show a genuine industrial recovery depends on domestic demand rather than on the base against which growth is measured.

    Industrial Growth in India

    • Manufacturing’s share is stuck: Manufacturing contributes around 17 per cent of Gross Domestic Product (GDP), far below the 25 per cent target set under Make in India.
    • Global standing: India holds about 2.8 per cent of global manufacturing output against China’s roughly 29 per cent, with domestic manufacturing output nearing $1 trillion in 2025-26.
    • Concentration: Maharashtra, Gujarat and Tamil Nadu account for about 40 per cent of net value added in manufacturing, and half the States have no operational Special Economic Zone.

    Government Initiatives for Industrial Growth

    • National Manufacturing Mission: Announced in the 2025-26 Budget, it unifies manufacturing policy and targets a 25 per cent GDP share with 143 million jobs by 2035.
    • Production Linked Incentive Scheme: Covers 14 sunrise and strategic sectors with outcome linked incentives, drawing over ₹1.76 lakh crore in committed investment as of March 2025.
    • Semiconductor Mission: A ₹76,000 crore framework under which 10 projects worth about ₹1.60 lakh crore have been approved.
    • Industrial Corridors Programme: India approved 11 corridors covering 32 projects, with 12 new industrial nodes cleared in 2024 for plug and play industrial cities.

    Challenges in Industrial Growth

    • Compliance load falls on small firms: Micro, small and medium enterprises face over 1,450 annual compliances, which consumes management time that would otherwise go into expansion. Eg. Annual compliance costs for such firms run to ₹13 lakh to ₹17 lakh. Fix. Adopt third party certification in place of repeat inspections, as the Ajay Shankar Committee recommended.
    • Regional concentration leaves capacity idle: Industrial value added clusters in three States, so national incentives do not translate into national capacity. Eg. Half of India’s States have no operational Special Economic Zone. Fix. Weight central incentive disbursal toward States below the national share of net value added.
    • Technology transition is slow in strategic segments: Domestic capability lags in electronics, semiconductors and renewable energy components, which keeps high value assembly abroad. Eg. India remains heavily dependent on imports for semiconductors and advanced electronic components. Fix. Extend Production Linked Incentives to upstream segments such as advanced materials and green hydrogen rather than final assembly alone.
    • Credit does not reach small manufacturers: Formal finance is unavailable to the great majority of small firms, so they cannot fund the fixed capital that raises productivity. Eg. The unmet credit demand of the micro, small and medium enterprise sector is estimated at about ₹20 lakh crore to ₹25 lakh crore. Fix. Expand cash flow based lending against Goods and Services Tax returns rather than collateral based assessment.
    • Trade barriers raise export uncertainty: Tariff action by large markets can remove the price advantage of an entire export segment without notice. Eg. The United States imposed a 50 per cent tariff in August 2025, hitting about 55 per cent of India’s exports to that market. Fix. Deepen global value chain participation through trade agreements and diversify destination markets under a China plus one strategy.
  • In a 5-4 ruling, Supreme Court for tweaking the definition of industry, exempts pending matters

    Why in the News

    A nine-judge Bench of the Supreme Court held on 20 August 2026, by a 5:4 margin, that the expansive 1978 interpretation of the term industry will not govern the Industrial Relations Code, 2020. The ruling preserves that interpretation for disputes already pending under the Industrial Disputes Act, 1947 and withdraws it from every case that follows.

    What is the ‘triple test’ laid down in Bangalore Water Supply (1978)?

    1. Origin: A seven-judge Constitution Bench in Bangalore Water Supply and Sewerage Board v. A. Rajappa (1978), authored by Justice V.R. Krishna Iyer, read Section 2(j) of the Industrial Disputes Act, 1947 expansively.
    2. The three conditions: An undertaking qualifies as an industry where there is systematic activity, organised by cooperation between employer and employee, for the production or distribution of goods or services calculated to satisfy human wants and wishes.
    3. What the test ignores: Profit motive is irrelevant to the classification. Purely spiritual or religious activity stays outside the definition.
    4. Reach: The test brought hospitals, educational institutions and municipalities within the fold of industry, exempting only core sovereign activities such as the judiciary, law and order and defence, in order to protect the state’s functional autonomy.

    What is the Industrial Relations Code, 2020?

    1. About: The Industrial Relations Code, 2020 consolidates the law on trade unions, standing orders and the settlement of industrial disputes into a single statute, and came into force in November 2025.
    2. The operative provision: Section 2(p) of the Code carries its own definition of industry, taking over the function that Section 2(j) of the 1947 Act performed for 48 years.

    What did the Supreme Court actually hold on the reach of the 1978 definition?

    1. A clean slate for the new Code: The majority held that industry under Section 2(p) of the Industrial Relations Code, 2020 would not be burdened by the 1978 interpretation of Section 2(j) of the 1947 Act.
    2. No sheet anchor: The Chief Justice of India stated that the 1978 judgment and its conclusion would not act as the sheet anchor or the foundation for any future interpretation of Section 2(p).
    3. A refinement, not a reversal: The majority found that the essential framework of the 1978 interpretation had withstood the test of time, and that some of its constituent elements could have been articulated differently to better reflect the scope and contours of Section 2(j).
    4. Prospective operation: The refined triple test evolved in the opinion of the Chief Justice of India will operate prospectively, and the modified definition will not apply to pending cases.
    5. Pending disputes protected: All matters presently pending before courts, tribunals and labour authorities under the Industrial Disputes Act, 1947 are to be adjudicated in accordance with the triple test as laid down in Bangalore Water Supply.
    6. Maintainability settled: The majority held that the reference questioning the correctness of the 1978 ruling was maintainable.
    7. Text still awaited: The fine print of the ruling prescribing the new formulation of the definition has not yet been released.

    Why was the 1978 definition sent to a nine-judge Bench at all?

    1. Docket explosion: Later Benches found that the 1978 definition produced what they called a docket explosion, bringing far more cases to the labour courts.
    2. A failed legislative narrowing: Parliament attempted to narrow the definition through the Industrial Disputes (Amendment) Act, 1982, excluding several organisations from its scope.
    3. The 2005 admission: The Centre told the Court in 2005 that no alternative dispute resolution mechanism existed for employees who would fall outside the amended definition, so the 1978 position continued to hold.
    4. Divergent readings: Subsequent rulings interpreted the 1978 judgment differently, and the case was referred to a nine-judge Bench for reconsideration.

    What three questions did the reference place before the Bench?

    1. Correctness of the test: Whether the test laid down in Bangalore Water Supply remains the correct interpretation of industry, and whether later legislative developments have any bearing on it.
    2. Welfare schemes: Whether welfare schemes run by the government count as an industrial activity.
    3. Sovereign function: What constitutes a sovereign function of the state, and whether such functions fall outside the ambit of labour law altogether.
    4. When framed: The Court identified these three broad questions for consideration in February 2026.

    Why does preserving the 1978 test only for pending cases divide the workforce in two?

    1. Two regimes running side by side: A dispute already filed under the 1947 Act is decided on the wide 1978 definition. An identical dispute arising under the Code is decided on a definition that has not yet been written out.
    2. The Court’s own reason: The majority stated that it did not intend to displace the governing legal position on pending proceedings, since doing so would create artificial discrimination.
    3. What the wide net secured: The 1978 definition enabled workers across a wide range of jobs to obtain legal recourse on wages, working hours, strikes, collective bargaining and protection against arbitrary dismissal.
    4. What the clean slate removes: Workers whose disputes arise after the Code’s commencement lose the settled presumption that their workplace is an industry, and must establish it afresh under Section 2(p).

    What does the dissent argue about the State as an employer?

    1. Reference itself questioned: Justice B.V. Nagarathna found the reference against the 1978 verdict unwarranted and not maintainable, and held that the ruling required no interference or modification.
    2. Identity of the employer is irrelevant: The dissent held that merely because a function is performed by the State, it cannot be exempted from the definition of industry, so the test of who carries out the activity is not relevant.
    3. Nature of the activity governs: Social welfare activities and schemes undertaken by government departments or their instrumentalities can be construed as industrial activities for the purpose of Section 2(j), depending on the nature of the activity and all other relevant factors.
    4. Why it matters now: The dissent held that it was important, now more than ever, to retain the inclusive definition of industry to safeguard workers’ rights.
    5. Split within the majority side: Justice Joymalya Bagchi recorded disagreement with the majority on the reformulation of the triple test, and Justices Dipankar Dutta and Ujjal Bhuyan wrote dissenting opinions.

    What challenges follow from redefining ‘industry’ under the new Code?

    1. Coverage uncertainty until the operative text arrives: The modified formulation was pronounced without the wording that prescribes it being available, so adjudicating authorities have no text to apply. Eg. The hour-long pronouncement on 20 August 2026 ended with the fine print of the new formulation still awaited.
    2. Identical workplaces treated differently by filing date: The cut-off is the date of the proceeding, not the nature of the work, so two workers in the same undertaking can face different definitions. Eg. A dispute in a municipal water supply undertaking filed under the 1947 Act is decided on the triple test, and one arising afterwards is not.
    3. No fallback forum for excluded categories: Narrowing the definition removes workers from the industrial adjudication machinery without putting anything in its place. Eg. The Centre itself told the Court in 2005 that no alternative dispute resolution mechanism existed for employees who would fall outside a narrowed definition.
    4. Threshold effects that discourage firms from growing: The Code applies its stricter obligations only above stated headcounts, which gives firms a reason to stop hiring below the line. Eg. Standing orders now apply at 300 employees and prior approval for layoff, retrenchment and closure applies at 300 workers, both raised from far lower thresholds.
    5. The sovereign function boundary left to case-by-case litigation: The Court has framed the question of what a sovereign function is without settling a workable test for it. Eg. Whether a government-run welfare scheme is an industrial activity was one of the three questions placed before the Bench in February 2026.
    6. A definition built for a standard employment relation: The triple test turns on cooperation between employer and employee, which platform-mediated work does not fit. Eg. Gig and platform workers are addressed through the Code on Social Security, 2020 rather than through the industrial dispute machinery.

    Conclusion

    The Court has separated the past from the future of a single statutory term, keeping Justice Krishna Iyer’s wide definition alive for disputes already in the system and denying it any authority over the Code that now governs Indian industrial relations. The substantive contest has therefore moved from the judiciary to the text of Section 2(p) and to whoever interprets it first. The Industrial Relations Code, 2020 has been in force since November 2025, and the next milestone is the release of the full text of the judgment carrying the refined formulation of the triple test.

    “[2024, GS3, 15] Discuss the merits and demerits of the four ‘Labour Codes’ in the context of labour market reforms in India. What has been the progress so far in this regard?”