💥Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

GS Paper: GS3

  • [2nd September 2026] The Hindu OpED: The two balance sheets behind every e-waste decision

    [2nd September 2026] The Hindu OpED: The two balance sheets behind every e-waste decision

    Question (2018): “What are the impediments in disposing the huge quantities of discarded solid wastes which are continuously being generated? How do we remove safely the toxic wastes that have been accumulating in our habitable environment?
    Linkage: Discarded computers, servers, and networking systems are a rapidly growing source of toxic and solid electronic waste. This question directly addresses the core administrative and logistical bottlenecks that prevent advanced recycling from becoming the default choice in India.

    Mentor Comment

    Governments and companies replace thousands of computers, servers, networking devices and storage systems every few years, and this discarded equipment holds copper, aluminium, gold, silver, palladium and critical minerals. Advanced recycling of such equipment has still not become the default choice in India. The reason is that procurement in both the public and private sectors rewards the lowest visible cost at the point of disposal. Every disposal decision creates two balance sheets, one financial and closed with the transaction, the other strategic and open long after it. The lowest-price principle that secures transparency and fiscal discipline in public procurement now sits in tension with the lifetime cost of decisions in electronics, batteries and renewable energy.

    What is urban mining?

    1. Definition: Urban mining is the recovery of valuable materials from products that have already served their purpose, in place of extracting fresh ore from the earth.
    2. The ore body: Discarded IT equipment is among the largest untapped sources of strategic raw materials as economies digitise, and it is hazardous waste when poorly handled.
    3. What safe recovery needs: Sophisticated technology, secure data destruction, environmentally compliant processing and traceable supply chains, with collection and segregation adding to the cost.

    Why has advanced recycling not become the default choice in India?

    1. Procurement rewards the lowest visible cost: Public and private buyers maximise resale value and minimise processing cost when they dispose of equipment.
    2. Strategic value stays off the invoice: Recovery of critical minerals, secure data destruction, environmental benefit and domestic industrial capability rarely appear in the price that decides the contract.
    3. The gains accrue to others: Less virgin mining, stronger domestic supplies of critical materials, lower import dependence and responsible handling of hazardous components are benefits the disposing organisation does not book.

    What are the two balance sheets every disposal decision creates?

    1. The first, financial and immediate: Purchase price, resale value and savings achieved, all measurable, auditable and reflected in annual budgets.
    2. The second, strategic and open ended: It stays open long after the transaction and records resource security, environmental sustainability, industrial capability, supply-chain resilience, public health and national competitiveness.
    3. Good governance manages both: Some investments look expensive at first and later transform economies. Eg. Fifteen years ago solar power struggled to compete with conventional electricity on cost and governments that invested early were criticised for paying too much. Scale and learning have since made solar one of the world’s cheapest sources of electricity, and countries that built manufacturing capacity early hold advantages a cost comparison could not have predicted.

    How do the costs left off the invoice return later?

    1. Recovery priced against disposal: Investment in urban mining infrastructure looks expensive when judged only against the cost of disposing of a computer. The calculation changes when recovered materials, avoided imports, environmental safeguards, data security and future industrial capability are counted together.
    2. Pollution becomes health-care expenditure: The public health cost of unsafe processing lands on the exchequer years after the disposal saving was booked.
    3. Resource depletion becomes import dependence: Metals not recovered at home are bought abroad, raising manufacturing costs.
    4. Weak domestic capability becomes strategic vulnerability: An economy without recovery capacity depends on others for the materials its industry runs on.
    5. Environmental costs turn economic: Governments spend more on remediation, businesses face higher compliance costs and citizens pay through taxes and lost productivity. The costs are delayed or redistributed and rarely avoided.

    What should an organisation ask before selecting a recycler?

    1. Secure data destruction: Whether sensitive data on the equipment is securely destroyed before any material moves.
    2. Refurbishment before recycling: Whether working equipment is refurbished for reuse before it is broken down for materials.
    3. Efficient and transparent mineral recovery: Whether critical minerals are recovered efficiently and the recovery is traceable.
    4. The cost of skipping the questions: A marginal gain today becomes tomorrow’s cybersecurity risk, import dependence, reputational damage and permanent loss of strategic resources.

    Can the lowest-price principle survive in sectors where acquisition cost is not lifetime cost?

    1. What the principle protects: Governments have relied on the lowest-price rule to ensure transparency and fiscal discipline in public spending.
    2. Where it fails: Renewable energy systems, batteries, electronics and advanced manufacturing are sectors where the lowest acquisition cost is rarely the lowest lifetime cost.
    3. The alternative many countries have adopted: Life-cycle costing (pricing an option across purchase, operation, disposal and recovery rather than at purchase alone) and value-based procurement ask which option delivers the greatest long-term public value. Procurement then becomes a tool of industrial policy that shapes which technologies scale and which capabilities are built.
    4. The same logic in compliance markets: Judging Extended Producer Responsibility (EPR, the obligation on a producer to finance the collection and recycling of the products it sells) compliance on the cheapest available certificate rewards the lowest-cost provider over the highest-quality outcome. Rewarding traceability, recovery efficiency and technological capability would instead draw investment into advanced recycling and strengthen India’s domestic supply of critical minerals.

    Challenges to urban mining of e-waste in India

    1. Fake certificates break traceability: An EPR certificate market cannot reward quality when the certificates themselves are unverified. Eg. The Central Pollution Control Board (CPCB) found over 600,000 fake recycling certificates in 2023 across Gujarat, Maharashtra, Karnataka.
      The Fix: Digitise certificate tracking against audited mass balance at each registered recycler, with cancellation of registration for a fake certificate.
    2. A floor price too low to sustain formal recycling: EPR pricing set below the cost of compliant recovery pushes material to informal and fraudulent channels. Eg. In April 2025 Daikin, Hitachi and Samsung sued the government opposing the mandated minimum recycler price.
      The Fix: Index the floor price to the audited cost of compliant recovery and revise it annually through a published formula.
    3. Inefficient recovery loses the minerals the policy exists to secure: Crude recycling wastes lithium, cobalt, nickel, copper, gold and silver. Eg. Improper battery handling alone could cost India over USD 1 billion in foreign exchange by 2030.
      The Fix: Fund research in advanced shredding, bioleaching and non-thermal recovery and tie EPR credit to recovery efficiency rather than to tonnage collected.
    4. No domestic refining of precious metals: Indian recyclers dismantle equipment and export the printed circuit boards, so the highest-value step happens abroad. Eg. Circuit boards from Indian dismantlers are shipped to integrated smelters in Belgium, Japan and South Korea for gold and palladium refining.
      The Fix: Mandate a minimum domestic refining share within EPR targets and treat integrated refining as eligible infrastructure under the critical mineral recycling incentive.

    Conclusion

    India’s discarded IT equipment will become either a strategic reserve or an environmental liability, and the deciding instrument is the procurement rule rather than the recycling technology. The reform that follows is to score public disposal tenders on lifetime value. That means amending the General Financial Rules, 2017, the rules for central procurement, so that a tender can weigh quality of recovery against the immediate price. The unresolved question is who pays: the buyer who funds advanced recycling is not the one who gains from resource security, and no mechanism yet closes that gap.

    E-Waste Management in India

    1. Scale: As per the CPCB, India generated 14,14,645 metric tonnes (about 1.41 million tonnes) of e-waste in 2025-26 till March 2026, of which 9,79,080 metric tonnes (about 0.98 million tonnes) was recycled.
    2. Global standing and growth: India is the third largest generator behind China and the United States. Volumes surged over 150 percent in six years from 0.71 million tonnes in 2017-18 and are projected to nearly double by 2030.
    3. Formal capacity: 386 registered recyclers across 19 States and Union Territories offer a capacity of about 34.66 lakh metric tonnes per annum.
    4. Concentration: Just 65 cities generate over 60 percent of total e-waste, and 10 States account for around 70 percent.

    Laws and Rules Governing E-Waste Management

    1. Environment (Protection) Act, 1986: The parent statute under which every set of e-waste rules is notified.
    2. E-Waste (Management) Rules, 2016: Introduced the Producer Responsibility Organisation (PRO) concept.
    3. E-Waste (Management) Rules, 2022: Make EPR the core engine, mandate registration of all producers, refurbishers and recyclers on the CPCB portal, and expand coverage from 21 to 106 electrical and electronic equipment items.
    4. E-Waste (Management) Second Amendment Rules, 2023: Added provisions for safe, sustainable refrigerant management in refrigeration and air-conditioning manufacturing.
    5. E-Waste (Management) Amendment Rules, 2024: Enabled CPCB supervised platforms for trading EPR certificates, priced between 30 percent and 100 percent of the environmental compensation for non-compliance.
    6. Hazardous and Other Wastes (Management and Transboundary Movement) Amendment Rules, 2025: Introduced an EPR framework for non-ferrous metal scrap, with targets rising from 10 percent in 2026-27 to 75 percent in 2032-33.
    7. Basel Convention, 1989: India is a signatory to this treaty limiting the transboundary movement of hazardous waste, including e-waste.

    Challenges in E-Waste Management

    1. Informal-sector dominance: Over 50 percent of e-waste is handled informally through open-air burning and acid leaching, exposing workers and residents to respiratory illness, neurological damage and DNA damage. Eg. Acid leaching of circuit boards in Moradabad releases toxic slurry into the Ramganga and local groundwater.
      The Fix: Train waste-pickers as certified green collar technicians with protective gear, certification and links to healthcare, insurance and pensions.
    2. Illegal imports: Developed nations export e-waste to India under cover of used goods. Eg. 29 illegal-import instances were identified during 2019-22 across Tamil Nadu, Maharashtra, Gujarat, West Bengal and Uttar Pradesh.
      The Fix: Pre-shipment inspection of used electronics consignments at ports under the Basel Convention notification procedure.
    3. Low awareness in the trade itself: The people who handle discarded electronics first do not know the rules. Eg. A 2021 Delhi study found 70 percent of repair workers and 79 percent of scrap dealers unaware of e-waste rules.
      The Fix: Run registration and awareness campaigns through resident welfare associations and self-help groups linked to registered collection points.
    4. Uneven infrastructure: Recycling capacity and expertise are concentrated in a few States. Eg. Telangana has built formal capacity, and Chandigarh lacks formal facilities.
      The Fix: Set up decentralised recycling hubs in every State with a collection target tied to the State’s generation share.
  • Majority of India’s gig workers remain out of govt’s reach

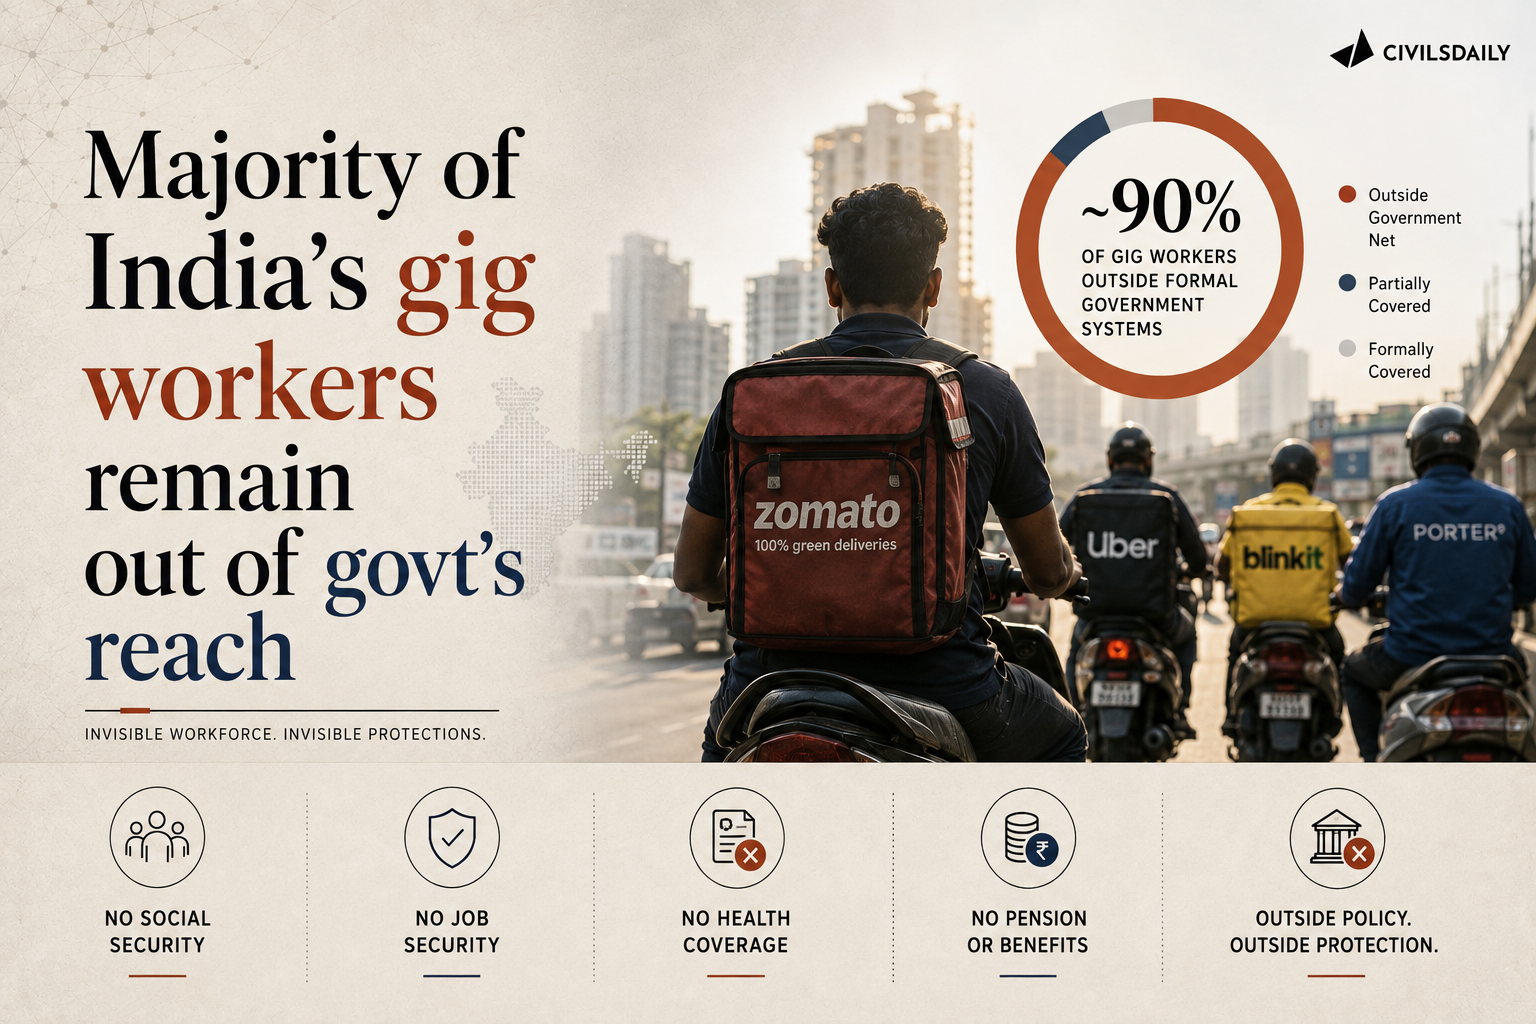
    Majority of India’s gig workers remain out of govt’s reach

    Why in the News

    Only 8.58 lakh gig workers stood registered on the e-Shram portal as of the Ministry of Labour and Employment’s reply in the Rajya Sabha in January 2026, the latest publicly available figure.

    How far has the Budget’s health cover promise actually reached?

    1. Registration against the promise: The Budget’s beneficiary figure of over one crore compares with 8.58 lakh registrations on e-Shram, the figure the Ministry gave Parliament in January 2026.
    2. The optimistic case still falls short: A doubling of registrations since January would still cover only around 15 percent of the estimated gig workforce.
    3. The promise itself drove enrolment: Registrations of gig workers on e-Shram rose sharply from 2025, and the health cover announcement is the visible cause of that surge.
    4. Registration is the gate to every benefit: Registration on e-Shram is a prerequisite for availing benefits, so an unregistered gig worker is invisible to the scheme by design.

    Why does the government not know how many gig workers India has?

    1. One source for every estimate: The figure of over one crore gig workers, quoted in many government replies in Parliament last year, comes from a single document, the NITI Aayog report “India’s Booming Gig and Platform Economy” released in June 2022.
    2. What that report estimated: It put the gig workforce at around 77 lakh in 2020-21 and projected 1.27 crore in 2024-25 and 1.43 crore in the year after.
    3. No dedicated measurement effort exists: In the absence of any effort to measure the gig workforce, official estimates rely solely on this NITI Aayog report.
    4. The national labour survey does not count them: The Periodic Labour Force Survey (PLFS) reports do not capture gig workers as a distinct category, even though the estimated gig workforce is about 2 percent of India’s total workforce of 61.6 crore as cited by the 2025 PLFS report.

    What has the government built for gig workers, and what has not arrived?

    1. e-Shram as the single register: The portal, launched in 2021, is conceptualised as an Aadhaar-seeded National Database of Unorganised Workers (NDUW) and has become the unified platform for tracking the unorganised workforce, including gig workers.
    2. A legal definition came only in 2020: The government officially defined a gig worker only in the Code on Social Security, 2020, which came into force last year.
    3. The Code’s promises remain largely on paper: The Code promised accident insurance, maternity benefits and a dedicated social security fund for gig workers, and most of these are yet to materialise.

    Where are the registered gig workers, by State and by sector?

    1. Registrations are uneven across States: The ten States with the most registered gig workers as of January 2026 are led by West Bengal (54,734), Delhi (49,479), Andhra Pradesh (39,212), Rajasthan (38,205), Karnataka (37,871), Gujarat (34,756) and Madhya Pradesh (34,351), with Maharashtra, Uttar Pradesh and Bihar completing the list.
    2. Urbanised southern States are missing from the top ten: Tamil Nadu (31,654), Telangana (29,951) and Keralam (11,219) are not among the ten States with the highest registrations, despite their high urbanisation.
    3. Twenty one sectors on paper, three in practice: NITI Aayog’s 2022 report listed 21 sectors with gig workers, including agriculture, healthcare, education and retail, but e-Shram registrations concentrate in the food industry, transportation, and domestic and household work.
    4. The sector shares are lopsided: The largest single sector accounts for 32.8 percent of registered gig workers, and construction (3.6 percent) and agriculture (3.4 percent) are the smallest of the top five sectors.

    Challenges to e-Shram as the gateway for gig worker welfare

    1. Enrolment depends on the worker, not the platform: e-Shram is a self-registration portal, and no aggregator is obliged to enrol the workers it engages. Eg. The Rajasthan Platform Based Gig Workers (Registration and Welfare) Act, 2023 instead makes aggregators register their workers with a State welfare board.
      The Fix: Require aggregators to push worker data into e-Shram at onboarding under the Code on Social Security, 2020, so registration stops depending on individual initiative.
    2. No survey category means no target to measure against: Without a gig work module in the labour survey, the government cannot say what share of the workforce any scheme covers. Eg. The Ministry’s January 2026 reply to Parliament could cite portal registrations but no survey count.
      The Fix: Add a platform and gig work classification to the PLFS questionnaire so coverage is measured against a surveyed denominator.
    3. The funding source has not been built: The Code provides for aggregator contributions of 1 to 2 percent of annual turnover, capped at 5 percent of payments to workers, and the fund those contributions were to feed has not materialised. Eg. Karnataka’s Platform Based Gig Workers (Social Security and Welfare) Act, 2025 levies its own transaction fee because no central fund is flowing.
      The Fix: Notify the contribution rules and the social security fund so central benefits do not depend on Budget-by-Budget announcements.
    4. State schemes fragment portability: State-level gig worker boards create separate registrations and benefits for a workforce that moves across State lines. Eg. A delivery worker registered in Rajasthan gains nothing from Karnataka’s fund on relocating.
      The Fix: Make e-Shram the single identifier that State boards read from, so benefits follow the worker across States.

    Conclusion

    The health cover promise has produced registrations faster than any earlier measure, but the register still holds a fraction of the workforce the promise was made for. The deeper problem is a denominator the state has never measured. The next e-Shram registration figure released to Parliament, and whether the Code’s social security fund is finally notified, are the two markers to watch.

    Back2Basics: Gig worker and platform worker under the Code on Social Security, 2020

    1. Gig worker: A person who performs work or participates in a work arrangement and earns from such activities outside the traditional employer-employee relationship.
    2. Platform worker: A person in platform work, meaning work arranged through an online platform that connects organisations or individuals with workers to provide specific services for payment.
    3. Aggregator: A digital intermediary or marketplace through which a buyer or user connects with a seller or service provider, the entity the Code identifies for contributions.
    4. Why the definitions matter: They are the first statutory recognition of gig work in India, and eligibility for the Code’s social security schemes is tied to them.

    [2024, GS3, 15 marks] Discuss the merits and demerits of the four ‘Labour Codes’ in the context of labour market reforms in India. What has been the progress so far in this regard?”

  • Foreign Assets Disclosure Scheme: Concerns rise over high fee on ESOPs, small investments

    Why in the News

    The Foreign Assets of Small Taxpayers – Disclosure Scheme (FAST-DS), launched on 16 August, charges a flat Rs 1 lakh fee to disclose a foreign asset that was already taxed or acquired as a non-resident but was not declared in the income tax return. Salaried employees holding unreported employee stock ownership plans (ESOPs) and restricted stock units (RSUs) (shares granted by an employer as part of pay, vesting over time) must pay the fee even where they made no gain. The scheme was proposed in this year’s Budget to address the “practical issues of small taxpayers like students, young professionals, tech employees, relocated NRIs”. The tension is between a fee designed as a low-cost route to compliance and a flat amount that exceeds the value of many of the assets it is meant to regularise.

    What are the two categories under FAST-DS?

    1. Where the complaints sit: The dispute is entirely about Category (ii), where the asset was never untaxed and the only lapse is non-disclosure in the return.
    2. The alternative the Act blocks: The Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015 does not recognise an updated return for income that was never taxed or disclosed, so an updated return does not cure the lapse.

    Why does a flat fee fall hardest on the smallest disclosers?

    1. Fee exceeding the asset: A salaried individual who invested Rs 90,000 in United States-listed stocks, now trading at a loss, must pay Rs 1 lakh upfront to disclose the loss-making holding. The transfer already appeared in the Annual Information Statement (AIS) of his return; only the separate Schedule FA entry was missing.
    2. Fee on salary already reported: An employee of a foreign company operating in India had the vesting details of his ESOPs in his salary but not in Schedule FA. He must pay Rs 1 lakh as a disclosure charge on income that was already part of his taxed pay.
    3. The employee’s objection: ESOPs are part of salary, and Rs 1 lakh for disclosure alone is too high a price for a reporting omission.
    4. The materiality test: Materiality is the maximum error allowed in financial statements before they are considered wrong. Where the amounts fall below any reasonable materiality threshold, a Rs 1 lakh penalty is disproportionate to the error.

    Why are ESOPs and residency status at the centre of the dispute?

    1. Non-residents who became residents: Many employees received ESOPs from their global companies as non-resident Indians (NRIs) and were later deputed to India, becoming residents. They did not disclose the old grants earlier and are disclosing them now.
    2. Disclosure invites a notice: After disclosure, the discloser receives a notice asking how the asset was acquired. The position put to the authorities is that the change from non-resident to resident status must be recorded before such notices issue.
    3. ESOPs as a mainstream pay component: ESOPs are a key salary component in the technology sector, startups and foreign companies. The scale shows in the Balance of Payments (BoP) line for “financial derivatives (other than reserves) and employee stock options”.
    4. The outflow figures: Net outflows under that BoP line stood at just under $24 billion in 2025-26, up 8 per cent from about $22 billion in 2024-25. The 2024-25 figure had itself almost tripled from nearly $8 billion in 2023-24.

    Is the updated return a way around the scheme?

    1. What employees are considering: Many employees are weighing an updated return for such anomalies instead of disclosing under the scheme, with greater scrutiny after disclosure the key concern.
    2. The tax department’s position: Even if an updated return is filed, the discloser remains liable to tax and penalty under the Black Money Act, because the Act does not recognise updated returns for income never taxed or disclosed. Disclosure under FAST-DS is therefore the safer route, and the department states there is no intention of additional scrutiny of such declarations.

    Challenges to FAST-DS

    1. A flat fee suppresses uptake: A disclosure window succeeds only if the cost of using it is below the cost of staying hidden, and a fee larger than the asset inverts that calculation for small holders. Eg. The 90-day compliance window under the Black Money Act in 2015 drew only 644 declarations totalling Rs 4,164 crore.
      The Fix: Slab the Category (ii) fee by asset value, with a nominal fee below a stated threshold.
    2. The department already holds the data: For many disclosers the asset is visible in the AIS or through automatic exchange of financial account information, so the fee is charged for reporting what the department can see. Eg. India receives account data on residents’ foreign holdings under the Common Reporting Standard, with exchanges running since 2017.
      The Fix: Pre-fill Schedule FA from AIS and exchanged data and treat a confirmed pre-filled entry as compliance without a separate fee.
    3. Post-disclosure notices deter the target group: Relocated professionals who disclose and then receive an acquisition notice signal to others that disclosure invites inquiry. Eg. Notices asking how an ESOP grant was acquired reach employees whose grant date predates their residency.
      The Fix: Issue a standing instruction that Category (ii) disclosures carrying non-resident acquisition dates close without notice unless a third-party data mismatch exists.

    Conclusion

    The scheme’s design assumes the small taxpayer’s problem is fear of the Black Money Act, when for ESOP holders the problem is a fee unrelated to the size of the lapse. That mismatch is unresolved and no revision of the fee has been announced. The scheme is open and the source states no closing date. What to watch is whether the Central Board of Direct Taxes slabs the Category (ii) fee or clarifies the treatment of grants acquired as a non-resident.

    Back2Basics

    1. Schedule FA: Schedule FA (Foreign Assets) is the part of the income tax return in which a resident and ordinarily resident taxpayer must list every foreign asset held at any time in the year, including shares, ESOPs, bank accounts and immovable property, whether or not it produced income.
    2. Who must file it: The obligation applies to residents only, so a non-resident who acquired an asset abroad first becomes liable to report it in the year he becomes resident.
    3. The penalty it carries: Failure to report attracts a penalty of Rs 10 lakh under the Black Money Act, relaxed from 2024 for movable foreign assets, other than immovable property, of up to Rs 20 lakh in aggregate.

    [2026] Which one of the following best describes the ‘Crowding Out Effect’ in the context of fiscal policy?

    (a) A situation where private investment increases due to increased Government spending

    (b) A situation where Government borrowing leads to higher interest rates, which reduces private investment

    (c) A situation where an increase in taxes leads to increased private sector investment

    (d) A situation where Government spending has no impact on aggregate demand

  • India’s data centre boom is colliding with its climate reality

    Why in the News

    India’s data centre capacity is set to grow from about 1.5 gigawatts (GW) today to 6.5 GW by 2030, a fourfold expansion in four years, on investment the government estimates at nearly $200 billion over the coming decade. Google, Meta, Amazon and Microsoft have committed billions to build facilities, and States are competing for them with tax exemptions, cheap land and duty waivers. No policy document at the Central or State level has assessed what guaranteed power costs a grid already strained under 45 degree Celsius heat, where cooling water will come from, or what the thermal load of thousands of servers does to regions already near dangerous temperatures. The tension is that the facilities are clustering in exactly the regions where water and grid stress are most acute, and State policies attach almost no conditions to the incentives they offer.

    Why is the scale of the build-out itself the problem?

    1. A fourfold expansion in four years: Capacity nearly tripled from 520 megawatts (MW) in 2020 to nearly 1.5 GW today. The 6.5 GW projected for 2030 compresses the next round of growth into four years.
    2. Electricity demand more than quadruples: Demand from data centres is expected to rise from about 13 terawatt-hours (TWh) in 2024 to roughly 57 TWh by 2030. The Union Ministry of Power estimates that artificial intelligence alone will add 26.3 GW of new demand by 2031-32.
    3. States compete on incentives, not conditions: Maharashtra wants to be the data centre capital. Telangana has declared data centres “essential services”. Karnataka is reviewing its policy to attract more, and Rajasthan is offering tax exemptions and cheap land.

    Why does data centre water use collide with groundwater stress?

    1. The volume per facility: A 100 MW data centre consumes about 2 million litres of water daily, equal to the daily use of roughly 6,500 households. India’s data centres consumed an estimated 150 billion litres in 2024-25, projected to more than double to 358 billion litres annually by 2030.
    2. Clustering in the most stressed regions: Rajasthan extracts 147.11 per cent of its annual groundwater recharge, the second highest rate in the country. Several groundwater assessment units in Maharashtra are classified as semi-critical. Telangana’s Irrigation Minister confirmed in May 2026 that 16 districts were under groundwater stress.
    3. Cities already rationing: Hyderabad’s surface water supply dropped 20 per cent in the summer of 2024 on poor monsoon recharge, forcing the water board to ration supply. Mumbai’s reservoirs stood at 44.5 per cent of capacity in March 2026.
    4. Unaccounted in every State policy: No State policy requires public disclosure of daily water consumption. None requires a hydrogeological assessment before approval. None mandates that water sourcing must not compete with agriculture or municipal supply.

    Why can the grid not deliver the power the boom needs?

    1. Record peaks and interconnection queues: Maharashtra’s peak demand hit 27,230 MW in April 2026, the highest ever handled by the State utility. Two-year waits for 220 kV grid interconnections across the country are lengthening project timelines.
    2. Renewable power is being thrown away: India curtailed 300 gigawatt-hours of renewable energy in the first quarter of 2026 alone because the grid could not carry it, per an Ember Energy analysis of Central Electricity Authority data. Over five years India has met only about 80 per cent of its annual transmission targets, one in four major transmission schemes runs a year or more behind schedule, and 20 GW of renewable capacity faces connectivity delays of more than four months.
    3. Wires lag panels: Rajasthan and Gujarat house the bulk of utility-scale solar and wind. Both face the longest queues at pooling stations (substations where several renewable plants aggregate output before it enters the transmission grid). Solar projects are being built faster than the lines to carry their power.
    4. The coal default: Data centres need reliable, uninterrupted electricity. If renewable power cannot reach them, the power comes from coal, adding to the emissions India is trying to curtail.

    How do data centres make their surroundings hotter?

    1. The satellite evidence: A March 2026 University of Cambridge study of 20 years of NASA satellite data found that data centres raise land surface temperatures by an average of 2 degree Celsius within a 10 km radius, with extreme cases reaching 9.1 degree Celsius. About 340 million people globally live within these affected zones.
    2. Indian cities are already at the edge: Mumbai’s land surface temperature rose from 40.9 degree Celsius in 2003 to 47.3 degree Celsius in 2023, driven largely by urbanisation and heat-trapping infrastructure. Hyderabad’s urban heat island intensity ranges from 5.74 to 6.82 degree Celsius, its urban area doubled between 2001 and 2020, and it recorded temperatures above 43 degree Celsius in the summer of 2024.
    3. The feedback loop: Data centres generate heat, and that heat raises ambient temperature. Higher ambient temperature increases cooling demand. Higher cooling demand raises electricity consumption. Unless that electricity is fully renewable, emissions rise and feed the climate change that is making India hotter.

    Do State policies ask for anything in return for their incentives?

    1. Generous on incentives: State policies offer electricity duty exemptions, transmission charge waivers, stamp duty relief and fast-track clearances.
    2. Silent on conditions: None of the major State policies requires a grid impact assessment before commissioning, mandatory renewable energy sourcing, or a thermal load assessment for surrounding communities.
    3. Telangana guarantees power in a stressed State: The “essential services” classification guarantees data centres uninterrupted power even during shortages, in a State where 16 districts face groundwater stress and temperatures have reached 47 degree Celsius.
    4. Maharashtra diluted its own mandate: The State’s policy originally required 100 per cent renewable energy for core operations. In June 2026 it cut the requirement to 51 per cent, framed as improving project viability.
    5. The exceptions, and their limit: Gujarat’s Data Centre Policy 2026-29 mandates at least 51 per cent green energy sourcing. Karnataka’s IT Minister told the Assembly in March 2026 that the State was reviewing its policy over water and energy concerns, and Tamil Nadu has linked incentives to renewable compliance. Even where mandates exist, enforcement and verification remain weak.

    Why is the constraint market design rather than generation capacity?

    1. Capacity is not the bottleneck: The Union Ministry of Power holds that India’s generation pipeline can absorb the additional demand from data centres. The constraint is market design and transmission infrastructure.
    2. Price grid services separately: The Council on Energy, Environment and Water (CEEW) argues for climate-intelligent power markets in which short-term markets pay separately for ramping, storage and demand response.
    3. Storage at the pooling station: Ember calculates that roughly 3 to 4 GW of two-hour battery storage at renewable pooling stations could have absorbed most of the generation curtailed in early 2026. The technical pieces exist; the gap is regulatory and commercial.

    What should a national sustainability framework contain?

    1. Enforceable use standards: CEEW proposes phased power and water use standards with enforceable benchmarks, and a national AI Energy Star rating that lets buyers and regulators compare how energy efficient a facility or model actually is.
    2. Who pays for the grid: The Institute for Energy Economics and Financial Analysis (IEEFA) warns that a significant part of the associated infrastructure cost could be socialised. Where wider grid infrastructure is required, government support or dedicated financing should stop the cost being passed to consumers through higher tariffs.
    3. Siting away from stressed hubs: IEEFA points to coastal locations. These offer proximity to near-shore wind and solar, and seawater cooling without desalination. Most facilities instead cluster around Mumbai, Hyderabad, Bengaluru and the National Capital Region, where water and grid stress are most acute.
    4. Four minimum standards: A national framework would set minimum standards for renewable energy sourcing, water consumption disclosure, grid impact assessment and thermal load evaluation. It would give investors one set of expectations and consumers one set of protections, on the premise that environmental constraints are economic constraints.

    Challenges to a national data centre framework

    1. Split jurisdiction: Water is a State List subject and electricity sits on the Concurrent List, so a Central standard on water sourcing or grid impact binds no State unless the State adopts it. Eg. The Ministry of Electronics and Information Technology’s draft National Data Centre Policy of 2020 addressed infrastructure status and single-window clearance, not resource standards.
      The Fix: Route the standards through the Central Electricity Authority’s technical standards and the Bureau of Energy Efficiency, which already bind connected consumers, and tie Central incentive money to State adoption.
    2. Mandates without metering: A renewable sourcing mandate is only as good as the verification behind it, and discoms already miss the obligations they carry. Eg. State distribution companies have missed Renewable Purchase Obligation targets for years, forcing the Ministry of New and Renewable Energy to renotify trajectories.
      The Fix: Require third-party audited reporting of power usage effectiveness and water usage effectiveness (ratios of total facility energy and water to that used by computing equipment) as a condition of every incentive.
    3. Cooling technology is a trade-off, not a free fix: Liquid and immersion cooling cut water use but raise capital cost and still dump heat locally. Eg. Evaporative cooling, the cheapest option at 45 degree Celsius, is also the most water intensive.
      The Fix: Set the water standard by climate zone rather than one national number, so a coastal seawater-cooled site and an inland Rajasthan site face different limits.

    Conclusion

    The data centres will be built, and the only open question is on whose terms. The unresolved tension is between States competing on incentives and a resource base that no State policy has been made to account for. What to watch is whether the Centre converts the four standards, renewable sourcing, water disclosure, grid impact and thermal load, into an enforceable national framework before the projected capacity is locked in. The nearer marker is whether Karnataka’s policy review produces conditions or only more incentives.

    Back2Basics

    1. Urban heat island: An urban heat island is the difference in temperature between a built-up city and its rural surroundings, caused by concrete, asphalt and roofs absorbing and re-emitting heat that vegetation and soil would have released through evaporation.
    2. Intensity: Its intensity is that temperature gap in degrees, so Hyderabad’s 5.74 to 6.82 degree Celsius means the city runs that much hotter than its surroundings at the same hour.
    3. Why data centres add to it: Servers convert almost all the electricity they draw into heat, and cooling systems reject that heat into the surrounding air or water, so a large facility acts as a fixed heat source inside the island.

    “[2026] Which of the following statements with regard to Green Hydrogen is/are correct?

    1. It is decarbonized hydrogen obtained from natural gas reforming combined with carbon capture and storage (CCS).

    2. It is produced using electrolysis of water with electricity generated by renewable energy.

    3. National Green Hydrogen Mission of India aims for abatement of nearly 50 MMT of annual greenhouse gas emissions by 2030.

    (a) 1 only (b) 2 and 3 only (c) 2 only (d) 1, 2 and 3

  • Economy is resilient, the road ahead will be less forgiving

    Why in the News

    India’s Gross Domestic Product (GDP) grew 7.8 per cent in the first quarter of 2026-27, beating expectations for yet another quarter. The print exceeded the 6.8 per cent median forecast of professional forecasters and the Reserve Bank of India’s (RBI) revised projection of 7 per cent. The outperformance came from domestic drivers holding up in a global environment marked by conflict in West Asia and weather uncertainty. The tension is that the conditions that produced this print are turning. Crisil expects the growth-inflation mix to worsen through 2026-27, with growth moderating to 7 per cent and inflation rising to 5.1 per cent, and the balance of risks has shifted from rate cuts towards possible rate hikes.

    What is the growth-inflation mix?

    1. About: The growth-inflation mix is the combination of real output growth and the inflation rate an economy records in the same period. A favourable mix pairs high growth with inflation inside the RBI’s target band of 4 per cent, with a tolerance of 2 percentage points either side.
    2. Why it matters for policy: The RBI sets the policy rate against this mix. Rising inflation alongside slowing growth forces a choice between tightening to contain prices and holding rates to protect activity.

    What drove the first quarter outperformance?

    1. Broad based domestic momentum: Robust industrial activity, healthy consumption and strong goods exports combined with accelerating government investment to drive growth. High-frequency indicators had signalled this momentum in advance.
    2. Residual policy support and transfers: Policy measures introduced last fiscal continued to feed through, and direct benefit transfers expanded steadily. 17 States now provide cash transfers, primarily to women.
    3. Goods and Services Tax (GST) rate cuts, visible in automobiles: Dealer discounts and higher disposable incomes from income-tax relief added to the effect of GST rate cuts. Eg. The Society of Indian Automobile Manufacturers (SIAM) reported first quarter sales growth of 26 per cent for passenger vehicles, 20.3 per cent for commercial vehicles and 18.3 per cent for two-wheelers.
    4. Retail credit funding consumption: Other personal loans, a proxy for short-term consumption, grew 14.2 per cent.
    5. Households shielded from crude: The government and oil companies absorbed most of the sharp rise in crude prices, particularly in the initial phase of the West Asia conflict, so household budgets did not take the hit.

    Why will the growth-inflation mix turn less favourable in 2026-27?

    1. Four sources of moderation: Growth will slow on disruptions from the West Asia conflict, unresolved tariff issues with the United States, weather-related risks and a strong base effect in the second half of the year.
    2. Last year’s two tailwinds are gone: Low crude oil prices and a normal monsoon were the two exogenous factors that worked in India’s favour last year. Neither is expected to provide similar support this year.
    3. The conflict’s cost channel: The West Asia conflict has disrupted supply chains and raised insurance, freight and input costs. This weighs on global and domestic growth at the same time.

    Does a deficient monsoon still translate into food inflation?

    1. The El Nino signal: El Nino conditions (a periodic warming of the equatorial Pacific that weakens the Indian monsoon) are intensifying. Over the past 25 years, five of the six El Nino years produced below-normal rainfall.
    2. The deficit so far: Cumulative rainfall stood 14 per cent below the long-period average (LPA) at the end of August. July was 1 per cent above the LPA, and August recorded a deficit of 16 per cent. The India Meteorological Department (IMD) has signalled below-normal rainfall in September.
    3. Irrigation has widened the cushion: India’s net irrigated area has risen by 10 percentage points to 59 per cent over the past decade, improving resilience to rainfall shocks.
    4. Stocks exceed buffer norms: The country holds ample rice and wheat stocks. Foodgrain stocks currently stand at more than twice the buffer norms. That cushion contains price spikes.
    5. Non-crop agriculture now carries the sector: Crop gross value added contracted by an average 0.5 per cent annually in the five years to 2023-24. Non-crop agriculture, now nearly 40 per cent of agricultural gross value added, expanded 6.5 per cent annually over the same period.
    6. The historical record is not linear: Deficient monsoons have not always led to higher food inflation.
    7. The vulnerability that remains: Crops without buffer stocks and perishable vegetables stay exposed to adverse weather. A weak monsoon also hurts rabi production by reducing soil moisture and lowering reservoir levels, so agricultural output and food inflation remain the key variables to watch.

    Why does benign core inflation understate the price risk?

    1. Headline eased, risks did not: Headline inflation eased in July and core inflation remained benign. Upside risks persist on three fronts, crude, input costs and demand.
    2. The crude assumption: Crisil’s base case assumes Brent crude averaging $82 to 87 per barrel this fiscal, with the unresolved West Asia conflict keeping prices volatile. Higher crude translates into slower growth, higher inflation and a wider current account deficit.
    3. Wholesale pressure is being passed on: Core inflation, a gauge of underlying demand pressure, appears deceptively low. Strong demand, rising fuel costs and other input pressures show up in near-double-digit wholesale price inflation, and are gradually being passed through to consumers.
    4. Automobiles show the pass-through: Vehicle prices are set to rise as manufacturers protect margins and dealer discounts are withdrawn. Combined with a high base effect, this moderates automobile growth in the second half.
    5. The rate cycle may reverse: Unlike last year, the balance of risks points towards possible interest rate hikes. Persistent inflationary pressure, the unresolved conflict and weather risk together bring monetary tightening back into consideration.

    What still supports activity through the moderation?

    1. External buffers: Foreign exchange reserves cover more than nine months of imports.
    2. Balance sheet strength: Corporate and banking-sector balance sheets are in robust health.
    3. Fiscal and wage support: Tax relief and public investment continue to support activity. The Pay Commission’s recommendations will add a further boost to consumption when implemented.
    4. The structural condition: Beyond cyclical tailwinds, sustained progress on structural reforms that enhance competitiveness is the condition for maintaining growth momentum.

    Challenges to sustaining the growth momentum

    1. Export exposure to United States tariff policy: Unresolved tariff issues leave goods exporters unable to price contracts beyond a quarter. Eg. In August 2025 the United States raised tariffs on Indian goods to 50 per cent, half of it as a penalty tied to Russian oil purchases.
      The Fix: Conclude the bilateral trade agreement under negotiation and operationalise the Comprehensive Economic and Trade Agreement with the United Kingdom signed in 2025, so exposure to one market falls.
    2. Crude dependence transmits every West Asian shock: India imports over 85 per cent of its crude, so a supply disruption raises the import bill, the fiscal cost of absorbing it and consumer prices together. Eg. About 40 per cent of India’s crude imports normally transit the Strait of Hormuz, and a large part of that supply has been offline since the disruptions of March 2026.
      The Fix: Widen the import slate to African, North American and South American barrels under term contracts and expand strategic petroleum reserve capacity beyond the present three sites.
    3. Consumption leaning on one-off boosts: Income-tax relief, GST rate cuts and a Pay Commission award lift spending once, and the base effect then turns against growth. Eg. The HSBC India Manufacturing Purchasing Managers’ Index fell to a five-year low of 52.8 in August 2026, with the survey recording job losses for the first time in over two years.
      The Fix: Tie the next round of support to employment, through the Employment Linked Incentive scheme, so that income growth rather than tax relief carries consumption.
    4. State cash transfers stretch State finances: A cash transfer to women is a recurring commitment that a State cannot withdraw without political cost. Eg. States’ aggregate fiscal deficit rose to 3.2 per cent of GDP in 2024-25, and only 11 States recorded a revenue surplus.
      The Fix: Ring-fence State capital expenditure under the Finance Commission’s fiscal roadmap so transfers do not crowd out investment.
    5. A rate hike would hit credit-led consumption first: Retail borrowing has been funding short-term consumption, and it is the most rate sensitive part of demand. Eg. The RBI raised risk weights on unsecured consumer credit in November 2023 to slow exactly this segment.
      The Fix: Use targeted macroprudential tools on unsecured lending before resorting to a policy rate hike that would also raise the cost of investment.

    Conclusion

    India enters 2026-27 with a strong quarter behind it and a weaker mix ahead. The thing that cannot be settled yet is whether inflation will rise faster than growth slows, because that decides whether the RBI tightens into a moderating economy. The Monetary Policy Committee’s October meeting is the first decision point. The monsoon’s September outcome and the rabi sowing that follows will decide the food inflation half of the equation.

    Key Facts about GDP Measurement

    1. New base year: The GDP base was revised from 2011-12 to 2022-23, with the new series released on 27 February 2026. The Consumer Price Index base moved to 2024 and the Index of Industrial Production base to 2022-23 alongside it.
    2. New data sources: GST data, the Public Financial Management System for central government accounts, e-Vahan for transport spending, and the Annual Survey of Unincorporated Sector Enterprises and the Periodic Labour Force Survey replaced proxy indicators.
    3. Refined deflation: Double deflation (deflating output and inputs separately) now applies in manufacturing and agriculture, and single deflation has been discontinued.
    4. Global alignment: The series aligns with the System of National Accounts 2008 and prepares for the transition to SNA 2025 by 2029-30.

    Challenges in GDP Growth

    1. Weak private investment: Capacity expansion depends on private capital formation, which has stayed subdued. Eg. Gross Fixed Capital Formation is around 30 per cent of GDP.
      The Fix: Scale the Production Linked Incentive scheme’s second phase and adopt Vietnam’s plug-and-play industrial park model to cut the time from approval to production.
    2. Skill mismatch: Skills produced by the education system do not match what industry demands, so rising participation adds less output. Eg. Only about half of graduates are employable.
      The Fix: Expand Industry 4.0 training and emulate Germany’s dual education and apprenticeship system.
    3. Participation gap: A large share of working-age women stays outside the labour force, capping the demographic dividend. Eg. The labour force participation rate is 59.3 per cent (2025), but the female rate is 40.0 per cent.
      The Fix: Deploy working women’s hostels and subsidised childcare on the model of Japan’s Womenomics.
    4. Jobless growth: Output growth is concentrated in sectors that employ few people. Eg. Services contribute about 55 per cent of GDP but employ under 30 per cent of the workforce.
      The Fix: Implement Employment Linked Incentives and study China’s township and village enterprises for rural labour absorption.
    5. Regulatory cost: Contract enforcement, clearance times and regulatory instability keep the cost of doing business above competitors. Eg. Logistics cost is near 8 per cent of GDP.
      The Fix: Emulate Singapore’s TradeNet single-window system to slash clearance times.

    [2021, GS3, 10 marks] Explain the difference between computing methodology of India’s Gross Domestic Product(GDP) before the year 2015 and after the year 2015.”

  • National Biodiversity Authority disburses Rs. 5.68 Crore in Access and Benefit Sharing funds

    National Biodiversity Authority disburses Rs. 5.68 Crore in Access and Benefit Sharing funds

    Why in the News

    The National Biodiversity Authority (NBA) disbursed Rs. 5.68 crore in Access and Benefit Sharing (ABS) funds.

    Core facts

    1. Disbursing body: The National Biodiversity Authority (NBA) released the funds.
    2. Amount: The verified headline figure is Rs. 5.68 crore, drawn from the release title.
    3. Mechanism: ABS returns a share of the commercial gains from biological resources to the communities and institutions that conserve them.
    4. Unverified detail: The recipient states, institutions and the per beneficiary split stated in the release body could not be verified this run. PRID 2304759.

    Static Context

    1. Biological Diversity Act, 2002: It gives effect to the Convention on Biological Diversity (CBD). It created a three tier structure.
    2. Three tier structure: The National Biodiversity Authority (NBA) sits at the national level. State Biodiversity Boards (SBBs) sit at the state level. Biodiversity Management Committees (BMCs) sit at the local body level.
    3. Access and Benefit Sharing: The principle flows from the Nagoya Protocol of 2010, a supplementary agreement to the CBD on fair and equitable sharing of benefits from genetic resources.
    4. Biopiracy check: The NBA regulates access to Indian biological resources by foreign entities. It clears Intellectual Property Rights (IPR) applications based on Indian biological material.
    5. 2023 amendment: The Biological Diversity (Amendment) Act, 2023 eased compliance for codified traditional knowledge and registered practitioners of Indian systems of medicine.

    Prelims angle

    The three tier NBA, SBB and BMC structure, the BMC role in ABS and the levy of collection fees, the Nagoya Protocol link, and the NBA gatekeeping of IPR applications are the testable static hooks.

    Mains angle

    GS Paper 3 (conservation, biodiversity governance). A question can assess whether the ABS mechanism delivers real incentives for community level conservation.

    “[2023] Consider the following statements:

    1. In India, the Biodiversity Management Committees are key to the realization of the objectives of the Nagoya Protocol.

    2. The Biodiversity Management Committees have important functions in determining access and benefit sharing, including the power to levy collection fees on the access of biological resources within its jurisdiction.

    Which of the statements given above is/are correct?

    (a) 1 only

    (b) 2 only

    (c) Both 1 and 2

    (d) Neither 1 nor 2

    “[2012] How does the National Biodiversity Authority (NBA) help in protecting the Indian agriculture?

    1. NBA checks the biopiracy and protects the indigenous and traditional genetic resources.

    2. NBA directly monitors and supervises the scientific research on genetic modification of crop plants.

    3. Application for Intellectual Property Rights related to genetic/biological resources cannot be made without approval of NBA.

    Which of the statements given above is/are correct?

    (a) 1 Only

    (b) 2 and 3 only

    (c) 1 and 3 only

    (d) 1, 2 and 3

  • Navy Chief: INS Nipun will enhance our critical underwater capabilities

    Navy Chief: INS Nipun will enhance our critical underwater capabilities

    Why in the News

    The Indian Navy has commissioned INS Nipun at Mumbai, a dedicated Diving Support and Submarine Rescue Vessel built for work beneath the surface.

    What capability does INS Nipun add?

    1. It is a specialist platform for underwater work: The vessel is built for deep sea diving, underwater intervention and submarine rescue.
    2. It can carry the rescue submersible: Its ability to embark and operate the Indian Navy’s Deep Submergence Rescue Vessel is what converts it into a rescue platform.
    3. The rescue role extends beyond Indian submarines: It can respond to a distressed submarine of the Indian Navy or of a partner navy, which is the basis of the claim that India can emerge as the region’s preferred submarine rescue partner.
    4. Its diving capability supports relief work: The specialised diving capability can assist partner nations in underwater salvage and in humanitarian assistance and disaster relief (HADR) missions.
    5. Few navies hold the combination: The vessel brings together a range of capabilities possessed by only a handful of navies.

    Why does the Navy frame this as a strategic requirement?

    1. The maritime environment is described as contested: The Chief of the Naval Staff assessed that threat perceptions are constantly evolving and morphing into newer forms.
    2. Preparedness is the stated response: The exact nature of future threats cannot be predicted, so robust capability has to be built against anticipated threats in advance.
    3. The Western Naval Command gains a full column capability: The addition allows the command to operate above, on and beneath the waves.
    4. Integration is the immediate task: The command is to fold the vessel into operational plans, exercise her capabilities rigorously and develop proficiency around her systems.

    What does the vessel mean for indigenous shipbuilding?

    1. The builder is an Indian yard: Hindustan Shipyard Limited at Visakhapatnam designed and built the vessel indigenously.
    2. The class is new to the fleet: INS Nipun is the second ship of the Nistar class of diving support vessels.
    3. The Ministry of Defence frames it as self-reliance: The induction is presented as a further step towards self-reliance in defence shipbuilding.
    4. The platform type is rarely built domestically: A diving and rescue vessel is a niche design, so building it in India establishes a capability that cannot be sourced quickly from imports.

    Challenges to India’s submarine rescue and underwater capability

    1. Rescue is a race against the air supply: A disabled submarine’s crew survives on limited oxygen, so a rescue system has to be transported and mated within hours. Eg. All 118 crew aboard the Russian submarine Kursk died in the Barents Sea in 2000 before foreign rescue assistance was accepted.
      The Fix: Keep rescue systems prepositioned on both seaboards with standing mating certification against partner navy hatch designs.
    2. The fleet operates on two seaboards with few rescue platforms: Indian submarines patrol the Arabian Sea and the Bay of Bengal, and dedicated rescue assets are limited in number. Eg. India inducted its first Deep Submergence Rescue Vehicle system only in 2018, with the second following the next year.
      The Fix: Retain air transportable rescue systems that can be flown to the nearest usable port instead of sailed from a home base.
    3. Rescue only works where the hatch fits: A rescue vehicle can dock only with a submarine whose escape hatch matches its mating skirt, so cross navy rescue depends on standardisation. Eg. The International Submarine Escape and Rescue Liaison Office exists to run exercises that test exactly this compatibility.
      The Fix: Certify Indian rescue systems against partner navy hatch standards and publish the compatibility list to regional navies.
    4. Naval shipbuilding timelines stretch: Indian yards have delivered warships and submarines behind their original schedules, which delays the capability rather than the contract. Eg. Deliveries under the Scorpene class submarine programme ran years behind the timeline set at signing.
      The Fix: Link yard payments to certified milestone completion rather than to calendar tranches.
    5. Saturation diving is a scarce skill: Deep diving support needs trained saturation divers and chamber operators, and that trained pool is small worldwide. Eg. Offshore energy operators and navies draw saturation divers from the same limited global workforce.
      The Fix: Run a joint naval and commercial diving training school whose certification is recognised for offshore industry work, so the pool grows beyond service requirements.

    Back2Basics: Hindustan Shipyard Limited

    1. Status: A shipyard at Visakhapatnam that was transferred to the Ministry of Defence in 2010 from the Ministry of Shipping.
    2. Origin: It was founded in 1941 as Scindia Shipyard and built India’s first indigenous merchant ship, Jala Usha, in 1948.
    3. Work: It builds and repairs merchant and naval vessels and carries out submarine refits for the Indian Navy.
    4. Current orders: It is building the Nistar class diving support vessels and the fleet support ships ordered for the Navy.

    [2026] Which of the following items of defence hardware is/are manufactured in India?

    1. Su-30 MKI Fighter Jets

    2. T-90 MK-III Tanks

    3. Akula Class Submarine

    (a) 1 and 2

    (b) 1 and 3

    (c) 1 only

    (d) 2 only

  • Domestic chip design to receive a boost with Rs 1.27 lakh cr push

    Domestic chip design to receive a boost with Rs 1.27 lakh cr push

    Why in the News

    The Centre has notified the operational framework for its Rs 1.27 lakh crore Semicon 2.0 programme, placing the design of Indian chips and the intellectual property behind them at the front of the country’s semiconductor strategy.

    Components of the Semicon 2.0 programme

    1. Support runs across six pillars: At least three of them are devoted entirely to chip design.
    2. Three design incentives are on offer: Chips designed for strategic purposes, chips for the commercial market, and domestically developed chips deployed at scale each attract separate support.
    3. The upstream chain has its own track: Makers of semiconductor materials, chemicals and manufacturing equipment are eligible outside the design pillars.
    4. Fabrication and packaging remain funded: Fabrication plants and advanced chip packaging continue to draw subsidy alongside the design tracks.

    How will the strategic chip design track work?

    1. The government picks the technologies first: It will identify technologies and building blocks, including intellectual property for compute, memory, radio frequency, power, networking and sensors, that it wants developed in India.
    2. The trigger is national importance: The track covers chips meant for areas of national importance and for critical infrastructure.
    3. Selection runs through competitive bidding: The Centre for Development of Advanced Computing (C-DAC), the government’s high performance computing research organisation under the Ministry of Electronics and Information Technology, will issue requests for proposals and select developers.
    4. The state keeps a share of the intellectual property: The intellectual property created under these projects will be jointly owned by the developing company and C-DAC.
    5. Consortiums are permitted: Indian owned and controlled companies can participate independently or alongside global companies, research organisations and academic institutions.

    What does the commercial design track offer?

    1. The target is a fabless industry: The track aims to build commercially viable Indian fabless chip companies, meaning firms that design chips and contract out their manufacture.
    2. Firms get access to design infrastructure: Eligible firms receive electronic design automation (EDA) tools, multi-project wafer fabrication, intellectual property cores, compute sub-systems and post-silicon validation.
    3. Small firms receive seed money: Start-ups and micro, small and medium enterprises (MSMEs) designing commercial chips can receive up to Rs 15 crore or 50 per cent of project cost, whichever is lower.
    4. The government can take equity: It can make equity co-investments alongside venture capital or private equity investors.
    5. Large firms repay through royalty: Larger companies can opt for royalty financing and pay 5 per cent of a product’s net revenue until 1.5 times the government’s financial support has been recovered.
    6. Eligibility now reaches Overseas Citizens of India: Companies incorporated and headquartered in India qualify if they are owned and controlled by Indian citizens or Overseas Citizens of India (OCIs) and maintain a significant operational and manpower presence in the country.

    What does the framework do for the upstream supply chain?

    1. Capital support is set at 30 per cent: Research and development facilities for semiconductor equipment, plants making semiconductor grade wafers, photomasks, photoresists, substrates, chemicals and gases, testing facilities, and units producing equipment and components can each claim that share of capital expenditure.
    2. Equipment makers get a declining incentive: A production linked incentive of 10, 8, 6, 4 and 2 per cent runs over five years beginning FY 2028-29.
    3. The incentive is tied to domestic sourcing: It is paid on the value of the bill of materials that an equipment maker sources from domestic manufacturers.
    4. Total support carries a ceiling: Combined support for these units is capped at 50 per cent of eligible capital expenditure.
    5. The chain being targeted is largely imported today: The upstream inputs needed to operate semiconductor factories are currently brought in from abroad.

    Challenges to India’s semiconductor design push

    1. A design still has to be turned into silicon: A fabless firm depends on a foundry, and the wafers for an Indian design are fabricated abroad until domestic plants reach production. Eg. Indian design centres of global chip firms already complete chip designs that are fabricated in Taiwan and South Korea.
      The Fix: Tie the later tranches of design support to committed capacity bookings at Indian fabrication plants, so domestic demand and domestic supply arrive together.
    2. The talent sits inside multinational captive centres: India supplies a large share of the world’s chip design engineers, and most of them work on parts of products owned elsewhere. Eg. Global semiconductor companies run large design centres in Bengaluru, Hyderabad and Noida.
      The Fix: Subsidise multi-project wafer runs for university teams so student designs reach silicon and full product ownership is learned before graduation.
    3. The design tools are a concentrated import: Electronic design automation software comes from a small number of United States based vendors and is subject to export control. Eg. The United States restricted sales of that software to Chinese customers in 2025 before reversing the order weeks later.
      The Fix: Secure long term licence access inside technology partnership agreements and fund an indigenous tool stack for mature process nodes.
    4. Approved outlay is not disbursed money: A start-up carries the working capital cost of a delayed claim, and slow disbursal has followed earlier electronics incentive schemes. Eg. Disbursals under production linked incentive schemes have repeatedly trailed the amounts approved across sectors.
      The Fix: Set a claim settlement deadline in the scheme guidelines with interest payable on delayed disbursal.
    5. Utilities decide where a plant can go: A fabrication plant requires ultrapure water and uninterrupted power at a scale few industrial locations can guarantee. Eg. Taiwan’s 2021 drought forced its foundries to truck in water and to cut consumption.
      The Fix: Pre-certify candidate sites for water and power reliability before approving a plant at that location.

    Conclusion

    Semicon 2.0 can transform India into a global semiconductor powerhouse by nurturing indigenous chip design, strengthening manufacturing, reducing import dependence, creating high-value jobs, and boosting technological self-reliance.

    Back2Basics: Centre for Development of Advanced Computing

    1. Establishment: Set up in 1988 as a scientific society under what is now the Ministry of Electronics and Information Technology.
    2. Origin: It was created to build indigenous supercomputers after India was refused access to imported high performance computing systems.
    3. Flagship line: It developed the PARAM series of supercomputers, beginning with PARAM 8000 in 1991.
    4. Present mandate: It works on high performance computing, microprocessors, language computing and cyber security, and implements the National Supercomputing Mission alongside the Indian Institute of Science.

    “[2025, GS3, 15 marks] India aims to become a semiconductor manufacturing hub. What are the challenges faced by the semiconductor industry in India? Mention the salient features of the India Semiconductor Mission.”

  • Will ‘talking’ cars reduce road accident deaths?

    Why in the News

    The Union Ministry of Road Transport and Highways will mandate Vehicle to Vehicle (V2V) communication, a system through which vehicles exchange movement data wirelessly and warn drivers of an approaching collision risk. The draft Central Motor Vehicles (Amendment) Rules, 2026 set out that mandate and invited public objections within 30 days of publication.

    How does Vehicle to Vehicle communication work?

    1. An on board unit does the exchanging: An On Board Unit (OBU) fitted in the vehicle sends data to and receives data from other vehicles wirelessly.
    2. The data exchanged is movement data: Vehicles continuously share real time speed, position, direction and acceleration.
    3. The carrier is cellular Vehicle-to-Everything technology: The system uses cellular Vehicle-to-Everything (C-V2X), a mobile network based standard for vehicle communication, in the 5.875 GHz to 5.925 GHz band.
    4. The alert reaches the driver before the hazard is visible: A vehicle braking suddenly triggers a slow down alert in nearby vehicles ahead of any driver seeing the brake lights.

    What do the draft Rules mandate, and by when?

    1. Compliance begins with voluntarily fitted vehicles: Two and three wheelers, cars, buses and goods vehicles manufactured on or after 1 October 2027 must meet Automotive Industry Standard 230 (AIS-230) if they carry a V2V system.
    2. Fitment becomes compulsory a year later: Vehicles manufactured on or after 1 October 2028 must be fitted with a V2V system meeting AIS-230 specifications.
    3. AIS-230 is the technical backbone: The standard lists the requirements a V2V system must satisfy and provides for phased introduction of other safety features.
    4. The spectrum was cleared first: The Centre exempted the 5.875 GHz to 5.925 GHz band from licensing requirements in June 2026, so original equipment manufacturers can use it in new vehicles.
    5. The cost sits on the new vehicle: On Board Units are expected to cost Rs 5,000 to Rs 7,000 and will be installed in new vehicles first.

    What can V2V do that camera based systems cannot?

    1. Existing systems are bounded by the line of sight: Camera based advanced driver assistance systems (ADAS), which use sensors to warn a driver or intervene in braking and steering, work only as far as the road is visible.
    2. V2V works around obstructions: It establishes contact with other vehicles at blind corners and behind large trucks.
    3. The warnings cover named hazards: Alerts flag sudden braking, black spots, unsafe lane changes, obstacles such as parked vehicles on roadsides, fog and potential collision risk.
    4. The detection range is about 300 metres: V2V systems typically identify vehicles within that distance.
    5. The two systems are complementary: V2V is expected to add forward collision prediction to what camera based systems already do.

    What does the limited deployment record show?

    1. Deployment abroad is narrow: V2V is working in a few countries, including the United States.
    2. Aviation already runs the same idea: Aircraft broadcast their position, speed and altitude, and nearby aircraft and ground stations receive that broadcast.
    3. The road sector is at an earlier stage: The broadcast approach is standard in global aviation and is still evolving on roads.

    Challenges to the Vehicle to Vehicle mandate

    1. The benefit depends on how many vehicles carry the unit: A network that warns only about equipped vehicles is worth little until a large share of the fleet carries the equipment. Eg. A mandate applying to vehicles manufactured from 2028 reaches none of the vehicles already registered, which stay on the road for well over a decade.
      The Fix: Fund retrofitment of On Board Units in commercial goods and public transport fleets first, since those vehicles cover the highest annual mileage.
    2. The allocated band may not carry the traffic load: It is unclear whether the frequency band set aside can support all vehicles broadcasting at once. Eg. A single congested urban intersection can hold several hundred vehicles inside the 300 metre broadcast range.
      The Fix: Fix a tested message capacity per square kilometre inside AIS-230 before the compulsory fitment date arrives.
    3. Continuous broadcasting creates a movement record: The system stores a large volume of data about vehicles, which exposes it to cyber attack and to surveillance use. Eg. FASTag toll crossings already generate a dated record of where a vehicle has been.
      The Fix: Mandate rotating pseudonymous vehicle identifiers and a fixed data retention limit in the final Rules.
    4. A wrong message can cause the crash it exists to prevent: Miscommunication between vehicles can trigger braking or a lane change that was never warranted. Eg. Automatic emergency braking systems have drawn regulatory investigation abroad over unprompted braking on highways.
      The Fix: Require cryptographic message authentication and a fail safe that suppresses alerts when integrity checks fail.
    5. The group most at risk is the hardest to equip: Two wheeler riders account for the largest share of road deaths in India, and the unit price is a significant fraction of an entry level motorcycle’s cost. Eg. Two wheelers account for roughly 44 per cent of road accident fatalities recorded in the Ministry’s annual Road Accidents in India report.
      The Fix: Subsidise On Board Units for two wheelers through the existing vehicle scrappage and safety incentive route rather than loading the cost onto the buyer.

    Conclusion

    V2V communication can make Indian roads significantly safer by enabling vehicles to detect hazards beyond line of sight and warn drivers earlier. With strong cybersecurity, privacy safeguards, affordable adoption, and wider fleet coverage, the mandate can become a major step toward smarter, safer and more connected mobility in India.

    Back2Basics: Central Motor Vehicles Rules, 1989

    1. Parent statute: They are framed under the Motor Vehicles Act, 1988, which governs registration, licensing, permits, insurance and road safety in India.
    2. What they cover: They set vehicle construction and maintenance standards, driving licence procedure, registration requirements and control of traffic.
    3. How they are changed: The Union Ministry of Road Transport and Highways notifies amendments, publishing a draft for public objections before final notification.
    4. Enforcement: Penalties for non-compliance flow from the Motor Vehicles Act, 1988, whose 2019 amendment sharply raised fines for traffic offences.
  • Lessons India, China, and Nepal must learn

    Lessons India, China, and Nepal must learn

    Why in the News

    A catastrophic flood in Nepal’s Rasuwa district, triggered by a glacial collapse near Langtang Lirung, has exposed vulnerabilities in Himalayan border management, infrastructure, disaster response and regional climate cooperation.

    Why does a border not contain a Himalayan disaster?

    1. A natural disaster does not recognise the line: The border as a geometric line, whose breach by another sovereign nation is treated as the uppermost national security concern, is not respected by a flood or an avalanche.
    2. Dependence-generating diplomacy no longer works: Nation states cannot afford to treat the sharing of information and expertise as a favour extended by one side to the other.
    3. Interdependence is the operating requirement: Data sharing, joint studies, institutional collaboration, non-sovereignty-centric treatment of climate change impact and a close inter-governmental early warning framework have become central.
    4. Science has to be converted into a public good: Translating findings into simple public awareness material is part of the same task.
    5. Border forces face a different threat set: Border defence personnel need retraining for security threats that now arrive as physical hazards rather than as incursions.
    6. Traditional knowledge belongs in operations: Human security in far-flung terrain depends on drawing on local knowledge in response operations rather than on external protocols alone.

    What does the flood expose in the region’s power system?

    1. Over 15 hydro projects were damaged on one river: The flood struck that many projects along the Trishuli, and the downstream exposure it created runs from national to trans-border scale.
    2. The cascade crosses four countries: Effects within Nepal, China and India, and further downstream in Bangladesh, can disrupt cross-border energy trading and regional power pools, producing energy insecurity.
    3. India’s oldest stake on the river is destroyed: India’s Central Water and Power Commission initiated the first hydel project on the Trishuli in 1953, an agreement was signed in 1958, and the 21 MW run-of-the-river project was commissioned at Tuphe in June 1972 at a cost of Rs 13.55 crore. It supplied power to Kathmandu for decades and now remains largely decimated.
    4. Highways were built along the river belts: Many China-built highways to Kathmandu run through valleys, including the 115 km Kathmandu to Kodari highway built in 1967 through the Sunkoshi valley, sited for strategic reasons and for easy access to sand and boulders.
    5. Ribbon development followed the alignment: Huge settlements have grown along those highways, which places population directly in the river’s path.
    6. Donors are reconsidering large infrastructure: This flood and others have pushed the funders of big infrastructure projects to rethink their strategies.

    Why does the response arrive from the wrong place?

    1. The first responder is the first victim: The impact falls at a very local level, where the area’s residents are both, and the response comes from distant capital-centric institutions in Kathmandu.
    2. Sikkim recorded the same pattern in 2023: Massive calving from the South Lhonak glacier’s snout triggered a glacial lake outburst flood in North Sikkim in October that year, and the Teesta rose 15 to 20 metres within hours.
    3. The damage crossed two States and a border: Downstream townships in Sikkim, West Bengal and Bangladesh were buried in slush and debris.
    4. The loss was 60 per cent of a State’s output: Damage was estimated at over Rs 25,000 crore, close to that share of Sikkim’s 2022-23 Gross State Domestic Product.
    5. Generation loss alone crossed Rs 19,000 crore: The 1,800 MW of capacity destroyed accounted for that much of the total.
    6. Local institutions had no capacity to absorb it: Municipalities and panchayats stood helpless before the scale of destruction, without training, technique, orientation, awareness, preparedness or the means to cope.
    7. No agency owned the warning function: No early warning mechanism existed, and no agency was responsible for creating one.
    8. The remedy named is relocation of capacity: National institutions and resources need to be based at the local level rather than at the capital.

    Why is there no common Himalayan climate policy?

    1. The region has no framework spanning its levels: The Himalayan region lacks a robust climate policy framework covering the local, national and regional levels together.
    2. The scientific warning is already published: The International Centre for Integrated Mountain Development (ICIMOD), the Kathmandu based intergovernmental knowledge centre for the Hindu Kush Himalaya, has published evidence-based reports warning of tipping points in the region’s deteriorating glaciology.
    3. India’s own instruments are national and sectoral: India has a National and State Action Plan on Climate Change with eight sectoral missions, including one for the Himalayas.
    4. The regional treaty exists on paper: The SAARC Convention on Cooperation on Environment was signed and took effect in 2013.
    5. The problem is fragmentation rather than absence: These scattered approaches have to be brought onto a common platform.

    Challenges to disaster preparedness in the Himalaya

    1. Disaster money is triggered by damage, not by risk: Spending flows overwhelmingly to relief and compensation after an event rather than to the monitoring and evacuation capacity that would reduce it. Eg. A separate National Disaster Mitigation Fund had to be created under the Disaster Management Act, 2005 precisely because response funds were not being spent on mitigation.
      The Fix: Ring-fence a fixed share of the mitigation fund for high altitude monitoring and evacuation infrastructure, with annual utilisation published State by State.
    2. Hill towns are built without a carrying capacity assessment: Settlements expand on slope debris and old landslide material without any study of how much construction the ground will bear. Eg. Land subsidence at Joshimath in January 2023 forced the evacuation of hundreds of families from a town built on old landslide debris.
      The Fix: Complete and publish carrying capacity studies for Himalayan towns, and hold new construction approvals until each town’s study is on record.
    3. No single agency owns glacier hazard: Glacier and glacial lake monitoring is split across geological, polar research and university institutions, so no body publishes a standing national risk list. Eg. India’s glacial lake inventories have been compiled separately by different agencies using different thresholds for what counts as a risk lake.
      The Fix: Designate one nodal agency to maintain and annually publish a national inventory of high risk glaciers and lakes.
    4. Reconstruction rebuilds the same exposure: Post-disaster funding restores roads, bridges and power projects on their original alignments, which returns the assets to the position that failed. Eg. Highways and hydel assets damaged in the 2013 Kedarnath floods were substantially rebuilt along the same valley routes.
      The Fix: Make a relocation-or-redesign assessment a condition of releasing post-disaster reconstruction funds for any asset in a hazard zone.
    5. Transboundary rivers carry no data obligation: Upstream flow, lake level and slope movement data are treated as strategic information rather than as a safety input owed to a downstream population. Eg. Countries in the region share river data under bilateral arrangements limited to defined seasons and defined stations.
      The Fix: Put glacier, lake and flow monitoring data into a standing regional exchange with agreed release timelines and an automatic alert threshold.

    Conclusion

    The Rasuwa flood underscores that Himalayan disasters demand cross-border cooperation, not isolated national responses. India must strengthen valley-level early warning systems, ensure real-time upstream data sharing, and establish clear institutional responsibility to prevent future disasters.

    Back2Basics: International Centre for Integrated Mountain Development

    1. Formation: An intergovernmental knowledge and learning centre established in 1983, with its headquarters at Kathmandu in Nepal.
    2. Membership: It serves eight regional member countries, namely Afghanistan, Bangladesh, Bhutan, China, India, Myanmar, Nepal and Pakistan.
    3. Coverage: Its mandate is the Hindu Kush Himalaya region, spanning the mountain systems from Afghanistan to Myanmar.
    4. Function: It produces regional assessments on glaciers, water, biodiversity and mountain livelihoods, including the Hindu Kush Himalaya Assessment reports.

    [2019, GS3, 10 marks] Disaster preparedness is the first step in any disaster management process. Explain how hazard zonation mapping will help in disaster mitigation in the case of landslides.”