Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Type: Explained

These Newscards correspond to the explained section of various newspapers. They become immensely important for both prelims and mains and special attention needs to be paid to them

  • Deletions in recent SIRs suggest arbitrary application of reasons

    Deletions in recent SIRs suggest arbitrary application of reasons

    Why in the News

    Draft electoral rolls released after the enumeration phase of the Special Intensive Revision (SIR), an exercise conducted by the Election Commission to verify every elector afresh rather than only updating additions and deletions, show wide variation in the reasons recorded for deleting names in Karnataka and Telangana. Both states saw roughly one-fifth of their electors deleted, the highest share among major states. A reason-wise breakdown of the deletions shows extreme, inconsistent use of the two largest deletion categories, “Shifted” and “Absent”, across constituencies of comparable size. The Election Commission has not defined when a Booth-level Officer (BLO) should mark an elector “Shifted” rather than “Absent”, and has never published the break-up between the two categories.

    What do the numbers show?

    1. No defined threshold between categories: The Election Commission’s Manual on Electoral Rolls, 2023 states that a person absent temporarily from their ordinary residence does not, by law, cease to be ordinarily resident there, which raises the question of whether an elector found “Absent” during enumeration should be deleted at all. The manual gives BLOs no rule for choosing between “Shifted” and “Absent”.
    2. Wide swings between similar constituencies in Telangana: Of 1,79,510 deletions in Jubilee Hills, 83% were marked “Shifted” and only 15,000 “Absent”. In the comparably sized Nizamabad (Urban), 50,307 of 83,282 deletions were marked “Absent”. In Nakrekal (SC), all 20,169 deletions were marked as reasons other than “Absent”, with not a single elector recorded as absent.
    3. Wide swings in Karnataka: In Hebbal, 87% of 1.3 lakh deletions were marked “Shifted” and only 287 “Absent”. In Hubli-Dharwad-East, roughly 25,000 of 47,000 deletions were marked “Absent”. In Bommanahalli, 2.65 lakh electors, 54.8% of the roll, were deleted, with only about 9,700 marked deceased.
    4. Aggregated official reporting hides the pattern: The Election Commission has only ever published a combined figure for “Shifted” and “Absent” deletions in every state where the SIR has run. The category-wise breakdown used in this analysis was derived independently by processing thousands of constituency-level deletion lists.

    Conclusion

    The scale of variation in reason-coding for deletions, without a defined rule separating “Shifted” from “Absent”, points to inconsistent application rather than a uniformly applied enumeration standard. The Election Commission has not made public a category-wise breakdown for any SIR state, leaving independent verification as the only route to auditing how deletions are being classified.

    Back2Basics: Special Intensive Revision (SIR)

    1. SIR is a full re-verification of the electoral roll, requiring every elector to be freshly enumerated, unlike the routine annual “Summary Revision” that only processes additions, deletions and corrections against the existing roll.
    2. Deletions during SIR are coded under four broad reasons: Shifted (or Permanently Shifted), Absent, Deceased and Duplicate.

    “[2024, GS2, 10 marks] Examine the need for electoral reforms as suggested by various committees with particular reference to “one nation-one election” principle.”

  • Why India’s R&D system needs a map of where funds really go

    Why India’s R&D system needs a map of where funds really go

    Why in the News

    A NITI Aayog report, ‘Ease of Doing R&D in India’, drawing on a survey of over 400 institutional leaders and 850 scientists, has found that close to 80% of funding under the Anusandhan National Research Foundation (ANRF, India’s apex research funding body, whose governing board is headed by the Prime Minister and which is mandated to draw much of its funding from non-governmental sources alongside Central contributions) is concentrated in the IITs, despite ANRF’s own mandate to support a wider base of universities and research bodies. The report also flagged that multiple central agencies may be funding overlapping research areas, leading to what it calls “inefficient” use of public money. NITI Aayog’s proposed response is the Unified Project Management System (UPMS), meant to streamline planning, funding, monitoring and evaluation of public R&D projects across ministries. The article argues that UPMS does not by itself fix the deeper gap it is meant to solve: India has no system that can tell funders, researchers or the public who is being funded, by whom, for what, and whether that funding has already been given elsewhere.

    What is a persistent digital identifier (PID), and why does India’s R&D funding lack one?

    1. Persistent digital identifier (PID): A permanent, unique, machine-readable identifier attached to every research grant, comparable to how a PAN number identifies a taxpayer or an IMEI number identifies a phone.
    2. Attached metadata: Each PID is meant to carry a standard set of details, which agency gave the money, to which institution, to which named researcher, what amount, over what period, and in which field, linked so officials can track outcomes when the PID is cited in a published paper.
    3. Scattered and inconsistent records today: This information already exists inside Indian funding agencies, but scattered across dozens of separate databases, in inconsistent formats, often as free text. Eg. A researcher’s name may appear as “IISc, Bangalore” in one dataset and “Indian Institute of Science, Bengaluru” in another, enough for an automated system to fail to recognise them as the same institution.

    What does the NITI Aayog report reveal about India’s R&D funding?

    1. Concentration in a few institutions: Close to 80% of ANRF funding is concentrated in the IITs, despite ANRF’s mandate to support a wider base of universities and research bodies than the traditional funding model has managed.
    2. Possible duplication across agencies: Multiple Central agencies are possibly funding similar research areas, resulting in overlap and “inefficient” use of public money, per the report’s survey of over 400 institutional leaders and 850 scientists.
    3. The underlying gap: Both findings point to the same root cause, the absence of a system that can tell funders, researchers or the public who is funded, by whom, for what, and whether that funding has already been given elsewhere.

    How have other countries solved this identifier problem?

    1. Crossref’s Grant Linking System (global, non-profit): Built by the open digital infrastructure organisation Crossref, this system now has more than 2 lakh grants registered worldwide from funders seeking to track duplication and concentration.
    2. Research Organisation Registry (ROR) and ORCID: A funder ID identifies the funding agency down to the division or department; a ROR ID identifies the receiving institution; an ORCID identifier, already familiar to Indian researchers since most journals require it, identifies the individual researcher so funding can be aggregated per person.
    3. Grant DOI, since 2020: Crossref extended its system to a permanent identifier for the grant itself, which can be linked to whatever the grant produces, papers, patents or data.
    4. Government-owned national portals compatible with the global standard: The U.K.’s “Gateway to Research” portal and the European Union’s CORDIS and OpenAIRE infrastructure run their own government-owned single points of entry for funding agencies, while generating identifiers fully compatible with the Crossref/ROR/ORCID standards, giving national governments ownership without breaking compatibility with the global dataset.
    5. Documented scale of the problem elsewhere: A 2013 analysis of U.S. federal grant applications using automated text-matching estimated duplicate or overlapping funding may have cost the U.S. nearly $70 million; a 2020 analysis of nearly 20,000 competitive grants in Denmark found funds concentrated among a small group of researchers and a narrow set of topics, a pattern the article says mirrors what NITI Aayog flagged for India.

    What are India’s options going forward?

    1. Build a sovereign national registry: India could develop and maintain its own India-specific grant registry from the ground up, giving it full control and the ability to tailor the system to its own agencies, federal structure and State research schemes.
    2. Join the existing global infrastructure: India’s funding agencies could become members of the Crossref ecosystem directly, which can be implemented faster since the technical standards and governance already exist internationally.
    3. A hybrid middle path: India could build a single national portal, the NITI Aayog’s own proposed UPMS, that internally mints Crossref-compatible grant DOIs and links every record to ROR and ORCID identifiers, following the model of the U.K.’s Gateway to Research and the EU’s CORDIS/OpenAIRE.

    Challenges to the Unified Project Management System (UPMS)

    1. Legacy data inconsistency: Migrating scattered, free-text agency records into a structured PID system requires resolving years of inconsistent naming across agencies before the system can produce reliable data. Eg. The same institution recorded as “IISc, Bangalore” in one dataset and “Indian Institute of Science, Bengaluru” in another. Fix. Mandate a common institutional and researcher master list, cross-validated against existing ORCID and ROR records, before agencies are required to report through UPMS.
    2. Compliance is not self-enforcing: A national portal only produces reliable data if every Central and State funding agency consistently deposits data into it; a voluntary or partially adopted system reproduces the same blind spots the report identifies. Fix. Make UPMS reporting a precondition for releasing funds under any Central research scheme, so compliance is enforced through the funding process itself.

    Conclusion

    NITI Aayog’s Unified Project Management System addresses the process of streamlining India’s R&D funding, but by itself does not supply the persistent digital identifier and metadata infrastructure that would let funders, researchers and the public actually see where public research money goes and whether it has already gone somewhere else. The next milestone is whether UPMS is designed to mint Crossref-compatible identifiers and how many agencies are made to report through it.

    “[2024, GS2, 15 marks] What are the aims and objects of the recently passed and enforced, The Public Examination (Prevention of Unfair Means) Act, 2024? Whether University/State Education Board examinations, too, are covered under the Act?”
  • SEBI’s ITRI: Global test for India’s future-ready financial architecture

    SEBI’s ITRI: Global test for India’s future-ready financial architecture

    Why in the News

    The Securities and Exchange Board of India (SEBI) has introduced an IT Resilience Index (ITRI) to assess the technological robustness of Market Infrastructure Institutions (MIIs), meaning stock exchanges, depositories and clearing corporations. The index responds to growing global concern about outages and cyberattacks at systemically important financial market infrastructure. It follows comparable resilience frameworks already adopted by regulators in the United Kingdom, the European Union, the United States, Singapore, Hong Kong and Australia. The tension is between certifying resilience on paper through a scored index and ensuring MIIs make the operational investment the index is meant to incentivise.

    What does the ITRI assess?

    1. Nine weighted parameters: The index scores each market infrastructure institution across nine parameters covering system uptime, cyber-incident preparedness, disaster recovery capability and related technology governance measures.
    2. Comparative design: SEBI has drawn on resilience frameworks used by regulators in the United Kingdom, the European Union, the United States, Singapore, Hong Kong and Australia in constructing the index.

    Why has SEBI shifted from compliance-checking to a quantitative resilience score for MIIs?

    • Systemic-risk trigger: Rising technological dependence in capital markets means even minutes of disruption at an MII can affect millions of investors and billions of rupees in trades.
    • Regulatory foundation: SEBI’s 2015 circular first classified MIIs as systemically important, mandating a robust cybersecurity framework.
    • Boardroom shift: Retail participation through online platforms, algorithmic trading volumes, and faster settlement cycles have made technology reliability inseparable from market efficiency.
    • Global first: ITRI is among the first attempts by any regulator to design a resilience barometer as measurable as capital adequacy is for banks.

    How does ITRI’s weighting structure reflect SEBI’s risk-prioritisation approach?

    • Nine-parameter design: ITRI rests on nine parameters, each weighted by a systemic-risk hierarchy, with sub-parameters to be defined by the Industry Standards Forum of MIIs.
    • Highest-weighted parameters: Availability and security carry the highest weight, at 20% each, as the first line of defence for market functioning.
    • Recovery-focused weighting: Business Continuity and Reliability carries 10% weight, reflecting a regulatory shift from preventing failures to absorbing shocks and recovering quickly.
    • Growth-risk calibration: Scalability carries only 5% weight, reflecting SEBI’s view that rapid market growth does not yet pose an immediate stability risk.
    • Early Warning System: MIIs will build an Early Warning System to detect parameter deterioration before it causes performance issues or disruptions.

    What do global resilience frameworks show about the alternatives to a single numeric index?

    • United Kingdom — FCA/PRA: Operational resilience rules require institutions to identify important business services and demonstrate recovery capability from severe shocks, without a single numeric score.
    • European Union — DORA: The Digital Operational Resilience Act functions as a regulatory rulebook rather than a numerical scorecard.
    • United States: No single resilience index exists for exchanges; technology resilience is embedded into general regulatory oversight instead.
    • Singapore — Monetary Authority of Singapore: Technology risk guidelines are considered particularly relevant to India given comparably high digital financial penetration and large retail investor bases.
    • Hong Kong: Cyber resilience assessment frameworks use measurable maturity levels, making them the closest structural parallel to SEBI’s numeric approach.

    Can a single numeric score capture resilience across MIIs with different technology architectures?

    • Architecture heterogeneity: Stock exchanges, clearing corporations and depositories operate different technology architectures and functions, raising doubts about a common index applying uniformly.
    • Weight uncertainty: Questions remain on the statistical estimation of the assigned weights, finalised through Technical Advisory Committee discussions rather than validated outage data.
    • Provisional status: The current weights are a starting framework that SEBI may have to refine using actual outage data, cyber incidents and stress tests.
    • Pace mismatch: Technology risks evolve faster than regulatory frameworks, making the index vulnerable to obsolescence even as it is being implemented.
    • Investment burden: Building automated monitoring systems, continuous testing and redundant infrastructure requires substantial investment from MIIs.

    Back2Basics: Market Infrastructure Institutions (MIIs)

    1. MIIs are the entities that provide the trading, clearing and settlement backbone of the securities market: stock exchanges, depositories and clearing corporations.
    2. They are classified as systemically important, since their failure or compromise can disrupt trading and settlement across the entire market rather than a single participant.
    3. SEBI regulates MIIs under the SEBI (Stock Exchanges and Clearing Corporations) Regulations and the SEBI (Depositories and Participants) Regulations.

    Conclusion

    SEBI’s ITRI converts technology resilience from a compliance checklist into a quantitative, weighted score, a model most global regulators have not attempted. Whether this scoring approach works depends on unresolved questions: the statistical basis of the weights, the comparability of a single index across MIIs with different architectures, and whether a high score actually translates into faster recovery during an actual technology shock. Until validated against real incident data, ITRI remains a measurement framework rather than a proven resilience guarantee.

    “[2015, GS2, 12 marks] For achieving the desired objectives, it is necessary to ensure that the regulatory institutions remain independent and autonomous. Discuss in the light of the experiences in recent past.”

  • $100,000 fee for H-1B: The new legal route Trump is pursuing

    $100,000 fee for H-1B: The new legal route Trump is pursuing

    Why in the News

    The US Department of Homeland Security (DHS) has proposed a new $103,265 fee on H-1B visa petitions, using a rulemaking route after a court struck down an earlier attempt to impose the same fee. The earlier fee had relied on a presidential proclamation, which a US court found exceeded executive authority. The administration is now pursuing the same outcome through a formal DHS rulemaking process instead. The move directly affects Indian workers, who receive the largest single-country share of H-1B visas, and sets up a tension between the United States’ stated intent to restrict low-cost skilled immigration and its technology sector’s dependence on Indian software professionals.

    What is the new legal route, and why does it matter?

    1. Rulemaking instead of proclamation: DHS is now proposing the fee through the standard federal rulemaking process, which carries stronger legal footing than a presidential proclamation but takes longer and includes a public comment period.
    2. Same fee, different vulnerability: A fee approved through rulemaking is harder to strike down in court than one imposed by proclamation, since it follows the procedure Congress has authorised for agency rule changes.

    What is the impact on Indian workers?

    1. Concentration of exposure: Indian nationals receive the largest single-country share of H-1B visas each year, so a steep new fee disproportionately raises the cost of hiring or transferring Indian technology professionals to the United States.
    2. Employer cost shift: US employers typically bear the H-1B fee, not visa applicants. The increase is likely to reduce new H-1B filings for Indian applicants rather than being absorbed by individual workers directly.

    Conclusion

    The Department of Homeland Security’s shift to a rulemaking process to reimpose the $100,000-plus H-1B fee is a more durable attempt to restrict skilled immigration than the earlier proclamation. The outcome for Indian workers now depends on the rulemaking’s public comment period and eventual finalisation, not merely a court challenge.

    Back2Basics: H-1B visa

    1. The H-1B is a US non-immigrant visa category for foreign workers in speciality occupations, typically requiring at least a bachelor’s degree in a related field.
    2. It is issued under an annual numerical cap, allocated through a lottery when applications exceed the cap.
    3. Indian nationals have consistently received the largest single-country share of H-1B approvals, concentrated in information technology roles.

    “[2023, GS2, 10 marks] Indian diaspora has scaled new heights in the West. Describe its economic and political benefits for India.”

  • Centre-state compromise on mines, minerals is in tatters

    Centre-state compromise on mines, minerals is in tatters

    Why in the News

    An opinion piece argues that the Mines and Minerals (Development and Regulation) Amendment Act, 2026 (MMDR Amendment Act) has centralised mineral taxation authority at the expense of States. This disturbs a long standing settlement, dating to the original Mines and Minerals (Development and Regulation) Act, 1957, under which States collected royalty on minerals within their territory without a corresponding compensation mechanism now built in. The piece contends this follows a pattern already seen in the Goods and Services Tax (GST) Council, where States have progressively lost autonomous taxation power to a Union-dominated body. The tension is between the Union’s claim that uniform mineral taxation supports national resource planning, and States’ claim that this erodes a revenue base the Seventh Schedule recognises as theirs.

    What changed under the amendment?

    1. Centralised rate-setting power: The amendment shifts the power to determine certain mineral levies and cesses from State legislatures to the Union government, narrowing what States can independently tax.
    2. Erosion of a settled compromise: Mineral royalty had functioned as a relatively stable, State-collected revenue source since the 1957 Act. The amendment disturbs that settlement without a corresponding compensation mechanism.

    Why is this compared to the GST Council experience?

    1. Repeated pattern of centralisation: The piece argues that the GST Council, though structured as a joint Centre-State body, has in practice let Union preferences dominate rate decisions, and that the same dynamic is now repeating in mineral taxation.
    2. States left to negotiate after the fact: Under both regimes, States raise objections after a rate or rule is set centrally, rather than co-designing the rule up front.

    Current Status of Fiscal Federalism in India

    1. The Union controls the most buoyant tax sources, income tax, corporate tax and the dominant share of the GST base, while States carry larger expenditure responsibilities in health, education and welfare, producing a standing vertical fiscal imbalance.
    2. Devolution to States is currently governed by the 16th Finance Commission’s award, which fixed the States’ share of the divisible pool at 41 percent.
    3. Mineral royalty and cesses have historically sat with States as an independent, non-shared revenue source, which is the specific arrangement this amendment narrows.

    Constitutional Provisions Related to Fiscal Federalism

    1. Article 246 and the Seventh Schedule: Distribute taxation and legislative subjects between the Union, State and Concurrent Lists, and mineral development is a subject that straddles Union and State competence under Entry 54 of the Union List and Entry 23 of the State List.
    2. Article 280: Establishes the Finance Commission to recommend the distribution of net tax proceeds between the Union and the States.
    3. Article 246A and Article 279A: Together create the GST regime and the GST Council as the joint body that recommends GST rates and administration.
    4. Article 293: Governs the Union’s control over State borrowing where a State remains indebted to the Union.

    Major debates surrounding Fiscal Federalism

    1. Divisible pool erosion through cesses and surcharges: Revenue the Union raises as a cess or surcharge does not enter the divisible pool the Finance Commission distributes, so a nominal 41 percent devolution understates the Union’s discretionary control over shared revenue.
    2. State taxation autonomy under GST: States gave up the power to independently tax goods and services on joining GST, leaving royalty and mineral levies among the few remaining independent State taxation instruments, which is precisely what this amendment now narrows.
    3. Weak third-tier finances: Local bodies devolved under the 73rd and 74th Amendments remain financially dependent on State and Union transfers, compounding the same imbalance one tier further down.

    Challenges in Fiscal Federalism

    1. No binding consultation requirement before a rate change: Neither the GST Council’s structure nor the MMDR Act requires the Union to secure State consent before altering a shared levy, only consultation. Eg. The GST Council’s voting structure gives the Union a one-third weightage sufficient to block any change it opposes. Fix. Amend Article 279A to require a demonstrated State revenue-neutral transition before a Council decision that narrows State taxation power takes effect.
    2. No compensation mechanism for a narrowed State tax base: Unlike the GST transition, which carried a five-year compensation guarantee for States, the MMDR Amendment Act, 2026 carries no equivalent revenue protection for States losing mineral levy autonomy. Eg. The GST Compensation Cess mechanism lapsed in 2022, and States have separately argued its withdrawal alone widened the same imbalance this amendment now adds to. Fix. Extend a time-bound compensation formula, indexed to each State’s historical mineral revenue, for a fixed transition period.

    Government Initiatives for Fiscal Federalism

    1. Finance Commission: A constitutional body appointed every five years to recommend Union-State and inter-State devolution of tax proceeds and grants-in-aid.
    2. GST Council: The joint Union-State body under Article 279A that recommends GST rates, exemptions and administrative rules.
    3. District Mineral Foundation: A statutory trust under the Mines and Minerals (Development and Regulation) Act, 1957 that channels a share of mineral royalty into welfare of mining-affected areas, funded from the same royalty base this dispute concerns.

    Back2Basics: Mines and Minerals (Development and Regulation) Act, 1957

    1. The Act is the principal central law governing mineral concessions and mineral development in India, most recently amended in 2026.
    2. It empowers the Union to prescribe rates of royalty and dead rent on minerals, which States then collect.
    3. A 2015 amendment introduced auction as the mandatory mode of allocating mineral concessions, replacing the earlier discretionary allotment system.

    Conclusion

    The mineral taxation dispute is presented as further evidence that fiscal federalism in India increasingly follows a pattern of after-the-fact State objection to Union-set rules, rather than genuine ex ante bargaining. What remains unresolved is whether States will pursue a legal challenge or extract a compensation formula through political negotiation.

    “[2025, GS2, 15 marks] Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India?”

  • India, China to advance boundary talks for ‘early harvest’, set up new LAC meeting points, hotlines

    India, China to advance boundary talks for ‘early harvest’, set up new LAC meeting points, hotlines

    Why in the News

    India and China have agreed to advance work on delimiting the Line of Actual Control (LAC) and to create new mechanisms for managing the border. The two sides reached this outcome at the conclusion of the 25th round of Special Representative (SR) talks, the designated channel between India’s National Security Adviser and China’s Foreign Minister for discussing a political framework for a boundary settlement. The talks follow the restoration of high level border diplomacy after the 2020 Galwan standoff, which had frozen the SR mechanism for several years. Eight outcome points have been agreed, including new military hotlines and meeting points, an expert mechanism on trans-border rivers, and a push toward “early harvest” delimitation in less disputed sectors, even as neither government has published a public roadmap for how full delimitation will proceed.

    What did the two sides actually agree to?

    1. New military hotlines and meeting points: The two sides will add direct communication lines and physical meeting points along the LAC to reduce the risk of miscalculation during patrols. Eg. Existing hotlines were credited with de-escalating stand-offs after 2020, and the new points extend coverage to previously uncovered stretches.
    2. Boundary delimitation working groups: Both sides will set up dedicated groups to work toward an “early harvest” agreement on sectors where the alignment is least contested, rather than attempting a single comprehensive settlement.
    3. Trans-border river mechanism: A joint expert mechanism will meet to share hydrological data on rivers that cross the border. This addresses a long standing Indian concern about upstream Chinese dam activity.

    Why does the lack of a public roadmap matter?

    1. Transparency gap: Neither government has released the substance of what an “early harvest” delimitation would cover or which sectors are prioritised. Parliament and citizens have no way to assess the trade-offs being discussed.
    2. Precedent for slippage: Past India-China dialogue mechanisms, including the Special Representative talks themselves, have lapsed for years after an initial burst of activity. An outcome document alone does not guarantee follow-through.

    Conclusion

    The 25th round of Special Representative talks has produced the most concrete institutional steps on the India-China boundary since the Galwan standoff, but a working roadmap for actual delimitation remains undisclosed. The next milestone is the first meeting of the delimitation working groups and whether the trans-border river mechanism produces a data-sharing protocol.

    Back2Basics: Line of Actual Control (LAC)

    1. The LAC is the de facto boundary separating Indian and Chinese controlled territory, distinct from an internationally recognised border.
    2. It is not a single demarcated line. Both sides hold differing perceptions of its alignment in several sectors, including eastern Ladakh and Arunachal Pradesh.
    3. The Special Representatives mechanism, established in 2003, is the designated channel for discussing a political framework for a boundary settlement.

    “[2026] The Chancellor of Germany visited India in January 2026. Which of the following is/are NOT correct in terms of outcomes?
    1. MoU between All India Institute of Ayurveda and University of Hamburg
    2. MoU on Youth Hockey Development between Hockey India and German Hockey Federation
    3. Establishment of a bilateral dialogue mechanism on the Indo-Pacific
    4. Opening of an Honorary Consul of Germany in Lucknow
    (a) 2 and 3 (b) 1 and 4 (c) 3 and 4 (d) 1 only

  • UN panel flags ‘human rights violations’ in India, urges Delhi to suspend, review NRC

    UN panel flags ‘human rights violations’ in India, urges Delhi to suspend, review NRC

    Why in the News

    The UN Committee on the Elimination of Racial Discrimination (CERD) has released concluding observations, following its eleventh periodic review of India on August 11-12, criticising the implementation of the National Register of Citizens (NRC) in Assam and calling for its suspension. This is a One development, one row item; The Hindu and The Indian Express both carried the Committee’s findings, and this entry is filed from the Indian Express account, which reports the call to suspend the NRC and the Committee’s specific concern about the Special Intensive Revision (SIR) process, in more detail.

    What did the Committee find, and what did it call on India to do?

    1. The Committee criticised the NRC’s implementation in Assam: It found that the process subjected Bengali-speaking Muslims to what it described as “systematic and structural racial discrimination,” and called for the NRC to be suspended and India’s legislative framework around it to be reviewed.
    2. The Special Intensive Revision process was separately flagged: The Committee raised concern that Bengali-speaking Muslim voters were reportedly disproportionately affected by the Election Commission’s SIR process in West Bengal and Assam.
    3. The Committee’s concern extends to Scheduled Castes, Scheduled Tribes, and Rohingya refugees: It said it was “gravely concerned” about reports of large-scale violations by law enforcement officials against ethnic and ethno-religious groups, including Scheduled Tribes, Scheduled Castes (particularly Dalits), and non-citizens, and cited allegations of racially motivated violence, excessive use of force, extrajudicial killings, arbitrary detention, torture and sexual violence.
    4. It called for accountability, not merely acknowledgement: The Committee asked India to conduct prompt, thorough and impartial investigations into these allegations and ensure accountability for those responsible, and to urgently address hate speech and hate crimes against Rohingya, Bengali-speaking Muslims, migrants and asylum-seekers.
    5. India’s response came through its review delegation: India sent the Solicitor-General as head of delegation for the underlying periodic review held on August 11-12, ahead of these concluding observations.

    Conclusion

    CERD’s concluding observations place NRC suspension, a review of the associated legislative framework, and law enforcement accountability toward Scheduled Castes, Scheduled Tribes and Rohingya refugees on record as a formal treaty-body finding against India, made under the same UN human rights review process, rather than as commentary on a single incident, with India’s substantive reply yet to be reported.

    Back2Basics

    1. UN Committee on the Elimination of Racial Discrimination (CERD): The treaty body of independent experts that monitors States parties’ implementation of the International Convention on the Elimination of All Forms of Racial Discrimination (ICERD), which India ratified in 1968, through periodic reviews and concluding observations.
    2. National Register of Citizens (NRC), Assam: A register, first prepared in 1951 and updated under Supreme Court supervision, intended to identify genuine Indian citizens in Assam by excluding illegal migrants, particularly in the context of the Assam Accord (1985).
  • Simpler mining tax model can mean more revenue for states

    Simpler mining tax model can mean more revenue for states

    Why in the News

    The chairperson of the Economic Advisory Council to the Prime Minister, argues that the recently passed Mines and Minerals (Development and Regulation) Amendment Act, 2026 replaces a fragmented mineral taxation system, up to 14 different taxes, charges, fees and levies across States, with a simpler, uniform and predictable framework, extending the certainty-over-discretion principle already applied to mineral block allocation in 2015 to mineral taxation itself.

    What does the amended Act change, and what does it retain?

    1. It targets fiscal fragmentation across States: The amendment addresses a landscape where mineral producers face up to 14 types of taxes, charges, fees and levies that differ by State, and aims to keep India’s mineral market integrated rather than fractured along State fiscal lines.
    2. The revenue-sharing formula with States is retained, not altered: Since the e-auction regime began in 2015, States have received more than Rs 7 lakh crore, about 90% of total revenue from the coal and non-coal sectors combined, through royalty, auction premium, District Mineral Foundation (DMF) contributions and GST; the amendment continues this formula, with 90 paise of every rupee earned from mineral production retained by the State.
    3. The reform is framed as continuing a 12-year trajectory: The op-ed traces the shift from a pre-2014 system of discretionary block allotment, marked by delay and opacity, to transparent competitive e-auctions, arguing that the new tax simplification extends the same certainty principle to fiscal treatment of mining.

    Conclusion

    The op-ed’s position is that a simpler, uniform mineral tax framework under the amended MMDR Act protects mineral-rich States’ own revenue pool while removing the fiscal fragmentation that has made India’s mineral market uncompetitive against import sources, an argument resting on the Act’s own revenue-sharing data rather than a general case for lower taxation.

    Back2Basics

    1. Mines and Minerals (Development and Regulation) Act, 1957: The principal central legislation governing regulation of mines and mineral development in India, under which State governments grant mineral concessions but the Centre sets the overarching regulatory and taxation framework.
    2. District Mineral Foundation (DMF): A non-profit trust set up in mining-affected districts under the Act to work for the interest and benefit of persons and areas affected by mining-related operations, funded through a share of royalty payments.

    “[2025, GS2, 15 marks] Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India?”

  • Karnataka’s draft SIR rolls reveal alarming levels of deletion

    Karnataka’s draft SIR rolls reveal alarming levels of deletion

    Why in the News

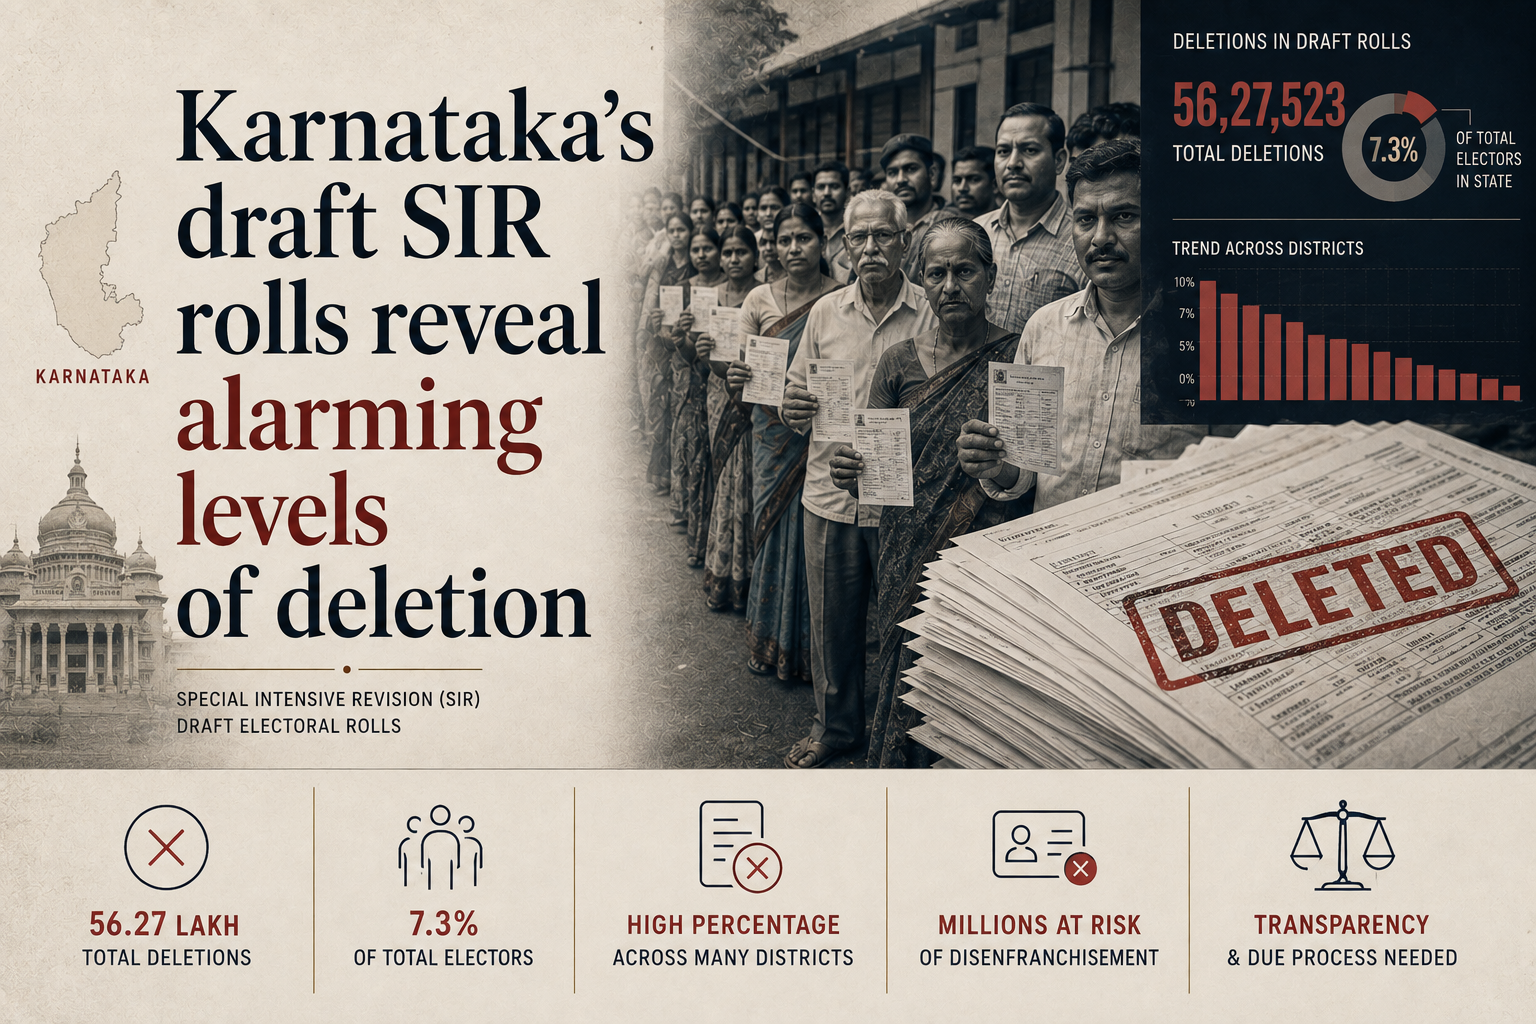
    The draft electoral rolls released after the enumeration phase of the Special Intensive Revision (SIR) show Karnataka’s rolls shrinking by 19.5%, a deletion of 1.08 crore names, the second-highest deletion rate among major States after Telangana. Constituency-level analysis shows the deletions concentrated overwhelmingly in Bengaluru’s urban core, and the Election Commission’s continuing refusal to release the electors-to-population ratio, combined with Karnataka’s own opaque disclosure practices, has deepened concerns about whether the exercise can be independently verified.

    What do the numbers show about how the deletions are distributed?

    1. Five constituencies lost more than half their electors: Bommanahalli (54.8%), Dasarahalli (52.1%), B.T.M. Layout (51.6%), Vijayanagar (51.1%), and C.V. Raman Nagar (51.1%) each saw over 50% of their rolls deleted, the first time any major State has recorded constituencies crossing that threshold during SIR enumeration, and all five sit in the core Bengaluru area.
    2. The deletions are heavily concentrated in a small number of seats: Half of the 1.08 crore deletions came from just 36 of Karnataka’s 224 Assembly Constituencies, of which 28 were in the core Bengaluru area.
    3. A structural gap against the eligible population persists: Karnataka’s draft SIR roll is at least 67 lakh short of the population eligible to vote as estimated by the Union government’s Technical Group on Population Projections, the largest shortfall among the major States compared in the underlying data.
    4. The “Shifted” category is unusually high even in rural constituencies: Unlike the urban-concentration pattern seen in other States, Karnataka recorded a high share of deletions marked “Shifted” even in predominantly rural constituencies.

    Why is the process itself under scrutiny, independent of the deletion numbers?

    1. The Election Commission has not released the electors-to-population ratio for any State during this SIR round: This ratio, mandatory during every roll revision, is the standard check on under- or over-enrolment, and its absence is attributed by the Commission to the lack of Census data.
    2. Karnataka’s disclosure practice is the weakest among major States: Unlike other States that host a searchable deletion list, Karnataka’s Chief Electoral Officer has hosted the deleted-voters list only as booth-wise documents on scattered Google Drive links, in English only, without old booth numbers, making verification difficult for affected voters.
    3. Gender-disaggregated data on deletions is missing: Karnataka has not released gender-wise deletion data, unlike other States, and the Chief Electoral Officer’s office has stated it does not hold this data.

    Conclusion

    The scale and concentration of Karnataka’s SIR deletions, combined with the Election Commission’s continuing non-disclosure of the electors-to-population ratio and Karnataka’s own weak search and disclosure infrastructure, leave roughly 44 lakh voters in the draft rolls facing discrepancy notices with no independently verifiable baseline against which the exercise’s accuracy can be tested.

    Back2Basics

    1. Special Intensive Revision (SIR): An intensive, house-to-house revision of electoral rolls carried out under the Representation of the People Act, 1950, distinct from the routine annual summary revision, undertaken to re-verify enrolment through fresh enumeration.
    2. Electors-to-Population (EP) ratio: The proportion of the population eligible to vote (18 years and above) that is actually enrolled on the electoral rolls; a low EP ratio indicates under-enrolment and a high one can indicate over-enrolment or padding.
  • Minister seeks fundamental shift in fight against drought

    Minister seeks fundamental shift in fight against drought

    Why in the News

    The Union Environment Minister has called for a fundamental shift in the global approach to droughts, from reactive relief to proactive, technology-enabled resilience. He made the appeal at the Ministerial Dialogue on Accelerating Drought Resilience during the 17th Conference of Parties (COP17) of the United Nations Convention to Combat Desertification (UNCCD), held in Ulaanbaatar, Mongolia.

    What did the Minister’s statement propose?

    1. Drought is reframed as a development challenge: The Minister said drought is no longer an occasional event but a defining development challenge, citing its compounding disruptions to global water security, agricultural food systems, biodiversity, and economic stability.
    2. India’s own model was presented as a template: He highlighted India’s coordinated, multi-institutional approach integrating early warning, mitigation, relief and community resilience, where rainfall monitoring and satellite-based drought assessments trigger preparedness at the inter-ministerial and State levels.
    3. Land restoration was linked directly to water security: He called for restoring the forest before restoring the flow, underscoring India’s focus on catchment and riverscape forestry to reduce erosion, improve water retention, and recharge groundwater.
    4. The Minister called for a shift from relief to prediction: He advocated integrating predictive technologies, localised early-warning monitoring, and proactive land management policies, so vulnerable communities can anticipate and absorb environmental shocks rather than depending primarily on post-disaster relief.

    Back2Basics

    1. United Nations Convention to Combat Desertification (UNCCD): Adopted in 1994 following the 1992 Rio Earth Summit, it is one of the three Rio Conventions, alongside the United Nations Framework Convention on Climate Change (UNFCCC) and the Convention on Biological Diversity (CBD).
    2. It is the sole legally binding international agreement linking environment and development to sustainable land management. COP17, held in Mongolia under the theme “Restoring Land. Restoring Hope,” is its 17th Conference of Parties.

    Conclusion

    The Minister’s intervention at COP17 sets out India’s preparedness-first model as its negotiating position within the UNCCD process, positioning predictive, land-restoration-based resilience as the alternative to a relief-centred global response to drought.

    “[2014, GS3, 12 marks] Drought has been recognised as a disaster in view of its party expense, temporal duration, slow onset and lasting effect on various vulnerable sections. With a focus on the September 2010 guidelines from the National disaster management authority, discuss the mechanism for preparedness to deal with the El Nino and La Nina fallouts in India.”