Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Type: Schemes

  • ‘Retirement-income replacement 35-40% vs. 60% globally’

    ‘Retirement-income replacement 35-40% vs. 60% globally’

    Why in the News

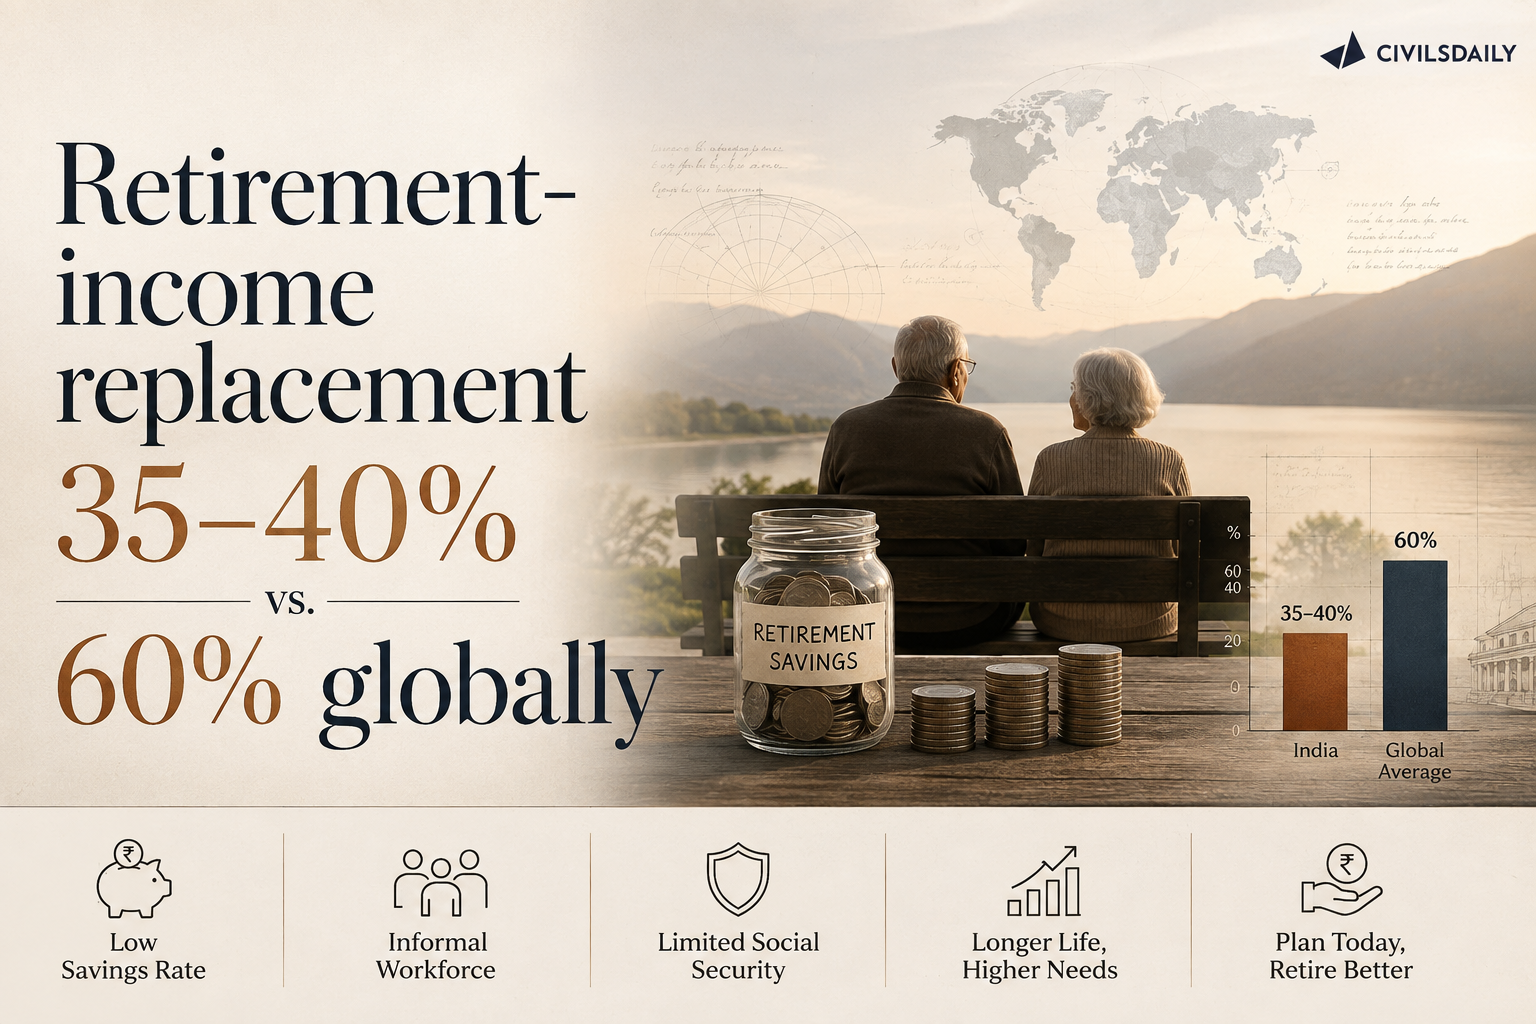
    India’s retirement income replacement rate stands at about 35 to 40 percent, against roughly 60 percent globally. The Pension Fund Regulatory and Development Authority (PFRDA), the statutory regulator of the pension sector, has set a target of covering 30 crore people through the National Pension System (NPS) and the Atal Pension Yojana (APY) over the next four to five years. That target sits almost entirely outside government employment, where the regulator says people neither hold a pension account nor know the product exists. Coverage therefore turns on distribution and awareness rather than on the design of the two schemes.

    What is the National Pension System (NPS)?

    1. A defined contribution retirement scheme: Subscribers and, where applicable, employers contribute to an individual account, and the accumulated corpus depends on contributions and market returns rather than on a promised payout.
    2. Who administers it: The scheme is regulated by the PFRDA under the Pension Fund Regulatory and Development Authority Act, 2013, with contributions invested by registered pension fund managers.
    3. Two account types: Tier I is the retirement account with withdrawal restrictions, and Tier II is a voluntary savings account without them.
    4. Exit design: A part of the corpus is withdrawn as a lump sum at retirement, and the balance is used to buy an annuity that pays the monthly pension.

    What is a retirement income replacement rate?

    1. Retirement income measured against final pay: The replacement rate is the share of a person’s last drawn pay that their retirement income reproduces, so a rate of 60 percent means retirement income equals 60 percent of final pay.
    2. Why the benchmark sits below 100: Work related costs and savings contributions end at retirement, so the accepted global benchmark of about 60 percent is treated as enough to hold living standards steady.

    What is the Unified Pension Scheme (UPS)?

    1. An assured payout option within the NPS framework: UPS gives central government employees covered by the NPS an assured monthly payout linked to the average basic pay drawn in the last twelve months of service, in place of a purely market linked corpus.

    What does the regulator say individuals should do about the shortfall?

    1. Encouraging higher contributions is the stated response: The regulator’s position is that people have to be encouraged to invest more, since the gap between India’s replacement rate and the global benchmark is a savings gap rather than a scheme design gap.
    2. No prescribed savings target: The PFRDA declined to fix how much an individual should save to secure a decent retirement income, on the ground that the amount cannot be predicted.
    3. Illustrations in place of a target: The regulator will instead show how regular monthly contributions can grow over a given number of years, drawing on past fund performance.
    4. The amount saved is not uniform: How much an individual saves depends on lifestyle and priorities, which is why a single national savings figure is not offered.
    5. The observed contribution range: Contributions among NPS subscribers now range from 200 rupees a month to 2 lakh rupees a month.

    Why is the non government segment the focus of the coverage push?

    1. Government enrolment is already growing: The PFRDA has about 2.2 crore NPS subscribers across government and non government categories, and government enrolment continues to rise on its own.
    2. The gap sits outside government service: The regulator’s stated job is to focus on the non government sector, whose workers do not have the benefit of NPS and do not know about it.
    3. The APY base is far larger: The Atal Pension Yojana already has about 10 crore customers, which makes it the wider of the two channels for the 30 crore target.
    4. Self employed and gig workers are the identified frontier: The regulator sees significant scope to expand pension coverage among the self employed and gig workers, who have no employer to enrol them.

    How is the digital push meant to widen distribution?

    1. Two platforms under development: The StAR NPS platform is being developed with the Bombay Stock Exchange (BSE), and NPS Tatkal is being developed with the National Payments Corporation of India (NPCI) and the Bharat Interface for Money (BHIM) app.
    2. What distributors are paid: The PFRDA gives distributors a 200 rupee onboarding fee and roughly 0.3 percent of assets under management as annual commission.
    3. Why the platform route matters: Digital onboarding could substantially cut the cost of acquiring each new client, which is the binding constraint on selling a small ticket pension product.

    What is changing in how pension funds invest?

    1. Resilience in returns is the stated focus: Pension funds have to diversify across asset classes to generate better returns at low volatility.
    2. Direct investment capability is being examined: The PFRDA is examining how pension funds can develop the expertise to invest directly in firms rather than only through market instruments.
    3. Competition among fund managers: The regulator had 14 pension fund managers and holds that greater competition could both raise returns and expand the scheme’s reach.

    What do the newer products add to the pension architecture?

    1. NPS Vatsalya: The product allows parents or guardians to build retirement savings for children and has crossed four lakh unique customers.
    2. NPS Swasthya: The product under preparation combines pension savings with a dedicated health corpus and top up health insurance.
    3. Why the health link is being added: Medical expenditure is the main claim on retirement savings, so a separate health corpus protects the pension corpus from being drawn down early.

    Where does the Unified Pension Scheme sit on cost?

    1. Between the contributory and the old model: The cost of the UPS to the government will be higher than the NPS and substantially lower than the Old Pension Scheme. That scheme paid an unfunded defined benefit from the exchequer.

    Conclusion

    India’s pension system currently replaces about a third of final pay against a global benchmark of about 60 percent, and the regulator has framed this as a savings and coverage problem rather than a design problem. The stated position is a target of 30 crore subscribers across NPS and APY within four to five years, with the non government, self employed and gig segments as the intended addition. The next markers are the rollout of the StAR NPS platform with the BSE and NPS Tatkal with the NPCI, and the launch of NPS Swasthya.

    “[2017] Who among the following can join the National Pension System (NPS)?

    (a) Resident Indian citizens only

    (b) Persons of age from 21 to 55 only

    (c) All State Government employees joining the services after the date of notification by the respective State Governments

    (d) All Central Governments Employees including those of Armed Forces joining the services on or after 1st April, 2004
  • SC lauds repealed MGNREGA as ‘neither freebie nor exploitation’

    Why in the News

    The Supreme Court has described the repealed Mahatma Gandhi National Rural Employment Guarantee Act, 2005 (MGNREGA) as a “salutary scheme” that was neither a freebie nor an exploitation of rural workers. A three judge Bench made the observation. It was hearing a petition seeking directions to the government to pay delayed wages under that Act along with compensation. Civil rights groups have meanwhile claimed that the successor law has produced a 50 per cent fall in employment generation. What is now contested is whether a guarantee of work rests on an enforceable right or on a Directive Principle that Parliament may redesign at will.

    What did the Court say about the repealed employment guarantee law?

    1. The Bench recorded an unqualified endorsement: The Chief Justice of India, heading a three judge Bench, orally observed that the repealed Act was a good and effective scheme.
    2. The reach was part of the praise: The observation noted that the scheme did a wonderful job in rural areas and was implemented across the whole country.
    3. It rejected both political labels attached to the scheme: The Bench held that the scheme was neither a freebie nor exploitation, which answers the charge that guaranteed public work is a handout and the charge that it is underpaid labour.
    4. The endorsement carries no operative effect: These were oral observations in a hearing, not a finding recorded in a judgment, so they bind nothing.

    What has changed under the successor law?

    1. A new statute has replaced the 2005 Act: The Viksit Bharat Guarantee for Rozgar and Ajeevika Mission (Gramin) Act, 2025, or VB-G RAM G Act, is now the governing law for rural employment guarantee.
    2. Guaranteed days have gone up: The entitlement rises from 100 days to 125 days of work per household each year.
    3. Employment generated has gone down: Civil rights groups claim a 50 per cent decline in employment generation under the new law, despite the higher entitlement.
    4. The design has moved from demand to allocation: The new law reflects a shift from a demand driven, rights based framework to a centrally controlled model.
    5. The funding split has been rewritten: The Centre to State ratio moves from 90:10 to 60:40, which raises the funding burden on States threefold.

    What did the petition ask the Court to do?

    1. Payment of arrears with compensation: The petition sought directions for the government to pay wages already delayed under the repealed Act, together with compensation for the delay.
    2. A test of the wage floor: The Court was urged to examine whether a law may prescribe minimum wages lower than the threshold determined by the State concerned.
    3. Elevation of the work guarantee: The petition asked that the statutory guarantee of rural work be raised to the status of a fundamental right under Article 21.
    4. The fiscal claim behind the numbers: It was submitted that States must now find nearly half the funds under the new law, that employment has halved, and that States do not have the money.

    Can a statutory guarantee of work be raised to a fundamental right?

    1. The Bench located the right in Part IV: A judge on the Bench observed that the Constitution does not make the right to work a fundamental right, and that it is more a democratic aspiration under the Directive Principles of State Policy.
    2. The consequence of that placement: To achieve that aspiration the state formulates a policy providing work at a graded, compensatory level. That is a matter of legislative choice rather than of enforceable entitlement.
    3. The petitioner’s route runs through dignity: It was argued that the right to lead a dignified life is part of Article 21, that a dignified life requires employment at minimum wages, and that anything below minimum wages amounts to forced labour.
    4. The question the Bench put remains open: Whether a Directive Principle worked out through a statute should be treated on par with Article 21 was posed from the Bench and not answered.

    Why did the Bench doubt a judicially fixed wage floor?

    1. A floor can shrink the work available: A judge on the Bench noted that mandating a minimum wage threshold might risk reducing the number of employment opportunities offered.
    2. Wages track local conditions: The Chief Justice of India observed that wages are usually linked to prevailing local conditions rather than to a single national figure.
    3. The two positions are not reconcilable within the scheme: A wage set by dignity produces one number, a wage set by local labour market conditions produces another, and only a legislature can choose between them.
    4. The judicial instrument is blunt here: A court can strike down a wage as unconstitutional, but it cannot fund the difference, which is why the Bench treated the question as a fiscal one.

    How did the Court dispose of the matter?

    1. The old law is no longer the right frame: A judge on the Bench stated that the issues raised must be examined afresh in the light of the new law rather than under the repealed Act.
    2. The petition was disposed of: The Court disposed of the present petition rather than deciding the questions it raised.
    3. Liberty was granted to start again: The petitioner was asked to file a fresh petition, which resets the challenge against the successor statute.
    4. The practical effect is delay: Both questions the petition raised survive, but only in a proceeding that has yet to be filed.

    Challenges to the rural employment guarantee framework

    1. A demand driven scheme collapses if funds are capped: Where the budget is fixed in advance, field staff suppress the registration of work demand rather than record an unmet entitlement. Eg. Work demand under the earlier scheme was routinely recorded only after funds were released for the block. Fix. Make the budget line for the guarantee an open ended charge that is revised at the supplementary stage against recorded demand.
    2. Delayed wages convert a guarantee into a loan from the worker: Payment beyond the statutory window pushes households into informal borrowing at the exact moment the scheme is meant to protect them. Eg. A large share of wage payments under the earlier scheme was released beyond the fifteen day statutory window in successive financial years. Fix. Automate the delay compensation payment through the same payment system that releases the wage, without requiring a claim.
    3. A higher State share transfers the risk to the weakest States: Poorer States with the largest demand for guaranteed work are least able to fund a 40 per cent share. Eg. States facing the highest rural distress also carry the highest ratio of committed expenditure to revenue. Fix. Apply a differentiated matching ratio linked to a State’s own revenue capacity rather than a uniform national split.
    4. Asset quality is weakly monitored: Works are selected for their ability to absorb labour rather than for durable value, so the assets created decay within seasons. Eg. Earthen works taken up before the monsoon are frequently washed out before they are measured. Fix. Require every work above a threshold cost to carry a technical sanction and a geotagged completion audit.
    5. Social audit is the design safeguard and the weakest link: The Gram Sabha audit is meant to catch fake muster rolls, but audit units are staffed and funded by the same administration they examine. Eg. Social audit units in several States operate with a fraction of their sanctioned staff. Fix. Fund social audit units directly from the central share and place their reporting line under the State Accountant General.
    6. Women’s participation depends on facilities that are rarely provided: Creche facilities and worksite shade are statutory entitlements that are treated as optional. Eg. Worksites routinely operate without the creche required where more than five children under six are present. Fix. Make release of the next tranche of administrative expenditure conditional on verified worksite facility compliance.

    Conclusion

    The Court’s endorsement of the repealed Act is a comment on record and nothing more, and the Bench made clear that the live questions must now be argued against the successor statute rather than the one it replaced. The petition was accordingly disposed of with liberty to file afresh, so both questions it raised remain undecided. The next milestone is the filing of that fresh petition. That petition will test the constitutional status of the work guarantee and the legality of a wage below a State determined minimum against the VB-G RAM G Act for the first time.

    “[2011] Among the following who are eligible to benefit from the “Mahatma Gandhi National Rural Employment Guarantee Act”?

    (a) Adult members of only the scheduled caste and scheduled tribe households

    (b) Adult members of below poverty line (BPL) households

    (c) Adult members of households of all backward communities

    (d) Adult members of any household

  • Centre notifies key scheme to manufacture mobile phones

    Why in the News

    The Ministry of Electronics and Information Technology (MeitY) has notified the Mobile Phone Manufacturing Scheme (MPMS), a ₹62,500 crore programme incentivising domestic assembly of smartphones and greater local value addition. The Union Cabinet approved the scheme on 15 July 2026. It succeeds the Production Linked Incentive Scheme for Large Scale Electronics Manufacturing, which ran from 2020 to the last financial year and rewarded incremental handset output from any qualifying firm. The new scheme splits that single track in two, creating a separate and richer channel for brands owned by Indian citizens and holding their intellectual property in India. What is contested is whether incentive design alone can move India from assembling other countries’ brands to owning its own.

    Components of the Mobile Phone Manufacturing Scheme

    1. Two parts: The notification divides the scheme in two, one part incentivising mobile phone manufacturing and one part supporting Indian mobile phone brands.
    2. Part 1, the assembly incentive: A base incentive on assembly tapers from 2.75 per cent to 2.25 per cent across the five year tenure. Applicable rates run from 2.25 per cent to 5 per cent depending on the year and on incremental sales.
    3. The domestic sourcing add on: An additional 1.5 per cent is payable on domestic component sourcing, built up from individual component incentives ranging from 0.2 per cent to 0.5 per cent.
    4. Part 2, the Indian brand track: An Indian owned brand draws a flat 5 per cent incentive for the full tenure, plus a domestic design and research and development incentive of 3 per cent.

    How does a firm actually earn the incentive?

    1. Turnover gate: Mobile phone companies, including electronics contract manufacturers, need a turnover of ₹10,000 crore in 2025-26 to qualify. Electronics manufacturing services firms with 51 per cent Indian ownership qualify at ₹1,000 crore.
    2. Growth gate: Incentives are disbursed only on sales beyond 115 per cent of the previous financial year’s production. A unit that produced ₹10 crore worth of phones in the preceding year and ₹12 crore in the next draws incentive on ₹50 lakh alone.
    3. Sourcing condition: The 1.5 per cent additional incentive applies only where a firm sources domestically for at least a quarter of the phones it sells in that financial year.
    4. No earmarking: The corpus is fungible overall, so no amount is reserved for domestic players. Foreign phonemakers face a higher bar to draw incentive, and they draw it from the same pool.

    What does the scheme change for Indian brands?

    1. Ownership test: An Indian brand must be majority owned by Indian citizens and incorporated in India, with intellectual property and trademarks held locally.
    2. No sales floor: Indian brands are exempt from the minimum sales threshold that applies to other brands, and their baseline is fixed at 2025-26.
    3. Stated intent: The Union Minister for Electronics and Information Technology framed the shift as one of Indian brand, Indian design and Indian intellectual property.
    4. Discretionary channel: An empowered committee will make recommendations to the government on Indian brand applications for incremental incentives and for non fiscal support.

    What has the assembly led phase achieved, and where has it stopped?

    1. Import to export: Around 70 per cent to 75 per cent of phones sold in India were imports in 2014-15, and the country is now an exporter of finished handsets.
    2. Global position: India is the second largest phone manufacturer in the world, and practically all phones sold in the country are made in it.
    3. Shallow value: Domestic value addition in mobile phone manufacturing stands at 23 per cent, so most of the value in an Indian assembled handset is still created abroad.
    4. A ceiling exists: The benchmark set by Chinese phone assembly units is itself bounded, because components in electronics value chains crisscross the globe several times before a device is finished.

    What does the scheme set out to achieve by 2030-31?

    1. Production: Cumulative production, measured as the combined sale value of finished products, is targeted at ₹39 lakh crore by the end of the scheme.
    2. Exports: Cumulative exports over the same period are targeted at ₹5 lakh crore.
    3. Value addition: The stated goal is to double overall domestic value addition from a band of 18 per cent to 23 per cent up to a band of 35 per cent to 40 per cent.
    4. Employment: The Secretary of the Ministry of Electronics and Information Technology put direct job creation under the scheme at 60,000.

    Why does the government treat phone assembly as a gateway sector?

    1. Skill and technology spillover: Technology and skill transfer from handset lines is stated to enable adjacent hardware production, in laptops, tablets and smart watches.
    2. New device categories: The same capability base is expected to carry into gaming consoles, drone manufacturing and medical devices.
    3. Beyond electronics: Components and automobile windshields are named as further beneficiaries of the manufacturing ecosystem the sector builds.

    Challenges to the Mobile Phone Manufacturing Scheme

    1. Incentive concentrates in a few assemblers: A single fungible pool rewards volume, and volume already sits with a small set of contract manufacturers. Eg. Under the earlier electronics scheme, most disbursed incentive flowed to a handful of contract assemblers serving Apple and Samsung. Fix. Ring fence a defined tranche of the corpus for the Indian brand track instead of leaving the whole corpus open to competition.
    2. The turnover gate excludes the firms the scheme names: A ₹1,000 crore revenue floor sits above what the surviving Indian handset brands turn over. Eg. Micromax and Lava operate at a fraction of the revenue of the contract assemblers they would compete with for the same pool. Fix. Add a staged eligibility ladder with a lower entry threshold and a rising production commitment.
    3. The sourcing bonus has a thin supplier base to draw on: Displays, camera modules and application processors are not made in India at scale. Eg. Display panels and camera modules for handsets assembled in India are imported largely from China, South Korea and Vietnam. Fix. Sequence disbursement under the Electronics Component Manufacturing Scheme ahead of assembly incentive, so a supplier base exists before the bonus is claimed.
    4. A demand slump erases a year’s eligibility: Incentive accrues only above a fixed growth threshold over the prior year, so a flat year pays nothing. Eg. Covid disruption in 2020-21 left applicants under the earlier electronics scheme unable to meet their first year incremental production targets. Fix. Allow an unmet incremental target to be carried into the following year within the same tenure.
    5. Locally held intellectual property can be bought rather than built: The Indian brand test rests on registered ownership, which an assignment satisfies without design capability moving to India. Eg. Contract design houses in Shenzhen supply reference designs that brands across Asia rebadge as their own. Fix. Tie the design and research incentive to audited domestic engineering headcount and to patents filed from India.

    Conclusion

    The Mobile Phone Manufacturing Scheme has moved from Cabinet approval to notification, with operational guidelines issued on 21 August 2026 and a tenure running to 2030-31. The next milestone is the application round. Assemblers file against the turnover gate. Indian brands file separately for the brand track. Whether the second track becomes a genuine channel or a minority claim on a shared pool will be visible in the empowered committee’s first set of recommendations.

    “[2025, GS3, 15 marks] Discuss the rationale of the Production Linked Incentive (PLI) scheme. What are its achievements? In what way can the functioning and outcomes of the scheme be improved?”

  • Centre set to expand mechanised sanitation scheme to rural India

    Why in the News

    The Social Justice Ministry has moved a proposal to extend the National Action for Mechanised Sanitation Ecosystem scheme from towns and cities to rural parts of the country. The scheme profiles sewer and septic tank workers as the route to its benefits, and coverage is being widened ahead of a delivery channel that approves capital subsidy for a small fraction of those profiled.

    Components of NAMASTE

    1. Profiling and identification: Sanitation workers are enumerated at camps run by urban local bodies, and that profile is the entry point to every other component of the scheme.
    2. Occupational safety: Profiled workers are given safety training and personal protective equipment for the work they already perform.
    3. Capital subsidy for self employment: A profiled worker or a Private Sanitation Service Organisation may apply for a capital subsidy to buy mechanised equipment and set up a sanitation enterprise.
    4. Emergency Response Sanitation Units: Urban local bodies are supported to set up standing units equipped with suction and jetting machines, so that a sewer or septic tank is cleaned by machine instead of by human entry.

    What is manual scavenging?

    1. Manual scavenging: Manual scavenging is the manual handling, carrying or disposing of human excreta from an insanitary latrine, an open drain, a pit or a railway track. The Prohibition of Employment as Manual Scavengers and their Rehabilitation Act, 2013 prohibits both the practice and the employment of any person for it.

    Who is a sewer and septic tank worker (SSW)?

    1. Sewer and septic tank worker: A sewer and septic tank worker (SSW) is a person engaged in cleaning sewer lines, manholes and septic tanks, whether employed directly or engaged through a contractor. The category is distinct from manual scavenging in law, since the work is lawful when performed with mechanised equipment and prescribed safety gear.

    What is a Private Sanitation Service Organisation (PSSO)?

    1. Private Sanitation Service Organisation: A Private Sanitation Service Organisation (PSSO) is a private entity providing mechanised sanitation services that can propose projects for capital subsidy under the scheme. It is one of two proposal routes, the other being an application by an individual worker.

    What is the Safai Udyami Yojana?

    1. Safai Udyami Yojana: The Safai Udyami Yojana is the self employment component under which sewer and septic tank workers receive capital subsidy to set up their own sanitation enterprise. It is one of the two self employment routes in which the National Commission for Scheduled Castes has flagged rejections.

    What does the proposed expansion change?

    1. Geographic extension: The proposal takes the scheme’s scope from towns and cities to rural parts of the country for the first time.
    2. New worker categories: Coverage will be widened to include drain cleaners, and workers in sewage treatment plants and faecal sludge treatment plants.
    3. Outlay and horizon: The Ministry has proposed around ₹498.73 crore for the expanded scheme, to be spent from this fiscal year to 2030-31.
    4. Second widening of scope: The scheme initially covered only sewer and septic tank workers and was first expanded to include waste pickers, so the rural extension is the second enlargement.
    5. Original aim retained: The scheme was started in 2023-24 with the aim of eradicating sewer and septic tank deaths, and the expansion does not alter that objective.

    Why has the scheme’s delivery record become the central concern?

    1. Profiling against approval: 90,915 sewer and septic tank workers have been profiled across the country, and only 810 have been approved for capital subsidies.
    2. Approval against disbursal: Of the 810 approved, 147 had actually received their funds as on 31 March 2026.
    3. Subsidy covers only part of the cost: The capital subsidy meets up to 50 per cent of total project cost, so an approved worker still has to raise the balance before the enterprise can start.
    4. Manual scavengers identified: Only 2,652 projects have been approved against the 58,000 manual scavengers identified under the scheme.
    5. Both routes inside the count: The 2,652 approvals include projects proposed by Private Sanitation Service Organisations as well as by individuals, so the figure is not a count of individual entrepreneurs alone.
    6. Waste picker coverage: 1.3 lakh waste pickers have been profiled alongside the sewer and septic tank workers, per the Ministry’s annual report for 2025-26.

    What has the National Commission for Scheduled Castes flagged?

    1. Repeated correspondence: The Commission has written repeatedly to the Social Justice Ministry since last year on the continued rejection of applications under the self employment and capital subsidy components.
    2. Rejections identified as the cause: It has held that one reason for the low number of approved projects is the high rate of rejections.
    3. Rejections across every part: It has noted rejections under each part of the capital subsidy component, and asked that these be examined.
    4. The August 2025 letter: That letter flagged rejections in the self employment components, both in the Safai Udyami Yojana and in the component for Private Sanitation Service Organisations.
    5. Source of the mandate: The Commission acts under Article 338, which empowers it to investigate and monitor safeguards for the Scheduled Castes and to inquire into specific complaints.

    Why do sewer and septic tank deaths persist under a statutory prohibition?

    1. Deaths on record: 498 people died across the country while engaged in the hazardous cleaning of sewers and septic tanks from 2019 to June 2026, per the Social Justice Ministry’s reply to Parliament in August 2026.
    2. Enforcement rests with the employer: The Prohibition of Employment as Manual Scavengers and their Rehabilitation Act, 2013 bars hazardous cleaning without protective gear, and the duty to enforce falls on local authorities who are frequently the employers themselves.
    3. Contracting layer: Sewer cleaning is routinely outsourced, which separates the municipal principal from the worker who enters the tank.
    4. Rehabilitation lag: A worker whose capital subsidy application is rejected returns to the same work, so profiling without disbursal leaves the occupational risk untouched.
    5. Rural gap unmeasured: Rural areas have been outside the scheme until this proposal, so deaths in village septic tanks have had no dedicated scheme response.

    Challenges to NAMASTE

    1. Rejection concentrated in the subsidy pipeline: The bottleneck sits between profiling and approval rather than between approval and identification. Eg. The National Commission for Scheduled Castes has recorded rejections under every part of the capital subsidy component and has asked the Ministry to explain them.
    2. Balance financing after subsidy: The worker must raise the uncovered share of project cost as a loan against negligible collateral. Eg. National Safai Karamcharis Finance and Development Corporation term loans routed through State channelising agencies have carried low utilisation and weak recovery.
    3. Urban local body capacity: Emergency Response Sanitation Units need trained crews and maintained machines, which small municipalities cannot sustain. Eg. The Safaimitra Suraksha Challenge launched in 2020 enrolled 246 cities to become sewer death free, and participation was concentrated in large municipal corporations rather than small towns.
    4. Contractor liability gap: Outsourcing lets the principal employer distance itself from a death inside a manhole. Eg. In Delhi Jal Board v National Campaign for Dignity and Rights of Sewerage and Allied Workers (2011), the Supreme Court held that the principal employer cannot escape liability by engaging contractors for sewer cleaning.
    5. No rural delivery cadre: Rural sanitation is administered by gram panchayats, which have no wing equivalent to an urban local body’s sanitation department. Eg. Faecal sludge emptying in villages is done by informal private operators outside any municipal register, which leaves no employer to profile a worker against.
    6. Monitoring by profiling count: Progress is reported as workers profiled rather than as workers rehabilitated, so the headline number rises without entitlement delivery following it. Eg. The Ministry’s annual report for 2025-26 leads with profiling totals for sewer and septic tank workers and waste pickers, and not with the count of workers placed in an alternative livelihood.

    Conclusion

    The Social Justice Ministry has proposed extending the National Action for Mechanised Sanitation Ecosystem scheme to rural India, to drain cleaners and to treatment plant workers. The proposal is at the stage of a Ministry submission and has not yet been notified, and the next milestone is approval of the expanded scheme and its outlay. The delivery record it inherits is a profiling count far ahead of the number of capital subsidy cases funded, alongside 498 sewer and septic tank deaths between 2019 and June 2026.

    “[2016] ‘Rashtriya Garima Abhiyaan’ is a national campaign to

    (a) rehabilitate the homeless and destitute persons and provide them with suitable sources of livelihood

    (b) release the sex workers from their practice and provide them with alternative sources of livelihood

    (c) eradicate the practice of manual scavenging and rehabilitate the manual scavengers

    (d) release the bonded labourers from their bondage and rehabilitate them

  • Can free public technology break the private coaching industry?

    Why in the News

    The Independence Day address of 15 August 2026 announced that the government will roll out free online coaching for competitive examinations using India’s digital public infrastructure. The announcement raises a question free access alone cannot settle, since the coaching industry sells structure, assessment and test strategy rather than lectures.

    What is the proposed free online coaching network?

    1. About: A publicly funded online coaching service for aspirants of competitive examinations, to be built on India’s existing digital public infrastructure, teachers and talent.
    2. Stated purpose: The stated objective is to save poor and middle-class families thousands of crores of rupees and to let students prepare without leaving their homes.
    3. Trigger for the announcement: The announcement was framed as an outreach to Gen-Z youth, following widespread student protests against the National Eligibility cum Entrance Test (NEET) paper leak.
    4. Design question left open: The current thinking within government is one course per examination, against a proposal for a single layered stack serving many examinations.

    What is SWAYAM?

    1. About: Study Webs of Active Learning for Young Aspiring Minds (SWAYAM) is the government’s massive open online course platform, offering courses from Class 9 to post-graduation free of cost to any learner.

    What is SAATHI?

    1. About: Self Assessment Test and Help for Entrance Exams (SAATHI) is a free preparation platform and application for national entrance examinations, carrying lectures and practice tests for aspirants.

    What is agentic artificial intelligence?

    1. About: Agentic artificial intelligence describes systems that pursue a goal across multiple steps on their own, choosing actions and tools rather than answering a single prompt at a time.
    2. Why it is invoked here: In a learning platform it allows the system to diagnose a student’s weak areas, set the next task and adapt the sequence without a teacher directing each step.

    What is a digital twin in education?

    1. About: A digital twin is a live digital replica of a real system, updated with data from that system so changes can be tested on the replica first.
    2. Why it is invoked here: A digital twin of a course or a classroom lets a student tweak the model and reshape the learning path to individual need.

    Why does coaching dependency persist when schools and colleges exist?

    1. Two different objectives: The school aims to conceptualise learning and focuses on board examinations. Competitive examinations ask whether a student can outperform millions of others under severe time pressure.
    2. A separate skill set: The two are different dimensions and require a separate skill set, which the school curriculum is not designed to build.
    3. Where dependency begins: Students in Classes 9 and 10 are less dependent on coaching. Dependency starts in Classes 11 and 12 as students begin preparing for the Joint Entrance Examination (JEE) and NEET and have to solve complex questions.
    4. The gap in objectives: The board curriculum is not designed to prepare a student for the examinations that follow it, so the objectives of the two systems diverge sharply.

    What does the private coaching industry sell that free lectures do not?

    1. Structure: Coaching classes are structured and deliver on what they promise, which free access to recorded lectures does not reproduce.
    2. Assessment and doubt resolution: The industry provides weekly assessments and doubt-solving forums as part of the same package.
    3. Examination technique: Coaching centres teach rapid problem solving and test strategies, including eliminating wrong options to arrive at the right answer, which directly improves rank.
    4. Price is not always the barrier: Not all coaching courses cost lakhs of rupees. Some tutors offer the same structure through an application for a minimum charge of around Rs 700 to Rs 800.
    5. The human element: Personalised feedback and a competitive peer environment come from teachers who mentor a student emotionally and academically, which an online module alone cannot supply.

    Does free access break coaching dependency or add another video library?

    1. The equity reading: The announcement is a major intervention in education equity and an opportunity to redesign the competitive examination preparation ecosystem, so the probability of success depends less on family income, geography and access to an elite coaching centre.
    2. The dependency reading: Accessibility and affordability are not the main issues. The deeper issue is the dependency of the Indian education system on coaching, and a platform that does not end that dependency becomes another free access platform where videos are uploaded daily.
    3. Why existing platforms fall short: The existing public platforms are traditional in nature and are not designed for a cohort that wants mobile-based delivery, quick content in different formats and room to experiment outside a classroom.
    4. The resource argument: The government has ample funds and the Indian Institutes of Technology (IITs) and the Indian Institutes of Management (IIMs) at its disposal, so it can make coaching free. The entire structure has to be incorporated, not only the lectures.
    5. The proposed middle path: A hybrid mechanism is needed, with skill hubs in schools that students attend physically for periodic mentoring alongside online classes, since the National Education Policy (NEP), 2020 already encourages skill hubs.

    Should the platform be one common stack or one platform per examination?

    1. The common stack case: India has over 100 major national-level examinations, including the Union Public Service Commission examinations, JEE and NEET, which attract millions of aspirants. About 70 to 80 per cent of these examinations have similar requirements for reasoning, language, general awareness and current affairs.
    2. The proposed grid: A national competitive learning and opportunity grid with a layered selection method would let a student adopt only the layers relevant to the examination being attempted.
    3. The dedicated platform case: The common stack model does not work in practice, since the same subject is taught differently for two examinations. Fundamental concepts in physics are the same for NEET and JEE, and the nature of the examination differs enough to require separate classes.
    4. The feasibility verdict: A common grid is a futuristic plan rather than a currently feasible one, so there should be one proper dedicated platform per examination.
    5. The dilution risk: Building coaching for all national examinations at one point risks diluting quality, which is why the scope of the plan has to be settled first.

    How can the last mile be reached?

    1. The double hurdle: Millions of students face two problems at once: the absence of reliable, high-speed Internet and electricity for online coaching, and examination centres located hundreds of kilometres away.
    2. Current coverage: Third generation and fourth generation mobile implementation has already reached tribal areas, so the residual problem is difficult terrain with low penetration and frequent disconnects.
    3. The satellite receiver: A small, compact ground antenna box is installed at a remote examination centre. The antenna connects directly to Low Earth Orbit (LEO) or Geostationary (GEO) satellites instead of relying on local broadband or mobile networks, in the manner of satellite television broadcasting.
    4. The offline base station: The base station receives the question paper from the satellite and stores it locally. It then acts as an offline server to display the paper or transmit it over short range to students.
    5. The digital answer pad: Students write answers with pen and paper placed over a small smart digital pad carrying short-range wireless capability such as near field communication or radio waves. The pad captures the answers as they are written, encrypts the data locally and saves it in real time, so no active Internet connection is needed during the test.
    6. The upload step: Once the examination ends and a satellite link connects, the local base station securely uploads all encrypted answer files back to the central examination authority.
    7. The low-technology alternative: Existing infrastructure can be improved instead, by installing smart boards, supplying all lectures, and having a mentor play the video and work through concepts and activities in front of the students.

    Challenges to the Free Online Coaching Network

    1. Content without structure: A platform that uploads lectures without weekly assessment and doubt resolution reproduces a library rather than a course. Eg. SWAYAM has run since 2017 with large enrolment and course completion rates that remain a small fraction of registrations.
    2. Device and bandwidth exclusion: Online delivery presumes a personal device and continuous data, which the poorest households do not have. Eg. The National Sample Survey round on education found that only about 8 per cent of rural households with members aged 5 to 24 had both a computer and an Internet connection.
    3. Teacher supply: A public platform needs subject teachers trained in examination technique, and the school system already runs short of teachers. Eg. Government schools carry lakhs of sanctioned teaching posts that lie vacant, with single-teacher schools still functioning in several States.
    4. Examination integrity: Moving preparation online does not address the leak risk in the examination itself, which is what triggered the protests. Eg. The NEET undergraduate paper leak of 2024 forced a re-examination and a Supreme Court-monitored review of the National Testing Agency’s processes.
    5. Coaching hubs and student distress: A free platform does not by itself dismantle the residential coaching economy or its pressures. Eg. Kota in Rajasthan recorded a series of student suicides, which led the district administration to mandate counselling and anti-suicide devices in hostels.
    6. Regional language coverage: Competitive examination content in Indian languages is thin, so a national platform in English replicates the existing advantage. Eg. NEET is conducted in 13 languages, and the supply of quality preparation material outside English and Hindi remains limited.
    7. Sustained financing: Platform costs are recurring, covering content refresh, mentors, assessment and bandwidth, and a one-time announcement does not fund them. Eg. Several State-run e-learning portals launched during the pandemic went dormant once the dedicated budget line lapsed.

    Conclusion

    Free public technology can lower the price of preparation, and price is not the mechanism that sustains coaching dependency. That dependency comes from the gap between what schools teach and what competitive examinations test, and from the structure, assessment and test strategy the coaching industry sells alongside its lectures. A public platform reduces dependency only if it reproduces that structure, adds physical mentoring through school skill hubs, and solves the connectivity and distance problem at the last mile. The scope question, one common stack against one platform per examination, remains unsettled and determines whether quality survives scale.

    “[2016] ‘SWAYAM’, an initiative of the Government of India, aims at

    (a) promoting the Self Help Groups in rural areas

    (b) providing financial and technical assistance to young start-up entrepreneurs

    (c) promoting the education and health of adolescent girls

    (d) providing affordable and quality education to the citizens for free

  • Conflict of Interest in the RDI Fund: When Proximity Is the Qualification

    Why in the News

    The Union Minister for Science and Technology has described the conflict of interest safeguards governing the Research, Development and Innovation Fund as fairly robust, and said more safeguards could be considered wherever feasible. The remarks follow a disclosure that most companies funded in the Fund’s first round had investment ties to members of the panel that selected them.

    What is the Research, Development and Innovation Fund and what does it finance?

    1. A public financing vehicle for frontier research: The Research, Development and Innovation (RDI) Fund was set up by the government last year to give low cost, long tenure loans to private companies doing cutting edge research.
    2. Priority areas named at launch: Eligible fields include quantum computing, robotics, space, biotechnology, clean energy and climate action.
    3. Corpus and horizon: The Fund is to carry a corpus of Rs 1 lakh crore built over six years.
    4. Instruments used: Money moves out as low interest loans, as equity, or as contributions to a fund of funds, not as a research grant.

    Why is the Fund built as a repayable capital instrument rather than a research grant?

    1. A revolving fund, not a one time outlay: The RDI Special Financial Rules provide for recycling of capital and its return to the Consolidated Fund of India. That makes it a revolving innovation fund rather than a spending line exhausted once disbursed.
    2. Co-financing ceiling: A selected company can draw a maximum of 50 percent of its project cost from the Fund. The remainder comes from the promoter and private investors, giving both a stake in the outcome.
    3. Risk reduced by portfolio and stage selection: Companies are chosen after their core technology risk has been overcome. The portfolio approach spreads residual risk across ventures rather than concentrating it in one bet.
    4. A shift in the state’s role: Public support moves away from the traditional grant model for research. The government now sets the strategic direction of technological progress and mobilises industry expertise and private capital alongside its own money.
    5. The bottleneck it targets: Government financing of high technology firms has been held back by cumbersome processes and by gaps in technical knowledge inside the bureaucracy.

    What conflict of interest architecture did the Fund already carry?

    1. Committee composition is mandated, not incidental: The scheme requires the Expert Advisory Committee to be composed of eminent industry leaders drawn from industry, investment or technology research and development sectors.
    2. Mandatory recusal: A committee member holding a stake in an applicant must declare that interest and step out of the evaluation of that applicant.
    3. Supermajority voting: The choice of an investee company requires a supermajority of the committee rather than a simple majority.
    4. Recommendation separated from decision: The Investment Committee is a recommending body only. Final accountability for a funding decision rests with the Technology Development Board.
    5. Guidelines framed in anticipation: These pre-investment rules were written in the expectation that connections between industry experts and applicants would be unavoidable.

    What did the first round of disbursement expose about that architecture?

    1. First round approvals: Loans worth Rs 2,192 crore were approved for 22 companies in the first round of funding.
    2. Extent of the overlap: Fifteen of those 22 companies had investment ties to seven members of the selection panel.
    3. The stated procedure was followed: The members concerned declared their interest and recused themselves in each such case, as the guidelines require.
    4. A different pattern in the second round: Only one of the 13 companies selected in the second round has any link to a member of the selection committee. That selection has been finalised and has not been disclosed.
    5. The question the overlap raised: A safeguard that operated correctly in every individual case still left most of the first round money going to companies connected to the panel.

    Is proximity between evaluators and investees a defect or a necessary input?

    1. Proximity as an information input: Not all proximity is conflicting where it improves the quality of the decision. Deep technology investment needs judgement that combines technological maturity with commercial viability.
    2. Who else could supply that judgement: Neither government officials nor academic and scientific evaluators alone can assess whether a frontier technology is ready to be sold.
    3. The connections are the qualification: The members are industry veterans who built and engaged deeply with India’s technology ecosystem. Their investee links are the same links that let them bridge the information gap in screening.
    4. The linkage data read the other way: At least 10 of the 15 startups publicly named have institutional or founder linkages to publicly funded premier technology institutions such as the Indian Institutes of Technology (IITs). Most had already raised external funding, which signals an independent assessment of their technical merit.
    5. The wrong yardstick: The Fund is a public capital deployment mechanism, not a public expenditure scheme. Judging it by the procedural propriety standards written for conventional bureaucratic spending misreads what it is, and outcomes plus the effectiveness of its governance architecture are the better test.
    6. The cost of over correction: Parliamentary and media scrutiny is essential for political accountability. Scrutiny that stifles the scheme damages an instrument on which India’s growth prospects rest.

    Why does India’s scale-up gap make the Fund’s design consequential?

    1. A decade of Startup India: Startup registrations have burgeoned since the programme began, and the entrepreneurial ecosystem has come a long way with them.
    2. The gap that remains: India has not produced many high impact global scale-ups, particularly in technology intensive sectors.
    3. What the Fund is aimed at: The RDI Fund is targeted at closing that gap in frontier sectors, not at early stage startup formation.
    4. Public money as a catalyst: Sectoral commitments by the government pull private investment into technology areas where mission mode initiatives already exist.
    5. The strategic stake: Capability in frontier technology bears directly on technological sovereignty and strategic autonomy.

    What is the government now changing in the Fund’s framework?

    1. The stated position on safeguards: The existing safeguards against conflict of interest in disbursement are held to be fairly robust, with more safeguards to be considered wherever feasible.
    2. A full procedural review: Every procedural safeguard in use against a conflict of interest situation was reviewed at the monthly meeting of secretaries of scientific departments.
    3. Due diligence held as non negotiable: Due diligence and verification processes must remain uncompromised, and suggestions from stakeholders are invited.
    4. Wider sectoral eligibility: Companies from many more sectors have been made eligible for loans, following a recommendation by an expert committee.
    5. Ministries asked to nominate areas: Inter-ministerial consultations have taken place, and every ministry has been asked to suggest areas of national importance where private research could be supported.
    6. Learning carried into later rounds: The experience of the first round is expected to make subsequent rounds function more smoothly and more efficiently.
    7. The balance the government names: Private sector participation inside a public funding framework is treated as a new experience that requires a balance between speed, responsibility and stakeholder confidence.

    Challenges to the Research, Development and Innovation Fund

    1. Concentration of capital in already backed firms: Selecting ventures whose technology risk is retired favours firms with prior institutional and investor backing over first time deep technology founders. e.g. under the Production Linked Incentive scheme for large scale electronics manufacturing, most approved incentive has flowed to a small group of mobile phone assemblers.
    2. Repayment mismatch in long gestation science: Loan repayment schedules sit poorly with fields where commercial revenue arrives a decade or more after the first working prototype. e.g. quantum computing, a stated priority area, has no volume hardware market anywhere in the world.
    3. No statutory conflict of interest code for non official members: The safeguards rest on scheme guidelines rather than on a binding statute, so a lapse carries no legal consequence. e.g. the 2024 controversy over the Securities and Exchange Board of India chairperson’s disclosed holdings ended in fresh internal disclosure norms and no statutory remedy.
    4. Thin domestic risk capital for follow on rounds: A public loan cannot substitute for the later stage private rounds a hardware venture needs to reach scale. e.g. Indian fabless semiconductor design ventures raise most of their growth capital from overseas funds.
    5. Eligibility drift diluting the frontier focus: Widening the eligible sector list risks turning a frontier technology instrument into a general industrial credit line. e.g. startup recognition under the Department for Promotion of Industry and Internal Trade expanded to cover trading and service ventures far removed from technology development.
    6. Propriety scrutiny slowing deployment: A financing vehicle under continuous propriety examination becomes defensive and slow, defeating the speed it was built for. e.g. the National Investment and Infrastructure Fund, announced in 2015, took several years to move from announcement to meaningful deployment.

    Conclusion

    The RDI Fund was designed to bring investor judgement into a public financing decision. The conflict of interest it now faces is the direct cost of that design choice. Recusal and voting thresholds manage the appearance of the problem without removing the overlap between those competent to evaluate deep technology and those already invested in it. What remains unsettled is whether a capital deployment vehicle will be judged on the technologies and returns it produces or on the procedural standards written for ordinary government spending.

    Matching Previous Year Question

    [2018, GS4, 10 marks] What is meant by conflict of interest? Illustrate with examples, the difference between the actual and potential conflicts of interest.

    [2014, GS3, 12.5 marks] Scientific research in Indian universities is declining, because a career in science is not as attractive as our business operations, engineering or administration, and the universities are becoming consume

  • RBI moves to define revolving credit for the first time and bar non-banks from offering it

    Why in the News

    The Reserve Bank of India (RBI) has proposed the first ever regulatory definitions of a term loan and revolving credit, and any facility failing the term loan test would become revolving credit that non-banking financial companies can no longer offer. Revolving credit is the instrument that carried formal finance into rural India, where income is seasonal and expenses run months ahead of receipts. The regulator is now weighing that inclusion gain against the risk of debt recycling through digital credit lines.

    What is revolving credit?

    1. About: Revolving credit comes with a pre approved credit limit against which a borrower can draw, repay and reuse without applying afresh each time.
    2. Contrast with a term loan: A normal term loan is sanctioned once and repaid in fixed instalments, and the limit is not restored after repayment.
    3. Function for the borrower: It works as a financial buffer, letting households, farmers and small entrepreneurs manage short term cash needs, emergencies and income fluctuations.
    4. Function for the lender: It provides recurring income streams, better utilisation of existing credit infrastructure and higher returns on assets through repeated usage.

    Why does rural India need revolving rather than term credit?

    1. Weight in the economy: Rural India contributes 46 to 50 percent of gross domestic product, and its income is largely seasonal.
    2. The cash flow mismatch: Farmers incur expenses on seeds, fertilisers, labour and irrigation months ahead of the income stream, and structural rigidity in the formal credit framework does not match that timing.
    3. What revolving credit does: It bridges the gap by supplying liquidity as and when it is required rather than in a single sanctioned tranche.
    4. Protective function: It acts as a shield against financial shocks and against informal loan sharks.
    5. The instruments it produced: The Kisan Credit Card (KCC), overdraft facilities, self help group credit lines, microfinance linked loans and, increasingly, digital credit products.
    6. Beyond the farm: Rural micro enterprises depend on flexible working capital, and the self help group and bank linkage programme supported by NABARD has created one of the world’s largest community based credit ecosystems.

    What has the Kisan Credit Card delivered?

    1. Introduction: The KCC scheme was introduced in 1998-99 as the principal form of revolving credit in rural areas.
    2. Widening scope: It expanded beyond crop cultivation to allied activities such as dairy, fisheries and animal husbandry.
    3. Current spread: More than 7.72 crore KCCs are active nationwide.
    4. Who holds them: The majority of beneficiaries are small and marginal farmers.
    5. Broader effect: The share of rural households accessing institutional credit channels such as the KCC has risen significantly.

    How have non-banking financial companies become the main channel?

    1. Why they entered: Small ticket unsecured revolving loans carry higher interest rates on higher risk, so the untapped rural market offered both volume and yield.
    2. Product spread: Non-banking financial companies (NBFCs) expanded revolving credit through consumer credit lines, digital loans, merchant finance, working capital loans to micro, small and medium enterprises, and fintech partnerships.
    3. Last mile role: They became a pillar of last mile credit delivery in rural and semi urban areas where banks face high transaction costs, lack of collateral and information asymmetry.
    4. Scale: More than 9,000 registered NBFCs operate in India, the vast majority in the Base Layer, with overall outstanding credit of Rs 58.61 lakh crore by mid-2026.
    5. Composition of the rural footprint: It is driven by microfinance institutions, gold loan companies, vehicle financiers, and lenders to micro, small and medium enterprises and small ticket retail borrowers.
    6. The gap in it: Agriculture remains a relatively small component of overall NBFC lending.

    What does the microfinance data show?

    1. Portfolio outstanding now: The portfolio outstanding of the microfinance sector, comprising NBFC microfinance institutions and small finance banks, stood at Rs 2.77 lakh crore as at March-end 2026.
    2. The two preceding years: It was Rs 3.35 lakh crore a year earlier and Rs 3.78 lakh crore as at March-end 2024.
    3. Rate of contraction: Total microfinance portfolio outstanding fell by about 17 percent year on year to Rs 2.77 lakh crore by March 2026, per the SIDBI-Equifax report.
    4. Geographic concentration: The top five States, Bihar, Uttar Pradesh, Tamil Nadu, West Bengal and Karnataka, account for 57 percent of total portfolio outstanding.
    5. What the numbers indicate: A two year contraction of over a quarter in the portfolio, concentrated in five States, signals asset quality stress rather than a policy induced slowdown.

    What is the RBI proposing to change?

    1. First ever definitions: The RBI is proposing an amendment that defines term loan and revolving credit for the first time.
    2. The term loan test: A term loan may be disbursed in one or more tranches, but repayment must follow a fixed schedule.
    3. The reuse bar: Once repaid, the credit limit cannot be restored or reused.
    4. The residual category: Any facility that does not meet this definition will be treated as revolving credit.
    5. The operative restriction: Revolving credit, so defined, is what NBFCs can no longer offer.

    Why is the RBI concerned?

    1. Evergreening: The regulator has repeatedly flagged the rapid growth of unsecured retail credit, particularly through fintech and NBFC partnerships offering high risk products as revolving credit.
    2. Masked indebtedness: It remains sceptical of forms of revolving credit where repayment patterns conceal the true level of household indebtedness.
    3. Ease outpacing discipline: Technology has made borrowing easier and faster than financial discipline, and multiple borrowings through various applications with weak due diligence have elevated risk.
    4. Underwriting by algorithm: Some digital platforms relied on algorithms and alternative data without sufficient assessment of repayment capacity.
    5. Purpose of the borrowing: Unlike farm or business revolving credit, many digital credit lines financed consumption rather than income generation.
    6. Official assessment: The latest Economic Survey acknowledged the critical role of NBFCs in inclusion while warning that unchecked expansion can weaken household balance sheets.

    Can the restriction be tightened without pushing borrowers back to informal lenders?

    1. The regulator’s mandate: The RBI must tread a delicate balance between financial inclusion and financial stability, and both claims are legitimate.
    2. The case against a blanket bar: A blanket restriction may be counterproductive, since the microfinance space has historically been underserved and lending is already muted on asset quality pressures and limited funding access.
    3. The instruments at stake: The KCC and similar instruments are essential for growth, while unchecked and easy accessibility through digital platforms and consumer finance channels creates fresh vulnerability.
    4. The real policy problem: The challenge is to identify credit that helps in income generation and separate it from credit that finances consumption, since the two carry different repayment logic.
    5. The failure mode: Excessive regulatory tightening may push borrowers back towards informal lenders, defeating the very purpose of financial inclusion.

    Challenges to Revolving Credit in Rural India

    1. Debt recycling: A revolving limit lets a borrower repay one obligation by drawing on another without the stress becoming visible. e.g. a household clearing one digital credit line by drawing on a second application in the same month.
    2. Multi lending and over indebtedness: Several lenders extending limits to the same household produce a repayment burden none of them has measured. e.g. the microfinance portfolio contracting by about 17 percent year on year to Rs 2.77 lakh crore by March 2026.
    3. Geographic concentration of risk: A localised shock hits a disproportionate share of the sector’s book. e.g. Bihar, Uttar Pradesh, Tamil Nadu, West Bengal and Karnataka holding 57 percent of microfinance portfolio outstanding.
    4. Consumption financing: Credit that funds consumption creates no repayment capacity of its own. e.g. digital credit lines used for durables and lifestyle spending rather than for working capital.
    5. Weak underwriting: Alternative data and algorithmic scoring substitute for an assessment of cash flow. e.g. platforms sanctioning limits without verifying seasonal farm income.
    6. Exclusion of tenant cultivators: Revolving farm credit is tied to land records, so the actual cultivator is often ineligible. e.g. oral lessees who cannot produce title to obtain a Kisan Credit Card.
    7. Delinquency and capital cost: Unchecked expansion raises delinquencies and capital requirements together, so profitability depends entirely on risk controls. e.g. small finance banks tightening disbursement after the microfinance portfolio fell from Rs 3.78 lakh crore in March 2024.

    Conclusion

    Revolving credit solved a timing problem that term lending could not, which is why the Kisan Credit Card, self help group credit lines and NBFC credit lines became the core of rural financial inclusion. The RBI is now proposing the first regulatory definitions of a term loan and revolving credit, with the effect that non-banks would be barred from the residual revolving category. The stated concern is evergreening and masked household indebtedness through fintech linked digital credit rather than farm or enterprise credit. The measure is at the proposal stage, and its success will be judged by whether the definitional line separates income generating credit from consumption credit, since a blanket restriction would return underserved borrowers to informal lenders.

    “[2014, GS3, 12.5 marks] “In the villages itself no form of credit organization will be suitable except the cooperative society.”-All India Rural Credit Survey. Discuss this statement in the background of agricultural finance in India. What constraints and challenges do financial institutions supplying agricultural finance face? How can technology be used to better reach and serve rural clients?”

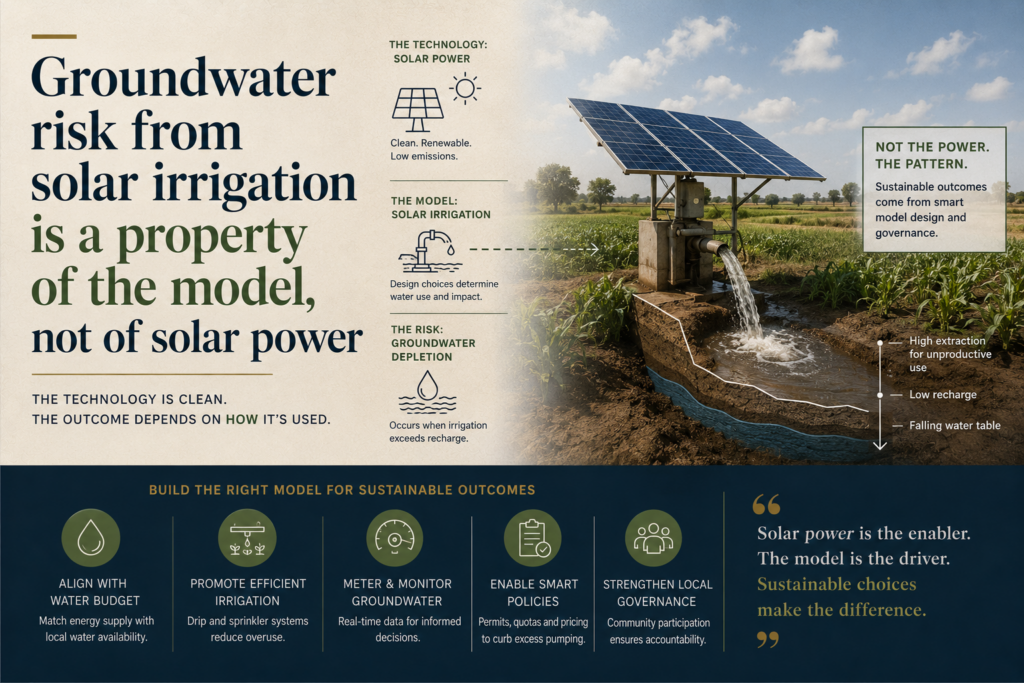
  • Groundwater risk from solar irrigation is a property of the model, not of solar power

    Why in the News

    India’s agricultural solar programme has installed over 2.5 million solar pumps in five years, and the government is now preparing PM-KUSUM 2.0. The standard objection is that free solar power removes every incentive to limit pumping and will therefore deepen the groundwater crisis. That objection treats solar irrigation as a single model, when the groundwater outcome is determined by ownership structure, pricing incentive and local hydrogeology.

    What is PM-KUSUM?

    1. About: The Pradhan Mantri Kisan Urja Suraksha evam Utthan Mahabhiyan (PM-KUSUM) is India’s agricultural solar programme, administered by the Ministry of New and Renewable Energy.
    2. Delivery so far: It has installed over 2.5 million solar pumps over the past five years, made affordable for smallholder farmers through subsidies.
    3. Three routes: It supports decentralised grid connected solar plants on barren land, standalone off grid solar pumps, and the solarisation of existing grid connected agricultural pumps.
    4. Next stage: The government is preparing PM-KUSUM 2.0, whose design challenge is to advance the clean energy transition without worsening an already over exploited groundwater base.

    What is a feed in tariff?

    1. About: A feed in tariff is a guaranteed per unit price at which a distribution utility buys electricity that a small generator exports to the grid.
    2. Why it matters here: A high enough tariff converts every unit of electricity not used for pumping into cash income, so saving water becomes profitable rather than merely virtuous.

    Why is the standard objection to solar irrigation incomplete?

    1. The objection itself: Heavily subsidised or free electricity has driven unsustainable groundwater abstraction, falling water tables, depleting aquifers and growing fiscal burdens on energy utilities, and solar is assumed to extend that pattern.
    2. First gap, the single model assumption: The debate treats solar irrigation as one model, typically a farmer running a standalone pump with no incentive to conserve water, when models differ by design, ownership structure and pricing incentive.
    3. Second gap, energy as the only variable: The debate discounts local hydrogeology, cropping patterns, marginal returns to irrigation and soil type, all of which shape irrigation behaviour independently of the energy source.
    4. Third gap, evaluation in a silo: Solar irrigation is judged as either a water intervention or an energy intervention, when its consequences span water, energy and food together.
    5. The reframed question: The question is not whether solar irrigation is inherently good or bad for groundwater, but what kind of model is deployed, where, and with what incentives.

    How do ownership and pricing change the groundwater outcome?

    1. Grid connected models create a price for restraint: Models that let farmers sell surplus solar electricity back to the grid give a direct financial reward for using less water.
    2. Gujarat’s Suryashakti Kisan Yojana: Around 100 agricultural feeders were transitioned to solar energy under the scheme.
    3. Measured behaviour change: Solar farmers showed significantly slower growth in energy consumption and in irrigation application than non solar farmers, indicating more sustainable water use.
    4. The tariff that produced it: The scheme offered around Rs 7 per unit as a feed in tariff, a meaningful incentive to conserve electricity and export energy.
    5. Income effect: By exporting energy, farmers earned an average of roughly Rs 21,900 annually, converting them from energy consumers into energy producers.
    6. Standalone pumps vary too: Even for standalone off grid pumps under PM-KUSUM, utilisation and the extent to which the pump replaces diesel rather than grid electricity vary widely with installed capacity, the depth of the water table and years of operating experience.

    What does the Bangladesh model show about pricing solar water?

    1. The dominant model there: Bangladesh’s most common arrangement is the fee for service centralised solar model, in which a pump owner supplies water to multiple farmers within a fixed command area.
    2. The revenue logic: The owner earns from selling water, so the pump is operated as a business rather than as a private convenience.
    3. The measured result: Farmers using solar irrigation did not apply more water than farmers using diesel, even though solar irrigation was 20 to 30 percent cheaper.
    4. The mechanism behind it: Excessive irrigation by one farmer reduces the operator’s ability to serve others, so efficient and equitable groundwater use becomes a condition of the business remaining financially sustainable.
    5. What the case demonstrates: A cheaper energy source did not raise water use once the water itself carried a price and a rationing constraint.

    Why does the same pump produce different outcomes across regions?

    1. Hard rock aquifer regions: Where storage capacity is limited and cropping is rainfed, each additional unit of irrigation water yields high marginal benefit, and water use changed little between solar and non solar users regardless of the energy source.
    2. Punjab and Haryana: Irrigation is already widespread and dominated by water intensive rice and wheat, leaving little scope to expand irrigated area, so solar is unlikely to drive further over exploitation.
    3. The real question in those States: Whether solar can make water, energy and food systems more sustainable by replacing subsidised fossil fuel electricity with grid connected solar, cutting subsidy costs and emissions together.
    4. Eastern India: Irrigation expansion has been constrained by access to energy rather than to water, with large rainfed areas, high diesel costs and unreliable power.
    5. Policy consequence: Solar irrigation policy must follow a differentiated regional approach with context specific model choice, paired with stronger groundwater monitoring and adaptive management to catch emerging stress early.

    What does solar irrigation change beyond groundwater?

    1. Emissions from pumping: Groundwater irrigation in India is estimated to generate between 45 and 62 million tonnes of carbon dioxide a year.
    2. Fiscal burden: Agricultural electricity subsidies across States amount to over Rs 1 lakh crore a year.
    3. Per farmer mitigation: Estimates from Gujarat suggest each grid connected solar farmer offsets approximately 12.3 tonnes of carbon dioxide annually through on farm solar use and electricity exported to the grid.
    4. Payback on public money: Subsidies covered nearly one fourth of government investments within the first two years.
    5. Scale of the opportunity: Applied across India’s more than 25 million agricultural pumps, the mitigation and fiscal implications are substantial.

    Should policy prioritise saving water or expanding access?

    1. The case for saving water: In water stressed regions, grid connected solar can be expanded through individual pumps or by taking entire agricultural feeders solar, with both models rewarding farmers for saving water.
    2. The case for expanding access: Where farmers still lack reliable irrigation, the priority is expanding access rather than saving water.
    3. The instrument each case needs: Standalone solar pumps remain the preferred option in areas with limited irrigation, poor grid access and low groundwater risk.
    4. The distributional point: Emphasis should shift from individual ownership to scaling through water user associations, water selling entrepreneurs and farmer cooperatives in India’s most irrigation deprived regions.
    5. Why the tension is real: A single national design cannot simultaneously suppress pumping in Punjab and expand it in Bihar, so the same programme must carry two opposite incentive structures.

    Why has the current design of both models underperformed?

    1. Weak uptake of surplus sale: The approach of paying farmers to save water by selling surplus electricity to the grid has seen limited uptake.
    2. Feeder transitions do not change behaviour: Feeder level transitions to solar have performed better on delivery, but in their current form do little to change pumping behaviour.
    3. What individual pumps need: Simpler grid connection procedures and attractive buyback prices that reflect the local value of water and crops.
    4. What distribution companies need: Distribution companies (DISCOMs), which buy and supply the power, must themselves be incentivised to support the individual pump model.
    5. What feeder solarisation needs: Pairing with water saving incentives such as support for micro irrigation and direct cash payments for reduced pumping, on the model of Punjab’s Pani Bachao Paisa Kamao and Haryana’s Mera Pani Meri Virasat schemes, so the gain is not confined to the distribution company.

    Challenges to PM-KUSUM

    1. Farmer contribution barrier: Even after central and State subsidy, the residual farmer share blocks the poorest applicants. e.g. smallholders in Bihar and Jharkhand, where the same pump costs a larger share of annual income than in Gujarat.
    2. Slow solarisation of existing pumps: Retrofitting grid connected pumps depends on a distribution company agreeing to buy the surplus at a workable price. e.g. the limited uptake of the surplus sale route recorded in the current programme.
    3. Feeder solarisation without behavioural conditions: Solarising a feeder cuts the utility’s power purchase cost without altering how much a farmer pumps. e.g. feeder transitions that improved supply economics while leaving abstraction unchanged.
    4. Unmetered farm supply: Without metering, neither pumping nor saving can be measured, so a water saving payment has no basis. e.g. Punjab, where agricultural supply is largely flat rate and unmetered.
    5. Land availability for decentralised plants: Barren and fallow land near substations is scarce in densely cultivated districts. e.g. canal command areas of western Uttar Pradesh with almost no uncultivated parcels.
    6. After sales service: A solar pump with no local technician becomes a stranded asset. e.g. standalone pumps idling in remote blocks for want of repair and spare parts.
    7. Equity of ownership: Individual ownership concentrates the benefit in farmers who already own a borewell and a landholding. e.g. tenant cultivators and landless water buyers, who gain nothing from a pump subsidy tied to land title.

    Conclusion

    The groundwater question about solar irrigation has been asked at the wrong level, because the outcome is set by ownership structure, pricing incentive and local hydrogeology rather than by the energy source. Gujarat’s feed in tariff and Bangladesh’s fee for service model both show that water use falls once restraint carries a price, while standalone pumps in energy constrained Eastern India are correctly an access instrument rather than a conservation one. PM-KUSUM 2.0 therefore has to carry two opposite incentive structures within one programme, tightened in water stressed States and loosened where irrigation is scarce. The unresolved condition is measurement, since no water saving payment can operate on a farm supply that is neither metered nor monitored.

    “[2025, GS3, 15 marks] Examine the factors responsible for depleting groundwater in India. What are the steps taken by the government to mitigate such depletion of groundwater?”

  • First talks begin on retailing E10 petrol alongside E20 amid the blending row

    Why in the News

    Early exploratory discussions have begun within the government and the fuel industry on whether E10 petrol can be retailed alongside E20, which is currently the only standard petrol variant sold across the country. The trigger is a policy success that has produced a consumer problem: India reached 20 percent ethanol blending five years ahead of the original deadline, which pushed the entire retail network onto a fuel that most vehicles on the road were never certified for. The question now is whether a national fuel supply chain built for a single base grade can be reopened to two.

    What is the Ethanol Blended Petrol (EBP) Programme?

    1. About: The Ethanol Blended Petrol Programme requires oil marketing companies to blend ethanol into petrol at a mandated percentage before sale, so that a share of transport fuel demand is met from domestically produced ethanol.
    2. Administering ministry: Run by the Ministry of Petroleum and Natural Gas, with the Ministry of Road Transport and Highways on vehicle compatibility and the Department of Food and Public Distribution on feedstock supply.
    3. Policy basis: Formalised under the National Policy on Biofuels, 2018, which sets the indicative blending target and defines permitted feedstocks.
    4. Objectives: Reduce crude oil import dependence, cut foreign exchange outgo, provide an assured market for surplus sugarcane and foodgrain, and lower tailpipe carbon monoxide and hydrocarbon emissions.
    5. Beneficiaries: Sugarcane and maize farmers, sugar mills and distilleries, and vehicle owners through the retail fuel price.
    6. Achievement: India reached 20 percent ethanol blending in petrol in 2025, five years ahead of the original target, and the milestone has been credited with displacing about 310 lakh tonnes of crude and saving roughly Rs 1.9 lakh crore in foreign exchange.

    What is E20 petrol?

    1. Composition: E20 is a blend of 80 percent petrol and 20 percent ethanol by volume.
    2. Current status: It is the only standard petrol variant sold across the country, and a notification of 17 February 2026 requires all States and Union Territories to sell E20 at a minimum Research Octane Number of 95 from 1 April 2026.

    What is E10 petrol?

    1. Composition: E10 is a blend of 90 percent petrol and 10 percent ethanol by volume.
    2. Why it is at issue: Older vehicles, particularly two wheelers, were certified for E10 petrol, and E10 was the base retail grade until the network shifted entirely to E20.

    What are Bharat Stage 6 phase two norms?

    1. Definition: Bharat Stage 6 phase two is the second stage of India’s sixth generation vehicle emission standard, which tightened real driving emission and on board diagnostic requirements for vehicles manufactured from April 2023.
    2. Relevance here: Full E20 material compatibility was mandated under these norms, which is why April 2023 is the dividing line between compliant and non compliant vehicles.

    Components of the Ethanol Blended Petrol Programme, by lifecycle stage

    Component and official instrument (lifecycle stage)Intervention and official numbersPrimary stakeholder
    Permitted feedstock list under the National Policy on Biofuels, 2018 (feedstock and input)Allows ethanol from sugarcane juice, sugar and sugar syrup, B heavy molasses, C heavy molasses, damaged foodgrain, maize and surplus rice; no per unit figure attaches to this componentSugarcane and maize farmers, sugar mills
    Ethanol Interest Subvention Scheme (financing)Interest subvention on loans for setting up new distilleries and expanding existing molasses based and grain based capacity; the release states the subvention period, not a fixed outlay per plantDistilleries and sugar mills
    Pradhan Mantri JI-VAN Yojana (plant or asset build, advanced biofuels)Viability gap funding for second generation ethanol projects using lignocellulosic feedstock such as agricultural residueTechnology developers and oil marketing companies
    Administered ethanol procurement price (production and pricing)Differential ex mill prices fixed by the Cabinet Committee on Economic Affairs for each feedstock route, highest for the sugarcane juice route and lowest for the C heavy molasses routeSugar mills and distilleries
    Long term offtake agreements by oil marketing companies (distribution and evacuation)Assured purchase of tendered ethanol volumes for each ethanol supply year, which runs from November to OctoberOil marketing companies and distilleries
    E20 as the base retail grade (offtake and demand)20 percent blending achieved in 2025, five years ahead of the 2030 target; minimum Research Octane Number of 95 required for E20 sold from 1 April 2026Vehicle owners

    What has triggered the rethink on a lower blend?

    1. The consumer complaint: Opposition to E20 has come from several quarters, with claims of notable reduction in mileage and engine component wear in older vehicles whose engines were not designed for higher ethanol blends.
    2. The government’s position on mileage: The drop in mileage in older vehicles would be 3 to 5 percent at most, and would be outweighed by E20’s benefits as a superior fuel.
    3. The government’s position on engine damage: Claims that E20 could damage engine components have been consistently rejected.
    4. The parliamentary figure: A reduction in fuel economy of 2 to 6 percent depending on vehicle category and vintage has been stated in Parliament.
    5. The absence of choice: Questions have been raised on why motorists are not offered a choice between pure petrol, E10 and E20, and some Opposition leaders have taken up the same point.
    6. The first official break: A co authored opinion article published on 17 August 2026 by the Chief Economic Adviser called for a lower ethanol petrol blend such as E10 to be made available alongside E20. The views were personal, and it is the first instance of a high ranking government official publicly calling for more petrol options.
    7. The stated rationale for restoring E10: Restoring a lower blend at the pumps alongside the option to buy E20 would calm public concern, lower total ethanol use instead of raising it, and protect the existing fleet while the retrofit programme catches up.

    Which vehicles are actually affected?

    1. The compliance line: Petrol vehicles manufactured and sold after April 2023 are considered fully E20 compliant, since this was mandated under Bharat Stage 6 phase two emission norms.
    2. What that leaves out: All vehicles currently being sold are E20 compliant, but most vehicles sold prior to 2023 are not.
    3. The scale of the gap: Of about 310 million petrol vehicles in use, only about 70 million built after April 2023 carry factory certified E20 compatibility.
    4. How long the legacy fleet stays on the road: The permissible life of a petrol vehicle in the National Capital Region is 15 years, which means cars manufactured in 2022 can be in use until 2037 under current norms.
    5. The most exposed category: The discussions were initiated specifically with older vehicles, particularly two wheelers, that were certified for E10 petrol, in mind.

    Why is retailing E10 alongside E20 a logistical problem?

    1. A parallel supply chain: Retailing E10 and E20 simultaneously requires a complex, parallel supply chain stretching from refineries to pumps.
    2. The volume distinction: Two or three premium petrol variants already coexist with the base fuel, and their consumption is minuscule compared with base petrol, so offering small volumes alongside E20 is manageable. Retailing E10 in large volumes is a different problem, since the existing chain has shifted entirely to E20.
    3. Underground storage is the binding constraint: Most retail outlets use single or dual underground tanks, so adding E10 alongside E20 would require replacing them with a dual tank system for petrol at thousands of pumps.
    4. Dispensing equipment: Outlets would additionally need separate dispensers for the base fuel.
    5. The government’s July position: Offering multiple grades of base fuel across the country would create an “enormous logistical challenge”, raise costs and reduce operational efficiencies in India’s complex fuel retail network.
    6. The sunk investment argument: The shift to E20 required massive investments already made, and reverting to a lower blend would not be prudent.
    7. Where the talks stand: The discussions are described as “preliminary” and as “keeping the older vehicles in mind”, are being held on technical and non technical aspects of the fuel retail supply chain, and no concrete conclusions have been arrived at.

    Where does the blending success pull against the consumer?

    1. A target met is not a fleet protected: Reaching 20 percent blending five years early moved the entire retail network onto a fuel that roughly four fifths of the petrol fleet was never certified for.
    2. The choice question has no cheap answer: Restoring choice requires physical infrastructure at thousands of outlets, so the demand for choice and the cost of supplying it move in opposite directions.
    3. Lower blend means lower ethanol demand: Restoring E10 would lower total ethanol use, which cuts against the assured offtake that distilleries and sugar mills invested against.
    4. Retrofit is the alternative to reversal: Protecting the existing fleet through a retrofit programme leaves E20 intact but transfers the cost from the fuel network to the vehicle owner.
    5. The time horizon is fixed by vehicle life: With 2022 vehicles running until 2037, the mismatch persists for over a decade regardless of which route is chosen.

    Challenges to the Ethanol Blended Petrol Programme

    1. Legacy fleet incompatibility: The bulk of vehicles on the road predate the E20 mandate. e.g. of about 310 million petrol vehicles in use, only about 70 million built after April 2023 carry factory certified E20 compatibility.
    2. Fuel economy loss: Ethanol has lower energy density than petrol, so the same volume delivers fewer kilometres. e.g. the government puts the drop at 3 to 5 percent in older vehicles, and a range of 2 to 6 percent by category and vintage has been stated in Parliament.
    3. Water footprint of feedstock: Sugarcane based ethanol carries a heavy irrigation demand in water stressed regions. e.g. sugarcane in Maharashtra’s Marathwada draws heavily on groundwater while occupying a small share of the cropped area.
    4. Food versus fuel diversion: Grain routed to distilleries competes with food and feed use. e.g. surplus rice from the Food Corporation of India and maize have been diverted to ethanol, tightening maize supply for the poultry feed industry.
    5. Fuel quality disputes: Contamination claims undermine public confidence in the blend. e.g. chloride and moisture contamination claims were raised against E20 in 2026 and rejected by state oil marketing companies after pan India testing.
    6. Supply chain rigidity: The retail network has been optimised for a single base grade. e.g. restoring E10 would require dual underground tanks and separate dispensers at thousands of outlets.
    7. Geographic concentration of distillery capacity: Ethanol production clusters in a few States, requiring long haul movement. e.g. Uttar Pradesh, Maharashtra and Karnataka account for the bulk of capacity, so deficit States in the east and north east draw on long distance tanker movement.
    8. Material compatibility in older engines: Ethanol acts on certain elastomers and metals used in pre 2023 fuel systems. e.g. rubber fuel lines and aluminium components in older two wheelers were specified against E10, not E20.

    What do other countries’ dual grade fuel markets show?

    1. Brazil: Mandates a high anhydrous ethanol blend in gasoline, raised to 30 percent in 2025, and sells hydrous ethanol as a separate grade at the same forecourt for its flex fuel fleet. The design feature is that the vehicle fleet was converted to flex fuel first, and the fuel grade followed.
    2. United States: E10 is the de facto base gasoline, with E15 and E85 offered at selected stations rather than universally. The design feature is that higher blends are optional and geographically limited, so no station is forced to carry every grade.
    3. Thailand: Retails gasohol E10, E20 and E85 simultaneously through its state fuel retailer network. The design feature is a differential excise structure that prices higher blends below lower ones, so demand shifts by price rather than by mandate.
    4. Germany: Sells Super E10 alongside a Super E5 protection grade, retained specifically for vehicles not certified for the higher blend. The design feature is the legal obligation on larger stations to keep the lower blend available, which is the arrangement now being examined in India.
    5. France: Retails SP95-E10 alongside SP98, with the lower ethanol grade preserved for older vehicles, and publishes a vehicle compatibility list so owners can check before filling. The design feature is that consumer information was issued as a public compatibility register, not left to manufacturers.

    Conclusion

    India met its 20 percent blending target five years early, and the cost of that speed is a national retail network carrying a single fuel grade that most of the vehicle fleet was never certified for. Discussions on retailing E10 alongside E20 are at a preliminary stage with no conclusions reached, and the binding constraint is physical, being underground tank and dispenser capacity at thousands of outlets rather than ethanol availability. The next development to watch is whether the government converts the current exploratory talks into a formal feasibility study, since the mismatch persists until the pre 2023 fleet ages out around 2037.

  • Buffalo Meat Boom: Exports Surge to $5.1 Billion

    Why in the News

    India’s buffalo meat exports rose 25.6% to $5.1 billion in 2025-26, with unit value rising to $3,591 per tonne. Exports grew another 66.6% in Q1 2026-27.

    Meat Export Development Fund

    • Purpose: Export promotion fund for meat, financed through an exporter levy.
    • Levy: APEDA charges ₹250 per tonne on frozen and chilled buffalo meat exports since 29 October 2025.
    • Uses: Market promotion, trade fairs, buyer-seller meets and addressing non-tariff barriers.
    • Model: Based on the Basmati Rice Fund (2008).

    Carabeef

    • Meaning: Meat of the water buffalo, distinct from cattle beef.
    • India does not permit beef exports; buffalo meat exports are allowed under specified categories.

    Key Export Trends

    • 2025-26: $5.1 billion, crossing $5 billion for the first time.
    • Q1 2026-27: Nearly $1.5 billion.
    • Unit value rose from $3,236/tonne (2024-25) to $3,591 (2025-26) and $4,392 (Q1 2026-27).
    • India is the third-largest bovine meat exporter, after Brazil and Australia.

    Regulatory Architecture

    • Exports allowed only through APEDA-registered plants meeting safety and hygiene standards.
    • 83 integrated abattoir-cum-processing plants, besides standalone slaughterhouses and processing units.
    • Periodic and surprise inspections ensure compliance.
    • Focus is shifting from bulk frozen blocks to processed and retail-ready products.